
Retail Investors Net-Buy $5.7 Billion in a Week as Momentum Trades Draw Down 14%: The AI Theme Shifts from ETF Chasing to Earnings Validation
目录
TL;DR
I. From $8.1 Billion to $5.7 Billion: The Change Is in Trading Style, Not Direction
II. The 14% Drawdown Exposes a Positioning Accident
III. AI Themes Continue to Attract Capital, but Investors Are Distinguishing “Build-Out Scale” from “Return on Investment”
IV. Google’s Earnings Show That Capex Beating Expectations No Longer Guarantees Share-Price Outperformance
V. Options Activity at the 99.9th Percentile Means a “Stock-Picker’s Market” Can Still Be Highly Fragile
VI. The Next-Stage Investment Framework: From Monitoring Flows to Validating Returns
VII. Conclusion: AI Is Not Receding, but the Old Trading Playbook Is
本内容基于公开资料和研报数据整理,不构成任何投资建议,不代表任何个人观点,仅供学习参考,请理性阅读
JPMorgan’s latest fund-flow report reveals a critical inflection point: retail investors have not abandoned the AI trade, but they are moving away from chasing gains through ETFs and toward stock selection around earnings and corporate events. Following a 14% one-month drawdown in the momentum factor, the market’s central question has become whether elevated capital expenditure can translate into revenue, earnings, and free cash flow.
TL;DR
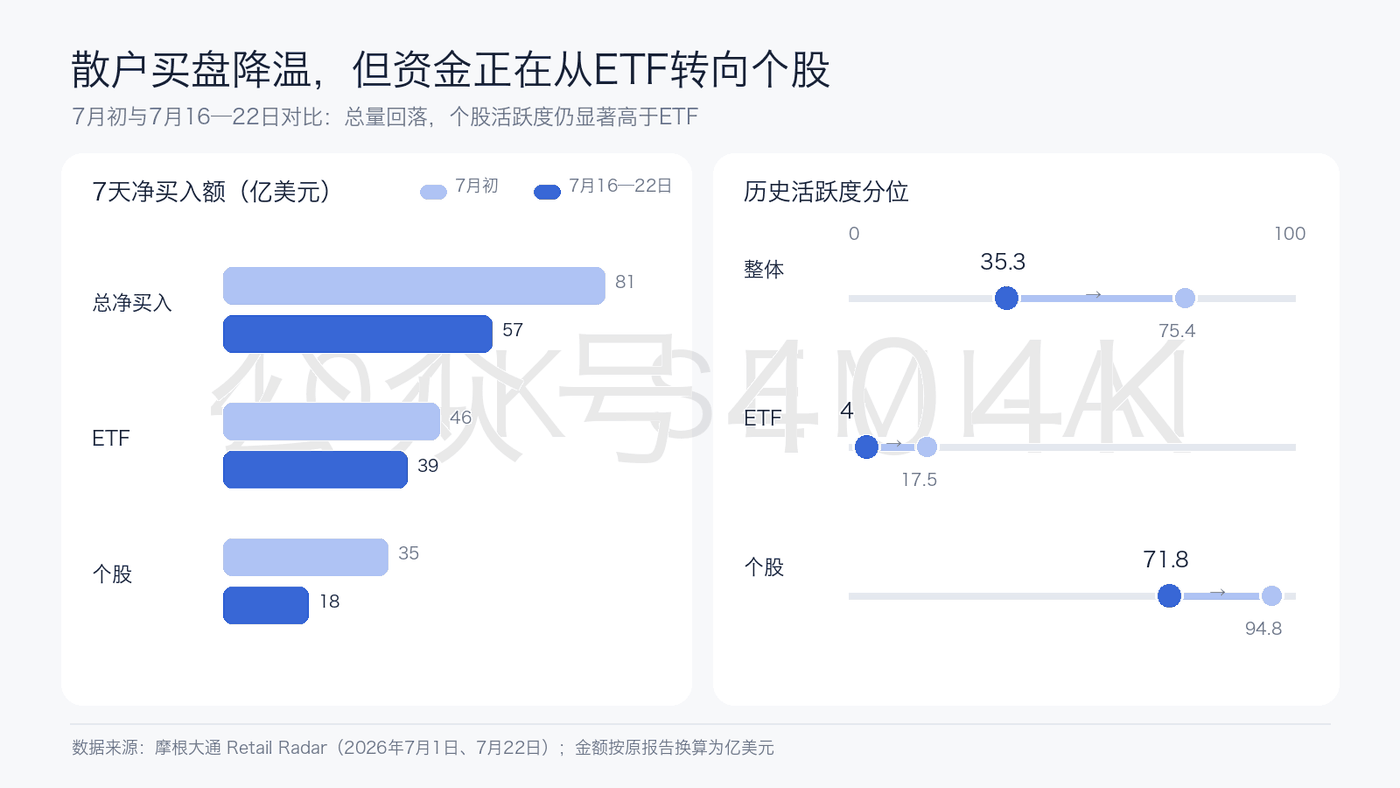
Retail flows are cooling, but investors are far from retreating. Net purchases totaled $5.7 billion over the seven days from July 16 to 22, below the trailing 12-month weekly average of $6.8 billion, with overall activity falling to the 35.3rd historical percentile. ETFs recorded $3.9 billion of net inflows, but activity was only at the 4th percentile; individual stocks attracted $1.8 billion, with activity rising to the 71.8th percentile. Capital is shifting from broad index and sector exposure toward individual stocks selected around earnings and corporate events.
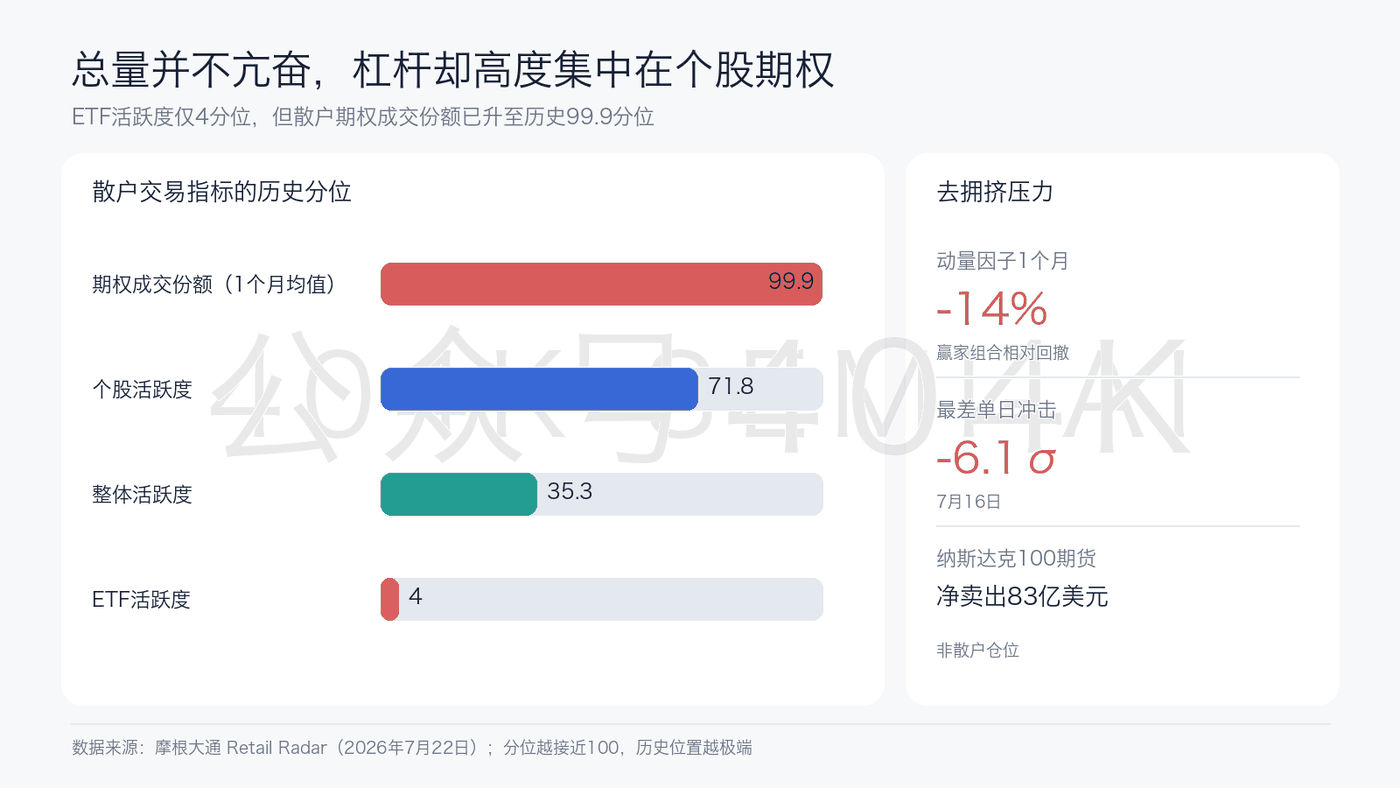
Momentum de-crowding has already occurred. JPMorgan’s large-cap momentum long-short factor has drawn down 14% over the past month. Of the 18 de-crowding trading days, seven produced shocks of negative three standard deviations or worse, including approximately negative 6.1 standard deviations on July 16. Technology ETF flows turned negative, with both SOXL and SMH among the most heavily sold instruments. This looks more like forced deleveraging of crowded positions than a simultaneous collapse in AI fundamentals.
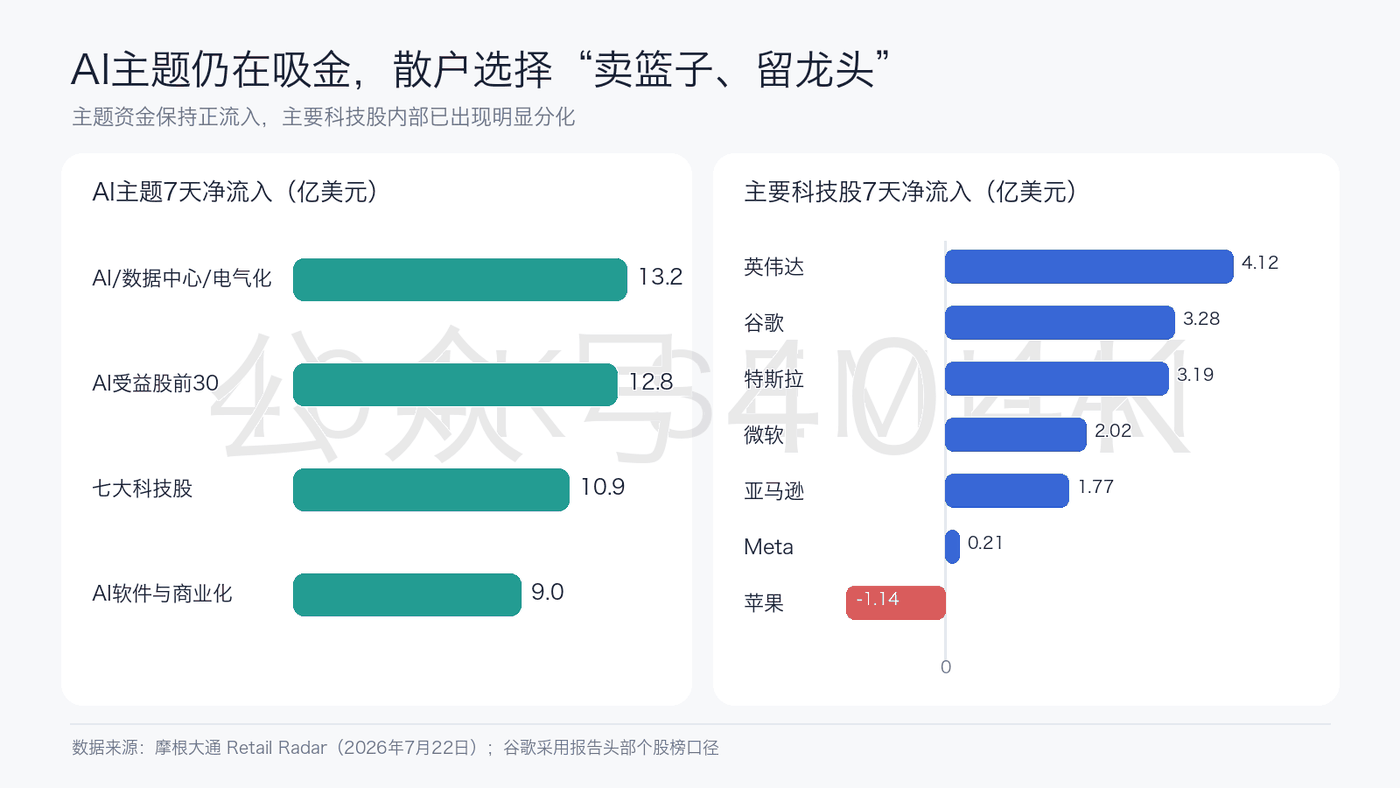
AI remains the dominant flow theme. AI, data center, and electrification themes attracted $1.32 billion of net inflows over seven days; the top 30 AI and data center beneficiaries received $1.28 billion; and the Magnificent Seven attracted $1.09 billion. Nvidia, Google, Tesla, Microsoft, and Amazon all remained net buys, indicating that retail investors are selling selected index vehicles and assets with weaker expectations rather than eliminating AI exposure altogether.
Cloud earnings are changing the market’s scorecard. Google Cloud revenue grew 82%, well above buyside expectations of 70%–75% and the market consensus of 64%. Yet Google fell approximately 4% after raising its 2026 capital-expenditure guidance to $195–205 billion. The market no longer treats higher capex as automatically bullish; it is now evaluating cloud revenue, AI monetization, depreciation, free cash flow, and the 2027 investment trajectory simultaneously.
The real tail risk lies in derivatives. The one-month average retail share of options volume is at the 99.9th historical percentile, with trading heavily concentrated in Tesla, Micron Technology, Nvidia, Amazon, Meta, Sandisk, Apple, AMD, Google, and Microsoft. Meanwhile, non-retail investors net-sold $8.3 billion of Nasdaq 100 futures. The combination of cash-equity stock selection, leveraged options exposure, and futures hedging is likely to amplify post-earnings dispersion and intraday volatility.
I. From $8.1 Billion to $5.7 Billion: The Change Is in Trading Style, Not Direction
Comparing this report with JPMorgan’s corresponding data from early July makes the inflection point clear. During the seven days from June 25 to July 1, retail investors net-bought $8.1 billion, above the then-current trailing 12-month weekly average of $6.7 billion, while activity in individual stocks reached the 94.8th percentile. By July 16–22, weekly net purchases had fallen to $5.7 billion, below the latest weekly average of $6.8 billion, with overall activity declining to the 35.3rd percentile.
Looking only at the aggregate figure could easily lead to the conclusion that retail enthusiasm is fading. The composition tells a different story: ETF activity fell further, from the 18th percentile to the 4th, while activity in individual stocks rose from the 51st percentile to the 71.8th. In other words, retail investors reduced mechanical allocation while increasing active judgments around corporate earnings, orders, and events. The $3.9 billion of ETF inflows looks more like baseline allocation, while the $1.8 billion flowing into individual stocks represents the marginal source of risk appetite.
This continues the signal identified in the early-July article, “JPMorgan Fund Flows Deep Dive: How Retail Dip-Buying and AI Rotation Will Shape the Second Half of the Semiconductor Trade”. At that point, investors were still “buying every index pullback and adding to memory and semiconductors together.” The trade has now shifted to “cooling demand for index vehicles and concentrated buying of companies that beat earnings expectations.” The AI trade has not disappeared; it has moved from a highly correlated thematic trade into a lower-correlation stock-picking phase.
Sector flows support this conclusion. Communication services and technology recorded net inflows of $535 million and $409 million, respectively, while industrials and consumer discretionary saw net outflows of $231 million and $226 million. The five largest net-buy names were SPCX, Nvidia, Google, Tesla, and NU; Apple recorded net selling of $114 million. Capital is not making a broad bet on economic growth. It remains concentrated in AI, cloud, platforms, and a small number of high-beta event-driven opportunities.
II. The 14% Drawdown Exposes a Positioning Accident
JPMorgan divides S&P; 500 companies into five market-cap-weighted groups to construct a momentum long-short factor: long recent winners and short recent losers. The factor has fallen 14% over the past month, indicating that the market’s most crowded outperformers are rapidly surrendering excess returns relative to recent laggards.
More important is the path of the drawdown. Seven of the 18 de-crowding trading days registered negative three-standard-deviation moves or worse, including approximately negative 6.1 standard deviations on July 16. A normal fundamental re-rating usually unfolds gradually around orders, earnings, and valuation. Such a dense cluster of extreme days is more consistent with quantitative deleveraging, triggered stop-losses, options hedging, and profit-taking reinforcing one another. Prices move violently first; the market only then reinterprets the fundamentals.
Technology ETFs shifted from net inflows to net outflows, while flow anomalies in both SOXL and SMH reached approximately negative 1.6 standard deviations, indicating that the most accessible and crowded vehicles for expressing the AI trade were being reduced. Yet flows into individual stocks remained positive, including $412 million for Nvidia, $328 million for Google, $319 million for Tesla, $202 million for Microsoft, and $177 million for Amazon. This combination of “selling the basket while retaining the leaders” is a hallmark of de-crowding rather than an outright bearish turn.
This also confirms the earlier assessment in “Morgan Stanley Warns Semiconductors May Be Near a Temporary Peak: The AI Theme Is Not Over, but the Momentum Trade Is Cooling”: positioning and fundamentals can move in opposite directions for some time. The most dangerous phase is not when demand suddenly falls to zero, but when good companies are sold as part of the same crowded trade. Conversely, the scale of a decline alone cannot validate a rebound; earnings and orders must provide renewed confirmation.
III. AI Themes Continue to Attract Capital, but Investors Are Distinguishing “Build-Out Scale” from “Return on Investment”
Thematic baskets show that AI remains the area where retail investors are most willing to take risk. AI, data center, and electrification themes attracted $1.32 billion of net inflows over seven days and $44.72 billion year to date. The top 30 AI and data center beneficiaries received $1.28 billion over seven days and $43.67 billion year to date. AI software, products, and commercialization attracted $900 million over seven days. These figures are incompatible with the idea of a wholesale flight from AI.
Semiconductor fundamentals also show no sign of a cyclical reversal. After falling approximately 20% from its late-June peak, the sector rebounded about 7% over seven days, versus a gain of only around 1% for the S&P; 500. JPMorgan expects the industry to report a solid quarter, provide constructive third-quarter commentary, and raise 2027 earnings expectations. It also believes the silicon supply-demand gap could widen in 2027, with tightness persisting into 2028. TSMC reported a gross margin above 60% for the first time, raised its 2026 revenue-growth guidance to more than 40%, and maintained its $60–64 billion capital-expenditure plan, continuing to demonstrate the strength of demand for computing infrastructure.
However, the market’s focus has shifted from “how much will be built” to “how much will be earned after it is built.” Forward risks identified in the report include new AI equity supply, the slope of the capex curve, the debt market’s capacity to absorb financing, breakthroughs in model efficiency, and the ultimate margins of AI infrastructure. They all point to the same issue: as long as capex is funded primarily through internal cash flow, the value chain can continue to enjoy high growth. Once dependence on external financing rises, unit compute prices decline, or depreciation erodes margins, even strong supply-chain orders will face a valuation discount.
The AI trade is therefore dividing into two asset categories. The first consists of chips, memory, advanced packaging, and power infrastructure, where physical bottlenecks, order visibility, and pricing power remain intact. The second consists of cloud platforms, models, and software, which must prove their returns on invested capital. The former determines whether the build-out can be completed; the latter determines whether it is worth continuing. Both are indispensable.
IV. Google’s Earnings Show That Capex Beating Expectations No Longer Guarantees Share-Price Outperformance
Google provides the most instructive earnings example in the report. On July 22, retail investors net-bought $74.7 million of Google shares ahead of earnings, with buying intensity reaching 1.9 standard deviations. The results showed Google Cloud revenue growth of 82%, above buyside expectations of 70%–75% and substantially ahead of the market consensus of 64%. Viewed solely through the lens of monetization, this represents strong AI demand and cloud-revenue conversion.
At the same time, Google raised its 2026 capital-expenditure guidance from $180–190 billion to $195–205 billion. The report also provides two estimates for 2027: approximately $250 billion from market consensus and approximately $290 billion from JPMorgan. Yet the shares still fell about 4% after earnings. This does not mean the market rejected the cloud business; it means the hurdle rate for validating capital expenditure has risen.
The previous valuation logic was straightforward: higher capex meant more chip and data center orders, lifting the entire AI value chain. The current framework adds four tests:
Can cloud revenue growth continue to match or exceed capex growth?
Can AI product revenue offset declining compute prices and intensifying model competition?
Will depreciation, energy, and financing costs compress margins?
If capex is raised again in 2027, can free cash flow remain stable?
The same tests apply to Amazon, Microsoft, and Meta. Capital expenditure by the four North American hyperscalers remains the most important aggregate switch for AI hardware demand, but the market will no longer focus solely on the combined figure. It will assess cloud revenue, monetization through advertising or enterprise software, internal chip efficiency, and balance-sheet strength on a company-by-company basis. The larger the capex commitment, the more clearly differences in returns will be reflected in share prices.
V. Options Activity at the 99.9th Percentile Means a “Stock-Picker’s Market” Can Still Be Highly Fragile
The one-month average retail share of options volume is at the 99.9th historical percentile, with the chart reading close to 24% of total market volume. Activity is also heavily concentrated in Tesla, Micron Technology, Nvidia, Amazon, Meta, Sandisk, Apple, AMD, Google, and Microsoft. This means that even as the market shifts from ETFs to individual stocks, leverage is not necessarily declining; it is simply moving from fund products into single-stock options.
Cross-market positioning warrants even greater caution. Non-retail investors net-sold approximately $4.1 billion of equity-index futures during the week, including $8.3 billion of Nasdaq 100 futures, while net-buying $2.3 billion of S&P; 500 futures and $1.9 billion of Russell 2000 futures. Institutions are not reducing US equity risk indiscriminately; they are selectively cutting Nasdaq and large-cap technology exposure. Retail investors buying technology stocks while institutions sell technology-index futures will increase price sensitivity on earnings days.
This is not a simple repeat of January 2021. The appendix shows that retail brokers’ share of trading peaked at approximately 37% at the time; today’s share of cash-equity trading remains well below that peak. What is genuinely unusual today is the combination of elevated options participation, concentrated AI exposure, and social-media attention. ONDS attracted $134.2 million of retail net buying during the week, with buying intensity reaching 4.3 standard deviations and short interest at approximately 42%. WYFI, NBIS, and ASTS also sit at the intersection of high short interest and elevated discussion volume. These names can generate localized short squeezes, but they cannot demonstrate improving profitability across the AI industry.
Different charts in the report also use different observation windows. For example, Sandisk’s net-selling figure differs between the weekly aggregate table and the individual-stock chart. These data should therefore be used with their corresponding dates and methodologies intact, rather than mechanically combined into a single fund-flow conclusion.
VI. The Next-Stage Investment Framework: From Monitoring Flows to Validating Returns
Following the momentum drawdown, assessing whether the AI theme remains healthy requires evaluating flows, earnings, and industry supply-demand conditions together. A single indicator can only show who is trading; it cannot show whether the trade is sustainable.
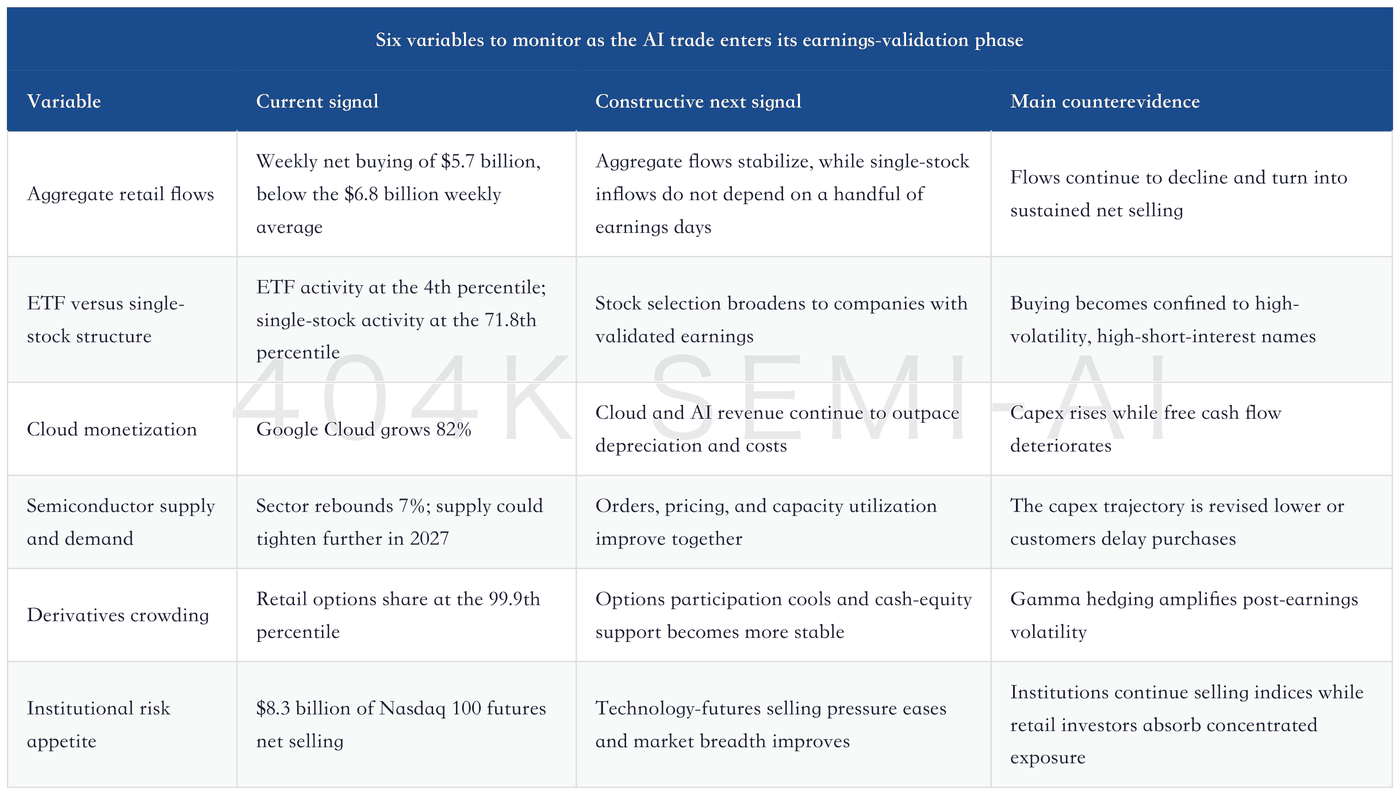
At the portfolio level, the implication is not simply to exit AI, but to divide “thematic exposure” into three layers. The first consists of hyperscalers and platforms, which must prove returns on capital. The second consists of physical bottlenecks such as chips, memory, packaging, and power, which must convert demand into orders. The third consists of event-driven trades with high short interest and heavy options participation, which primarily reflect liquidity and sentiment. The first two layers can validate one another; the third cannot substitute for fundamentals.
The most constructive path would combine accelerating cloud revenue, continued capex growth with stable free cash flow, semiconductor supply tightness translating into orders and pricing, a gradual decline in the options share of trading, and an end to concentrated institutional selling of technology indices. The most dangerous path would involve continued capex increases without corresponding share-price or cash-flow performance at the hyperscalers, concentrated retail options buying in a handful of AI winners, and continued institutional risk reduction through Nasdaq futures.
VII. Conclusion: AI Is Not Receding, but the Old Trading Playbook Is
The most important conclusion from JPMorgan’s report is not the difference between $5.7 billion and the $6.8 billion weekly average, but that market participants are changing instruments. ETF and momentum exposures are being reduced, retail investors are shifting toward earnings-driven stock selection, institutions are using Nasdaq futures to manage risk, and options are re-amplifying single-stock volatility.
This indicates that the AI theme has moved from its first phase—when higher capex alone could lift the entire sector—to a second phase in which capital expenditure must be validated through revenue, earnings, and cash flow. Google Cloud’s 82% growth failing to prevent a share-price decline is the clearest evidence of this transition. The sustainability of the rally will no longer depend solely on how many chips Nvidia sells, but on whether Google, Amazon, Meta, and Microsoft can convert compute capacity into sustainable returns.
The 14% momentum drawdown can clear crowded positioning, but it cannot automatically create a new upside thesis. That thesis can only come from earnings: cloud-revenue conversion, improved returns on capital expenditure, continued tightness in semiconductor supply and demand, and reduced derivatives crowding. AI is not receding; what is receding is the old trading approach that required no earnings validation and relied only on chasing momentum.