
Repricing Japanese Hardware Assets: How Hitachi Grid, Mitsubishi Electric EML, Sony IP, and Panasonic BBU Connect to AI Capex
目录
Too Long; Didn’t Read
1. The Main Line in Japanese Tech Stocks Is Shifting from Consumer Electronics to AI Infrastructure
II. Core Model: Do Not Buy as “Electronics Stocks”; Buy as “AI Bottlenecks”
III. Hitachi: The Power Grid Is the Hardest Infrastructure Constraint in the AI Era
IV. Mitsubishi Electric: EML, Power Supply, Defense, and FA Jointly Support Resilience
V. NEC and Fujitsu: Traditional SI Needs to Turn Man-Day Projects into Platform Profit
VI. Sony: IP, Platforms, and Sensors Determine Whether It Is a Different Kind of AI Asset
VII. Panasonic Holdings: BBU and Materials Are Options; Batteries and Portfolio Discount Are Reality
8. Portfolio Ranking: Certainty First, Then Optionality, Then Options
9. Three Scenarios: Which Path Delivers the Japan Hardware Re-rating?
10. Capability Migration: How Old Japan Manufacturing Connects to AI Capex
11. From GPUs to the Grid, the Asset Attributes of Japanese Hardware Are Migrating
12. Why Traditional Consumer Electronics and the Printing Chain Are Not in the Core
XIII. Falsification Checklist: How to Track This Theme
本内容基于公开资料和研报数据整理,不构成任何投资建议,不代表任何个人观点,仅供学习参考,请理性阅读
AI capex is spilling over from GPUs into power grids, optical networks, systems integration, content platforms, and backup power. The divergence in Japanese electronics stocks is not about whether consumer electronics recover, but about which companies can turn these incremental drivers into sustained margin expansion and valuation premia. JPMorgan prefers Hitachi, Mitsubishi Electric, NEC, Fujitsu, and Sony, while Panasonic is more of an option asset.
Too Long; Didn’t Read
Japanese hardware is entering a second screening phase. The first round of Japanese tech-stock rerating was about the yen, governance, buybacks, and cyclical recovery. The second round is about where AI capex actually flows. Hitachi, Mitsubishi Electric, NEC, Fujitsu, and Sony share one trait: they sit in the non-GPU segments of AI infrastructure, including power grids, optical networks, systems integration, content platforms, and high-end sensors. Panasonic has BBU and materials options, but automotive batteries and a conglomerate discount still weigh on valuation.
Hitachi is the most complete infrastructure asset. AI data-center power density is moving from around 10kW per rack in the A100/H100 era to 120-140kW for GB200/GB300, and then to megawatt-class racks for Rubin Ultra. The bottleneck will shift from GPUs to grids, transformers, switchgear, HVDC, and dispatch software. Hitachi Energy has grid hardware, automation, software, and Lumada digitalization, giving it the clearest revenue and profit slope in energy for FY2026-FY2029.
Mitsubishi Electric needs to prove EML can lift profits. AI server expansion is pushing the data-center optical interconnect market from roughly $4 billion toward roughly $20 billion. Mitsubishi Electric has a strong position in data-center EML lasers. UPS, data-center cooling, FA price increases, defense export liberalization, and space electronics also provide profit upside. The real validation point is whether these exposures can continue to raise the traditional industrial-company operating-margin ceiling above 10%.
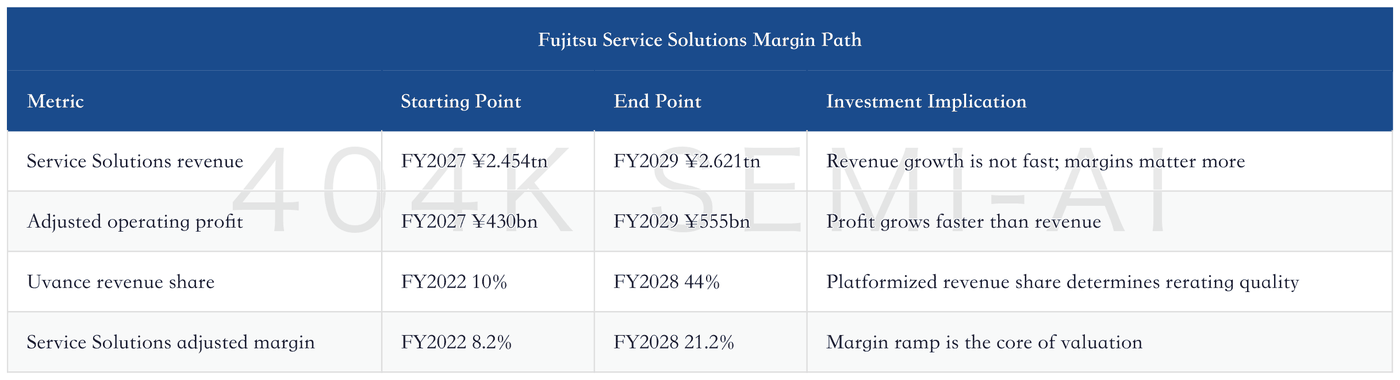
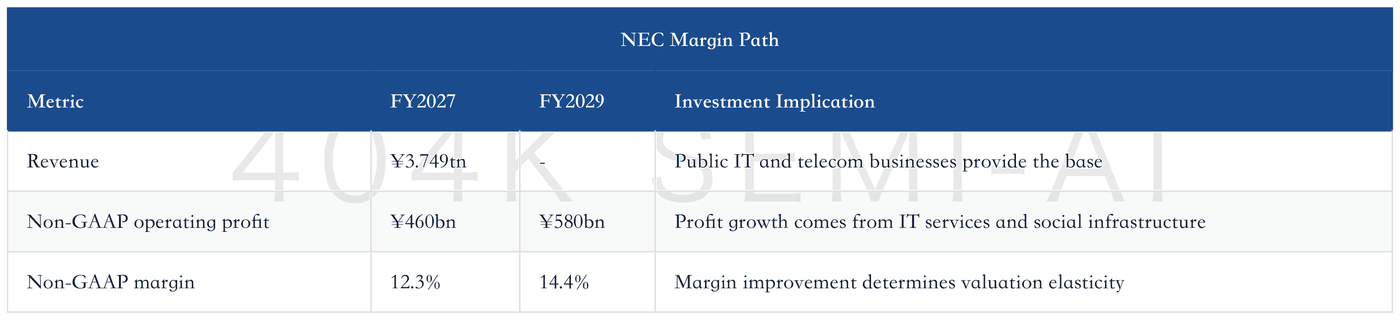
SI services depend on platformized margins. NEC’s BluStellar, Fujitsu’s Uvance, and Hitachi’s Lumada are all moving traditional systems integration from project-based delivery toward industry templates, software reuse, and AI agents. In JPMorgan’s model, Fujitsu’s service-solutions margin can reach 21.2% by FY2029, while NEC’s non-GAAP operating margin also continues to rise. Whether valuations can keep moving higher depends on whether these businesses truly escape the old model of low-gross-margin, headcount-based delivery.
Sony’s asset base is platforms and IP. Sony’s rerating variables are gaming networks, music rights, film and television, anime platforms, image sensors, and IP synergies. In SOTP, Game & Network Services, Music, Pictures, and sensors together contribute the vast majority of value. Sony has the largest upside, but the validation cycle is also slower: PS platform profits, Crunchyroll subscriptions, music-rights monetization, and sensor growth outside smartphones need to materialize together over several consecutive quarters.
Panasonic is more like a discounted asset with options. BBU, MEGTRON materials, and Blue Yonder allow Panasonic to participate in AI data centers, but automotive-battery profits, the true profitability of the energy business after IRA adjustments, automotive-electronics losses, and the conglomerate discount remain hard constraints. The buying point for Panasonic is whether BBU orders can move from the planned scale of roughly JPY800 billion into revenue recognition, while automotive batteries stop absorbing improvements elsewhere in the portfolio.
Portfolio ranking should prioritize certainty. In ranking terms, Hitachi is better suited as a core holding; Mitsubishi Electric is industrial AI hardware beta; Sony is an IP and platform rerating story; NEC and Fujitsu are AI-service margin-improvement plays; Panasonic is only suitable once BBU and energy profits actually materialize. The bear case rests on four sets of numbers: grid orders and deliveries, EML and optical-network demand, SI platform gross margins, and BBU revenue plus energy-business margins after subsidies.
1. The Main Line in Japanese Tech Stocks Is Shifting from Consumer Electronics to AI Infrastructure
Japanese electronics stocks used to be easy to put into one large basket: consumer electronics, office equipment, cameras, printers, FA, heavy electrical equipment, home appliances, and precision instruments. That classification was still barely workable in the previous cycle, because the market cared most about the yen, inventories, global consumer-goods demand, and corporate governance. But AI capex has dismantled that framework. The truly valuable Japanese hardware assets are no longer defined by the label “Japanese electronics,” but by whether they can capture the bottlenecks squeezed out of AI infrastructure by GPUs.
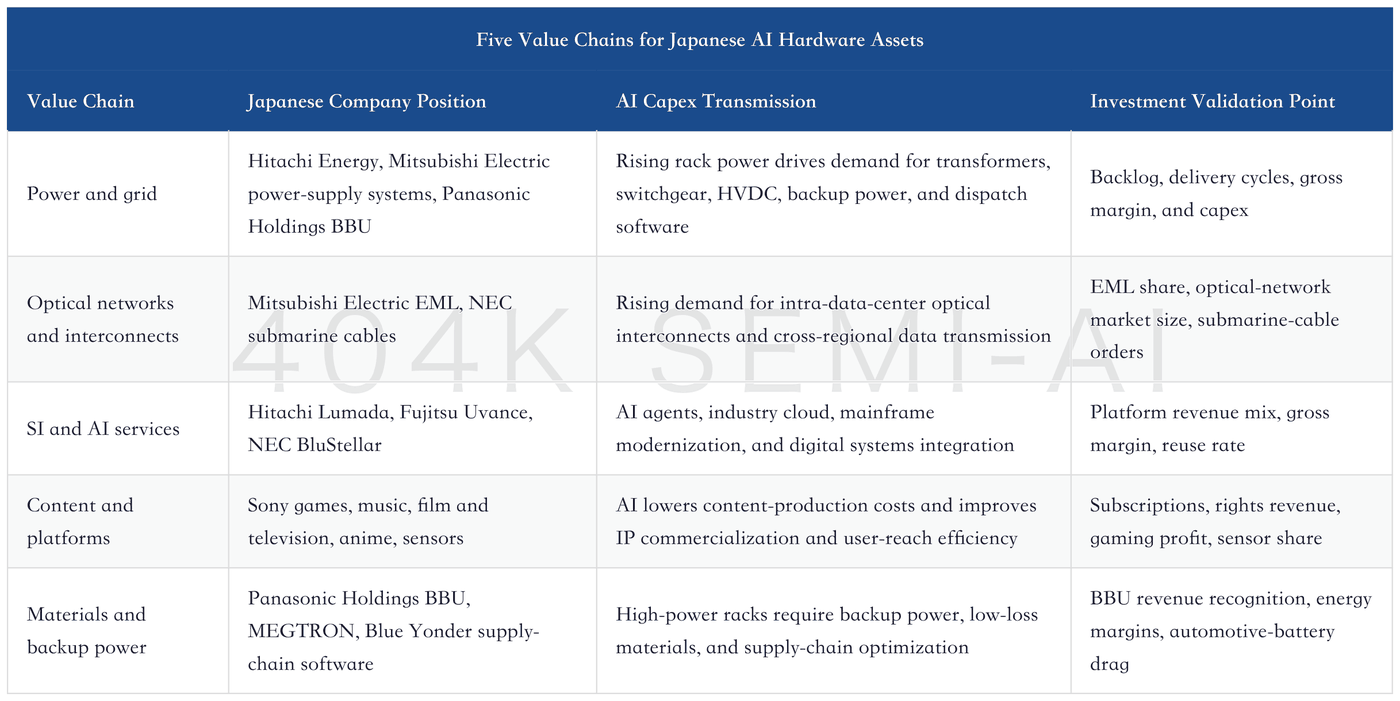
The most valuable aspect of this JPMorgan coverage model is that it does not simply describe Japanese tech stocks as an “AI beneficiary basket.” It breaks the AI value chain into power, networking, computing, foundation models, generative/agentic AI, and Physical AI, then maps Japanese companies into those positions: Hitachi corresponds to power grids and Lumada; Mitsubishi Electric to data-center power supply, cooling, and EML optical devices; NEC to submarine cables and BluStellar; Fujitsu to CPUs, quantum, Uvance, and AI services; Panasonic to BBU, CCL materials, and supply-chain software; and Sony to content creation, platforms, and image sensors.
This breakdown matters. GPUs themselves still carry the greatest value, but capital markets are already very familiar with GPUs, HBM, advanced packaging, and CSP capex. The next stage of excess returns is more likely to appear in segments that were previously treated as old economy, but have suddenly become constraints on the pace of AI buildout. Power grids are not new. Transformers are not new. Submarine cables, EML, UPS, BBU, and SI services are not new either. What AI changes is demand visibility, pricing power, and asset characteristics in these segments.
The rerating of Japanese hardware assets can be divided into three categories. The first is hard-constraint assets, such as Hitachi Energy’s grid equipment and software, Mitsubishi Electric’s EML and power-supply systems, and NEC’s submarine cables. These segments directly affect whether AI data centers can be energized, interconnected, and connected for cross-regional data transmission. The second is margin-improvement assets, such as NEC, Fujitsu, and Hitachi’s AI-platformized SI services. They do not directly sell rack hardware, but they can convert AI applications, industry templates, cloud migration, and mainframe modernization into higher-margin service revenue. The third is platform and IP assets, such as Sony. It is not a picks-and-shovels supplier of AI compute, but it may benefit from the long-term value created by AI diffusion in content generation, gaming networks, anime platforms, and image capture.
The real area to watch is the fourth category: narrative without a profit entry point. Traditional consumer electronics, printers, low-end hardware, and companies with high portfolio complexity can rise briefly during thematic rallies if they cannot provide a clear AI revenue, margin, or cash-flow path, but they tend to return to their prior valuation discounts. This is the logic behind JPMorgan’s underweight rating on Seiko Epson and neutral ratings on Canon, Ricoh, Casio, and others: not every Japanese electronics company can be repriced because of AI.
II. Core Model: Do Not Buy as “Electronics Stocks”; Buy as “AI Bottlenecks”
The valuation ranking from this coverage model is quite interesting. Sony has the largest upside implied by the target price. Hitachi, NEC, and Fujitsu also have more than 20% upside. Mitsubishi Electric has relatively lower upside, but its business elasticity and AI exposure are more direct. Panasonic’s target price is essentially close to the current price, suggesting the AI option is not yet sufficient to offset the conglomerate discount and pressure in the battery business.
From a risk-reward perspective, Hitachi looks most like a high-conviction core asset, Mitsubishi Electric most like a hardware elasticity asset, Sony most like a platform re-rating asset, NEC and Fujitsu are margin-improvement assets, and Panasonic is an option asset. This ranking matters more than simply looking at target-price upside. Sony’s model upside is large, but realization requires evidence from multiple businesses at the same time. Hitachi’s target-price upside is lower than Sony’s, but it is easier to verify continuously through orders, revenue, margins, and buybacks.
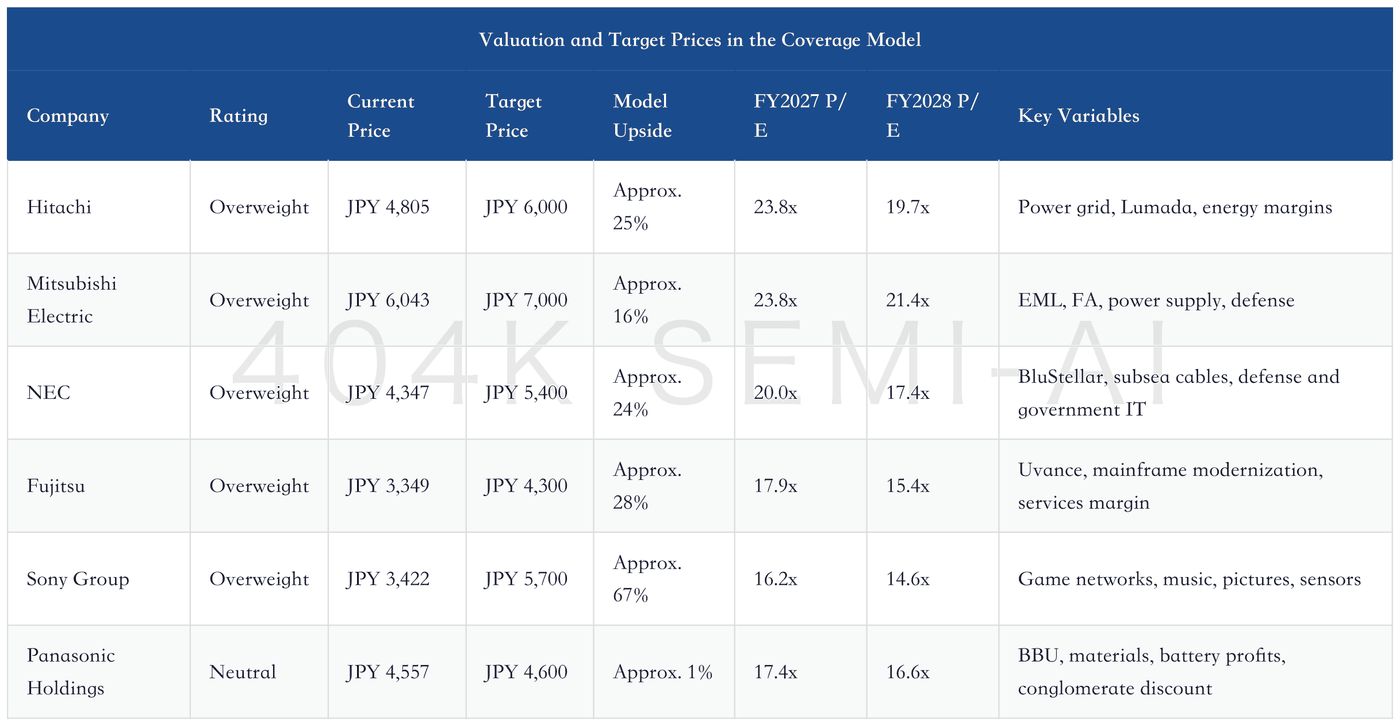
This table should not be interpreted mechanically as “Sony is the cheapest and Panasonic is the most expensive.” Sony’s P/E is low and target-price upside is high, but its value decomposition depends on SOTP: Game & Network Services, music, pictures, electronics products, image sensors, financial equity interests, and net cash together make up the target price. The market discount on Sony partly comes from its group structure, and partly from the gaming hardware cycle, content investment, and sensor volatility. Hitachi and Mitsubishi Electric are easier to place within an industrial and infrastructure framework, and their verification cadence is clearer.
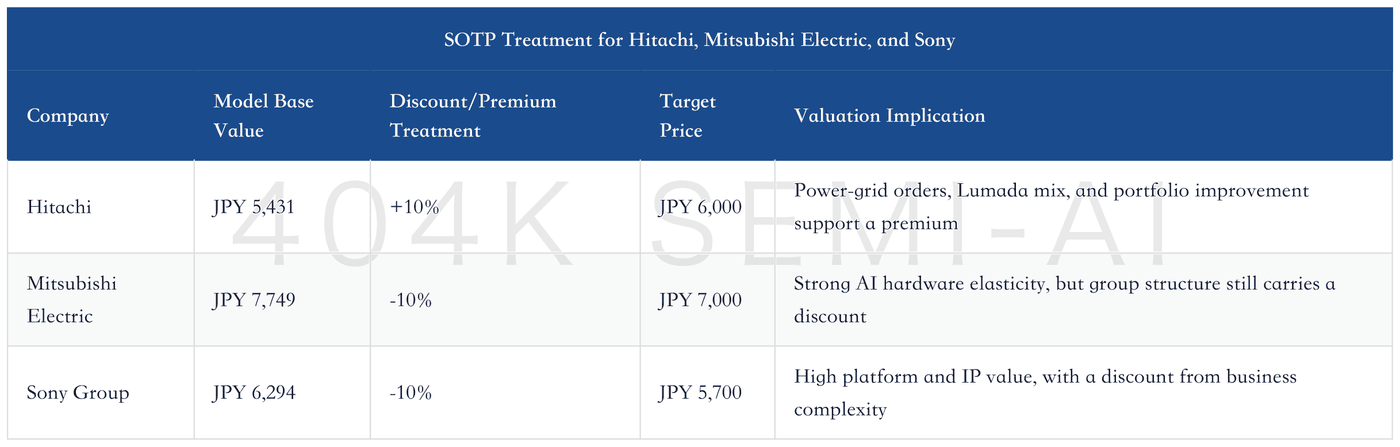
JPMorgan applies different SOTP discounts and premiums to the three companies. This distinction matters more than the target prices themselves: Hitachi receives an infrastructure premium, Mitsubishi Electric remains constrained by a conglomerate discount, and Sony’s discount comes from its complex platform portfolio.
In portfolio terms, the best allocation here is not to buy all six companies equally, but to tier them by verification difficulty. The first tier is Hitachi, because its AI infrastructure exposure overlaps with the traditional power-grid supercycle, and orders, revenue, margins, and capital returns can validate one another. The second tier is Mitsubishi Electric and Sony: the former is AI optical-network and industrial power-supply hardware; the latter is a re-rating of IP platform and sensor value. The third tier is a low-weight allocation to NEC and Fujitsu, pending further delivery in SI services margin data. The fourth tier is only an option position in Panasonic, unless BBU and energy margins truly change the group’s cash-flow structure.
III. Hitachi: The Power Grid Is the Hardest Infrastructure Constraint in the AI Era
Hitachi is the most complete AI infrastructure asset among this group of Japanese hardware companies. Its core value is not that it “has an AI software platform,” but that it can form a closed loop across power-grid hardware, dispatch software, systems integration, and industrial data platforms. As AI data-center power density continues to rise, the real scarcity is not any single component, but end-to-end delivery capability across power generation, transmission and distribution, transformers, switchgear, HVDC, site dispatch, and the data-center load side.
Nvidia’s rack roadmap provides very direct context for this view. In the A100 and H100/H200 eras, per-rack power was still in the single digits to around 10kW. GB200 NVL72 has reached 120kW, and GB300 NVL72 rises further to 140kW. If Rubin Ultra moves toward megawatt-scale racks, the value of power-related content will rise significantly. In JPMorgan’s materials, Rubin Ultra’s per-rack power-related content value is estimated at USD 561,000, including about USD 188,000 for PSUs and about USD 373,000 for other components within the power architecture. The exact numbers may change, but the direction is clear: AI hardware value is starting to spill over from GPU boards into power-supply systems.
Hitachi’s advantage is that it does not only sell one transformer or one software module. Hitachi Energy already has strong positions in grid automation, Grid Integration, high-voltage equipment, and transformers, with products and services covering a large number of utilities globally. The company’s disclosed capacity-expansion plans also show that by around 2030, dry capacitors, valves, switchgear, semiconductors, conventional power transformers, HVDC transformers, and other segments will all see significant expansion. Announced cumulative investment exceeds USD 6.25 billion, including global transformer capacity, transmission and distribution, R&D;, and critical components.
This type of expansion is the easiest to underestimate. The market often treats grid orders as part of the traditional heavy electrical equipment cycle, but AI data-center demand has different characteristics. First, customers care more about delivery speed and reliability, and are unwilling to sacrifice delivery windows for lower prices. Second, supply cycles for transformers, switchgear, HVDC, and automation software are long, making it difficult to expand capacity quickly through price competition in the short term. Third, AI data centers have high loads, concentrated power consumption, and high redundancy requirements, which raise demands on grid interfaces and site dispatch. Hitachi’s hardware and software portfolio happens to place “equipment delivery” and “operating efficiency” within the same framework.
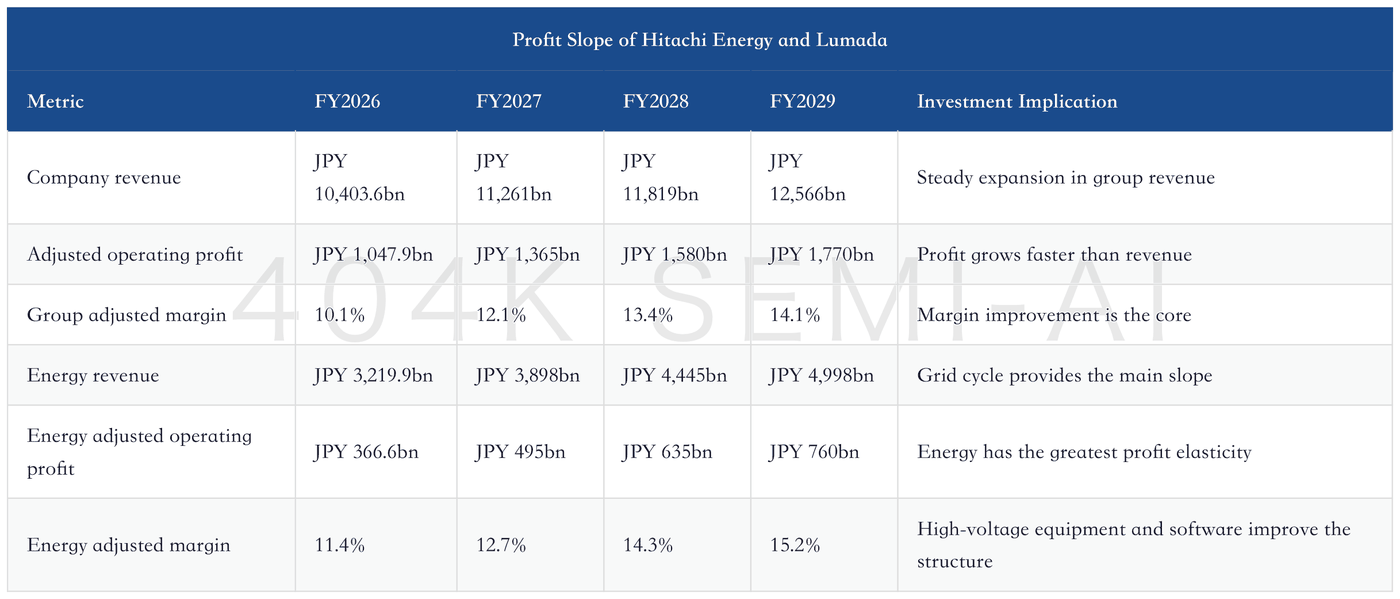
Hitachi’s second layer of value is Lumada. Many companies talk about AI services, but Hitachi’s Lumada is not a standalone software business. It is a reuse platform for data across industry, energy, rail, manufacturing, and social infrastructure. In JPMorgan’s model, Lumada revenue rises from 39% of total revenue in FY2026 to 50% in FY2028, while Lumada’s share within the energy business also rises from 24% to 30%. If these targets are achieved, Hitachi’s valuation will no longer be only heavy electrical equipment, but a composite asset of “hardware delivery + operating data + industry software.”
GlobalLogic is also part of this logic. It has around 20,000 employees, multiple co-creation centers and delivery bases, and more than 400 customers. Historically, it has been able to achieve relatively high adjusted EBITDA margins. Placing this type of digital-engineering capability into Hitachi’s energy, industrial, and transportation customers is not just about selling more IT services. It extends the operations, optimization, and digitalization revenue that follows one-off equipment sales.
Hitachi’s risks are also clear. The first is the pace at which orders convert into revenue. Grid orders are strong, but delivery cycles for high-voltage equipment and transformers are long. If capacity expansion, components, and project execution cannot keep pace, revenue recognition will lag. The second is whether margins can improve as modeled. Heavy electrical equipment expansion may bring labor, materials, and supply-chain pressure; good order pricing does not mean every project can generate high gross margins. The third is the quality of Lumada revenue. The market needs to see that this is not simply traditional IT projects being renamed, but genuinely higher reuse rates and margins.
The view on Hitachi can be reduced to one sentence: it is not the most glamorous stock in AI hardware, but it may be the stock in Japan’s market that most resembles a core holding in “AI power infrastructure.” As long as energy orders keep expanding, margins continue rising, and Lumada’s revenue contribution keeps increasing, the valuation premium has support.
IV. Mitsubishi Electric: EML, Power Supply, Defense, and FA Jointly Support Resilience
Mitsubishi Electric’s investment case is more diversified than Hitachi’s, and also more resilient. It has the cyclical attributes of FA and industrial automation, as well as the structural attributes of data-center power supply, cooling, EML optical devices, defense, and space electronics. JPMorgan rates it Overweight, but the target price implies only about 16% upside, suggesting the market has already partly priced in its improvement. The remaining key question is whether these structural businesses can keep lifting the group margin.
EML is Mitsubishi Electric’s most direct AI networking exposure. As intra-data-center optical interconnects move from 400G/800G to 1.6T, the value and technical requirements of electro-absorption modulated lasers in high-speed optical modules continue to rise. JPMorgan materials show the data-center optical networking market growing from about US$4 billion in 2023 to about US$20 billion in 2028, with high-speed and ultra-high-speed categories increasing their share. Mitsubishi Electric has a strong market position in data-center EML. This segment is not as crowded by investors as GPUs, but it is highly correlated with AI server volume growth, high-speed switches, and optical module upgrades.
Power supply and cooling are the second line. As AI racks move from hundreds of kW toward higher density, data centers need not only optical interconnects, but also UPS, power supply equipment, cooling systems, and more complex building/facility controls. Mitsubishi Electric has long-standing capabilities in power equipment, air conditioning and refrigeration, and FA control, allowing it to embed traditional industrial capabilities into AI data-center construction. These businesses will not see the same near-term explosion as GPUs, but they have long project cycles, high customer stickiness, and usually better earnings quality than ordinary consumer electronics.
Defense and space electronics are the third line. Expectations that Japan will ease policy restrictions on defense equipment exports in 2026 have improved visibility for Mitsubishi Electric’s defense business. The company has exposure to radar, next-generation fighter avionics, lasers, communications satellites, electronic warfare, and overseas cooperation. The combination of AI and defense should not simply be framed as a thematic concept; what truly affects profit is orders, delivery, export permits, and project margins. But within industrial companies, defense businesses usually have better order visibility and cash flow stability.
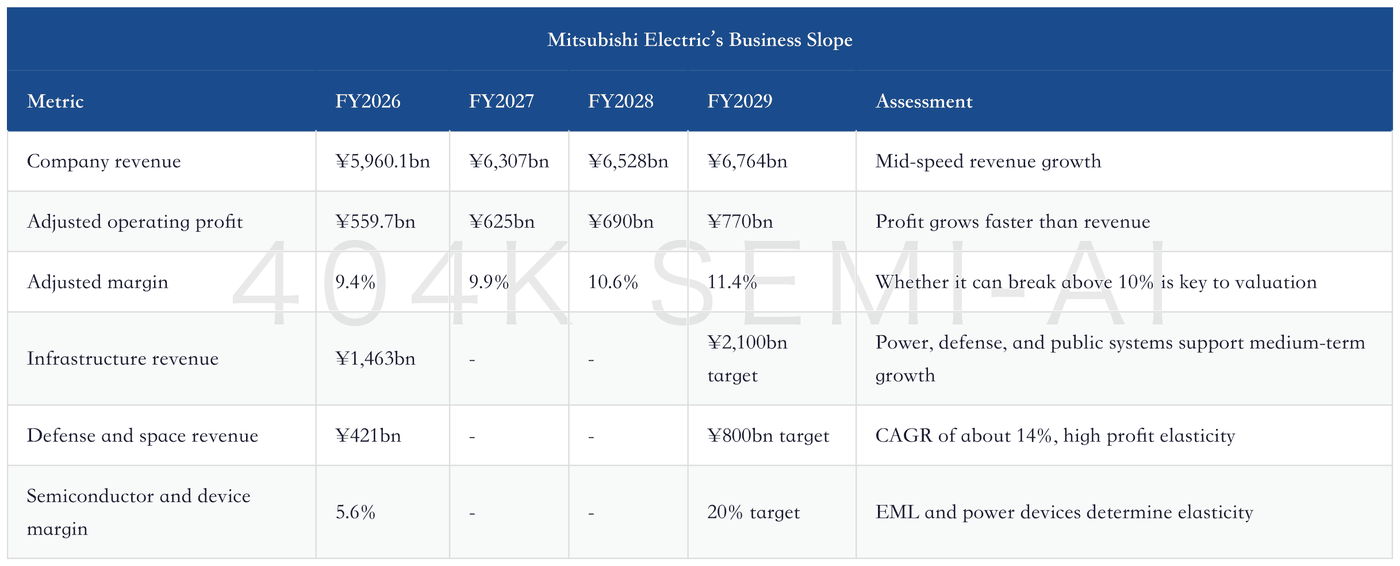
Mitsubishi Electric also has an easily overlooked variable: FA pricing and product mix. Over the past few years, the FA industry has been under pressure from inventory, the cycle, and China demand, but price increases for high-end products and mix improvement have begun to change margins. JPMorgan materials note that price increases for some FA products can reach the 10%-80% range, showing that industrial automation is not a pure volume story, but a combination of product upgrades, supply discipline, and customer stickiness.
The valuation difficulty for Mitsubishi Electric lies in the group structure. It simultaneously has industrial, infrastructure, building systems, life, semiconductor devices, defense, and space electronics businesses, making it hard for investors to assign equally high multiples to all segments. The 10% group discount embedded in the target price reflects this. To narrow the discount, the company needs to continue proving three things: clearer capital allocation, low-return businesses not becoming a drag, and AI-related and defense-related businesses contributing higher margins.
The investment judgment on Mitsubishi Electric is: it is not an asset like Hitachi, where “grid” is a single very strong main line. Instead, it is a multi-factor resilience story composed of AI data centers, optical networking, defense, and FA improvement. After the share price has already had one run, chasing higher requires evidence that EML orders, semiconductor device margins, defense orders, and group ROE can continue to be revised up.
V. NEC and Fujitsu: Traditional SI Needs to Turn Man-Day Projects into Platform Profit
The rerating logic for NEC and Fujitsu is more software- and services-oriented, but they are not SaaS companies. Their old problem is also typical: large revenue, stable customers, and deep government and enterprise IT relationships, but traditional system integration is easily viewed by the market as a low-margin, low-growth, man-day delivery business. Whether AI can change this depends on whether BluStellar and Uvance can turn industry solutions, AI agents, cloud migration, mainframe modernization, security, and data platforms into reusable products.
NEC’s strengths lie in government, communications, public safety, submarine cables, and large enterprise systems. BluStellar is its main vehicle for pushing traditional public-sector IT and enterprise systems toward AI services, while submarine cables provide harder network infrastructure exposure. Its core customers include government, telecom, and manufacturing. Customer relationships are stable, but the project-based nature still needs to be validated through margins.
Fujitsu’s strengths lie in Uvance, mainframe modernization, and industry services. If Uvance continues to increase its revenue share and gross margin, Fujitsu will no longer be an ordinary IT services provider, but a margin-improvement asset driven by “mainframe modernization + industry AI templates.”
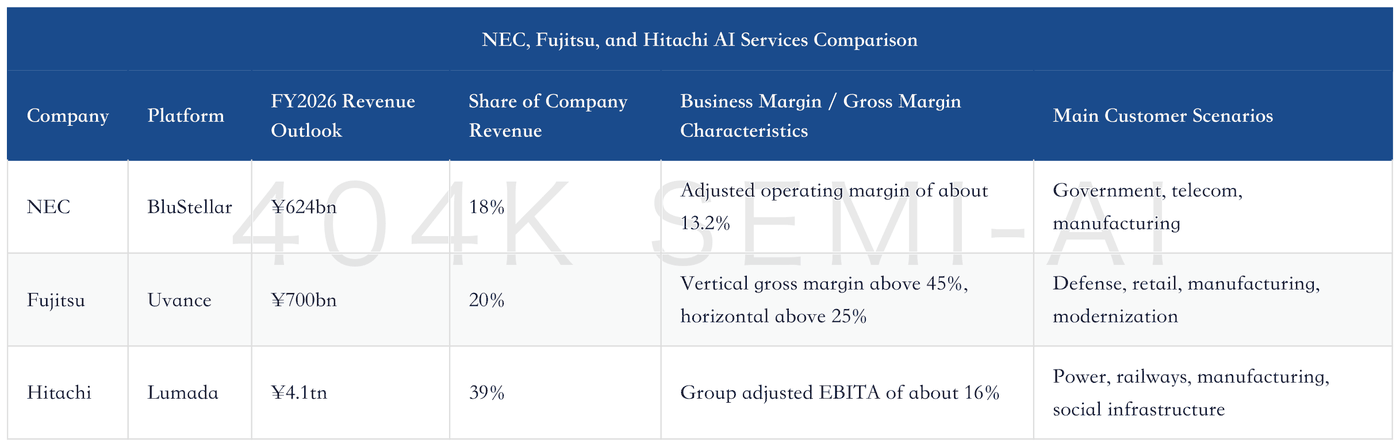
All three companies are talking about AI, but AI means different things for each. NEC is more like AI transformation for the public sector and communications infrastructure, combined with cybersecurity, defense, submarine cables, and government IT. Fujitsu is more like enterprise modernization and industry templates, especially legacy mainframe migration, cloudification, AI agents, and industry applications. Hitachi is more like a data platform for industrial and social infrastructure. Which company ultimately receives a higher market valuation will depend on margins and revenue reuse rates, not how many times “AI” appears in a presentation.
Fujitsu’s margin model is particularly worth watching. The real key is not revenue growth itself, but whether Service Solutions can push its adjusted margin to a higher level as Uvance’s share rises.
NEC’s profit curve is also improving. Its advantage is a stable public-sector and telecom customer base; its weakness is a high share of project-based business, meaning revenue recognition and margin improvement may not be as smooth as investors hope.
The ways to falsify SI services are straightforward. First, revenue growth cannot rely only on large one-off projects; the share of platformized revenue must rise. Second, gross margin must improve with industry templates and software reuse, otherwise AI is just custom projects under a new name. Third, sales expenses and delivery headcount must not consume the gross margin improvement. Fourth, customer cases need to move from proof of concept to scaled deployment, especially in vertical scenarios such as government, manufacturing, defense, retail, and telecom.
For the investment ranking between NEC and Fujitsu, I prefer treating Fujitsu as a margin-improvement allocation and NEC as a beneficiary of public infrastructure and cybersecurity. Fujitsu’s advantage is a clearer margin path; NEC’s advantage is scarcer government, submarine cable, and security assets. Neither is suitable for judging purely by one quarter of orders. They are better validated through margin improvement over a 2-3 year horizon.
VI. Sony: IP, Platforms, and Sensors Determine Whether It Is a Different Kind of AI Asset
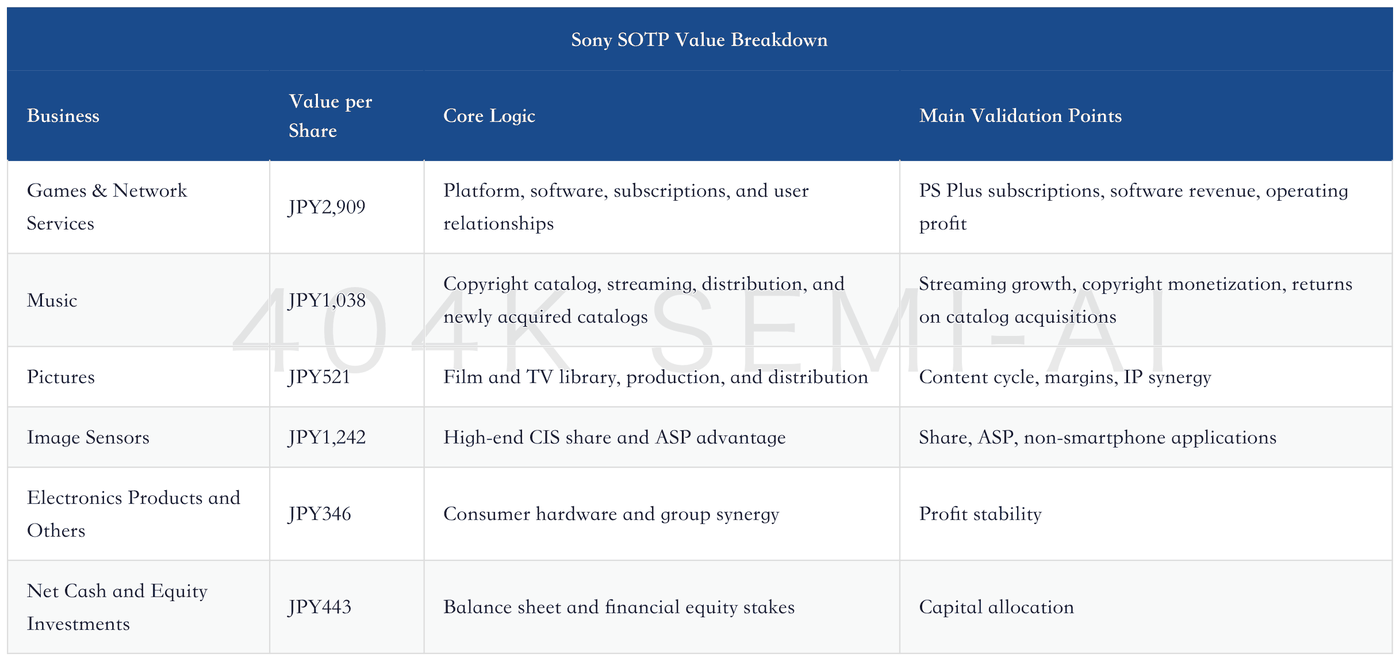
Sony is the most distinctive company in this group. It is neither a power-grid company nor an AI hardware company in the traditional sense. JPMorgan rates Sony Overweight with a JPY5,700 price target, underpinned by an SOTP re-rating: Games & Network Services, Music, Pictures, Electronics Products, Image Sensors, and financial equity stakes together form the value base. It has the largest upside, but also receives the heaviest market discount, because Sony’s business mix is too complex and its verification cadence is less direct than power-grid orders.
The core investment view on Sony is this: in the AI era, content platforms and IP assets may become more valuable again. Generative AI reduces the cost of content production and distribution, but high-quality IP, music copyrights, gaming communities, anime platforms, and film/TV libraries become scarcer. Models can generate content, but they cannot automatically own global user relationships, copyrights, characters, communities, and distribution networks. Sony happens to own these assets.
In JPMorgan’s SOTP, Games & Network Services contributes JPY2,909 per share, Sony’s largest source of value; Music contributes JPY1,038, Pictures JPY521, Image Sensors JPY1,242, plus Electronics Products, net cash, and equity investments. This breakdown shows that Sony has long since ceased to be a pure hardware company. PlayStation hardware itself is not highly profitable and may even be a drag; software, network services, subscriptions, and IP content are the core.
Music copyrights are among Sony’s most easily underestimated assets. Over the past few years, Sony has continued to acquire high-value music catalogs, including major artists and copyright portfolios. In May 2026, Sony and GIC acquired the Recognition Music Group catalog, covering roughly 45,000 songs, in a transaction valued at about USD4 billion. The investment logic for copyright catalogs resembles long-duration cash-flow assets: they may not drive a large near-term profit uplift, but once combined with streaming, short video, film and TV, gaming, and AI licensing, the commercialization paths for the copyright library multiply.
For the gaming business, the focus should be platform profit, not hardware shipments. JPMorgan’s model shows Games & Network Services revenue and operating profit continuing to improve in FY2027-2029, with PS Plus subscriptions rising steadily from the 47 million level to above 50 million. This growth rate is not spectacular, but the quality of platform revenue matters more than the hardware cycle. As long as software sales, subscriptions, network services, and first-party content profit continue to improve, Sony will look more like a platform company than a consumer-electronics company.
Image sensors are Sony’s connection point to AI hardware. In JPMorgan’s materials, Sony’s revenue share in image sensors is materially higher than its shipment share, indicating strong ASP and high-end share. In 2025, Sony’s CIS shipment share was about 25%, revenue share about 54%, and ASP about USD6.8, above major competitors. Smartphones remain the core base, but robotics, automotive, security, industrial, XR, and AI vision devices may all provide a second growth curve. What investors really need to track is not the statement that “sensors also benefit from AI,” but whether the revenue share from non-smartphone applications and ASP can remain stable.
Deep Dive on Japanese Electronic Components: AI Servers Push MLCCs from Cyclical Products Toward Compute Infrastructure
Sony’s risks are also more complex than Hitachi’s. First, the gaming hardware cycle and content investment can cause profit volatility. Second, if music copyright acquisitions are priced too aggressively, near-term returns will come under pressure. Third, the Pictures business is materially affected by project cycles. Fourth, CIS remains exposed to smartphone demand and customer mix, while non-smartphone AI vision applications have not yet fully taken over as a growth driver. Fifth, the group has many businesses, and the market needs clearer capital allocation and shareholder returns.
The judgment on Sony is this: it is the most imaginative asset in this group, but not the most suitable as a high-conviction core holding. Sony’s upside comes from SOTP discount narrowing and multiple businesses delivering at the same time. If gaming network profit, music copyright cash flow, Crunchyroll subscriptions, and high-end CIS share all improve together, valuation elasticity will be significant. Conversely, if any two core businesses fall short of expectations, the market will continue to suppress it with a conglomerate discount.
VII. Panasonic Holdings: BBU and Materials Are Options; Batteries and Portfolio Discount Are Reality
Panasonic is the most typical asset in this group with “AI optionality, but continued pressure in the core business.” JPMorgan maintains a Neutral rating with a JPY4,600 price target, close to the current share price. This rating does not deny the value of BBU, MEGTRON, and Blue Yonder; rather, it reminds investors that the optionality is not yet large enough to offset automotive batteries, automotive electronics losses, and the group discount.
BBU is Panasonic’s most direct AI data-center option. High-power AI racks require greater power continuity. Beyond traditional data-center UPS systems, rack-level or near-rack backup power is becoming more important. JPMorgan’s materials show that Panasonic is planning data-center energy storage systems, with a related revenue target approaching JPY800 billion by FY2028. If this figure translates into actual orders and revenue recognition, it would significantly change the growth curve of Panasonic’s energy business.
But BBU cannot be assessed by plans alone. First, customer qualification takes time, especially as hyperscale data centers have extremely high requirements for safety, lifetime, thermal management, and certification. Second, BBU is tied to battery systems, power electronics, rack architecture, and facility-side power design; the standardization process will affect suppliers’ bargaining power. Third, BBU margins are not necessarily high by default, depending on cell costs, system integration, customer pricing, and after-sales obligations. Fourth, if rack architecture continues to evolve, BBU form factors and installation locations may also change.
Panasonic’s second AI option is MEGTRON materials. AI servers and high-speed networks require low-loss PCB/CCL materials, and Panasonic has long-standing accumulation in high-end materials. This logic is consistent with the re-rating of Japanese electronic components, ABF, MLCCs, and CCL: the high-speed, high-frequency, high-power, and high-reliability requirements of AI servers are pushing previously cyclical materials segments toward higher value-added. But the materials business remains relatively small within Panasonic’s group scale and needs sustained volume growth before it can change overall valuation.
Deep Dive on Japanese Electronic Components: AI Servers Push MLCCs, HDD Heads, and ABF Substrates Toward 2027 Supply Anchors
Panasonic’s real constraints are in energy and automotive. The slope of the energy business in the model looks attractive, but energy margins excluding the impact of IRA still need to be verified. The automotive business remains loss-making through the model period, making it difficult for the overall group to immediately enjoy a high valuation.
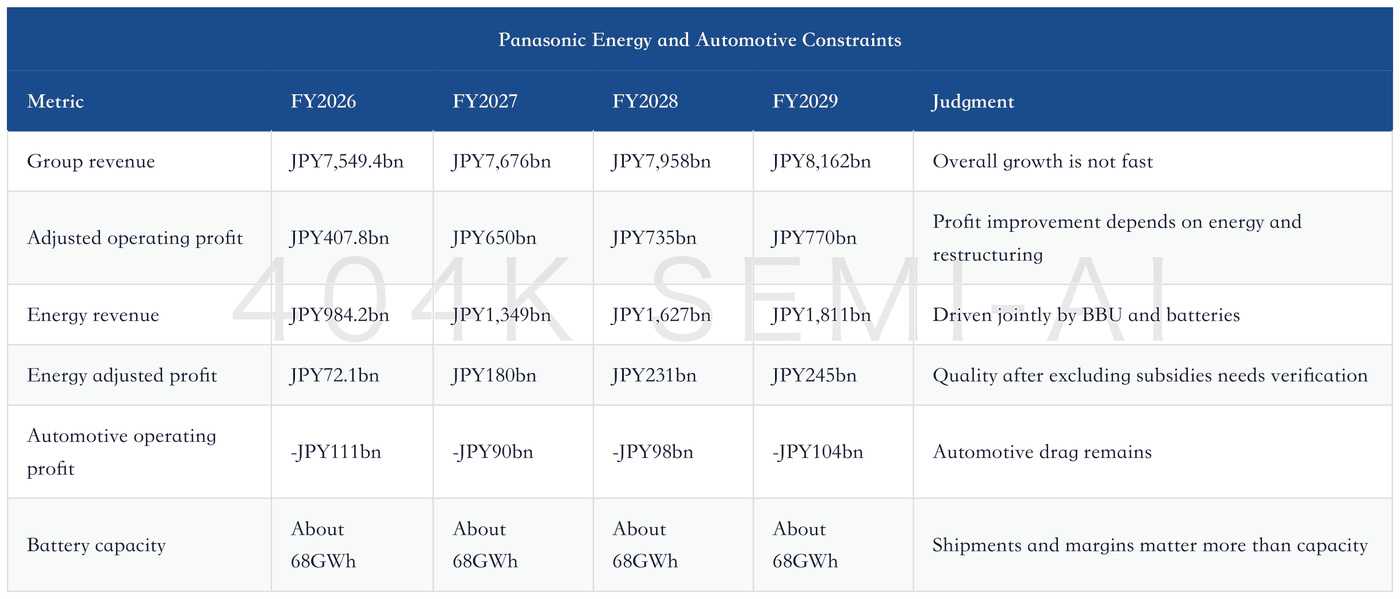
For Panasonic to move from Neutral to a more attractive stock, three conditions need to be met at the same time. First, BBU orders must move from planning to recognizable revenue, with a sufficiently high-quality customer mix. Second, the energy business must improve margins after excluding subsidies, rather than relying on policy income. Third, automotive batteries and automotive electronics must stop consuming improvements from the group’s other businesses. If any one condition is missing, the market will continue to apply a portfolio discount.
The investment conclusion on Panasonic should be disciplined. It has AI data-center optionality, as well as materials and supply-chain software assets, but these options cannot yet offset group complexity and automotive losses. It is suitable for low-weight tracking while waiting for BBU revenue, energy margins, and automotive improvement to appear simultaneously; it is not suitable for a heavy position based on the single theme of “AI data-center backup power.”
8. Portfolio Ranking: Certainty First, Then Optionality, Then Options
When looking at this group of companies together, the investment ranking cannot be based only on target-price upside, nor only on share-price performance over the past year. Over the past year, Panasonic Holdings, Seiko Group, Citizen and others have rallied sharply, while Mitsubishi Electric has also significantly outperformed. Hitachi, NEC, Fujitsu and Sony have been less strong relative to TOPIX. Near-term share prices have already pulled forward part of the story; what matters next is earnings delivery.
The portfolio ranking should be built around three questions. First, has AI capex become clearly identifiable revenue? Second, can that revenue translate into higher margins? Third, has valuation already fully priced this in? Hitachi is the strongest on the first and second questions, while valuation still has upside. Mitsubishi Electric has multiple entry points on the first question, but valuation already partly reflects this. Sony is the most attractive on the third question, but validation of the first and second questions is more complex. NEC and Fujitsu depend on margin delivery. Panasonic depends on option value being realized.
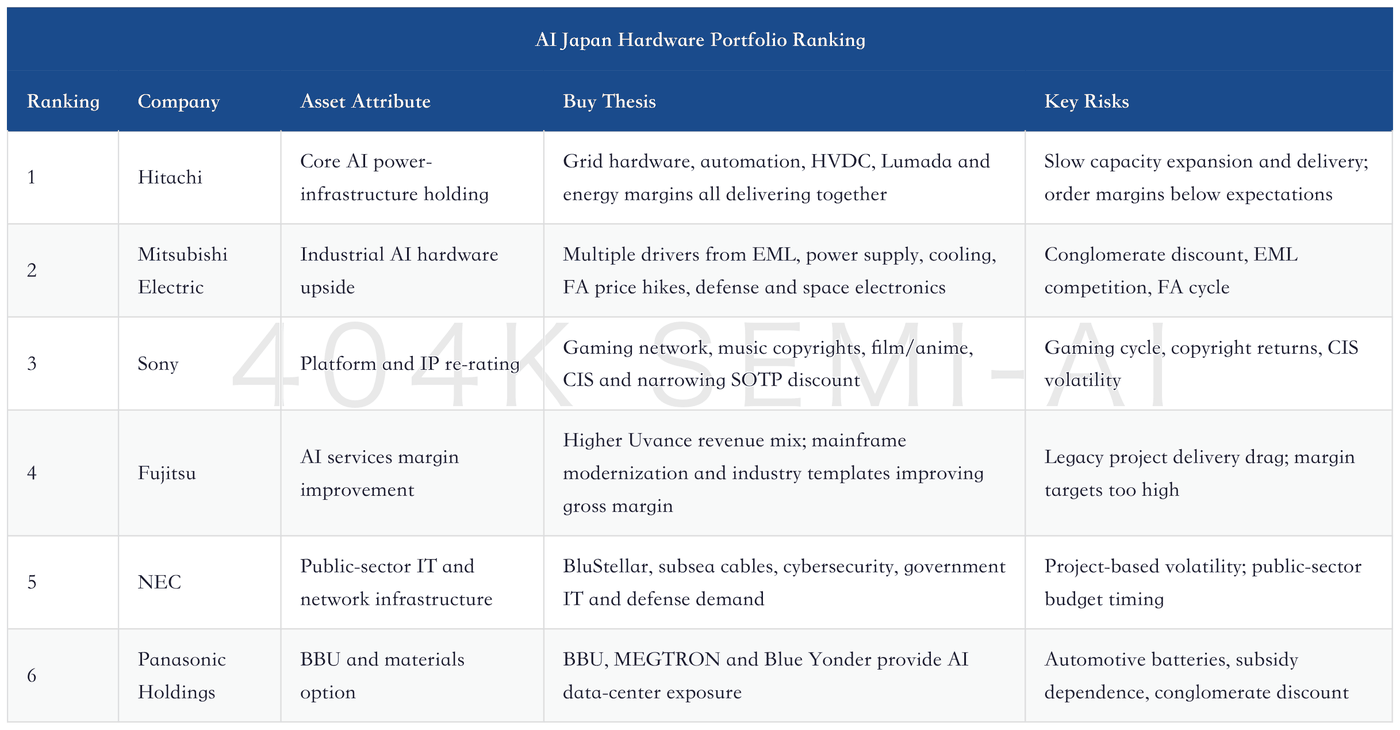
The core of this ranking is to first buy the bottlenecks that AI buildout must solve. Hitachi’s grid assets and Mitsubishi Electric’s EML/power-supply exposure are bottleneck assets. Sony is not an infrastructure bottleneck, but it owns global content and user platforms, making it a scarce asset in AI-driven content diffusion. NEC and Fujitsu are closer to margin-improvement plays as AI applications are implemented. Panasonic still needs to wait for its options to turn from narrative into orders.
In terms of portfolio weights, Hitachi can be the core holding, Mitsubishi Electric and Sony the upside positions, NEC and Fujitsu lower-weight allocations, and Panasonic a name to wait on for signals. This portfolio is more reasonable than simply buying an “AI Japan technology ETF,” because the asset quality and AI exposure of Japanese technology companies vary too widely.
It is worth noting that traditional consumer-electronics and printing-related companies are not part of the core ranking. Canon, Ricoh, Casio, Seiko Epson, Sharp and others are not without improvement opportunities, but their AI capex transmission is weak. They are still driven more by their own product cycles, cost control, exchange rates and portfolio restructuring. The market may give them periodic valuation repair, but it is hard to assign them the same AI premium as Hitachi, Mitsubishi Electric and Sony.
9. Three Scenarios: Which Path Delivers the Japan Hardware Re-rating?
The re-rating of Japanese hardware assets can be split into three scenarios. The first is a continuing power bottleneck, where AI data-center construction remains constrained by transformers, switchgear, HVDC, backup power and site-level power management. The second is accelerated upgrades in optical networks and rack systems, where 1.6T optical modules, EML, power supply, cooling and high-frequency materials become new value pools. The third is AI applications spreading from cloud training to enterprises, governments, manufacturing, content platforms and Physical AI, with SI services, content IP and sensor platforms beginning to deliver profits.
These three scenarios are not mutually exclusive, but they have a major impact on company rankings. In the power-bottleneck scenario, Hitachi is the strongest, while Mitsubishi Electric and Panasonic also benefit. In the optical-network and rack-upgrade scenario, Mitsubishi Electric, Panasonic’s materials business and the Japanese electronic-components chain are better positioned. In the AI-application diffusion scenario, Sony, Fujitsu, NEC and Hitachi Lumada have more room to perform. The portfolio should avoid putting all positions on the same path.
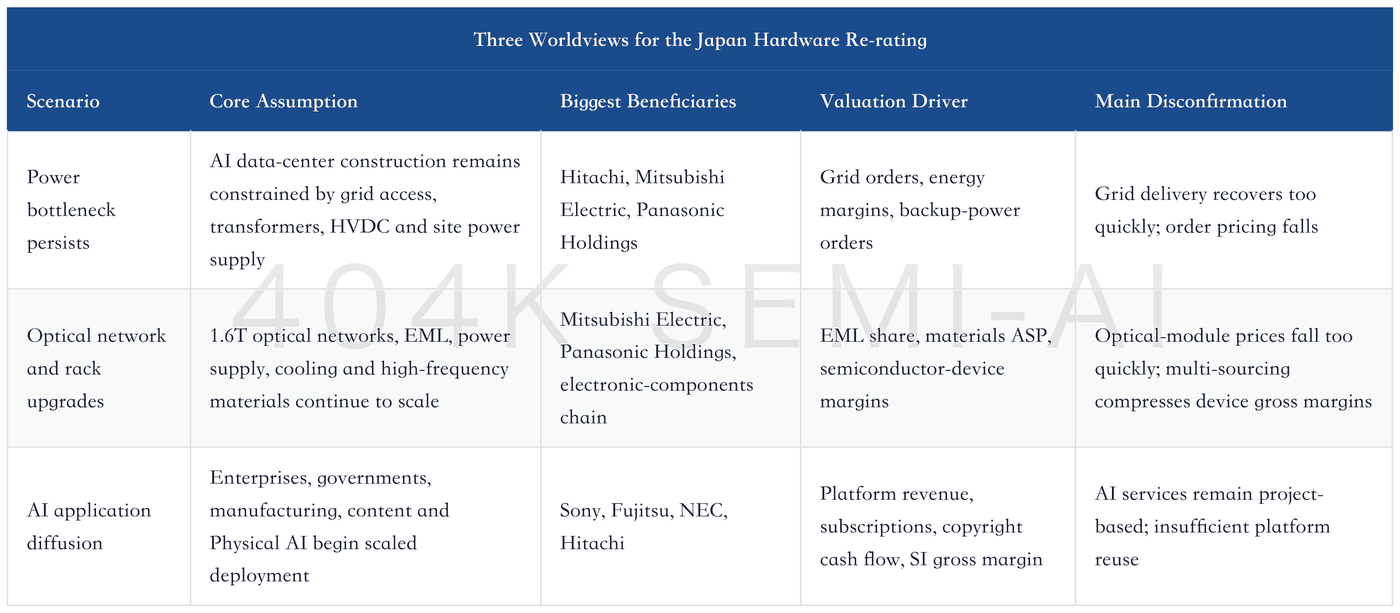
The advantage of the power-bottleneck scenario is that it is the easiest to verify. Order backlog, revenue recognition, capacity-expansion plans, project gross margins and free cash flow can all be tracked quarter by quarter. Hitachi has the highest certainty here because it has grid equipment, automation, software and Lumada at the same time. Mitsubishi Electric can benefit from power supply, cooling and infrastructure. Panasonic’s BBU can also benefit, but it needs to prove that it is not merely a battery supplier, and that it can enter rack and data-center power systems.
The optical-network and rack-upgrade scenario has higher upside. Once the AI server bottleneck spills over from GPUs into switching, optical interconnects, power conversion, cooling and materials, the value chain will spread into more hardware segments. Mitsubishi Electric’s EML has a direct benefit logic. Panasonic’s MEGTRON materials have an indirect benefit logic. Japan’s electronic-components chain will also benefit from requirements for high reliability, high frequency, high power and miniaturization. The risk in this scenario is pricing: once high-speed optical modules and devices move quickly into oversupply, revenue growth may be offset by ASP declines.
The AI-application diffusion scenario is the hardest to verify, but it also has a high ceiling. Sony’s music, film, gaming, anime and image sensors are, in essence, content and data entry points in the AI era. The service platforms of Fujitsu, NEC and Hitachi are tools for implementing AI in enterprises and the public sector. This scenario requires more time, because the path from pilots to deployment, and from deployment to profit recognition, is usually slower than hardware orders. It is better suited to longer-duration valuation, not chasing single-quarter news.
The “price framework” also needs to be clarified. The target prices in JPMorgan’s table come from the same model, on the same day, in the same currency and for the same share trading units, so the internal comparison basis is relatively consistent. But target-price upside across different companies cannot be equated directly with recommendation strength. Sony has the highest target-price upside because its SOTP discount is large and its platform assets have high valuation elasticity. Hitachi has somewhat lower upside, but much stronger order visibility. Panasonic’s target price is almost in line with the current price because its AI option is still offset by drag from batteries and automotive electronics.
A more practical portfolio framework would be to treat Hitachi as the “high-certainty core holding,” Mitsubishi Electric as “AI hardware diffusion upside,” Sony as “platform discount repair,” Fujitsu and NEC as “AI services margin improvement,” and Panasonic as a “BBU realization option.” What the portfolio really needs to guard against is not one company underperforming in the short term, but holding a group of positions with different names that are all, in substance, exposed to the same risk. Power, optical networks, platform services and IP should ideally be tracked separately.
This scenario framework has another implication: if AI capex sees a temporary slowdown in the future, Hitachi and Mitsubishi Electric should be more defensive than the pure server chain. Grid and defense demand have longer cycles, and enterprise IT modernization will not disappear entirely with one quarter of GPU order volatility. Conversely, if AI capex continues to be revised upward, the greatest upside may come from Mitsubishi Electric and Sony: one driven by optical networks and industrial hardware, the other by narrowing discounts on platform and content assets.
10. Capability Migration: How Old Japan Manufacturing Connects to AI Capex
The easiest way to underwrite this rerating of Japanese hardware too superficially is to see only “incremental demand from AI” and miss the migration in corporate capabilities. Hitachi, Mitsubishi Electric, Sony, NEC, Fujitsu, and Panasonic are not new companies, nor did they suddenly start doing AI from scratch. Their rerating comes from old capabilities being repriced by new demand: grid engineering, industrial control, optical devices, mainframe systems, content distribution, copyright operations, precision manufacturing, and battery materials used to map to separate mature markets. Now AI capex is reconnecting them into one value chain.
Hitachi’s capability migration is the clearest. Old Hitachi was a heavy electrical equipment, rail, industrial systems, and large-project company, with valuation easily constrained by cyclicality, project execution, and group complexity. The key to new Hitachi is turning these social-infrastructure scenarios into a combination of grid hardware, dispatch software, industrial data, and Lumada services. AI data centers are not bringing a single isolated order; they are driving simultaneous increases in power-system expansion, load management, equipment delivery, and digital O&M.; If Hitachi can keep energy margins, Lumada’s revenue mix, and portfolio optimization on the same upward curve, its valuation should move closer to an infrastructure platform than a traditional equipment company.
Mitsubishi Electric’s migration looks more like “industrial hardware moving from cyclical to structural.” Factory automation, buildings, air conditioning, semiconductor devices, and defense were originally quite fragmented, making it hard for investors to give them a unified narrative. AI data centers connect several of these lines: EML maps to high-speed optical interconnects, UPS and cooling map to rack infrastructure, FA maps to the recovery in automation investment, and defense and space electronics map to longer-cycle orders. Mitsubishi Electric’s challenge is to turn multiple opportunities into margins, rather than letting each business tell its own story. As long as semiconductor devices and infrastructure can lift group margins, it can move from an ordinary industrial cyclical stock to a higher-beta asset for the diffusion of AI hardware.
Sony’s migration is happening at the level of asset perception. The market has tended to see Sony as a game console, camera, TV, headphone, and consumer-electronics brand, but Sony’s real scarcity lies in the combination of global IP, content production, distribution, subscriptions, gaming networks, and image sensors. AI will lower the threshold for ordinary content production, but it will also amplify the value of high-quality IP and platforms, because user attention, copyright licensing, character assets, and community relationships are harder to replicate. Whether Sony can rerate depends on whether it can prove that gaming networks, music copyrights, anime platforms, and high-end CIS share are not isolated businesses, but a set of global content infrastructure capable of continuously generating cash flow.
NEC and Fujitsu’s migration will test execution the most. The biggest problem with traditional SI companies is that they have deep customer relationships, but their delivery models are too labor-intensive, and revenue growth is easily consumed by labor costs. AI gives them an opportunity to convert industry knowledge, mainframe modernization, government IT, communications networks, security, and enterprise processes into reusable solutions. If NEC’s BluStellar and Fujitsu’s Uvance are only new labels for selling projects, valuations will not change much. If they can turn industry templates, data governance, AI agents, and cloud migration into higher-gross-margin platforms, the market will reassess the margin ceiling of Japanese IT services companies.
Panasonic’s migration requires the most patience. Its old assets include batteries, materials, home appliances, automotive electronics, and supply-chain software, as well as many businesses that weigh on the group’s valuation. AI data centers have opened entry points into BBUs, low-loss materials, and energy systems, but those entry points still need orders, customer adoption, and margin proof. Panasonic is not already positioned on the main grid value chain like Hitachi, nor does it have the more direct beta in EML and industrial power supply that Mitsubishi Electric has. It is more like a portfolio rerating asset waiting for options to pay off. Only when BBUs and materials materially change the profit structure of the energy business will Panasonic’s discount have a real basis to narrow.
This is also why this line should be bought based on company capability migration, not keywords. In Hitachi, one is buying the migration of grid and digital infrastructure. In Mitsubishi Electric, one is buying the diffusion of industrial hardware into AI data centers and defense. In Sony, one is buying the IP and platform under the consumer-electronics shell. In Fujitsu and NEC, one is buying the migration of traditional SI toward platform margins. In Panasonic, one is buying energy and materials optionality. Every company must use its old capabilities to capture new AI demand. Companies that cannot migrate can only remain in theme-driven trading.
This line has another easily overlooked benefit: most Japanese companies have already experienced a long period of low valuation, low capital efficiency, and conglomerate discount, so market expectations for them are not perfect. As long as AI capex can turn some old assets back into growth assets, valuation repair does not need to rely on extremely optimistic assumptions. Hitachi’s grid, Mitsubishi Electric’s EML, Sony’s IP, and NEC and Fujitsu’s industry services are all new slopes growing out of old assets. This kind of rerating is slower than pure concept stocks, but it is also easier to validate continuously through orders, margins, and cash flow.
What must be avoided is mixing “low-valuation Japanese assets” and “AI-related assets” into one basket. Low valuation only provides margin of safety; AI relevance only provides imagination. Only when both turn into profit and cash flow is the rerating sustainable. Hitachi and Mitsubishi Electric are validated more through hardware, Sony through platform quality, NEC and Fujitsu through service margins, and Panasonic through option realization. These paths are different, which is why they can all be retained in a portfolio, but each position should have its own tracking indicators.
This also determines the trading rhythm. Hardware-constrained assets are best confirmed through order and delivery trends; platform assets through profit quality and discount repair; option assets require revenue and cash flow to truly penetrate the group financial statements.
This determines the final ranking.
11. From GPUs to the Grid, the Asset Attributes of Japanese Hardware Are Migrating
In the first stage of AI capex, capital bought GPUs, HBM, advanced packaging, server ODMs, and optical modules. In the second stage, capital began buying power supply, liquid cooling, transformers, data-center land, generation, and networks. In the third stage, capital will continue to diffuse into system integration, software platforms, data security, content assets, and Physical AI. Japanese hardware companies have a stronger presence in the second and third stages.
Hitachi maps to “power infrastructure rerating.” It most resembles the conversion of traditional heavy electrical assets from cyclicals into admission tickets for AI buildout. Mitsubishi Electric maps to “industrial hardware upgrade.” It combines EML, power supply, cooling, FA, defense, and space electronics into multi-point beta. NEC and Fujitsu map to “enterprise and public-sector AI implementation.” Their validation point is not theme exposure, but margins. Sony maps to a “content and sensor platform.” Its asset attributes are closer to global IP and a user platform. Panasonic maps to “backup power and materials optionality.” It needs to prove that the option is large enough to offset the group discount.
This migration also explains why the Japanese market will diverge. In the past, yen depreciation and governance improvement could lift many Japanese stocks together. Going forward, the market will be more selective. Only companies that can win direct AI capex orders, raise margins, sustain buybacks, and optimize portfolios deserve higher valuations.
For investors, there are two most dangerous misjudgments. The first is treating all Japanese electronics companies as AI assets. The second is looking only at short-term share-price strength and not whether asset attributes have already changed. Mitsubishi Electric and Panasonic have risen strongly over the past year, showing that the market has already recognized part of the story in advance. Hitachi and Sony’s relative performance has been less strong, which may instead indicate that the market is still waiting for clearer profit validation. Valuation is not an independent variable; it must be viewed together with evidence.
12. Why Traditional Consumer Electronics and the Printing Chain Are Not in the Core
JPMorgan’s coverage also includes a group of companies that can be pulled along by thematic trading, including Seiko Epson, Canon, Ricoh, Casio, Sharp, Citizen Watch, and Seiko Group. They each have their own cyclical, cost, product-refresh, and governance-improvement opportunities, but they should not be placed on the same AI main line as Hitachi, Mitsubishi Electric, Sony, NEC, and Fujitsu. The reason is simple: AI capex transmission is not direct enough, and margin validation is not hard enough.
Seiko Epson’s Underweight rating best illustrates the boundary. Printing, projection, commercial printing, and consumer electronics can deliver cost control and may benefit from FX or cyclical recovery, but they lack a clear bridge to AI data-center construction. As long as revenue growth still mainly comes from mature hardware and channels, valuation is unlikely to be structurally lifted by AI infrastructure. A target price below the current share price reflects that the market has already granted some recovery, while earnings and asset attributes have not upgraded in parallel.
Canon and Ricoh are similar. Office equipment, cameras, printing, and IT services all have stable cash flow, but the variables that can truly drive a market rerating need to come from new growth curves, margin improvement, or capital allocation. AI can improve image processing, office automation, and enterprise processes, but these benefits are more like efficiency gains. They do not directly bottleneck AI capex in the way grids, EML, BBUs, and submarine cables do. Stability does not equal rerating, and good cash flow does not mean a company will receive an AI multiple.
Sharp’s case is more complicated. It may have value in displays, equipment, brand, and restructuring, but historical baggage, profit volatility, and competitive position make it hard for investors to assign high certainty. If the AI theme only brings a round of valuation imagination without orders, margins, and cash flow, pricing will ultimately return to asset quality. For these companies, the most important question is not whether there is an AI story, but whether there is sufficiently strong asset disposal, cost restructuring, product upgrade, or shareholder return.
Citizen Watch and Seiko Group have risen strongly over the past year, reflecting more of consumption, FX, brands, governance, and low-valuation repair. They can be part of Japanese market style rotation, but they are hard to include in an AI infrastructure portfolio. Profit improvement in watches, precision parts, and branded businesses can bring valuation repair, but it does not make them direct picks-and-shovels beneficiaries of AI capex. Including these companies in the core portfolio would dilute the investment theme and make tracking indicators more confused.
The screening standard for the core portfolio should remain strict. First, the company must have a clear AI capex entry point, at least in one of power, networks, power supply, SI services, content platforms, sensors, or materials/backup power. Second, this entry point must be able to affect group profit, not just a small business line. Third, there must be verifiable data over the next four quarters. Fourth, valuation cannot rely only on story; it must be explainable through SOTP, margins, or order slope.
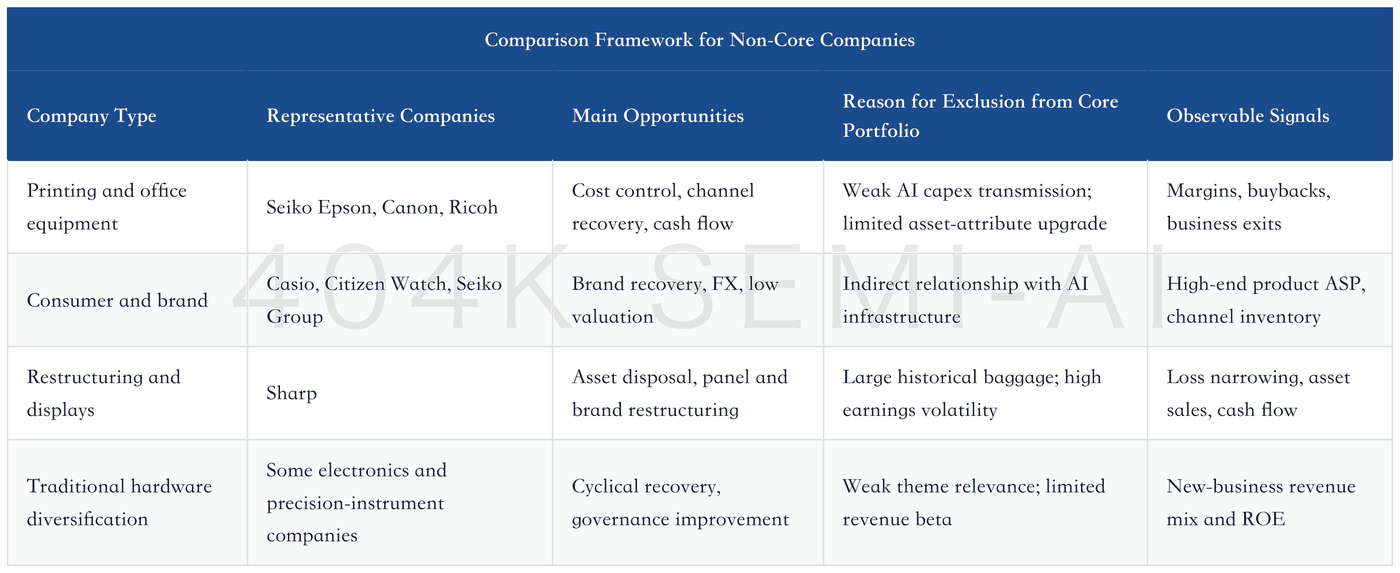
This boundary matters for investing. The easiest mistake in AI thematic trading is putting every company that can describe an AI use case into the portfolio. Useful screening does not ask whether a company can talk about AI, but whether AI demand has changed its revenue structure, margins, and capital returns. Hitachi, Mitsubishi Electric, Sony, NEC, Fujitsu, and Panasonic can at least provide trackable answers to these questions. Traditional printing, consumer electronics, and brand assets are more part of Japanese market repair than the AI infrastructure main line.
Therefore, the core portfolio should not seek maximum coverage, but the strongest evidence chain. Holding fewer companies with weak themes, slow validation, and small earnings beta makes the portfolio clearer. Once these companies truly show new orders, new products, new margins, and new capital allocation, it will not be too late to raise allocation weights.
XIII. Falsification Checklist: How to Track This Theme
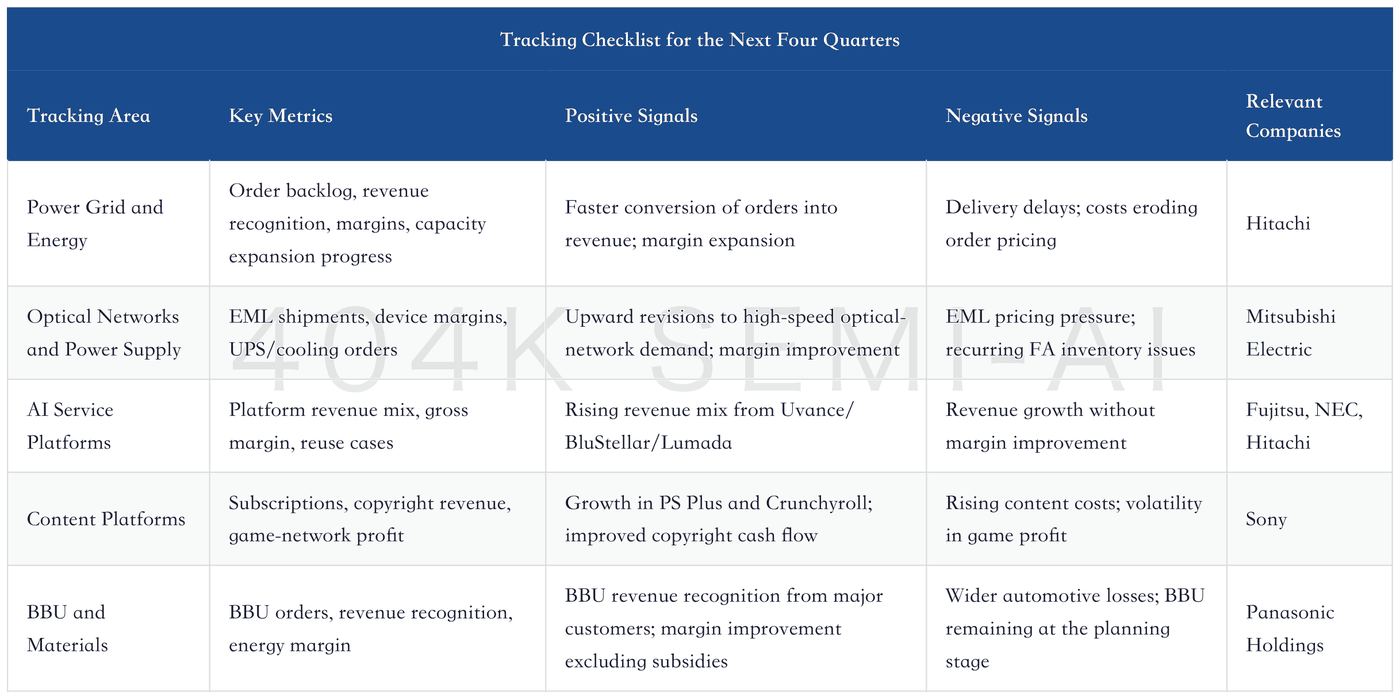
This Japanese hardware re-rating theme should not be tracked through a single news catalyst. It should be monitored quarterly across four sets of indicators.
The first set is the power grid. Track Hitachi Energy’s order backlog, delivery lead times, transformer and high-voltage equipment capacity, energy business revenue growth, adjusted margin in energy, and Lumada revenue mix. If orders remain strong but do not convert into revenue, or revenue converts but margins do not improve, it means grid expansion is being absorbed by costs and delivery constraints.
The second set is optical networks and power supply. Track Mitsubishi Electric’s EML shipments, optical-network customer demand, semiconductor device margins, data-center power and cooling orders, FA pricing, and defense orders. If EML competition intensifies, pricing declines, or the FA cycle drags more than AI contributes, Mitsubishi Electric will struggle to continue benefiting from valuation upgrades.
The third set is AI services. Track the revenue mix, gross margin, reuse rate, and major-customer cases for NEC BluStellar, Fujitsu Uvance, and Hitachi Lumada. If revenue is built up through low-margin projects, the market will cut margin expectations. The key for AI services is not how many conceptual partnerships are signed, but whether the same industry templates can be repeatedly sold to more customers.
The fourth set is platforms and optionality. For Sony, track PS Plus subscriptions, game-network profit, music-copyright cash flow, Crunchyroll subscriptions, CIS revenue share, and non-smartphone applications. For Panasonic, track BBU orders, energy-business margin excluding subsidies, automotive-battery shipments, and losses in the automotive business. Sony needs multiple businesses to deliver at the same time; Panasonic needs its option businesses to become large enough.
The final judgment can be condensed into one sentence: the opportunity in Japanese technology hardware is not the broad label of “Japanese electronics,” but the re-pricing of bottleneck assets after the spillover of AI capex. Hitachi and Mitsubishi Electric rely on hardware constraints, Sony relies on platforms and IP, NEC and Fujitsu rely on AI-service margins, and Panasonic relies on BBU and materials optionality. The companies truly worth buying are not those that sound most like AI, but those that can translate AI demand into orders, margins, and cash flow.Repricing Japanese Hardware Assets: How Hitachi Grid, Mitsubishi Electric EML, Sony IP, and Panasonic BBU Connect to AI Capex
目录
Too Long; Didn’t Read
1. The Main Line in Japanese Tech Stocks Is Shifting from Consumer Electronics to AI Infrastructure
II. Core Model: Do Not Buy as “Electronics Stocks”; Buy as “AI Bottlenecks”
III. Hitachi: The Power Grid Is the Hardest Infrastructure Constraint in the AI Era
IV. Mitsubishi Electric: EML, Power Supply, Defense, and FA Jointly Support Resilience
V. NEC and Fujitsu: Traditional SI Needs to Turn Man-Day Projects into Platform Profit
VI. Sony: IP, Platforms, and Sensors Determine Whether It Is a Different Kind of AI Asset
VII. Panasonic Holdings: BBU and Materials Are Options; Batteries and Portfolio Discount Are Reality
8. Portfolio Ranking: Certainty First, Then Optionality, Then Options
9. Three Scenarios: Which Path Delivers the Japan Hardware Re-rating?
10. Capability Migration: How Old Japan Manufacturing Connects to AI Capex
11. From GPUs to the Grid, the Asset Attributes of Japanese Hardware Are Migrating
12. Why Traditional Consumer Electronics and the Printing Chain Are Not in the Core
XIII. Falsification Checklist: How to Track This Theme
本内容基于公开资料和研报数据整理,不构成任何投资建议,不代表任何个人观点,仅供学习参考,请理性阅读
AI capex is spilling over from GPUs into power grids, optical networks, systems integration, content platforms, and backup power. The divergence in Japanese electronics stocks is not about whether consumer electronics recover, but about which companies can turn these incremental drivers into sustained margin expansion and valuation premia. JPMorgan prefers Hitachi, Mitsubishi Electric, NEC, Fujitsu, and Sony, while Panasonic is more of an option asset.
Too Long; Didn’t Read
Japanese hardware is entering a second screening phase. The first round of Japanese tech-stock rerating was about the yen, governance, buybacks, and cyclical recovery. The second round is about where AI capex actually flows. Hitachi, Mitsubishi Electric, NEC, Fujitsu, and Sony share one trait: they sit in the non-GPU segments of AI infrastructure, including power grids, optical networks, systems integration, content platforms, and high-end sensors. Panasonic has BBU and materials options, but automotive batteries and a conglomerate discount still weigh on valuation.
Hitachi is the most complete infrastructure asset. AI data-center power density is moving from around 10kW per rack in the A100/H100 era to 120-140kW for GB200/GB300, and then to megawatt-class racks for Rubin Ultra. The bottleneck will shift from GPUs to grids, transformers, switchgear, HVDC, and dispatch software. Hitachi Energy has grid hardware, automation, software, and Lumada digitalization, giving it the clearest revenue and profit slope in energy for FY2026-FY2029.
Mitsubishi Electric needs to prove EML can lift profits. AI server expansion is pushing the data-center optical interconnect market from roughly $4 billion toward roughly $20 billion. Mitsubishi Electric has a strong position in data-center EML lasers. UPS, data-center cooling, FA price increases, defense export liberalization, and space electronics also provide profit upside. The real validation point is whether these exposures can continue to raise the traditional industrial-company operating-margin ceiling above 10%.
SI services depend on platformized margins. NEC’s BluStellar, Fujitsu’s Uvance, and Hitachi’s Lumada are all moving traditional systems integration from project-based delivery toward industry templates, software reuse, and AI agents. In JPMorgan’s model, Fujitsu’s service-solutions margin can reach 21.2% by FY2029, while NEC’s non-GAAP operating margin also continues to rise. Whether valuations can keep moving higher depends on whether these businesses truly escape the old model of low-gross-margin, headcount-based delivery.
Sony’s asset base is platforms and IP. Sony’s rerating variables are gaming networks, music rights, film and television, anime platforms, image sensors, and IP synergies. In SOTP, Game & Network Services, Music, Pictures, and sensors together contribute the vast majority of value. Sony has the largest upside, but the validation cycle is also slower: PS platform profits, Crunchyroll subscriptions, music-rights monetization, and sensor growth outside smartphones need to materialize together over several consecutive quarters.
Panasonic is more like a discounted asset with options. BBU, MEGTRON materials, and Blue Yonder allow Panasonic to participate in AI data centers, but automotive-battery profits, the true profitability of the energy business after IRA adjustments, automotive-electronics losses, and the conglomerate discount remain hard constraints. The buying point for Panasonic is whether BBU orders can move from the planned scale of roughly JPY800 billion into revenue recognition, while automotive batteries stop absorbing improvements elsewhere in the portfolio.
Portfolio ranking should prioritize certainty. In ranking terms, Hitachi is better suited as a core holding; Mitsubishi Electric is industrial AI hardware beta; Sony is an IP and platform rerating story; NEC and Fujitsu are AI-service margin-improvement plays; Panasonic is only suitable once BBU and energy profits actually materialize. The bear case rests on four sets of numbers: grid orders and deliveries, EML and optical-network demand, SI platform gross margins, and BBU revenue plus energy-business margins after subsidies.
1. The Main Line in Japanese Tech Stocks Is Shifting from Consumer Electronics to AI Infrastructure
Japanese electronics stocks used to be easy to put into one large basket: consumer electronics, office equipment, cameras, printers, FA, heavy electrical equipment, home appliances, and precision instruments. That classification was still barely workable in the previous cycle, because the market cared most about the yen, inventories, global consumer-goods demand, and corporate governance. But AI capex has dismantled that framework. The truly valuable Japanese hardware assets are no longer defined by the label “Japanese electronics,” but by whether they can capture the bottlenecks squeezed out of AI infrastructure by GPUs.
The most valuable aspect of this JPMorgan coverage model is that it does not simply describe Japanese tech stocks as an “AI beneficiary basket.” It breaks the AI value chain into power, networking, computing, foundation models, generative/agentic AI, and Physical AI, then maps Japanese companies into those positions: Hitachi corresponds to power grids and Lumada; Mitsubishi Electric to data-center power supply, cooling, and EML optical devices; NEC to submarine cables and BluStellar; Fujitsu to CPUs, quantum, Uvance, and AI services; Panasonic to BBU, CCL materials, and supply-chain software; and Sony to content creation, platforms, and image sensors.
This breakdown matters. GPUs themselves still carry the greatest value, but capital markets are already very familiar with GPUs, HBM, advanced packaging, and CSP capex. The next stage of excess returns is more likely to appear in segments that were previously treated as old economy, but have suddenly become constraints on the pace of AI buildout. Power grids are not new. Transformers are not new. Submarine cables, EML, UPS, BBU, and SI services are not new either. What AI changes is demand visibility, pricing power, and asset characteristics in these segments.
The rerating of Japanese hardware assets can be divided into three categories. The first is hard-constraint assets, such as Hitachi Energy’s grid equipment and software, Mitsubishi Electric’s EML and power-supply systems, and NEC’s submarine cables. These segments directly affect whether AI data centers can be energized, interconnected, and connected for cross-regional data transmission. The second is margin-improvement assets, such as NEC, Fujitsu, and Hitachi’s AI-platformized SI services. They do not directly sell rack hardware, but they can convert AI applications, industry templates, cloud migration, and mainframe modernization into higher-margin service revenue. The third is platform and IP assets, such as Sony. It is not a picks-and-shovels supplier of AI compute, but it may benefit from the long-term value created by AI diffusion in content generation, gaming networks, anime platforms, and image capture.
The real area to watch is the fourth category: narrative without a profit entry point. Traditional consumer electronics, printers, low-end hardware, and companies with high portfolio complexity can rise briefly during thematic rallies if they cannot provide a clear AI revenue, margin, or cash-flow path, but they tend to return to their prior valuation discounts. This is the logic behind JPMorgan’s underweight rating on Seiko Epson and neutral ratings on Canon, Ricoh, Casio, and others: not every Japanese electronics company can be repriced because of AI.
II. Core Model: Do Not Buy as “Electronics Stocks”; Buy as “AI Bottlenecks”
The valuation ranking from this coverage model is quite interesting. Sony has the largest upside implied by the target price. Hitachi, NEC, and Fujitsu also have more than 20% upside. Mitsubishi Electric has relatively lower upside, but its business elasticity and AI exposure are more direct. Panasonic’s target price is essentially close to the current price, suggesting the AI option is not yet sufficient to offset the conglomerate discount and pressure in the battery business.
From a risk-reward perspective, Hitachi looks most like a high-conviction core asset, Mitsubishi Electric most like a hardware elasticity asset, Sony most like a platform re-rating asset, NEC and Fujitsu are margin-improvement assets, and Panasonic is an option asset. This ranking matters more than simply looking at target-price upside. Sony’s model upside is large, but realization requires evidence from multiple businesses at the same time. Hitachi’s target-price upside is lower than Sony’s, but it is easier to verify continuously through orders, revenue, margins, and buybacks.
This table should not be interpreted mechanically as “Sony is the cheapest and Panasonic is the most expensive.” Sony’s P/E is low and target-price upside is high, but its value decomposition depends on SOTP: Game & Network Services, music, pictures, electronics products, image sensors, financial equity interests, and net cash together make up the target price. The market discount on Sony partly comes from its group structure, and partly from the gaming hardware cycle, content investment, and sensor volatility. Hitachi and Mitsubishi Electric are easier to place within an industrial and infrastructure framework, and their verification cadence is clearer.
JPMorgan applies different SOTP discounts and premiums to the three companies. This distinction matters more than the target prices themselves: Hitachi receives an infrastructure premium, Mitsubishi Electric remains constrained by a conglomerate discount, and Sony’s discount comes from its complex platform portfolio.
In portfolio terms, the best allocation here is not to buy all six companies equally, but to tier them by verification difficulty. The first tier is Hitachi, because its AI infrastructure exposure overlaps with the traditional power-grid supercycle, and orders, revenue, margins, and capital returns can validate one another. The second tier is Mitsubishi Electric and Sony: the former is AI optical-network and industrial power-supply hardware; the latter is a re-rating of IP platform and sensor value. The third tier is a low-weight allocation to NEC and Fujitsu, pending further delivery in SI services margin data. The fourth tier is only an option position in Panasonic, unless BBU and energy margins truly change the group’s cash-flow structure.
III. Hitachi: The Power Grid Is the Hardest Infrastructure Constraint in the AI Era
Hitachi is the most complete AI infrastructure asset among this group of Japanese hardware companies. Its core value is not that it “has an AI software platform,” but that it can form a closed loop across power-grid hardware, dispatch software, systems integration, and industrial data platforms. As AI data-center power density continues to rise, the real scarcity is not any single component, but end-to-end delivery capability across power generation, transmission and distribution, transformers, switchgear, HVDC, site dispatch, and the data-center load side.
Nvidia’s rack roadmap provides very direct context for this view. In the A100 and H100/H200 eras, per-rack power was still in the single digits to around 10kW. GB200 NVL72 has reached 120kW, and GB300 NVL72 rises further to 140kW. If Rubin Ultra moves toward megawatt-scale racks, the value of power-related content will rise significantly. In JPMorgan’s materials, Rubin Ultra’s per-rack power-related content value is estimated at USD 561,000, including about USD 188,000 for PSUs and about USD 373,000 for other components within the power architecture. The exact numbers may change, but the direction is clear: AI hardware value is starting to spill over from GPU boards into power-supply systems.
Hitachi’s advantage is that it does not only sell one transformer or one software module. Hitachi Energy already has strong positions in grid automation, Grid Integration, high-voltage equipment, and transformers, with products and services covering a large number of utilities globally. The company’s disclosed capacity-expansion plans also show that by around 2030, dry capacitors, valves, switchgear, semiconductors, conventional power transformers, HVDC transformers, and other segments will all see significant expansion. Announced cumulative investment exceeds USD 6.25 billion, including global transformer capacity, transmission and distribution, R&D;, and critical components.
This type of expansion is the easiest to underestimate. The market often treats grid orders as part of the traditional heavy electrical equipment cycle, but AI data-center demand has different characteristics. First, customers care more about delivery speed and reliability, and are unwilling to sacrifice delivery windows for lower prices. Second, supply cycles for transformers, switchgear, HVDC, and automation software are long, making it difficult to expand capacity quickly through price competition in the short term. Third, AI data centers have high loads, concentrated power consumption, and high redundancy requirements, which raise demands on grid interfaces and site dispatch. Hitachi’s hardware and software portfolio happens to place “equipment delivery” and “operating efficiency” within the same framework.
Hitachi’s second layer of value is Lumada. Many companies talk about AI services, but Hitachi’s Lumada is not a standalone software business. It is a reuse platform for data across industry, energy, rail, manufacturing, and social infrastructure. In JPMorgan’s model, Lumada revenue rises from 39% of total revenue in FY2026 to 50% in FY2028, while Lumada’s share within the energy business also rises from 24% to 30%. If these targets are achieved, Hitachi’s valuation will no longer be only heavy electrical equipment, but a composite asset of “hardware delivery + operating data + industry software.”
GlobalLogic is also part of this logic. It has around 20,000 employees, multiple co-creation centers and delivery bases, and more than 400 customers. Historically, it has been able to achieve relatively high adjusted EBITDA margins. Placing this type of digital-engineering capability into Hitachi’s energy, industrial, and transportation customers is not just about selling more IT services. It extends the operations, optimization, and digitalization revenue that follows one-off equipment sales.
Hitachi’s risks are also clear. The first is the pace at which orders convert into revenue. Grid orders are strong, but delivery cycles for high-voltage equipment and transformers are long. If capacity expansion, components, and project execution cannot keep pace, revenue recognition will lag. The second is whether margins can improve as modeled. Heavy electrical equipment expansion may bring labor, materials, and supply-chain pressure; good order pricing does not mean every project can generate high gross margins. The third is the quality of Lumada revenue. The market needs to see that this is not simply traditional IT projects being renamed, but genuinely higher reuse rates and margins.
The view on Hitachi can be reduced to one sentence: it is not the most glamorous stock in AI hardware, but it may be the stock in Japan’s market that most resembles a core holding in “AI power infrastructure.” As long as energy orders keep expanding, margins continue rising, and Lumada’s revenue contribution keeps increasing, the valuation premium has support.
IV. Mitsubishi Electric: EML, Power Supply, Defense, and FA Jointly Support Resilience
Mitsubishi Electric’s investment case is more diversified than Hitachi’s, and also more resilient. It has the cyclical attributes of FA and industrial automation, as well as the structural attributes of data-center power supply, cooling, EML optical devices, defense, and space electronics. JPMorgan rates it Overweight, but the target price implies only about 16% upside, suggesting the market has already partly priced in its improvement. The remaining key question is whether these structural businesses can keep lifting the group margin.
EML is Mitsubishi Electric’s most direct AI networking exposure. As intra-data-center optical interconnects move from 400G/800G to 1.6T, the value and technical requirements of electro-absorption modulated lasers in high-speed optical modules continue to rise. JPMorgan materials show the data-center optical networking market growing from about US$4 billion in 2023 to about US$20 billion in 2028, with high-speed and ultra-high-speed categories increasing their share. Mitsubishi Electric has a strong market position in data-center EML. This segment is not as crowded by investors as GPUs, but it is highly correlated with AI server volume growth, high-speed switches, and optical module upgrades.
Power supply and cooling are the second line. As AI racks move from hundreds of kW toward higher density, data centers need not only optical interconnects, but also UPS, power supply equipment, cooling systems, and more complex building/facility controls. Mitsubishi Electric has long-standing capabilities in power equipment, air conditioning and refrigeration, and FA control, allowing it to embed traditional industrial capabilities into AI data-center construction. These businesses will not see the same near-term explosion as GPUs, but they have long project cycles, high customer stickiness, and usually better earnings quality than ordinary consumer electronics.
Defense and space electronics are the third line. Expectations that Japan will ease policy restrictions on defense equipment exports in 2026 have improved visibility for Mitsubishi Electric’s defense business. The company has exposure to radar, next-generation fighter avionics, lasers, communications satellites, electronic warfare, and overseas cooperation. The combination of AI and defense should not simply be framed as a thematic concept; what truly affects profit is orders, delivery, export permits, and project margins. But within industrial companies, defense businesses usually have better order visibility and cash flow stability.
Mitsubishi Electric also has an easily overlooked variable: FA pricing and product mix. Over the past few years, the FA industry has been under pressure from inventory, the cycle, and China demand, but price increases for high-end products and mix improvement have begun to change margins. JPMorgan materials note that price increases for some FA products can reach the 10%-80% range, showing that industrial automation is not a pure volume story, but a combination of product upgrades, supply discipline, and customer stickiness.
The valuation difficulty for Mitsubishi Electric lies in the group structure. It simultaneously has industrial, infrastructure, building systems, life, semiconductor devices, defense, and space electronics businesses, making it hard for investors to assign equally high multiples to all segments. The 10% group discount embedded in the target price reflects this. To narrow the discount, the company needs to continue proving three things: clearer capital allocation, low-return businesses not becoming a drag, and AI-related and defense-related businesses contributing higher margins.
The investment judgment on Mitsubishi Electric is: it is not an asset like Hitachi, where “grid” is a single very strong main line. Instead, it is a multi-factor resilience story composed of AI data centers, optical networking, defense, and FA improvement. After the share price has already had one run, chasing higher requires evidence that EML orders, semiconductor device margins, defense orders, and group ROE can continue to be revised up.
V. NEC and Fujitsu: Traditional SI Needs to Turn Man-Day Projects into Platform Profit
The rerating logic for NEC and Fujitsu is more software- and services-oriented, but they are not SaaS companies. Their old problem is also typical: large revenue, stable customers, and deep government and enterprise IT relationships, but traditional system integration is easily viewed by the market as a low-margin, low-growth, man-day delivery business. Whether AI can change this depends on whether BluStellar and Uvance can turn industry solutions, AI agents, cloud migration, mainframe modernization, security, and data platforms into reusable products.
NEC’s strengths lie in government, communications, public safety, submarine cables, and large enterprise systems. BluStellar is its main vehicle for pushing traditional public-sector IT and enterprise systems toward AI services, while submarine cables provide harder network infrastructure exposure. Its core customers include government, telecom, and manufacturing. Customer relationships are stable, but the project-based nature still needs to be validated through margins.
Fujitsu’s strengths lie in Uvance, mainframe modernization, and industry services. If Uvance continues to increase its revenue share and gross margin, Fujitsu will no longer be an ordinary IT services provider, but a margin-improvement asset driven by “mainframe modernization + industry AI templates.”
All three companies are talking about AI, but AI means different things for each. NEC is more like AI transformation for the public sector and communications infrastructure, combined with cybersecurity, defense, submarine cables, and government IT. Fujitsu is more like enterprise modernization and industry templates, especially legacy mainframe migration, cloudification, AI agents, and industry applications. Hitachi is more like a data platform for industrial and social infrastructure. Which company ultimately receives a higher market valuation will depend on margins and revenue reuse rates, not how many times “AI” appears in a presentation.
Fujitsu’s margin model is particularly worth watching. The real key is not revenue growth itself, but whether Service Solutions can push its adjusted margin to a higher level as Uvance’s share rises.
NEC’s profit curve is also improving. Its advantage is a stable public-sector and telecom customer base; its weakness is a high share of project-based business, meaning revenue recognition and margin improvement may not be as smooth as investors hope.
The ways to falsify SI services are straightforward. First, revenue growth cannot rely only on large one-off projects; the share of platformized revenue must rise. Second, gross margin must improve with industry templates and software reuse, otherwise AI is just custom projects under a new name. Third, sales expenses and delivery headcount must not consume the gross margin improvement. Fourth, customer cases need to move from proof of concept to scaled deployment, especially in vertical scenarios such as government, manufacturing, defense, retail, and telecom.
For the investment ranking between NEC and Fujitsu, I prefer treating Fujitsu as a margin-improvement allocation and NEC as a beneficiary of public infrastructure and cybersecurity. Fujitsu’s advantage is a clearer margin path; NEC’s advantage is scarcer government, submarine cable, and security assets. Neither is suitable for judging purely by one quarter of orders. They are better validated through margin improvement over a 2-3 year horizon.
VI. Sony: IP, Platforms, and Sensors Determine Whether It Is a Different Kind of AI Asset
Sony is the most distinctive company in this group. It is neither a power-grid company nor an AI hardware company in the traditional sense. JPMorgan rates Sony Overweight with a JPY5,700 price target, underpinned by an SOTP re-rating: Games & Network Services, Music, Pictures, Electronics Products, Image Sensors, and financial equity stakes together form the value base. It has the largest upside, but also receives the heaviest market discount, because Sony’s business mix is too complex and its verification cadence is less direct than power-grid orders.
The core investment view on Sony is this: in the AI era, content platforms and IP assets may become more valuable again. Generative AI reduces the cost of content production and distribution, but high-quality IP, music copyrights, gaming communities, anime platforms, and film/TV libraries become scarcer. Models can generate content, but they cannot automatically own global user relationships, copyrights, characters, communities, and distribution networks. Sony happens to own these assets.
In JPMorgan’s SOTP, Games & Network Services contributes JPY2,909 per share, Sony’s largest source of value; Music contributes JPY1,038, Pictures JPY521, Image Sensors JPY1,242, plus Electronics Products, net cash, and equity investments. This breakdown shows that Sony has long since ceased to be a pure hardware company. PlayStation hardware itself is not highly profitable and may even be a drag; software, network services, subscriptions, and IP content are the core.
Music copyrights are among Sony’s most easily underestimated assets. Over the past few years, Sony has continued to acquire high-value music catalogs, including major artists and copyright portfolios. In May 2026, Sony and GIC acquired the Recognition Music Group catalog, covering roughly 45,000 songs, in a transaction valued at about USD4 billion. The investment logic for copyright catalogs resembles long-duration cash-flow assets: they may not drive a large near-term profit uplift, but once combined with streaming, short video, film and TV, gaming, and AI licensing, the commercialization paths for the copyright library multiply.
For the gaming business, the focus should be platform profit, not hardware shipments. JPMorgan’s model shows Games & Network Services revenue and operating profit continuing to improve in FY2027-2029, with PS Plus subscriptions rising steadily from the 47 million level to above 50 million. This growth rate is not spectacular, but the quality of platform revenue matters more than the hardware cycle. As long as software sales, subscriptions, network services, and first-party content profit continue to improve, Sony will look more like a platform company than a consumer-electronics company.
Image sensors are Sony’s connection point to AI hardware. In JPMorgan’s materials, Sony’s revenue share in image sensors is materially higher than its shipment share, indicating strong ASP and high-end share. In 2025, Sony’s CIS shipment share was about 25%, revenue share about 54%, and ASP about USD6.8, above major competitors. Smartphones remain the core base, but robotics, automotive, security, industrial, XR, and AI vision devices may all provide a second growth curve. What investors really need to track is not the statement that “sensors also benefit from AI,” but whether the revenue share from non-smartphone applications and ASP can remain stable.
Deep Dive on Japanese Electronic Components: AI Servers Push MLCCs from Cyclical Products Toward Compute Infrastructure
Sony’s risks are also more complex than Hitachi’s. First, the gaming hardware cycle and content investment can cause profit volatility. Second, if music copyright acquisitions are priced too aggressively, near-term returns will come under pressure. Third, the Pictures business is materially affected by project cycles. Fourth, CIS remains exposed to smartphone demand and customer mix, while non-smartphone AI vision applications have not yet fully taken over as a growth driver. Fifth, the group has many businesses, and the market needs clearer capital allocation and shareholder returns.
The judgment on Sony is this: it is the most imaginative asset in this group, but not the most suitable as a high-conviction core holding. Sony’s upside comes from SOTP discount narrowing and multiple businesses delivering at the same time. If gaming network profit, music copyright cash flow, Crunchyroll subscriptions, and high-end CIS share all improve together, valuation elasticity will be significant. Conversely, if any two core businesses fall short of expectations, the market will continue to suppress it with a conglomerate discount.
VII. Panasonic Holdings: BBU and Materials Are Options; Batteries and Portfolio Discount Are Reality
Panasonic is the most typical asset in this group with “AI optionality, but continued pressure in the core business.” JPMorgan maintains a Neutral rating with a JPY4,600 price target, close to the current share price. This rating does not deny the value of BBU, MEGTRON, and Blue Yonder; rather, it reminds investors that the optionality is not yet large enough to offset automotive batteries, automotive electronics losses, and the group discount.
BBU is Panasonic’s most direct AI data-center option. High-power AI racks require greater power continuity. Beyond traditional data-center UPS systems, rack-level or near-rack backup power is becoming more important. JPMorgan’s materials show that Panasonic is planning data-center energy storage systems, with a related revenue target approaching JPY800 billion by FY2028. If this figure translates into actual orders and revenue recognition, it would significantly change the growth curve of Panasonic’s energy business.
But BBU cannot be assessed by plans alone. First, customer qualification takes time, especially as hyperscale data centers have extremely high requirements for safety, lifetime, thermal management, and certification. Second, BBU is tied to battery systems, power electronics, rack architecture, and facility-side power design; the standardization process will affect suppliers’ bargaining power. Third, BBU margins are not necessarily high by default, depending on cell costs, system integration, customer pricing, and after-sales obligations. Fourth, if rack architecture continues to evolve, BBU form factors and installation locations may also change.
Panasonic’s second AI option is MEGTRON materials. AI servers and high-speed networks require low-loss PCB/CCL materials, and Panasonic has long-standing accumulation in high-end materials. This logic is consistent with the re-rating of Japanese electronic components, ABF, MLCCs, and CCL: the high-speed, high-frequency, high-power, and high-reliability requirements of AI servers are pushing previously cyclical materials segments toward higher value-added. But the materials business remains relatively small within Panasonic’s group scale and needs sustained volume growth before it can change overall valuation.
Deep Dive on Japanese Electronic Components: AI Servers Push MLCCs, HDD Heads, and ABF Substrates Toward 2027 Supply Anchors
Panasonic’s real constraints are in energy and automotive. The slope of the energy business in the model looks attractive, but energy margins excluding the impact of IRA still need to be verified. The automotive business remains loss-making through the model period, making it difficult for the overall group to immediately enjoy a high valuation.
For Panasonic to move from Neutral to a more attractive stock, three conditions need to be met at the same time. First, BBU orders must move from planning to recognizable revenue, with a sufficiently high-quality customer mix. Second, the energy business must improve margins after excluding subsidies, rather than relying on policy income. Third, automotive batteries and automotive electronics must stop consuming improvements from the group’s other businesses. If any one condition is missing, the market will continue to apply a portfolio discount.
The investment conclusion on Panasonic should be disciplined. It has AI data-center optionality, as well as materials and supply-chain software assets, but these options cannot yet offset group complexity and automotive losses. It is suitable for low-weight tracking while waiting for BBU revenue, energy margins, and automotive improvement to appear simultaneously; it is not suitable for a heavy position based on the single theme of “AI data-center backup power.”
8. Portfolio Ranking: Certainty First, Then Optionality, Then Options
When looking at this group of companies together, the investment ranking cannot be based only on target-price upside, nor only on share-price performance over the past year. Over the past year, Panasonic Holdings, Seiko Group, Citizen and others have rallied sharply, while Mitsubishi Electric has also significantly outperformed. Hitachi, NEC, Fujitsu and Sony have been less strong relative to TOPIX. Near-term share prices have already pulled forward part of the story; what matters next is earnings delivery.
The portfolio ranking should be built around three questions. First, has AI capex become clearly identifiable revenue? Second, can that revenue translate into higher margins? Third, has valuation already fully priced this in? Hitachi is the strongest on the first and second questions, while valuation still has upside. Mitsubishi Electric has multiple entry points on the first question, but valuation already partly reflects this. Sony is the most attractive on the third question, but validation of the first and second questions is more complex. NEC and Fujitsu depend on margin delivery. Panasonic depends on option value being realized.
The core of this ranking is to first buy the bottlenecks that AI buildout must solve. Hitachi’s grid assets and Mitsubishi Electric’s EML/power-supply exposure are bottleneck assets. Sony is not an infrastructure bottleneck, but it owns global content and user platforms, making it a scarce asset in AI-driven content diffusion. NEC and Fujitsu are closer to margin-improvement plays as AI applications are implemented. Panasonic still needs to wait for its options to turn from narrative into orders.
In terms of portfolio weights, Hitachi can be the core holding, Mitsubishi Electric and Sony the upside positions, NEC and Fujitsu lower-weight allocations, and Panasonic a name to wait on for signals. This portfolio is more reasonable than simply buying an “AI Japan technology ETF,” because the asset quality and AI exposure of Japanese technology companies vary too widely.
It is worth noting that traditional consumer-electronics and printing-related companies are not part of the core ranking. Canon, Ricoh, Casio, Seiko Epson, Sharp and others are not without improvement opportunities, but their AI capex transmission is weak. They are still driven more by their own product cycles, cost control, exchange rates and portfolio restructuring. The market may give them periodic valuation repair, but it is hard to assign them the same AI premium as Hitachi, Mitsubishi Electric and Sony.
9. Three Scenarios: Which Path Delivers the Japan Hardware Re-rating?
The re-rating of Japanese hardware assets can be split into three scenarios. The first is a continuing power bottleneck, where AI data-center construction remains constrained by transformers, switchgear, HVDC, backup power and site-level power management. The second is accelerated upgrades in optical networks and rack systems, where 1.6T optical modules, EML, power supply, cooling and high-frequency materials become new value pools. The third is AI applications spreading from cloud training to enterprises, governments, manufacturing, content platforms and Physical AI, with SI services, content IP and sensor platforms beginning to deliver profits.
These three scenarios are not mutually exclusive, but they have a major impact on company rankings. In the power-bottleneck scenario, Hitachi is the strongest, while Mitsubishi Electric and Panasonic also benefit. In the optical-network and rack-upgrade scenario, Mitsubishi Electric, Panasonic’s materials business and the Japanese electronic-components chain are better positioned. In the AI-application diffusion scenario, Sony, Fujitsu, NEC and Hitachi Lumada have more room to perform. The portfolio should avoid putting all positions on the same path.
The advantage of the power-bottleneck scenario is that it is the easiest to verify. Order backlog, revenue recognition, capacity-expansion plans, project gross margins and free cash flow can all be tracked quarter by quarter. Hitachi has the highest certainty here because it has grid equipment, automation, software and Lumada at the same time. Mitsubishi Electric can benefit from power supply, cooling and infrastructure. Panasonic’s BBU can also benefit, but it needs to prove that it is not merely a battery supplier, and that it can enter rack and data-center power systems.
The optical-network and rack-upgrade scenario has higher upside. Once the AI server bottleneck spills over from GPUs into switching, optical interconnects, power conversion, cooling and materials, the value chain will spread into more hardware segments. Mitsubishi Electric’s EML has a direct benefit logic. Panasonic’s MEGTRON materials have an indirect benefit logic. Japan’s electronic-components chain will also benefit from requirements for high reliability, high frequency, high power and miniaturization. The risk in this scenario is pricing: once high-speed optical modules and devices move quickly into oversupply, revenue growth may be offset by ASP declines.
The AI-application diffusion scenario is the hardest to verify, but it also has a high ceiling. Sony’s music, film, gaming, anime and image sensors are, in essence, content and data entry points in the AI era. The service platforms of Fujitsu, NEC and Hitachi are tools for implementing AI in enterprises and the public sector. This scenario requires more time, because the path from pilots to deployment, and from deployment to profit recognition, is usually slower than hardware orders. It is better suited to longer-duration valuation, not chasing single-quarter news.
The “price framework” also needs to be clarified. The target prices in JPMorgan’s table come from the same model, on the same day, in the same currency and for the same share trading units, so the internal comparison basis is relatively consistent. But target-price upside across different companies cannot be equated directly with recommendation strength. Sony has the highest target-price upside because its SOTP discount is large and its platform assets have high valuation elasticity. Hitachi has somewhat lower upside, but much stronger order visibility. Panasonic’s target price is almost in line with the current price because its AI option is still offset by drag from batteries and automotive electronics.
A more practical portfolio framework would be to treat Hitachi as the “high-certainty core holding,” Mitsubishi Electric as “AI hardware diffusion upside,” Sony as “platform discount repair,” Fujitsu and NEC as “AI services margin improvement,” and Panasonic as a “BBU realization option.” What the portfolio really needs to guard against is not one company underperforming in the short term, but holding a group of positions with different names that are all, in substance, exposed to the same risk. Power, optical networks, platform services and IP should ideally be tracked separately.
This scenario framework has another implication: if AI capex sees a temporary slowdown in the future, Hitachi and Mitsubishi Electric should be more defensive than the pure server chain. Grid and defense demand have longer cycles, and enterprise IT modernization will not disappear entirely with one quarter of GPU order volatility. Conversely, if AI capex continues to be revised upward, the greatest upside may come from Mitsubishi Electric and Sony: one driven by optical networks and industrial hardware, the other by narrowing discounts on platform and content assets.
10. Capability Migration: How Old Japan Manufacturing Connects to AI Capex
The easiest way to underwrite this rerating of Japanese hardware too superficially is to see only “incremental demand from AI” and miss the migration in corporate capabilities. Hitachi, Mitsubishi Electric, Sony, NEC, Fujitsu, and Panasonic are not new companies, nor did they suddenly start doing AI from scratch. Their rerating comes from old capabilities being repriced by new demand: grid engineering, industrial control, optical devices, mainframe systems, content distribution, copyright operations, precision manufacturing, and battery materials used to map to separate mature markets. Now AI capex is reconnecting them into one value chain.
Hitachi’s capability migration is the clearest. Old Hitachi was a heavy electrical equipment, rail, industrial systems, and large-project company, with valuation easily constrained by cyclicality, project execution, and group complexity. The key to new Hitachi is turning these social-infrastructure scenarios into a combination of grid hardware, dispatch software, industrial data, and Lumada services. AI data centers are not bringing a single isolated order; they are driving simultaneous increases in power-system expansion, load management, equipment delivery, and digital O&M.; If Hitachi can keep energy margins, Lumada’s revenue mix, and portfolio optimization on the same upward curve, its valuation should move closer to an infrastructure platform than a traditional equipment company.
Mitsubishi Electric’s migration looks more like “industrial hardware moving from cyclical to structural.” Factory automation, buildings, air conditioning, semiconductor devices, and defense were originally quite fragmented, making it hard for investors to give them a unified narrative. AI data centers connect several of these lines: EML maps to high-speed optical interconnects, UPS and cooling map to rack infrastructure, FA maps to the recovery in automation investment, and defense and space electronics map to longer-cycle orders. Mitsubishi Electric’s challenge is to turn multiple opportunities into margins, rather than letting each business tell its own story. As long as semiconductor devices and infrastructure can lift group margins, it can move from an ordinary industrial cyclical stock to a higher-beta asset for the diffusion of AI hardware.
Sony’s migration is happening at the level of asset perception. The market has tended to see Sony as a game console, camera, TV, headphone, and consumer-electronics brand, but Sony’s real scarcity lies in the combination of global IP, content production, distribution, subscriptions, gaming networks, and image sensors. AI will lower the threshold for ordinary content production, but it will also amplify the value of high-quality IP and platforms, because user attention, copyright licensing, character assets, and community relationships are harder to replicate. Whether Sony can rerate depends on whether it can prove that gaming networks, music copyrights, anime platforms, and high-end CIS share are not isolated businesses, but a set of global content infrastructure capable of continuously generating cash flow.
NEC and Fujitsu’s migration will test execution the most. The biggest problem with traditional SI companies is that they have deep customer relationships, but their delivery models are too labor-intensive, and revenue growth is easily consumed by labor costs. AI gives them an opportunity to convert industry knowledge, mainframe modernization, government IT, communications networks, security, and enterprise processes into reusable solutions. If NEC’s BluStellar and Fujitsu’s Uvance are only new labels for selling projects, valuations will not change much. If they can turn industry templates, data governance, AI agents, and cloud migration into higher-gross-margin platforms, the market will reassess the margin ceiling of Japanese IT services companies.
Panasonic’s migration requires the most patience. Its old assets include batteries, materials, home appliances, automotive electronics, and supply-chain software, as well as many businesses that weigh on the group’s valuation. AI data centers have opened entry points into BBUs, low-loss materials, and energy systems, but those entry points still need orders, customer adoption, and margin proof. Panasonic is not already positioned on the main grid value chain like Hitachi, nor does it have the more direct beta in EML and industrial power supply that Mitsubishi Electric has. It is more like a portfolio rerating asset waiting for options to pay off. Only when BBUs and materials materially change the profit structure of the energy business will Panasonic’s discount have a real basis to narrow.
This is also why this line should be bought based on company capability migration, not keywords. In Hitachi, one is buying the migration of grid and digital infrastructure. In Mitsubishi Electric, one is buying the diffusion of industrial hardware into AI data centers and defense. In Sony, one is buying the IP and platform under the consumer-electronics shell. In Fujitsu and NEC, one is buying the migration of traditional SI toward platform margins. In Panasonic, one is buying energy and materials optionality. Every company must use its old capabilities to capture new AI demand. Companies that cannot migrate can only remain in theme-driven trading.
This line has another easily overlooked benefit: most Japanese companies have already experienced a long period of low valuation, low capital efficiency, and conglomerate discount, so market expectations for them are not perfect. As long as AI capex can turn some old assets back into growth assets, valuation repair does not need to rely on extremely optimistic assumptions. Hitachi’s grid, Mitsubishi Electric’s EML, Sony’s IP, and NEC and Fujitsu’s industry services are all new slopes growing out of old assets. This kind of rerating is slower than pure concept stocks, but it is also easier to validate continuously through orders, margins, and cash flow.
What must be avoided is mixing “low-valuation Japanese assets” and “AI-related assets” into one basket. Low valuation only provides margin of safety; AI relevance only provides imagination. Only when both turn into profit and cash flow is the rerating sustainable. Hitachi and Mitsubishi Electric are validated more through hardware, Sony through platform quality, NEC and Fujitsu through service margins, and Panasonic through option realization. These paths are different, which is why they can all be retained in a portfolio, but each position should have its own tracking indicators.
This also determines the trading rhythm. Hardware-constrained assets are best confirmed through order and delivery trends; platform assets through profit quality and discount repair; option assets require revenue and cash flow to truly penetrate the group financial statements.
This determines the final ranking.
11. From GPUs to the Grid, the Asset Attributes of Japanese Hardware Are Migrating
In the first stage of AI capex, capital bought GPUs, HBM, advanced packaging, server ODMs, and optical modules. In the second stage, capital began buying power supply, liquid cooling, transformers, data-center land, generation, and networks. In the third stage, capital will continue to diffuse into system integration, software platforms, data security, content assets, and Physical AI. Japanese hardware companies have a stronger presence in the second and third stages.
Hitachi maps to “power infrastructure rerating.” It most resembles the conversion of traditional heavy electrical assets from cyclicals into admission tickets for AI buildout. Mitsubishi Electric maps to “industrial hardware upgrade.” It combines EML, power supply, cooling, FA, defense, and space electronics into multi-point beta. NEC and Fujitsu map to “enterprise and public-sector AI implementation.” Their validation point is not theme exposure, but margins. Sony maps to a “content and sensor platform.” Its asset attributes are closer to global IP and a user platform. Panasonic maps to “backup power and materials optionality.” It needs to prove that the option is large enough to offset the group discount.
This migration also explains why the Japanese market will diverge. In the past, yen depreciation and governance improvement could lift many Japanese stocks together. Going forward, the market will be more selective. Only companies that can win direct AI capex orders, raise margins, sustain buybacks, and optimize portfolios deserve higher valuations.
For investors, there are two most dangerous misjudgments. The first is treating all Japanese electronics companies as AI assets. The second is looking only at short-term share-price strength and not whether asset attributes have already changed. Mitsubishi Electric and Panasonic have risen strongly over the past year, showing that the market has already recognized part of the story in advance. Hitachi and Sony’s relative performance has been less strong, which may instead indicate that the market is still waiting for clearer profit validation. Valuation is not an independent variable; it must be viewed together with evidence.
12. Why Traditional Consumer Electronics and the Printing Chain Are Not in the Core
JPMorgan’s coverage also includes a group of companies that can be pulled along by thematic trading, including Seiko Epson, Canon, Ricoh, Casio, Sharp, Citizen Watch, and Seiko Group. They each have their own cyclical, cost, product-refresh, and governance-improvement opportunities, but they should not be placed on the same AI main line as Hitachi, Mitsubishi Electric, Sony, NEC, and Fujitsu. The reason is simple: AI capex transmission is not direct enough, and margin validation is not hard enough.
Seiko Epson’s Underweight rating best illustrates the boundary. Printing, projection, commercial printing, and consumer electronics can deliver cost control and may benefit from FX or cyclical recovery, but they lack a clear bridge to AI data-center construction. As long as revenue growth still mainly comes from mature hardware and channels, valuation is unlikely to be structurally lifted by AI infrastructure. A target price below the current share price reflects that the market has already granted some recovery, while earnings and asset attributes have not upgraded in parallel.
Canon and Ricoh are similar. Office equipment, cameras, printing, and IT services all have stable cash flow, but the variables that can truly drive a market rerating need to come from new growth curves, margin improvement, or capital allocation. AI can improve image processing, office automation, and enterprise processes, but these benefits are more like efficiency gains. They do not directly bottleneck AI capex in the way grids, EML, BBUs, and submarine cables do. Stability does not equal rerating, and good cash flow does not mean a company will receive an AI multiple.
Sharp’s case is more complicated. It may have value in displays, equipment, brand, and restructuring, but historical baggage, profit volatility, and competitive position make it hard for investors to assign high certainty. If the AI theme only brings a round of valuation imagination without orders, margins, and cash flow, pricing will ultimately return to asset quality. For these companies, the most important question is not whether there is an AI story, but whether there is sufficiently strong asset disposal, cost restructuring, product upgrade, or shareholder return.
Citizen Watch and Seiko Group have risen strongly over the past year, reflecting more of consumption, FX, brands, governance, and low-valuation repair. They can be part of Japanese market style rotation, but they are hard to include in an AI infrastructure portfolio. Profit improvement in watches, precision parts, and branded businesses can bring valuation repair, but it does not make them direct picks-and-shovels beneficiaries of AI capex. Including these companies in the core portfolio would dilute the investment theme and make tracking indicators more confused.
The screening standard for the core portfolio should remain strict. First, the company must have a clear AI capex entry point, at least in one of power, networks, power supply, SI services, content platforms, sensors, or materials/backup power. Second, this entry point must be able to affect group profit, not just a small business line. Third, there must be verifiable data over the next four quarters. Fourth, valuation cannot rely only on story; it must be explainable through SOTP, margins, or order slope.
This boundary matters for investing. The easiest mistake in AI thematic trading is putting every company that can describe an AI use case into the portfolio. Useful screening does not ask whether a company can talk about AI, but whether AI demand has changed its revenue structure, margins, and capital returns. Hitachi, Mitsubishi Electric, Sony, NEC, Fujitsu, and Panasonic can at least provide trackable answers to these questions. Traditional printing, consumer electronics, and brand assets are more part of Japanese market repair than the AI infrastructure main line.
Therefore, the core portfolio should not seek maximum coverage, but the strongest evidence chain. Holding fewer companies with weak themes, slow validation, and small earnings beta makes the portfolio clearer. Once these companies truly show new orders, new products, new margins, and new capital allocation, it will not be too late to raise allocation weights.
XIII. Falsification Checklist: How to Track This Theme
This Japanese hardware re-rating theme should not be tracked through a single news catalyst. It should be monitored quarterly across four sets of indicators.
The first set is the power grid. Track Hitachi Energy’s order backlog, delivery lead times, transformer and high-voltage equipment capacity, energy business revenue growth, adjusted margin in energy, and Lumada revenue mix. If orders remain strong but do not convert into revenue, or revenue converts but margins do not improve, it means grid expansion is being absorbed by costs and delivery constraints.
The second set is optical networks and power supply. Track Mitsubishi Electric’s EML shipments, optical-network customer demand, semiconductor device margins, data-center power and cooling orders, FA pricing, and defense orders. If EML competition intensifies, pricing declines, or the FA cycle drags more than AI contributes, Mitsubishi Electric will struggle to continue benefiting from valuation upgrades.
The third set is AI services. Track the revenue mix, gross margin, reuse rate, and major-customer cases for NEC BluStellar, Fujitsu Uvance, and Hitachi Lumada. If revenue is built up through low-margin projects, the market will cut margin expectations. The key for AI services is not how many conceptual partnerships are signed, but whether the same industry templates can be repeatedly sold to more customers.
The fourth set is platforms and optionality. For Sony, track PS Plus subscriptions, game-network profit, music-copyright cash flow, Crunchyroll subscriptions, CIS revenue share, and non-smartphone applications. For Panasonic, track BBU orders, energy-business margin excluding subsidies, automotive-battery shipments, and losses in the automotive business. Sony needs multiple businesses to deliver at the same time; Panasonic needs its option businesses to become large enough.
The final judgment can be condensed into one sentence: the opportunity in Japanese technology hardware is not the broad label of “Japanese electronics,” but the re-pricing of bottleneck assets after the spillover of AI capex. Hitachi and Mitsubishi Electric rely on hardware constraints, Sony relies on platforms and IP, NEC and Fujitsu rely on AI-service margins, and Panasonic relies on BBU and materials optionality. The companies truly worth buying are not those that sound most like AI, but those that can translate AI demand into orders, margins, and cash flow.