
Qualcomm Q3 Earnings: Autos Grow 61%, but a 20% Handset Decline Creates Transition Pressure
目录
TL;DR
I. Conclusion: A Shift in Revenue Mix, Not a Profit Inflection Point
II. Handsets Down 20%: Not One Cause, but Two Layers of Pressure
III. Automotive Up 61%: Revenue Has Materialized, but Earnings Quality Requires Further Validation
IV. The Cost Shock Matters More Than Revenue Guidance
V. Data Centers: The Roadmap Was Validated This Quarter, but Profitability Was Not
VI. Cash Flow and Capital Allocation: Buybacks Remain Strong, but the Buffer Is Shrinking
VII. Four Sets of Forward Validation Metrics
本内容基于公开资料和研报数据整理,不构成任何投资建议,不代表任何个人观点,仅供学习参考,请理性阅读
Qualcomm’s revenue mix has begun to shift, but its profit mix has not yet caught up: autos and IoT are growing rapidly, while handsets, costs, and upfront investment are simultaneously weighing on earnings and cash flow.
TL;DR
Qualcomm’s FY2026 Q3 revenue was $9.947 billion, down 4% year over year; GAAP EPS was $1.87 and non-GAAP EPS was $2.21, down 23% and 20%, respectively. Revenue was near the high end of prior guidance, but the earnings decline was significantly greater than the revenue decline.
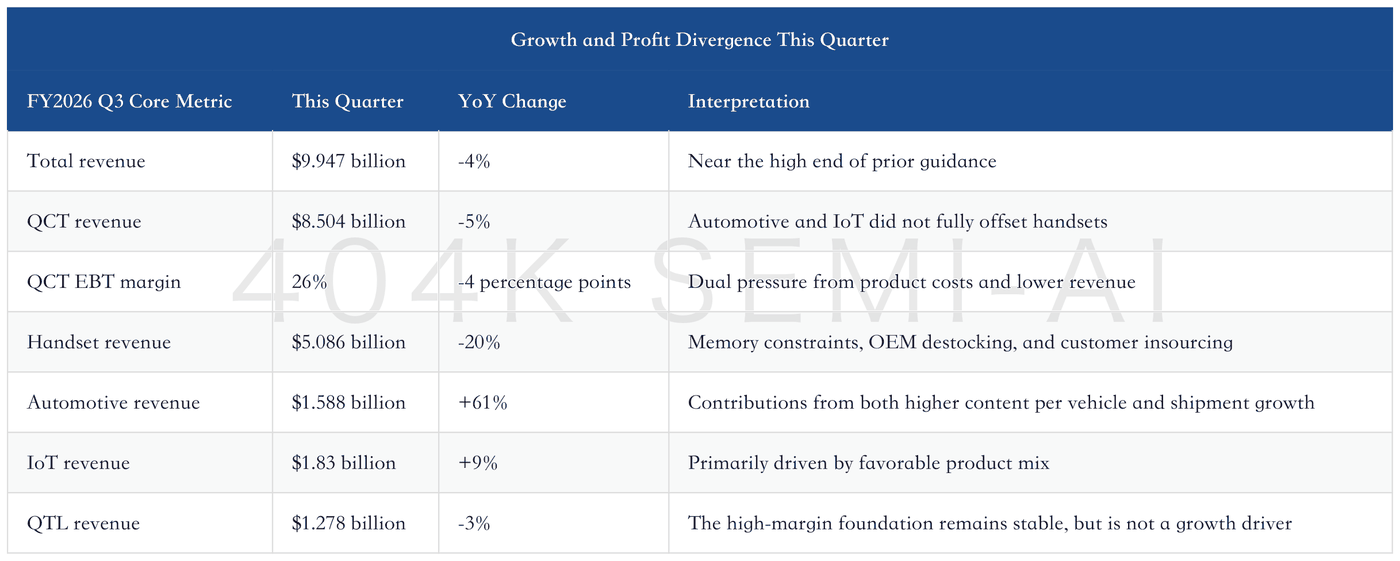
QCT showed extreme divergence: handset revenue was $5.086 billion, down 20% year over year; automotive revenue was $1.588 billion, up 61%; and IoT revenue was $1.83 billion, up 9%. Automotive and IoT grew 28% combined, but still did not offset the $1.242 billion decline in handsets.
The real near-term issue is margin. QCT EBT margin fell from 30% to 26%, with Q4 guidance declining further to 23%—25%. Prices are rising broadly across memory, wafers, assembly, testing, advanced packaging, and materials. Qualcomm has raised prices, but management acknowledged that the benefits will materialize gradually.
The market may easily attribute the entire handset decline to Apple’s in-house modem substitution, but two pressures are actually overlapping: higher memory prices are prompting Chinese Android vendors to reduce inventories; and beginning in Q4, Qualcomm’s modem share in the next iPhone is expected to be significantly below its previous 20% estimate.
Automotive growth has progressed from “design wins” to revenue realization, but data centers remain in an “investment first, revenue later” phase. Non-handset revenue growth of more than 60% in FY2027 and $40 billion in non-handset revenue in FY2029 are targets for the next validation cycle, not explanations for this quarter’s profit.
Operating cash flow for the first nine months fell from $10.016 billion to $8.405 billion, capital expenditures rose from $785 million to $1.578 billion, and inventory increased from $6.526 billion at the beginning of the fiscal year to $8.379 billion. Buybacks and dividends remain strong, but the buffers provided by free cash flow and the balance sheet are thinning.
I. Conclusion: A Shift in Revenue Mix, Not a Profit Inflection Point
Qualcomm displayed three clear trajectories this quarter: the handset business entered a dual downturn driven by the memory cycle and customers’ in-house modems; automotive and IoT began providing a meaningful offset; and data centers entered a buildout phase involving substantial investment but not yet contributing sufficient profit. Revenue of $9.947 billion at the high end of guidance and 61% automotive growth must both be understood within these transitions.
This makes the quarter appear to offer two opposing conclusions. From a business-mix perspective alone, Qualcomm’s diversification is succeeding: combined quarterly automotive and IoT revenue reached $3.418 billion, up 28% year over year, while automotive has delivered double-digit year-over-year growth for 23 consecutive quarters. From an earnings-quality perspective, the transition is not yet complete: QCT revenue fell 5%, but EBT declined 18% and margin contracted by 4 percentage points; consolidated operating income was $1.626 billion, down 41% year over year.
A more accurate conclusion is therefore that Qualcomm has demonstrated its ability to generate substantial revenue outside handsets, but has not yet demonstrated that this revenue can sustain its previous margins and cash-generation capacity during a handset downturn. Automotive provides the current earnings anchor, data centers provide the future growth trajectory, and handsets and supply costs will determine whether the transition between the two is smooth.
II. Handsets Down 20%: Not One Cause, but Two Layers of Pressure
Handset revenue declined by $1.242 billion year over year this quarter, making it the primary drag on QCT. The 10-Q directly attributed the decline to recent memory supply constraints and price increases, which led some major OEMs to adjust production plans and reduce inventories. The presentation further quantified the impact: Qualcomm expects FY2026 Android handset revenue to decline approximately 20% from FY2025, reducing full-year EPS by more than $1.50; handset revenue from Chinese OEMs is estimated to have bottomed in the fiscal third quarter and is expected to deliver double-digit sequential growth in Q4.
This means the pressure on Android handsets is cyclical and cannot simply be extrapolated into a persistent contraction. Higher memory prices simultaneously increase device costs, weaken end demand, and prompt manufacturers to reduce component inventories; once supply-demand conditions and pricing improve, both shipments and inventory replenishment may rebound. However, a recovery in the inventory cycle cannot resolve the structural substitution by Apple.
Qualcomm explicitly stated that, due to its own supply constraints, its modem share in the next-generation iPhone is expected to be significantly below its previous 20% estimate, and the decline in revenue from Apple products will accelerate beginning in Q4. The Android memory impact is a cyclical issue, while Apple’s in-house modem is a market-share issue. Their overlap over the next several quarters explains why the midpoint of Q4 revenue guidance is only slightly above this quarter, while the midpoint of non-GAAP EPS guidance is slightly lower.
The first point the market is most likely to misread is attributing the entire handset decline this quarter to Apple. The second is treating the pressure on handsets as over because Chinese Android revenue has bottomed. A more reasonable breakdown is that Android may recover sequentially, but Apple revenue still faces a structural step-down, partially offsetting the recovery in total handset revenue.
III. Automotive Up 61%: Revenue Has Materialized, but Earnings Quality Requires Further Validation
Automotive provided the quarter’s most compelling positive evidence. Revenue of $1.588 billion increased by $604 million year over year, with $381 million attributable to favorable product mix and higher average selling prices and $223 million attributable to shipment growth driven by new vehicle models. This was neither solely a function of industry unit sales nor solely dependent on a single cockpit chip; digital cockpit, connectivity, ADAS, and automated-driving products collectively increased content per vehicle.
The newly disclosed Stellantis partnership covers cockpit, connectivity, and L2+ driving, while BMW selected Qualcomm as its principal compute-chip supplier for digital cockpits and next-generation ADAS/automated-driving systems over the coming decade. These developments reinforce the earlier assessment: automotive is the first of Qualcomm’s diversification businesses to progress from design wins to revenue generation and platformization.
Automotive growth, however, cannot be directly equated with an improvement in QCT margin. QCT faced higher product costs and lower revenue this quarter, with EBT margin falling from 30% to 26%; the company’s Q4 guidance range declines further to 23%—25%. Greater automotive scale can improve R&D; reuse and customer stickiness, but it also involves long design cycles, automotive-grade quality obligations, and ongoing software investment. The real question is not whether automotive can continue to grow, but whether the combination of automotive, IoT, and future data-center revenue can return QCT margin to a stable range after the handset mix declines.
IV. The Cost Shock Matters More Than Revenue Guidance
Management described the supply-side pressures in highly specific terms: input-cost inflation spans wafer fabrication, assembly, testing, advanced packaging, memory, and other materials. Qualcomm is reflecting these costs in product pricing, but acknowledged that the price increases will take effect gradually. This explains why Q4 revenue guidance of $9.7 billion to $10.5 billion does not appear weak, while QCT margin guidance continues to decline.
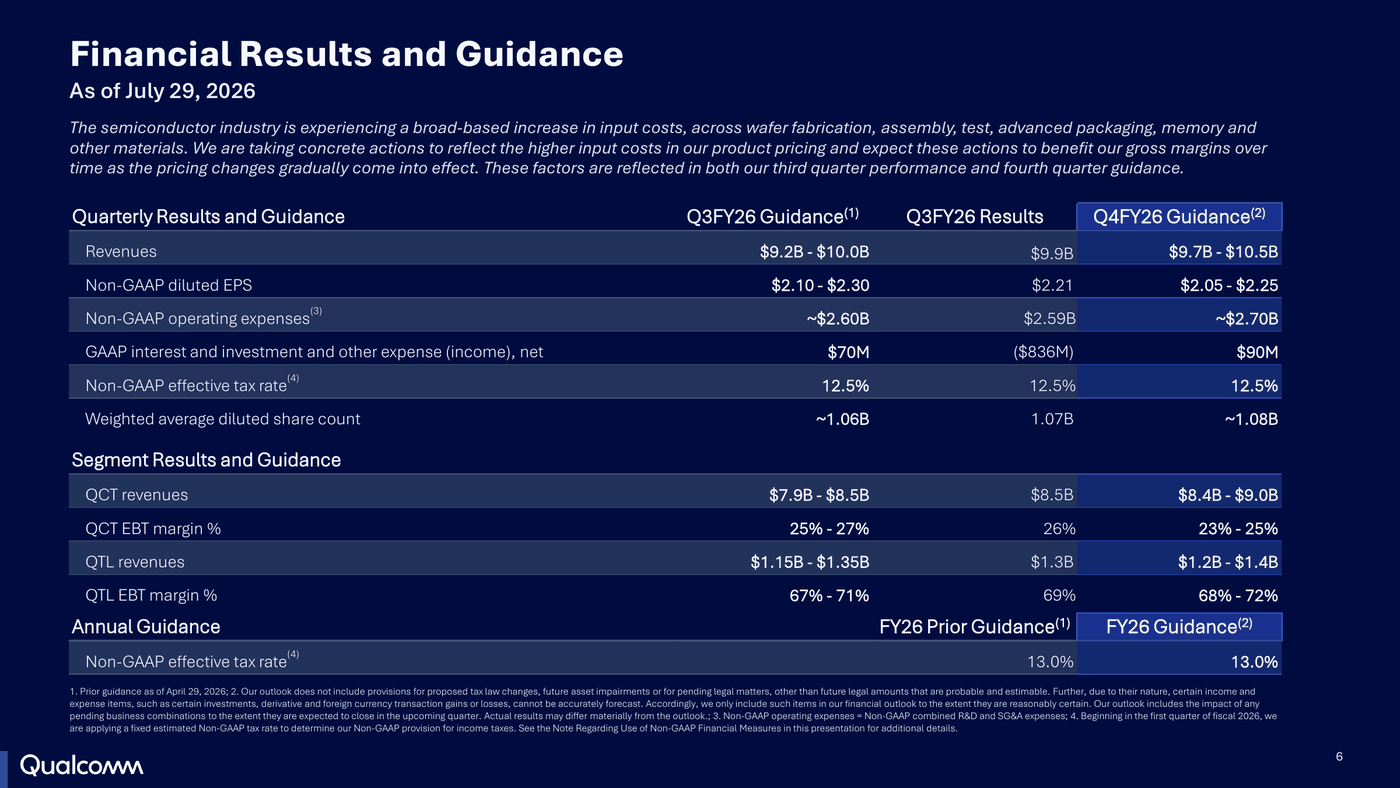
Page 6 of Qualcomm’s FY2026 Q3 earnings presentation: the midpoint of Q4 revenue guidance is above this quarter, but QCT EBT margin guidance declines to 23%—25%, directly reflecting margin pressure before the price increases take effect.
This is also the primary reason profit declined more sharply than revenue this quarter. Consolidated gross margin fell from 56% to 53%, R&D; expense increased by $381 million year over year, and selling, general, and administrative expense increased by $205 million. Growth investment is not inherently negative, but during a handset revenue downturn, fixed investment in R&D; and acquisition integration amplifies profit volatility.
Non-GAAP EPS of $2.21 is more useful than GAAP EPS of $1.87 for assessing ongoing operating trends, but it should not be used in isolation. This quarter’s non-GAAP results excluded $827 million of stock-based compensation, as well as QSI investment gains and acquisition- and restructuring-related items. Conversely, GAAP income before taxes included a sizable gain from the public listing of a QSI equity investment. Both measures have their own distortions; the most reliable cross-check remains QCT segment margin, operating income, and cash flow.
V. Data Centers: The Roadmap Was Validated This Quarter, but Profitability Was Not
The two preceding foundation reports characterized Qualcomm as undergoing a “second platform moment”: expanding from a handset and edge-chip company into a data-center platform spanning connectivity, custom silicon, AI accelerators, CPUs, and software. This quarter’s presentation continued and refined that roadmap, while also clearly highlighting the timing gap.
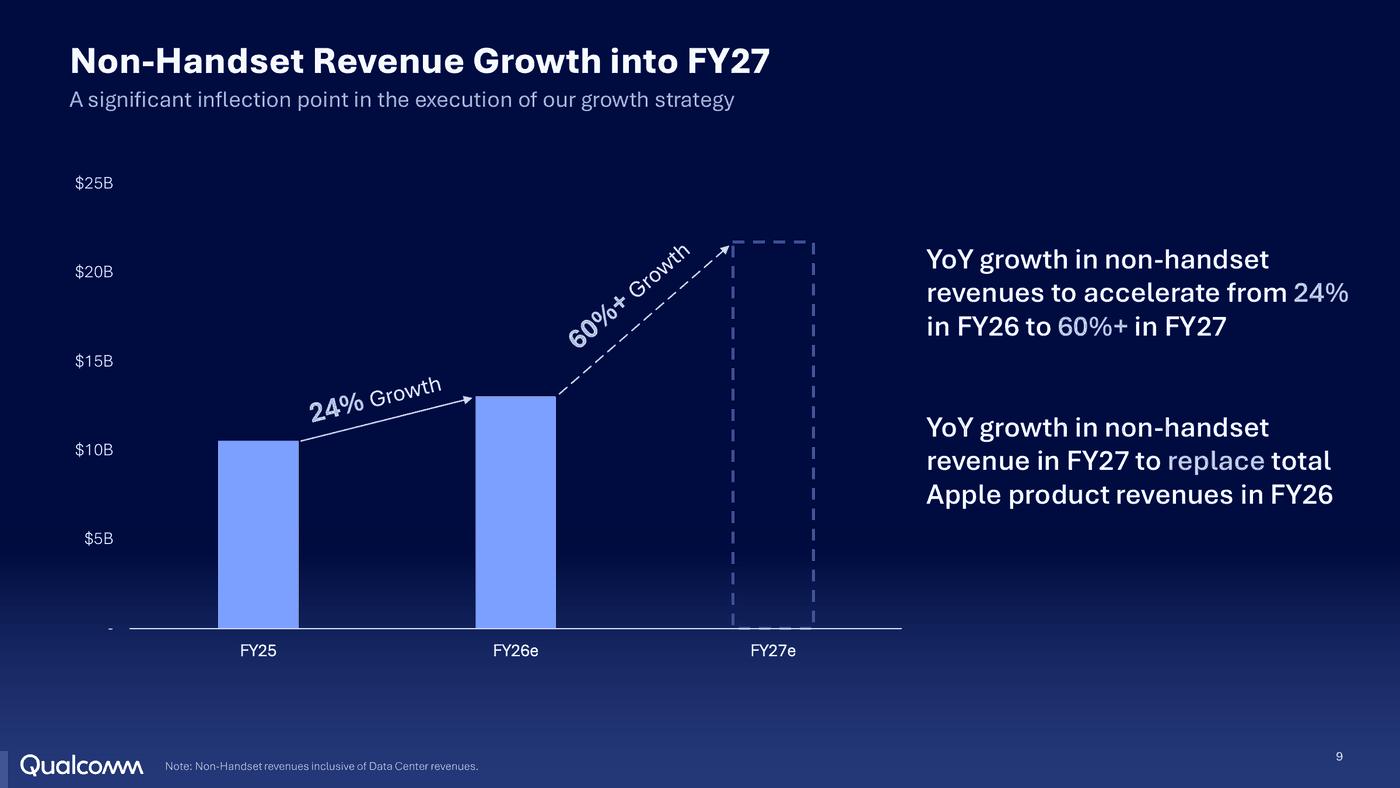
Page 9 of Qualcomm’s FY2026 Q3 earnings presentation: Management expects FY2027 non-handset revenue to grow by more than 60% YoY and replace all FY2026 Apple product revenue. This chart supports the revenue bridge; it does not mean margins have already materialized.
Data-center revenue begins ramping in FY2026, with a target of approximately $5 billion in FY2027 and at least $15 billion in FY2029. Two hyperscale customers are each expected to contribute more than $1 billion in FY2027, while custom silicon should be accretive to QCT margins. AI accelerators and CPUs remain in an “investment ahead of revenue” phase, with Dragonfly C1000 not scheduled for mass production until 2H 2028. Modular was acquired at a valuation of approximately $3.1 billion, adding a hardware-agnostic layer to the software ecosystem, but it will also introduce stock-based compensation, acquisition-related amortization, and integration costs.
Accordingly, the acceleration in FY2027 non-handset revenue growth from 24% in FY2026 to more than 60% does provide a clear revenue bridge. Management even stated that this incremental revenue would be sufficient to replace all FY2026 Apple product revenue. But “replacing revenue” is not the same as “replacing profit.” The share of wafer and packaging costs in custom silicon, the value added by software and IP, customer concentration, and R&D; reuse efficiency will determine whether its margins can approach or enhance QCT’s average margin.
This quarter’s update to the prior assessment does not overturn the “second platform” thesis; it adds a more stringent hurdle: the data-center business must demonstrate both revenue scale and earnings quality. If it delivers only high-volume, low-margin silicon shipments without sufficient software, connectivity, and platform content, Qualcomm will become larger, but not necessarily higher quality.
VI. Cash Flow and Capital Allocation: Buybacks Remain Strong, but the Buffer Is Shrinking
Qualcomm returned $2.3 billion to shareholders this quarter, including $973 million in dividends and $1.4 billion in share repurchases. Over the first nine months, cumulative repurchases reached $6.806 billion and dividends totaled $2.868 billion, with $20.562 billion of repurchase authorization remaining at the end of June. Capital returns remain consistent with the company’s longstanding approach and also support per-share metrics during the phase-out of Apple revenue and the data-center investment cycle.
However, cash flow reveals the cost of the transition more clearly than net income. Nine-month operating cash flow was $8.405 billion, down $1.611 billion YoY, while capital expenditures nearly doubled to $1.578 billion. On a rough operating-cash-flow-minus-capex basis, cash generation declined from $9.231 billion in the prior-year period to $6.827 billion. Over the same period, inventory increased by $1.798 billion to $8.379 billion; management said this included changes in customer demand resulting from memory constraints.
From the beginning of the fiscal year through quarter-end, cash, cash equivalents, and marketable securities declined from $12.478 billion to $8.304 billion, while debt stood at $15.27 billion. Part of the decline reflected the Alphawave acquisition, share repurchases, and dividends, and therefore remained the result of deliberate capital allocation. But if inventory continues to rise, price increases are delayed, and data-center investment expands, the trade-off between the pace of buybacks and acquisition funding needs will become more pronounced.
Investors should also avoid interpreting nine-month GAAP net income of $12.377 billion as an operating inflection. The release of a $5.7 billion deferred-tax valuation allowance in the second quarter materially boosted net income without an equivalent increase in operating cash flow. This quarter’s 19% effective tax rate provides a more appropriate starting point for assessing operating earnings.
VII. Four Sets of Forward Validation Metrics
First, whether handset pressure diverges along the path outlined by management. Q4 revenue from Chinese Android handsets should post double-digit sequential growth, while the decline in Apple product revenue accelerates. If Android does not rebound, memory and end-market demand issues are deeper than expected.
Second, whether price pass-through can halt the decline in QCT margins. Q4 guidance is 23%–25%, and a near-term trough is not unexpected; the key question is whether margins can recover afterward as price increases take effect. If revenue remains stable while margins continue to decline, Qualcomm’s ability to pass through costs will need to be reassessed.
Third, whether automotive and data centers can progress from revenue growth to profit contribution. Automotive must sustain both shipment growth and higher content per vehicle. For data centers, approximately $5 billion of FY2027 revenue, more than $1 billion from each of two customers, and margin accretion to QCT from custom silicon are more demanding validation milestones.
Fourth, whether inventory and cash flow recover. Inventory of $8.379 billion and declining operating cash flow should not coexist for an extended period. If inventory subsequently falls, operating cash flow recovers, and capital expenditures stabilize, it would indicate that handset destocking and growth investment are moving past their peaks. Otherwise, the transition period may last longer than the revenue guidance suggests.
Qualcomm’s results are neither a one-dimensional story of a handset-business stall nor a growth story in which automotive and AI are sufficient to obscure everything else. They look more like a speed mismatch during a gear change: new businesses are already supplying power, legacy businesses are still decelerating, and margins and cash flow are absorbing the cost of the gears engaging. Over the next several quarters, the real question is not whether long-term targets can be framed more ambitiously, but whether the changing revenue mix can begin translating into an improved profit mix and higher-quality cash flow.