
Post-Earnings Reviews from Four Major Banks on Alphabet: $400–$447 Price Targets and How 2027 Capex Is Rewriting the Valuation
目录
TL;DR
Four Banks Saw the Same Results but Discounted Different Years
First Layer of Consensus: AI Has Not Broken Search, While Cloud Has Passed the Revenue-Validation Threshold
New Post-Earnings Evidence Changed Three Things—and Left Three Existing Questions Unresolved
Second-Layer Debate: What Valuation Premium Does 82% Cloud Growth Warrant?
Third-Layer Debate: Is Capital Expenditure a Leading Indicator of Orders or a Drag on Shareholder Returns?
Third-Party Compute: The Same Cost Supports Both Citi’s Optimism and Morgan Stanley’s Caution
TPUs Turn Google from a Cloud Service Provider into a Hardware Vendor, Making Revenue Quality Harder to Compare
Gemini 4 Is the Validation Gate Between $400 and $447
Capital Structure Is Entering the Valuation Equation: AI Returns Are No Longer Determined Solely by the Income Statement
Breaking Down the Four Models: The Five Parameters That Truly Differ
Four Valuation Methods and Their Embedded Assumptions
The Four Most Common Ways to Misread These Results
Why All Four Firms Are Positive, Yet None Simply Calls the Results a “Comprehensive Beat”
Our View: Around $425 Represents a Compromise Between Demand Visibility and Cash Flow Uncertainty
The Seven Sets of Metrics That Matter Most Over the Next Four Quarters
Conclusion
本内容基于公开资料和研报数据整理,不构成任何投资建议,不代表任何个人观点,仅供学习参考,请理性阅读
Alphabet’s second-quarter 2026 results demonstrated that AI is already generating revenue and segment profit, while also revealing unprecedented capital requirements. All four banks maintained positive ratings, but their price targets ranged from $400 to $447. The valuation gap hinges on cloud margins, the pace of cash recovery, and 2027 capital expenditure.
TL;DR
All four institutions broadly agree on operating performance. Google Cloud revenue reached $24.768 billion, up 82% year over year, with operating income of $8.814 billion and a 35.6% margin. Search and other advertising revenue reached $63.271 billion, up 17%. Cloud demonstrated that AI can generate incremental revenue, while Search showed that AI has not yet undermined the existing cash cow.
The median price target is $427.50. Based on the July 22, 2026 closing price of $342.09 used across all four reports, Goldman Sachs’ $435 target, JPMorgan’s $420, Morgan Stanley’s $400, and Citi’s $447 imply upside of approximately 27%, 23%, 17%, and 31%, respectively. All targets point higher, but the $47 spread between the highest and lowest reflects different assumptions about 2027 costs and valuation multiples.
Capex is the real post-earnings debate. The company raised its 2026 capex guidance from $180–$190 billion to $195–$205 billion and said spending would increase significantly again in 2027. Goldman Sachs, JPMorgan, and Morgan Stanley forecast approximately $349.9 billion, $378.3 billion, and $375.0 billion, respectively, for 2027—suggesting capex could approach 60% of that year’s revenue.
Higher revenue estimates do not imply commensurate profit upgrades. Goldman Sachs raised its 2027 cloud revenue forecast by 13% while cutting cloud operating income by 7.8%. Citi raised its 2027 group revenue estimate by 2.5% while reducing operating income by 2.2%. Morgan Stanley cut its 2027 EPS estimate by 7%. Strong demand is forcing Google to rent third-party compute capacity, procure equipment earlier, and absorb higher depreciation, leaving incremental revenue with lower cash conversion than traditional search advertising.
Citi is the most bullish; Morgan Stanley is the most cautious. Citi views rented compute capacity as a strategic bridge necessitated by supply shortages and expects margins to recover as internally built capacity comes online, supporting its $447 target. Morgan Stanley believes higher investment has already reduced 2027–2028 earnings and that Google must still prove itself through Gemini 4 and clearer visibility into 2028 TPU revenue; it therefore cut its target from $415 to $400.
Future valuation will no longer be determined by revenue growth alone. Investors must assess Google Cloud growth, cloud margins, backlog conversion, TPU revenue mix, capex, depreciation, and financing simultaneously. The best-case scenario is sustained high cloud growth, margins holding above 30%, and operating cash flow once again covering capex.
Four Banks Saw the Same Results but Discounted Different Years
The table below compares the four conclusions. One caveat is that the price targets are not fully comparable: JPMorgan extended its target date to December 2027, Goldman Sachs and Citi use an approximately 12-month framework, and Morgan Stanley values the shares on a forward 12-month risk-reward basis. The different target dates alone explain part of the price gap.
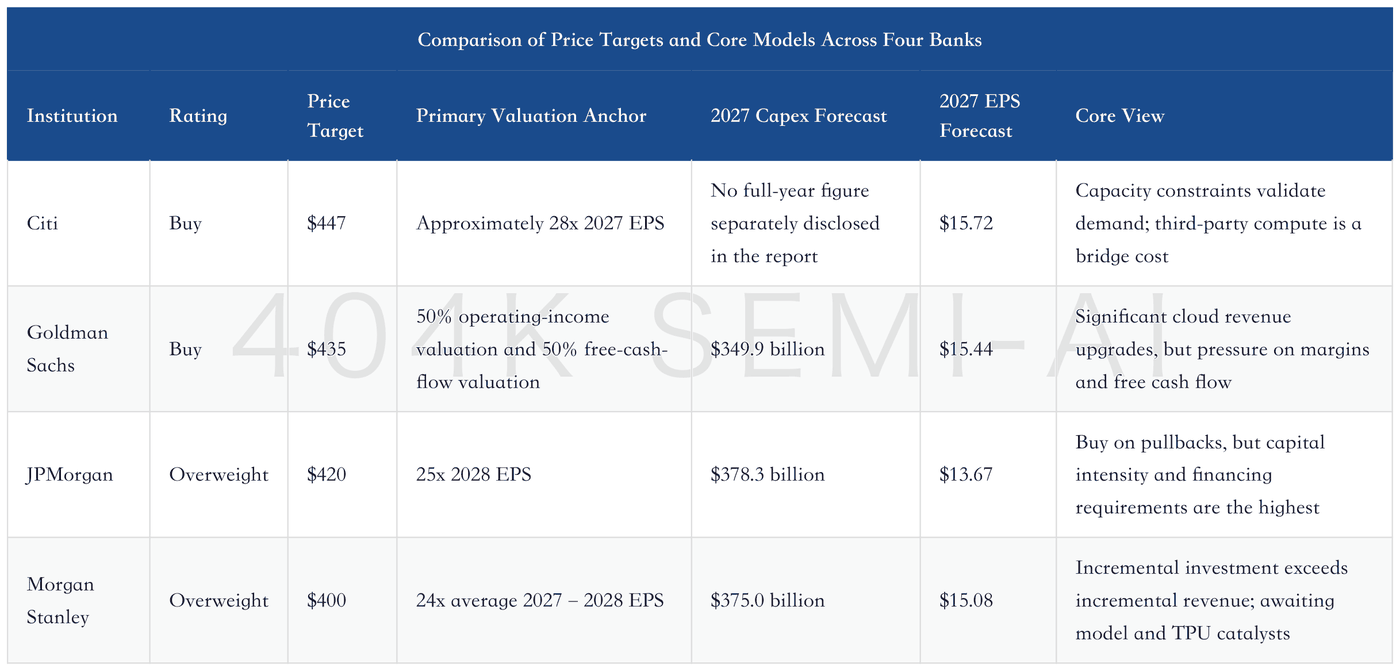
The average price target is $425.50, and the median is $427.50. This consensus appears orderly, but the underlying models are not: Citi is willing to assign 28x 2027 earnings, Goldman Sachs explicitly incorporates forward free cash flow into its valuation, JPMorgan shifts the valuation basis to 2028, while Morgan Stanley requires Google first to deliver a new frontier model and clearer TPU revenue visibility. What the market must ultimately price is whether the growth premium from Google’s evolution from an advertising platform into an AI infrastructure platform can offset the discount applied to cash flow.
First Layer of Consensus: AI Has Not Broken Search, While Cloud Has Passed the Revenue-Validation Threshold
Google generated total quarterly revenue of $119.796 billion, up 24% year over year, with operating income of $40.77 billion and a 34% margin. Looking only at EPS of $9.11 would materially overstate underlying operating performance because it included approximately $99 billion in gains on equity securities. All four reports focused their analysis on segment operations rather than annualizing non-recurring investment gains.
Search and other advertising revenue reached $63.271 billion, up 17% year over year. AI Mode exceeded 1 billion monthly active users, shopping-ad relevance improved by 20%, and AI Max had approximately 500,000 advertisers. Advertisers using AI Max or Performance Max generated, on average, approximately 15% more conversions or conversion value at broadly unchanged returns on ad spend. Citi and JPMorgan therefore concluded that AI is increasing query volumes, improving intent recognition, and creating long-tail commercial queries that were previously difficult to monetize, without yet causing users to abandon Google Search.
These figures answer the defensive question of the past two years: will generative AI directly undermine the search gateway? At least this quarter, the answer is no. However, 17% Search growth does not mean the business can sustain that pace indefinitely. Goldman Sachs lowered its 2027 and 2028 Search revenue forecasts, while JPMorgan reduced its 2027 estimate by approximately 1.6%. The reasons include tougher year-over-year comparisons, foreign exchange, changes in query mix, and the inference costs of AI-generated answers. Search has demonstrated the resilience of the core franchise—not a return to permanently elevated growth.
Google Cloud, meanwhile, answered the offensive question. Revenue reached $24.768 billion, up 81.8% year over year and $4.74 billion sequentially. Operating income rose approximately 212% to $8.814 billion, while the margin expanded from 20.7% to 35.6%. Backlog increased by approximately $52 billion sequentially to $514 billion. Nearly 90% of Fortune 100 companies use Gemini Enterprise, model APIs process approximately 22 billion tokens per minute, new-customer acquisition has more than doubled year over year, and actual usage by existing customers exceeds committed levels by more than 50%.
More importantly, Citi estimates that TPU hardware sales contributed approximately $1.2 billion. Even excluding that contribution, core cloud growth remained approximately 73%. This rules out the simplistic explanation that the entire 82% growth rate was manufactured through gross recognition of hardware revenue. All four institutions therefore acknowledge that enterprise AI demand, core cloud migrations, model usage, and compute infrastructure are accelerating together.
New Post-Earnings Evidence Changed Three Things—and Left Three Existing Questions Unresolved
The first change is that the Search risk has shifted from gateway loss to unit economics. Before the results, the most bearish assumption was that users would leave traditional Search directly, followed by advertisers. This quarter’s 17% Search growth, more than 1 billion AI Mode monthly active users, and improved ad relevance reduced the probability of that extreme outcome. The more realistic question now is whether the advertising revenue generated by complex queries can cover the additional inference resources required for AI-generated answers. Search remains a cash cow, but the evaluation framework must expand from revenue growth to revenue, cost, and profit per query.
The second change is that cloud demand has moved from management narrative to verifiable orders and profit. The $514 billion backlog, actual customer usage more than 50% above commitments, 22 billion tokens processed per minute, and a 35.6% cloud margin together provide a more complete evidence chain than revenue growth alone. Before the results, the market could question whether AI infrastructure spending was merely front-loaded. After the results, at least some of that spending is demonstrably tied to customer contracts, actual consumption, and segment profit. This is also the common basis for all four institutions maintaining positive ratings.
The third change is that the ceiling and duration of capex have been reopened. The market had previously focused on 2026 guidance of $180–$190 billion. The company has now raised that range to $195–$205 billion while continuing to emphasize significant growth in 2027. Bank models go further, projecting approximately $350–$378 billion for 2027 and more than $400 billion for 2028. The normalized valuation year has therefore shifted further out, while capital structure and depreciation have moved from footnotes to core variables.
The first unresolved issue is Gemini’s relative position in frontier models and agentic coding. User growth demonstrates distribution strength, but cannot by itself establish model capability, developer preference, or enterprise willingness to pay. Management acknowledged that coding still requires improvement, Gemini 4 remains in training, and both Morgan Stanley and Citi identified the new model release as a future validation point.
The second unresolved issue is the economic value of the backlog, which has not been fully disclosed. The company said slightly more than half of the backlog is expected to convert into revenue over the next 24 months, but it did not sufficiently disaggregate minimum commitments, TPU hardware, hosted compute, core cloud services, contract gross margins, or cancellation terms. The $514 billion backlog provides revenue visibility, but cannot be translated directly into free cash flow. This is precisely why Goldman Sachs raised its cloud revenue estimate while cutting its cloud profit forecast.
The third unresolved issue is continuing regulatory and platform-distribution risk. All four reports cite antitrust, data, and privacy regulation as risks. The stronger Search and advertising perform, the less likely regulatory scrutiny of gateways, default settings, advertising technology, and data usage is to disappear. AI has improved Google’s product competitiveness, but it will not automatically reduce the regulatory discount applied to the platform.
