
目录
TL;DR
Conclusion: The Financial Evidence Has Shifted from “Storytelling” to Simultaneous Delivery Across All Three Financial Statements
Five-Quarter Continuity: Growth, Margins, and Order Conversion Moving in the Same Direction
Business Drivers: The Evidence for AIP Is Its Integration into Workflows, Not the Customer Testimonials Themselves
Profit and Cash: An Asset-Light Model Is Not Enough; Collections and Contract Liabilities Are Critical
Guidance: Not Just a Raise, but an Embedded Mathematical Requirement for Further Acceleration in Q4
The Three Points Most Easily Misread by the Market
Disconfirming Evidence and Future Validation Metrics
Research Scope and Calculation Notes
本内容基于公开资料和研报数据整理,不构成任何投资建议,不代表任何个人观点,仅供学习参考,请理性阅读
Demand, GAAP earnings, and cash flow validated one another at the same pace for the first time. That is the core takeaway from this quarter’s results.
TL;DR
Q2 2026 revenue reached $1.935 billion, up 93% year over year and 19% sequentially; U.S. commercial and U.S. government revenue increased 149% and 90% year over year, respectively, showing that the acceleration was not driven by a single customer category.
GAAP operating income was $912 million, with a 47% margin, while operating cash flow was $1.216 billion, with a 63% margin; operating leverage has moved beyond the stage where it can only be demonstrated on a non-GAAP basis.
Order signals are strong, but TCV and RDV should not be treated as revenue. Both include unexercised customer options, and most contracts may also be terminated for convenience; non-cancelable RPO increased from $2.42 billion to $4.9 billion, making it a more stringent signal of future revenue.
The midpoint of full-year revenue guidance is $8.154 billion, implying average quarterly revenue of approximately $2.293 billion in the second half. The midpoint of Q3 guidance is $2.162 billion, so the validation points are now clear: Q3 must grow approximately 12% sequentially, and Q4 must accelerate further.
Conclusion: The Financial Evidence Has Shifted from “Storytelling” to Simultaneous Delivery Across All Three Financial Statements
The most important change this quarter was the simultaneous acceleration in revenue, improvement in gross margin, decline in expense ratios, and strengthening of cash flow. Revenue was $1.935 billion and gross profit was $1.639 billion. Based on the unaudited income statement, GAAP gross margin was approximately 84.7%, up from 80.8% in the prior-year period. Sales and marketing, R&D;, and general and administrative expenses totaled $727 million, up approximately 34% year over year, materially below revenue growth; these three expenses declined from approximately 54% of revenue to 37.5%. This was the fundamental driver of the increase in GAAP operating margin from approximately 27% to 47%.
Adjusted operating income reached $1.194 billion, with a 62% margin, but that figure should not be used to obscure stock-based compensation. Stock-based compensation was $265 million this quarter, up 66% year over year and equal to approximately 13.7% of revenue; related employer payroll taxes were $17 million. The positive is that stock-based compensation grew more slowly than revenue, allowing GAAP operating leverage to continue expanding; what still needs to be validated is whether this ratio can continue declining amid increased hiring and business expansion.
Five-Quarter Continuity: Growth, Margins, and Order Conversion Moving in the Same Direction
Looking only at Q2’s year-over-year figures could make it easy to attribute the exceptionally high growth rate to base effects. The five consecutive quarters of data in the official presentation provide stronger evidence to the contrary. From Q2 2025 to Q2 2026, quarterly revenue was $1.004 billion, $1.181 billion, $1.407 billion, $1.633 billion, and $1.935 billion, respectively. Each quarter set a new high, and sequential growth did not slow materially as the revenue base expanded. Over the same period, GAAP operating income increased from $269 million to $912 million, while adjusted operating income rose from $464 million to $1.194 billion. Adjusted operating margins were 46%, 51%, 57%, 60%, and 62%, respectively, showing that margin expansion was a continuous process rather than a one-quarter fluctuation in expenses.
This continuity also extends to order conversion. Over the five quarters, RPO increased from $2.42 billion to $4.9 billion, including an increase in short-term RPO from $1.02 billion to $2.09 billion; billings rose sequentially from $1.102 billion to $1.226 billion, $1.489 billion, $1.750 billion, and $2.072 billion. Growth in short-term RPO and billings corroborates revenue growth, indicating that at least part of the large contracts is converting into recognizable and billable activity. Conversely, if TCV and RDV continue growing rapidly but short-term RPO, billings, and deferred revenue no longer follow, it may indicate weakening option exercise, delivery progress, or customer payment terms.
The customer mix provides a third layer of validation. The number of U.S. commercial customers increased 35% year over year, materially below the segment’s 149% revenue growth; net dollar retention rose to 157%, indicating that incremental revenue did not come solely from new customers, with expansion among existing customers also serving as an important driver. Of the 220 transactions worth more than $1 million this quarter, 98 exceeded $5 million and 73 exceeded $10 million, showing that expansion was not limited to low-value trials. However, higher contract values also increase delivery complexity and volatility in cash collection, so future analysis must consider customer count, retention, and accounts receivable together rather than substituting any single metric for a complete assessment.
The Rule of 40 increased from 94% in Q2 2025 to 155% currently, also reflecting simultaneous increases in revenue growth and adjusted operating margin. The structural significance of this trend is greater than the standalone 155% figure: most high-growth companies trade current-period expenses for future scale, whereas Palantir is currently expanding sales and delivery while improving margins. This does not guarantee that the metric will continue rising linearly, but it does show that this quarter’s results extend an ongoing operating trend. Therefore, the most informative future divergence will not be whether the company maintains 155%, but whether GAAP operating margin, short-term RPO, and billings continue moving in the same direction.
Business Drivers: The Evidence for AIP Is Its Integration into Workflows, Not the Customer Testimonials Themselves
The official presentation positions AIP as an operating system for sovereign AI: customers can run models on-premises, in sovereign clouds, or at the edge while retaining control over their data, semantic layer, code, and permission boundaries. Use cases range from private-equity fundraising at Kirkland to uranium-enrichment capacity expansion at Centrus, SAP migration, McCarthy construction sites, USDA agricultural subsidies, and customer service and repairs at Parts Town. These cases point to one common feature: the product does not merely provide model access; it integrates models into existing data, permissions, and execution workflows.
However, case studies are evidence of the commercialization path, not a substitute for proof of revenue. The harder evidence appears on page 14: the number of U.S. commercial customers reached 653, up 35% year over year and 6% sequentially; U.S. commercial RDV was $6.238 billion, up 124% year over year; and quarterly U.S. commercial TCV reached $2.132 billion, up 153% year over year. The simultaneous increase in customer count, large transactions, and transaction value provides stronger evidence than any single flagship customer that AIP is moving from pilots into a replicable deployment phase.
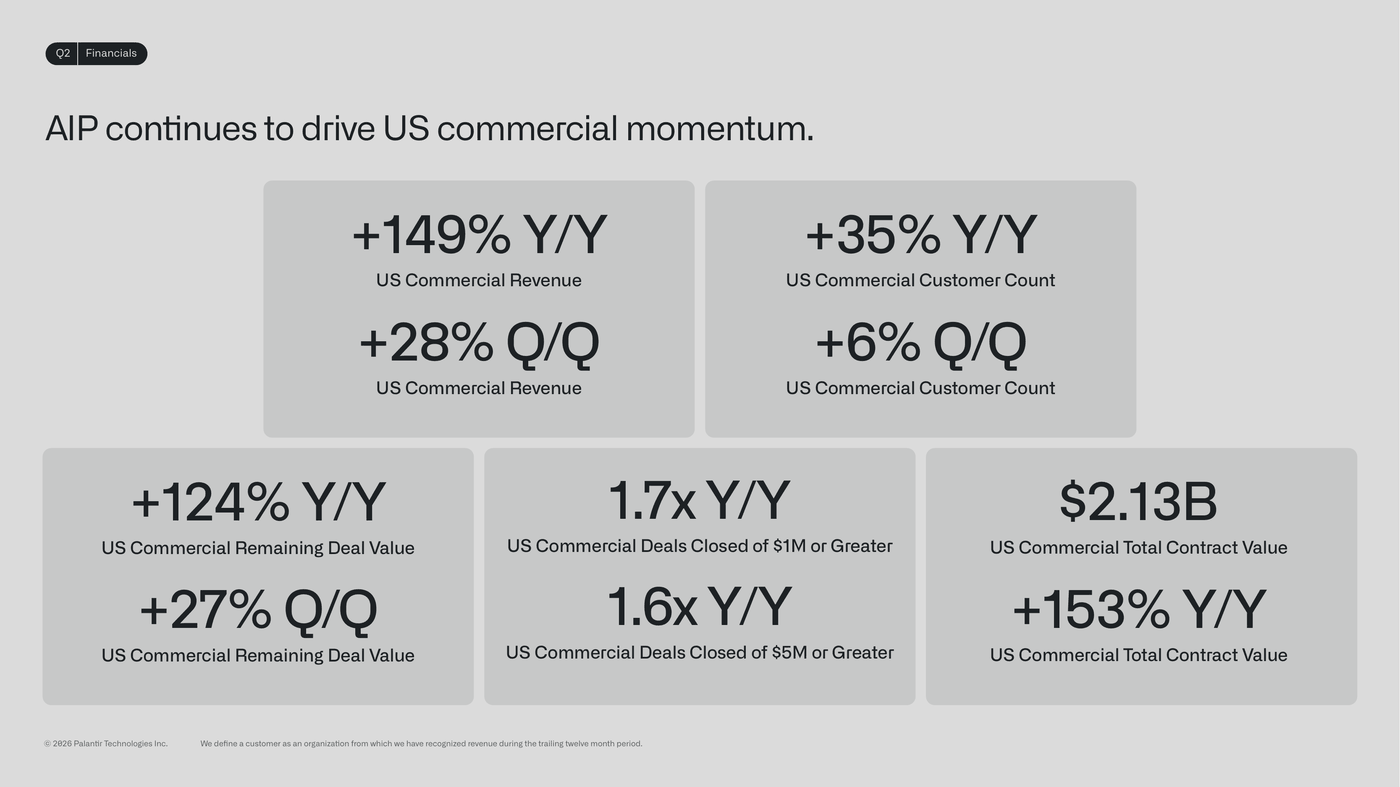
Palantir Q2 2026 Business Update, physical page 14: cross-validation across U.S. commercial revenue, customer count, RDV, and TCV.
The government business is not merely a backdrop either. U.S. government revenue was $809 million, up 90% year over year and 18% sequentially; U.S. commercial revenue was $764 million, up 149% year over year and 28% sequentially. Globally, commercial and government revenue totaled $945 million and $990 million, respectively, representing year-over-year growth of 110% and 79%. These figures rebut both oversimplified narratives—that growth depends solely on U.S. commercial customers or solely on large government contracts.
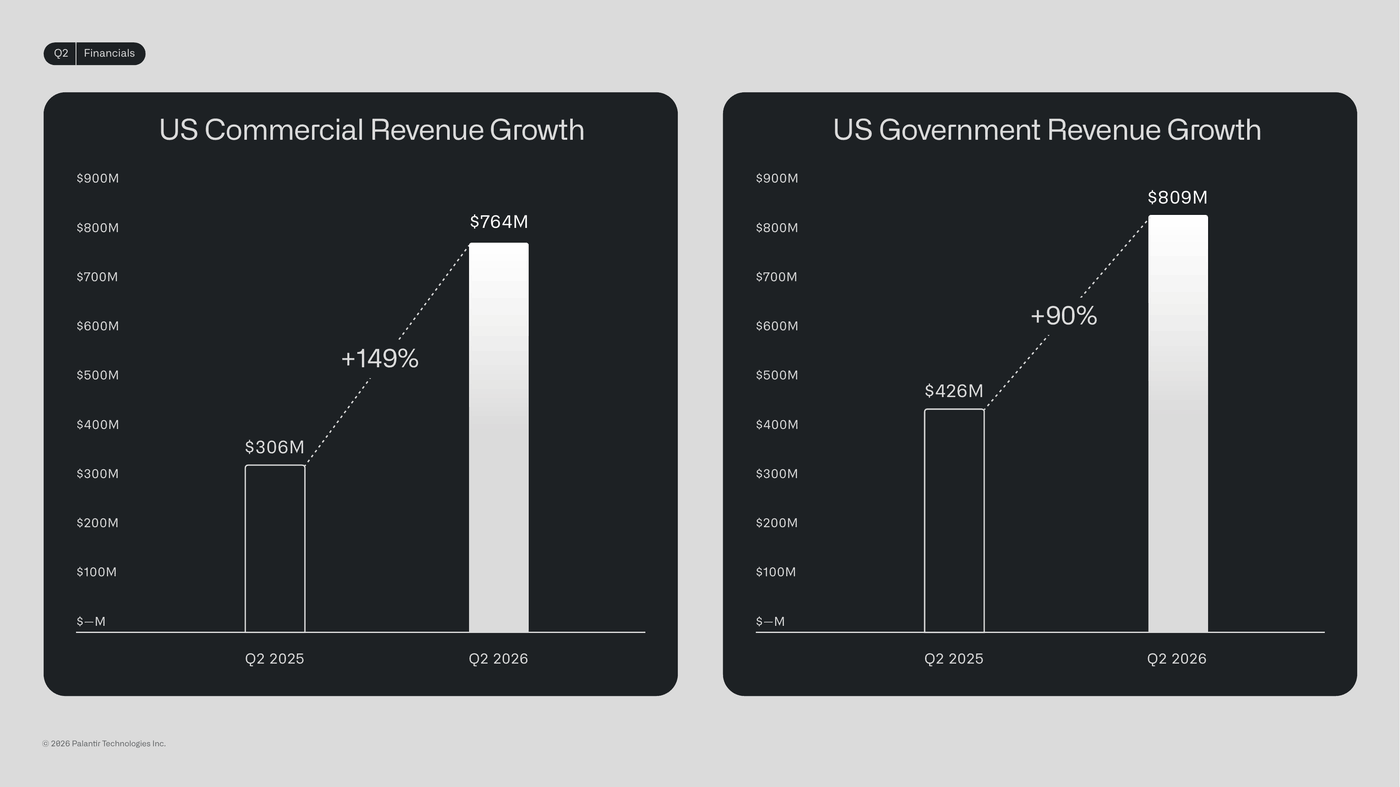
Palantir Q2 2026 Business Update, physical page 19: both U.S. commercial and government revenue accelerated materially.
Profit and Cash: An Asset-Light Model Is Not Enough; Collections and Contract Liabilities Are Critical
Operating cash flow was $1.216 billion this quarter, up 126% year over year; adjusted free cash flow was $1.22 billion, with a 63% margin. The difference between the two was minimal because the adjusted measure added back $19 million in stock-based-compensation-related employer payroll taxes and then deducted $15 million in capital expenditures. First-half capital expenditures were only $22 million, showing that expansion of AIP has not transformed the software model into an asset-heavy one.
The cash flow statement also highlights two working-capital changes worth tracking. Accounts receivable produced a $434 million cash outflow in the first half, while contract liabilities generated a $257 million cash inflow. As of the end of June, accounts receivable had increased from $1.042 billion at the beginning of the year to $1.485 billion, consistent with accelerating revenue but also indicating that future analysis cannot focus solely on aggregate contract value; billings conversion and cash collection must also be monitored.
On the balance sheet, cash and cash equivalents were $2.03 billion and marketable securities were $7.379 billion, totaling approximately $9.41 billion. The official presentation reported approximately $9.2 billion under its definition of cash, cash equivalents, and U.S. Treasury securities, with no debt. Although the definitions differ, the conclusion is the same: near-term capital constraints are minimal. The materials for this period do not indicate that large-scale share repurchases or M&A; were major uses of cash, and most liquidity remains held in marketable securities.
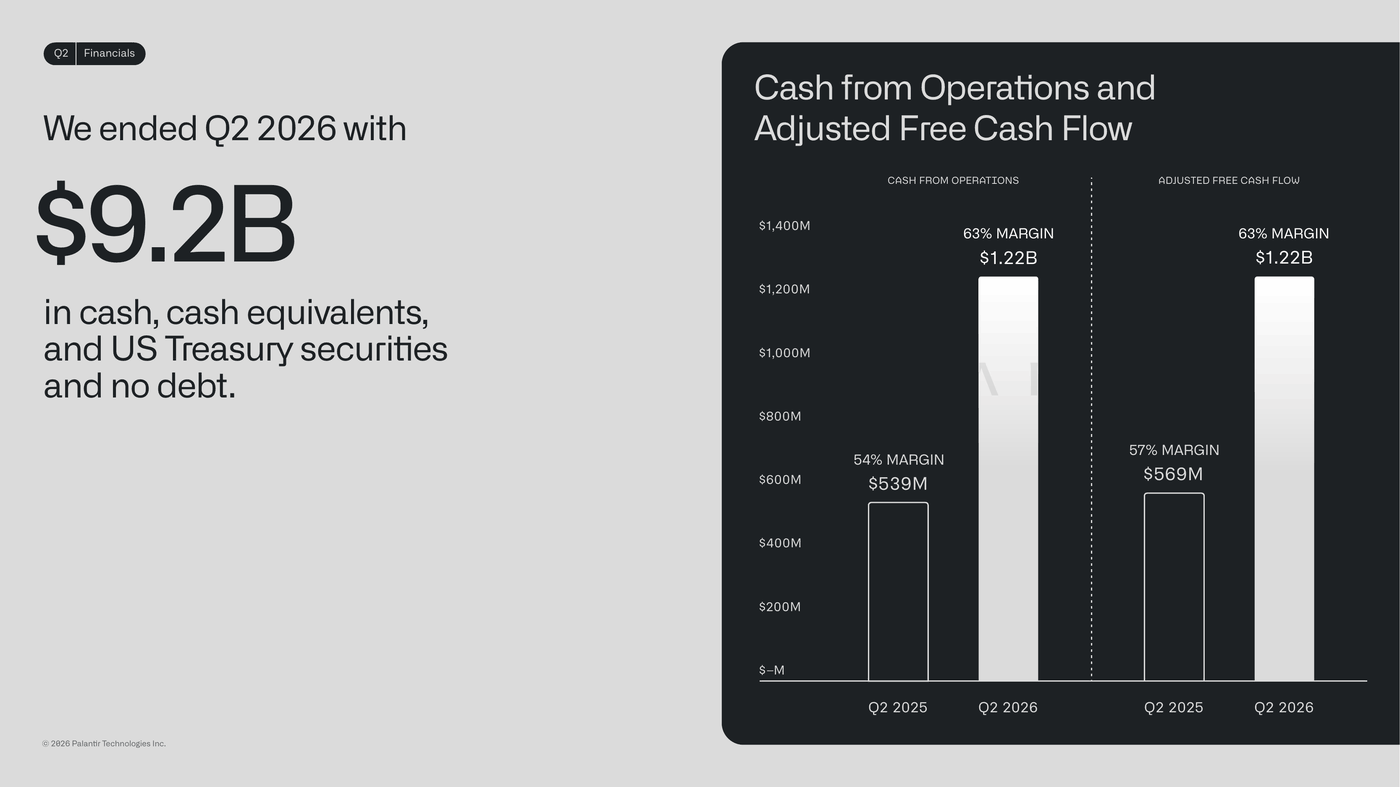
Palantir Q2 2026 Business Update, physical page 26: cash, no debt, and a 63% operating/adjusted free cash flow margin.
Guidance: Not Just a Raise, but an Embedded Mathematical Requirement for Further Acceleration in Q4
Management expects Q3 revenue of $2.160 billion to $2.164 billion and adjusted operating income of $1.292 billion to $1.296 billion. At the midpoint, revenue would grow approximately 11.7% sequentially from Q2, with an adjusted operating margin of approximately 59.9%, below Q2’s 62%. This does not necessarily imply deteriorating earnings quality and is more likely to reflect continued investment, delivery cadence, and customer mix; however, if revenue exceeds guidance while margins still decline, the delivery costs of new contracts will need to be reassessed.
Full-year revenue guidance is $8.150 billion to $8.158 billion, adjusted operating income guidance is $4.889 billion to $4.897 billion, and adjusted free cash flow guidance is $4.5 billion to $4.7 billion. Revenue totaled $3.568 billion in the first half; based on the full-year midpoint, the second half must generate approximately $4.586 billion, or an average of $2.293 billion per quarter. Subtracting the midpoint of Q3 guidance implies Q4 revenue of approximately $2.424 billion, requiring another approximately 12.1% sequential increase from Q3. This is a mathematical derivation based on official guidance, not separate Q4 guidance issued by the company.
Full-year U.S. commercial revenue guidance is above $3.424 billion, corresponding to growth of at least 134%. Back-solving from Q2 revenue of $764 million and 28% sequential growth gives estimated Q1 U.S. commercial revenue of approximately $597 million; therefore, the second half must contribute more than $2.06 billion, or over $1.03 billion per quarter on average. Because the sequential growth percentage is rounded, this calculation is used only to gauge the strength of the guidance; it nevertheless clearly shows that U.S. commercial revenue cannot merely remain at Q2’s absolute level in the second half.
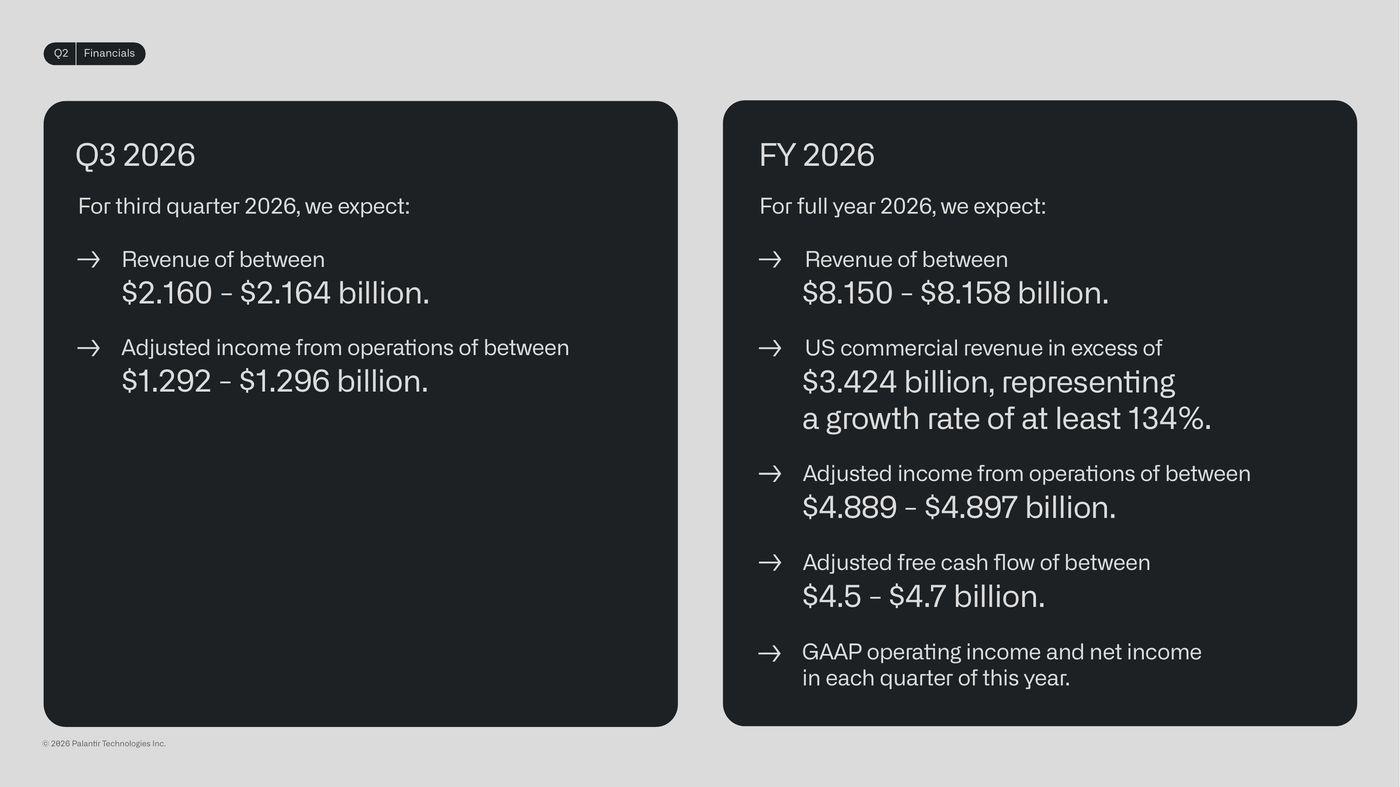
Palantir Q2 2026 Business Update, physical page 27: Q3 and FY2026 guidance for revenue, adjusted operating income, U.S. commercial revenue, and free cash flow.
The Three Points Most Easily Misread by the Market
First, “Rule of 40 reached 155%” is not a standardized metric that can be compared unconditionally across all companies. Palantir derives 155% by adding 93% year-over-year revenue growth to a 62% adjusted operating margin; however, the adjusted margin excludes stock-based compensation and related employer payroll taxes. A more comparable approach is to track the GAAP operating margin alongside it, which was 47% this quarter.
Second, “contract value surged” does not mean an equivalent amount of revenue has already been secured. TCV is the potential total lifecycle value at signing, while RDV is the remaining value at period-end; both generally assume that customers exercise all options and do not terminate their contracts. RPO represents non-cancellable contracted amounts and is recognized as revenue only after the related performance obligations are satisfied in future periods; however, under a practical expedient in accounting standards, contracts with an original term of one year or less are not disclosed. The correct approach is to use TCV/RDV to assess demand strength, RPO to assess more stringent long-term visibility, and billings, deferred revenue, and cash flow to evaluate actual conversion.
Third, adjusted net income is not always higher than GAAP net income. This quarter, GAAP net income attributable to common stockholders was $1.062 billion, while adjusted net income was $1.047 billion, which was slightly lower. This was because $297 million of tax effects and adjustments exceeded the add-back for stock-based compensation and related employer payroll taxes. Diluted EPS was $0.41 under both measures, also because the tax adjustment eliminated the difference—not because stock-based compensation has disappeared.
Disconfirming Evidence and Future Validation Metrics
Current evidence supports the conclusion that “AIP commercialization and government demand are accelerating simultaneously, while scale benefits are flowing through to GAAP earnings and cash flow.” However, disproving this conclusion does not require waiting for the broader narrative to reverse; sustained deterioration in the following observable indicators would be sufficient:
Whether Q3 revenue reaches $2.160 billion to $2.164 billion and whether actual sequential growth can approach 12%.
Whether the Q3 adjusted operating margin remains around 60% while the GAAP operating margin continues to expand, rather than maintaining Rule of 40 solely through add-backs.
Whether U.S. commercial revenue can grow faster than customer count and whether NDR can remain at 157%; this will distinguish between “new-customer additions” and “deeper expansion among existing customers.”
Whether RPO, current RPO, billings, deferred revenue, and operating cash flow can grow in the same direction as TCV/RDV; if only TCV/RDV increases, conversion risk will rise.
Whether accounts receivable and stock-based compensation as a percentage of revenue continue to decline. The former validates collection quality, while the latter validates the sustainability of GAAP operating leverage.
Whether the full-year targets of $4.5 billion to $4.7 billion in adjusted free cash flow and more than $3.424 billion in U.S. commercial revenue can be delivered; these are management’s two most challenging commitments for the second half.
Overall, Palantir’s product replication, contract expansion, GAAP profitability, and cash-generation capabilities all advanced to a new level this quarter. Going forward, the analytical focus should shift to whether massive AIP demand can continue to convert into revenue, translate into cash collections, and be delivered with limited dilution.
Research Scope and Calculation Notes
This report uses only Palantir Technologies Inc.’s unaudited Q2 2026 financial statements in official Form 8-K Exhibit 99.1 and its 36-page Business Update presentation, with the company’s official SEC-filed Forms 10-Q and 10-K used to establish the financial baseline for the past two years. It does not use media reports, sell-side research, market valuations, or price targets. Sequential growth rates, margins, and implied second-half figures in this report are calculations based on official data, not additional company guidance; this report does not constitute a recommendation to buy or sell any security.