
目录
One Timeline Revision Has Shifted the Market Debate
Scale-Out, Scale-Up, and Scale-Across Determine Where Incremental Demand Emerges
Four Sets of Multiples Explain the Elasticity of Optical-Connectivity Demand
Why the Timeline Could Accelerate—and Why Capacity Still Constrains Delivery
Sumitomo Electric’s Advantage Lies in Its Coverage of Multiple Critical Links
Furukawa Electric, Fujikura, and US Optical-Component Suppliers Benefit from Different Variables
Indium Phosphide Substrates Could Become an Upstream Bottleneck, with Two Supply Relationships Still Unclear
Converting Industry Demand into Revenue, Profit, and Cash Flow Requires Clearing Four Hurdles
Earlier Demand Has Very Different Implications Under Three Scenarios
What Would Invalidate the Current Thesis
Focus Next on Orders, Qualification, and Mass Production—Not More Rhetoric
本内容基于公开资料和研报数据整理,不构成任何投资建议,不代表任何个人观点,仅供学习参考,请理性阅读
Optical scale-up demand is showing signs of arriving earlier than expected. Lumentum has brought forward its NPO launch timeline by approximately one year, while Coherent says customers are also accelerating their requirements. If these plans materialize, optical connectivity will move from inter-rack to intra-rack applications, creating incremental demand for lasers, optical fiber, connectivity components, and indium phosphide substrates.
One Timeline Revision Has Shifted the Market Debate
The market had previously worried that CPO adoption would be slower than expected, and shares of three Japanese cable companies pulled back following reports of deployment delays. The debate centered on when large AI clusters would need to place optical engines near switch chips and whether this transition would be sufficient to support upstream capacity expansion. Nomura’s September 1 report incorporated the latest comments from Lumentum, Coherent, and Applied Optoelectronics, providing a clearer demand signal.
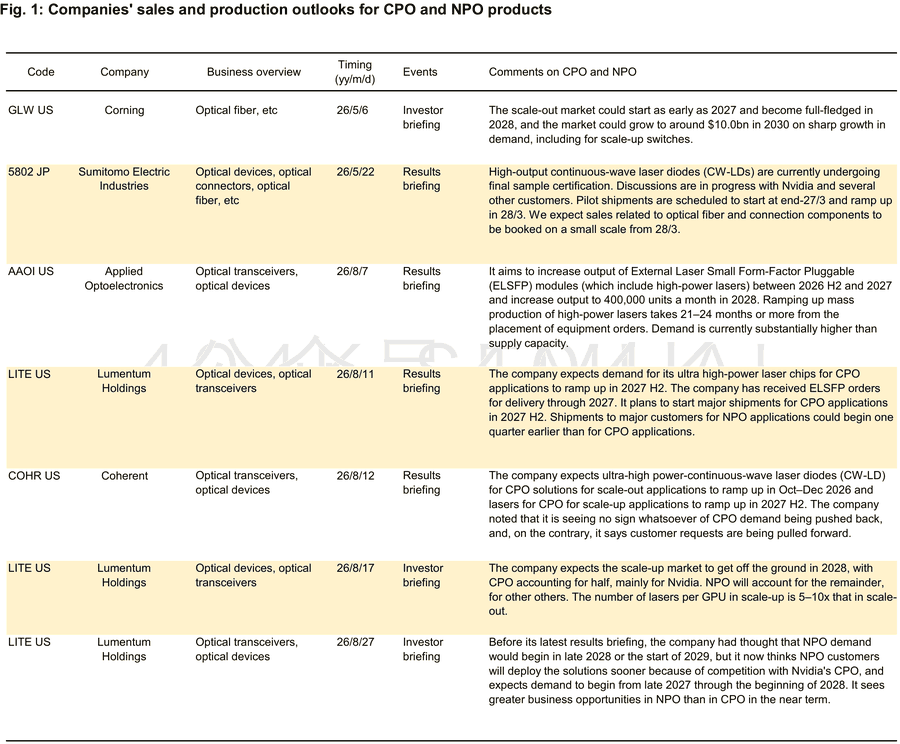
At its August 27 investor meeting, Lumentum revised its NPO timeline. The company had previously expected demand to begin in late 2028 or early 2029, but now anticipates a start in late 2027 to early 2028—approximately one year earlier. It also believes that NPO could generate more business than CPO in the near term. Customer competition is the key driver: Nvidia has secured substantial CPO component supply through long-term agreements, prompting other customers to adopt NPO more aggressively as they seek to upgrade interconnect capacity faster.
Coherent is signaling the same direction. The company has seen no delay in CPO demand; instead, customers are bringing requirements forward. It expects ultra-high-power continuous-wave lasers for scale-out applications to begin ramping between October and December 2026, followed potentially by scale-up applications in the second half of 2027. Applied Optoelectronics said current demand materially exceeds supply capacity and plans to raise monthly ELSFP production to 400,000 units in 2028.
These comments increase the credibility of an earlier demand cycle, but they do not constitute realized shipments. Suppliers may allocate capacity based on customer forecasts, while customers may still revise architecture choices, deployment schedules, and procurement volumes. The market debate has shifted from “Will CPO be delayed?” to “Which customers and applications will adopt CPO and NPO first?” This broadens the analytical framework and means that the success or failure of any single architecture will no longer determine overall optical-connectivity demand.
Scale-Out, Scale-Up, and Scale-Across Determine Where Incremental Demand Emerges
The key to understanding this report is to distinguish among three types of network connectivity. Scale-out connects more servers, racks, or switches to expand a cluster horizontally. Scale-up increases communication capacity among GPUs and chips within the same compute domain, allowing more accelerators to operate as a single large machine. Scale-across connects computing resources across different data halls or locations, mitigating power and site constraints.
Traditional scale-out networks already use optical modules extensively. In this setting, CPO primarily moves the optical engine from a pluggable module to a position near the switch chip. This shortens transmission distances, reduces electrical loss, and enables higher port density. It raises the technical requirements for lasers, fiber arrays, connectors, and packaging, although part of the demand replaces existing optical modules. Total optical-connection volumes remain driven by the number of switching tiers and ports, as well as bandwidth upgrades.
The economics of scale-up are different. Intra-rack connections currently rely primarily on copper cabling. As GPU counts and per-port speeds increase, copper interconnects face constraints in reach, power consumption, heat dissipation, and signal integrity. If even part of these links shifts to optical connectivity, connections that previously contained no optical components will require lasers, optical engines, fiber, and connectivity components. Because this market is growing from a near-zero base, its incremental demand potential is more significant.
Both CPO and NPO can support this transition. CPO places the optical engine in the same package as, or immediately adjacent to, the switch chip, minimizing the length of the copper electrical connection and making it suitable for systems targeting extremely high bandwidth density. NPO positions the optical engine near the chip but retains a somewhat longer copper connection. It offers greater flexibility in integration, maintenance, and system design; its continuous-wave lasers generally require slightly less power, and its fiber runs may also be shorter than those in CPO systems.
The per-device value opportunity cannot be assumed to be the same across the two architectures. NPO has a different mix of high-power lasers, fiber, and connectivity components from CPO. Nevertheless, it still converts formerly copper-based links to optical connectivity and therefore expands the optical-component market. Lumentum expects Nvidia to favor CPO and other customers to lean toward NPO, suggesting that the two architectures may coexist over the long term. The supply chain must therefore monitor customer mix and product mix rather than focusing solely on the penetration rate of one architecture.
Scale-across represents a longer-term source of incremental demand. Large data centers face constraints in power, land, and construction lead times, potentially forcing computing capacity to be distributed across multiple campuses. Coordinating resources across campuses requires longer-reach, more reliable optical connections. Lumentum believes the potential demand from this application remains underestimated. However, clear mass-production volumes and timelines are not yet available, making scale-across a medium- to long-term watch item rather than revenue that can already be treated as certain.
Four Sets of Multiples Explain the Elasticity of Optical-Connectivity Demand
Citing Corning materials, Nomura breaks the growth in optical-fiber and cabling-material demand into four drivers. First, once a single cluster exceeds 130,000 GPUs, a two-tier network may no longer be sufficient and may need to expand to three tiers. Corning estimates that adding a network tier could increase demand by approximately 50%, equivalent to roughly 1.5 times the amount of fiber and cabling materials.
Second, upgrading bandwidth from 400G to 3.2T changes fiber counts. Fiber counts may double in the transition from 400G to 800G. Whether the move from 800G to 1.6T requires more fiber depends on the per-wavelength data rate. At 3.2T, fiber counts may double again if each wavelength carries 200G, but could remain stable if each wavelength carries 400G. The overall increase from 400G to 3.2T is therefore approximately 2 to 4 times.
