
目录
Executive Summary
From a Two-Year Downturn to This Quarter’s Inflection Point: The Recovery Has Begun, but the Previous Peak Remains Distant
PSG Is the Revenue Engine, While AMG and ISG Remain Counterevidence
AI Power Tree: Content Could Increase Nearly Eightfold, but Revenue Recognition Comes with a Time Lag
Gross Margin Is the Hardest Validation Metric in This Earnings Report
The GAAP Rebound Must Be Viewed in the Context of Restructuring Charges
Free Cash Flow Was a Highlight, with Low Capital Expenditure Also an Important Driver
Convertible Notes Increased Cash but Also Complicated the Share-Count Framework
Synaptics Broadens the Platform Boundary but Also Adds Integration Risk
The Five Points Most Likely to Be Misread by the Market
Validation Checklist for the Next Four Quarters
Conclusion: From “Past the Trough” to “Proving the Profit Platform”
Research Scope and Official Sources
本内容基于公开资料和研报数据整理,不构成任何投资建议,不代表任何个人观点,仅供学习参考,请理性阅读
onsemi has passed the revenue trough, with its power business, gross margin, and cash flow beginning to improve in tandem.
Executive Summary
This quarter’s concentrated recovery was led by the power business and AI demand. onsemi (ON) reported second-quarter revenue of $1.6035 billion, up 6% sequentially and 9% year over year; however, automotive end-market revenue declined 2% sequentially, while industrial grew only 1%. The real drivers were a 13% sequential increase in Power Solutions Group (PSG) revenue and 34% sequential growth in the “Other” end market, which includes AI data centers.
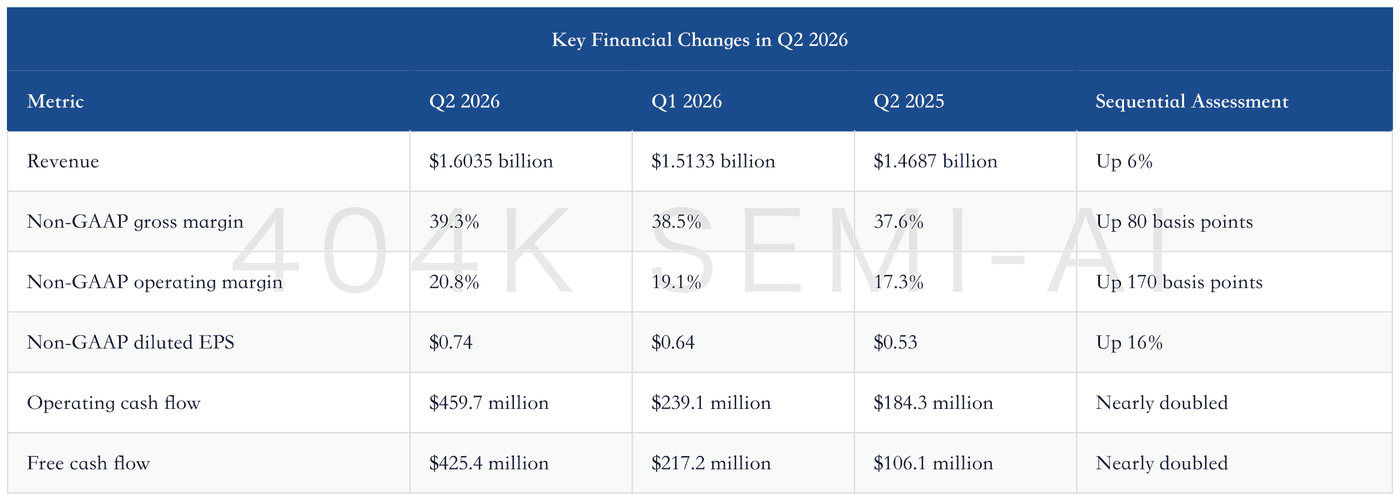
Earnings quality was stronger than revenue growth. Non-GAAP gross margin was 39.3%, up 80 basis points sequentially and 170 basis points year over year; operating margin was 20.8%, up 170 basis points sequentially; diluted EPS was $0.74, up 16% sequentially. This indicates that the revenue recovery has begun to translate through fixed-cost absorption and expense discipline into operating leverage.
Third-quarter guidance provides a second stage of validation. The revenue midpoint is $1.7 billion, implying approximately 6% sequential growth; the non-GAAP gross-margin midpoint is 41%, another 170-basis-point sequential improvement; and the EPS midpoint is $0.87, approximately 18% higher sequentially. If achieved, the market’s focus will shift from whether revenue has bottomed to whether gross margin can sustainably return to a higher level.
Free cash flow of $425.4 million was very strong, but should not be mechanically annualized. Operating cash flow was $459.7 million this quarter, while capital expenditure was only $34.30 million, producing a free-cash-flow margin of approximately 26.5%. Low capital expenditure and a $44.60 million net working-capital inflow jointly amplified the quarterly result; the more prudent anchor is the 24.2% free-cash-flow margin over the past 12 months.
The most easily misread items are the GAAP rebound, AI content opportunity, and share repurchases. The sharp decline from the first quarter’s $329.3 million restructuring charge lifted GAAP operating margin from -3.5% to 16.1%; the increase in AI rack content from approximately $15,000 to approximately $115,000 is management’s estimate for the 2030 800V architecture, not confirmed orders; and while share repurchases reduced the share count, $1.3 billion of convertible notes created different diluted share-count treatments under GAAP and non-GAAP reporting.
From a Two-Year Downturn to This Quarter’s Inflection Point: The Recovery Has Begun, but the Previous Peak Remains Distant
onsemi is a semiconductor company focused on intelligent power and sensing. Its products span silicon power devices, silicon carbide, gallium nitride, analog and mixed-signal chips, image sensors, and system solutions, primarily serving automotive, industrial, and AI data-center markets. For this company, revenue is only the first-order variable; more important is how the power-device mix, factory utilization, and product mix collectively affect gross margin.
Official data from the past two years provide clear reference points. Revenue was $7.0823 billion in 2024, with a non-GAAP gross margin of 45.5% and operating margin of 27.9%; in 2025, revenue declined 15% year over year to $5.9954 billion, while gross margin fell to 38.4% and operating margin to 18.6%. In other words, this downturn not only reduced revenue but also eroded gross margin by approximately 7 percentage points and operating margin by 9.3 percentage points. Revenue was $1.5133 billion in the first quarter of 2026, when management stated that the cycle had passed its trough; second-quarter revenue increased to $1.6035 billion, while trailing-12-month revenue reached approximately $6.1978 billion, marking the first sustained sequential recovery.
However, this quarter cannot yet be characterized as a broad-based recovery. The presentation showed automotive end-market revenue of $781 million, down 2% sequentially; industrial revenue of $423 million, up 1%; and Other end-market revenue of $400 million, up 34%. The company did not define all of “Other” as AI, so the entire $400 million cannot be directly classified as data-center revenue. What can be confirmed is that management described AI data centers as its fastest-growing business and raised its 2026 related revenue outlook to growth of more than 100%.
PSG Is the Revenue Engine, While AMG and ISG Remain Counterevidence
Segment data explain the underlying drivers better than consolidated revenue. PSG generated revenue of $829 million, up 13% sequentially and 19% year over year, accounting for the vast majority of the company’s incremental revenue; Analog and Mixed-Signal Group (AMG) revenue was $545.7 million, up 1% sequentially and down 2% year over year; Intelligent Sensing Group (ISG) revenue was $228.8 million, down 3% sequentially and up 7% year over year.
PSG benefits because AI data centers increase demand for MOSFETs, silicon carbide, gallium nitride, controllers, and power stages across the entire chain—from the grid, energy storage, backup power, hot-swap, and intermediate bus to the GPU core. This quarter, onsemi disclosed an expanded collaboration with the NVIDIA MGX ecosystem, a design win for Great Wall’s cloud-infrastructure power platform, and the launch of GaNEXUS covering 40V to 650V. On the automotive side, it also secured Rivian R2 zonal-architecture and onboard-charging solutions, but end-market revenue still declined sequentially, demonstrating that design wins and near-term industry demand must be assessed separately.
The performance of AMG and ISG, however, reminds investors that onsemi has not yet completed a smooth transition from a power-semiconductor company into a full-stack, high-growth platform. The Treo 65nm BCD platform covers 1V to 90V, and the company says it can shorten the path from specification to silicon to 6 to 9 months; image sensors also continue to have automotive and industrial applications. Nevertheless, the combined revenue of these two businesses did not show the same momentum as PSG this quarter. If PSG continues to grow while AMG and ISG stagnate, consolidated revenue will improve, but more evidence will still be needed regarding the long-term product mix and gross-margin ceiling.
AI Power Tree: Content Could Increase Nearly Eightfold, but Revenue Recognition Comes with a Time Lag
onsemi breaks down the AI data-center opportunity into a power tree extending from the grid to the GPU core. In today’s 54V, 120 kW racks, the company estimates addressable content of approximately $15,000 per rack; by 2030, if the architecture shifts to 800V high-voltage direct current and rack power rises to 600 kW to 1 MW, estimated content would reach approximately $115,000, nearly 7.7 times the current level. The increase in content is not driven by higher prices for individual devices, but by the need for more power semiconductors across high-voltage conversion, hot-swap, protection, backup power, and multi-stage voltage-conversion functions.
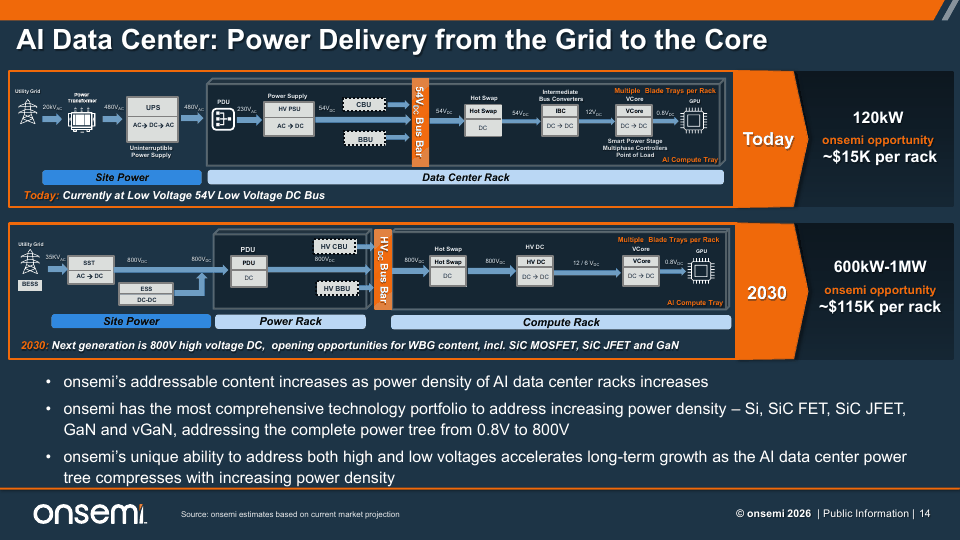
Source: Page 14 of onsemi’s “Q2 2026 Quarterly Investor Presentation.” The chart supports the 54V-to-800V power tree, rack-power assumptions, and the company’s content estimates; the figures are onsemi’s estimates based on current market forecasts.
Three boundaries must be preserved here. First, $15,000 and $115,000 are the company’s estimates of the opportunity, not actual average selling prices or orders. Second, the 2030 800V architecture cannot be pulled forward into the next four quarters; more realistic evidence for 2026 will be samples, qualifications, platform adoption, and AI revenue growth. Third, the wide-bandgap roadmap still carries mass-production risk: onsemi says its 700V and 1200V vertical GaN devices have been sampled to early customers, with mass production targeted for year-end 2026; any delay in mass production, yields, or customer qualification would defer earnings realization.
This is also consistent with our previous assessment of the 800V data-center power tree: the architectural upgrade represents a structural opportunity, but the key indicators in 2026 are design adoption and qualification; the end-state 2030 power tree cannot be treated directly as current-period revenue.
Gross Margin Is the Hardest Validation Metric in This Earnings Report
Revenue increased 6%, non-GAAP operating income rose 15%, and earnings per share grew 16%, indicating that profit growth has already outpaced revenue growth. Second-quarter non-GAAP gross margin was 39.3%, marking the fourth consecutive quarter of improvement; operating expenses were $296.8 million, only $3.1 million higher than in the first quarter, allowing more revenue growth to flow through to operating income.
Third-quarter guidance extends this operating leverage: revenue of $1.65 billion to $1.75 billion, non-GAAP gross margin of 40% to 42%, operating expenses of $303 million to $318 million, and earnings per share of $0.81 to $0.93. At the midpoint, revenue would grow approximately 6% sequentially, gross margin would expand by 170 basis points, and earnings per share would increase approximately 18%. Gross-margin expansion outpacing revenue growth implies that at least some combination of product mix, utilization, cost structure, and pricing is improving concurrently.
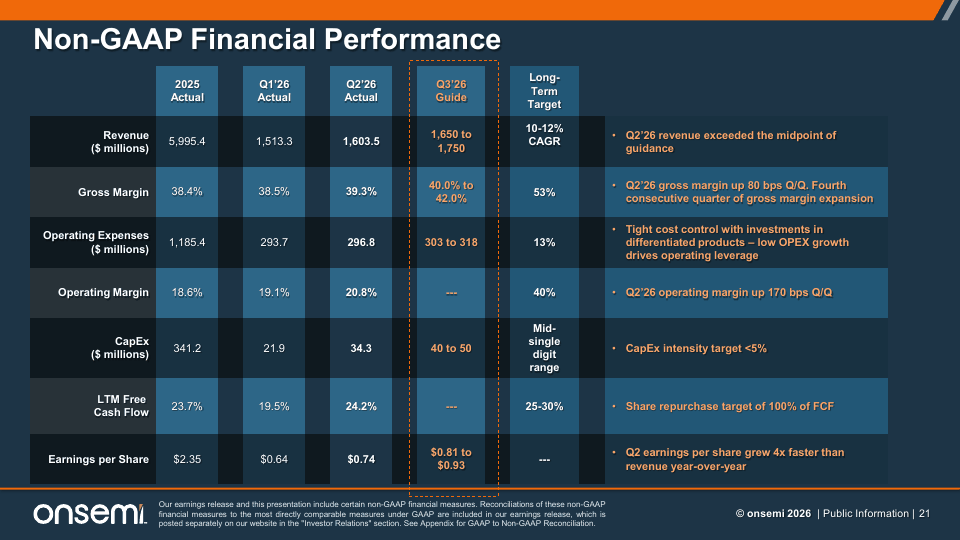
Source: Page 21 of onsemi’s “Q2 2026 Quarterly Investor Presentation.” The chart compares 2025, Q1/Q2 2026, Q3 guidance, and long-term non-GAAP targets.
However, the long-term targets are still not the base-case forecast. The company has set targets of 10% to 12% revenue CAGR, 53% gross margin, a 13% operating-expense ratio, 40% operating margin, mid-single-digit capital expenditure intensity, and a 25% to 30% free-cash-flow margin. The second-quarter gross margin of 39.3% remains 13.7 percentage points below 53%, while the operating margin of 20.8% remains 19.2 percentage points below 40%. What investors truly need to see is not merely the existence of these targets, but whether each quarter’s PSG growth, product mix, and cost improvements can narrow the gaps.
The GAAP Rebound Must Be Viewed in the Context of Restructuring Charges
Second-quarter GAAP operating margin was 16.1%, versus negative 3.5% in the first quarter, representing an apparent jump of 19.6 percentage points. However, the first quarter included $329.3 million of restructuring, asset-impairment, and other charges, while this item declined to $41.2 million in the second quarter. The reconciliation from second-quarter GAAP operating income of $258.6 million to non-GAAP operating income of $334.1 million also primarily included $13.4 million of restructuring-related inventory charges, $11.7 million of intangible-asset amortization, and $7.6 million of acquisition- and divestiture-related expenses.
The most prudent interpretation is therefore: the sharp rebound in GAAP earnings reflects both operating improvement and lower special charges, while the 170-basis-point increase in non-GAAP operating margin is more representative of this quarter’s incremental operating improvement. Conversely, non-GAAP results should not be used in isolation because restructuring, impairment, and M&A; expenses consume real economic resources. If special items remain elevated for an extended period, a gap will persist between so-called “core earnings” and the earnings actually accruing to shareholders.
Free Cash Flow Was a Highlight, with Low Capital Expenditure Also an Important Driver
Operating cash flow was $459.7 million this quarter, up $275.4 million year over year; capital expenditure was $34.3 million, down $43.9 million year over year; and free cash flow was $425.4 million, approximately 4 times the prior-year level, representing a free-cash-flow margin of approximately 26.5%. The cash-flow statement also shows that changes in working capital and other assets and liabilities contributed $44.6 million, versus a use of $199.8 million in the prior-year period, indicating that the year-over-year cash-flow improvement came from three areas: earnings, working capital, and capital expenditure.
Low capital expenditure was not accidental. Capital expenditure was $341.2 million in 2025, only $21.9 million in Q1 2026 and $34.3 million in Q2, with third-quarter guidance of $40 million to $50 million. Management believes the major investment cycle is now largely over and targets a long-term capital expenditure ratio below 5%. If equipment investment remains low while revenue and gross margin improve, cash flow will be highly responsive; however, if low capital expenditure reflects capacity reductions, asset divestitures, or deferred investment, the single-quarter free-cash-flow margin of 26.5% should not be treated as permanent.
Capital allocation also varies by reporting basis. The company’s summary states that it repurchased $332 million of shares this quarter, while the cash-flow statement reports $344.8 million of cash outflows for repurchases, with the difference potentially reflecting transaction and settlement timing; this report uses the company summary’s $332 million as the reported figure for the quarter. First-half cash outflows for repurchases were $690.5 million, and the company stated that year-to-date shareholder returns were approximately 105% of free cash flow. This supports per-share metrics, but it also means repurchase intensity exceeded free cash flow over the same period and cannot be assessed independently of financing and cash balances.
Convertible Notes Increased Cash but Also Complicated the Share-Count Framework
Quarter-end cash and cash equivalents were $3.5145 billion, with short-term investments of $350 million, for a combined $3.8645 billion; current and long-term debt totaled $4.4594 billion. Cash increased by $1.5109 billion from the first quarter, but debt also increased by approximately $1.4765 billion, primarily due to the issuance of $1.3 billion of 0% convertible notes due 2031 and the related bond-hedge and warrant transactions. The increase in cash therefore does not represent a proportionate reduction in net financial risk.
GAAP diluted shares were 404.4 million this quarter, versus 397 million on a non-GAAP basis; third-quarter guidance is 402 million and 395 million, respectively. The difference reflects the antidilutive impact of the convertible-note hedge included in the company’s non-GAAP calculation, while actual dilution will change when the share price exceeds the various conversion prices and warrant exercise prices. The simultaneous occurrence of repurchases and convertible-note issuance means that “repurchases necessarily reduce the earnings-per-share denominator” is no longer a linear relationship.
Inventory has not deteriorated for now: quarter-end inventory was $2.0475 billion, essentially unchanged from $2.0492 billion in the first quarter, but $57.9 million higher than at the end of 2025. If third-quarter revenue continues to grow while inventory remains stable, the quality of the recovery will improve; if inventory resumes growing faster than revenue, investors should be alert to a potential mismatch between customer purchases and internal capacity utilization.
Synaptics Broadens the Platform Boundary but Also Adds Integration Risk
onsemi plans to acquire Synaptics, aiming to expand from power and sensing into connected computing, and says the transaction will add a gross-margin-accretive business mix. Strategically, this could move the company beyond being a component supplier and closer to becoming an automotive, industrial, and physical-AI platform provider, with opportunities to cross-sell power, sensing, connectivity, edge computing, and human-machine interfaces.
However, this quarter’s earnings report still provides no evidence of revenue synergies. The acquisition has so far generated only special-item expenses; the real factors requiring validation are regulatory approval, closing timing, customer cross-selling, revenue retention, gross margin, and R&D; integration. Our previous industry deep dive on the Synaptics transaction characterized it as a “platform option,” and that assessment should remain unchanged this quarter: the transaction expands long-term optionality but cannot substitute for current-period execution in PSG and AI projects.
The Five Points Most Likely to Be Misread by the Market
First, interpreting revenue growth as a simultaneous recovery in automotive and industrial. Automotive revenue still declined sequentially, industrial grew only modestly, and incremental growth was highly concentrated in PSG and other end markets.
Second, attributing the entire jump in GAAP operating margin to operating leverage. The decline in the first quarter’s substantial restructuring charges made a meaningful contribution, and the operating trend should be cross-validated against non-GAAP margins and cash flow.
Third, treating the entire “other” end-market category as AI data centers. The company confirmed rapid AI growth but did not disclose AI’s precise share of the other end-market category.
Fourth, treating 800V rack content as a revenue forecast. Approximately $115,000 is an estimate of the potential opportunity in 2030 and still depends on architectural standards, customer qualifications, market share, component pricing, and mass-production yields.
Fifth, directly annualizing free cash flow and share repurchases. Capital expenditure was only $34.3 million this quarter, working capital shifted to a cash inflow, and the convertible notes materially changed both cash and share count; the quarterly result was strong, but long-term quality will depend on free cash flow after capital expenditure normalizes.
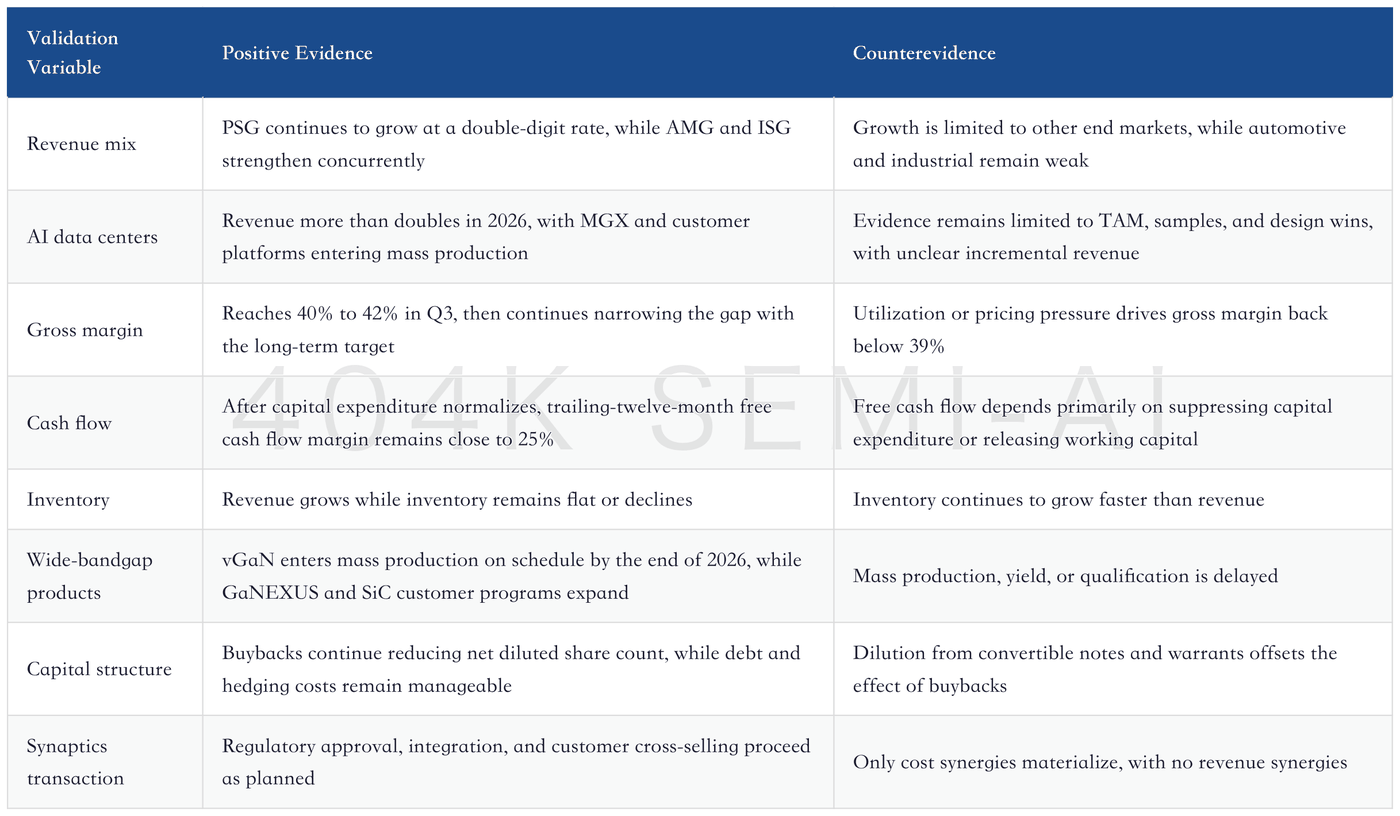
Validation Checklist for the Next Four Quarters
The key validation is the simultaneous delivery of gross margin, cash flow, and AI revenue
Conclusion: From “Past the Trough” to “Proving the Profit Platform”
onsemi’s second-quarter results were better than the headline suggested: revenue grew only 6%, but non-GAAP operating profit increased 15%, free cash flow nearly doubled, and third-quarter guidance points to concurrent improvements in revenue, gross margin, and earnings per share. This indicates that the cyclical recovery is beginning to flow through the income statement rather than remaining confined to order sentiment.
However, the report also establishes clear boundaries. Automotive and industrial have not yet fully recovered, part of the GAAP rebound came from lower restructuring charges, free cash flow benefited from exceptionally low capital expenditure, AI rack content remains a long-term management estimate, and Synaptics has not yet generated synergy revenue. The most compelling evidence going forward would not be another TAM announcement, but Q3 gross margin reaching 40% to 42%, sustained PSG growth, AI revenue more than doubling, no deterioration in inventory, and free cash flow margin remaining close to 25% after capital expenditure normalizes.
If these variables materialize simultaneously, onsemi’s narrative will be upgraded from “a cyclical recovery in power semiconductors” to “an AI power-tree-driven profit platform”; if only the AI narrative expands while automotive and industrial, gross margin, and cash flow begin to diverge, this quarter is more likely to represent a concentrated rebound from a low base. Ultimately, the verdict rests not on the 2030 roadmap, but on whether revenue, margins, and cash flow can remain aligned over the next four quarters.
Research Scope and Official Sources
This article uses only onsemi’s Q2 2026 Financial Results and Financial Statements, Q2 2026 Quarterly Investor Presentation, and historical quarterly and annual reports from the company’s investor relations website. All non-GAAP metrics are used alongside the GAAP reconciliation tables provided by the company; long-term TAM, rack content, and financial targets are identified as management estimates and do not constitute investment advice.
Related Reading
Arm FY2027 Q1 Deep Dive: Data Center Royalties More Than Double, AGI CPU Demand Exceeds $2 Billion