
目录
Table of Contents
What Made the $96.2 Billion Quarter Stand Out
Data Center Growth Is Shifting Gears
How Market Expectations and Peer Competition Are Changing
Can the 75% Gross Margin Hold?
How Rubin Takes Over as the Primary Growth Driver
Why Profit, Cash Flow, and Working Capital Diverged
How Long-Term Commitments and Guarantees Change the Picture
Six Numbers to Watch Next Quarter
本内容基于公开资料和研报数据整理,不构成任何投资建议,不代表任何个人观点,仅供学习参考,请理性阅读
NVIDIA once again delivered above-consensus growth, but the bigger shift this quarter was its increasing use of long-term commitments and credit support to sustain AI infrastructure demand.
Table of Contents
Magnitude and Sources of the Earnings Beat
Data Center Growth Is Shifting Gears
How Market Expectations and Peer Competition Are Changing
Can NVIDIA Sustain a 75% Gross Margin?
How Rubin Will Take Over as the Primary Growth Driver
Why Profit, Cash Flow, and Working Capital Are Diverging
How Long-Term Commitments and Guarantees Change the Equation
Six Numbers to Watch Most Closely Next Quarter
What Made the $96.2 Billion Quarter Stand Out
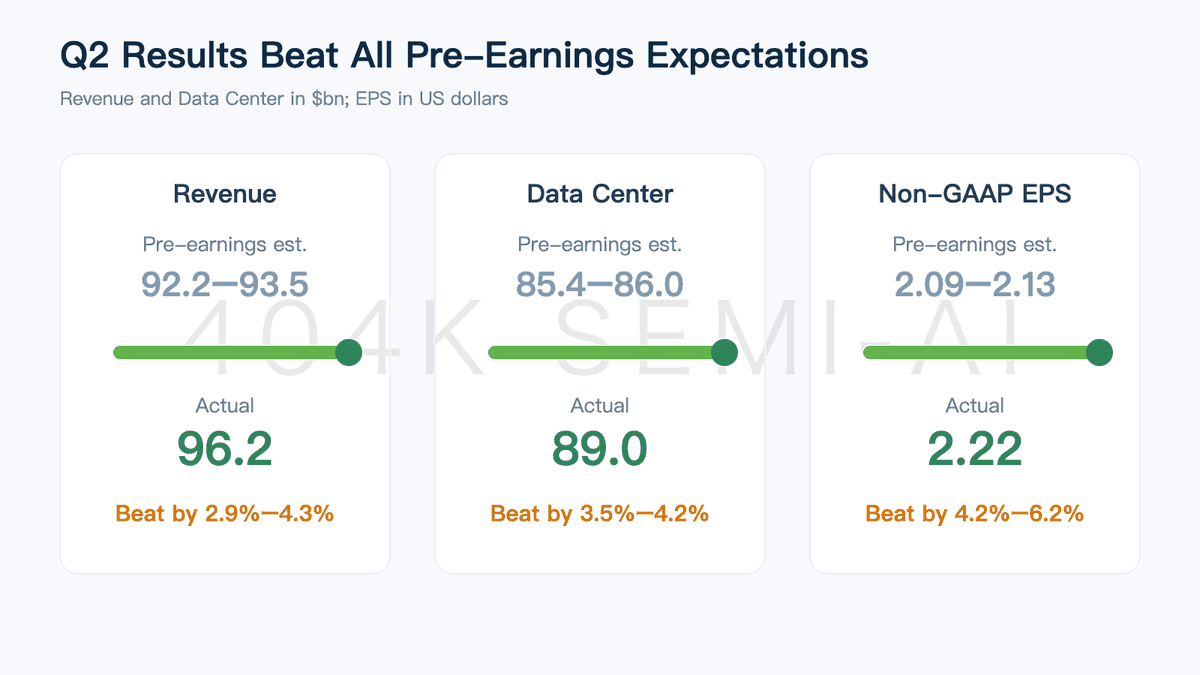
NVIDIA outperformed across revenue, data center, and earnings per share, with the upside driven by simultaneous improvement across multiple operating metrics. Fiscal Q2 2027 revenue was $96.221 billion, up 106% year over year and 18% quarter over quarter; data center revenue was $89.023 billion, up 117% year over year and 18% quarter over quarter. Non-GAAP EPS was $2.22, up 120% year over year and 19% quarter over quarter. Even from this exceptionally large base, NVIDIA added approximately $14.6 billion of sequential quarterly revenue, maintaining growth above most pre-earnings estimates.
Public premarket expectations varied by source. Depending on the aggregation methodology, revenue estimates ranged from approximately $92.2 billion to $93.5 billion, data center estimates from approximately $85.4 billion to $86.0 billion, and non-GAAP EPS estimates from approximately $2.09 to $2.13. Against these ranges, actual revenue was 2.9% to 4.3% higher, data center revenue was 3.5% to 4.2% higher, and EPS was 4.2% to 6.2% higher. Bank of America expected NVIDIA to deliver its customary 3% to 4% beat and raise, and the actual results broadly matched that view.
Premarket option prices implied an earnings move of approximately 5.4% to 5.6%, equivalent to roughly $280 billion in market capitalization. This pricing showed that investors expected very strong results but were concerned that elevated expectations would blunt the impact of an ordinary beat. NVIDIA exceeded revenue and data center expectations and issued higher Q3 guidance; the decline in gross margin, long-term commitments, and cash conversion therefore became the next variables shaping the post-earnings reaction.
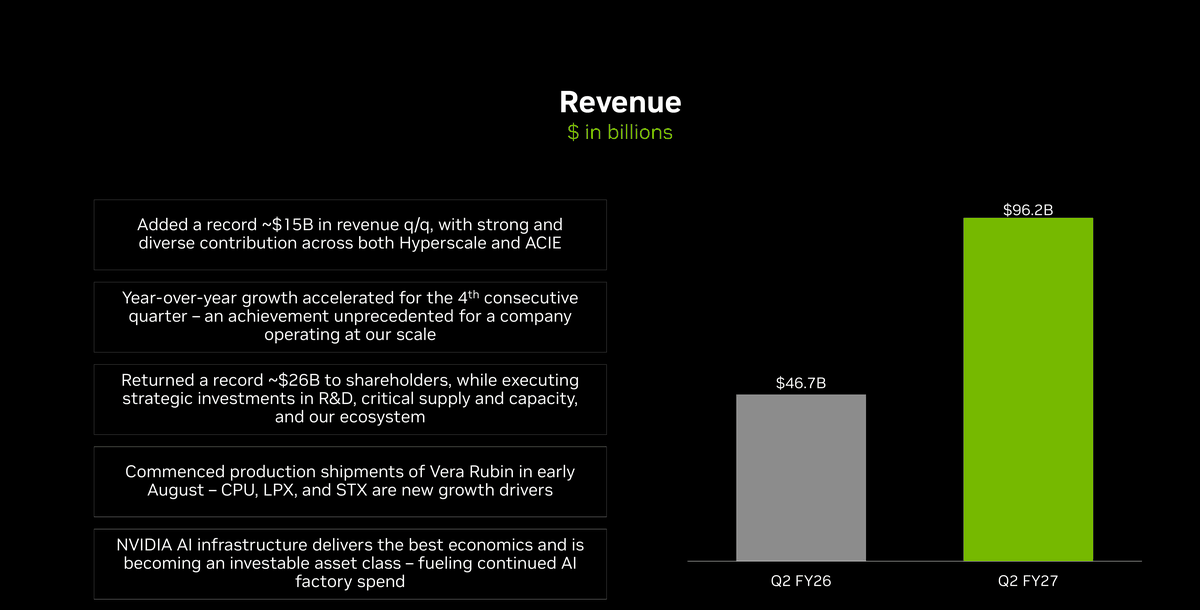
The magnitude of the beat indicates that the market underestimated both the delivery pace of Blackwell Ultra and the breadth of customer demand. Page 3 of NVIDIA’s Q2 FY2027 investor presentation shows revenue rising year over year from $46.7 billion to $96.2 billion, with hyperscale customers as well as AI cloud, industrial, and enterprise customers all making substantial contributions. Growth did not depend on a single AI lab or cloud provider. The number of customers, range of projects, and deployment geographies are all expanding, reducing the effect that a short-term purchasing delay by any one customer could have on quarterly revenue.
The bar for Q3 has also risen. Public pre-earnings expectations ranged from approximately $103.0 billion to $104.2 billion, while some investors viewed revenue above $100.0 billion as the threshold confirming sustained demand. NVIDIA’s formal guidance was $108.0 billion, plus or minus 2%, implying a range of $105.8 billion to $110.2 billion. Even the low end exceeds most premarket point estimates. Q3 guidance excludes China data center compute revenue, meaning near-term growth will continue to depend primarily on markets outside China and Rubin’s initial contribution.
Data Center Growth Is Shifting Gears
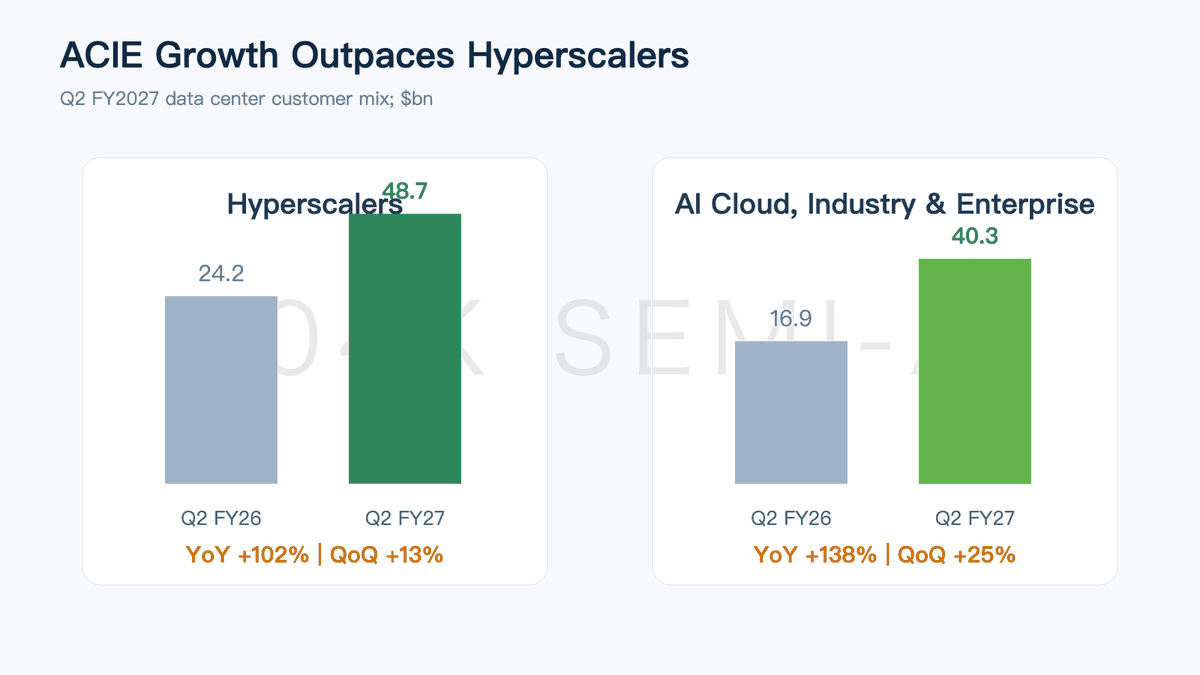
Hyperscale cloud providers remain NVIDIA’s largest customer group, but the faster-growing segment has shifted to AI cloud, industrial, and enterprise customers. Hyperscale customer revenue was $48.71 billion this quarter, up 102% year over year and 13% quarter over quarter. Revenue from AI cloud, industrial, and enterprise customers was $40.313 billion, up 138% year over year and 25% quarter over quarter. The latter segment is now approaching the former in scale and contributed a larger sequential increase.
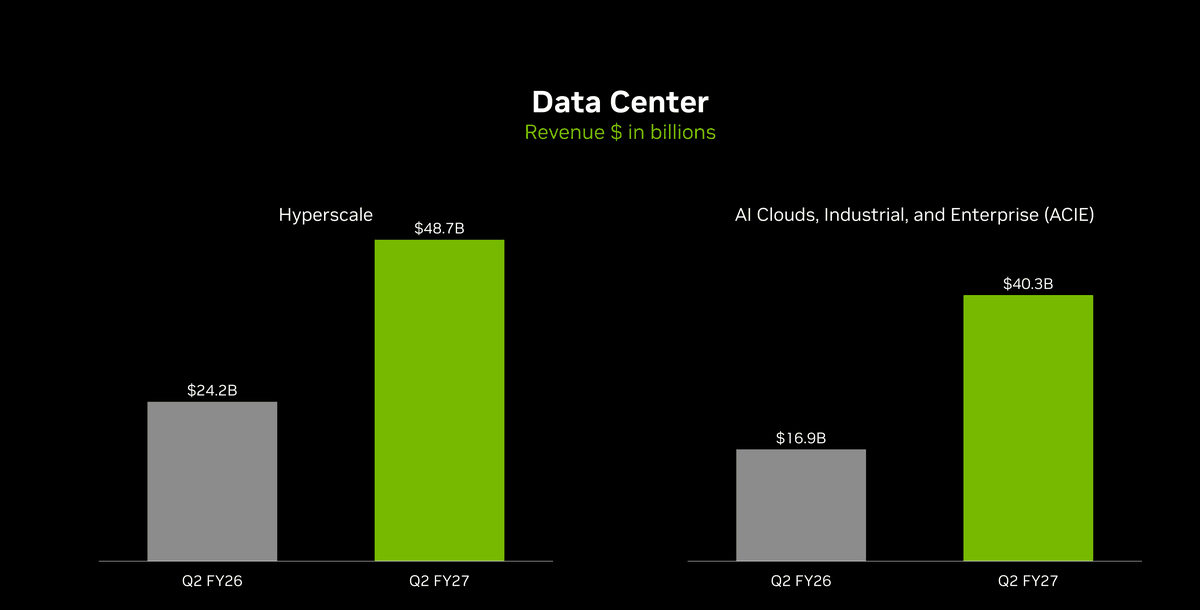
Page 4 of NVIDIA’s Q2 FY2027 investor presentation compares the two customer groups directly. Hyperscale customers still account for approximately 55% of data center revenue, while AI cloud, industrial, and enterprise customers contribute approximately 45%. This shift has three implications. First, AI demand is spreading beyond a handful of leading training clusters to model companies, sovereign projects, enterprise inference, and industrial deployments. Second, NVIDIA’s revenue growth is increasingly supported by a wider range of end markets. Third, newer customers often have weaker balance sheets than large cloud providers, requiring NVIDIA to assume greater responsibility for financing coordination and delivery assurance.
Faster ACIE growth expands NVIDIA’s revenue opportunity but also makes customer credit quality and project execution more important. Hyperscale cloud providers have mature financing channels and stable cash flows, while emerging AI clouds, model companies, and sovereign projects depend more heavily on long-term leases, project financing, and supplier support. NVIDIA’s days sales outstanding rose to 60 days this quarter, which the company attributed to longer payment terms for large, multi-quarter agreements with certain investment-grade customers. The simultaneous expansion of the customer base and extension of collection cycles should be monitored together.
Edge computing revenue was $7.198 billion, up 27% year over year and 13% quarter over quarter. This segment includes workstations, consumer PCs, automotive products, and physical-AI-related offerings. It currently represents only approximately 7.5% of total revenue, so its contribution to overall growth remains limited. Its strategic value lies primarily in broadening deployment of the CUDA and inference ecosystems. Edge computing will become a second financial growth engine only if local models, robotics, and autonomous driving begin generating revenue at scale.
