
North American Internet Triopoly Deep Dive: Cloud Demand Upgrades, AI Monetization, and the US$801 Billion Capex Test
目录
TL;DR
The Real Question This Earnings Season Is Not Whether Demand Exists
Alphabet: Search Defends the Cash Cow as TPUs Take Cloud to a New Scale
Meta: Advertising Has Proven Its Efficiency; 14GW of Compute Has Yet to Prove Its Returns
Amazon: AWS Capacity Expansion, with Retail and Advertising Providing a Cash-Flow Buffer
The Three Companies Are Pursuing Three Distinct Monetization Paths
Valuation Is Not About Who Has the Most Target-Price Upside
What Would Invalidate This View
Conclusion: The Larger the Capital Expenditure, the Shorter the Required Evidence Chain
本内容基于公开资料和研报数据整理,不构成任何投资建议,不代表任何个人观点,仅供学习参考,请理性阅读
TL;DR
Citi’s latest revisions center on a widening divergence between growth and cash flow. The three companies’ combined 2027 capital expenditure is projected at approximately US$801 billion, about 18% above the previous forecast, before exceeding US$1 trillion in 2028. Meanwhile, combined 2027 free cash flow has swung from positive US$35.6 billion to negative US$31.7 billion. AI demand is already evident; the next test is whether revenue realization can outpace capital expenditure, depreciation, and capital tied up.
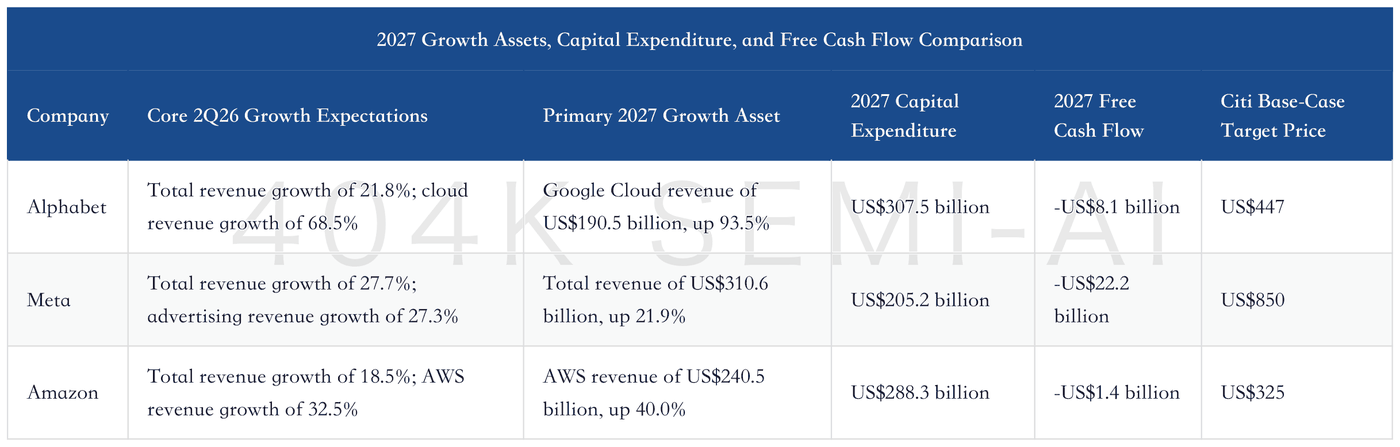
Alphabet offers the greatest model upside. Citi raised its 2027 Google Cloud revenue forecast by 30% to US$190.5 billion, up 93.5% year over year, including approximately US$62 billion from sales of 3.5 million proprietary tensor processing units. Search is still growing by more than 10%, but cloud is the business truly reshaping the revenue mix: Google Cloud’s share of revenue is expected to rise from 20.1% in 2026 to 30.5% in 2027. However, US$307.5 billion of capital expenditure would push 2027 free cash flow down to negative US$8.1 billion. The primary validation point is whether hardware sales can generate margins commensurate with cloud services.
Meta has the greatest demand visibility—and the largest gap in returns on capital. Citi expects advertising revenue to grow 26.4% in 2026 and average daily time spent by US Instagram users to increase 12%. However, it raised its 2027 capital expenditure forecast by 22% to US$205.2 billion, with free cash flow falling to negative US$22.2 billion. Recommendation algorithms can already lift ad pricing; Meta must now demonstrate that approximately 14 GW of compute capacity, its superintelligence team, and new products can generate measurable revenue beyond advertising.
Amazon has the most balanced growth trajectory and remains Citi’s top pick in the internet sector. Citi expects AWS revenue to grow 33.5% in 2026 and 40% in 2027, supported by additional capacity, long-term customer commitments, and demand from AI laboratories. North American retail and advertising provide an earnings buffer. Capital expenditure rises to US$288.3 billion in 2027, but free cash flow turns only modestly negative at US$1.4 billion, leaving cash-flow pressure materially lower than at Alphabet and Meta.
The three companies cannot be assessed solely by comparing cloud growth. For Alphabet, investors should track TPU sales, cloud backlog, and cloud margins; for Meta, ad impressions, ad pricing, revenue per user, expense guidance, and utilization of incremental compute capacity; and for Amazon, new AWS capacity, conversion of contractual commitments, North American retail margins, and depreciation growth. If any company raises capital expenditure without demonstrating order conversion and unit economics, its valuation could compress first.
In terms of the post-earnings watchlist, Amazon is best assessed against whether cloud acceleration and retail margins can improve simultaneously, validating its operating balance. Alphabet is best assessed against whether upgraded cloud revenue genuinely reflects sustainable service demand, validating its growth elasticity. Meta must demonstrate a closed loop between capital expenditure and expense guidance on one side and advertising monetization on the other. A quarterly revenue beat is only the starting point. The true entry signal is management clearly articulating the return path over the next two years and delivering against it consistently in subsequent quarters.
The Real Question This Earnings Season Is Not Whether Demand Exists
Advertising, e-commerce, and cloud demand have not suffered the cliff-edge decline previously feared by the market. Based on advertising-industry checks, e-commerce trends, and surveys of enterprise IT decision-makers, Citi believes Alphabet, Meta, and Amazon could deliver second-quarter 2026 revenue and earnings above consensus, while some companies may also issue stronger-than-expected third-quarter guidance. Viewed only through this lens, the three companies still appear to fit the familiar narrative of revenue beats and continued earnings growth.
Strictly speaking, these are not three equivalent “cloud providers.” Alphabet and Amazon operate public clouds for external customers, while Meta primarily uses internally built compute capacity to support advertising, recommendations, and new products. Grouping them together is a comparison of the same return-on-capital challenge, not a market-share contest among three homogeneous public-cloud businesses.
The problem is that strong demand does not automatically translate into improved shareholder returns. Over the past two years, AI investment has initially appeared as spending on servers, chips, data centers, power, and networking equipment. Revenue must wait for capacity to come online, customers to migrate, model usage to scale, advertising efficiency to improve, and new products to begin charging. There is a clear timing gap between investment and returns, while capital expenditure will convert into depreciation over the coming years and continue flowing through the income statement.
Citi’s latest model quantifies this timing gap directly. The three companies’ combined capital expenditure is approximately US$541 billion in 2026, rising nearly 48% to US$801 billion in 2027 and then to approximately US$1 trillion in 2028. Combined revenue is projected at approximately US$1.88 trillion in 2027, making capital expenditure equivalent to 42.7% of revenue. This ratio does not necessarily imply excessive investment, but it does mean the market can no longer justify valuations through revenue growth alone. It must also assess the capital efficiency of incremental investment.
Free cash flow warrants even greater caution. Under the previous model, the three companies were expected to generate approximately US$35.6 billion of combined free cash flow in 2027; the new model projects negative US$31.7 billion, a single-revision reduction of approximately US$67.3 billion. Capital expenditure continues to grow in 2028, while combined free cash flow remains negative at US$22.6 billion. In other words, Citi has raised revenue forecasts while pushing all three companies’ free cash flow into negative territory. The simultaneous upgrades to demand and downgrades to cash flow are the central tension of this earnings season.
The previous earnings cycle already demonstrated that AI demand and capital expenditure can accelerate simultaneously, while cloud and advertising can continue growing. Microsoft, Alphabet, Meta, and Amazon Q1 Earnings: AI Demand Holds Up, Capex Surges First, Cloud and Advertising Accelerate, and Cash Flow Comes Under Pressure
The new issue is that capital expenditure has moved up another order of magnitude. The three companies must provide more granular evidence on orders, capacity, pricing, and margins to demonstrate that this is not a mutually reinforcing race to overinvest.
Alphabet: Search Defends the Cash Cow as TPUs Take Cloud to a New Scale
The easiest way to misread Alphabet is to interpret its projected 27.6% total revenue growth in 2027 as a renewed acceleration in search. In Citi’s model, 2027 Search and Other revenue is approximately US$293.5 billion, up 12.5% year over year, while YouTube advertising revenue is approximately US$48.8 billion, up 9.5%. Both remain stable cash cows, but neither is sufficient to explain total revenue growth approaching 28%.
The real change comes from Google Cloud. Citi expects second-quarter 2026 Google Cloud revenue of approximately US$23 billion, up 68.5% year over year, rising to US$190.5 billion in 2027, up 93.5% and 30% above its previous forecast. Google Cloud’s share of company revenue is projected to rise from 20.1% in 2026 to 30.5% in 2027 and nearly 35.9% in 2028. If this model is realized, Alphabet will no longer be simply “search plus other businesses”; it will have a dual-core structure built around search and cloud.
The most distinctive component of this growth trajectory is Citi’s first-time inclusion of external sales of proprietary tensor processing units in its Google Cloud forecast. The model assumes sales of approximately 3.5 million units in 2027, contributing around US$62 billion of revenue. This represents nearly one-third of Google Cloud’s projected 2027 revenue and explains why Citi has raised revenue, capital expenditure, and earnings-per-share estimates while lowering the valuation multiple from approximately 30x to 28x: the model’s upside has expanded, but so has execution risk.
TPU revenue cannot simply be equated with high-quality cloud-services revenue. Chip sales are recognized more quickly and involve larger transaction sizes, but may carry gross margins, customer concentration, and procurement cycles that differ from compute services, storage, and software subscriptions. Citi expects Google Cloud to deliver a 34.5% operating margin in 2027. If the US$62 billion of hardware revenue materializes while cloud margins remain stable at this level, it would indicate that Alphabet is not merely selling chips but is retaining sufficient value through the associated platform, networking, and services. If revenue rises while margins fall materially, the market will reassess the quality of this growth.
Backlog provides another layer of evidence for demand. Citi expects Google Cloud backlog to reach US$552 billion in 2026 and US$673.4 billion in 2027, assuming approximately 50% is recognized over the following 24 months. However, the model’s “cloud revenue derived from backlog” exceeds total cloud revenue in certain periods, and the table also contains a reference error. Backlog is therefore useful for assessing demand direction and visibility, but should not be treated mechanically as a revenue-recognition schedule. More relevant disclosures on the earnings call will include the pace of new bookings, contract duration, the mix between TPUs and conventional cloud services, and whether actual customer consumption is growing in tandem.
Capital expenditure is the other side of Alphabet’s valuation. Citi raised its 2027 capital expenditure estimate by 20.8% to US$307.5 billion, equivalent to 49.2% of annual revenue, with a further increase to US$393.8 billion in 2028. Meanwhile, 2027 free cash flow falls from the previous forecast of positive US$17.6 billion to negative US$8.1 billion and remains negative at US$6.1 billion in 2028. Depreciation and amortization is expected to rise from US$34.4 billion in 2026 to US$104.3 billion in 2028, meaning pressure on the future income statement will not disappear once server purchases are complete.
Citi assigns Alphabet a base-case target price of US$447, based on 2027 earnings per share of US$15.90 and a 28x price-to-earnings multiple. Its bull-, base-, and bear-case values are US$517, US$447, and US$289, respectively. The true determinant of scenario shifts is not only search growth, but whether Google Cloud can preserve margins while nearly doubling revenue and whether TPU sales can generate repeatable customer demand. Alphabet offers the greatest upside elasticity, but it also has the greatest dependence on a single model assumption.
Meta: Advertising Has Proven Its Efficiency; 14GW of Compute Has Yet to Prove Its Returns
Meta’s earnings visibility comes from its mature advertising system, not continued rapid user growth. Citi expects monthly active users to grow by approximately 4% in 2026 and slow further to 3.5% in 2027; average revenue per monthly active user is expected to rise by 21.4% and 17.1%, respectively. This indicates that revenue growth will primarily depend on higher ad pricing, more precise recommendations, and stronger commercial conversion rather than simply expanding the user base.
Current data support this view. In 1Q26, Meta’s ad impressions increased 19% year over year, while ad pricing rose 12%. Citi expects 2Q advertising revenue of approximately $59.3 billion, up 27.3% year over year. Average daily time spent by Instagram users in the US was approximately 58 minutes, up 12% year over year. Short-form video recommendations, ad ranking, and creative-generation tools have collectively increased monetizable engagement and the value of each impression, meaning Meta’s AI investment is already generating returns in its core advertising business.
However, a stronger core advertising business does not mean all incremental compute capacity will generate the same returns. Meta plans to increase compute capacity from approximately 8GW in 2026 to approximately 14GW in 2027. Its long-term Hyperion project targets more than 5GW, while Prometheus is planned to exceed 1GW in 2026. Citi also includes revenue from AI agents, subscriptions, and potential compute services, but even if subscriptions contribute approximately $3 billion in 2027, that would represent only around 1.5% of that year’s capital expenditure and cannot independently justify the scale of investment.
The income statement is already reflecting the pressure. Citi expects Meta’s total revenue to grow 26.8% in 2026, while operating income rises only 8.5%, with operating margin declining from 41.4% in 2025 to 35.5%. R&D; expenses are expected to increase 50.7%, with total expenses up 39.7%. In 2027, revenue growth is projected to slow to 21.9%, while operating margin recovers only slightly to 36.1%. In other words, the advertising business remains strong, but incremental R&D;, talent, and infrastructure costs are absorbing operating leverage.
Meta faces the most pronounced cash-flow pressure of the three companies. Citi raised its 2027 capital expenditure forecast for Meta by 22.1% to $205.2 billion, equivalent to 66.1% of revenue that year; free cash flow falls from the previous forecast of positive $8.5 billion to negative $22.2 billion. Capital expenditure rises further to $237.6 billion in 2028, while free cash flow remains negative at $12.7 billion. Even if the core advertising thesis remains fully intact, the capital-return window could be longer than the market expects.
Meta’s earnings therefore cannot be assessed solely on whether revenue exceeds $60.66 billion. The first layer is whether ad impressions and pricing can continue to rise together. The second is whether Instagram engagement, business messaging, and AI agents create incremental ad inventory or new monetization channels. The third is whether expense and capital expenditure guidance is raised again. Only then should investors consider whether management can quantify the utilization and revenue contribution of 14GW of compute capacity. If the first three layers remain strong but the fourth is absent, the shares could still react as though “results were strong, but the cash-flow outlook deteriorated.”
Citi’s base-case price target is $850, equivalent to approximately 23 times 2027 EPS of $37.74; the bull- and bear-case targets are $947 and $573, respectively. The visibility of Meta’s advertising business means downside is not determined solely by demand, but increasingly by investment discipline. For Meta, the key is no longer proving that AI can improve click-through rates, but demonstrating that improvements in advertising efficiency can cover the long-term costs of superintelligence and its compute platform.
Amazon: AWS Capacity Expansion, with Retail and Advertising Providing a Cash-Flow Buffer
Amazon has the most readily decomposable return pathway of the three companies. Citi expects 2Q26 total revenue of approximately $198.7 billion, up 18.5% year over year, and AWS revenue of approximately $40.9 billion, up 32.5%. AWS growth is expected to accelerate further to 35% in 3Q and 37% in 4Q. This is not a simple extrapolation of single-quarter demand, but a model revision based on new compute capacity coming online, partnerships with AI laboratories, enterprise workload migration, and price increases for machine-learning capacity blocks.
For 2027, Citi expects AWS revenue of approximately $240.5 billion, up 40% year over year and 5.2% above its previous forecast. AWS’s share of Amazon’s total revenue is expected to rise from 20.8% in 2026 to 25.5% in 2027, while its share of total operating income reaches 58.4%. This means AWS will contribute only around one-quarter of revenue but nearly 60% of operating income, making the timely deployment of incremental capacity a direct determinant of group earnings.
Long-term customer commitments improve revenue visibility. Citi’s model estimates AWS commitments at approximately $514.8 billion in 2026, rising to $592.1 billion in 2027. In 1Q26, the weighted-average remaining term of these contracts extended from approximately 4.1 years to 5.5 years. These figures refer to Citi-defined AWS Commitments, not recognized revenue, and should not be equated without qualification to the company’s officially reported remaining performance obligations. The amount and duration of these contracts indicate that customers are willing to lock in long-term compute capacity, but long-duration contracts cannot substitute for current consumption. The most important evidence in the earnings report will be whether signed commitments rapidly convert into actual usage after new capacity comes online, not whether the commitment balance itself continues to expand.
Amazon has an additional layer of protection compared with the other two companies. Citi expects 2Q26 North American retail revenue to grow approximately 15%, with a 7.3% operating margin. By 2027, the North American segment’s operating margin is expected to rise to 9.9%. Advertising revenue is projected at approximately $97.4 billion in 2027, up 17%. As the revenue mix shifts toward third-party sellers, advertising, subscriptions, and AWS, services revenue is expected to increase from 61.6% of group revenue in 2026 to 65% in 2027, continuing to improve the profit mix.
