
North American Cloud CapEx Raised Again: How $851 Billion, a $2 Trillion Order Backlog, and 50% Growth in 2027 Flow Through to GPUs, ASICs, WFE, and Cash Flow
目录
Executive Summary
I. What Changed with the July Upward Revision: Strong Growth in 2026, Still No Cliff in 2027
II. The $2 Trillion Order Backlog: Sufficient to Support Construction, but Not Directly Equivalent to Revenue
III. Cash Flow Stress Test: Funding Is Available, but Revenue Must Catch Up With Depreciation to Deliver Returns
IV. Four Companies, Four Paths: The Same CapEx Increase, Entirely Different Revenue Channels
Microsoft: Strongest Contract Coverage, but Leases and Depreciation Require the Closest Monitoring
Amazon: The Largest Capital Budget, With Trainium Determining Unit Economics
Google: TPU Is Moving From an Internal Cost Center to an External Product
Meta: Monetize Advertising Returns First, Then Test Compute and Model Services
V. How CapEx Flows Through the Supply Chain: GPUs Remain Strong, While ASICs, HBM, Packaging, and WFE Gain a Longer Growth Runway
VI. The Valuation Framework Is Changing: From “How Much Is Being Spent” to “How Much Revenue Each Dollar Generates”
VII. Three Scenarios: Delivering 50% Growth in 2027 Requires Demand, Supply, and Cash Flow to Align
Validation Checklist for the Next Four Quarters
VIII. Conclusion: The CapEx Cycle Continues, but Return-Based Screening Has Begun
本内容基于公开资料和研报数据整理,不构成任何投资建议,不代表任何个人观点,仅供学习参考,请理性阅读
North American cloud providers raised capital spending guidance again in July, with 2026 spending now pointing to $851 billion and 2027 growth potentially remaining at 35%-50%. Orders and financing are extending the buildout cycle, while negative free cash flow, depreciation, and the pace of compute monetization are beginning to drive valuations. This report examines where the capital is flowing, how it translates into revenue, and the signals that would invalidate the thesis.
Executive Summary
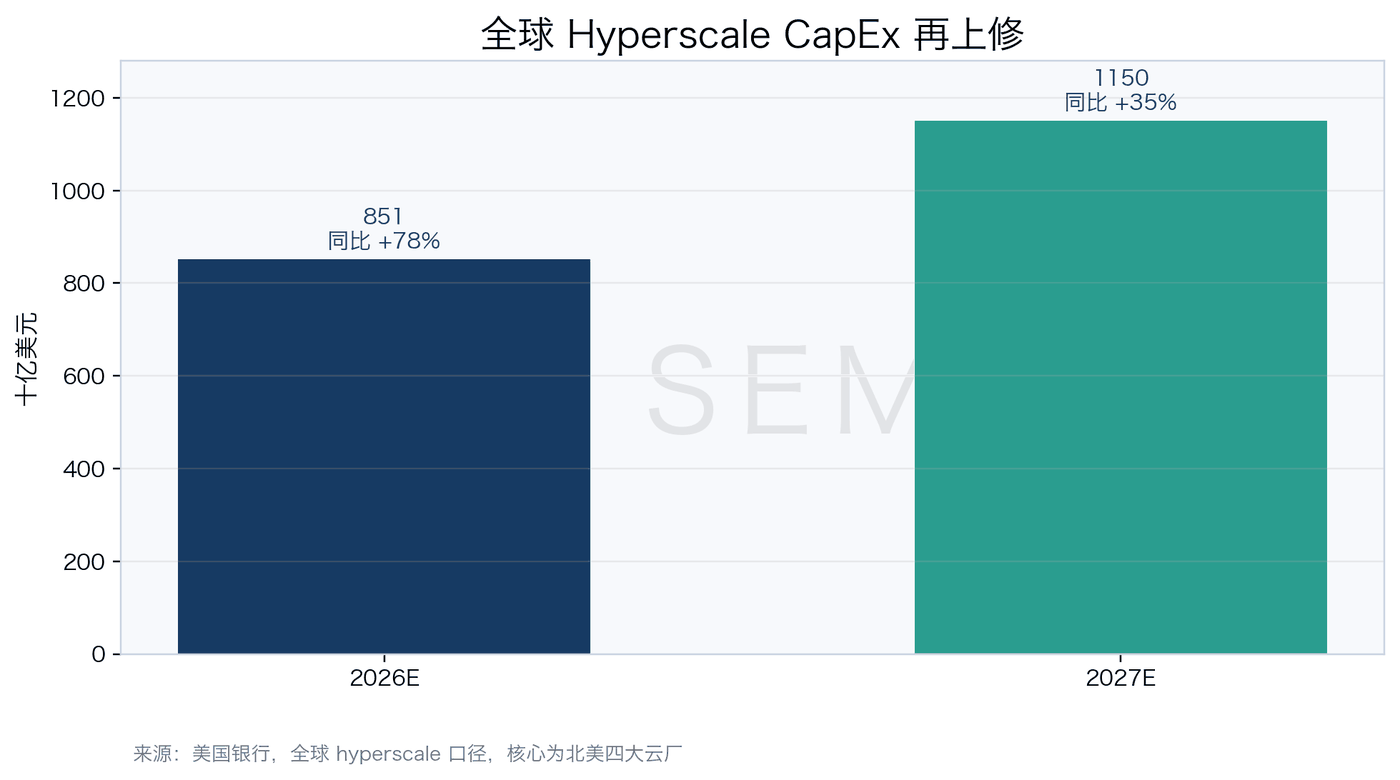
Growth continues in 2027. Bank of America raised its estimates for global hyperscaler CapEx in 2026 and 2027 to $851 billion and $1.15 trillion, respectively, with the latter still representing 35% growth. JPMorgan expects data-center investment by the four largest North American cloud providers to grow by at least 50% the following year. The two estimates differ in scope, but both challenge the linear assumption that spending peaks this year and falls off a cliff next year.
Orders already cover the construction cycle. Disclosed or estimated remaining performance obligations and backlogs at Microsoft, Oracle, Google, and Amazon exceed $2 trillion in aggregate: approximately $627 billion at Microsoft, $638 billion at Oracle, more than $460 billion at Google, and approximately $364 billion at Amazon. Contract definitions and revenue-recognition periods are not standardized, so these figures cannot be treated directly as future revenue. They are nevertheless sufficient to support multiyear procurement commitments for power, campuses, servers, and networking equipment.
Cash flow is entering a stress test. From 2026 to 2028, cloud-provider CapEx could reach 100%-115% of operating cash flow, with industry free-cash-flow margins expected to face pressure of approximately 1, 5, and 4 percentage points, respectively, versus prior baselines. Since 2026, leading companies have raised approximately $244 billion through long-term debt, equity, and structured financing, so near-term construction funding should not be constrained. The valuation divide is shifting toward whether depreciation growth, compute utilization, and revenue per watt can improve in tandem.
Four companies are taking four different paths. Microsoft is using Azure contracts and leases to accelerate delivery; Amazon is using Trainium to reduce unit inference costs; Google is attempting to turn TPU from an internal asset into an externally marketable product; and Meta is exploring the rental of temporarily surplus compute capacity alongside model services. CapEx indicates only the intensity of the buildout. Whether that spending produces high utilization, stable gross margins, and recurring software revenue will determine whether it ultimately translates into revenue or depreciation.
ASIC share is rising. JPMorgan expects AI accelerator shipments to reach 16.3 million units in 2026 and 23.3 million in 2027. The unit share of custom ASICs/XPUs is projected to rise from 32% in 2025 to 42% in 2026 and 53% in 2027. Nvidia’s ecosystem continues to dominate high-performance training and the general-purpose software stack, but incremental spending will flow more broadly into custom chips, HBM, advanced packaging, high-speed interconnects, test equipment, and wafer-fabrication equipment.
Four sets of metrics are sufficient for tracking the thesis. First, monitor CapEx growth and operating-cash-flow coverage. Second, track cloud revenue, backlog conversion, and compute utilization. Third, watch depreciation, lease liabilities, and free cash flow. Fourth, follow GPU/ASIC shipments and HBM and advanced-packaging supply. As long as backlog conversion, cloud revenue, and utilization continue to outpace depreciation, further CapEx increases can support the supply chain. Conversely, if new capacity sits idle while pricing declines, long-term return assumptions should be revised downward.
I. What Changed with the July Upward Revision: Strong Growth in 2026, Still No Cliff in 2027
The key message from this revision is the duration of the cycle. On July 9, Bank of America raised its two-year forecasts again, increasing the growth trajectory for both years by 10 percentage points versus May. Second-quarter spending is expected to reach $197 billion, up 83% year over year, indicating that the revision is already flowing into current procurement and deliveries while increasing confidence that subsequent projects will come online on schedule. Annual spending and growth rates are presented in the chart and comparison table below to avoid conflating different reporting periods in the main text.
The spending trajectory is even steeper among the core North American cloud providers. On July 10, JPMorgan estimated that data-center CapEx at the four largest North American cloud providers would grow by approximately 80% in 2026 and by at least 50% in 2027. This data-center-focused estimate cannot be added directly to Bank of America’s global hyperscaler figures, but both point in the same direction: 2027 remains a capacity-expansion year, albeit with growth moderating from exceptionally high levels.
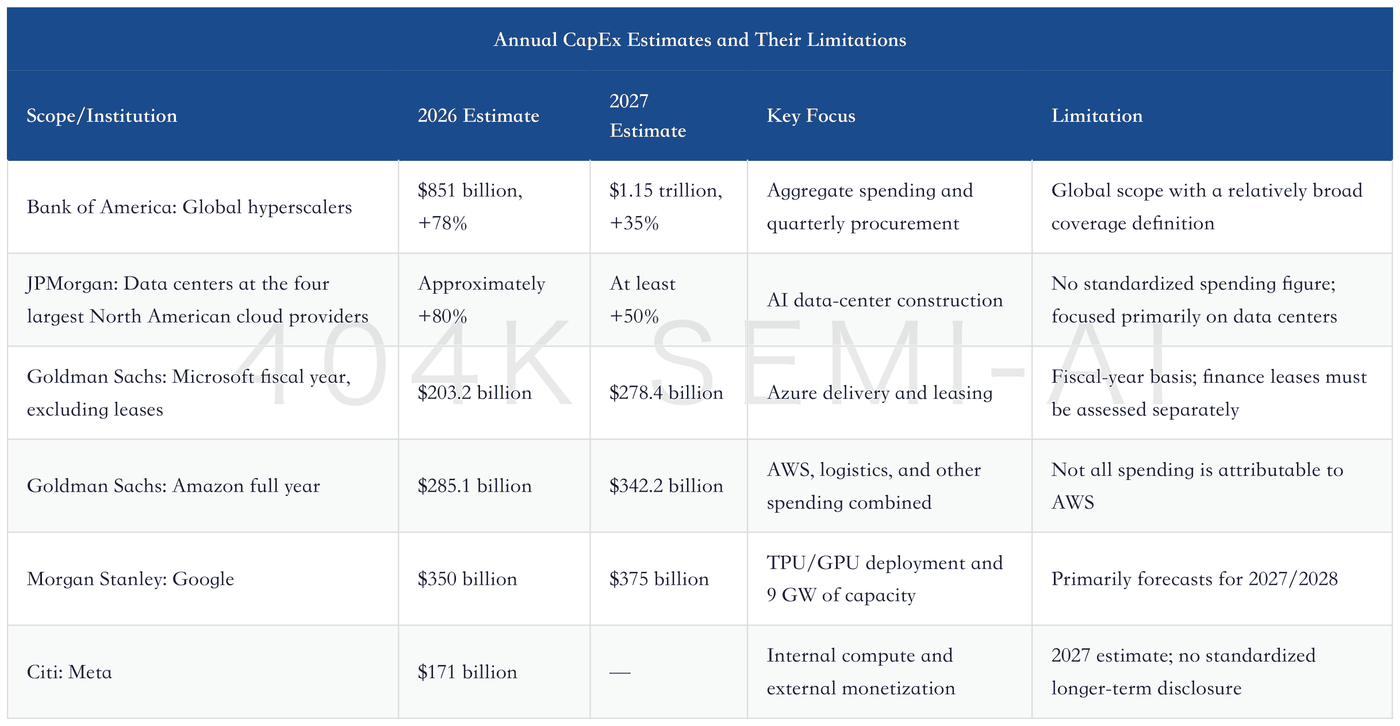
The differences in scope are themselves a key research consideration. Microsoft discloses cash CapEx separately from finance leases, while Amazon’s CapEx also includes logistics and other assets. Google’s and Meta’s figures are more directly associated with AI infrastructure expansion. Mechanically adding the four companies’ figures would create false precision. A more reliable approach is to assess each company’s incremental capacity and then track how quickly that capacity converts into cloud revenue, advertising efficiency, model services, or external compute sales.
Microsoft, Google, Meta, and Amazon Q1 Comparison: A $1.3 Trillion Order Backlog and 19.5 GW of New Capacity—Who Is Converting AI CapEx into Revenue?
The market’s previous concern about a “2027 digestion period” is being pushed out. Supply-chain orders, long-term power contracts, and campus construction all involve significant lead times, so cloud providers will not cancel most projects in response to a single quarter of revenue volatility. What can be adjusted rapidly is server configuration, the mix of leased versus self-built capacity, the GPU/ASIC mix, and the sequence in which different campuses are energized. Continued growth in the overall budget does not guarantee that every segment will expand at its previous rate.
II. The $2 Trillion Order Backlog: Sufficient to Support Construction, but Not Directly Equivalent to Revenue
The backlog gives cloud providers the confidence to sign long-term contracts. Bank of America data indicate approximately $627 billion for Microsoft and $638 billion for Oracle. Google’s backlog exceeds $460 billion, while Amazon’s is approximately $364 billion. The combined total exceeds $2 trillion and spans enterprise cloud migration, AI training, inference services, software subscriptions, and multiyear infrastructure agreements, providing management teams with greater visibility than spot demand alone.
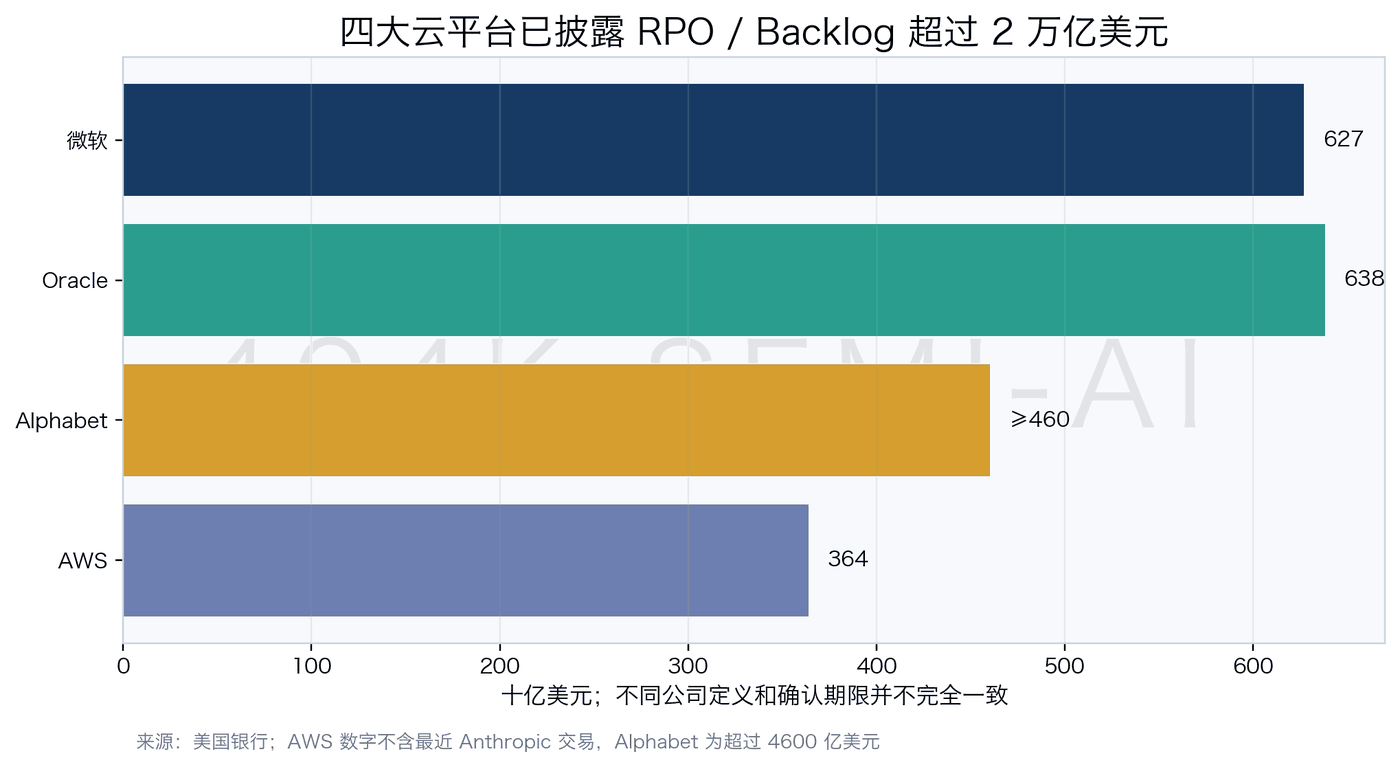
Three discounts must be applied to this $2 trillion figure. The first relates to duration: revenue recognition for multiyear contracts may extend over five years or longer. The second concerns definitions: companies do not disclose remaining performance obligations, contract backlogs, and commitments on a consistent basis. The third relates to customer quality: large model developers and emerging cloud providers may depend on continued financing to fulfill their obligations. The larger the contract, the more closely investors should examine the customer’s cash flow and minimum-purchase commitments.
Data center remains the key stronghold into Q2 semis earnings, with four major US hyperscalers (Google, Microsoft, Meta, Amazon) set to report in the coming weeks. Ahead of earnings, our tracker (mix of BofAe and consensus) indicates Q2 global hyperscale capex at $197bn, up +30% QoQ or +83% YoY. For CY26/CY27, capex now points to $851bn/$1.15Tn (+78%/+35% YoY), well above our +68%/+25% post-Q1 outlook in May.
This passage assesses quarterly deliveries alongside annual budgets. Second-quarter CapEx of $197 billion indicates that servers, networking, and power equipment are already entering deployment, while the $851 billion and $1.15 trillion figures reflect project scheduling. The backlog reduces the probability of construction being halted, but it cannot replace analysis of individual customer credit quality and the timing of revenue recognition.
A $1.7 Trillion Order Backlog, $650 Billion of CapEx, and 314 Million Shares Repurchased: Q2 2026 Preview for the Four Largest North American Cloud Providers
The value of the backlog must be tested against conversion rates. If a company’s new orders are growing rapidly while cloud revenue remains below capacity growth for an extended period, projects may still be under construction, customers may not yet have gone live, or contract recognition periods may be longer than expected. Conversely, slower order growth alongside rising revenue and utilization may simply indicate that earlier contracts are beginning to convert. Quarterly analysis should place orders, revenue, construction in progress, and depreciation in the same table; relying on any single metric can be misleading.
Financing extends fulfillment capacity beyond 2027. Since 2026, leading cloud providers and related large-scale projects have raised approximately $244 billion through debt, equity, and structured financing. Matching long-term debt with future cash flows reduces near-term liquidity risk and defers questions about capital discipline until after projects enter service. The more significant future risk is a combination of higher financing costs and low utilization—not a sudden inability by any single company to purchase servers.
The quality of the $244 billion in financing matters more than its scale. Long-dated, fixed-rate debt can align construction and payback periods; equity financing distributes project risk across existing and new shareholders; and data-center project financing may isolate an individual campus from the parent company’s balance sheet. All three instruments can extend the construction cycle, but they impose different costs on per-share value. Debt requires stable cash flow to cover interest, equity causes dilution, and project financing typically includes minimum-use commitments, collateral, or long-term leases. The financing must therefore be analyzed by maturity, cost, guarantees, and underlying assets to determine whether it improves capital efficiency or merely defers pressure on returns.
Large-customer concentration is the hidden variable in the order book. An increasing share of cloud-provider orders comes from a small number of model developers, internet platforms, and large enterprises, with individual contracts potentially reaching tens of billions of dollars. Customers that sign agreements across multiple cloud platforms can reduce single-platform risk, but they may also be reserving the same capacity before it is genuinely required. The appropriate tests are prepayments, minimum-purchase volumes, cancellation clauses, and the customers’ own financing. If the same group of customers has mutually reinforcing financing, compute-procurement, and revenue expectations, research should avoid treating all circular commitments as independent demand.
III. Cash Flow Stress Test: Funding Is Available, but Revenue Must Catch Up With Depreciation to Deliver Returns
CapEx is already approaching the upper limit of operating cash flow. Bank of America estimates that cloud providers’ capital expenditures could reach 100%-115% of operating cash flow from 2026 to 2028. Relative to the previous baseline, industry free cash flow margins face pressure of approximately 1 percentage point in 2026, 5 percentage points in 2027, and 4 percentage points in 2028. Pressure peaks in 2027 because many projects initiated in 2025-2026 will enter service, bringing depreciation and lease expenses onto the income statement while revenue is still ramping.
Lower free cash flow does not automatically mean the investment has failed. Data centers incur land, power, construction, and server costs before revenue begins to flow. As long as new capacity is covered by customer contracts and cloud revenue and gross profit ultimately grow faster than depreciation, temporarily negative free cash flow is acceptable. If utilization remains low after capacity comes online, compute pricing continues to decline, and useful lives are not materially extended, cash flow pressure will translate into lower returns on capital.
Behind the 138GW Data Center Expansion Plan: How North American Cloud Providers Are Financing AI Infrastructure
Leasing makes capital expenditures appear lighter but also increases fixed commitments. Goldman Sachs raised its estimate of Microsoft’s FY2028 capital expenditures including finance leases to $319.0 billion, from $287.0 billion previously, versus consensus of approximately $252.0 billion; excluding leases, the figure is $278.4 billion. Leasing provides faster access to capacity and reduces upfront cash outlays, but creates long-term payment obligations. Company comparisons must consider cash capital expenditures, new lease additions, lease liabilities, and depreciation together to avoid mistaking financing structures for differences in underlying investment.
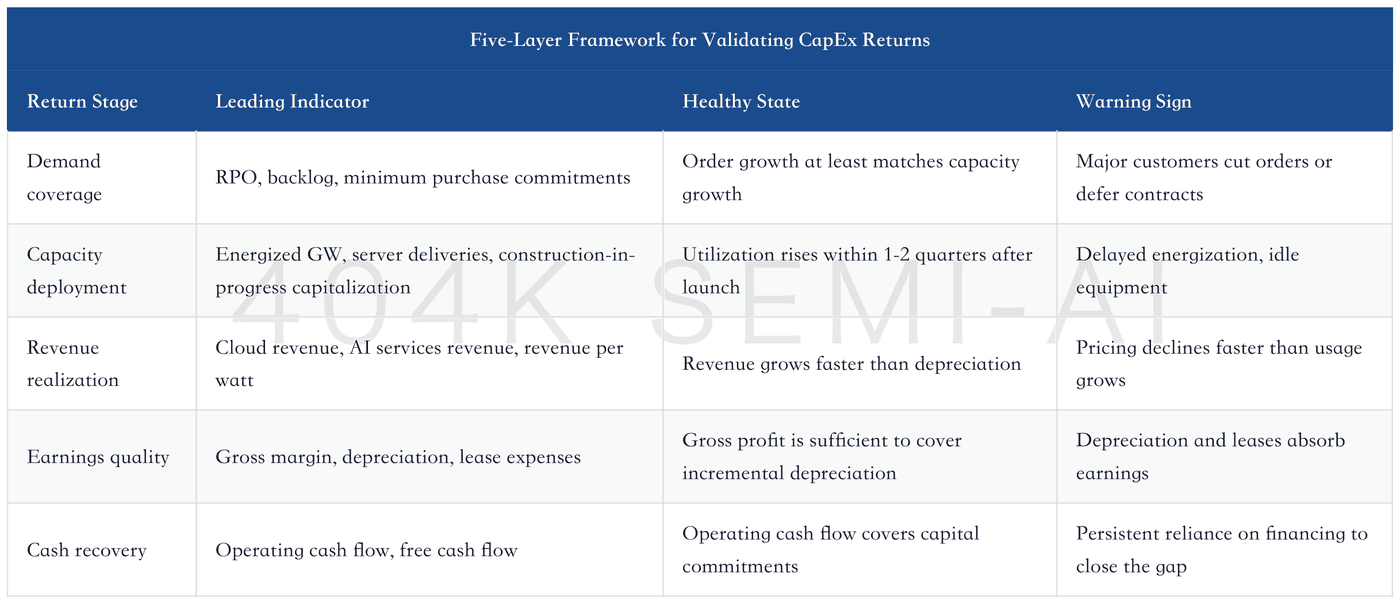
Revenue per watt is a useful bridge between engineering and financial performance. Morgan Stanley estimates that Google’s capacity monetization could reach $15 per watt in 2027 and $18 per watt in 2028. This metric compresses power, chips, utilization, pricing, and software value-add into a common denominator. Rising revenue per watt indicates that higher utilization, greater inference volumes, or higher-value software is absorbing the capital deployed. If capacity grows rapidly while revenue per watt stagnates, project returns will deteriorate.
IV. Four Companies, Four Paths: The Same CapEx Increase, Entirely Different Revenue Channels
Ranking companies by spending cannot substitute for analyzing their business models. All four companies are purchasing chips, building campuses, and signing power contracts, but their monetization channels differ: Microsoft relies on Azure and enterprise software customers; Amazon relies on AWS scale and in-house chips; Google is seeking to expand TPU adoption among external customers; and Meta first serves advertising and model training before pursuing additional compute-sales channels.
Microsoft: Strongest Contract Coverage, but Leases and Depreciation Require the Closest Monitoring
Microsoft has the clearest enterprise demand channel. Microsoft’s approximately $627.0 billion in remaining performance obligations provides long-term coverage for Azure capacity, while Office, data platforms, security, and developer tools allow AI capabilities to be embedded within existing customer budgets. Goldman Sachs estimates that Microsoft’s capital expenditures excluding leases will reach $112.6 billion, $203.2 billion, and $278.4 billion in fiscal 2026, 2027, and 2028, respectively.
The lease-inclusive figure is higher. Investment including finance leases reaches $319.0 billion in fiscal 2028, materially above cash capital expenditures. Both measures must be tracked to understand the company’s actual capacity commitments.
The market is concerned that revenue estimates are rising more slowly than capital expenditure estimates. Microsoft makes extensive use of Nvidia systems, leaving memory and complete-system costs more exposed to supply-chain price increases, while its in-house chips are less mature than those of Google and Amazon. Key indicators to monitor are Azure revenue growth, AI services gross margin, incremental finance leases, and depreciation. If the capital required for each incremental dollar of Azure revenue continues to rise, the benefit of strong order coverage will be offset by lower incremental returns.
Amazon: The Largest Capital Budget, With Trainium Determining Unit Economics
Amazon’s total includes more non-AWS assets. Goldman Sachs estimates Amazon’s capital expenditures at $200.1 billion, $285.1 billion, and $342.2 billion in 2026, 2027, and 2028, respectively. These figures also include logistics, warehousing, and other business assets and therefore cannot be attributed entirely to AI data centers. An analysis of AWS must separate server, data center, lease, and network investments and match them against AWS revenue and operating profit.
Trainium will determine whether Amazon can translate scale into returns. In-house chips can reduce unit training and inference costs, lessen dependence on expensive general-purpose accelerators, and allow Amazon to offer customers lower prices. If Trainium usage rises while AWS gross margins remain stable, capital efficiency will improve. If customers continue to prefer Nvidia’s software ecosystem, however, the development and inventory requirements of in-house chips will instead add complexity.
Google: TPU Is Moving From an Internal Cost Center to an External Product
Google’s incremental value comes from commercializing TPU. Morgan Stanley expects Google to add 9GW of compute capacity in 2028, comprising approximately 7GW of TPU capacity and 2GW of GPU capacity, with potentially around 4GW of first-party TPU capacity sold externally. Its forecast points to cloud revenue exceeding $300 billion and cloud EBIT of approximately $130 billion in 2028, making capacity monetization the central driver of valuation upside.
We see Google adding 9 GW of compute capacity in '28 and selling 4 GW of TPU on a 1P basis. This isn't priced as we raise Cloud ests, now seeing over $300bn/$130bn of rev/EBIT in '28 and $19 of Google EPS. Tactical flows weigh on Google even as visibility improves; OW, PT to $415 (~20% upside).
If Google can secure external customer adoption of TPU, its revenue base will expand beyond its own search, advertising, and model-training workloads into general-purpose cloud services. The challenges are software compatibility, developer migration, and customer concerns about vendor lock-in. The expected 4GW of external sales must be continually validated against the number of TPU customers, cloud orders, inference pricing, and revenue per watt.
Meta: Monetize Advertising Returns First, Then Test Compute and Model Services
Meta’s primary return still comes from its own businesses. Incremental compute capacity can improve recommendations, advertising conversion, and model capabilities. These internal benefits may not be disclosed separately but will be reflected in advertising revenue, engagement, and margins. Citi estimates Meta’s capital expenditures at approximately $139.0 billion in 2026 and $171.0 billion in 2027, with free cash flow of approximately $14.6 billion and $8.5 billion, respectively, materially reducing its cash flow buffer.
Selling compute capacity externally provides a second monetization channel. Meta is evaluating two types of services: leasing raw compute capacity and offering hosted APIs and model services. Morgan Stanley estimates that leasing 250MW of capacity for one year at $40 per watt could add approximately $3 to 2028 EPS, an increase of around 8%. Raw compute capacity is easier to launch, while a full cloud service requires software, sales, customer support, and additional capital investment.
The plans reportedly include two potential offerings: 1) hosted API/modelaccess service similar to AWS Bedrock (which would serve models including Muse Spark to developers) and 2) a neocloud-like raw silicon offering. The effort would sit within Meta Compute, the business division they set up in January to manage the company's compute procurement. Note Meta has not commented on this morning's headlines.
This path shows that temporarily surplus capacity can be monetized, but it does not establish that the industry is already oversupplied. Citi’s research continues to indicate that data center leasing demand is beginning to secure deliveries for 2028-2030. Investors need to monitor how much capacity Meta sells, the duration of those contracts, and whether its own model training remains capacity-constrained after those sales.
Meta Sells Compute Capacity: From Advertising Company to AI Infrastructure Provider, With 250MW Potentially Adding $3 to EPS
