
目录
Executive Summary
1. The Revenue Curve Has Shifted Higher—but 454% Does Not Tell the Whole Story
2. A 50% Cloud Margin Is an Operating Breakthrough—not the End Point for Group Profitability
3. Improving Contract Pricing and Payback Periods Signal a Clear Step-Up in Growth Quality
4. The 5 GW Target Represents a Resource Pipeline, but the Execution Chain Remains Long
5. Operating Cash Flow Has Turned Positive, but Expansion Is Far from Self-Funding
6. The $8 Billion Cash Balance Is Backed by Parallel Expansion in Debt and Equity
7. Full-Year Guidance Is Unchanged, but the Math Has Become Much More Demanding
8. Software Is Increasing the Value of the Cloud, but Has Yet to Demonstrate Standalone Revenue
9. Six Questions the Next Earnings Report Must Answer
Conclusion
本内容基于公开资料和研报数据整理,不构成任何投资建议,不代表任何个人观点,仅供学习参考,请理性阅读
Nebius has shown that demand, pricing, and cloud margins can all rise simultaneously. The next test is converting massive upfront infrastructure investment into recurring revenue, rather than continuing to explain growth through the pace of financing.
Executive Summary
Second-quarter 2026 group revenue reached $582.3 million, up 454% year over year and 46% sequentially. AI cloud revenue was $574.9 million, accounting for 98.7% of group revenue. AI cloud annualized run-rate revenue reached $3.0 billion at the end of June, up 56% from the end of March, indicating that revenue continued to accelerate within the quarter rather than merely benefiting from a low comparison base.
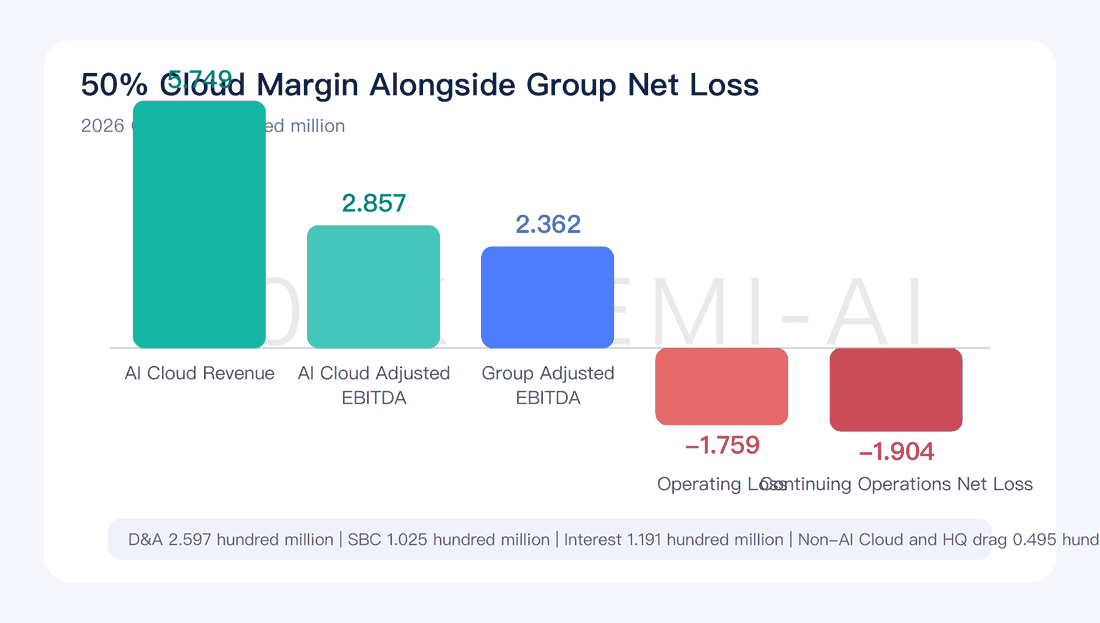
AI cloud adjusted EBITDA reached $285.7 million, representing a 49.7% margin. Group adjusted EBITDA was $236.2 million, with a 40.6% margin. This demonstrates strong operating leverage in commissioned clusters, but the group still reported an operating loss of $175.9 million and a continuing-operations net loss of $190.4 million. Depreciation, share-based compensation, and interest expense continue to create a substantial gap further down the income statement.
Contract economics delivered the quarter’s most significant quality improvement. Four landmark AI cloud contracts had an average total value exceeding $1.0 billion, with annual contract value of $20 million–$25 million per MW. Approximately 70% of second-quarter transactions included upfront payments covering 50%–60% of the associated capex, shortening the expected payback period from 2–3 years to 1 year and 10 months.
The 5 GW target refers to contracted power by the end of 2026—not capacity that is already online and billable. The company still expects 0.8–1.0 GW of connected power by year-end and plans to deploy more than 1 GW annually from 2027 onward. The gap between contracted and connected power represents both the future revenue opportunity and the associated engineering, equipment, financing, and customer-acceptance risks.
Second-quarter operating cash flow was $2.2461 billion, but purchases of property, equipment, and intangible assets totaled $5.6574 billion, leaving simple free cash flow negative at $3.4113 billion. More importantly, accounts-receivable collections and increases in deferred revenue contributed a combined $2.3838 billion—more than the quarter’s total operating cash flow. Much of the cash-flow improvement therefore came from customer funding received in advance, not from net income turning positive.
At the end of June, unrestricted cash was $8.0421 billion, debt was $8.5457 billion, deferred revenue was $5.9752 billion, and net property and equipment stood at $13.0452 billion. First-half financing cash flow totaled $9.1604 billion, driven by convertible notes, pre-funded warrants, and sales of treasury shares. Liquidity remains ample, but expansion still depends on a combination of customer prepayments, debt, and equity financing.
The company reiterated its 2026 guidance for full-year revenue of $3.0 billion–$3.4 billion, year-end annualized run-rate revenue of $7.0 billion–$9.0 billion, an AI cloud adjusted EBITDA margin of approximately 40%, and year-end connected power of 0.8–1.0 GW. Based on first-half results, second-half revenue must reach $2.0187 billion–$2.4187 billion, implying average quarterly revenue 73%–108% above the second quarter. Delivering the full-year outlook therefore remains highly dependent on capacity coming online in the second half.
1. The Revenue Curve Has Shifted Higher—but 454% Does Not Tell the Whole Story
Nebius (Nasdaq: NBIS) generated second-quarter revenue of $582.3 million, up 454% from $105.1 million a year earlier and 46% from $399 million in the first quarter. First-half revenue reached $981.3 million, up 529% year over year. Although the annual growth rate still benefits from a low comparison base, nearly 50% sequential growth confirms that the acceleration is not limited to year-over-year comparisons.
The revenue mix is even more important. Second-quarter AI cloud revenue reached $574.9 million, up 514% year over year and representing 98.7% of group revenue. Avride, TripleTen, and other projects contributed only approximately $7.4 million combined. Nebius is now primarily an AI cloud company; its other businesses and strategic investments are better viewed as long-duration options that remain too small to alter the group’s heavy exposure to AI-compute demand.
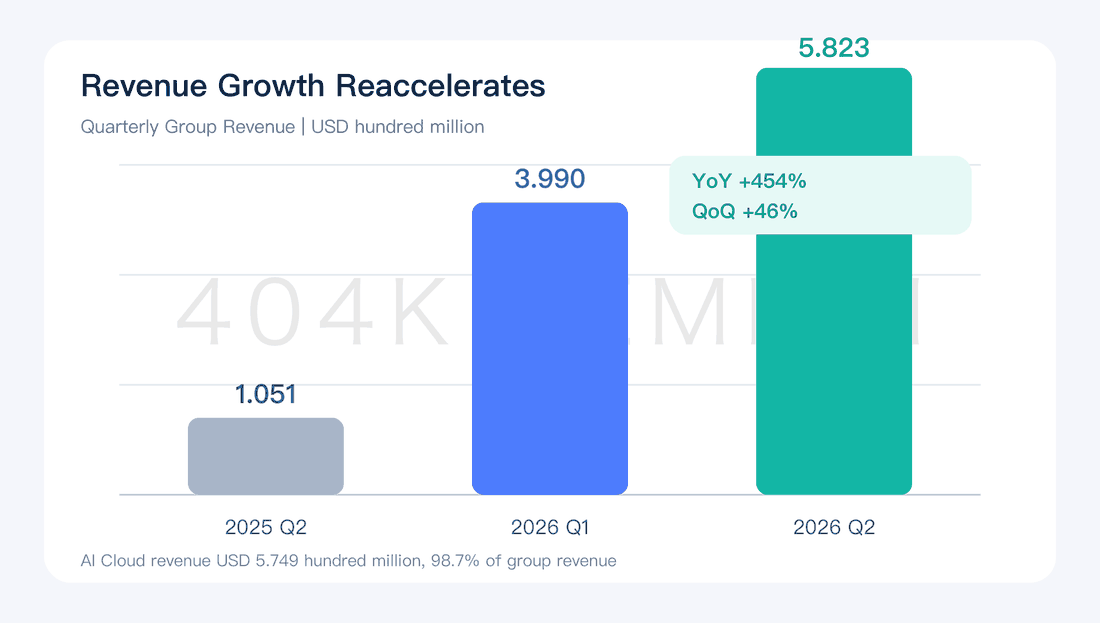
AI cloud annualized run-rate revenue reached $3.0 billion at the end of June, up 598% year over year and 56% from $1.9 billion at the end of March. This metric annualizes June AI cloud revenue by multiplying it by 12; it does not represent signed but undelivered orders or revenue guaranteed to be recognized over the next 12 months. It nevertheless provides a useful measure of momentum: average monthly AI cloud revenue in the second quarter was approximately $191.6 million, while a $3.0 billion annualized run rate implies approximately $250 million for June alone—around 30% above the quarterly monthly average.
This explains why group quarterly revenue rose 46% while the exit run rate increased 56%: more capacity likely began billing late in the quarter, and utilization or pricing may also have continued to rise. Provided these clusters do not encounter customer-acceptance, utilization, or power-supply issues in the third quarter, the exit rate at the end of the second quarter should form the starting point for third-quarter revenue.
Annualized run-rate revenue should not, however, be conflated with total contract value. The former describes the revenue pace already being generated in June; the latter represents aggregate commitments under multiyear contracts. Adding together $3.0 billion of annualized run-rate revenue, more than $40.0 billion of customer commitments, and 5 GW of contracted power would combine different time horizons, delivery stages, and risk profiles into a single headline number that cannot be realized as such. The correct analytical sequence is: commissioned capacity generates current revenue; signed contracts support future construction; prepayments help finance that construction; and only capacity that ultimately comes online and passes customer acceptance contributes to revenue.
2. A 50% Cloud Margin Is an Operating Breakthrough—not the End Point for Group Profitability
AI cloud adjusted EBITDA reached $285.7 million in the second quarter, representing a 49.7% margin, up from approximately 45% in the first quarter and approximately 24% in the fourth quarter of 2025. Group adjusted EBITDA was $236.2 million, with a 40.6% margin, an increase of $106.7 million from the first quarter. The approximately $49.5 million gap between AI cloud and the group reflects corporate overhead and other businesses that are not yet self-funding.
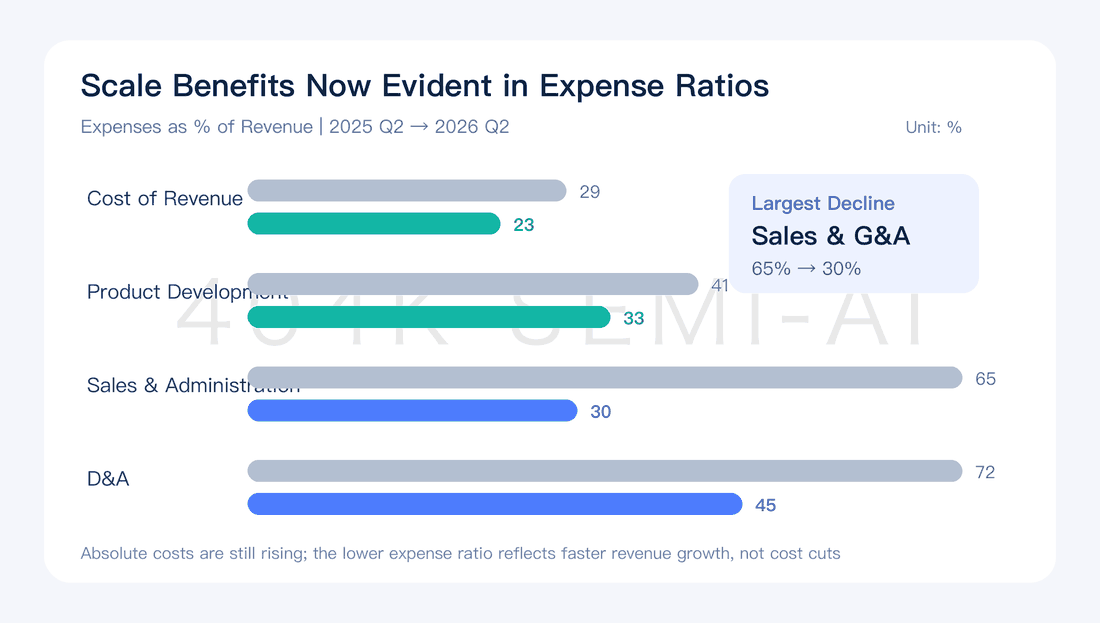
The margin expansion has a genuine operating foundation. Cost of revenue declined from 29% to 23% of revenue, product-development expense from 41% to 33%, sales and administrative expense from 65% to 30%, and depreciation and amortization from 72% to 45%. These ratios show that incremental revenue is materially diluting fixed organizational, data-center operating, and platform costs. The GPU clusters already in service are not generating larger losses as revenue grows.
Adjusted EBITDA does not, however, capture asset consumption or the cost of capital. Second-quarter depreciation and amortization totaled $259.7 million, share-based compensation $102.5 million, and interest expense $119.1 million. The group reported an operating loss of $175.9 million and a continuing-operations net loss of $190.4 million; even the adjusted net loss remained $33.2 million. In other words, the cloud business is already highly profitable before depreciation, share-based compensation, and similar items, but the group remains unprofitable after accounting for the asset consumption and financing costs generated by rapid expansion.
Product-development expense also included $115.9 million of one-time share-based compensation and post-acquisition costs related to the Eigen AI acquisition. This amount is not presented on the same classification basis as the $102.5 million of total group share-based compensation disclosed in the financial statements and therefore cannot simply be added to it. The former is management’s description of the source of a particular expense, while the latter is total share-based compensation reported in the cash-flow statement and expense footnotes. Analysts should avoid double-counting the two figures.
Another easily overlooked accounting change is that, beginning in 2026, the company extended the estimated useful life of servers and networking equipment from 4 years to 5 years, citing usage patterns and existing utilization commitments. A longer useful life reduces depreciation recognized on the same assets in each period, meaning current depreciation expense is not fully comparable with 2025. The company did not disclose how much higher second-quarter depreciation would have been under the previous 4-year assumption, so there is no basis for making an unsupported earnings adjustment. The estimate change should nonetheless remain part of the assessment of whether the 49.7% cloud margin is sustainable.
The appropriate conclusion is neither that “the company is already profitable” nor that “adjusted earnings are meaningless.” A more accurate interpretation is that the operating returns on commissioned cloud assets are beginning to be validated, while the group has yet to demonstrate that those returns can sustainably cover depreciation, equity compensation, interest, corporate investment, and the cost of upgrading to the next generation of GPUs.
3. Improving Contract Pricing and Payback Periods Signal a Clear Step-Up in Growth Quality
The second quarter was Nebius’s strongest commercial quarter to date. The company signed four landmark AI cloud contracts, each with an average total contract value of more than $1 billion. Customers included Reflection, Cohere, an emerging US AI lab, and a large US quantitative-trading firm. Total value of new contracts signed during the quarter increased nearly 4-fold sequentially, while total value from new-customer contracts rose more than 9-fold.
Beyond contract volume, economics per MW provide a clearer measure of quality. The 2026 business benchmark is approximately $12 million in annual contract value per MW, while contracts won in the second quarter averaged more than $20 million; the four large deals ranged from $20 million–$25 million. The company also said pricing for older-generation GPUs increased by more than 30% from the first quarter. Supply scarcity, GPU generation, software capabilities, and delivery speed are all increasingly reflected in pricing, making growth less dependent on capital-spending expansion alone.
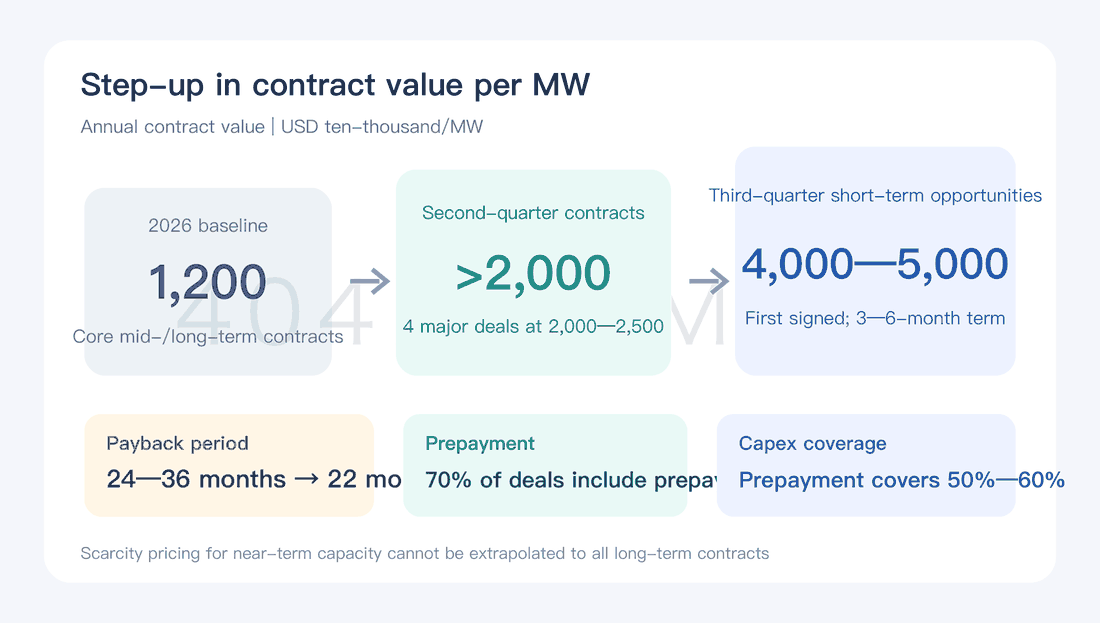
Cash terms are also improving. Approximately 70% of second-quarter transactions included prepayments, which can cover 50%–60% of the associated capital expenditure. The expected payback period on the corresponding capital and operating costs is 1 year and 10 months, down materially from 2–3 years previously. For a capital-intensive cloud business, a shorter payback period matters more than headline contract-value growth because it reduces the time each expansion cycle ties up external funding.
In the third quarter, the company began testing 3–6-month capacity contracts and held its first capacity auction, identifying an opportunity for $40 million–$50 million in annual contract value per MW. It has already signed its first short-term contract. This reflects an exceptionally tight near-term GPU supply environment and gives Nebius a reason not to sell all its 2027 capacity too early at lower prices.
Short-term pricing, however, should not be extrapolated directly into long-term average pricing. Customers signing 3–6-month contracts typically face time-sensitive workloads that cannot wait and are therefore willing to pay a substantial premium for immediately available capacity. Upon expiry, pricing will move with supply and demand, GPU generations, and customer budgets. The $40 million–$50 million range is better viewed as the marginal price of scarce capacity than as a sustainable annual revenue rate for the entire future 5 GW portfolio.
Similarly, the 1 year and 10 months payback period is based on forecast costs and contracted future capacity using revenue-recognition assumptions, and explicitly excludes the prepayments themselves. It demonstrates improving unit economics but still depends on on-time construction, continued customer performance, and equipment costs remaining within budget. The more attractive the projected payback period, the more important it is to validate it in subsequent reporting through actual capital expenditure, revenue recognition, and asset utilization.
4. The 5 GW Target Represents a Resource Pipeline, but the Execution Chain Remains Long
Nebius has again raised its year-end 2026 contracted-power target, this time to 5 GW. The target stood at more than 1 GW in August 2025, before rising successively to more than 2.5 GW, more than 3 GW, more than 4 GW, and now 5 GW. Repeated upward revisions within one year indicate that the company is securing land and power resources far faster than previously planned, creating greater expansion capacity beyond 2027.
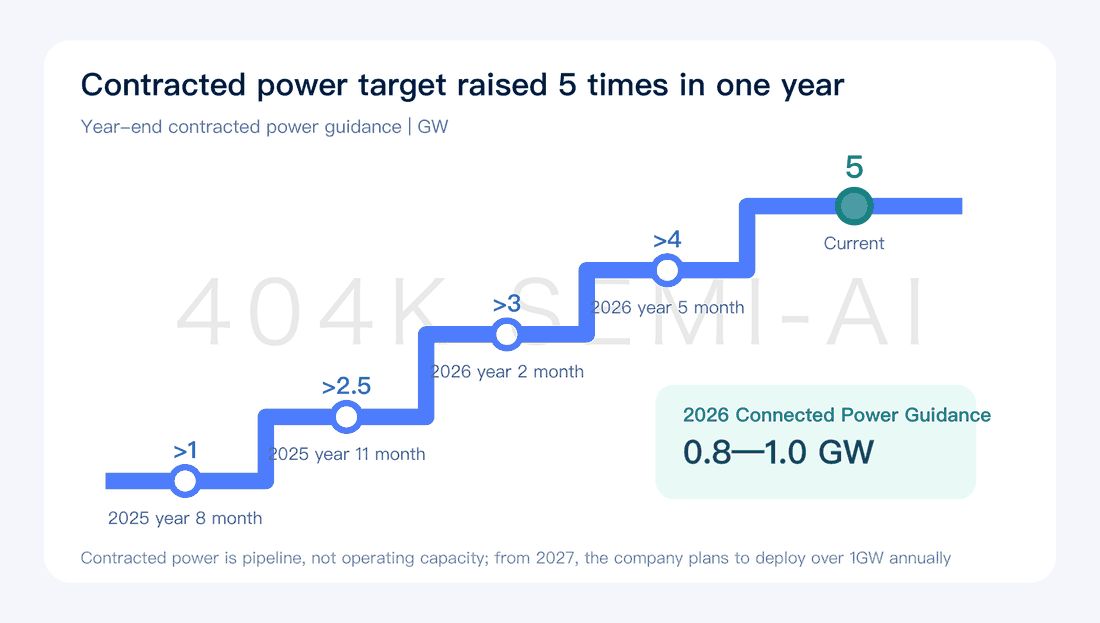
“Contracted power,” “connected power,” and “active power” must be distinguished. Contracted power represents secured land and power commitments. Connected power refers to completed, fully equipped data centers connected to the grid. Active power means installed IT equipment is operating and available to generate revenue. The 5 GW target sits only at the first stage. The company’s previous guidance for year-end 2026 connected power remains 0.8–1.0 GW, and the second-quarter shareholder letter explicitly reaffirmed all full-year guidance.
Nebius expects to deploy more than 1 GW annually beginning in 2027, while building its own AI factories in the US and expanding sites in the UK, Estonia, and Finland. Capacity under the second Meta agreement is expected to begin delivery in early 2027, while all tranches under the Microsoft contract have already been delivered. The first NVIDIA Vera Rubin NVL72 systems have also been received and tested. These developments show progress on both equipment and customer commitments, but contracted resources must still pass through power delivery, construction, GPU and networking deployment, cluster commissioning, customer acceptance, and utilization ramp-up before generating revenue.
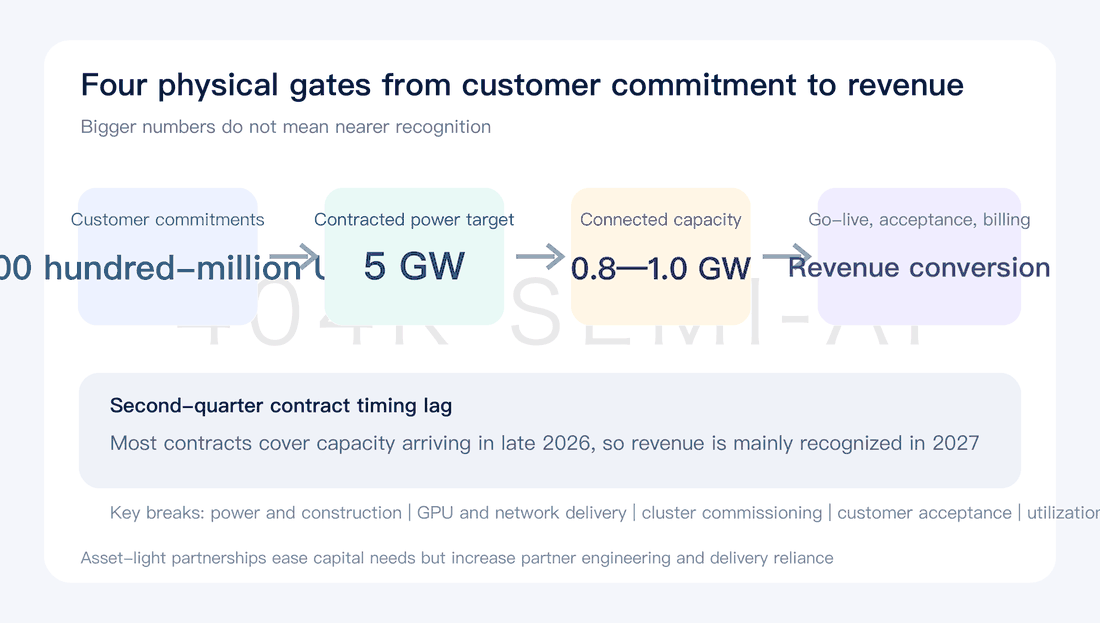
The timing gap is particularly important. The company explicitly stated that most second-quarter contracts relate to capacity scheduled to arrive at the end of 2026 and will therefore contribute primarily to 2027 revenue. The quarter’s contract momentum improves future visibility rather than immediately increasing second-quarter revenue. Multiplying newly signed contract values by the number of quarters and including the result in 2026 revenue would prematurely recognize computing capacity that has not yet been built.
To ease both capital and capacity constraints, Nebius has introduced an asset-light partnership model. Partners own the land, facilities, power infrastructure, and hardware, while Nebius provides the architecture, cloud platform, software, and customer acquisition. The model reduces Nebius’s capital commitment and accelerates replication, but increases its dependence on partners for engineering quality, delivery timing, and infrastructure control. Investors should monitor revenue-sharing arrangements, margins, balance-sheet treatment, and service levels rather than assume that the “asset-light” label will immediately reduce capital expenditure.
5. Operating Cash Flow Has Turned Positive, but Expansion Is Far from Self-Funding
Second-quarter operating cash flow was $2.2461 billion, a marked improvement from negative $171.6 million in the prior-year period. First-half operating cash flow reached $4.5041 billion. On the surface, operating cash flow already substantially exceeds both group adjusted EBITDA and net income, suggesting that expansion could fund itself.
The cash-flow statement provides a more complete explanation. Changes in accounts receivable generated a $1.1868 billion second-quarter cash inflow, while the increase in deferred revenue contributed another $1.197 billion. Together, these items totaled $2.3838 billion, exceeding total operating cash flow for the quarter. They reflect both faster customer collections and customer funding received before service delivery. These are evidence of improving commercial quality and financing efficiency, but they do not represent earned revenue and remain tied to future capacity construction and performance obligations.
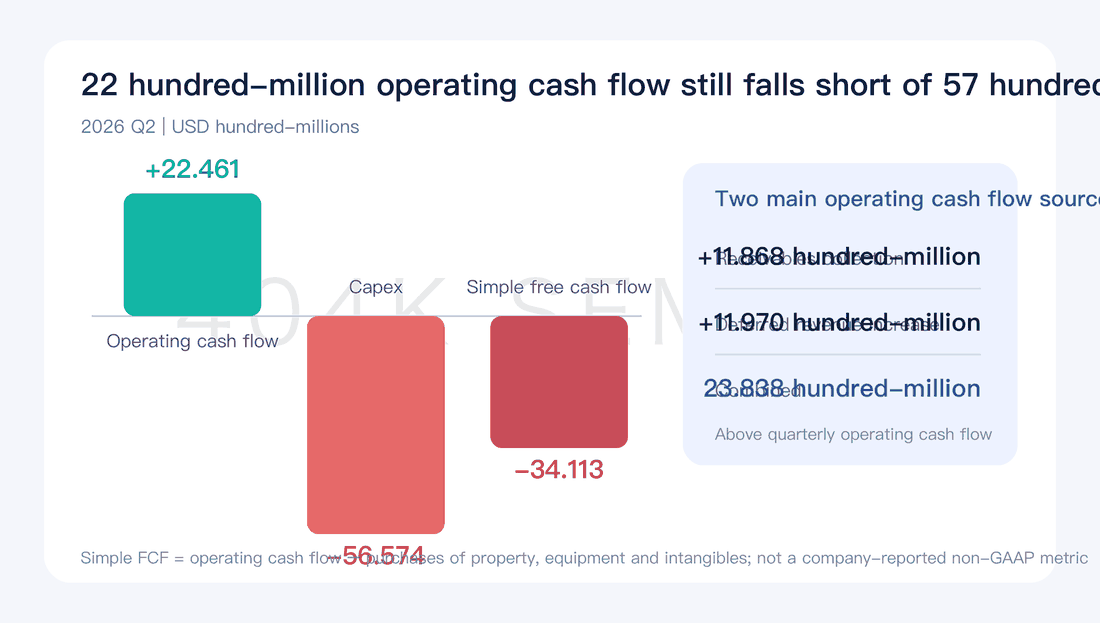
Meanwhile, second-quarter purchases of property, equipment, and intangible assets totaled $5.6574 billion, primarily for GPUs, related hardware, and data-center expansion. Subtracting this expenditure from operating cash flow produces simple free cash flow of negative $3.4113 billion; the first-half figure was negative $3.6262 billion. This calculation is intended only to illustrate the funding gap. It is not a company-reported non-GAAP measure and does not distinguish growth capital expenditure from maintenance capital expenditure.
Cash flow should be interpreted on three levels. First, customers’ willingness to prepay increases confidence in demand and enhances the financing value of contracts. Second, those prepayments are recorded as deferred revenue, and Nebius must still deliver the contracted capacity. Third, even if prepayments cover 50%–60% of the associated project capital expenditure, the remainder and other construction spending must still be financed through company cash, debt, equity, or partner capital.
Nebius expects customer prepayments to exceed $9 billion in 2026, an amount greater than its $8.0421 billion of unrestricted cash at the end of June. These prepayments can materially reduce external financing pressure, but they will also widen the gap between operating cash flow and accounting earnings. If prepayment growth slows while capital expenditure remains elevated, operating cash flow will reveal funding pressure earlier than revenue or adjusted EBITDA.
6. The $8 Billion Cash Balance Is Backed by Parallel Expansion in Debt and Equity
At the end of June, Nebius held $8.0421 billion in cash and $1.056 billion in restricted cash, for a combined $9.0981 billion. Current and non-current debt totaled $8.5457 billion. Compared only with unrestricted cash, the company had approximately $503.6 million of net debt; including restricted cash, it retained approximately $552.4 million of net cash. The two calculations serve different purposes, and restricted cash should not be treated as freely available to fund construction.
Asset growth was even more pronounced. Net property and equipment increased from $5.5533 billion at year-end 2025 to $13.0452 billion, an increase of $7.4919 billion, or approximately 135%, in six months. Deferred revenue rose from $1.5775 billion to $5.9752 billion, an increase of $4.3977 billion. The simultaneous expansion of assets and performance obligations is the balance-sheet expression of a model in which customers pay first and the company subsequently builds capacity.
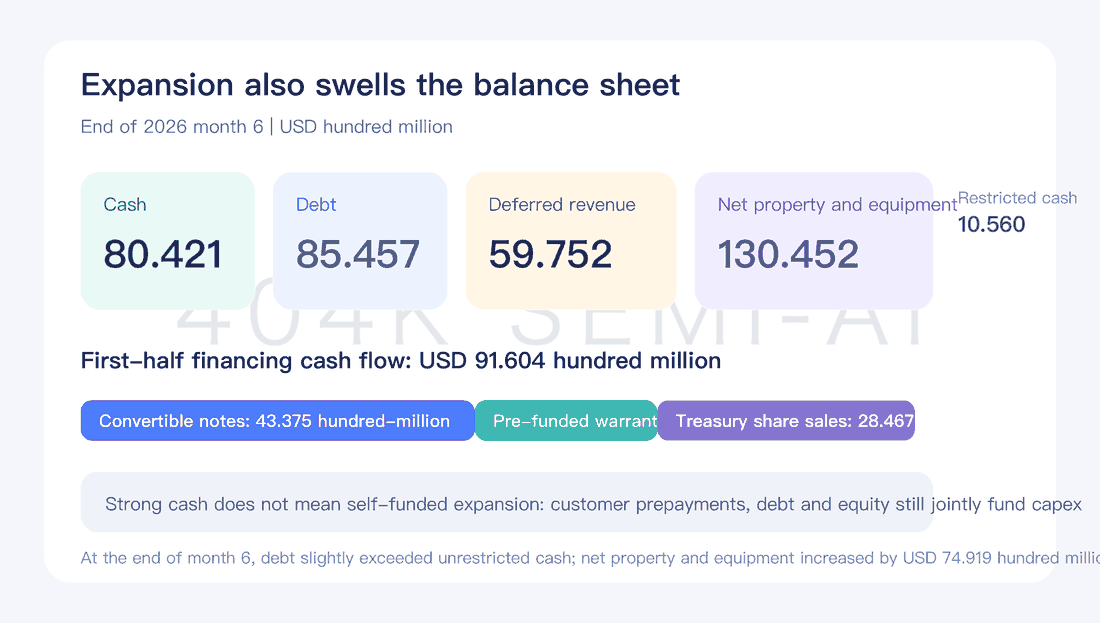
First-half net financing cash inflow was $9.1604 billion, primarily comprising $4.3375 billion of convertible notes, $2 billion of pre-funded warrants, and $2.8467 billion in proceeds from the sale of treasury shares. During the second quarter, Nebius sold 12.70 million Class A shares through its at-the-market offering program at an average price of $223.6, raising approximately $2.8 billion. At period-end, another 12.30 million shares remained available for sale under the program.
Equity financing reduces near-term debt-servicing pressure but expands the denominator for per-share metrics. Second-quarter basic weighted-average shares increased 17.6%, from 238.5 million in the prior-year period to 280.4 million. At the end of June, combined Class A and Class B shares outstanding totaled 271.9 million, excluding another 50.19 million treasury shares. If Nebius continues using equity to close the capital-expenditure funding gap, growth in total revenue and profit may not translate proportionately into per-share results.
Debt financing is also becoming more closely aligned with project cash flows. In July, Nebius completed its first $775 million secured financing at SOFR plus 2.50%, collateralized by deployed GPUs and cash flows from investment-grade customer contracts. This asset-backed structure helps convert long-term customer credit into lower-cost funding, but it also binds each project’s equipment, contracts, and debt more tightly together. Customer delays, lower equipment utilization, or changes in refinancing conditions could therefore affect both project cash flow and financing terms.
The $8 billion cash balance is therefore better understood as capital temporarily held during the construction cycle than as a static margin of safety. Assessing balance-sheet health requires looking beyond period-end cash to customer prepayments, capital expenditure, restricted cash, debt maturities, interest costs, equity dilution, and the speed at which new capacity begins billing.
7. Full-Year Guidance Is Unchanged, but the Math Has Become Much More Demanding
The second-quarter shareholder letter reaffirmed all 2026 full-year targets. Together with the official first-quarter shareholder letter, these include full-year revenue of $3.0 billion–$3.4 billion, year-end AI cloud annualized run-rate revenue of $7.0 billion–$9.0 billion, an AI cloud adjusted EBITDA margin of approximately 40%, and 0.8–1.0 GW of connected power at year-end. This quarter, the company also raised its year-end contracted-power target from more than 4 GW to 5 GW.
First-half revenue was $981.3 million, implying that Nebius must generate $2,018,700,000–$2,418,700,000 in the second half, or an average of $1,009,400,000–$1,209,400,000 per quarter. That average is 73%–108% above second-quarter revenue of $582.3 million. With substantial capacity likely to come online late in each quarter, delivery will probably be heavily weighted toward the fourth quarter.
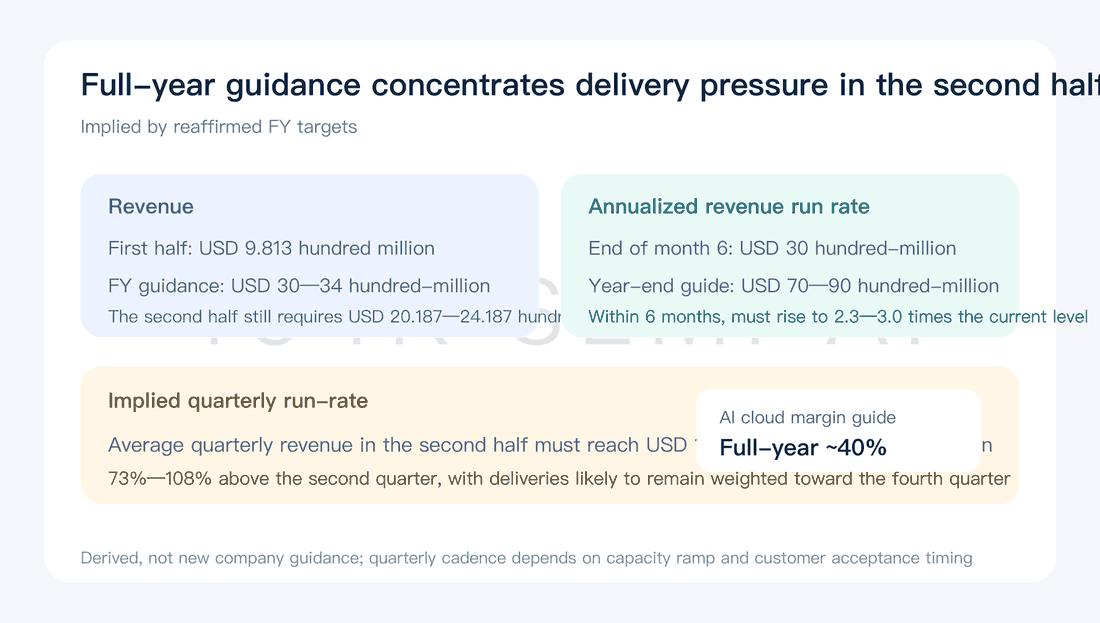
The required trajectory for annualized run-rate revenue is equally steep. The $3.0 billion reported at the end of June must rise to $7.0 billion–$9.0 billion within 6 months, equivalent to 2.3–3.0 times the current level. Because annualized run-rate revenue is calculated by multiplying the final month’s revenue by 12, the year-end monthly figure can substantially exceed the full-year average without conflicting with the $3.0 billion–$3.4 billion full-year revenue target. It does, however, require capacity, utilization, and pricing to rise concurrently throughout the second half.
The AI cloud adjusted EBITDA margin reached 49.7% in the second quarter, above the approximately 40% full-year guidance. This should not be interpreted as making an upward revision inevitable. New capacity typically incurs operating, hiring, and commissioning costs before utilization ramps. Short-duration, premium-priced contracts support margins, while rapid expansion and investment in new products may weigh on them. The approximately 40% full-year target appears to preserve a buffer between strong growth and capacity-launch costs.
The second-quarter materials also stated that “detailed guidance will be shared on the earnings call,” but no verifiable audio or transcript replay was available on the company’s website when this report was finalized. The figures above therefore reflect the prior quarter’s official guidance, which the company explicitly reaffirmed, rather than treating unavailable earnings-call commentary as new disclosure. Any more granular guidance on quarterly phasing, capital expenditure, or financing should be verified separately in the next update.
8. Software Is Increasing the Value of the Cloud, but Has Yet to Demonstrate Standalone Revenue
Nebius aims to become a full-stack AI cloud rather than merely a GPU-rental provider. Token Factory production inference workloads grew by more than 3 times in the second quarter; object-storage reads increased 30%, while small-file operations on the shared file system rose approximately 3 times. The company released Aether 3.6 and added inference-optimization capabilities through the acquisitions of Eigen AI and Clarifai. The first Vera Rubin NVL72 systems have also entered testing.
These product advances could improve unit economics through 3 channels: keeping customers’ training and inference workloads on the same platform and increasing cluster utilization; raising revenue per MW through storage, networking, and orchestration services; and reducing customers’ willingness to migrate by improving the developer experience. The simultaneous increase in annual contract value per MW and pricing for older GPUs indicates that customers are willing to pay for availability and platform capabilities rather than comparing only per-GPU rental rates.
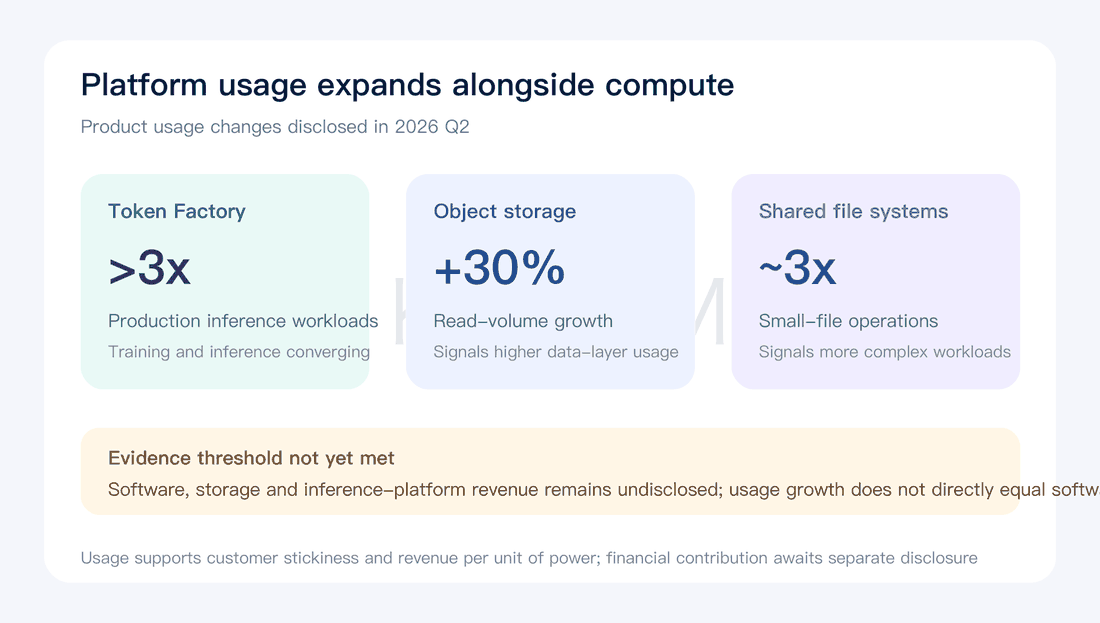
However, the financial statements still do not separately disclose revenue from software, storage, or the inference platform, while AI cloud accounts for 98.7% of group revenue. The evidence therefore supports the conclusion that software is enhancing cloud contract value, but not yet that Nebius has established independently priced, low-capex software revenue. The most persuasive next-stage evidence would be separate disclosure of revenue per unit of power, inference mix, customer expansion rates, or software-services revenue.
The other businesses also remain in investment mode. Avride’s fleet exceeds 200 vehicles, logged more than 1 million autonomous-driving miles in 2026, and completed more than 60,000 commercial rides on the Uber platform. TripleTen launched an AI Systems Engineering program and expanded its enterprise business. When ClickHouse raised capital in January 2026, it disclosed a company valuation of $15 billion, with Nebius holding a significant minority stake. These assets may create long-term value, but the approximately $49.5 million gap between group and AI cloud adjusted EBITDA this quarter indicates that, collectively, they are still consuming profits generated by the core cloud business.
9. Six Questions the Next Earnings Report Must Answer
First, can the $3.0 billion annualized run-rate revenue reported at the end of June carry smoothly through the third quarter, rather than falling back because of customer acceptance timing or capacity ramp-up? The gap between annualized run-rate revenue and quarterly AI cloud revenue is the clearest indicator of whether intra-quarter acceleration is continuing.
Second, how much of the 5 GW of contracted power will convert into connected and energized power? Continued growth in contracted resources is valuable, but if connected power remains near 0.8–1.0 GW for an extended period, revenue generation and capital recovery will be delayed.
Third, will the annual contract value per MW and 22-month payback period on the second quarter’s 4 major contracts be validated after actual delivery? The $40 million–$50 million marginal pricing on short-duration contracts is impressive, but the more important question is whether medium- and long-term contracts can sustain $20 million–$25 million as scale increases.
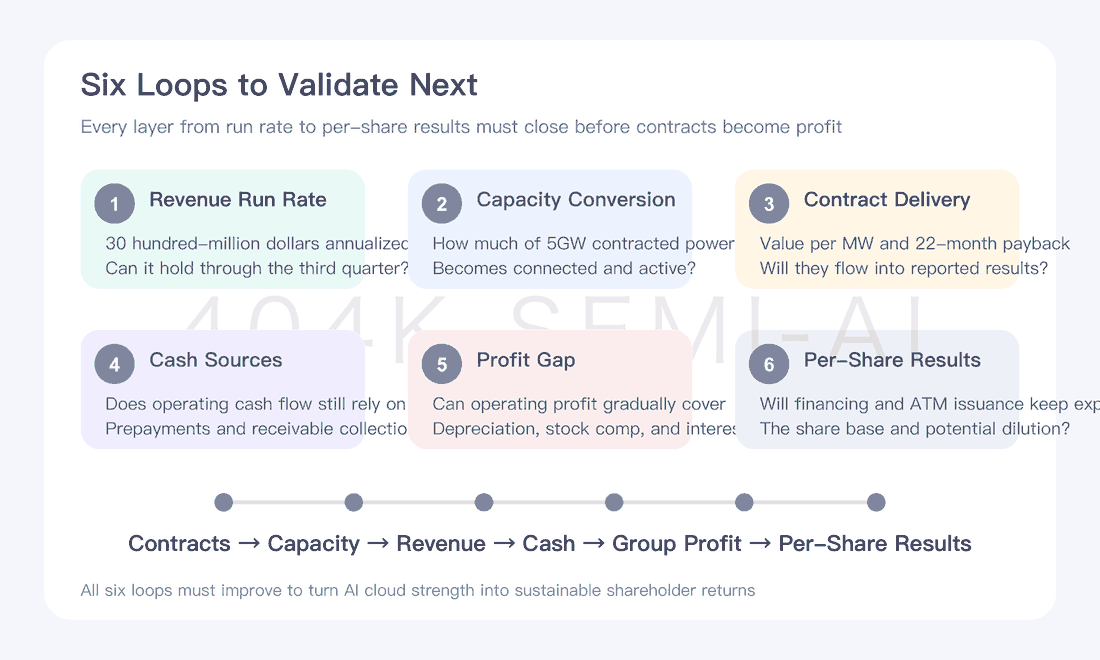
Fourth, is the contribution of customer prepayments and receivables collection to operating cash flow sustainable? Prepayments are attractive financing, but they also create performance obligations. If operating cash flow improvement depends entirely on growth in deferred revenue, free cash flow will remain constrained by capital expenditure.
Fifth, can depreciation, share-based compensation, and interest expense grow more slowly than revenue? Comparisons of depreciation require greater caution after the estimated useful life of servers was extended from 4 years to 5 years. The group’s earnings quality will approach the level implied by AI cloud adjusted EBITDA only when operating profit progressively covers interest expense.
Sixth, will financing continue to dilute per-share results? Asset-backed debt can reduce reliance on equity, but the remaining ATM capacity, potential conversion of convertible debt, and new financing could still increase the share count. Future analysis must compare not only revenue growth, but also changes in revenue per share, cash flow per share, and tangible assets per share.
Conclusion
Nebius’s second-quarter results were about more than rapid growth. The deeper shift was the simultaneous improvement in AI cloud margins, contract value per MW, customer-prepayment ratios, and projected payback periods, indicating that demand is converting from expressions of interest into more favorable commercial terms. The company is also no longer relying on a single long-term contract to lock in capacity; instead, it is combining short-duration contracts, core medium-term agreements, and investment-grade long-term contracts to balance pricing, utilization, and financing.
However, the results did not eliminate the fundamental constraints of a capital-intensive AI cloud. Quarterly capital expenditure of $5.6574 billion substantially exceeded operating cash flow of $2.2461 billion, while operating cash flow itself was heavily supported by receivables collection and deferred revenue. A vast construction and commissioning chain still separates 5 GW of contracted power from the year-end target of 0.8–1.0 GW of connected power, and most of the major second-quarter contracts will primarily contribute revenue in 2027.
The key issue for Nebius is therefore whether 3 curves can converge simultaneously: continued improvement in contract pricing and prepayments; on-schedule capacity deployment that converts into revenue; and operating profit that ultimately covers depreciation, interest, and share-count expansion. Whether demand exists has become a secondary question. The second quarter made the first 2 curves more credible; the third still requires validation in future financial statements. This is the central tension between a 50% cloud margin and $5.7 billion of capital expenditure.