
NAURA In-Depth Update: How Memory/Logic Expansion, Glass Substrate TGV, and a RMB1,031 Target Price Revalue the Equipment Platform
目录
Too Long; Didn't Read
I. What Is Actually New in This Update: From “Orders Absorbing Expenses” to “Three New Order Curves”
II. What HSBC’s Model Is Saying: Profits Cut, Valuation Raised
III. Why Memory Customers Matter: From a Mature-Node Proxy to a DRAM/NAND Expansion Proxy
IV. Logic Expansion Remains the Base: Advanced Logic Determines the Quality of a Platform Supplier
V. Glass Substrates: TGV/ECP Is Not Current Profit, But a Genuine New TAM
VI. How to Read the Target Price Upgrade: RMB1,031.90 Is Based on PS Valuation, Not a Short-Term Buy Signal
VII. Core Model: Three-Stage Validation of Orders, Revenue, and Margin
VIII. Compared with the Prior Report: Glass Substrate Is New, Memory Is Reinforced, Expense Pressure Is Unchanged
IX. Peer Positioning: NAURA’s Advantage Is Not Being the Strongest at One Point, but Participating in More Equipment Steps
X. Financial Bridge: After Revenue Steps Up, Margin Is the Final Pricing Variable
11. Three Worldviews: When You Are Bullish on NAURA, Which Future Are You Actually Choosing?
12. Falsification Checklist: What This Report Is Most Afraid Of
13. How to Track the Next Four Quarters: Orders First, Then Revenue Recognition, Finally Earnings Quality
XIV. Conclusion: Naura Is Moving from an “Equipment Leader” to a “Multi-TAM Platform,” but Valuation Still Needs Margin Confirmation
本内容基于公开资料和研报数据整理,不构成任何投资建议,不代表任何个人观点,仅供学习参考,请理性阅读
The core of this NAURA update is that order sources are expanding from advanced logic into memory capacity expansion and glass-substrate equipment. HSBC Qianhai raised its target price to RMB1,031.90. The real change is that the valuation anchor has shifted from current earnings to 2027 revenue and incremental platform TAM, with validation depending on whether orders, revenue, and margins are delivered in the same direction.
Too Long; Didn't Read
NAURA has added three new order curves. HSBC believes higher capex at domestic memory fabs, continued advanced-logic expansion, and incremental room from glass-substrate equipment will support a revenue CAGR of around 27%-28% for NAURA in 2026-2028. The prior deep dive focused on whether etch, deposition, and HBM packaging tools could absorb expense pressure; this update adds glass-substrate TGV/ECP equipment and order elasticity from memory customers.
The target-price upgrade comes from a change in valuation anchor. The report shifts the valuation base to 2027 revenue and raises the target price to RMB1,031.90, while cutting profit forecasts for the next two years and acknowledging higher expense pressure during the expansion phase. In other words, the bullish case is not that near-term profits are strong, but that the revenue platform and earnings elasticity become clearer after 2027.
Memory customers are the strongest marginal variable. HSBC notes that CXMT and YMTC still have global DRAM/NAND shares well below China’s share of demand. Potential IPO financing and the memory price cycle may continue to support capacity expansion. HSBC expects NAURA’s 2026 orders from memory and logic customers to grow by 50%+ and 30%+, respectively. This turns NAURA from a domestic-substitution beneficiary at mature nodes into a front-end equipment proxy for domestic memory capex.
Glass substrates are a new option. HSBC estimates the glass-substrate market will reach roughly USD11.3bn by 2032, with equipment and materials accounting for around 10%. NAURA already has a commercialized PVD base and can provide descum and PIQ equipment; later electroplating tools can reuse TSV experience. This story is still small today, but it adds a long-term “advanced packaging substrate equipment” path to NAURA’s platform valuation.
The counterevidence remains in expense ratios and gross margin. HSBC cut 2026/2027 EPS from RMB10.33/13.85 to RMB9.62/13.41, showing that higher orders and TAM do not automatically eliminate expense pressure. If 2026 orders are strong but 2027 revenue recognition, gross margin, and operating leverage do not improve in tandem, the PS valuation anchor behind the RMB1,031.90 target price will be compressed back into a current-earnings framework.
Watch five numbers over the next four quarters: memory/logic order growth, the revenue contribution from advanced products, whether gross margin stabilizes around 40% or higher, whether R&D; and SG&A; expense ratios peak, and whether glass-substrate TGV/ECP equipment enters a verifiable order phase. NAURA’s valuation does not lack narratives; it lacks evidence that orders, revenue, and margins are moving in the same direction.
I. What Is Actually New in This Update: From “Orders Absorbing Expenses” to “Three New Order Curves”
The central tension in the prior NAURA deep dive was whether advanced-process orders could absorb expense pressure from R&D;, share incentives, and new-product introductions. That report had already broken down the company across etch, deposition, HBM packaging tools, Kingsemi coating/developing, and advanced-logic orders: strong orders do not equal strong profits; the more advanced products there are, the heavier the upfront expenses, and the market must wait for revenue recognition and falling expense ratios as secondary validation.
HSBC Qianhai’s July 6 update pushes the question one step forward. The report does not deny expense pressure; on the contrary, it cuts 2026/2027 net-profit forecasts. But it also raises the target price sharply because the sources of revenue growth have broadened. NAURA is no longer only following advanced-logic expansion; it is now exposed simultaneously to three curves: domestic memory-fab expansion, continued advanced-logic capex, and glass-substrate equipment.
The first curve is memory. HSBC notes that CXMT and YMTC still have global DRAM/NAND shares below China’s share of demand. If potential IPO financing is combined with an upcycle in memory prices, domestic memory-fab expansion may continue to drive front-end equipment procurement. If NAURA can gain higher share in etch, deposition, thermal processing, cleaning, and other steps, memory orders will become the strongest variable for the 2026-2027 revenue slope.
The second curve is logic. The report cites China’s advanced-capacity expansion and lithography tool import price data to show that advanced-logic capex has not ended. Logic customers typically have higher requirements for equipment stability, delivery, process tuning, and customer service, making it easier for platform equipment vendors to secure multi-step orders. NAURA’s product breadth is more valuable in logic fabs than a single-equipment breakthrough.
The third curve is glass substrates. This is not the main driver of NAURA’s current revenue, but it is a valuation option. If glass substrates enter the upgrade path for high-performance packaging and AI chip substrates, TGV, PVD seed layer, descum, PIQ, and electroplating equipment will generate new equipment demand. HSBC has included this market in its target-price logic, meaning NAURA’s “platform” definition is extending from front-end WFE to advanced packaging substrate equipment.
NAURA In Depth: From Etch and Deposition to HBM Packaging Tools, How Advanced-Process Orders Absorb Expense Pressure
These three curves explain why HSBC still sees room after the share-price rebound. The report notes that NAURA has risen 57% over the past two months, but still lags the 72% gain in the Wind Semiconductor Equipment Index. The reasons for the relative lag are, first, market concerns about the gross-margin trend after 1Q26, and second, NAURA’s lower revenue exposure to memory customers versus peers such as AMEC and Piotech. HSBC’s view is that the product mix and customer structure are now addressing this shortfall.
This is not a simple “laggard catch-up” trade. If it were only laggard catch-up, the target-price increase would not need to come alongside cuts to profit forecasts. The real logic is that near-term margin downgrades already reflect expansion costs, while the long-term revenue pool and addressable market have expanded, allowing valuation to shift from the EPS trough to PS and revenue compound growth. Whether this switch holds depends on whether 2026 orders become 2027 revenue, not on whether a single-quarter net margin immediately recovers.
II. What HSBC’s Model Is Saying: Profits Cut, Valuation Raised
The most important part of this report is the model structure. HSBC is not simply raising the target price; it puts revenue, profit, ROE, and valuation multiples into one framework: revenue continues to step up, while earnings elasticity strengthens materially in 2027 and 2028. The specific figures are shown below. The more important issue in the text is why profit elasticity lags orders.
But the report does not blindly raise earnings. HSBC cuts EPS for the next two years because operating expenses are higher during the company’s expansion phase; R&D;, SG&A;, product validation, and headcount investment all hit the income statement first. It acknowledges that near-term profits are weaker than previously expected, but raises 2028 EPS to a higher level, showing that the core issue is not one-year profit in 2026, but subsequent compound earnings growth.
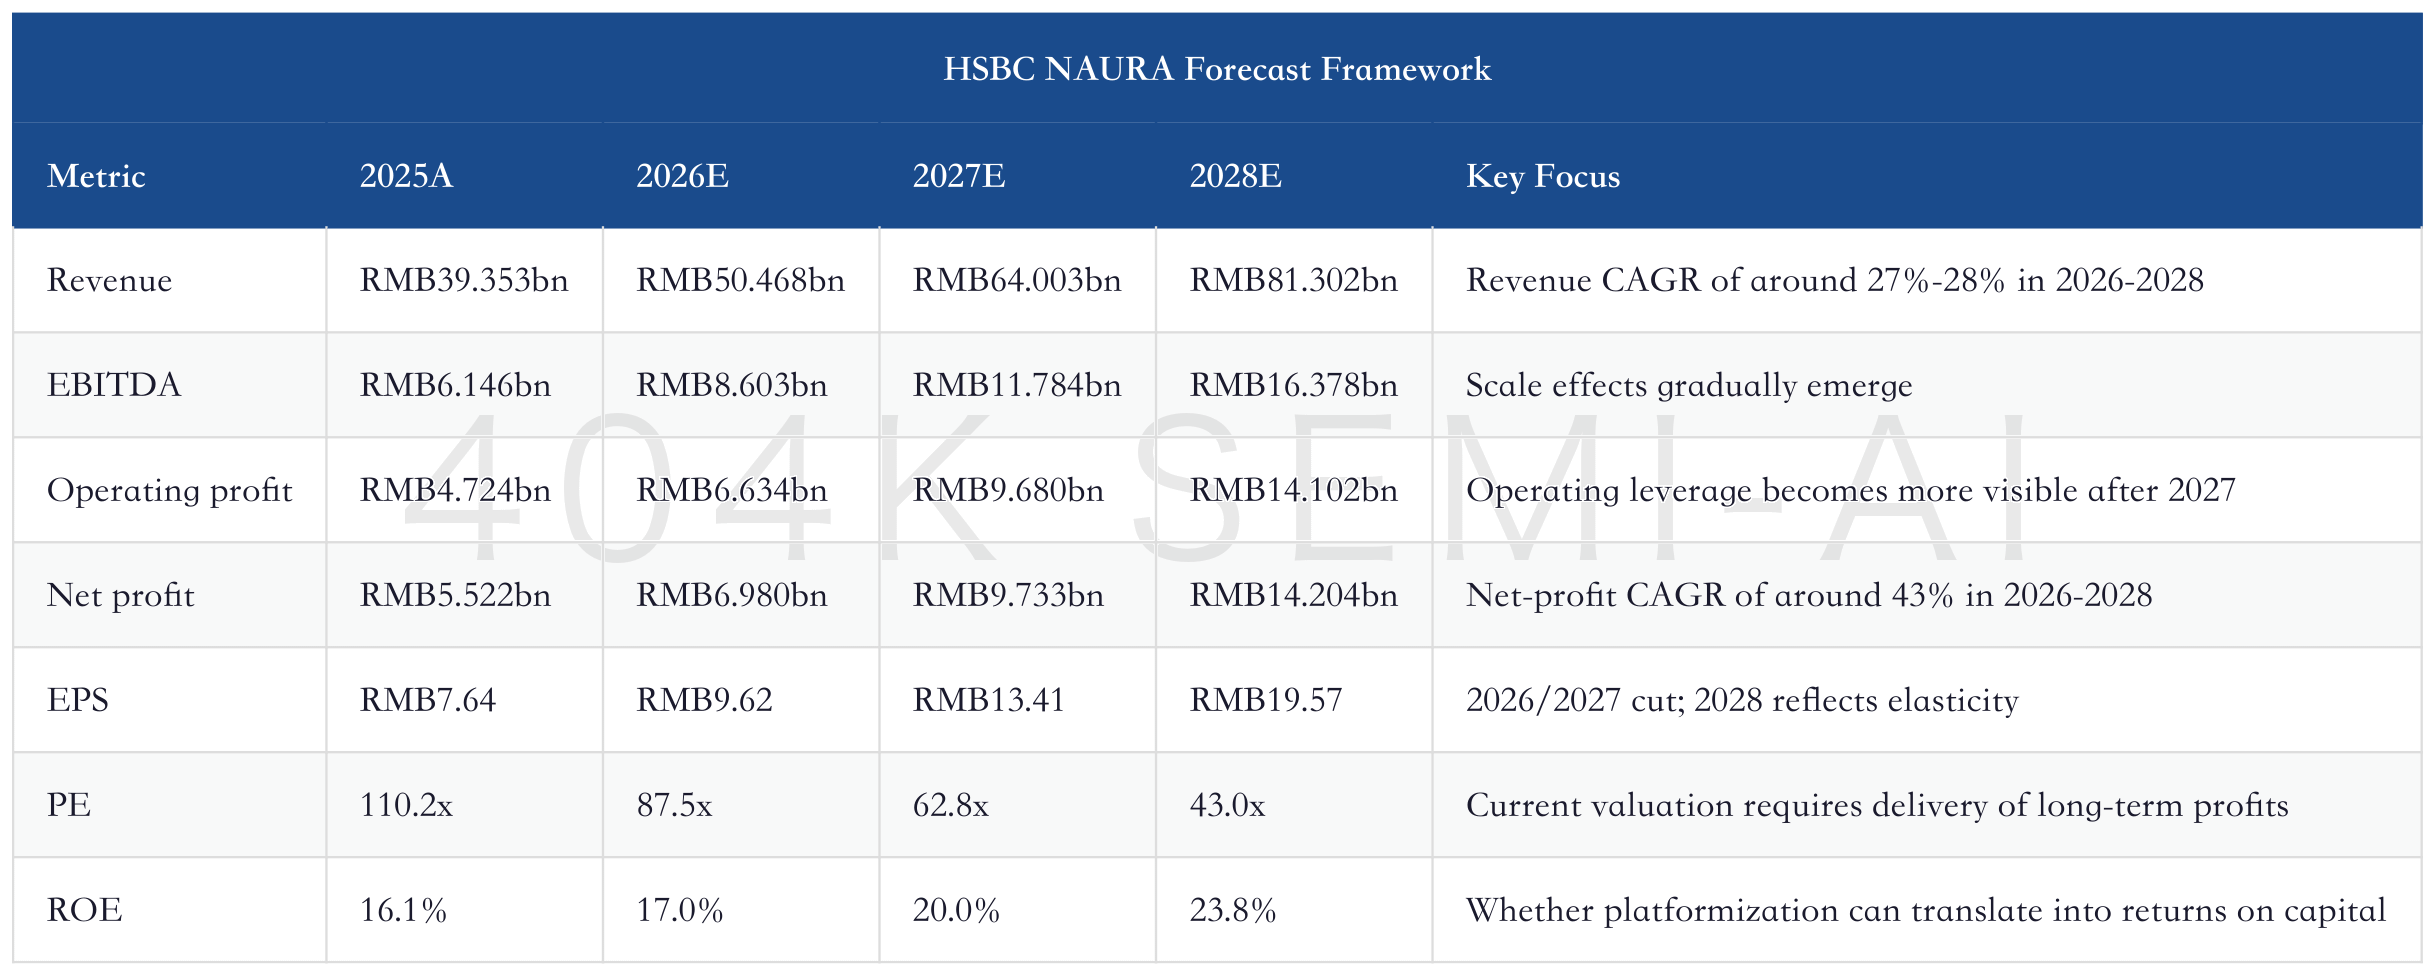
This table shows that HSBC is not betting on a sudden improvement in 2026 margins. It is betting that once the revenue platform rises, operating leverage will be released in 2027-2028. The stock looks expensive in 2026, but the 2028 PE falls to 43x; that is the basis for the report’s willingness to assign a high PS-based target price. If 2028 profits do not materialize, the target price naturally will not hold.
When reading this table, the focus should not be on any single number, but on the slope. The revenue slope represents customer expansion and equipment share; the operating-profit slope represents expense absorption; the ROE slope represents returns on capital. If NAURA delivers only the revenue slope, the stock will trade on growth. If it also delivers the operating-profit and ROE slopes, the valuation will shift from order expectations to earnings quality.
This is also the most easily overlooked part of equipment stocks: orders are leading indicators, profits are lagging indicators, and between them sit delivery, acceptance, yield, and service costs. The value of researching NAURA lies in breaking down these intermediate steps, rather than only looking at changes in the target price.
The valuation method has also changed. HSBC continues to use PS valuation, raising the target multiple from 7.5x previously to 11.7x, corresponding to 2027 revenue per share of RMB88.20 and producing a target price of RMB1,031.90. Choosing PS rather than PE essentially says: margins are still unstable during the expansion phase, and revenue visibility is a more suitable primary anchor than current net margin.
This is also a common revaluation path for semiconductor equipment growth stocks. In the early stage, the market watches orders; in the middle stage, revenue; in the later stage, margins. NAURA is now between orders and revenue: order clues are increasing, revenue forecasts are starting to rise, but margins are still pressured by expenses. The premise for using PS valuation is that investors believe revenue will convert into profit; once expense ratios fail to decline, the market will fold the PS multiple back into PE.
China Semiconductor Equipment In-Depth Update: CXMT Server DRAM Long-Term Orders, Advanced-Logic Expansion, and the Switch to 2030E Discounted PE
III. Why Memory Customers Matter: From a Mature-Node Proxy to a DRAM/NAND Expansion Proxy
In the past, when the market looked at Naura Technology, it often first thought of mature-node domestic substitution and advanced logic tool adoption. HSBC places greater emphasis on memory this time because memory capacity expansion brings forward the pace of equipment capex. If CXMT and YMTC continue to raise capacity, front-end tools such as etch, deposition, furnaces, and cleaning will all be pulled along, and Naura happens to cover these key segments.
A key comparison in HSBC’s framework is that CXMT’s and YMTC’s global DRAM/NAND shares remain below China’s share of demand. As long as domestic demand, supply security, and the pricing cycle coexist, continued capacity expansion by memory makers remains logical. Memory is not simply a domestic-substitution theme; it is also tied to AI servers, enterprise SSDs, the HBM ecosystem, and the capex cycle of domestic cloud vendors.
Memory is especially important for Naura because it may address the market’s previous concern over “insufficient memory-customer exposure.” HSBC believes Naura’s share price lagged peers over the past two months partly because the market viewed its revenue exposure to memory customers as lower than AMEC and Piotech. If orders from memory customers grow by more than 50% in 2026, that discount will be reassessed.
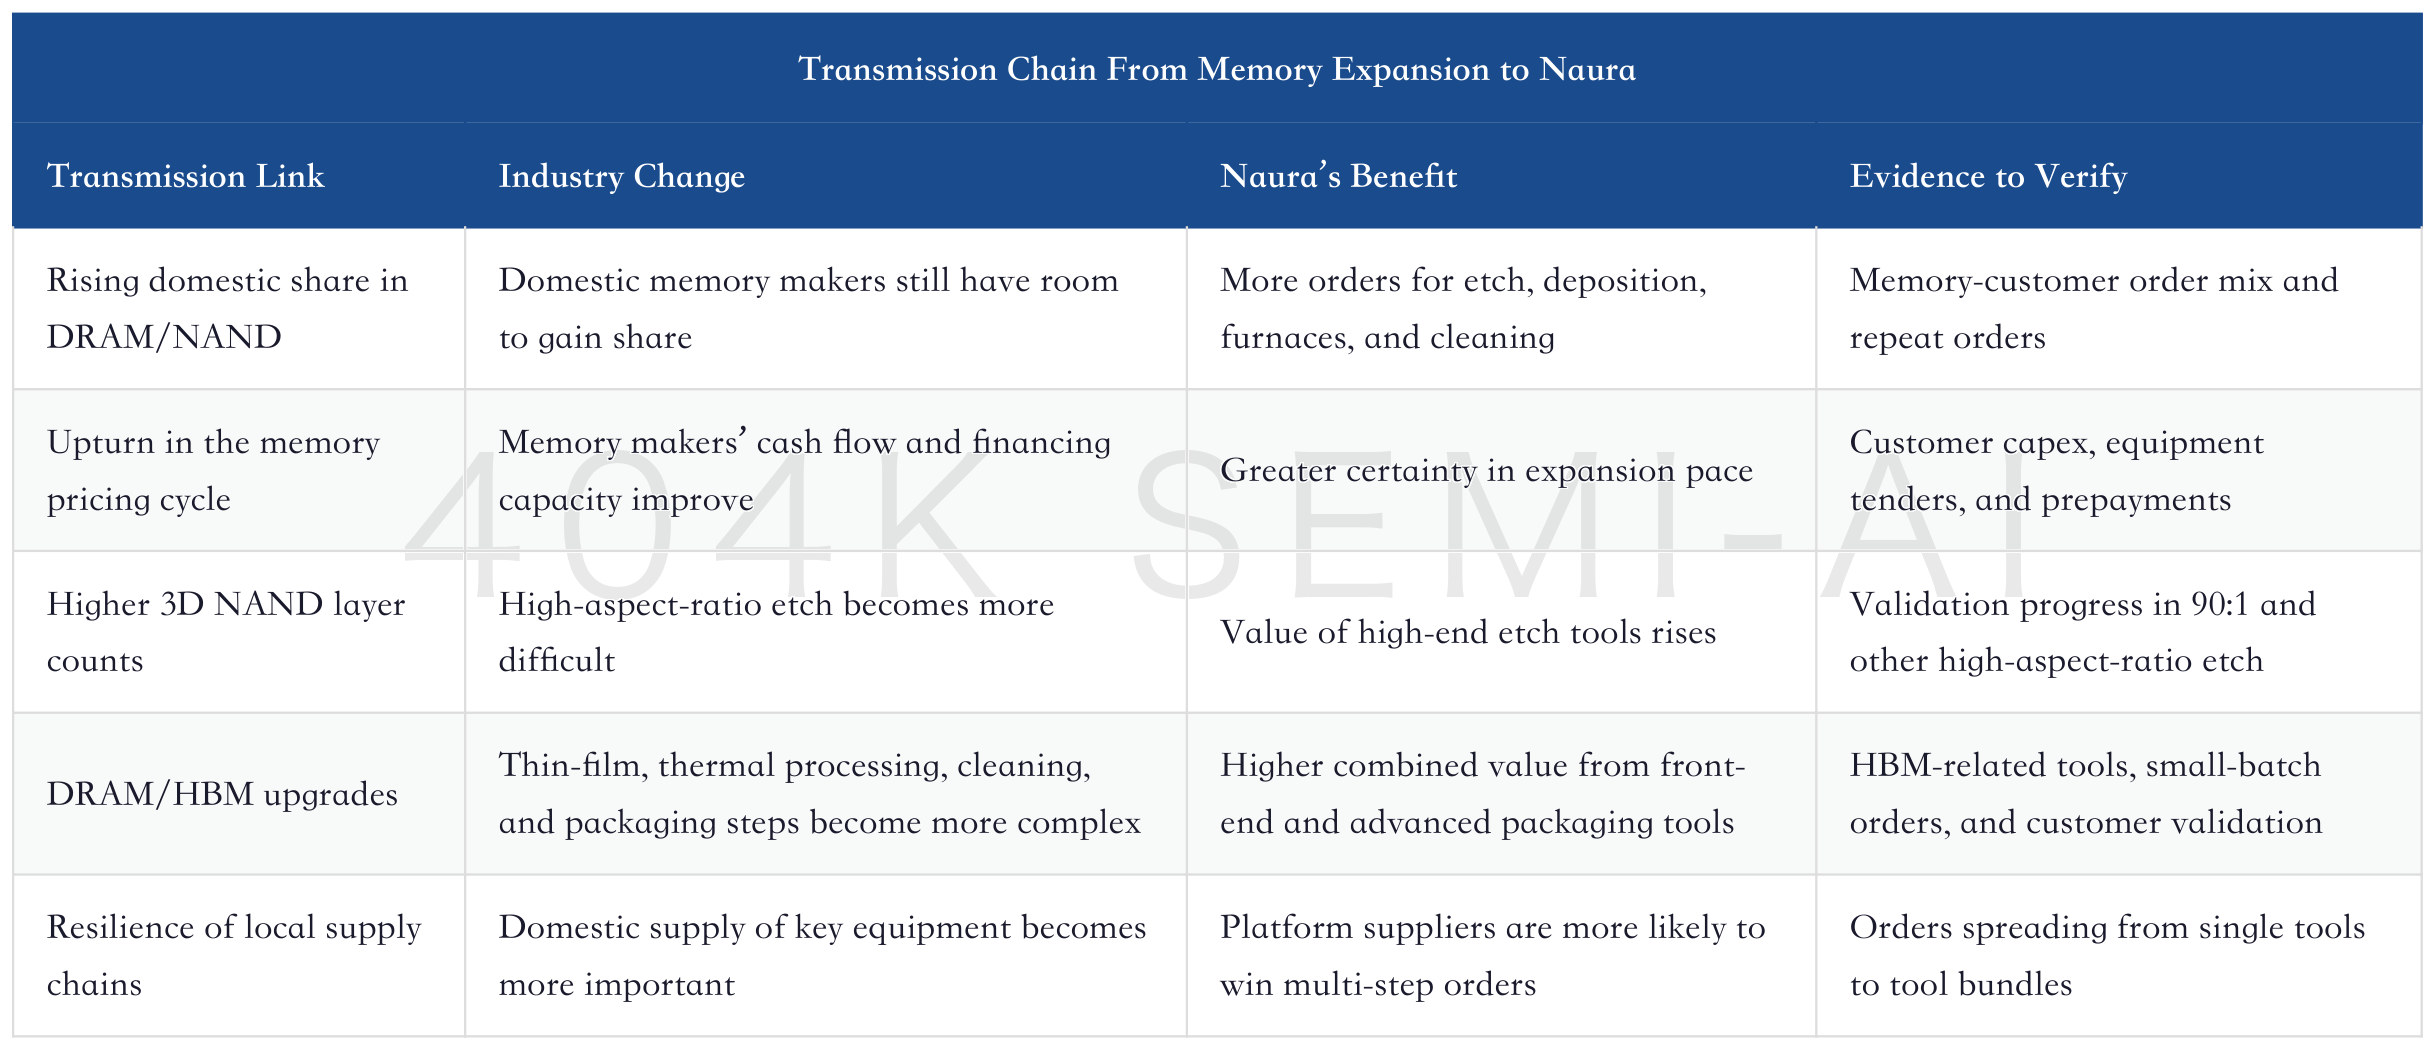
The most important part of this transmission chain is repeat orders. It is not difficult for equipment vendors to secure prototype validation; the hard part is customer repurchases and replication across production lines. If Naura can only win a small number of validation orders from memory customers, revenue elasticity will be limited. If it can extend from etch and deposition into a multi-step equipment portfolio, memory customers will become an important source of revenue upgrades in 2027.
This is also why order growth matters more than current-period profit. The cycle from equipment order to revenue recognition is often long. If memory-customer expansion generates orders in 2026, more of the revenue will be reflected in 2027. The market is willing to assign a PS valuation in advance because it trades orders first, then waits for revenue and earnings validation. Conversely, if 2026 orders do not grow by more than 50%, the PS valuation will lack its first building block.
IV. Logic Expansion Remains the Base: Advanced Logic Determines the Quality of a Platform Supplier
Memory is the marginal variable, while advanced logic remains the base. HSBC notes that China’s plan to expand advanced capacity before 2030, as well as changes in Dutch lithography-tool import value and ASP in 2025, both point to continued growth in advanced fab capex. Lithography tools are a leading indicator for line construction. Once customers buy more expensive and more advanced lithography equipment, supporting tools such as etch, deposition, cleaning, thermal processing, and metrology will follow.
Naura’s value in advanced logic is not limited to any single type of equipment. Advanced logic lines involve many steps, complex tuning, and narrow yield windows, so customers care more about whether suppliers can provide multi-step delivery and field service. Etch and deposition form the chassis, while furnaces, cleaning, ion implantation, coating and developing, and advanced packaging tools increase platform completeness. The more complete the platform, the more likely customers are to hand over additional process steps to the same supplier.
This differs from ordinary mature-node expansion. Mature nodes are more prone to price competition, while advanced logic places greater emphasis on stability, delivery cycles, spare-parts service, and process coordination. If Naura can keep expanding its product categories in advanced logic, it will not merely take share from overseas equipment vendors; it will increase stickiness within customer production lines.
HSBC expects Naura’s orders from logic customers to grow by more than 30% in 2026. This is lower than the more than 50% growth expected from memory customers, but logic orders are more like the core base: continued advanced logic capex means Naura does not need to rely solely on the memory cycle and the glass substrate option for its story. Stable logic orders, elastic memory orders, and long-term upside from glass substrates together form the revenue pool behind the RMB1,031.90 target price.
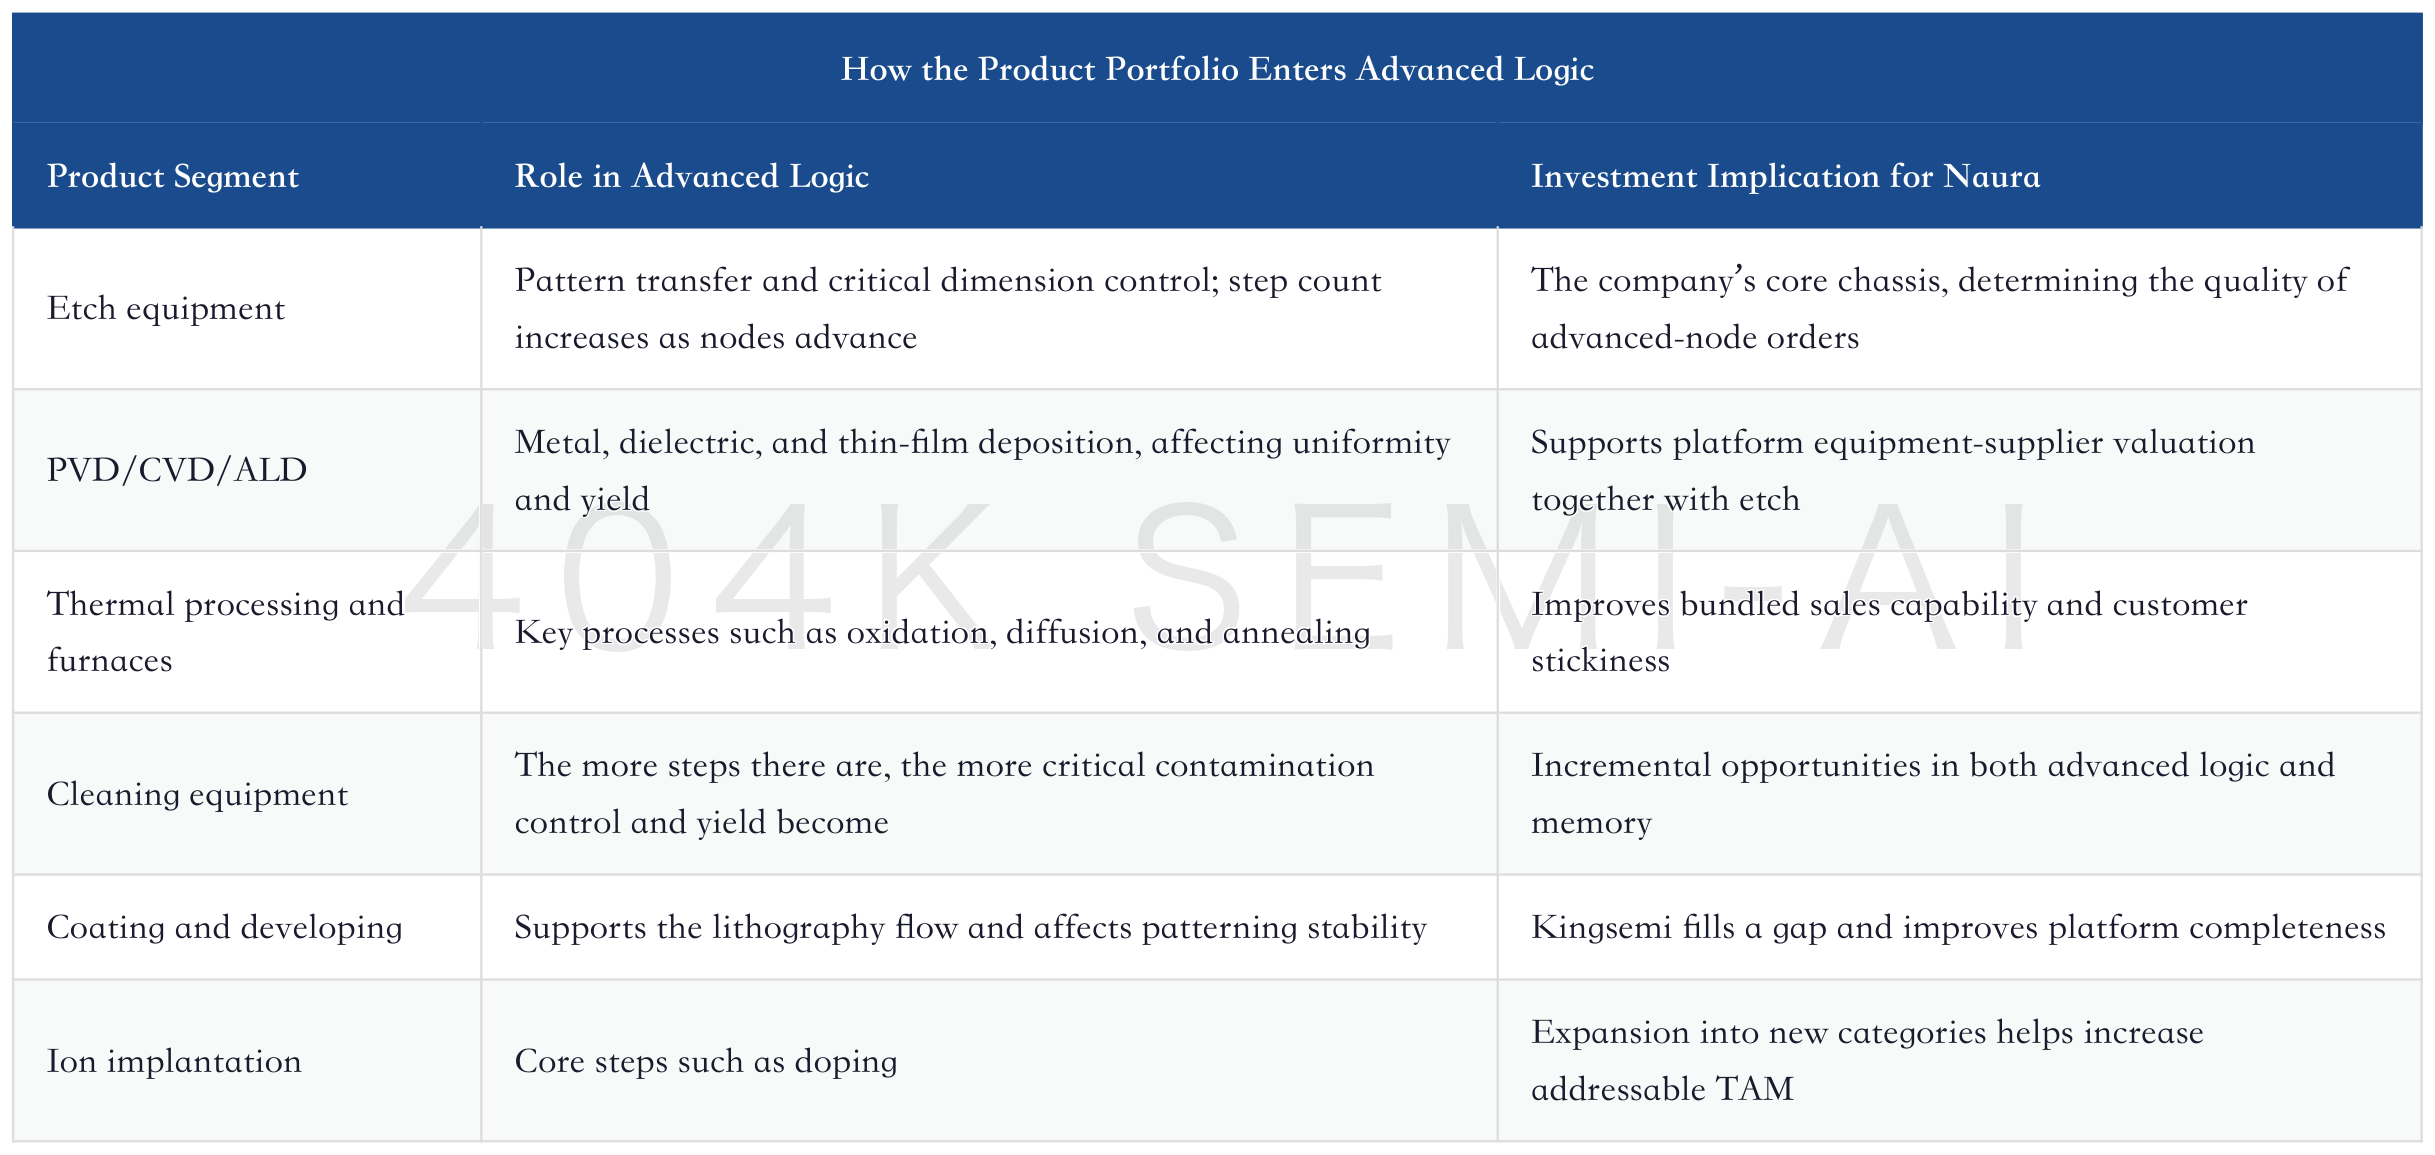
Naura’s valuation should be assessed through the “reuse rate of its product portfolio.” If customers buy etch equipment and then continue to adopt the company’s deposition, thermal processing, cleaning, and coating/developing tools, its R&D; and service costs can be spread across multiple categories. Conversely, if every new category requires separate investment, separate validation, and separate price discounts, the platform story becomes a cost story.
V. Glass Substrates: TGV/ECP Is Not Current Profit, But a Genuine New TAM
Glass substrates are the most novel part of this HSBC report. As AI chip packaging continues to evolve toward higher I/O, higher bandwidth, lower warpage, and better thermal stability, glass substrates are viewed as a direction that could replace or complement some organic substrate and interposer solutions. It is not yet a mature large market, but once the industry enters volume production, equipment and materials will benefit first.
HSBC estimates the glass substrate market will reach about US$11.3 billion by 2032, with equipment and materials accounting for about 10%. For Naura, this is not a business that can contribute several billion renminbi of revenue immediately, but rather an option on whether its equipment platform can spill over into advanced packaging substrates. The market is willing to value this option provided the company already has reusable technologies.
Naura’s reusable technologies are mainly in three areas. First is the PVD seed layer: conductive seed layers on glass substrates require PVD deposition, where the company already has a commercial foundation. Second are descum and PIQ tools, where yield sensitivity can demonstrate the company’s process understanding. Third is subsequent electroplating equipment; HSBC believes Naura can leverage its existing TSV experience to extend into TGV ECP tools.
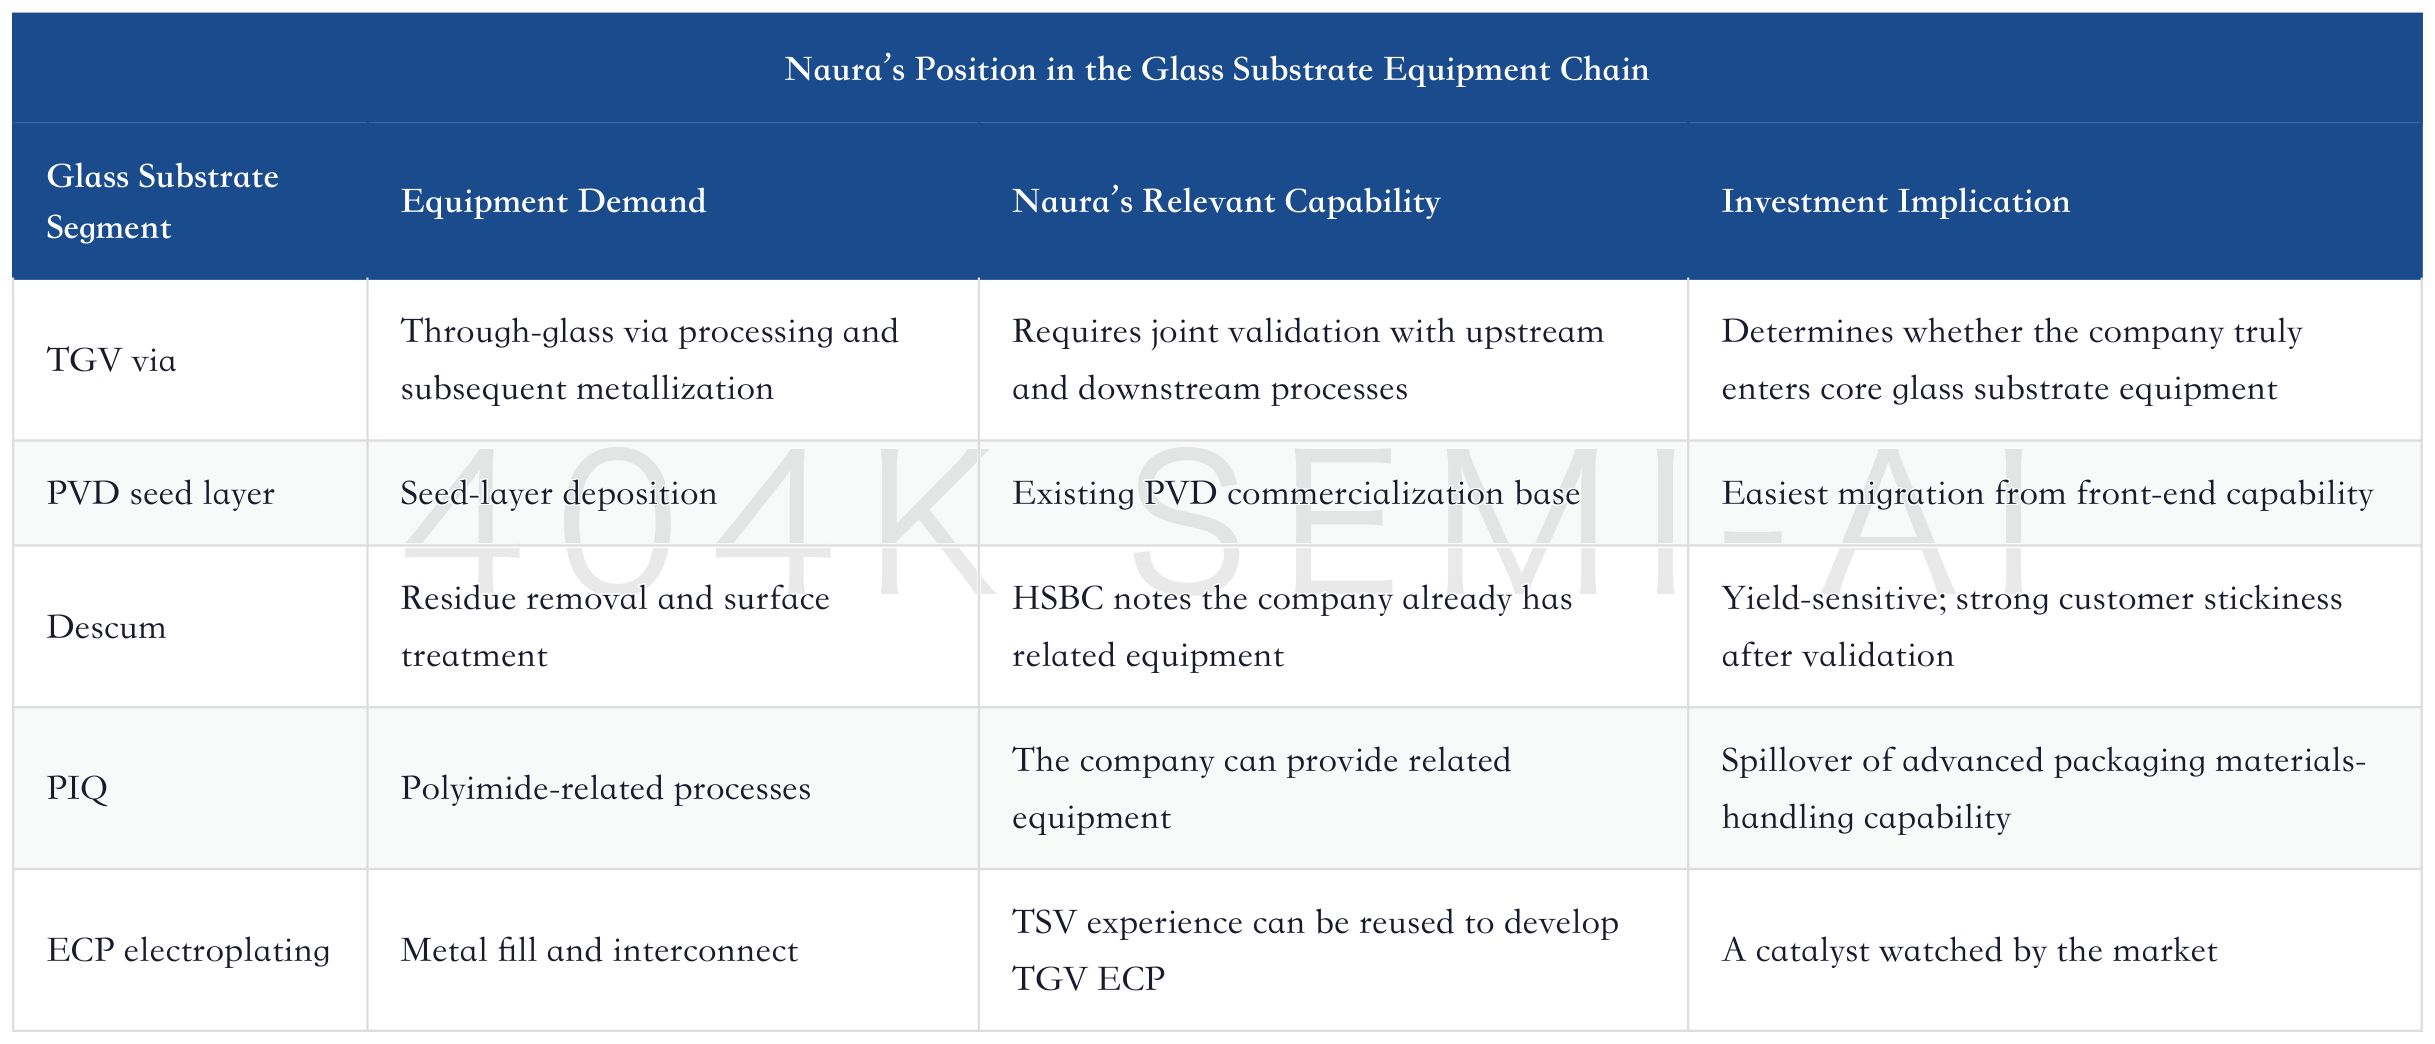
The benefit of glass substrates is that they are tied to AI packaging upgrades; the drawback is uncertain industry timing. For now, this is more like a post-2027 valuation option than a 2026 profit source. If the company releases TGV ECP equipment and enters customer validation, the market will view it as successful platform extension. If validation is slow or industry adoption is delayed, its impact on 2026-2027 profit will be limited.
This is why glass substrates should not be framed as “certain profit.” They are better understood as a counter-test of Naura’s platformization: can the company migrate its front-end PVD, TSV, electroplating, cleaning, and materials-processing experience into advanced packaging substrates? If it can, Naura’s TAM will be tied not only to fab WFE, but also to AI packaging substrate upgrades.
VI. How to Read the Target Price Upgrade: RMB1,031.90 Is Based on PS Valuation, Not a Short-Term Buy Signal
HSBC raised its target price from RMB528.40 to RMB1,031.90, a very large increase. The number is eye-catching, but it should be broken into three questions: first, why the valuation method moved from 7.5x PS to 11.7x PS; second, why 2027 revenue is used rather than 2026 profit; third, why the target price upgrade and profit downgrade appear at the same time.
The answer to the first question is improved visibility on revenue growth. HSBC expects revenue CAGR of about 27% in 2026-2028, close to the roughly 26% average revenue CAGR of global equipment peers, and therefore assigns NAURA a PS multiple closer to global peers. NAURA’s historical discount reflected market concerns over insufficient memory exposure, unstable gross margin, and high expenses. The report now argues that memory, logic, and glass substrates have widened the revenue pool.
The answer to the second question is that 2026 remains an expansion investment year. 2026 profit is suppressed by expenses, making PE look expensive. But if 2027 revenue recognition and profit improvement become clearer, PS valuation can better reflect order value than current-period PE. During an order upcycle, equipment companies are often valued on revenue first and margin later, especially when new product introduction and customer qualification have not yet fully released operating leverage.
The answer to the third question is that the valuation anchor has shifted from “near-term profit” to “long-dated platform revenue.” HSBC’s downgrade to 2026/2027 net profit acknowledges expansion costs; its target price upgrade reflects a view that the revenue platform and long-term profit elasticity are higher. This combination is not contradictory, but it also carries higher risk: if revenue fails to materialize, valuation will quickly revert to a profit-based framework.
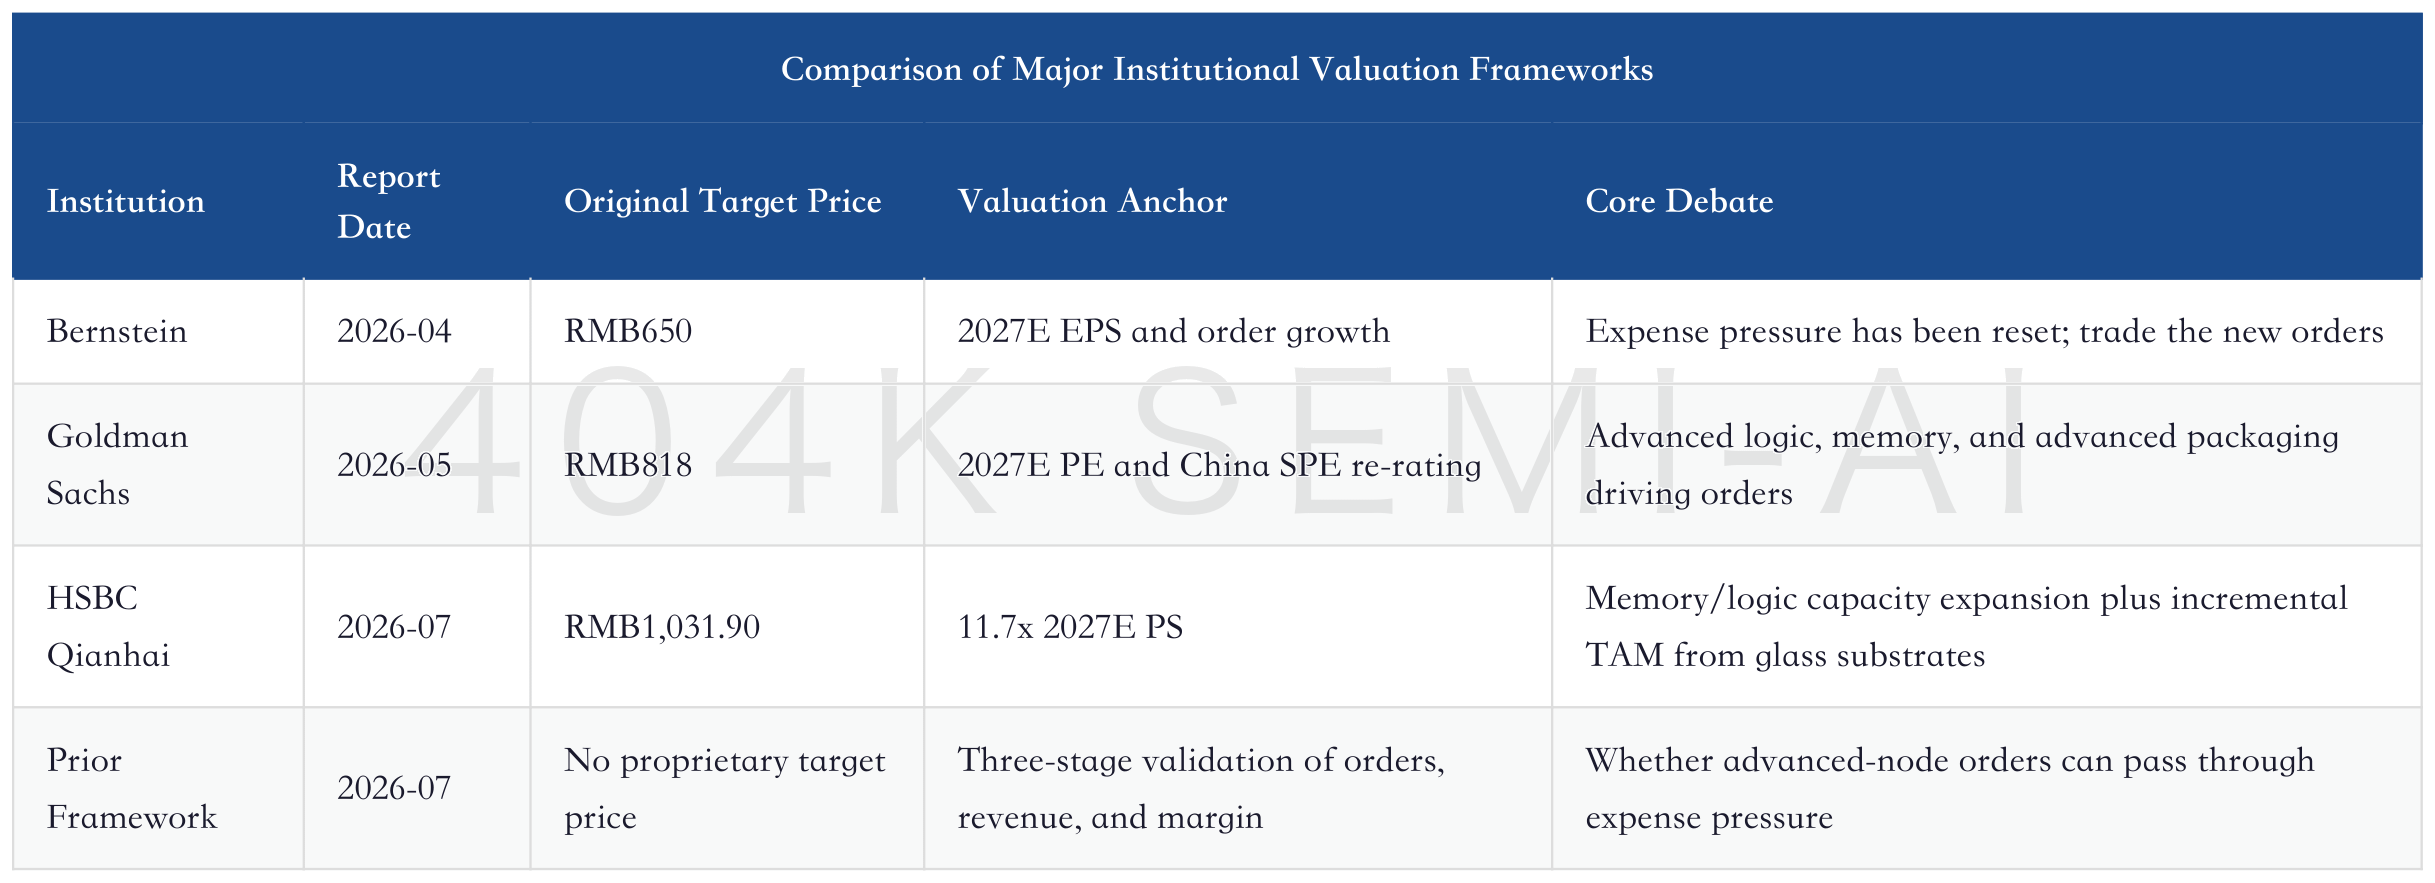
This table should not be used to rank target prices mechanically. Report dates, valuation methods, and forecast years differ, so each target price reflects a different worldview. HSBC’s worldview leans more toward “revenue platform and incremental TAM”; Bernstein emphasizes order restart; Goldman Sachs focuses more on advanced tools and China semiconductor capex. The common point is that none of them still treats NAURA as a company valued only on current-quarter earnings.
Equipment Capex Ledger Update: AI Financing, US$250 Billion WFE, and Semiconductor Equipment Repricing
VII. Core Model: Three-Stage Validation of Orders, Revenue, and Margin
NAURA is best understood through a three-stage model. The first stage is orders, which determines whether the market is willing to assign valuation first. The second stage is revenue, which determines whether forecasts can be revised up. The third stage is margin, which determines whether the valuation can hold. HSBC’s report strengthens the first and second stages, but the third still requires follow-up validation.
The order stage depends on customers and products. If memory customer orders grow by more than 50%, logic customer orders grow by more than 30%, and the orders come not only from mature nodes but also from advanced logic, advanced memory, glass substrates, and advanced packaging, the market will continue to price in revenue upgrades. The biggest risk is order growth concentrated in categories with low gross margin, high qualification cost, or intense competition.
The revenue stage depends on the recognition cycle. Equipment orders usually do not turn into revenue immediately. Delivery, installation, acceptance, and customer fab ramp all take time. 2026 orders are more likely to affect 2027 revenue, which is also why HSBC values the company on 2027 revenue. If 2026 orders are strong but 2027 revenue recognition is slow, PS valuation will come under pressure first.
The margin stage depends on operating leverage. NAURA does not lack a revenue story now; what it lacks is proof that “expense ratio can decline after revenue grows.” R&D;, SG&A;, equity incentives, and new product qualification are all necessary investments during the order introduction phase. But if the expense ratio still does not decline after revenue reaches the RMB60 billion and RMB80 billion levels, platformization will not have translated into earnings quality.
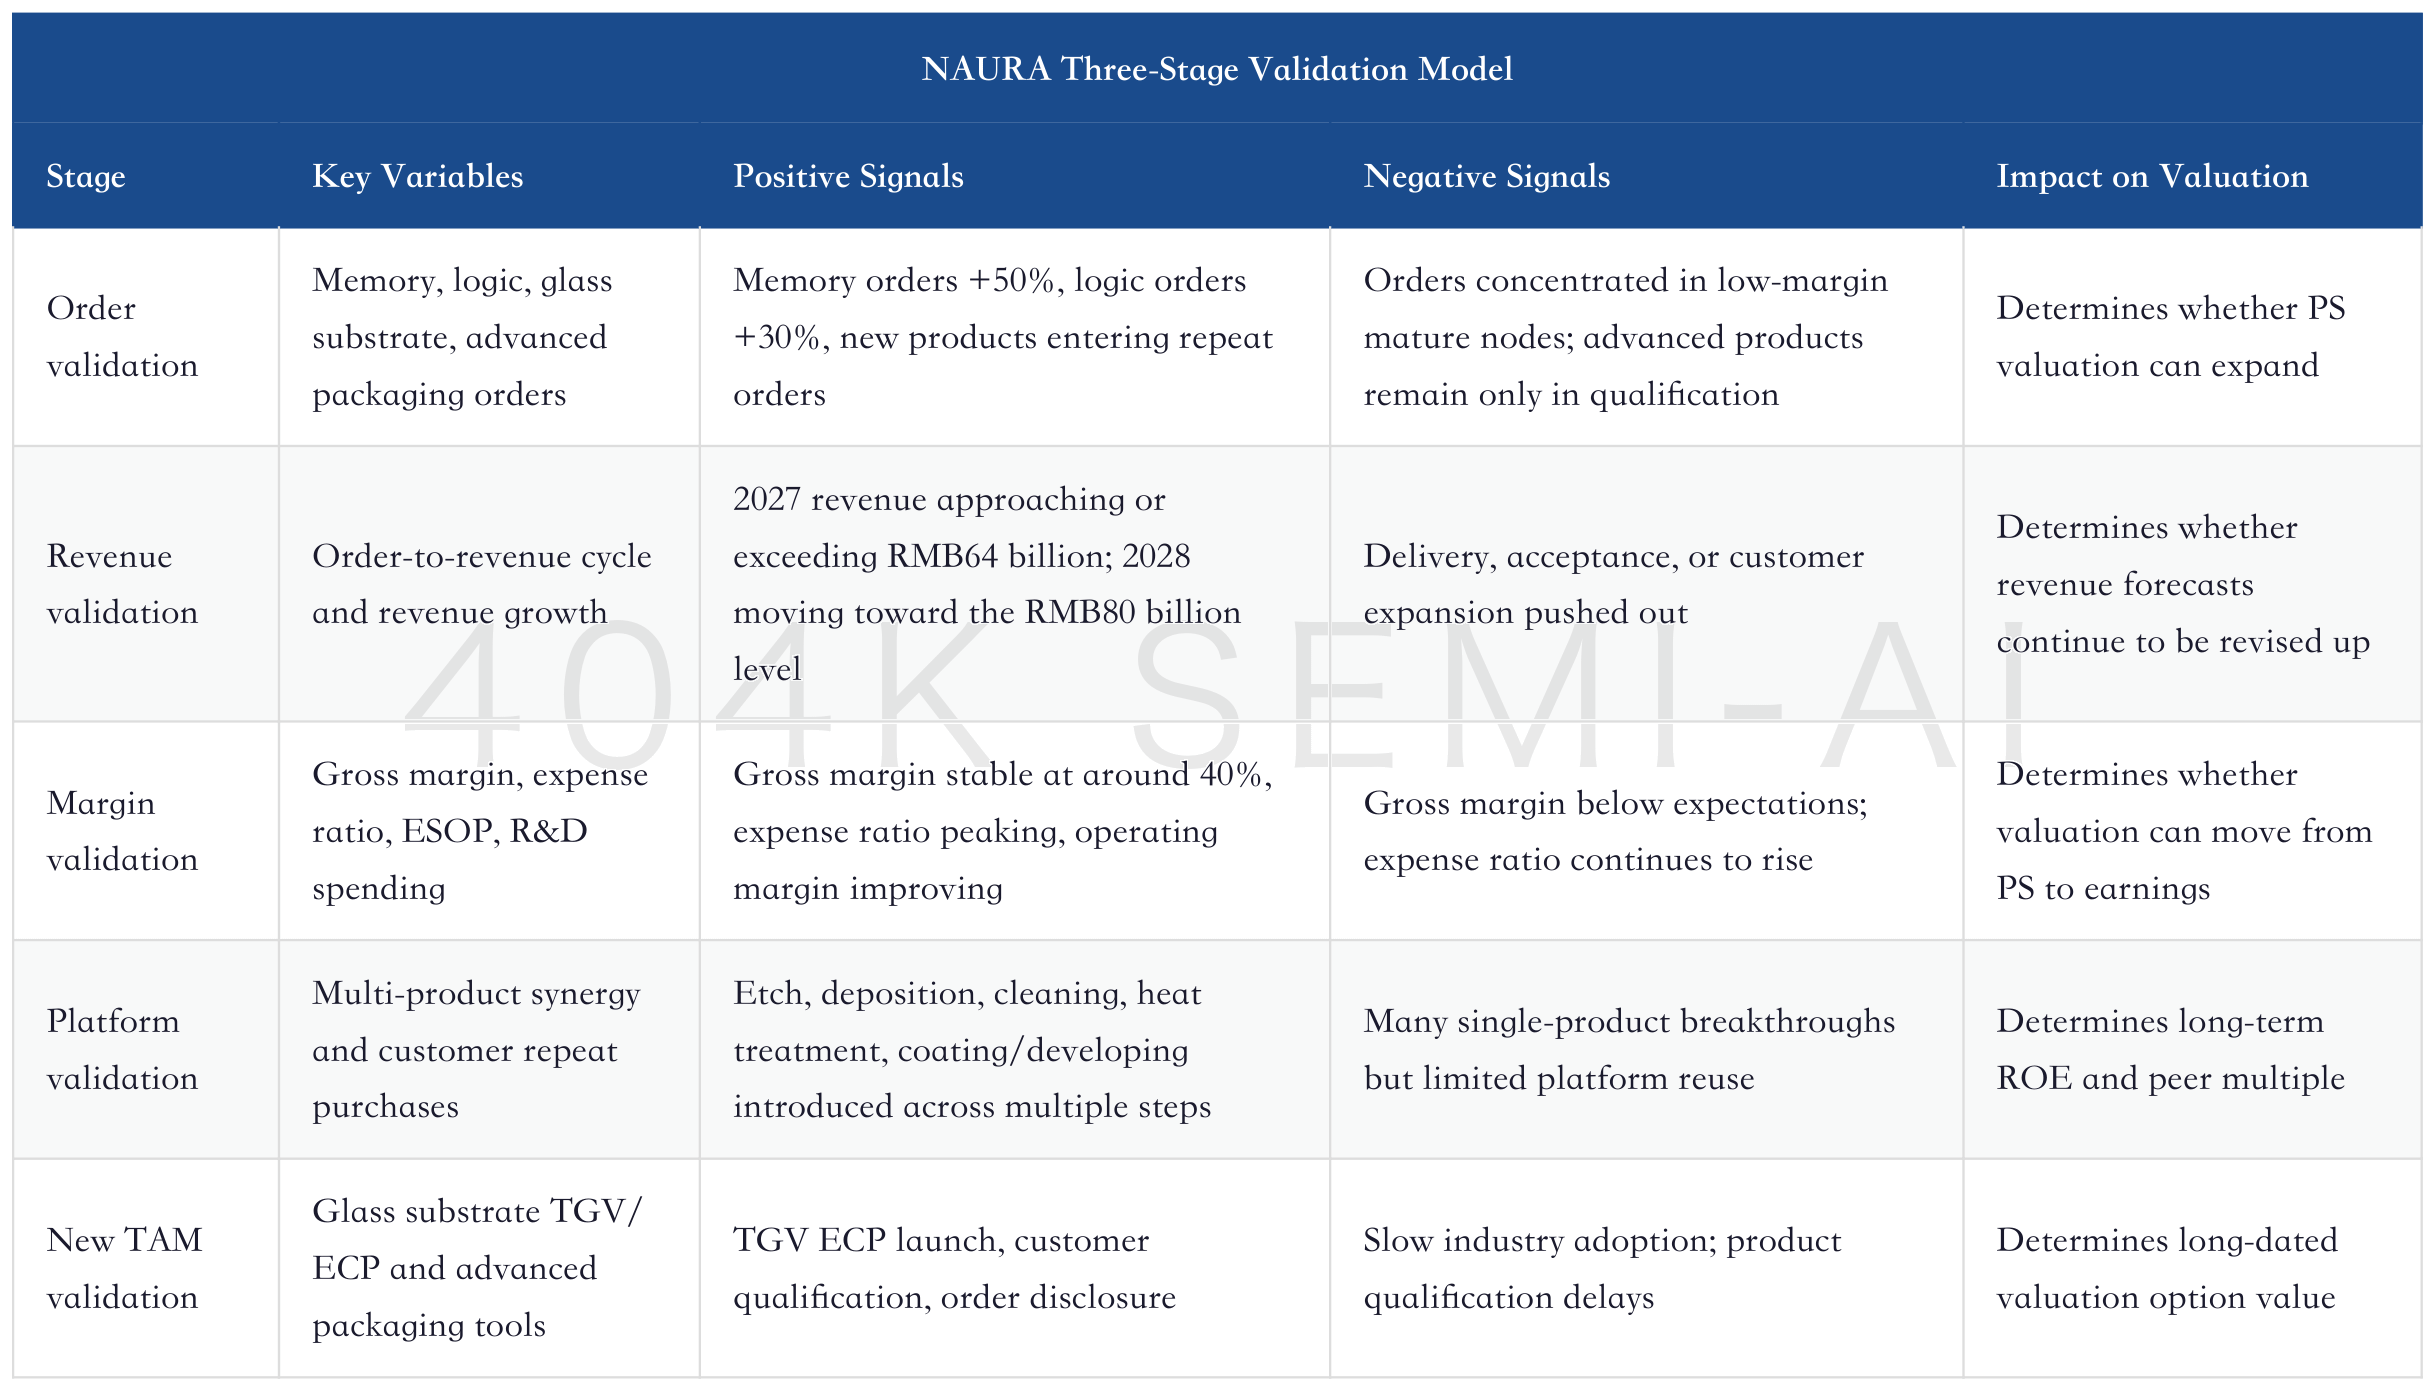
This model also explains why NAURA’s share price volatility can be high. Orders and revenue can drive valuation ahead of fundamentals, while margin determines drawdown magnitude. In each quarterly report, if revenue is good but gross margin is weak, the market will hesitate; if orders are strong but profit is weak, the market may tolerate it first; only when orders, revenue, and margin are all strong will a true main uptrend logic form.
VIII. Compared with the Prior Report: Glass Substrate Is New, Memory Is Reinforced, Expense Pressure Is Unchanged
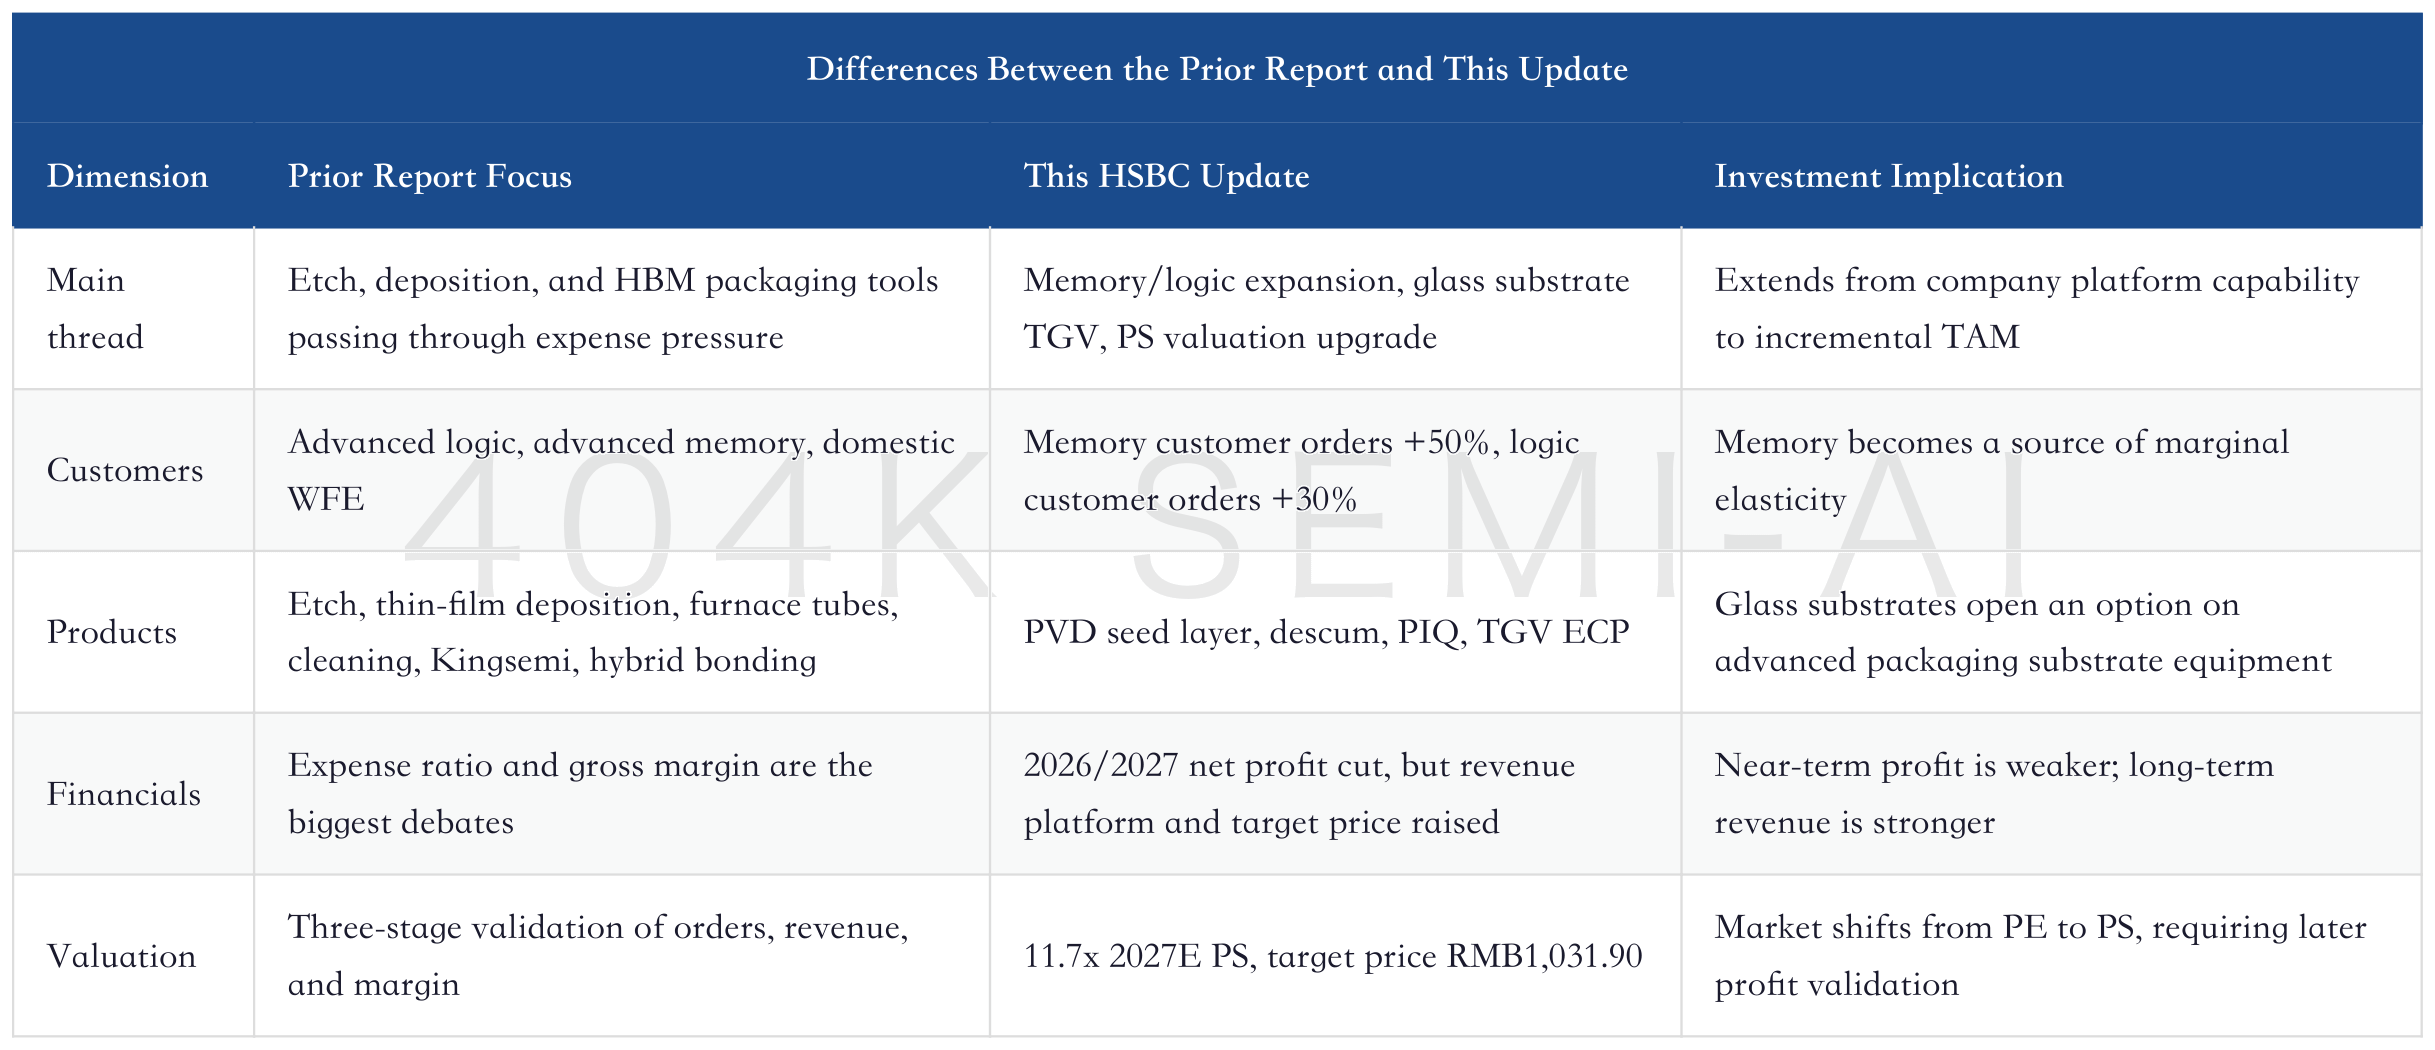
The prior report focused on “from etch and deposition to HBM packaging tools, how advanced-process orders pass through expense pressure.” That report already answered what NAURA sells, why orders are strong, why expenses pressure profit, and why 2027 is the key year. This update does not need to rewrite the company profile; it needs to answer what new evidence the latest report provides.
One new piece of evidence is stronger order elasticity from memory customers. The prior report had already discussed advanced memory and high-aspect-ratio etch for 3D NAND, but HSBC provides a more explicit order-growth assumption: memory customer orders rising by more than 50%. If this figure is validated by subsequent financial reports and order indicators, NAURA’s revenue elasticity will move closer to a “memory capex proxy,” rather than merely a “beneficiary of advanced logic expansion.”
The second new piece of evidence is glass substrate equipment. The prior report covered HBM hybrid bonding and advanced packaging tools, but did not treat glass substrate TGV/ECP as a standalone TAM. HSBC incorporates glass substrate market size, PVD seed layer, descum, PIQ, and electroplating tools into its logic, effectively adding a new curve to NAURA’s platform extension.
The unchanged issue is expense pressure. HSBC’s downgrade to 2026/2027 net profit forecasts is consistent with the prior report’s view: NAURA is not a company whose margin concerns have already disappeared. The larger its orders and TAM, the greater its R&D;, qualification, service, and staffing investment. Near-term EPS may continue to be suppressed by expenses. The market is willing to assign it a higher target price because it believes expenses will be diluted by future revenue, not because expenses have already vanished.
IX. Peer Positioning: NAURA’s Advantage Is Not Being the Strongest at One Point, but Participating in More Equipment Steps
The easiest way to misread NAURA Technology Group is to compare it as a single-equipment leader. If one looks only at etch, the high-aspect-ratio etch narrative more naturally maps to AMEC; if one looks only at thin-film deposition, Piotech has the clearer label; if one looks only at cleaning, coating/developing, or ion implantation, different specialist equipment companies come into view. NAURA’s real feature is that it has positions across multiple core front-end steps, and is extending those positions into advanced packaging and glass substrates.
This determines a valuation approach that differs from single-point equipment companies. For a single-point equipment company, the most important question is whether a given tool can win high share at key customers, in key processes, and at key nodes. For NAURA, the more important question is whether it can win a basket of equipment orders when customers expand capacity. When advanced logic or memory customers build lines, NAURA touches not one process step, but a sequence of process steps. Product breadth itself carries option value.
But product breadth also has side effects. Every new category requires R&D;, validation, process service, and after-sales systems, so near-term expense ratios are hard to keep low. NAURA’s advantage is not “low expense,” but that after multiple product lines enter the repeat-order stage, customer service, supply chain, on-site tuning, and R&D; platforms can be reused. Platform value only becomes margin after reuse occurs; before reuse, it only becomes expense.
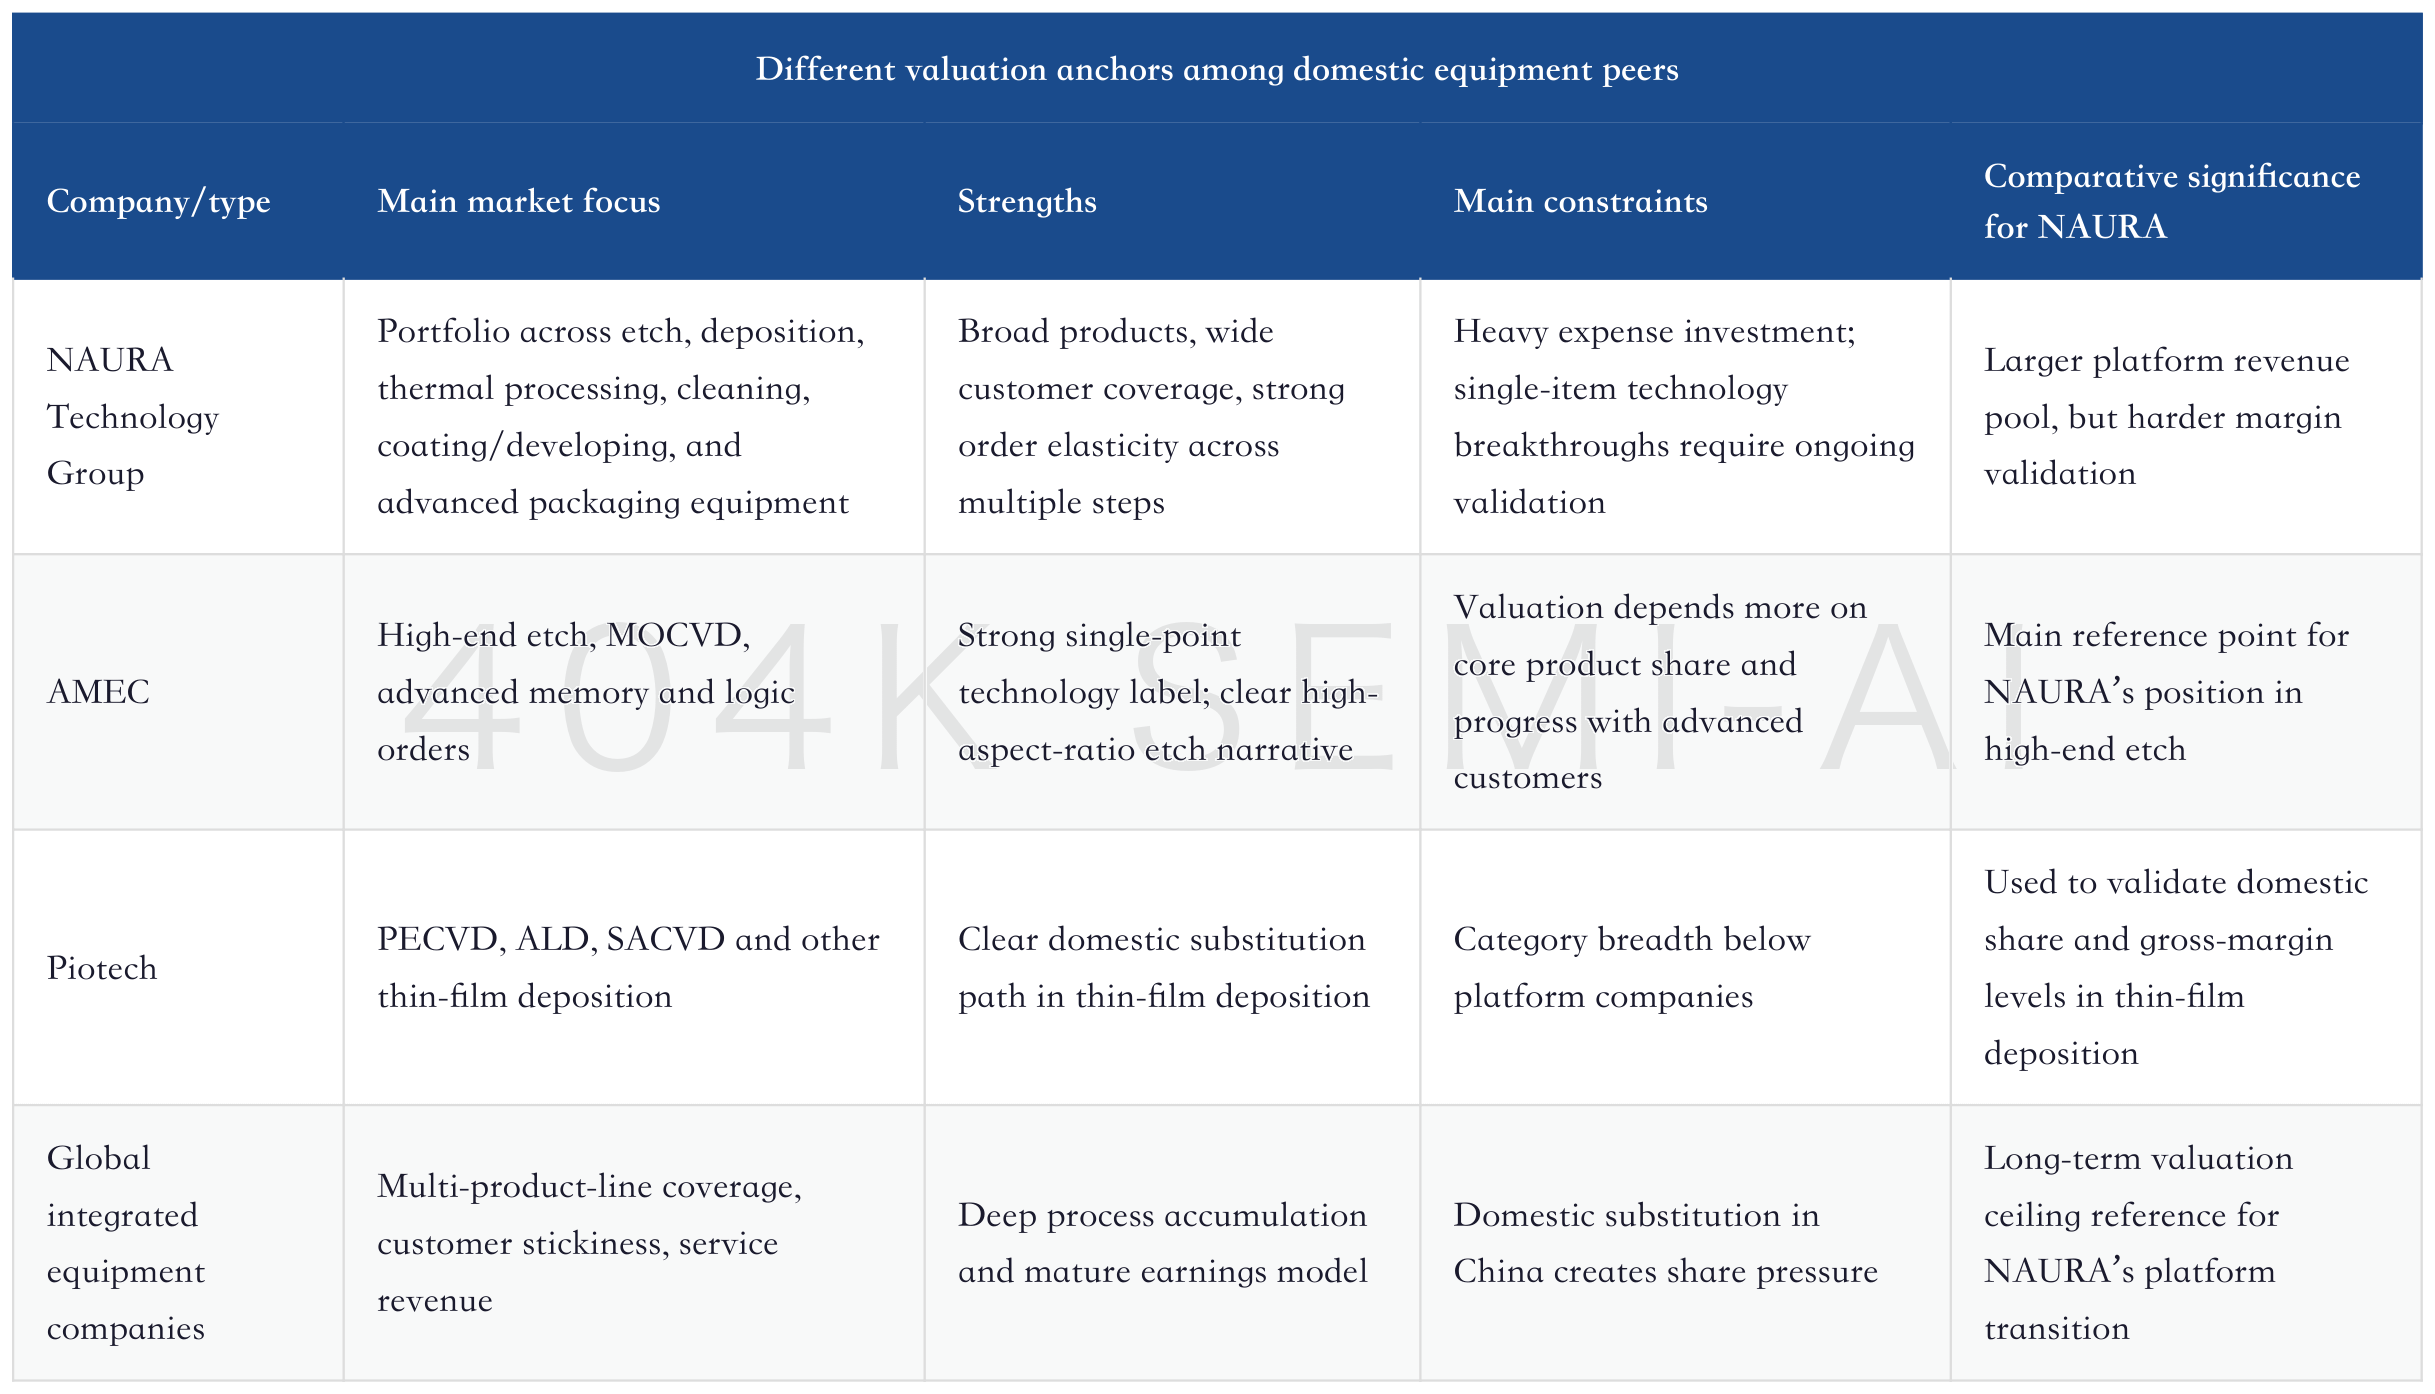
The gap between NAURA and global integrated equipment companies lies mainly not in the product catalog, but in depth of advanced-process validation, global customer coverage, and service-revenue quality. Companies such as Applied Materials, Lam Research, and Tokyo Electron have been able to sustain high valuations over the long term because their equipment, processes, services, and customer roadmaps are deeply tied together. NAURA is still moving from “equipment substitution” toward a “process platform.” The market’s PS valuation is an early trade on that migration.
From this perspective, HSBC’s comparison of NAURA’s 2026-2028 revenue growth with global equipment peers is logical. If revenue growth approaches that of global equipment leaders while product lines are still expanding, the customer mix is still improving, and domestic share is still rising, NAURA has reason to enjoy a higher growth multiple. The issue is that the earnings quality of global leaders has already been validated through many cycles, while NAURA still needs the next few quarters to prove that expense investment can be absorbed by the revenue platform.
Peer comparison also points to one risk: NAURA cannot rely on the four words “domestic equipment platform” alone for valuation. A platform company must satisfy three conditions at the same time. First, products must enter key customers’ core processes, not merely replace non-critical steps. Second, customers must place repeat orders, allowing R&D; and service investment to be amortized. Third, new categories must form sales and process synergies, rather than operating independently. If any one of these three conditions is missing, the platform valuation will be discounted.
X. Financial Bridge: After Revenue Steps Up, Margin Is the Final Pricing Variable
In HSBC’s forecast table, the item most worth turning into a financial bridge is not the target price, but the transmission from revenue to profit. Both revenue and net profit are stepping up, but net profit has higher elasticity, implying that the report assumes operating leverage will be released after 2027. The specific amounts are shown below. The key question in the text is whether this profit bridge can be jointly supported by orders, gross margin, and expense ratios.
The first section of the bridge is revenue. Revenue is projected at RMB 50.468bn in 2026, RMB 64.003bn in 2027, and RMB 81.302bn in 2028. If memory and logic orders land on schedule, the revenue step-up is not hard to understand. China’s semiconductor capex direction has moved from mature-node expansion toward parallel expansion across advanced logic, advanced memory, and advanced packaging. NAURA has product exposure in all these directions, so the upward revenue revision comes more from customer mix than from simple price increases.
The second section is operating profit. HSBC expects operating profit to rise from RMB 4.724bn in 2025 to RMB 14.102bn in 2028, with operating margin increasing from about 12.0% to about 17.3%. This is the most critical step because it means expense ratios are beginning to be diluted by revenue. If revenue grows but operating margin does not improve, the market will view the company as using higher expenses to buy higher revenue. If operating margin rises in step with revenue, platformization is truly reflected in the income statement.
The third section is net profit and ROE. HSBC expects ROE to rise from 16.1% in 2025 to 23.8% in 2028. The significance of higher ROE is not just more profit, but that the company’s invested capital is starting to generate higher returns. Equipment companies consume cash and inventory during expansion periods, while also increasing receivables and after-sales service investment. Only when ROE rises can growth quality be shown not to have been dragged down by working capital.
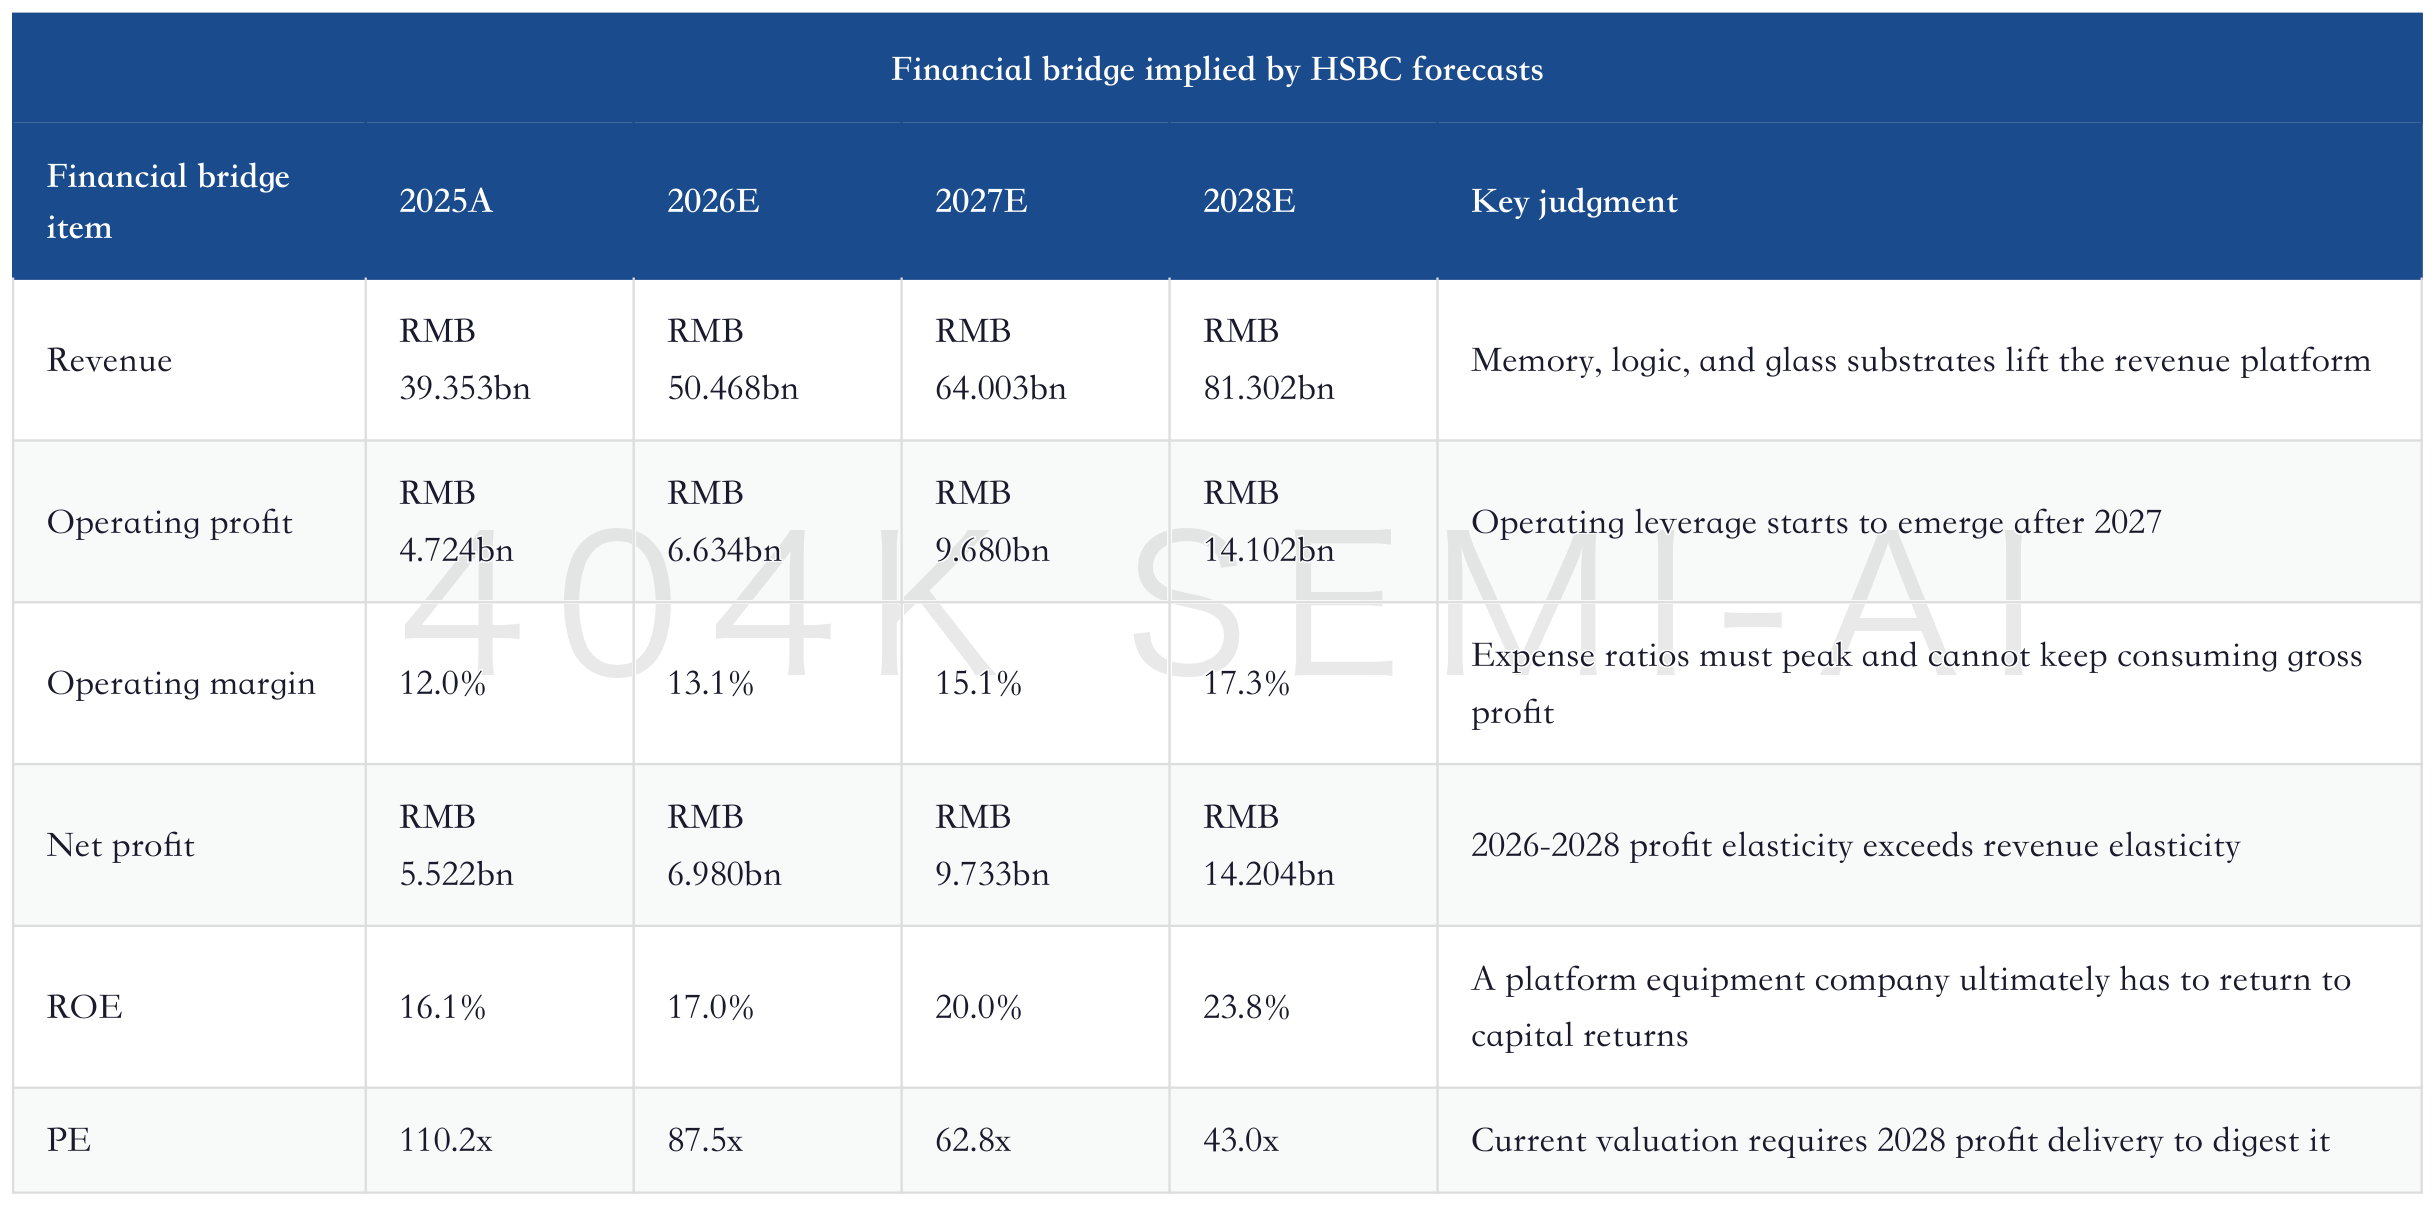
The most sensitive year here is 2027. In 2026, the market can accept expense pressure because orders are coming from memory and logic customers. In 2028, the market can see profit elasticity, but that is still too far away. 2027 is the bridge year. If revenue approaches RMB 64.0bn, operating margin approaches 15%, and ROE reaches around 20%, HSBC’s PS valuation has a basis. If 2027 revenue and margin both fall short, the RMB 1,031.90 target price will look too early.
Cash flow also needs to be tracked. For equipment companies in an expansion cycle, a common issue is that the income statement grows quickly, while inventory, receivables, prepayments, and customer acceptance cycles drag on operating cash flow. If NAURA continues to win large orders, inventory and shipped-but-unaccepted goods may rise. That is not necessarily bad, but the question is whether they ultimately convert into revenue and cash. Over the next few quarters, changes in operating cash flow and contract liabilities will explain order quality better than single-quarter net profit attributable to the parent.
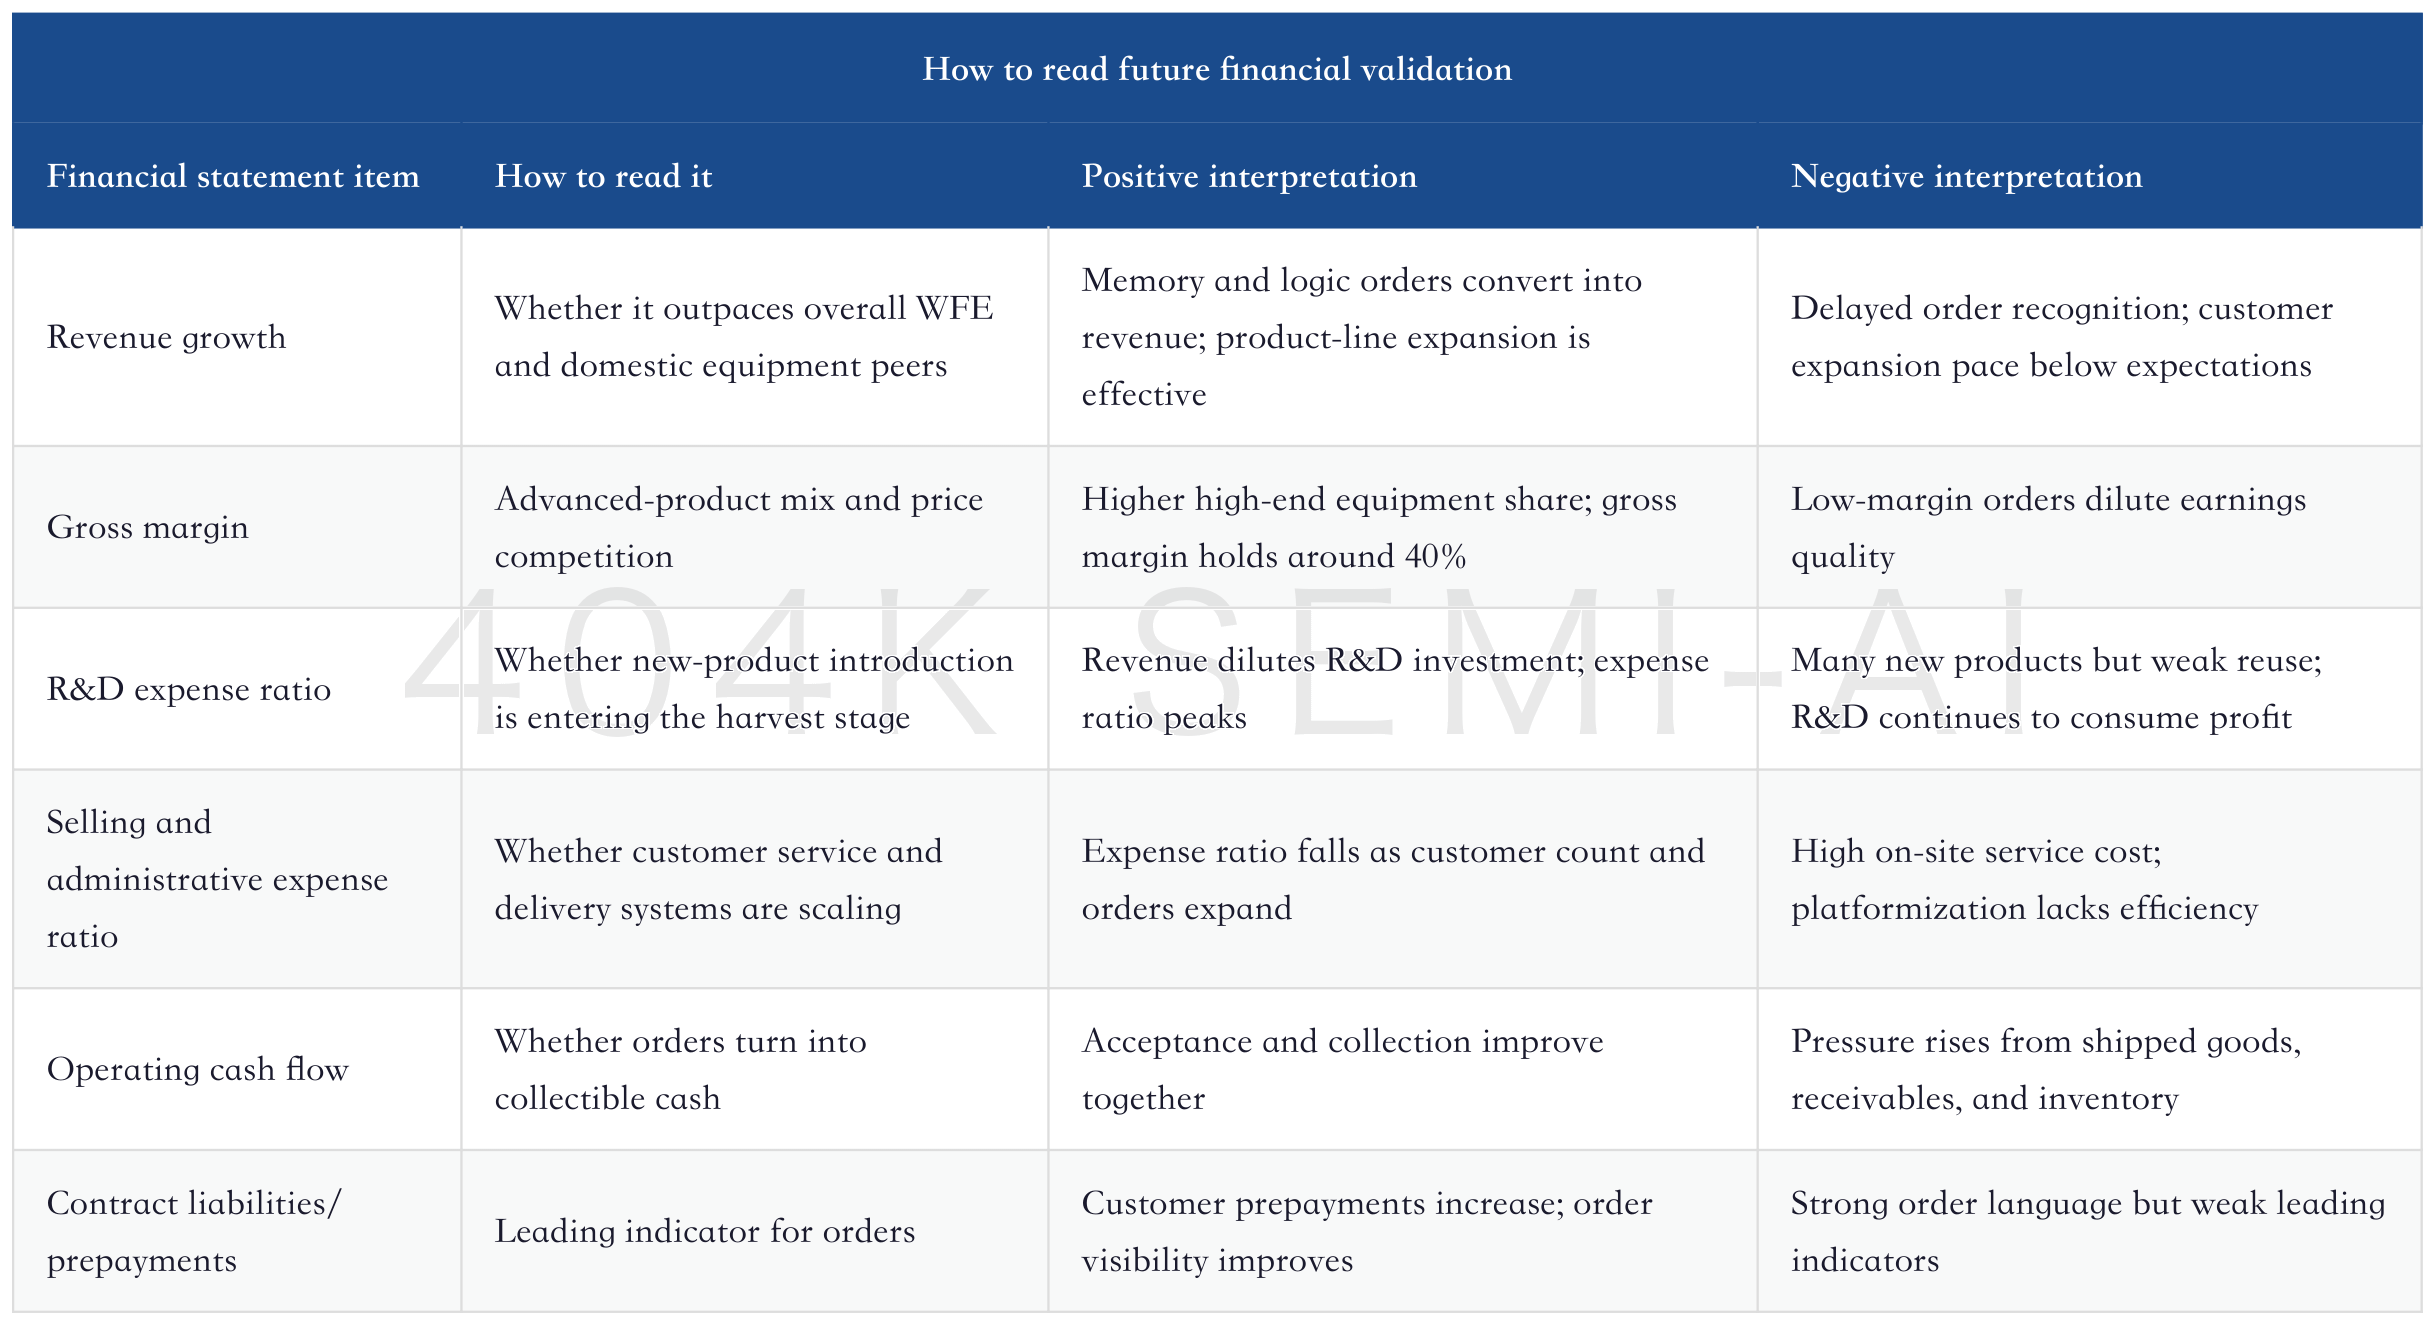
The purpose of this table is to turn subsequent earnings reports from “whether they look good” into “which section has been validated.” If a quarter has strong revenue, weak gross margin, and a high expense ratio, but strong contract liabilities and order signals, the market may continue to give the company time. If revenue is strong but cash flow deteriorates, gross margin falls, and the expense ratio does not decline, the market will suspect the company is using low-quality orders to buy growth. Research on NAURA cannot stop at the target price; it must focus on revenue quality.
11. Three Worldviews: When You Are Bullish on NAURA, Which Future Are You Actually Choosing?
The current debate around NAURA is not whether domestic substitution exists, but what kind of company it ultimately becomes. If it is only a substitute supplier for mature-node equipment, it should be valued on a lower P/E and cyclical orders. If it is a core platform for advanced logic and memory capacity expansion, it can be valued on revenue growth and long-term margins. If it can also enter glass substrates, advanced packaging substrate equipment, and the HBM ecosystem, it gains another new TAM curve.
In the conservative worldview, NAURA remains an excellent domestic equipment company, but new TAM realization is slow. Memory customer orders grow below expectations, logic capacity expansion is delayed by customer pacing and lithography constraints, and glass substrate equipment remains at the release and validation stage. Revenue still grows, but expense ratios weigh on earnings, and valuation returns to a P/E framework. In this case, the stock behaves more like a high-volatility equipment leader than a platform rerating story.
In the base-case worldview, memory and logic orders are gradually realized according to HSBC’s assumptions. Orders are strong in 2026, revenue is recognized in 2027, and margins improve in 2028. Glass substrates do not contribute much, but provide a valuation option. NAURA’s investment case shifts from a single domestic-substitution story to an equipment platform for China’s advanced production-line buildout. P/S valuation can work for a period, but every earnings report must renew that logic through revenue and margins.
In the optimistic worldview, NAURA generates repeat orders across memory, logic, and advanced packaging at the same time. Memory customers accelerate capacity expansion, advanced logic customers continue to expand, and glass substrate equipment such as TGV/ECP enters verifiable orders. The company’s revenue base moves higher, R&D; and service systems start to be reused, operating margins rise, and ROE improves. At that point, it is no longer just a Chinese equipment substitution company, but one of the most domestically leveraged integrated equipment platforms in the global WFE cycle.
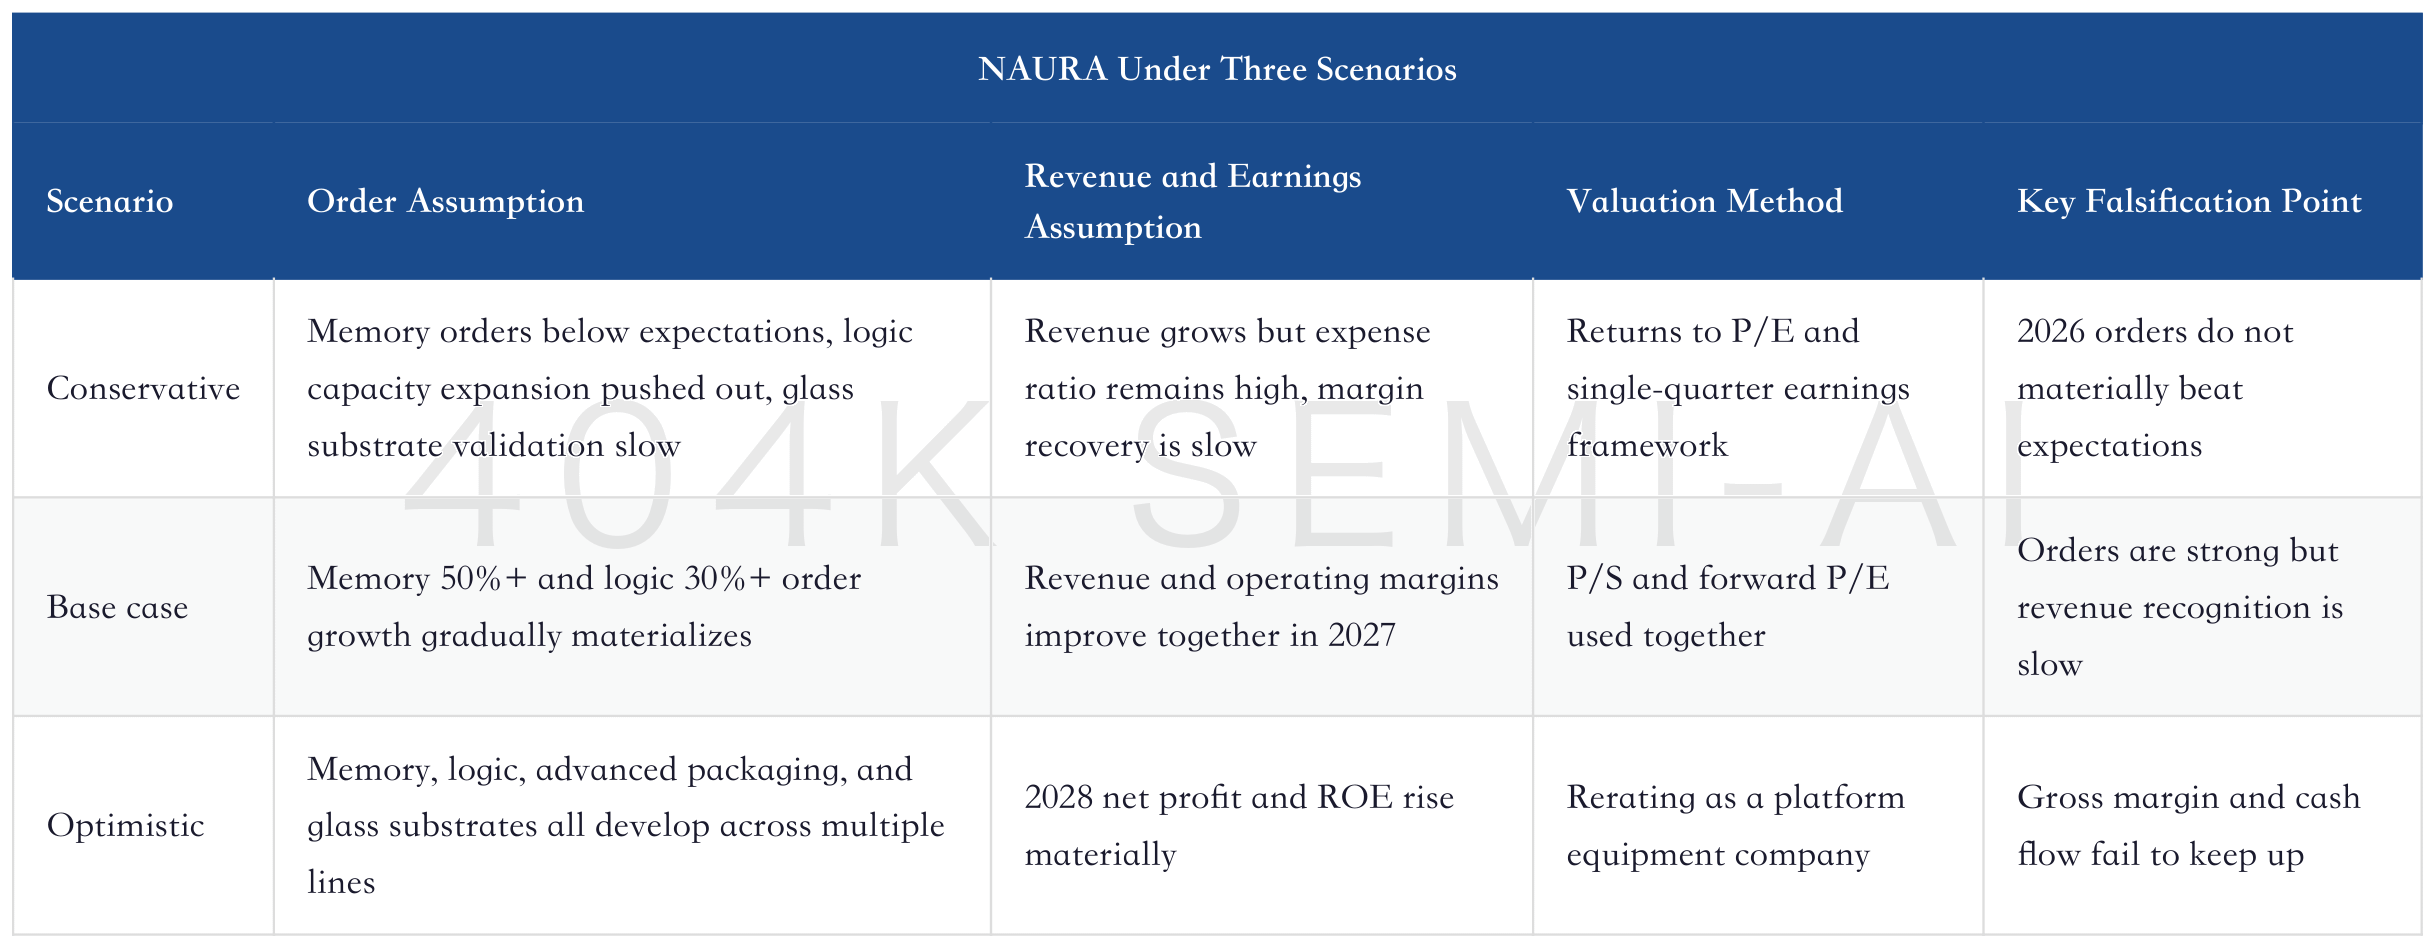
Among these three worldviews, the real bet is whether the base case can move toward the optimistic case. The conservative case does not mean the company is poor; it means the current valuation has priced in too much too early. The optimistic case is not achieved through slogans either, but through continuous verification by orders, revenue, margins, and cash flow. Investors need to avoid valuing every new TAM as certain earnings, while also not ignoring the earnings leverage that can emerge once a platform company achieves reuse.
NAURA’s relationship with AI capex also needs to be understood within this framework. AI does not place orders directly with NAURA. AI indirectly lifts equipment demand through servers, memory, HBM, advanced packaging, wafer-fab capex, and domestic supply-chain security. The closer the business is to wafer fabs and advanced packaging equipment, the shorter the transmission chain; the closer it is to the long-dated glass substrate option, the longer the transmission chain. Different businesses should receive different certainty weights in valuation.
12. Falsification Checklist: What This Report Is Most Afraid Of
NAURA’s risk is not that there is “no domestic substitution story.” The market already knows it is a platform company in China’s semiconductor equipment sector, and it also knows China’s WFE capex is resilient. The real falsification points are whether the order structure is high quality enough, whether revenue is recognized on schedule, and whether margins can return to a level the market is willing to believe for a platform equipment company.
First, if memory customer orders do not accelerate as scheduled, HSBC’s incremental logic weakens. Memory expansion is an important marginal variable behind this target-price upgrade. If CXMT and Yangtze Memory’s expansion pace, financing plans, or equipment procurement fall short of expectations, NAURA’s memory order growth of more than 50% will be difficult to realize.
Second, if logic capacity expansion is slowed by lithography, yields, or customer capex pacing, the conversion of orders into revenue will be delayed. However broad NAURA’s product portfolio is, it still has to follow customer fab construction. Advanced logic is not simply a matter of buying equipment and entering mass production. It is jointly affected by lithography tools, process integration, yield ramp, and downstream demand.
Third, if industry adoption of glass substrates is slow, the market will discount the TGV/ECP option. This direction is inherently a long-dated TAM and should not receive an overly high certainty weight. If TGV/ECP equipment release, customer validation, and order progress are slower than expected, it will remain more of a narrative and will not contribute earnings.
Fourth, if the expense ratio continues to rise, P/S valuation will be pulled back to reality by margins. HSBC has already lowered 2026/2027 EPS. The market can accept one expense reset, but not repeated resets. If R&D; and SG&A; expense ratios cannot decline after revenue moves to the next level, platformization cannot translate into ROE.
Fifth, if gross margin falls below 40% and cannot recover for a long time, the market will question order quality. High growth in equipment orders is not necessarily good. Low-gross-margin orders, heavily discounted orders, and orders with high validation costs may bring revenue without earnings. NAURA must prove that its advanced product mix can support gross margin, rather than exchanging price for share.
13. How to Track the Next Four Quarters: Orders First, Then Revenue Recognition, Finally Earnings Quality
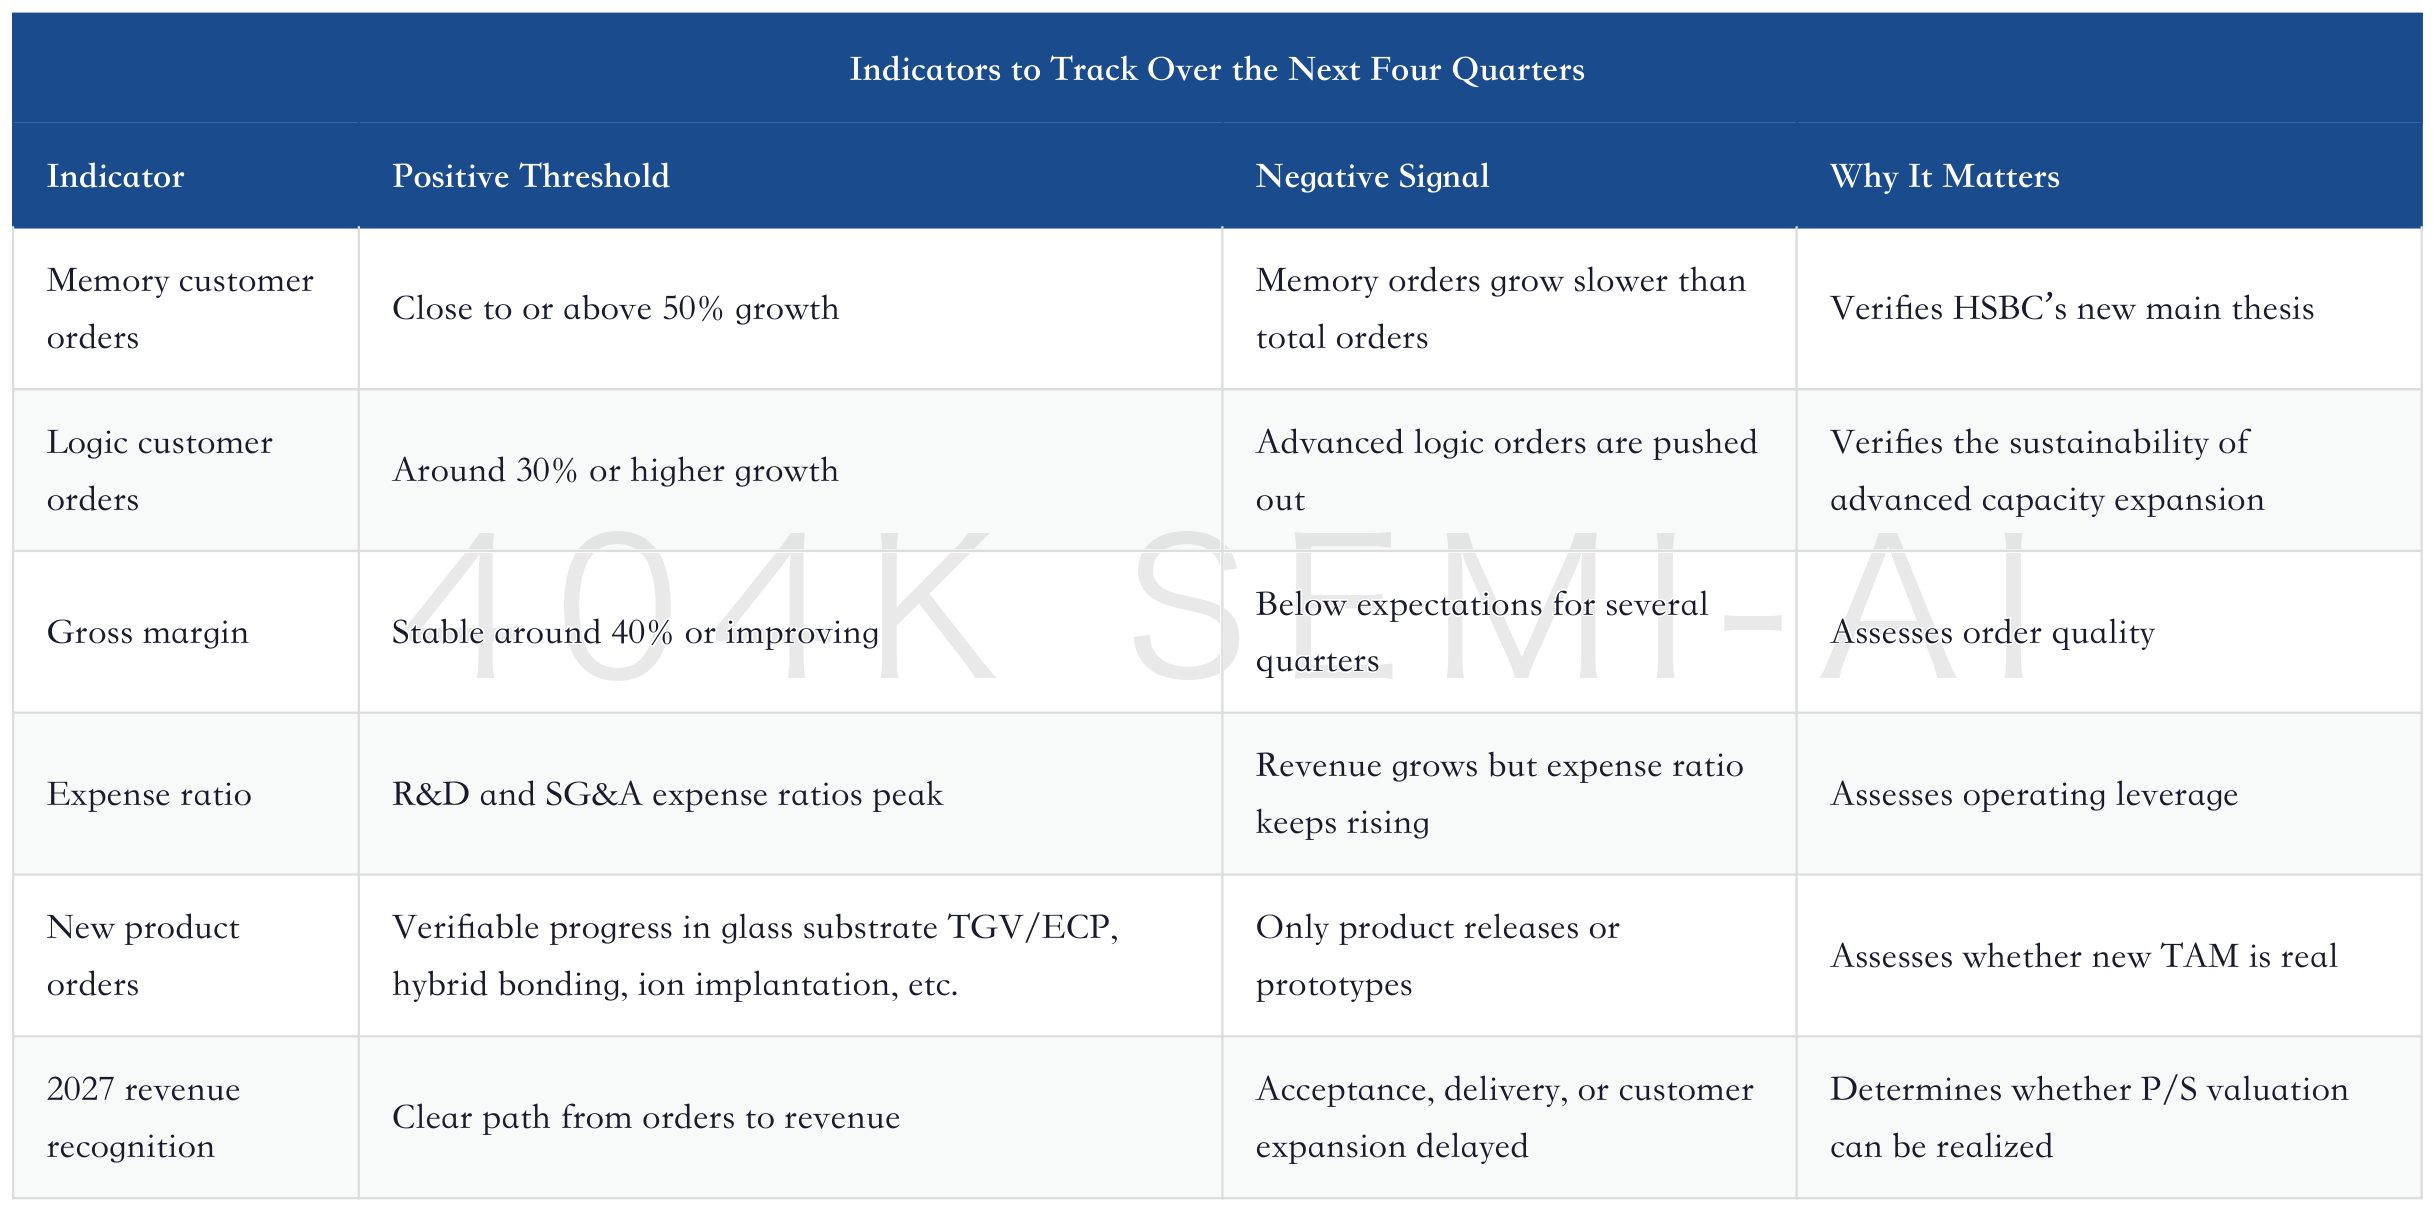
The next phase of tracking NAURA cannot focus only on single-quarter net profit growth. Single-quarter net profit is easily distorted by expenses, share-based compensation, government subsidies, product acceptance timing, and customer delivery schedules. A more effective sequence is to look first at orders and customers, then revenue recognition, then gross margin and expense ratios, and finally cash flow. This sequence matches the operating cycle of equipment companies and is also consistent with HSBC’s use of P/S valuation this time.
In the first quarter, the priority is whether there are independent clues for memory and logic orders. HSBC’s 50%+ memory customer order growth and 30%+ logic customer order growth are the most important testable assumptions in this report. If company announcements, meeting notes, tender clues, customer capex, or contract liabilities confirm that orders continue to rise, the market will continue to tolerate margin pressure. If order clues are not strong, revenue and earnings forecasts will lack a premise.
In the second quarter, the focus should be whether orders convert into revenue recognition. From signing to revenue recognition, equipment orders require shipment, installation, commissioning, and acceptance. Advanced products and new customers have even longer cycles. If 2026 orders are strong but revenue recognition is slow, that does not necessarily falsify the company in the short term, but it will affect market confidence in the 2027 revenue forecast of RMB64 billion. The smoother the recognition, the easier it is to sustain P/S valuation; the slower the recognition, the more the market will return to current P/E.
In the third quarter, the key is whether gross margin and expense ratio improve in the same direction. If NAURA can keep gross margin around 40% while R&D; and SG&A; expense ratios peak, it indicates that platform reuse is starting to appear. If revenue growth comes with declining gross margin and no decline in expense ratios, growth may depend on low-gross-margin orders, new-product introduction costs, or customer service costs, and platform value has not yet entered the income statement.
In the fourth quarter, the question is whether advanced packaging and glass substrates move from narrative to orders. Terms such as TGV/ECP, PVD seed layer, descum, and PIQ only become valuation contributors when they appear in customer validation, repeat orders, equipment delivery, and revenue recognition. If they remain only at the product-release or technology-reserve stage, they offer limited help to 2026-2027 valuation. If verifiable orders emerge, NAURA’s TAM will be revised upward again.
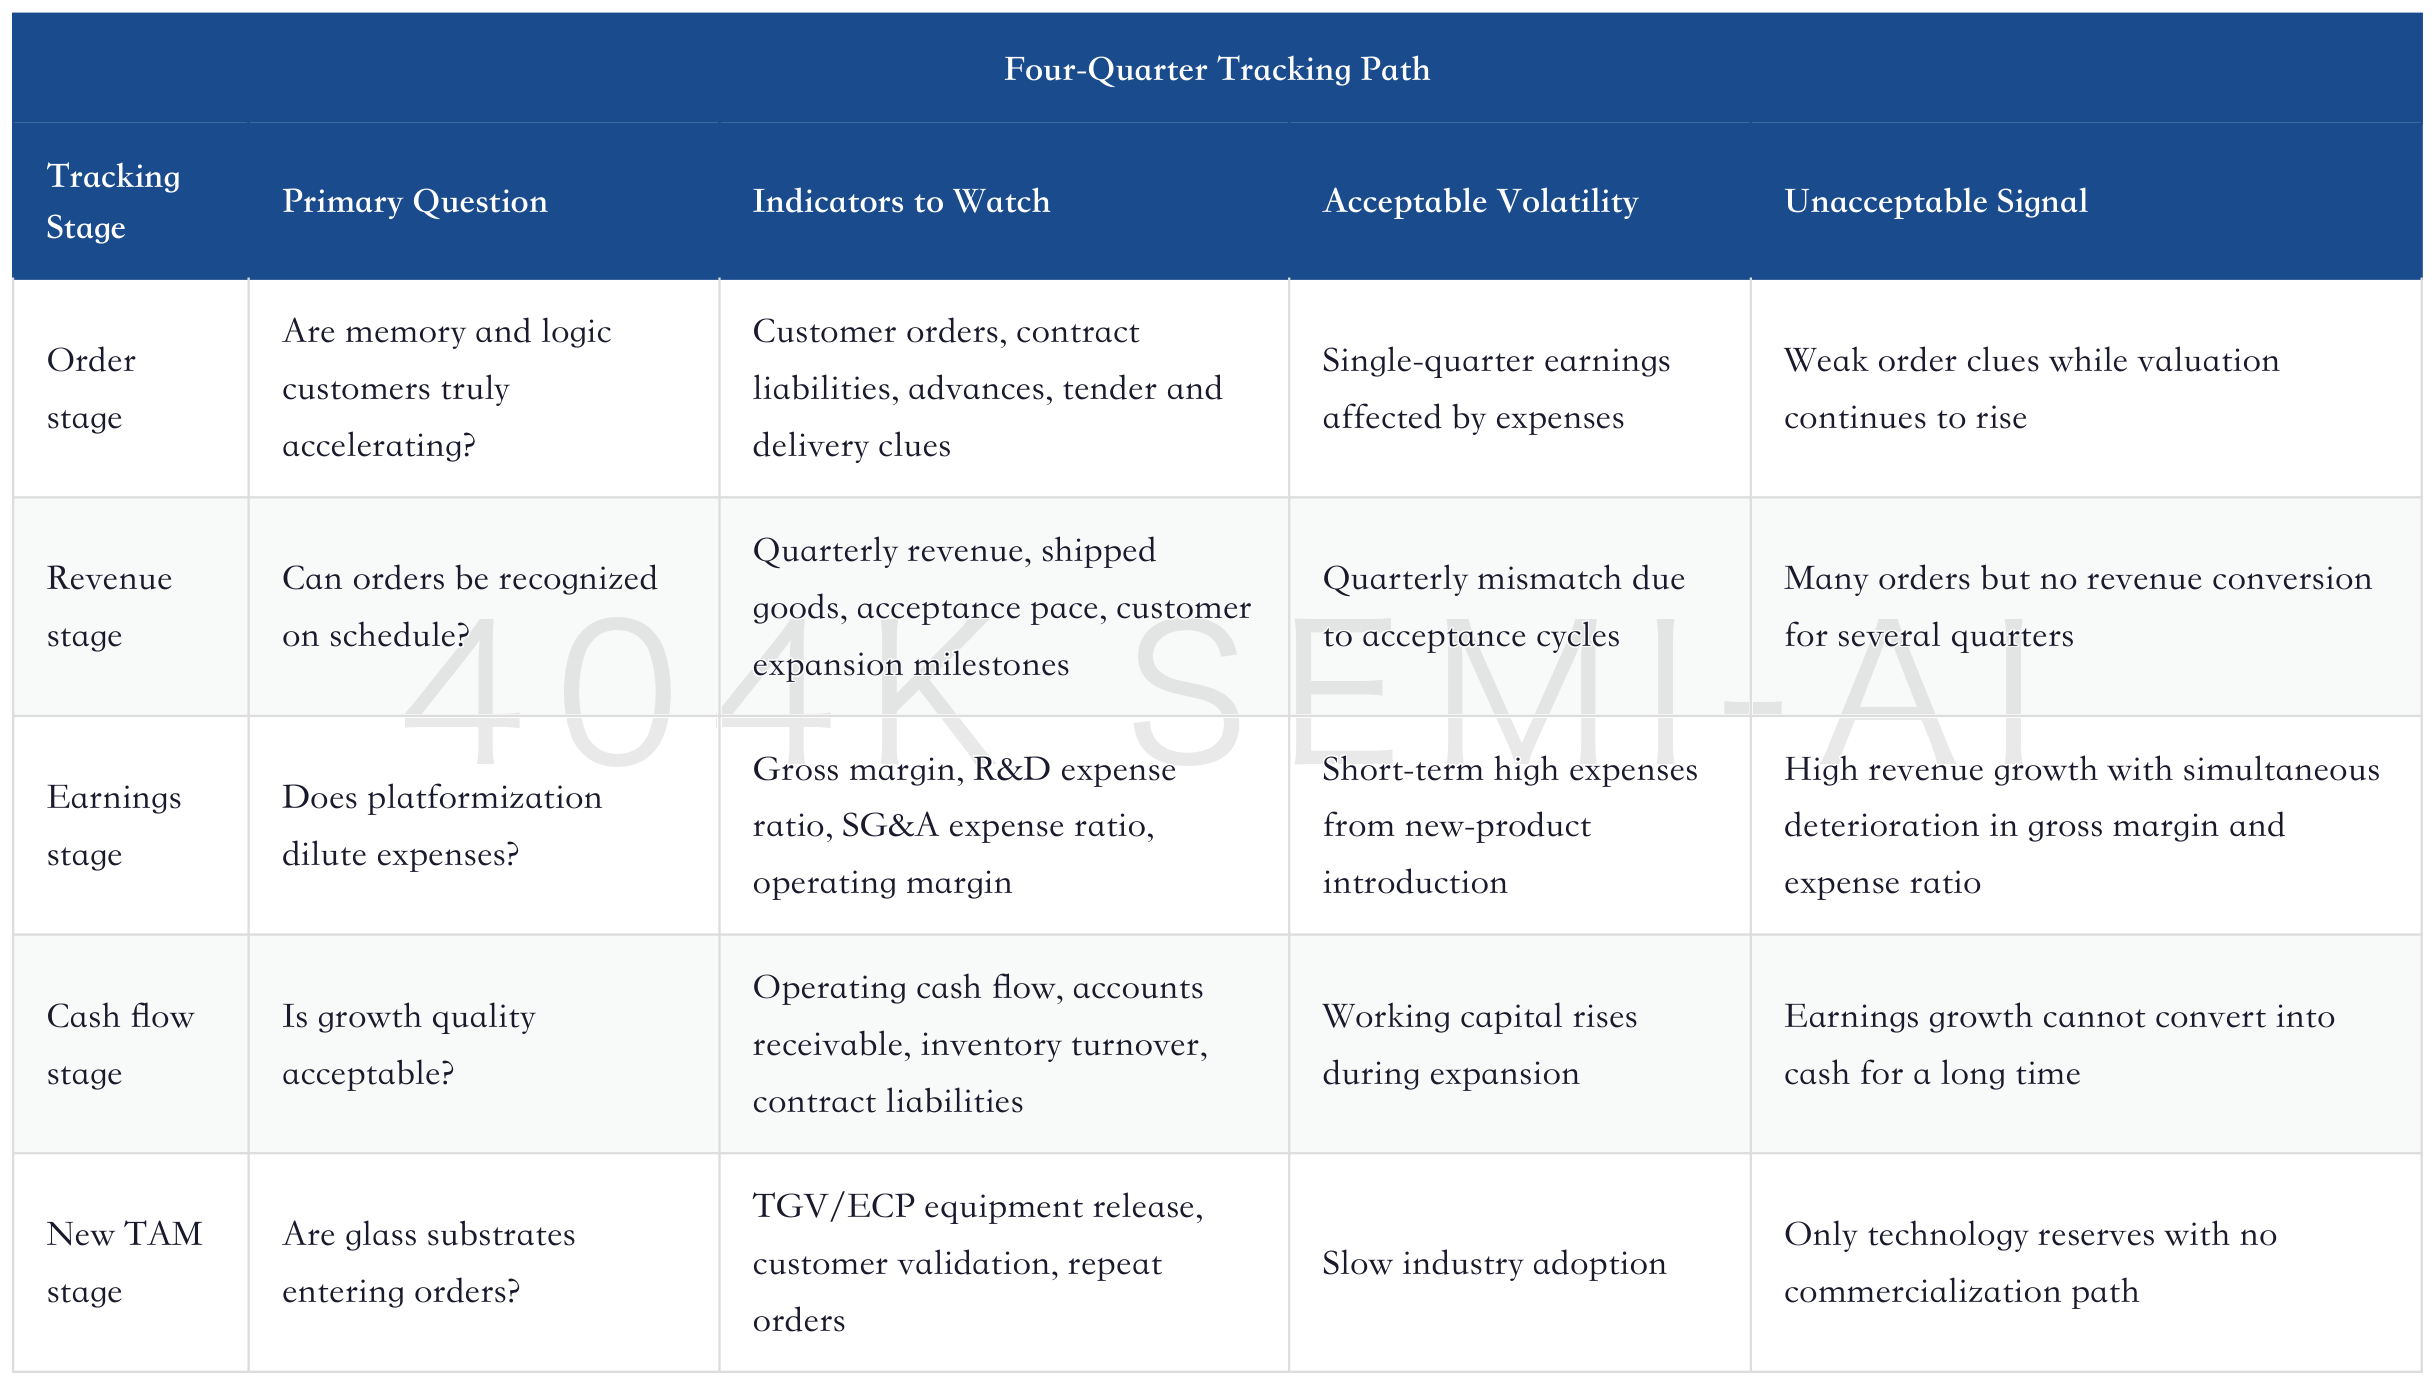
This tracking path can avoid two common misjudgments. The first is fully rejecting the company just because near-term margins are weak. During the introduction of new equipment categories, equipment companies may invest first and harvest later; single-quarter margins are not the only answer. The second is ignoring earnings quality just because order clues are strong. Orders ultimately need to convert into revenue, gross profit, cash flow, and ROE; otherwise they represent only scale growth, not platform rerating.
For NAURA, the best earnings combination is not “the highest single-quarter net profit,” but “strong order clues, stable revenue recognition, gross margin not breaking down, expense ratios peaking, and no deterioration in cash flow.” This combination would make the market willing to continue using P/S and forward earnings valuation. Conversely, if net profit looks good because of non-recurring items or expense timing, but orders and contract liabilities do not keep up, that is not the best signal.
The target-price framework should also be used dynamically. HSBC’s RMB1,031.90 target price corresponds to 2027 revenue and 11.7x P/S. It should not be directly ranked against target prices from other institutions based on 2027 P/E, 2030 discounted P/E, or order-growth frameworks. A more reasonable approach is to break each institution’s target price into assumptions: revenue baseline, margin, target multiple, time window, and new TAM weight. The level of the target price is only the result; whether the assumptions are verified by earnings reports is what matters.
Another easily overlooked issue is the security, share capital, and report date corresponding to the target price. NAURA is an A-share company. HSBC’s target price this time is given for RMB ordinary shares, and cannot be directly compared in the same table with the USD market caps of overseas equipment companies, Hong Kong shares, or ADR target prices. Even for NAURA itself, different institutions have different report dates, and the share-price base, earnings forecasts, target multiples, and corporate action windows may all change. The most prudent approach is to treat the target price only as a compressed expression of a sell-side worldview, not as an independent conclusion. The investment judgment should return to the same set of questions: are orders there, can revenue be recognized, are gross margin and expense ratios improving, is cash flow keeping up, and does the new TAM have actual orders? As long as these variables are not verified in the same direction, even a high target price is only advance pricing; if these variables are continuously verified, the target price instead becomes a lagging indicator.
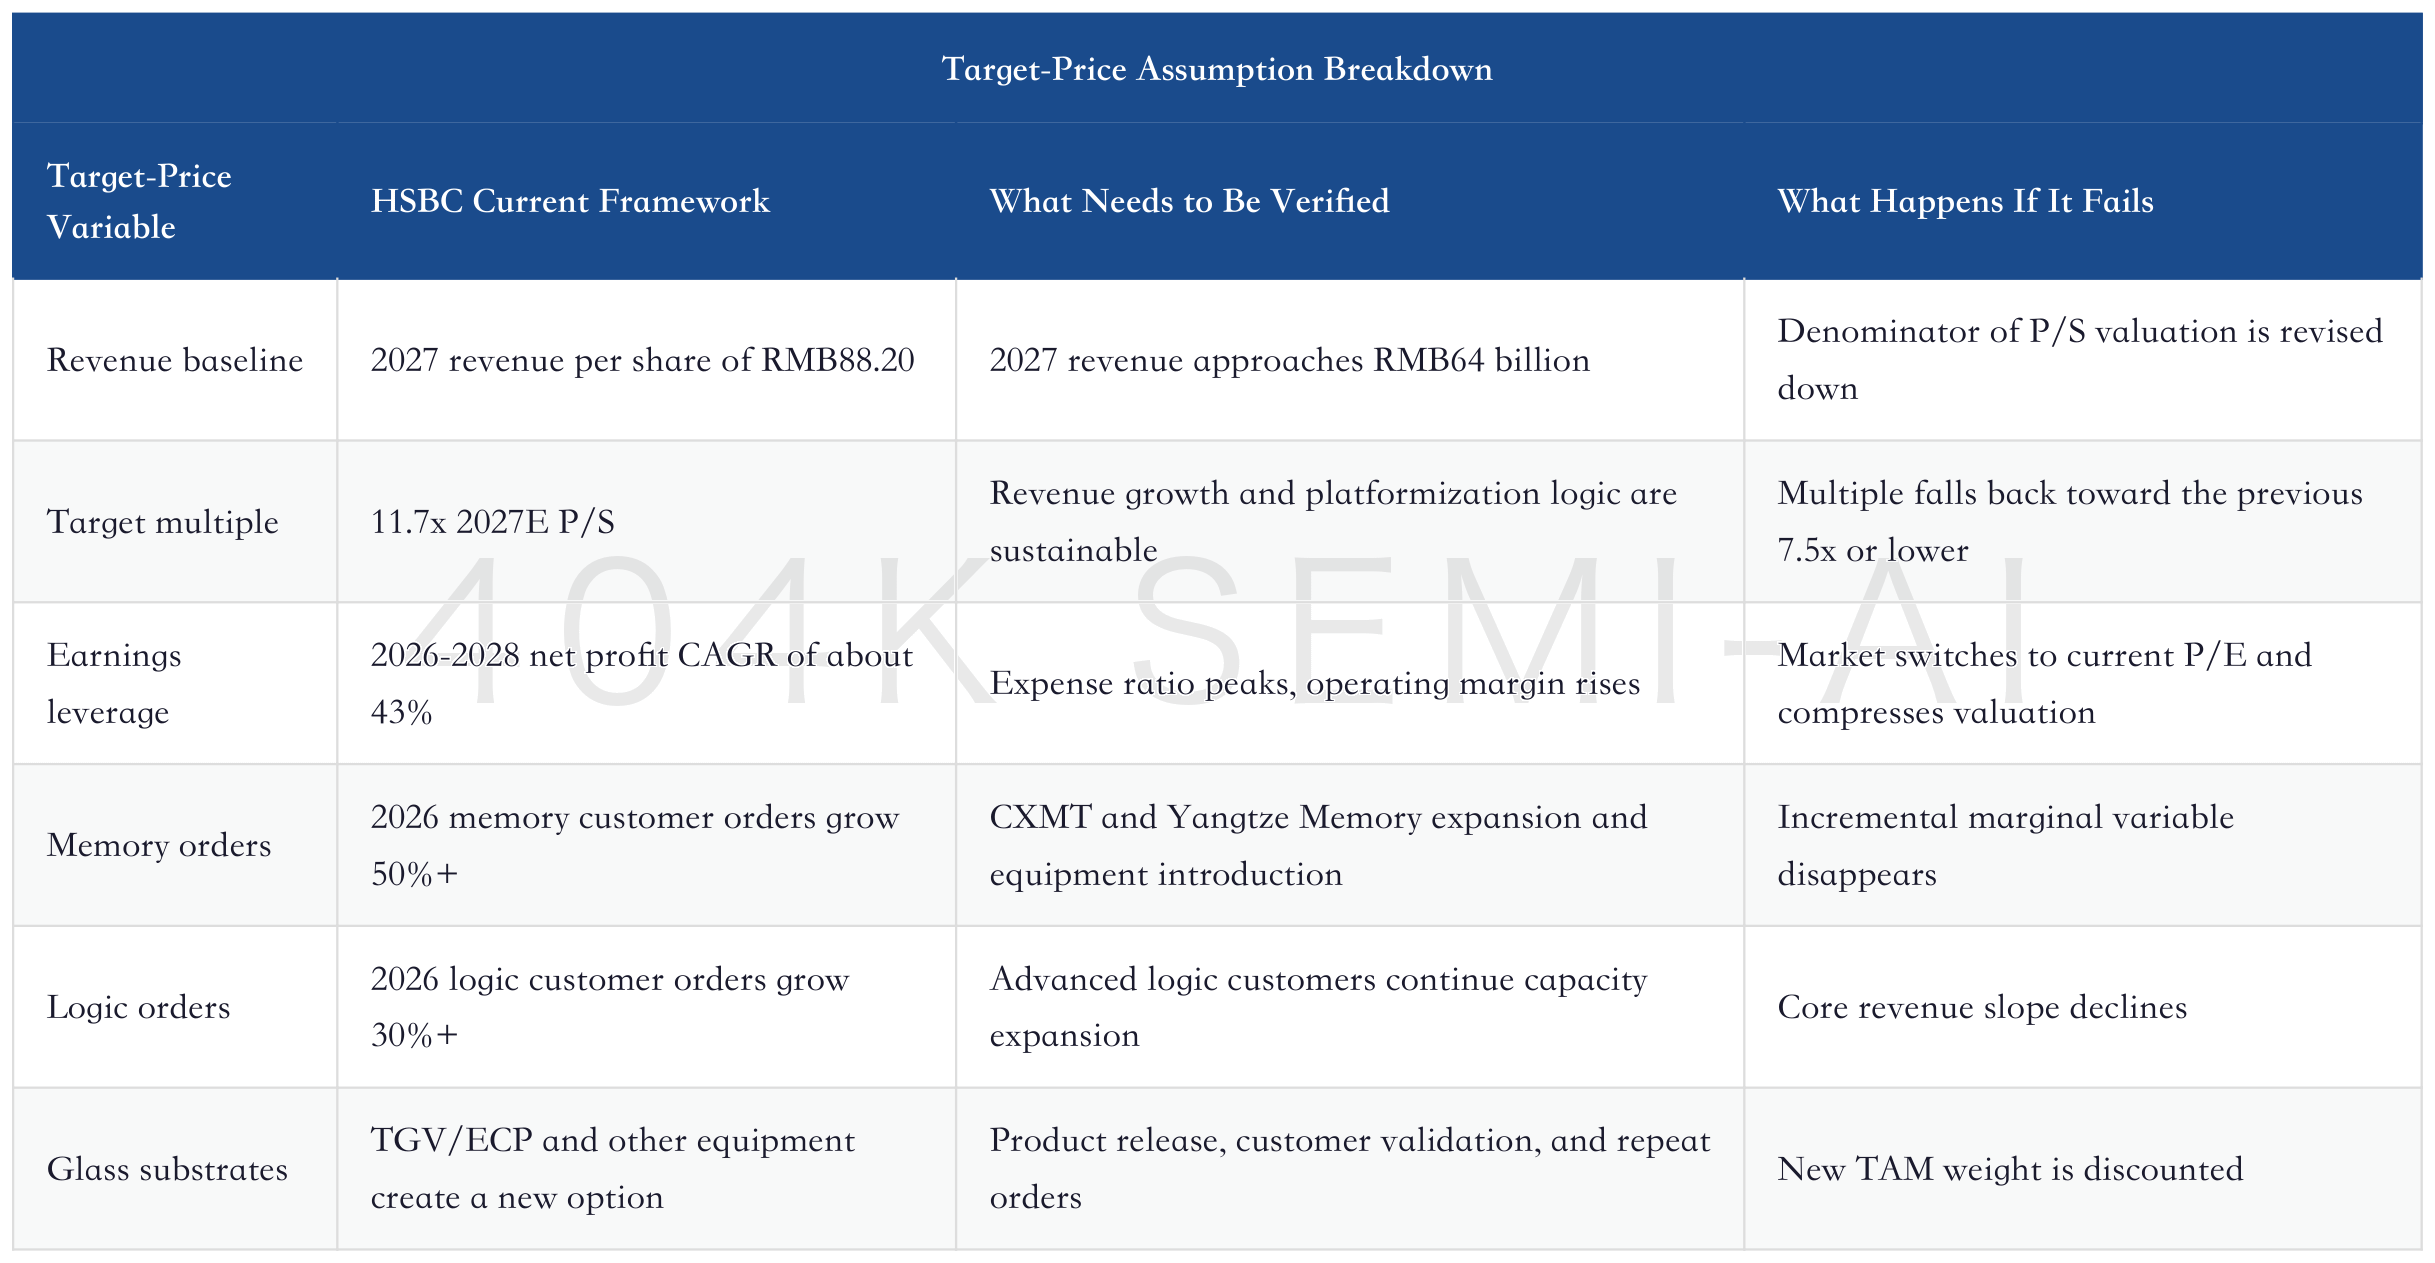
This table provides a clearer trading boundary. If revenue, orders, and margins all improve at the same time, the RMB1,031.90 target price is not the endpoint, but the starting point for the market to rediscuss NAURA’s long-term TAM. If only orders improve while margins do not move, the stock can rise, but volatility will be high. If orders are not strong either, the target price is only valuation extrapolation without enough fundamental support.
Research on NAURA should move from “how much is an equipment leader worth?” to “can platform reuse improve earnings quality?” Equipment leader is a static label; platform reuse is dynamic evidence. Over the coming quarters, as long as every order, revenue, gross margin, expense ratio, and cash-flow data point moves in the same direction, the market will continue to raise its confidence in the company’s long-term earnings. If these indicators diverge, valuation will first rise and then become volatile, or even retrace quickly.
This is also the most practical use of this update. It should not be read as “HSBC gave a higher target price, so how much upside remains for the stock?” It is better read as a verification checklist: whether 2026 orders first prove that memory and logic customers are truly accelerating, whether 2027 revenue proves that these orders are not stuck in acceptance and delivery, and whether 2028 margins prove that platformization did not remain only at revenue scale. If verification across these three years can connect step by step, NAURA’s valuation will move from “high-cycle equipment stock” to “multi-TAM platform company.” If any link breaks along the way, the market will pull it back into the framework of expense ratio, gross margin, and single-quarter earnings.
XIV. Conclusion: Naura Is Moving from an “Equipment Leader” to a “Multi-TAM Platform,” but Valuation Still Needs Margin Confirmation
HSBC’s report adds two important anchors for Naura: one is 2027 revenue and an 11.7x PS valuation; the other is the option value of glass-substrate TGV/ECP equipment. The report does not deny expense pressure; instead, it cuts 2026/2027 profit forecasts. But it believes the three growth curves of memory, logic, and glass substrates are sufficient to support a higher revenue platform. This is a more aggressive, but also clearer, worldview.
For Naura, the best-case scenario is that memory and logic orders both grow rapidly in 2026, glass-substrate equipment enters customer validation, revenue recognition accelerates in 2027, the expense ratio begins to fall, and gross margin holds at around 40%. In that case, the company would no longer be just a domestic equipment leader, but an equipment platform for domestic advanced fabs and advanced packaging substrate upgrades.
The neutral case is that orders continue to grow, but the recovery in expense ratio and gross margin is slow, and valuation switches back and forth between PS and PE. The stock can trade on orders, but each quarterly report will be pulled back by margins. This may be the more realistic path over the next few quarters.
This neutral path is not bad. It means the company’s fundamentals are still improving, but the capital market will not fully price in forward revenue, forward margins, and new TAM all at once. For long-term research, the neutral path is actually better suited to continuous tracking, because each quarter provides new evidence on orders, revenue, and expense ratio to update valuation.
The worst-case scenario is that memory orders do not materialize, logic capacity expansion is pushed out, glass-substrate validation is slow, and the expense ratio continues to rise. In that case, the market would reclassify Naura from a platform-type equipment company back into an equipment stock with “high revenue growth but unstable earnings quality,” and its valuation multiple would be compressed.
Therefore, the core conclusion of this deep-dive update is this: Naura’s upside comes from multi-TAM platformization, while the risk comes from expenses and gross margin failing to prove platform reuse. What really needs to be validated behind the RMB1,031.90 target price is not a single price point, but whether 2026 orders, 2027 revenue, and 2028 profits can connect into one line. Orders provide the first elasticity, revenue provides confirmation, and margins provide the final answer. This is also the core boundary for follow-up tracking, the valuation dividing line, and the key clue. As long as this validation chain remains intact, there is still room for Naura’s valuation debate to move higher; once it breaks, all TAM narratives will return to the income statement for repricing.NAURA In-Depth Update: How Memory/Logic Expansion, Glass Substrate TGV, and a RMB1,031 Target Price Revalue the Equipment Platform
目录
Too Long; Didn’t Read
I. What Is Actually New in This Update: From “Orders Absorbing Expenses” to “Three New Order Curves”
II. What HSBC’s Model Is Saying: Profits Cut, Valuation Raised
III. Why Memory Customers Matter: From a Mature-Node Proxy to a DRAM/NAND Expansion Proxy
IV. Logic Expansion Remains the Base: Advanced Logic Determines the Quality of a Platform Supplier
V. Glass Substrates: TGV/ECP Is Not Current Profit, But a Genuine New TAM
VI. How to Read the Target Price Upgrade: RMB1,031.90 Is Based on PS Valuation, Not a Short-Term Buy Signal
VII. Core Model: Three-Stage Validation of Orders, Revenue, and Margin
VIII. Compared with the Prior Report: Glass Substrate Is New, Memory Is Reinforced, Expense Pressure Is Unchanged
IX. Peer Positioning: NAURA’s Advantage Is Not Being the Strongest at One Point, but Participating in More Equipment Steps
X. Financial Bridge: After Revenue Steps Up, Margin Is the Final Pricing Variable
11. Three Worldviews: When You Are Bullish on NAURA, Which Future Are You Actually Choosing?
12. Falsification Checklist: What This Report Is Most Afraid Of
13. How to Track the Next Four Quarters: Orders First, Then Revenue Recognition, Finally Earnings Quality
XIV. Conclusion: Naura Is Moving from an “Equipment Leader” to a “Multi-TAM Platform,” but Valuation Still Needs Margin Confirmation
本内容基于公开资料和研报数据整理,不构成任何投资建议,不代表任何个人观点,仅供学习参考,请理性阅读
The core of this NAURA update is that order sources are expanding from advanced logic into memory capacity expansion and glass-substrate equipment. HSBC Qianhai raised its target price to RMB1,031.90. The real change is that the valuation anchor has shifted from current earnings to 2027 revenue and incremental platform TAM, with validation depending on whether orders, revenue, and margins are delivered in the same direction.
Too Long; Didn’t Read
NAURA has added three new order curves. HSBC believes higher capex at domestic memory fabs, continued advanced-logic expansion, and incremental room from glass-substrate equipment will support a revenue CAGR of around 27%-28% for NAURA in 2026-2028. The prior deep dive focused on whether etch, deposition, and HBM packaging tools could absorb expense pressure; this update adds glass-substrate TGV/ECP equipment and order elasticity from memory customers.
The target-price upgrade comes from a change in valuation anchor. The report shifts the valuation base to 2027 revenue and raises the target price to RMB1,031.90, while cutting profit forecasts for the next two years and acknowledging higher expense pressure during the expansion phase. In other words, the bullish case is not that near-term profits are strong, but that the revenue platform and earnings elasticity become clearer after 2027.
Memory customers are the strongest marginal variable. HSBC notes that CXMT and YMTC still have global DRAM/NAND shares well below China’s share of demand. Potential IPO financing and the memory price cycle may continue to support capacity expansion. HSBC expects NAURA’s 2026 orders from memory and logic customers to grow by 50%+ and 30%+, respectively. This turns NAURA from a domestic-substitution beneficiary at mature nodes into a front-end equipment proxy for domestic memory capex.
Glass substrates are a new option. HSBC estimates the glass-substrate market will reach roughly USD11.3bn by 2032, with equipment and materials accounting for around 10%. NAURA already has a commercialized PVD base and can provide descum and PIQ equipment; later electroplating tools can reuse TSV experience. This story is still small today, but it adds a long-term “advanced packaging substrate equipment” path to NAURA’s platform valuation.
The counterevidence remains in expense ratios and gross margin. HSBC cut 2026/2027 EPS from RMB10.33/13.85 to RMB9.62/13.41, showing that higher orders and TAM do not automatically eliminate expense pressure. If 2026 orders are strong but 2027 revenue recognition, gross margin, and operating leverage do not improve in tandem, the PS valuation anchor behind the RMB1,031.90 target price will be compressed back into a current-earnings framework.
Watch five numbers over the next four quarters: memory/logic order growth, the revenue contribution from advanced products, whether gross margin stabilizes around 40% or higher, whether R&D; and SG&A; expense ratios peak, and whether glass-substrate TGV/ECP equipment enters a verifiable order phase. NAURA’s valuation does not lack narratives; it lacks evidence that orders, revenue, and margins are moving in the same direction.
I. What Is Actually New in This Update: From “Orders Absorbing Expenses” to “Three New Order Curves”
The central tension in the prior NAURA deep dive was whether advanced-process orders could absorb expense pressure from R&D;, share incentives, and new-product introductions. That report had already broken down the company across etch, deposition, HBM packaging tools, Kingsemi coating/developing, and advanced-logic orders: strong orders do not equal strong profits; the more advanced products there are, the heavier the upfront expenses, and the market must wait for revenue recognition and falling expense ratios as secondary validation.
HSBC Qianhai’s July 6 update pushes the question one step forward. The report does not deny expense pressure; on the contrary, it cuts 2026/2027 net-profit forecasts. But it also raises the target price sharply because the sources of revenue growth have broadened. NAURA is no longer only following advanced-logic expansion; it is now exposed simultaneously to three curves: domestic memory-fab expansion, continued advanced-logic capex, and glass-substrate equipment.
The first curve is memory. HSBC notes that CXMT and YMTC still have global DRAM/NAND shares below China’s share of demand. If potential IPO financing is combined with an upcycle in memory prices, domestic memory-fab expansion may continue to drive front-end equipment procurement. If NAURA can gain higher share in etch, deposition, thermal processing, cleaning, and other steps, memory orders will become the strongest variable for the 2026-2027 revenue slope.
The second curve is logic. The report cites China’s advanced-capacity expansion and lithography tool import price data to show that advanced-logic capex has not ended. Logic customers typically have higher requirements for equipment stability, delivery, process tuning, and customer service, making it easier for platform equipment vendors to secure multi-step orders. NAURA’s product breadth is more valuable in logic fabs than a single-equipment breakthrough.
The third curve is glass substrates. This is not the main driver of NAURA’s current revenue, but it is a valuation option. If glass substrates enter the upgrade path for high-performance packaging and AI chip substrates, TGV, PVD seed layer, descum, PIQ, and electroplating equipment will generate new equipment demand. HSBC has included this market in its target-price logic, meaning NAURA’s “platform” definition is extending from front-end WFE to advanced packaging substrate equipment.
NAURA In Depth: From Etch and Deposition to HBM Packaging Tools, How Advanced-Process Orders Absorb Expense Pressure
These three curves explain why HSBC still sees room after the share-price rebound. The report notes that NAURA has risen 57% over the past two months, but still lags the 72% gain in the Wind Semiconductor Equipment Index. The reasons for the relative lag are, first, market concerns about the gross-margin trend after 1Q26, and second, NAURA’s lower revenue exposure to memory customers versus peers such as AMEC and Piotech. HSBC’s view is that the product mix and customer structure are now addressing this shortfall.
This is not a simple “laggard catch-up” trade. If it were only laggard catch-up, the target-price increase would not need to come alongside cuts to profit forecasts. The real logic is that near-term margin downgrades already reflect expansion costs, while the long-term revenue pool and addressable market have expanded, allowing valuation to shift from the EPS trough to PS and revenue compound growth. Whether this switch holds depends on whether 2026 orders become 2027 revenue, not on whether a single-quarter net margin immediately recovers.
II. What HSBC’s Model Is Saying: Profits Cut, Valuation Raised
The most important part of this report is the model structure. HSBC is not simply raising the target price; it puts revenue, profit, ROE, and valuation multiples into one framework: revenue continues to step up, while earnings elasticity strengthens materially in 2027 and 2028. The specific figures are shown below. The more important issue in the text is why profit elasticity lags orders.
But the report does not blindly raise earnings. HSBC cuts EPS for the next two years because operating expenses are higher during the company’s expansion phase; R&D;, SG&A;, product validation, and headcount investment all hit the income statement first. It acknowledges that near-term profits are weaker than previously expected, but raises 2028 EPS to a higher level, showing that the core issue is not one-year profit in 2026, but subsequent compound earnings growth.
This table shows that HSBC is not betting on a sudden improvement in 2026 margins. It is betting that once the revenue platform rises, operating leverage will be released in 2027-2028. The stock looks expensive in 2026, but the 2028 PE falls to 43x; that is the basis for the report’s willingness to assign a high PS-based target price. If 2028 profits do not materialize, the target price naturally will not hold.
When reading this table, the focus should not be on any single number, but on the slope. The revenue slope represents customer expansion and equipment share; the operating-profit slope represents expense absorption; the ROE slope represents returns on capital. If NAURA delivers only the revenue slope, the stock will trade on growth. If it also delivers the operating-profit and ROE slopes, the valuation will shift from order expectations to earnings quality.
This is also the most easily overlooked part of equipment stocks: orders are leading indicators, profits are lagging indicators, and between them sit delivery, acceptance, yield, and service costs. The value of researching NAURA lies in breaking down these intermediate steps, rather than only looking at changes in the target price.
The valuation method has also changed. HSBC continues to use PS valuation, raising the target multiple from 7.5x previously to 11.7x, corresponding to 2027 revenue per share of RMB88.20 and producing a target price of RMB1,031.90. Choosing PS rather than PE essentially says: margins are still unstable during the expansion phase, and revenue visibility is a more suitable primary anchor than current net margin.
This is also a common revaluation path for semiconductor equipment growth stocks. In the early stage, the market watches orders; in the middle stage, revenue; in the later stage, margins. NAURA is now between orders and revenue: order clues are increasing, revenue forecasts are starting to rise, but margins are still pressured by expenses. The premise for using PS valuation is that investors believe revenue will convert into profit; once expense ratios fail to decline, the market will fold the PS multiple back into PE.
China Semiconductor Equipment In-Depth Update: CXMT Server DRAM Long-Term Orders, Advanced-Logic Expansion, and the Switch to 2030E Discounted PE
III. Why Memory Customers Matter: From a Mature-Node Proxy to a DRAM/NAND Expansion Proxy
In the past, when the market looked at Naura Technology, it often first thought of mature-node domestic substitution and advanced logic tool adoption. HSBC places greater emphasis on memory this time because memory capacity expansion brings forward the pace of equipment capex. If CXMT and YMTC continue to raise capacity, front-end tools such as etch, deposition, furnaces, and cleaning will all be pulled along, and Naura happens to cover these key segments.
A key comparison in HSBC’s framework is that CXMT’s and YMTC’s global DRAM/NAND shares remain below China’s share of demand. As long as domestic demand, supply security, and the pricing cycle coexist, continued capacity expansion by memory makers remains logical. Memory is not simply a domestic-substitution theme; it is also tied to AI servers, enterprise SSDs, the HBM ecosystem, and the capex cycle of domestic cloud vendors.
Memory is especially important for Naura because it may address the market’s previous concern over “insufficient memory-customer exposure.” HSBC believes Naura’s share price lagged peers over the past two months partly because the market viewed its revenue exposure to memory customers as lower than AMEC and Piotech. If orders from memory customers grow by more than 50% in 2026, that discount will be reassessed.
The most important part of this transmission chain is repeat orders. It is not difficult for equipment vendors to secure prototype validation; the hard part is customer repurchases and replication across production lines. If Naura can only win a small number of validation orders from memory customers, revenue elasticity will be limited. If it can extend from etch and deposition into a multi-step equipment portfolio, memory customers will become an important source of revenue upgrades in 2027.
This is also why order growth matters more than current-period profit. The cycle from equipment order to revenue recognition is often long. If memory-customer expansion generates orders in 2026, more of the revenue will be reflected in 2027. The market is willing to assign a PS valuation in advance because it trades orders first, then waits for revenue and earnings validation. Conversely, if 2026 orders do not grow by more than 50%, the PS valuation will lack its first building block.
IV. Logic Expansion Remains the Base: Advanced Logic Determines the Quality of a Platform Supplier
Memory is the marginal variable, while advanced logic remains the base. HSBC notes that China’s plan to expand advanced capacity before 2030, as well as changes in Dutch lithography-tool import value and ASP in 2025, both point to continued growth in advanced fab capex. Lithography tools are a leading indicator for line construction. Once customers buy more expensive and more advanced lithography equipment, supporting tools such as etch, deposition, cleaning, thermal processing, and metrology will follow.
Naura’s value in advanced logic is not limited to any single type of equipment. Advanced logic lines involve many steps, complex tuning, and narrow yield windows, so customers care more about whether suppliers can provide multi-step delivery and field service. Etch and deposition form the chassis, while furnaces, cleaning, ion implantation, coating and developing, and advanced packaging tools increase platform completeness. The more complete the platform, the more likely customers are to hand over additional process steps to the same supplier.
This differs from ordinary mature-node expansion. Mature nodes are more prone to price competition, while advanced logic places greater emphasis on stability, delivery cycles, spare-parts service, and process coordination. If Naura can keep expanding its product categories in advanced logic, it will not merely take share from overseas equipment vendors; it will increase stickiness within customer production lines.
HSBC expects Naura’s orders from logic customers to grow by more than 30% in 2026. This is lower than the more than 50% growth expected from memory customers, but logic orders are more like the core base: continued advanced logic capex means Naura does not need to rely solely on the memory cycle and the glass substrate option for its story. Stable logic orders, elastic memory orders, and long-term upside from glass substrates together form the revenue pool behind the RMB1,031.90 target price.
Naura’s valuation should be assessed through the “reuse rate of its product portfolio.” If customers buy etch equipment and then continue to adopt the company’s deposition, thermal processing, cleaning, and coating/developing tools, its R&D; and service costs can be spread across multiple categories. Conversely, if every new category requires separate investment, separate validation, and separate price discounts, the platform story becomes a cost story.
V. Glass Substrates: TGV/ECP Is Not Current Profit, But a Genuine New TAM
Glass substrates are the most novel part of this HSBC report. As AI chip packaging continues to evolve toward higher I/O, higher bandwidth, lower warpage, and better thermal stability, glass substrates are viewed as a direction that could replace or complement some organic substrate and interposer solutions. It is not yet a mature large market, but once the industry enters volume production, equipment and materials will benefit first.
HSBC estimates the glass substrate market will reach about US$11.3 billion by 2032, with equipment and materials accounting for about 10%. For Naura, this is not a business that can contribute several billion renminbi of revenue immediately, but rather an option on whether its equipment platform can spill over into advanced packaging substrates. The market is willing to value this option provided the company already has reusable technologies.
Naura’s reusable technologies are mainly in three areas. First is the PVD seed layer: conductive seed layers on glass substrates require PVD deposition, where the company already has a commercial foundation. Second are descum and PIQ tools, where yield sensitivity can demonstrate the company’s process understanding. Third is subsequent electroplating equipment; HSBC believes Naura can leverage its existing TSV experience to extend into TGV ECP tools.
The benefit of glass substrates is that they are tied to AI packaging upgrades; the drawback is uncertain industry timing. For now, this is more like a post-2027 valuation option than a 2026 profit source. If the company releases TGV ECP equipment and enters customer validation, the market will view it as successful platform extension. If validation is slow or industry adoption is delayed, its impact on 2026-2027 profit will be limited.
This is why glass substrates should not be framed as “certain profit.” They are better understood as a counter-test of Naura’s platformization: can the company migrate its front-end PVD, TSV, electroplating, cleaning, and materials-processing experience into advanced packaging substrates? If it can, Naura’s TAM will be tied not only to fab WFE, but also to AI packaging substrate upgrades.
VI. How to Read the Target Price Upgrade: RMB1,031.90 Is Based on PS Valuation, Not a Short-Term Buy Signal
HSBC raised its target price from RMB528.40 to RMB1,031.90, a very large increase. The number is eye-catching, but it should be broken into three questions: first, why the valuation method moved from 7.5x PS to 11.7x PS; second, why 2027 revenue is used rather than 2026 profit; third, why the target price upgrade and profit downgrade appear at the same time.
The answer to the first question is improved visibility on revenue growth. HSBC expects revenue CAGR of about 27% in 2026-2028, close to the roughly 26% average revenue CAGR of global equipment peers, and therefore assigns NAURA a PS multiple closer to global peers. NAURA’s historical discount reflected market concerns over insufficient memory exposure, unstable gross margin, and high expenses. The report now argues that memory, logic, and glass substrates have widened the revenue pool.
The answer to the second question is that 2026 remains an expansion investment year. 2026 profit is suppressed by expenses, making PE look expensive. But if 2027 revenue recognition and profit improvement become clearer, PS valuation can better reflect order value than current-period PE. During an order upcycle, equipment companies are often valued on revenue first and margin later, especially when new product introduction and customer qualification have not yet fully released operating leverage.
The answer to the third question is that the valuation anchor has shifted from “near-term profit” to “long-dated platform revenue.” HSBC’s downgrade to 2026/2027 net profit acknowledges expansion costs; its target price upgrade reflects a view that the revenue platform and long-term profit elasticity are higher. This combination is not contradictory, but it also carries higher risk: if revenue fails to materialize, valuation will quickly revert to a profit-based framework.
This table should not be used to rank target prices mechanically. Report dates, valuation methods, and forecast years differ, so each target price reflects a different worldview. HSBC’s worldview leans more toward “revenue platform and incremental TAM”; Bernstein emphasizes order restart; Goldman Sachs focuses more on advanced tools and China semiconductor capex. The common point is that none of them still treats NAURA as a company valued only on current-quarter earnings.
Equipment Capex Ledger Update: AI Financing, US$250 Billion WFE, and Semiconductor Equipment Repricing
VII. Core Model: Three-Stage Validation of Orders, Revenue, and Margin
NAURA is best understood through a three-stage model. The first stage is orders, which determines whether the market is willing to assign valuation first. The second stage is revenue, which determines whether forecasts can be revised up. The third stage is margin, which determines whether the valuation can hold. HSBC’s report strengthens the first and second stages, but the third still requires follow-up validation.
The order stage depends on customers and products. If memory customer orders grow by more than 50%, logic customer orders grow by more than 30%, and the orders come not only from mature nodes but also from advanced logic, advanced memory, glass substrates, and advanced packaging, the market will continue to price in revenue upgrades. The biggest risk is order growth concentrated in categories with low gross margin, high qualification cost, or intense competition.
The revenue stage depends on the recognition cycle. Equipment orders usually do not turn into revenue immediately. Delivery, installation, acceptance, and customer fab ramp all take time. 2026 orders are more likely to affect 2027 revenue, which is also why HSBC values the company on 2027 revenue. If 2026 orders are strong but 2027 revenue recognition is slow, PS valuation will come under pressure first.
The margin stage depends on operating leverage. NAURA does not lack a revenue story now; what it lacks is proof that “expense ratio can decline after revenue grows.” R&D;, SG&A;, equity incentives, and new product qualification are all necessary investments during the order introduction phase. But if the expense ratio still does not decline after revenue reaches the RMB60 billion and RMB80 billion levels, platformization will not have translated into earnings quality.
This model also explains why NAURA’s share price volatility can be high. Orders and revenue can drive valuation ahead of fundamentals, while margin determines drawdown magnitude. In each quarterly report, if revenue is good but gross margin is weak, the market will hesitate; if orders are strong but profit is weak, the market may tolerate it first; only when orders, revenue, and margin are all strong will a true main uptrend logic form.
VIII. Compared with the Prior Report: Glass Substrate Is New, Memory Is Reinforced, Expense Pressure Is Unchanged
The prior report focused on “from etch and deposition to HBM packaging tools, how advanced-process orders pass through expense pressure.” That report already answered what NAURA sells, why orders are strong, why expenses pressure profit, and why 2027 is the key year. This update does not need to rewrite the company profile; it needs to answer what new evidence the latest report provides.
One new piece of evidence is stronger order elasticity from memory customers. The prior report had already discussed advanced memory and high-aspect-ratio etch for 3D NAND, but HSBC provides a more explicit order-growth assumption: memory customer orders rising by more than 50%. If this figure is validated by subsequent financial reports and order indicators, NAURA’s revenue elasticity will move closer to a “memory capex proxy,” rather than merely a “beneficiary of advanced logic expansion.”
The second new piece of evidence is glass substrate equipment. The prior report covered HBM hybrid bonding and advanced packaging tools, but did not treat glass substrate TGV/ECP as a standalone TAM. HSBC incorporates glass substrate market size, PVD seed layer, descum, PIQ, and electroplating tools into its logic, effectively adding a new curve to NAURA’s platform extension.
The unchanged issue is expense pressure. HSBC’s downgrade to 2026/2027 net profit forecasts is consistent with the prior report’s view: NAURA is not a company whose margin concerns have already disappeared. The larger its orders and TAM, the greater its R&D;, qualification, service, and staffing investment. Near-term EPS may continue to be suppressed by expenses. The market is willing to assign it a higher target price because it believes expenses will be diluted by future revenue, not because expenses have already vanished.
IX. Peer Positioning: NAURA’s Advantage Is Not Being the Strongest at One Point, but Participating in More Equipment Steps
The easiest way to misread NAURA Technology Group is to compare it as a single-equipment leader. If one looks only at etch, the high-aspect-ratio etch narrative more naturally maps to AMEC; if one looks only at thin-film deposition, Piotech has the clearer label; if one looks only at cleaning, coating/developing, or ion implantation, different specialist equipment companies come into view. NAURA’s real feature is that it has positions across multiple core front-end steps, and is extending those positions into advanced packaging and glass substrates.
This determines a valuation approach that differs from single-point equipment companies. For a single-point equipment company, the most important question is whether a given tool can win high share at key customers, in key processes, and at key nodes. For NAURA, the more important question is whether it can win a basket of equipment orders when customers expand capacity. When advanced logic or memory customers build lines, NAURA touches not one process step, but a sequence of process steps. Product breadth itself carries option value.
But product breadth also has side effects. Every new category requires R&D;, validation, process service, and after-sales systems, so near-term expense ratios are hard to keep low. NAURA’s advantage is not “low expense,” but that after multiple product lines enter the repeat-order stage, customer service, supply chain, on-site tuning, and R&D; platforms can be reused. Platform value only becomes margin after reuse occurs; before reuse, it only becomes expense.
The gap between NAURA and global integrated equipment companies lies mainly not in the product catalog, but in depth of advanced-process validation, global customer coverage, and service-revenue quality. Companies such as Applied Materials, Lam Research, and Tokyo Electron have been able to sustain high valuations over the long term because their equipment, processes, services, and customer roadmaps are deeply tied together. NAURA is still moving from “equipment substitution” toward a “process platform.” The market’s PS valuation is an early trade on that migration.
From this perspective, HSBC’s comparison of NAURA’s 2026-2028 revenue growth with global equipment peers is logical. If revenue growth approaches that of global equipment leaders while product lines are still expanding, the customer mix is still improving, and domestic share is still rising, NAURA has reason to enjoy a higher growth multiple. The issue is that the earnings quality of global leaders has already been validated through many cycles, while NAURA still needs the next few quarters to prove that expense investment can be absorbed by the revenue platform.
Peer comparison also points to one risk: NAURA cannot rely on the four words “domestic equipment platform” alone for valuation. A platform company must satisfy three conditions at the same time. First, products must enter key customers’ core processes, not merely replace non-critical steps. Second, customers must place repeat orders, allowing R&D; and service investment to be amortized. Third, new categories must form sales and process synergies, rather than operating independently. If any one of these three conditions is missing, the platform valuation will be discounted.
X. Financial Bridge: After Revenue Steps Up, Margin Is the Final Pricing Variable
In HSBC’s forecast table, the item most worth turning into a financial bridge is not the target price, but the transmission from revenue to profit. Both revenue and net profit are stepping up, but net profit has higher elasticity, implying that the report assumes operating leverage will be released after 2027. The specific amounts are shown below. The key question in the text is whether this profit bridge can be jointly supported by orders, gross margin, and expense ratios.
The first section of the bridge is revenue. Revenue is projected at RMB 50.468bn in 2026, RMB 64.003bn in 2027, and RMB 81.302bn in 2028. If memory and logic orders land on schedule, the revenue step-up is not hard to understand. China’s semiconductor capex direction has moved from mature-node expansion toward parallel expansion across advanced logic, advanced memory, and advanced packaging. NAURA has product exposure in all these directions, so the upward revenue revision comes more from customer mix than from simple price increases.
The second section is operating profit. HSBC expects operating profit to rise from RMB 4.724bn in 2025 to RMB 14.102bn in 2028, with operating margin increasing from about 12.0% to about 17.3%. This is the most critical step because it means expense ratios are beginning to be diluted by revenue. If revenue grows but operating margin does not improve, the market will view the company as using higher expenses to buy higher revenue. If operating margin rises in step with revenue, platformization is truly reflected in the income statement.
The third section is net profit and ROE. HSBC expects ROE to rise from 16.1% in 2025 to 23.8% in 2028. The significance of higher ROE is not just more profit, but that the company’s invested capital is starting to generate higher returns. Equipment companies consume cash and inventory during expansion periods, while also increasing receivables and after-sales service investment. Only when ROE rises can growth quality be shown not to have been dragged down by working capital.
The most sensitive year here is 2027. In 2026, the market can accept expense pressure because orders are coming from memory and logic customers. In 2028, the market can see profit elasticity, but that is still too far away. 2027 is the bridge year. If revenue approaches RMB 64.0bn, operating margin approaches 15%, and ROE reaches around 20%, HSBC’s PS valuation has a basis. If 2027 revenue and margin both fall short, the RMB 1,031.90 target price will look too early.
Cash flow also needs to be tracked. For equipment companies in an expansion cycle, a common issue is that the income statement grows quickly, while inventory, receivables, prepayments, and customer acceptance cycles drag on operating cash flow. If NAURA continues to win large orders, inventory and shipped-but-unaccepted goods may rise. That is not necessarily bad, but the question is whether they ultimately convert into revenue and cash. Over the next few quarters, changes in operating cash flow and contract liabilities will explain order quality better than single-quarter net profit attributable to the parent.
The purpose of this table is to turn subsequent earnings reports from “whether they look good” into “which section has been validated.” If a quarter has strong revenue, weak gross margin, and a high expense ratio, but strong contract liabilities and order signals, the market may continue to give the company time. If revenue is strong but cash flow deteriorates, gross margin falls, and the expense ratio does not decline, the market will suspect the company is using low-quality orders to buy growth. Research on NAURA cannot stop at the target price; it must focus on revenue quality.
11. Three Worldviews: When You Are Bullish on NAURA, Which Future Are You Actually Choosing?
The current debate around NAURA is not whether domestic substitution exists, but what kind of company it ultimately becomes. If it is only a substitute supplier for mature-node equipment, it should be valued on a lower P/E and cyclical orders. If it is a core platform for advanced logic and memory capacity expansion, it can be valued on revenue growth and long-term margins. If it can also enter glass substrates, advanced packaging substrate equipment, and the HBM ecosystem, it gains another new TAM curve.
In the conservative worldview, NAURA remains an excellent domestic equipment company, but new TAM realization is slow. Memory customer orders grow below expectations, logic capacity expansion is delayed by customer pacing and lithography constraints, and glass substrate equipment remains at the release and validation stage. Revenue still grows, but expense ratios weigh on earnings, and valuation returns to a P/E framework. In this case, the stock behaves more like a high-volatility equipment leader than a platform rerating story.
In the base-case worldview, memory and logic orders are gradually realized according to HSBC’s assumptions. Orders are strong in 2026, revenue is recognized in 2027, and margins improve in 2028. Glass substrates do not contribute much, but provide a valuation option. NAURA’s investment case shifts from a single domestic-substitution story to an equipment platform for China’s advanced production-line buildout. P/S valuation can work for a period, but every earnings report must renew that logic through revenue and margins.
In the optimistic worldview, NAURA generates repeat orders across memory, logic, and advanced packaging at the same time. Memory customers accelerate capacity expansion, advanced logic customers continue to expand, and glass substrate equipment such as TGV/ECP enters verifiable orders. The company’s revenue base moves higher, R&D; and service systems start to be reused, operating margins rise, and ROE improves. At that point, it is no longer just a Chinese equipment substitution company, but one of the most domestically leveraged integrated equipment platforms in the global WFE cycle.
Among these three worldviews, the real bet is whether the base case can move toward the optimistic case. The conservative case does not mean the company is poor; it means the current valuation has priced in too much too early. The optimistic case is not achieved through slogans either, but through continuous verification by orders, revenue, margins, and cash flow. Investors need to avoid valuing every new TAM as certain earnings, while also not ignoring the earnings leverage that can emerge once a platform company achieves reuse.
NAURA’s relationship with AI capex also needs to be understood within this framework. AI does not place orders directly with NAURA. AI indirectly lifts equipment demand through servers, memory, HBM, advanced packaging, wafer-fab capex, and domestic supply-chain security. The closer the business is to wafer fabs and advanced packaging equipment, the shorter the transmission chain; the closer it is to the long-dated glass substrate option, the longer the transmission chain. Different businesses should receive different certainty weights in valuation.
12. Falsification Checklist: What This Report Is Most Afraid Of
NAURA’s risk is not that there is “no domestic substitution story.” The market already knows it is a platform company in China’s semiconductor equipment sector, and it also knows China’s WFE capex is resilient. The real falsification points are whether the order structure is high quality enough, whether revenue is recognized on schedule, and whether margins can return to a level the market is willing to believe for a platform equipment company.
First, if memory customer orders do not accelerate as scheduled, HSBC’s incremental logic weakens. Memory expansion is an important marginal variable behind this target-price upgrade. If CXMT and Yangtze Memory’s expansion pace, financing plans, or equipment procurement fall short of expectations, NAURA’s memory order growth of more than 50% will be difficult to realize.
Second, if logic capacity expansion is slowed by lithography, yields, or customer capex pacing, the conversion of orders into revenue will be delayed. However broad NAURA’s product portfolio is, it still has to follow customer fab construction. Advanced logic is not simply a matter of buying equipment and entering mass production. It is jointly affected by lithography tools, process integration, yield ramp, and downstream demand.
Third, if industry adoption of glass substrates is slow, the market will discount the TGV/ECP option. This direction is inherently a long-dated TAM and should not receive an overly high certainty weight. If TGV/ECP equipment release, customer validation, and order progress are slower than expected, it will remain more of a narrative and will not contribute earnings.
Fourth, if the expense ratio continues to rise, P/S valuation will be pulled back to reality by margins. HSBC has already lowered 2026/2027 EPS. The market can accept one expense reset, but not repeated resets. If R&D; and SG&A; expense ratios cannot decline after revenue moves to the next level, platformization cannot translate into ROE.
Fifth, if gross margin falls below 40% and cannot recover for a long time, the market will question order quality. High growth in equipment orders is not necessarily good. Low-gross-margin orders, heavily discounted orders, and orders with high validation costs may bring revenue without earnings. NAURA must prove that its advanced product mix can support gross margin, rather than exchanging price for share.
13. How to Track the Next Four Quarters: Orders First, Then Revenue Recognition, Finally Earnings Quality
The next phase of tracking NAURA cannot focus only on single-quarter net profit growth. Single-quarter net profit is easily distorted by expenses, share-based compensation, government subsidies, product acceptance timing, and customer delivery schedules. A more effective sequence is to look first at orders and customers, then revenue recognition, then gross margin and expense ratios, and finally cash flow. This sequence matches the operating cycle of equipment companies and is also consistent with HSBC’s use of P/S valuation this time.
In the first quarter, the priority is whether there are independent clues for memory and logic orders. HSBC’s 50%+ memory customer order growth and 30%+ logic customer order growth are the most important testable assumptions in this report. If company announcements, meeting notes, tender clues, customer capex, or contract liabilities confirm that orders continue to rise, the market will continue to tolerate margin pressure. If order clues are not strong, revenue and earnings forecasts will lack a premise.
In the second quarter, the focus should be whether orders convert into revenue recognition. From signing to revenue recognition, equipment orders require shipment, installation, commissioning, and acceptance. Advanced products and new customers have even longer cycles. If 2026 orders are strong but revenue recognition is slow, that does not necessarily falsify the company in the short term, but it will affect market confidence in the 2027 revenue forecast of RMB64 billion. The smoother the recognition, the easier it is to sustain P/S valuation; the slower the recognition, the more the market will return to current P/E.
In the third quarter, the key is whether gross margin and expense ratio improve in the same direction. If NAURA can keep gross margin around 40% while R&D; and SG&A; expense ratios peak, it indicates that platform reuse is starting to appear. If revenue growth comes with declining gross margin and no decline in expense ratios, growth may depend on low-gross-margin orders, new-product introduction costs, or customer service costs, and platform value has not yet entered the income statement.
In the fourth quarter, the question is whether advanced packaging and glass substrates move from narrative to orders. Terms such as TGV/ECP, PVD seed layer, descum, and PIQ only become valuation contributors when they appear in customer validation, repeat orders, equipment delivery, and revenue recognition. If they remain only at the product-release or technology-reserve stage, they offer limited help to 2026-2027 valuation. If verifiable orders emerge, NAURA’s TAM will be revised upward again.
This tracking path can avoid two common misjudgments. The first is fully rejecting the company just because near-term margins are weak. During the introduction of new equipment categories, equipment companies may invest first and harvest later; single-quarter margins are not the only answer. The second is ignoring earnings quality just because order clues are strong. Orders ultimately need to convert into revenue, gross profit, cash flow, and ROE; otherwise they represent only scale growth, not platform rerating.
For NAURA, the best earnings combination is not “the highest single-quarter net profit,” but “strong order clues, stable revenue recognition, gross margin not breaking down, expense ratios peaking, and no deterioration in cash flow.” This combination would make the market willing to continue using P/S and forward earnings valuation. Conversely, if net profit looks good because of non-recurring items or expense timing, but orders and contract liabilities do not keep up, that is not the best signal.
The target-price framework should also be used dynamically. HSBC’s RMB1,031.90 target price corresponds to 2027 revenue and 11.7x P/S. It should not be directly ranked against target prices from other institutions based on 2027 P/E, 2030 discounted P/E, or order-growth frameworks. A more reasonable approach is to break each institution’s target price into assumptions: revenue baseline, margin, target multiple, time window, and new TAM weight. The level of the target price is only the result; whether the assumptions are verified by earnings reports is what matters.
Another easily overlooked issue is the security, share capital, and report date corresponding to the target price. NAURA is an A-share company. HSBC’s target price this time is given for RMB ordinary shares, and cannot be directly compared in the same table with the USD market caps of overseas equipment companies, Hong Kong shares, or ADR target prices. Even for NAURA itself, different institutions have different report dates, and the share-price base, earnings forecasts, target multiples, and corporate action windows may all change. The most prudent approach is to treat the target price only as a compressed expression of a sell-side worldview, not as an independent conclusion. The investment judgment should return to the same set of questions: are orders there, can revenue be recognized, are gross margin and expense ratios improving, is cash flow keeping up, and does the new TAM have actual orders? As long as these variables are not verified in the same direction, even a high target price is only advance pricing; if these variables are continuously verified, the target price instead becomes a lagging indicator.
This table provides a clearer trading boundary. If revenue, orders, and margins all improve at the same time, the RMB1,031.90 target price is not the endpoint, but the starting point for the market to rediscuss NAURA’s long-term TAM. If only orders improve while margins do not move, the stock can rise, but volatility will be high. If orders are not strong either, the target price is only valuation extrapolation without enough fundamental support.
Research on NAURA should move from “how much is an equipment leader worth?” to “can platform reuse improve earnings quality?” Equipment leader is a static label; platform reuse is dynamic evidence. Over the coming quarters, as long as every order, revenue, gross margin, expense ratio, and cash-flow data point moves in the same direction, the market will continue to raise its confidence in the company’s long-term earnings. If these indicators diverge, valuation will first rise and then become volatile, or even retrace quickly.
This is also the most practical use of this update. It should not be read as “HSBC gave a higher target price, so how much upside remains for the stock?” It is better read as a verification checklist: whether 2026 orders first prove that memory and logic customers are truly accelerating, whether 2027 revenue proves that these orders are not stuck in acceptance and delivery, and whether 2028 margins prove that platformization did not remain only at revenue scale. If verification across these three years can connect step by step, NAURA’s valuation will move from “high-cycle equipment stock” to “multi-TAM platform company.” If any link breaks along the way, the market will pull it back into the framework of expense ratio, gross margin, and single-quarter earnings.
XIV. Conclusion: Naura Is Moving from an “Equipment Leader” to a “Multi-TAM Platform,” but Valuation Still Needs Margin Confirmation
HSBC’s report adds two important anchors for Naura: one is 2027 revenue and an 11.7x PS valuation; the other is the option value of glass-substrate TGV/ECP equipment. The report does not deny expense pressure; instead, it cuts 2026/2027 profit forecasts. But it believes the three growth curves of memory, logic, and glass substrates are sufficient to support a higher revenue platform. This is a more aggressive, but also clearer, worldview.
For Naura, the best-case scenario is that memory and logic orders both grow rapidly in 2026, glass-substrate equipment enters customer validation, revenue recognition accelerates in 2027, the expense ratio begins to fall, and gross margin holds at around 40%. In that case, the company would no longer be just a domestic equipment leader, but an equipment platform for domestic advanced fabs and advanced packaging substrate upgrades.
The neutral case is that orders continue to grow, but the recovery in expense ratio and gross margin is slow, and valuation switches back and forth between PS and PE. The stock can trade on orders, but each quarterly report will be pulled back by margins. This may be the more realistic path over the next few quarters.
This neutral path is not bad. It means the company’s fundamentals are still improving, but the capital market will not fully price in forward revenue, forward margins, and new TAM all at once. For long-term research, the neutral path is actually better suited to continuous tracking, because each quarter provides new evidence on orders, revenue, and expense ratio to update valuation.
The worst-case scenario is that memory orders do not materialize, logic capacity expansion is pushed out, glass-substrate validation is slow, and the expense ratio continues to rise. In that case, the market would reclassify Naura from a platform-type equipment company back into an equipment stock with “high revenue growth but unstable earnings quality,” and its valuation multiple would be compressed.
Therefore, the core conclusion of this deep-dive update is this: Naura’s upside comes from multi-TAM platformization, while the risk comes from expenses and gross margin failing to prove platform reuse. What really needs to be validated behind the RMB1,031.90 target price is not a single price point, but whether 2026 orders, 2027 revenue, and 2028 profits can connect into one line. Orders provide the first elasticity, revenue provides confirmation, and margins provide the final answer. This is also the core boundary for follow-up tracking, the valuation dividing line, and the key clue. As long as this validation chain remains intact, there is still room for Naura’s valuation debate to move higher; once it breaks, all TAM narratives will return to the income statement for repricing.