
NAURA Deep Dive: From Etch and Deposition to HBM Packaging Tools, How Advanced-Node Orders Can Push Through Expense Pressure
目录
Too Long; Didn't Read
1. NAURA's Real Change: The Etch and Deposition Base Is Extending Into Advanced Memory and HBM Tools
NAURA's Valuation Tension
2. Order Clues: The 2026 Trade Is Not the Profit Trough, but the Advance Ledger for Revenue Recognition
The 2026 Order and Revenue Evidence Chain
3. Product Lines: Etch and Deposition Are the Base; Advanced Memory and Kingsemi Are the Upside
Product Lines and Investment Implications
The Nature of the Equipment Business: It Sells Production-Line Certainty, Not Machines
4. Margin: Expense Pressure Is Not Noise, but the Admission Ticket for This Re-Rating
Broker Forecast Divergence on Margins
The Path to Margin Recovery
5. Valuation: The Higher the Target Price, the Less It Is Just "Applying a Higher PE"
Major Target Prices and Methodologies
Three Worldviews
6. Compared With Global Equipment Leaders: NAURA's Scarcity Comes From Its Platform Position in a Constrained Market
How to Read Peer Positioning
7. Financial Bridge: Revenue Growth Is Relatively Clear; Profit Quality Still Has Three Gates to Pass
Revenue Bridge: From Rmb30bn to Rmb60bn, Driven by Three Types of Orders
Profit Bridge: Three Variables Determine Whether 2027 EPS Can Be Revised Up
From Old Asset Attribute to New Asset Attribute
8. Risks and Falsification: Where This Report Could Be Wrong
Falsification Checklist
9. What to Watch Over the Next Four Quarters
Tracking Checklist
Signal Priority
Triggers for Upgrading or Downgrading the View
How Capital Will Price This
10. Conclusion: What Investors Are Buying Is 2027 Platform Conversion, Not a Perfect 2026 Income Statement
本内容基于公开资料和研报数据整理,不构成任何投资建议,不代表任何个人观点,仅供学习参考,请理性阅读
The key change at NAURA is not simply that it has won a few more domestic-substitution orders. It is that advanced logic, advanced memory, and a broader platform equipment portfolio are now jointly determining the revenue slope. The next test is whether high order growth can pass through the margin pressure created by R&D;, equity incentives, and new-product ramp-up. This is not just a one-quarter earnings recovery story.
Too Long; Didn't Read
Orders are the first signal. Multiple investment banks have shifted the NAURA trading narrative from current-period profit back to new orders: Goldman Sachs emphasizes that China semiconductor capex remains elevated, Citi focuses on advanced memory expansion, and Bernstein expects new orders for domestic equipment vendors to potentially reaccelerate to more than 50%. Short-term margin volatility has not disappeared, but orders have become the earlier variable.
Advanced nodes raise platform value. NAURA's story has moved from volume growth in standalone etch and deposition tools to coordination across etch, PVD/CVD, furnaces, cleaning, ion implantation, advanced packaging, and coat/develop track. J.P. Morgan expects the company's share of China WFE demand to have room to rise from about 10% in 2024 to about 20% in 2027, mainly because advanced logic and memory lines need platform suppliers more than mature nodes do.
Margin remains the biggest debate. 4Q25 and 1Q26 show that revenue growth does not automatically translate into profit release: R&D; expense, SG&A;, ESOP, new-product qualification, and customer price discounts can all weigh on net margin. Goldman Sachs is more constructive on gross margin stability, while Bernstein is more concerned about expenses and net margin. The disagreement centers on whether operating leverage can emerge after revenue scales.
2027 is the valuation-basis switch point. Brokers are broadly raising the revenue platform, but Goldman Sachs, J.P. Morgan, UBS, and Citi differ sharply on assumptions for 2027 net profit or EPS recovery. The market will only be willing to assign a higher multiple if, after 2026 orders convert, 2027 revenue recognition and a lower expense ratio appear at the same time.
Memory is the new source of upside. UBS focuses on the significance of 90:1 high-aspect-ratio etch for 300-plus-layer 3D NAND, Citi focuses on the release of China advanced memory orders starting in 2Q26, and Goldman Sachs has written 3D NAND/DRAM tools and HBM hybrid bonding into the company's 2026 product roadmap. If memory moves from qualification to scaled procurement, NAURA's TAM will expand materially.
The falsification path is also straightforward. Over the next four quarters, watch five numbers: new-order growth, the share of advanced logic and advanced memory orders, whether gross margin returns above 40%, whether R&D; and SG&A; ratios peak, and whether ESOP expense is digested in a one-off manner by the end of 2026 as expected. If orders are strong but gross margin and expense ratios keep deteriorating, the platform story will be pulled back into the old problem of "trading scale for profit."
1. NAURA's Real Change: The Etch and Deposition Base Is Extending Into Advanced Memory and HBM Tools
The part of NAURA most worth revaluing now is that it is starting to move from "domestic equipment leader" to a "gatekeeper asset" for whether advanced production lines can ramp smoothly. Semiconductor equipment stocks usually first trade capex, then orders, then revenue, and only then margins. NAURA's volatility over the past two years is exactly the result of these four variables becoming misaligned.
In 2Q25, Morgan Stanley saw seasonality and revenue-recognition timing: the company reported revenue of Rmb7.9bn, down 3.3% QoQ and up 22.5% YoY, below its forecast and consensus expectations; gross margin was 41.3%, down 1.7 percentage points QoQ and 6.1 percentage points YoY. But that same report did not frame it as a demand inflection point, because the company's full-year revenue target was unchanged, while etch equipment and deposition equipment accounted for 31% and 40% of 1H25 revenue, respectively, and the order pipeline still pointed to strong WFE conditions in 2H25 and 1H26.
By 2026, the disagreement became clearer. In 1Q26, NAURA revenue was Rmb10.323bn, up 26% YoY, while gross margin rebounded from the 4Q25 low to about 40.8%-41%; however, net margin remained below some institutions' expectations. The revenue side shows demand is still there, while the profit side shows that conversion is not smooth. The real question is not "are there orders," but which customers, process nodes, and product categories the orders come from, and how long they will take to become high-quality profit.
The WFE Supercycle Has Just Begun: How AI Capex Is Pushing Semiconductor Equipment Toward US$250bn
NAURA's product breadth is the starting point for this re-rating. Under the company's official website classification, NAURA's semiconductor equipment covers process equipment and core components such as etchers, PVD, ALD, CVD, oxidation/diffusion furnaces, cleaning tools, and gas mass-flow controllers, with applications in integrated circuits, advanced packaging, power semiconductors, compound semiconductors, and other areas. Investment-bank materials further extend this to ion implantation, advanced packaging, HBM hybrid bonding, and the coat/develop track segment filled in through Kingsemi.
In the equipment industry, single-product breakthroughs and platform supply are not the same thing. A single-product breakthrough can explain revenue growth in a given year. Platform supply explains why customers at more advanced, more constrained, and more complex line-debugging nodes give more orders to the same supplier. The higher capex becomes in advanced logic and advanced memory, the less willing customers are to split every critical step among unfamiliar suppliers. The more steps an equipment vendor can cover, the easier it is to win systematic share.
NAURA's Valuation Tension
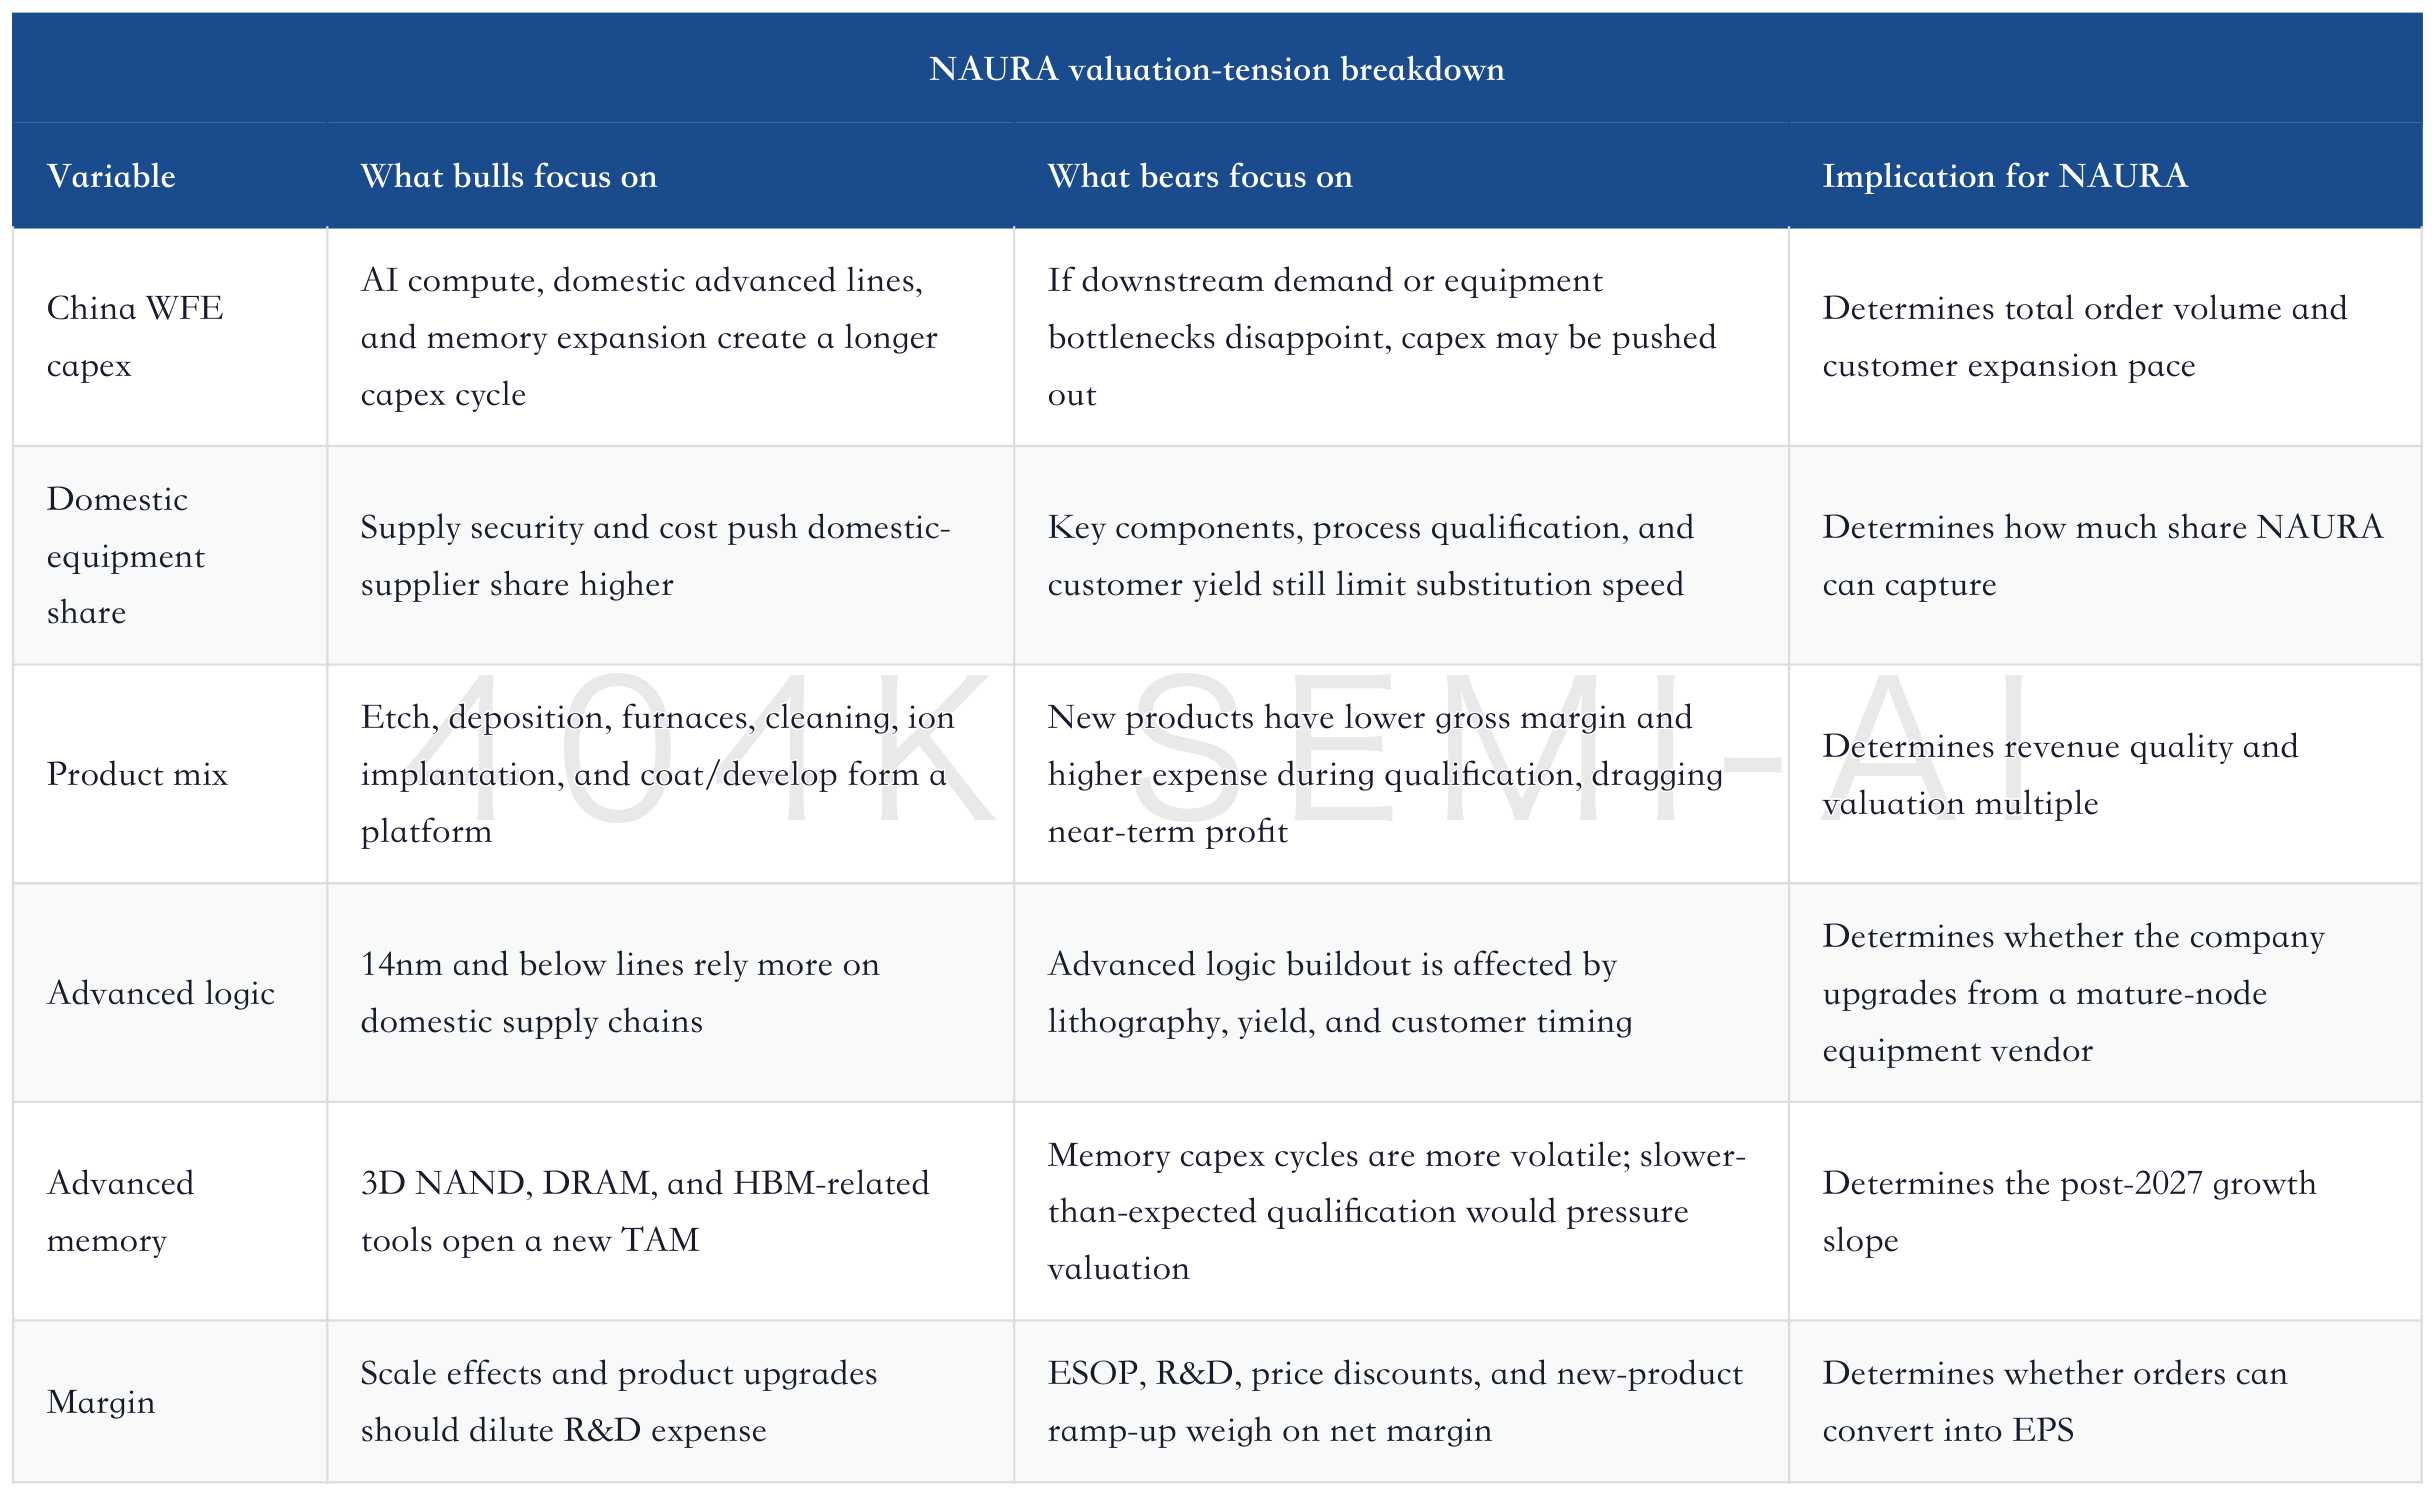
The most important point in this table is not a single quarter's EPS, but whether "total orders, share, product mix, and expense ratio" can all move in the same direction. If the first three variables are moving up, the expense ratio is only a matter of time. If orders come from low-margin, highly competitive products with long qualification cycles, high revenue growth can still be eaten away by margin pressure.
2. Order Clues: The 2026 Trade Is Not the Profit Trough, but the Advance Ledger for Revenue Recognition
The most common mistake with equipment companies is to treat revenue as demand itself. In reality, NAURA's demand first appears in customer expansion plans and new orders, then becomes financial-statement revenue through delivery, acceptance, and revenue recognition. Bernstein's explanation of 1Q26 is representative: revenue was Rmb10.3bn, up 26% YoY and down 14% QoQ, but this largely corresponds to 1Q25 orders, with a revenue-recognition cycle of about one year; what is really worth trading is 1Q26 new-order growth, which is expected to be meaningfully faster than revenue growth.
This point is critical for NAURA. If revenue recognition lags by about 12 months, 2026 new orders determine the 2027 revenue curve, and the 2027 revenue curve determines whether the market is willing to shift valuation away from "current margin pressure" and back to "order-driven growth stock." That is also why, despite seeing 1Q26 net margin below expectations, Bernstein still maintained Outperform and focused on order growth.
Citi's May 2026 company-day notes provided another set of leading indicators: management believed China advanced memory capacity could rise from about 80,000 wafers per month in 2025 to about 120,000 wafers per month in 2026, with 2027 potentially more aggressive; about 60% of 1Q26 new orders came from advanced logic customers, while advanced memory orders started to show from 2Q26. This information moves NAURA from a pure "mature-node domestic substitution" story to a dual narrative of "advanced logic plus memory expansion."
From HBM to WFE: How AI Turns the Memory Cycle Into an Equipment Supercycle, and How Much Further Semiconductor Equipment Can Run
Goldman Sachs' May 2026 report amplifies this line further: it expects China semiconductor capex of about US$44.6bn and US$44.9bn in 2026 and 2027, respectively. The domestic AI supply chain and ecosystem, including compute and HBM, are important reasons capex remains elevated. NAURA is not benefiting from the expansion of a single customer, but from logic, memory, and advanced packaging all pushing customers to qualify domestic SPE tools.
There are three layers of meaning behind high order growth. The first is total volume: the pool of China equipment procurement remains large. The second is structure: advanced logic and memory are more capital-intensive than mature nodes. The third is share: domestic suppliers have more qualification opportunities in constrained segments. Only when all three are true does NAURA move from "having orders" to "lifting both share and valuation."
The 2026 Order and Revenue Evidence Chain
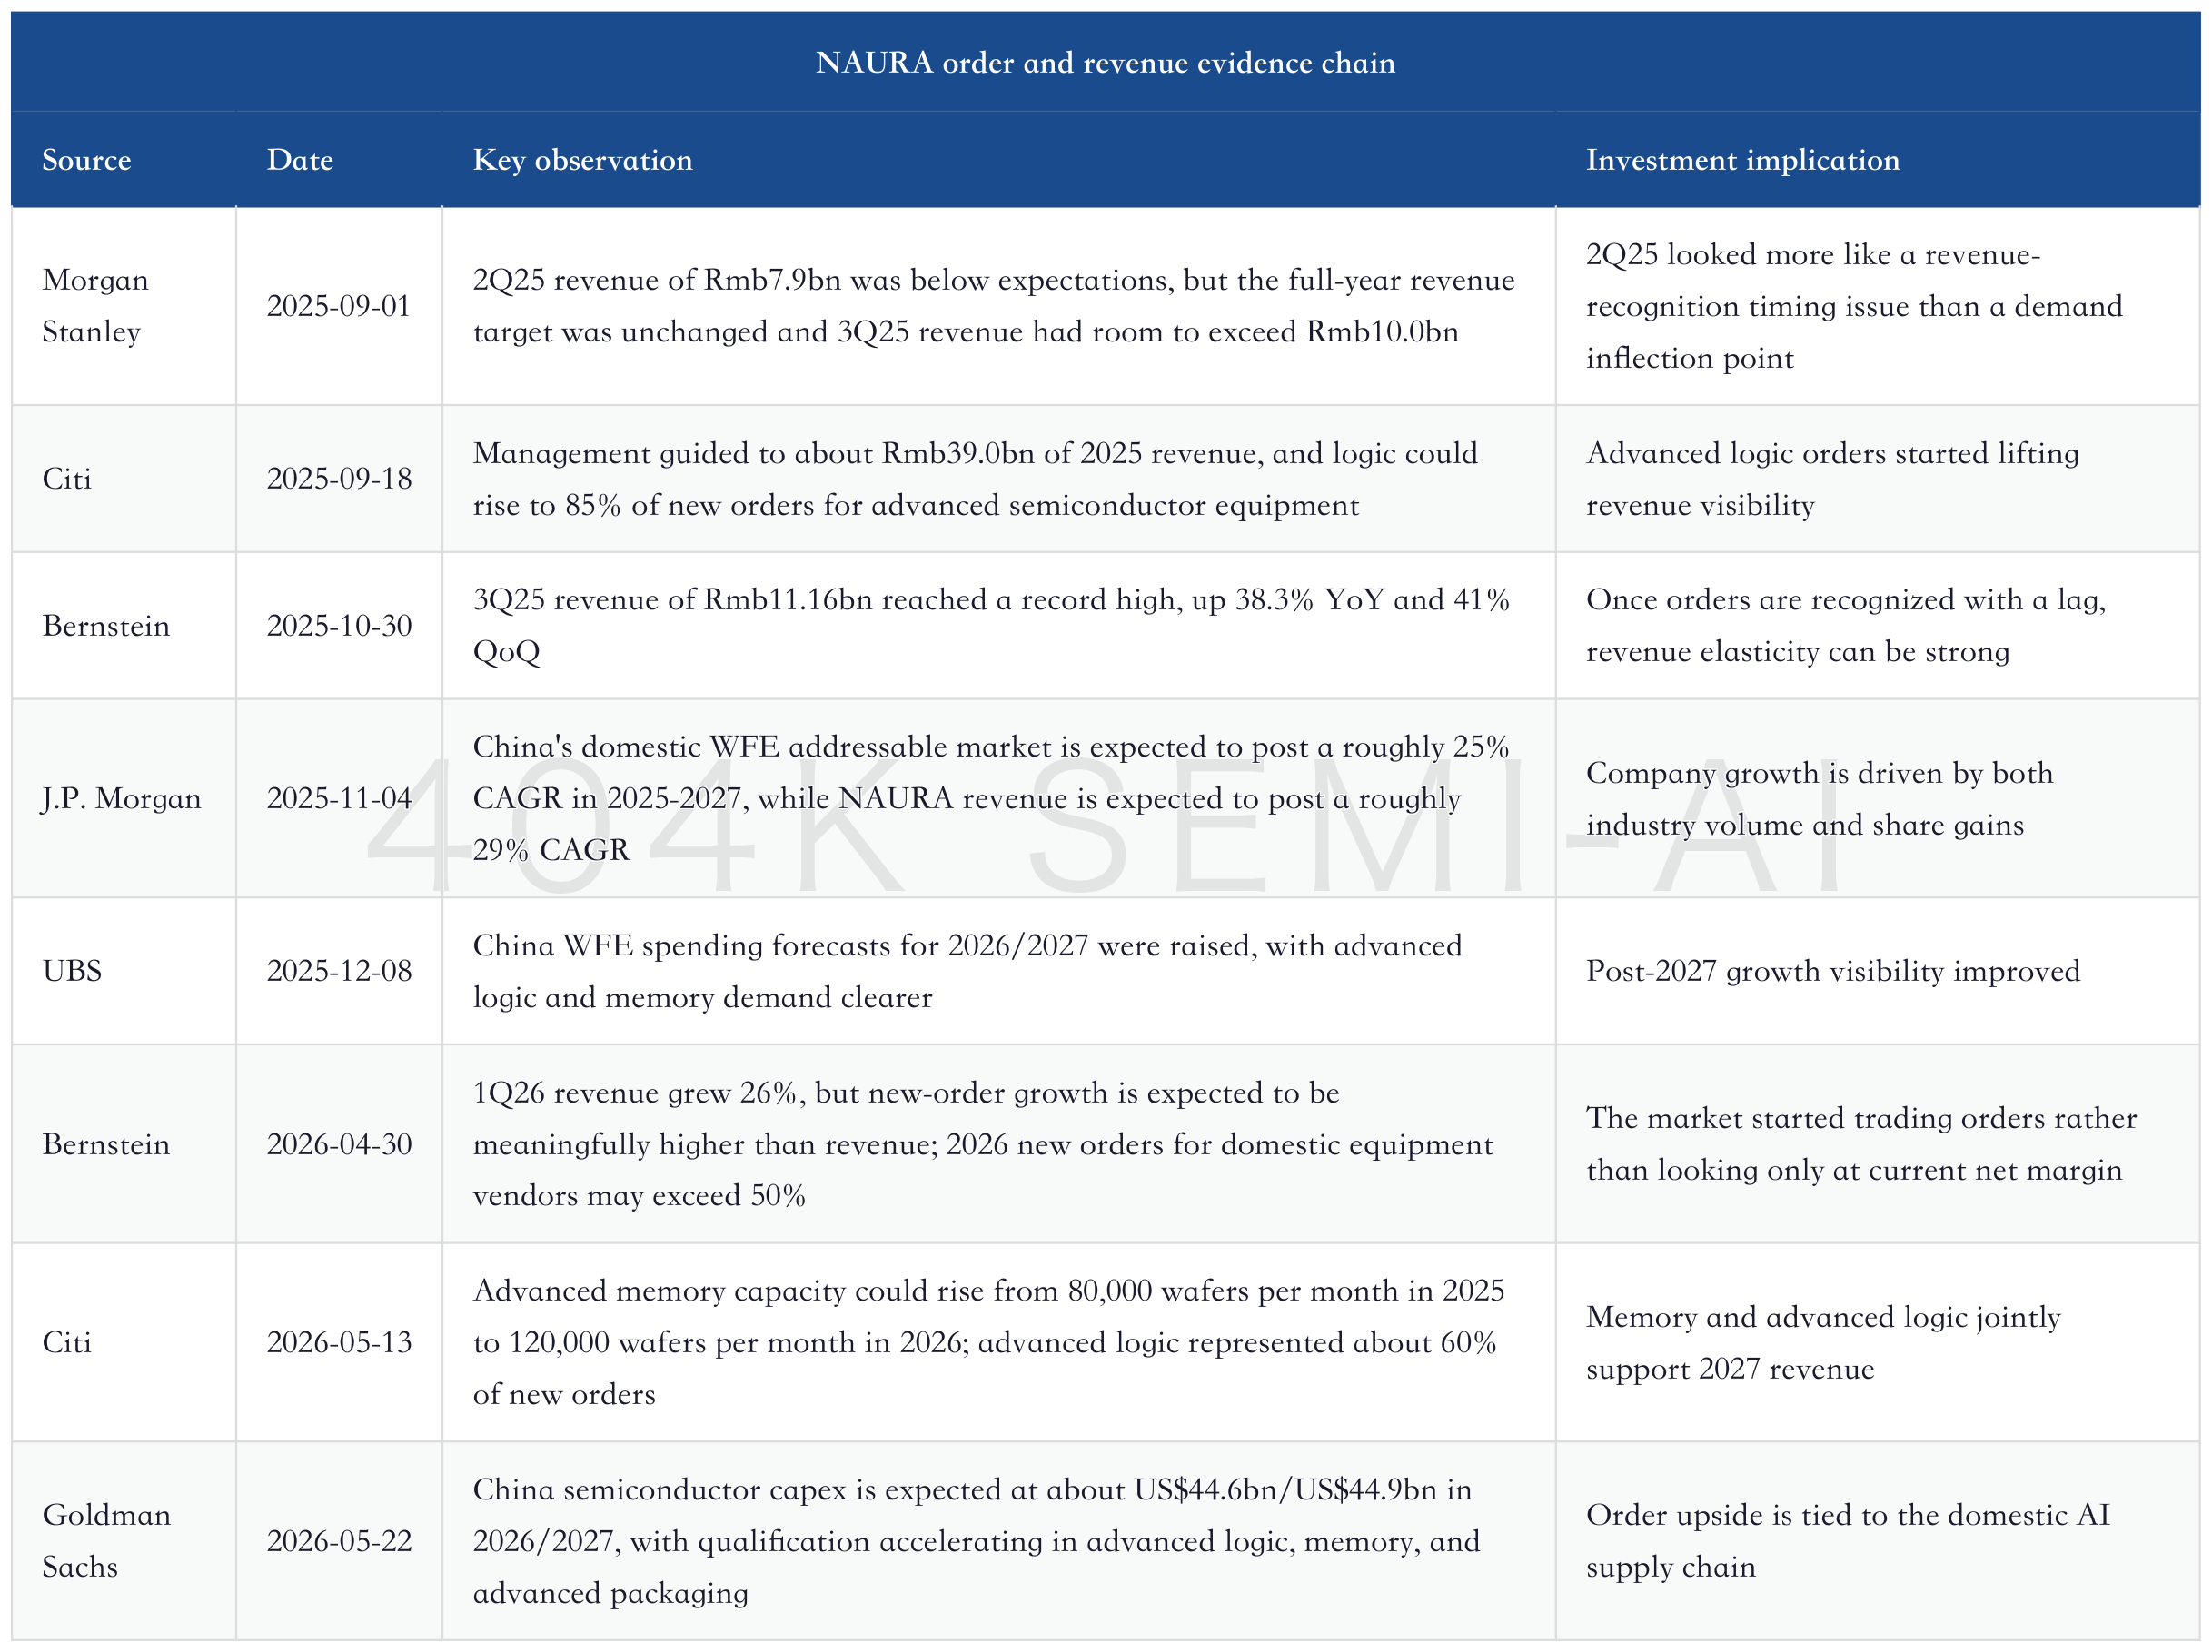
This evidence chain shows that NAURA did not suddenly begin to have demand in 2026. Rather, orders, capacity, and product upgrades since 2025 have gradually converged. Market disappointment with margins in 4Q25 and 1Q26 reflected expense release coming before revenue recognition. But if 2026 orders do reaccelerate, the weakness in the income statement will lag the repair in the balance sheet and order book.
3. Product Lines: Etch and Deposition Are the Base; Advanced Memory and Kingsemi Are the Upside
NAURA's first layer of foundation is still etch and deposition. Morgan Stanley estimates that in 1H25, etch equipment represented about 31% of company revenue and deposition equipment about 40%. J.P. Morgan also views the company's share in dry etch and thin-film deposition as its core advantage versus domestic peers. The reason is simple: both sit in core front-end processes. They benefit from mature-node expansion and are also more likely to see higher process difficulty from advanced logic and advanced memory.
Deposition and etch are not ordinary manufacturing equipment. They directly affect film uniformity, pattern transfer, critical-dimension control, and yield. As advanced logic nodes progress, there are more etch steps and narrower process windows; as 3D NAND layer counts rise, high-aspect-ratio etch becomes harder; as DRAM and HBM-related flows upgrade, coordination across thin film, thermal processing, cleaning, and packaging equipment also increases. NAURA's value lies in the fact that it is not only exposed to one step, but to the rising complexity of the entire production line.
UBS's view on 3D NAND deserves separate attention. Its December 2025 report focused on NAURA's progress in 90:1 high-aspect-ratio etch, arguing that this type of equipment is a key tool for 300-plus-layer 3D NAND. If this qualification progress becomes orders, the market NAURA can access will no longer be limited to logic expansion and mature nodes, but will include high-value segments created by higher-layer-count memory iteration.
Goldman Sachs' May 2026 report presents a more complete new-product roadmap: next-generation logic equipment, advanced tools for 3D NAND/DRAM, HBM hybrid bonding tools, and new categories such as ion implantation. This shows that NAURA is expanding its product mix from "etch plus deposition" into an "advanced-node platform." The benefit of platformization is a higher share ceiling; the cost is that R&D;, qualification, and delivery costs enter the income statement earlier.
Product Lines and Investment Implications
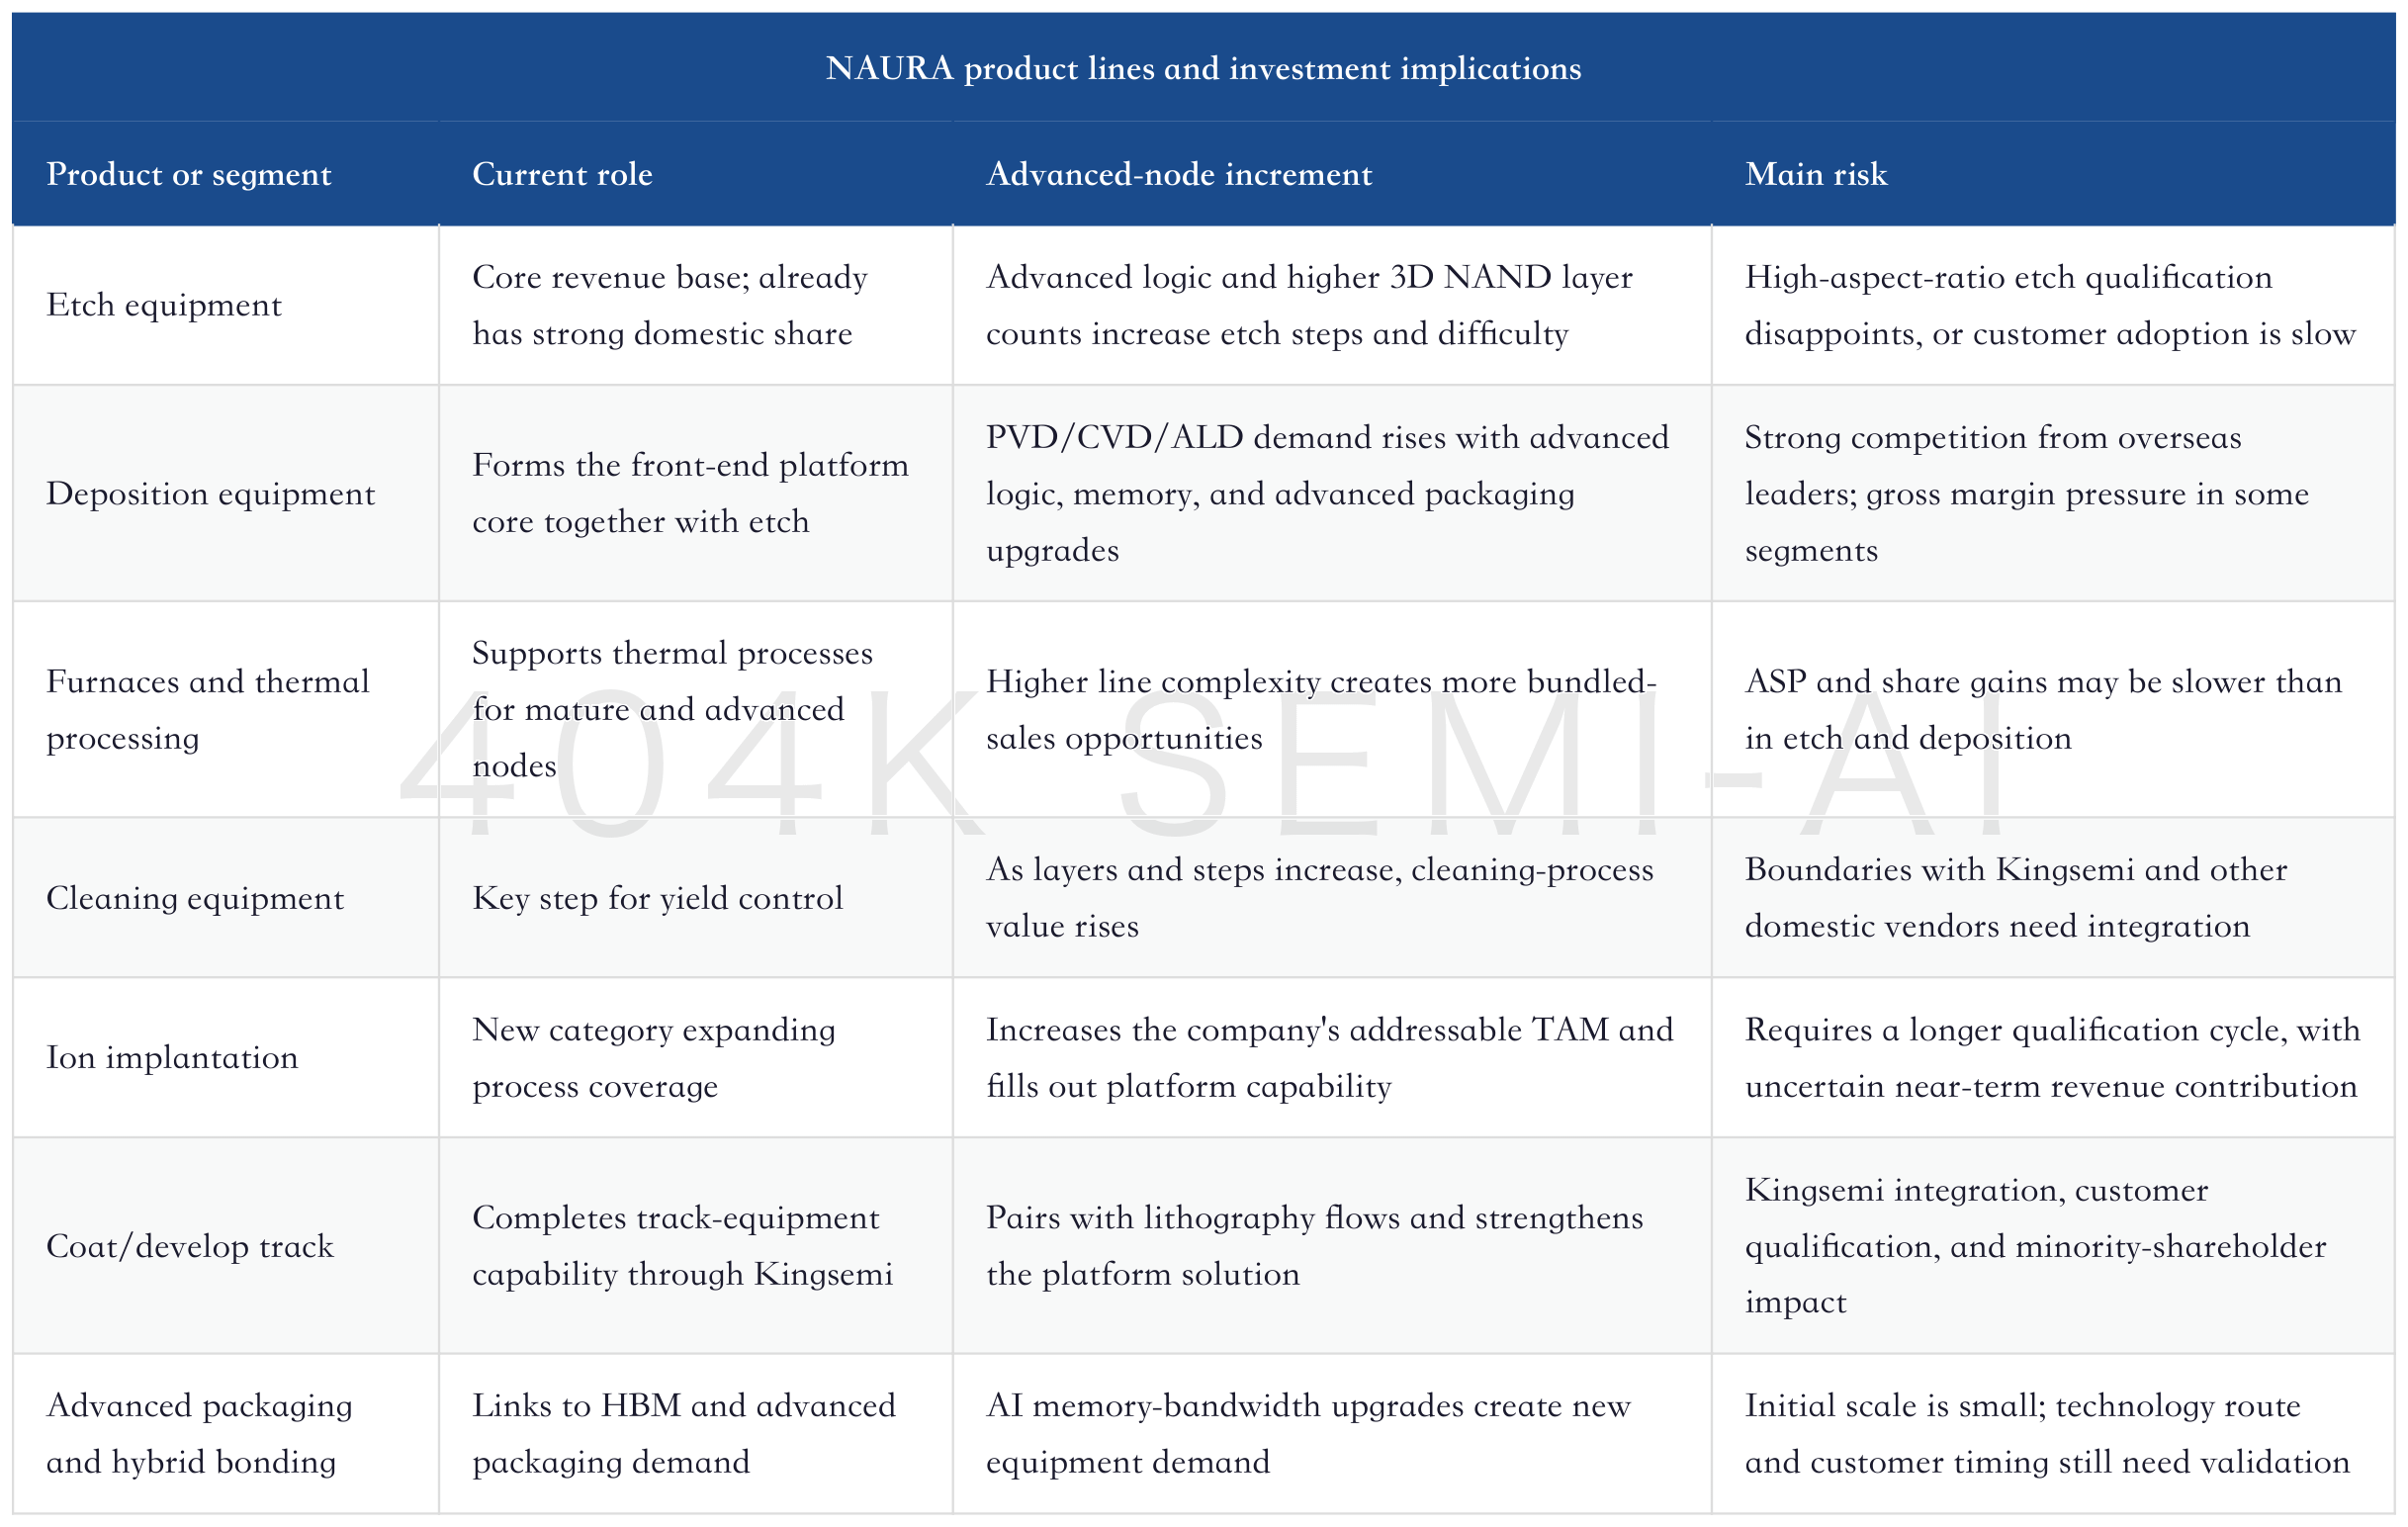
The most important column in this table is "advanced-node increment." If growth only came from mature-node expansion, NAURA could certainly still grow, but the valuation would not be especially scarce. The value of platform suppliers rises only if advanced logic, memory, and advanced packaging all require more domestic tools. In other words, the company's future pricing power comes from "more process steps that customers cannot bypass," not from the localization rate of a single piece of equipment.
China Semiconductors 2026: From Domestic Substitution to Compute Re-Rating Across the Supply Chain
Kingsemi is an easily underestimated part of this platform story. J.P. Morgan views NAURA's acquisition of control over Kingsemi as an important step in filling the coat/develop equipment gap and improving integrated platform capability. Coat/develop has long been dominated globally by leaders such as Tokyo Electron, and NAURA's coverage in this segment was previously incomplete. After consolidating Kingsemi, the company can place etch, deposition, cleaning, thermal processing, and track equipment into a single customer solution.
The near-term issues of the acquisition cannot be ignored. Kingsemi's revenue recognition, inventory, contract liabilities, minority interests, and product qualification will all make the financial statements more complex. A platform acquisition does not immediately enhance net margin and may even dilute margin first. But for advanced-line customers, whether a supplier can provide more steps, faster debugging, and more stable delivery matters more than one quarter's margin.
The Nature of the Equipment Business: It Sells Production-Line Certainty, Not Machines
To understand NAURA, it is best to first unpack the word "equipment." When a fab buys equipment, on the surface it is buying etchers, deposition tools, furnaces, cleaning machines, and coat/develop equipment. In substance, it is buying yield, delivery time, debugging experience, spare-parts supply, and process-iteration speed. What customers really fear is not that a single tool is slightly more expensive, but that a bottleneck in one step prevents the entire line from ramping as planned.
This is also why advanced nodes lift the value of platform suppliers more than mature nodes do. Mature-node process windows are wider, and customers can combine more suppliers. Advanced logic and high-layer-count memory have narrower process windows, and instability in any one step transmits into yield, capacity utilization, and customer shipments. Once a supplier enters more critical process steps, it is no longer merely selling equipment; it is sharing mass-production risk with the customer.
NAURA's opportunity comes from this risk-sharing. Etch, deposition, thermal processing, cleaning, coat/develop, and advanced packaging are separate equipment categories when viewed in isolation. Viewed together, they are multi-point support for whether an advanced line can be tuned on schedule. The more customers emphasize delivery certainty, the more likely they are to give additional steps to suppliers that have already proved service capability, process understanding, and delivery cadence. This is where the commercial value of platformization lies.
This also explains why NAURA's R&D; expense should not be understood only as "higher expense." R&D; investment in semiconductor equipment is often prepayment for future customer-adoption eligibility. Without enough engineers, application teams, and on-site debugging experience, equipment can struggle to run stably in customer fabs even if technical metrics are close. Part of NAURA's current expense-ratio pressure is exactly the upfront investment required before advanced-node adoption.
The issue is that investment must generate returns. If R&D; expense brings more advanced logic and memory orders, the market will treat it as an admission ticket. If R&D; merely sustains competition in old products, the market will treat it as profit erosion. The dividing line is whether the order structure is upgrading, not the absolute level of expense.
Customer adoption also has its own rhythm. Semiconductor equipment is not consumer electronics; customers do not immediately replace critical tools because one quote is cheaper. Equipment has to pass small-batch qualification, process-window qualification, stability testing, yield ramp-up, and repeat mass-production purchases. Many of NAURA's high-end tools are now in the middle stage between qualification and volume ramp, so the income statement sees expense first, the order book sees opportunity first, and the revenue statement recognizes later.
This lag is important for investment judgment. Investors who only look at current-quarter net margin can easily misread the adoption period; investors who only look at orders can easily ignore the risk of failed qualification. The right approach is to split customer adoption into four steps: sample-tool qualification, small-batch orders, repeat orders, and cross-line replication. Only at steps three and four does NAURA's advanced-node story truly enter the profit-realization stage.
From the customer perspective, NAURA's biggest attraction is not "cheap" but "controllable." In advanced-capacity construction, controllable delivery, service, upgrades, and spare parts matter more than the initial price of a single tool. When customers give domestic equipment vendors qualification opportunities, they are essentially assigning value to supply-chain resilience. Whether equipment vendors can turn this opportunity into long-term share depends on whether stable delivery can replace one-off introduction.
This is also what differentiates NAURA from ordinary manufacturing companies. In ordinary manufacturing, more capacity after expansion may bring price competition. In semiconductor equipment, once a vendor enters customers' critical processes, follow-on service, spare parts, software upgrades, and process iteration create stronger stickiness. NAURA's real future profit upside is not only new-equipment sales, but also repeat purchases from installed customers and cross-category adoption.
Therefore, NAURA's operating quality should be evaluated across three layers. The first is revenue growth, which shows that equipment has been sold. The second is gross-margin stability, which shows that equipment has not entered purely through low pricing. The third is a declining expense ratio, which shows platform capability is starting to be reused. Only when all three appear can NAURA upgrade from a high-order-growth company into a high-quality equipment platform.
This business logic also explains why broker target prices diverge so widely. Optimistic institutions believe NAURA has already entered the platform-reuse stage, with expenses to be diluted by revenue. Conservative institutions worry the company is still in customer qualification, with expenses continuing to be front-loaded. The two sides are not debating one quarter's profit; they are debating where the company sits on the adoption curve.
In one sentence: NAURA's valuation ceiling depends on whether it can turn "customers are willing to try it" into "customers cannot do without it." The trial stage is about orders; the indispensable stage is about margins. Today's NAURA is already beyond the stage of only watching trials, but has not fully entered the indispensable stage. That is exactly why it is in its most elastic and most volatile position.
4. Margin: Expense Pressure Is Not Noise, but the Admission Ticket for This Re-Rating
When analyzing NAURA, the margin issue cannot be dismissed as a "short-term disturbance." Expense pressure in 4Q25 and 1Q26 shows the company has entered a more investment-intensive phase. R&D; expense, SG&A;, equity incentives, new-product qualification, customer discounts, and acquisition integration hit the income statement before revenue is fully recognized.
UBS's description of 4Q25 was direct: revenue still grew, but net profit was significantly below expectations because R&D;, selling, and administrative expenses rose materially, while 4Q25 gross margin fell to 37.2%. By 1Q26, gross margin recovered to about 40.8%-41%, but net margin was still weighed down by expenses. Goldman Sachs also wrote in its 1Q26 report that revenue was broadly in line with expectations and gross margin improved, but net profit was below its forecast because of the R&D; expense ratio.
Bernstein's concern is more structural. In 3Q25, it already noted that revenue reached a record high but gross margin had been below expectations for several quarters, possibly related to advanced logic new-product ramp-up, product mix, and competition. By 1Q26, Bernstein still believed elevated expenses caused net margin to miss expectations again, but viewed this as an earnings-expectation reset: if the market has already incorporated near-term margin pressure into valuation, the subsequent trade will return to order growth.
This is the subtle part of NAURA: R&D; and expenses are both near-term bad news and prerequisites for long-term good news. Without R&D; investment, the company cannot enter more advanced etch, deposition, ion implantation, hybrid bonding, and high-aspect-ratio 3D NAND tools. But if R&D; investment never converts into gross margin and scale effects, valuation will move from "platform expansion" back to "burning money for revenue."
Broker Forecast Divergence on Margins
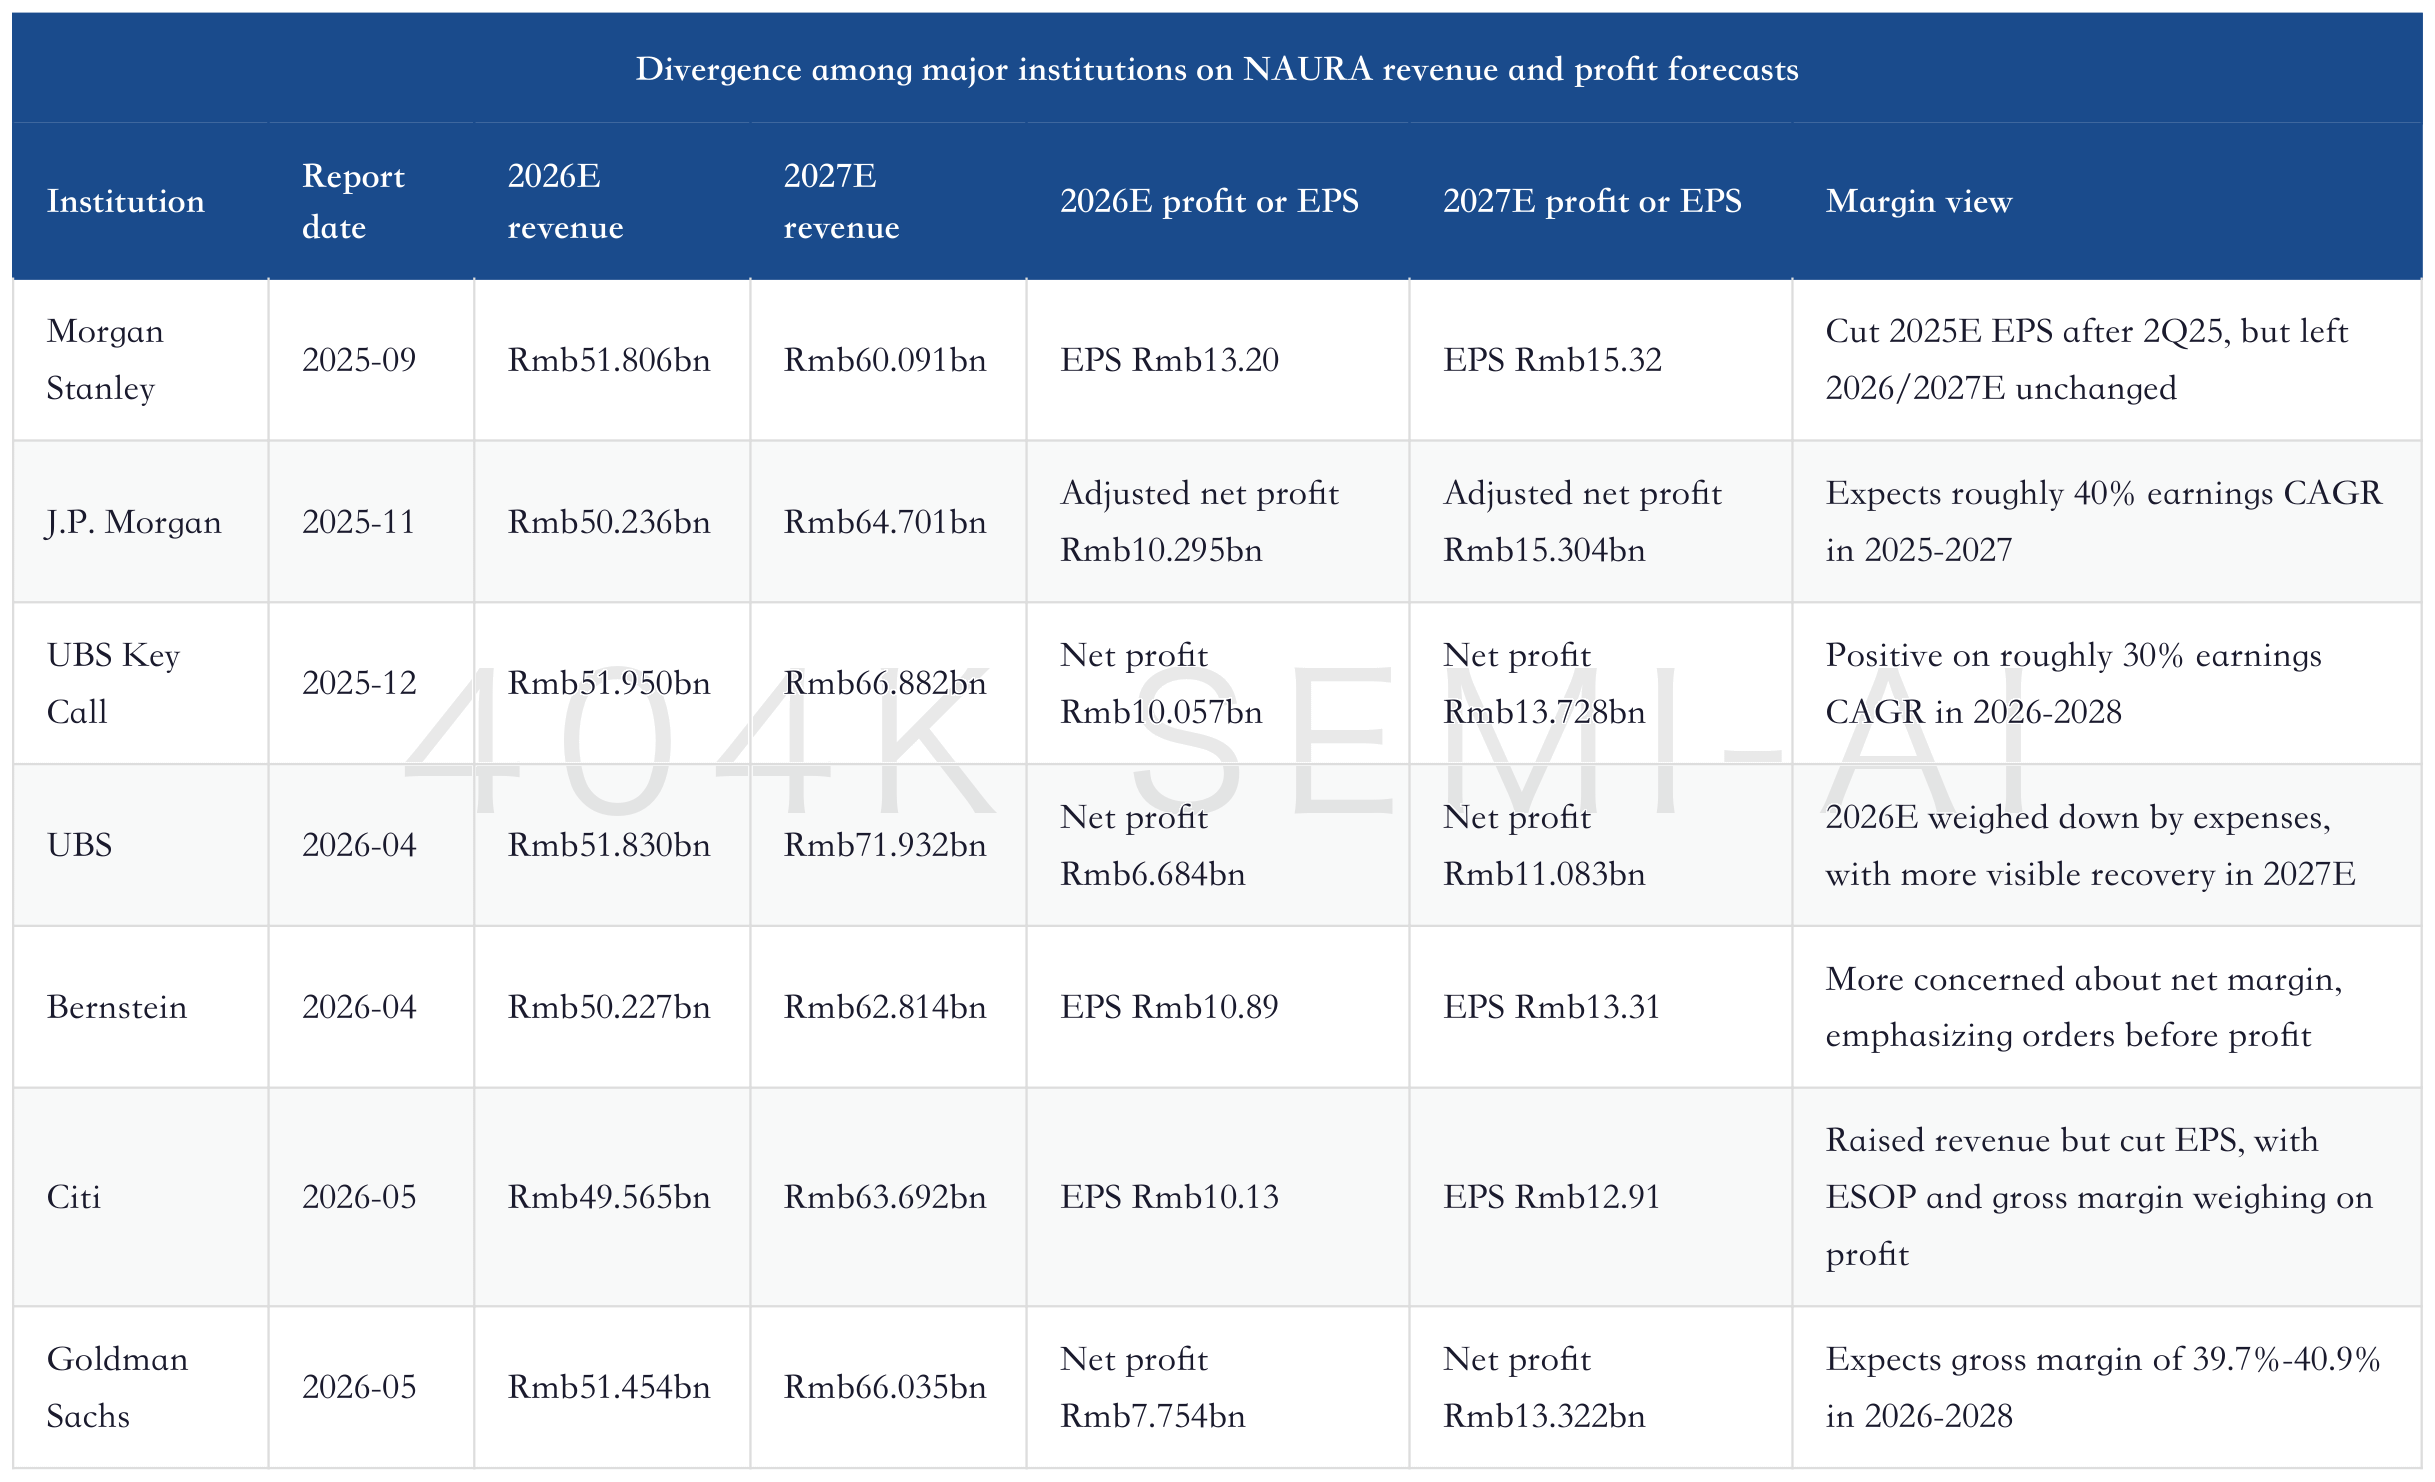
The table supports two conclusions. First, revenue disagreement is not large: mainstream forecasts cluster around Rmb50bn for 2026 and roughly Rmb63bn-Rmb67bn for 2027, which means the market is relatively aligned on the direction of order and revenue growth. Second, profit disagreement is large: the divergence in 2026 net profit or EPS reflects different assumptions on expense ratios, equity incentives, gross margin, and revenue-recognition timing.
This is also why a single target price is not enough. Goldman Sachs puts NAURA's 2027E net profit at Rmb13.3bn, J.P. Morgan's adjusted net profit is Rmb15.3bn, UBS's April version is lower on 2027E net profit, and Citi and Bernstein are more conservative on EPS. Similar revenue lines but diverging profit lines show that the true swing factor is operating leverage.
The Path to Margin Recovery
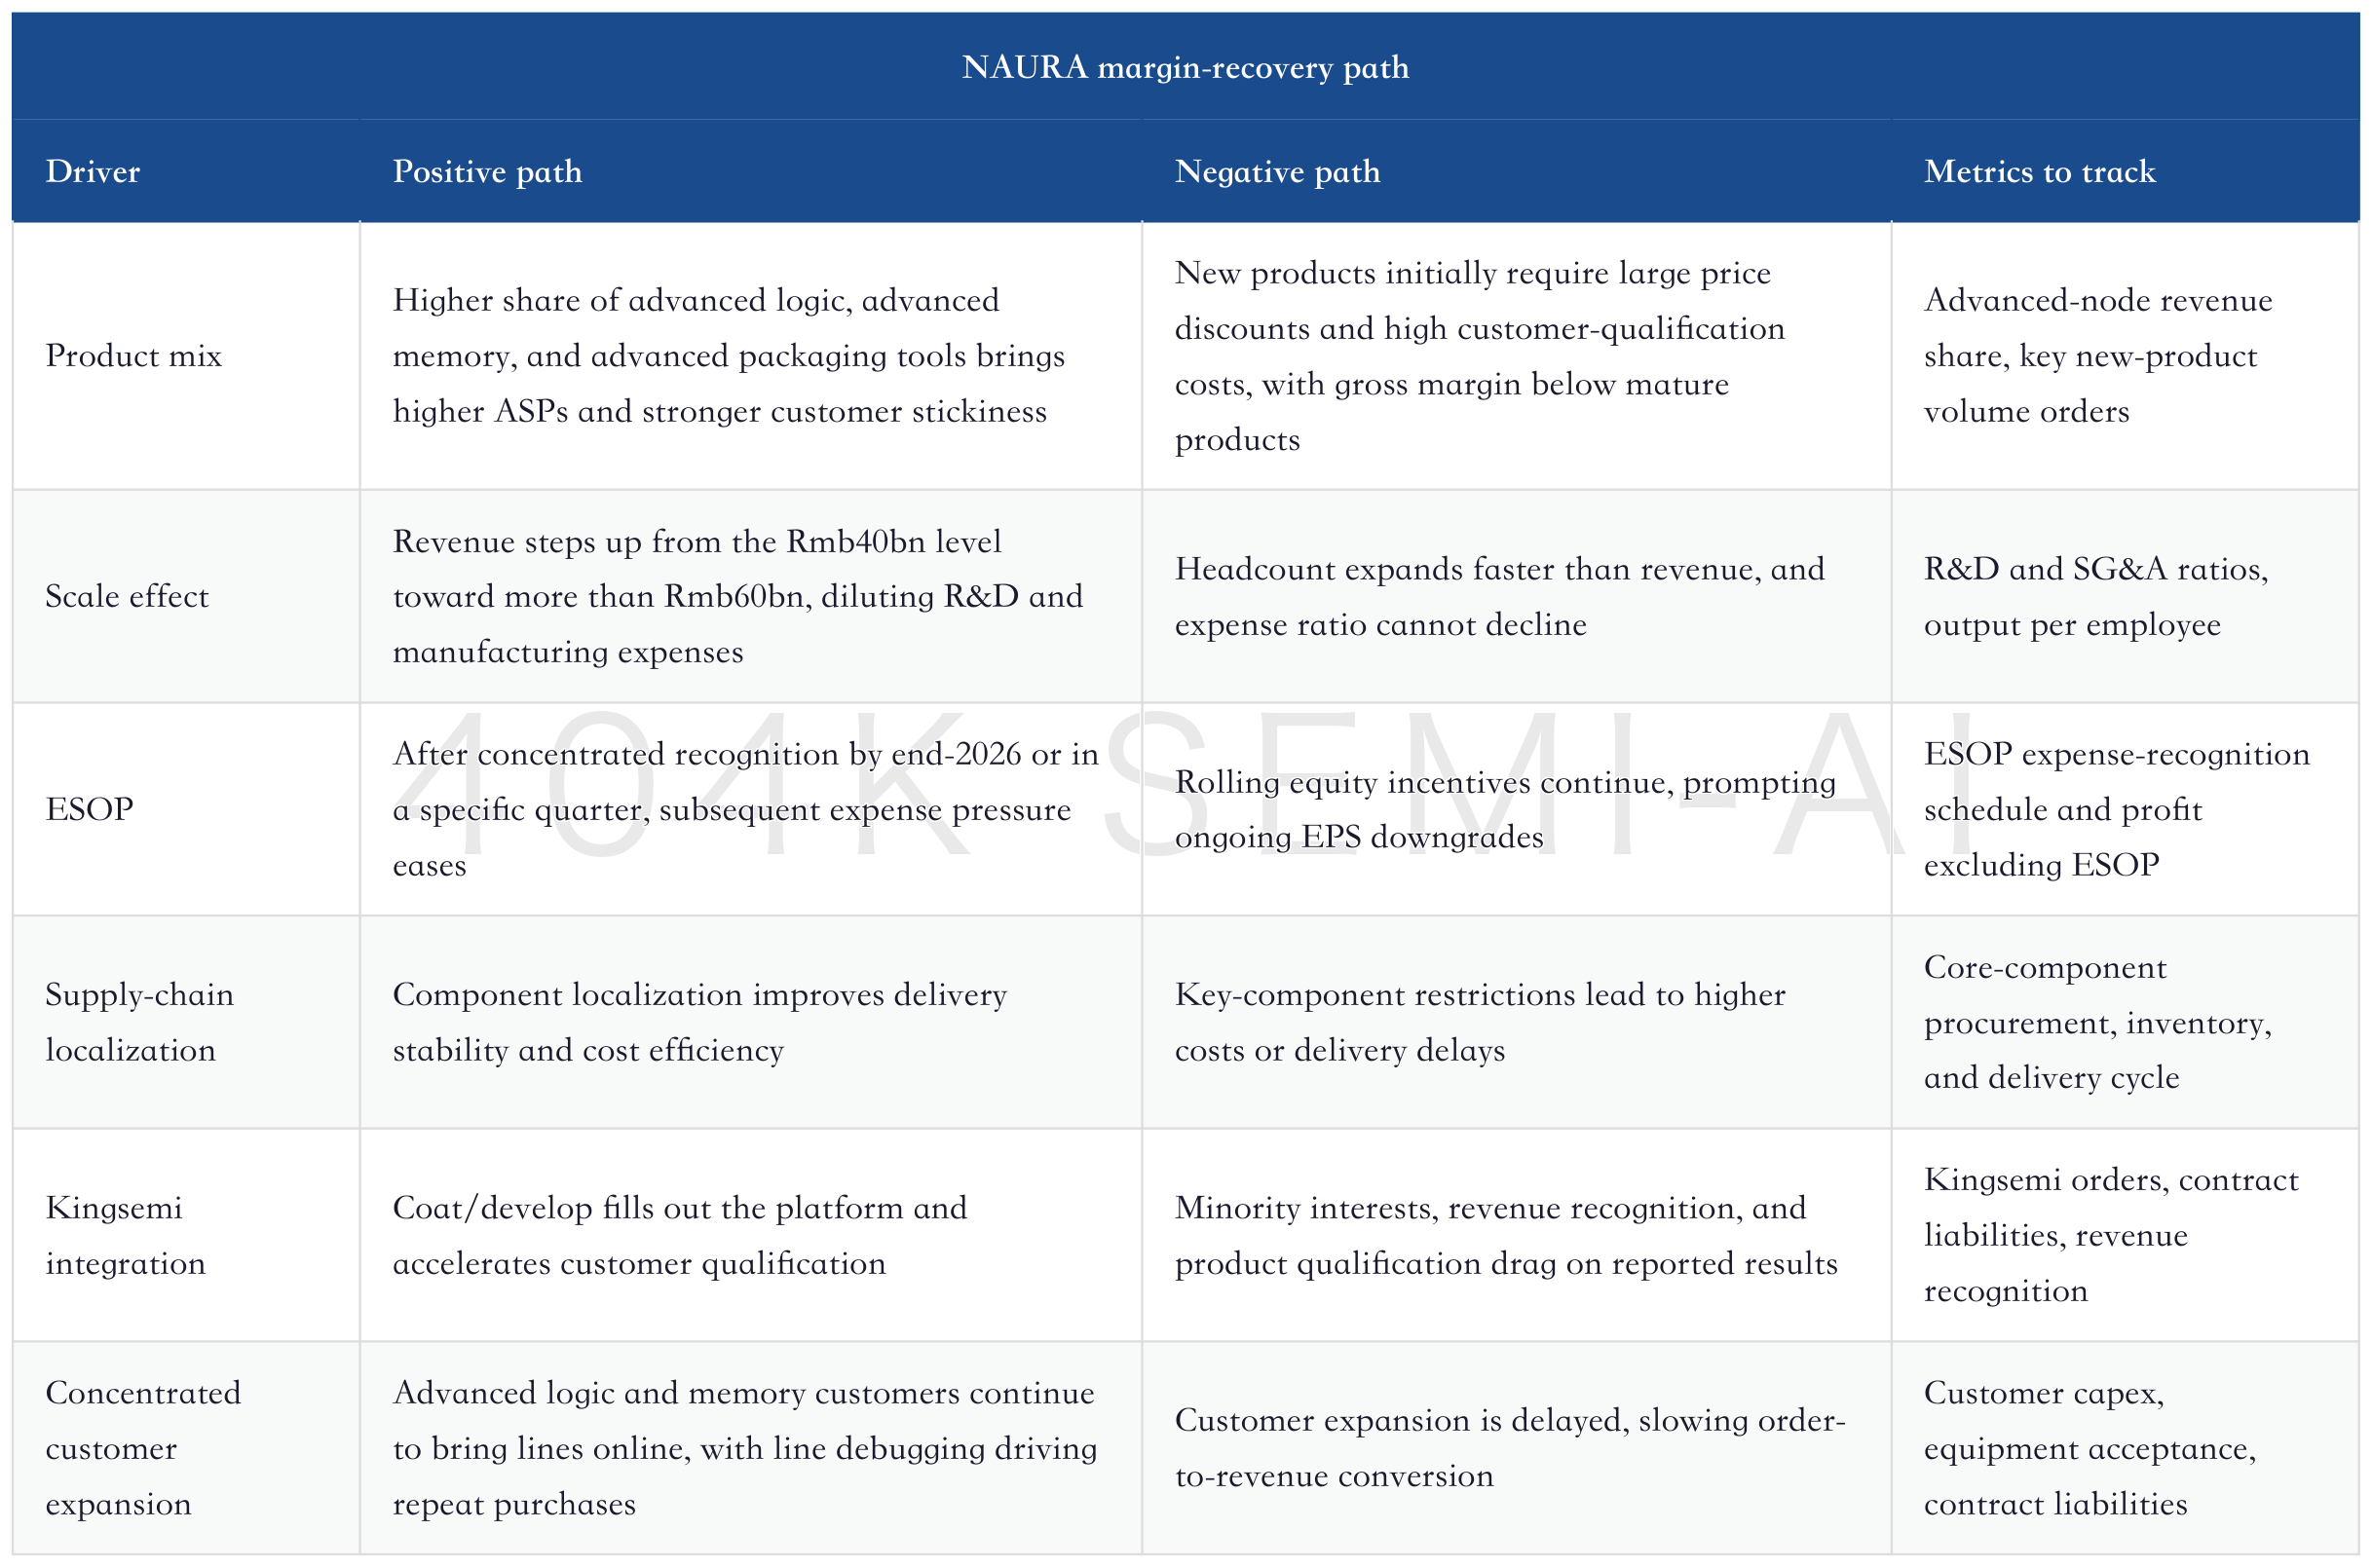
Margin recovery has to come from these six variables together. The best case is: 2026 orders grow strongly, 2027 revenue recognition scales, the expense ratio starts to decline, and the share of advanced-node products rises. The worst case is: orders are not scarce, but new-product discounts, R&D; expense, and customer-qualification costs continue to consume gross profit, so revenue growth instead dilutes valuation.
5. Valuation: The Higher the Target Price, the Less It Is Just "Applying a Higher PE"
NAURA's current valuation debate is not about one investment bank's target price, but about which framework the market is willing to use. In 2H25, Morgan Stanley and Bernstein were still more focused on 2025/2026 EPS and near-term gross margin. By May 2026, Goldman Sachs, Citi, and industry models had already shifted the valuation base to 2027 or even further out.
There is a clear logic behind this. If NAURA is only a high-growth equipment company with volatile margins, the market will focus on current PE. If it becomes an equipment platform for advanced logic, memory, and advanced packaging, the market will be willing to look at 2027 revenue, order visibility, and WFE scenario models. The latter carries a higher multiple, but also higher requirements.
Target prices cannot be compared mechanically. Different report dates, share-price bases, forecast years, and valuation methods mean target-price levels are not a simple ranking of optimism. For example, Morgan Stanley's Rmb450 was based in September 2025 on a residual-income model and a 2025E EPS scenario; UBS's Rmb587.50 in December 2025 used 2026E P/BV and mid-cycle ROE; Citi's Rmb695 in May 2026 shifted to 2027E P/S; and Goldman Sachs' Rmb818 used 2027E PE and a China SPE re-rating.
Equipment Capex Ledger Update: AI Financing, US$250bn WFE, and the Re-Pricing of Semiconductor Equipment
Major Target Prices and Methodologies
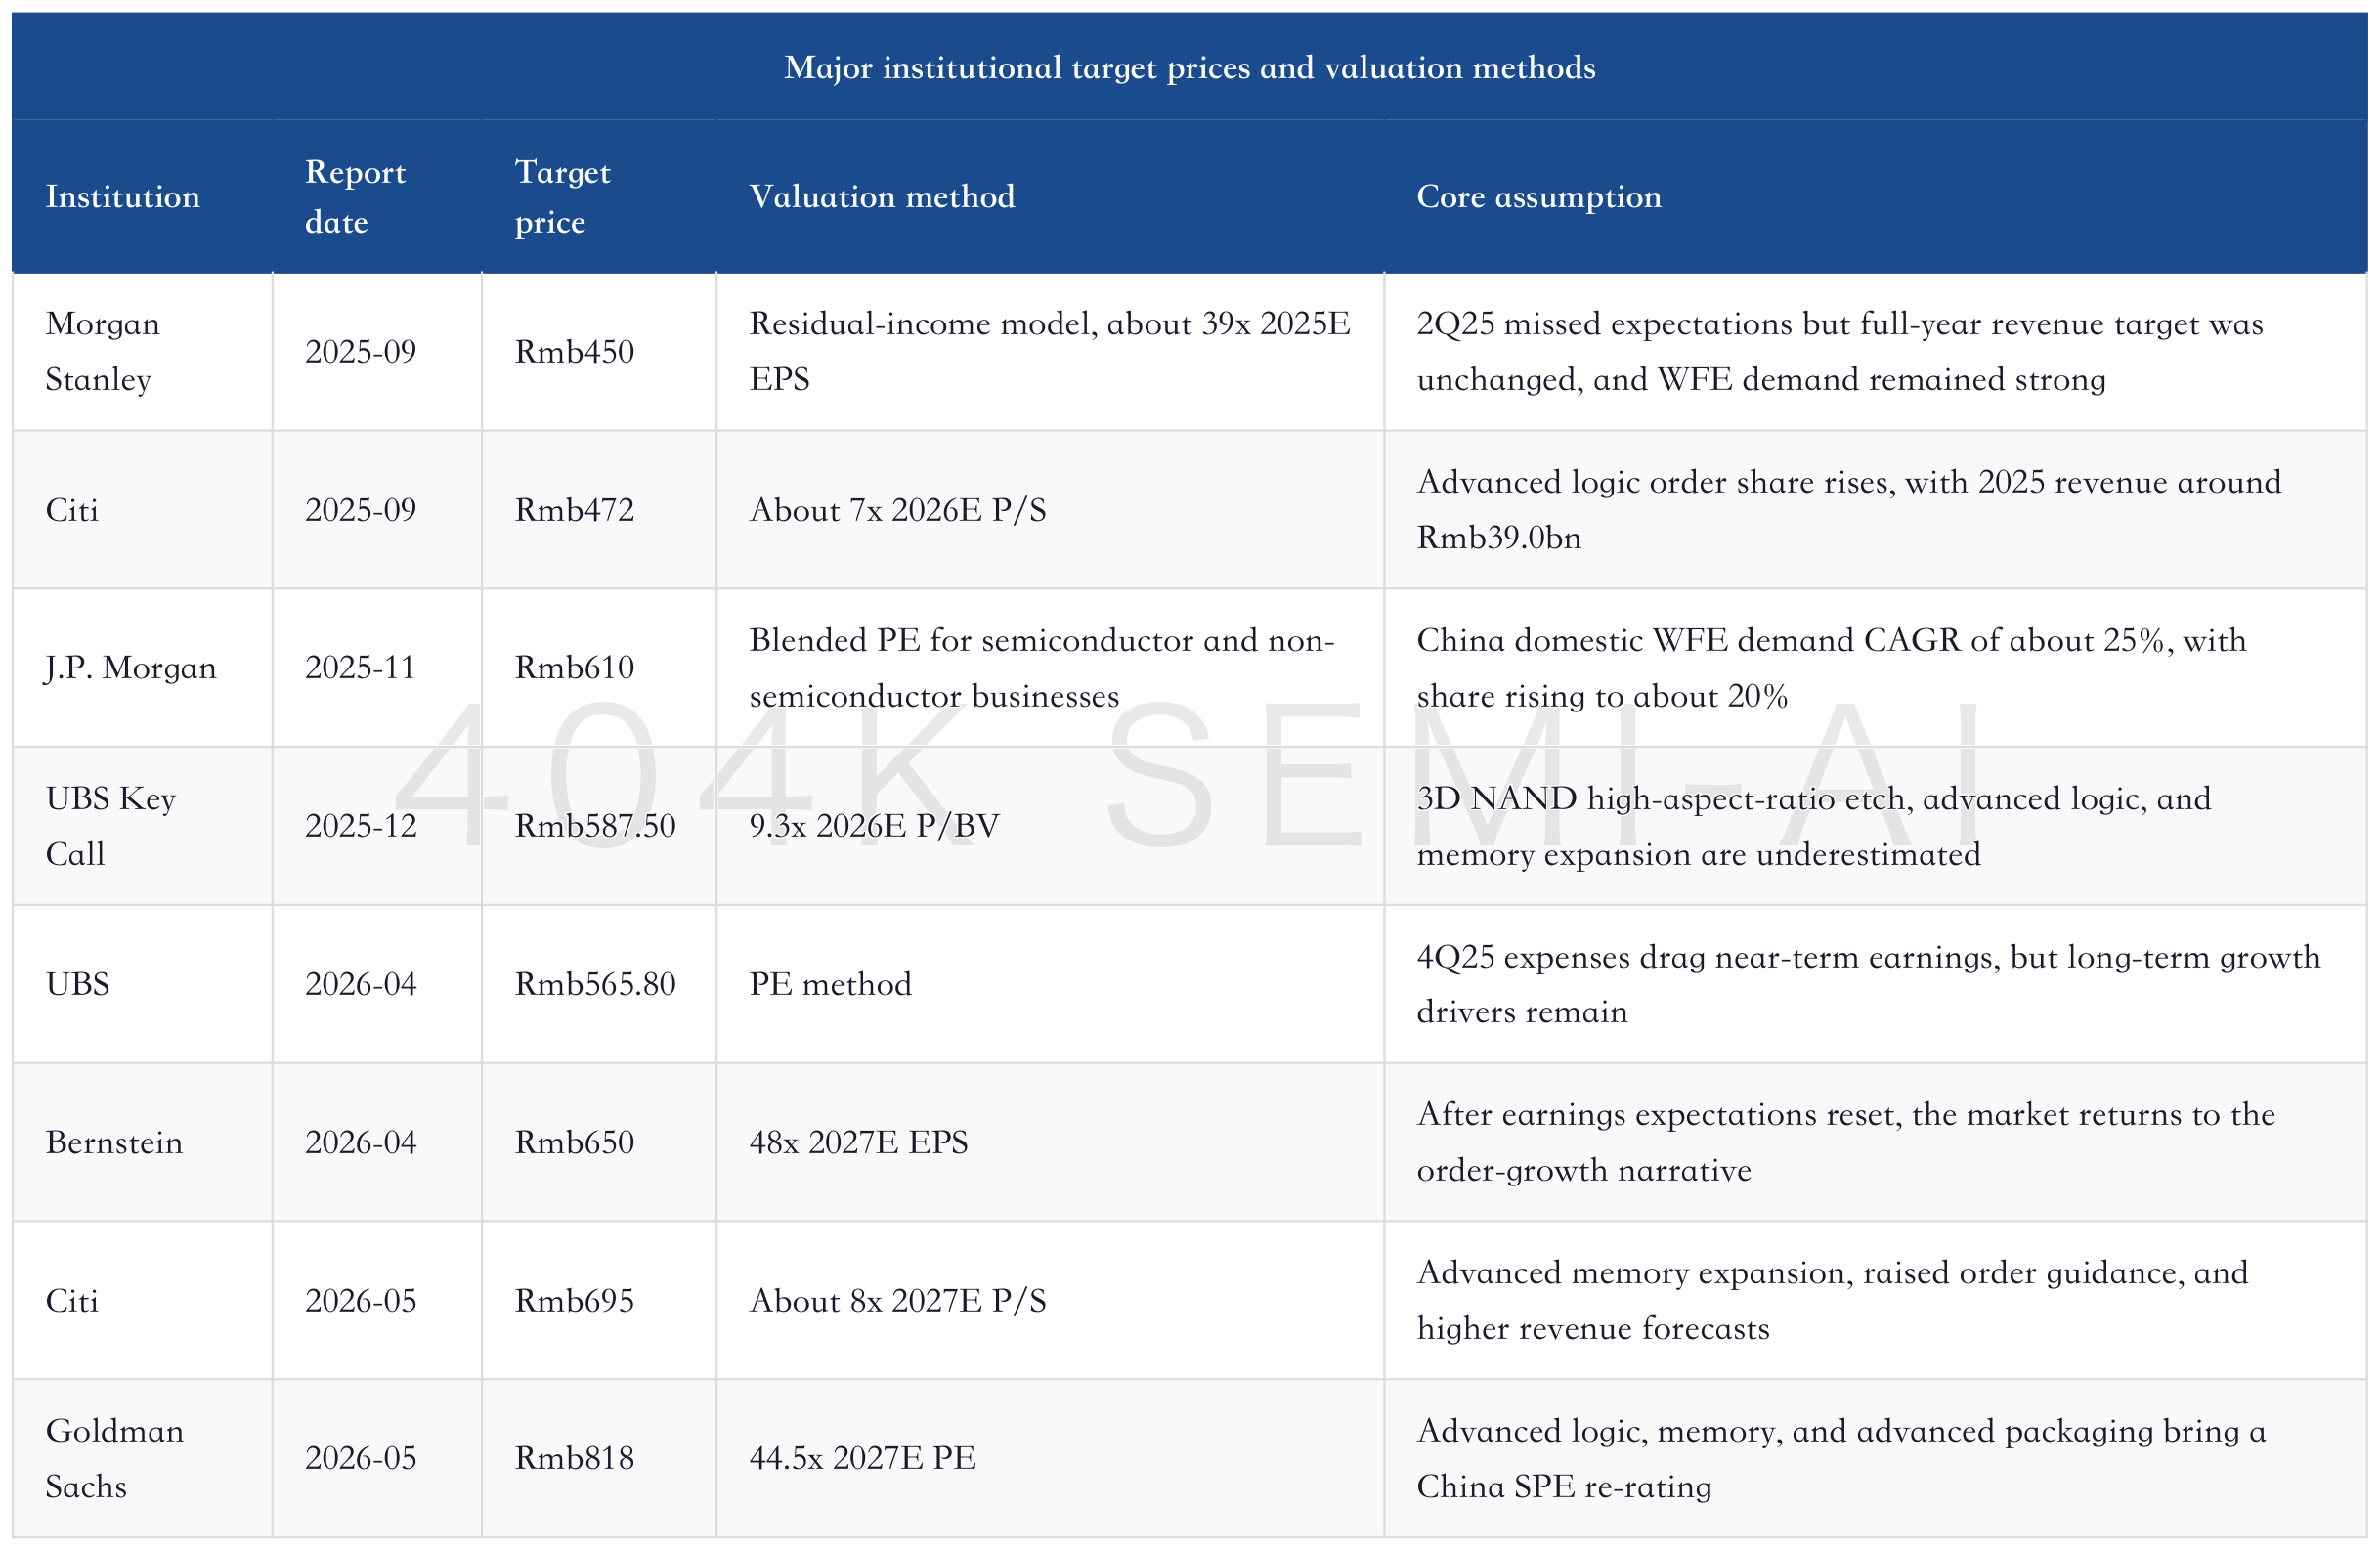
The target-price methodologies show the market's "leap of faith." Valuations in 2025 could still be explained by current EPS. High target prices in 2026 are already inseparable from 2027 order conversion, advanced-node product scaling, and margin recovery. In other words, the market is not giving NAURA a high multiple unconditionally. It is betting that the company upgrades from a domestic equipment leader into a platform supplier for China's advanced production lines.
Goldman Sachs' May 2026 industry scenario model also illustrates this issue. It places China semiconductor capex, the domestic equipment supply ratio, and the profitability of NAURA and AMEC into the same sensitivity framework, and argues that even the conservative case still leaves some upside, while the optimistic case implies greater share-price elasticity for NAURA. The key to this type of model is not a specific price point, but that it expands valuation from a single-company income statement to industry capex and domestic equipment share.
Three Worldviews
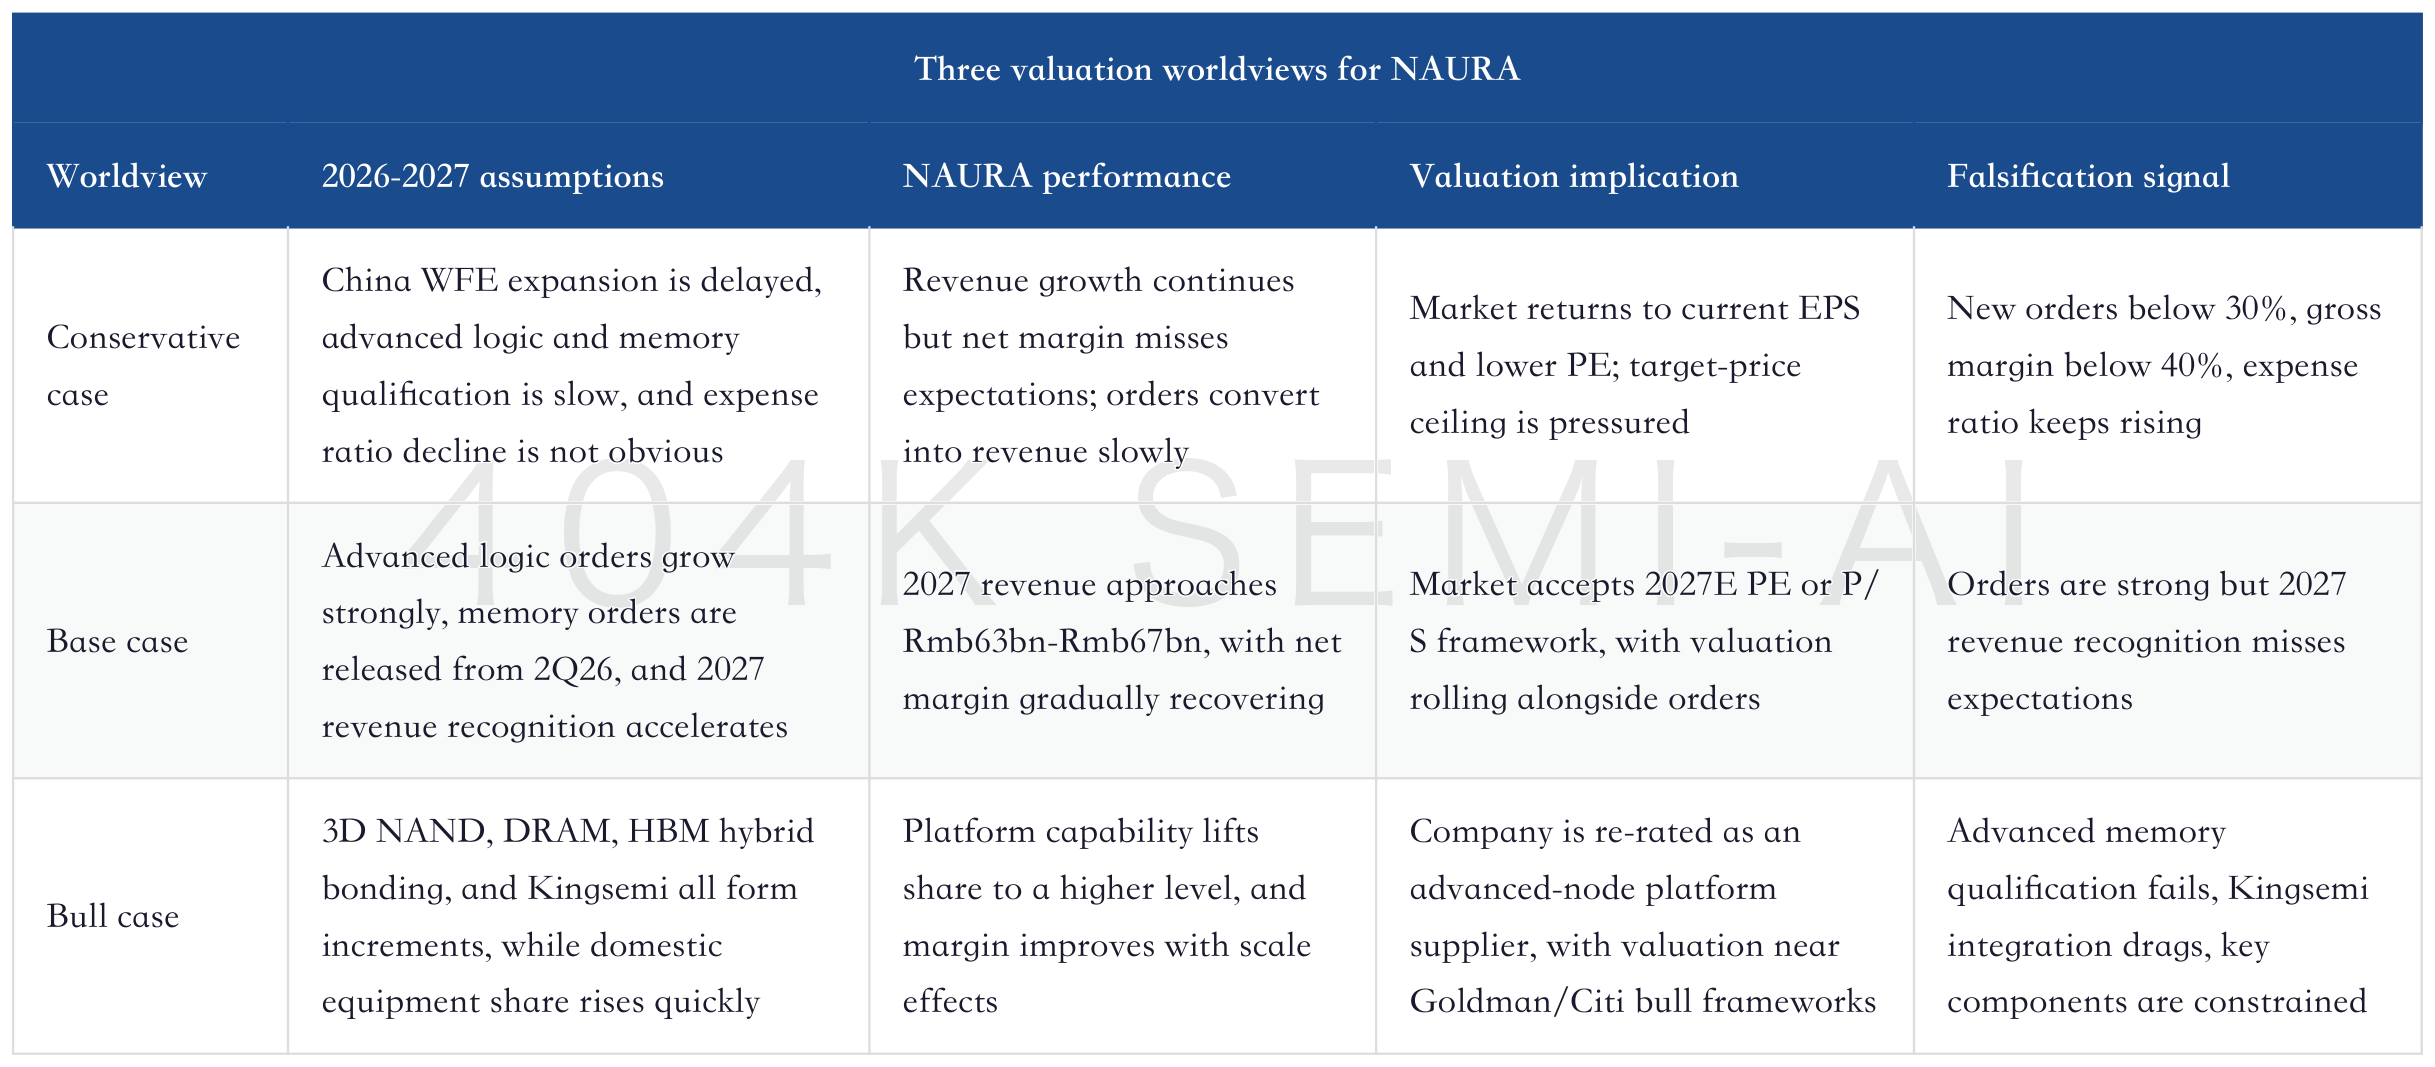
The most reasonable trading approach is to view NAURA as a portfolio of options: orders are the short-term option, revenue recognition is the medium-term option, and margin is the long-term option. If orders convert first, valuation can rise first; if revenue recognition follows, earnings forecasts will be revised; if margins then recover, valuation can hold. If any link breaks, valuation will retrace.
6. Compared With Global Equipment Leaders: NAURA's Scarcity Comes From Its Platform Position in a Constrained Market
The common trait among global WFE equipment leaders is high share, high stickiness, and high service revenue in certain critical processes. Applied Materials, Lam Research, Tokyo Electron, KLA, and ASML each correspond to different critical segments. NAURA cannot be compared with them simply by market cap, revenue, or margin, because it is still in the phase of product qualification, share gain, and coordinated expansion with domestic customers.
But NAURA has a special variable that global leaders do not: it is in a market where supply-chain restrictions are stronger, customers are more willing to adopt domestic suppliers, and advanced logic and memory expansion require greater supply security. This market's TAM is not necessarily the largest, but the speed of domestic share gain may be faster. J.P. Morgan expects China's WFE localization rate to rise from about 20% in 2024 to about 35% in 2027, and NAURA's share of China WFE demand to rise from about 10% to about 20%. This is the logic.
Applied Materials Deep Dive: How the WFE Supercycle, DRAM Expansion, and Advanced Packaging Re-Rate the Profit Slope
Applied Materials' value lies in spanning multiple segments, including deposition, etch, ion implantation, metrology, and advanced packaging, allowing it to capture broad demand alongside the global WFE supercycle. NAURA is similar in platformization. The difference is that its platformization is happening in a market where domestic substitution is still accelerating. Applied Materials is about the slope of global equipment demand; NAURA also depends on the slope of domestic share gain.
Compared with AMEC, NAURA's difference is also clear. AMEC is more like a high-quality leader in subsegments such as etch and MOCVD, while NAURA is more like a broader WFE platform. The advantage of a platform company is a larger addressable market and a more complete customer solution. The disadvantage is more products, heavier R&D; investment, and margins that are more easily dragged down by new-product cycles. Therefore, AMEC is better analyzed through single-product competitiveness, while NAURA is better analyzed as a portfolio.
Compared with Tokyo Electron, the significance of Kingsemi is even more intuitive. Tokyo Electron has a footprint across coat/develop, etch, deposition, cleaning, and other segments, and has long benefited from platformization and customer service. By filling the track-equipment gap through Kingsemi, NAURA may face consolidation and qualification friction in the short term, but over the long term it gains more bargaining chips with advanced-line customers.
How to Read Peer Positioning
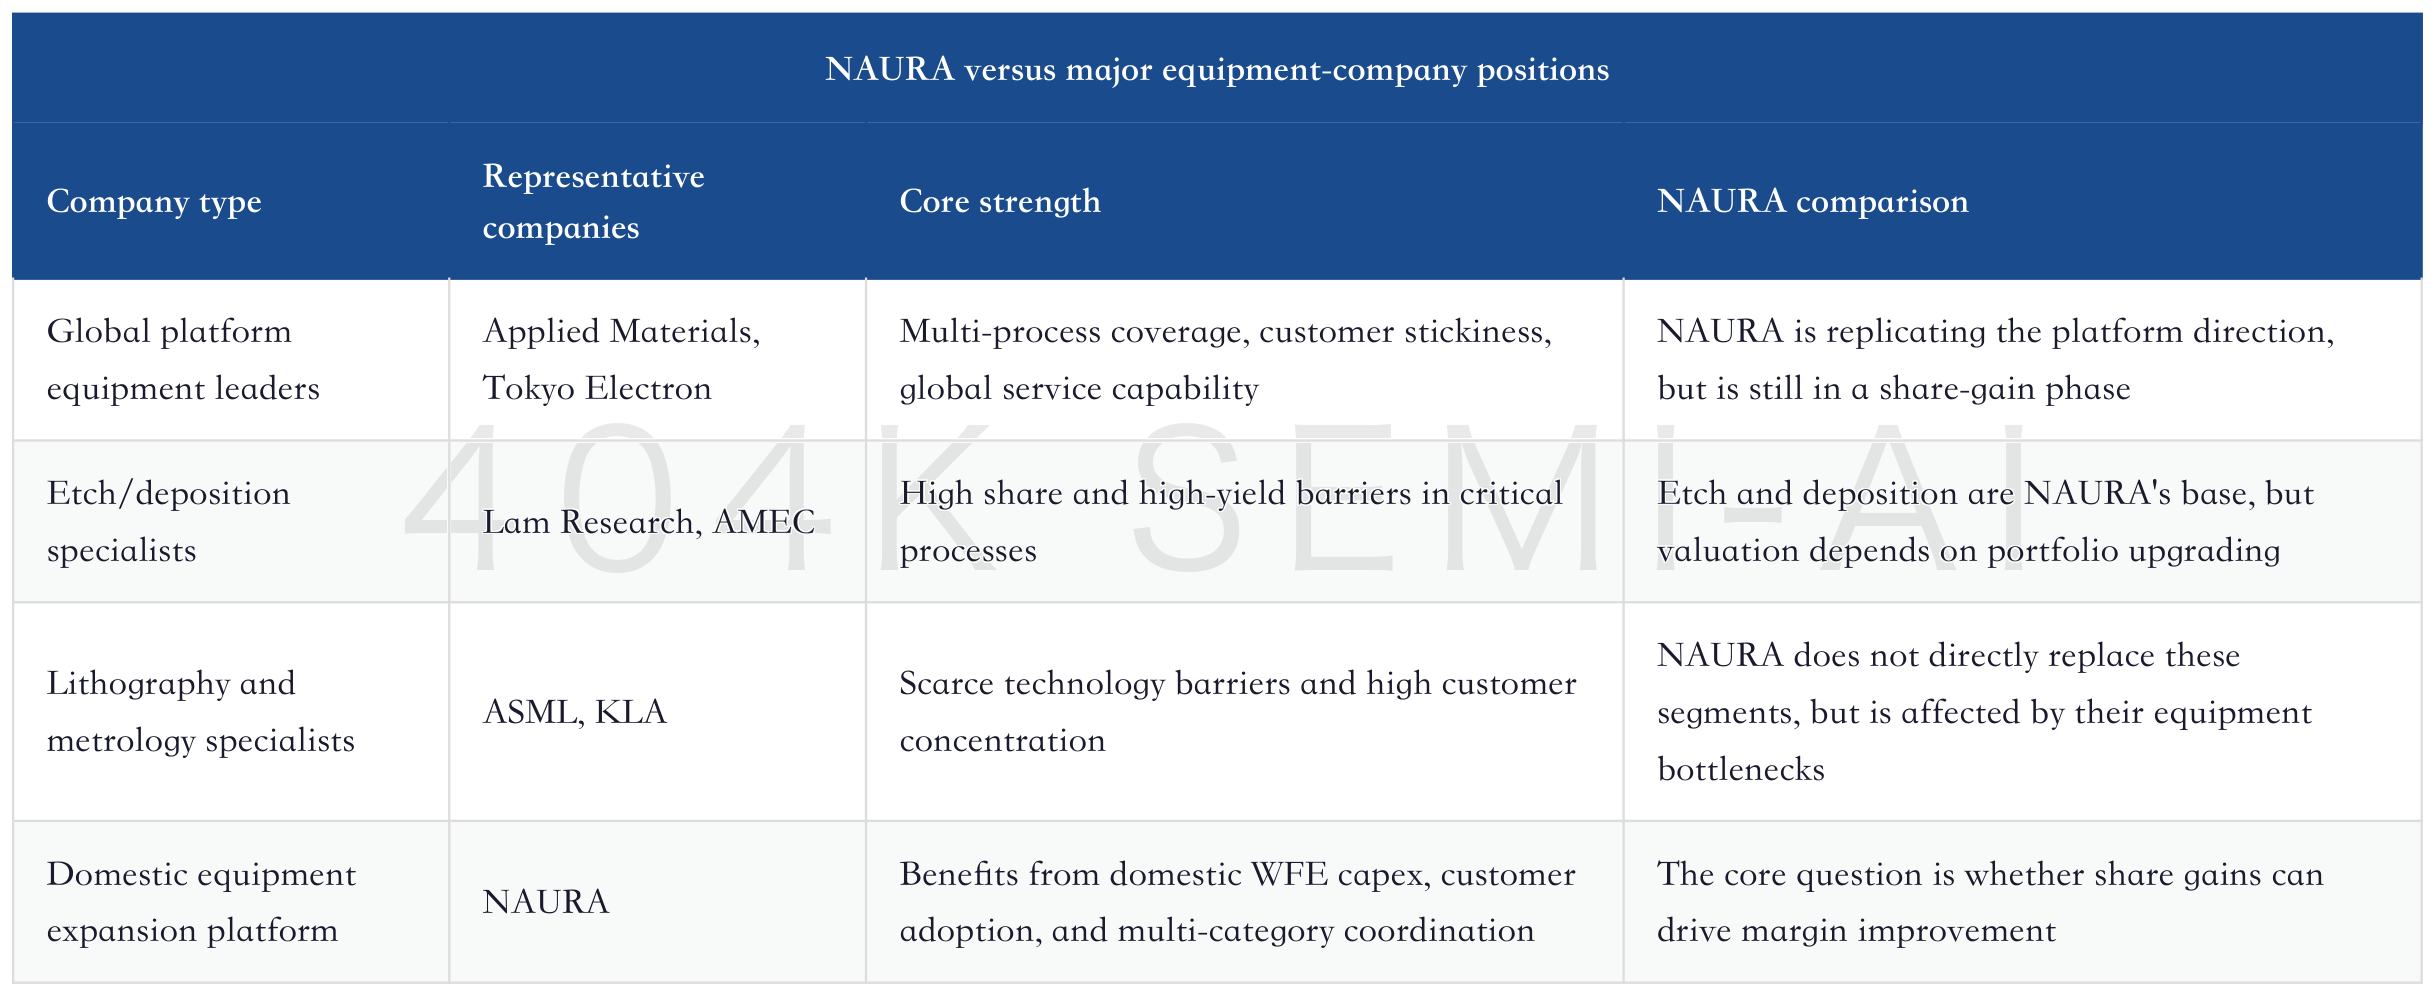
NAURA cannot be valued directly on the margin profile of mature global leaders, nor should it receive the low multiple of an ordinary domestic-substitution stock. It sits in an intermediate state: technology is still catching up, categories are still being filled in, expenses are still being invested, but orders and customers have already pushed it into a core position in advanced-node production lines. This state will be volatile, but once it crosses the qualification stage, valuation elasticity can also be large.
7. Financial Bridge: Revenue Growth Is Relatively Clear; Profit Quality Still Has Three Gates to Pass
NAURA's financial model can be split into three gates: the order gate, the revenue gate, and the profit gate. The order gate is about customer expansion and domestic adoption. The revenue gate is about delivery, acceptance, and recognition cycle. The profit gate is about gross margin, expense ratio, and equity incentives. The market is most confident about the first gate, is raising expectations on the second, and still disagrees on the third.
The revenue bridge is relatively clear. 2024 revenue was about Rmb29.8bn. Mainstream 2025 forecasts fall around Rmb39.0bn-Rmb39.9bn. 2026 is mostly around Rmb49.6bn-Rmb51.9bn, and 2027 is around Rmb62.8bn-Rmb66.9bn. Different institutions disagree on 2027 revenue, but the direction is not contradictory: advanced logic, memory expansion, and platformized new products are enough to support another step-up in revenue over the next two years.
The profit bridge is much more complex. Some institutions expect 2025 net profit or EPS to be dragged down by ESOP, R&D; expense, and gross-margin pressure, and 2026 may not immediately recover. But by 2027, some institutions assume that revenue scale, expense ratios, and product mix improve at the same time, releasing meaningful profit elasticity. Goldman Sachs puts 2027 net profit at Rmb13.322bn, J.P. Morgan's adjusted net profit is higher, while UBS's April version is more conservative. This is not simple optimism or pessimism, but different judgments about the expense-ratio inflection point.
