
Nanya Technology Deep Dive: DDR4 EOL, SOCAMM Server Memory, and an NT$710 Target Price: The Three Gates for Re-rating a Tier-2 DRAM Vendor
目录
Too Long; Didn’t Read
1. The Key to Nanya’s Re-rating Is “Legacy DRAM” Re-entering the AI Supply Chain
2. Company Profile: What Does Nanya Actually Sell, and Where Is It Strong or Weak?
3. What JPM Changed in Its Model: From NT$230 to NT$710, Not a Routine Upgrade
4. Why DDR4 EOL Is Not a Legacy-Capacity Story, But a Supply-Chain Insurance Story
V. SOCAMM and Server Memory: Nanya Technology’s Second Growth Curve Is Still in Early Validation
VI. 1B, 1C/1D, and Fab 5A: This Is Not a Capacity Expansion Story, but a Cost and Product Moat Story
VII. Valuation: NT$710 Is Defensible, but It Is Not a Low-Risk Target Price
8. Sell-Side Divergence: Why Nanya Technology’s Risks Are More Concentrated Despite the Same Positive View on Memory
9. Financial Quality: 1Q26 Was Very Strong, but Do Not Treat One Quarter’s Profit as Permanent
10. Three Worldviews: Which Future Will Nanya Technology’s Share Price Ultimately Trade?
XI. Falsification Checklist: What Would Invalidate NT$710
XII. Four-Quarter Tracking Table: Watch the Numbers, Not the News
XIII. Trading Framework: Split Nanya Technology into Price, Customer, and Option Buckets
XIV. Conclusion: What Nanya Technology Offers Is a Conditional Re-Rating, Not Blind Cycle Chasing
本内容基于公开资料和研报数据整理,不构成任何投资建议,不代表任何个人观点,仅供学习参考,请理性阅读
The core of Nanya Technology’s current re-rating is not a generic DRAM cycle rebound. It is the simultaneous emergence of DDR4/LPDDR4 supply exits, long-term agreements tied to eSSD and networking demand, and optionality in SOCAMM server memory. The market is starting to reprice tier-2 DRAM vendors, and to reprice their risks as well.
Too Long; Didn’t Read
Nanya Technology’s asset profile has changed. It used to look more like a cyclical consumer and specialty DRAM stock. The debate now is whether pricing, customers, and process technology can preserve peak earnings. JPMorgan’s NT$710 target price is essentially a re-rating based on server exposure, long-term agreements, and cash-flow sustainability, not just one quarter of price increases.
Legacy-spec supply is the first ticket. After Samsung, SK hynix, and Micron shifted capacity toward HBM, advanced DRAM, and high-end products, legacy memory was no longer just a lagging product category. It became a supply gap still required by eSSD, switches, BMCs, NICs, autos, and consumer devices. Nanya has already shown through official financials that supply contraction can quickly flow through to ASP, gross margin, and net profit.
Serverization is the second ticket. Nanya’s server revenue remains at a low base, but the company has already increased RDIMM sales and has included server modules, TSV, SOCAMM-related opportunities, and customized high-bandwidth products in its roadmap. If eSSD, networking, and server orders expand, the customer mix will shift from consumer tail demand toward AI server adjacency demand.
The valuation risk is that forecasts are too steep. JPMorgan’s model is not a mild recovery scenario. It assumes sustained high pricing, capacity discipline, customer long-term agreements, and yields all hold at the same time. If any one of these breaks, the target price will be retested, and the market may mark Nanya back down from a server supply-chain asset to a cyclical stock.
Financial quality provides a cushion. The latest quarterly report and monthly revenue already show that the company has entered a phase of high revenue, high margin, and high cash flow. Private placement capital has further strengthened the balance sheet. The issue is that Fab 5A, advanced processes, and customized products also require capex, so dividend flexibility must be assessed together with the expansion cadence.
Watch five variables next: pricing, gross margin, server revenue, process nodes, and long-term-agreement orders. These matter more than news flow and target prices. Nanya’s re-rating depends not on a bigger story, but on these variables staying intact. If validation continues, it can qualify to move from a legacy DRAM price-hike stock to a cash-flow asset in the AI storage supply chain.
1. The Key to Nanya’s Re-rating Is “Legacy DRAM” Re-entering the AI Supply Chain
The easiest way to misread Nanya is to treat it simply as a DDR4 price-hike stock. That view is too shallow. DDR4 price increases are only the first layer of change at the pricing level. What is truly worth studying is how legacy DRAM capacity has found a role again inside the AI server supply chain.
The company’s historical revenue mix was not high-end. Its official 2025 annual report disclosed that consumer electronics applications accounted for about 55% of revenue, low-power products about 19%, personal computer systems about 21%, and data center and server applications about 5%. This means Nanya is not an HBM-led company like SK hynix, nor is it a full-category advanced memory leader like Samsung or Micron. Its advantage lies in retaining a broad enough portfolio across DDR4, LPDDR4, DDR3/DDR2, KGD, MCP, UDIMM, RDIMM, and LPCAMM2, allowing it to capture the “necessary but unglamorous” supply gaps left behind after leading vendors shifted production.
These gaps are not valuable in a downcycle. Customers view legacy-spec DRAM as replaceable components, with prices driven by inventory and utilization. Tier-2 vendors struggle to secure stable valuations. In an upcycle, the logic reverses: when Samsung, SK hynix, and Micron prioritize wafers, equipment, R&D;, and customer resources for HBM, high-capacity DDR5, LPDDR5, and AI server products, DDR4/LPDDR4 supply begins to shrink. Legacy-node capacity that capital markets previously ignored suddenly becomes safety stock that customers must secure.
Nanya’s 2025 income statement has already provided evidence. The company posted 2025 revenue of NT$66.59 billion, up 95.1% year on year, net profit after tax of NT$6.61 billion, and EPS of NT$2.13. More importantly, the quarterly cadence was striking: in Q3, ASP rose more than 40% quarter on quarter, while shipments increased more than 20%; in Q4, ASP rose by more than 30% quarter on quarter again, while shipments increased about 10%, with Q4 single-quarter profit reaching NT$11.09 billion. This slope cannot be explained by normal seasonality. It corresponds to a change in supply structure.
Storage Deep-Dive Update: Morgan Stanley Calls for Buying Legacy Memory; Why DDR4, SLC NAND, and NOR Are Still Rising
JPMorgan’s upgrade of Nanya from Neutral to Overweight, and its target-price increase from NT$230 to NT$710, effectively moves the market debate to a higher level. If this is only a short-term squeeze in DDR4 spot pricing, the valuation should not reach 8x FY27E EPS. If this is a new long-term-agreement cycle driven by AI servers, eSSD, networking, RDIMM, and SOCAMM, then Nanya can no longer be assessed only on the average P/B of traditional tier-2 DRAM vendors.
My view is that Nanya is now in the middle of an asset-profile transition. The old asset profile was “cyclical leverage to consumer and specialty DRAM.” The new asset profile is “AI server-adjacent memory supplier.” The valuation gap between these two profiles is large, but the transition is not complete. The market is now willing to pay in advance because pricing, customers, and cash flow have all provided evidence. What will truly determine how far this re-rating can go is whether the next four quarters can prove that serverization is not a one-off shortage, but a restructuring of the customer mix.
Nanya’s asset profile is shifting from cyclical leverage toward the server supply chain
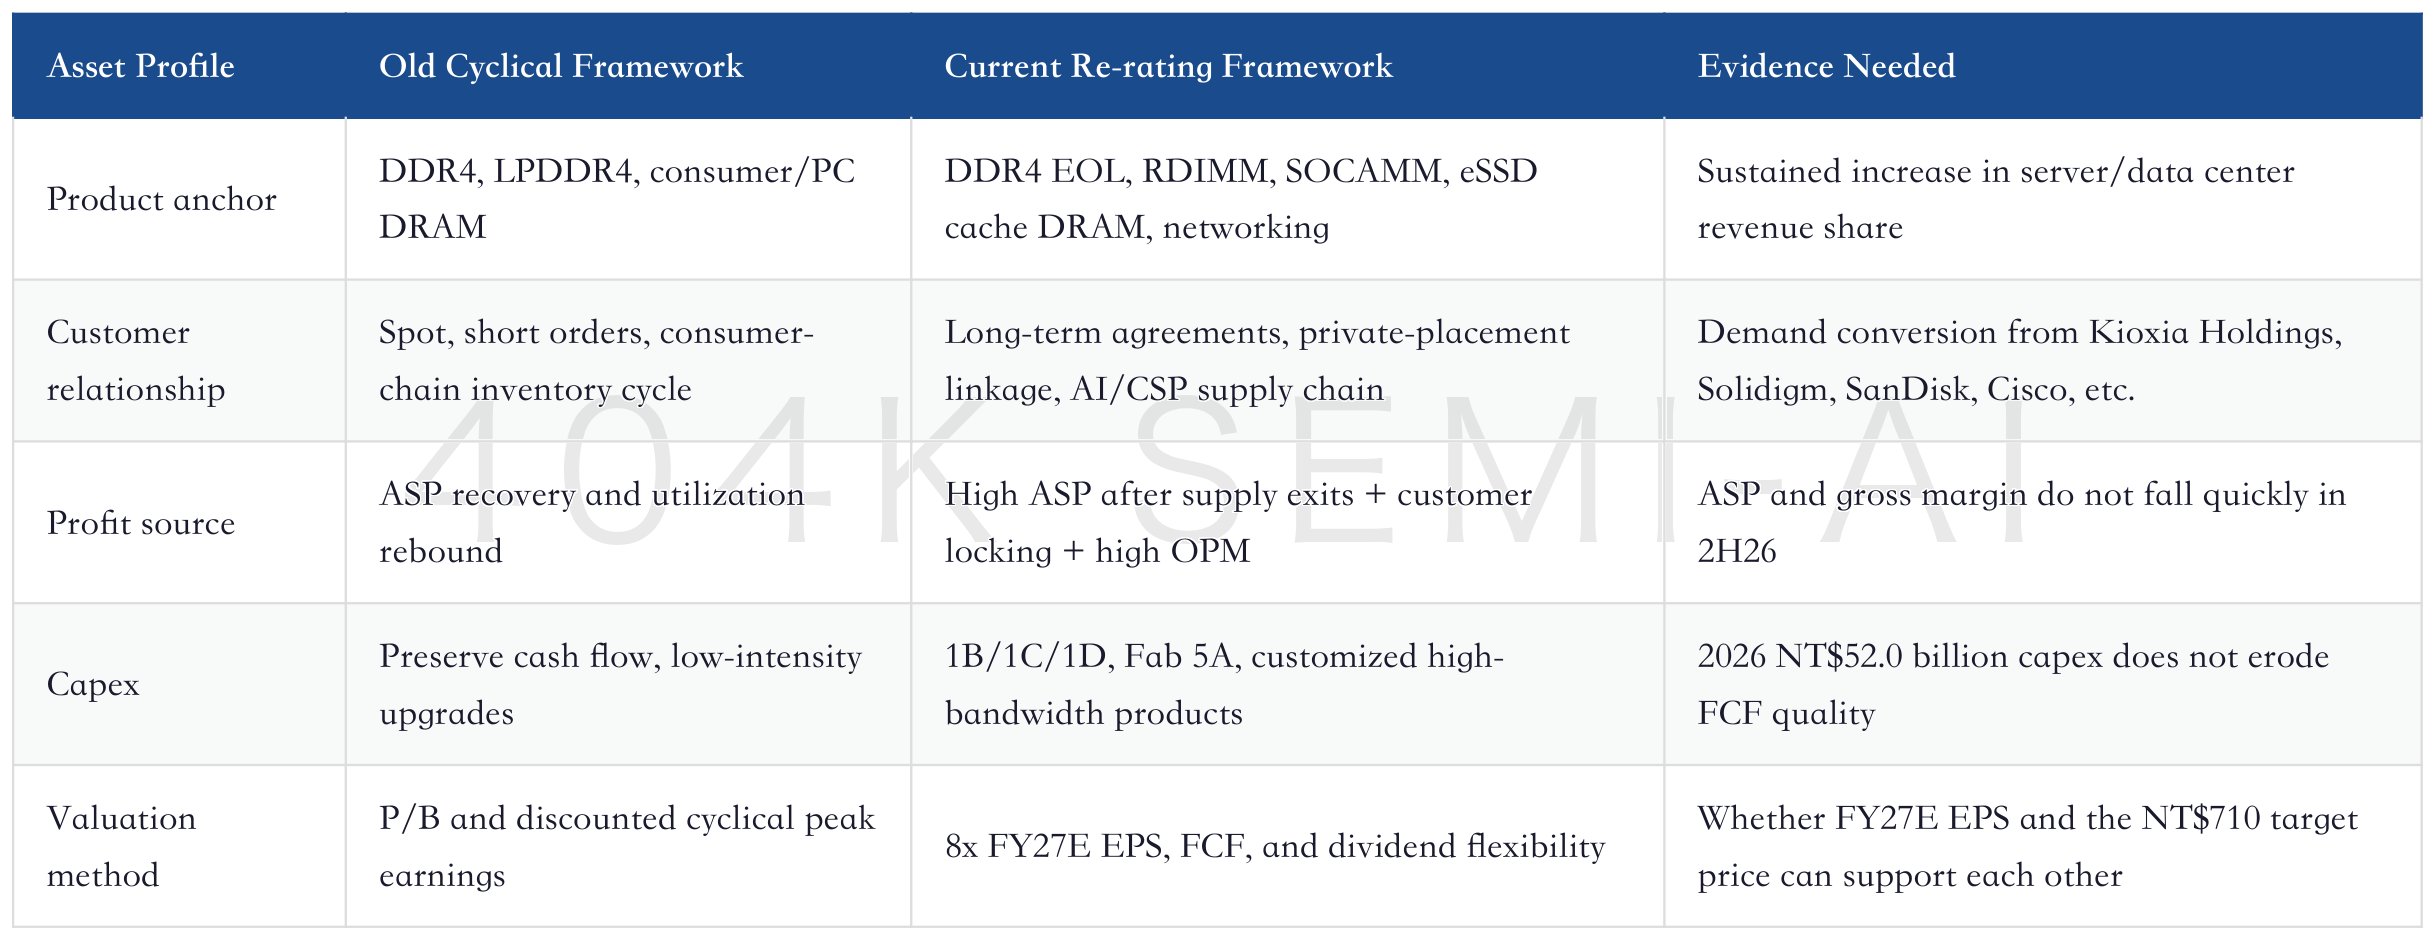
This is also why this report begins with Nanya itself rather than the industry. Industry strength provides beta; the company’s re-rating depends on three alphas. First, DDR4/LPDDR4 supply exits make legacy products valuable again. Second, private placements and long-term supply agreements bind the company more tightly to eSSD and networking demand. Third, 1B, DDR5, RDIMM, SOCAMM, and customized high-bandwidth products give it a chance to move from legacy DRAM into server memory. If any one of these three alphas fails, the valuation will revert to that of a cyclical stock. If all three materialize, Nanya will become the tier-2 asset with the greatest cash-flow leverage in the storage upcycle.
2. Company Profile: What Does Nanya Actually Sell, and Where Is It Strong or Weak?
Nanya’s core business is very pure: it is almost entirely DRAM. In its 1Q26 financial report, DRAM revenue was NT$49.07 billion, accounting for nearly all of total revenue of NT$49.09 billion; other revenue was only about NT$20 million. This purity gives the company extremely strong leverage in a pricing cycle, but also leaves it with little earnings buffer from NAND, HBM, logic ICs, or packaging and testing.
The product line is not narrow. Standard DRAM listed on the company website covers DDR5, DDR4, DDR3, DDR3L, and DDR2. Low-power products cover LPDDR5/5X, LPDDR4/4X, LPDDR4X, LPDDR4, LPDDR3, and LPDDR2. KGD, MCP, eMCP, uMCP, and module products cover SODIMM, CSODIMM, UDIMM, CUDIMM, RDIMM, and LPCAMM2. This shows that Nanya is not relying solely on a single DDR4 die, but has relatively complete long-tail product capabilities across legacy specs, low-power products, modules, and bare-die supply.
The company’s strengths are also clear. First, it has retained and upgraded 20nm and 1Bnm DDR4 capacity, allowing it to quickly become a replenishment source for customers as leading vendors exit legacy-product supply. Second, it has Formosa group backing and long-term DRAM manufacturing experience, giving it the ability to invest in Fab 5A, 1C/1D, and customized products after cash flow improves. Third, its customer mix is expanding from consumer electronics into servers, networking, SSDs, and automotive. In particular, after private placements brought in Kioxia Holdings, Solidigm, SanDisk, and Cisco, the quality of customer linkage has clearly improved.
The weaknesses should not be ignored. Nanya is not an HBM leader. DDR5 still did not account for a high share of revenue in early 2026, and server applications accounted for only about 5% of 2025 revenue. For the company to move from DDR4 price increases to a server-driven re-rating, it must cross four gates: product qualification, customer long-term agreements, yield ramp, and capacity allocation. If its technology roadmap stops at DDR4 pricing leverage, the valuation will struggle to remain above a cyclical peak for long. If 1B/1C/1D, RDIMM, SOCAMM, and customized high-bandwidth products progress slowly, the market will treat NT$710 as a cycle-top valuation.
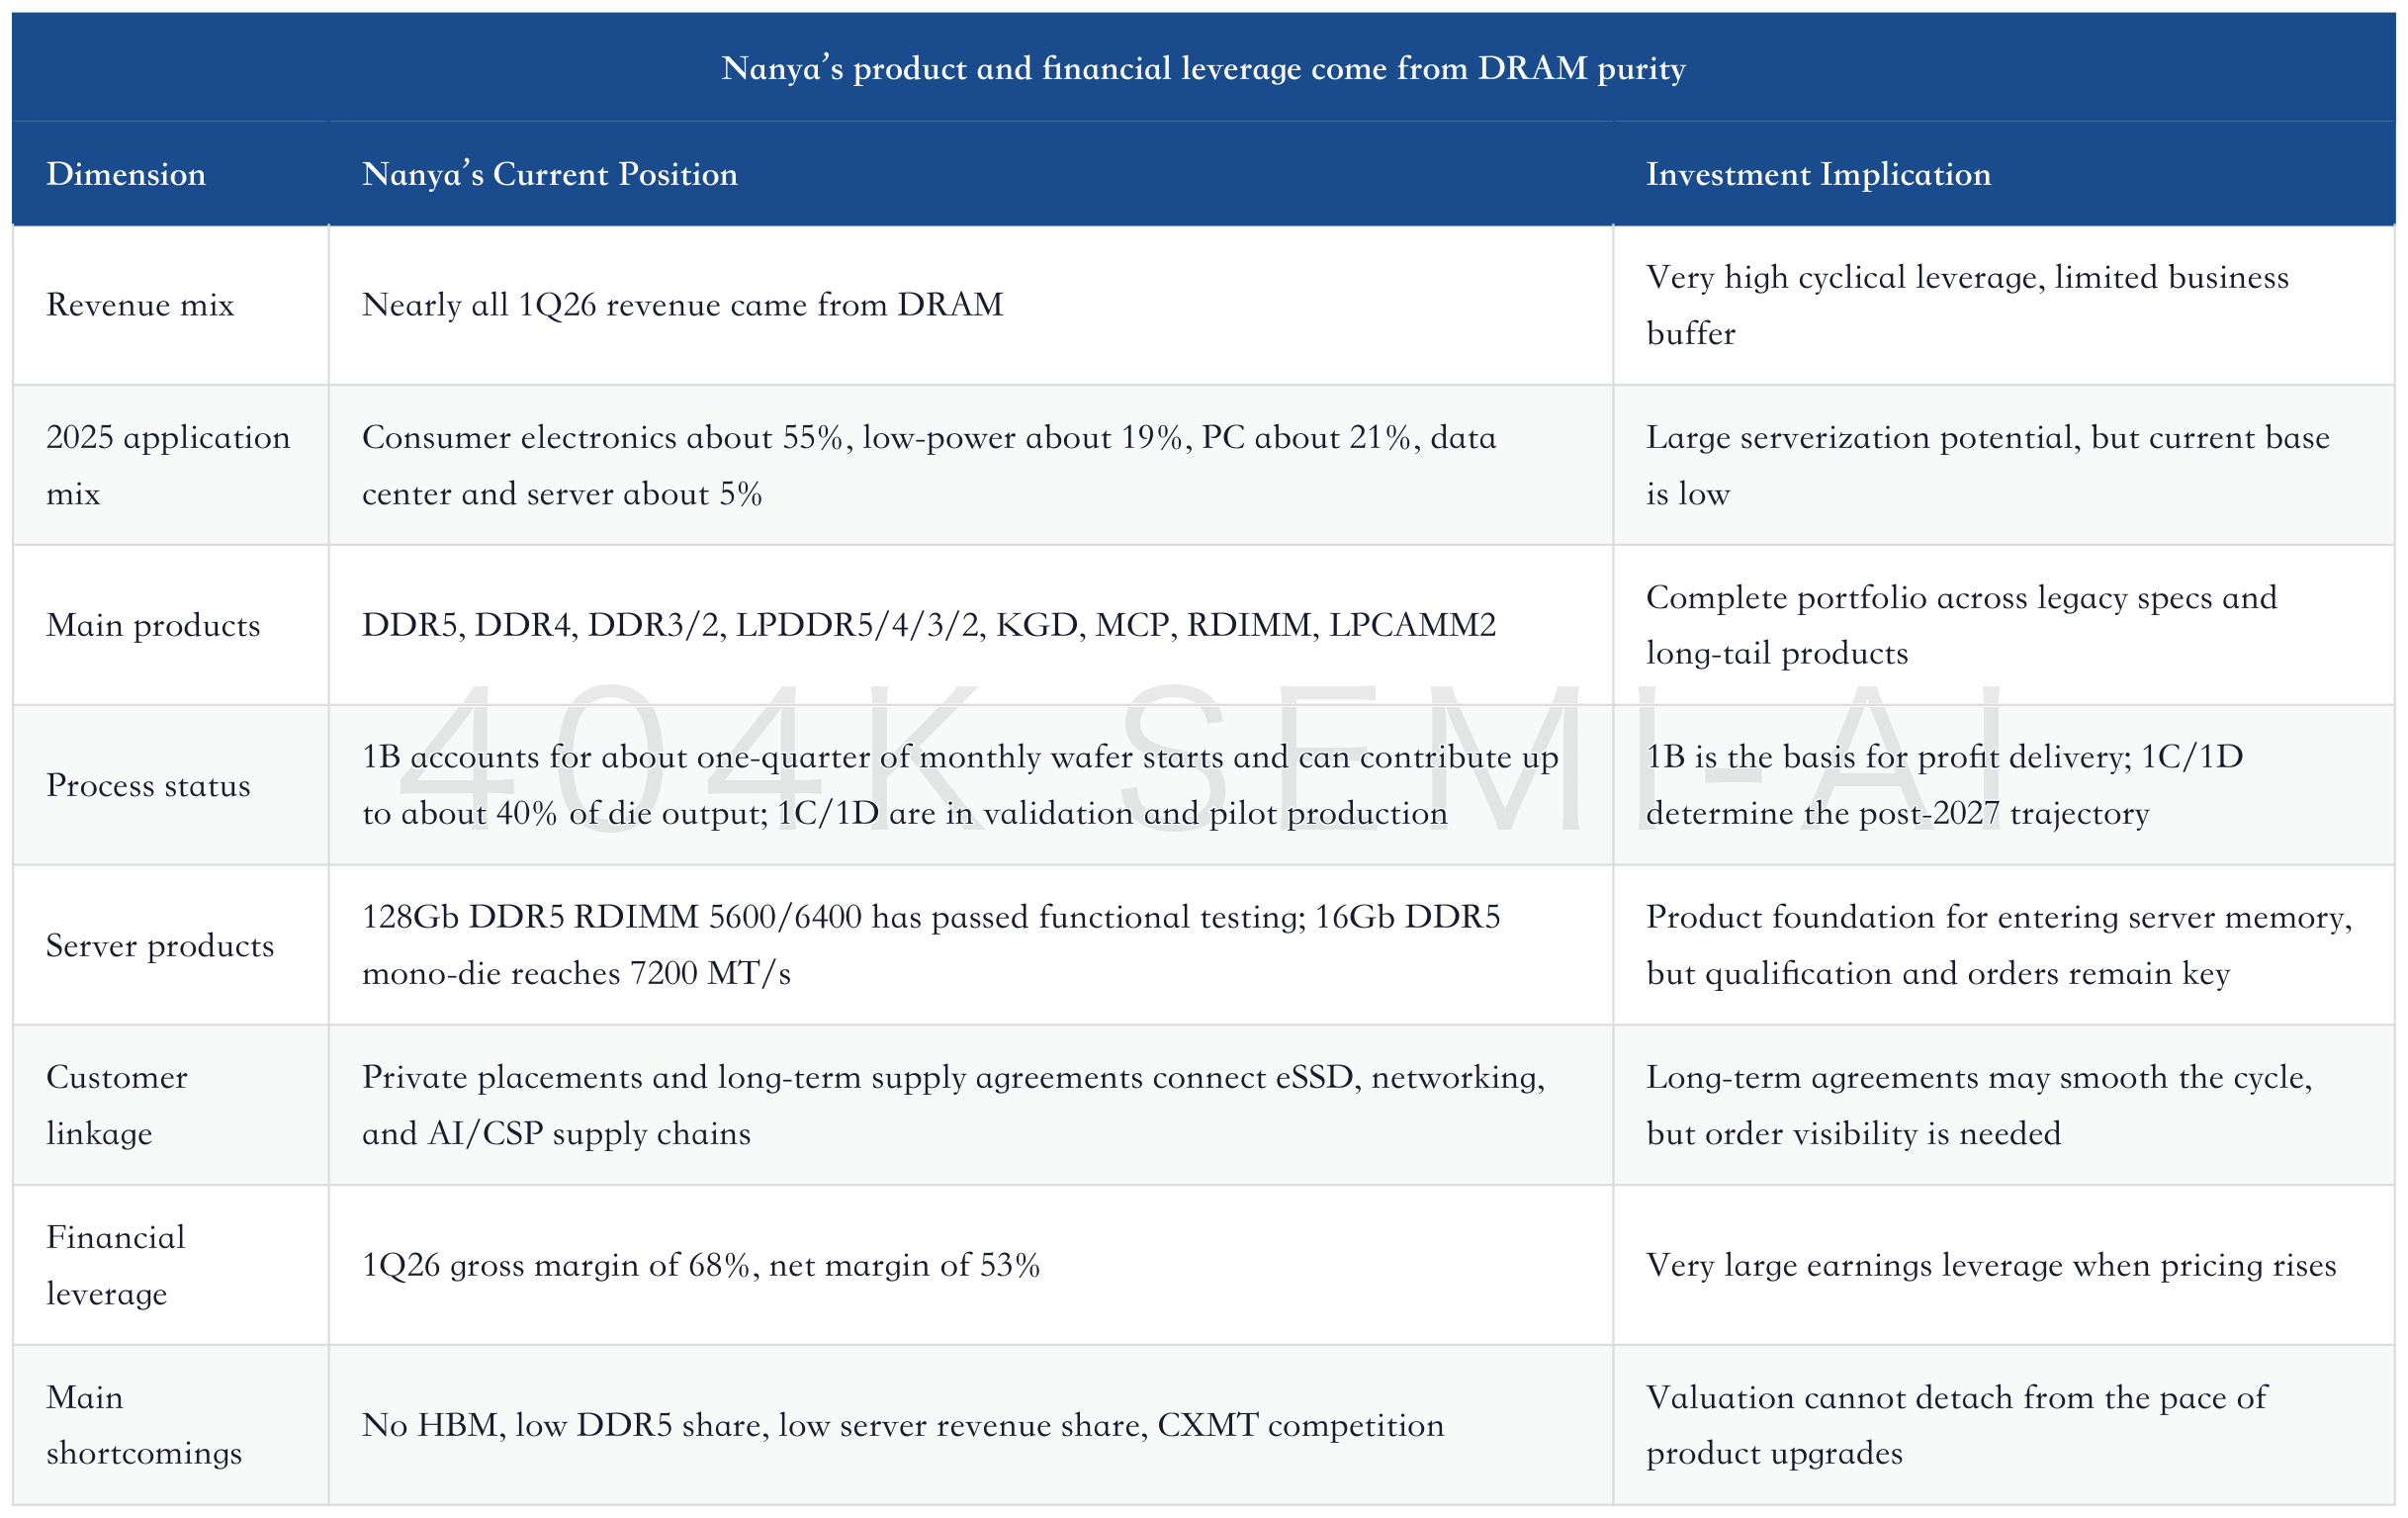
The most important question for this company is not “can prices rise?” It is “after prices rise, can the company move customers and product tiers upward?” Without server customers, DDR4 price increases will ultimately be absorbed by new supply, substitution, and customer inventory. If eSSD, networking, RDIMM, SOCAMM, and customized low-power products take over the demand, DDR4 EOL becomes an entry point for customer lock-in and long-term supply negotiations.
Official materials are also describing the same issue more directly. In its 2025 annual report, the company clearly set its 2026 strategic direction as optimizing its DDR4/LPDDR4/DDR5 portfolio, increasing shipments of server-class memory modules, accelerating customized ultra-high-bandwidth memory, and advancing Fab 5A construction. The annual report also stated that 1B-related 16Gb DDR5, 8Gb DDR4, and 4Gb DDR4 have entered mass production and are shipping to customers; the 1C 16Gb DDR5 pilot product entered trial production in Q3 2025; and the 1D 16Gb DDR5 pilot product is expected to enter trial production in Q2 2026. The key here is not the wording, but that the roadmap has already shifted from “selling legacy DRAM” to “using legacy-product cash flow to fund new-product qualification.”
3. What JPM Changed in Its Model: From NT$230 to NT$710, Not a Routine Upgrade
JPMorgan’s upgrade this time is aggressive. It is not raising Nanya Technology’s 2026 earnings by 10% or 20%; it raised FY26E-FY28E EPS by 48%-118% and moved the valuation multiple to 8x FY27E EPS, in line with Korean DRAM leaders. The assumption behind this move is clear: in a DRAM upcycle, the market will not only buy HBM leaders, but also all DRAM assets that can release earnings from supply discipline and elevated pricing.
Start with the core forecasts. JPMorgan expects Nanya Technology’s revenue to rise from NT$66.59bn in 2025 to NT$322.90bn in 2026, NT$467.30bn in 2027, and NT$532.86bn in 2028; adjusted net income to rise from NT$6.61bn in 2025 to NT$198.64bn in 2026, NT$308.00bn in 2027, and NT$357.01bn in 2028; and adjusted EPS to rise from NT$2.13 to NT$58.43, NT$89.27, and NT$103.47. This slope implies the company is not merely turning profitable, but moving directly from a low-margin legacy-node fab into a state close to peak-cycle high-end profitability.
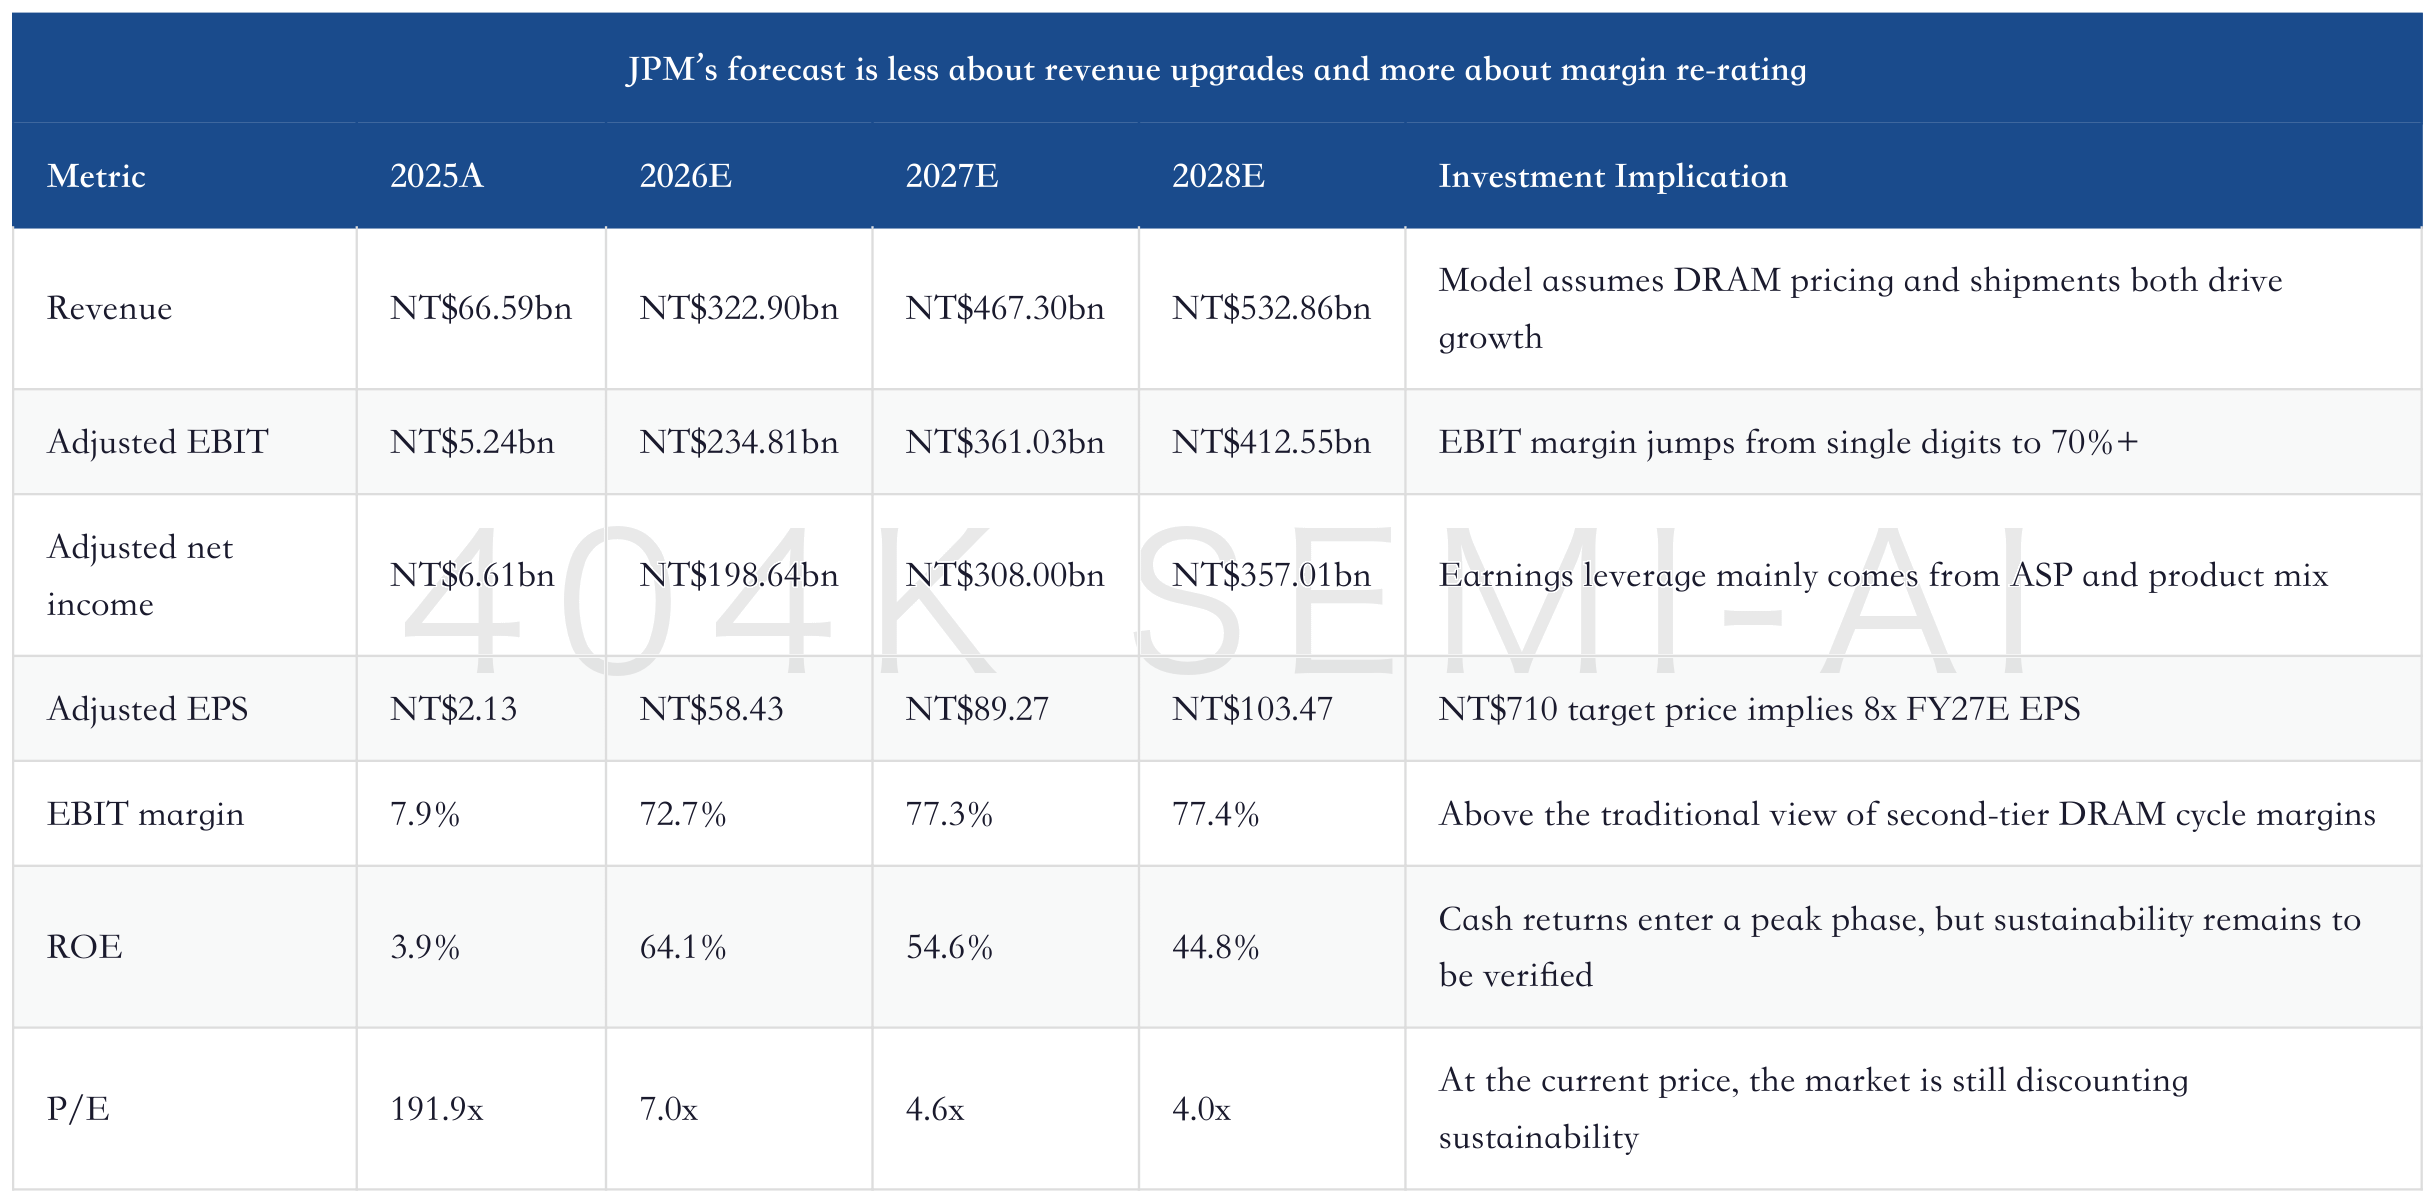
This table is the core model table of the entire report. It tells investors that Nanya Technology is not trading on “earning a bit of money this year,” but on whether it can sustain high profitability through 2026-2028. That is also where the risk lies: if 2026 EPS is NT$58.43, the current price of NT$409.5 implies roughly 7x; if 2027 EPS is NT$89.27, the current price implies only about 4.6x. The multiple looks cheap, but it is cheap only if 2027 earnings are not a cyclical peak.
JPMorgan’s upgrades to revenue, gross margin, and EPS mainly come from three assumptions. First, DDR4 and DDR5 both rise in an upcycle, and legacy products do not lose pricing power simply because they are behind the leading edge. Second, after DDR4/LPDDR4 EOL, eSSD, networking, automotive, the long tail of consumer demand, and server-edge demand will absorb legacy capacity. Third, Nanya Technology can gradually raise server-related revenue from a low base, especially through opportunities in SOCAMM, RDIMM, and eSSD cache memory.
JPM’s upgrades for Nanya Technology are concentrated in revenue, margins, and EPS
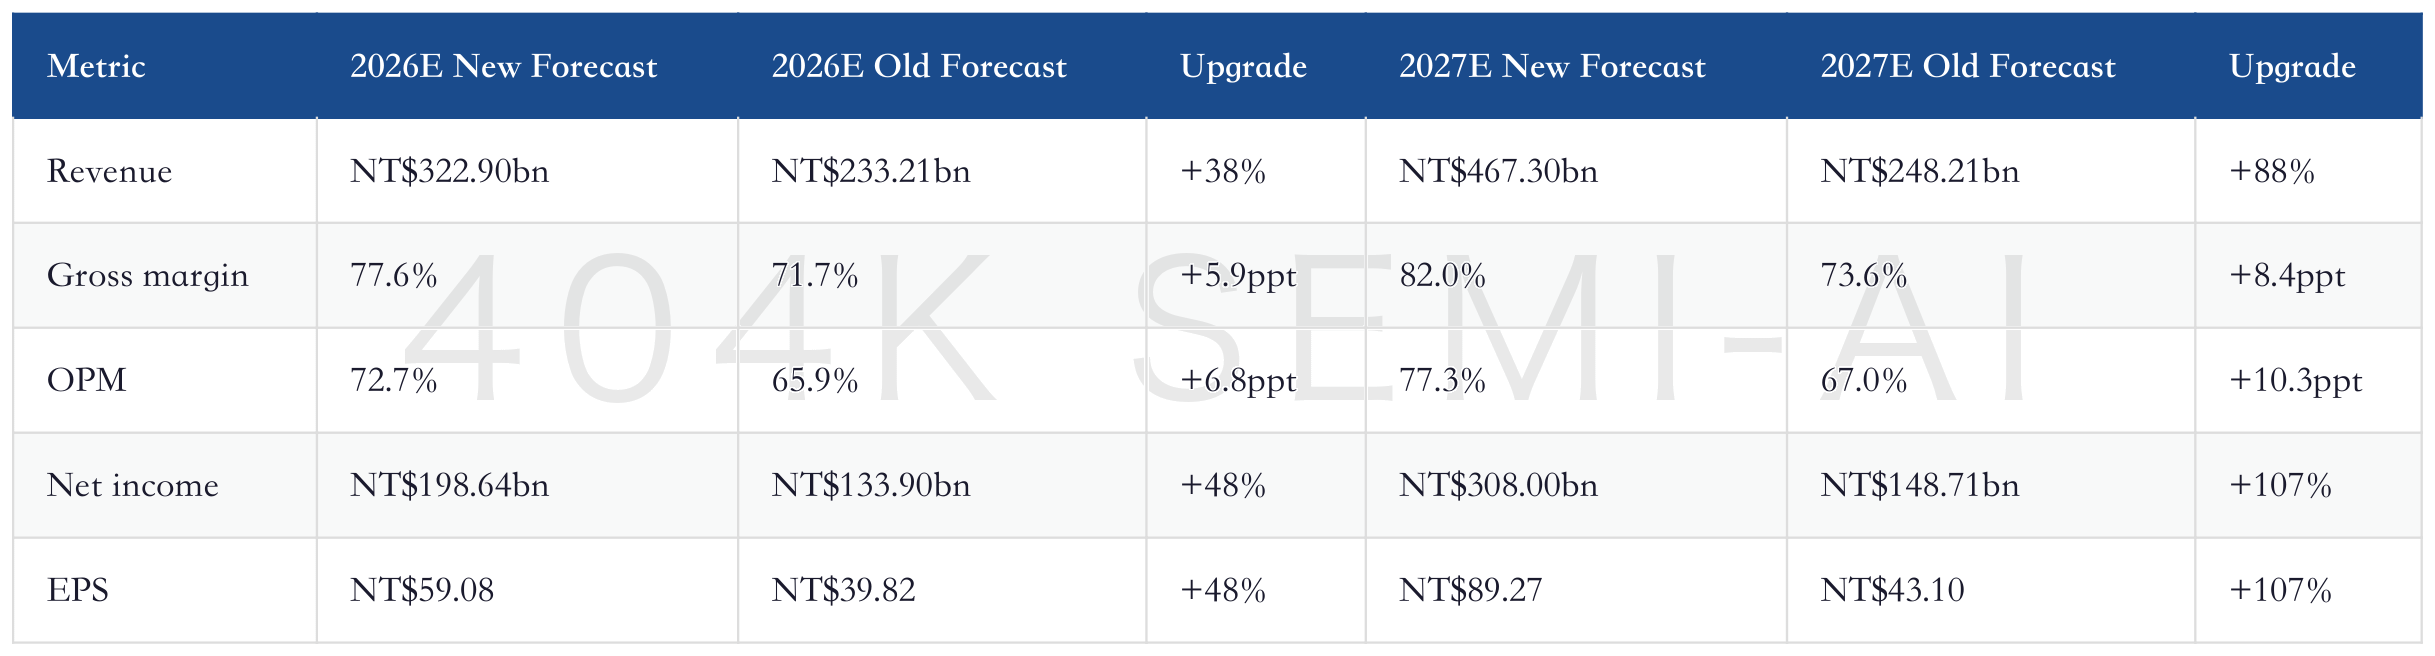
The most important items here are gross margin and OPM. Revenue upgrades can be explained by ASP; margin upgrades mean the sell side believes Nanya Technology is not just passively benefiting from price increases, but may gain better bargaining power through customer structure and product mix. Nanya Technology’s gross margin already reached 68% in 1Q26, showing this direction is not purely hypothetical; but moving from 68% to 77%-82% still requires further validation in 2Q/3Q26.
Memory Is No Longer Just a Cyclical Sector: JPM LTA Breakdown, Agentic AI Memory Multiples, and the Rewriting of Samsung and SK Hynix Valuations
The real question for the market is whether Nanya Technology can enjoy a valuation multiple similar to Korean DRAM leaders. My answer is that it can approach that level in phases, but should not be treated as equivalent without conditions. Korean leaders have a full portfolio across HBM, DDR5, high-end servers, and global major customers. Nanya Technology is more like a high-beta supply-shortage asset. It can capture similar cyclical profits when supply and demand are extremely tight, but it has not yet proven that its technology and customer structure can carry it through the next downturn. Therefore, 8x FY27E EPS can serve as an upcycle target-price framework, but should not be understood as a permanent valuation center.
4. Why DDR4 EOL Is Not a Legacy-Capacity Story, But a Supply-Chain Insurance Story
The investment implication of DDR4 EOL cannot be understood only as “old products getting more expensive.” The cycle for old-product price increases is short: once customers rebuild inventory, prices will fall back. The supply-chain insurance cycle is longer, because customers are not just replenishing spot supply; they are confirming that they will not face shortages over the next 12-24 months.
AI servers have absorbed the capex of mainstream DRAM makers. HBM, advanced DDR5, high-capacity server RDIMM, LPDDR5X, and customized high-bandwidth products all require advanced process technology, advanced packaging, customer qualification, and priority capacity. When Samsung, SK Hynix, and Micron push resources into these products, capacity for legacy DDR4/LPDDR4 passively becomes scarce. Scarcity itself is not value; scarcity plus “customers still must use it” is value.
eSSD is the most typical example. Enterprise SSDs need DRAM as controller cache. If NAND suppliers want to expand AI storage and data-center SSD shipments, they must lock in sufficiently stable DRAM supply. Kioxia Holdings investing in Nanya Technology as a NAND maker and signing a long-term DRAM supply agreement shows this is not a purely financial investment, but a supply-chain security arrangement. Solidigm, SanDisk, and other NAND-related customers participating in the private placement reinforce the same logic: for eSSD, DRAM is not a commodity accessory, but part of product delivery capability.
Networking follows similar logic. Switches, NICs, BMCs, and networking and communications equipment still use large amounts of DDR4 or similar-spec memory. AI cluster expansion requires not only GPUs and HBM, but also switches, network interfaces, storage controllers, and management chips. These links do not have DRAM capacity and bandwidth requirements as extreme as HBM, but they are more sensitive to stable supply and long product lifecycles. Once leading vendors withdraw legacy products from production, customers are willing to exchange long-term contracts for supply.
The value of legacy-spec DRAM comes from application gaps that still cannot do without it
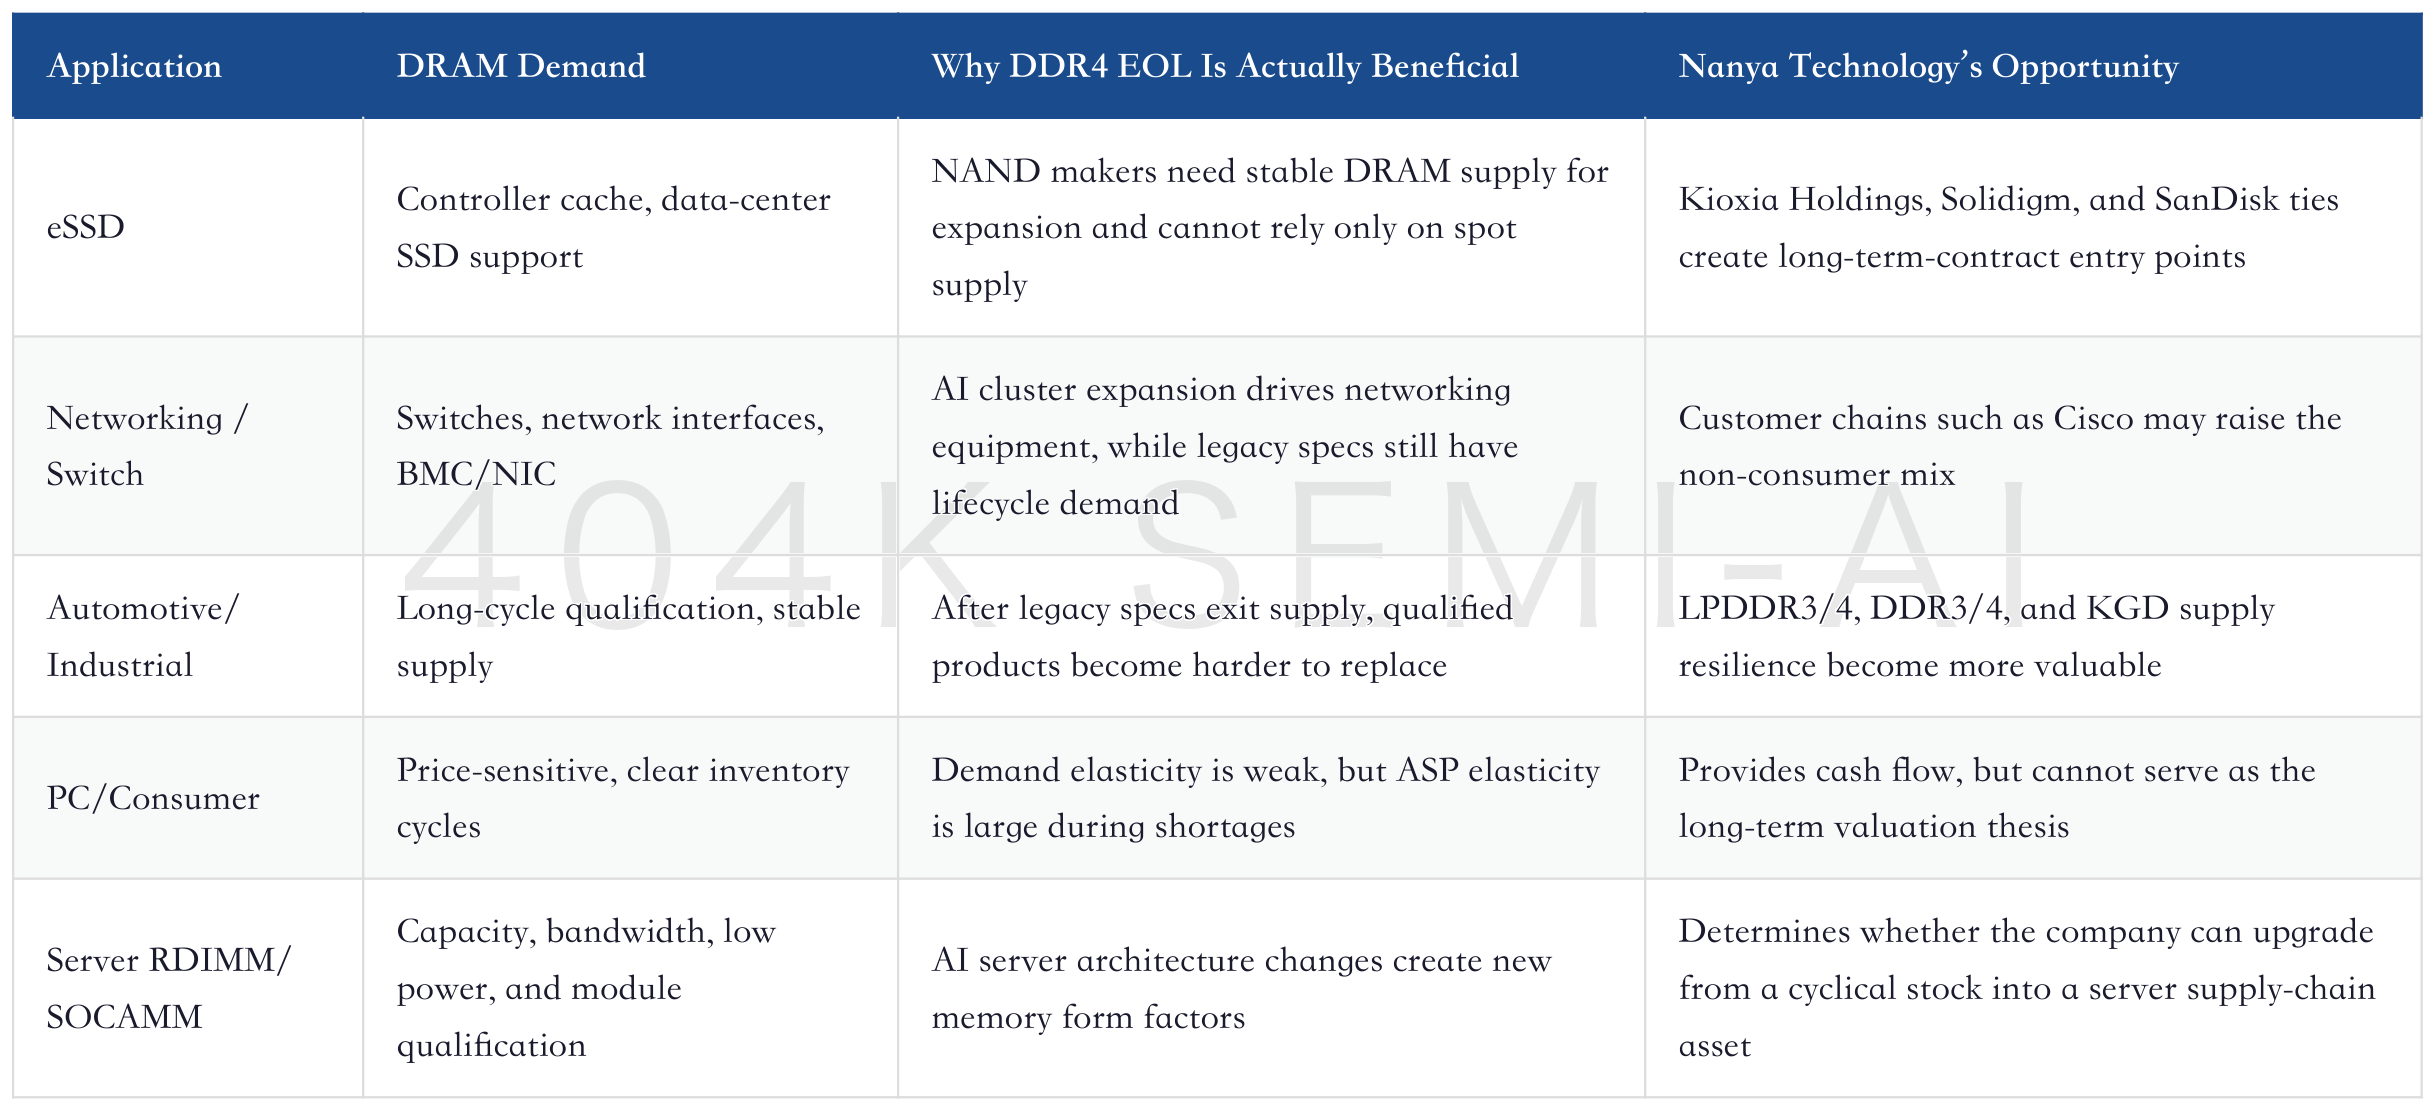
This is also the difference between Nanya Technology and a pure legacy-capacity stock. The company is not merely keeping legacy capacity at low cost; it is using 1B, DDR5, RDIMM, LPDDR5, LPCAMM2, and customized high-bandwidth products to guide old customers toward new products. Legacy products provide cash flow; new products determine the valuation multiple. Looking only at DDR4 pricing misses this transition; looking only at the SOCAMM story overestimates the speed of technology delivery.
JPMorgan’s logic that “all DRAM moves together in an upcycle” is ultimately based on supply-chain insurance. Mainstream investors like to buy high-end products because HBM and DDR5 have stronger technology stories. But when tight supply spreads across all nodes, customers do not necessarily buy only the most advanced products; they also buy the most reliable products, the least likely to be cut off, and those most capable of being locked into long-term supply agreements. That is where Nanya Technology’s value lies.
Rubin Will Consume Smartphone Memory in 2027: Why Nvidia Is Taking Smartphone Memory, and How Vera Rubin Rewrites DRAM Capacity Prioritization
The risk also comes from here. If DDR4 EOL is only a short-term withdrawal, customers can ease the gap through inventory, alternative materials, platform migration, and restocking from Chinese suppliers. If customers accelerate the shift from DDR4 to DDR5, Nanya Technology’s high ASPs for legacy specs will fall back quickly. What Nanya Technology needs to prove is that what it is selling is not just old inventory, but supply insurance for customers’ future product roadmaps.
V. SOCAMM and Server Memory: Nanya Technology’s Second Growth Curve Is Still in Early Validation
SOCAMM is the term in this report most likely to excite the market, but it is not yet realized profit. It is more like an admission ticket: if AI servers and ARM-architecture CPUs create new board-level memory form factors, second-tier DRAM vendors may have a chance to enter the supply chain through low power consumption, high bandwidth, modular packaging, and customer qualification. If product qualification is slow and share is low, SOCAMM will remain only a valuation story, not a profit driver.
Nanya Technology has the foundation to enter this track. Its 2025 annual report disclosed that the company increased sales of RDIMM modules for server applications and captured demand from BMC, NIC, and other applications; 128Gb DDR5 RDIMM 5600/6400 has passed functional testing; 16Gb DDR5 mono-die has reached 7200 MT/s; customized ultra-high-bandwidth product design is underway; the company also plans to co-develop high-performance, low-power, ultra-high-bandwidth memory solutions with partners and expects revenue contribution in 1H27. This shows Nanya Technology is not stopping at DDR4, but is filling gaps in server and low-power high-bandwidth capabilities.
But a foundation does not equal share. Data center and server revenue accounted for only about 5% in 2025, meaning Nanya Technology’s server business is still at a low base. JPMorgan noted that server-side market exposure could continue expanding from low double digits, and every 100bps of SOCAMM share could bring substantial revenue potential. That leverage is attractive, but it must be proven through customer validation, design-ins, volume shipments, and long-term pricing.
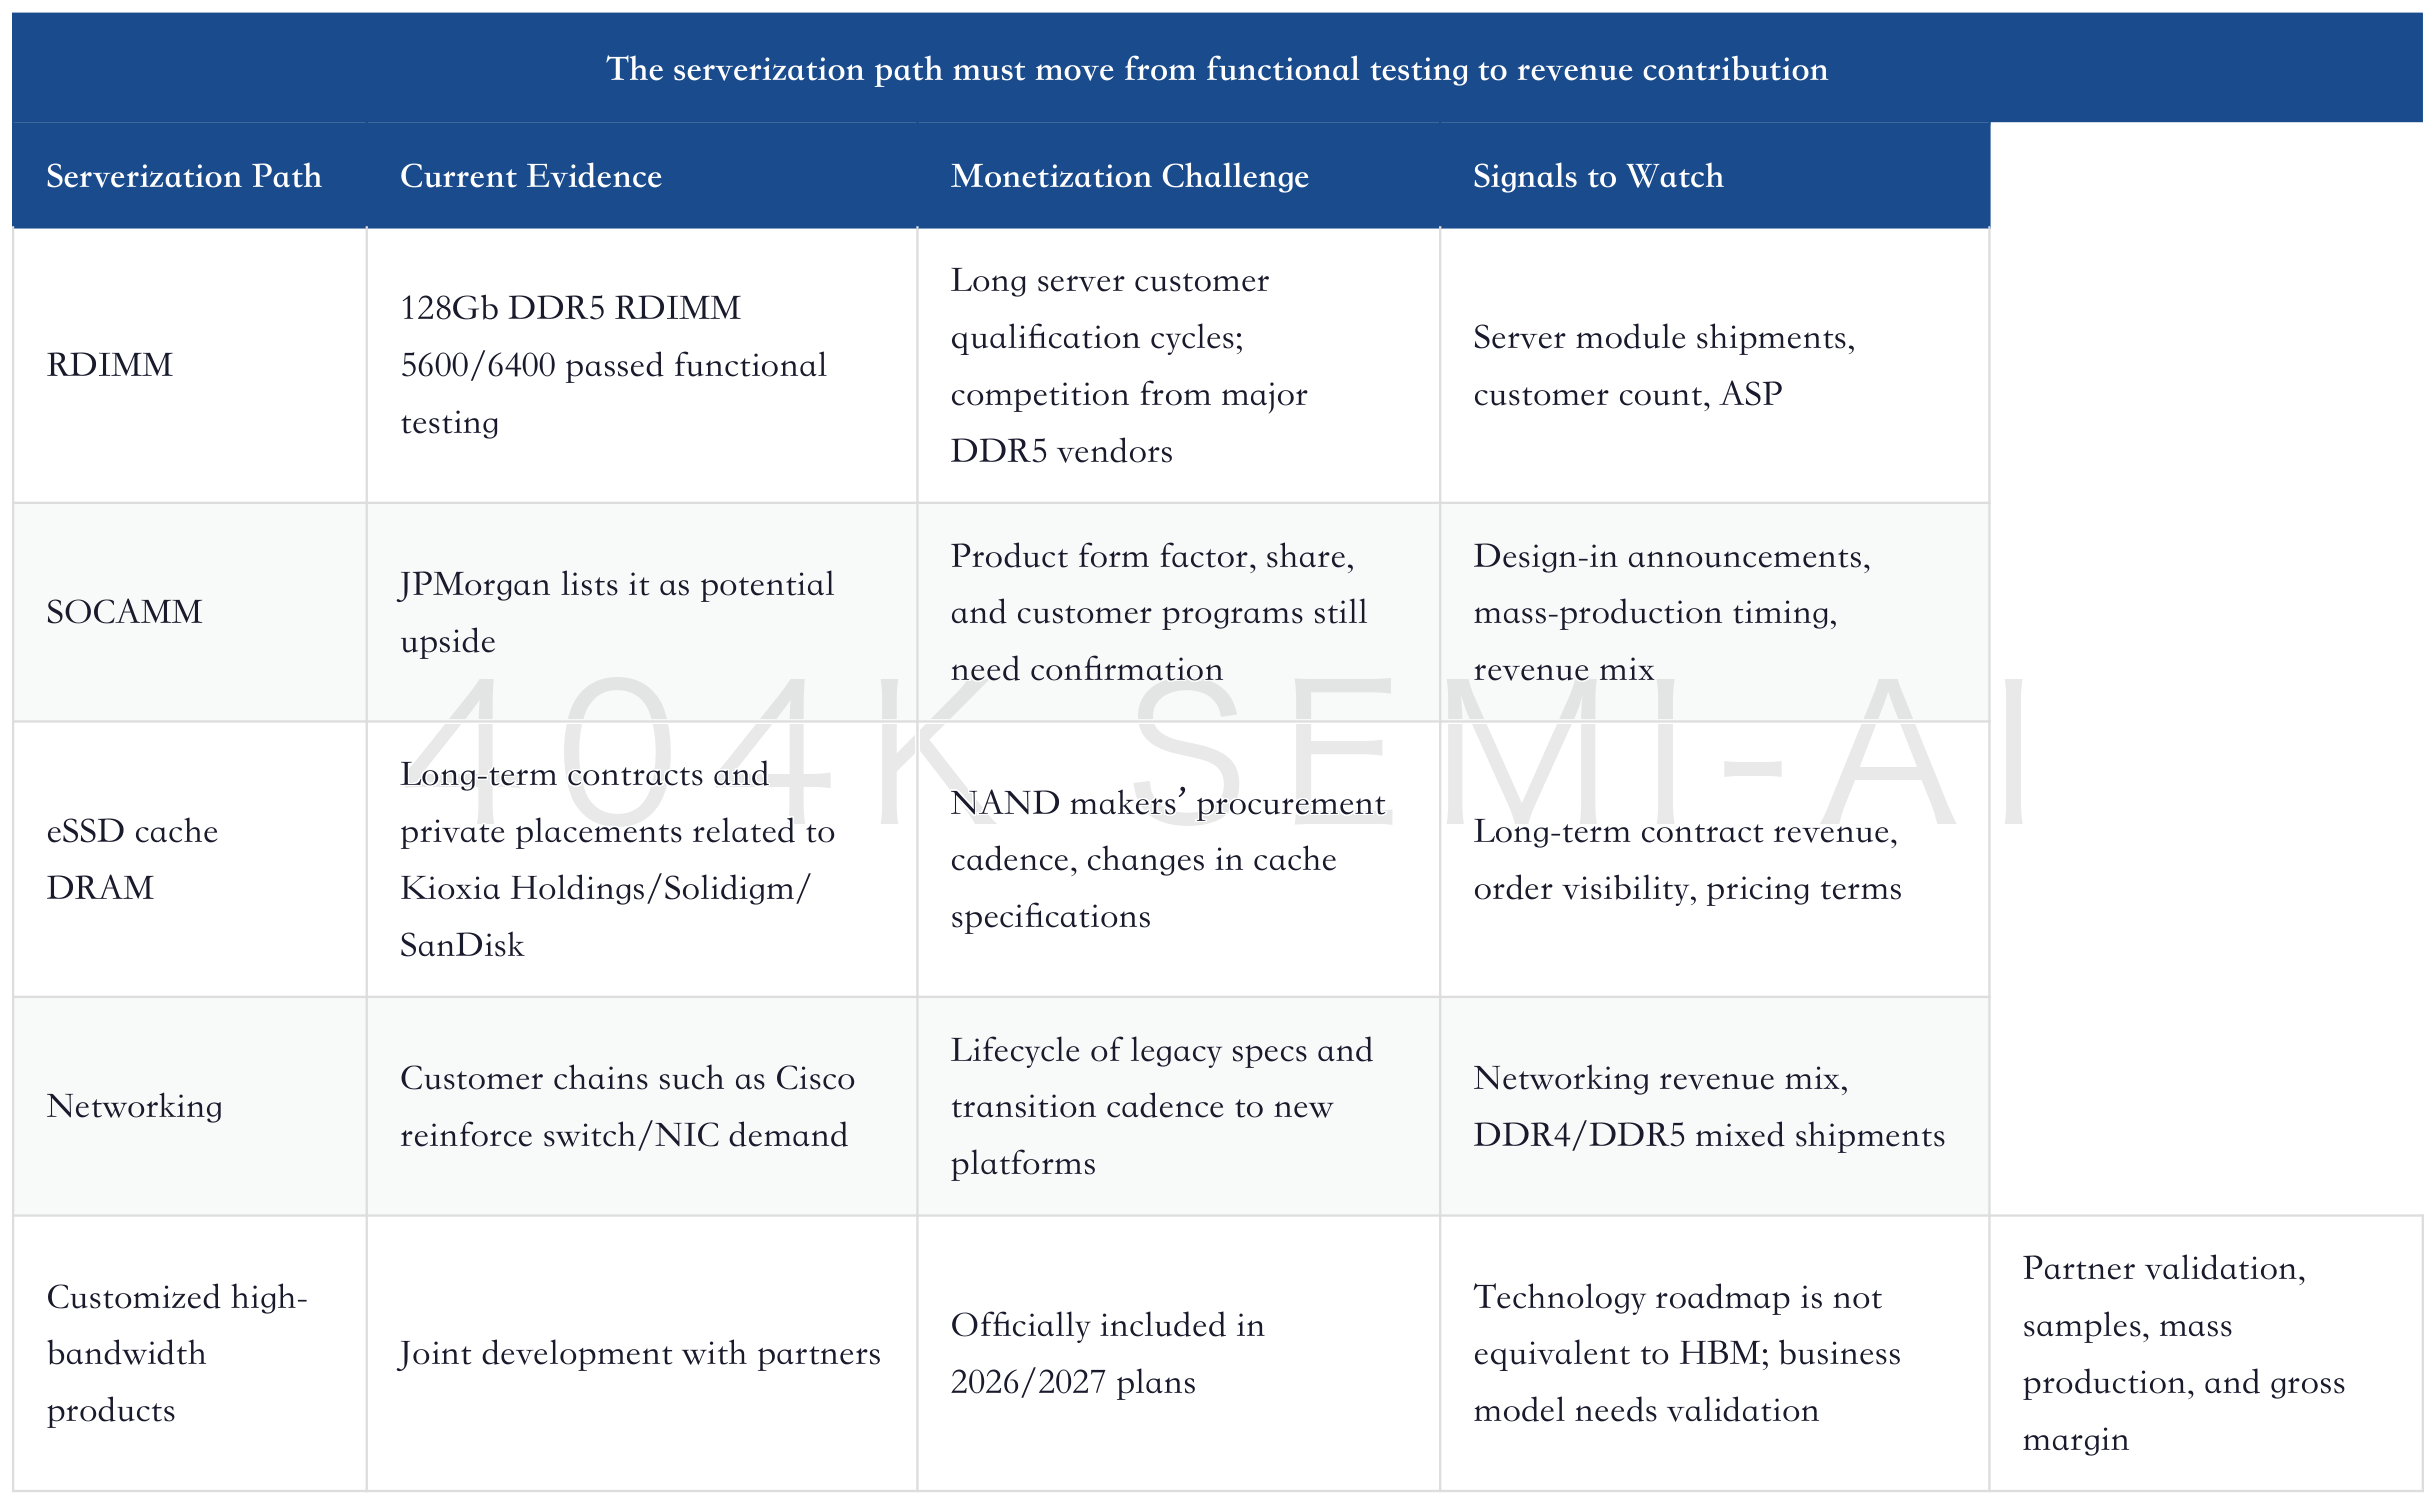
If Nanya Technology only benefits from DDR4 price increases, its valuation ceiling will mainly be determined by the pricing cycle. If it can lift server revenue from 5% to 10%, 15%, or even higher, the valuation logic changes. Server products usually require more rigorous qualification, place greater emphasis on stable supply, are more likely to be covered by long-term contracts, and better explain the sustainability of high OPM. JPMorgan’s NT$710 target is essentially an early bet on this structural shift.
My base-case view is that SOCAMM should not be the primary variable in Nanya Technology’s investment thesis. The primary variables remain DDR4/LPDDR4 supply exits and long-term contracts in eSSD/Networking, because these have already translated into orders and pricing. SOCAMM is a second-layer upside option: it explains why the market is willing to imagine Nanya Technology migrating from a cyclical stock toward a server supply-chain asset, but in the financial model it should be treated with scenario weighting rather than booked directly as certain revenue.
This point is important. Many valuation errors in second-tier semiconductor companies come from treating “having samples” as “having share,” and treating “having a roadmap” as “having profit.” For Nanya Technology to firmly support NT$710, SOCAMM/RDIMM/customized memory must move from the roadmap into the shipment schedule, and then from the shipment schedule into gross margin. Without that process, valuation will retreat quickly after DDR4 prices peak.
VI. 1B, 1C/1D, and Fab 5A: This Is Not a Capacity Expansion Story, but a Cost and Product Moat Story
Nanya Technology’s 2026 capex ceiling of NT$52 billion looks like capacity expansion on the surface. More precisely, it is “using peak-cycle cash flow to buy the next round of product qualifications.” The mistake DRAM companies most often make in an upcycle is confusing high prices with long-term demand, blindly expanding capacity and then bearing depreciation pressure in the downcycle. Nanya Technology needs to do something different: allocate capex to 1B, 1C/1D, Fab 5A, server modules, and customized products, rather than simply increasing legacy DDR4 wafer volume.
The official annual report disclosed that the 1B process accounts for about one quarter of the company’s monthly wafer starts and can contribute up to about 40% of die output; 16Gb DDR5, 8Gb DDR4, and 4Gb DDR4 are already in mass production and shipping to customers. 1B is the foundation of current profit realization because it covers both DDR4 and DDR5, allowing the company to switch between legacy product price increases and new product validation. JPMorgan also noted that DDR5’s revenue contribution remained low in early 2026, but existing DDR4 capacity can be converted to DDR5 within 3-6 months, giving the company some optionality.
1C/1D is the key after 2027. The company disclosed that 1C 16Gb DDR5 pilot products entered trial production in 3Q25, and 1D pilot products are expected to enter trial production in 2Q26. They may not immediately change the revenue mix, but they will determine whether Nanya Technology can continue serving DDR5, LPDDR5, server modules, and customized high-bandwidth products after the DDR4 peak. For investors, 1C/1D is not technology news, but the valuation discount period.
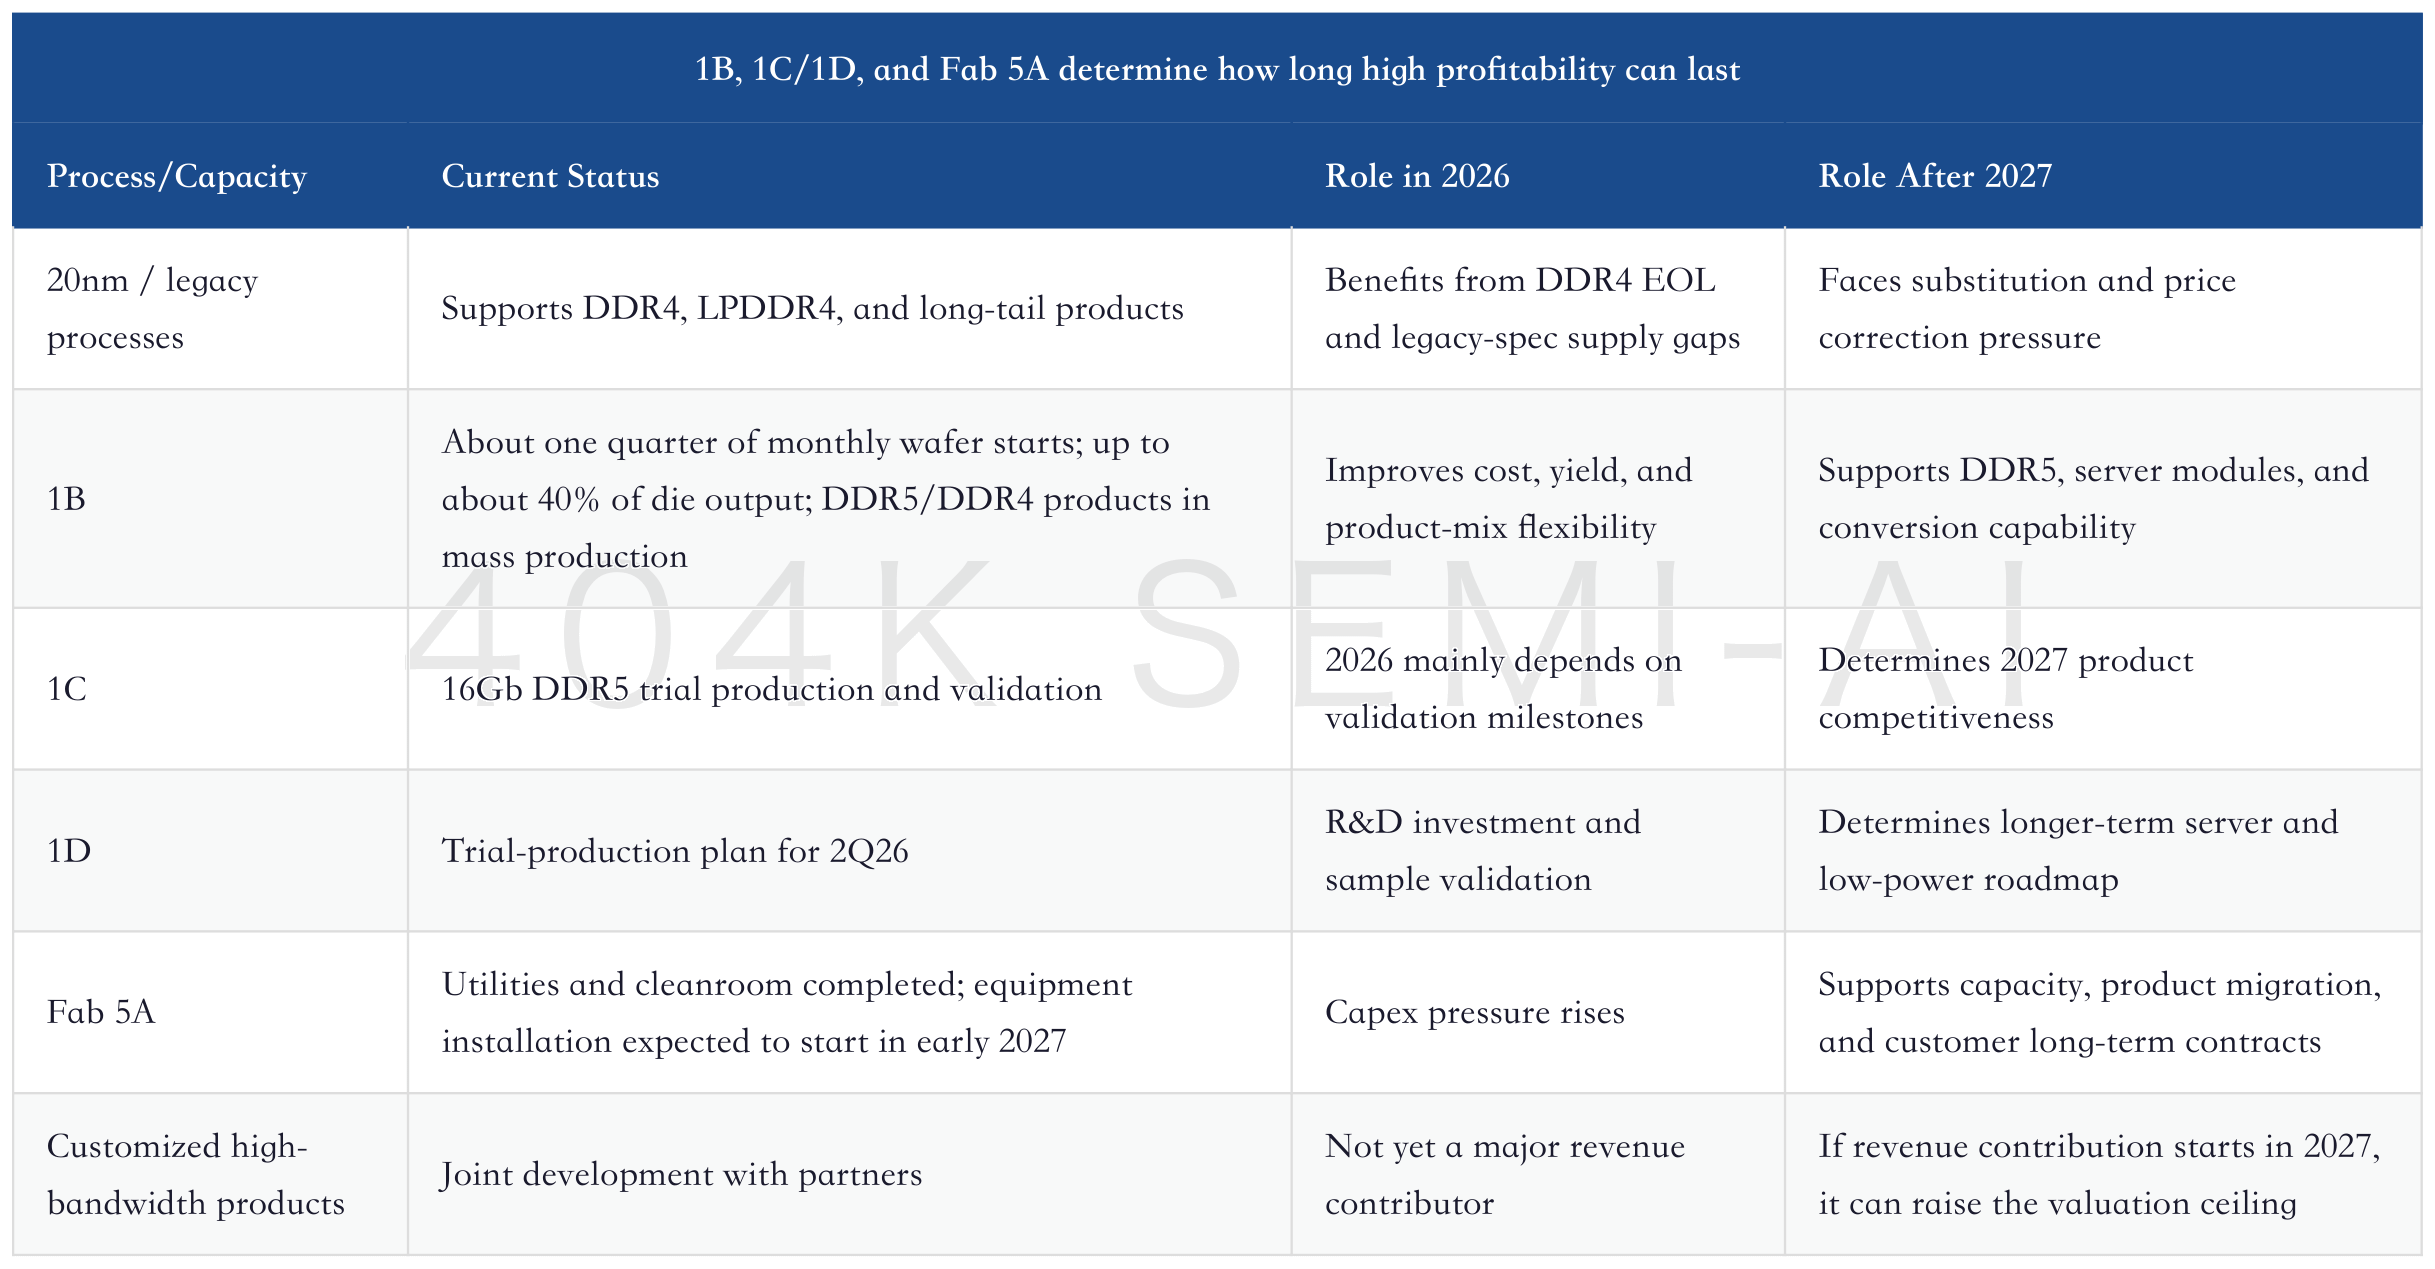
Fab 5A also should not be understood only as capacity expansion. The annual report shows that utilities and the cleanroom for the new fab have been completed, and process equipment installation is expected to begin in early 2027. This timing aligns with JPMorgan’s FY27E EPS peak: 2026 profit comes from pricing and existing capacity, while 2027 needs new products, customer long-term contracts, and stronger processes to retain profitability. If Fab 5A merely adds commodity capacity, the risks are depreciation and oversupply; if it supports servers, low-power products, customized products, and advanced DDR5, then it is a true moat investment.
There is a counterintuitive point here: the best case for Nanya Technology is not the fastest capacity growth, but the scarcest capacity that can be locked in by customers. JPMorgan assumes 12-inch-equivalent monthly capacity will stay roughly stable at 62k wpm in 2026, rise quarterly to 72k wpm in 2027, and then reach 76k wpm in 2028. The profit surge in the model mainly comes from ASP and margin improvement, not a capacity explosion. This means Nanya Technology does not need major capacity expansion to prove its value; instead, it needs capacity discipline to prove that high profitability is sustainable.
In JPMorgan’s model, the profit surge mainly comes from ASP, not a capacity explosion
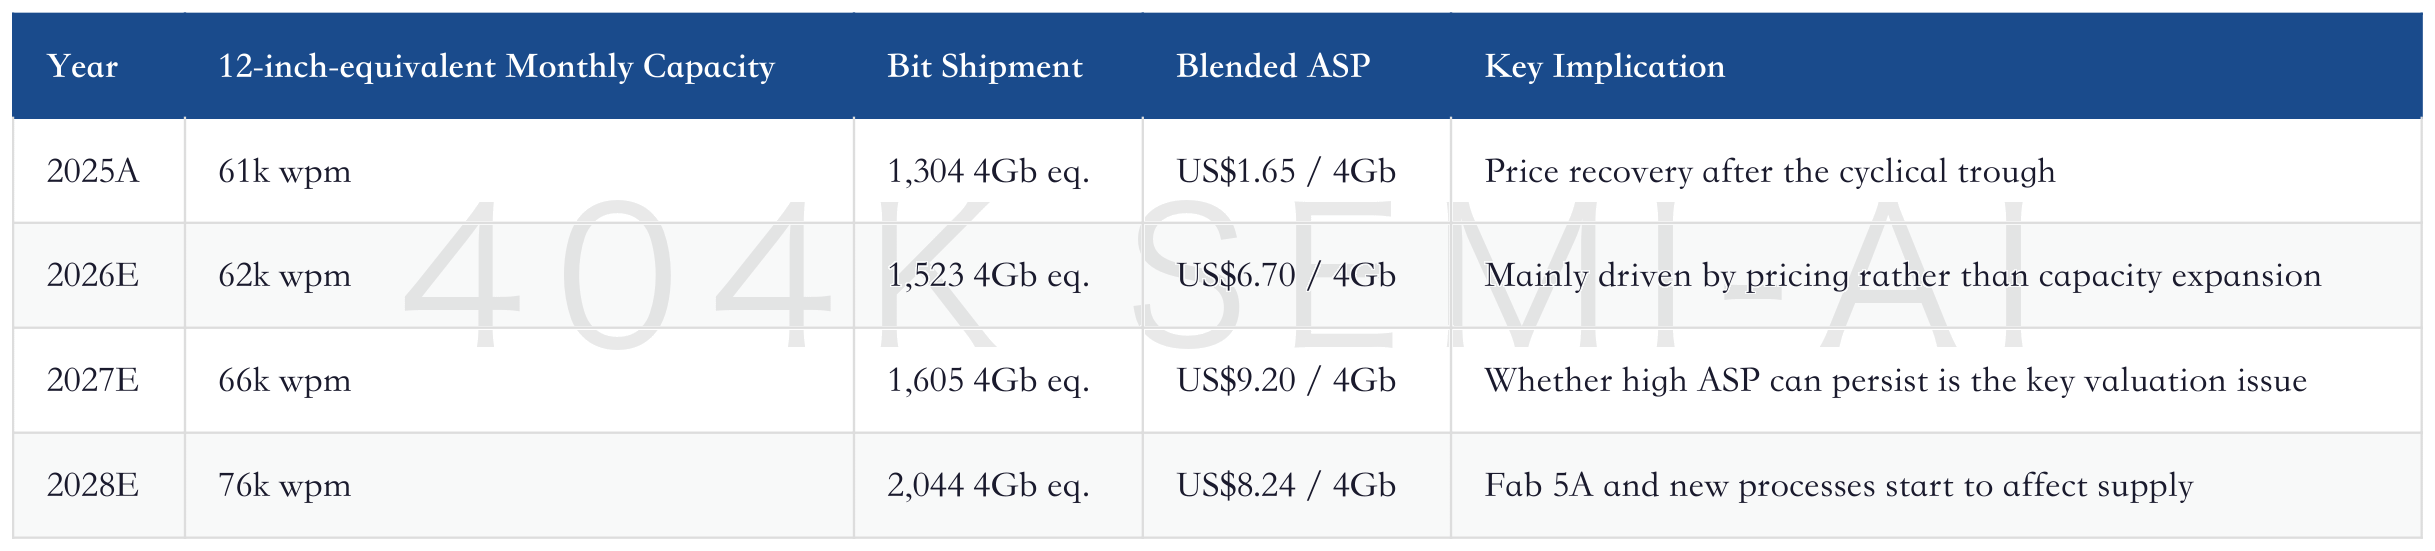
This table also explains why the risk is concentrated in pricing. If ASP cannot stay high in 2027, modest capacity growth will not offset margin compression. If Fab 5A brings more shipments in 2028 but industry pricing has already turned down, valuation will shift from EPS multiples back to PB and depreciation cycles. Therefore, Nanya Technology’s capex is not “the higher the better”; the key is whether it brings customer lock-in, product upgrades, and cost reduction.
VII. Valuation: NT$710 Is Defensible, but It Is Not a Low-Risk Target Price
The NT$710 target price looks high, but in substance it is FY27E EPS of NT$89.27 multiplied by 8x. The calculation is simple; the difficult question is whether 8x is justified. Traditional second-tier DRAM vendors can also generate large profits in an upcycle, but the market is usually unwilling to assign high multiples because investors worry that EPS is at a peak. JPMorgan is willing to give 8x this time because it believes this cycle will be longer, DDR4 and DDR5 prices will rise together, and servers plus long-term contracts will make profit sustainability higher than in the past.
Based on Nanya Technology’s NT$409.5 share price on July 3, 2026, the stock trades at about 7.0x JPMorgan’s 2026E EPS, about 4.6x 2027E EPS, and about 4.0x 2028E EPS. This valuation is not expensive, but the sense of cheapness depends entirely on earnings delivery. If 2027E EPS is revised down to NT$50, the current price is above 8x; if EPS really reaches NT$89.27, NT$710 is also only 8x and not excessive.
The NT$710 target price depends on both FY27E EPS and the valuation multiple holding
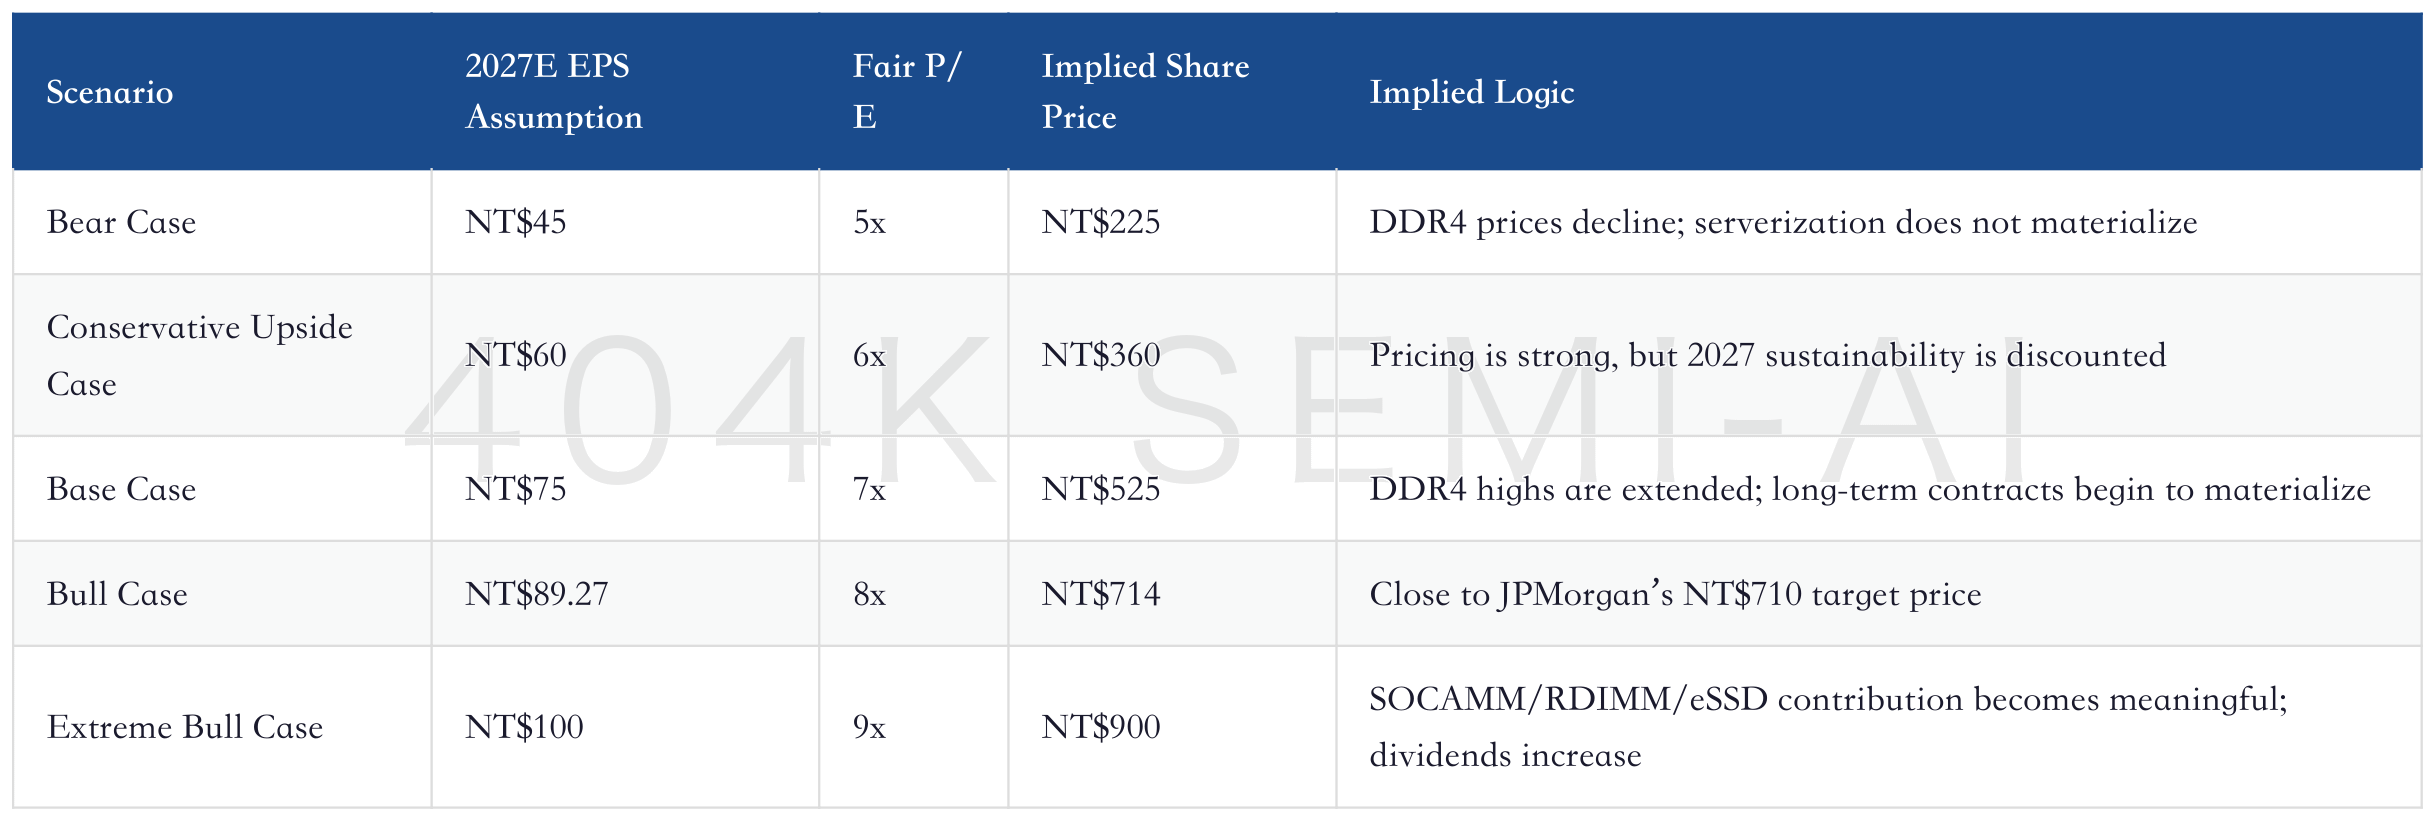
This scenario table is more useful than a single target price. Nanya Technology currently trades on a double click of “earnings slope” and “valuation multiple.” If only earnings are revised up, the market may assign 5-6x; only if earnings are revised up while server revenue mix rises, long-term contracts become visible, FCF is strong, and dividends improve will the market assign 8x or even higher. The key to NT$710 is not the share-price upside, but whether 8x FY27E EPS can be treated as the new-cycle midpoint.
JPMorgan also provides a shareholder-return anchor: from 2026 to 2028, the company may generate about NT$690 billion of cumulative FCF, and under a conservative 35% payout assumption, FY27E/FY28E dividend yields are estimated at 5.5%/8.6%. This framework is attractive because it turns Nanya Technology from a pure pricing trade into a cash-return trade. If a second-tier DRAM vendor only benefits from price increases, valuation is hard to stabilize; if it can sustain FCF and dividends, the valuation discount will narrow.
But dividends are not free. Nanya Technology’s 2026 capex ceiling is NT$52 billion, and Fab 5A equipment installation, 1B/1C/1D, customized products, and server modules all require cash. The roughly NT$78.7 billion private placement in April 2026 did strengthen the balance sheet, and cash of NT$86.28 billion at the end of 1Q26 was also substantial. But if the company decides to accelerate capacity and R&D;, the actual payout may not reach what investors imagine. Cash returns depend on board-level capital allocation, not only modelled FCF.
My valuation view is that Nanya Technology can now shift from a traditional PB cyclical stock to an EPS/FCF framework, but only with a “conditional re-rating.” Conditional re-rating means that when FY27E EPS is close to NT$90, 8x is acceptable; if FY27E EPS is revised below NT$60, 8x becomes expensive. From an investment action perspective, investors cannot focus only on the target price; quarterly pricing, gross margin, server revenue, long-term contracts, and capex cadence need to be tracked on the same sheet.
8. Sell-Side Divergence: Why Nanya Technology’s Risks Are More Concentrated Despite the Same Positive View on Memory
Across multiple sell-side firms, the common direction for memory is upward revisions. DRAM and NAND supply discipline, AI servers, HBM displacement, eSSD demand, and DDR4 EOL are all pushing memory profitability higher into 2026. The difference is that the logic for the Korean leaders is more about high-end products and technology share, while Nanya Technology’s logic is more about legacy-product supply gaps and customer lock-in. This means Nanya Technology has higher earnings torque, but the thesis can also be invalidated faster.
For the Korean leaders, the risks are HBM share, advanced processes, customer pricing, and capex. For Nanya Technology, the risks are more direct: whether DDR4/LPDDR4 prices remain high, whether CXMT accelerates supply, whether customer long-term agreements can truly lock in eSSD/Networking demand, and whether SOCAMM and RDIMM can contribute revenue. It does not have the same technology moat as the HBM leaders, nor Samsung’s full-chain ability to absorb cyclicality.
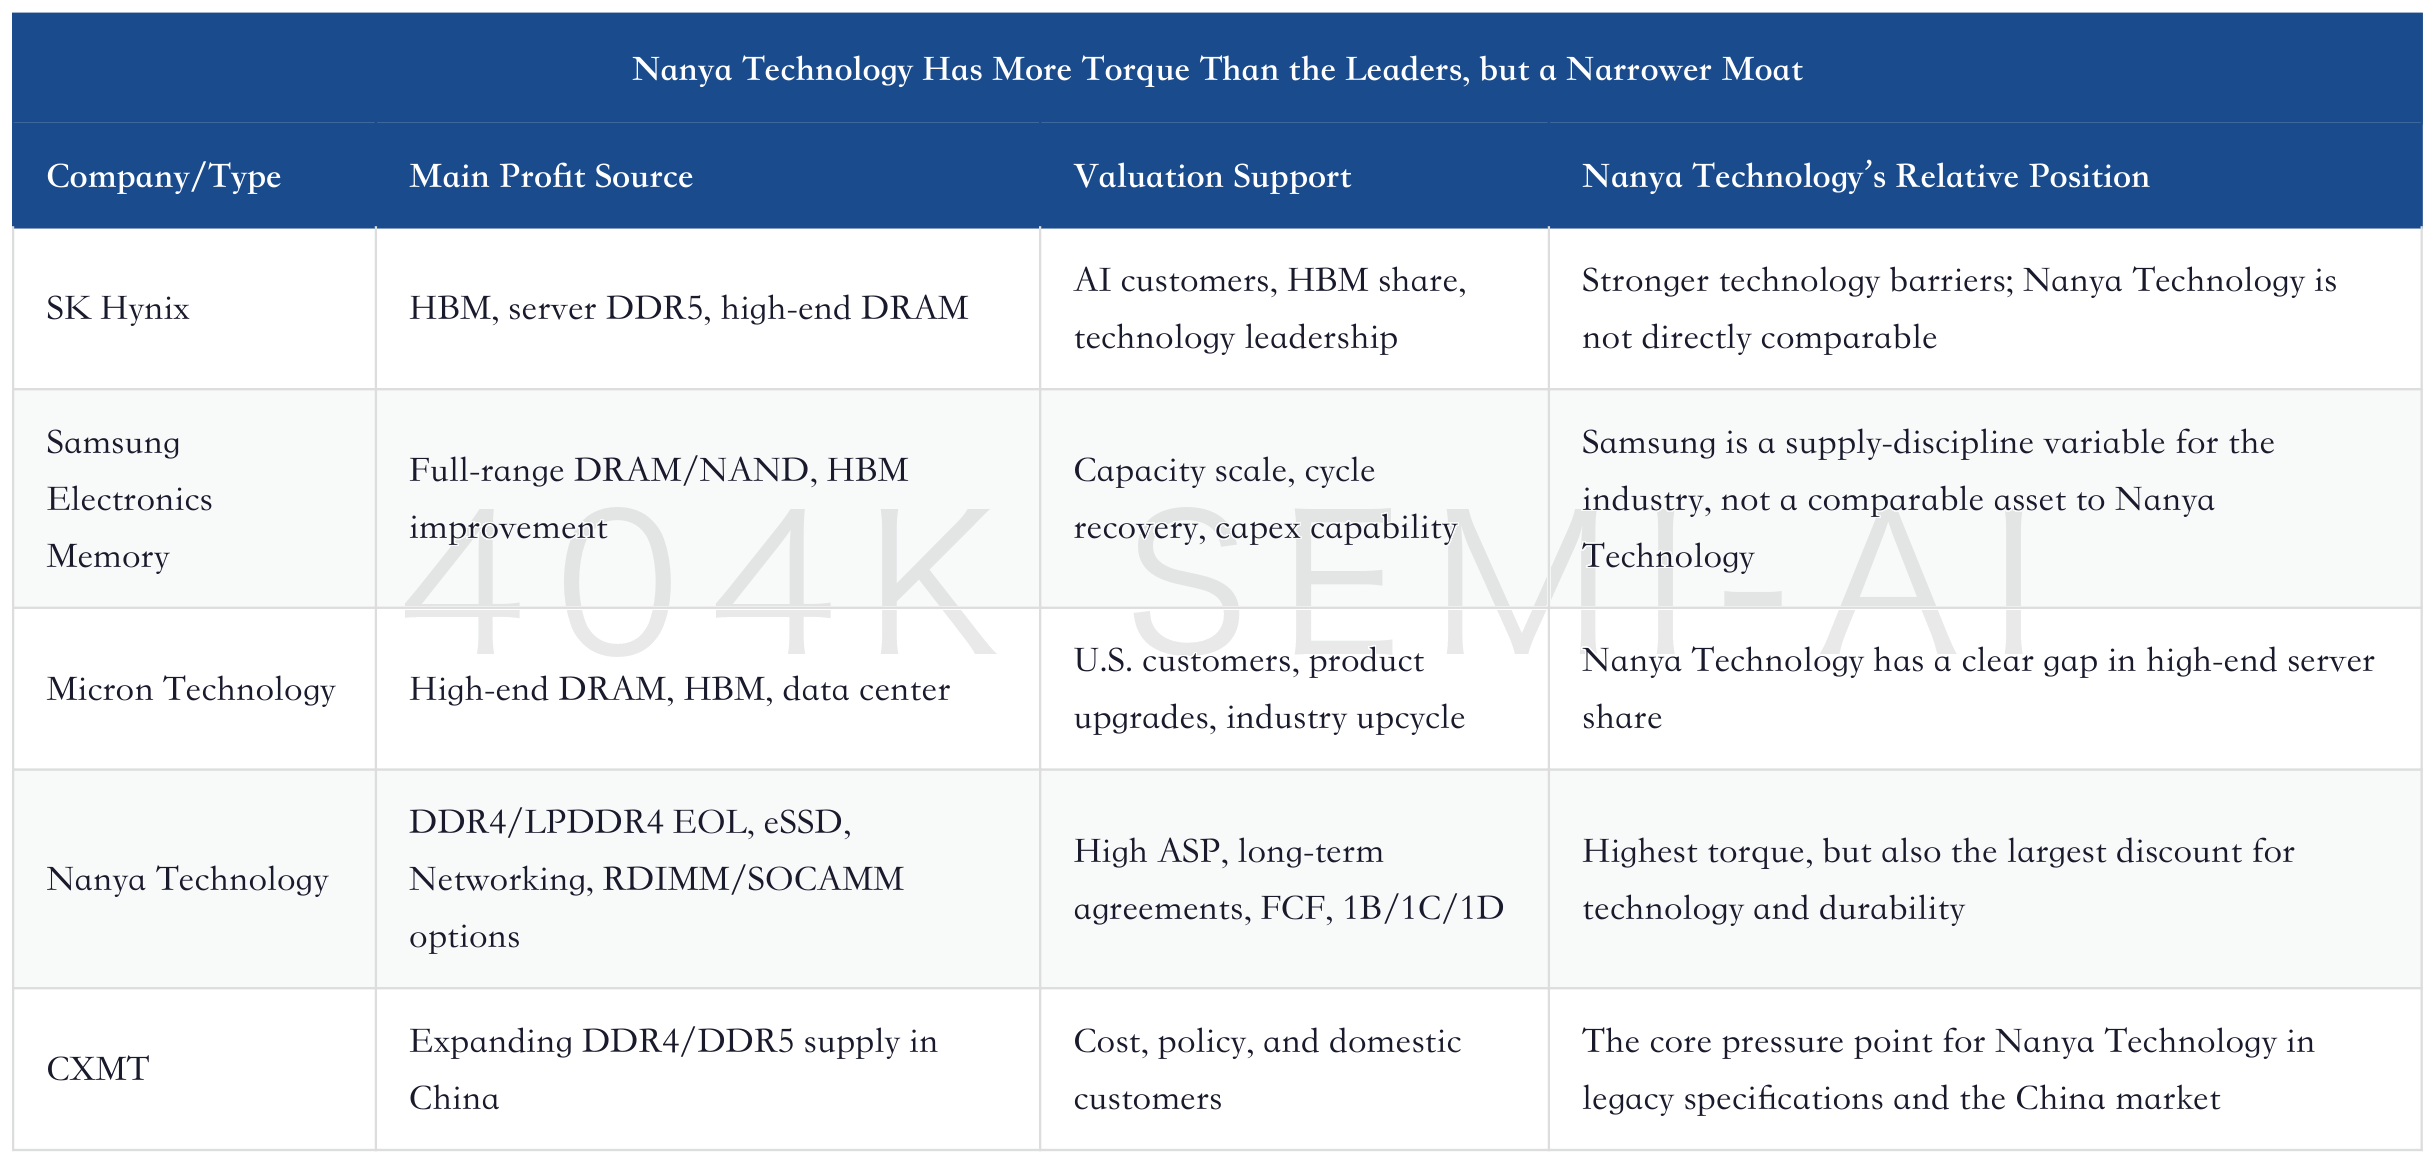
CXMT deserves particular attention here. Nanya Technology’s 2025 annual report already listed capacity expansion by Chinese DRAM manufacturers as a risk, noting that CXMT capacity could reach 300,000 wafers per month by the end of 2025, and that it had already started DDR5 mass production in December 2024. CXMT’s products overlap with Nanya Technology’s, which will affect sales strategy, pricing, and margins in the China market. Nanya Technology’s response is to differentiate by product and application, consolidate demand that CXMT has difficulty supplying, develop customized products, raise the share of sales outside China, and negotiate long-term supply with key customers.
This official risk disclosure matters because it reminds investors that DDR4 EOL does not mean a permanent global shortage of legacy DRAM. Korean and U.S. leaders exiting part of their legacy-specification capacity will create supply gaps; capacity expansion by Chinese DRAM manufacturers will add supply back in some markets. Whether Nanya Technology can sustain high ASPs depends on whether it can avoid pure commoditized competition and shift toward long-term agreements, non-China markets, automotive, industrial, eSSD, Networking, and server qualification.
One reason JPMorgan is optimistic on Nanya Technology is that it believes Nanya Technology and Chinese DRAM competitors have some customer and product mismatch. This judgment is acceptable, but it should not be extrapolated too far. Mismatch is not a moat. Customer qualification, long-term supply agreements, special specifications, and stable delivery are the real moats. If Nanya Technology can sell legacy DRAM into more stable server, networking, storage, and automotive customers, CXMT’s impact will be buffered. If it still mainly sells standardized consumer DRAM, price competition will eventually return.
9. Financial Quality: 1Q26 Was Very Strong, but Do Not Treat One Quarter’s Profit as Permanent
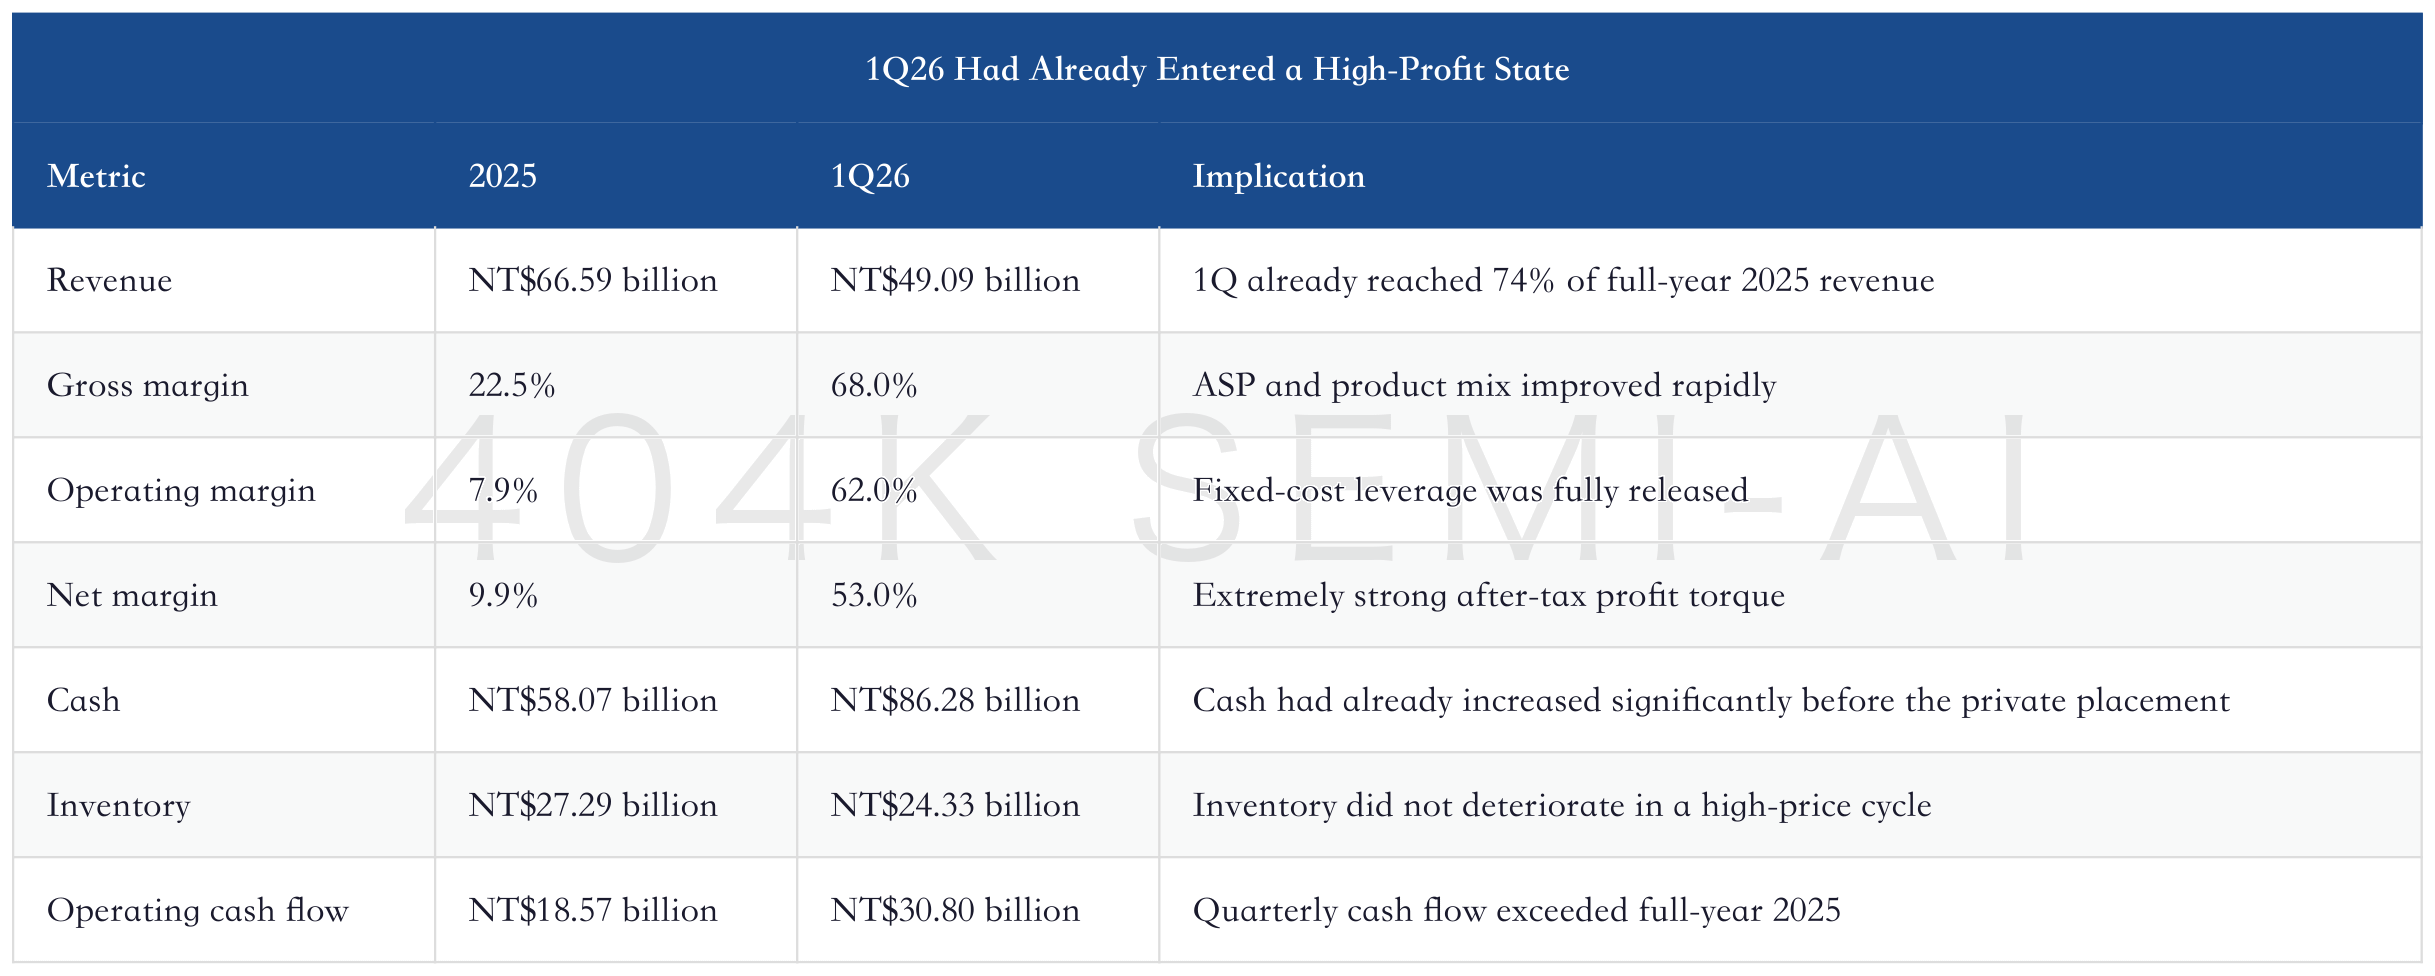
Nanya Technology’s 1Q26 financial results were very strong. Quarterly revenue was NT$49.09 billion, versus only NT$7.19 billion in the same period last year. Gross profit was NT$33.32 billion, with a 68% gross margin. Operating profit was NT$30.11 billion, with a 62% operating margin. Net profit after tax was NT$26.06 billion, with a 53% net margin. This is no longer just a turnaround; it is a high-profit state in an upward pricing cycle.
Cash flow was also solid. In 1Q26, operating cash inflow was NT$30.80 billion, capex cash outflow was about NT$2.81 billion, inventory declined from NT$27.29 billion at end-2025 to NT$24.33 billion at end-1Q26, and cash rose from NT$58.07 billion to NT$86.28 billion. After the private placement was completed in April, another roughly NT$78.7 billion of capital was added, giving the balance sheet the capacity for expansion and R&D; investment.
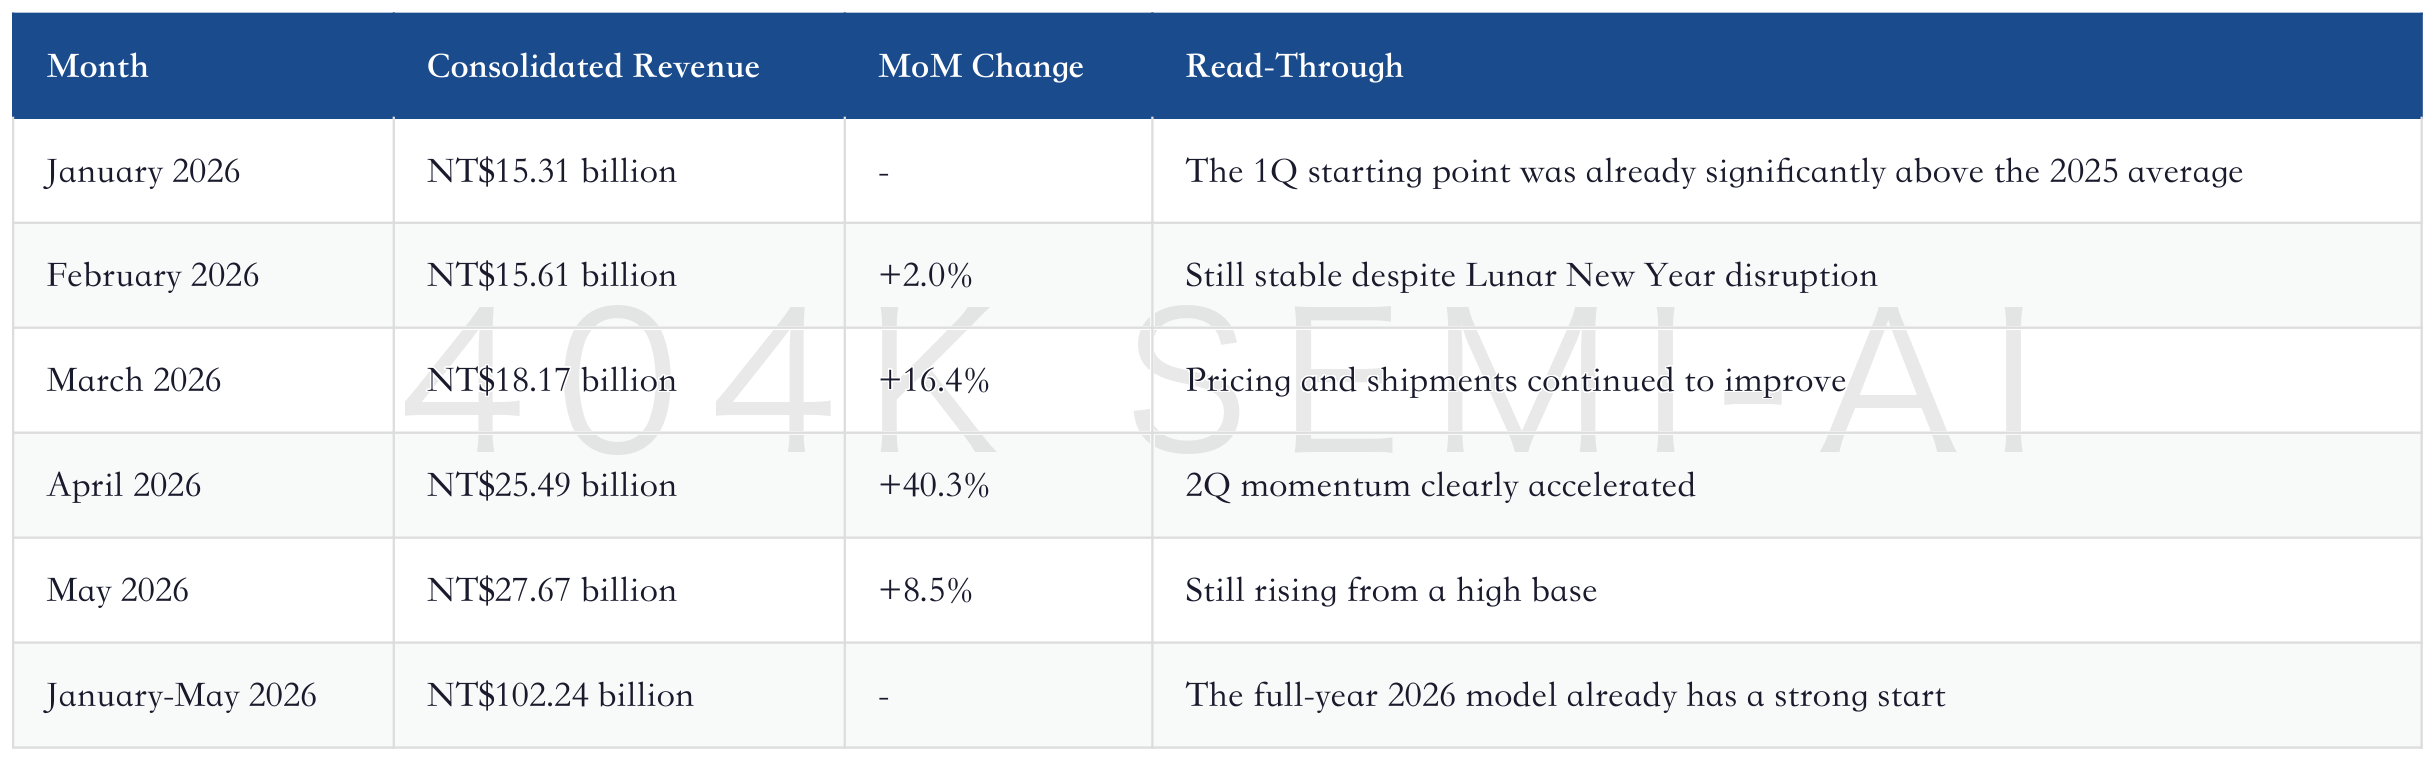
May monthly revenue further strengthened the near-term cycle. Cumulative consolidated revenue for January-May 2026 was NT$102.24 billion, including NT$15.31 billion in January, NT$15.61 billion in February, NT$18.17 billion in March, NT$25.49 billion in April, and NT$27.67 billion in May. Consecutive increases in monthly revenue show that pricing and shipment trends remained strong in 2Q26, giving JPMorgan’s expectations for high profitability in 2Q/3Q26 a real basis.
Monthly Revenue in the First Five Months of 2026 Confirms the Cycle Is Still Accelerating
But investors should not directly annualize 1Q26’s 68% gross margin and 53% net margin. These margins are inherently cyclical, driven by simultaneous tailwinds from ASP, inventory cost, capacity utilization, and fixed-cost dilution. If prices remain high, profits will continue to be amplified. If prices decline, gross margin will fall just as quickly. Nanya Technology’s financial quality is improving, but it remains high-beta financial quality, not stable consumer-staples-style financial quality.
A more accurate judgment is that 1Q26 gave Nanya Technology an “entry ticket” for valuation re-rating, not a “graduation certificate.” The entry ticket is that the company has proven with actual financials that DDR4/LPDDR4 supply exit can generate real profits. The graduation certificate would be that in 2H26 and 2027, after normal ASP volatility, rising capex, execution of long-term customer agreements, and server product introductions, the company can still sustain high ROE and high FCF. That certificate has not yet been earned.
10. Three Worldviews: Which Future Will Nanya Technology’s Share Price Ultimately Trade?
The investment debate around Nanya Technology can be split into three worldviews. These are not about right or wrong, but about different weights assigned to supply durability, customer long-term agreements, and product upgrades.
The first is “short-cycle squeeze.” In this world, DDR4/LPDDR4 price increases mainly come from customer restocking and near-term capacity shifts by major manufacturers. After 2H26, as inventories are replenished, platforms migrate, and Chinese supply increases, prices fall quickly. Nanya Technology’s 2026 EPS is very high, but 2027 is revised down significantly. In this world, the company’s reasonable valuation is closer to a discounted cyclical peak earnings framework, with roughly 5x EPS or a PB framework more appropriate.
The second is “long-cycle supply-chain insurance.” In this world, AI servers continue to crowd out advanced capacity, major manufacturers have no incentive to return to DDR4/LPDDR4 at large scale, and eSSD, Networking, automotive, industrial, and edge-server demand is willing to lock in supply through long-term agreements. Nanya Technology can maintain high profits in both 2026 and 2027, with FCF and dividends becoming valuation anchors. In this world, 8x FY27E EPS can be justified.
The third is “serverization re-rating.” In this world, Nanya Technology is not just legacy-specification supply insurance, but also enters the AI server peripheral memory supply chain through RDIMM, SOCAMM, LPDDR5, LPCAMM2, and customized high-bandwidth products. Server revenue share rises from 5% toward 15% or even higher, customer long-term agreements improve visibility, and the market starts to assign it a multiple closer to server supply-chain assets. In this world, NT$710 is not the endpoint, but a neutral-to-optimistic target.
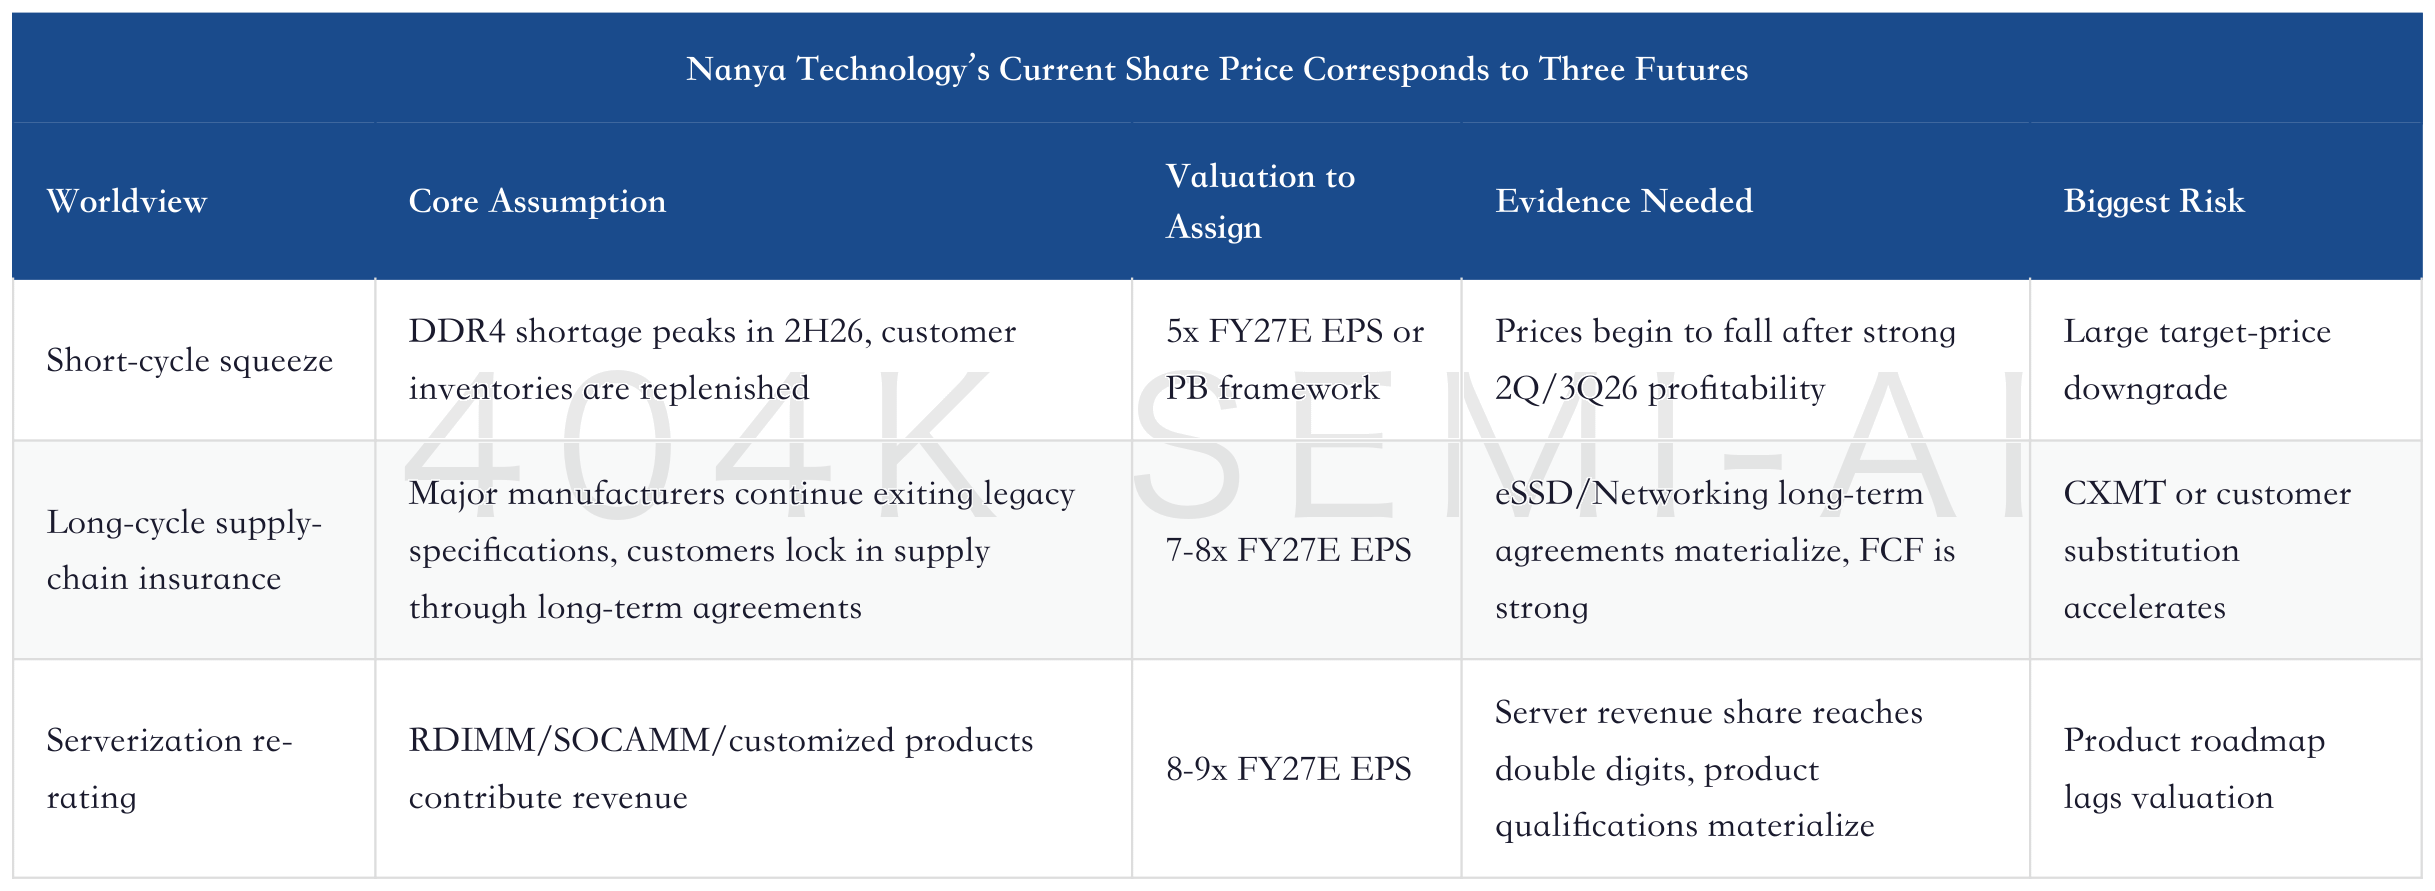
I lean more toward the second worldview, while assigning some option value to the third. The reason is that Nanya Technology has already obtained financial validation from 2025 and 1Q26, as well as customer validation through the private placement and long-term supply agreements. But there is still insufficient evidence on the revenue share from serverization, SOCAMM share, and margins on customized products. From an investment perspective, “long-cycle supply-chain insurance” should be the base case, “serverization re-rating” the upside, and “short-cycle squeeze” the invalidation risk.
This is also the difference in position sizing and tracking method. If one only believes in the first worldview, Nanya Technology can only be traded as price momentum, and one should exit when DDR4 prices soften. If one believes in the second worldview, one needs to tolerate monthly price volatility and focus on long-term agreements, FCF, dividends, and customer structure. If one believes in the third worldview, one must accept a longer product qualification cycle and focus on the 2027 revenue structure rather than single-quarter profit in 2026.
XI. Falsification Checklist: What Would Invalidate NT$710
For a stock like Nanya Technology, the biggest risk is not getting the direction wrong, but getting the direction right while ignoring changes in slope. When the DRAM cycle is moving up, every indicator looks good. When an inflection point appears, it usually shows up first in pricing, order terms, and inventory details, not suddenly in an annual report. The falsification checklist needs to be specific.
First, DDR4 spot prices weaken earlier than expected in 2H26. If DDR4 16Gb or mainstream legacy-spec prices fall quickly after the third quarter, it would suggest customer inventory restocking is complete, or substitute supply is starting to emerge. Nanya Technology’s high gross margin would be compressed first, and EPS forecasts would be revised down.
Second, gross margin fails to hold high levels. In JPMorgan’s model, 2026E/2027E gross margins are as high as 77.6%/82.0%, and 1Q26 has already reached 68%. If 2Q26 gross margin fails to keep rising, or 3Q26 comes in clearly below market expectations, it would suggest ASP and cost leverage are not as strong as the model assumes.
Third, the revenue contribution from servers and data centers does not rise. Server applications were about 5% in 2025, a very low base. If there is still no material contribution from RDIMM, eSSD, Networking, or SOCAMM to the revenue mix by end-2026, the market will reclassify Nanya Technology as a legacy DRAM price-upcycle stock.
Fourth, long-term contract customers do not convert into visible orders. The private-placement participants and supply-chain relationships with Kioxia Holdings, Solidigm, SanDisk, Cisco, and others are important evidence for Nanya Technology’s valuation re-rating. If these relationships remain only financial investments and framework agreements, without verifiable orders, pricing terms, or revenue contribution, the market will reduce the long-term contract premium.
Fifth, CXMT or other supply creates an earlier-than-expected shock. Nanya Technology’s official annual report has already listed Chinese DRAM capacity expansion as a risk. If Chinese suppliers accelerate volume ramp in standard DDR4/DDR5 products and customers are willing to substitute, Nanya Technology’s ASPs in China and standard-spec products will come under pressure.
Sixth, 1C/1D and Fab 5A progress is delayed. To sustain its valuation after 2027, Nanya Technology must move from legacy-spec price increases to new-product revenue. If 1C/1D validation, Fab 5A equipment installation, server module certification, or customized high-bandwidth product progress falls short of expectations, the market will reduce the sustainability weight assigned to post-2027 EPS.
Nanya Technology’s falsification conditions are concentrated in pricing, customers, and process technology
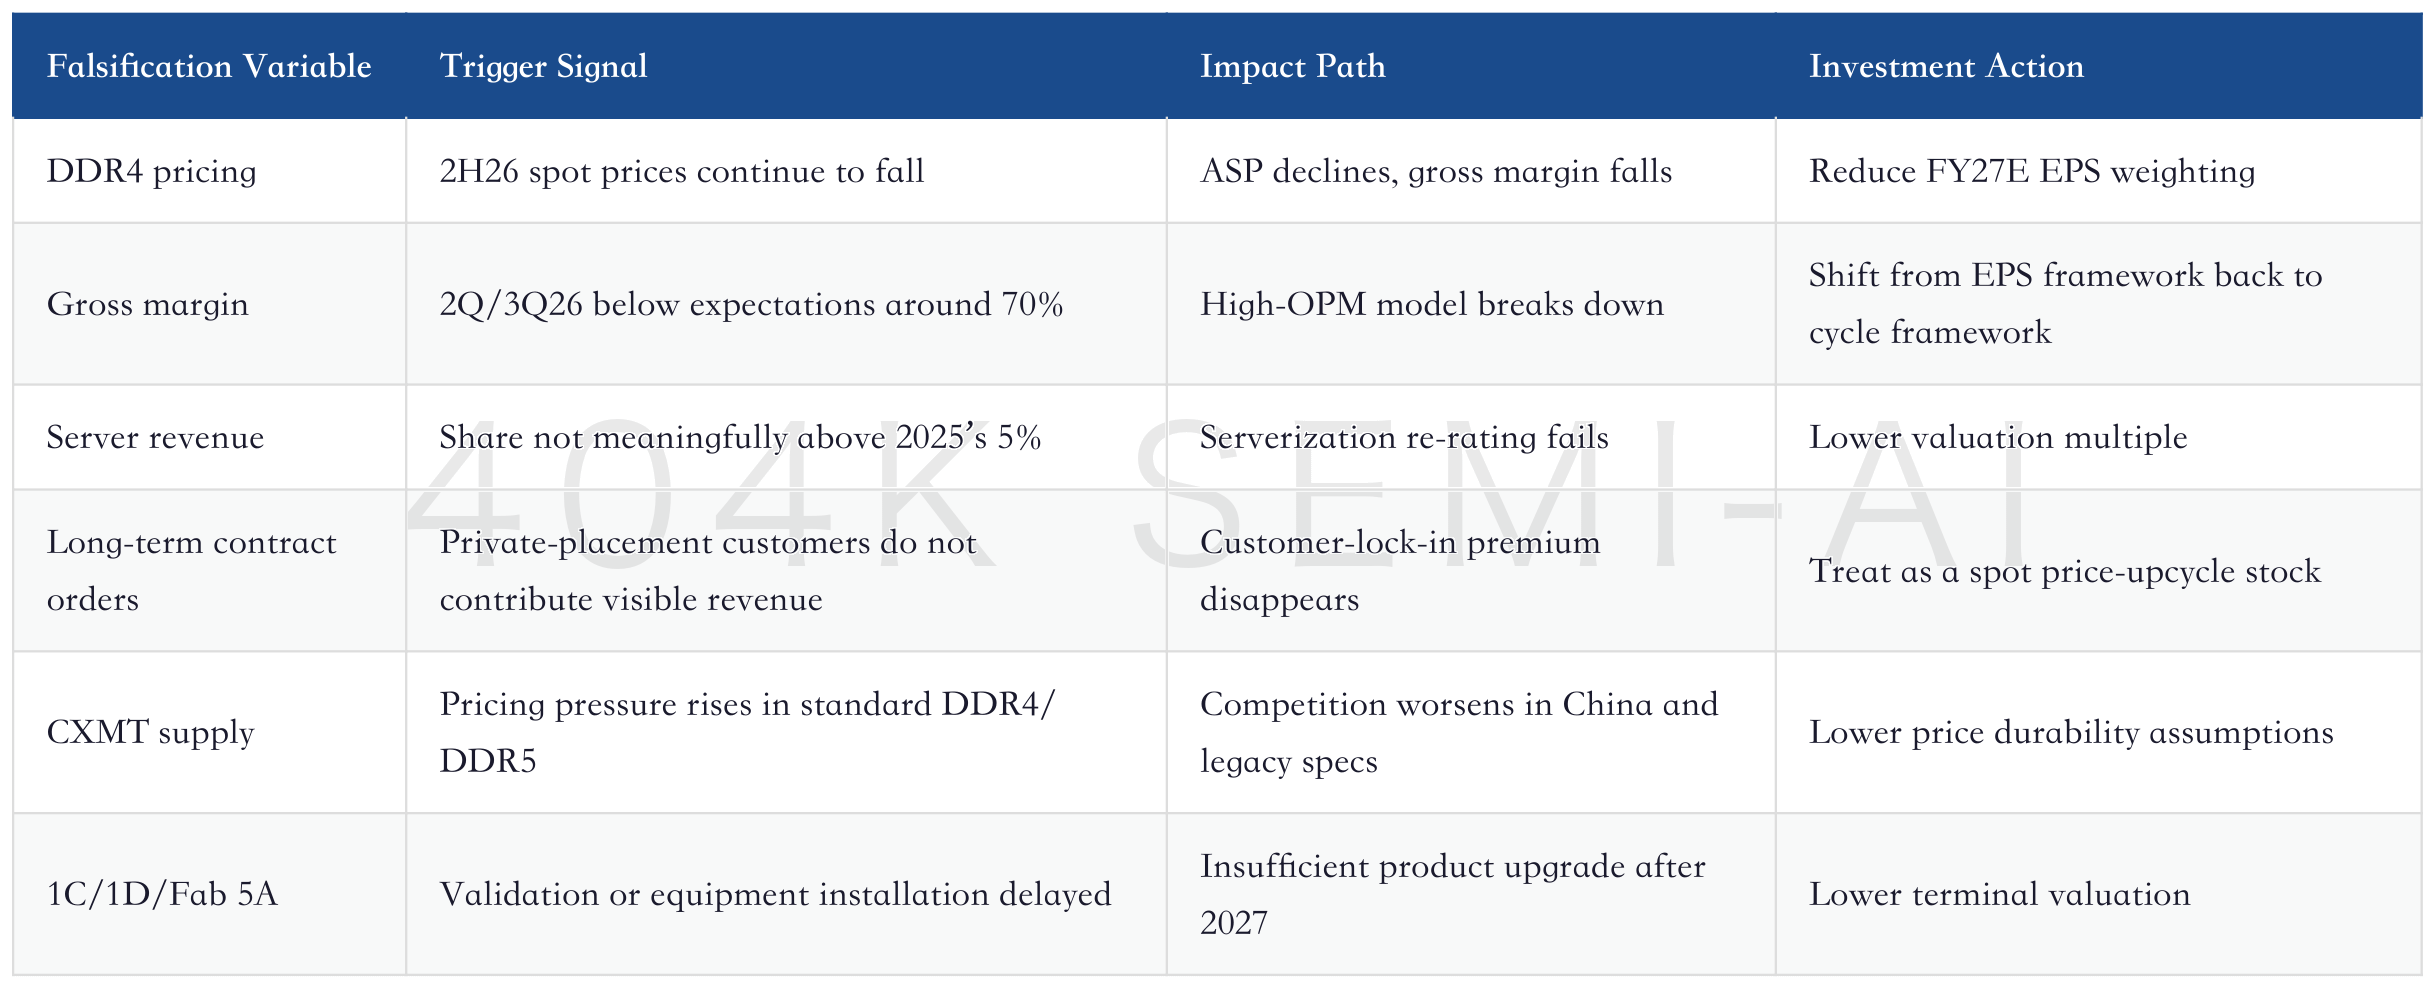
These falsification conditions matter more than the target price. Nanya Technology’s share-price elasticity comes from the slope of the model. Once that slope changes, valuation will react before earnings. Investors need to accept one fact: this is not a low-volatility, high-certainty company. It is a hybrid cyclical growth asset with high cash flow, high price elasticity, and rapid falsification speed.
XII. Four-Quarter Tracking Table: Watch the Numbers, Not the News
Over the next four quarters, the five most important numbers to track for Nanya Technology are monthly revenue, gross margin, server-related revenue share, capex/cash flow, and product validation milestones. News and target prices can stimulate short-term moves, but these numbers determine whether the re-rating can continue.
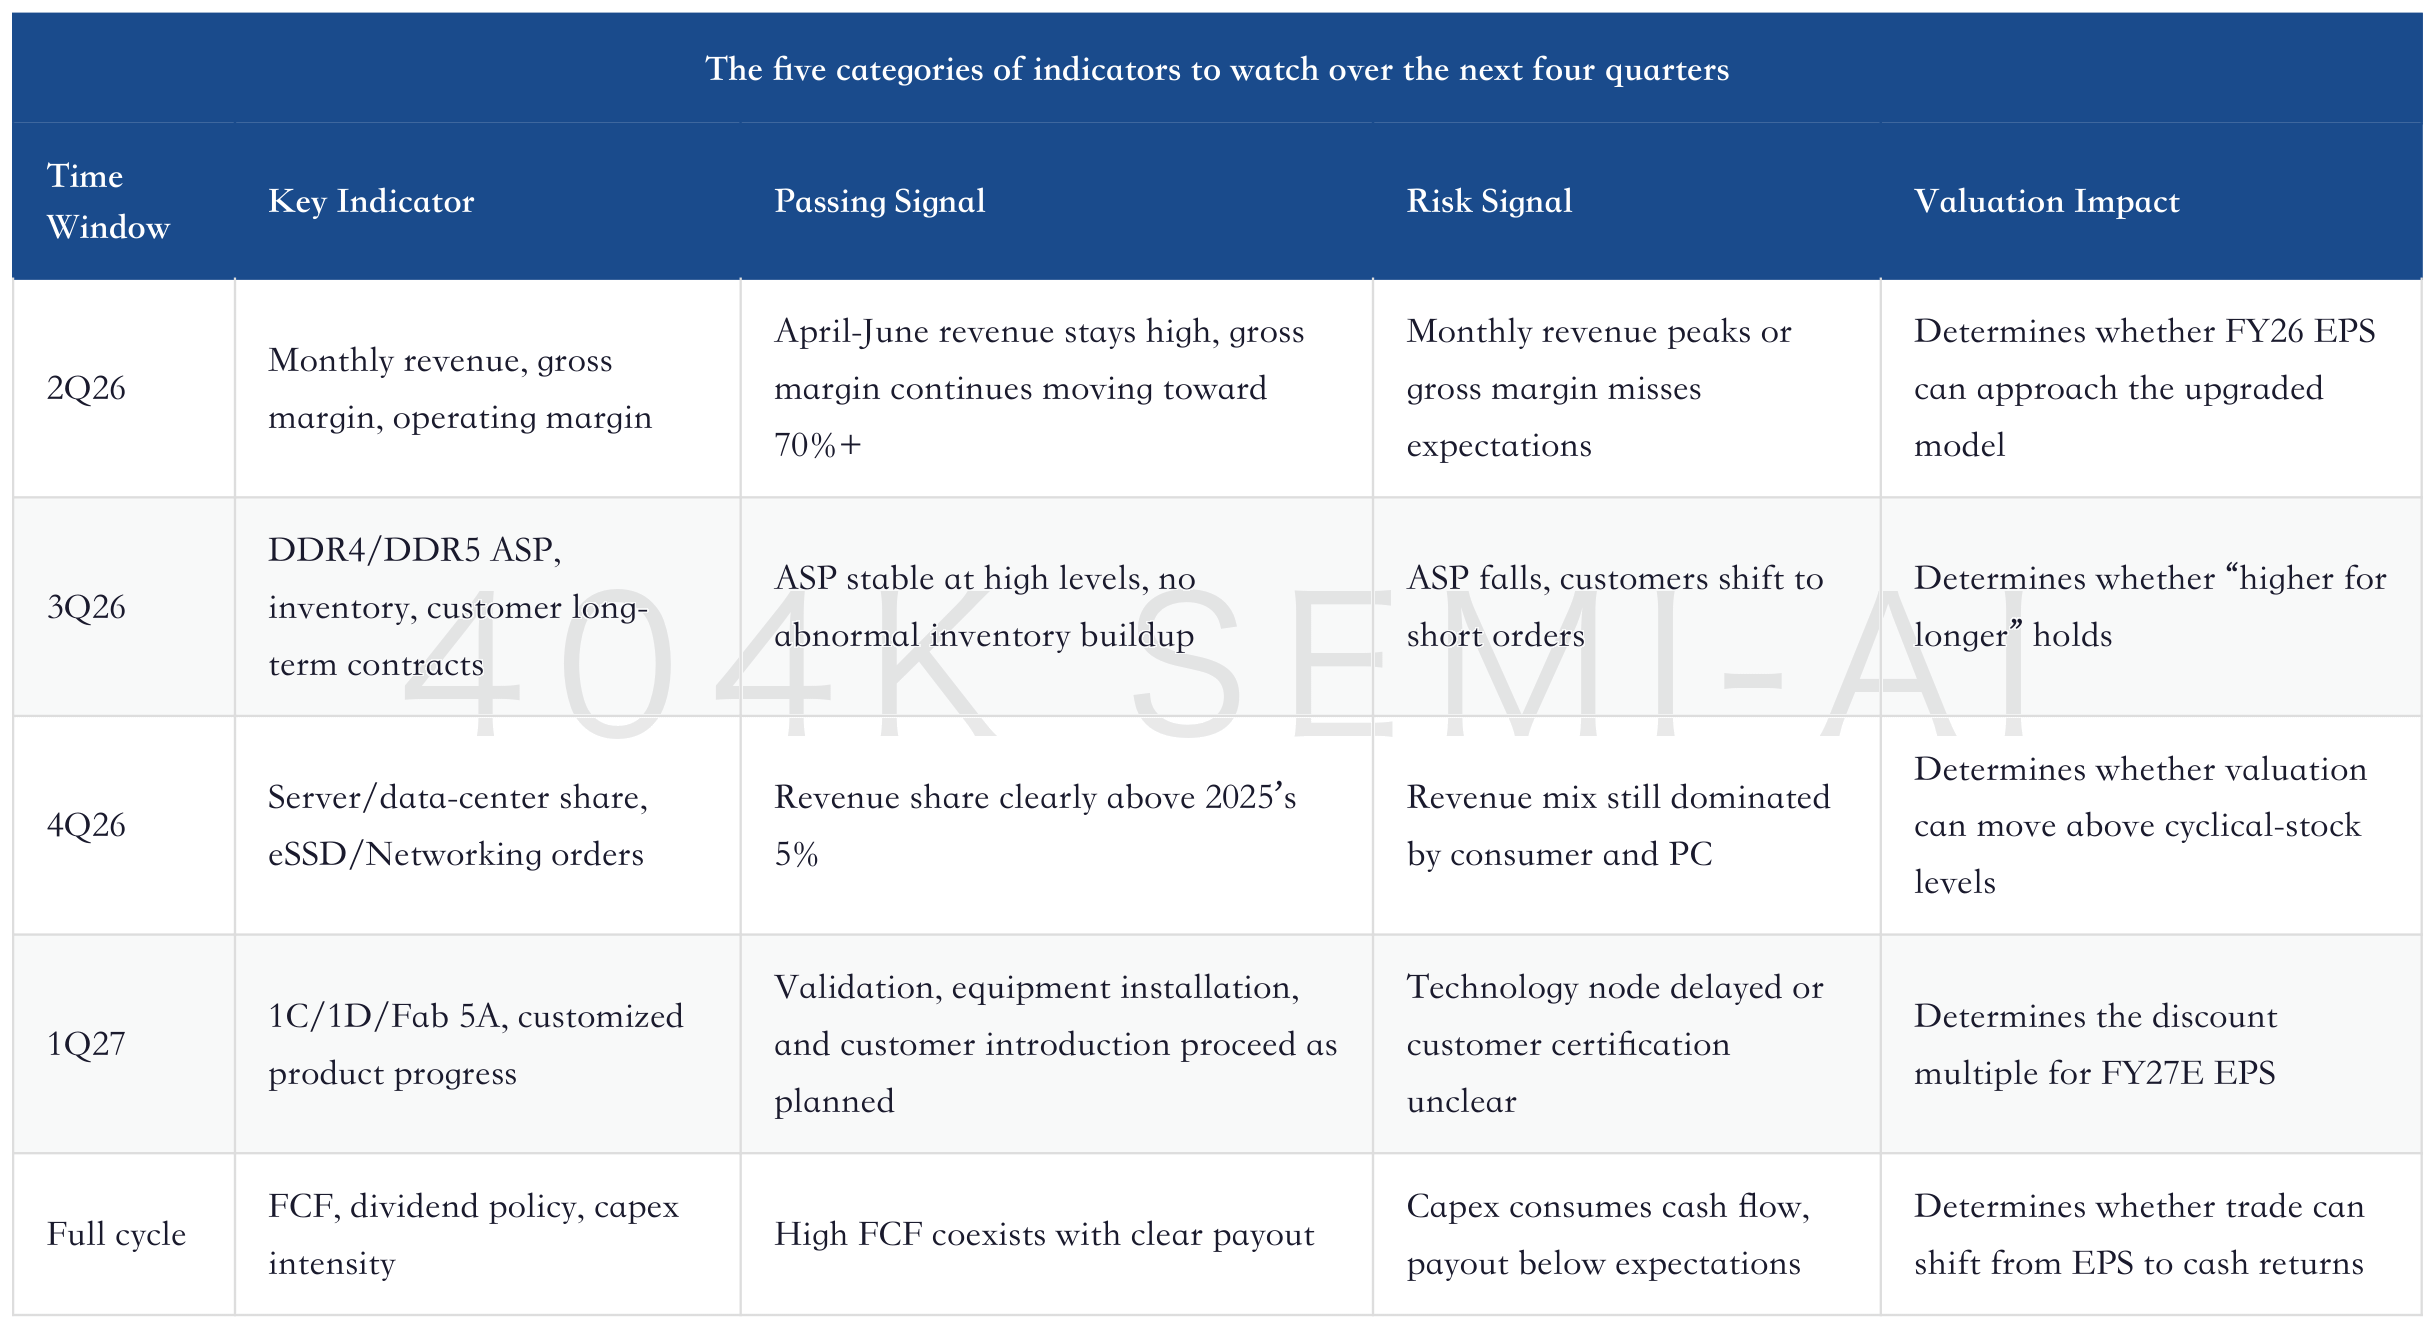
This tracking table also explains why investors should not only watch whether the share price reaches NT$710. Nanya Technology could approach the target price on short-term price momentum, or see valuation volatility before fundamentals continue to improve. A more mature approach is to rescore the numbers each quarter under three worldviews: whether it looks more like a short-cycle squeeze, a long-cycle supply-chain insurance asset, or the start of a serverization re-rating.
If 2Q/3Q26 gross margin continues to rise, monthly revenue stays high, customer long-term contract news increases, and server-related revenue share rises, NT$710 is not an extreme target price. If DDR4 pricing falls in 2H26, serverization evidence is insufficient, and CXMT competition intensifies, the market will compress the FY27E multiple in advance even if 2026 EPS is high.
XIII. Trading Framework: Split Nanya Technology into Price, Customer, and Option Buckets
Nanya Technology is best tracked using a layered framework. The first layer is the price bucket, centered on ASPs, contract prices, and spot prices for legacy-spec DRAM. This bucket is the most sensitive and the easiest place to make quick money because the income statement has very high elasticity to ASP. Its risk is equally clear: once pricing starts to loosen, the market will immediately treat high EPS as a cyclical peak rather than stable earnings.
The second layer is the customer bucket, centered on whether eSSD, Networking, automotive, industrial, and server customers can turn orders into long-term contracts. The customer bucket is slower than the price bucket, but higher quality. The price bucket answers “how much can be earned in this cycle”; the customer bucket answers “whether customers will still be willing to lock supply in advance in the next cycle.” After Nanya Technology brought in industrial customers such as Kioxia Holdings, Solidigm, SanDisk, and Cisco, the market assigned it a higher valuation not because those names sound good, but because they can turn legacy-spec DRAM from a spot-traded product into a supply-chain security allocation.
The third layer is the option bucket, centered on RDIMM, SOCAMM, LPDDR5, LPCAMM2, TSV, and customized high-bandwidth products. The option bucket cannot be valued as a core business too early, because certification, yield, customer introduction, and mass production all take time. But it also cannot be ignored, because it determines whether Nanya Technology can shed the label of “legacy-spec price-upcycle stock.” Once serverization products start contributing revenue, the market will reopen the debate over what EPS multiple, FCF yield, and dividend assumptions should be used to price the company.
These three buckets correspond to three trading disciplines. The price bucket should be fast: changes in ASP, gross margin, and monthly revenue trends require reassessment. The customer bucket should be stable: focus on long-term contracts, supply agreements, customer concentration, and revenue mix, without being led astray by one month of price volatility. The option bucket requires patience: a single product announcement should not directly raise terminal valuation, and the lack of near-term revenue should not zero out all technology pathways.
The most attractive feature of Nanya Technology today is that all three buckets have evidence at the same time for the first time. The price bucket has already been validated by financial results; the customer bucket is supported by private placements and long-term supply agreements; the option bucket has an official product roadmap and server module progress. The biggest risk is also that these three buckets may not move in sync: pricing may peak first, customer orders may be slower than expected, and the serverization option may not have time to materialize. If the market fully prices in the option before it is exercised, the margin for error will fall.
Therefore, the reasonable holding logic for Nanya Technology is not “buy because the target price was raised,” but “rescore the three buckets every quarter.” If the price bucket stays intact, it can at least support earnings elasticity. If the customer bucket continues to strengthen, valuation can move up from cyclical-stock levels. Only when the option bucket starts generating revenue does the stock qualify for a higher valuation range. As long as two of the three buckets are still improving, share-price pullbacks look more like validation-period volatility. If two buckets weaken at the same time, position assumptions should be reduced no matter how high the target price is.
This framework has another benefit: it separates short-term price volatility from long-term asset characteristics. Nanya Technology can deliver a rapid profit surge because of legacy-spec price increases, but whether it can retain a higher valuation depends on proof from customers and products.
XIV. Conclusion: What Nanya Technology Offers Is a Conditional Re-Rating, Not Blind Cycle Chasing
Nanya Technology now looks most like a DRAM company whose asset attributes are shifting gears. In the past, its value came from the cyclical elasticity of consumer, PC, low-power, and legacy-spec products. Now its value comes from supply insurance after DDR4/LPDDR4 EOL, eSSD and Networking customer lock-in, the serverization option from RDIMM/SOCAMM, and product upgrades from 1B/1C/1D/Fab 5A.
JPMorgan’s NT$710 target price is not unreasonable, but it is conditional. First, the DDR4/DDR5 upcycle needs to last longer than a traditional cycle, without rapid price declines in 2H26. Second, Nanya Technology’s 2026-2027 gross margin and OPM need to approach the model assumptions. Third, servers, eSSD, Networking, SOCAMM, and RDIMM need to provide at least some revenue evidence. Fourth, the company cannot sacrifice FCF and dividend optionality for capacity expansion.
If these conditions hold, Nanya Technology is not just a DDR4 price-upcycle stock, but a second-tier DRAM asset being repriced within the AI storage supply chain. It does not have the technical moat of the HBM leaders, but it has unique elasticity from legacy-spec supply exits, long-term customer contracts, cash flow, and server bypass demand. The market’s willingness to assign it 8x FY27E EPS is a bet that this storage cycle is no longer only price mean reversion, but also a long-term contraction in supply structure and a rebuild of customer safety inventory.
If these conditions do not hold, Nanya Technology will quickly revert to being a cyclical stock. Nearly all of the company’s revenue comes from DRAM, margins are extremely sensitive to ASP, server application revenue share remains low, 1C/1D and SOCAMM are still in validation, and supply competition from CXMT and others has not disappeared. Its upside and downside come from the same fact: the business is very pure, elasticity is high, and falsification is fast.
The most reasonable investment conclusion is that Nanya Technology is suitable as a “high-elasticity core watchlist name” in a storage upcycle, not as a low-risk long-term compounder. The buy case is not “JPM gave it NT$710,” but using pricing, gross margin, server share, long-term contract orders, and product milestones each quarter to validate the four premises behind NT$710. As long as validation continues to pass, valuation can migrate from cyclical stock toward server supply-chain asset. Once validation breaks, even a high target price is only a footnote to the cyclical peak.
Nanya Technology’s final thesis can be compressed into one sentence: DDR4 EOL gives it profit, long-term customer contracts give it cash flow, SOCAMM/RDIMM give it a valuation option, and 1B/1C/1D plus Fab 5A determine whether it can retain this cycle’s high profits beyond 2027. Investors should buy the continued delivery of these four things, not simply a raised target price.Nanya Technology Deep Dive: DDR4 EOL, SOCAMM Server Memory, and an NT$710 Target Price: The Three Gates for Re-rating a Tier-2 DRAM Vendor
目录
Too Long; Didn’t Read
1. The Key to Nanya’s Re-rating Is “Legacy DRAM” Re-entering the AI Supply Chain
2. Company Profile: What Does Nanya Actually Sell, and Where Is It Strong or Weak?
3. What JPM Changed in Its Model: From NT$230 to NT$710, Not a Routine Upgrade
4. Why DDR4 EOL Is Not a Legacy-Capacity Story, But a Supply-Chain Insurance Story
V. SOCAMM and Server Memory: Nanya Technology’s Second Growth Curve Is Still in Early Validation
VI. 1B, 1C/1D, and Fab 5A: This Is Not a Capacity Expansion Story, but a Cost and Product Moat Story
VII. Valuation: NT$710 Is Defensible, but It Is Not a Low-Risk Target Price
8. Sell-Side Divergence: Why Nanya Technology’s Risks Are More Concentrated Despite the Same Positive View on Memory
9. Financial Quality: 1Q26 Was Very Strong, but Do Not Treat One Quarter’s Profit as Permanent
10. Three Worldviews: Which Future Will Nanya Technology’s Share Price Ultimately Trade?
XI. Falsification Checklist: What Would Invalidate NT$710
XII. Four-Quarter Tracking Table: Watch the Numbers, Not the News
XIII. Trading Framework: Split Nanya Technology into Price, Customer, and Option Buckets
XIV. Conclusion: What Nanya Technology Offers Is a Conditional Re-Rating, Not Blind Cycle Chasing
本内容基于公开资料和研报数据整理,不构成任何投资建议,不代表任何个人观点,仅供学习参考,请理性阅读
The core of Nanya Technology’s current re-rating is not a generic DRAM cycle rebound. It is the simultaneous emergence of DDR4/LPDDR4 supply exits, long-term agreements tied to eSSD and networking demand, and optionality in SOCAMM server memory. The market is starting to reprice tier-2 DRAM vendors, and to reprice their risks as well.
Too Long; Didn’t Read
Nanya Technology’s asset profile has changed. It used to look more like a cyclical consumer and specialty DRAM stock. The debate now is whether pricing, customers, and process technology can preserve peak earnings. JPMorgan’s NT$710 target price is essentially a re-rating based on server exposure, long-term agreements, and cash-flow sustainability, not just one quarter of price increases.
Legacy-spec supply is the first ticket. After Samsung, SK hynix, and Micron shifted capacity toward HBM, advanced DRAM, and high-end products, legacy memory was no longer just a lagging product category. It became a supply gap still required by eSSD, switches, BMCs, NICs, autos, and consumer devices. Nanya has already shown through official financials that supply contraction can quickly flow through to ASP, gross margin, and net profit.
Serverization is the second ticket. Nanya’s server revenue remains at a low base, but the company has already increased RDIMM sales and has included server modules, TSV, SOCAMM-related opportunities, and customized high-bandwidth products in its roadmap. If eSSD, networking, and server orders expand, the customer mix will shift from consumer tail demand toward AI server adjacency demand.
The valuation risk is that forecasts are too steep. JPMorgan’s model is not a mild recovery scenario. It assumes sustained high pricing, capacity discipline, customer long-term agreements, and yields all hold at the same time. If any one of these breaks, the target price will be retested, and the market may mark Nanya back down from a server supply-chain asset to a cyclical stock.
Financial quality provides a cushion. The latest quarterly report and monthly revenue already show that the company has entered a phase of high revenue, high margin, and high cash flow. Private placement capital has further strengthened the balance sheet. The issue is that Fab 5A, advanced processes, and customized products also require capex, so dividend flexibility must be assessed together with the expansion cadence.
Watch five variables next: pricing, gross margin, server revenue, process nodes, and long-term-agreement orders. These matter more than news flow and target prices. Nanya’s re-rating depends not on a bigger story, but on these variables staying intact. If validation continues, it can qualify to move from a legacy DRAM price-hike stock to a cash-flow asset in the AI storage supply chain.
1. The Key to Nanya’s Re-rating Is “Legacy DRAM” Re-entering the AI Supply Chain
The easiest way to misread Nanya is to treat it simply as a DDR4 price-hike stock. That view is too shallow. DDR4 price increases are only the first layer of change at the pricing level. What is truly worth studying is how legacy DRAM capacity has found a role again inside the AI server supply chain.
The company’s historical revenue mix was not high-end. Its official 2025 annual report disclosed that consumer electronics applications accounted for about 55% of revenue, low-power products about 19%, personal computer systems about 21%, and data center and server applications about 5%. This means Nanya is not an HBM-led company like SK hynix, nor is it a full-category advanced memory leader like Samsung or Micron. Its advantage lies in retaining a broad enough portfolio across DDR4, LPDDR4, DDR3/DDR2, KGD, MCP, UDIMM, RDIMM, and LPCAMM2, allowing it to capture the “necessary but unglamorous” supply gaps left behind after leading vendors shifted production.
These gaps are not valuable in a downcycle. Customers view legacy-spec DRAM as replaceable components, with prices driven by inventory and utilization. Tier-2 vendors struggle to secure stable valuations. In an upcycle, the logic reverses: when Samsung, SK hynix, and Micron prioritize wafers, equipment, R&D;, and customer resources for HBM, high-capacity DDR5, LPDDR5, and AI server products, DDR4/LPDDR4 supply begins to shrink. Legacy-node capacity that capital markets previously ignored suddenly becomes safety stock that customers must secure.
Nanya’s 2025 income statement has already provided evidence. The company posted 2025 revenue of NT$66.59 billion, up 95.1% year on year, net profit after tax of NT$6.61 billion, and EPS of NT$2.13. More importantly, the quarterly cadence was striking: in Q3, ASP rose more than 40% quarter on quarter, while shipments increased more than 20%; in Q4, ASP rose by more than 30% quarter on quarter again, while shipments increased about 10%, with Q4 single-quarter profit reaching NT$11.09 billion. This slope cannot be explained by normal seasonality. It corresponds to a change in supply structure.
Storage Deep-Dive Update: Morgan Stanley Calls for Buying Legacy Memory; Why DDR4, SLC NAND, and NOR Are Still Rising
JPMorgan’s upgrade of Nanya from Neutral to Overweight, and its target-price increase from NT$230 to NT$710, effectively moves the market debate to a higher level. If this is only a short-term squeeze in DDR4 spot pricing, the valuation should not reach 8x FY27E EPS. If this is a new long-term-agreement cycle driven by AI servers, eSSD, networking, RDIMM, and SOCAMM, then Nanya can no longer be assessed only on the average P/B of traditional tier-2 DRAM vendors.
My view is that Nanya is now in the middle of an asset-profile transition. The old asset profile was “cyclical leverage to consumer and specialty DRAM.” The new asset profile is “AI server-adjacent memory supplier.” The valuation gap between these two profiles is large, but the transition is not complete. The market is now willing to pay in advance because pricing, customers, and cash flow have all provided evidence. What will truly determine how far this re-rating can go is whether the next four quarters can prove that serverization is not a one-off shortage, but a restructuring of the customer mix.
Nanya’s asset profile is shifting from cyclical leverage toward the server supply chain
This is also why this report begins with Nanya itself rather than the industry. Industry strength provides beta; the company’s re-rating depends on three alphas. First, DDR4/LPDDR4 supply exits make legacy products valuable again. Second, private placements and long-term supply agreements bind the company more tightly to eSSD and networking demand. Third, 1B, DDR5, RDIMM, SOCAMM, and customized high-bandwidth products give it a chance to move from legacy DRAM into server memory. If any one of these three alphas fails, the valuation will revert to that of a cyclical stock. If all three materialize, Nanya will become the tier-2 asset with the greatest cash-flow leverage in the storage upcycle.
2. Company Profile: What Does Nanya Actually Sell, and Where Is It Strong or Weak?
Nanya’s core business is very pure: it is almost entirely DRAM. In its 1Q26 financial report, DRAM revenue was NT$49.07 billion, accounting for nearly all of total revenue of NT$49.09 billion; other revenue was only about NT$20 million. This purity gives the company extremely strong leverage in a pricing cycle, but also leaves it with little earnings buffer from NAND, HBM, logic ICs, or packaging and testing.
The product line is not narrow. Standard DRAM listed on the company website covers DDR5, DDR4, DDR3, DDR3L, and DDR2. Low-power products cover LPDDR5/5X, LPDDR4/4X, LPDDR4X, LPDDR4, LPDDR3, and LPDDR2. KGD, MCP, eMCP, uMCP, and module products cover SODIMM, CSODIMM, UDIMM, CUDIMM, RDIMM, and LPCAMM2. This shows that Nanya is not relying solely on a single DDR4 die, but has relatively complete long-tail product capabilities across legacy specs, low-power products, modules, and bare-die supply.
The company’s strengths are also clear. First, it has retained and upgraded 20nm and 1Bnm DDR4 capacity, allowing it to quickly become a replenishment source for customers as leading vendors exit legacy-product supply. Second, it has Formosa group backing and long-term DRAM manufacturing experience, giving it the ability to invest in Fab 5A, 1C/1D, and customized products after cash flow improves. Third, its customer mix is expanding from consumer electronics into servers, networking, SSDs, and automotive. In particular, after private placements brought in Kioxia Holdings, Solidigm, SanDisk, and Cisco, the quality of customer linkage has clearly improved.
The weaknesses should not be ignored. Nanya is not an HBM leader. DDR5 still did not account for a high share of revenue in early 2026, and server applications accounted for only about 5% of 2025 revenue. For the company to move from DDR4 price increases to a server-driven re-rating, it must cross four gates: product qualification, customer long-term agreements, yield ramp, and capacity allocation. If its technology roadmap stops at DDR4 pricing leverage, the valuation will struggle to remain above a cyclical peak for long. If 1B/1C/1D, RDIMM, SOCAMM, and customized high-bandwidth products progress slowly, the market will treat NT$710 as a cycle-top valuation.
The most important question for this company is not “can prices rise?” It is “after prices rise, can the company move customers and product tiers upward?” Without server customers, DDR4 price increases will ultimately be absorbed by new supply, substitution, and customer inventory. If eSSD, networking, RDIMM, SOCAMM, and customized low-power products take over the demand, DDR4 EOL becomes an entry point for customer lock-in and long-term supply negotiations.
Official materials are also describing the same issue more directly. In its 2025 annual report, the company clearly set its 2026 strategic direction as optimizing its DDR4/LPDDR4/DDR5 portfolio, increasing shipments of server-class memory modules, accelerating customized ultra-high-bandwidth memory, and advancing Fab 5A construction. The annual report also stated that 1B-related 16Gb DDR5, 8Gb DDR4, and 4Gb DDR4 have entered mass production and are shipping to customers; the 1C 16Gb DDR5 pilot product entered trial production in Q3 2025; and the 1D 16Gb DDR5 pilot product is expected to enter trial production in Q2 2026. The key here is not the wording, but that the roadmap has already shifted from “selling legacy DRAM” to “using legacy-product cash flow to fund new-product qualification.”
3. What JPM Changed in Its Model: From NT$230 to NT$710, Not a Routine Upgrade
JPMorgan’s upgrade this time is aggressive. It is not raising Nanya Technology’s 2026 earnings by 10% or 20%; it raised FY26E-FY28E EPS by 48%-118% and moved the valuation multiple to 8x FY27E EPS, in line with Korean DRAM leaders. The assumption behind this move is clear: in a DRAM upcycle, the market will not only buy HBM leaders, but also all DRAM assets that can release earnings from supply discipline and elevated pricing.
Start with the core forecasts. JPMorgan expects Nanya Technology’s revenue to rise from NT$66.59bn in 2025 to NT$322.90bn in 2026, NT$467.30bn in 2027, and NT$532.86bn in 2028; adjusted net income to rise from NT$6.61bn in 2025 to NT$198.64bn in 2026, NT$308.00bn in 2027, and NT$357.01bn in 2028; and adjusted EPS to rise from NT$2.13 to NT$58.43, NT$89.27, and NT$103.47. This slope implies the company is not merely turning profitable, but moving directly from a low-margin legacy-node fab into a state close to peak-cycle high-end profitability.
This table is the core model table of the entire report. It tells investors that Nanya Technology is not trading on “earning a bit of money this year,” but on whether it can sustain high profitability through 2026-2028. That is also where the risk lies: if 2026 EPS is NT$58.43, the current price of NT$409.5 implies roughly 7x; if 2027 EPS is NT$89.27, the current price implies only about 4.6x. The multiple looks cheap, but it is cheap only if 2027 earnings are not a cyclical peak.
JPMorgan’s upgrades to revenue, gross margin, and EPS mainly come from three assumptions. First, DDR4 and DDR5 both rise in an upcycle, and legacy products do not lose pricing power simply because they are behind the leading edge. Second, after DDR4/LPDDR4 EOL, eSSD, networking, automotive, the long tail of consumer demand, and server-edge demand will absorb legacy capacity. Third, Nanya Technology can gradually raise server-related revenue from a low base, especially through opportunities in SOCAMM, RDIMM, and eSSD cache memory.
JPM’s upgrades for Nanya Technology are concentrated in revenue, margins, and EPS
The most important items here are gross margin and OPM. Revenue upgrades can be explained by ASP; margin upgrades mean the sell side believes Nanya Technology is not just passively benefiting from price increases, but may gain better bargaining power through customer structure and product mix. Nanya Technology’s gross margin already reached 68% in 1Q26, showing this direction is not purely hypothetical; but moving from 68% to 77%-82% still requires further validation in 2Q/3Q26.
Memory Is No Longer Just a Cyclical Sector: JPM LTA Breakdown, Agentic AI Memory Multiples, and the Rewriting of Samsung and SK Hynix Valuations
The real question for the market is whether Nanya Technology can enjoy a valuation multiple similar to Korean DRAM leaders. My answer is that it can approach that level in phases, but should not be treated as equivalent without conditions. Korean leaders have a full portfolio across HBM, DDR5, high-end servers, and global major customers. Nanya Technology is more like a high-beta supply-shortage asset. It can capture similar cyclical profits when supply and demand are extremely tight, but it has not yet proven that its technology and customer structure can carry it through the next downturn. Therefore, 8x FY27E EPS can serve as an upcycle target-price framework, but should not be understood as a permanent valuation center.
4. Why DDR4 EOL Is Not a Legacy-Capacity Story, But a Supply-Chain Insurance Story
The investment implication of DDR4 EOL cannot be understood only as “old products getting more expensive.” The cycle for old-product price increases is short: once customers rebuild inventory, prices will fall back. The supply-chain insurance cycle is longer, because customers are not just replenishing spot supply; they are confirming that they will not face shortages over the next 12-24 months.
AI servers have absorbed the capex of mainstream DRAM makers. HBM, advanced DDR5, high-capacity server RDIMM, LPDDR5X, and customized high-bandwidth products all require advanced process technology, advanced packaging, customer qualification, and priority capacity. When Samsung, SK Hynix, and Micron push resources into these products, capacity for legacy DDR4/LPDDR4 passively becomes scarce. Scarcity itself is not value; scarcity plus “customers still must use it” is value.
eSSD is the most typical example. Enterprise SSDs need DRAM as controller cache. If NAND suppliers want to expand AI storage and data-center SSD shipments, they must lock in sufficiently stable DRAM supply. Kioxia Holdings investing in Nanya Technology as a NAND maker and signing a long-term DRAM supply agreement shows this is not a purely financial investment, but a supply-chain security arrangement. Solidigm, SanDisk, and other NAND-related customers participating in the private placement reinforce the same logic: for eSSD, DRAM is not a commodity accessory, but part of product delivery capability.
Networking follows similar logic. Switches, NICs, BMCs, and networking and communications equipment still use large amounts of DDR4 or similar-spec memory. AI cluster expansion requires not only GPUs and HBM, but also switches, network interfaces, storage controllers, and management chips. These links do not have DRAM capacity and bandwidth requirements as extreme as HBM, but they are more sensitive to stable supply and long product lifecycles. Once leading vendors withdraw legacy products from production, customers are willing to exchange long-term contracts for supply.
The value of legacy-spec DRAM comes from application gaps that still cannot do without it
This is also the difference between Nanya Technology and a pure legacy-capacity stock. The company is not merely keeping legacy capacity at low cost; it is using 1B, DDR5, RDIMM, LPDDR5, LPCAMM2, and customized high-bandwidth products to guide old customers toward new products. Legacy products provide cash flow; new products determine the valuation multiple. Looking only at DDR4 pricing misses this transition; looking only at the SOCAMM story overestimates the speed of technology delivery.
JPMorgan’s logic that “all DRAM moves together in an upcycle” is ultimately based on supply-chain insurance. Mainstream investors like to buy high-end products because HBM and DDR5 have stronger technology stories. But when tight supply spreads across all nodes, customers do not necessarily buy only the most advanced products; they also buy the most reliable products, the least likely to be cut off, and those most capable of being locked into long-term supply agreements. That is where Nanya Technology’s value lies.
Rubin Will Consume Smartphone Memory in 2027: Why Nvidia Is Taking Smartphone Memory, and How Vera Rubin Rewrites DRAM Capacity Prioritization
The risk also comes from here. If DDR4 EOL is only a short-term withdrawal, customers can ease the gap through inventory, alternative materials, platform migration, and restocking from Chinese suppliers. If customers accelerate the shift from DDR4 to DDR5, Nanya Technology’s high ASPs for legacy specs will fall back quickly. What Nanya Technology needs to prove is that what it is selling is not just old inventory, but supply insurance for customers’ future product roadmaps.
V. SOCAMM and Server Memory: Nanya Technology’s Second Growth Curve Is Still in Early Validation
SOCAMM is the term in this report most likely to excite the market, but it is not yet realized profit. It is more like an admission ticket: if AI servers and ARM-architecture CPUs create new board-level memory form factors, second-tier DRAM vendors may have a chance to enter the supply chain through low power consumption, high bandwidth, modular packaging, and customer qualification. If product qualification is slow and share is low, SOCAMM will remain only a valuation story, not a profit driver.
Nanya Technology has the foundation to enter this track. Its 2025 annual report disclosed that the company increased sales of RDIMM modules for server applications and captured demand from BMC, NIC, and other applications; 128Gb DDR5 RDIMM 5600/6400 has passed functional testing; 16Gb DDR5 mono-die has reached 7200 MT/s; customized ultra-high-bandwidth product design is underway; the company also plans to co-develop high-performance, low-power, ultra-high-bandwidth memory solutions with partners and expects revenue contribution in 1H27. This shows Nanya Technology is not stopping at DDR4, but is filling gaps in server and low-power high-bandwidth capabilities.
But a foundation does not equal share. Data center and server revenue accounted for only about 5% in 2025, meaning Nanya Technology’s server business is still at a low base. JPMorgan noted that server-side market exposure could continue expanding from low double digits, and every 100bps of SOCAMM share could bring substantial revenue potential. That leverage is attractive, but it must be proven through customer validation, design-ins, volume shipments, and long-term pricing.
If Nanya Technology only benefits from DDR4 price increases, its valuation ceiling will mainly be determined by the pricing cycle. If it can lift server revenue from 5% to 10%, 15%, or even higher, the valuation logic changes. Server products usually require more rigorous qualification, place greater emphasis on stable supply, are more likely to be covered by long-term contracts, and better explain the sustainability of high OPM. JPMorgan’s NT$710 target is essentially an early bet on this structural shift.
My base-case view is that SOCAMM should not be the primary variable in Nanya Technology’s investment thesis. The primary variables remain DDR4/LPDDR4 supply exits and long-term contracts in eSSD/Networking, because these have already translated into orders and pricing. SOCAMM is a second-layer upside option: it explains why the market is willing to imagine Nanya Technology migrating from a cyclical stock toward a server supply-chain asset, but in the financial model it should be treated with scenario weighting rather than booked directly as certain revenue.
This point is important. Many valuation errors in second-tier semiconductor companies come from treating “having samples” as “having share,” and treating “having a roadmap” as “having profit.” For Nanya Technology to firmly support NT$710, SOCAMM/RDIMM/customized memory must move from the roadmap into the shipment schedule, and then from the shipment schedule into gross margin. Without that process, valuation will retreat quickly after DDR4 prices peak.
VI. 1B, 1C/1D, and Fab 5A: This Is Not a Capacity Expansion Story, but a Cost and Product Moat Story
Nanya Technology’s 2026 capex ceiling of NT$52 billion looks like capacity expansion on the surface. More precisely, it is “using peak-cycle cash flow to buy the next round of product qualifications.” The mistake DRAM companies most often make in an upcycle is confusing high prices with long-term demand, blindly expanding capacity and then bearing depreciation pressure in the downcycle. Nanya Technology needs to do something different: allocate capex to 1B, 1C/1D, Fab 5A, server modules, and customized products, rather than simply increasing legacy DDR4 wafer volume.
The official annual report disclosed that the 1B process accounts for about one quarter of the company’s monthly wafer starts and can contribute up to about 40% of die output; 16Gb DDR5, 8Gb DDR4, and 4Gb DDR4 are already in mass production and shipping to customers. 1B is the foundation of current profit realization because it covers both DDR4 and DDR5, allowing the company to switch between legacy product price increases and new product validation. JPMorgan also noted that DDR5’s revenue contribution remained low in early 2026, but existing DDR4 capacity can be converted to DDR5 within 3-6 months, giving the company some optionality.
1C/1D is the key after 2027. The company disclosed that 1C 16Gb DDR5 pilot products entered trial production in 3Q25, and 1D pilot products are expected to enter trial production in 2Q26. They may not immediately change the revenue mix, but they will determine whether Nanya Technology can continue serving DDR5, LPDDR5, server modules, and customized high-bandwidth products after the DDR4 peak. For investors, 1C/1D is not technology news, but the valuation discount period.
Fab 5A also should not be understood only as capacity expansion. The annual report shows that utilities and the cleanroom for the new fab have been completed, and process equipment installation is expected to begin in early 2027. This timing aligns with JPMorgan’s FY27E EPS peak: 2026 profit comes from pricing and existing capacity, while 2027 needs new products, customer long-term contracts, and stronger processes to retain profitability. If Fab 5A merely adds commodity capacity, the risks are depreciation and oversupply; if it supports servers, low-power products, customized products, and advanced DDR5, then it is a true moat investment.
There is a counterintuitive point here: the best case for Nanya Technology is not the fastest capacity growth, but the scarcest capacity that can be locked in by customers. JPMorgan assumes 12-inch-equivalent monthly capacity will stay roughly stable at 62k wpm in 2026, rise quarterly to 72k wpm in 2027, and then reach 76k wpm in 2028. The profit surge in the model mainly comes from ASP and margin improvement, not a capacity explosion. This means Nanya Technology does not need major capacity expansion to prove its value; instead, it needs capacity discipline to prove that high profitability is sustainable.
In JPMorgan’s model, the profit surge mainly comes from ASP, not a capacity explosion
This table also explains why the risk is concentrated in pricing. If ASP cannot stay high in 2027, modest capacity growth will not offset margin compression. If Fab 5A brings more shipments in 2028 but industry pricing has already turned down, valuation will shift from EPS multiples back to PB and depreciation cycles. Therefore, Nanya Technology’s capex is not “the higher the better”; the key is whether it brings customer lock-in, product upgrades, and cost reduction.
VII. Valuation: NT$710 Is Defensible, but It Is Not a Low-Risk Target Price
The NT$710 target price looks high, but in substance it is FY27E EPS of NT$89.27 multiplied by 8x. The calculation is simple; the difficult question is whether 8x is justified. Traditional second-tier DRAM vendors can also generate large profits in an upcycle, but the market is usually unwilling to assign high multiples because investors worry that EPS is at a peak. JPMorgan is willing to give 8x this time because it believes this cycle will be longer, DDR4 and DDR5 prices will rise together, and servers plus long-term contracts will make profit sustainability higher than in the past.
Based on Nanya Technology’s NT$409.5 share price on July 3, 2026, the stock trades at about 7.0x JPMorgan’s 2026E EPS, about 4.6x 2027E EPS, and about 4.0x 2028E EPS. This valuation is not expensive, but the sense of cheapness depends entirely on earnings delivery. If 2027E EPS is revised down to NT$50, the current price is above 8x; if EPS really reaches NT$89.27, NT$710 is also only 8x and not excessive.
The NT$710 target price depends on both FY27E EPS and the valuation multiple holding
This scenario table is more useful than a single target price. Nanya Technology currently trades on a double click of “earnings slope” and “valuation multiple.” If only earnings are revised up, the market may assign 5-6x; only if earnings are revised up while server revenue mix rises, long-term contracts become visible, FCF is strong, and dividends improve will the market assign 8x or even higher. The key to NT$710 is not the share-price upside, but whether 8x FY27E EPS can be treated as the new-cycle midpoint.
JPMorgan also provides a shareholder-return anchor: from 2026 to 2028, the company may generate about NT$690 billion of cumulative FCF, and under a conservative 35% payout assumption, FY27E/FY28E dividend yields are estimated at 5.5%/8.6%. This framework is attractive because it turns Nanya Technology from a pure pricing trade into a cash-return trade. If a second-tier DRAM vendor only benefits from price increases, valuation is hard to stabilize; if it can sustain FCF and dividends, the valuation discount will narrow.
But dividends are not free. Nanya Technology’s 2026 capex ceiling is NT$52 billion, and Fab 5A equipment installation, 1B/1C/1D, customized products, and server modules all require cash. The roughly NT$78.7 billion private placement in April 2026 did strengthen the balance sheet, and cash of NT$86.28 billion at the end of 1Q26 was also substantial. But if the company decides to accelerate capacity and R&D;, the actual payout may not reach what investors imagine. Cash returns depend on board-level capital allocation, not only modelled FCF.
My valuation view is that Nanya Technology can now shift from a traditional PB cyclical stock to an EPS/FCF framework, but only with a “conditional re-rating.” Conditional re-rating means that when FY27E EPS is close to NT$90, 8x is acceptable; if FY27E EPS is revised below NT$60, 8x becomes expensive. From an investment action perspective, investors cannot focus only on the target price; quarterly pricing, gross margin, server revenue, long-term contracts, and capex cadence need to be tracked on the same sheet.
8. Sell-Side Divergence: Why Nanya Technology’s Risks Are More Concentrated Despite the Same Positive View on Memory
Across multiple sell-side firms, the common direction for memory is upward revisions. DRAM and NAND supply discipline, AI servers, HBM displacement, eSSD demand, and DDR4 EOL are all pushing memory profitability higher into 2026. The difference is that the logic for the Korean leaders is more about high-end products and technology share, while Nanya Technology’s logic is more about legacy-product supply gaps and customer lock-in. This means Nanya Technology has higher earnings torque, but the thesis can also be invalidated faster.
For the Korean leaders, the risks are HBM share, advanced processes, customer pricing, and capex. For Nanya Technology, the risks are more direct: whether DDR4/LPDDR4 prices remain high, whether CXMT accelerates supply, whether customer long-term agreements can truly lock in eSSD/Networking demand, and whether SOCAMM and RDIMM can contribute revenue. It does not have the same technology moat as the HBM leaders, nor Samsung’s full-chain ability to absorb cyclicality.
CXMT deserves particular attention here. Nanya Technology’s 2025 annual report already listed capacity expansion by Chinese DRAM manufacturers as a risk, noting that CXMT capacity could reach 300,000 wafers per month by the end of 2025, and that it had already started DDR5 mass production in December 2024. CXMT’s products overlap with Nanya Technology’s, which will affect sales strategy, pricing, and margins in the China market. Nanya Technology’s response is to differentiate by product and application, consolidate demand that CXMT has difficulty supplying, develop customized products, raise the share of sales outside China, and negotiate long-term supply with key customers.
This official risk disclosure matters because it reminds investors that DDR4 EOL does not mean a permanent global shortage of legacy DRAM. Korean and U.S. leaders exiting part of their legacy-specification capacity will create supply gaps; capacity expansion by Chinese DRAM manufacturers will add supply back in some markets. Whether Nanya Technology can sustain high ASPs depends on whether it can avoid pure commoditized competition and shift toward long-term agreements, non-China markets, automotive, industrial, eSSD, Networking, and server qualification.
One reason JPMorgan is optimistic on Nanya Technology is that it believes Nanya Technology and Chinese DRAM competitors have some customer and product mismatch. This judgment is acceptable, but it should not be extrapolated too far. Mismatch is not a moat. Customer qualification, long-term supply agreements, special specifications, and stable delivery are the real moats. If Nanya Technology can sell legacy DRAM into more stable server, networking, storage, and automotive customers, CXMT’s impact will be buffered. If it still mainly sells standardized consumer DRAM, price competition will eventually return.
9. Financial Quality: 1Q26 Was Very Strong, but Do Not Treat One Quarter’s Profit as Permanent
Nanya Technology’s 1Q26 financial results were very strong. Quarterly revenue was NT$49.09 billion, versus only NT$7.19 billion in the same period last year. Gross profit was NT$33.32 billion, with a 68% gross margin. Operating profit was NT$30.11 billion, with a 62% operating margin. Net profit after tax was NT$26.06 billion, with a 53% net margin. This is no longer just a turnaround; it is a high-profit state in an upward pricing cycle.
Cash flow was also solid. In 1Q26, operating cash inflow was NT$30.80 billion, capex cash outflow was about NT$2.81 billion, inventory declined from NT$27.29 billion at end-2025 to NT$24.33 billion at end-1Q26, and cash rose from NT$58.07 billion to NT$86.28 billion. After the private placement was completed in April, another roughly NT$78.7 billion of capital was added, giving the balance sheet the capacity for expansion and R&D; investment.
May monthly revenue further strengthened the near-term cycle. Cumulative consolidated revenue for January-May 2026 was NT$102.24 billion, including NT$15.31 billion in January, NT$15.61 billion in February, NT$18.17 billion in March, NT$25.49 billion in April, and NT$27.67 billion in May. Consecutive increases in monthly revenue show that pricing and shipment trends remained strong in 2Q26, giving JPMorgan’s expectations for high profitability in 2Q/3Q26 a real basis.
Monthly Revenue in the First Five Months of 2026 Confirms the Cycle Is Still Accelerating
But investors should not directly annualize 1Q26’s 68% gross margin and 53% net margin. These margins are inherently cyclical, driven by simultaneous tailwinds from ASP, inventory cost, capacity utilization, and fixed-cost dilution. If prices remain high, profits will continue to be amplified. If prices decline, gross margin will fall just as quickly. Nanya Technology’s financial quality is improving, but it remains high-beta financial quality, not stable consumer-staples-style financial quality.
A more accurate judgment is that 1Q26 gave Nanya Technology an “entry ticket” for valuation re-rating, not a “graduation certificate.” The entry ticket is that the company has proven with actual financials that DDR4/LPDDR4 supply exit can generate real profits. The graduation certificate would be that in 2H26 and 2027, after normal ASP volatility, rising capex, execution of long-term customer agreements, and server product introductions, the company can still sustain high ROE and high FCF. That certificate has not yet been earned.
10. Three Worldviews: Which Future Will Nanya Technology’s Share Price Ultimately Trade?
The investment debate around Nanya Technology can be split into three worldviews. These are not about right or wrong, but about different weights assigned to supply durability, customer long-term agreements, and product upgrades.
The first is “short-cycle squeeze.” In this world, DDR4/LPDDR4 price increases mainly come from customer restocking and near-term capacity shifts by major manufacturers. After 2H26, as inventories are replenished, platforms migrate, and Chinese supply increases, prices fall quickly. Nanya Technology’s 2026 EPS is very high, but 2027 is revised down significantly. In this world, the company’s reasonable valuation is closer to a discounted cyclical peak earnings framework, with roughly 5x EPS or a PB framework more appropriate.
The second is “long-cycle supply-chain insurance.” In this world, AI servers continue to crowd out advanced capacity, major manufacturers have no incentive to return to DDR4/LPDDR4 at large scale, and eSSD, Networking, automotive, industrial, and edge-server demand is willing to lock in supply through long-term agreements. Nanya Technology can maintain high profits in both 2026 and 2027, with FCF and dividends becoming valuation anchors. In this world, 8x FY27E EPS can be justified.
The third is “serverization re-rating.” In this world, Nanya Technology is not just legacy-specification supply insurance, but also enters the AI server peripheral memory supply chain through RDIMM, SOCAMM, LPDDR5, LPCAMM2, and customized high-bandwidth products. Server revenue share rises from 5% toward 15% or even higher, customer long-term agreements improve visibility, and the market starts to assign it a multiple closer to server supply-chain assets. In this world, NT$710 is not the endpoint, but a neutral-to-optimistic target.
I lean more toward the second worldview, while assigning some option value to the third. The reason is that Nanya Technology has already obtained financial validation from 2025 and 1Q26, as well as customer validation through the private placement and long-term supply agreements. But there is still insufficient evidence on the revenue share from serverization, SOCAMM share, and margins on customized products. From an investment perspective, “long-cycle supply-chain insurance” should be the base case, “serverization re-rating” the upside, and “short-cycle squeeze” the invalidation risk.
This is also the difference in position sizing and tracking method. If one only believes in the first worldview, Nanya Technology can only be traded as price momentum, and one should exit when DDR4 prices soften. If one believes in the second worldview, one needs to tolerate monthly price volatility and focus on long-term agreements, FCF, dividends, and customer structure. If one believes in the third worldview, one must accept a longer product qualification cycle and focus on the 2027 revenue structure rather than single-quarter profit in 2026.
XI. Falsification Checklist: What Would Invalidate NT$710
For a stock like Nanya Technology, the biggest risk is not getting the direction wrong, but getting the direction right while ignoring changes in slope. When the DRAM cycle is moving up, every indicator looks good. When an inflection point appears, it usually shows up first in pricing, order terms, and inventory details, not suddenly in an annual report. The falsification checklist needs to be specific.
First, DDR4 spot prices weaken earlier than expected in 2H26. If DDR4 16Gb or mainstream legacy-spec prices fall quickly after the third quarter, it would suggest customer inventory restocking is complete, or substitute supply is starting to emerge. Nanya Technology’s high gross margin would be compressed first, and EPS forecasts would be revised down.
Second, gross margin fails to hold high levels. In JPMorgan’s model, 2026E/2027E gross margins are as high as 77.6%/82.0%, and 1Q26 has already reached 68%. If 2Q26 gross margin fails to keep rising, or 3Q26 comes in clearly below market expectations, it would suggest ASP and cost leverage are not as strong as the model assumes.
Third, the revenue contribution from servers and data centers does not rise. Server applications were about 5% in 2025, a very low base. If there is still no material contribution from RDIMM, eSSD, Networking, or SOCAMM to the revenue mix by end-2026, the market will reclassify Nanya Technology as a legacy DRAM price-upcycle stock.
Fourth, long-term contract customers do not convert into visible orders. The private-placement participants and supply-chain relationships with Kioxia Holdings, Solidigm, SanDisk, Cisco, and others are important evidence for Nanya Technology’s valuation re-rating. If these relationships remain only financial investments and framework agreements, without verifiable orders, pricing terms, or revenue contribution, the market will reduce the long-term contract premium.
Fifth, CXMT or other supply creates an earlier-than-expected shock. Nanya Technology’s official annual report has already listed Chinese DRAM capacity expansion as a risk. If Chinese suppliers accelerate volume ramp in standard DDR4/DDR5 products and customers are willing to substitute, Nanya Technology’s ASPs in China and standard-spec products will come under pressure.
Sixth, 1C/1D and Fab 5A progress is delayed. To sustain its valuation after 2027, Nanya Technology must move from legacy-spec price increases to new-product revenue. If 1C/1D validation, Fab 5A equipment installation, server module certification, or customized high-bandwidth product progress falls short of expectations, the market will reduce the sustainability weight assigned to post-2027 EPS.
Nanya Technology’s falsification conditions are concentrated in pricing, customers, and process technology
These falsification conditions matter more than the target price. Nanya Technology’s share-price elasticity comes from the slope of the model. Once that slope changes, valuation will react before earnings. Investors need to accept one fact: this is not a low-volatility, high-certainty company. It is a hybrid cyclical growth asset with high cash flow, high price elasticity, and rapid falsification speed.
XII. Four-Quarter Tracking Table: Watch the Numbers, Not the News
Over the next four quarters, the five most important numbers to track for Nanya Technology are monthly revenue, gross margin, server-related revenue share, capex/cash flow, and product validation milestones. News and target prices can stimulate short-term moves, but these numbers determine whether the re-rating can continue.
This tracking table also explains why investors should not only watch whether the share price reaches NT$710. Nanya Technology could approach the target price on short-term price momentum, or see valuation volatility before fundamentals continue to improve. A more mature approach is to rescore the numbers each quarter under three worldviews: whether it looks more like a short-cycle squeeze, a long-cycle supply-chain insurance asset, or the start of a serverization re-rating.
If 2Q/3Q26 gross margin continues to rise, monthly revenue stays high, customer long-term contract news increases, and server-related revenue share rises, NT$710 is not an extreme target price. If DDR4 pricing falls in 2H26, serverization evidence is insufficient, and CXMT competition intensifies, the market will compress the FY27E multiple in advance even if 2026 EPS is high.
XIII. Trading Framework: Split Nanya Technology into Price, Customer, and Option Buckets
Nanya Technology is best tracked using a layered framework. The first layer is the price bucket, centered on ASPs, contract prices, and spot prices for legacy-spec DRAM. This bucket is the most sensitive and the easiest place to make quick money because the income statement has very high elasticity to ASP. Its risk is equally clear: once pricing starts to loosen, the market will immediately treat high EPS as a cyclical peak rather than stable earnings.
The second layer is the customer bucket, centered on whether eSSD, Networking, automotive, industrial, and server customers can turn orders into long-term contracts. The customer bucket is slower than the price bucket, but higher quality. The price bucket answers “how much can be earned in this cycle”; the customer bucket answers “whether customers will still be willing to lock supply in advance in the next cycle.” After Nanya Technology brought in industrial customers such as Kioxia Holdings, Solidigm, SanDisk, and Cisco, the market assigned it a higher valuation not because those names sound good, but because they can turn legacy-spec DRAM from a spot-traded product into a supply-chain security allocation.
The third layer is the option bucket, centered on RDIMM, SOCAMM, LPDDR5, LPCAMM2, TSV, and customized high-bandwidth products. The option bucket cannot be valued as a core business too early, because certification, yield, customer introduction, and mass production all take time. But it also cannot be ignored, because it determines whether Nanya Technology can shed the label of “legacy-spec price-upcycle stock.” Once serverization products start contributing revenue, the market will reopen the debate over what EPS multiple, FCF yield, and dividend assumptions should be used to price the company.
These three buckets correspond to three trading disciplines. The price bucket should be fast: changes in ASP, gross margin, and monthly revenue trends require reassessment. The customer bucket should be stable: focus on long-term contracts, supply agreements, customer concentration, and revenue mix, without being led astray by one month of price volatility. The option bucket requires patience: a single product announcement should not directly raise terminal valuation, and the lack of near-term revenue should not zero out all technology pathways.
The most attractive feature of Nanya Technology today is that all three buckets have evidence at the same time for the first time. The price bucket has already been validated by financial results; the customer bucket is supported by private placements and long-term supply agreements; the option bucket has an official product roadmap and server module progress. The biggest risk is also that these three buckets may not move in sync: pricing may peak first, customer orders may be slower than expected, and the serverization option may not have time to materialize. If the market fully prices in the option before it is exercised, the margin for error will fall.
Therefore, the reasonable holding logic for Nanya Technology is not “buy because the target price was raised,” but “rescore the three buckets every quarter.” If the price bucket stays intact, it can at least support earnings elasticity. If the customer bucket continues to strengthen, valuation can move up from cyclical-stock levels. Only when the option bucket starts generating revenue does the stock qualify for a higher valuation range. As long as two of the three buckets are still improving, share-price pullbacks look more like validation-period volatility. If two buckets weaken at the same time, position assumptions should be reduced no matter how high the target price is.
This framework has another benefit: it separates short-term price volatility from long-term asset characteristics. Nanya Technology can deliver a rapid profit surge because of legacy-spec price increases, but whether it can retain a higher valuation depends on proof from customers and products.
XIV. Conclusion: What Nanya Technology Offers Is a Conditional Re-Rating, Not Blind Cycle Chasing
Nanya Technology now looks most like a DRAM company whose asset attributes are shifting gears. In the past, its value came from the cyclical elasticity of consumer, PC, low-power, and legacy-spec products. Now its value comes from supply insurance after DDR4/LPDDR4 EOL, eSSD and Networking customer lock-in, the serverization option from RDIMM/SOCAMM, and product upgrades from 1B/1C/1D/Fab 5A.
JPMorgan’s NT$710 target price is not unreasonable, but it is conditional. First, the DDR4/DDR5 upcycle needs to last longer than a traditional cycle, without rapid price declines in 2H26. Second, Nanya Technology’s 2026-2027 gross margin and OPM need to approach the model assumptions. Third, servers, eSSD, Networking, SOCAMM, and RDIMM need to provide at least some revenue evidence. Fourth, the company cannot sacrifice FCF and dividend optionality for capacity expansion.
If these conditions hold, Nanya Technology is not just a DDR4 price-upcycle stock, but a second-tier DRAM asset being repriced within the AI storage supply chain. It does not have the technical moat of the HBM leaders, but it has unique elasticity from legacy-spec supply exits, long-term customer contracts, cash flow, and server bypass demand. The market’s willingness to assign it 8x FY27E EPS is a bet that this storage cycle is no longer only price mean reversion, but also a long-term contraction in supply structure and a rebuild of customer safety inventory.
If these conditions do not hold, Nanya Technology will quickly revert to being a cyclical stock. Nearly all of the company’s revenue comes from DRAM, margins are extremely sensitive to ASP, server application revenue share remains low, 1C/1D and SOCAMM are still in validation, and supply competition from CXMT and others has not disappeared. Its upside and downside come from the same fact: the business is very pure, elasticity is high, and falsification is fast.
The most reasonable investment conclusion is that Nanya Technology is suitable as a “high-elasticity core watchlist name” in a storage upcycle, not as a low-risk long-term compounder. The buy case is not “JPM gave it NT$710,” but using pricing, gross margin, server share, long-term contract orders, and product milestones each quarter to validate the four premises behind NT$710. As long as validation continues to pass, valuation can migrate from cyclical stock toward server supply-chain asset. Once validation breaks, even a high target price is only a footnote to the cyclical peak.
Nanya Technology’s final thesis can be compressed into one sentence: DDR4 EOL gives it profit, long-term customer contracts give it cash flow, SOCAMM/RDIMM give it a valuation option, and 1B/1C/1D plus Fab 5A determine whether it can retain this cycle’s high profits beyond 2027. Investors should buy the continued delivery of these four things, not simply a raised target price.