
NAND Industry Deep-Dive Update: Triple Validation of AI eSSD Shortages, Supply Discipline, and 2028 New Capacity
目录
Too Long; Didn’t Read
1. What This NAND Update Needs to Answer
2. What the Recent Reports Actually Added
3. Morgan Stanley Supply-Demand Model: AI NAND Moves from Incremental Demand to the Main Variable
IV. eSSD Is Hard Evidence: May Capacity Shipments +139% YoY
V. 3Q26 Price Divergence: eSSD Still Strong, Consumer Starting to Buckle
VI. Supply Discipline: Why NAND Has Not Immediately Been Knocked Back by Capacity Expansion
VII. 2028 Scenario Test: New Capacity Is the Biggest Variable in This Cycle
VIII. NBM and LTA: Can Cyclical Profit Become a Cash-Flow Asset?
IX. Company and Segment Ranking: Prioritize Manufacturers, Module Makers Diverge, Controllers Depend on Certification
10. Three Worldviews: Shortage Extension, Structural Balance, Supply Return
11. Tracking Indicators: The Next Four Numbers Matter Most
12. Conclusion: NAND Is Not Over, but Entry Points Are Now More Selective
本内容基于公开资料和研报数据整理,不构成任何投资建议,不代表任何个人观点,仅供学习参考,请理性阅读
The NAND cycle has moved from reviewing price increases to validating supply discipline: AI eSSD is still creating shortages, the consumer side is starting to hit a pricing ceiling, manufacturers are prioritizing DRAM/HBM ahead of NAND expansion, and new capacity in 2028 will determine whether this profit cycle is a cash-flow re-rating or a cyclical peak.
Too Long; Didn’t Read
The NAND trade has entered its second stage. The first stage bought into the price surge; the second stage depends on whether AI eSSD can continue absorbing supply, whether manufacturers can maintain capex discipline, and whether new capacity in 2028 pushes scarcity back into oversupply. The common shift across several reports over the past seven days is that the debate has moved from “will prices rise in 2Q26” to “can the shortage persist in 2027, and will it reverse in 2028.”
AI eSSD is the main axis of this NAND shortage. Morgan Stanley estimates AI-related NAND demand will rise from 205EB in 2025 to 609EB in 2027, lifting its share of total NAND demand from 18% to 41%; JPM’s May data also show enterprise/data center SSD capacity shipments up 139% YoY, far stronger than ordinary SSD unit shipments. NAND is no longer driven only by smartphones, PCs, and consumer SSDs. The data center capacity layer is rewriting the demand structure.
Pricing is clearly diverging. The strongest category in 3Q26 remains eSSD, while price increases for consumer-grade and mobile NAND are starting to lag. Morgan Stanley’s channel checks show TLC eSSD still rising about 30% QoQ, while consumer-grade products are only up slightly. This divergence matters: the industry remains tight, but price increases can no longer be passed through indiscriminately to all customers.
Supply discipline remains the core bull case. Goldman Sachs raised its Kioxia target price to JPY116,000, citing CY26 NAND ASP up 4.5x YoY, CY27 up 38% YoY, and major memory vendors prioritizing DRAM/HBM investment, with new NAND fab supply additions likely to become more visible only in CY28. Citi also raised its SanDisk target price to USD2,500, emphasizing that NAND tightness could persist beyond CY27 and, in some scenarios, into CY28.
2028 is the largest window for disconfirmation. Morgan Stanley’s 2028 scenario analysis puts the key variable on new NAND capacity, especially new Chinese capacity and AI SSD demand growth. If AI SSD demand can still grow 50%-60% YoY in 2028, supply could remain tight; if demand grows only 30% and new capacity accelerates, supply-demand could shift into oversupply. For the bull case to win through 2028, both demand and discipline must be right.
Investment ranking needs to shift from “who benefits from price hikes” to “who can defend profits.” Pure-play NAND manufacturers and companies with long-term agreements, eSSD qualifications, and QLC/high-IOPS products are more likely to convert price increases into durable profits; ordinary module makers and consumer-channel players are more likely to be squeezed by inventory, FIFO costs, and customer resistance to price hikes. Track four numbers next: eSSD capacity shipments, 3Q26/4Q26 ASP divergence, manufacturers’ NAND capex, and the cadence of new capacity in 2028.
1. What This NAND Update Needs to Answer
The most important question for NAND is no longer “have prices risen.” Prices have already risen, by enough that the market has already reflected one round of this in the share prices of SanDisk, Kioxia, Micron, Samsung, SK Hynix, A-share module companies, and controller companies. The question now is whether this profit cycle can extend beyond 2027 and withstand the return of supply in 2028.
That is the shared thread across several research reports from the past week. Morgan Stanley’s global NAND industry outlook extends the supply-demand model to 2028; Goldman Sachs revised up its Kioxia model; Citi used Micron’s results to read through to SanDisk and NAND pricing; Korean price tracking provided segmented 3Q26 ASPs; JPM used May HDD/SSD data to validate enterprise SSD capacity demand. They approach the issue from different angles but point to the same conclusion: the NAND industry has not simply peaked, but it is no longer in a broad-based price-hike phase.
There are three most direct changes.
First, the subject of demand has changed. In the past, NAND price increases often came from restocking in smartphones, PCs, and consumer SSDs. Now the subject has shifted to AI data centers, enterprise SSDs, high-capacity QLC drives, KV cache, RAG, and agentic AI. The consumer side remains important, but it is no longer the strongest marginal driver.
Second, the supply constraint has changed. In past NAND cycles, supply depended on production cuts, inventory digestion, and price recovery. Now supply discipline comes from another layer: DRAM/HBM is occupying capex priority, while new NAND capacity construction and customer qualification are both slower than the slope of AI demand. Manufacturers do not lack the desire to make money; rather, the more profitable DRAM/HBM opportunity is taking cleanroom, equipment, and engineering resources first.
Third, the timing of disconfirmation has changed. Tightness in 2026 has already been incorporated into many models, and the 2027 shortage is becoming the base case for bulls. The real contest is in 2028. New fabs, technology migration, new Chinese supply from Yangtze Memory Technologies and others, and subsequent resource shifts by Samsung/Micron/SK Hynix will all affect NAND supply-demand around 2028.
AI Drives a Sector-Wide Storage Re-Rating: DRAM, NAND, SSD, and HDD Pricing Power, Cross-Validated by Samsung, SK Hynix, SanDisk, Western Digital, and Seagate Earnings
Therefore, this NAND industry update will not repeat why the “storage supercycle” matters. The prior storage series has already discussed HBM, DRAM, NAND, SSD, and HDD within the AI data stack. What is needed now is to isolate NAND and clarify where the industry stands: price increases continue, but strength is now tiered; manufacturers still have pricing power, but customers have started to select by product; 2027 remains tight, while 2028 needs to be recalculated.
2. What the Recent Reports Actually Added
The recent NAND-related reports do not offer the same target price, nor are they simply a repeated bullish call from the same institution. Each adds a separate piece of evidence. Together, they form the core of this industry update.
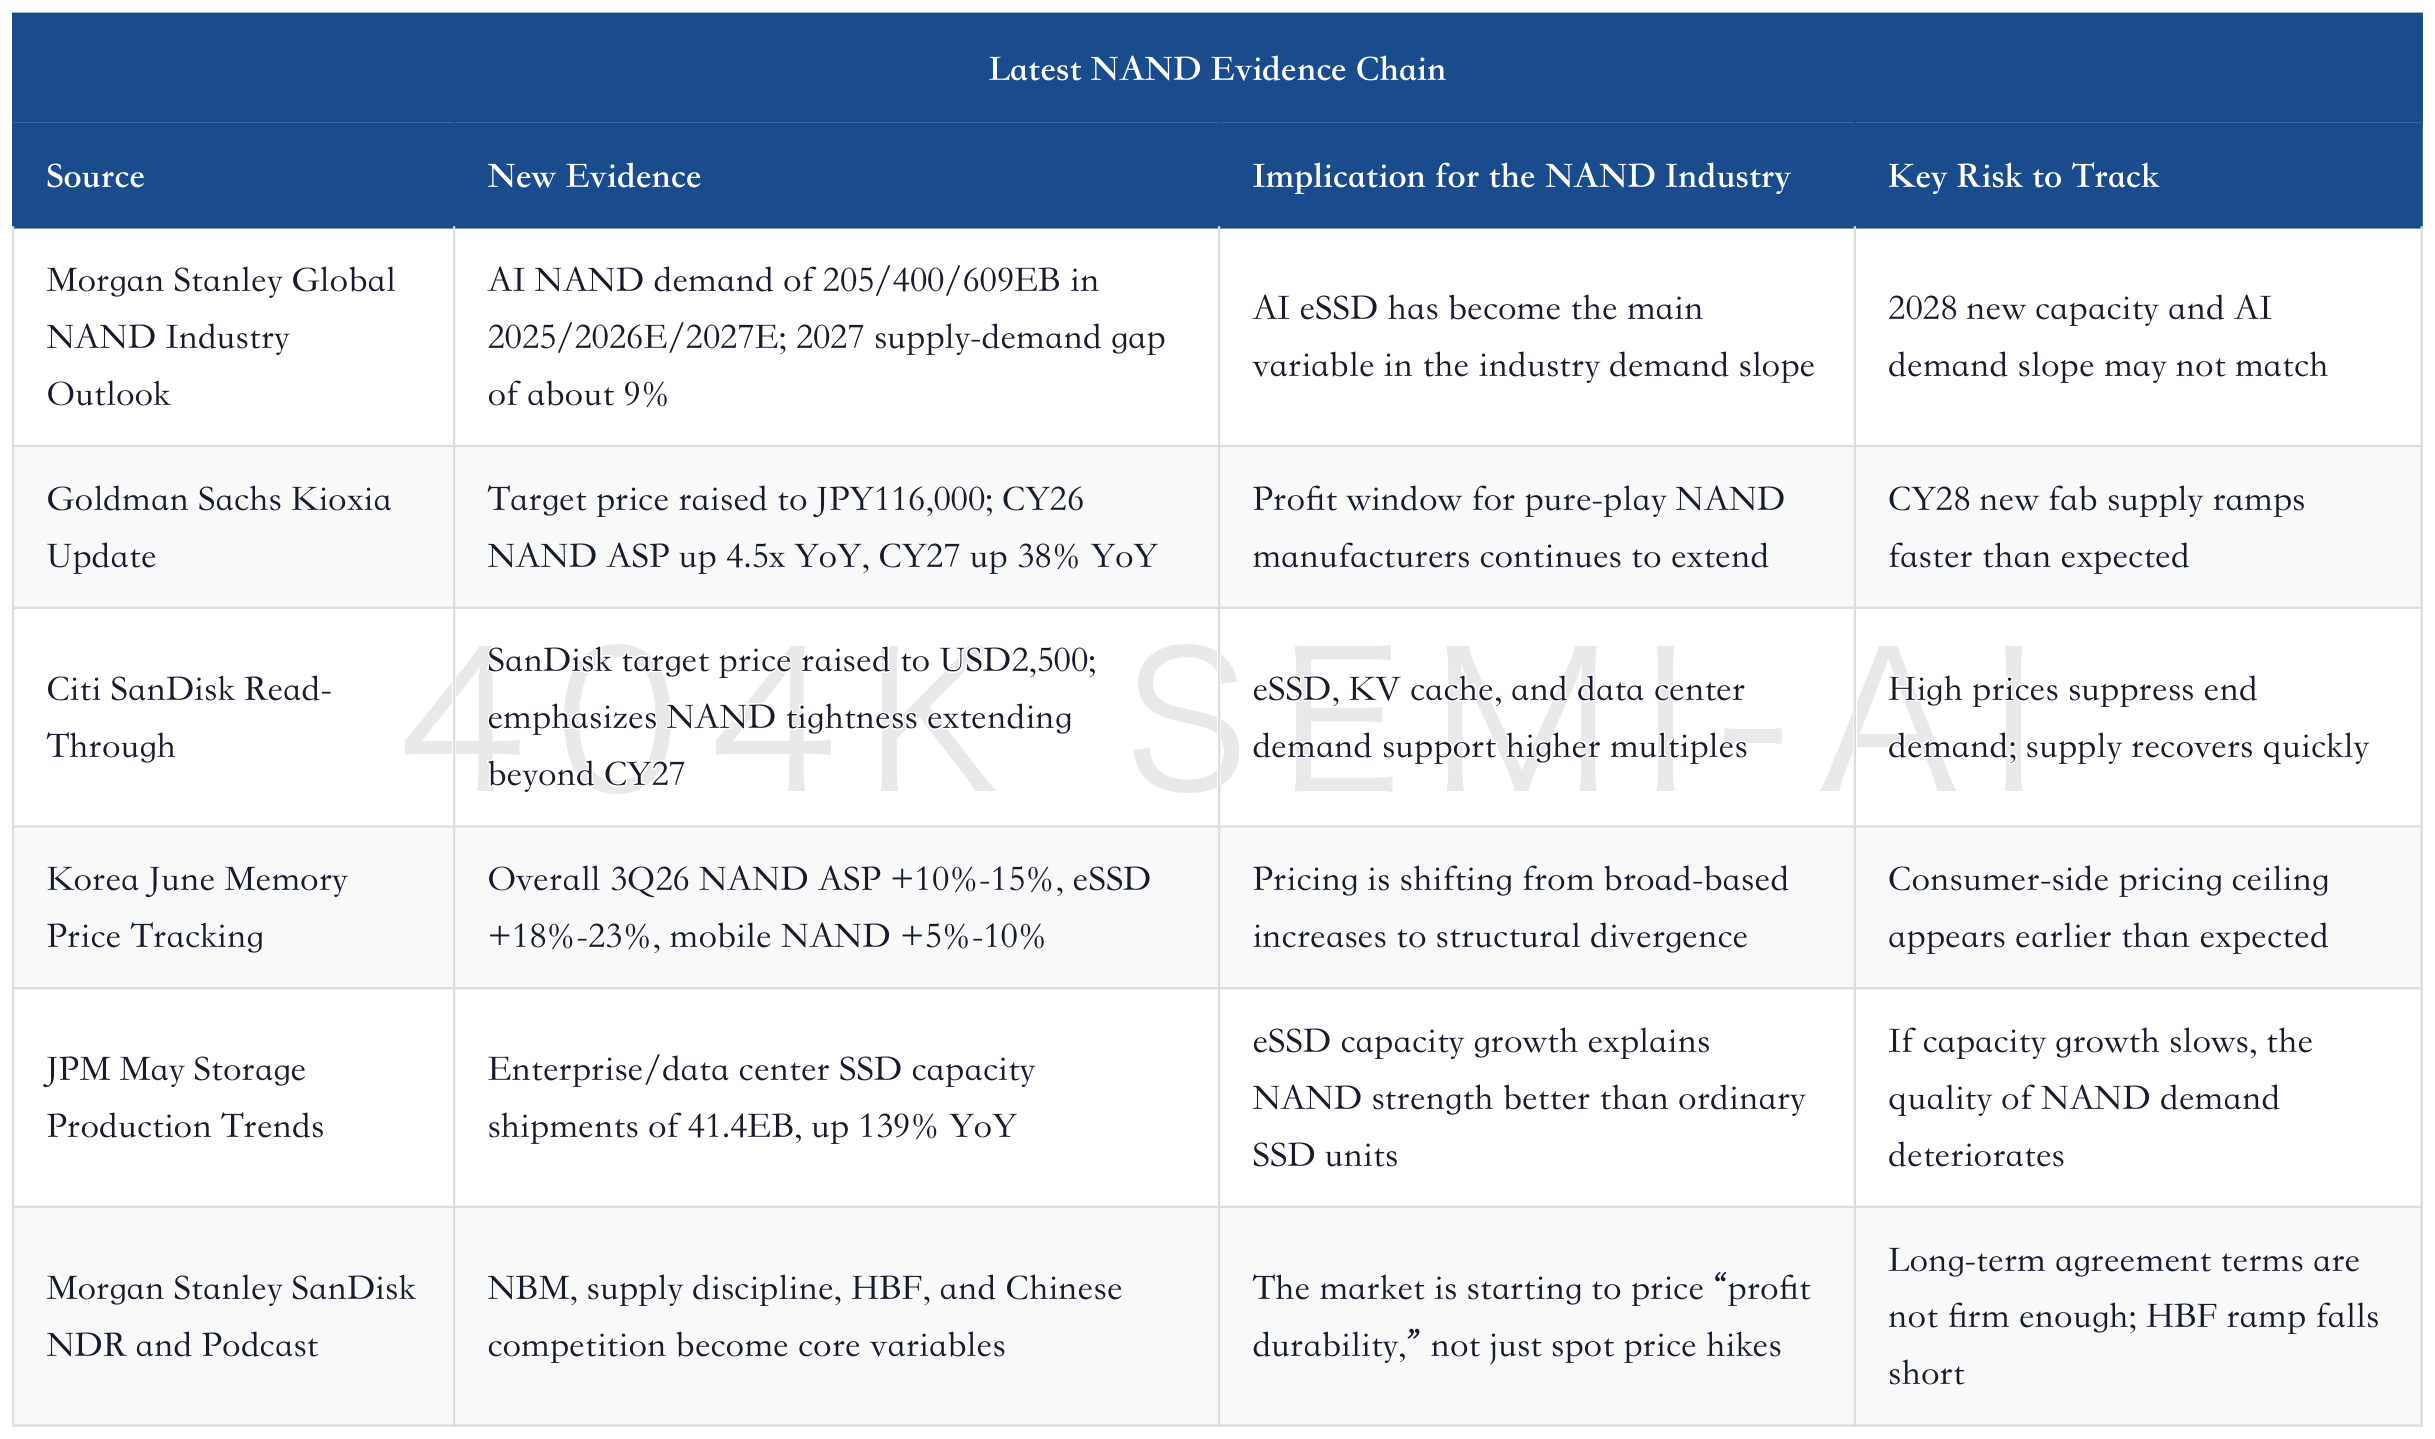
This table helps distinguish what is new information from what is merely an old view stated differently. NAND tightness is not a new view, and AI storage is not a new concept. The genuinely new change is that several pieces of evidence are pointing simultaneously to “extended tightness, but with structural divergence.”
On one side, the data center is stronger. Morgan Stanley’s supply-demand model lifts AI NAND demand as a share of total demand from 18% in 2025 to 41% in 2027; JPM’s May data also show enterprise/data center SSD capacity up 139% YoY. This suggests demand is not only in company guidance, but also in monthly industry data.
On the other side, the consumer side is weakening. In Korean price tracking, eSSD can still rise 18%-23% in 3Q26, while mobile NAND is only up 5%-10%; Morgan Stanley’s channel checks also show TLC eSSD up about 30% QoQ, while consumer-grade NAND is only up slightly. Customers still need NAND, but different customers have completely different tolerance for prices.
The third side is that supply remains slow. Goldman Sachs’ equipment-channel checks indicate major memory vendors continue to prioritize DRAM investment, and new NAND fab supply additions may become more visible only in CY28. Citi also emphasizes that limited cleanroom space is constraining NAND bit supply growth. If supply discipline holds, a 2027 shortage is not just a slogan.
The fourth side is that the 2028 uncertainty has increased. Morgan Stanley’s 2028 scenario analysis brings new capacity to the foreground: if AI SSD demand continues growing rapidly and new capacity remains controlled, the shortage can persist; if new capacity accelerates and AI SSD demand slows, NAND supply-demand could quickly return to oversupply risk.
Global Storage Deep Dive: 2Q26 Earnings Divergence, and Whether 3Q Pricing Improvement Can Restart a Storage Stock Re-Rating
This is the difference between an industry note and a single-stock note. A single-stock note needs to answer whose profit leverage is greatest. An industry note needs to answer where the boundaries of that profit leverage lie. For NAND, those boundaries are now clear: 2026 is about pricing, 2027 is about the persistence of shortages, and 2028 is about supply discipline.
3. Morgan Stanley Supply-Demand Model: AI NAND Moves from Incremental Demand to the Main Variable
The core table in Morgan Stanley’s global NAND industry outlook is its AI NAND demand and global NAND supply-demand table. It advances the market debate from “will AI use NAND” to “how many EB will AI consume.”
In Morgan Stanley’s estimate, AI-related NAND demand rises from 205EB in 2025 to 400EB in 2026E and then to 609EB in 2027E. Its share of total NAND demand rises from 18% to 32% and then to 41%. This is not a small supplementary item, but the most important incremental driver of total demand.
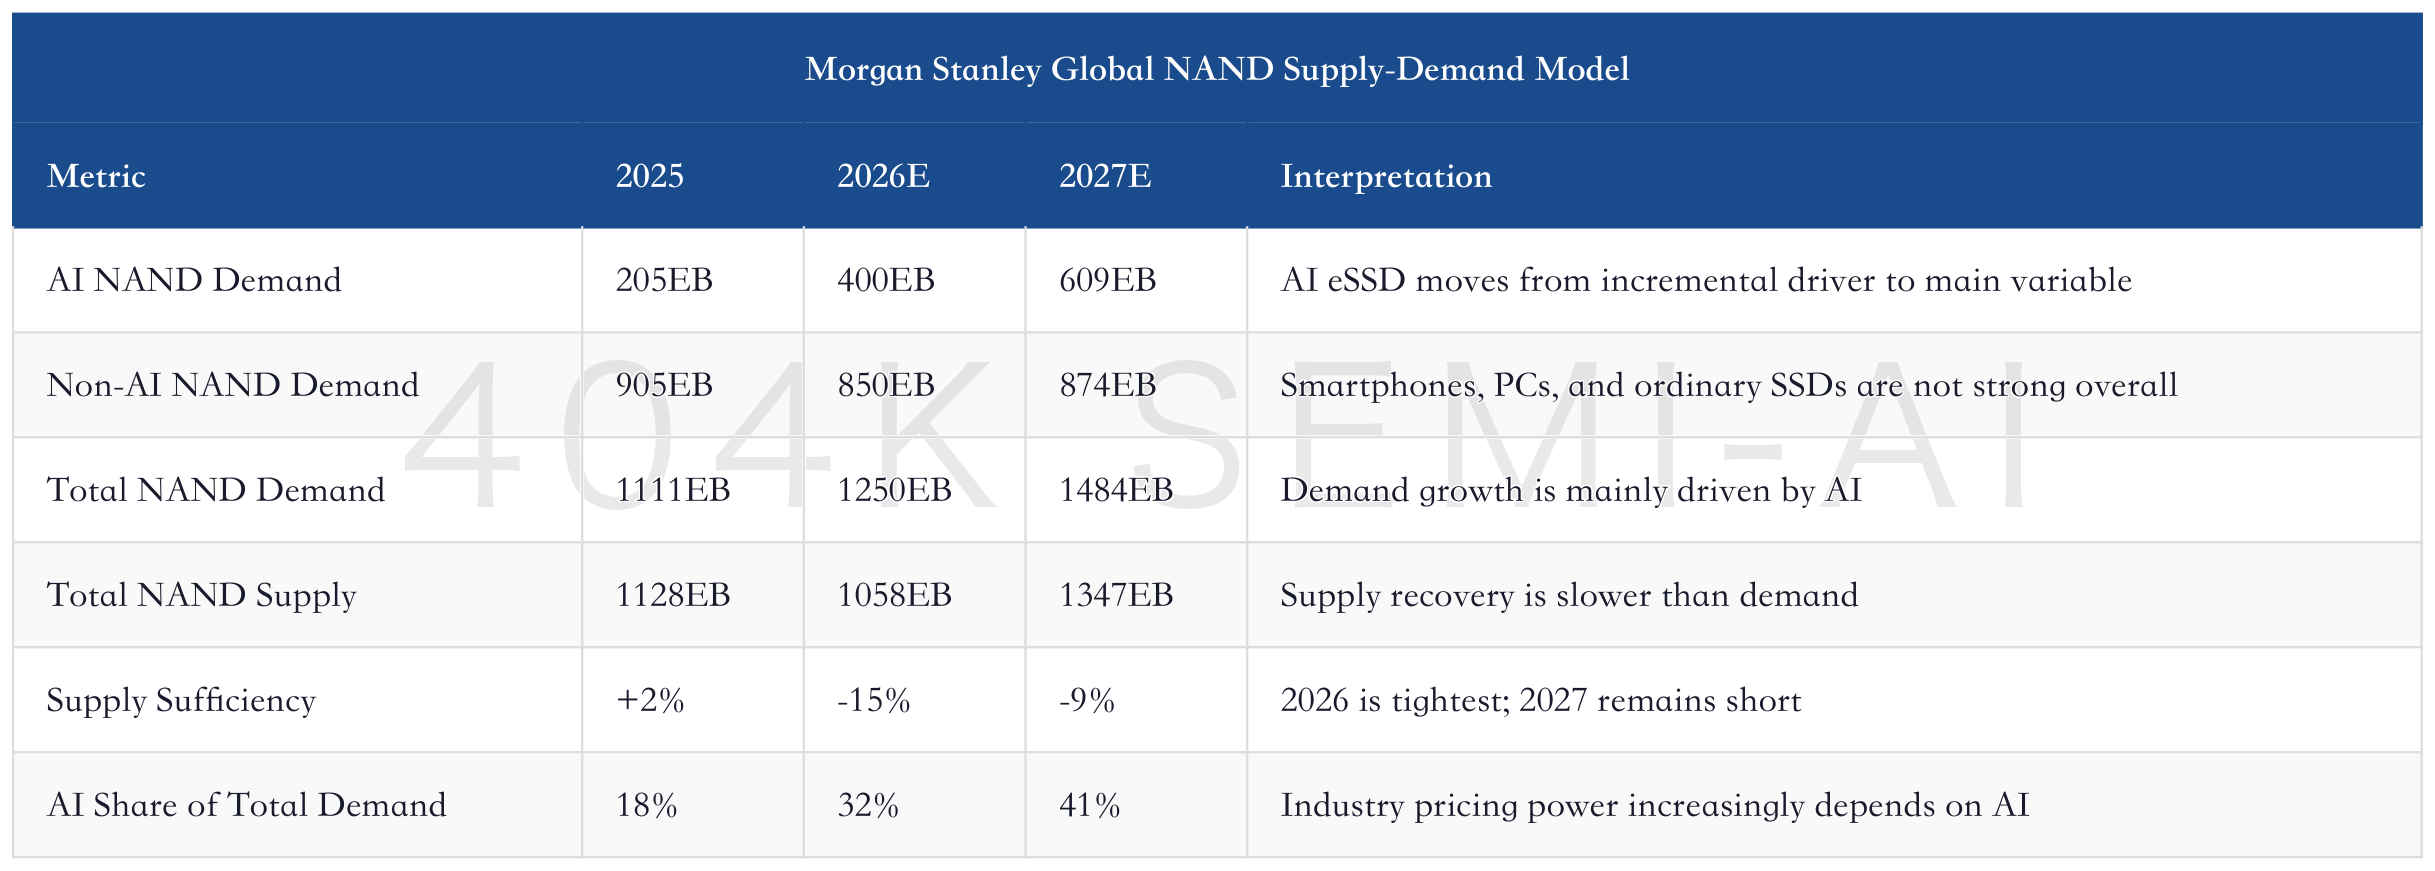
This table has two important implications.
First, non-AI demand is not the protagonist. Non-AI NAND demand in 2026E is below 2025, and 2027E only recovers slightly. Smartphones, PCs, and ordinary SSDs are not providing a sector-level strong recovery. If the NAND bull case only talks about consumer electronics restocking, it is hard to justify such high earnings forecasts.
Second, AI demand is not one-off inventory. Morgan Stanley’s AI NAND breakdown comes from multiple sources, including ASIC/GPGPU shipments, actual CSP deployments, in-rack eSSD, external storage, QLC data lakes, additional Blackwell configurations, CPU racks, and Seagate Technology CMS. It places NAND inside AI racks and data lakes, rather than treating it merely as traditional server SSD.
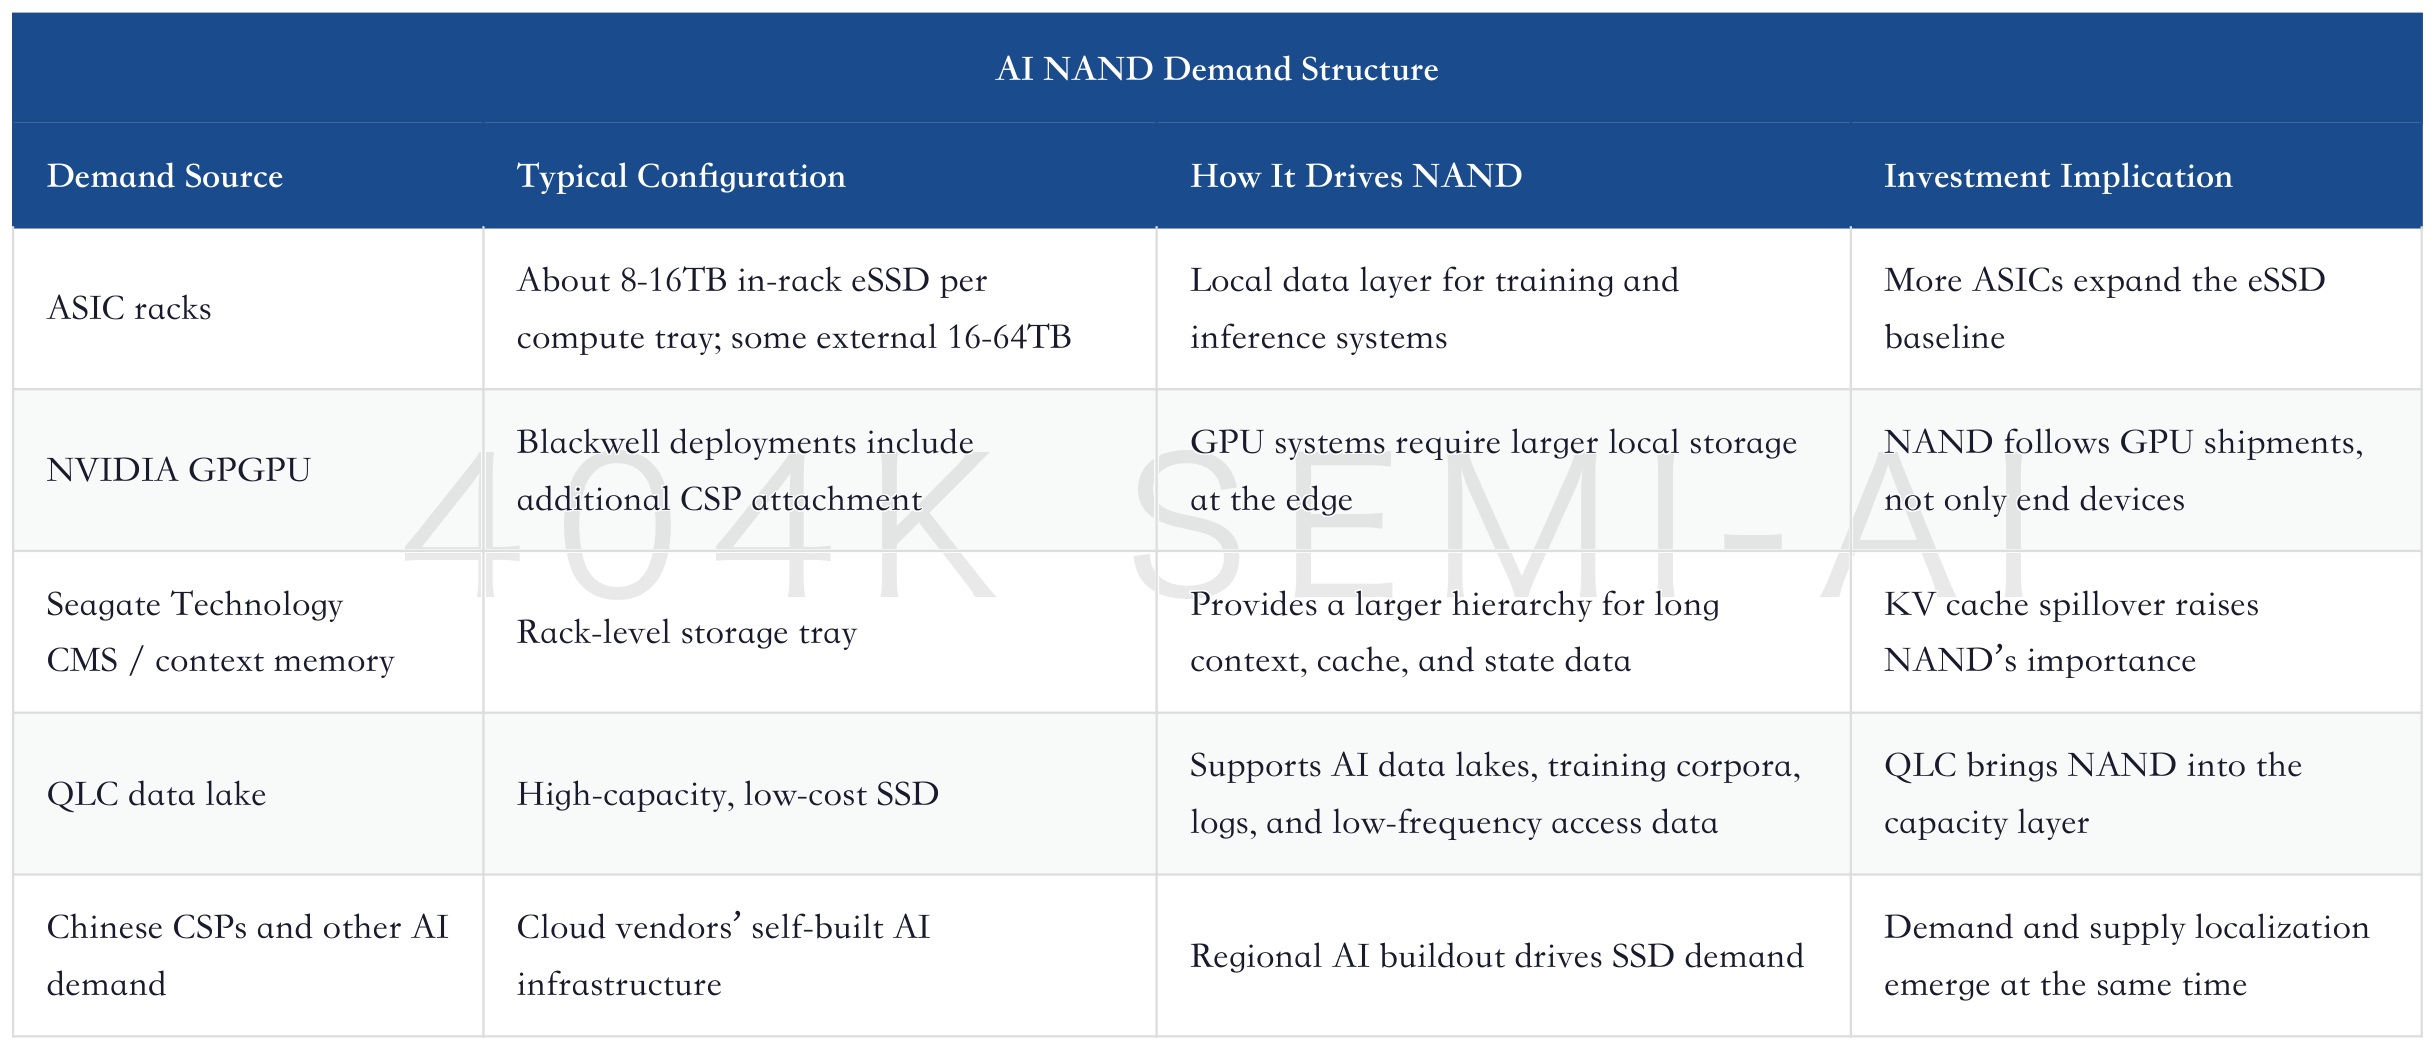
Morgan Stanley’s supply-demand model also highlights an underappreciated point: non-AI demand can be weak, yet AI demand can still be sufficient to create a shortage. NAND’s structure is starting to look like a “barbell”: one end is the extremely strong data center, while the other is the pressured consumer side. Industry ASPs, company profits, and valuation leverage all depend on which end carries more weight.
How to Bypass the Memory Tax: NAND, CXL, and PIM Are Being Repriced as the Storage Hierarchy Is Rebuilt
This is also why follow-up tracking cannot look only at NAND spot prices. Spot prices are affected by the consumer side, channel inventory, and short-term trading. More important indicators are enterprise SSD capacity shipments, high-capacity QLC products, cloud procurement, long-term agreement coverage, server inventory, and manufacturers’ capex. These indicators are better at judging whether AI NAND demand is still present.
IV. eSSD Is Hard Evidence: May Capacity Shipments +139% YoY
If Morgan Stanley’s supply-demand model answers “where the future NAND shortage comes from,” JPM’s May storage production trends answer “whether data center SSD demand is being realized now.”
The key in the May data is not SSD units, but capacity. Unit shipments of ordinary SSDs are not strong, but enterprise/data center SSD capacity shipments have already separated the quality of NAND demand.
The most important part of this dataset is not units, but capacity. NAND is sold in bits, and the value of enterprise SSDs increasingly depends on capacity, performance, reliability, and qualification, rather than the number of drives.
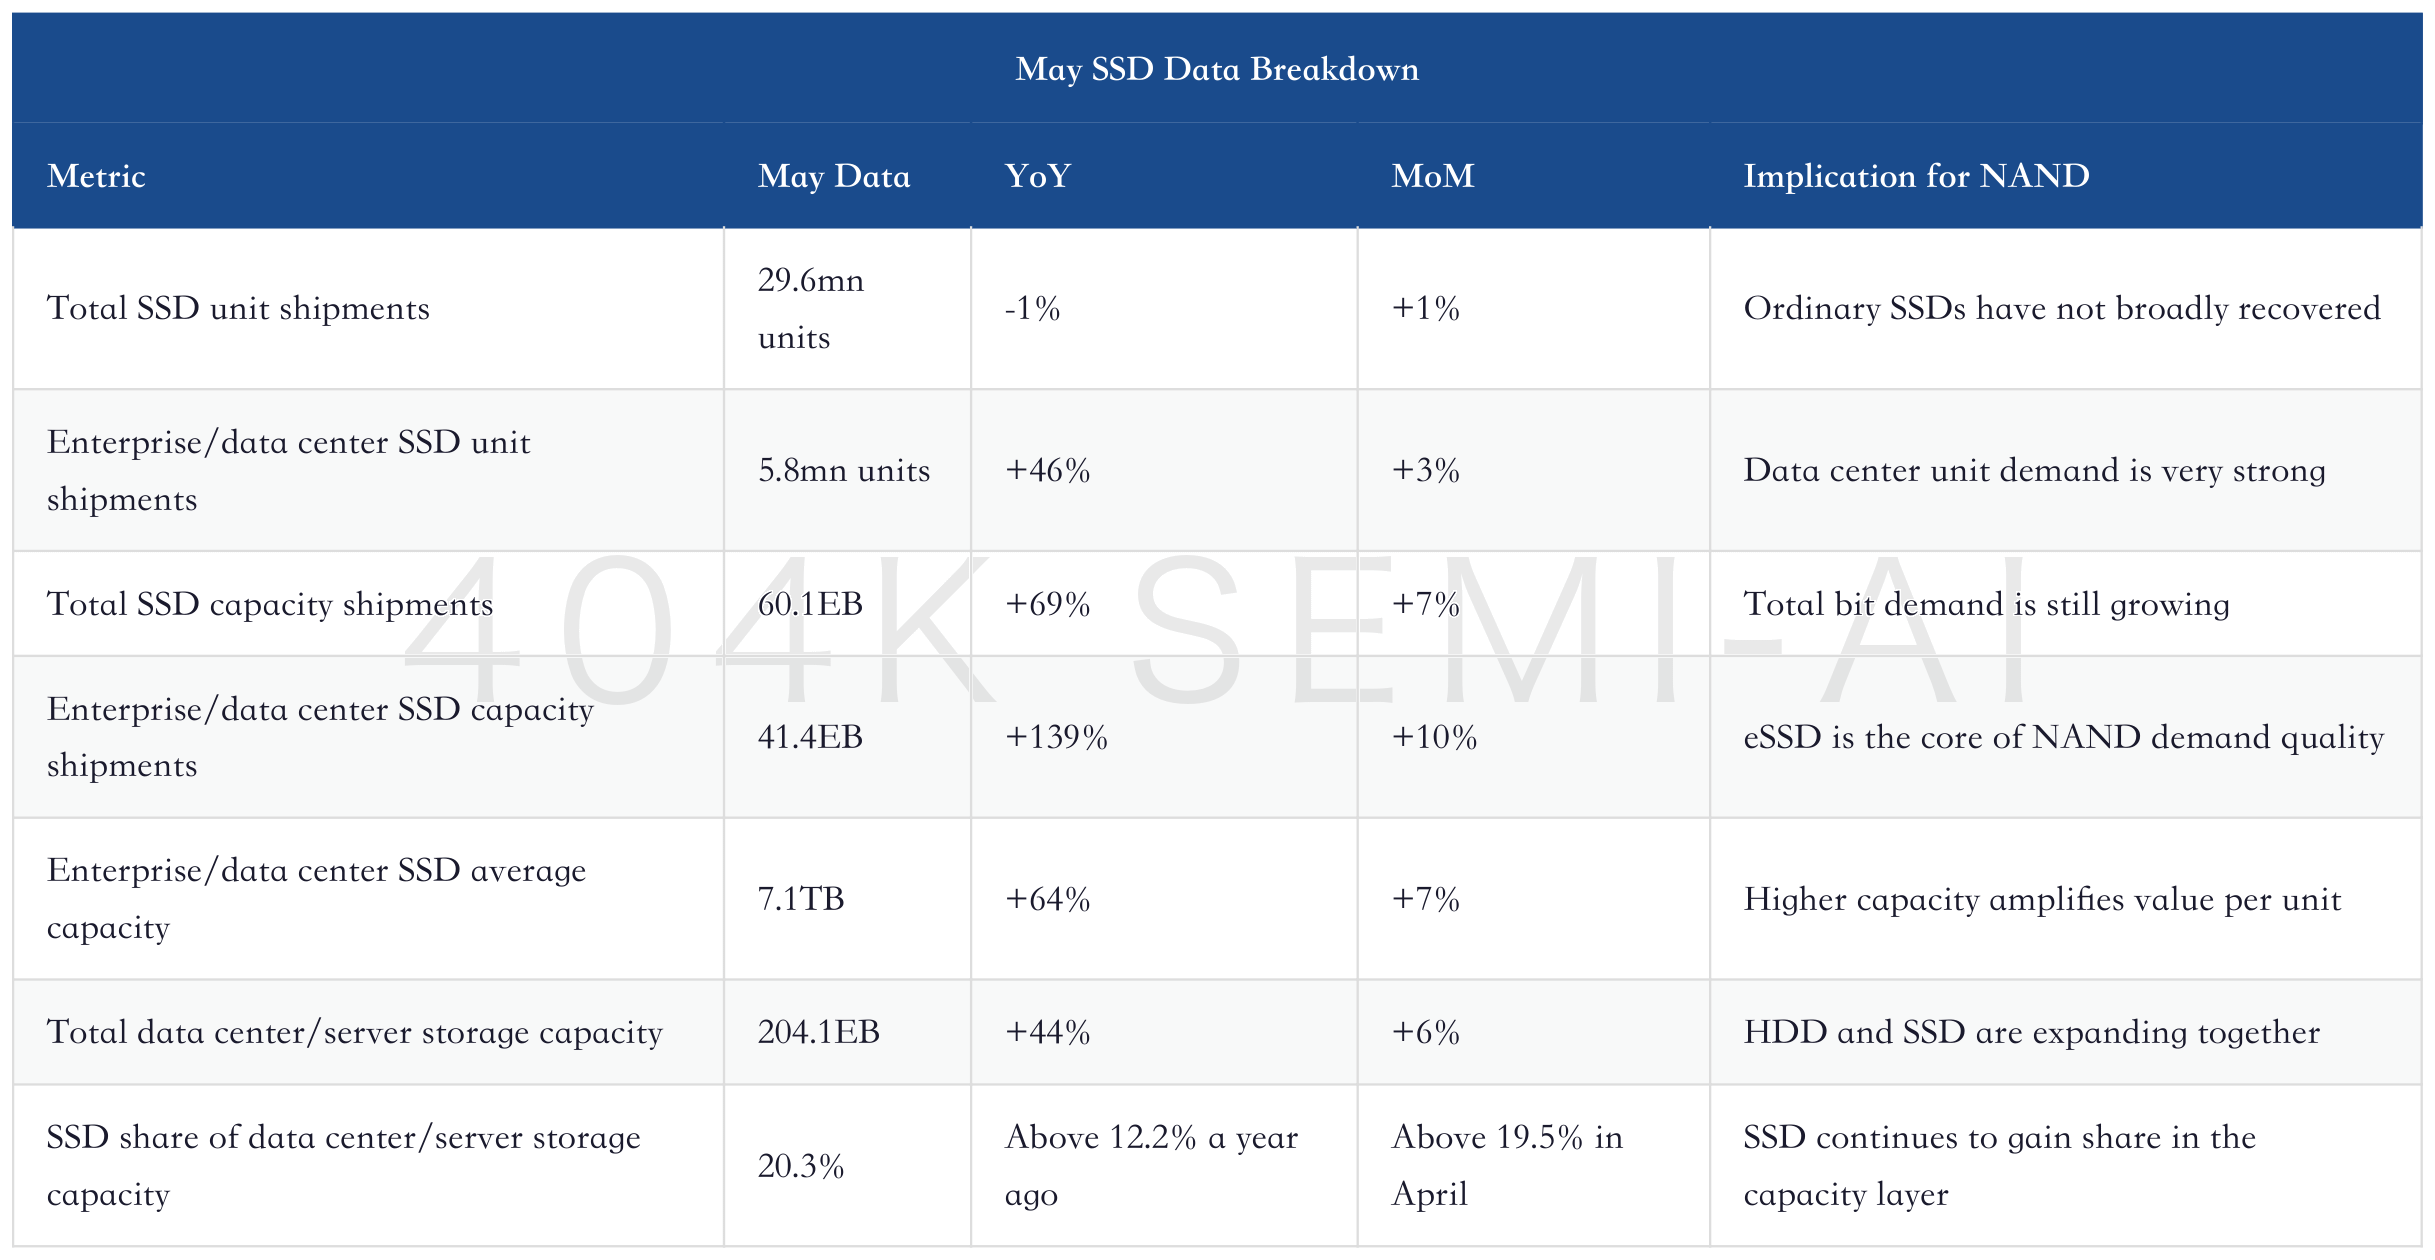
There is one key message here: demand is coming not only from “more SSDs,” but also from “larger SSDs.” JPM noted that demand for high-capacity enterprise/data center SSD products such as 61.44TB, 122.88TB, and 245.76TB has reached very high levels, and QLC designs are becoming more common in these capacity tiers. This corroborates Morgan Stanley’s model, which classifies data lake-related demand under QLC.
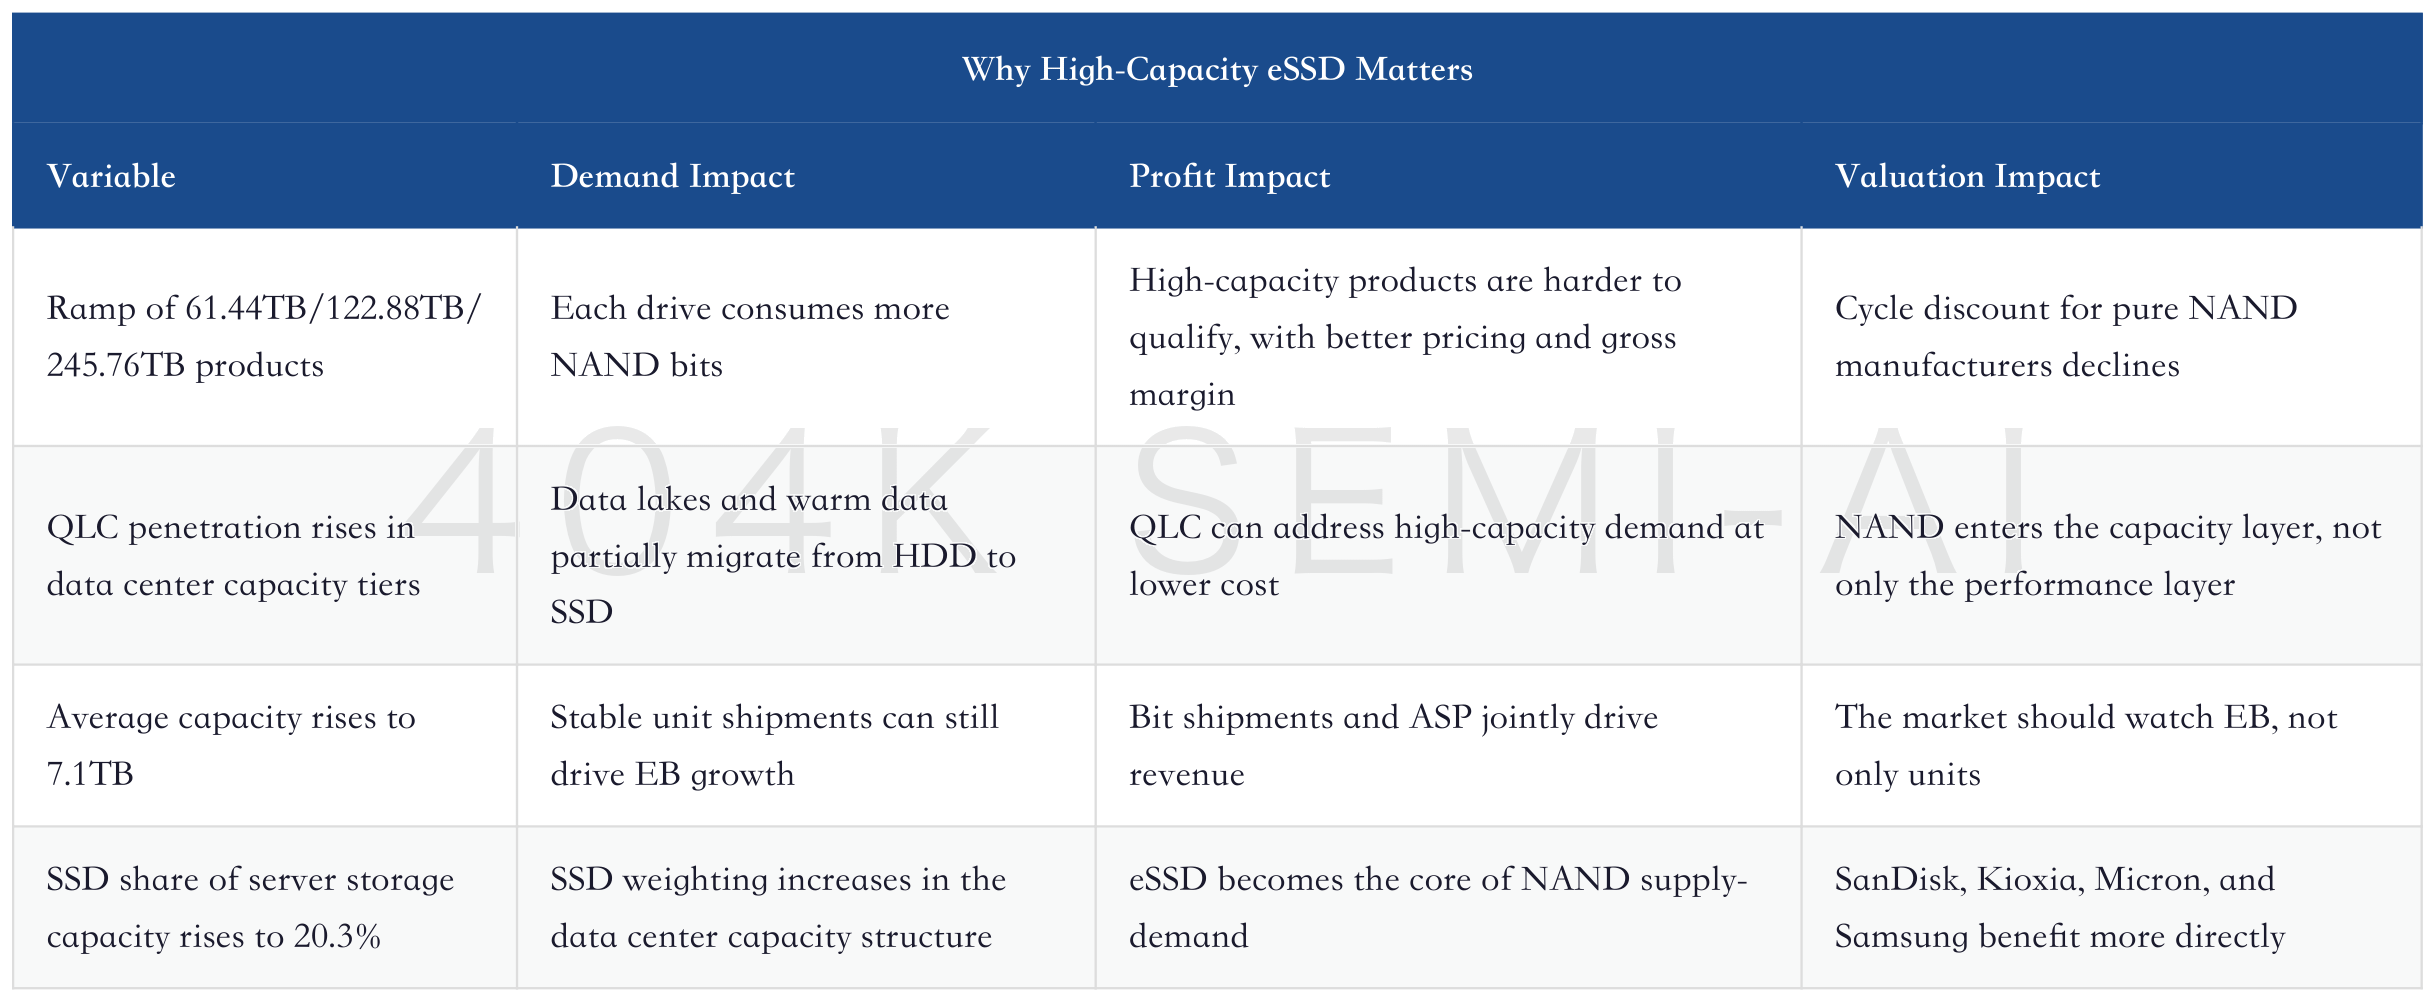
This explains why NAND and HDD can both be strong at the same time. Enterprise SSDs are not simply replacing nearline HDDs, and nearline HDDs are not suppressing enterprise SSDs. AI data centers are expanding the entire storage pyramid: hot data needs SSDs, warm data needs both SSDs and HDDs, and cold data needs HDDs and tape. Within this pyramid, NAND is taking the higher-performance, higher-capacity, higher-value layers.
AI Storage Deep-Dive Update: Morgan Stanley’s May HDD and SSD Data Confirms Data Center Capacity Demand Remains Elevated
This also gives the NAND industry a validation method. As long as enterprise/data center SSD capacity continues to grow strongly, AI demand for NAND is still present. If total SSD units remain flat and consumer SSD demand is weak, but eSSD capacity continues to rise, the industry structure will continue to tilt toward original manufacturers and high-end products. If eSSD capacity growth falls back to the level of ordinary SSDs, the NAND bull case loses its hardest data support.
V. 3Q26 Price Divergence: eSSD Still Strong, Consumer Starting to Buckle
Pricing is the easiest NAND indicator to observe, and also the easiest to misread. The price signals from recent reports are not fully consistent, but they are useful when pieced together: eSSD is still rising sharply, overall NAND is still rising, and consumer-side price increases are starting to slow.
Korea Tech’s June memory price tracker and Morgan Stanley’s channel checks point in the same direction: overall NAND is still rising, eSSD is clearly stronger, and mobile and consumer products are starting to lag. The specific increases are clearer in table form.
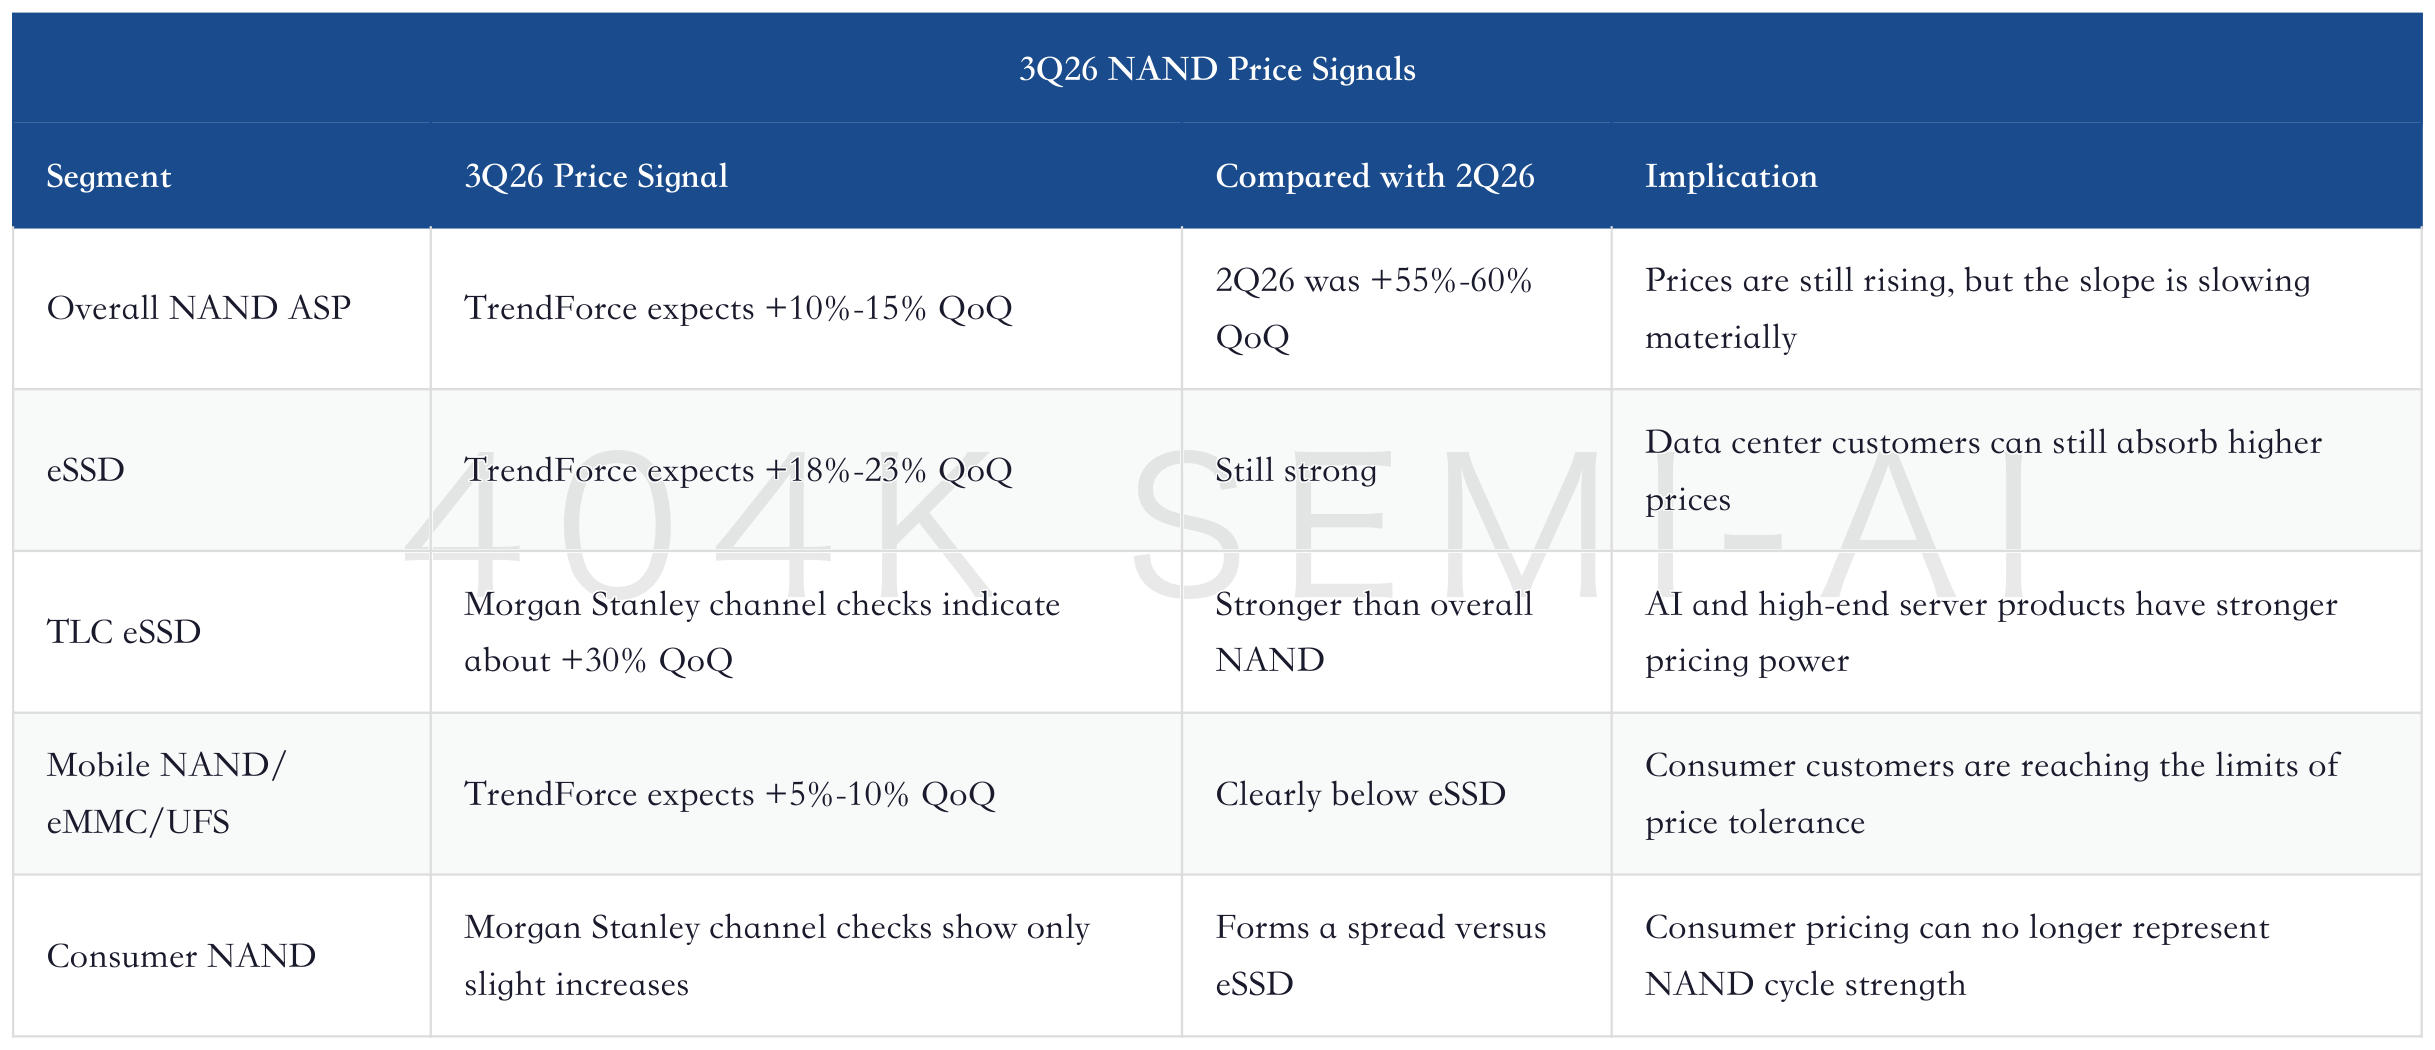
This table has a clear conclusion: NAND is still rising, but the industry has entered a phase of “structural price increases.” Structural price increases are more favorable to original manufacturers and more demanding for channels and module makers.
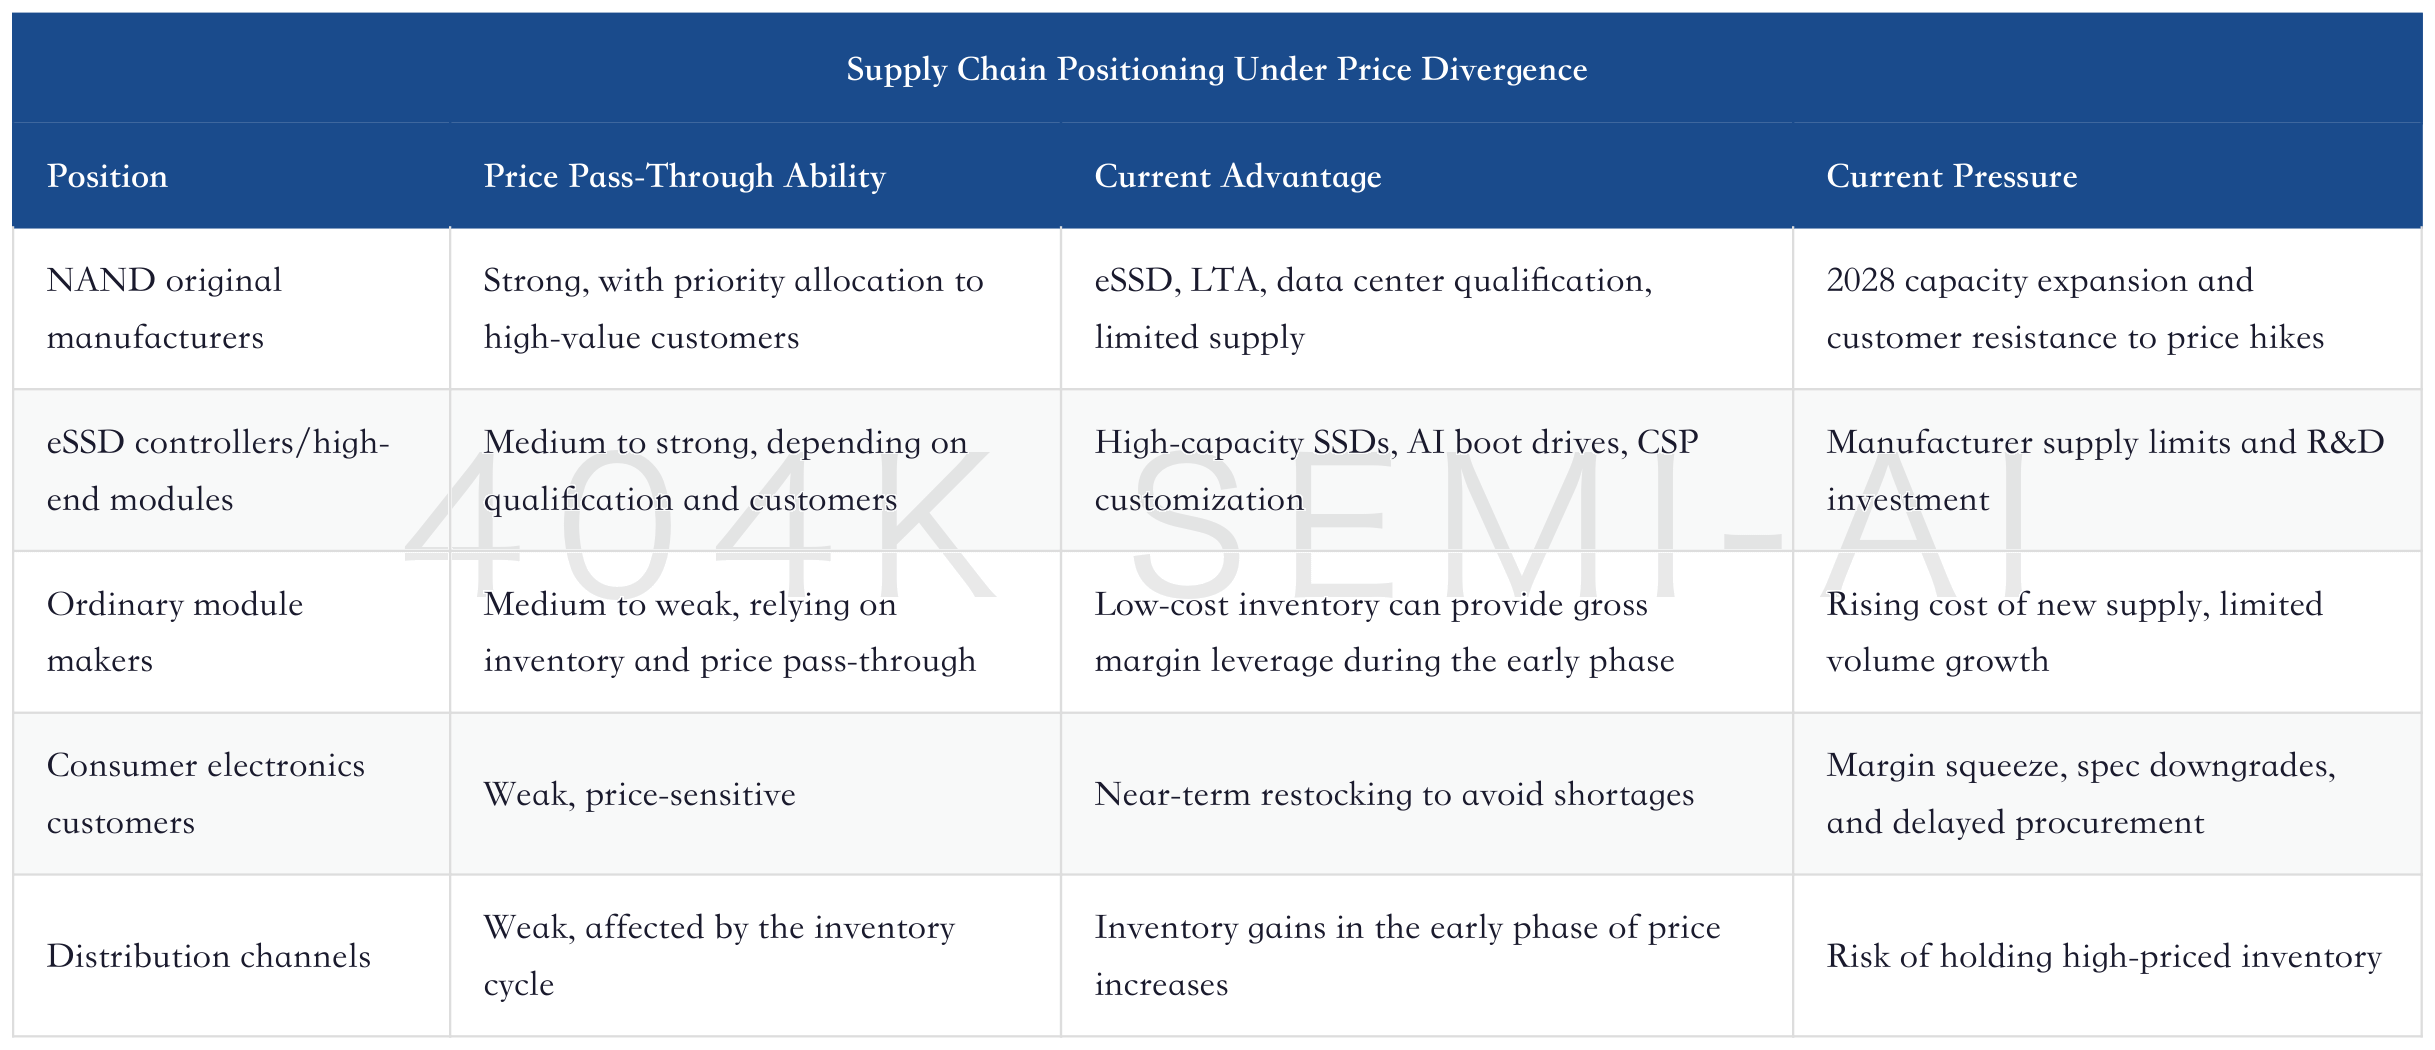
Original manufacturers can prioritize limited supply for cloud customers, enterprise SSDs, high-capacity QLC, low-latency TLC, and other high-value products. Module makers and consumer customers face two pressures: manufacturers are unwilling to provide enough low-priced supply, while end customers are unwilling to accept continued large price increases. The mismatch among inventory, FIFO costs, and price pass-through will amplify profit volatility.
This is also what Morgan Stanley means by “AI vs consumer bifurcation” in its global NAND industry outlook. Servers remain tight, while consumer-side inventory and channel pressure are starting to rise. Higher inventories at module makers and distributors do not necessarily mean end demand has deteriorated, but they do create pressure from holding high-priced inventory. Small and mid-sized customers are deterred by high prices, transaction volume shrinks, and the price-increase ceiling on the consumer side appears earlier.
Memory Tax Keeps Rising: Storage Prices May Post Sharp Sequential Increases for Two Consecutive Quarters in 2H This Year
Therefore, NAND industry price validation cannot rely on a single ASP number. A better validation method is to look at the spread between eSSD and consumer NAND. If eSSD continues to rise while the consumer side slows, original manufacturers’ profits can still hold up, but modules and the consumer chain will diverge. If eSSD also starts to slow, the industry bull case will enter a stress test.
VI. Supply Discipline: Why NAND Has Not Immediately Been Knocked Back by Capacity Expansion
Every memory price increase faces the same question: with prices this high, manufacturers will eventually expand capacity and kill the cycle. This concern is still valid for NAND, but recent reports show that supply return will not be as fast as the price response.
Goldman Sachs’ Kioxia update provides the clearest supply framing. It raised FY3/27-FY3/29 operating profit forecasts by 9%/19%/29%, respectively, and increased its CY26 NAND ASP assumption to 4.5x YoY and CY27 to +38% YoY. One key assumption behind this is that major memory manufacturers are still prioritizing DRAM investment, and supply additions from new NAND fabs may not become more visible until CY28.
Citi’s SanDisk update gives a similar logic. It believes NAND suppliers are shifting cleanroom space from NAND to DRAM, and overall limited cleanroom availability is constraining NAND bit supply growth. Even if industry supply gradually improves in 2028, management has not clearly seen when supply will catch up with demand.
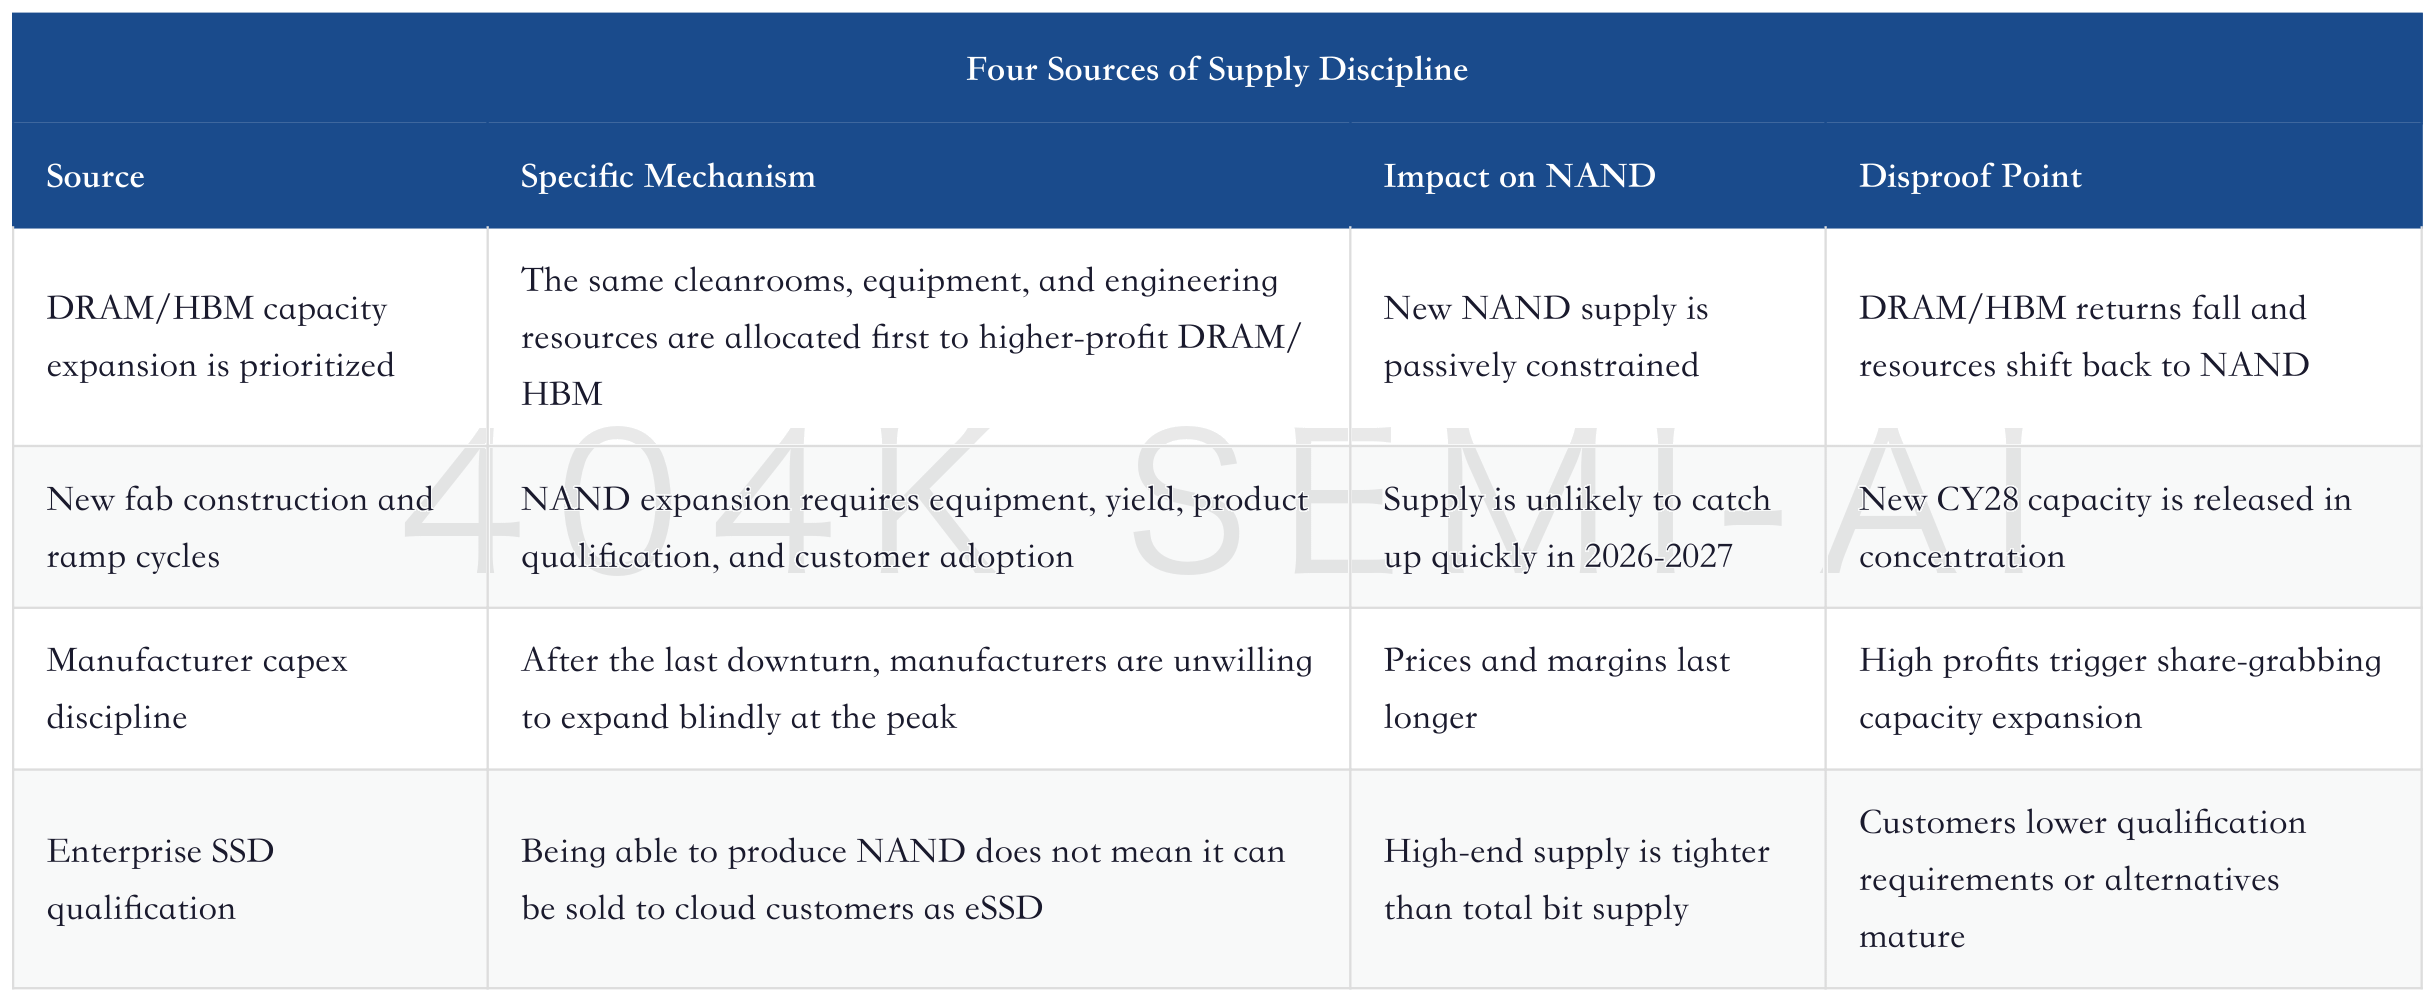
The most important factor here is the crowding-out effect from DRAM/HBM. NAND tightness is not an isolated event; it is linked to the broader AI memory cycle. HBM, DDR5, and server DRAM are all rising. When manufacturers make investment choices, they prioritize products with firmer customers, higher prices, and longer qualification cycles. NAND is gaining supply discipline precisely because it is “not receiving the most capex.”
This is also the paradox for pure NAND assets such as Kioxia and SanDisk. They lack direct DRAM/HBM revenue, but benefit when integrated memory manufacturers allocate resources to DRAM/HBM, thereby suppressing NAND supply growth. As long as pure NAND companies maintain capex discipline, they can achieve very high profit leverage in 2026-2027.
Kioxia Deep-Dive Update: Goldman Sachs Raises Target Price to JPY 116,000; How NAND Tightness Revalues the AI Storage Cycle
Supply discipline should not be mythologized. The historical pattern of the memory industry still exists: high prices attract supply, high profits induce technology migration and new capacity, and customers look for alternatives. The bull case works now because supply response is slower than demand, not because supply will never respond.
Therefore, three supply-side indicators should be tracked.
First, NAND WFE orders. As long as NAND-related equipment orders begin to accelerate materially, the market will discount 2028 supply pressure in advance.
Second, manufacturers’ capex mix. If Samsung, Micron, SK Hynix, Kioxia, SanDisk, and others shift more resources from DRAM/HBM to NAND, supply discipline will weaken.
Third, high-end eSSD qualification capability. If new NAND bits are mainly ordinary products, AI eSSD may still be tight. If new supply directly enters cloud customers’ high-capacity SSDs, pricing pressure will transmit more quickly.
VII. 2028 Scenario Test: New Capacity Is the Biggest Variable in This Cycle
2028 is the year neither NAND bulls nor bears can avoid. Morgan Stanley’s scenario test frames the issue clearly: AI SSD demand growth and new NAND capacity together determine the direction of supply and demand.
Morgan Stanley assumes non-AI NAND demand grows 5% YoY in 2028, other suppliers expand capacity in line with forecasts from its U.S. semiconductor team, and AI SSD demand growth ranges from 30% to 60%. It also places Yangtze Memory Technologies’ 2028 capacity in a range of 310-470kwpm. The results show that the higher AI SSD demand is and the more disciplined capacity additions are, the tighter supply-demand becomes; if AI SSD demand slows and capacity accelerates, supply-demand is more likely to swing into oversupply.
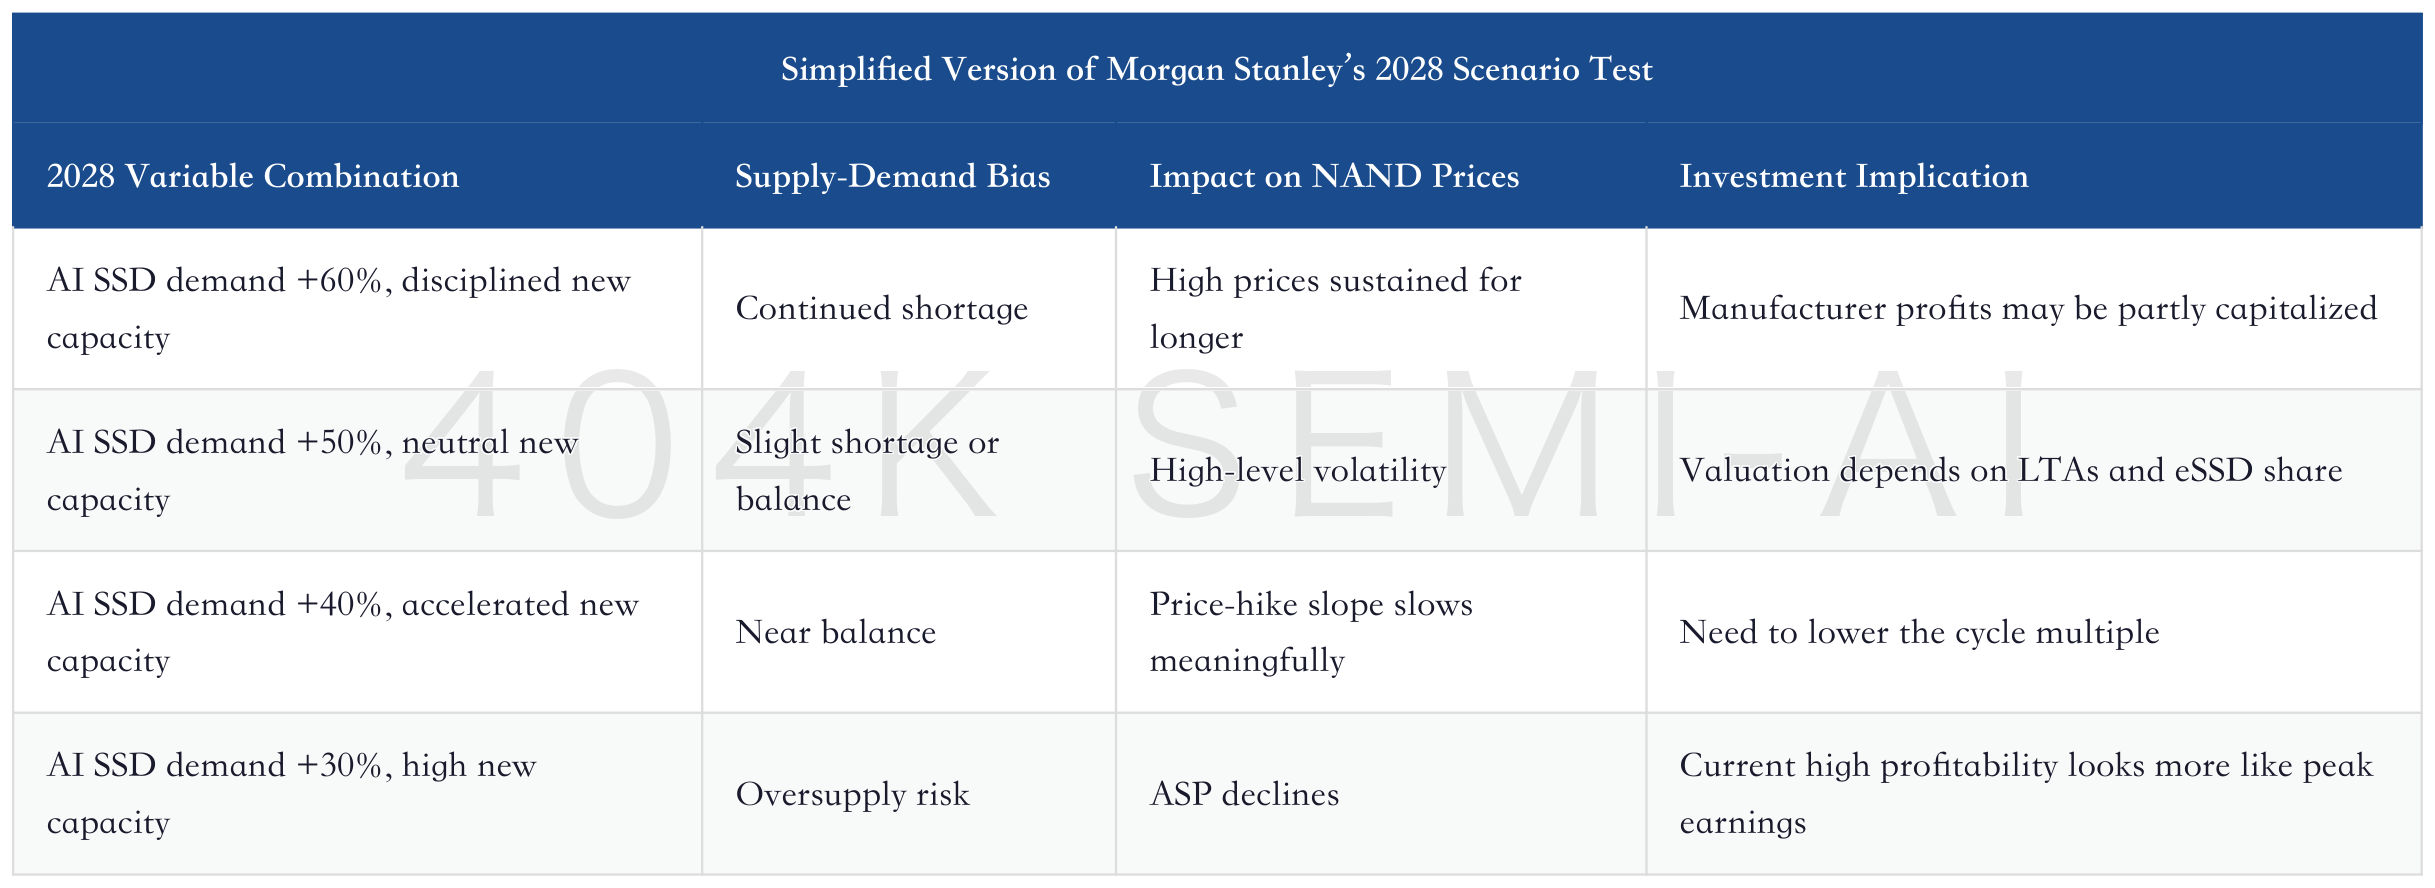
The most valuable part of this test is that it does not reduce 2028 to a single conclusion. NAND in 2028 could remain tight, or it could shift into oversupply. The difference is not about belief, but two hard variables: AI SSD demand and new capacity.
On the demand side, the key is whether AI applications continue to absorb more storage. RAG, vector databases, long context, agentic AI, training data lakes, inference logs, video, and multimodal data will all drive NAND demand. If these applications remain concepts and do not convert into large-scale procurement, the 2028 demand slope will fall.
On the supply side, the key is whether new capacity comes online at the same time. Morgan Stanley specifically notes that Chinese NAND suppliers are building multiple fabs; if all of them are used for NAND, their long-term share could rise significantly. This variable does not necessarily mean oversupply, but it does mean NAND supply elasticity after 2028 will be greater than in 2026-2027.
There is also an underappreciated upside variable in 2028: Super High IOPS SSDs. Morgan Stanley notes that its 2028 model does not include the potential wafer consumption of ultra-high-IOPS SSDs for AI inference. If these products enter volume production in 2028, they may consume roughly 3x the capacity of ordinary SSDs, further tightening industry supply. In other words, 2028 is not simply a story of supply returning; new products may once again absorb supply.
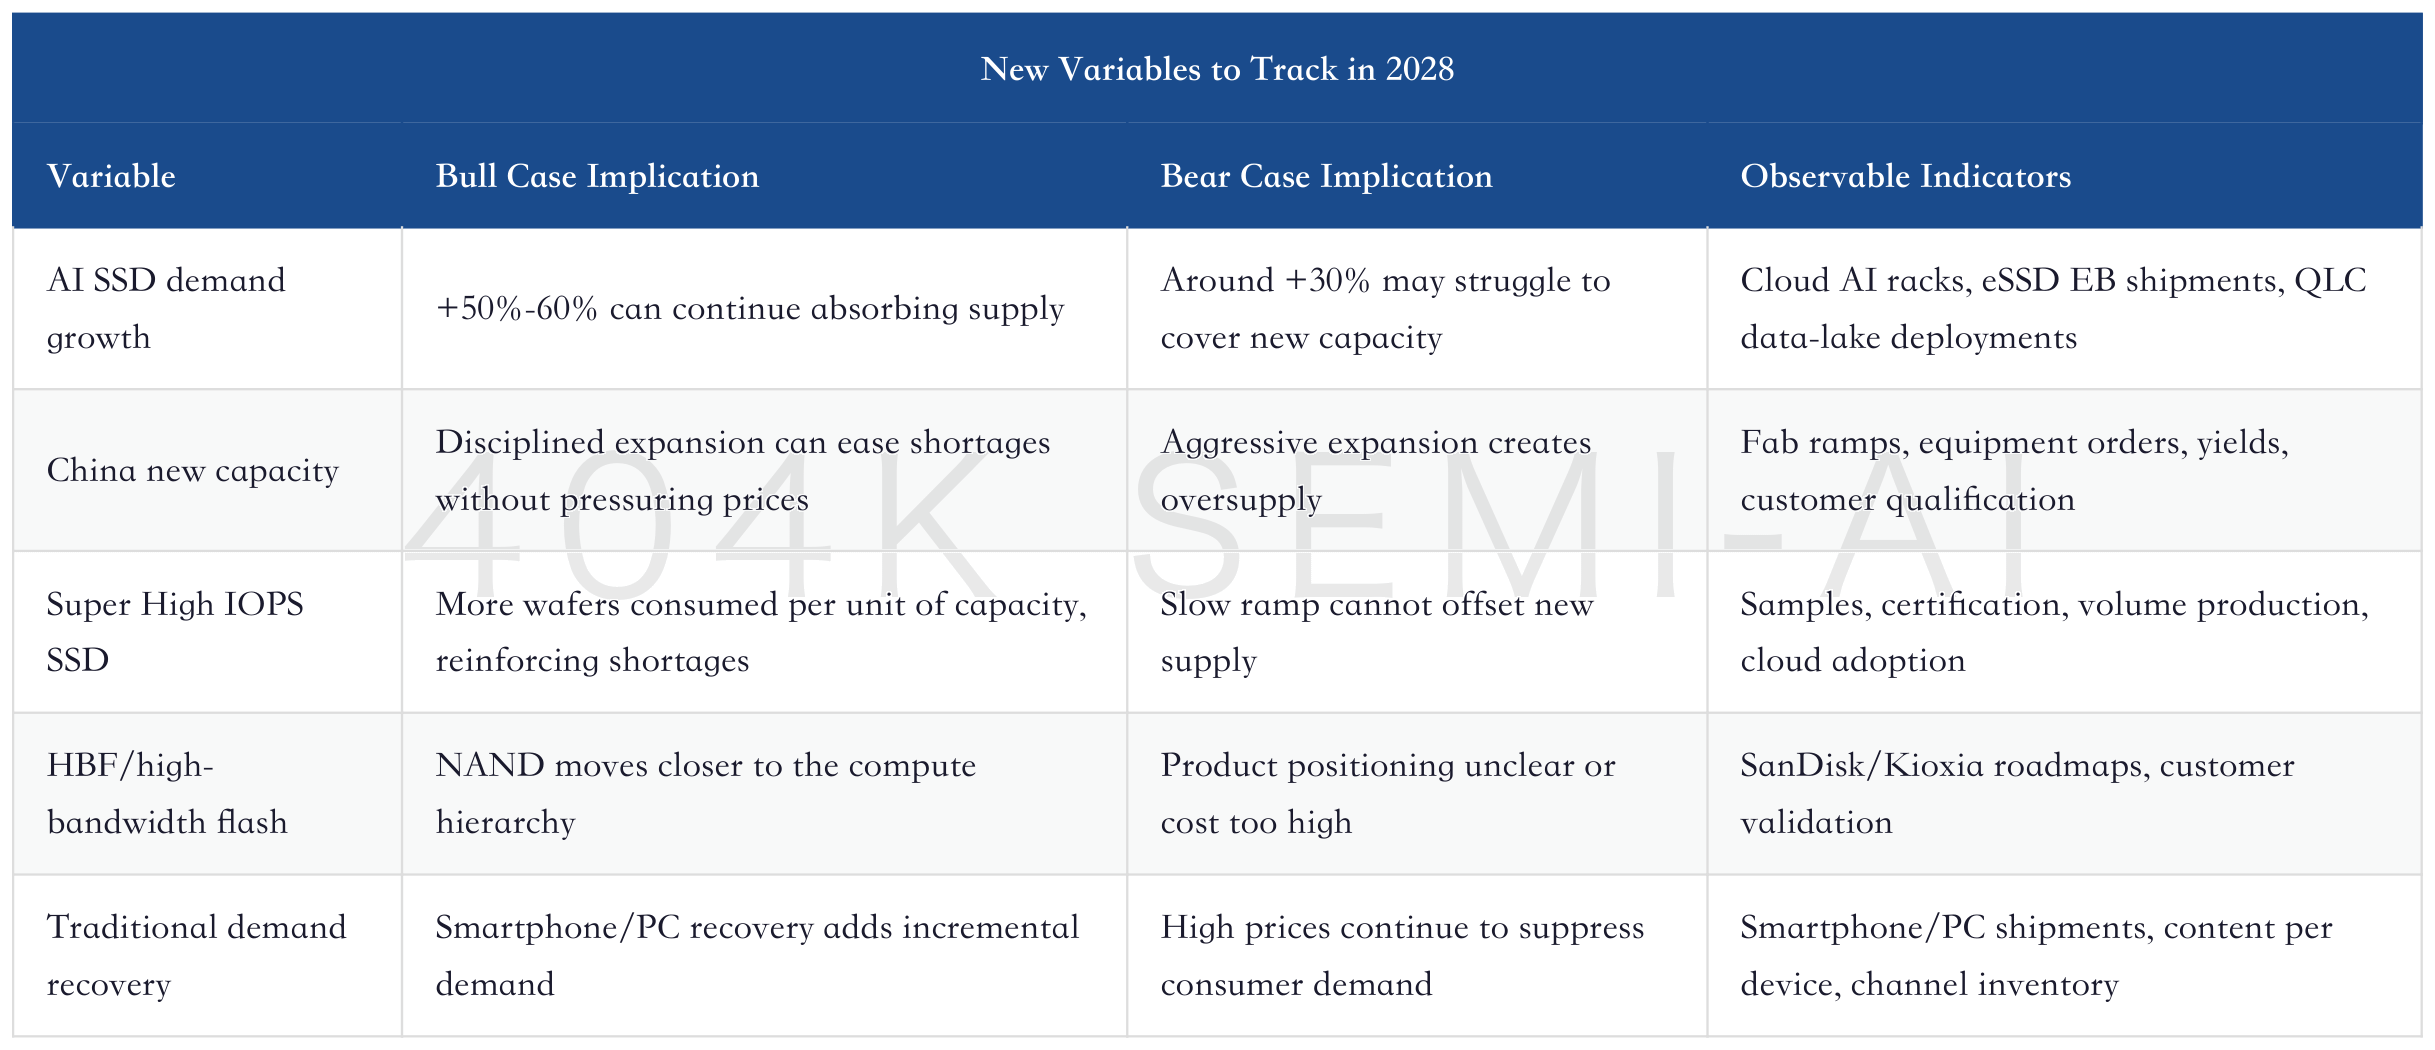
The investment implication for 2028 is straightforward. Looking only at 2026-2027, NAND manufacturer profits should remain very strong. Extending the horizon to 2028, valuation cannot rely only on peak EPS; it must be judged by how long high profits can last, where the trough sits on the way down, and how much can be locked in through long-term agreements.
VIII. NBM and LTA: Can Cyclical Profit Become a Cash-Flow Asset?
Whether NAND stocks can continue to rerate ultimately depends on whether profit can move from spot price increases to visible cash flow. The key terms here are NBM and LTA.
Morgan Stanley’s SanDisk podcast places NBM in a prominent position: fixed prices, cap-and-floor structures, and decommit penalties. In investment-research terms, this means customers are not only committing to procurement, but also accepting price bands and exit costs. Only this type of contract can potentially capitalize part of peak profits.
But long-term agreements are harder in NAND than in DRAM. Morgan Stanley’s channel checks note that customers are more willing to pay for DRAM to secure supply, while NAND price increases face more pushback. The reason is simple: DRAM is closer to server and GPU performance bottlenecks, so shortages have a more direct system-level impact. NAND is also important, but consumer customers and some enterprise customers are more price sensitive.
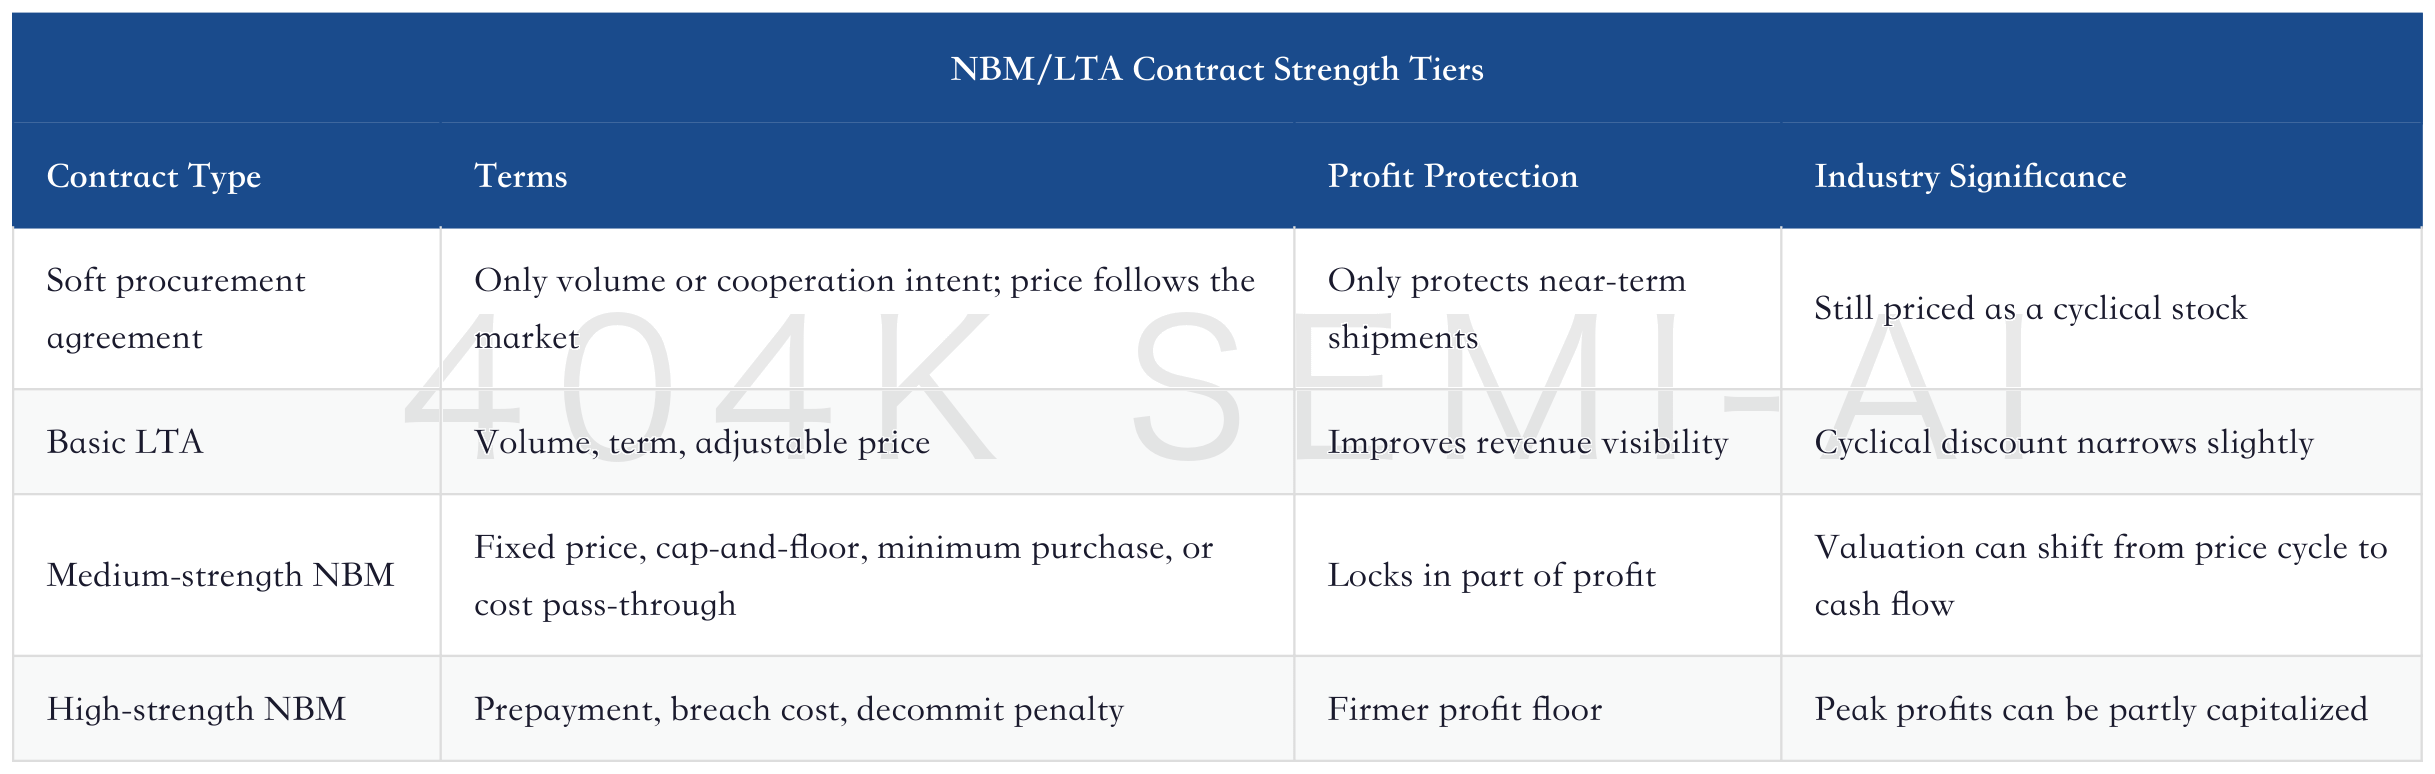
Kioxia and SanDisk are also following different paths. Goldman Sachs says Kioxia prioritizes price and margins and will not sacrifice too much upside to sign LTAs. This choice is favorable in the short term, because the company can capture price increases. Over the long term, the question is whether there is enough downside protection when the cycle turns. SanDisk, by contrast, emphasizes NBM and data-center customer binding, which is why the market is willing to assign it a higher multiple.
SanDisk Deep-Dive Update: Citi Raises Target Price to $2,500, NAND Tightness Cycle Extends Beyond CY27
NBM and LTAs are not cure-alls. Customers will demand renegotiation when prices fall, and cloud customers will also use multi-supplier strategies to reduce the bargaining power of any single manufacturer. If a contract lacks a clear floor price, breach cost, or exit penalty, it is more like supply assurance than profit assurance.
Four things matter when judging the quality of NBM/LTAs.
First, coverage. The higher the coverage, the stronger revenue visibility, though excessive coverage can also sacrifice upside flexibility.
Second, pricing terms. Fixed prices, price bands, cost pass-through, and limits on price increases or declines matter far more than the words “long-term cooperation.”
Third, customer type. LTAs with hyperscalers, server OEMs, and AI infrastructure customers are higher quality than those with ordinary consumer channels.
Fourth, exit cost. LTAs without decommit penalties provide limited protection when prices decline.
Therefore, NBM/LTAs are the first gate for NAND valuation. If NAND manufacturers pass this gate, they can shift from price-hike stocks to partial cash-flow assets. If they do not, high profits remain cyclical peak earnings.
IX. Company and Segment Ranking: Prioritize Manufacturers, Module Makers Diverge, Controllers Depend on Certification
NAND opportunities can no longer be ranked simply by “who has NAND exposure.” The real ranking depends on three dimensions: control of original supply, entry into enterprise/data-center SSD customers, and sufficiently strong contracts and certifications.
Manufacturers are the most direct beneficiaries. Kioxia and SanDisk are the purest NAND elasticity plays. Micron, Samsung, and SK Hynix are full-category memory assets, with NAND providing additional upside beyond HBM/DRAM. The common advantage of manufacturers is control over supply allocation and pricing, allowing them to prioritize shipments to eSSD, cloud customers, and LTA customers.
Module makers and the consumer chain will diverge. Early low-cost inventory will create profit elasticity, but as new high-cost supply enters, consumer price ceilings emerge, and manufacturers prioritize supply to CSPs, ordinary module makers will face pressure on both volume growth and gross margins. They can benefit from price increases, but it is harder for them to convert price increases into durable profit.
Controllers and high-end modules depend on certification. If companies such as Silicon Motion and Phison can enter AI boot drives, enterprise SSD controllers, and CSP-customized solutions, they are no longer ordinary consumer-controller stories. If they remain mainly in consumer and channel markets, NAND price increases may instead compress customer demand.
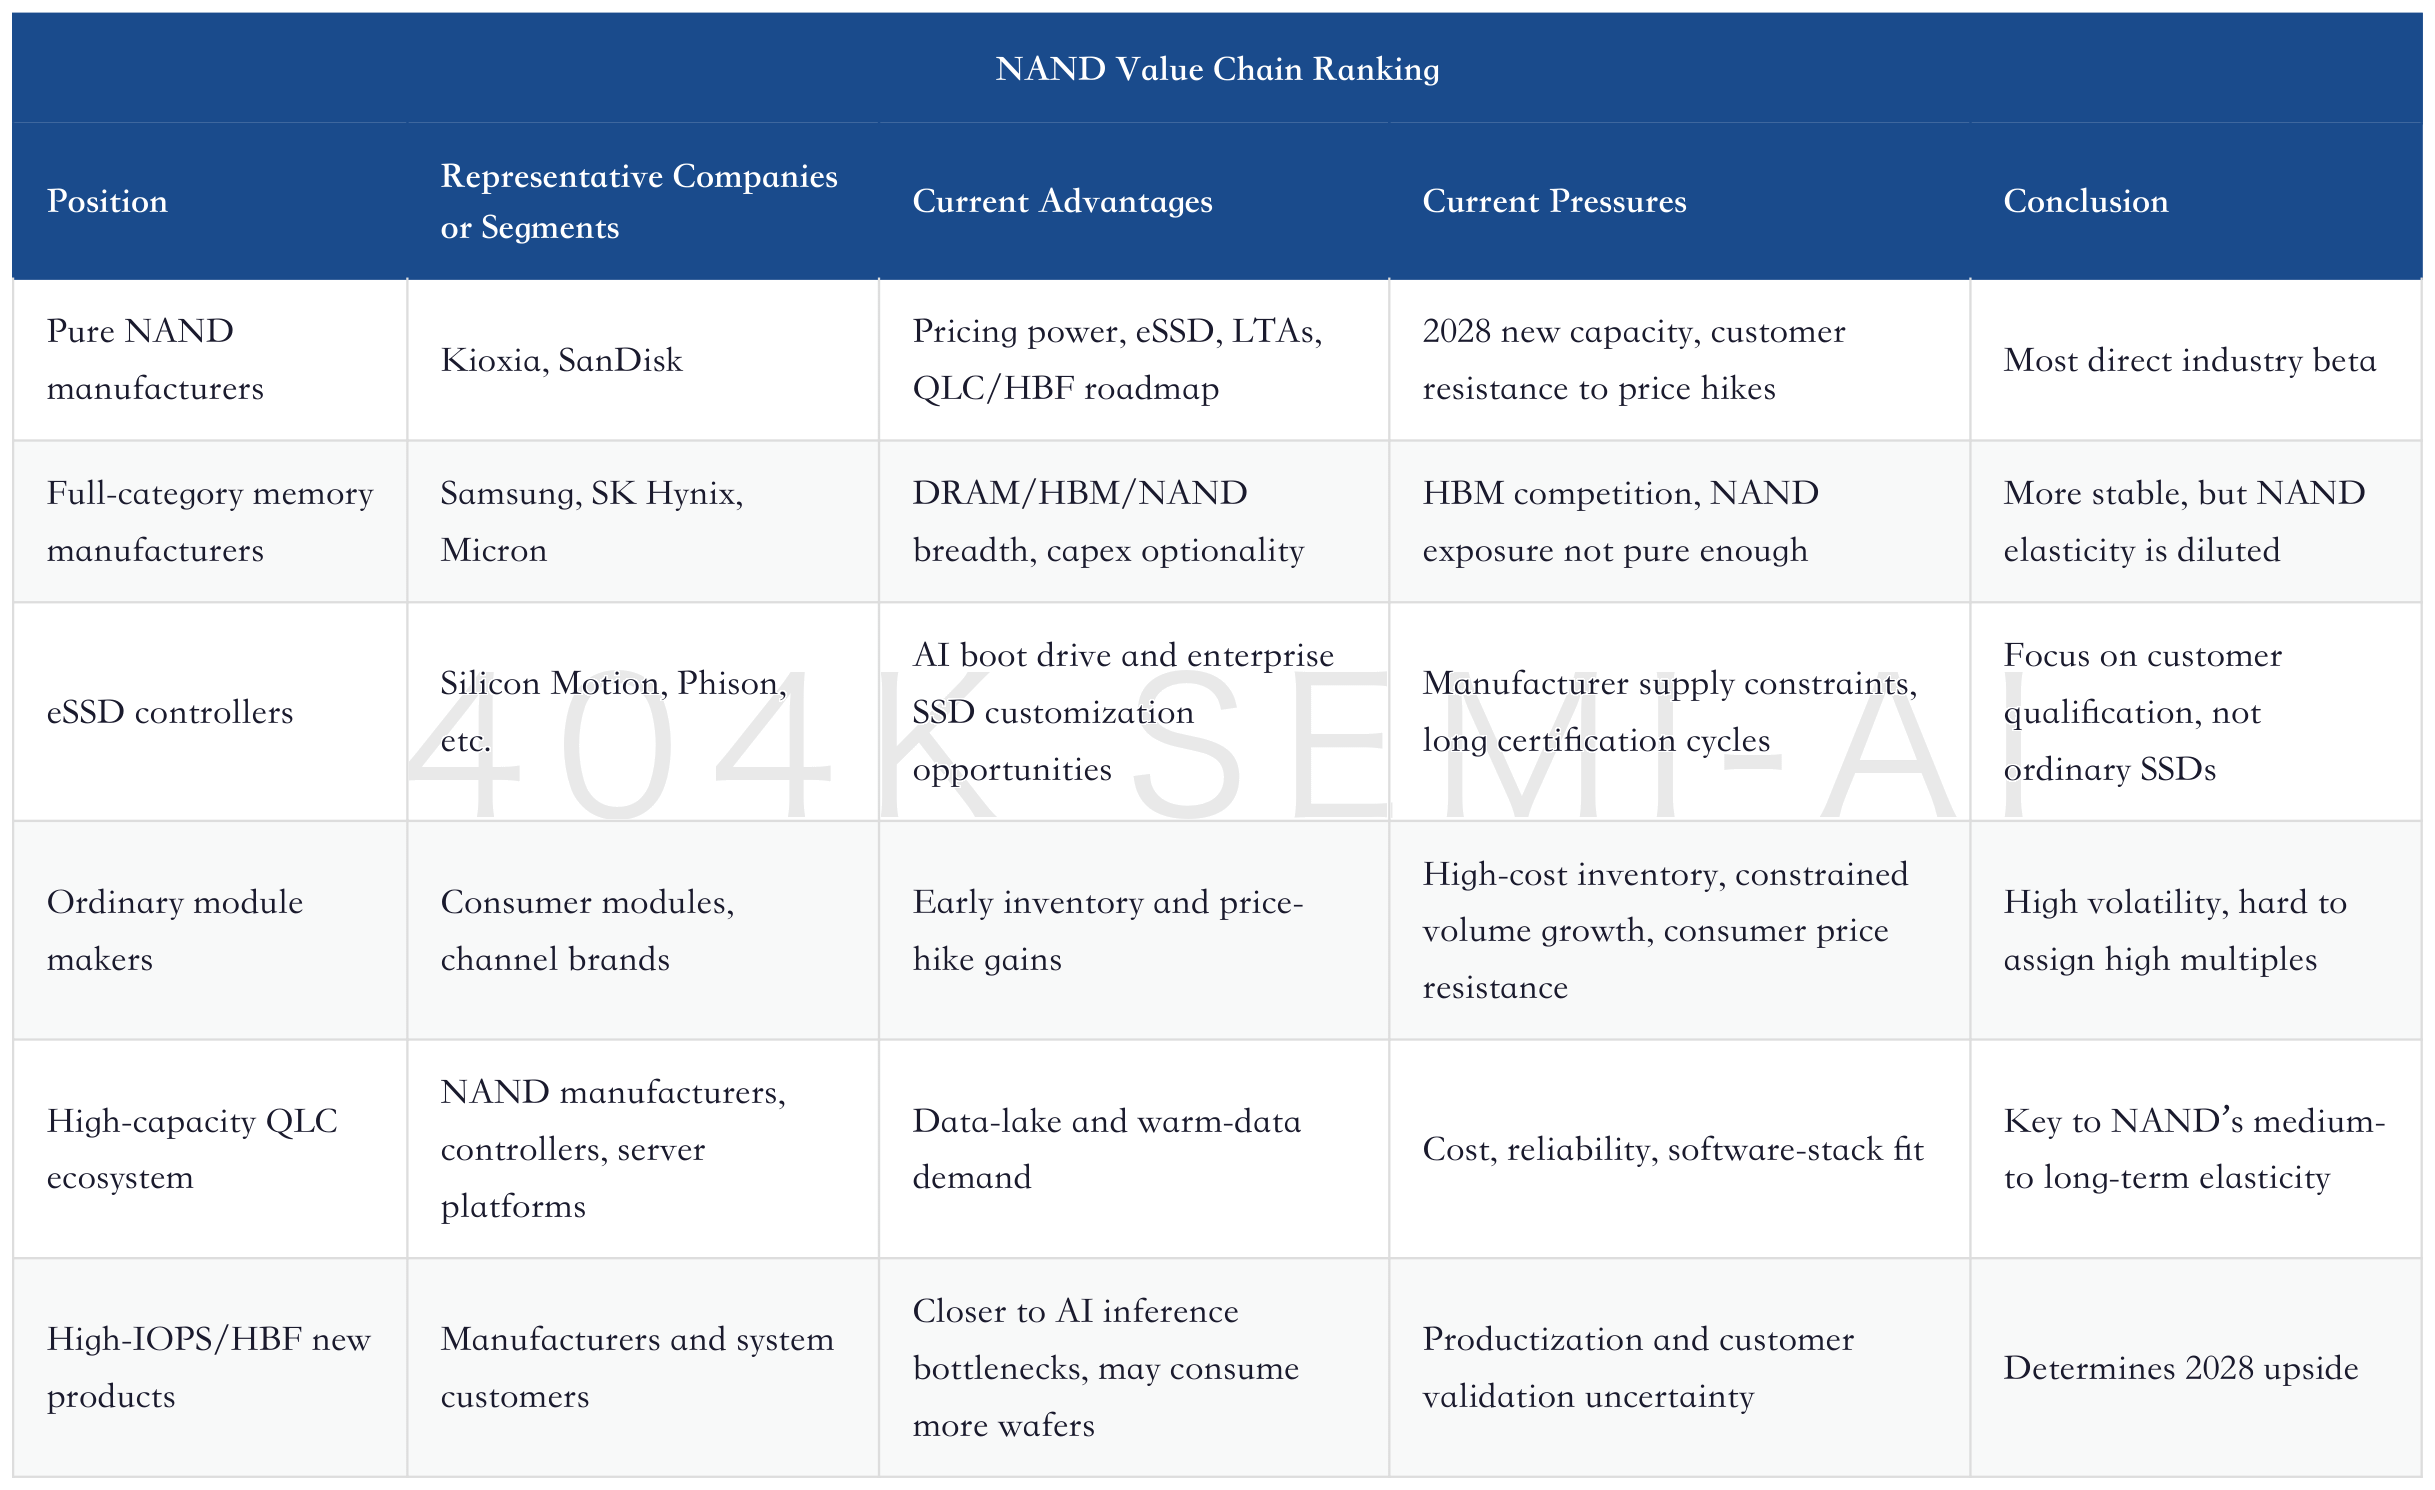
This ranking also explains why NAND industry reports should be separated from single-company reports. A single company may have near-term elasticity due to target prices, share prices, and earnings models. At the industry level, the key is to judge where value-chain profits are flowing. For now, profits are flowing first to manufacturers and the high-end eSSD chain, while ordinary modules and the consumer chain are more likely to come under pressure.
SanDisk Deep-Dive Update: Jefferies’ $3,000 Target Price, eSSD Share Recovery, and How NAND LTAs Rerate Profit Durability
Valuation should also be differentiated according to this table. Manufacturers should be assessed on 2027-2028 profit durability, controllers on certification and customer share, and module makers on inventory, gross margin, and cash flow. Calling all of them “beneficiaries of NAND price increases” would misread the risks.
10. Three Worldviews: Shortage Extension, Structural Balance, Supply Return
There are now three worldviews for NAND, each of which can explain part of the data.
The bullish worldview is “shortage extension.” AI SSD demand continues to grow rapidly, CSPs put more capacity into racks, data lakes, and context memory, suppliers continue to prioritize capex for DRAM/HBM, and incremental NAND supply grows more slowly than demand. In this world, shortages persist in 2027, and even if supply recovers in 2028, it is hard to push margins back to historically low levels. Pure-play NAND suppliers such as Kioxia and SanDisk enjoy the highest operating leverage.
The neutral worldview is “structural balance.” eSSD remains strong, the consumer side weakens, and the overall slope of NAND price increases declines. Suppliers still make money, but earnings are no longer revised up linearly; companies with strong long-term agreements and eSSD share defend high profitability, while standard modules and consumer chains are squeezed first. In this world, the industry still has opportunities, but not all NAND exposure should be bought.
The bearish worldview is “supply return.” New capacity is released in a concentrated way in 2028, AI SSD demand growth slows, consumer-side price resistance expands to enterprise customers, and bit supply from accelerated NAND WFE exceeds demand. In this world, 2026-2027 profits will be reclassified by the market as peak earnings, and low P/E again becomes a cyclical trap.
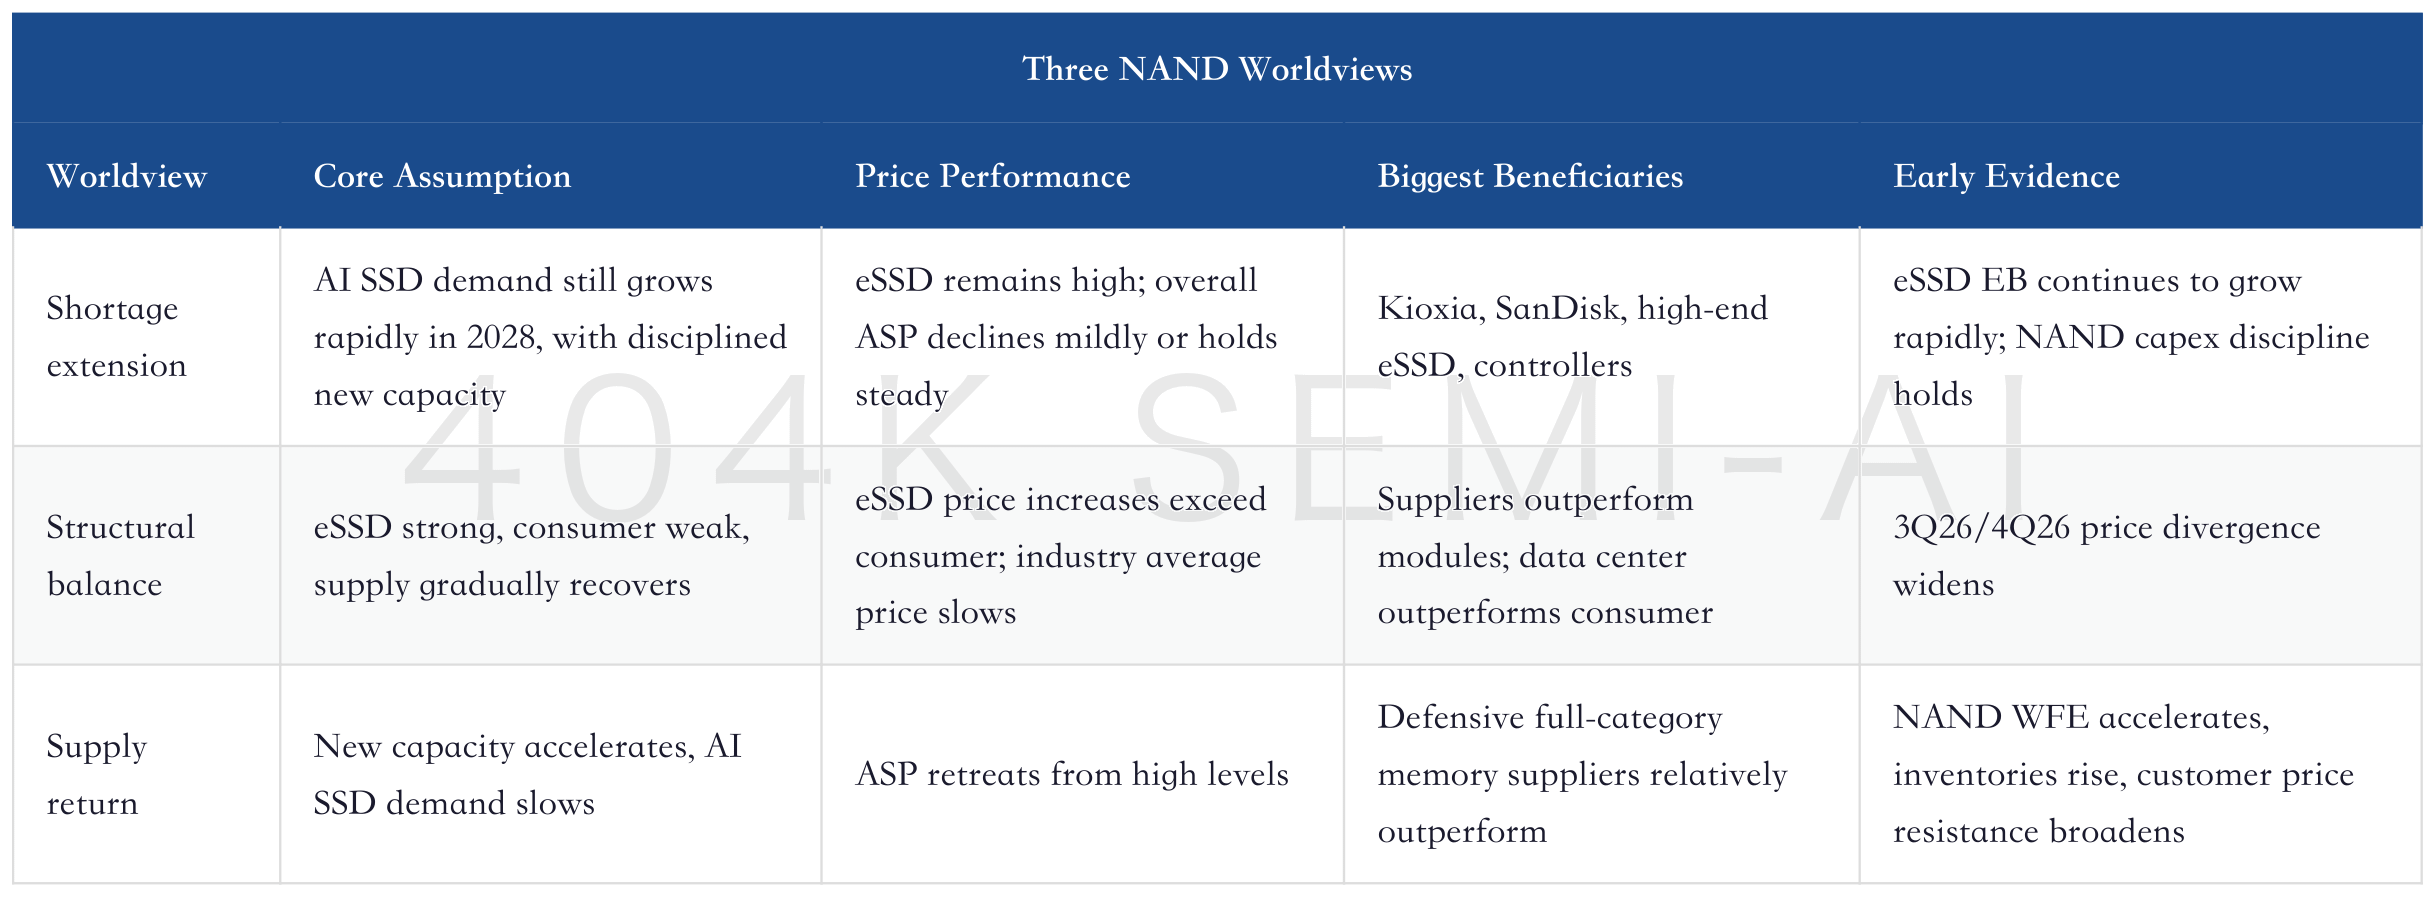
Current evidence is closer to somewhere between “shortage extension” and “structural balance.” eSSD is very strong, supply discipline remains in place, and the 2027 gap is still visible; but the consumer side already has a price ceiling, module and distribution inventories are rising, and customer acceptance of NAND price increases is weaker than for DRAM. In one sentence: the bullish case has not been falsified, but NAND can no longer be bought as an indiscriminate price-hike trade.
Market pricing will next shift from “price increases” to “profit quality.” Within the same NAND upcycle, eSSD long-term agreements, NBM, high-capacity QLC, and high-IOPS SSD will generate higher-quality profits; consumer NAND, channel inventory, and standard modules will have shorter profit windows.
11. Tracking Indicators: The Next Four Numbers Matter Most
The NAND industry does not lack narratives; it lacks validation. The four most important sets of numbers to watch are as follows.
First, enterprise/data-center SSD capacity shipments. JPM’s May figure of 41.4 EB, up 139% year over year, is hard evidence. If this growth rate continues to exceed standard SSD growth, AI NAND demand is still intact; if capacity growth clearly falls back, the core data support for the bullish case will be shaken.
Second, ASP divergence in 3Q26 and 4Q26. eSSD price increases, TLC eSSD price increases, mobile NAND price increases, and consumer NAND price increases need to be viewed separately. As long as eSSD remains high and the consumer side slows, supplier profits may still hold; if eSSD also decelerates, industry earnings revisions will stop.
Third, NAND WFE and capex structure. DRAM/HBM investment priority is the key to supply discipline. If NAND WFE begins to accelerate persistently, or if major memory suppliers clearly shift capex back to NAND, the market will discount 2028 supply pressure in advance.
Fourth, long-term agreements and NBM terms. It is not enough to say long-term agreements have been signed; the floor price, ceilings and floors, default costs, customer type, and coverage ratio matter. The harder the contracts, the more profits can be capitalized; the softer the contracts, the more high profitability looks like a cyclical peak.
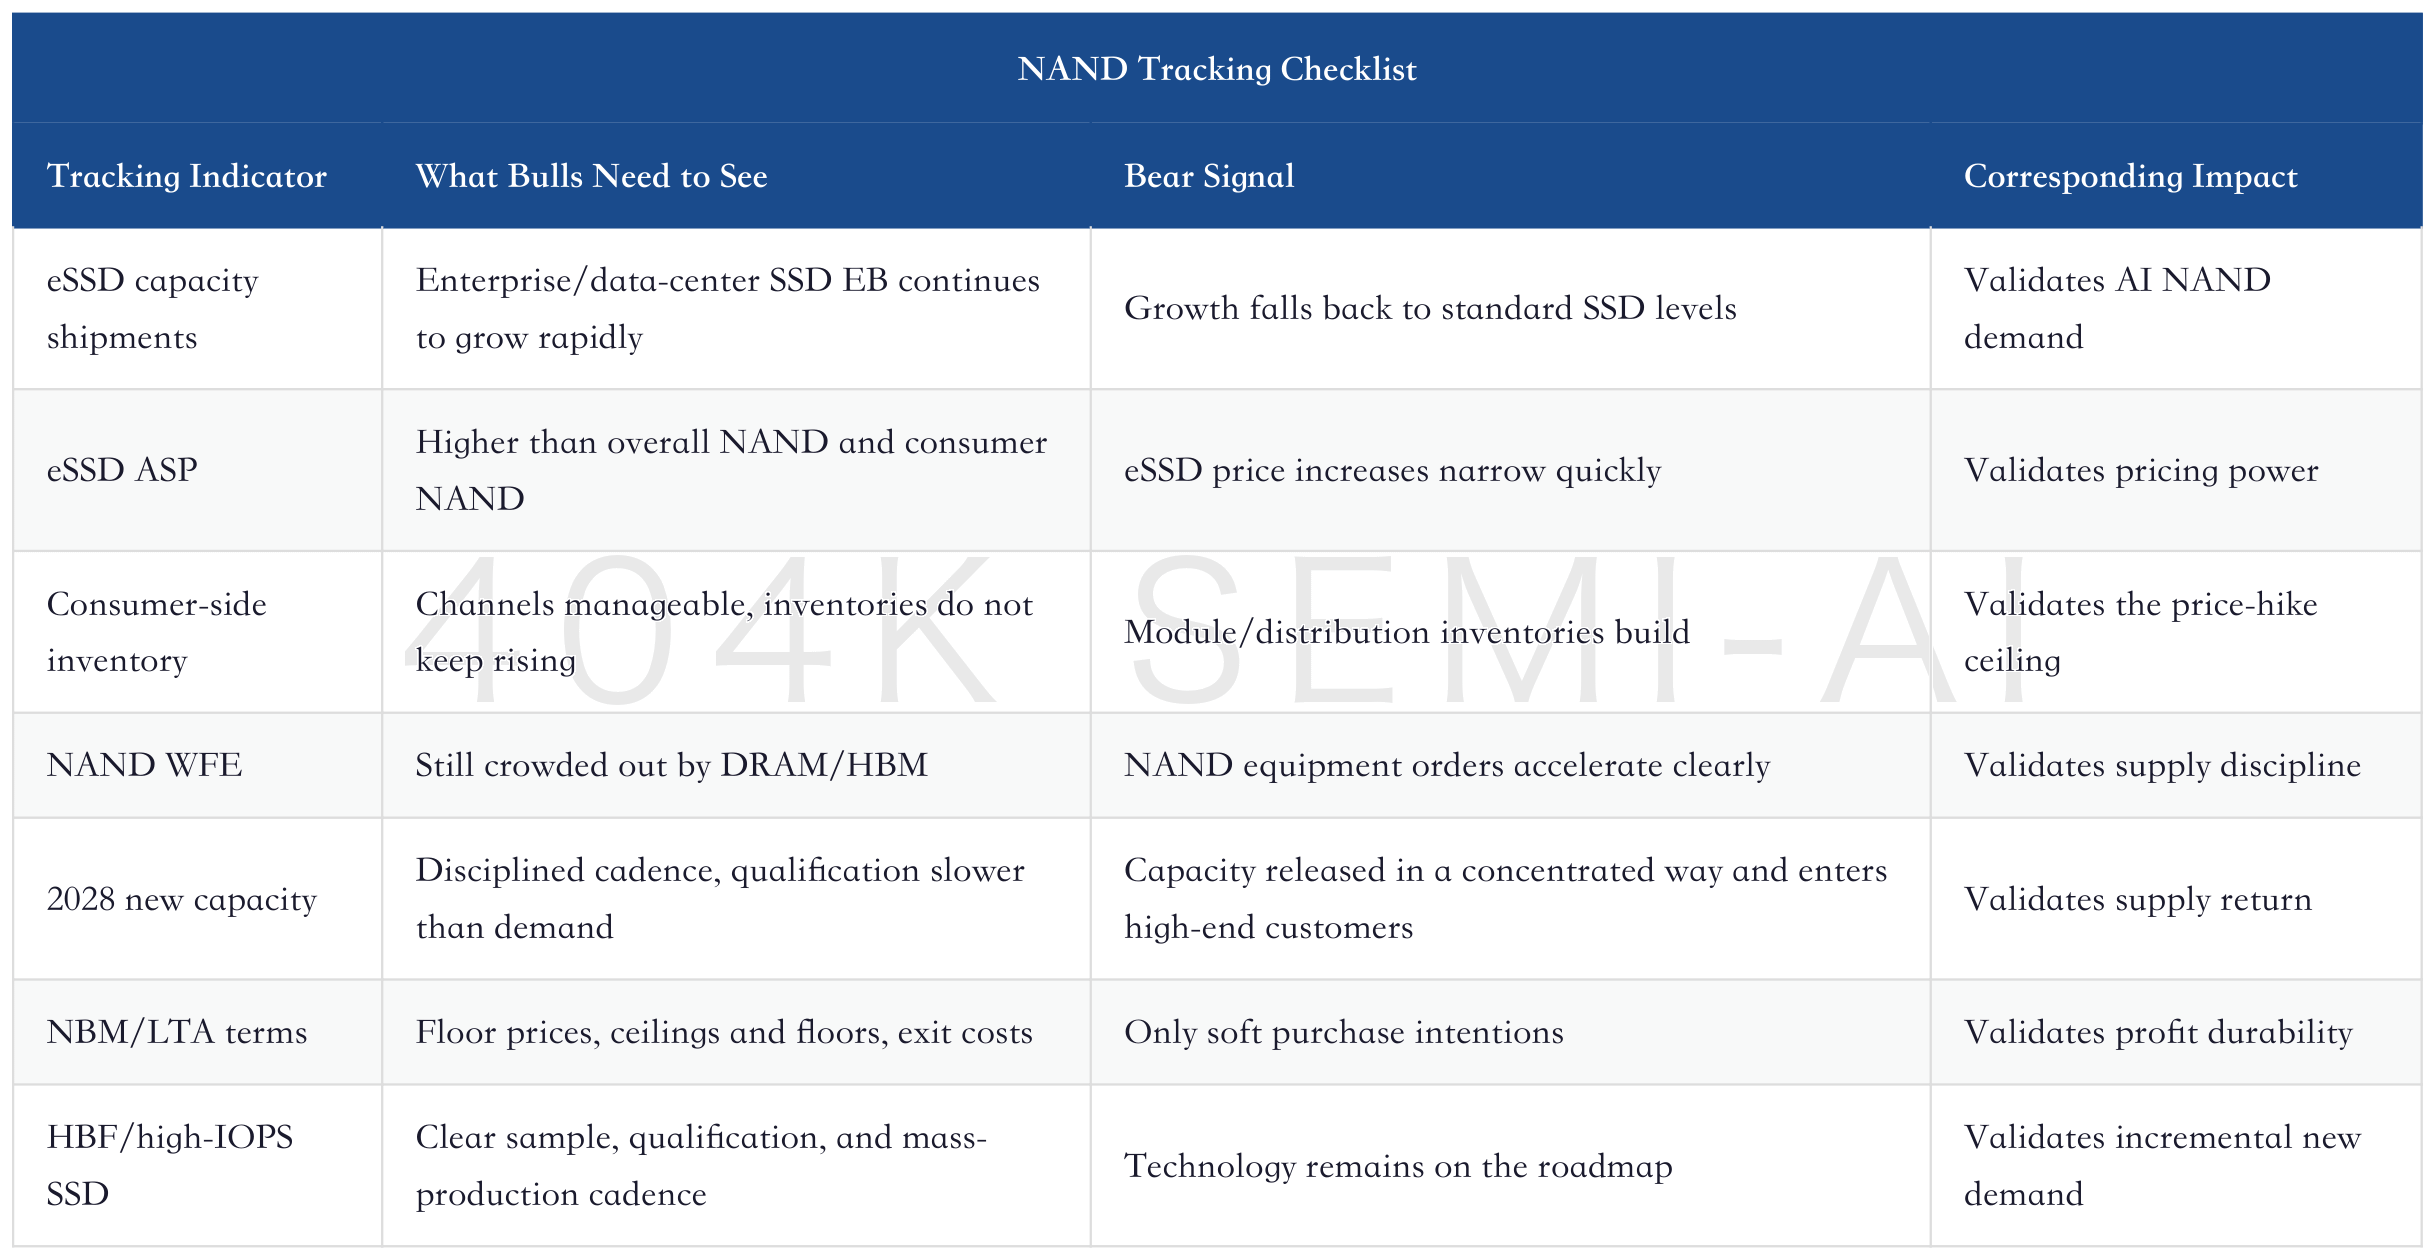
These indicators are more useful than a single month of share-price moves or one target-price change. The NAND industry is now in a “data validation phase,” and the market will continuously recalibrate valuations using prices, shipments, inventories, capex, and contract terms.
12. Conclusion: NAND Is Not Over, but Entry Points Are Now More Selective
The NAND trade is not over. AI eSSD demand is strong enough, the 2027 supply-demand gap remains visible, supplier supply discipline is still intact, and DRAM/HBM-prioritized expansion has created additional constraints for NAND. Evidence from Goldman Sachs, Citi, Morgan Stanley, JPM, and Korean price tracking corroborates one another: data-center NAND remains strong, and enterprise SSD is the core variable in this memory cycle.
But the NAND trade can no longer be crudely understood as “industry-wide price increases.” Price ceilings are starting to appear on the consumer side, mobile NAND price increases are lower than eSSD, module and distribution inventory pressure is rising, and customer acceptance of NAND price increases is weaker than for DRAM. The industry bull case remains intact, but profits will concentrate in suppliers, high-end eSSD, long-term agreements, and high-capacity products.
This is the most important current investment judgment: NAND is moving from a price trade to a profit-quality trade.
A price trade asks who can raise prices the fastest; a profit-quality trade asks who can defend those profits the longest. For Kioxia and SanDisk, the key variables are eSSD, BiCS/QLC, NBM/LTA, and capex discipline; for Samsung, Micron, and SK Hynix, the key variables are full-category breadth and DRAM/HBM priority; for controller and module companies, the key variables are customer qualification, supply access, and gross-margin pressure. The operating leverage of ordinary consumer chains will become increasingly short-lived.
2028 is the final stress test. If AI SSD demand continues to grow rapidly, and new demand such as Super High IOPS SSD, HBF, and QLC data lakes consumes more wafers, NAND profits can receive higher capitalization; if new capacity accelerates, the consumer side continues to resist price increases, and eSSD growth slows, high profitability will return to a traditional cyclical peak.
The task now is not to ask whether NAND prices will keep rising, but to ask four more specific questions: how much longer eSSD can rise, how long supply discipline can hold, how much profit long-term agreements can lock in, and whether 2028 new capacity will arrive early. The answers to these four questions will determine whether the NAND industry continues to be re-rated or retreats from a supercycle back to an ordinary cycle.NAND Industry Deep-Dive Update: Triple Validation of AI eSSD Shortages, Supply Discipline, and 2028 New Capacity
目录
Too Long; Didn’t Read
1. What This NAND Update Needs to Answer
2. What the Recent Reports Actually Added
3. Morgan Stanley Supply-Demand Model: AI NAND Moves from Incremental Demand to the Main Variable
IV. eSSD Is Hard Evidence: May Capacity Shipments +139% YoY
V. 3Q26 Price Divergence: eSSD Still Strong, Consumer Starting to Buckle
VI. Supply Discipline: Why NAND Has Not Immediately Been Knocked Back by Capacity Expansion
VII. 2028 Scenario Test: New Capacity Is the Biggest Variable in This Cycle
VIII. NBM and LTA: Can Cyclical Profit Become a Cash-Flow Asset?
IX. Company and Segment Ranking: Prioritize Manufacturers, Module Makers Diverge, Controllers Depend on Certification
10. Three Worldviews: Shortage Extension, Structural Balance, Supply Return
11. Tracking Indicators: The Next Four Numbers Matter Most
12. Conclusion: NAND Is Not Over, but Entry Points Are Now More Selective
本内容基于公开资料和研报数据整理,不构成任何投资建议,不代表任何个人观点,仅供学习参考,请理性阅读
The NAND cycle has moved from reviewing price increases to validating supply discipline: AI eSSD is still creating shortages, the consumer side is starting to hit a pricing ceiling, manufacturers are prioritizing DRAM/HBM ahead of NAND expansion, and new capacity in 2028 will determine whether this profit cycle is a cash-flow re-rating or a cyclical peak.
Too Long; Didn’t Read
The NAND trade has entered its second stage. The first stage bought into the price surge; the second stage depends on whether AI eSSD can continue absorbing supply, whether manufacturers can maintain capex discipline, and whether new capacity in 2028 pushes scarcity back into oversupply. The common shift across several reports over the past seven days is that the debate has moved from “will prices rise in 2Q26” to “can the shortage persist in 2027, and will it reverse in 2028.”
AI eSSD is the main axis of this NAND shortage. Morgan Stanley estimates AI-related NAND demand will rise from 205EB in 2025 to 609EB in 2027, lifting its share of total NAND demand from 18% to 41%; JPM’s May data also show enterprise/data center SSD capacity shipments up 139% YoY, far stronger than ordinary SSD unit shipments. NAND is no longer driven only by smartphones, PCs, and consumer SSDs. The data center capacity layer is rewriting the demand structure.
Pricing is clearly diverging. The strongest category in 3Q26 remains eSSD, while price increases for consumer-grade and mobile NAND are starting to lag. Morgan Stanley’s channel checks show TLC eSSD still rising about 30% QoQ, while consumer-grade products are only up slightly. This divergence matters: the industry remains tight, but price increases can no longer be passed through indiscriminately to all customers.
Supply discipline remains the core bull case. Goldman Sachs raised its Kioxia target price to JPY116,000, citing CY26 NAND ASP up 4.5x YoY, CY27 up 38% YoY, and major memory vendors prioritizing DRAM/HBM investment, with new NAND fab supply additions likely to become more visible only in CY28. Citi also raised its SanDisk target price to USD2,500, emphasizing that NAND tightness could persist beyond CY27 and, in some scenarios, into CY28.
2028 is the largest window for disconfirmation. Morgan Stanley’s 2028 scenario analysis puts the key variable on new NAND capacity, especially new Chinese capacity and AI SSD demand growth. If AI SSD demand can still grow 50%-60% YoY in 2028, supply could remain tight; if demand grows only 30% and new capacity accelerates, supply-demand could shift into oversupply. For the bull case to win through 2028, both demand and discipline must be right.
Investment ranking needs to shift from “who benefits from price hikes” to “who can defend profits.” Pure-play NAND manufacturers and companies with long-term agreements, eSSD qualifications, and QLC/high-IOPS products are more likely to convert price increases into durable profits; ordinary module makers and consumer-channel players are more likely to be squeezed by inventory, FIFO costs, and customer resistance to price hikes. Track four numbers next: eSSD capacity shipments, 3Q26/4Q26 ASP divergence, manufacturers’ NAND capex, and the cadence of new capacity in 2028.
1. What This NAND Update Needs to Answer
The most important question for NAND is no longer “have prices risen.” Prices have already risen, by enough that the market has already reflected one round of this in the share prices of SanDisk, Kioxia, Micron, Samsung, SK Hynix, A-share module companies, and controller companies. The question now is whether this profit cycle can extend beyond 2027 and withstand the return of supply in 2028.
That is the shared thread across several research reports from the past week. Morgan Stanley’s global NAND industry outlook extends the supply-demand model to 2028; Goldman Sachs revised up its Kioxia model; Citi used Micron’s results to read through to SanDisk and NAND pricing; Korean price tracking provided segmented 3Q26 ASPs; JPM used May HDD/SSD data to validate enterprise SSD capacity demand. They approach the issue from different angles but point to the same conclusion: the NAND industry has not simply peaked, but it is no longer in a broad-based price-hike phase.
There are three most direct changes.
First, the subject of demand has changed. In the past, NAND price increases often came from restocking in smartphones, PCs, and consumer SSDs. Now the subject has shifted to AI data centers, enterprise SSDs, high-capacity QLC drives, KV cache, RAG, and agentic AI. The consumer side remains important, but it is no longer the strongest marginal driver.
Second, the supply constraint has changed. In past NAND cycles, supply depended on production cuts, inventory digestion, and price recovery. Now supply discipline comes from another layer: DRAM/HBM is occupying capex priority, while new NAND capacity construction and customer qualification are both slower than the slope of AI demand. Manufacturers do not lack the desire to make money; rather, the more profitable DRAM/HBM opportunity is taking cleanroom, equipment, and engineering resources first.
Third, the timing of disconfirmation has changed. Tightness in 2026 has already been incorporated into many models, and the 2027 shortage is becoming the base case for bulls. The real contest is in 2028. New fabs, technology migration, new Chinese supply from Yangtze Memory Technologies and others, and subsequent resource shifts by Samsung/Micron/SK Hynix will all affect NAND supply-demand around 2028.
AI Drives a Sector-Wide Storage Re-Rating: DRAM, NAND, SSD, and HDD Pricing Power, Cross-Validated by Samsung, SK Hynix, SanDisk, Western Digital, and Seagate Earnings
Therefore, this NAND industry update will not repeat why the “storage supercycle” matters. The prior storage series has already discussed HBM, DRAM, NAND, SSD, and HDD within the AI data stack. What is needed now is to isolate NAND and clarify where the industry stands: price increases continue, but strength is now tiered; manufacturers still have pricing power, but customers have started to select by product; 2027 remains tight, while 2028 needs to be recalculated.
2. What the Recent Reports Actually Added
The recent NAND-related reports do not offer the same target price, nor are they simply a repeated bullish call from the same institution. Each adds a separate piece of evidence. Together, they form the core of this industry update.
This table helps distinguish what is new information from what is merely an old view stated differently. NAND tightness is not a new view, and AI storage is not a new concept. The genuinely new change is that several pieces of evidence are pointing simultaneously to “extended tightness, but with structural divergence.”
On one side, the data center is stronger. Morgan Stanley’s supply-demand model lifts AI NAND demand as a share of total demand from 18% in 2025 to 41% in 2027; JPM’s May data also show enterprise/data center SSD capacity up 139% YoY. This suggests demand is not only in company guidance, but also in monthly industry data.
On the other side, the consumer side is weakening. In Korean price tracking, eSSD can still rise 18%-23% in 3Q26, while mobile NAND is only up 5%-10%; Morgan Stanley’s channel checks also show TLC eSSD up about 30% QoQ, while consumer-grade NAND is only up slightly. Customers still need NAND, but different customers have completely different tolerance for prices.
The third side is that supply remains slow. Goldman Sachs’ equipment-channel checks indicate major memory vendors continue to prioritize DRAM investment, and new NAND fab supply additions may become more visible only in CY28. Citi also emphasizes that limited cleanroom space is constraining NAND bit supply growth. If supply discipline holds, a 2027 shortage is not just a slogan.
The fourth side is that the 2028 uncertainty has increased. Morgan Stanley’s 2028 scenario analysis brings new capacity to the foreground: if AI SSD demand continues growing rapidly and new capacity remains controlled, the shortage can persist; if new capacity accelerates and AI SSD demand slows, NAND supply-demand could quickly return to oversupply risk.
Global Storage Deep Dive: 2Q26 Earnings Divergence, and Whether 3Q Pricing Improvement Can Restart a Storage Stock Re-Rating
This is the difference between an industry note and a single-stock note. A single-stock note needs to answer whose profit leverage is greatest. An industry note needs to answer where the boundaries of that profit leverage lie. For NAND, those boundaries are now clear: 2026 is about pricing, 2027 is about the persistence of shortages, and 2028 is about supply discipline.
3. Morgan Stanley Supply-Demand Model: AI NAND Moves from Incremental Demand to the Main Variable
The core table in Morgan Stanley’s global NAND industry outlook is its AI NAND demand and global NAND supply-demand table. It advances the market debate from “will AI use NAND” to “how many EB will AI consume.”
In Morgan Stanley’s estimate, AI-related NAND demand rises from 205EB in 2025 to 400EB in 2026E and then to 609EB in 2027E. Its share of total NAND demand rises from 18% to 32% and then to 41%. This is not a small supplementary item, but the most important incremental driver of total demand.
This table has two important implications.
First, non-AI demand is not the protagonist. Non-AI NAND demand in 2026E is below 2025, and 2027E only recovers slightly. Smartphones, PCs, and ordinary SSDs are not providing a sector-level strong recovery. If the NAND bull case only talks about consumer electronics restocking, it is hard to justify such high earnings forecasts.
Second, AI demand is not one-off inventory. Morgan Stanley’s AI NAND breakdown comes from multiple sources, including ASIC/GPGPU shipments, actual CSP deployments, in-rack eSSD, external storage, QLC data lakes, additional Blackwell configurations, CPU racks, and Seagate Technology CMS. It places NAND inside AI racks and data lakes, rather than treating it merely as traditional server SSD.
Morgan Stanley’s supply-demand model also highlights an underappreciated point: non-AI demand can be weak, yet AI demand can still be sufficient to create a shortage. NAND’s structure is starting to look like a “barbell”: one end is the extremely strong data center, while the other is the pressured consumer side. Industry ASPs, company profits, and valuation leverage all depend on which end carries more weight.
How to Bypass the Memory Tax: NAND, CXL, and PIM Are Being Repriced as the Storage Hierarchy Is Rebuilt
This is also why follow-up tracking cannot look only at NAND spot prices. Spot prices are affected by the consumer side, channel inventory, and short-term trading. More important indicators are enterprise SSD capacity shipments, high-capacity QLC products, cloud procurement, long-term agreement coverage, server inventory, and manufacturers’ capex. These indicators are better at judging whether AI NAND demand is still present.
IV. eSSD Is Hard Evidence: May Capacity Shipments +139% YoY
If Morgan Stanley’s supply-demand model answers “where the future NAND shortage comes from,” JPM’s May storage production trends answer “whether data center SSD demand is being realized now.”
The key in the May data is not SSD units, but capacity. Unit shipments of ordinary SSDs are not strong, but enterprise/data center SSD capacity shipments have already separated the quality of NAND demand.
The most important part of this dataset is not units, but capacity. NAND is sold in bits, and the value of enterprise SSDs increasingly depends on capacity, performance, reliability, and qualification, rather than the number of drives.
There is one key message here: demand is coming not only from “more SSDs,” but also from “larger SSDs.” JPM noted that demand for high-capacity enterprise/data center SSD products such as 61.44TB, 122.88TB, and 245.76TB has reached very high levels, and QLC designs are becoming more common in these capacity tiers. This corroborates Morgan Stanley’s model, which classifies data lake-related demand under QLC.
This explains why NAND and HDD can both be strong at the same time. Enterprise SSDs are not simply replacing nearline HDDs, and nearline HDDs are not suppressing enterprise SSDs. AI data centers are expanding the entire storage pyramid: hot data needs SSDs, warm data needs both SSDs and HDDs, and cold data needs HDDs and tape. Within this pyramid, NAND is taking the higher-performance, higher-capacity, higher-value layers.
AI Storage Deep-Dive Update: Morgan Stanley’s May HDD and SSD Data Confirms Data Center Capacity Demand Remains Elevated
This also gives the NAND industry a validation method. As long as enterprise/data center SSD capacity continues to grow strongly, AI demand for NAND is still present. If total SSD units remain flat and consumer SSD demand is weak, but eSSD capacity continues to rise, the industry structure will continue to tilt toward original manufacturers and high-end products. If eSSD capacity growth falls back to the level of ordinary SSDs, the NAND bull case loses its hardest data support.
V. 3Q26 Price Divergence: eSSD Still Strong, Consumer Starting to Buckle
Pricing is the easiest NAND indicator to observe, and also the easiest to misread. The price signals from recent reports are not fully consistent, but they are useful when pieced together: eSSD is still rising sharply, overall NAND is still rising, and consumer-side price increases are starting to slow.
Korea Tech’s June memory price tracker and Morgan Stanley’s channel checks point in the same direction: overall NAND is still rising, eSSD is clearly stronger, and mobile and consumer products are starting to lag. The specific increases are clearer in table form.
This table has a clear conclusion: NAND is still rising, but the industry has entered a phase of “structural price increases.” Structural price increases are more favorable to original manufacturers and more demanding for channels and module makers.
Original manufacturers can prioritize limited supply for cloud customers, enterprise SSDs, high-capacity QLC, low-latency TLC, and other high-value products. Module makers and consumer customers face two pressures: manufacturers are unwilling to provide enough low-priced supply, while end customers are unwilling to accept continued large price increases. The mismatch among inventory, FIFO costs, and price pass-through will amplify profit volatility.
This is also what Morgan Stanley means by “AI vs consumer bifurcation” in its global NAND industry outlook. Servers remain tight, while consumer-side inventory and channel pressure are starting to rise. Higher inventories at module makers and distributors do not necessarily mean end demand has deteriorated, but they do create pressure from holding high-priced inventory. Small and mid-sized customers are deterred by high prices, transaction volume shrinks, and the price-increase ceiling on the consumer side appears earlier.
Memory Tax Keeps Rising: Storage Prices May Post Sharp Sequential Increases for Two Consecutive Quarters in 2H This Year
Therefore, NAND industry price validation cannot rely on a single ASP number. A better validation method is to look at the spread between eSSD and consumer NAND. If eSSD continues to rise while the consumer side slows, original manufacturers’ profits can still hold up, but modules and the consumer chain will diverge. If eSSD also starts to slow, the industry bull case will enter a stress test.
VI. Supply Discipline: Why NAND Has Not Immediately Been Knocked Back by Capacity Expansion
Every memory price increase faces the same question: with prices this high, manufacturers will eventually expand capacity and kill the cycle. This concern is still valid for NAND, but recent reports show that supply return will not be as fast as the price response.
Goldman Sachs’ Kioxia update provides the clearest supply framing. It raised FY3/27-FY3/29 operating profit forecasts by 9%/19%/29%, respectively, and increased its CY26 NAND ASP assumption to 4.5x YoY and CY27 to +38% YoY. One key assumption behind this is that major memory manufacturers are still prioritizing DRAM investment, and supply additions from new NAND fabs may not become more visible until CY28.
Citi’s SanDisk update gives a similar logic. It believes NAND suppliers are shifting cleanroom space from NAND to DRAM, and overall limited cleanroom availability is constraining NAND bit supply growth. Even if industry supply gradually improves in 2028, management has not clearly seen when supply will catch up with demand.
The most important factor here is the crowding-out effect from DRAM/HBM. NAND tightness is not an isolated event; it is linked to the broader AI memory cycle. HBM, DDR5, and server DRAM are all rising. When manufacturers make investment choices, they prioritize products with firmer customers, higher prices, and longer qualification cycles. NAND is gaining supply discipline precisely because it is “not receiving the most capex.”
This is also the paradox for pure NAND assets such as Kioxia and SanDisk. They lack direct DRAM/HBM revenue, but benefit when integrated memory manufacturers allocate resources to DRAM/HBM, thereby suppressing NAND supply growth. As long as pure NAND companies maintain capex discipline, they can achieve very high profit leverage in 2026-2027.
Kioxia Deep-Dive Update: Goldman Sachs Raises Target Price to JPY 116,000; How NAND Tightness Revalues the AI Storage Cycle
Supply discipline should not be mythologized. The historical pattern of the memory industry still exists: high prices attract supply, high profits induce technology migration and new capacity, and customers look for alternatives. The bull case works now because supply response is slower than demand, not because supply will never respond.
Therefore, three supply-side indicators should be tracked.
First, NAND WFE orders. As long as NAND-related equipment orders begin to accelerate materially, the market will discount 2028 supply pressure in advance.
Second, manufacturers’ capex mix. If Samsung, Micron, SK Hynix, Kioxia, SanDisk, and others shift more resources from DRAM/HBM to NAND, supply discipline will weaken.
Third, high-end eSSD qualification capability. If new NAND bits are mainly ordinary products, AI eSSD may still be tight. If new supply directly enters cloud customers’ high-capacity SSDs, pricing pressure will transmit more quickly.
VII. 2028 Scenario Test: New Capacity Is the Biggest Variable in This Cycle
2028 is the year neither NAND bulls nor bears can avoid. Morgan Stanley’s scenario test frames the issue clearly: AI SSD demand growth and new NAND capacity together determine the direction of supply and demand.
Morgan Stanley assumes non-AI NAND demand grows 5% YoY in 2028, other suppliers expand capacity in line with forecasts from its U.S. semiconductor team, and AI SSD demand growth ranges from 30% to 60%. It also places Yangtze Memory Technologies’ 2028 capacity in a range of 310-470kwpm. The results show that the higher AI SSD demand is and the more disciplined capacity additions are, the tighter supply-demand becomes; if AI SSD demand slows and capacity accelerates, supply-demand is more likely to swing into oversupply.
The most valuable part of this test is that it does not reduce 2028 to a single conclusion. NAND in 2028 could remain tight, or it could shift into oversupply. The difference is not about belief, but two hard variables: AI SSD demand and new capacity.
On the demand side, the key is whether AI applications continue to absorb more storage. RAG, vector databases, long context, agentic AI, training data lakes, inference logs, video, and multimodal data will all drive NAND demand. If these applications remain concepts and do not convert into large-scale procurement, the 2028 demand slope will fall.
On the supply side, the key is whether new capacity comes online at the same time. Morgan Stanley specifically notes that Chinese NAND suppliers are building multiple fabs; if all of them are used for NAND, their long-term share could rise significantly. This variable does not necessarily mean oversupply, but it does mean NAND supply elasticity after 2028 will be greater than in 2026-2027.
There is also an underappreciated upside variable in 2028: Super High IOPS SSDs. Morgan Stanley notes that its 2028 model does not include the potential wafer consumption of ultra-high-IOPS SSDs for AI inference. If these products enter volume production in 2028, they may consume roughly 3x the capacity of ordinary SSDs, further tightening industry supply. In other words, 2028 is not simply a story of supply returning; new products may once again absorb supply.
The investment implication for 2028 is straightforward. Looking only at 2026-2027, NAND manufacturer profits should remain very strong. Extending the horizon to 2028, valuation cannot rely only on peak EPS; it must be judged by how long high profits can last, where the trough sits on the way down, and how much can be locked in through long-term agreements.
VIII. NBM and LTA: Can Cyclical Profit Become a Cash-Flow Asset?
Whether NAND stocks can continue to rerate ultimately depends on whether profit can move from spot price increases to visible cash flow. The key terms here are NBM and LTA.
Morgan Stanley’s SanDisk podcast places NBM in a prominent position: fixed prices, cap-and-floor structures, and decommit penalties. In investment-research terms, this means customers are not only committing to procurement, but also accepting price bands and exit costs. Only this type of contract can potentially capitalize part of peak profits.
But long-term agreements are harder in NAND than in DRAM. Morgan Stanley’s channel checks note that customers are more willing to pay for DRAM to secure supply, while NAND price increases face more pushback. The reason is simple: DRAM is closer to server and GPU performance bottlenecks, so shortages have a more direct system-level impact. NAND is also important, but consumer customers and some enterprise customers are more price sensitive.
Kioxia and SanDisk are also following different paths. Goldman Sachs says Kioxia prioritizes price and margins and will not sacrifice too much upside to sign LTAs. This choice is favorable in the short term, because the company can capture price increases. Over the long term, the question is whether there is enough downside protection when the cycle turns. SanDisk, by contrast, emphasizes NBM and data-center customer binding, which is why the market is willing to assign it a higher multiple.
SanDisk Deep-Dive Update: Citi Raises Target Price to $2,500, NAND Tightness Cycle Extends Beyond CY27
NBM and LTAs are not cure-alls. Customers will demand renegotiation when prices fall, and cloud customers will also use multi-supplier strategies to reduce the bargaining power of any single manufacturer. If a contract lacks a clear floor price, breach cost, or exit penalty, it is more like supply assurance than profit assurance.
Four things matter when judging the quality of NBM/LTAs.
First, coverage. The higher the coverage, the stronger revenue visibility, though excessive coverage can also sacrifice upside flexibility.
Second, pricing terms. Fixed prices, price bands, cost pass-through, and limits on price increases or declines matter far more than the words “long-term cooperation.”
Third, customer type. LTAs with hyperscalers, server OEMs, and AI infrastructure customers are higher quality than those with ordinary consumer channels.
Fourth, exit cost. LTAs without decommit penalties provide limited protection when prices decline.
Therefore, NBM/LTAs are the first gate for NAND valuation. If NAND manufacturers pass this gate, they can shift from price-hike stocks to partial cash-flow assets. If they do not, high profits remain cyclical peak earnings.
IX. Company and Segment Ranking: Prioritize Manufacturers, Module Makers Diverge, Controllers Depend on Certification
NAND opportunities can no longer be ranked simply by “who has NAND exposure.” The real ranking depends on three dimensions: control of original supply, entry into enterprise/data-center SSD customers, and sufficiently strong contracts and certifications.
Manufacturers are the most direct beneficiaries. Kioxia and SanDisk are the purest NAND elasticity plays. Micron, Samsung, and SK Hynix are full-category memory assets, with NAND providing additional upside beyond HBM/DRAM. The common advantage of manufacturers is control over supply allocation and pricing, allowing them to prioritize shipments to eSSD, cloud customers, and LTA customers.
Module makers and the consumer chain will diverge. Early low-cost inventory will create profit elasticity, but as new high-cost supply enters, consumer price ceilings emerge, and manufacturers prioritize supply to CSPs, ordinary module makers will face pressure on both volume growth and gross margins. They can benefit from price increases, but it is harder for them to convert price increases into durable profit.
Controllers and high-end modules depend on certification. If companies such as Silicon Motion and Phison can enter AI boot drives, enterprise SSD controllers, and CSP-customized solutions, they are no longer ordinary consumer-controller stories. If they remain mainly in consumer and channel markets, NAND price increases may instead compress customer demand.
This ranking also explains why NAND industry reports should be separated from single-company reports. A single company may have near-term elasticity due to target prices, share prices, and earnings models. At the industry level, the key is to judge where value-chain profits are flowing. For now, profits are flowing first to manufacturers and the high-end eSSD chain, while ordinary modules and the consumer chain are more likely to come under pressure.
SanDisk Deep-Dive Update: Jefferies’ $3,000 Target Price, eSSD Share Recovery, and How NAND LTAs Rerate Profit Durability
Valuation should also be differentiated according to this table. Manufacturers should be assessed on 2027-2028 profit durability, controllers on certification and customer share, and module makers on inventory, gross margin, and cash flow. Calling all of them “beneficiaries of NAND price increases” would misread the risks.
10. Three Worldviews: Shortage Extension, Structural Balance, Supply Return
There are now three worldviews for NAND, each of which can explain part of the data.
The bullish worldview is “shortage extension.” AI SSD demand continues to grow rapidly, CSPs put more capacity into racks, data lakes, and context memory, suppliers continue to prioritize capex for DRAM/HBM, and incremental NAND supply grows more slowly than demand. In this world, shortages persist in 2027, and even if supply recovers in 2028, it is hard to push margins back to historically low levels. Pure-play NAND suppliers such as Kioxia and SanDisk enjoy the highest operating leverage.
The neutral worldview is “structural balance.” eSSD remains strong, the consumer side weakens, and the overall slope of NAND price increases declines. Suppliers still make money, but earnings are no longer revised up linearly; companies with strong long-term agreements and eSSD share defend high profitability, while standard modules and consumer chains are squeezed first. In this world, the industry still has opportunities, but not all NAND exposure should be bought.
The bearish worldview is “supply return.” New capacity is released in a concentrated way in 2028, AI SSD demand growth slows, consumer-side price resistance expands to enterprise customers, and bit supply from accelerated NAND WFE exceeds demand. In this world, 2026-2027 profits will be reclassified by the market as peak earnings, and low P/E again becomes a cyclical trap.
Current evidence is closer to somewhere between “shortage extension” and “structural balance.” eSSD is very strong, supply discipline remains in place, and the 2027 gap is still visible; but the consumer side already has a price ceiling, module and distribution inventories are rising, and customer acceptance of NAND price increases is weaker than for DRAM. In one sentence: the bullish case has not been falsified, but NAND can no longer be bought as an indiscriminate price-hike trade.
Market pricing will next shift from “price increases” to “profit quality.” Within the same NAND upcycle, eSSD long-term agreements, NBM, high-capacity QLC, and high-IOPS SSD will generate higher-quality profits; consumer NAND, channel inventory, and standard modules will have shorter profit windows.
11. Tracking Indicators: The Next Four Numbers Matter Most
The NAND industry does not lack narratives; it lacks validation. The four most important sets of numbers to watch are as follows.
First, enterprise/data-center SSD capacity shipments. JPM’s May figure of 41.4 EB, up 139% year over year, is hard evidence. If this growth rate continues to exceed standard SSD growth, AI NAND demand is still intact; if capacity growth clearly falls back, the core data support for the bullish case will be shaken.
Second, ASP divergence in 3Q26 and 4Q26. eSSD price increases, TLC eSSD price increases, mobile NAND price increases, and consumer NAND price increases need to be viewed separately. As long as eSSD remains high and the consumer side slows, supplier profits may still hold; if eSSD also decelerates, industry earnings revisions will stop.
Third, NAND WFE and capex structure. DRAM/HBM investment priority is the key to supply discipline. If NAND WFE begins to accelerate persistently, or if major memory suppliers clearly shift capex back to NAND, the market will discount 2028 supply pressure in advance.
Fourth, long-term agreements and NBM terms. It is not enough to say long-term agreements have been signed; the floor price, ceilings and floors, default costs, customer type, and coverage ratio matter. The harder the contracts, the more profits can be capitalized; the softer the contracts, the more high profitability looks like a cyclical peak.
These indicators are more useful than a single month of share-price moves or one target-price change. The NAND industry is now in a “data validation phase,” and the market will continuously recalibrate valuations using prices, shipments, inventories, capex, and contract terms.
12. Conclusion: NAND Is Not Over, but Entry Points Are Now More Selective
The NAND trade is not over. AI eSSD demand is strong enough, the 2027 supply-demand gap remains visible, supplier supply discipline is still intact, and DRAM/HBM-prioritized expansion has created additional constraints for NAND. Evidence from Goldman Sachs, Citi, Morgan Stanley, JPM, and Korean price tracking corroborates one another: data-center NAND remains strong, and enterprise SSD is the core variable in this memory cycle.
But the NAND trade can no longer be crudely understood as “industry-wide price increases.” Price ceilings are starting to appear on the consumer side, mobile NAND price increases are lower than eSSD, module and distribution inventory pressure is rising, and customer acceptance of NAND price increases is weaker than for DRAM. The industry bull case remains intact, but profits will concentrate in suppliers, high-end eSSD, long-term agreements, and high-capacity products.
This is the most important current investment judgment: NAND is moving from a price trade to a profit-quality trade.
A price trade asks who can raise prices the fastest; a profit-quality trade asks who can defend those profits the longest. For Kioxia and SanDisk, the key variables are eSSD, BiCS/QLC, NBM/LTA, and capex discipline; for Samsung, Micron, and SK Hynix, the key variables are full-category breadth and DRAM/HBM priority; for controller and module companies, the key variables are customer qualification, supply access, and gross-margin pressure. The operating leverage of ordinary consumer chains will become increasingly short-lived.
2028 is the final stress test. If AI SSD demand continues to grow rapidly, and new demand such as Super High IOPS SSD, HBF, and QLC data lakes consumes more wafers, NAND profits can receive higher capitalization; if new capacity accelerates, the consumer side continues to resist price increases, and eSSD growth slows, high profitability will return to a traditional cyclical peak.
The task now is not to ask whether NAND prices will keep rising, but to ask four more specific questions: how much longer eSSD can rise, how long supply discipline can hold, how much profit long-term agreements can lock in, and whether 2028 new capacity will arrive early. The answers to these four questions will determine whether the NAND industry continues to be re-rated or retreats from a supercycle back to an ordinary cycle.