
Murata Manufacturing Deep Update: Citi's JPY 15,000 Target Price and How AI Server MLCC Re-rates the Profit Slope
目录
TL;DR
1. Conclusion First: Citi's Upgrade Is Buying the "High-Capacitance MLCC Profit Gate"
2. What Exactly Citi Changed: Rating, Target Price, Earnings, and Discount Rate Moved Together
3. The Essence of AI Server MLCC: From "More Units" to "Higher Capacitance"
4. Earnings Bridge: Why Operating Profit Moves from Recovery to Step-Function Growth
5. Pricing Discipline: Murata Wants High-End Mix-Led Price Increases
6. RoIC-WACC Valuation: JPY 15,000 Requires Murata to Become a High-Capital-Efficiency Asset
7. Murata's Capability Migration: From Cyclical Leader to AI Server Power-Supply Materials Platform
8. Peer Comparison: Murata Captures Specifications, Samsung Electro-Mechanics Captures Elasticity, Taiyo Yuden Captures the Cycle, and Yageo Captures Inventory and Channels
9. Relationship with ABF and PCB: The AI Server Materials Chain Spills Over from Main Chips to the Power Layer
10. Three Scenarios: JPY 15,000 Is the Base Case, JPY 18,000 Requires Broad Price Increases, and the Stress Case Depends on Inventory and Yield
11. Data Framework: In the Next Stage, Look First at Order Quality, Then Profit Quality
12. Why Citi Is More Aggressive Than the Previous Market View: It Turned "Higher Server Specifications" into Income-Statement Assumptions
13. Historical Positioning: What Really Makes Murata Valuable Is Turning Materials Capability into Customer Standards
14. Risk Breakdown: Under a High Valuation, Any Failed Validation Link Will Be Amplified
15. Linkage with Previous MLCC Reports: Industry Logic Has Evolved from "Shortage" to "Who Can Turn Shortage into RoIC"
16. Profit Bridge Breakdown: From GPU Board to RoIC, There Are Six Gates in Between
17. Expansion and Supply: 20% Additional Capacity Is Only the Starting Point; Capacity Quality Is the Key
18. Reverse-Engineering the Target Price: What Evidence Is Needed for JPY 15,000, and What Extra Conditions Are Needed for JPY 18,000
19. How to Track the Next Four Quarters: Look First at High-Capacitance MLCC, Then at Drag from Ordinary Businesses
20. Financial Quality: Earnings Upgrades Must Move Through Inventory, FX, and Capex
21. How to Read Management Commentary: Listen Less to Price-Hike Slogans, More to Mix and Discipline
22. Conclusion: Murata Has Entered a High-Standard Delivery Period, and JPY 15,000 Requires Profit Quality
本内容基于公开资料和研报数据整理,不构成任何投资建议,不代表任何个人观点,仅供学习参考,请理性阅读
Citi upgraded Murata Manufacturing to Buy and set a JPY 15,000 target price. The core logic is that AI server MLCC is shifting from unit-count expansion to a simultaneous rise in capacitance, ASP, and RoIC. This report breaks down earnings upgrades, valuation assumptions, pricing discipline, and follow-up validation signals to assess whether this re-rating can move through the ordinary MLCC cycle.
TL;DR
Citi has lifted the valuation anchor to JPY 15,000. The rating was upgraded from Neutral to Buy, with a sharp target-price increase driven by changes in earnings forecasts, risk premium, and the valuation base year. This adjustment means Citi has moved Murata from a normal MLCC cycle-recovery framework into a capital-efficiency re-rating driven by high-capacitance MLCC for AI servers.
AI servers are rewriting the MLCC profit slope. GPU boards are increasing MLCC unit count, capacitance, and layer-count requirements at the same time, benefiting Murata's high-capacitance MLCC pricing, yield, and customer qualification threshold. The key follow-up is whether migration from 47uF to 100uF continues, and whether high-capacitance products truly enter revenue and gross margin.
Earnings upgrades are concentrated in capacitors. Citi has moved operating profit forecasts to a new level, with passive-component margins rising materially. Recovery in devices and modules mainly provides a profit floor. The real driver of the target price is whether the capacitor business can turn AI server orders into continuous improvement in ASP, gross margin, and RoIC.
Pricing discipline determines re-rating quality. The company has not yet actively pushed broad price increases for standard products. The JPY 15,000 target price mainly reflects high-end mix upgrade, while JPY 18,000 would require stronger evidence of industry-wide price increases. If standard-product price hikes trigger inventory backlash, valuation quality would decline; if high-capacitance mix improvement continues, the base target price becomes more robust.
RoIC has become the core valuation variable. Citi uses a RoIC-WACC framework, and the target price implies a PE above historical peaks. That requires continuous delivery in AI server margins and capital efficiency. The market will next examine expansion yield, passive-component margins, and cash flow, not just one-quarter EPS upgrades.
Watch six numbers for validation. Book-to-bill, AI server revenue mix, MLCC ASP, passive-component margin, inventory cash flow, and expansion pace will determine how far this re-rating can go and whether it can move through ordinary cycle and valuation volatility. If all six improve together, Murata looks more like a leader in AI server power-supply materials. If the indicators diverge, valuation will return to the MLCC cycle framework.
1. Conclusion First: Citi's Upgrade Is Buying the "High-Capacitance MLCC Profit Gate"
Citi's upgrade of Murata Manufacturing is aggressive and highly directional. The rating was raised from Neutral to Buy, and the target price was lifted from JPY 3,900 to JPY 15,000. Based on the June 26, 2026 closing price of JPY 10,770, that target implies roughly 40% total return upside. The number is easy to read as a simple target-price increase, but the real change in the report is that the valuation framework has moved from "MLCC cycle recovery" to an "AI server high-capacitance MLCC profit gate."
Murata Manufacturing has historically been treated as a cyclical stock tied to smartphones, automotive electronics, and general MLCC. AI servers are starting to loosen that label. A standard server board needs roughly 2,000 MLCCs, while a GPU board could approach 11,000 units by 2026. Standard servers more often use products around 10uF, while AI servers are moving from 47uF toward 100uF. Higher capacitance means more thin-film layers, a heavier process load, and greater importance for yield and materials capability. Citi's view is that Murata's production yield and materials development capability in high-capacitance MLCC are becoming a harder-to-replicate source of profit.
This is also the basis for the JPY 15,000 target price. Citi does not frame the upgrade simply as "industry-wide price increases." Instead, it repeatedly emphasizes that the company remains restrained on supply-demand-led price hikes for ordinary MLCC. The base target price relies on AI server mix upgrade, product-mix improvement, operating profit upgrades, and higher RoIC. If ordinary MLCC prices rise by more than 10% across the board, Citi's upside scenario can approach JPY 18,000, but that path requires stronger evidence of industry-wide price increases.
Murata Manufacturing Deep Dive: AI Server MLCC, from Small Component to Profit Gate
The most important way to read this update is to separate "target-price upgrade" from "business-model upgrade." The target price is the result; the business-model upgrade is the reason. Murata obtains order elasticity from consumer electronics and automotive cycles, and specification barriers and margin elasticity from AI servers. As long as specification upgrades, ASP improvement, expansion yield, and customer qualification are all delivered, the market will be willing to understand Murata through a higher-RoIC framework. If these variables remain only short-term price hikes, valuation will return to the ordinary MLCC cycle.
2. What Exactly Citi Changed: Rating, Target Price, Earnings, and Discount Rate Moved Together
The strength of this update comes from four variables changing at the same time. First, the rating was upgraded from Neutral to Buy. Second, the target price was raised sharply. Third, earnings forecasts for FY2027 to FY2029 were lifted, especially the MLCC profit contribution. Fourth, valuation parameters also became more favorable, with the equity risk premium reduced from 4.0% to 3.0% and the valuation base year rolled forward from FY2028 to FY2029.
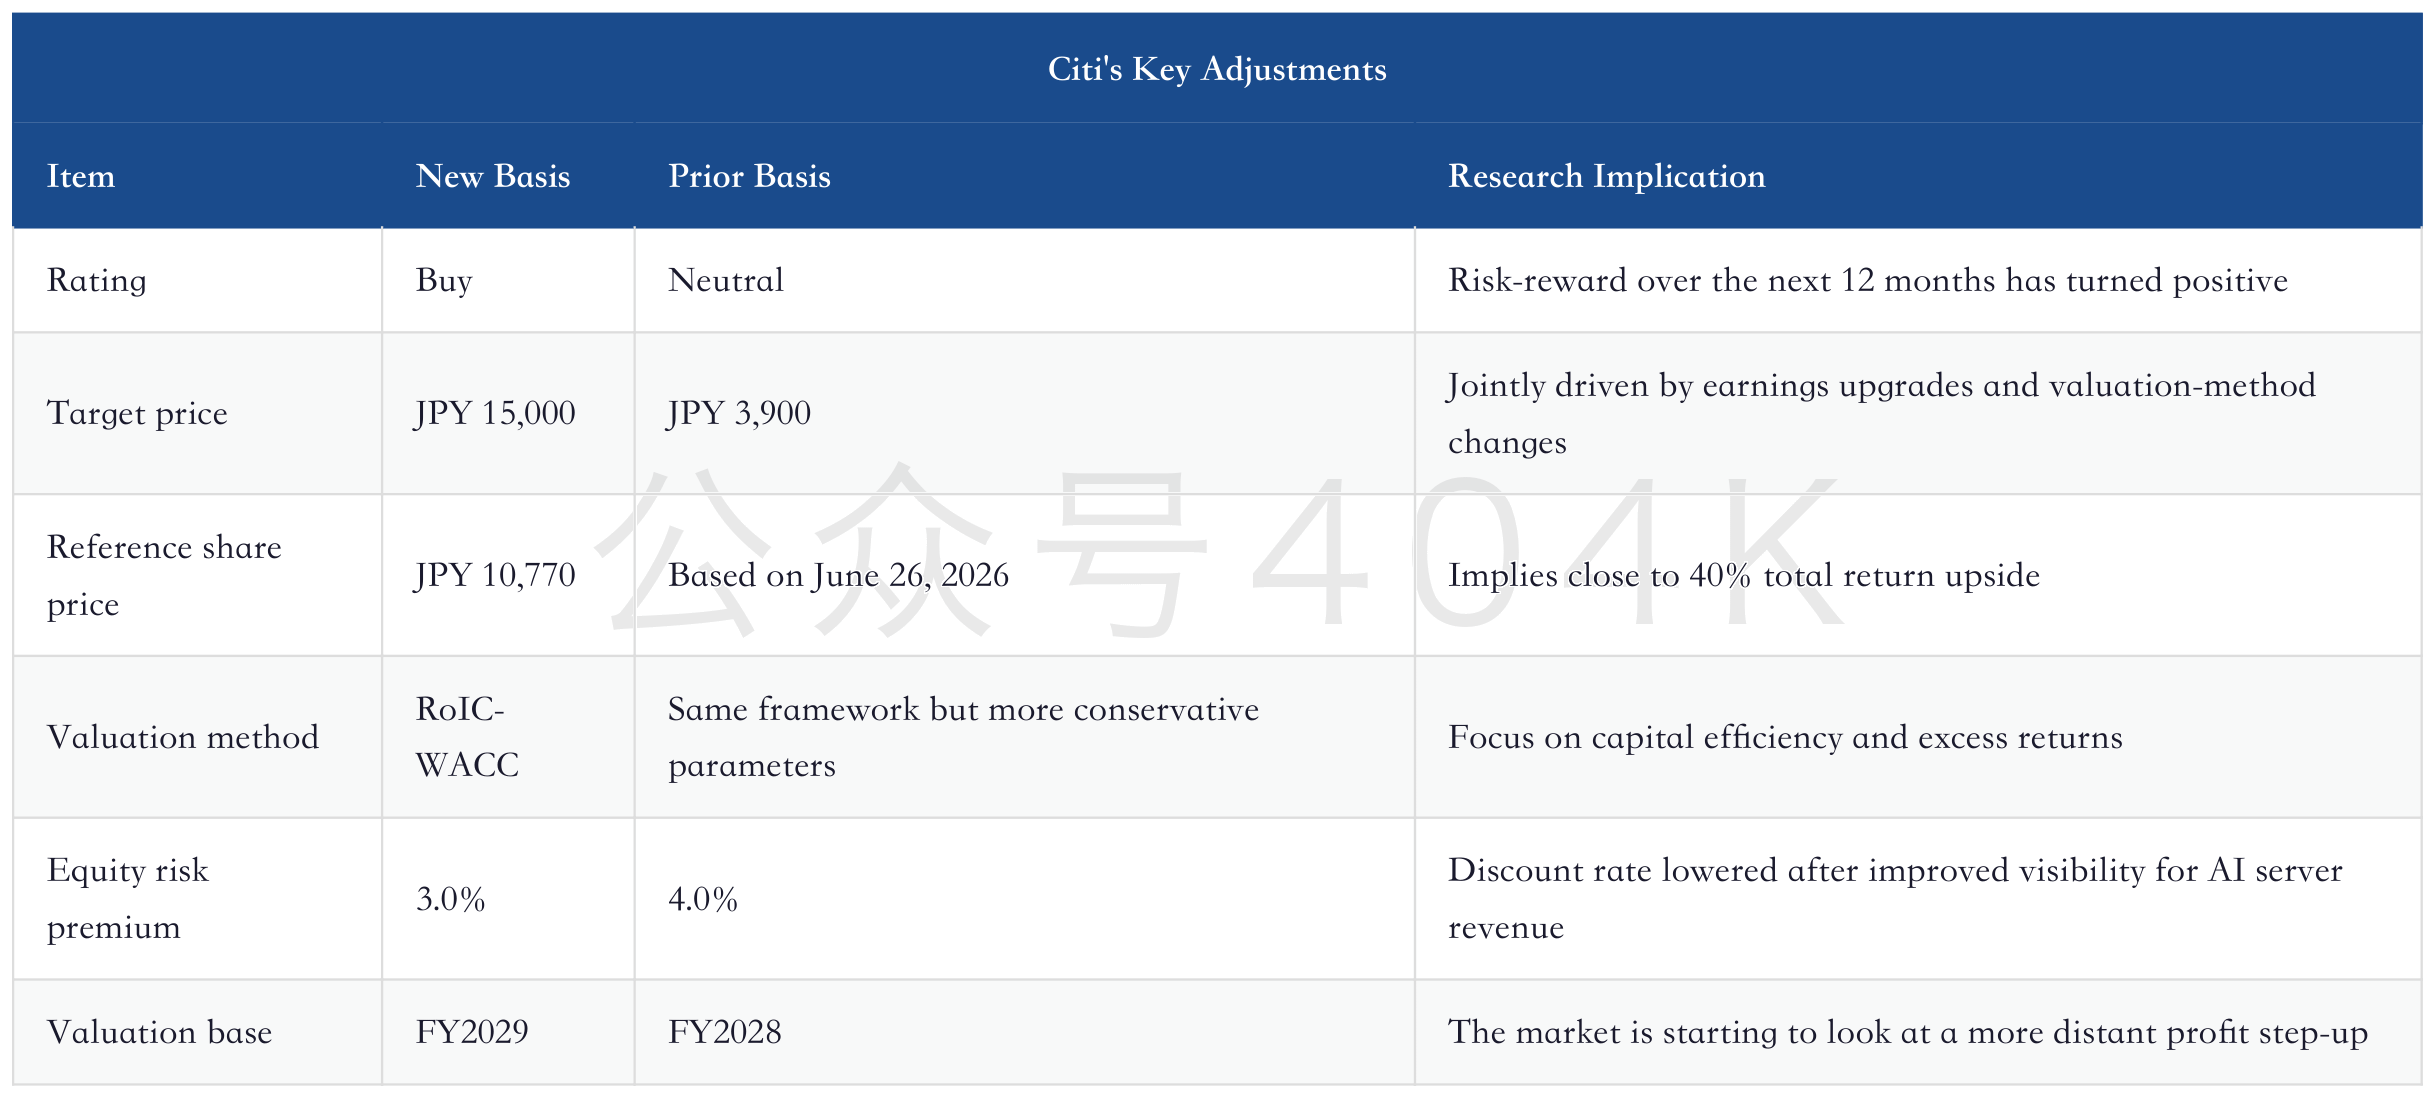
This adjustment has two layers of meaning. The surface meaning is that Citi raised earnings forecasts, so the target price moved higher. The deeper meaning is that Citi is willing to assign a lower risk premium and a later valuation year, indicating it believes visibility, margin, and durability for AI server MLCC demand are now stronger than in an ordinary consumer-electronics cycle.
The biggest risk in reading this kind of upgrade is to treat it as "a broker has given a higher number." The key to JPY 15,000 is not the number itself, but the fact that it places Murata into a higher-standard validation phase. Previously, an MLCC leader could recover earnings as long as smartphones recovered, auto demand was not weak, and channel inventory normalized. Now the market will require Murata to prove that high-capacitance MLCC can keep lifting ASP, preserving yield, expanding capacity, maintaining customer stickiness, and converting those profits into high RoIC.
3. The Essence of AI Server MLCC: From "More Units" to "Higher Capacitance"
The demand shift for AI server MLCC looks on the surface like an increase in unit count, but the core is capacitance and process difficulty. Server motherboards, power supplies, GPU boards, and high-speed interconnects all need stable power delivery. The higher GPU power and transient current become, the greater the dependence on high-capacitance MLCC for bypass, decoupling, and filtering. Standard servers already use many MLCCs, but GPU boards raise volume, specification, and reliability requirements at the same time.
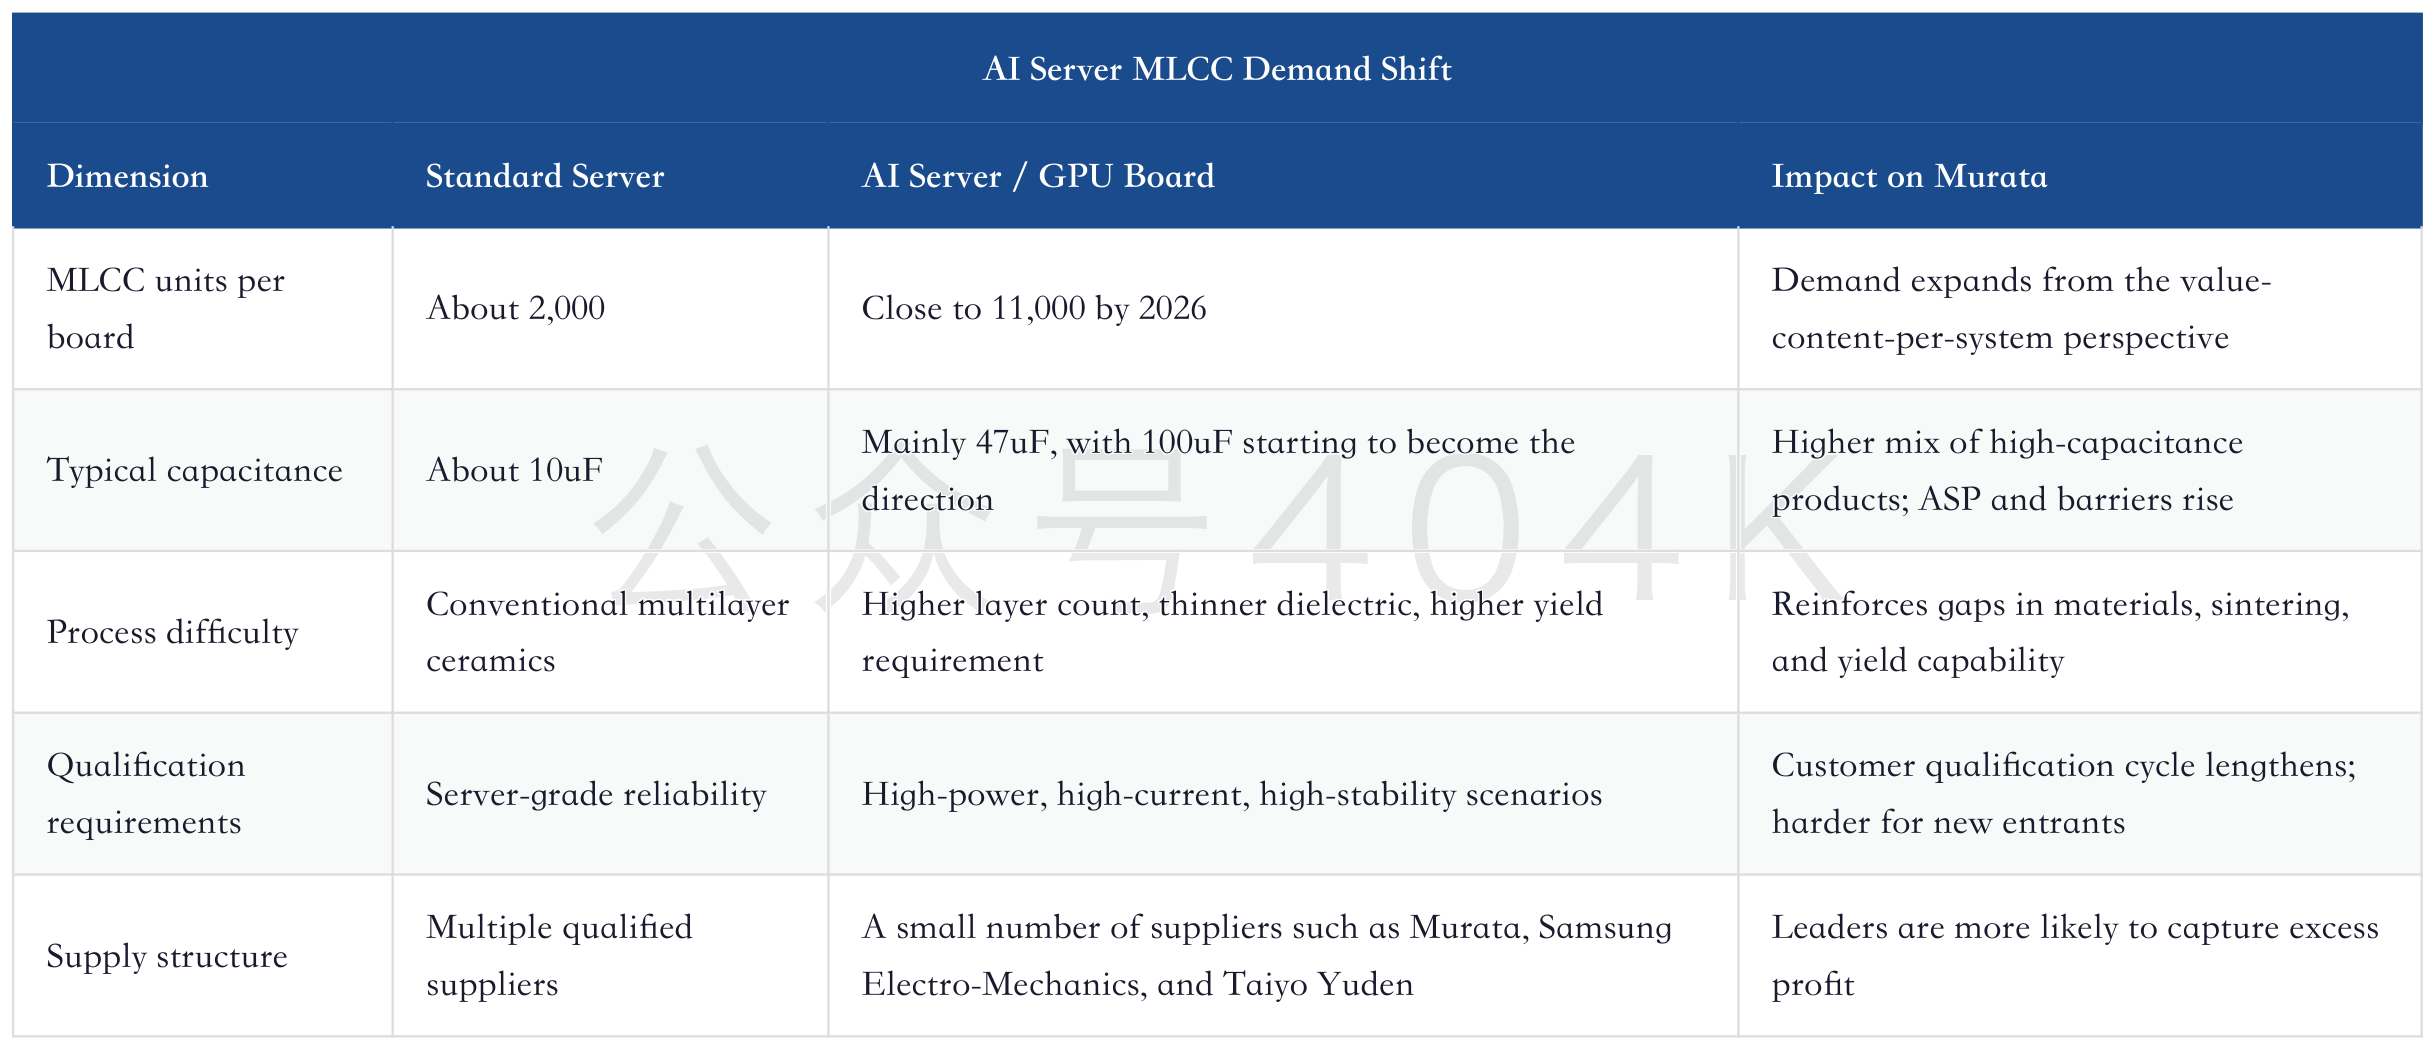
This change creates three profit channels. The first is higher value per system, as GPU boards directly raise the MLCC dollar content needed in each server. The second is better product mix: high-capacitance products carry higher ASP and depend more on yield and materials formulas. The third is lower supply elasticity: the higher the MLCC specification, the harder it is to expand quickly, making prices and gross margins easier to sustain.
Citi particularly emphasizes the significance of 100uF high-capacitance MLCC. 47uF is already higher than the common specification used in standard servers, while 100uF means more layers, heavier production load, and higher yield risk. Price increases in general MLCC can easily attract competitors, but high-capacitance MLCC requires long-term materials accumulation, powder control, thin-layer processes, and customer qualification. These barriers give Murata stronger pricing power.
MLCC Deep Update: AI Servers Push a Cyclical Component Toward a Power-Supply Bottleneck, and Who Can Turn Price Increases into Profit
Murata's AI server opportunity therefore cannot be viewed only through "MLCC unit count." Unit count determines total demand, capacitance determines ASP, yield determines margin, and customer qualification determines durability. Citi's target-price upgrade essentially writes these four variables into the FY2027 to FY2029 income statement.
4. Earnings Bridge: Why Operating Profit Moves from Recovery to Step-Function Growth
Citi's earnings forecast upgrades mainly land in operating profit and passive-component margins. Revenue growth is of course important, but Murata's valuation elasticity mainly comes from margins. Once AI server MLCC enters the revenue mix as a high-specification product, ASP, gross margin, capacity utilization, and capital efficiency all improve together.
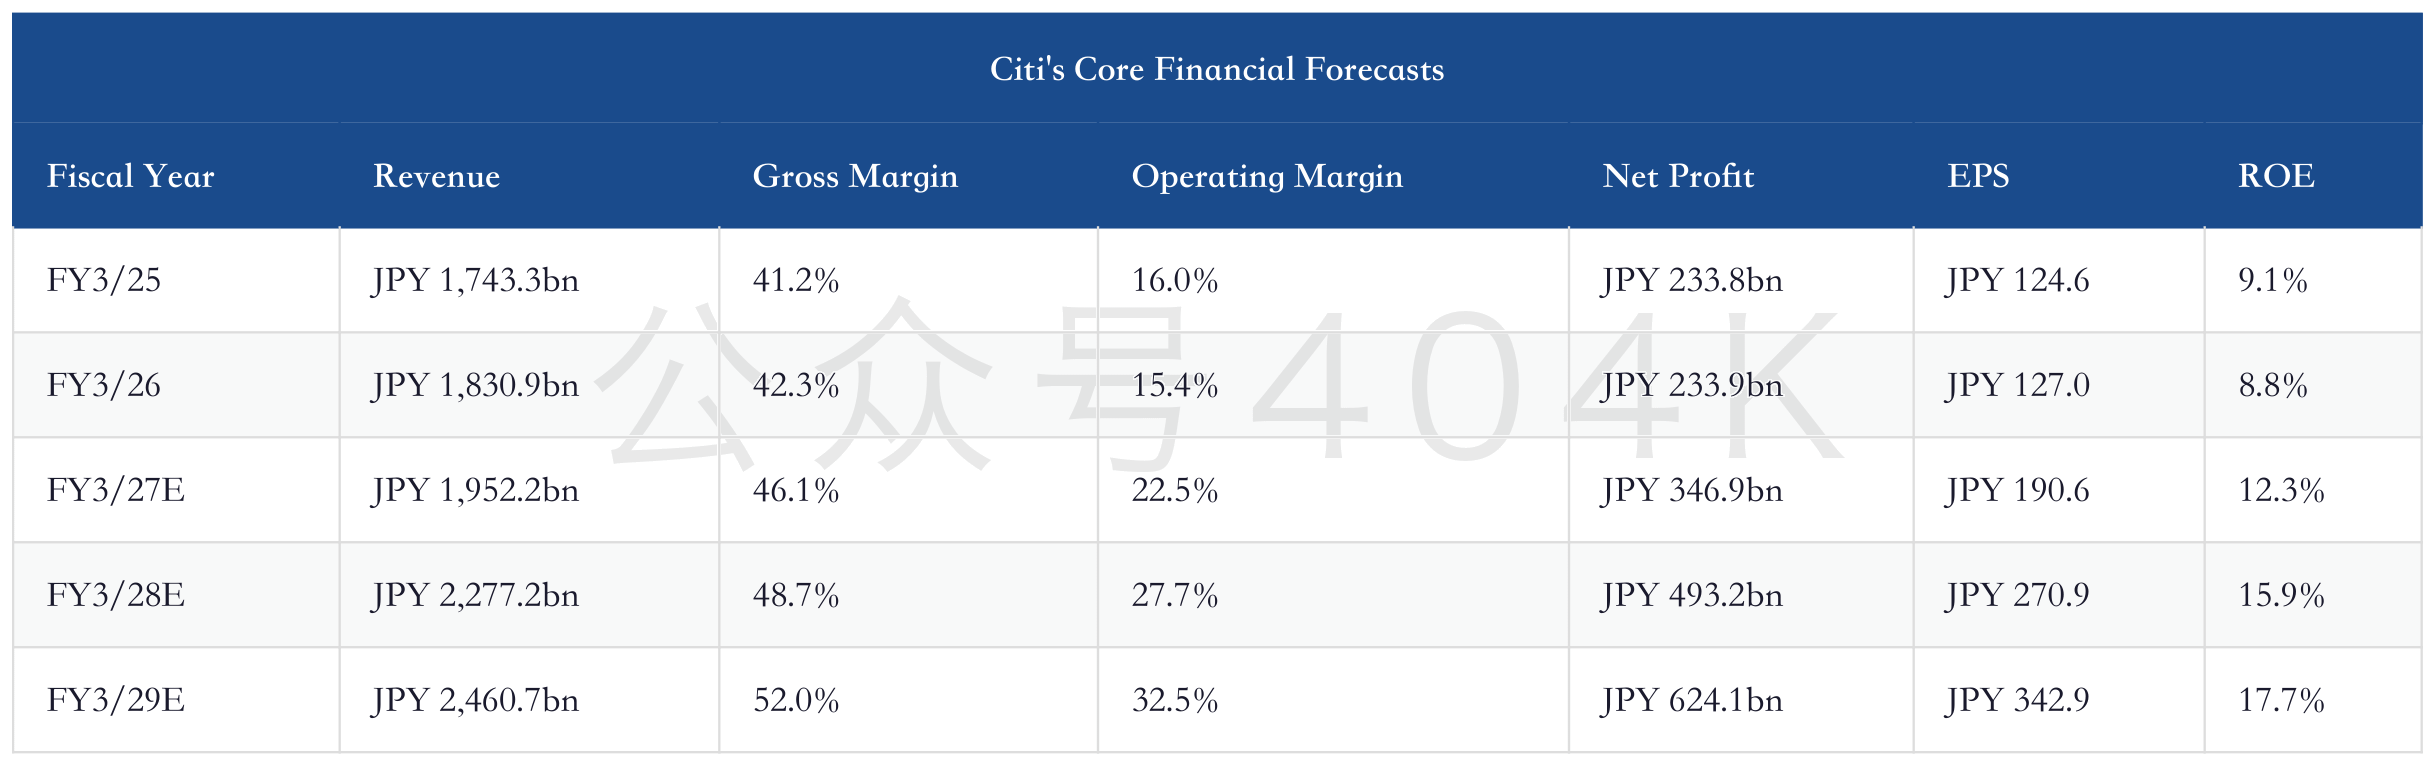
The key point in this table is the margin step-up; revenue growth is only the underlying variable. Revenue continues to grow from FY2026 to FY2029, but gross margin and operating margin rise faster. Operating margin increases from around 15% to above 32%, indicating the model assumes Murata sells more high-value MLCC and shifts its mix from ordinary specifications toward higher-margin, higher-barrier high-capacitance specifications.
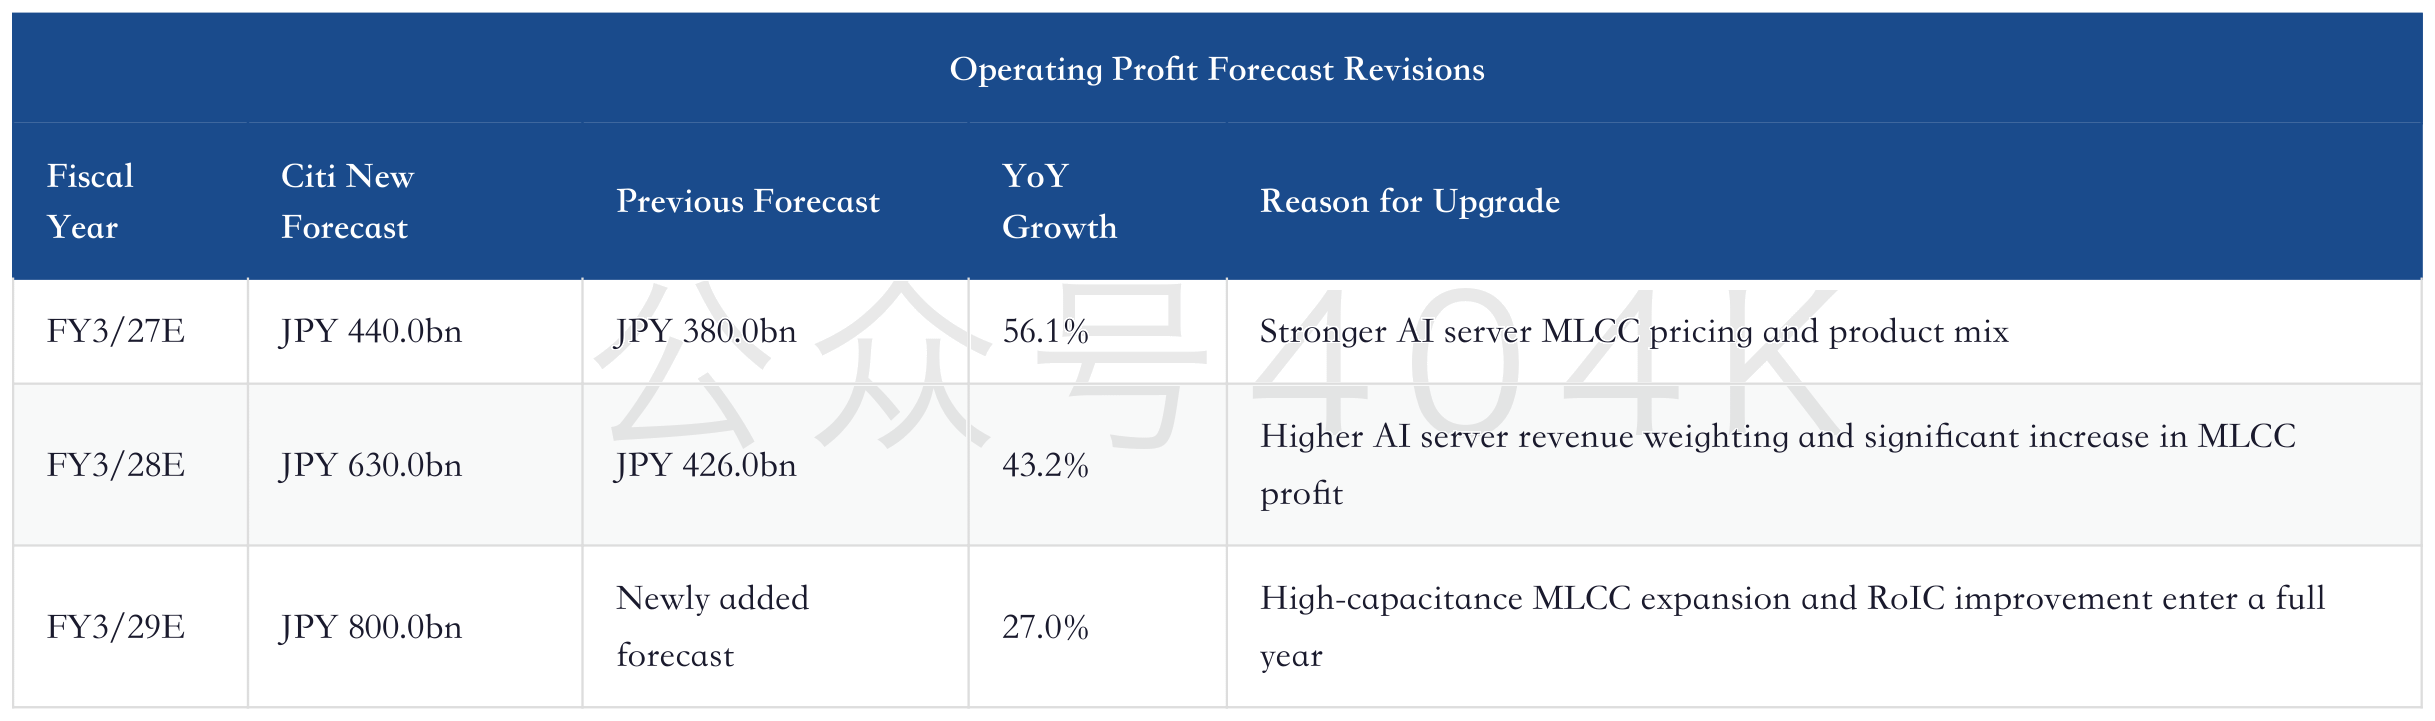
Citi also raised its FY2027 assumption for yen-denominated MLCC ASP improvement from single digits to double digits. Three variables sit behind this: stronger AI server MLCC pricing assumptions, reduced price-decline pressure in consumer MLCC, and more favorable FX assumptions. FX also needs to be placed inside the validation framework. Murata reports profit in yen, so USD/JPY movements will amplify or weaken overseas revenue and profit elasticity. Not all gross-margin improvement can be attributed to product strength.
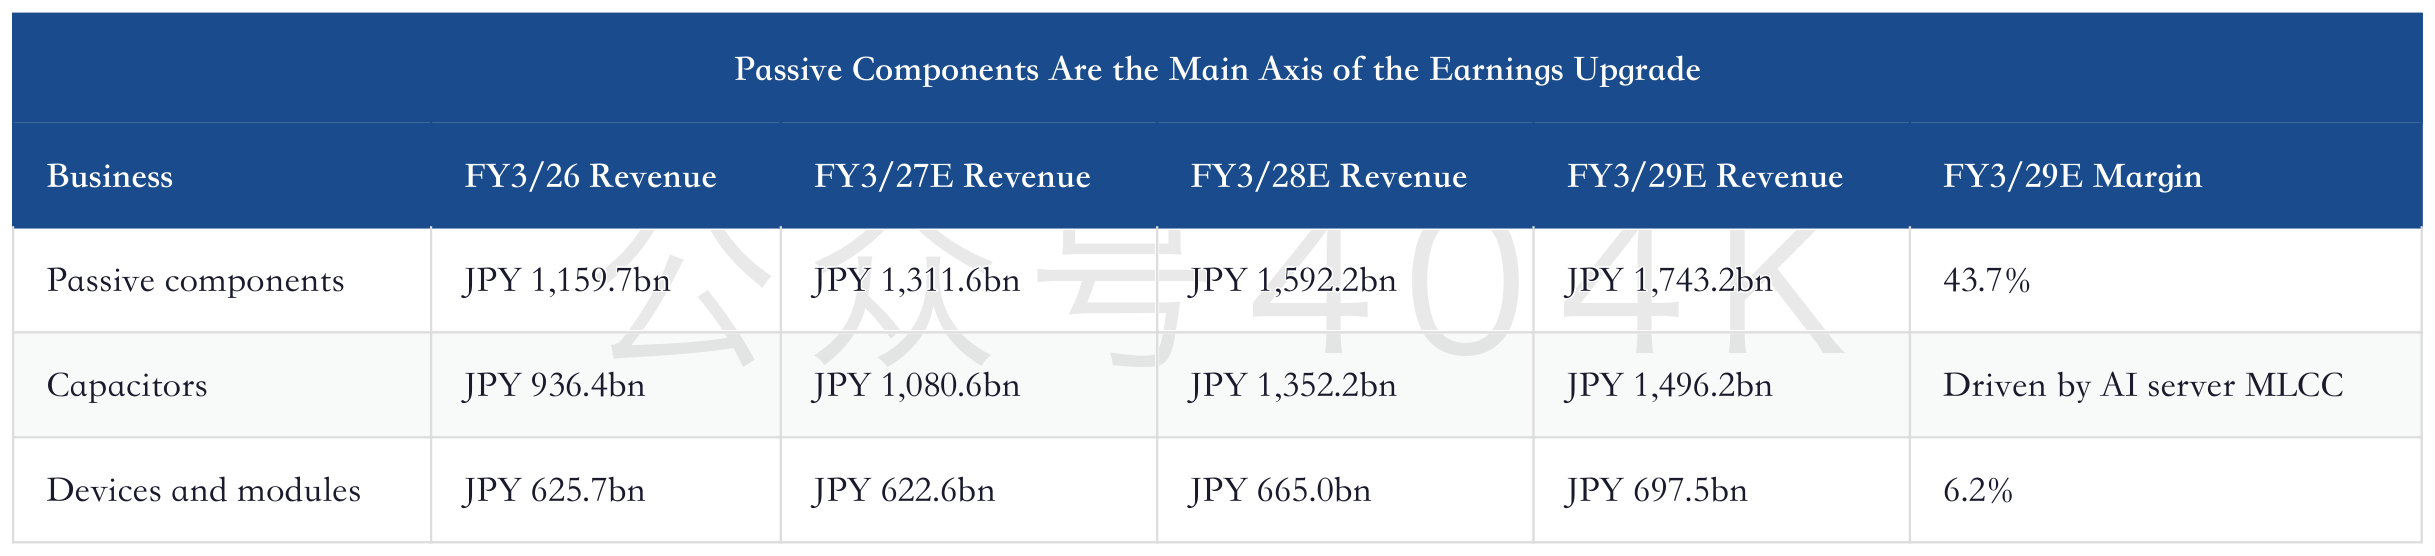
The structure is clear. Recovery in devices and modules from losses or low profitability can improve the floor, but the main re-rating line remains passive components, especially capacitors. Citi assumes roughly JPY 200.0bn of additional MLCC operating profit in FY2028 and raises the AI server-related weighting to a higher level. That is the core acceleration in the income statement.
5. Pricing Discipline: Murata Wants High-End Mix-Led Price Increases
The easiest mistake in MLCC investing is to treat every price increase as good news. When standard MLCC supply is tight, broad price hikes can quickly lift profit, but they also stimulate competitor expansion and compress leaders' long-term share. The higher-quality route for Murata's re-rating is high-end product-mix-led pricing. Supply-demand price hikes in ordinary products are better observed as an upside scenario.
Citi notes that Murata's book-to-bill ratio reached 1.36 in January to March 2026, a ten-year high. That number naturally leads the market to expect price increases. At the same time, Citi also notes that the company remains cautious on company-led supply-demand price adjustments for ordinary products. Taiyo Yuden management has also publicly said it will pass through materials costs but has no plan for additional price hikes due to tight supply-demand. The attitude of industry leaders shows that the current price-increase logic still has boundaries.
The 2018-2019 MLCC cycle is worth reviewing. At that time, smartphone multifunctionality and automotive electronics lifted demand, and the industry went through a round of price increases. Trade frictions, economic slowdown, and channel inventory accumulation subsequently pressured prices. Murata's AI server opportunity today is stronger, but the historical lesson has not disappeared. As soon as price increases spread to too many ordinary categories, inventory, substitution, and competitor expansion will appear together.
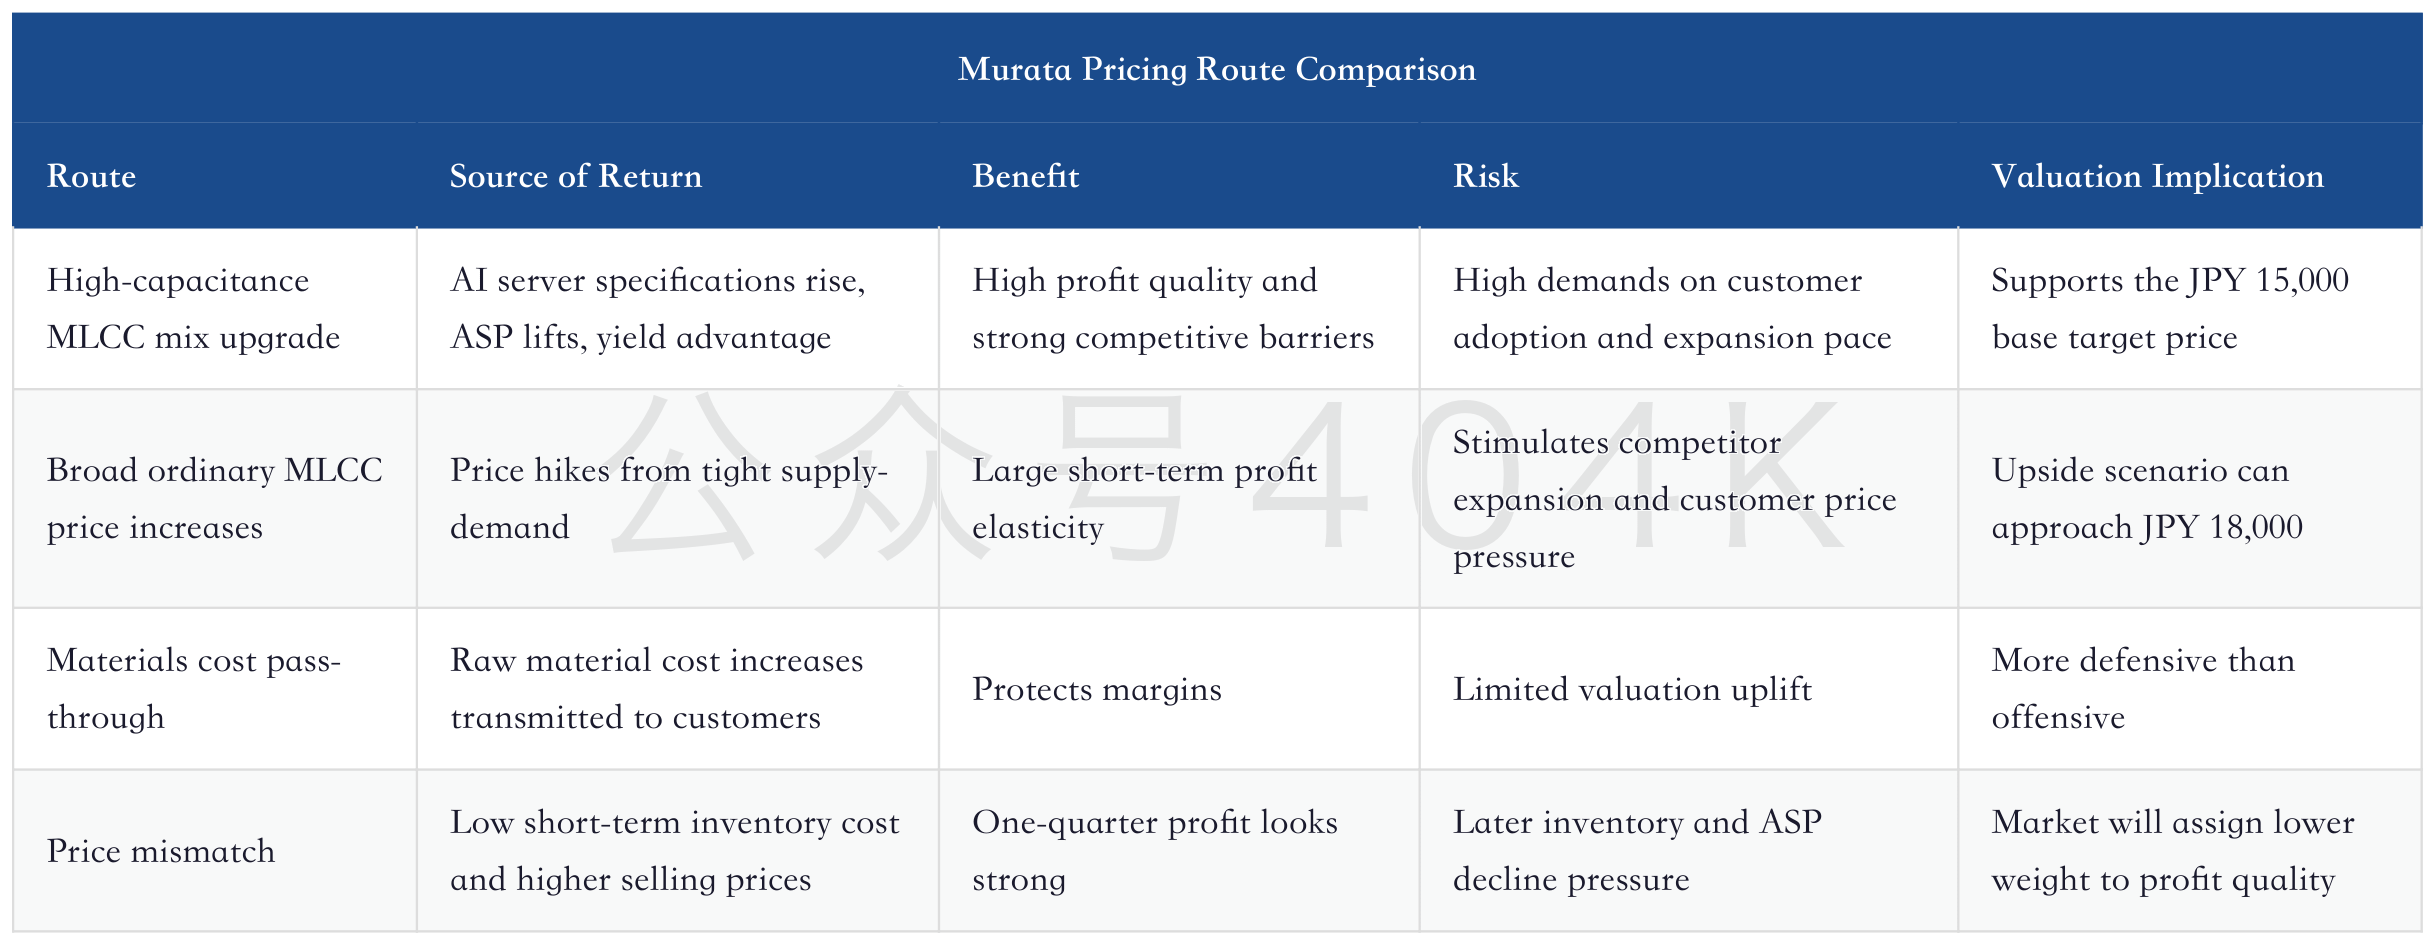
This is one of the most important points in the report. Citi does not treat broad price increases as the base assumption, but places them in scenario analysis. The base target price depends on mix upgrade, while the optimistic upside depends on industry-wide price increases. If Murata later appears to rely mainly on ordinary-product price hikes, while high-capacitance MLCC share, yield, and customer qualification do not improve together, the quality of JPY 15,000 would decline. If high-capacitance mix upgrade continues to be delivered, ordinary-product prices only need to remain stable for the base target price to have stronger support.
6. RoIC-WACC Valuation: JPY 15,000 Requires Murata to Become a High-Capital-Efficiency Asset
Citi prices Murata using a RoIC-WACC framework, which explains this upgrade better than a simple PE multiple. MLCC is a capital-intensive business. Capacity expansion requires investment in equipment, materials, sintering, inspection, and yield management. Valuation can keep moving higher only when incremental capital generates higher returns. The investment significance of AI server high-capacitance MLCC is precisely that the same production line, materials system, and customer qualification can generate higher profit and higher returns on capital.
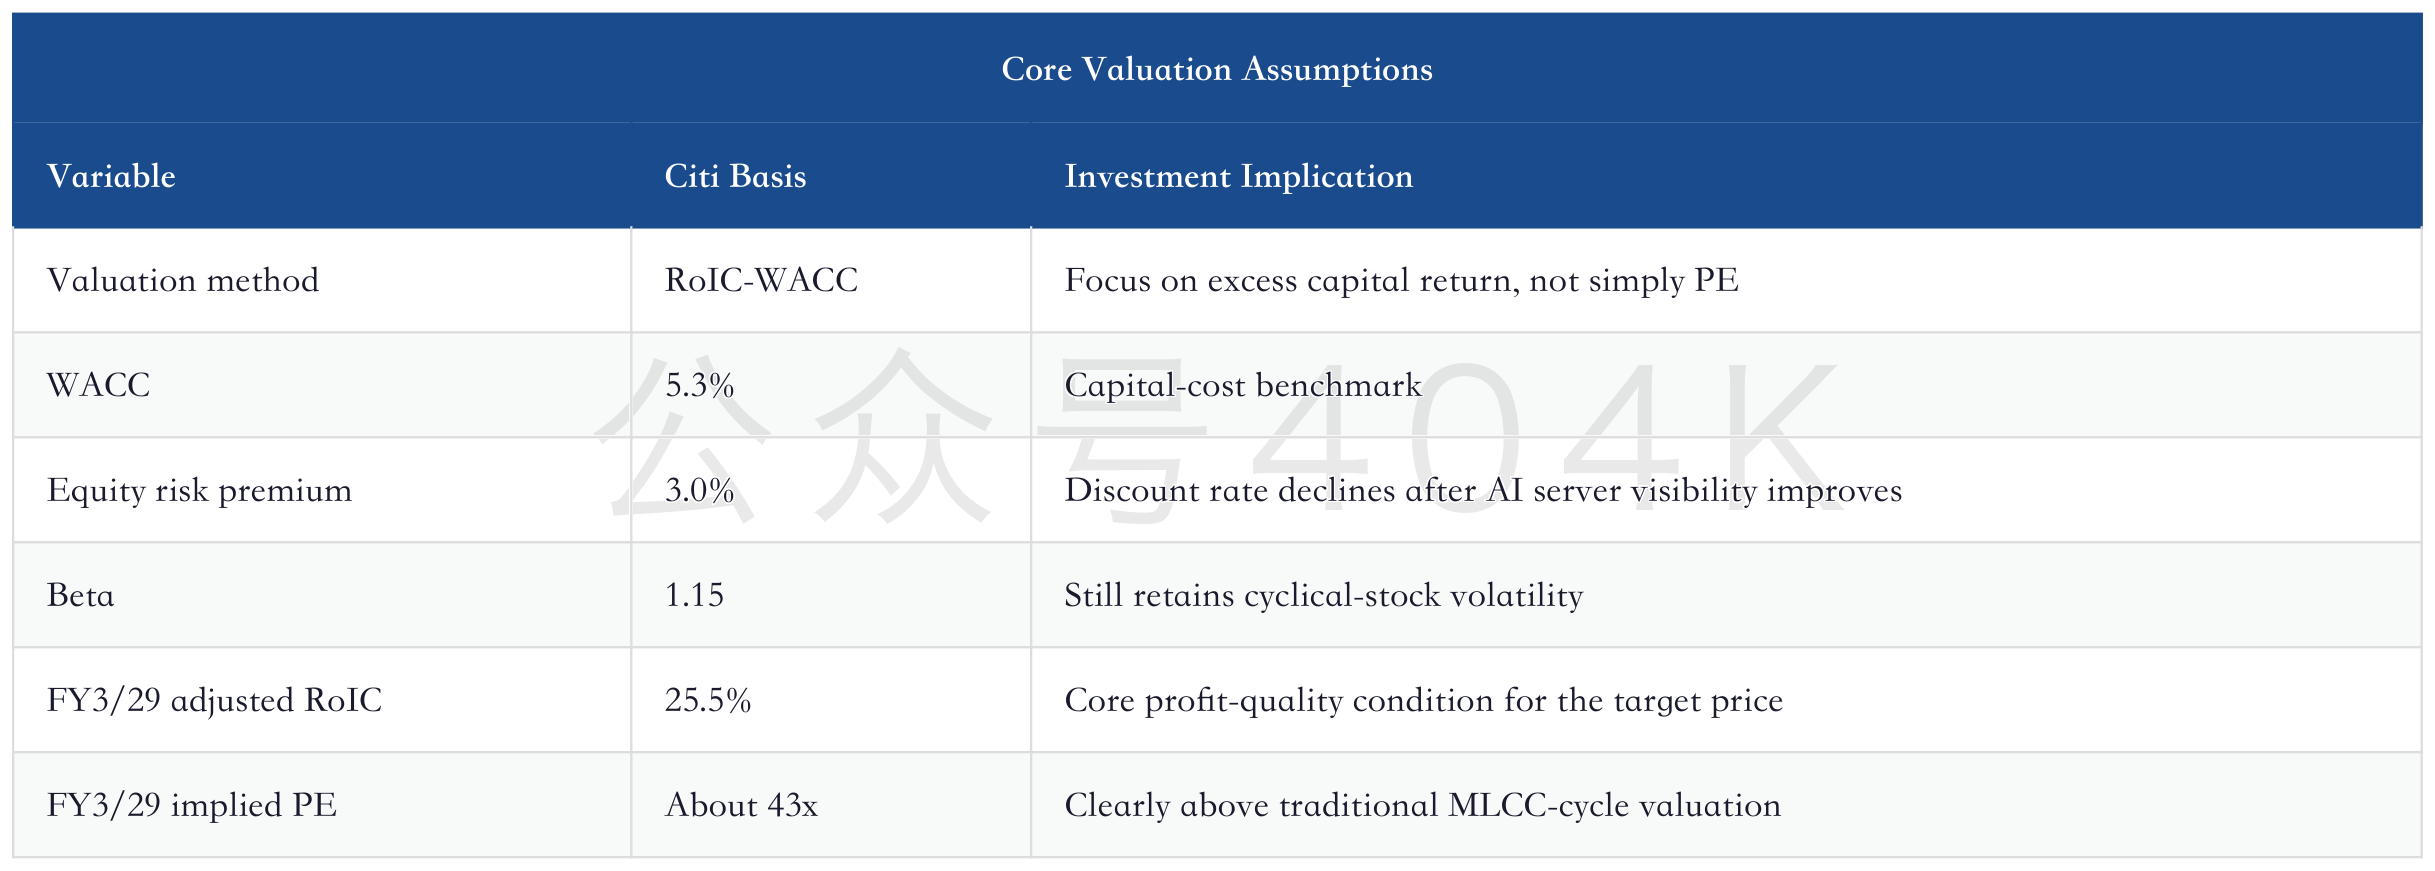
This valuation is not cheap. Citi itself acknowledges that the target price implies a PE above Murata's historical high range. For the market to accept this premium, it must see sustained RoIC improvement, not merely EPS upgrades. EPS can be amplified by FX, inventory, and short-term price increases; RoIC requires margins, capital turnover, and expansion discipline to work together.
The RoIC path can be understood as follows. In FY2027, AI server MLCC enters the income statement, and Murata moves from ordinary cyclical recovery to margin expansion. In FY2028, the revenue weighting of high-capacitance MLCC rises and operating margin continues to improve. In FY2029, expansion, yield, and product mix form a full-year contribution, pushing RoIC into the 25%+ range. As long as this path holds, the JPY 15,000 target price goes beyond PE expansion and becomes a capital-efficiency re-rating.
There is also valuation risk here. A roughly 43x FY2029 PE is already high for a traditional electronic-components company. If AI server MLCC demand slows, customers start pressing prices, 100uF high-capacitance product adoption is slow, or expansion yield falls short of expectations, the market will first compress the valuation multiple and then reduce earnings forecasts. Murata's valuation elasticity is large, and so is its downside elasticity.
Japan Electronic Components Deep Update: High-Value AI Data Center Component Expansion and Valuation Discipline for Murata, TDK, and Ibiden
7. Murata's Capability Migration: From Cyclical Leader to AI Server Power-Supply Materials Platform
Murata Manufacturing's legacy strengths are scale, materials, yield, and customer coverage. In the smartphone era, it built advantages through miniaturization, high reliability, and large-scale supply capability. In the automotive electronics era, it extended product life cycles through automotive-grade qualification and high reliability. In the AI server era, it needs to migrate these capabilities into high-capacitance MLCC with higher capacitance, higher power, and higher stability requirements.
This migration is harder than ordinary capacity expansion. AI server customers want continuous supply, specification iteration, reliability, and co-development capability. The challenge of high-capacitance MLCC is not merely making capacitance larger. It involves ceramic powder, dielectric thin-layering, internal electrodes, stacking, sintering, inspection, and failure-rate management. The higher the capacitance, the greater the layer count, the narrower the process window, and the more sensitive the yield. If Murata can maintain high yield on the 100uF path, it will convert materials and process capability into margin.
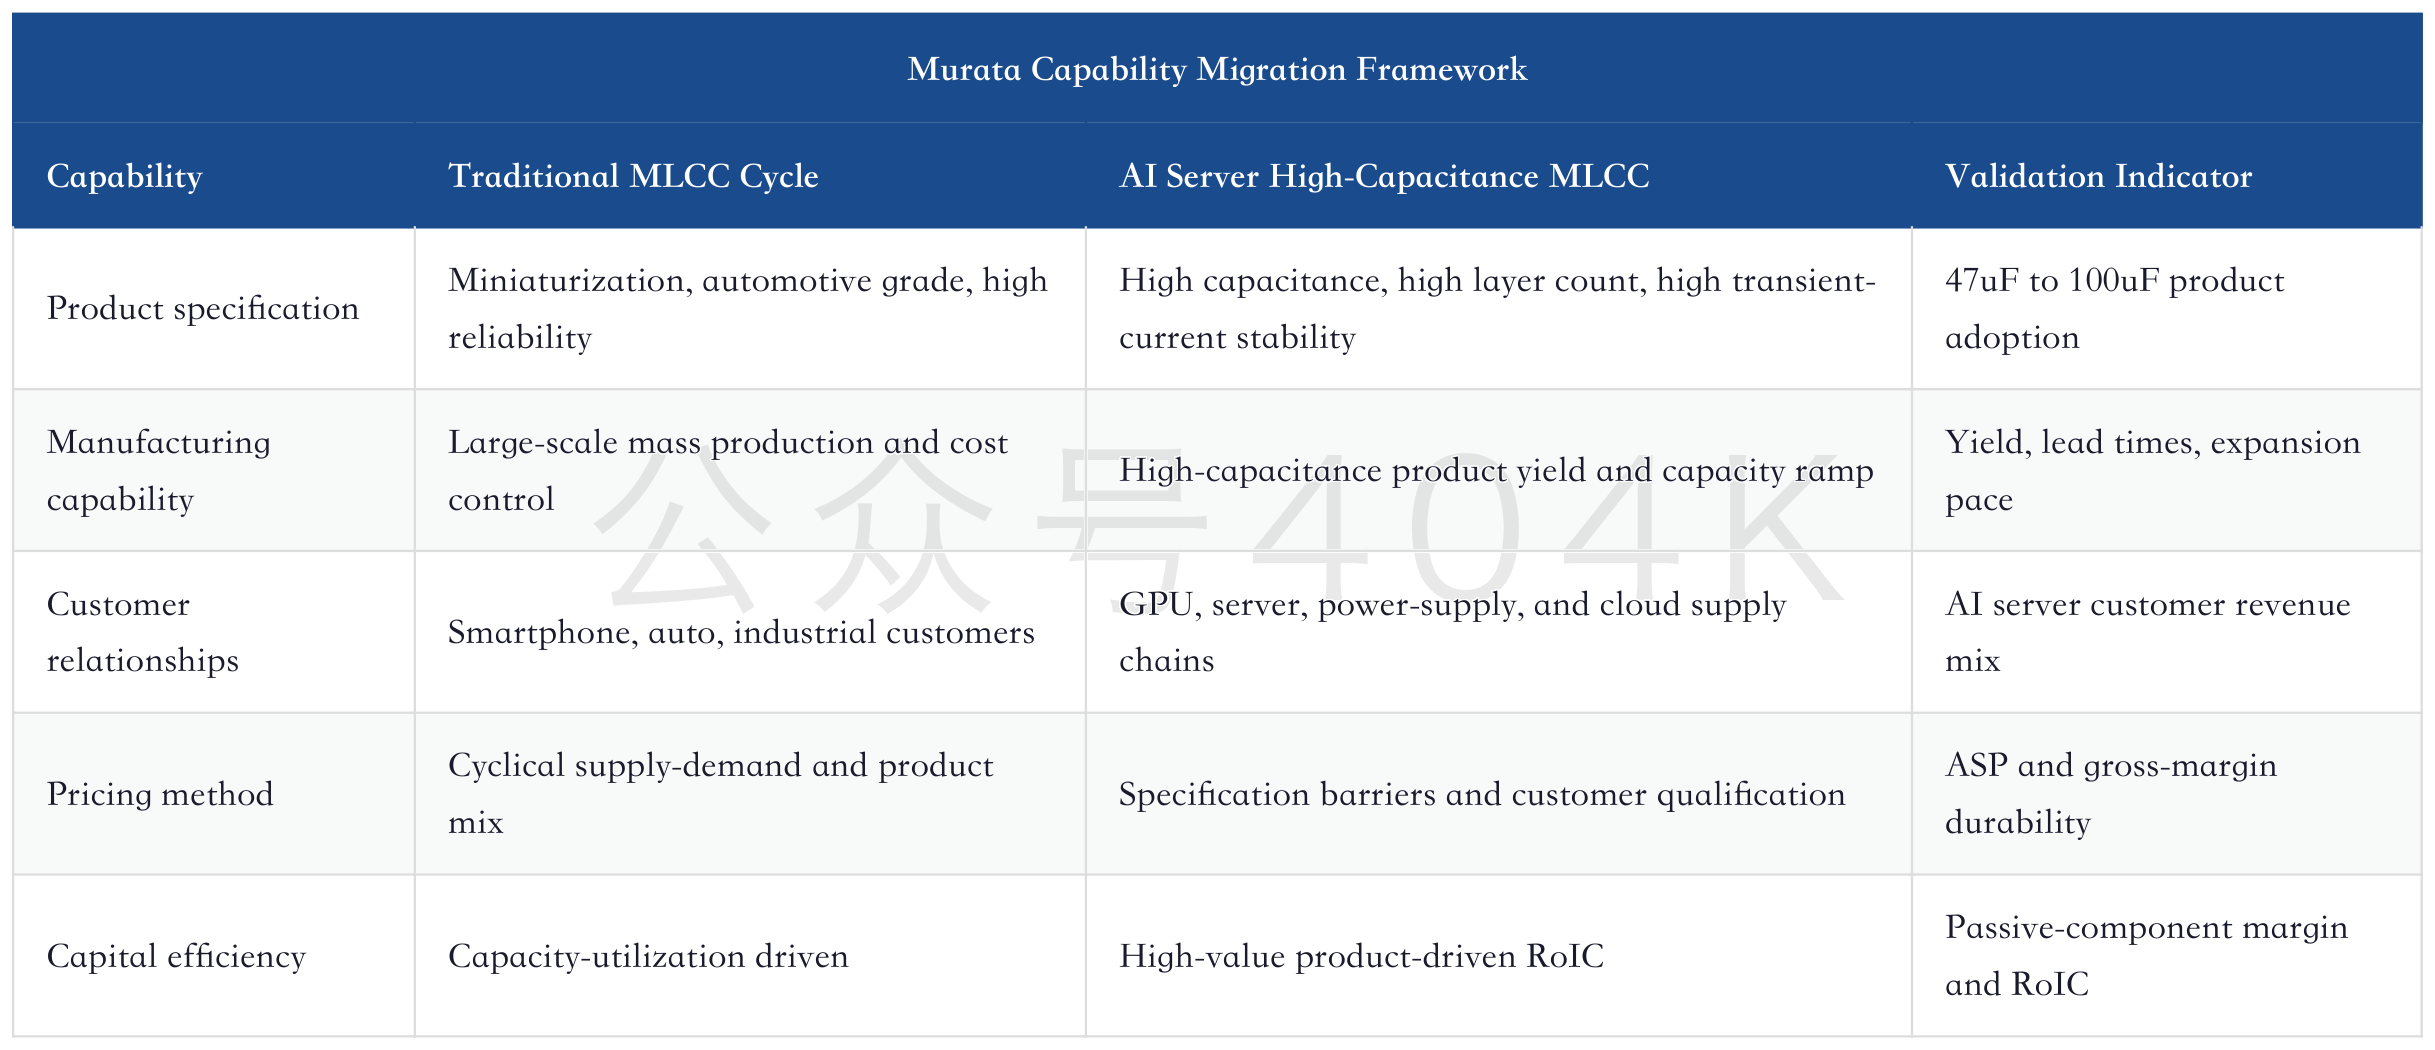
This migration also explains why Murata can receive a higher valuation than ordinary MLCC companies. Ordinary MLCC price increases are about supply-demand; high-capacitance MLCC re-rating is about capability. Murata's share advantage comes from yield and materials capability, while short-term pricing behavior is only an auxiliary variable. Citi estimates Murata's share in high-capacitance AI server MLCC at about 50%, which means it sits in the first tier of the most difficult product layer.
Of course, 50% share also brings higher expectations. The market will require Murata to deliver high-capacitance products more consistently than peers such as Samsung Electro-Mechanics and Taiyo Yuden. If competitors catch up in yield, Murata's share and price premium will both face pressure. If customers intentionally support second suppliers for supply-chain security, Murata may still retain a leading share, but excess margin could be diluted.
8. Peer Comparison: Murata Captures Specifications, Samsung Electro-Mechanics Captures Elasticity, Taiyo Yuden Captures the Cycle, and Yageo Captures Inventory and Channels
Peer comparison in the MLCC industry cannot be ranked only by "who raises prices more." Different companies have different product tiers, customer structures, inventory positions, and expansion capabilities. Murata's core is high-end AI server and high-capacitance MLCC. Samsung Electro-Mechanics also has high-end capability, but its profit elasticity and group supply-chain position differ. Taiyo Yuden is more affected by the ordinary MLCC cycle and capacity utilization. Yageo has its own elasticity in channels, M&A;, and industrial customers.
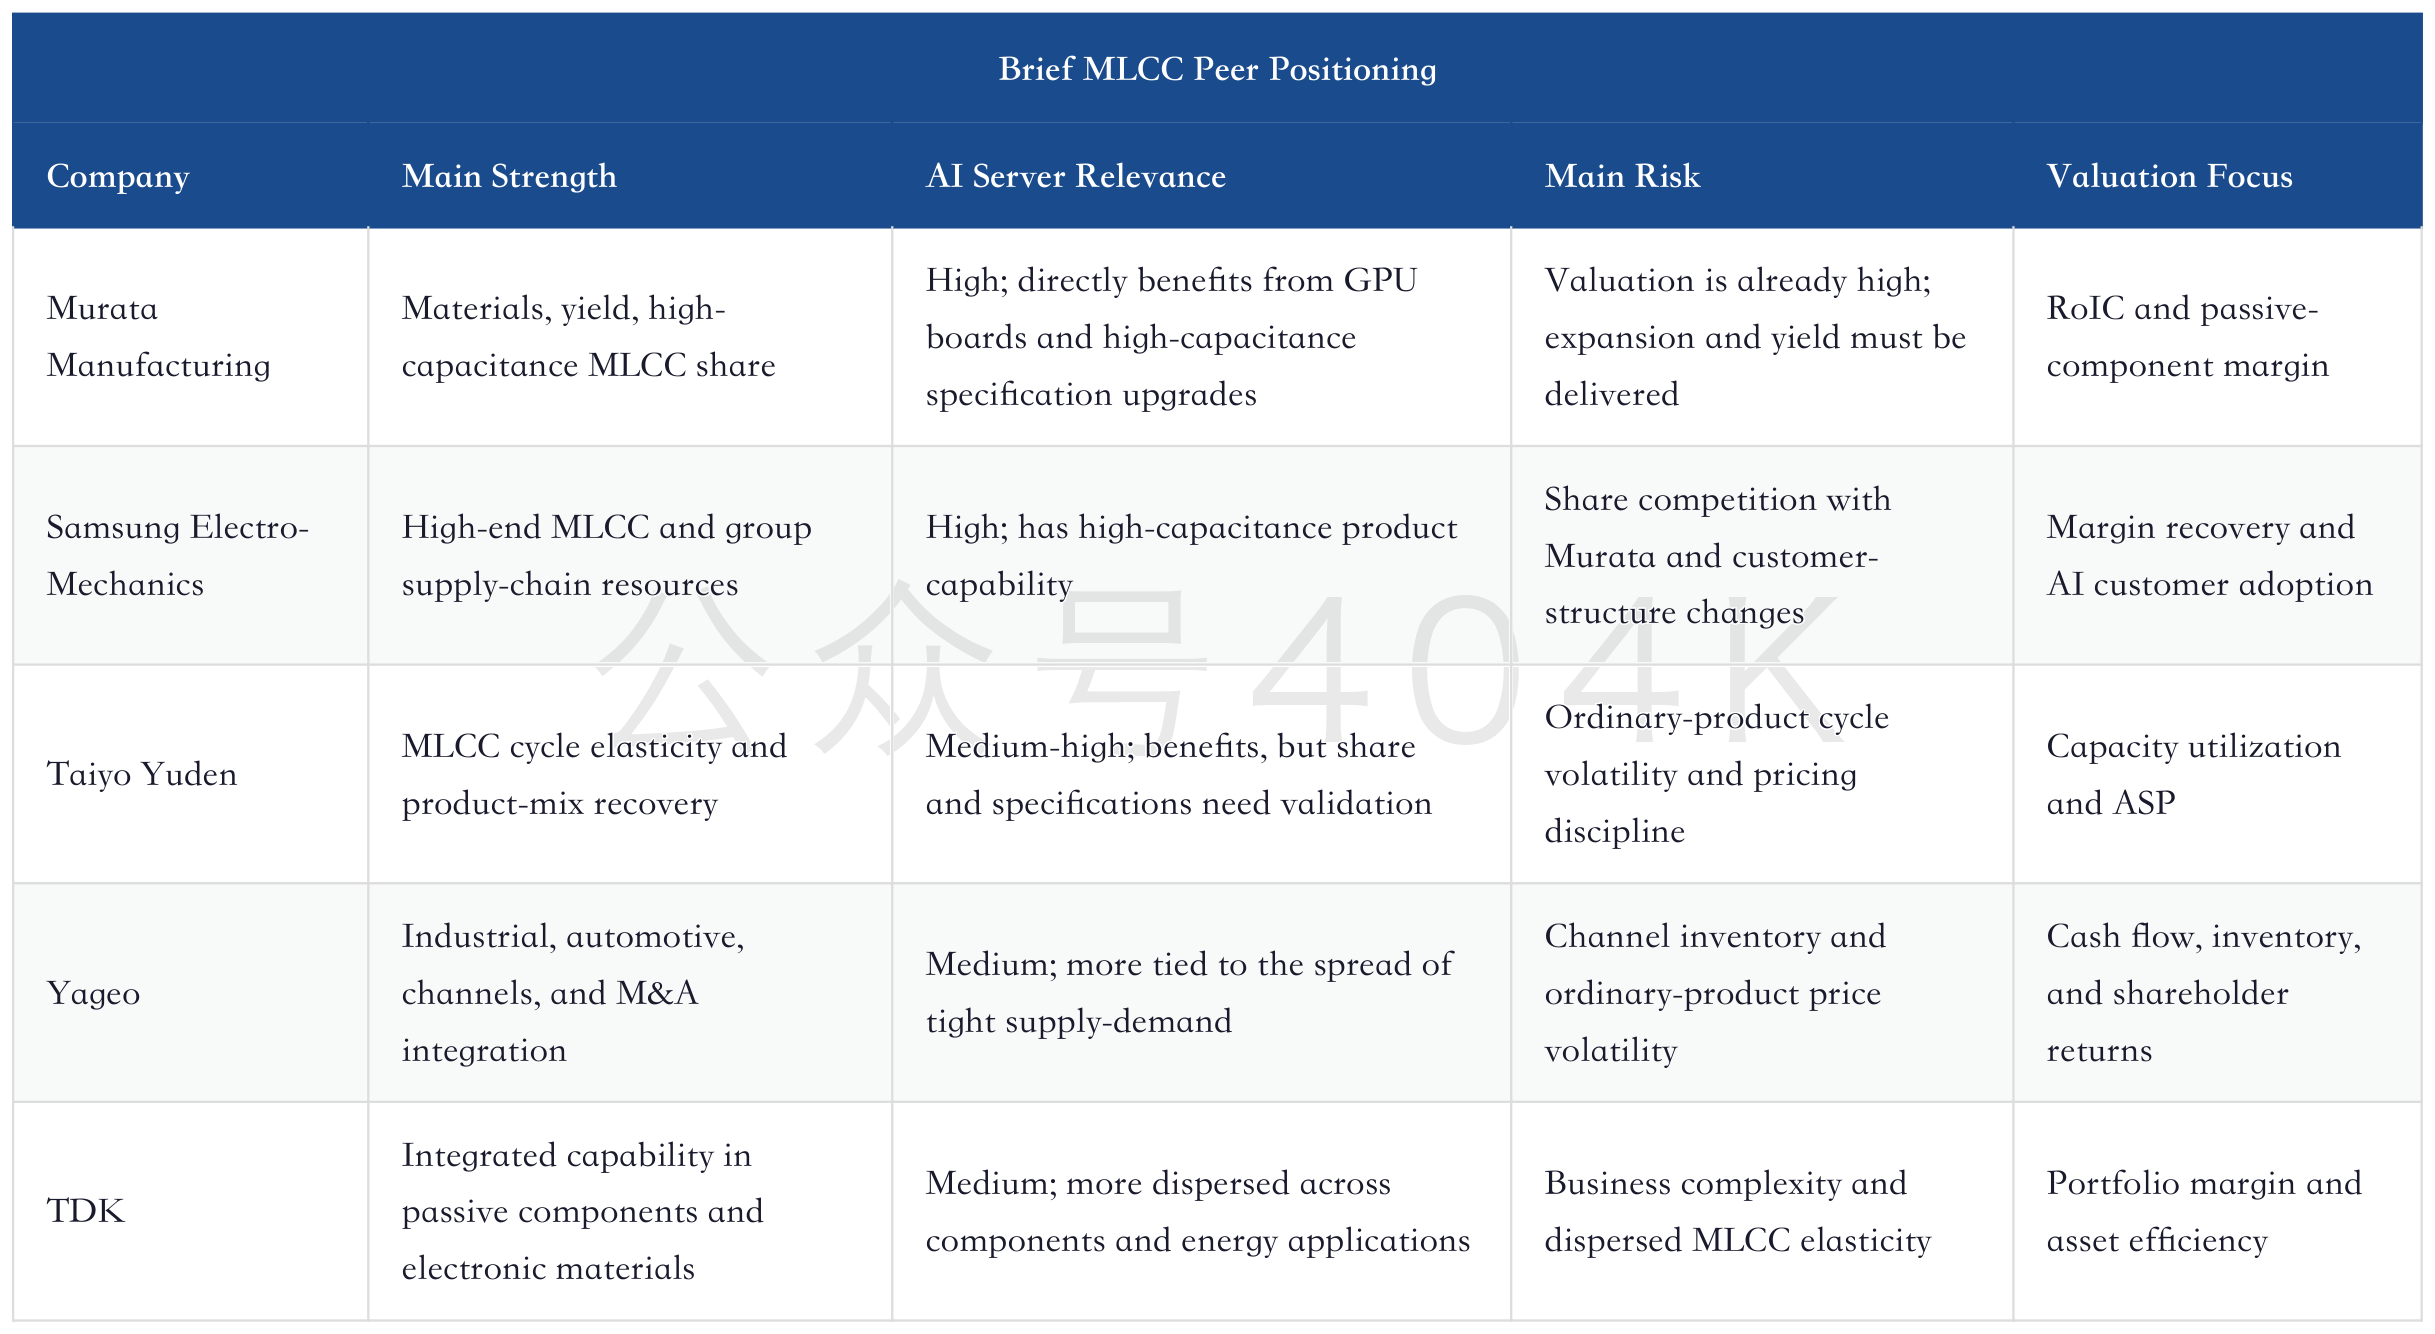
The conclusion from this table is direct: Murata is not cheap in an MLCC price-increase trade, but it is the clearest target for high-end specification upgrade. Cheap companies need to prove cyclical upturn; high-end companies need to prove barrier realization. Citi's higher target price for Murata is effectively a bet that profit quality in high-capacitance MLCC is stronger than ordinary MLCC price increases.
MLCC Deep Dive: JPMorgan's Sharp Upgrade, from Cyclical Recovery to Structural Re-rating as AI Servers Rewrite the Supply-Demand Gap
From the supply-chain perspective, the AI server materials chain has already seen two types of re-rating. One is "physical interconnect constraints" such as ABF substrates, PCB, CCL, and connectors. The other is "power stability constraints" such as MLCC, power management, and magnetic components. Murata belongs to the second category. It does not determine compute power directly like GPUs, nor package area like ABF, but it determines whether high-power systems can operate stably. This position is not conspicuous, but it is hard to bypass.
9. Relationship with ABF and PCB: The AI Server Materials Chain Spills Over from Main Chips to the Power Layer
The re-rating sequence in the AI server supply chain previously began with GPU and HBM, then moved to packaging, ABF substrates, PCB/CCL, thermal management, and power. The MLCC re-rating came later because its value share in the system is not high, and the market easily treats it as an ordinary passive component. But as GPU board power consumption, power density, and transient current continue to rise, MLCC begins to move from a "low-presence component" to a "high-reliability power-supply material."
This spillover path has three stages. In the first stage, AI server shipment growth drives growth in MLCC units per system. In the second stage, GPU board current and power consumption rise, the mix of high-capacitance MLCC increases, and ASP and gross margin begin to improve. In the third stage, customers incorporate high-capacitance MLCC into long-term supply security, and leading companies obtain a longer profit cycle through qualification, yield, and expansion. Murata is now positioned in the migration from the second stage to the third stage.
The Second Re-rating of the AI Server Materials Chain: From Passive Components to PCB/CCL, ABF Substrates, and Test Equipment
Compared with ABF and PCB, MLCC is characterized by low value per unit, large aggregate volume, and fine specification stratification. ABF substrates are often driven by a single project, customer, or product generation, while MLCC is dispersed across many board and power-supply scenarios. This difference makes MLCC revenue recognition smoother and demand validation harder. Investors cannot look only at the launch date of a single GPU platform. They also need to watch AI server system shipments, board design, customer qualification, and supplier share.
Murata benefits from exposure to AI servers while retaining a base in automotive, industrial, and consumer electronics. The risk is that valuation will capitalize the AI server contribution first, while any inventory or pricing pressure in ordinary businesses will lower overall profit quality. This mix makes Murata steadier than a single AI materials company, but more expensive than an ordinary MLCC cyclical stock.
10. Three Scenarios: JPY 15,000 Is the Base Case, JPY 18,000 Requires Broad Price Increases, and the Stress Case Depends on Inventory and Yield
Citi's JPY 15,000 target price can be viewed as the base case. The core conditions are high growth in AI server MLCC, product-mix improvement, higher passive-component margins, and RoIC uplift. JPY 18,000 is closer to an upside scenario and requires ordinary MLCC to see broad price increases of more than 10%, without triggering excessive expansion or customer substitution. The stress case comes from the reverse combination of price, inventory, expansion, and competition.
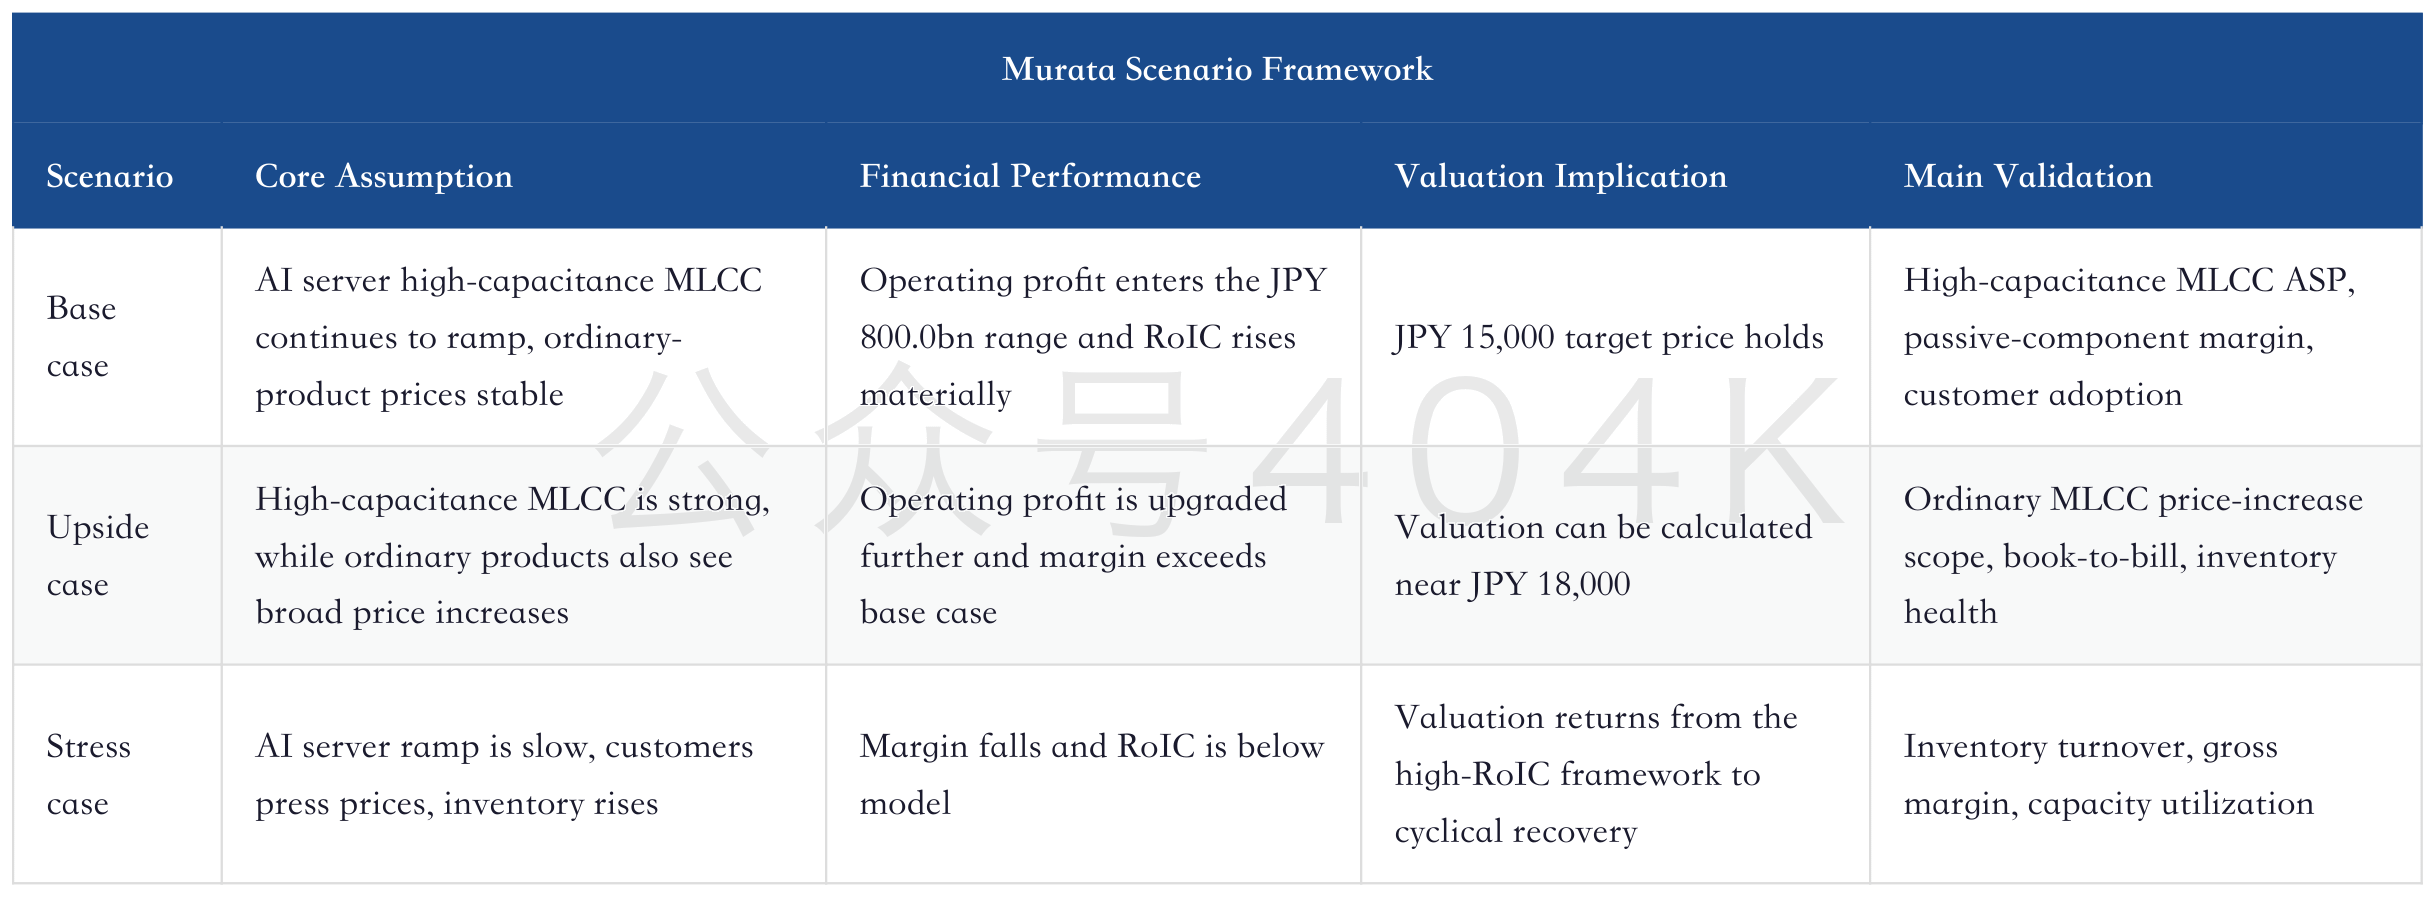
The base case and upside case should not be mixed together. JPY 15,000 requires delivery of high-end mix upgrade, while JPY 18,000 requires broader industry price increases. If future evidence shows only ordinary-product price increases, without more evidence of high-capacitance MLCC specification upgrade and customer qualification, the market will suspect this is merely an ordinary cyclical rally. If high-capacitance MLCC keeps expanding while ordinary-product prices remain stable, the base case is healthier.
The key in the stress case is that profit quality falls short of expectations. For example, slow yield ramp in high-capacitance products could keep costs above model assumptions. Customers could introduce more suppliers to reduce risk, lowering Murata's share. Inventory in ordinary consumer and automotive MLCC could rise again, dragging overall margins. FX could shift from favorable to unfavorable, amplifying profit volatility. All of these variables would first pressure the high valuation.
11. Data Framework: In the Next Stage, Look First at Order Quality, Then Profit Quality
Murata's follow-up validation cannot look only at revenue growth. In an AI server cycle, revenue growth may come from genuine demand, but also from customers pre-building inventory. ASP increases may come from specification upgrade, but also from short-term supply-demand tightness. Gross-margin improvement may come from high-capacitance products, but also from FX and low-cost inventory. To judge the quality of the JPY 15,000 target price, orders, pricing, margins, inventory, and capital expenditure need to be linked.
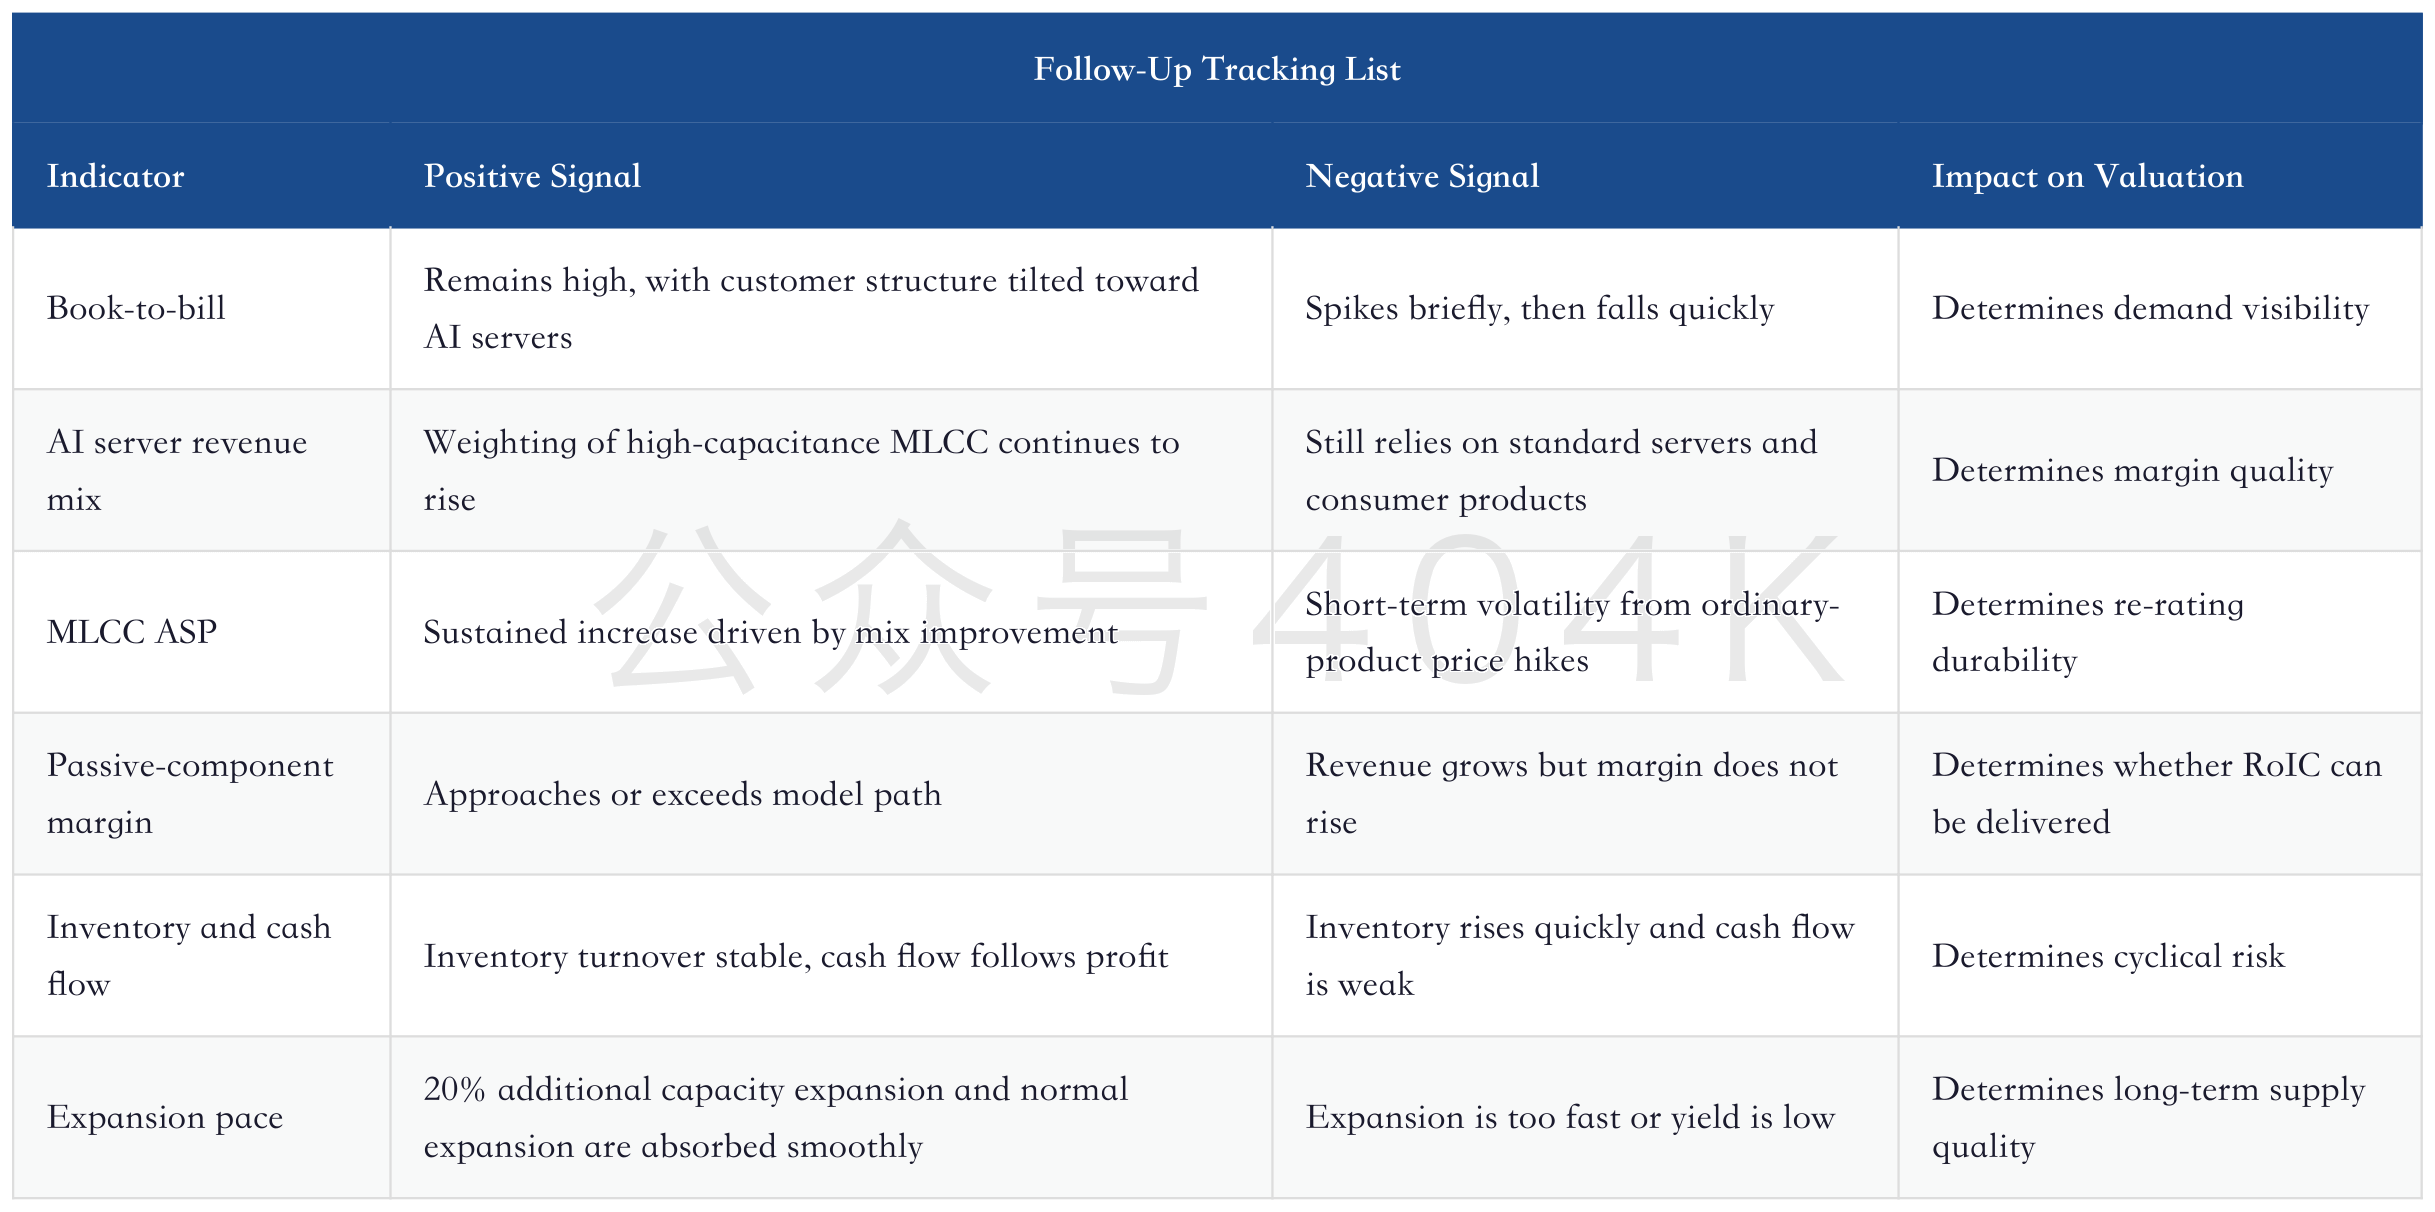
This sequence matters. Orders lead, ASP and gross margin then confirm, while inventory and cash flow reveal risks last. If orders, ASP, and gross margin are strong while inventory and cash flow are healthy, the market will be more willing to believe Murata has entered a new profit step. If orders are strong but inventory also rises quickly, or if revenue is strong but gross margin does not rise, the market will first mark down the high valuation.
Citi's book-to-bill figure of 1.36 is attractive, but it is only the starting point. The real validation is whether orders can convert into high-capacitance MLCC revenue, whether revenue can convert into gross margin, and whether gross margin can convert into RoIC. Murata has repeatedly experienced supply-demand mismatches in the ordinary MLCC cycle. AI servers improve demand quality, but they do not eliminate cyclical risk.
12. Why Citi Is More Aggressive Than the Previous Market View: It Turned "Higher Server Specifications" into Income-Statement Assumptions
Research on Murata and MLCC has moved from "AI drives MLCC demand" to "AI server high-capacitance MLCC changes profit distribution." Citi's update further writes that judgment into earnings forecasts: stronger AI server MLCC pricing assumptions, higher AI server-related weighting in FY2028, a larger operating profit upgrade, and RoIC valuation based on a later year.
Murata Manufacturing Deep Update: AI Server MLCC's Profit Gate and Valuation Discipline
The more aggressive assumptions are mainly in three areas. First, Citi places more weight on server specification upgrades; AI server unit growth is only the base variable. Second, Citi places more emphasis on the yield barrier for high-capacitance MLCC, believing Murata's share and margins can be sustained for longer. Third, Citi is willing to use a lower risk premium and a later valuation year, showing it believes this round of profit improvement has a chance to last for multiple quarters.
These aggressive assumptions are also easier to falsify. If MLCC usage per AI server does not continue to rise, or 100uF product progress is slow, ASP improvement will be weaker than the model. If peers such as Samsung Electro-Mechanics and Taiyo Yuden catch up faster in high-capacitance product yields, Murata's share may fall below the roughly 50% assumption. If ordinary consumer and automotive MLCC drag overall margins, the AI server contribution will be diluted. Citi's high target price means it needs more positive feedback.
13. Historical Positioning: What Really Makes Murata Valuable Is Turning Materials Capability into Customer Standards
Murata Manufacturing's long-term advantages in the MLCC industry are in-house materials development, process control, miniaturization, reliability, scale manufacturing, and customer co-development. AI servers place these capabilities into a higher-value application scenario.
MLCC looks like a standardized component, but high-end products are not standardized. In high-reliability scenarios, customers do not compare only price. They also compare failure rates, lead times, long-term supply capability, and design support. Murata's entry into the core high-capacitance MLCC supply chain for AI servers shows that its materials and manufacturing capabilities have been incorporated into customers' system designs. Once this position is formed, replacement costs are higher than for ordinary MLCC.
This is the core of the "asset-attribute change." In the past, Murata was a high-quality cyclical stock, with profit fluctuating with smartphone, automotive, and industrial demand. AI servers add a layer of power-supply materials platform attributes: Murata does not directly sell compute power, but it sells high-reliability power-supply components required for stable operation of compute systems. This change raises the margin ceiling, and also increases valuation volatility.
Murata still needs to manage legacy businesses. Consumer electronics demand, automotive electronics inventory, industrial customer recovery, and FX all affect total profit. High-end AI server MLCC can lift valuation, but it cannot fully shield the traditional cycle. What investors really need to watch is whether high-end mix improvement is large enough to offset volatility in ordinary businesses.
14. Risk Breakdown: Under a High Valuation, Any Failed Validation Link Will Be Amplified
The JPY 15,000 target price gives the market high expectations. Risks should be judged by the same high standard. Murata faces the risk of validating multiple variables at the same time. AI server MLCC demand, ASP, yield, expansion, inventory, FX, ordinary businesses, and the competitive landscape will all affect valuation if any one is materially below the model.
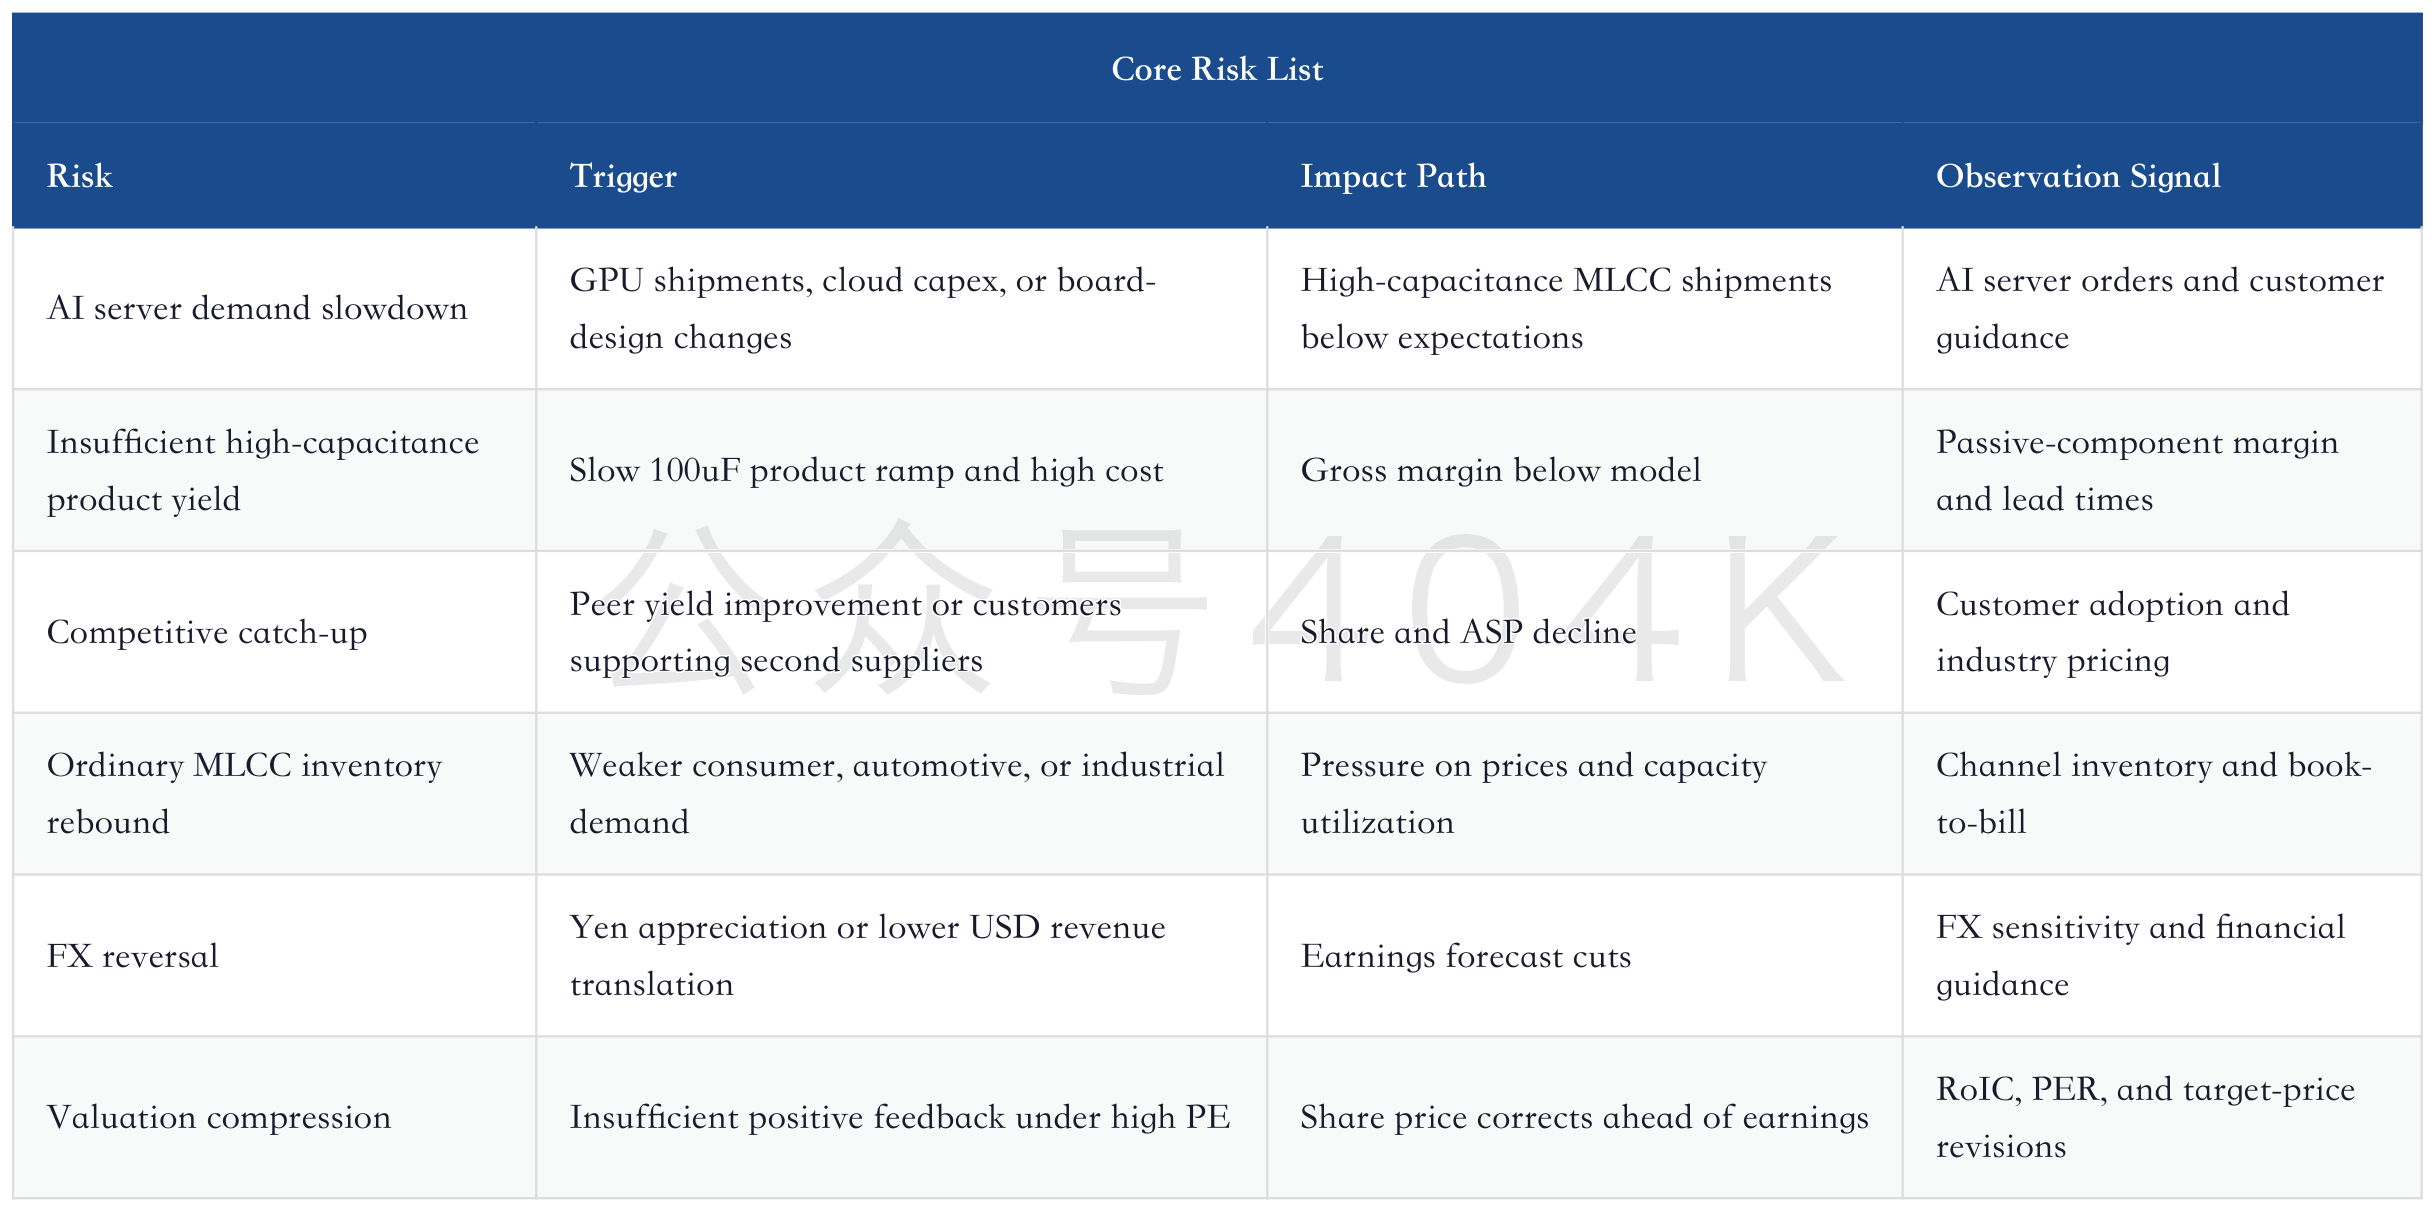
The common point across these risks is that they affect valuation before earnings. Market pricing for high-valuation stocks is more sensitive, and investors do not necessarily wait for the income statement to deteriorate materially before adjusting expectations. A decline in book-to-bill from a high level, slower-than-expected customer adoption, inventory growth, or gross margin below model could all make the share price react first.
Murata's strengths are strong capabilities, high share, and good customer stickiness. Its weakness is that valuation has already discounted a great deal of future success. This combination is best tracked through an "evidence-weighted" approach: each quarter that adds a high-quality piece of evidence makes JPY 15,000 more stable; each quarter that produces counter-evidence on profit quality lowers the valuation weight.
15. Linkage with Previous MLCC Reports: Industry Logic Has Evolved from "Shortage" to "Who Can Turn Shortage into RoIC"
The MLCC industry has moved from ordinary supply-demand recovery into a second stage. The first stage looks at shortage and orders, the second at price increases and inventory, and the third at who can convert specification upgrade into long-term capital return. Murata now represents the third stage. It needs to prove that AI server high-capacitance MLCC has the product-line attributes to continuously lift RoIC, rather than being a one-off cyclical rally.
Yageo Deep Update: AI Demand Begins Tightening MLCC Supply, and How Mid- to Low-Capacitance Price Increases Rewrite the 2027-2028 Income Statement
Yageo, Taiyo Yuden, Samsung Electro-Mechanics, and Murata will all benefit from MLCC strength, but in different ways. Yageo and Taiyo Yuden are more easily seen as price and capacity-utilization elasticity. Samsung Electro-Mechanics and Murata rely more on high-end specifications, while Murata receives a higher valuation anchor because of materials and yield advantages. This ranking will change dynamically, and the follow-up depends on customer qualification, expansion, inventory, and pricing discipline.
If the industry only stays in shortage, the best trade may be the company with the greatest cyclical elasticity. If the industry enters the high-specification power-supply materials stage, the best asset will be the company that can turn specification upgrade into RoIC. Citi's move to lift Murata's target price to JPY 15,000 is effectively a choice of the second worldview.
16. Profit Bridge Breakdown: From GPU Board to RoIC, There Are Six Gates in Between
The most important part to unpack in Citi's target-price upgrade is the earnings transmission chain. AI server demand does not automatically become Murata profit. It must first enter GPU board design, then high-capacitance MLCC specifications, then customer qualification and mass-production yield, and only then appear as ASP, margin, and RoIC. If any gate fails to open, the earnings upgrade will be weakened.
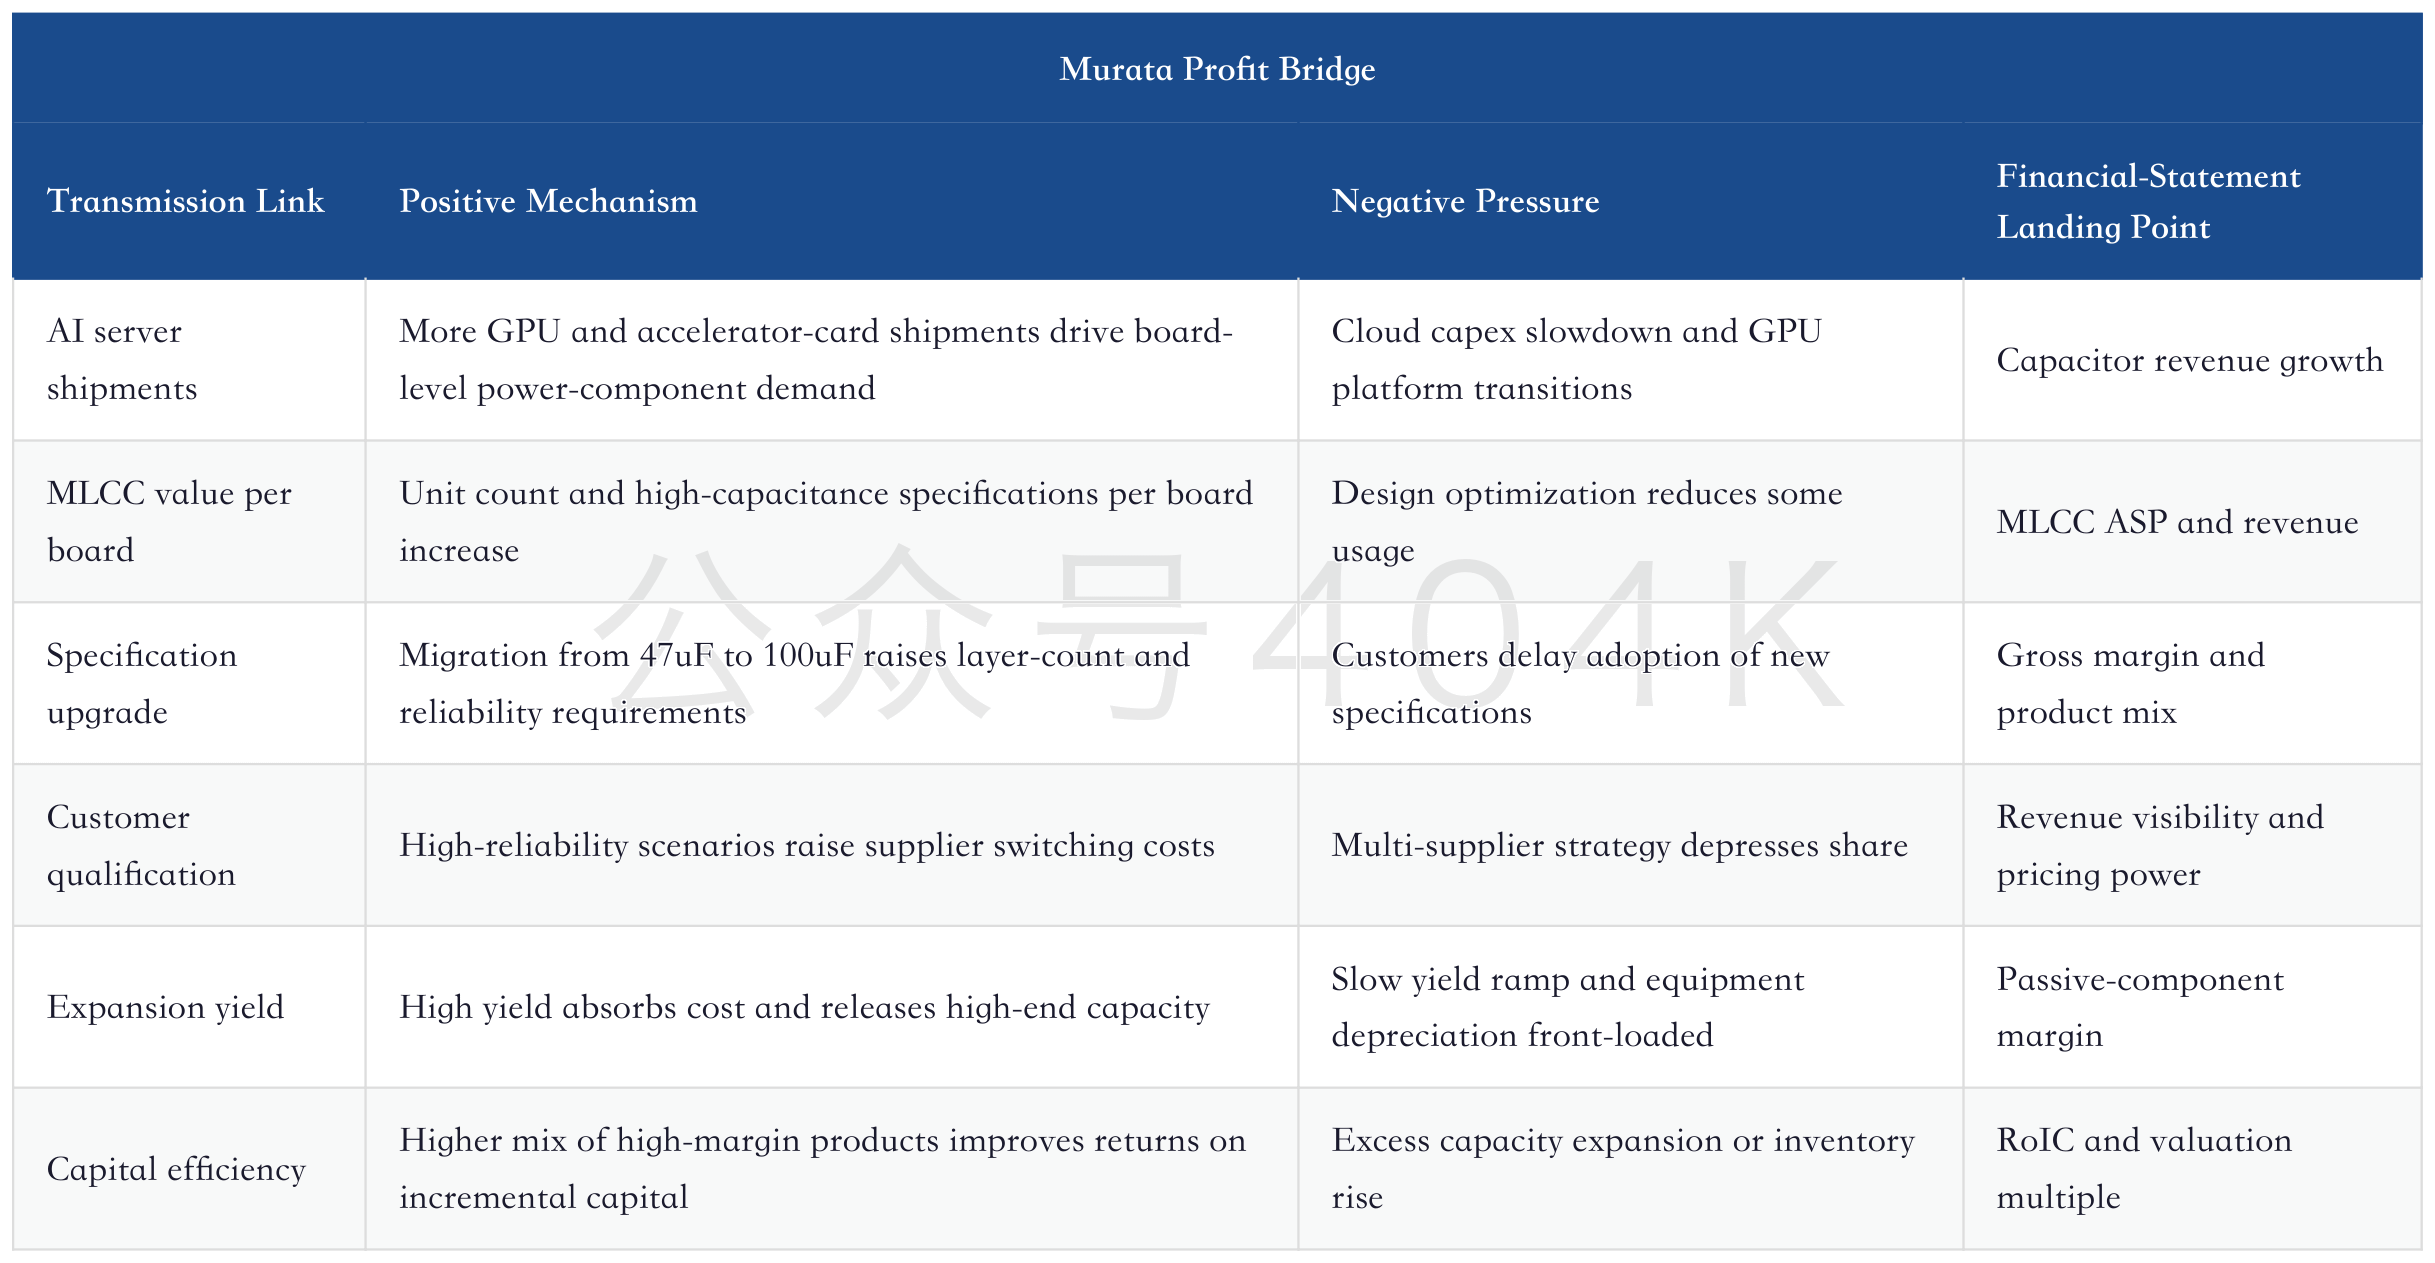
Among these six gates, expansion yield is the easiest to underestimate. Strong AI server customer demand only shows pull from the order side. Whether Murata can turn orders into high-quality profit depends on whether high-capacitance MLCC capacity can be released steadily. If yield is high, new capacity quickly enters high-value products, and depreciation pressure is covered by ASP and gross margin. If yield is low, stronger orders create greater delivery and cost pressure, slowing profit delivery instead.
The second easily underestimated variable is customer qualification. High-capacitance MLCC has gone beyond component procurement and started to enter the complete server power-supply design. Once customers complete design validation, they place greater emphasis on supply stability, failure rate, and long-term iteration. This gives Murata stronger stickiness and means share changes will not be as rapid as in ordinary consumer MLCC. However, customers will still support second suppliers to avoid single-supplier risk, so share advantage must be continuously proven through yield and delivery.
The third variable is product mix. In Citi's model, yen-denominated MLCC ASP improvement comes from structure, price, and FX together. The truly high-quality part is structural improvement, meaning more AI server high-capacitance products enter revenue. FX and ordinary price increases can amplify short-term profit, but structural improvement is what keeps lifting RoIC. In follow-up tracking, if the company only discloses total ASP growth, investors still need to keep separating contributions from high-capacitance products, ordinary products, and FX.
From an investment perspective, Murata now wins through "specification upgrade x yield x customer qualification x capital efficiency." Volume can only explain revenue growth; yield and specifications explain margin; customer qualification explains durability; RoIC explains valuation. Citi's target price jump from JPY 3,900 to JPY 15,000 is really a move from a volume framework to a RoIC framework.
17. Expansion and Supply: 20% Additional Capacity Is Only the Starting Point; Capacity Quality Is the Key
Citi notes that Murata announced roughly 20% additional capacity expansion on top of ordinary annual expansion. This figure naturally leads the market to think of shortage, but for Murata, the core of expansion is not making capacity larger. AI server high-capacitance MLCC requires usable capacity, qualified capacity, and high-yield capacity. If nominal capacity increases but cannot translate into yield for high-capacitance products, it will instead bring depreciation and inventory pressure.
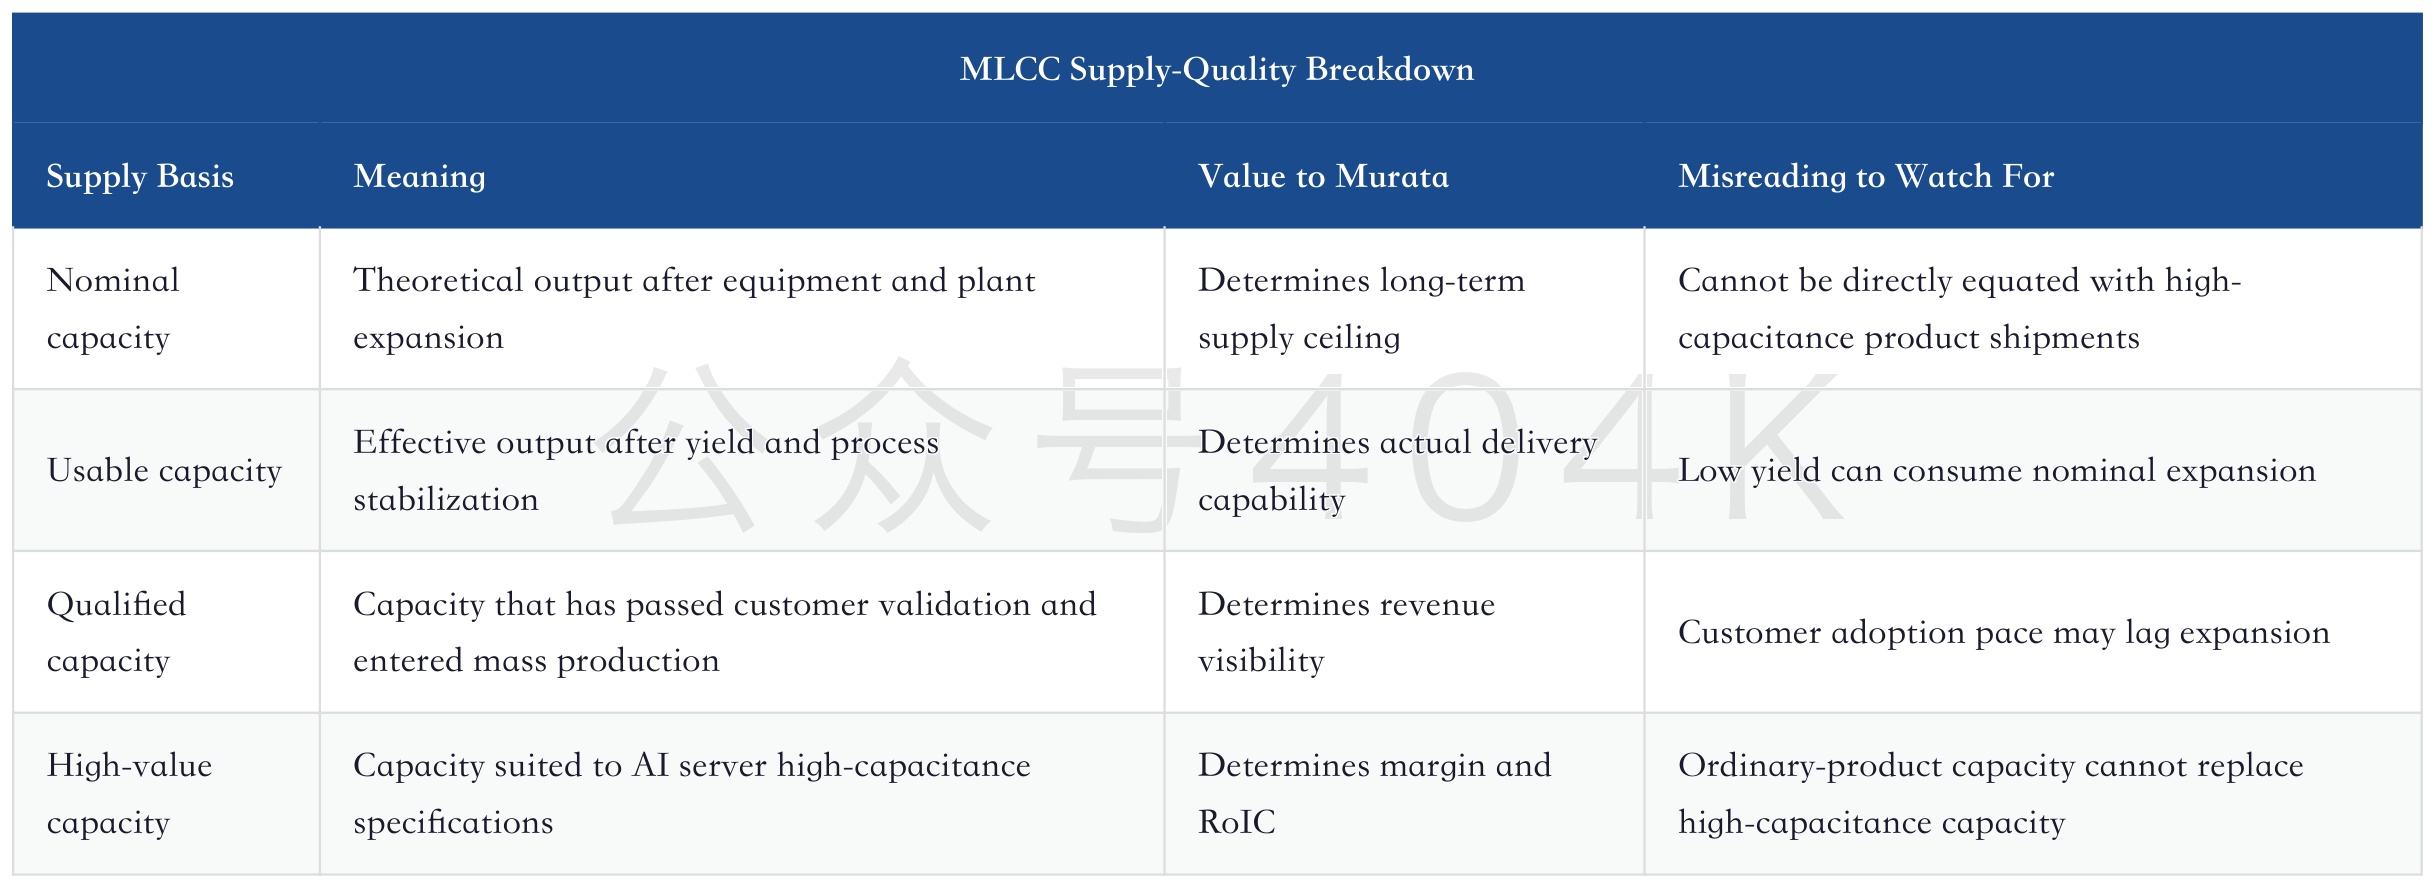
This point is important because the MLCC industry has repeatedly seen cycles of "capacity expands first, demand weakens later, prices fall." Murata's advantage today is that high-capacitance MLCC capacity is harder to replicate and has higher expansion quality. The risk is that the market may treat all expansion as high-end capacity. As long as management continues to emphasize high-capacitance product yield, customer qualification, and mix improvement, expansion is more likely to be a positive signal. If only total capacity, inventory, and gross margin fail to improve together, expansion becomes a risk.
Capacity quality will also affect the competitive landscape. Samsung Electro-Mechanics and Taiyo Yuden are not without high-end capability, and customers will introduce multiple suppliers for supply security. The premise for Murata maintaining roughly 50% high-capacitance share is that new capacity passes customer qualification faster than peers and has more stable yield. If peer expansion is smooth, Murata will still benefit from industry growth, but excess margin will decline. If peer expansion is slow, Murata's delivery capability will become stronger pricing power.
Citi writes Murata's high-end share and margin into its model, effectively treating expansion quality as a key assumption. This assumption will be easiest to observe in three types of data: whether passive-component margin keeps rising, whether free cash flow remains healthy after capex increases, and whether inventory turnover stays stable. If all three improve together, expansion is creating high-quality profit. If they diverge, expansion is consuming cash flow or pulling forward inventory.
18. Reverse-Engineering the Target Price: What Evidence Is Needed for JPY 15,000, and What Extra Conditions Are Needed for JPY 18,000
A target price can be reverse-engineered into operating assumptions. Citi's JPY 15,000 target price corresponds to sustained high-capacitance MLCC ramp, rising margin, higher RoIC, and a lower risk premium. The JPY 18,000 upside scenario requires ordinary MLCC to enter broader price increases as well, without damaging long-term share and customer relationships. Separating these two bases is necessary to read incoming data.
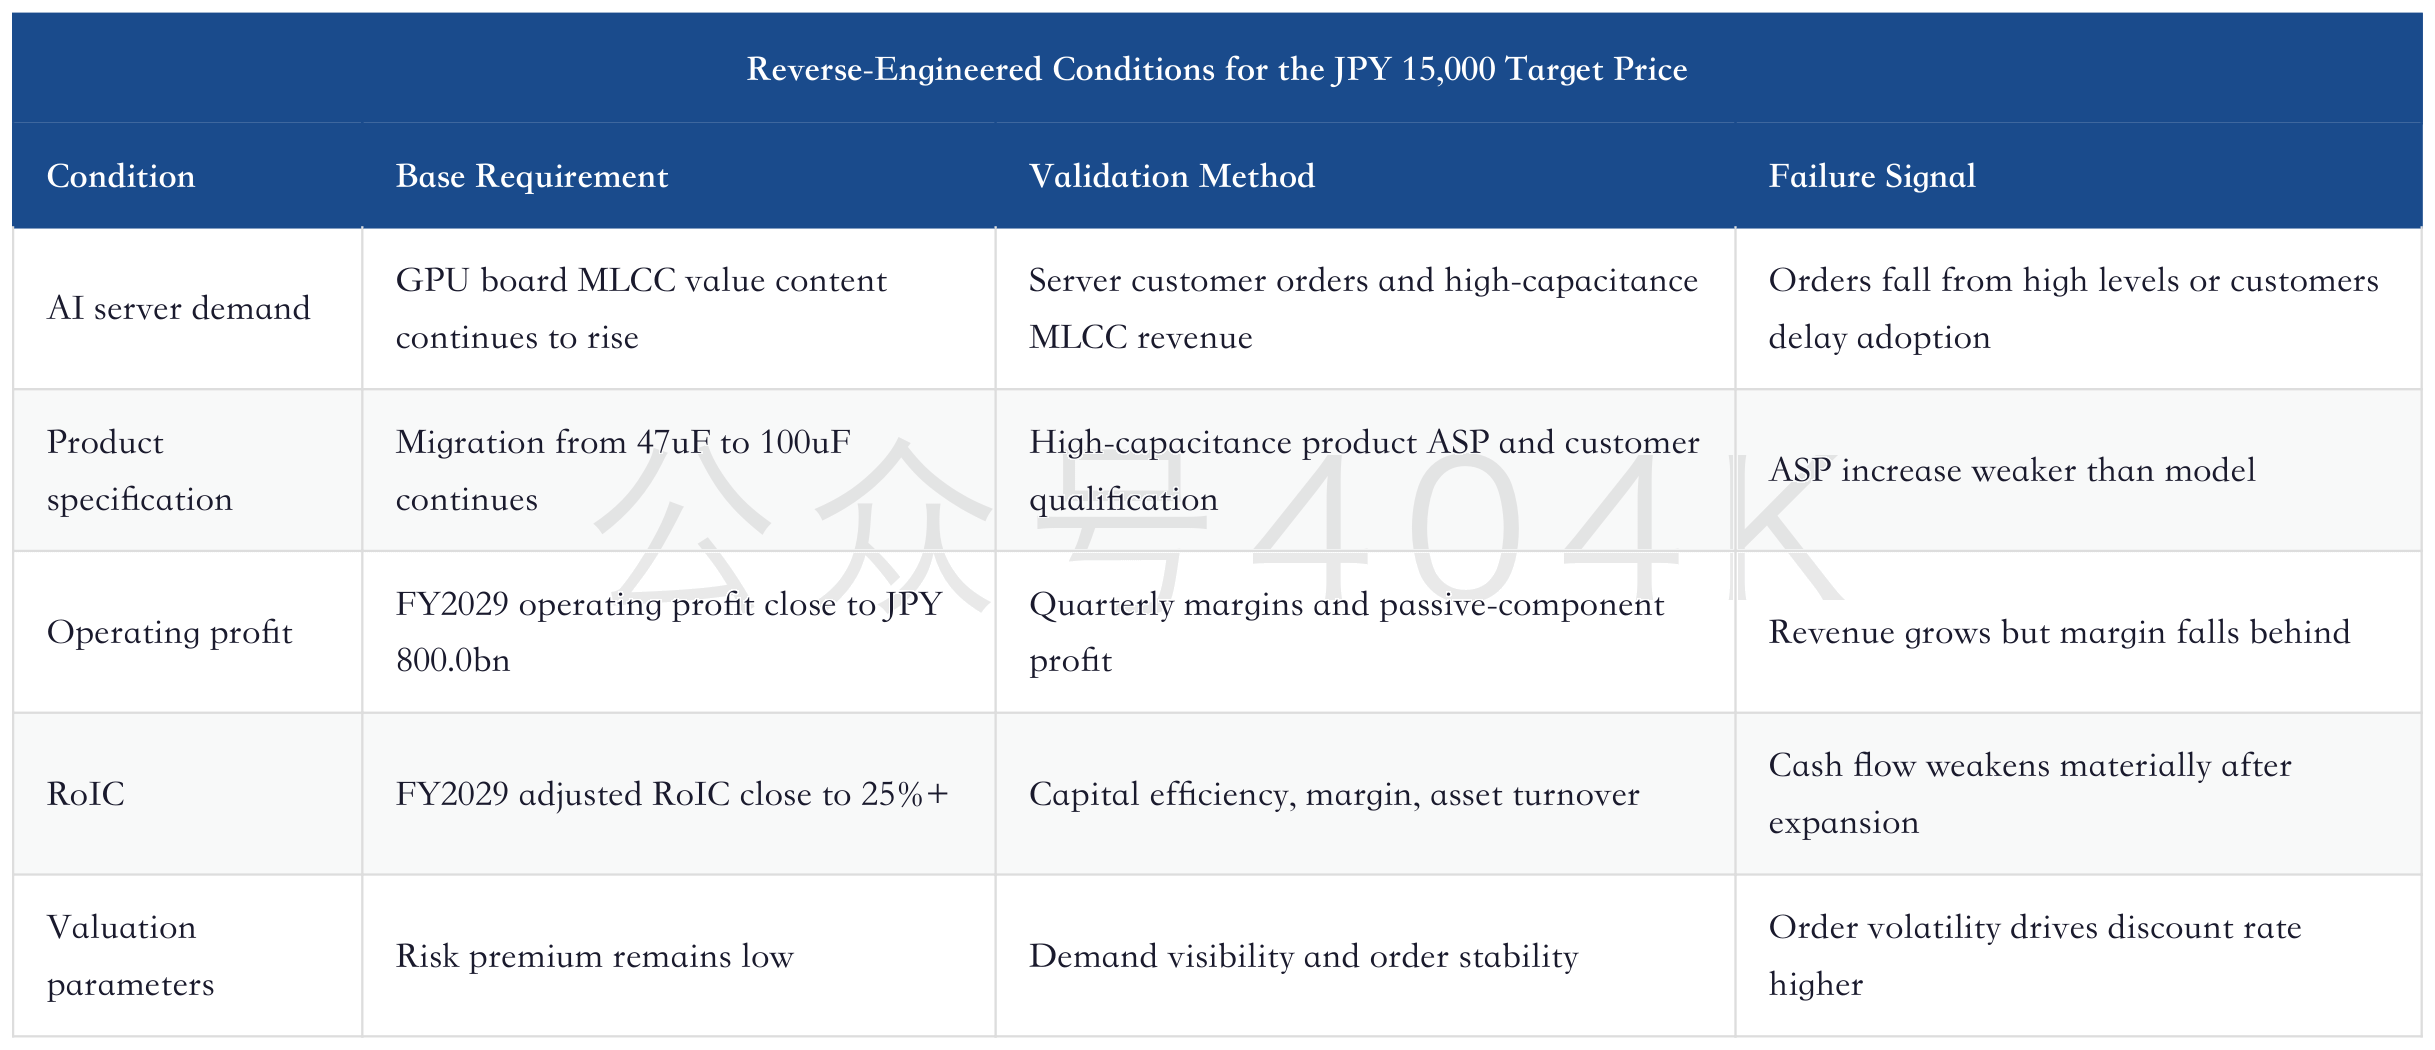
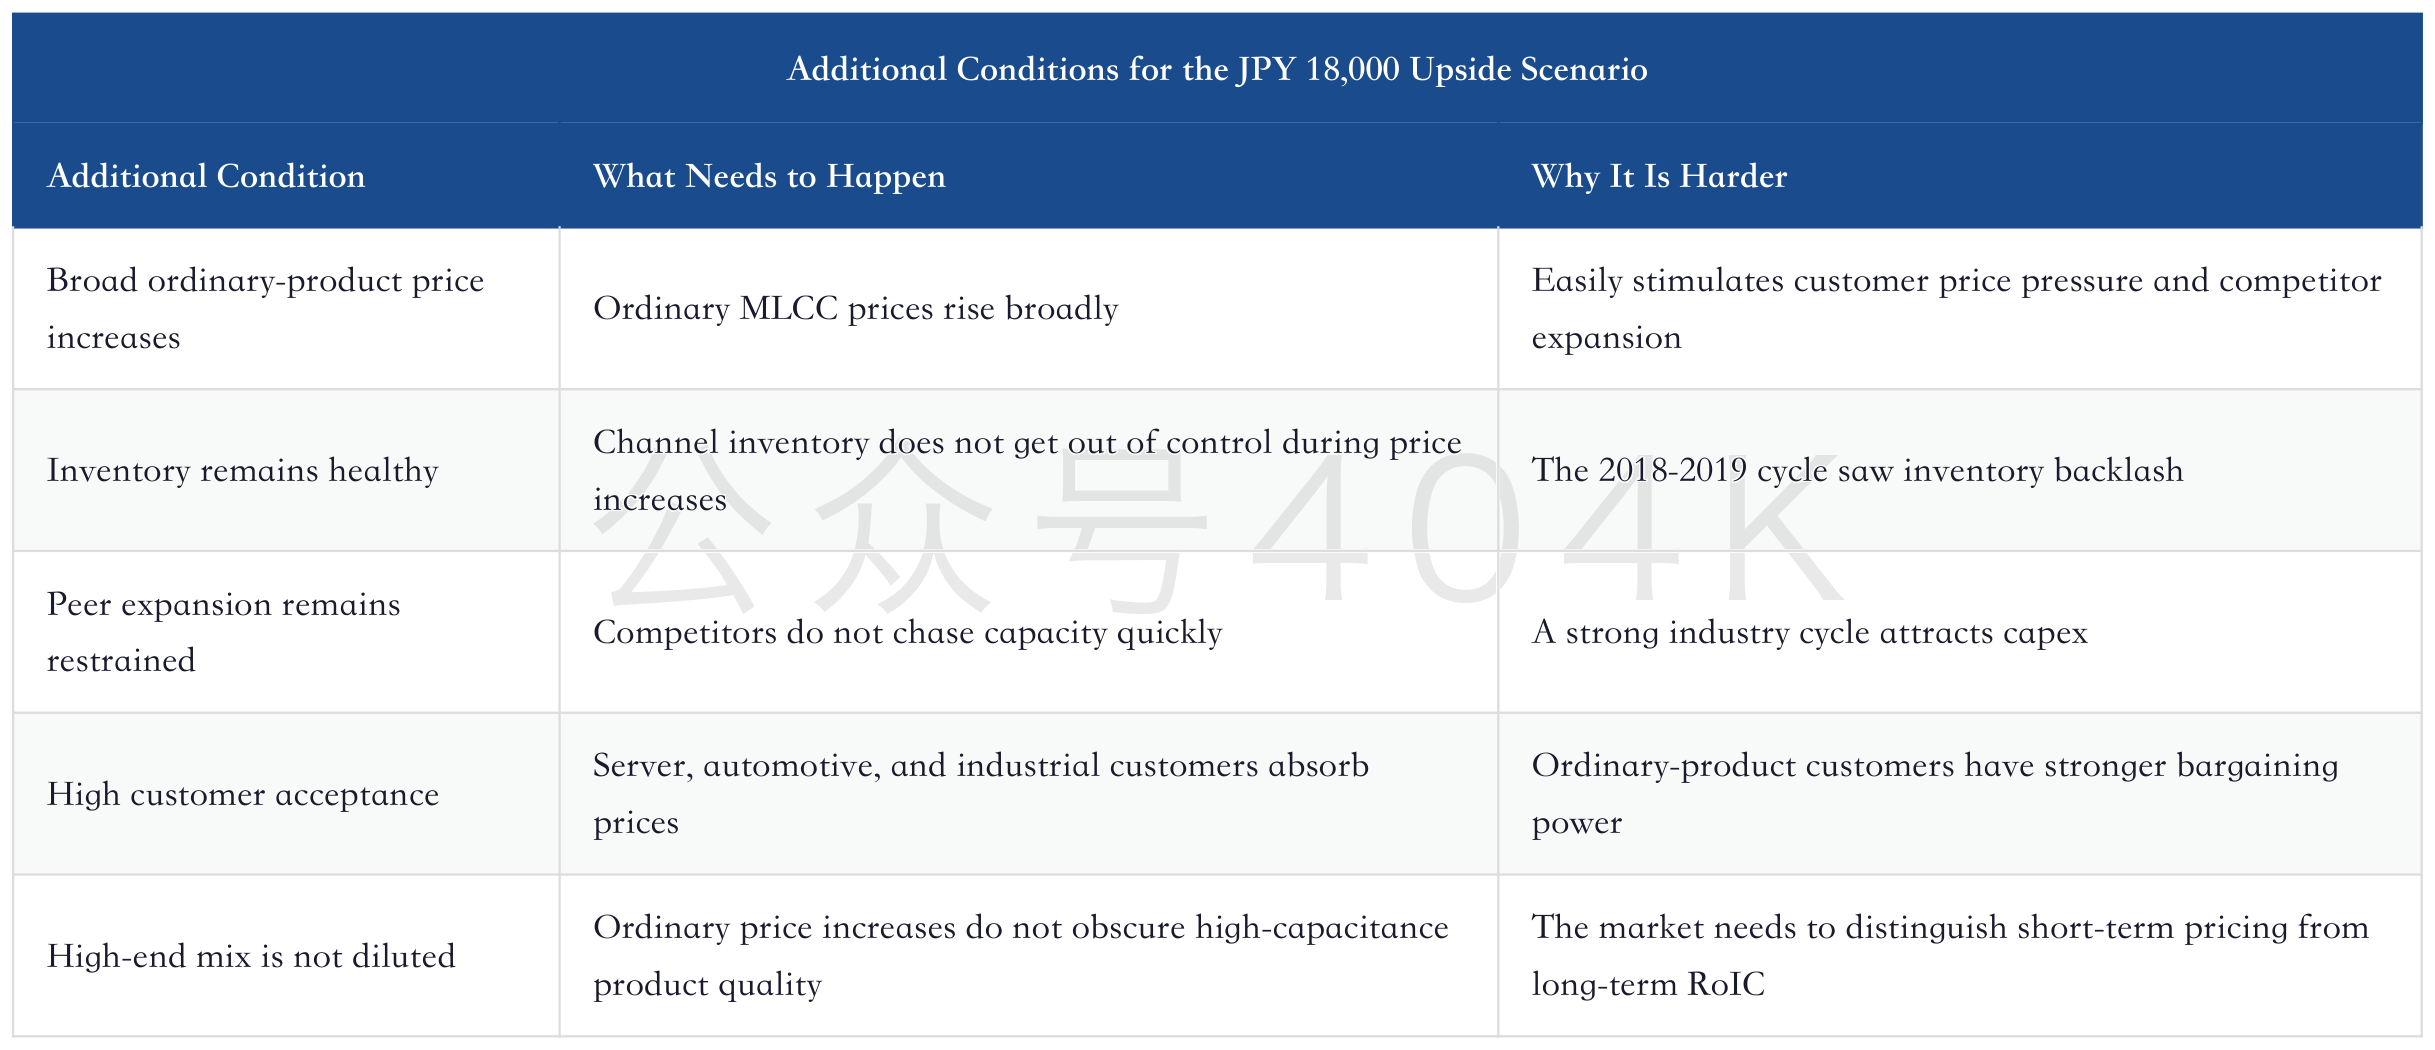
Therefore, the difference between JPY 15,000 and JPY 18,000 reflects two different sets of evidence. The base target price mainly depends on AI server high-end mix, while the upside scenario also requires ordinary-product price increases to spread. If ordinary-product prices rise but inventory begins to accumulate, the market will not fully capitalize it. If ordinary-product prices remain stable but high-capacitance MLCC margin continues to rise, JPY 15,000 has better quality.
This reverse-engineering framework can also handle share-price volatility. If Murata's share price approaches the target price in the short term, investors need to assess whether new evidence is approaching the JPY 18,000 scenario. If the share price pulls back, the first question is whether this is market valuation compression or deteriorating operating evidence. The former may just be high-valuation volatility; the latter affects the target price itself. High-valuation assets are most vulnerable to evidence gaps and most need consecutive quarterly delivery.
19. How to Track the Next Four Quarters: Look First at High-Capacitance MLCC, Then at Drag from Ordinary Businesses
Over the next four quarters, Murata's tracking priorities can be arranged in time order. Step one is orders, step two is ASP and gross margin, step three is inventory and cash flow, and step four is management commentary on expansion and customer adoption. Tracking in this order helps avoid being misled by one quarter of high revenue or high profit.
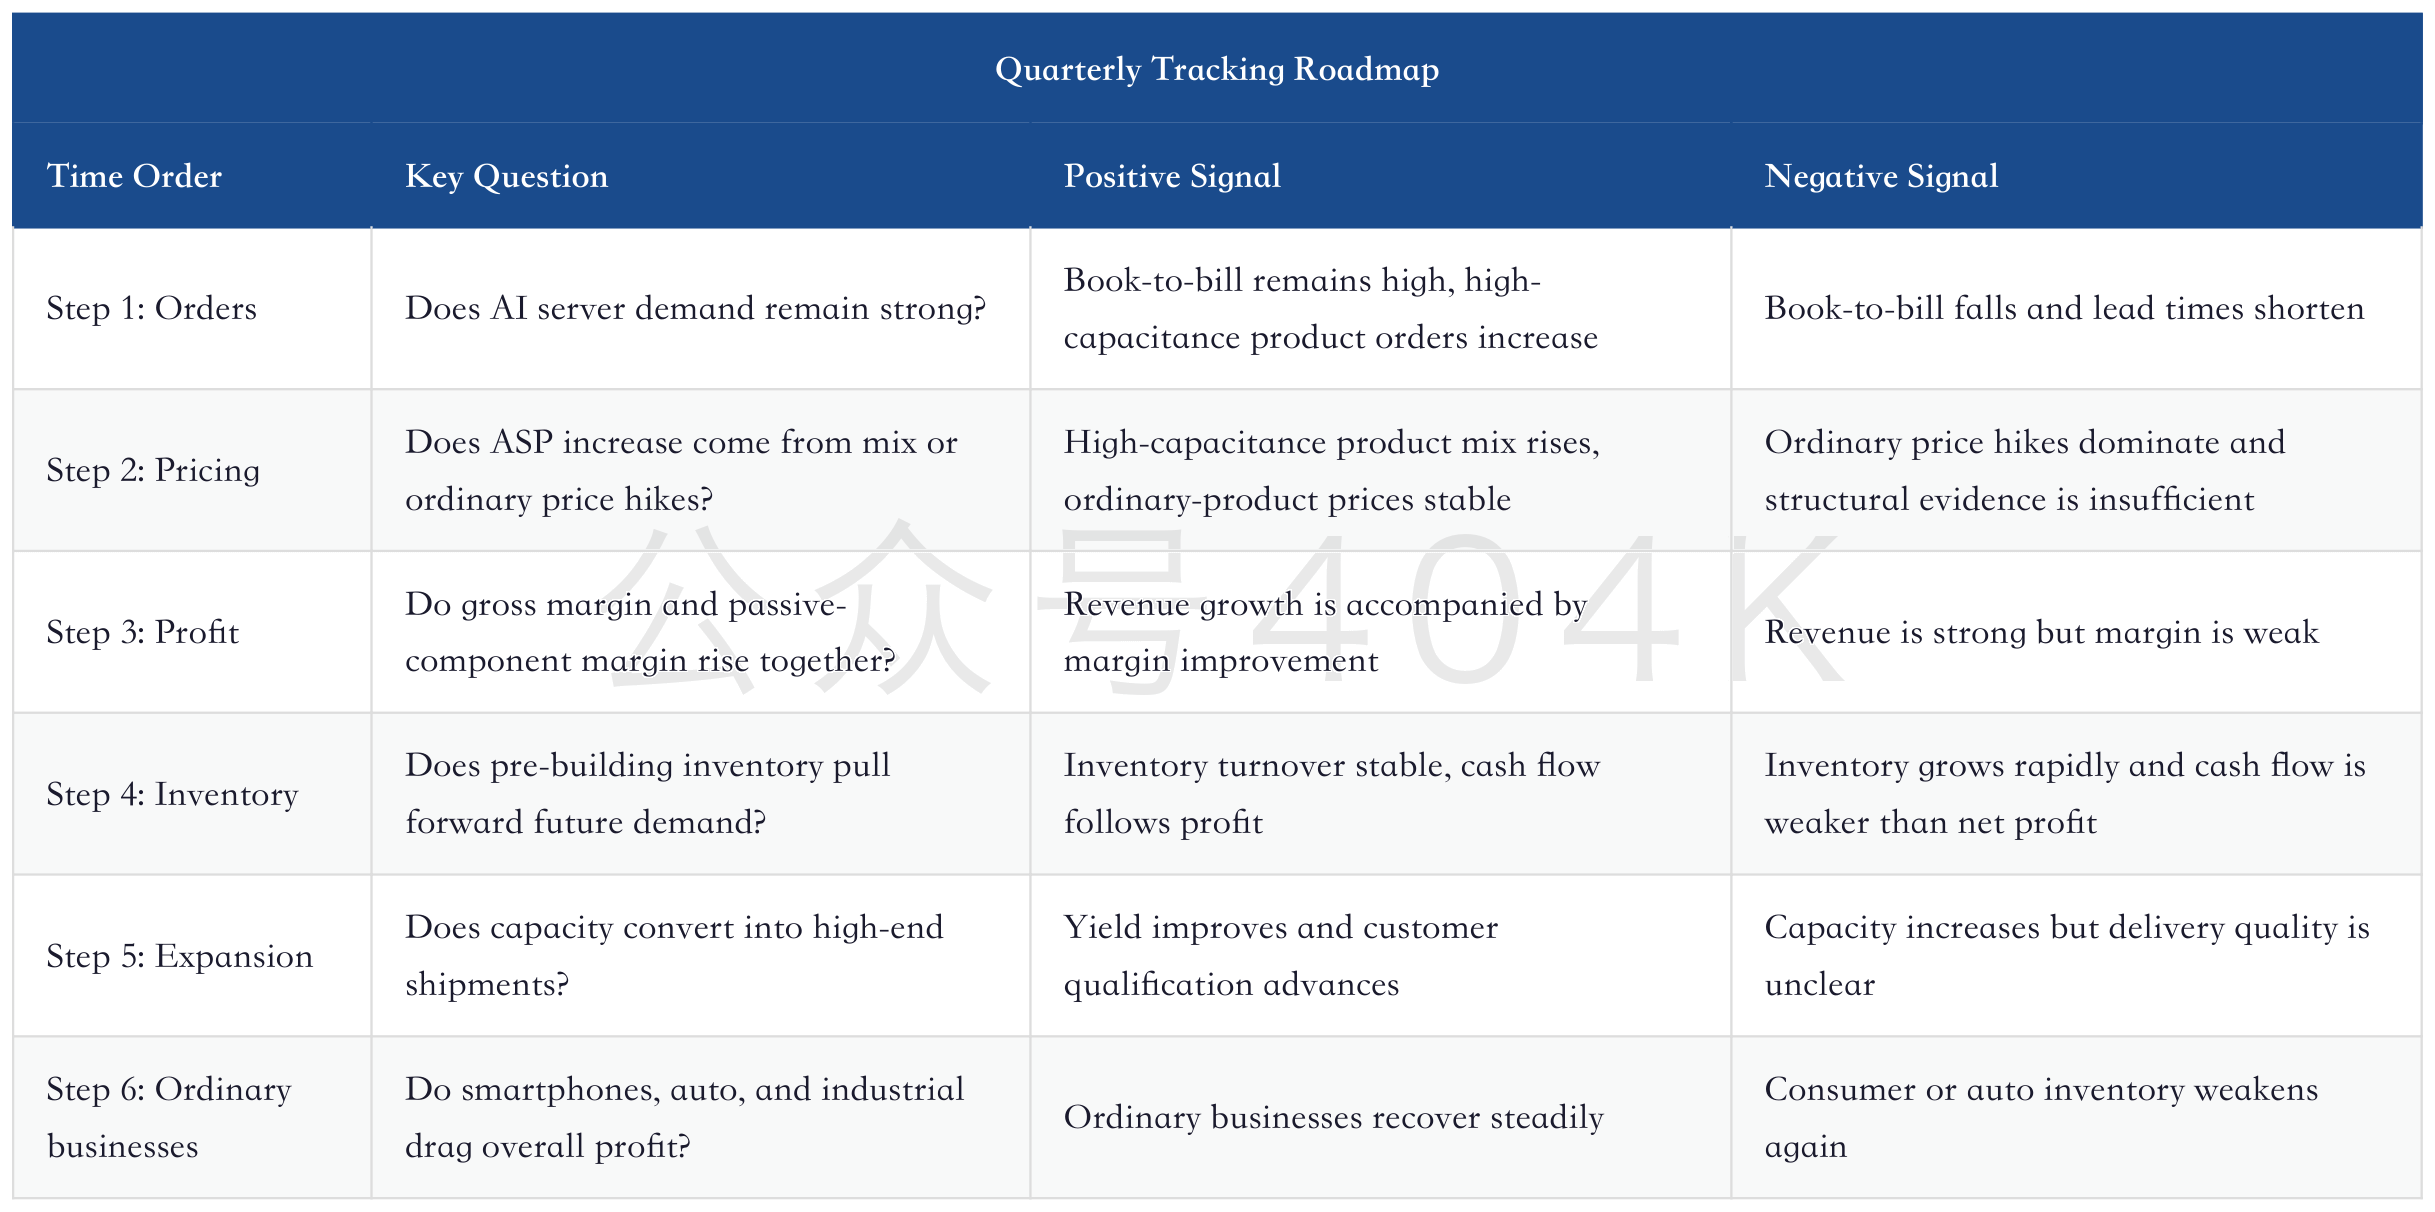
In this roadmap, the combination of step two and step three is the most important. If ASP growth comes from mix improvement, gross margin should improve in tandem. If ASP growth comes from short-term price increases, gross margin will also improve, but inventory and customer order quality are more likely to show later volatility. Step four, inventory cash flow, is needed to distinguish the two.
Ordinary businesses also cannot be ignored. However strong Murata's AI server story is, total revenue still includes smartphones, automotive, industrial, and modules. If ordinary businesses decline, AI server high-capacitance MLCC needs an even stronger contribution to lift overall margin. If ordinary businesses are stable, the AI server contribution will enter the income statement more clearly. If ordinary businesses become a material drag, the market will reassess whether Murata can move beyond the traditional MLCC cycle.
In terms of pace, quarterly performance in FY2027 will validate "margin starting to rise," FY2028 will validate "higher high-capacitance MLCC weighting," and FY2029 will validate "RoIC entering a new platform." Citi has already placed FY2029 into the valuation base, so the market will trade this path in advance and punish deviations on the path in advance as well.
20. Financial Quality: Earnings Upgrades Must Move Through Inventory, FX, and Capex
The core of Murata's re-rating is profit quality. Operating profit upgrades are important, but they only become sustainable valuation after passing through three filters: inventory, FX, and capex. High-capacitance MLCC margins are high, but capex is also high. Orders are strong, but inventory-management pressure also rises. A favorable yen exchange rate helps profit elasticity, but the market will discount part of that. Separating these variables is necessary to judge the quality of the JPY 15,000 target price.
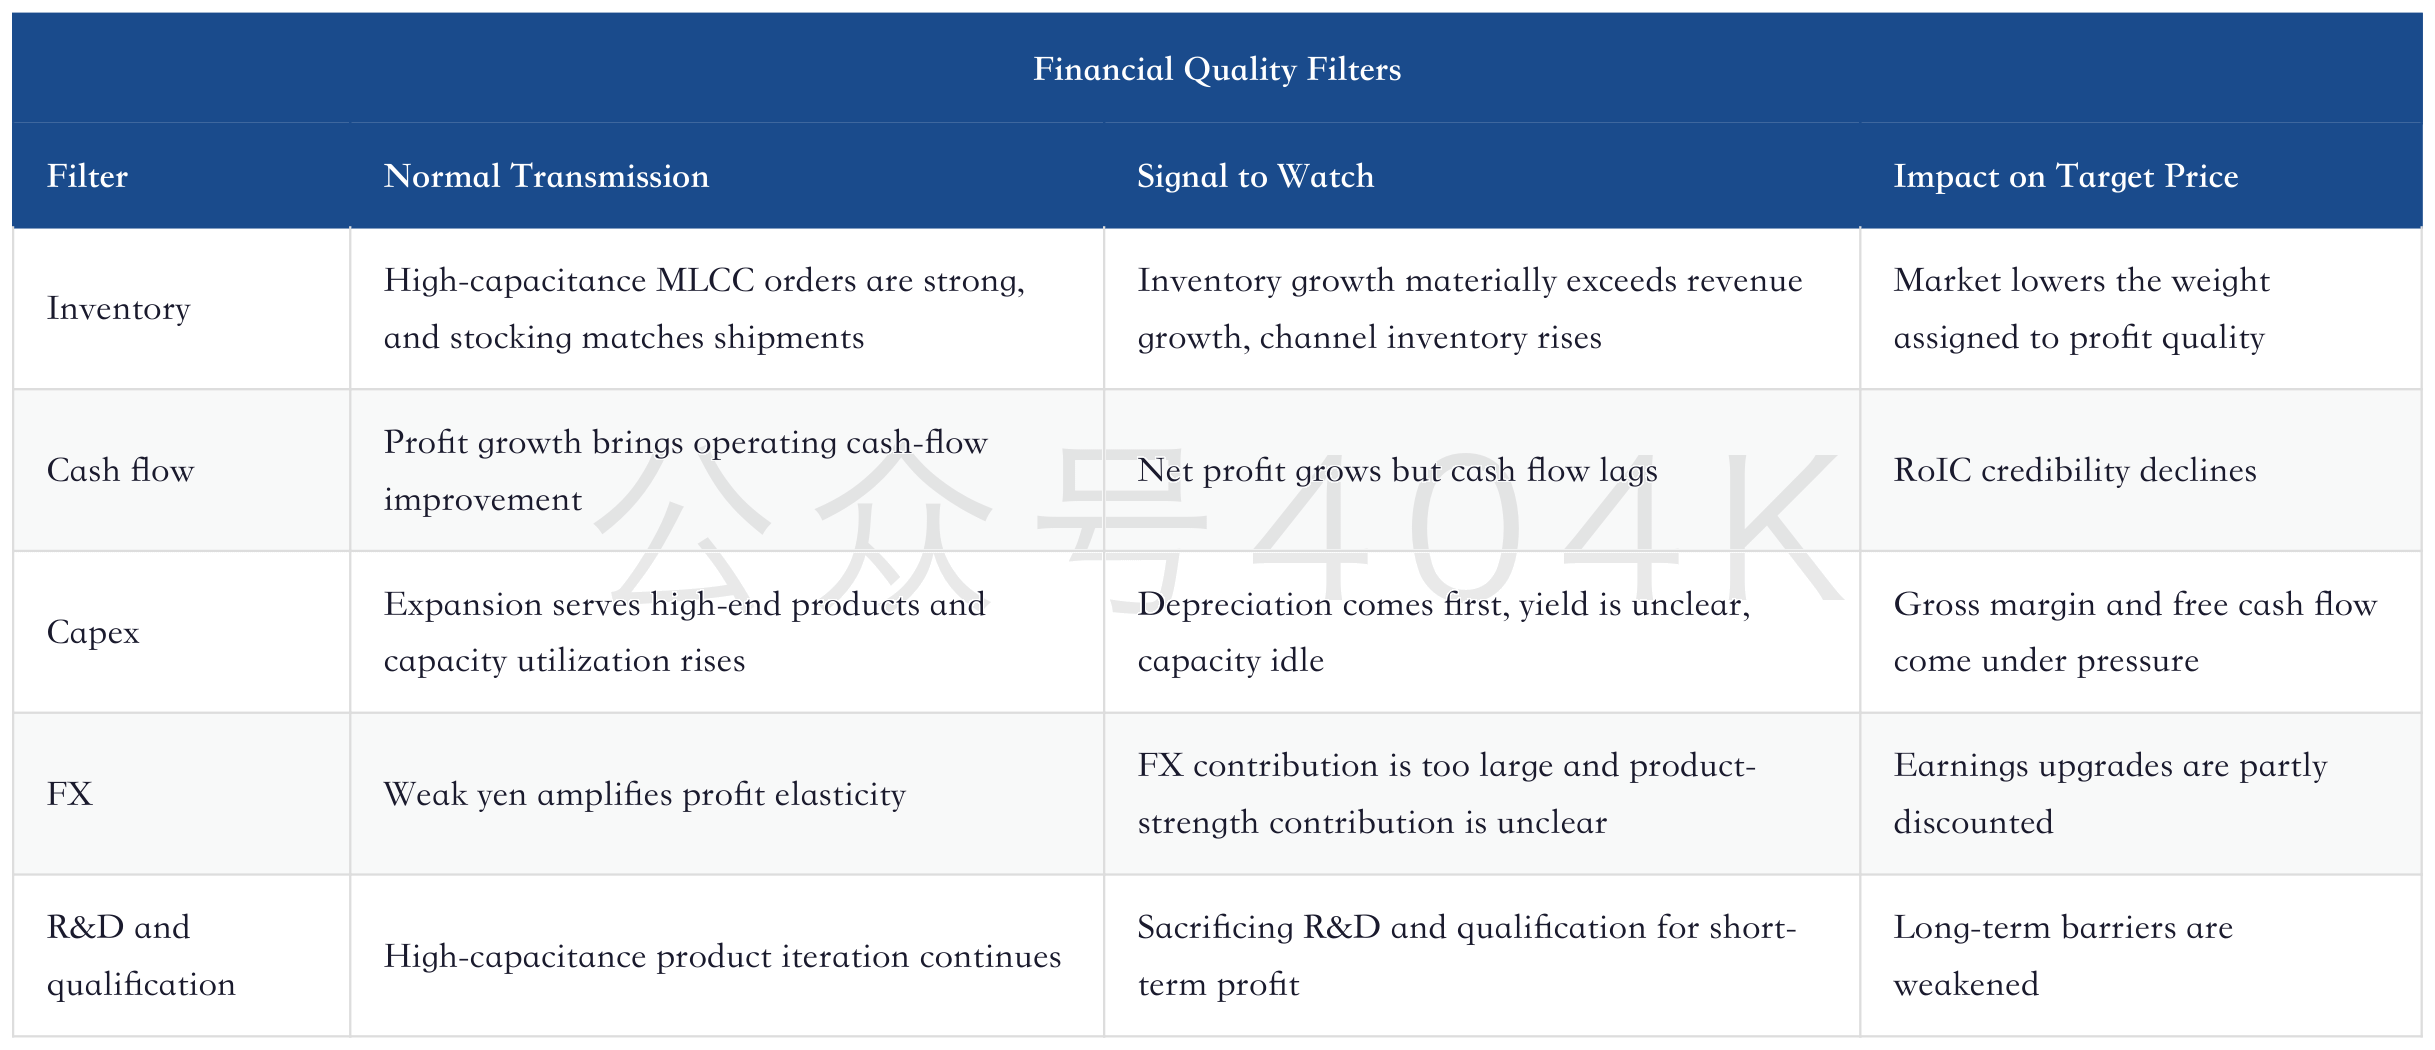
Inventory is the financial-statement item that exposes cyclical risk earliest. When AI server demand is strong, both customers and suppliers are more willing to build inventory. Reasonable stocking improves supply stability, but overly rapid accumulation pulls future demand into the current financial statements. In historical MLCC cycles, channel inventory has often been amplified near demand peaks, followed by pressure on both prices and shipments. If Murata wants to prove this re-rating has high quality, inventory growth needs to match AI server orders and high-capacitance product delivery.
Cash flow is the second filter. The income statement can first reflect ASP and product mix, while cash flow more honestly reflects customer payments, inventory, and capex. If Murata's net profit rises and operating cash flow improves at the same time, it indicates high-capacitance MLCC profit is turning into real cash. If net profit rises but operating cash flow lags materially, the market will worry that inventory, receivables, and stocking are consuming profit quality.
Capex is the third filter. Citi's model has already incorporated expansion and high-end product contributions into future profit. Expansion itself is not negative; the key is whether new capacity enters high-end products. If passive-component margin and RoIC rise together after capex increases, expansion is creating high-value capacity. If margins decline after capex increases, depreciation, yield, or capacity utilization has started to drag on the model.
FX needs to be separated as well. Citi used more favorable FX assumptions when raising forecasts. A weaker yen increases overseas revenue translation and profit elasticity. This variable can support earnings upgrades, but it cannot be treated as a long-term barrier. Investors should separate the FX contribution from the product-mix contribution: FX contribution lifts short-term EPS, while product-mix contribution lifts long-term RoIC.
The conclusion on financial quality is simple. To support the JPY 15,000 target price, Murata needs profit growth, cash flow, inventory, and capex to remain aligned. A single quarter of earnings beat is only the first step. Consecutive quarters of healthy cash flow and inventory will persuade the market that AI server MLCC has pushed Murata into a new profit step.
21. How to Read Management Commentary: Listen Less to Price-Hike Slogans, More to Mix and Discipline
When listening to Murata management going forward, separate three types of commentary. The first is demand commentary, such as AI servers, high-capacitance MLCC, customer qualification, and order visibility. The second is supply commentary, such as expansion, yield, lead times, and capex. The third is pricing commentary, such as whether ordinary MLCC prices will rise, whether materials costs can be passed through, and whether customers accept high-capacitance product pricing. Together, these three categories form a complete judgment.
Specifically, it can be read this way. If management emphasizes strong AI server demand, the positive signal is higher visibility for high-capacitance MLCC orders, while the caution point is that shipments and customer mix still need confirmation. If management emphasizes smooth high-capacitance product adoption, the positive signal is progress in customer qualification and specification upgrade, while the caution point is that yield and mass-production scale still need to be checked. If management emphasizes additional capacity expansion, the positive signal is that the company sees medium-term demand, while the caution point is ordinary capacity oversupply and depreciation pressure. If management emphasizes stable ordinary-product pricing, the positive signal is good pricing discipline and limited cyclical backlash, while the caution point is weaker short-term profit explosiveness. If management emphasizes materials cost pass-through, it is more about protecting gross margin. If management emphasizes controllable inventory, it directly improves the credibility of profit quality.
This framework helps readers avoid two misreadings. The first is to equate "strong demand" directly with strong profit. Strong demand only proves there is pull from the order side; profit still depends on specifications, yield, ASP, and cost. The second is to interpret "the company is not actively pushing broad price increases" as insufficient elasticity. For Murata, broad ordinary-product price increases would lift short-term profit, but they would also increase cyclical backlash. High-capacitance product mix-led pricing is better suited to supporting long-term valuation.
If management continues to emphasize AI server customer adoption, high-capacitance product yield, and expansion discipline, the market will be more willing to place Murata in a high-RoIC framework. If management shifts toward emphasizing ordinary-product price increases, longer short-term lead times, and industry shortages, the market will first trade profit elasticity but will also inspect inventory more quickly. If management starts emphasizing demand uncertainty, customer inventory adjustment, or slower expansion pace, the JPY 15,000 target price will need to be reassessed.
Therefore, Murata's subsequent conference calls and results briefings should not be read through a single keyword. A better reading is: demand commentary shows the real pull from AI servers; supply commentary shows the quality of high-end capacity; pricing commentary shows the ratio of mix-led pricing to ordinary price increases; financial commentary shows whether profit, inventory, and cash flow are moving together. Only when these four signals are aligned can Citi's upgrade move from report assumption into company operations.
22. Conclusion: Murata Has Entered a High-Standard Delivery Period, and JPY 15,000 Requires Profit Quality
Citi's report confirms the latest stage of Murata Manufacturing's re-rating: AI server MLCC has moved from industry narrative into the earnings model, the target price has been raised from JPY 3,900 to JPY 15,000, and the rating has been upgraded to Buy. The core of this change is that high-capacitance MLCC lifts ASP, margin, and RoIC together, while ordinary MLCC supply-demand tightness only provides auxiliary elasticity.
Murata's upside logic is clear. AI servers raise MLCC value content per system, migration from 47uF to 100uF raises product barriers, Murata has share and yield advantages in high-capacitance products, passive-component margin rises materially, and the RoIC-WACC model therefore produces a higher valuation. As long as this evidence continues to be delivered, Murata will move further from a high-quality cyclical stock toward a leader in AI server power-supply materials.
Murata's pressure is equally clear. The JPY 15,000 target price implies a high PE and strong RoIC assumptions. Any adverse movement in orders, ASP, yield, inventory, expansion, or FX will be amplified. The JPY 18,000 upside case requires broader ordinary MLCC price increases, while the base target price relies mainly on high-end mix upgrade. Separating the two bases is necessary to avoid conflating cyclical price increases with asset re-rating.
In the next stage, tracking Murata only by revenue will not be enough. The true indicators to watch are order quality, AI server weighting, MLCC ASP, passive-component margin, inventory cash flow, and expansion yield. They determine whether Murata can turn the AI server power-supply bottleneck into long-term capital efficiency. If these indicators continue to improve together, the JPY 15,000 target price becomes more stable. If the indicators begin to diverge, the market will place Murata back into the MLCC cyclical-stock framework.
Japan Electronic Components Deep Update: Morgan Stanley Asia Investor Survey, How AI Servers Widen the MLCC and ABF Valuation GapMurata Manufacturing Deep Update: Citi’s JPY 15,000 Target Price and How AI Server MLCC Re-rates the Profit Slope
目录
TL;DR
1. Conclusion First: Citi’s Upgrade Is Buying the “High-Capacitance MLCC Profit Gate”
2. What Exactly Citi Changed: Rating, Target Price, Earnings, and Discount Rate Moved Together
3. The Essence of AI Server MLCC: From “More Units” to “Higher Capacitance”
4. Earnings Bridge: Why Operating Profit Moves from Recovery to Step-Function Growth
5. Pricing Discipline: Murata Wants High-End Mix-Led Price Increases
6. RoIC-WACC Valuation: JPY 15,000 Requires Murata to Become a High-Capital-Efficiency Asset
7. Murata’s Capability Migration: From Cyclical Leader to AI Server Power-Supply Materials Platform
8. Peer Comparison: Murata Captures Specifications, Samsung Electro-Mechanics Captures Elasticity, Taiyo Yuden Captures the Cycle, and Yageo Captures Inventory and Channels
9. Relationship with ABF and PCB: The AI Server Materials Chain Spills Over from Main Chips to the Power Layer
10. Three Scenarios: JPY 15,000 Is the Base Case, JPY 18,000 Requires Broad Price Increases, and the Stress Case Depends on Inventory and Yield
11. Data Framework: In the Next Stage, Look First at Order Quality, Then Profit Quality
12. Why Citi Is More Aggressive Than the Previous Market View: It Turned “Higher Server Specifications” into Income-Statement Assumptions
13. Historical Positioning: What Really Makes Murata Valuable Is Turning Materials Capability into Customer Standards
14. Risk Breakdown: Under a High Valuation, Any Failed Validation Link Will Be Amplified
15. Linkage with Previous MLCC Reports: Industry Logic Has Evolved from “Shortage” to “Who Can Turn Shortage into RoIC”
16. Profit Bridge Breakdown: From GPU Board to RoIC, There Are Six Gates in Between
17. Expansion and Supply: 20% Additional Capacity Is Only the Starting Point; Capacity Quality Is the Key
18. Reverse-Engineering the Target Price: What Evidence Is Needed for JPY 15,000, and What Extra Conditions Are Needed for JPY 18,000
19. How to Track the Next Four Quarters: Look First at High-Capacitance MLCC, Then at Drag from Ordinary Businesses
20. Financial Quality: Earnings Upgrades Must Move Through Inventory, FX, and Capex
21. How to Read Management Commentary: Listen Less to Price-Hike Slogans, More to Mix and Discipline
22. Conclusion: Murata Has Entered a High-Standard Delivery Period, and JPY 15,000 Requires Profit Quality
本内容基于公开资料和研报数据整理,不构成任何投资建议,不代表任何个人观点,仅供学习参考,请理性阅读
Citi upgraded Murata Manufacturing to Buy and set a JPY 15,000 target price. The core logic is that AI server MLCC is shifting from unit-count expansion to a simultaneous rise in capacitance, ASP, and RoIC. This report breaks down earnings upgrades, valuation assumptions, pricing discipline, and follow-up validation signals to assess whether this re-rating can move through the ordinary MLCC cycle.
TL;DR
Citi has lifted the valuation anchor to JPY 15,000. The rating was upgraded from Neutral to Buy, with a sharp target-price increase driven by changes in earnings forecasts, risk premium, and the valuation base year. This adjustment means Citi has moved Murata from a normal MLCC cycle-recovery framework into a capital-efficiency re-rating driven by high-capacitance MLCC for AI servers.
AI servers are rewriting the MLCC profit slope. GPU boards are increasing MLCC unit count, capacitance, and layer-count requirements at the same time, benefiting Murata’s high-capacitance MLCC pricing, yield, and customer qualification threshold. The key follow-up is whether migration from 47uF to 100uF continues, and whether high-capacitance products truly enter revenue and gross margin.
Earnings upgrades are concentrated in capacitors. Citi has moved operating profit forecasts to a new level, with passive-component margins rising materially. Recovery in devices and modules mainly provides a profit floor. The real driver of the target price is whether the capacitor business can turn AI server orders into continuous improvement in ASP, gross margin, and RoIC.
Pricing discipline determines re-rating quality. The company has not yet actively pushed broad price increases for standard products. The JPY 15,000 target price mainly reflects high-end mix upgrade, while JPY 18,000 would require stronger evidence of industry-wide price increases. If standard-product price hikes trigger inventory backlash, valuation quality would decline; if high-capacitance mix improvement continues, the base target price becomes more robust.
RoIC has become the core valuation variable. Citi uses a RoIC-WACC framework, and the target price implies a PE above historical peaks. That requires continuous delivery in AI server margins and capital efficiency. The market will next examine expansion yield, passive-component margins, and cash flow, not just one-quarter EPS upgrades.
Watch six numbers for validation. Book-to-bill, AI server revenue mix, MLCC ASP, passive-component margin, inventory cash flow, and expansion pace will determine how far this re-rating can go and whether it can move through ordinary cycle and valuation volatility. If all six improve together, Murata looks more like a leader in AI server power-supply materials. If the indicators diverge, valuation will return to the MLCC cycle framework.
1. Conclusion First: Citi’s Upgrade Is Buying the “High-Capacitance MLCC Profit Gate”
Citi’s upgrade of Murata Manufacturing is aggressive and highly directional. The rating was raised from Neutral to Buy, and the target price was lifted from JPY 3,900 to JPY 15,000. Based on the June 26, 2026 closing price of JPY 10,770, that target implies roughly 40% total return upside. The number is easy to read as a simple target-price increase, but the real change in the report is that the valuation framework has moved from “MLCC cycle recovery” to an “AI server high-capacitance MLCC profit gate.”
Murata Manufacturing has historically been treated as a cyclical stock tied to smartphones, automotive electronics, and general MLCC. AI servers are starting to loosen that label. A standard server board needs roughly 2,000 MLCCs, while a GPU board could approach 11,000 units by 2026. Standard servers more often use products around 10uF, while AI servers are moving from 47uF toward 100uF. Higher capacitance means more thin-film layers, a heavier process load, and greater importance for yield and materials capability. Citi’s view is that Murata’s production yield and materials development capability in high-capacitance MLCC are becoming a harder-to-replicate source of profit.
This is also the basis for the JPY 15,000 target price. Citi does not frame the upgrade simply as “industry-wide price increases.” Instead, it repeatedly emphasizes that the company remains restrained on supply-demand-led price hikes for ordinary MLCC. The base target price relies on AI server mix upgrade, product-mix improvement, operating profit upgrades, and higher RoIC. If ordinary MLCC prices rise by more than 10% across the board, Citi’s upside scenario can approach JPY 18,000, but that path requires stronger evidence of industry-wide price increases.
Murata Manufacturing Deep Dive: AI Server MLCC, from Small Component to Profit Gate
The most important way to read this update is to separate “target-price upgrade” from “business-model upgrade.” The target price is the result; the business-model upgrade is the reason. Murata obtains order elasticity from consumer electronics and automotive cycles, and specification barriers and margin elasticity from AI servers. As long as specification upgrades, ASP improvement, expansion yield, and customer qualification are all delivered, the market will be willing to understand Murata through a higher-RoIC framework. If these variables remain only short-term price hikes, valuation will return to the ordinary MLCC cycle.
2. What Exactly Citi Changed: Rating, Target Price, Earnings, and Discount Rate Moved Together
The strength of this update comes from four variables changing at the same time. First, the rating was upgraded from Neutral to Buy. Second, the target price was raised sharply. Third, earnings forecasts for FY2027 to FY2029 were lifted, especially the MLCC profit contribution. Fourth, valuation parameters also became more favorable, with the equity risk premium reduced from 4.0% to 3.0% and the valuation base year rolled forward from FY2028 to FY2029.
This adjustment has two layers of meaning. The surface meaning is that Citi raised earnings forecasts, so the target price moved higher. The deeper meaning is that Citi is willing to assign a lower risk premium and a later valuation year, indicating it believes visibility, margin, and durability for AI server MLCC demand are now stronger than in an ordinary consumer-electronics cycle.
The biggest risk in reading this kind of upgrade is to treat it as “a broker has given a higher number.” The key to JPY 15,000 is not the number itself, but the fact that it places Murata into a higher-standard validation phase. Previously, an MLCC leader could recover earnings as long as smartphones recovered, auto demand was not weak, and channel inventory normalized. Now the market will require Murata to prove that high-capacitance MLCC can keep lifting ASP, preserving yield, expanding capacity, maintaining customer stickiness, and converting those profits into high RoIC.
3. The Essence of AI Server MLCC: From “More Units” to “Higher Capacitance”
The demand shift for AI server MLCC looks on the surface like an increase in unit count, but the core is capacitance and process difficulty. Server motherboards, power supplies, GPU boards, and high-speed interconnects all need stable power delivery. The higher GPU power and transient current become, the greater the dependence on high-capacitance MLCC for bypass, decoupling, and filtering. Standard servers already use many MLCCs, but GPU boards raise volume, specification, and reliability requirements at the same time.
This change creates three profit channels. The first is higher value per system, as GPU boards directly raise the MLCC dollar content needed in each server. The second is better product mix: high-capacitance products carry higher ASP and depend more on yield and materials formulas. The third is lower supply elasticity: the higher the MLCC specification, the harder it is to expand quickly, making prices and gross margins easier to sustain.
Citi particularly emphasizes the significance of 100uF high-capacitance MLCC. 47uF is already higher than the common specification used in standard servers, while 100uF means more layers, heavier production load, and higher yield risk. Price increases in general MLCC can easily attract competitors, but high-capacitance MLCC requires long-term materials accumulation, powder control, thin-layer processes, and customer qualification. These barriers give Murata stronger pricing power.
MLCC Deep Update: AI Servers Push a Cyclical Component Toward a Power-Supply Bottleneck, and Who Can Turn Price Increases into Profit
Murata’s AI server opportunity therefore cannot be viewed only through “MLCC unit count.” Unit count determines total demand, capacitance determines ASP, yield determines margin, and customer qualification determines durability. Citi’s target-price upgrade essentially writes these four variables into the FY2027 to FY2029 income statement.
4. Earnings Bridge: Why Operating Profit Moves from Recovery to Step-Function Growth
Citi’s earnings forecast upgrades mainly land in operating profit and passive-component margins. Revenue growth is of course important, but Murata’s valuation elasticity mainly comes from margins. Once AI server MLCC enters the revenue mix as a high-specification product, ASP, gross margin, capacity utilization, and capital efficiency all improve together.
The key point in this table is the margin step-up; revenue growth is only the underlying variable. Revenue continues to grow from FY2026 to FY2029, but gross margin and operating margin rise faster. Operating margin increases from around 15% to above 32%, indicating the model assumes Murata sells more high-value MLCC and shifts its mix from ordinary specifications toward higher-margin, higher-barrier high-capacitance specifications.
Citi also raised its FY2027 assumption for yen-denominated MLCC ASP improvement from single digits to double digits. Three variables sit behind this: stronger AI server MLCC pricing assumptions, reduced price-decline pressure in consumer MLCC, and more favorable FX assumptions. FX also needs to be placed inside the validation framework. Murata reports profit in yen, so USD/JPY movements will amplify or weaken overseas revenue and profit elasticity. Not all gross-margin improvement can be attributed to product strength.
The structure is clear. Recovery in devices and modules from losses or low profitability can improve the floor, but the main re-rating line remains passive components, especially capacitors. Citi assumes roughly JPY 200.0bn of additional MLCC operating profit in FY2028 and raises the AI server-related weighting to a higher level. That is the core acceleration in the income statement.
5. Pricing Discipline: Murata Wants High-End Mix-Led Price Increases
The easiest mistake in MLCC investing is to treat every price increase as good news. When standard MLCC supply is tight, broad price hikes can quickly lift profit, but they also stimulate competitor expansion and compress leaders’ long-term share. The higher-quality route for Murata’s re-rating is high-end product-mix-led pricing. Supply-demand price hikes in ordinary products are better observed as an upside scenario.
Citi notes that Murata’s book-to-bill ratio reached 1.36 in January to March 2026, a ten-year high. That number naturally leads the market to expect price increases. At the same time, Citi also notes that the company remains cautious on company-led supply-demand price adjustments for ordinary products. Taiyo Yuden management has also publicly said it will pass through materials costs but has no plan for additional price hikes due to tight supply-demand. The attitude of industry leaders shows that the current price-increase logic still has boundaries.
The 2018-2019 MLCC cycle is worth reviewing. At that time, smartphone multifunctionality and automotive electronics lifted demand, and the industry went through a round of price increases. Trade frictions, economic slowdown, and channel inventory accumulation subsequently pressured prices. Murata’s AI server opportunity today is stronger, but the historical lesson has not disappeared. As soon as price increases spread to too many ordinary categories, inventory, substitution, and competitor expansion will appear together.
This is one of the most important points in the report. Citi does not treat broad price increases as the base assumption, but places them in scenario analysis. The base target price depends on mix upgrade, while the optimistic upside depends on industry-wide price increases. If Murata later appears to rely mainly on ordinary-product price hikes, while high-capacitance MLCC share, yield, and customer qualification do not improve together, the quality of JPY 15,000 would decline. If high-capacitance mix upgrade continues to be delivered, ordinary-product prices only need to remain stable for the base target price to have stronger support.
6. RoIC-WACC Valuation: JPY 15,000 Requires Murata to Become a High-Capital-Efficiency Asset
Citi prices Murata using a RoIC-WACC framework, which explains this upgrade better than a simple PE multiple. MLCC is a capital-intensive business. Capacity expansion requires investment in equipment, materials, sintering, inspection, and yield management. Valuation can keep moving higher only when incremental capital generates higher returns. The investment significance of AI server high-capacitance MLCC is precisely that the same production line, materials system, and customer qualification can generate higher profit and higher returns on capital.
This valuation is not cheap. Citi itself acknowledges that the target price implies a PE above Murata’s historical high range. For the market to accept this premium, it must see sustained RoIC improvement, not merely EPS upgrades. EPS can be amplified by FX, inventory, and short-term price increases; RoIC requires margins, capital turnover, and expansion discipline to work together.
The RoIC path can be understood as follows. In FY2027, AI server MLCC enters the income statement, and Murata moves from ordinary cyclical recovery to margin expansion. In FY2028, the revenue weighting of high-capacitance MLCC rises and operating margin continues to improve. In FY2029, expansion, yield, and product mix form a full-year contribution, pushing RoIC into the 25%+ range. As long as this path holds, the JPY 15,000 target price goes beyond PE expansion and becomes a capital-efficiency re-rating.
There is also valuation risk here. A roughly 43x FY2029 PE is already high for a traditional electronic-components company. If AI server MLCC demand slows, customers start pressing prices, 100uF high-capacitance product adoption is slow, or expansion yield falls short of expectations, the market will first compress the valuation multiple and then reduce earnings forecasts. Murata’s valuation elasticity is large, and so is its downside elasticity.
Japan Electronic Components Deep Update: High-Value AI Data Center Component Expansion and Valuation Discipline for Murata, TDK, and Ibiden
7. Murata’s Capability Migration: From Cyclical Leader to AI Server Power-Supply Materials Platform
Murata Manufacturing’s legacy strengths are scale, materials, yield, and customer coverage. In the smartphone era, it built advantages through miniaturization, high reliability, and large-scale supply capability. In the automotive electronics era, it extended product life cycles through automotive-grade qualification and high reliability. In the AI server era, it needs to migrate these capabilities into high-capacitance MLCC with higher capacitance, higher power, and higher stability requirements.
This migration is harder than ordinary capacity expansion. AI server customers want continuous supply, specification iteration, reliability, and co-development capability. The challenge of high-capacitance MLCC is not merely making capacitance larger. It involves ceramic powder, dielectric thin-layering, internal electrodes, stacking, sintering, inspection, and failure-rate management. The higher the capacitance, the greater the layer count, the narrower the process window, and the more sensitive the yield. If Murata can maintain high yield on the 100uF path, it will convert materials and process capability into margin.
This migration also explains why Murata can receive a higher valuation than ordinary MLCC companies. Ordinary MLCC price increases are about supply-demand; high-capacitance MLCC re-rating is about capability. Murata’s share advantage comes from yield and materials capability, while short-term pricing behavior is only an auxiliary variable. Citi estimates Murata’s share in high-capacitance AI server MLCC at about 50%, which means it sits in the first tier of the most difficult product layer.
Of course, 50% share also brings higher expectations. The market will require Murata to deliver high-capacitance products more consistently than peers such as Samsung Electro-Mechanics and Taiyo Yuden. If competitors catch up in yield, Murata’s share and price premium will both face pressure. If customers intentionally support second suppliers for supply-chain security, Murata may still retain a leading share, but excess margin could be diluted.
8. Peer Comparison: Murata Captures Specifications, Samsung Electro-Mechanics Captures Elasticity, Taiyo Yuden Captures the Cycle, and Yageo Captures Inventory and Channels
Peer comparison in the MLCC industry cannot be ranked only by “who raises prices more.” Different companies have different product tiers, customer structures, inventory positions, and expansion capabilities. Murata’s core is high-end AI server and high-capacitance MLCC. Samsung Electro-Mechanics also has high-end capability, but its profit elasticity and group supply-chain position differ. Taiyo Yuden is more affected by the ordinary MLCC cycle and capacity utilization. Yageo has its own elasticity in channels, M&A;, and industrial customers.
The conclusion from this table is direct: Murata is not cheap in an MLCC price-increase trade, but it is the clearest target for high-end specification upgrade. Cheap companies need to prove cyclical upturn; high-end companies need to prove barrier realization. Citi’s higher target price for Murata is effectively a bet that profit quality in high-capacitance MLCC is stronger than ordinary MLCC price increases.
MLCC Deep Dive: JPMorgan’s Sharp Upgrade, from Cyclical Recovery to Structural Re-rating as AI Servers Rewrite the Supply-Demand Gap
From the supply-chain perspective, the AI server materials chain has already seen two types of re-rating. One is “physical interconnect constraints” such as ABF substrates, PCB, CCL, and connectors. The other is “power stability constraints” such as MLCC, power management, and magnetic components. Murata belongs to the second category. It does not determine compute power directly like GPUs, nor package area like ABF, but it determines whether high-power systems can operate stably. This position is not conspicuous, but it is hard to bypass.
9. Relationship with ABF and PCB: The AI Server Materials Chain Spills Over from Main Chips to the Power Layer
The re-rating sequence in the AI server supply chain previously began with GPU and HBM, then moved to packaging, ABF substrates, PCB/CCL, thermal management, and power. The MLCC re-rating came later because its value share in the system is not high, and the market easily treats it as an ordinary passive component. But as GPU board power consumption, power density, and transient current continue to rise, MLCC begins to move from a “low-presence component” to a “high-reliability power-supply material.”
This spillover path has three stages. In the first stage, AI server shipment growth drives growth in MLCC units per system. In the second stage, GPU board current and power consumption rise, the mix of high-capacitance MLCC increases, and ASP and gross margin begin to improve. In the third stage, customers incorporate high-capacitance MLCC into long-term supply security, and leading companies obtain a longer profit cycle through qualification, yield, and expansion. Murata is now positioned in the migration from the second stage to the third stage.
The Second Re-rating of the AI Server Materials Chain: From Passive Components to PCB/CCL, ABF Substrates, and Test Equipment
Compared with ABF and PCB, MLCC is characterized by low value per unit, large aggregate volume, and fine specification stratification. ABF substrates are often driven by a single project, customer, or product generation, while MLCC is dispersed across many board and power-supply scenarios. This difference makes MLCC revenue recognition smoother and demand validation harder. Investors cannot look only at the launch date of a single GPU platform. They also need to watch AI server system shipments, board design, customer qualification, and supplier share.
Murata benefits from exposure to AI servers while retaining a base in automotive, industrial, and consumer electronics. The risk is that valuation will capitalize the AI server contribution first, while any inventory or pricing pressure in ordinary businesses will lower overall profit quality. This mix makes Murata steadier than a single AI materials company, but more expensive than an ordinary MLCC cyclical stock.
10. Three Scenarios: JPY 15,000 Is the Base Case, JPY 18,000 Requires Broad Price Increases, and the Stress Case Depends on Inventory and Yield
Citi’s JPY 15,000 target price can be viewed as the base case. The core conditions are high growth in AI server MLCC, product-mix improvement, higher passive-component margins, and RoIC uplift. JPY 18,000 is closer to an upside scenario and requires ordinary MLCC to see broad price increases of more than 10%, without triggering excessive expansion or customer substitution. The stress case comes from the reverse combination of price, inventory, expansion, and competition.
The base case and upside case should not be mixed together. JPY 15,000 requires delivery of high-end mix upgrade, while JPY 18,000 requires broader industry price increases. If future evidence shows only ordinary-product price increases, without more evidence of high-capacitance MLCC specification upgrade and customer qualification, the market will suspect this is merely an ordinary cyclical rally. If high-capacitance MLCC keeps expanding while ordinary-product prices remain stable, the base case is healthier.
The key in the stress case is that profit quality falls short of expectations. For example, slow yield ramp in high-capacitance products could keep costs above model assumptions. Customers could introduce more suppliers to reduce risk, lowering Murata’s share. Inventory in ordinary consumer and automotive MLCC could rise again, dragging overall margins. FX could shift from favorable to unfavorable, amplifying profit volatility. All of these variables would first pressure the high valuation.
11. Data Framework: In the Next Stage, Look First at Order Quality, Then Profit Quality
Murata’s follow-up validation cannot look only at revenue growth. In an AI server cycle, revenue growth may come from genuine demand, but also from customers pre-building inventory. ASP increases may come from specification upgrade, but also from short-term supply-demand tightness. Gross-margin improvement may come from high-capacitance products, but also from FX and low-cost inventory. To judge the quality of the JPY 15,000 target price, orders, pricing, margins, inventory, and capital expenditure need to be linked.
This sequence matters. Orders lead, ASP and gross margin then confirm, while inventory and cash flow reveal risks last. If orders, ASP, and gross margin are strong while inventory and cash flow are healthy, the market will be more willing to believe Murata has entered a new profit step. If orders are strong but inventory also rises quickly, or if revenue is strong but gross margin does not rise, the market will first mark down the high valuation.
Citi’s book-to-bill figure of 1.36 is attractive, but it is only the starting point. The real validation is whether orders can convert into high-capacitance MLCC revenue, whether revenue can convert into gross margin, and whether gross margin can convert into RoIC. Murata has repeatedly experienced supply-demand mismatches in the ordinary MLCC cycle. AI servers improve demand quality, but they do not eliminate cyclical risk.
12. Why Citi Is More Aggressive Than the Previous Market View: It Turned “Higher Server Specifications” into Income-Statement Assumptions
Research on Murata and MLCC has moved from “AI drives MLCC demand” to “AI server high-capacitance MLCC changes profit distribution.” Citi’s update further writes that judgment into earnings forecasts: stronger AI server MLCC pricing assumptions, higher AI server-related weighting in FY2028, a larger operating profit upgrade, and RoIC valuation based on a later year.
Murata Manufacturing Deep Update: AI Server MLCC’s Profit Gate and Valuation Discipline
The more aggressive assumptions are mainly in three areas. First, Citi places more weight on server specification upgrades; AI server unit growth is only the base variable. Second, Citi places more emphasis on the yield barrier for high-capacitance MLCC, believing Murata’s share and margins can be sustained for longer. Third, Citi is willing to use a lower risk premium and a later valuation year, showing it believes this round of profit improvement has a chance to last for multiple quarters.
These aggressive assumptions are also easier to falsify. If MLCC usage per AI server does not continue to rise, or 100uF product progress is slow, ASP improvement will be weaker than the model. If peers such as Samsung Electro-Mechanics and Taiyo Yuden catch up faster in high-capacitance product yields, Murata’s share may fall below the roughly 50% assumption. If ordinary consumer and automotive MLCC drag overall margins, the AI server contribution will be diluted. Citi’s high target price means it needs more positive feedback.
13. Historical Positioning: What Really Makes Murata Valuable Is Turning Materials Capability into Customer Standards
Murata Manufacturing’s long-term advantages in the MLCC industry are in-house materials development, process control, miniaturization, reliability, scale manufacturing, and customer co-development. AI servers place these capabilities into a higher-value application scenario.
MLCC looks like a standardized component, but high-end products are not standardized. In high-reliability scenarios, customers do not compare only price. They also compare failure rates, lead times, long-term supply capability, and design support. Murata’s entry into the core high-capacitance MLCC supply chain for AI servers shows that its materials and manufacturing capabilities have been incorporated into customers’ system designs. Once this position is formed, replacement costs are higher than for ordinary MLCC.
This is the core of the “asset-attribute change.” In the past, Murata was a high-quality cyclical stock, with profit fluctuating with smartphone, automotive, and industrial demand. AI servers add a layer of power-supply materials platform attributes: Murata does not directly sell compute power, but it sells high-reliability power-supply components required for stable operation of compute systems. This change raises the margin ceiling, and also increases valuation volatility.
Murata still needs to manage legacy businesses. Consumer electronics demand, automotive electronics inventory, industrial customer recovery, and FX all affect total profit. High-end AI server MLCC can lift valuation, but it cannot fully shield the traditional cycle. What investors really need to watch is whether high-end mix improvement is large enough to offset volatility in ordinary businesses.
14. Risk Breakdown: Under a High Valuation, Any Failed Validation Link Will Be Amplified
The JPY 15,000 target price gives the market high expectations. Risks should be judged by the same high standard. Murata faces the risk of validating multiple variables at the same time. AI server MLCC demand, ASP, yield, expansion, inventory, FX, ordinary businesses, and the competitive landscape will all affect valuation if any one is materially below the model.
The common point across these risks is that they affect valuation before earnings. Market pricing for high-valuation stocks is more sensitive, and investors do not necessarily wait for the income statement to deteriorate materially before adjusting expectations. A decline in book-to-bill from a high level, slower-than-expected customer adoption, inventory growth, or gross margin below model could all make the share price react first.
Murata’s strengths are strong capabilities, high share, and good customer stickiness. Its weakness is that valuation has already discounted a great deal of future success. This combination is best tracked through an “evidence-weighted” approach: each quarter that adds a high-quality piece of evidence makes JPY 15,000 more stable; each quarter that produces counter-evidence on profit quality lowers the valuation weight.
15. Linkage with Previous MLCC Reports: Industry Logic Has Evolved from “Shortage” to “Who Can Turn Shortage into RoIC”
The MLCC industry has moved from ordinary supply-demand recovery into a second stage. The first stage looks at shortage and orders, the second at price increases and inventory, and the third at who can convert specification upgrade into long-term capital return. Murata now represents the third stage. It needs to prove that AI server high-capacitance MLCC has the product-line attributes to continuously lift RoIC, rather than being a one-off cyclical rally.
Yageo Deep Update: AI Demand Begins Tightening MLCC Supply, and How Mid- to Low-Capacitance Price Increases Rewrite the 2027-2028 Income Statement
Yageo, Taiyo Yuden, Samsung Electro-Mechanics, and Murata will all benefit from MLCC strength, but in different ways. Yageo and Taiyo Yuden are more easily seen as price and capacity-utilization elasticity. Samsung Electro-Mechanics and Murata rely more on high-end specifications, while Murata receives a higher valuation anchor because of materials and yield advantages. This ranking will change dynamically, and the follow-up depends on customer qualification, expansion, inventory, and pricing discipline.
If the industry only stays in shortage, the best trade may be the company with the greatest cyclical elasticity. If the industry enters the high-specification power-supply materials stage, the best asset will be the company that can turn specification upgrade into RoIC. Citi’s move to lift Murata’s target price to JPY 15,000 is effectively a choice of the second worldview.
16. Profit Bridge Breakdown: From GPU Board to RoIC, There Are Six Gates in Between
The most important part to unpack in Citi’s target-price upgrade is the earnings transmission chain. AI server demand does not automatically become Murata profit. It must first enter GPU board design, then high-capacitance MLCC specifications, then customer qualification and mass-production yield, and only then appear as ASP, margin, and RoIC. If any gate fails to open, the earnings upgrade will be weakened.
Among these six gates, expansion yield is the easiest to underestimate. Strong AI server customer demand only shows pull from the order side. Whether Murata can turn orders into high-quality profit depends on whether high-capacitance MLCC capacity can be released steadily. If yield is high, new capacity quickly enters high-value products, and depreciation pressure is covered by ASP and gross margin. If yield is low, stronger orders create greater delivery and cost pressure, slowing profit delivery instead.
The second easily underestimated variable is customer qualification. High-capacitance MLCC has gone beyond component procurement and started to enter the complete server power-supply design. Once customers complete design validation, they place greater emphasis on supply stability, failure rate, and long-term iteration. This gives Murata stronger stickiness and means share changes will not be as rapid as in ordinary consumer MLCC. However, customers will still support second suppliers to avoid single-supplier risk, so share advantage must be continuously proven through yield and delivery.
The third variable is product mix. In Citi’s model, yen-denominated MLCC ASP improvement comes from structure, price, and FX together. The truly high-quality part is structural improvement, meaning more AI server high-capacitance products enter revenue. FX and ordinary price increases can amplify short-term profit, but structural improvement is what keeps lifting RoIC. In follow-up tracking, if the company only discloses total ASP growth, investors still need to keep separating contributions from high-capacitance products, ordinary products, and FX.
From an investment perspective, Murata now wins through “specification upgrade x yield x customer qualification x capital efficiency.” Volume can only explain revenue growth; yield and specifications explain margin; customer qualification explains durability; RoIC explains valuation. Citi’s target price jump from JPY 3,900 to JPY 15,000 is really a move from a volume framework to a RoIC framework.
17. Expansion and Supply: 20% Additional Capacity Is Only the Starting Point; Capacity Quality Is the Key
Citi notes that Murata announced roughly 20% additional capacity expansion on top of ordinary annual expansion. This figure naturally leads the market to think of shortage, but for Murata, the core of expansion is not making capacity larger. AI server high-capacitance MLCC requires usable capacity, qualified capacity, and high-yield capacity. If nominal capacity increases but cannot translate into yield for high-capacitance products, it will instead bring depreciation and inventory pressure.
This point is important because the MLCC industry has repeatedly seen cycles of “capacity expands first, demand weakens later, prices fall.” Murata’s advantage today is that high-capacitance MLCC capacity is harder to replicate and has higher expansion quality. The risk is that the market may treat all expansion as high-end capacity. As long as management continues to emphasize high-capacitance product yield, customer qualification, and mix improvement, expansion is more likely to be a positive signal. If only total capacity, inventory, and gross margin fail to improve together, expansion becomes a risk.
Capacity quality will also affect the competitive landscape. Samsung Electro-Mechanics and Taiyo Yuden are not without high-end capability, and customers will introduce multiple suppliers for supply security. The premise for Murata maintaining roughly 50% high-capacitance share is that new capacity passes customer qualification faster than peers and has more stable yield. If peer expansion is smooth, Murata will still benefit from industry growth, but excess margin will decline. If peer expansion is slow, Murata’s delivery capability will become stronger pricing power.
Citi writes Murata’s high-end share and margin into its model, effectively treating expansion quality as a key assumption. This assumption will be easiest to observe in three types of data: whether passive-component margin keeps rising, whether free cash flow remains healthy after capex increases, and whether inventory turnover stays stable. If all three improve together, expansion is creating high-quality profit. If they diverge, expansion is consuming cash flow or pulling forward inventory.
18. Reverse-Engineering the Target Price: What Evidence Is Needed for JPY 15,000, and What Extra Conditions Are Needed for JPY 18,000
A target price can be reverse-engineered into operating assumptions. Citi’s JPY 15,000 target price corresponds to sustained high-capacitance MLCC ramp, rising margin, higher RoIC, and a lower risk premium. The JPY 18,000 upside scenario requires ordinary MLCC to enter broader price increases as well, without damaging long-term share and customer relationships. Separating these two bases is necessary to read incoming data.
Therefore, the difference between JPY 15,000 and JPY 18,000 reflects two different sets of evidence. The base target price mainly depends on AI server high-end mix, while the upside scenario also requires ordinary-product price increases to spread. If ordinary-product prices rise but inventory begins to accumulate, the market will not fully capitalize it. If ordinary-product prices remain stable but high-capacitance MLCC margin continues to rise, JPY 15,000 has better quality.
This reverse-engineering framework can also handle share-price volatility. If Murata’s share price approaches the target price in the short term, investors need to assess whether new evidence is approaching the JPY 18,000 scenario. If the share price pulls back, the first question is whether this is market valuation compression or deteriorating operating evidence. The former may just be high-valuation volatility; the latter affects the target price itself. High-valuation assets are most vulnerable to evidence gaps and most need consecutive quarterly delivery.
19. How to Track the Next Four Quarters: Look First at High-Capacitance MLCC, Then at Drag from Ordinary Businesses
Over the next four quarters, Murata’s tracking priorities can be arranged in time order. Step one is orders, step two is ASP and gross margin, step three is inventory and cash flow, and step four is management commentary on expansion and customer adoption. Tracking in this order helps avoid being misled by one quarter of high revenue or high profit.
In this roadmap, the combination of step two and step three is the most important. If ASP growth comes from mix improvement, gross margin should improve in tandem. If ASP growth comes from short-term price increases, gross margin will also improve, but inventory and customer order quality are more likely to show later volatility. Step four, inventory cash flow, is needed to distinguish the two.
Ordinary businesses also cannot be ignored. However strong Murata’s AI server story is, total revenue still includes smartphones, automotive, industrial, and modules. If ordinary businesses decline, AI server high-capacitance MLCC needs an even stronger contribution to lift overall margin. If ordinary businesses are stable, the AI server contribution will enter the income statement more clearly. If ordinary businesses become a material drag, the market will reassess whether Murata can move beyond the traditional MLCC cycle.
In terms of pace, quarterly performance in FY2027 will validate “margin starting to rise,” FY2028 will validate “higher high-capacitance MLCC weighting,” and FY2029 will validate “RoIC entering a new platform.” Citi has already placed FY2029 into the valuation base, so the market will trade this path in advance and punish deviations on the path in advance as well.
20. Financial Quality: Earnings Upgrades Must Move Through Inventory, FX, and Capex
The core of Murata’s re-rating is profit quality. Operating profit upgrades are important, but they only become sustainable valuation after passing through three filters: inventory, FX, and capex. High-capacitance MLCC margins are high, but capex is also high. Orders are strong, but inventory-management pressure also rises. A favorable yen exchange rate helps profit elasticity, but the market will discount part of that. Separating these variables is necessary to judge the quality of the JPY 15,000 target price.
Inventory is the financial-statement item that exposes cyclical risk earliest. When AI server demand is strong, both customers and suppliers are more willing to build inventory. Reasonable stocking improves supply stability, but overly rapid accumulation pulls future demand into the current financial statements. In historical MLCC cycles, channel inventory has often been amplified near demand peaks, followed by pressure on both prices and shipments. If Murata wants to prove this re-rating has high quality, inventory growth needs to match AI server orders and high-capacitance product delivery.
Cash flow is the second filter. The income statement can first reflect ASP and product mix, while cash flow more honestly reflects customer payments, inventory, and capex. If Murata’s net profit rises and operating cash flow improves at the same time, it indicates high-capacitance MLCC profit is turning into real cash. If net profit rises but operating cash flow lags materially, the market will worry that inventory, receivables, and stocking are consuming profit quality.
Capex is the third filter. Citi’s model has already incorporated expansion and high-end product contributions into future profit. Expansion itself is not negative; the key is whether new capacity enters high-end products. If passive-component margin and RoIC rise together after capex increases, expansion is creating high-value capacity. If margins decline after capex increases, depreciation, yield, or capacity utilization has started to drag on the model.
FX needs to be separated as well. Citi used more favorable FX assumptions when raising forecasts. A weaker yen increases overseas revenue translation and profit elasticity. This variable can support earnings upgrades, but it cannot be treated as a long-term barrier. Investors should separate the FX contribution from the product-mix contribution: FX contribution lifts short-term EPS, while product-mix contribution lifts long-term RoIC.
The conclusion on financial quality is simple. To support the JPY 15,000 target price, Murata needs profit growth, cash flow, inventory, and capex to remain aligned. A single quarter of earnings beat is only the first step. Consecutive quarters of healthy cash flow and inventory will persuade the market that AI server MLCC has pushed Murata into a new profit step.
21. How to Read Management Commentary: Listen Less to Price-Hike Slogans, More to Mix and Discipline
When listening to Murata management going forward, separate three types of commentary. The first is demand commentary, such as AI servers, high-capacitance MLCC, customer qualification, and order visibility. The second is supply commentary, such as expansion, yield, lead times, and capex. The third is pricing commentary, such as whether ordinary MLCC prices will rise, whether materials costs can be passed through, and whether customers accept high-capacitance product pricing. Together, these three categories form a complete judgment.
Specifically, it can be read this way. If management emphasizes strong AI server demand, the positive signal is higher visibility for high-capacitance MLCC orders, while the caution point is that shipments and customer mix still need confirmation. If management emphasizes smooth high-capacitance product adoption, the positive signal is progress in customer qualification and specification upgrade, while the caution point is that yield and mass-production scale still need to be checked. If management emphasizes additional capacity expansion, the positive signal is that the company sees medium-term demand, while the caution point is ordinary capacity oversupply and depreciation pressure. If management emphasizes stable ordinary-product pricing, the positive signal is good pricing discipline and limited cyclical backlash, while the caution point is weaker short-term profit explosiveness. If management emphasizes materials cost pass-through, it is more about protecting gross margin. If management emphasizes controllable inventory, it directly improves the credibility of profit quality.
This framework helps readers avoid two misreadings. The first is to equate “strong demand” directly with strong profit. Strong demand only proves there is pull from the order side; profit still depends on specifications, yield, ASP, and cost. The second is to interpret “the company is not actively pushing broad price increases” as insufficient elasticity. For Murata, broad ordinary-product price increases would lift short-term profit, but they would also increase cyclical backlash. High-capacitance product mix-led pricing is better suited to supporting long-term valuation.
If management continues to emphasize AI server customer adoption, high-capacitance product yield, and expansion discipline, the market will be more willing to place Murata in a high-RoIC framework. If management shifts toward emphasizing ordinary-product price increases, longer short-term lead times, and industry shortages, the market will first trade profit elasticity but will also inspect inventory more quickly. If management starts emphasizing demand uncertainty, customer inventory adjustment, or slower expansion pace, the JPY 15,000 target price will need to be reassessed.
Therefore, Murata’s subsequent conference calls and results briefings should not be read through a single keyword. A better reading is: demand commentary shows the real pull from AI servers; supply commentary shows the quality of high-end capacity; pricing commentary shows the ratio of mix-led pricing to ordinary price increases; financial commentary shows whether profit, inventory, and cash flow are moving together. Only when these four signals are aligned can Citi’s upgrade move from report assumption into company operations.
22. Conclusion: Murata Has Entered a High-Standard Delivery Period, and JPY 15,000 Requires Profit Quality
Citi’s report confirms the latest stage of Murata Manufacturing’s re-rating: AI server MLCC has moved from industry narrative into the earnings model, the target price has been raised from JPY 3,900 to JPY 15,000, and the rating has been upgraded to Buy. The core of this change is that high-capacitance MLCC lifts ASP, margin, and RoIC together, while ordinary MLCC supply-demand tightness only provides auxiliary elasticity.
Murata’s upside logic is clear. AI servers raise MLCC value content per system, migration from 47uF to 100uF raises product barriers, Murata has share and yield advantages in high-capacitance products, passive-component margin rises materially, and the RoIC-WACC model therefore produces a higher valuation. As long as this evidence continues to be delivered, Murata will move further from a high-quality cyclical stock toward a leader in AI server power-supply materials.
Murata’s pressure is equally clear. The JPY 15,000 target price implies a high PE and strong RoIC assumptions. Any adverse movement in orders, ASP, yield, inventory, expansion, or FX will be amplified. The JPY 18,000 upside case requires broader ordinary MLCC price increases, while the base target price relies mainly on high-end mix upgrade. Separating the two bases is necessary to avoid conflating cyclical price increases with asset re-rating.
In the next stage, tracking Murata only by revenue will not be enough. The true indicators to watch are order quality, AI server weighting, MLCC ASP, passive-component margin, inventory cash flow, and expansion yield. They determine whether Murata can turn the AI server power-supply bottleneck into long-term capital efficiency. If these indicators continue to improve together, the JPY 15,000 target price becomes more stable. If the indicators begin to diverge, the market will place Murata back into the MLCC cyclical-stock framework.
Japan Electronic Components Deep Update: Morgan Stanley Asia Investor Survey, How AI Servers Widen the MLCC and ABF Valuation Gap