
Murata Manufacturing Deep-Dive Update: Data Center Revenue Doubles, Validating MLCC Price Increases at 95% Utilization
目录
Executive Summary
1. What This Report Truly Changes Is the Strength of the Evidence
2. First Quarter Beat Expectations, but Revenue Guidance Rose Faster Than Profit Guidance
3. Data Centers Double: AI MLCCs Are Now the Core Financial Driver
4. Book-to-Bill of 1.47: Genuine Shortages and Channel Stockpiling Coexist
5. The Core of Price Increases: Distributors Are the Starting Point, but Major Customers Are the Endgame
6. The Profit Ceiling: The Components Business Is Very Strong, but the Group Still Has Leakage
7. Valuation and Validation: ¥15,200 Requires Consistent Delivery
本内容基于公开资料和研报数据整理,不构成任何投资建议,不代表任何个人观点,仅供学习参考,请理性阅读
The first-quarter beat is only the beginning: orders, backlog, and data center revenue are all accelerating, but the true determinant of the earnings ceiling is whether price increases can extend beyond distribution channels, as well as yields and costs at 95% utilization.
Executive Summary
Murata Manufacturing’s first-quarter operating profit was JPY98.5 billion, above JPMorgan’s JPY86.5 billion forecast and the Bloomberg consensus of JPY90.5 billion. The company raised its full-year operating profit guidance from JPY380 billion to JPY430 billion, but the revised figure is already close to the JPY433.3 billion market consensus. The view that “guidance is conservative” requires validation from subsequent results and cannot rely solely on broker assessments.
Data centers have moved from narrative to reported financials. First-quarter data center revenue was JPY69.7 billion, up 81% year over year and 25% quarter over quarter; full-year guidance was raised from JPY325 billion to JPY370.6 billion, implying expected year-over-year growth of 110%. Data centers’ share of group revenue has also risen to 13.9%, with the new guidance implying approximately 17.6% for the full year.
There is hard evidence of tight supply and demand, but order quality remains uncertain. The capacitor book-to-bill ratio rose from 1.36 to 1.47, while first-quarter orders increased 85.5% year over year and backlog rose 170.5%. However, orders from long-term customers were broadly in line with expectations, with more of the incremental upside coming from distributors. This may therefore reflect genuine shortages, but may also include channel stockpiling.
The key issue for price increases is the customer segment. Distributors are only the starting point; large customers will determine the full-year pricing level. The company has only explicitly said it is considering price increases for distribution products facing supply-demand imbalances, while continuing to emphasize long-term relationships and annual autumn negotiations for large customers such as automakers. Utilization of 95% creates substantial earnings sensitivity, but also means that yield issues, outsourcing costs, and delivery constraints will surface more quickly.
The JPY15,200 price target depends on a long-term margin step-up; current-year guidance is not the core valuation anchor. JPMorgan values the company using FY2029 EPS of JPY541 under its methodology and a 28x P/E multiple. This requires AI-server MLCC demand, pricing, yields, capacity efficiency, and loss reduction in non-core businesses all to materialize; any slowdown in any part of the chain would hit the valuation first.
1. What This Report Truly Changes Is the Strength of the Evidence
The full deep dive published in June previously characterized Murata Manufacturing as the “earnings gatekeeper” for AI-server MLCCs: rising GPU power consumption and rack density would simultaneously increase MLCC content, capacitance requirements, process complexity, and customer qualification barriers. The greatest uncertainty at the time was when demand would move from industry research into reported financials.
The July results provided the first systematic validation: data center revenue increased 81% year over year, including 75% to 80% growth in MLCC revenue; the capacitor book-to-bill ratio rose to 1.47; utilization remained around 95%; and the company began discussing price increases for certain distribution products. Demand, capacity, and pricing converged in the same quarter for the first time.
But this does not mean the “earnings gate” has fully opened. The new data validates AI-server demand and high utilization, but has not yet demonstrated that price increases can extend to large, long-term customers, nor has it demonstrated that capacity utilization can translate into higher margins without leakage. This update should therefore advance the previous view from “the direction is valid” to “volumes have materialized, while pricing and quality await validation.”
Murata Manufacturing Deep Dive: How AI-Server MLCCs Become an Earnings Gatekeeper
2. First Quarter Beat Expectations, but Revenue Guidance Rose Faster Than Profit Guidance
First-quarter revenue was JPY502.3 billion, up 20.7% year over year; operating profit was JPY98.5 billion, up 59.8%, with the operating margin rising from 14.8% to 19.6%. This was a high-quality start, but the guidance contains another signal: the company raised full-year revenue guidance from JPY1.96 trillion to JPY2.11 trillion, an increase of JPY150 billion, while operating profit guidance increased by only JPY50 billion. The implied operating margin on this incremental revenue is approximately 33%, which is solid but still below the exceptionally high incremental margin that the market envisioned at elevated utilization.
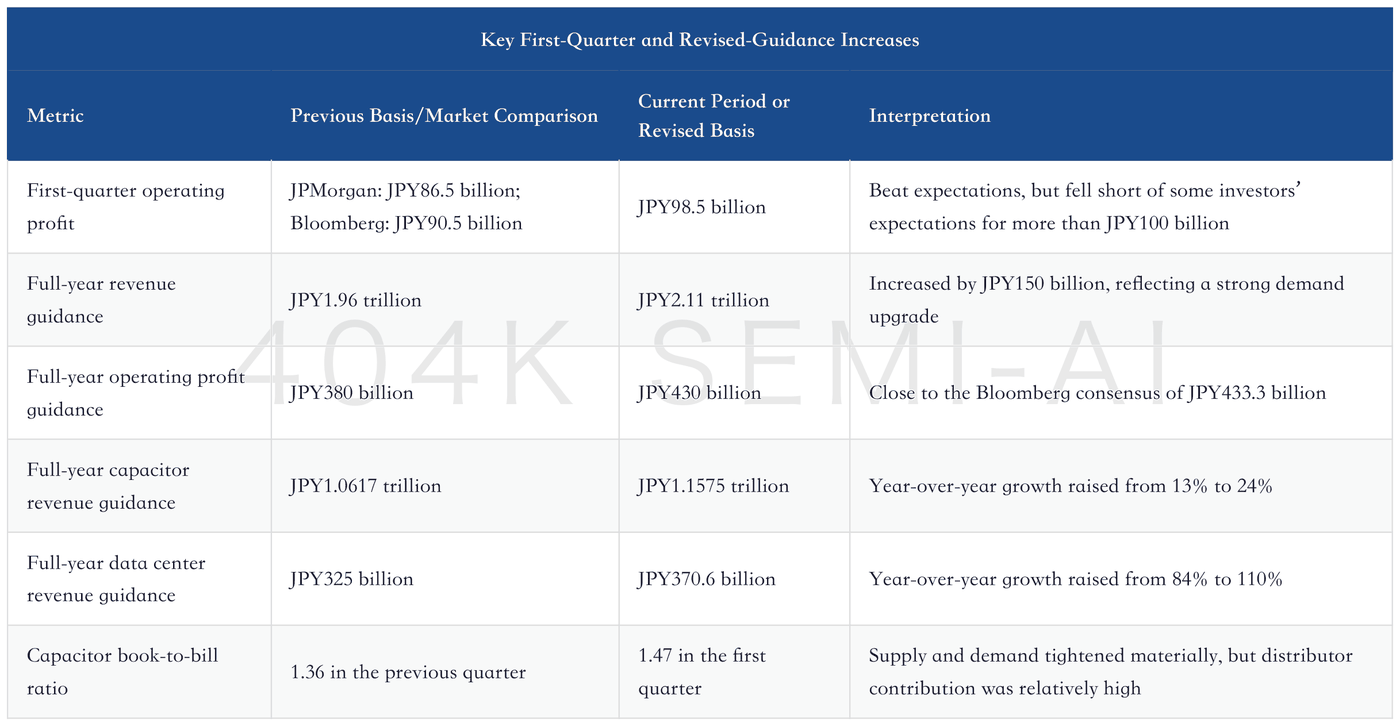
The company attributed the gap to higher raw-material costs, including precious metals, as well as higher fixed costs and manufacturing outsourcing expenses. Foreign exchange also improved reported revenue and profit: the company changed its full-year USD/JPY assumption from 150 to 156 and will use 155 from the second quarter onward. The profit-guidance increase therefore cannot be attributed entirely to MLCC pricing power; subsequent analysis should focus more on margins excluding foreign-exchange and one-off effects.
3. Data Centers Double: AI MLCCs Are Now the Core Financial Driver
Data centers are the most certain source of this guidance increase. First-quarter data center revenue was JPY69.7 billion, representing 13.9% of group revenue; based on full-year guidance of JPY370.6 billion, the share will reach 17.6%. More importantly, the business mix is changing: data centers are approaching the status of another core application alongside communications and automotive.
Growth is not being driven solely by system volumes. The company disclosed that, looking only at MLCCs within data centers, first-quarter revenue increased 35% to 40% quarter over quarter and 75% to 80% year over year, with full-year growth expected to exceed 100%, covering both AI and general-purpose servers. This is consistent with the previous industry view: AI servers simultaneously increase power consumption, board-space requirements, and power-integrity thresholds, driving higher per-system content, higher-capacitance specifications, and higher unit prices.
The next test for this thesis shifts to incremental profit as scale expands. If data center revenue continues to double while the group operating margin remains around 19% to 21%, this would indicate that raw materials, outsourcing, or yields are absorbing the mix benefit; only if the data center revenue share and the components-business margin rise in tandem can Murata demonstrate that it has converted specification barriers into financial barriers.
4. Book-to-Bill of 1.47: Genuine Shortages and Channel Stockpiling Coexist
First-quarter capacitor orders were JPY415.5 billion, up 85.5% year over year and 26% quarter over quarter; backlog was JPY402.2 billion, up 170.5% year over year and 49.4% quarter over quarter. The company-wide book-to-bill ratio was 1.34, while the capacitor ratio was 1.47. These figures demonstrate that shipment growth has not exhausted demand; instead, unfilled orders have expanded further.
However, order mix matters more than total orders. Management explicitly stated that orders from long-term customers were broadly in line with expectations, while distributor orders increased more substantially. Distributors have an incentive to build inventory in advance when lead times lengthen and expectations of price increases emerge, and may even place duplicate orders. The 1.47 ratio therefore cannot be mechanically extrapolated into actual consumption over the next several quarters.
The most informative falsification test will come in the second quarter. The company guides to second-quarter capacitor sales of JPY287.1 billion, only 2% above the first quarter’s JPY282.5 billion. If the book-to-bill ratio remains high, backlog continues to grow, and shipments rise moderately, the shortage is capacity-constrained; if the book-to-bill ratio and distributor orders decline rapidly, part of the first-quarter peak should be attributed back to channel inventory.
5. The Core of Price Increases: Distributors Are the Starting Point, but Major Customers Are the Endgame
Murata Manufacturing is considering price increases for certain distributor products, provided that their supply-demand balance has been disrupted and orders have surged. This marks a clear turning point in the pricing cycle, as Murata has moved from “narrowing price declines” to discussing selective increases. However, this is still not a broad-based price increase.
For automotive and other long-term customers, the company emphasized supply assurance, long-term trust, and “win-win” outcomes, and will begin annual negotiations in the autumn, but did not disclose how costs would be passed through or whether prices would rise. This distinction matters: distributor-channel pricing responds quickly, but offers limited revenue stability and scale; major-customer contracts respond slowly, but determine the full-year average selling price and normalized margin level.
Price increases will also be constrained by the supply strategy. Murata will prioritize existing customers, while planning to first raise the productivity of current capacity before expanding capacity to cover the remaining shortfall. This is consistent with its new official guidance: the full-year revenue forecast was raised by ¥150.0 billion, while capital expenditure was increased only from ¥250.0 billion to ¥255.0 billion, and the post-tax ROIC forecast was raised from 12.3% to 13.9%, indicating that management is prioritizing incremental output from existing capacity and productivity improvements. For high-end MLCCs used in AI servers, the key to productivity improvement is increasing effective output without compromising yield or reliability. With utilization already close to 95%, profit leverage is considerable, but delivery delays, lower yields, and rising outsourcing costs may also be amplified simultaneously.
Murata Manufacturing In-Depth Update: The Profit Gate and Valuation Discipline for AI-Server MLCCs
6. The Profit Ceiling: The Components Business Is Very Strong, but the Group Still Has Leakage
In Q1, the Components business generated external revenue of ¥346.8 billion, total segment revenue of ¥349.3 billion, and operating profit of ¥113.6 billion, with an official segment operating margin of 32.5%; the Devices & Modules business generated external revenue of ¥151.4 billion, an operating loss of ¥12.9 billion, and an operating margin of -8.5%. The Components business’s profit already exceeded the group’s total operating profit of ¥98.5 billion, clearly showing that the MLCC thesis is strong, but group profit continues to be diluted by non-core businesses.
The company’s full-year target for the Devices & Modules business is merely breakeven, making incremental improvement in this segment one of the most overlooked near-term sources of profit. Conversely, if its losses persist, the market may mistakenly treat the Components business’s high margin as the group margin. Q1 also recorded ¥4.0 billion in gains from US tariff refunds, while JPMorgan estimates that overall one-off factors contributed approximately ¥1.0 billion on a net basis. This does not change the direction of the Q1 earnings beat, but it should be excluded from recurring profit in financial models.
JPMorgan believes that, if USD/JPY is approximately 160, full-year operating profit of ¥480.0 billion to ¥500.0 billion may be achievable. However, the report’s formal forecast table still shows ¥411.7 billion, below the company’s new guidance of ¥430.0 billion. There is a clear difference in timing and basis here: ¥480.0 billion to ¥500.0 billion should be treated as an upside scenario in the commentary, rather than a formally updated base-case forecast. This distinction is especially important to avoid double-counting optimistic expectations.
7. Valuation and Validation: ¥15,200 Requires Consistent Delivery
JPMorgan maintained its Overweight rating and ¥15,200 price target, versus a share price of ¥7,416 on the report date. The price target is based on its FY2029 EPS estimate of ¥541 and a 28x P/E multiple. The 28x multiple is derived from the sector average of 20x and Murata’s 1.4x relative premium at the peaks of the two MLCC cycles in 2017–2018 and 2020–2021.
This valuation combines long-dated earnings with a high multiple. On a fiscal-year-end reporting basis, JPMorgan expects Murata Manufacturing’s operating margin to rise from 15.4% in the fiscal year ending March 2026 to 20.7% in the fiscal year ending March 2027, 28.6% in the fiscal year ending March 2028, and 36.4% in the fiscal year ending March 2029. This effectively assumes that high-end MLCCs for AI servers can drive sustained improvements in revenue mix, pricing, and utilization, ultimately translating into a margin uplift beyond a normal cyclical recovery. Since the price target is underwriting a long-term worldview, the market will be more sensitive to any loss of momentum in an interim quarter.
Five groups of indicators should be monitored continuously. The first is whether Q2 capacitor sales can reach ¥287.1 billion and whether the book-to-bill ratio and order backlog remain strong. The second is whether the full-year data-center guidance of ¥370.6 billion and the doubling of MLCC growth can be delivered. The third is the divergence between distributor orders and long-term customer orders, which can be used to assess the channel-inventory component. The fourth is the relative trend among autumn negotiations with major customers, average selling prices, product mix, and raw-material costs. The fifth is the Components business margin, loss reduction in Devices & Modules, and the group margin excluding foreign-exchange effects.
The real evidence for upside would be successful price adjustments for long-term customers, improved yields for high-end MLCCs, and simultaneous increases in data-center revenue and the Components business margin. The clearest disconfirming evidence would be a pullback in distributor orders, unchanged pricing for major customers, continued erosion of incremental profit by raw-material and outsourcing costs, or the AI cycle peaking before long-term margin assumptions are realized. Q1 has already demonstrated the direction of demand; from this point forward, Murata Manufacturing must prove whether that demand can pass through capacity and costs to become sustainable excess profit.
Related Reading
Arm FY2027 Q1 Deep Dive: Data Center Royalties More Than Double, AGI CPU Demand Exceeds $2 Billion