
Morgan Stanley Warns Semiconductors May Be Temporarily Peaking: The AI Theme Is Not Over, But Momentum Trading Is Cooling
目录
Too Long; Didn't Read
1. What Exactly Is Morgan Stanley Warning About?
2. Two Reports Express the Same Signal
3. Why Semiconductors Have Become a Crowded Trade Now
4. First Signal: Hyperscalers Weaken First
5. Second Signal: EPS Revision Breadth Is Near Historical Highs
6. Third Signal: Price Momentum Has Entered a Commodity-Style Phase
7. Fourth Signal: Spot-Up/Vol-Up Makes High Exposure Harder to Maintain
8. Rotation Direction: Who Does Morgan Stanley Prefer to Take Over?
9. How Semiconductors May Differentiate Internally
10. Why Memory Both Benefits and Remains Sensitive
11. Why Semiconductor Equipment Will Also Be Reassessed
12. Optical Interconnects and PCB Look More Like Bottleneck Assets, But Cannot Avoid Rotation
13. Macro Background: Oil Prices, Real Rates, and Liquidity Jointly Drive Rotation
14. How This Can Coexist With "Long-Term AI Is Fine"
15. Three Scenarios: Healthy Rotation, Crowding Release, Risk Repricing
16. Implications for A-Share and Asian Semiconductor Stocks
17. How to Track Six Indicators Going Forward
18. Capital Reallocation: From AI Purity Back to Earnings Breadth
19. Valuation Floor: Strong Fundamentals Need Higher Cash-Flow Quality
20. Industry Ranking: From Index Weight to Profit Evidence
21. Data Misread: Price Strength, Volatility Strength, and Fundamental Strength Must Be Separated
22. Timeline: Prices Change First, Profits and Orders Later
23. Disconfirmation Conditions: What Would Make Semiconductors Strong Again
24. Portfolio Reading: Shift From Single Beta to a Verification Checklist
25. How to Read the Report: Break the Slogan Into Positioning, Earnings, and Breadth
26. Execution Framework: Confirm Rotation First, Then Screen Companies
27. Further Judgment: Semiconductors Move From Valuation Expansion Back to Profit Verification
28. Boundary of the View: Bearish on Momentum, Preserving the Long-Term Demand Framework
29. Conclusion: The AI Trade Enters Its Second Phase
本内容基于公开资料和研报数据整理,不构成任何投资建议,不代表任何个人观点,仅供学习参考,请理性阅读
Morgan Stanley's latest risk warning is focused on AI beneficiaries where price momentum, earnings upgrades, and crowded positioning are all nearing extremes. Two same-day materials point to the same shift: in the short term, semiconductors may move from the market's strongest theme to a source of rotation pressure. The key variables are hyperscaler performance, EPS revision breadth, volatility, and whether capital continues to broaden out.
Too Long; Didn't Read
Semiconductor risk comes from crowded positioning. Morgan Stanley's core point is that AI beneficiaries' price momentum, earnings upgrades, and concentrated positioning are all near elevated levels; once hyperscalers weaken first, semiconductor relative returns can become more volatile. Going forward, watch whether SOX continues to weaken versus the S&P; 500 and whether cloud capex can still be interpreted positively by the market.
The silver-equity analogy points to a momentum top. Morgan Stanley compares semiconductors with silver equities on a four-month lag, implying that semiconductors are shifting from a fundamentals-led trade to a commodity-style momentum trade. This phase is most vulnerable when prices keep rising while volatility also increases. If higher volatility is accompanied by falling high net exposure, it means capital has shifted from chasing the trend to controlling risk.
Rotation is challenging the single-line AI narrative. Equal-weight indices, small-cap cyclicals, consumer discretionary goods, transports, and regional banks are starting to outperform, showing that investors are no longer willing to chase only AI hardware. This will compress valuation tolerance for SOX, memory, and AI equipment. Whether the rotation persists depends on whether earnings recovery in lower-positioned cyclicals can keep attracting incremental capital.
Fundamentals are strong, but share prices still need confirmation. AI capex, memory shortages, and equipment upgrades remain valid, but once semiconductor EPS revision breadth approaches historical highs, new positives need stronger evidence to drive further valuation expansion. In the next earnings season, the focus should be on whether orders, gross margins, cash flow, and inventories improve in the same direction.
Watch six indicators for follow-up confirmation. Focus on SOX versus the S&P; 500, hyperscaler relative performance, semiconductor EPS revision breadth, volatility and net exposure, equal-weight relative strength, oil prices, and real yields. These numbers determine whether the rotation is healthy turnover or risk repricing. If several indicators deteriorate simultaneously, semiconductor underperformance will escalate from trading pressure to valuation pressure.
The research conclusion is cooling, not the end of the cycle. Semiconductors are moving from a one-way theme to layered verification. The assets under the most pressure are the AI leaders with the highest crowding and fullest expectations; segments with real orders, pricing, cash flow, and supply bottlenecks can still withstand the rotation. The next stage of judgment will shift from AI labels to profit quality and cash-flow evidence.
1. What Exactly Is Morgan Stanley Warning About?
Morgan Stanley is warning about a short-term momentum top in semiconductors, while keeping the AI capex logic intact. Read together, Michael Wilson's weekly report and Global Macro Forum materials are very clear: semiconductors and other AI beneficiaries have been too strong over the past few months, the market has narrowed again, and capital is crowded into the same group of winners. Now hyperscalers have started to underperform first, and semiconductors, as their key beneficiaries, may enter a period of relative underperformance.
This needs to be separated into layers. The first layer is fundamentals: AI compute spending remains strong, and memory, advanced packaging, optical interconnects, servers, equipment, and the power chain still have real orders and supply constraints. The second layer is trading: share prices have risen too fast, earnings expectations have been upgraded too smoothly, and positioning is too concentrated, so any marginal cooling will first be released from the most crowded areas. Morgan Stanley is discussing the second layer this time.
Calling this "Morgan Stanley turns fully bearish on semiconductors" would miss the most important boundary. Morgan Stanley's original text clearly keeps the view that the cycle is not over; it simply argues that weaker short-term price momentum will make room for other sectors to perform. This is more like an internal style shift within the market: the AI trade remains in place, but investors are no longer willing to grant semiconductors the highest valuation premium unconditionally.
"Semiconductor momentum is likely to fade further."
This short sentence is enough to show the direction. It points to momentum fade, not demand collapse. If one wants to call it "bearish," the more accurate expression is that Morgan Stanley is bearish on semiconductors' short-term momentum and relative returns.
The AI Trade Has Moved Ahead of Macro: Recalibrating Compute Capex, Earnings Expectations, and Market Pricing
When discussing the recalibration of the AI trade earlier, the core tension was that capex and earnings expectations had moved ahead of macro variables. This Morgan Stanley weekly report pushes the same issue one step further: once AI beneficiaries have already priced in earnings upgrades, order visibility, and crowded positioning, the market starts asking, "Who can still deliver further upgrades, and who is merely a crowded trade?"
2. Two Reports Express the Same Signal
The first weekly report provides the textual logic, while the second Global Macro Forum deck provides graphical confirmation. In the weekly report, Morgan Stanley places semiconductors in a "broadening under weaker tape" framework: the overall market is not comfortable, but equal-weight indices and small-cap cyclicals are improving relatively, and the concentrated rally previously dominated by semiconductors, memory, and AI beneficiaries is starting to loosen.
The forum slides are more direct. Michael Wilson's section first says that the breadth trade is re-emerging, then includes a page titled "semiconductor momentum leadership may be peaking," comparing the SOX index with a silver-equity ETF on a lagged basis. Its function is to turn the relative-return logic in the weekly report into a cross-asset graphical signal, rather than adding new company fundamental data.
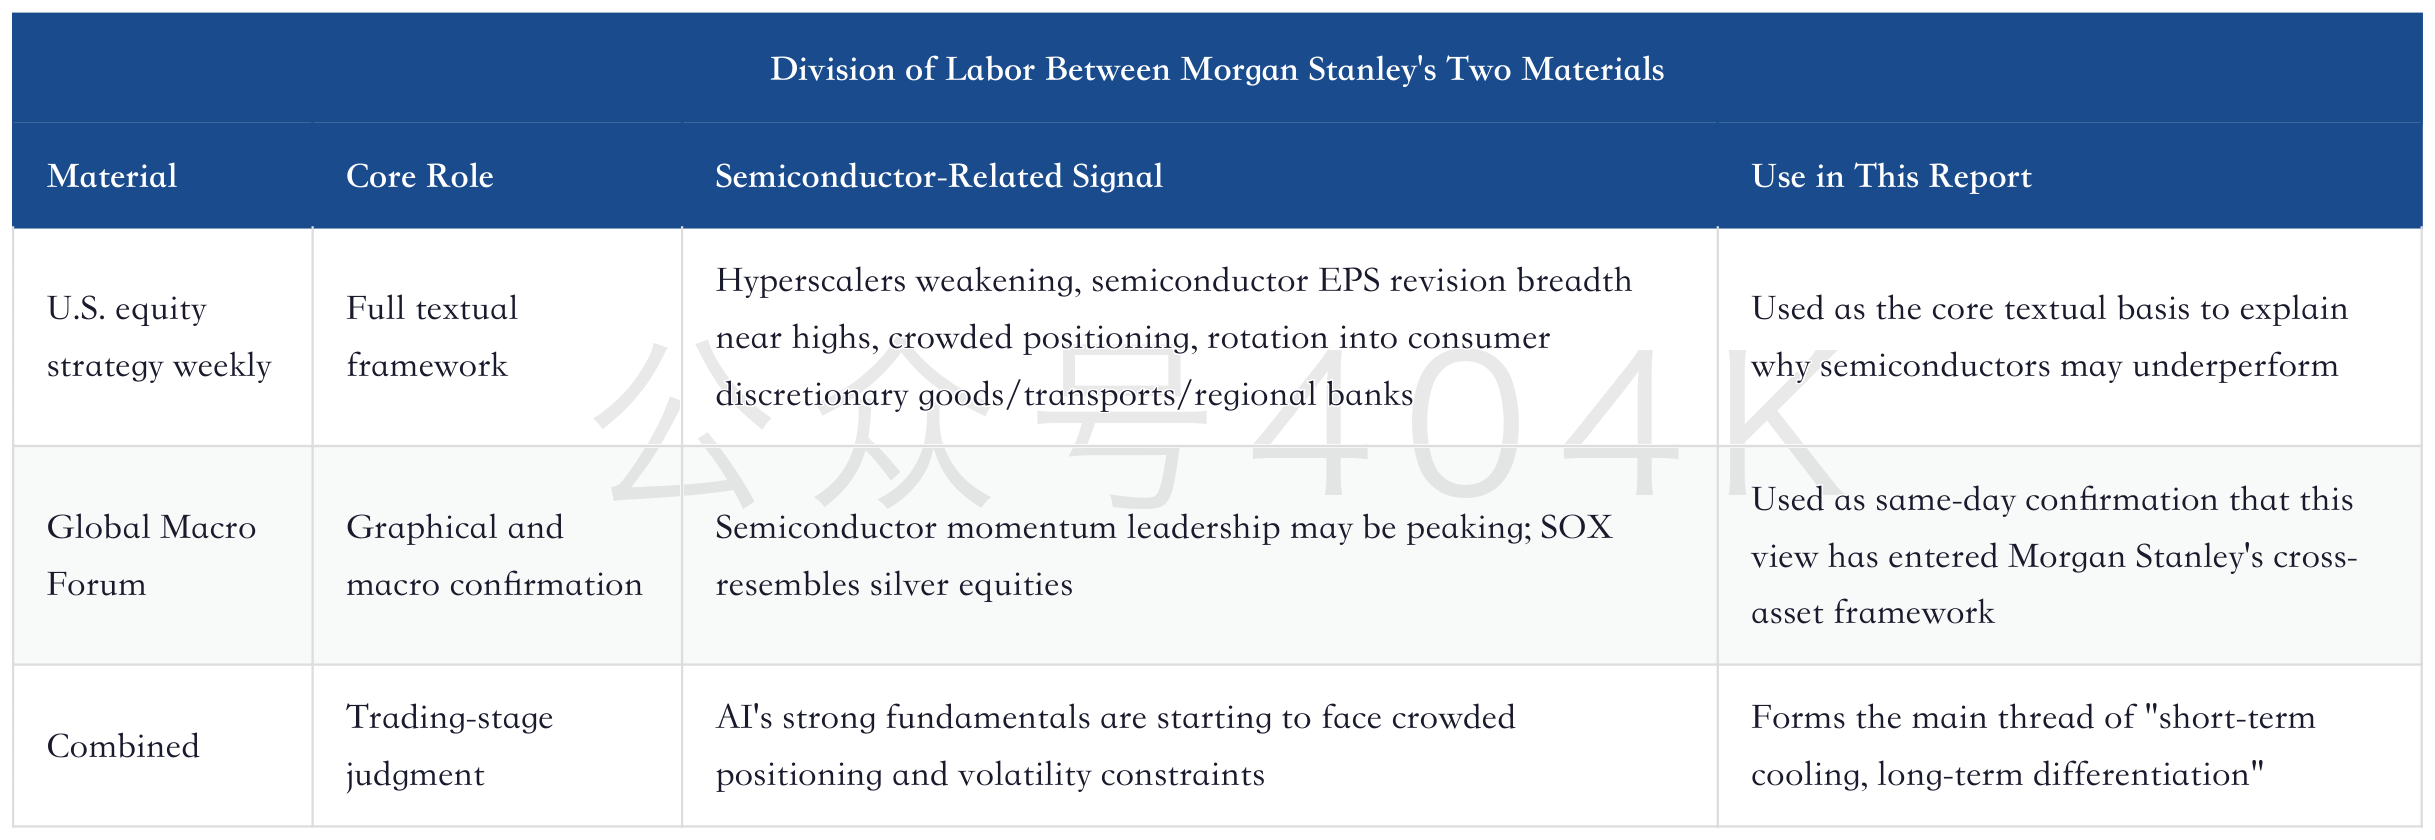
This division is important. The weekly report provides the logic chain, while the forum page highlights the market communication point. The two materials appeared on the same day, showing that this view has entered Morgan Stanley's strategy framework: semiconductors have moved from "the strongest beneficiary" to "the asset that most needs crowding to be tested."
3. Why Semiconductors Have Become a Crowded Trade Now
Semiconductors have become crowded because they have benefited from three types of positives at the same time. The first is AI capex upgrades, as cloud vendors and emerging AI infrastructure companies continue to raise compute spending. The second is supply bottlenecks, with tight constraints in HBM, advanced packaging, optical modules, memory, ABF, MLCC, and equipment deliveries. The third is earnings revisions, as analysts keep raising revenue and profit forecasts for the AI hardware chain.
All three positives are real. The problem is that after real positives are repeatedly traded by the market, incremental positives become expensive. The most dangerous stage for a sector often occurs when fundamentals are still improving, but prices have already embedded the tailwinds of the next several quarters into valuations. Morgan Stanley's point that semiconductor EPS revision breadth is near historical highs points exactly to this stage.
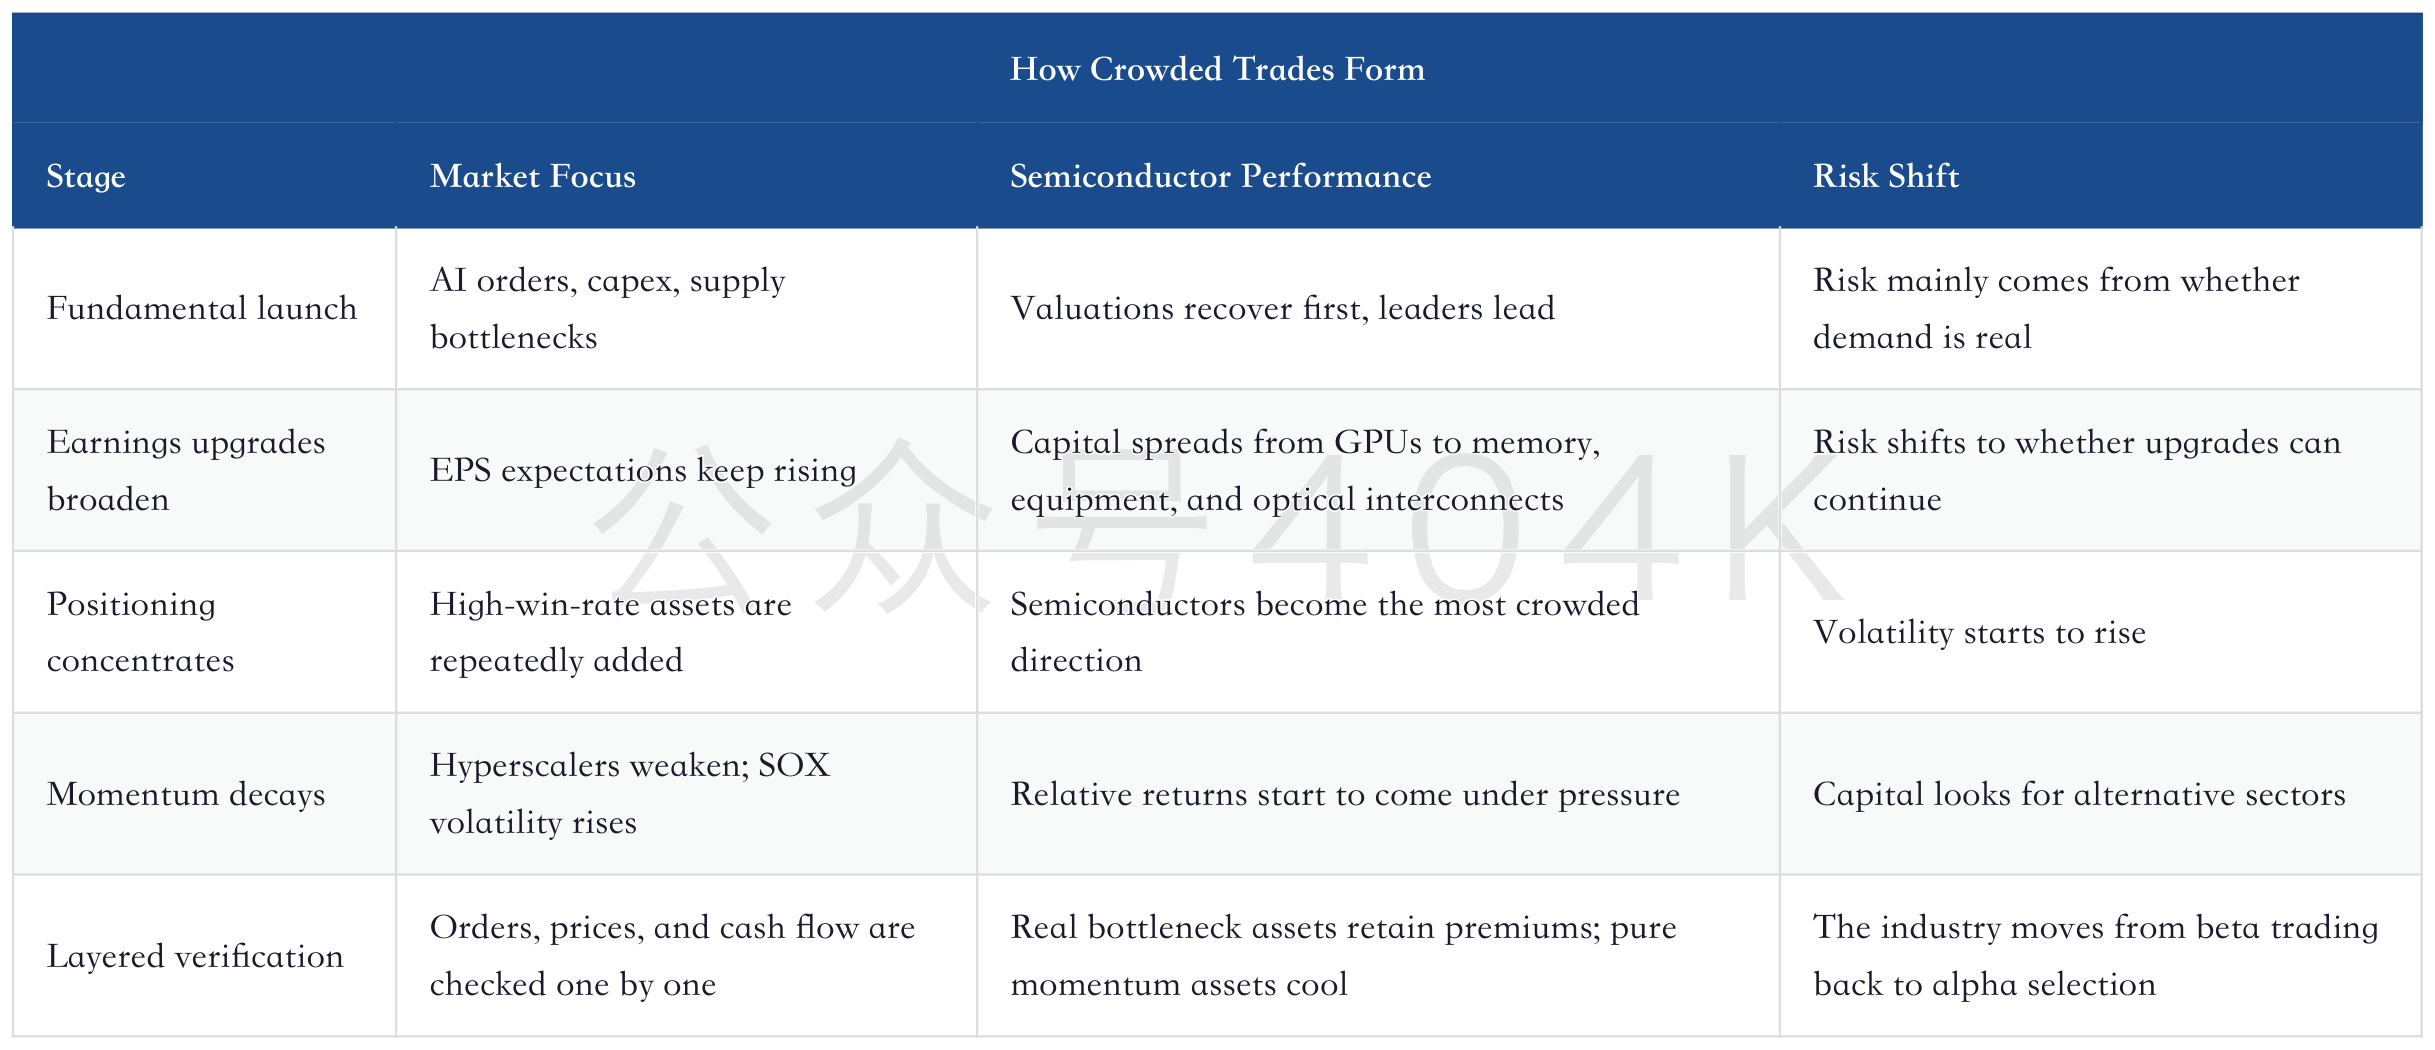
Morgan Stanley now believes the market is moving from the third stage into the fourth. Semiconductors remain a strong fundamental sector, but investors have begun to ask: is crowding here too high, and will the next unit of incremental capital continue to chase the same group of assets?
BofA Flow Show Deep Update: Is Capital Retreating From AI Giants as Small-Cap Cyclicals and Emerging Markets Take Over?
Changes in fund flows corroborate Morgan Stanley's latest view. BofA Flow Show discusses capital retreating from AI giants and rotating into small-cap cyclicals and emerging markets; Morgan Stanley discusses relative weakness in hyperscalers and semis, with consumer discretionary goods, transports, and regional banks starting to take over. Together, the two lines show that the AI trade is moving from a single-line bet into multi-line rotation.
4. First Signal: Hyperscalers Weaken First
Hyperscalers are the payers for AI capex. Whether semiconductor companies, equipment companies, memory companies, and optical interconnect companies can continue to be priced at high valuations depends heavily on whether cloud vendors and large internet platforms keep expanding capex. If the payers' share prices and relative returns weaken first, the market will naturally ask: spending intensity is still there, but how much valuation premium is the capital market willing to pay for that spending?
Morgan Stanley describes hyperscaler weakness as a leading signal that semiconductors may underperform relatively, and the logic is straightforward. Profits in the AI hardware chain come from cloud vendors' continued procurement. If cloud-vendor share prices start digesting capex pressure, depreciation pressure, free-cash-flow pressure, and pressure to realize AI revenue, the hardware chain will also face valuation transmission. When the payer cools first, suppliers can hardly remain completely unaffected.
This signal does not mean orders immediately deteriorate. Cloud capex usually has contracts, delivery schedules, and supply-chain lock-in, and it will not contract immediately because of share-price volatility. It is more like a valuation signal: the market is shifting from "higher capex is better" to "at what point does high capex suppress cash flow?" Once that question is repriced, valuation tolerance for the semiconductor chain declines.
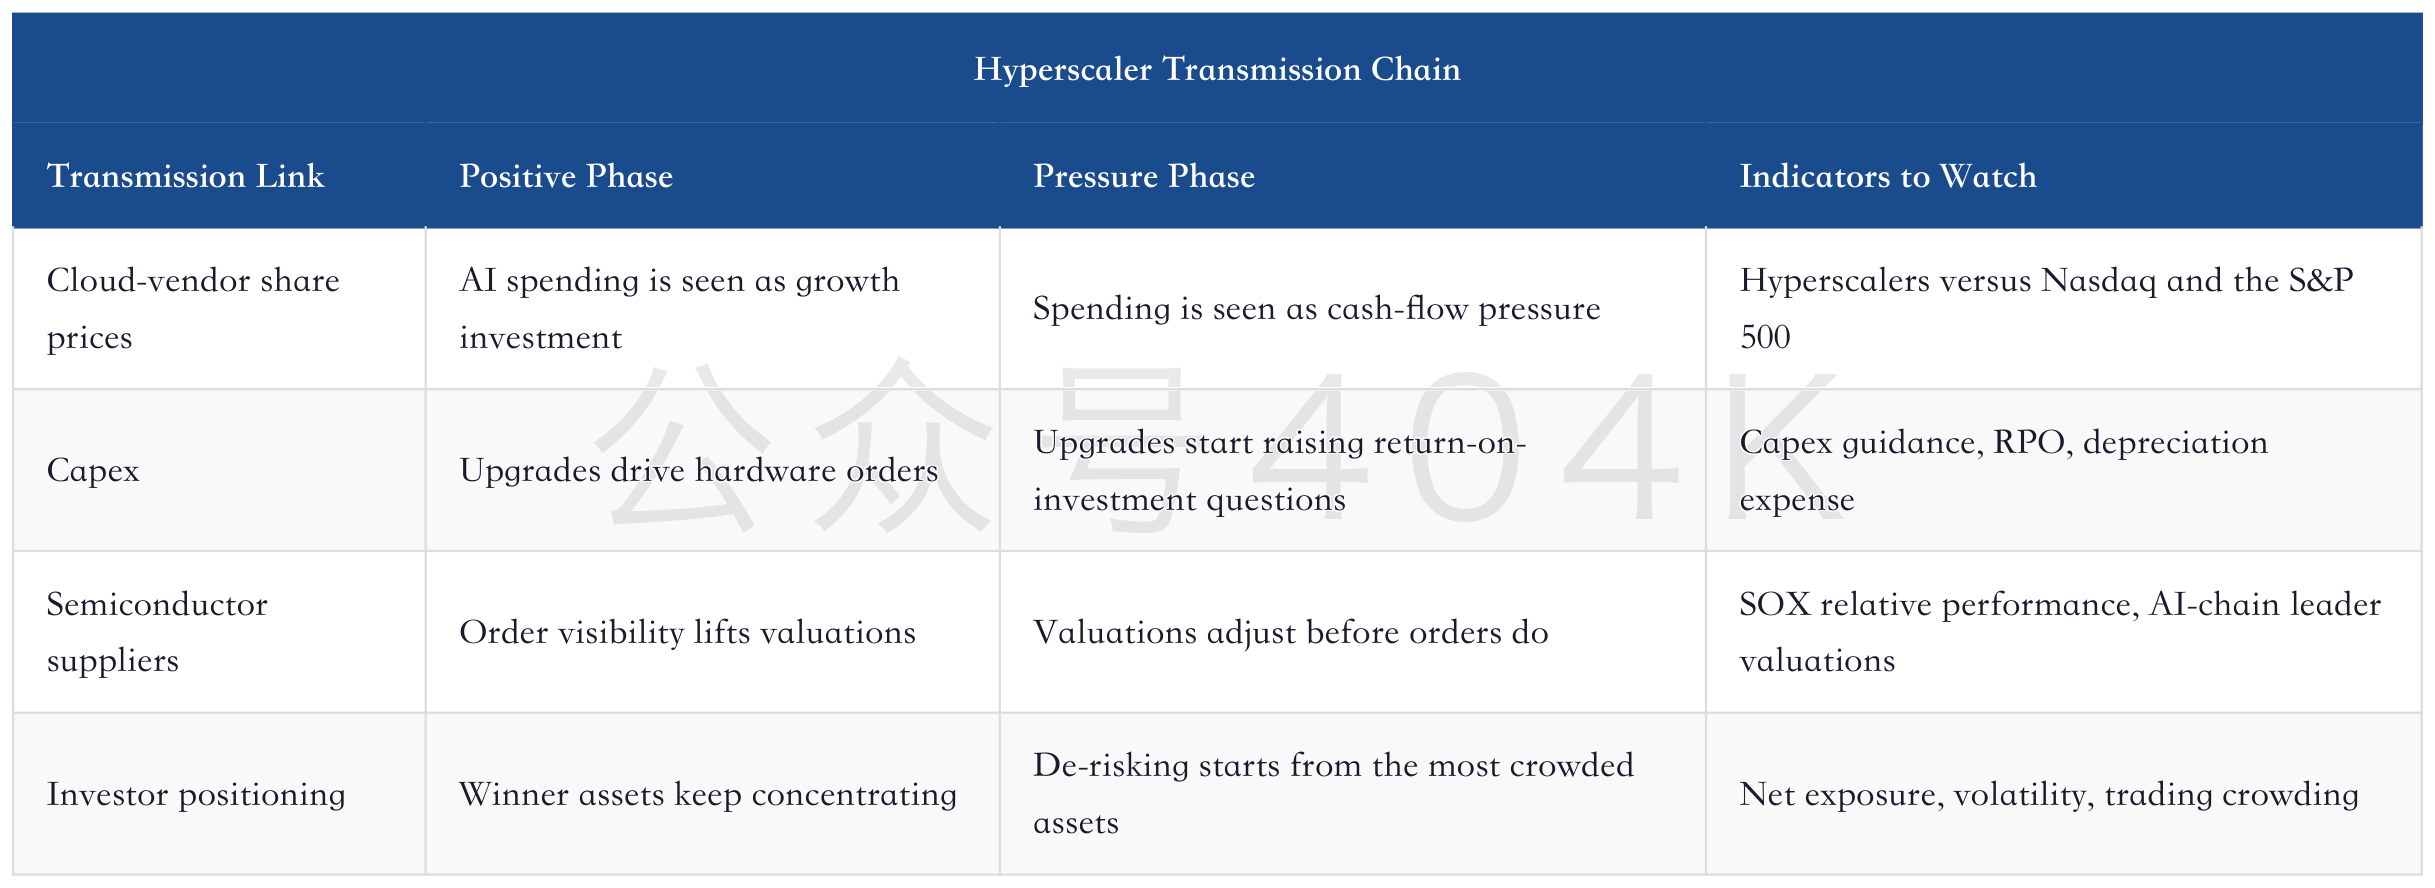
This is also why Morgan Stanley does not start directly from memory prices or GPU orders, but first looks at hyperscalers. Cyclical peaks usually show up first in prices or inventory; crowded-trade peaks often show up first in the payer and positioning structure.
5. Second Signal: EPS Revision Breadth Is Near Historical Highs
EPS revision breadth is a useful indicator for judging whether sector expectations are too full. If many semiconductor companies are seeing earnings forecasts upgraded simultaneously, it means fundamental strength has been widely confirmed by analysts, and it also means the market can easily enter a stage where "continued upgrades" are merely the baseline. The key point in Morgan Stanley's Exhibit 8 is that the four-week average of S&P; 500 semiconductor earnings revision breadth is already near historical highs.
This indicator has two meanings. The positive meaning is that semiconductor fundamentals are indeed very strong; otherwise, such concentrated earnings upgrades would not occur. The pressure point is that when upgrade breadth reaches an extreme, it becomes harder to beat expectations further. The market does not reward "still good"; it rewards "better than already-high expectations."
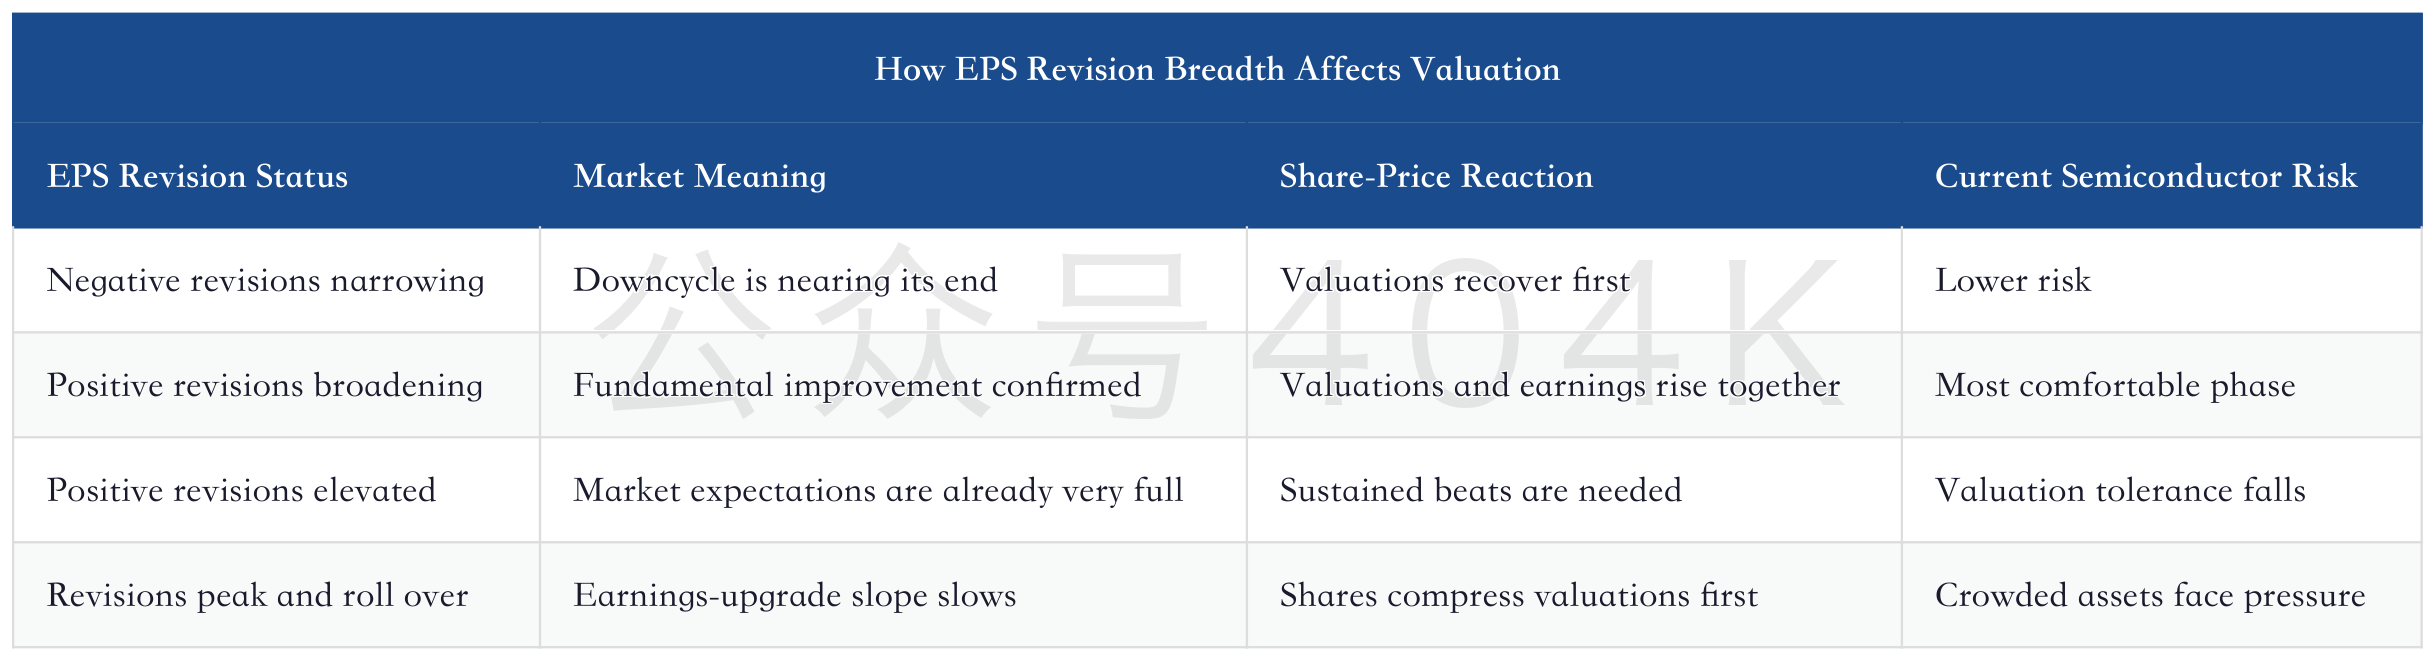
The current pressure on semiconductors comes from upgrades already being visible to the market. This stage is most prone to "good results but flat share prices," because prices have already reflected strong expectations in advance. Investors need to shift from asking "whether there are upgrades" to asking "whether the upgrade slope continues to accelerate."
U.S. Semiconductors Deep Dive: AI Extends Visibility to 2028; Who Can Still Re-rate After BofA's Estimate Upgrades?
This does not conflict with improved visibility in U.S. semiconductors. Longer visibility addresses long-term revenue visibility, while high EPS revision breadth addresses short-term expectation crowding. A sector can have both strong fundamentals and high crowding at the same time; this is precisely the hardest part of today's AI semiconductor trade.
6. Third Signal: Price Momentum Has Entered a Commodity-Style Phase
Morgan Stanley's comparison between semiconductors and silver equities is the most viral part of this report. Silver equities first experienced a strong momentum rally this year and then pulled back; on the chart, semiconductors look like they are replicating silver equities' rhythm on a four-month lag. The key point of this analogy is that both entered a commodity-style trading state in which capital chased a strong trend, not that their fundamentals are identical.
Commodity-style momentum has three characteristics. First, price itself becomes the reason to chase; the more it rises, the more it attracts trend-following capital. Second, the fundamental narrative is real enough that investors are reluctant to go against it too early. Third, once volatility rises, positioning stability starts to decline, especially for leveraged and high-net-exposure capital, which will reduce risk first.
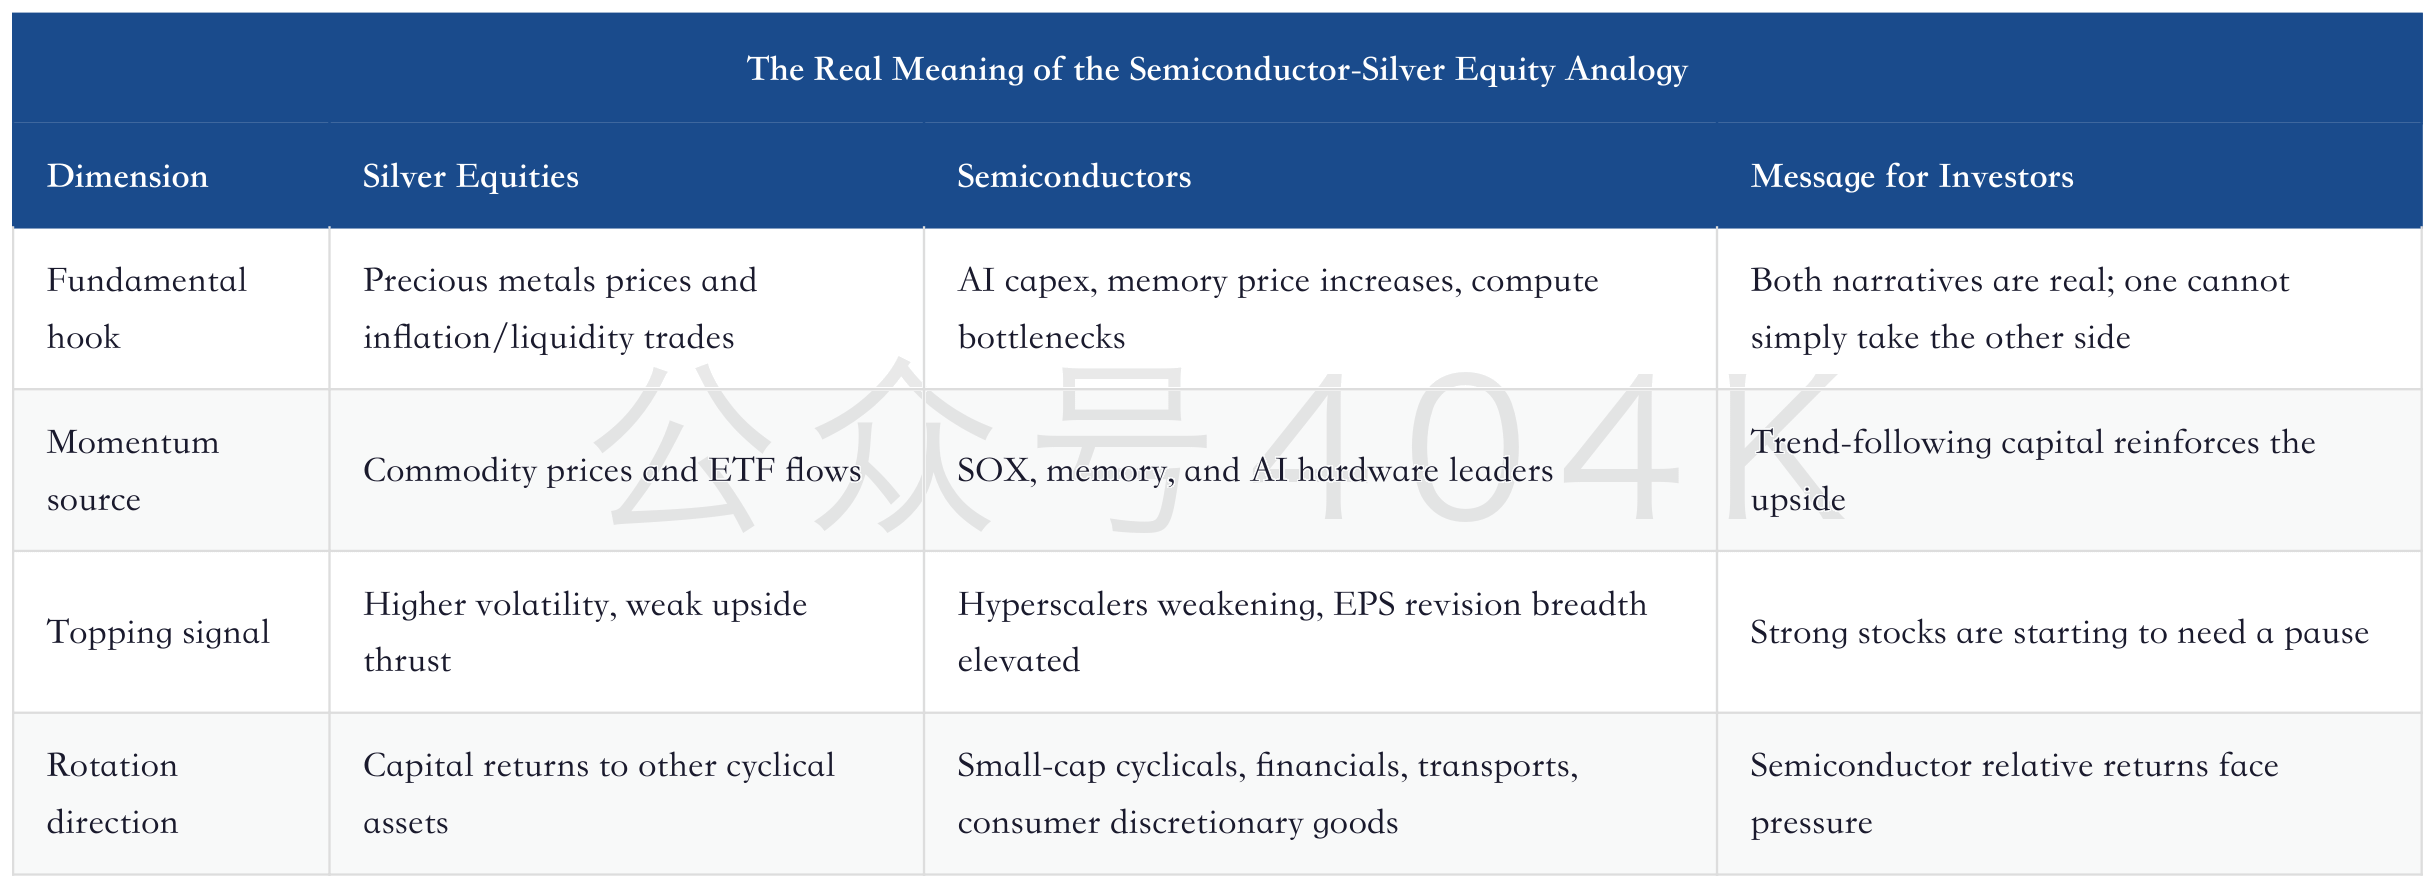
This analogy is best used to explain short-term rhythm, not to negate long-term AI demand. Silver equities can experience a commodity-style momentum pullback without ending the precious-metals narrative; semiconductors are similar. Even if AI capex continues to expand, SOX can still enter a valuation digestion phase first.
"This doesn't mean the cycle is over."
This short sentence is the boundary of the whole note. Morgan Stanley is not saying the semiconductor cycle is over; it is saying that after momentum weakens, the market will give other sectors room to perform.
7. Fourth Signal: Spot-Up/Vol-Up Makes High Exposure Harder to Maintain
Morgan Stanley specifically notes one detail: even in a "spot up, vol up" environment, high net exposure to semiconductors becomes harder to maintain. This detail is important. In a normal strong market, share prices rise and volatility falls, and capital is willing to increase exposure. If share prices rise and volatility also rises, it means the quality of the rally has started to deteriorate.
For institutions, rising volatility directly affects positioning. Risk-control models raise risk consumption, portfolio managers reduce net exposure, and long/short funds reduce the size of crowded long positions. If semiconductors are already the "most crowded area of the market," rising volatility will force some capital to de-risk here first.
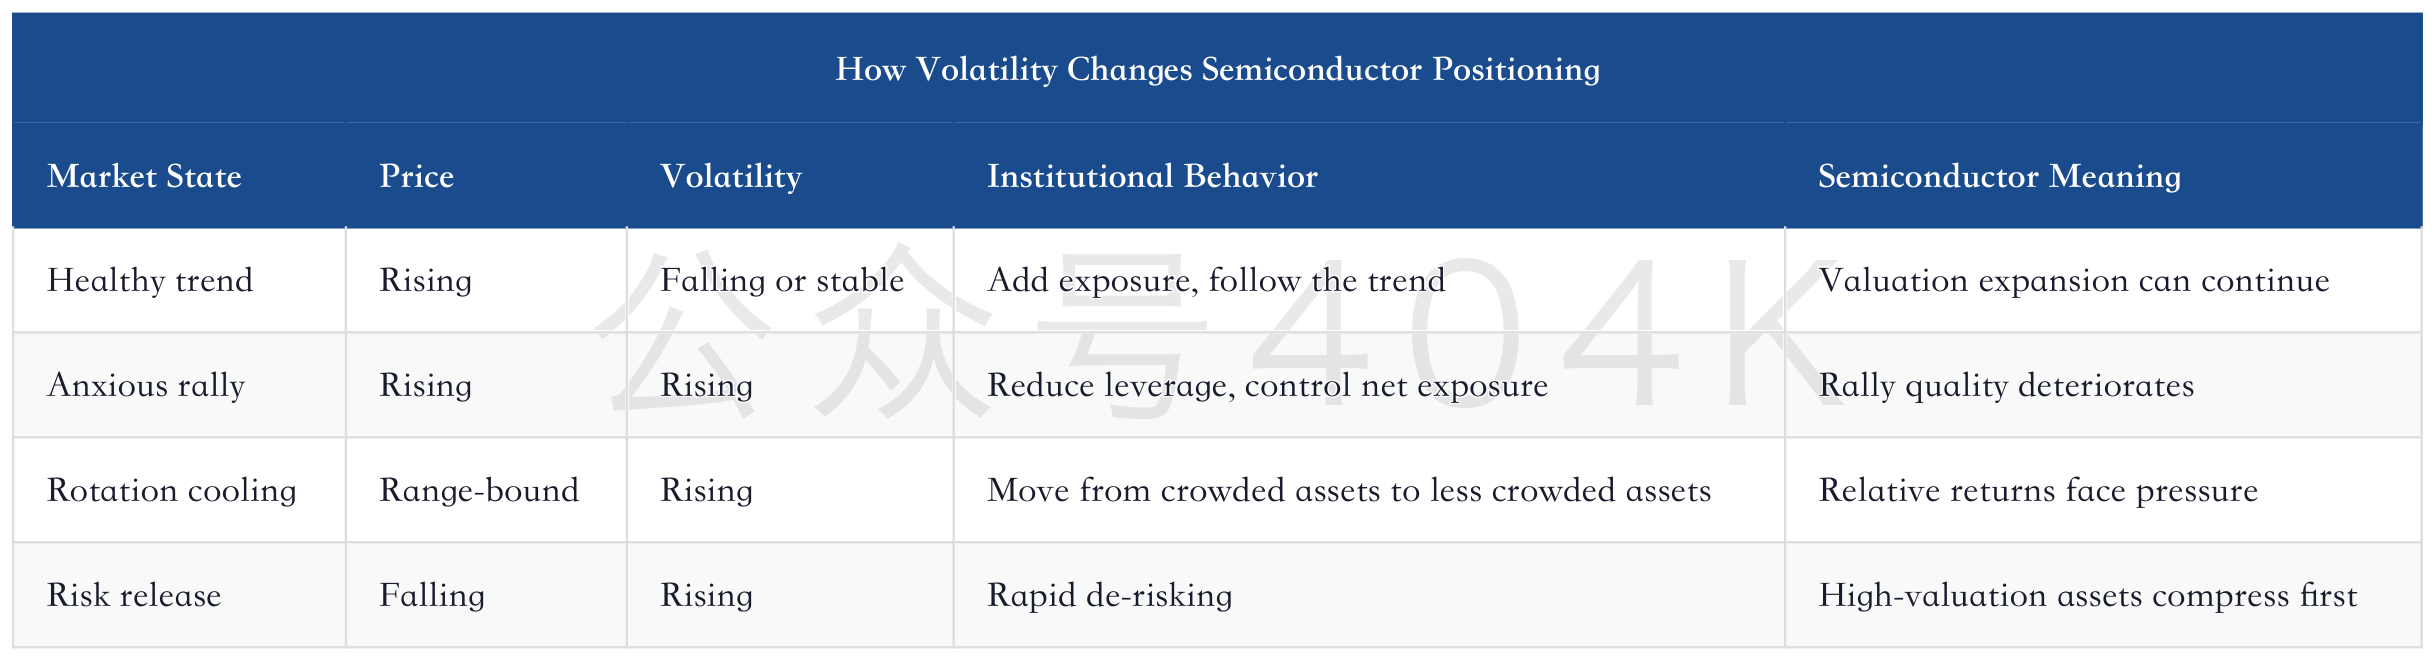
Semiconductors are now closer to the area between the second and third states. The price trend has not been fully broken, but volatility and relative performance have made high exposure harder to hold. Morgan Stanley's comment that broadening trades are being mentioned more often in investor conversations is the market expression of this positioning pressure.
8. Rotation Direction: Who Does Morgan Stanley Prefer to Take Over?
Morgan Stanley's preferred successors are clear: consumer discretionary goods, transports, and regional banks. This combination looks far removed from AI semiconductors, but it reflects the same macro judgment. Morgan Stanley believes the U.S. economy and earnings are stronger than consensus, earnings growth for the equal-weight index and the median stock is starting to improve, and lower oil prices plus easing real-rate pressure are favorable for previously suppressed cyclical sectors.
This is not simply a shift from growth to value. It is more like a shift from "a handful of AI winners" to "earnings recovery across more ordinary companies." When the market only believes in AI, semiconductors, memory, and cloud capex chains enjoy the highest valuations. When the market starts believing in broader economic recovery, capital gives more attention to lower-positioned cyclicals, consumer, and financials.
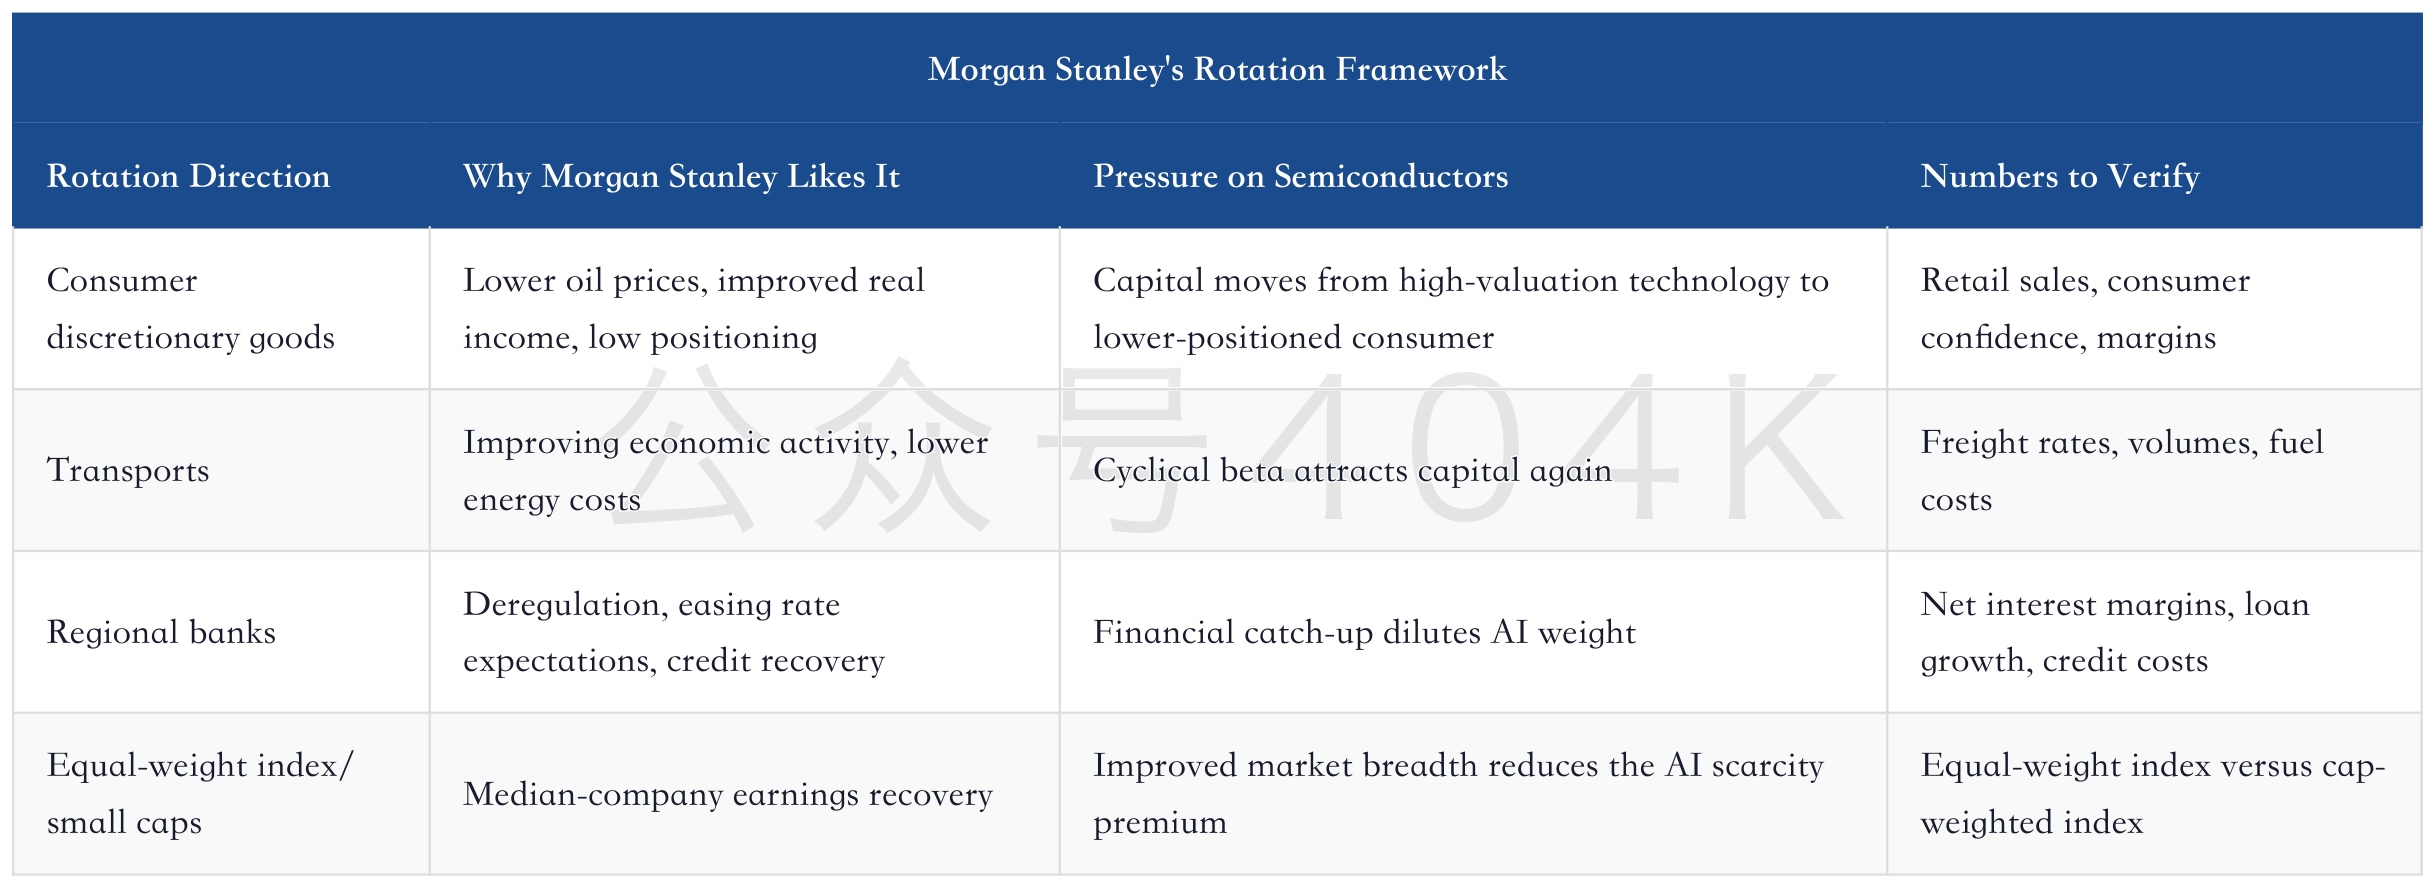
If this line holds, semiconductors do not need fundamentals to deteriorate to underperform relatively. The capital pool is finite. When lower-positioned sectors start seeing both earnings recovery and valuation repair, incremental capital for AI semiconductors is diverted.
9. How Semiconductors May Differentiate Internally
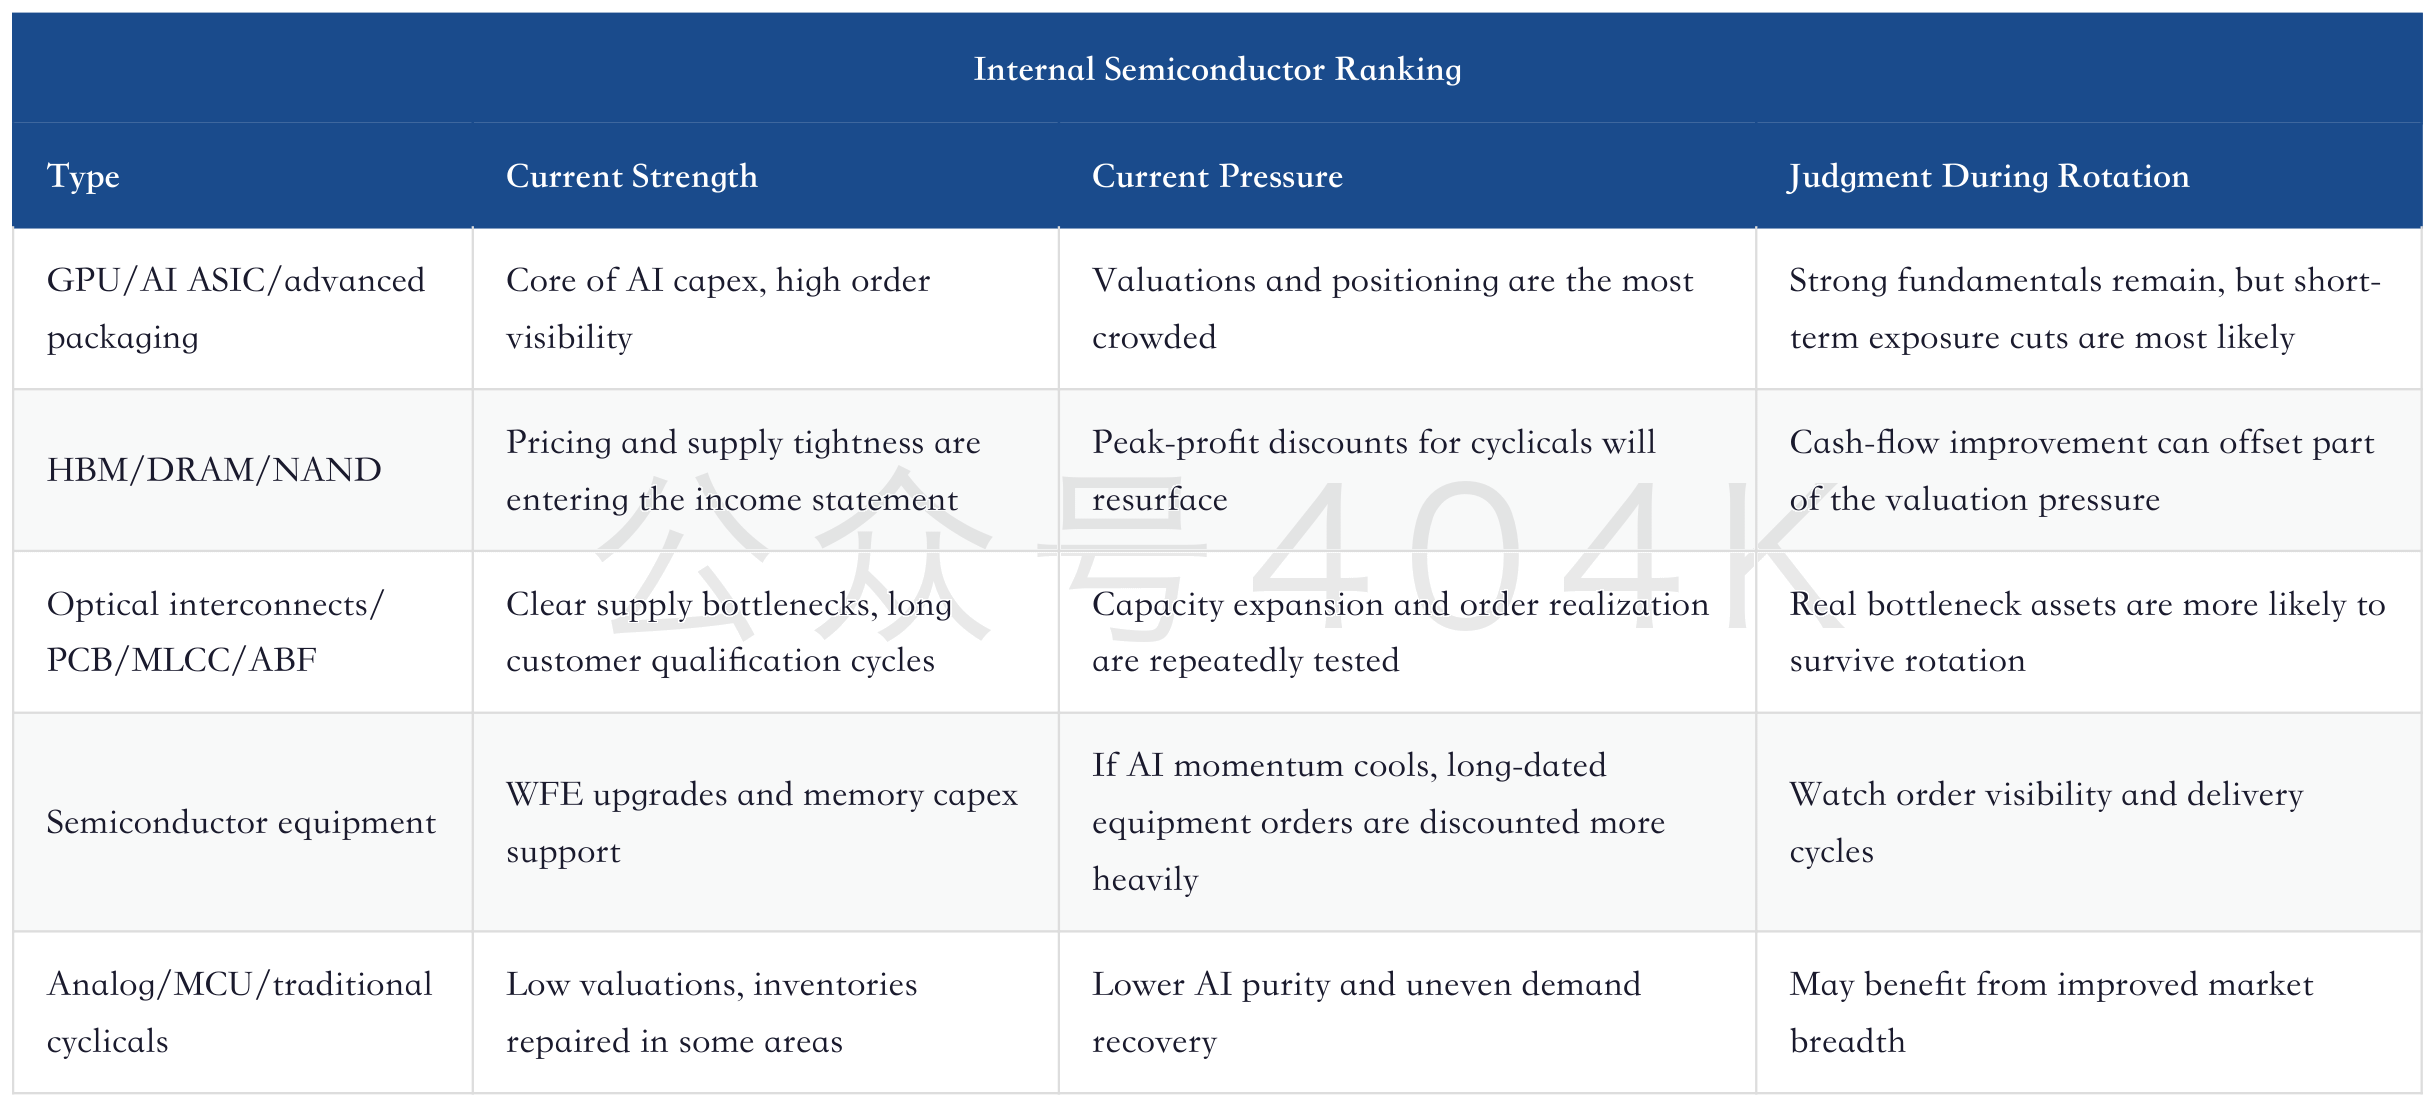
Semiconductors will neither fall together nor all power through together. When crowded trades cool, the first assets under pressure are those with the fullest expectations, heaviest positioning, and valuations most dependent on long-dated earnings. The assets most able to withstand pressure are those supported by near-term pricing, orders, cash flow, and supply constraints. When Morgan Stanley's macro warning is applied within the industry, the focus is differentiation.
The first category is the AI-leading core, including GPUs, AI ASICs, advanced packaging, HBM, and key equipment. Their fundamentals are the strongest, but they are also the most crowded. The second category is memory and legacy memory, where the price cycle is clearer and cash-flow improvement is faster, but share prices have also already traded through a round. The third category is bottleneck links such as optical interconnects, PCB, MLCC, and ABF, where valuation pressure depends on order visibility and supply discipline. The fourth category is traditional cyclical semiconductors and analog; if economic breadth recovers, they may actually gain lower-positioned rotation opportunities.
AI Semiconductors Have One Core Thread Left: Repricing From Dual Compute Cores to Bottleneck Assets
The earlier piece "AI Semiconductors Have One Core Thread Left" emphasized that AI compute was spreading from the dual cores of GPUs and ASICs to bottleneck assets. Morgan Stanley's latest warning does not overturn that thread; it simply shortens the time horizon: long term, bottlenecks still matter; short term, crowding and volatility come first.
10. Why Memory Both Benefits and Remains Sensitive
Memory is the most typical "dual asset" in this AI hardware cycle. On one hand, AI demand is genuinely squeezing HBM, DRAM, NAND, and legacy-memory supply, while prices, long-term agreements, and cash flow are all improving. On the other hand, memory is inherently cyclical: the faster prices rise, the more the market worries whether peak profits can be capitalized.
If semiconductor momentum cools, memory stocks will face an offset between two forces. Fundamental support comes from price increases, long-term agreements, and supply-demand gaps; trading pressure comes from de-risking across AI hardware and peak-profit discounts for cyclicals. Short-term performance depends on which force is stronger. If prices keep rising and inventories remain healthy, memory may outperform the most crowded AI hardware links. If SOX broadly cools and price expectations slow, memory will also be pulled into exposure cuts.
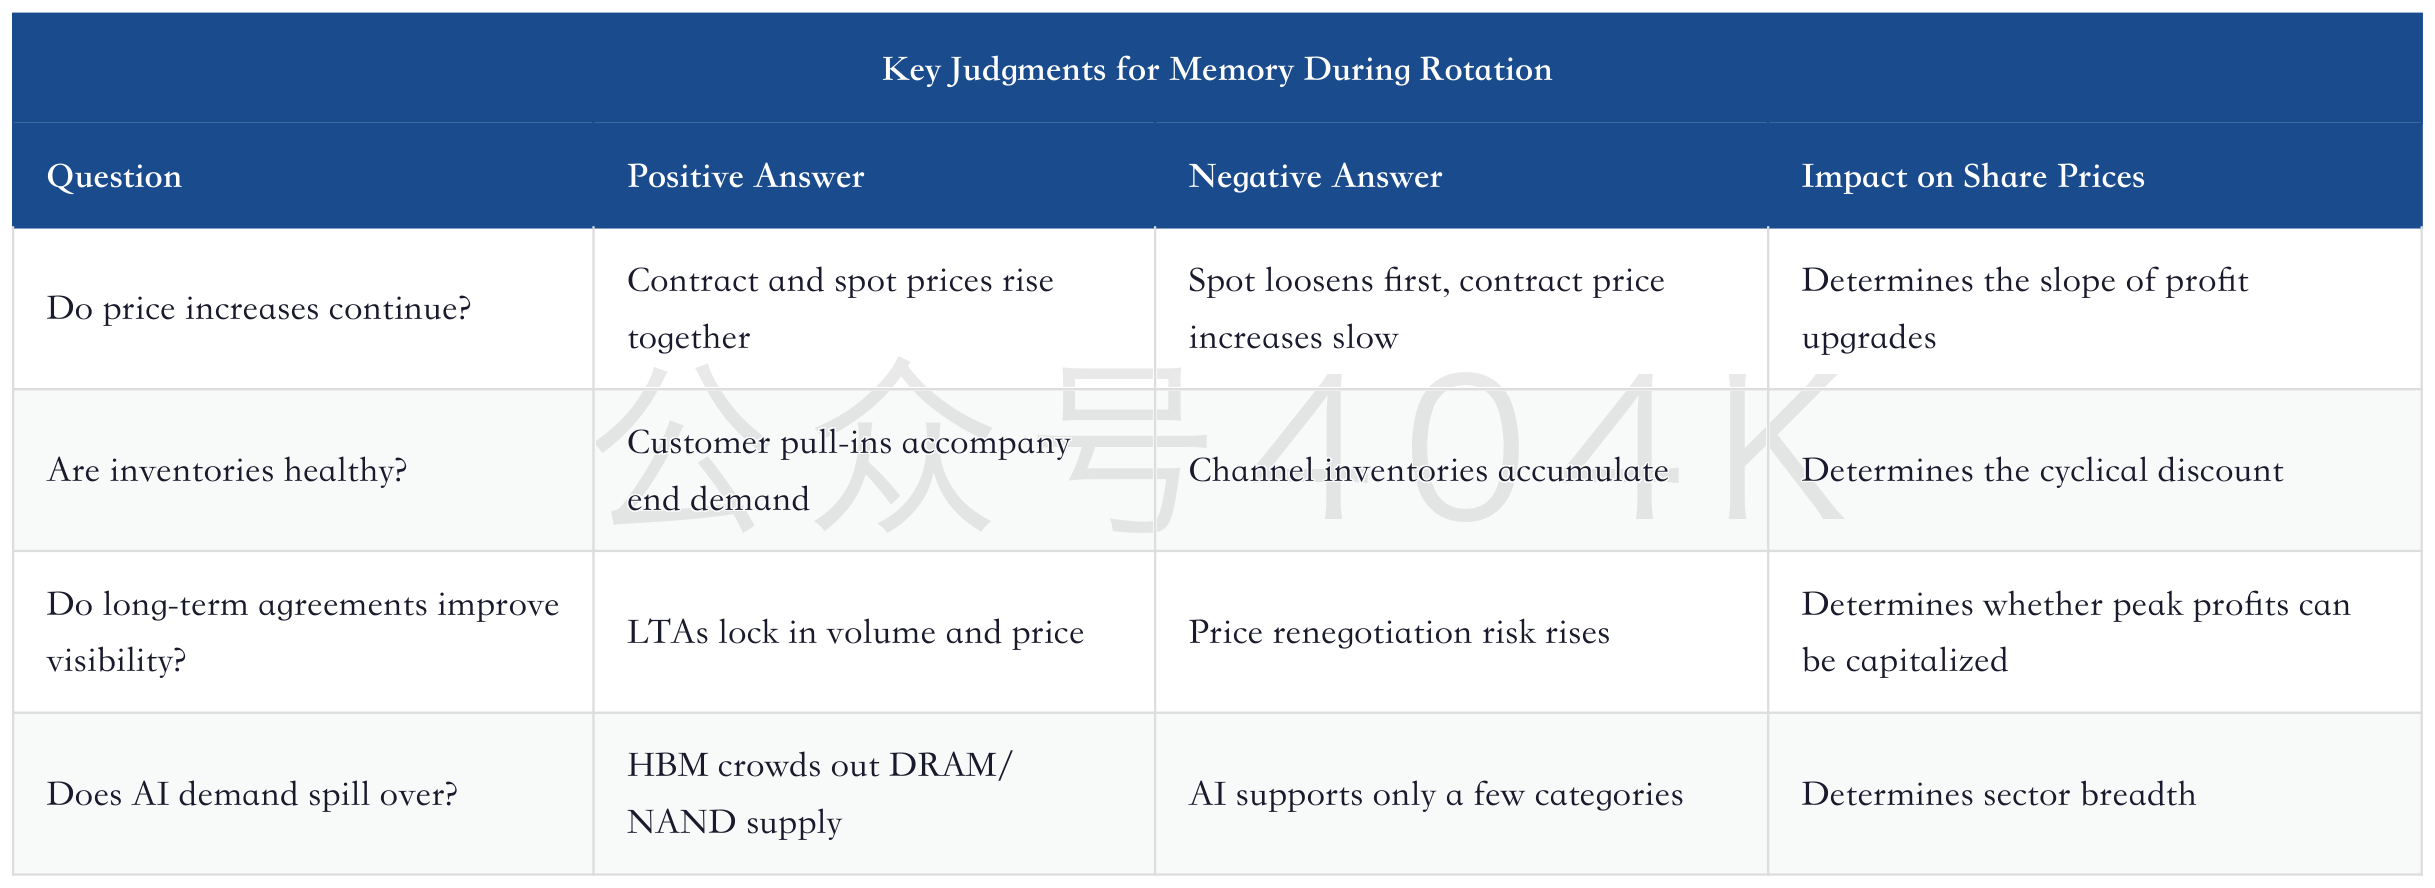
The Memory Tax Is Here: How AI Is Turning HBM, DRAM, and NAND Into a Global Macro Bottleneck
The relationship between memory and AI semiconductors becomes more subtle here. The memory-tax logic remains valid and may even strengthen because of supply constraints. But if the market enters a rotation phase, it will distinguish more strictly between "prices entering the income statement" and "the story already being fully reflected in prices."
11. Why Semiconductor Equipment Will Also Be Reassessed
The semiconductor-equipment logic is more long-dated. AI demand drives investment in memory, logic, advanced packaging, and back-end testing, and equipment companies benefit from WFE upgrades and capacity expansion. But equipment stocks usually discount orders from multiple future quarters, or even multiple years, into current share prices. Once AI momentum cools, the market will first examine the realization pace of equipment orders and capex discipline.
Equipment stocks are most likely to face three questions. First, have memory capex upgrades already entered orders? Second, are advanced-packaging and HBM-related equipment genuinely in short supply? Third, will customer capacity expansions create new supply pressure after 2027? As long as these questions are not clearly answered, equipment stocks will fluctuate with overall semiconductor valuations.
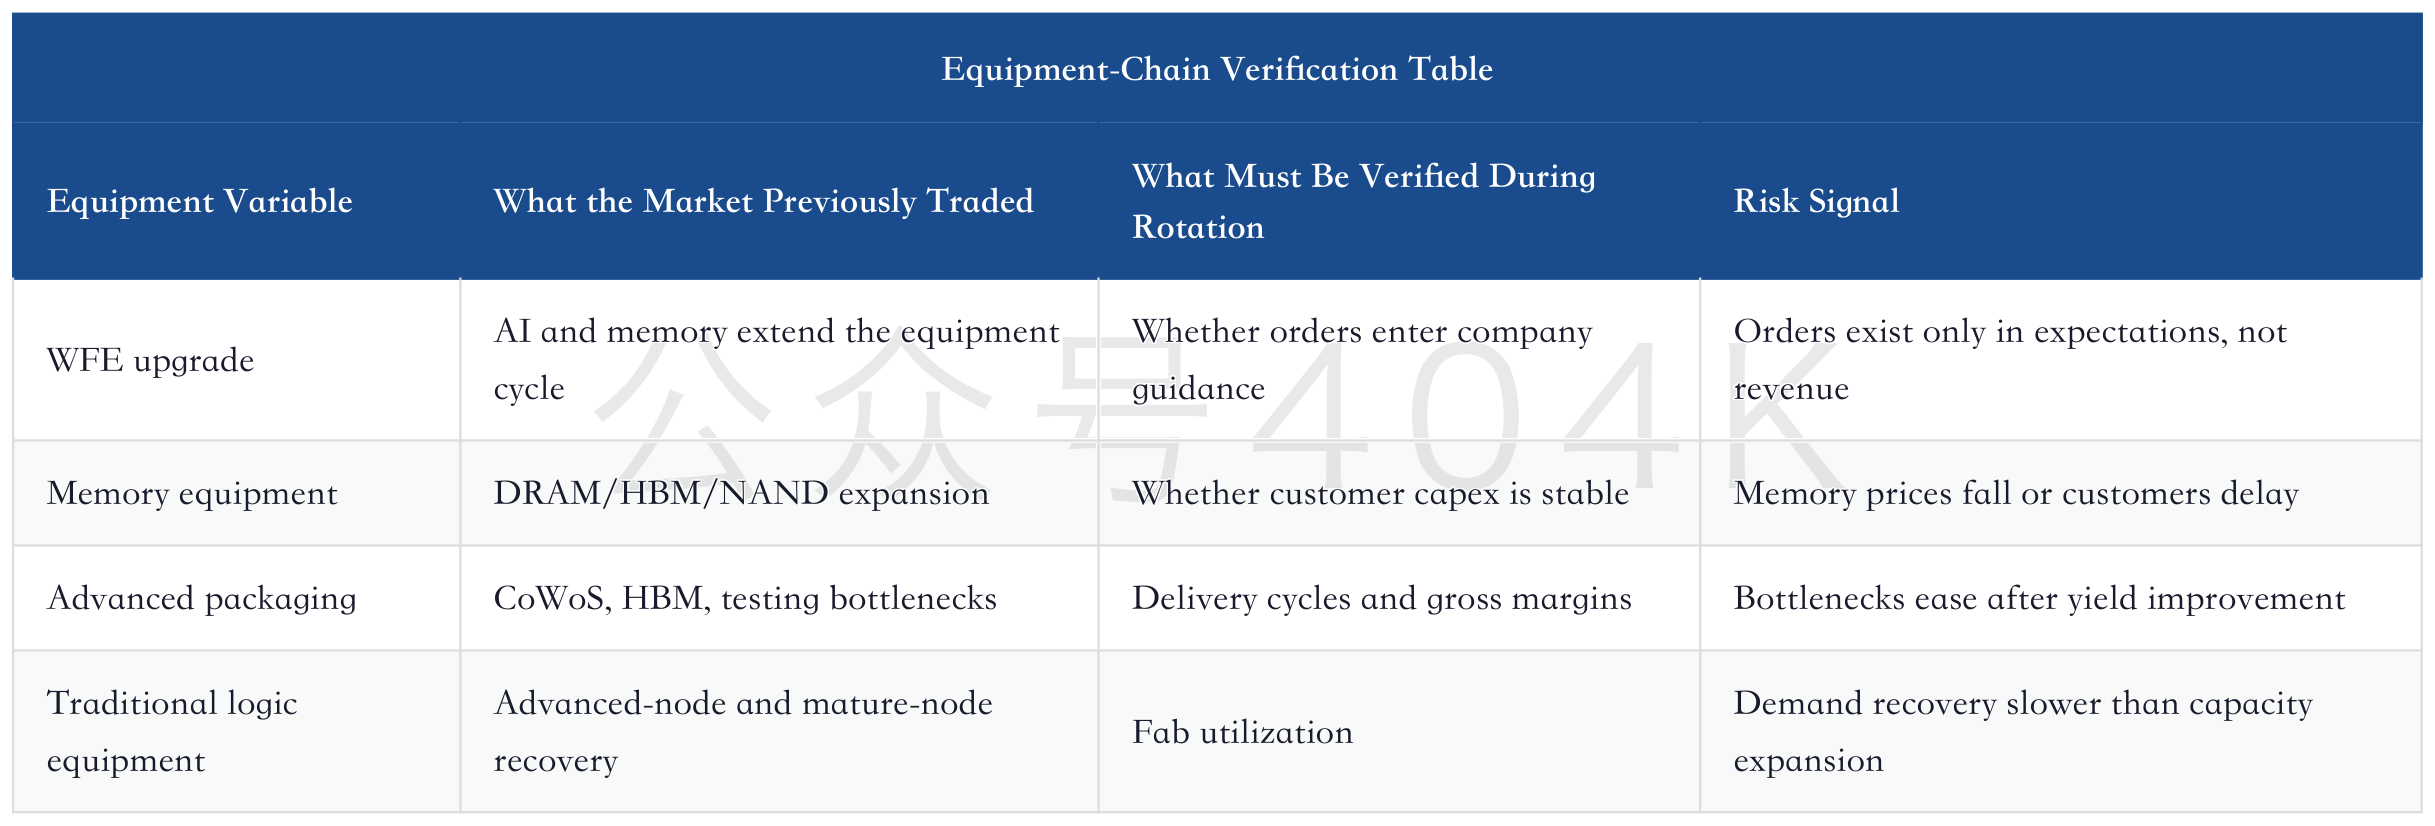
From HBM to WFE: How AI Turns the Memory Cycle Into an Equipment Supercycle, and How Much Longer Can Semiconductor Equipment Rise?
The equipment chain still has its own independent logic, but Morgan Stanley's warning will affect valuation rhythm. The market will shift from "AI expansion naturally benefits equipment" to "which orders are already visible, and which are only long-dated imagination?" This will widen dispersion within equipment stocks.
12. Optical Interconnects and PCB Look More Like Bottleneck Assets, But Cannot Avoid Rotation
The advantage of optical interconnects, PCB, ABF, and MLCC lies in more specific supply bottlenecks. They do not fully depend on semiconductor-index momentum; they depend more on customer qualification, yield, lead times, and effective capacity. As long as AI server upgrades continue, there is real demand for 800G, 1.6T, 3.2T, high-layer-count PCB, high-end copper-clad laminate, and high-end MLCC.
But rotation also affects these assets. First, valuations will move from "bottleneck story" back to "profit realization." Second, the market will pay more attention to whether capacity expansion undermines supply discipline. Third, customer qualification and delivery timing will become share-price dividing lines. Strong assets will not lose orders simply because SOX cools, but their share prices will rely more on quarterly data.
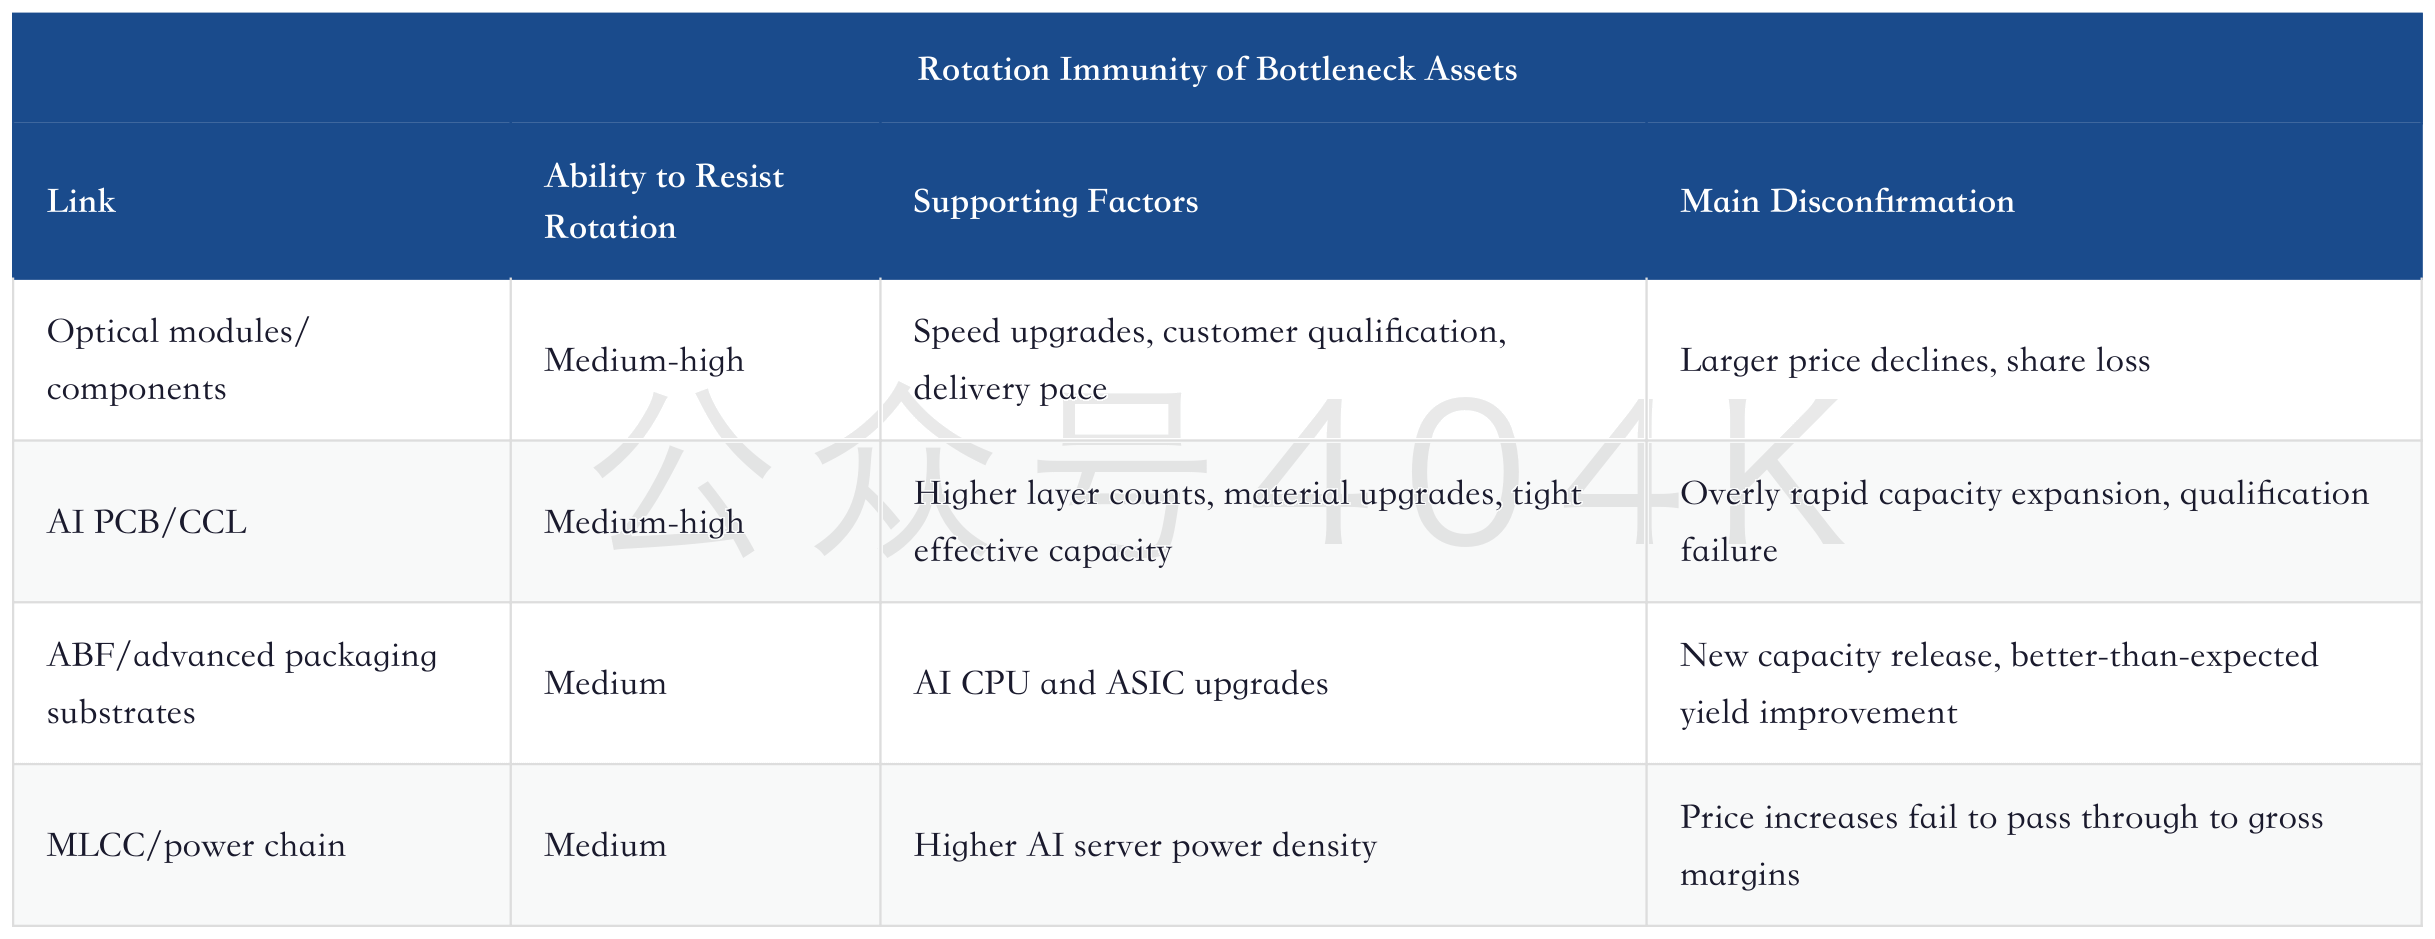
These segments are typical examples of "strong long-term fundamentals, but short-term impact from valuation rotation." In practical terms, one should not slash all AI hardware exposure just because Morgan Stanley warns of a semiconductor momentum top. The more appropriate approach is to separate crowding, order realization, and cash-flow quality.
13. Macro Background: Oil Prices, Real Rates, and Liquidity Jointly Drive Rotation
Morgan Stanley's report sits within a U.S. equity strategy framework, not a pure semiconductor industry view. The report also covers lower oil prices, the Fed no longer becoming more hawkish, possible easing in real rates, improvement in equal-weight indices, and relative strength in regional banks and transports. The semiconductor momentum top is only part of the return of the breadth trade.
This macro backdrop determines where pressure on semiconductor relative returns comes from. If oil prices fall, inflation pressure eases, and real rates stop rising, cyclical sectors previously suppressed by high oil prices and rates will recover. Once investors see that cyclical earnings can also improve, they no longer need to place all growth premiums on AI semiconductors.
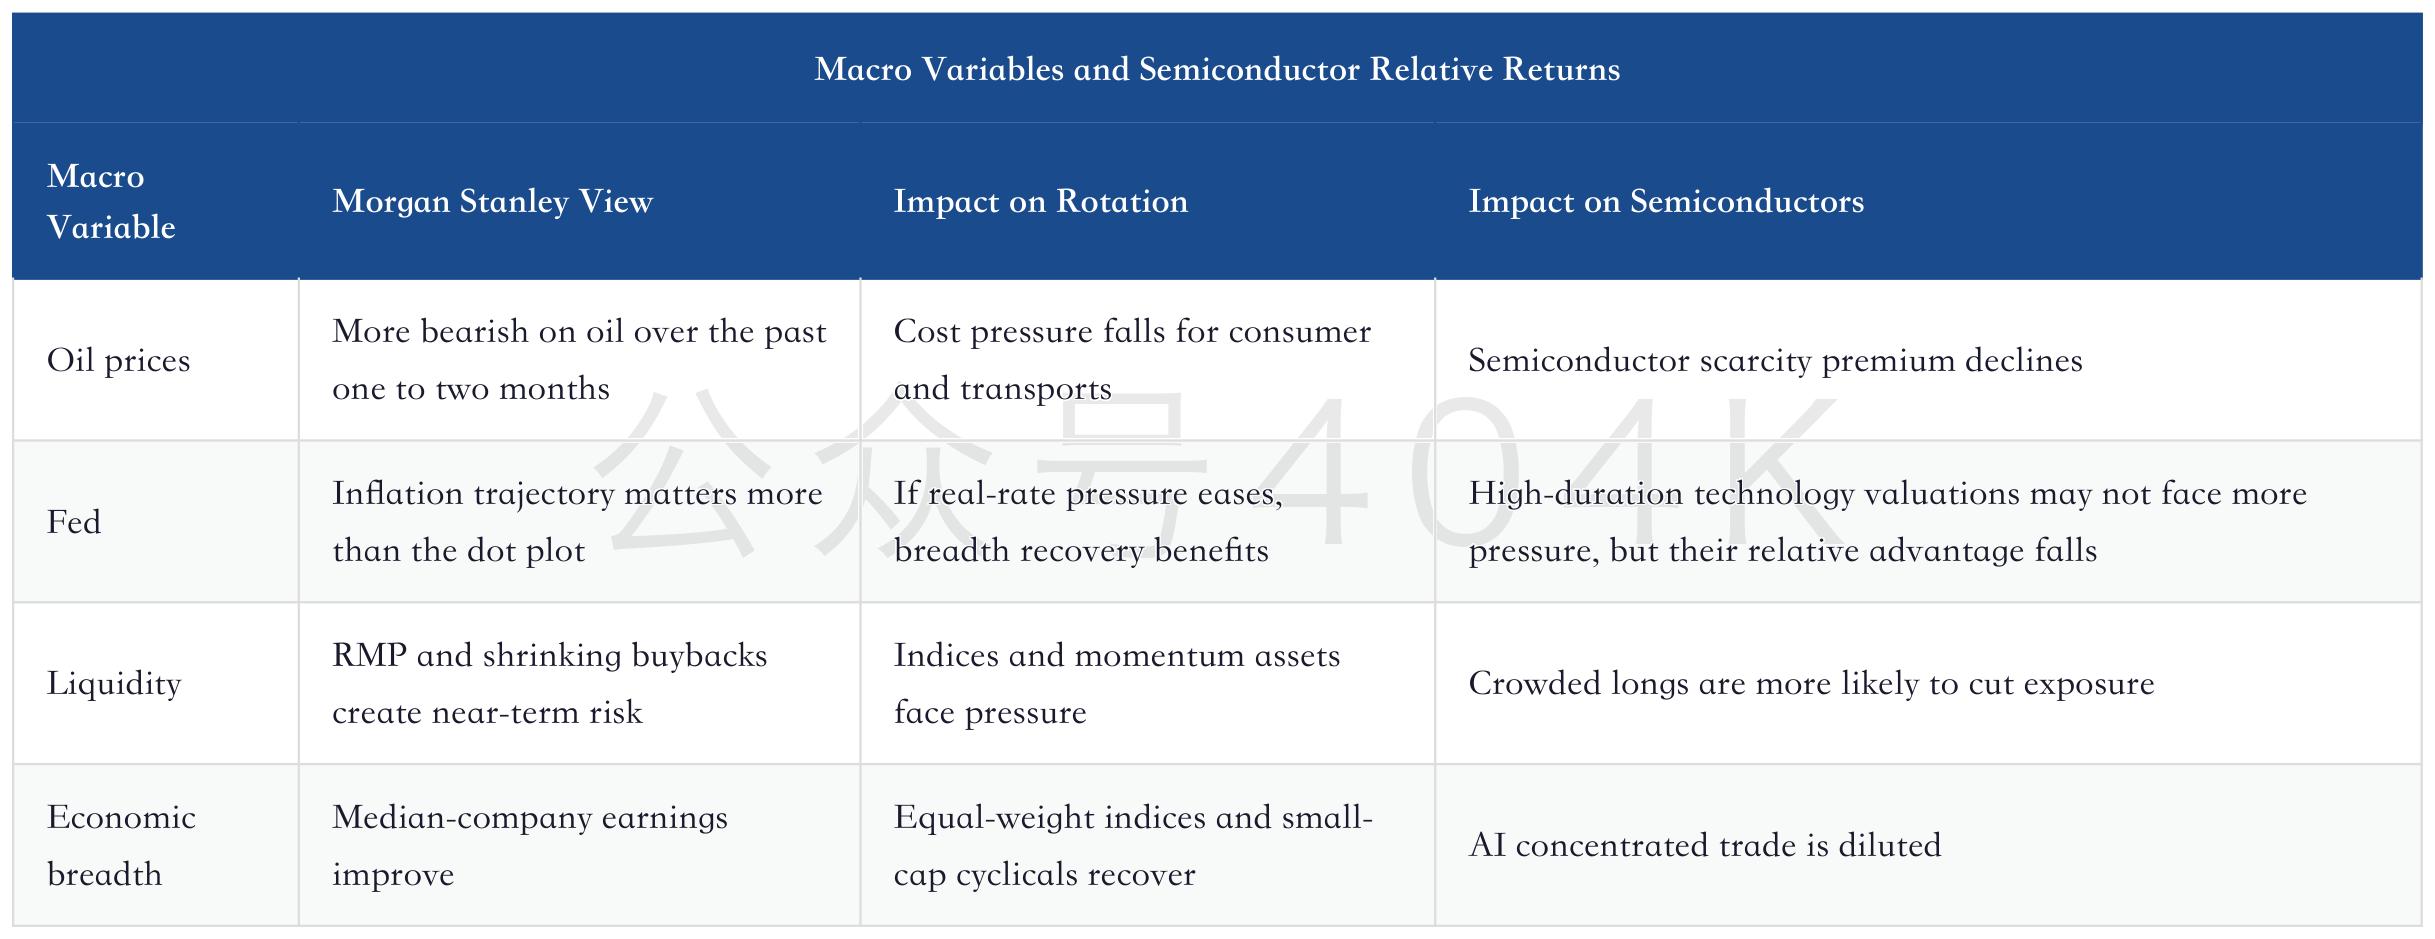
Liquidity is the most subtle part. Morgan Stanley believes oil prices and the Fed may support the breadth trade, while also warning that liquidity is not that loose. This combination is not friendly to semiconductors: if economic breadth improves, capital rotates; if liquidity tightens, crowded momentum assets de-risk first.
14. How This Can Coexist With "Long-Term AI Is Fine"
Long-term AI can be fine while semiconductors underperform in the short term. This combination often appears in investing: the industry trend is very strong, but share prices have moved too far ahead; fundamentals keep improving, but valuations enter digestion first; companies continue to deliver, but sector relative returns weaken. Morgan Stanley's report is addressing exactly this combination.
AI capex still has three hard supports. Cloud vendors need to train and infer models, enterprise AI is spreading, and memory, networking, power, and data centers still face bottlenecks. As the core of compute infrastructure, semiconductors' long-term demand is not overturned by one strategy weekly. The issue is that long-term demand does not automatically guarantee continued short-term share-price outperformance.
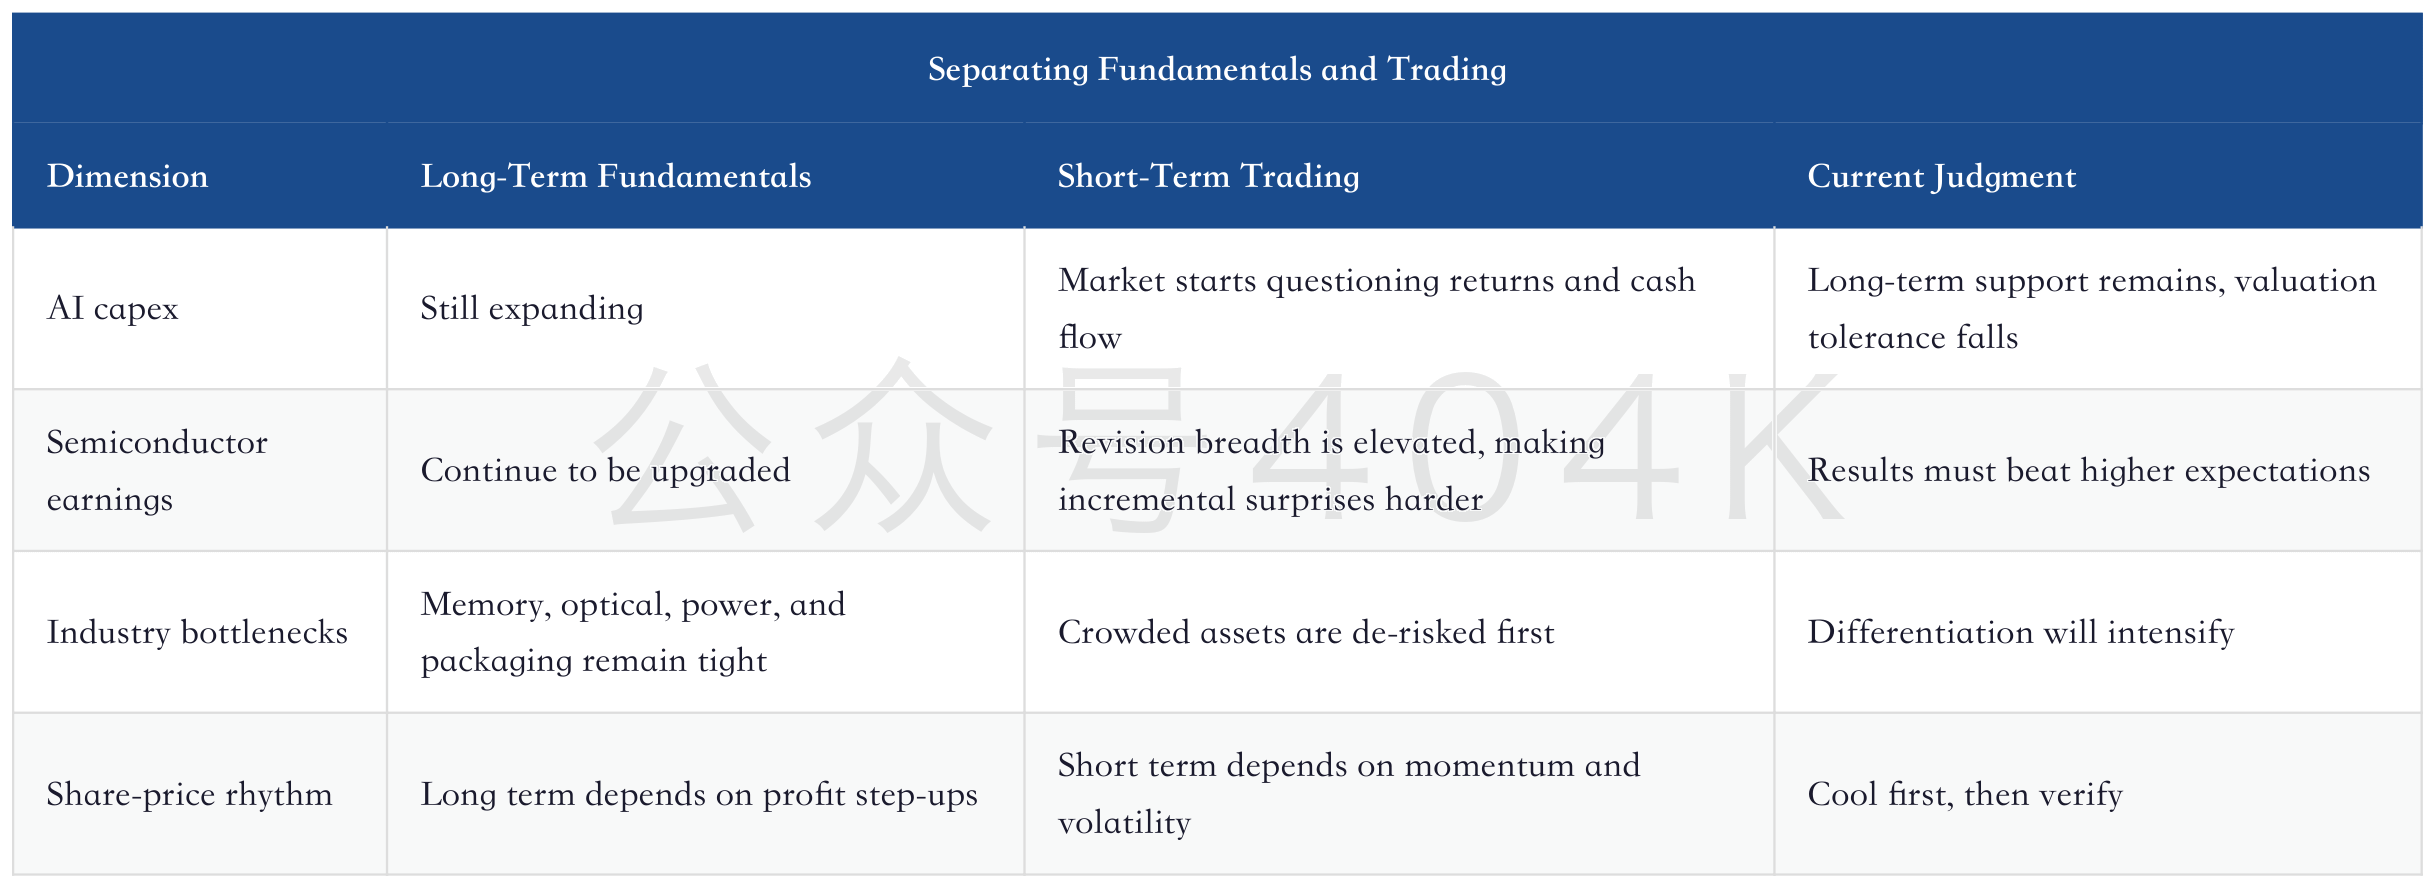
This is also the central point of the report. Being constructive on the industry and cautious on the trade are not contradictory. The real difficulty is identifying trading crowding inside a strong industry trend and avoiding turning long-term correctness into short-term high-level chasing.
15. Three Scenarios: Healthy Rotation, Crowding Release, Risk Repricing
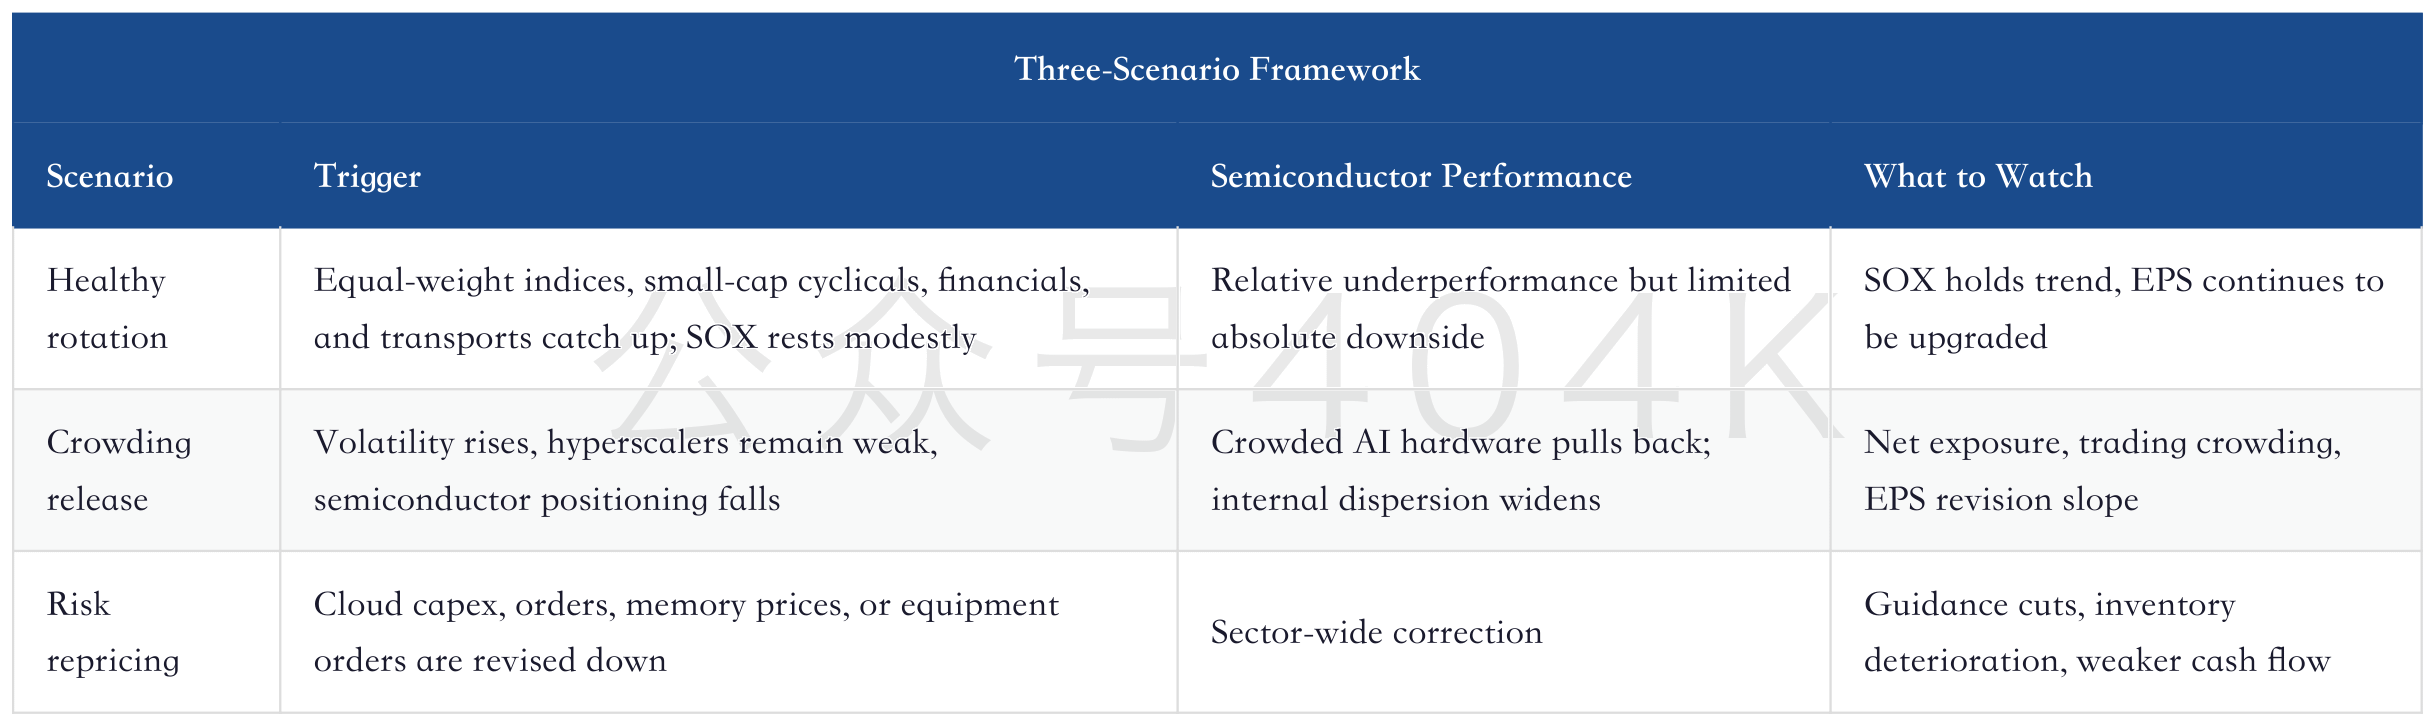
For semiconductors, the most important next step is to distinguish among three scenarios. The first is healthy rotation: AI hardware rests at high levels, capital flows into lower-positioned cyclicals, and semiconductors digest valuations before earnings take over. The second is crowding release: SOX relative returns pull back, earnings upgrades slow, and crowded long positions fall, but orders do not deteriorate meaningfully. The third is risk repricing: hyperscaler capex expectations are revised down, and semiconductor orders and earnings expectations weaken at the same time.
The current situation looks more like something between the first two. Morgan Stanley's wording does not support the third, more extreme scenario, but it warns that the first two may happen first. If the market mistakes the first healthy rotation for the end of the cycle, it may wrongly sell real bottleneck assets. If it mistakes the second crowding release for ordinary volatility, it will underestimate the drawdown in high-valuation assets.
"Peak in Momentum Leadership—Semis."
This phrase comes from the forum page title and emphasizes a leadership peak. A peak in market leadership does not equal a peak in industry fundamentals; it affects relative performance first, then valuations and capital allocation.
16. Implications for A-Share and Asian Semiconductor Stocks
Cooling in U.S. SOX will transmit to A-share and Asian semiconductor stocks, but the transmission is rarely linear. In A-shares and Asia, memory, optical modules, PCB, equipment, packaging and testing, materials, passive components, and server ODMs each have different drivers. Cooling in U.S. semiconductors first pressures valuations and risk appetite; orders and profits come second.
For A-shares, the most sensitive assets are those that have already risen a lot, whose valuations have already priced in AI upside, but whose quarterly profits have not yet fully materialized. The most resilient assets are companies already showing rising prices, capacity bottlenecks, order landing, and cash-flow improvement. A-shares also have domestic substitution, capital-structure, and policy-expectation factors, so SOX cannot be copied mechanically.
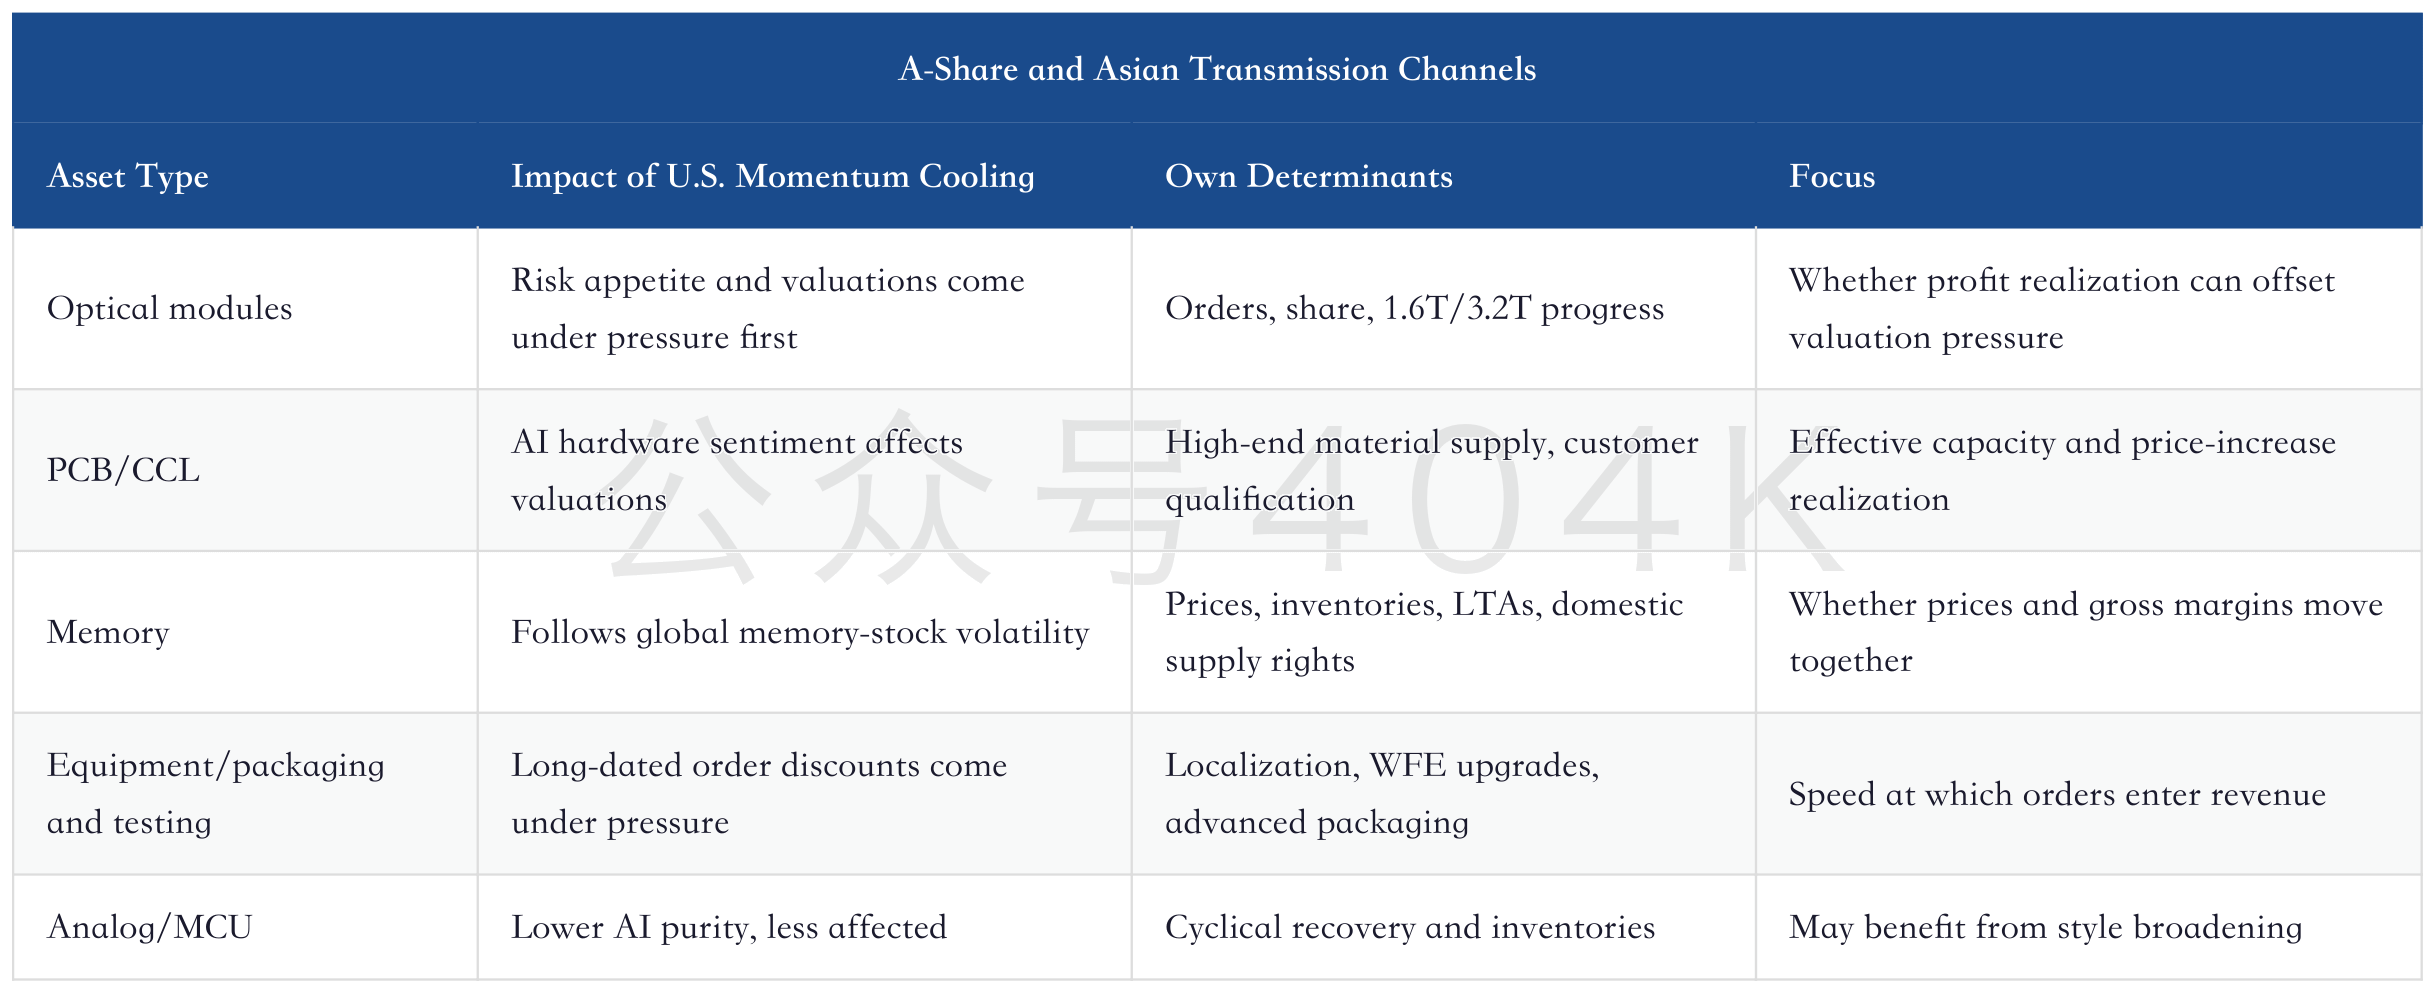
This framework helps avoid simplistic conclusions. Morgan Stanley is warning about a crowded U.S. semiconductor trade; in A-shares, it should not be translated directly into "all semiconductors are uninvestable." The more reasonable action is to separate valuation beta from earnings realization: the more an asset depends on sentiment and long-dated imagination, the more its weight should be reduced; the more it has near-term pricing and cash flow, the more it can continue to be tracked.
17. How to Track Six Indicators Going Forward
The biggest risk in this kind of strategy call is looking only at the view and not the evidence. Morgan Stanley's clues can be converted into six trackable indicators: SOX versus the S&P; 500, hyperscaler relative performance, semiconductor EPS revision breadth, volatility and net exposure, equal-weight relative strength, and oil prices plus real yields. They correspond respectively to price, payer, earnings expectations, positioning, market breadth, and macro environment.
If all six indicators point toward rotation at the same time, the probability of short-term semiconductor underperformance will rise meaningfully. If only one or two signals change, it is more likely ordinary volatility. The real warning sign is simultaneous "payer weakness, peaking EPS upgrades, rising volatility, and equal-weight strength."
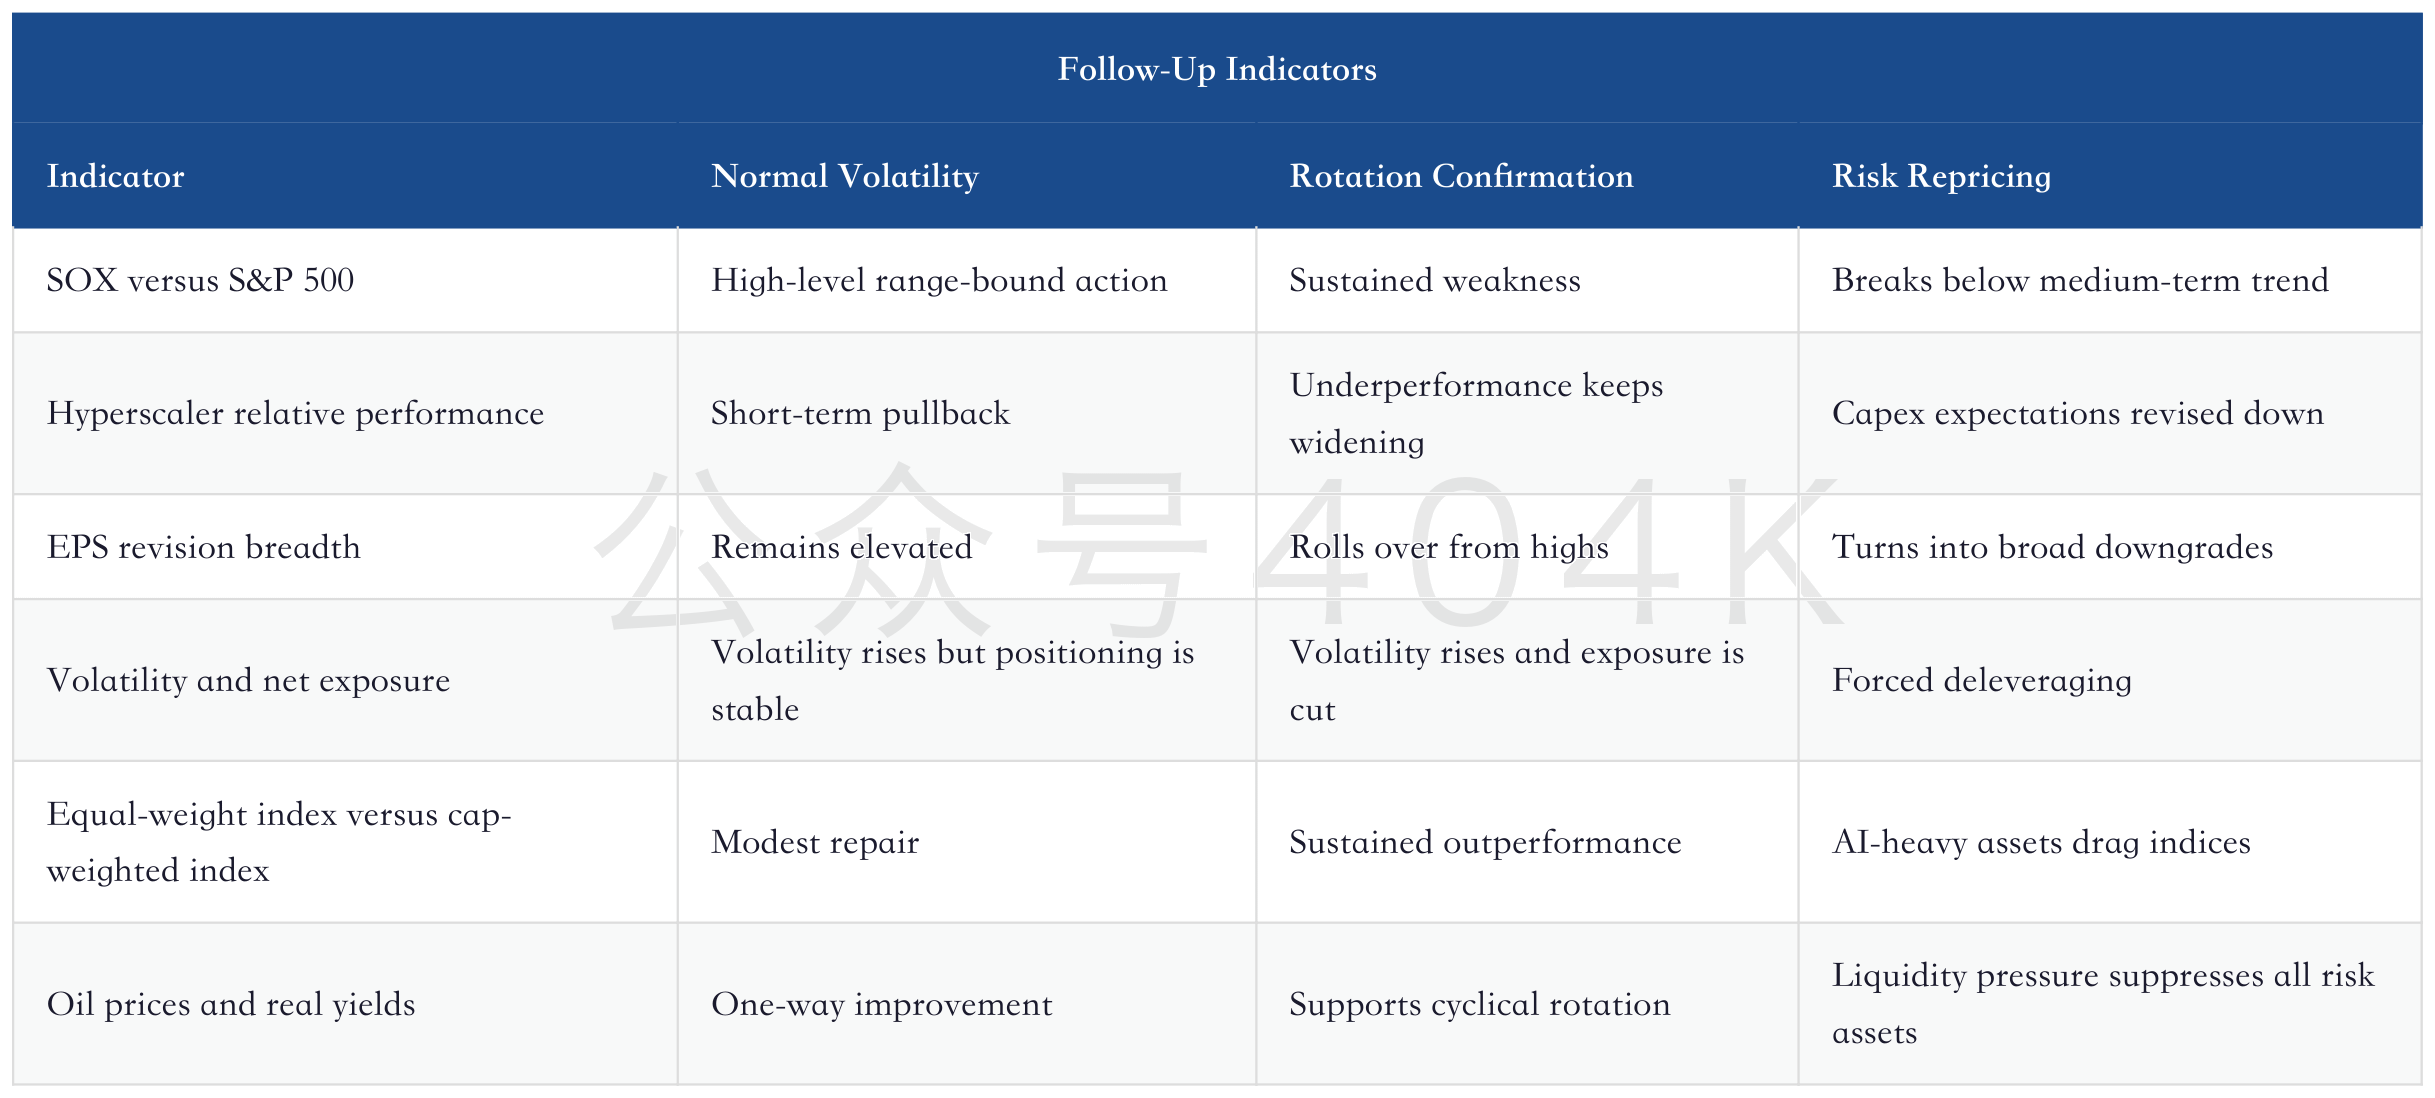
This table is more valuable than saying "Morgan Stanley is bearish on semiconductors." It turns the view into a verifiable framework. As long as SOX remains stable, hyperscalers recover, and EPS upgrades continue, semiconductors are in healthy cooling. If multiple indicators deteriorate simultaneously, the relative-underperformance risk in the report will be repriced by the market.
18. Capital Reallocation: From AI Purity Back to Earnings Breadth
Behind semiconductor momentum cooling is a change in how capital evaluates assets. When the AI trade was strongest, the market awarded higher valuations to assets with high "AI purity": as long as revenue and capex could be linked to AI, valuations expanded easily. Once rotation appears, capital starts to revisit earnings breadth, cash flow, and valuation position. This change will not automatically interrupt the AI theme, but it will reduce the premium attached to the AI label itself.
This change is crucial for semiconductors. Over the past few quarters, the market was more willing to pay for long-dated capacity, customer qualification, next-generation products, and revenue after 2027. Now capital will require more near-term evidence: whether orders have entered production schedules, whether gross margins have already improved, whether cash flow has kept up with earnings, whether customers are willing to sign long-term agreements, and whether capacity expansion will undermine supply discipline. AI purity remains important, but it must appear together with financial quality.
The direction of capital reallocation also explains why Morgan Stanley places semiconductors in the same framework as consumer discretionary goods, transports, and regional banks. The industries look very different, but the underlying question is the same: capital is looking for assets that were previously undervalued, whose earnings are improving, and whose positioning is less crowded. Semiconductors' disadvantage in this comparison is that valuations have already reflected too many tailwinds in advance.
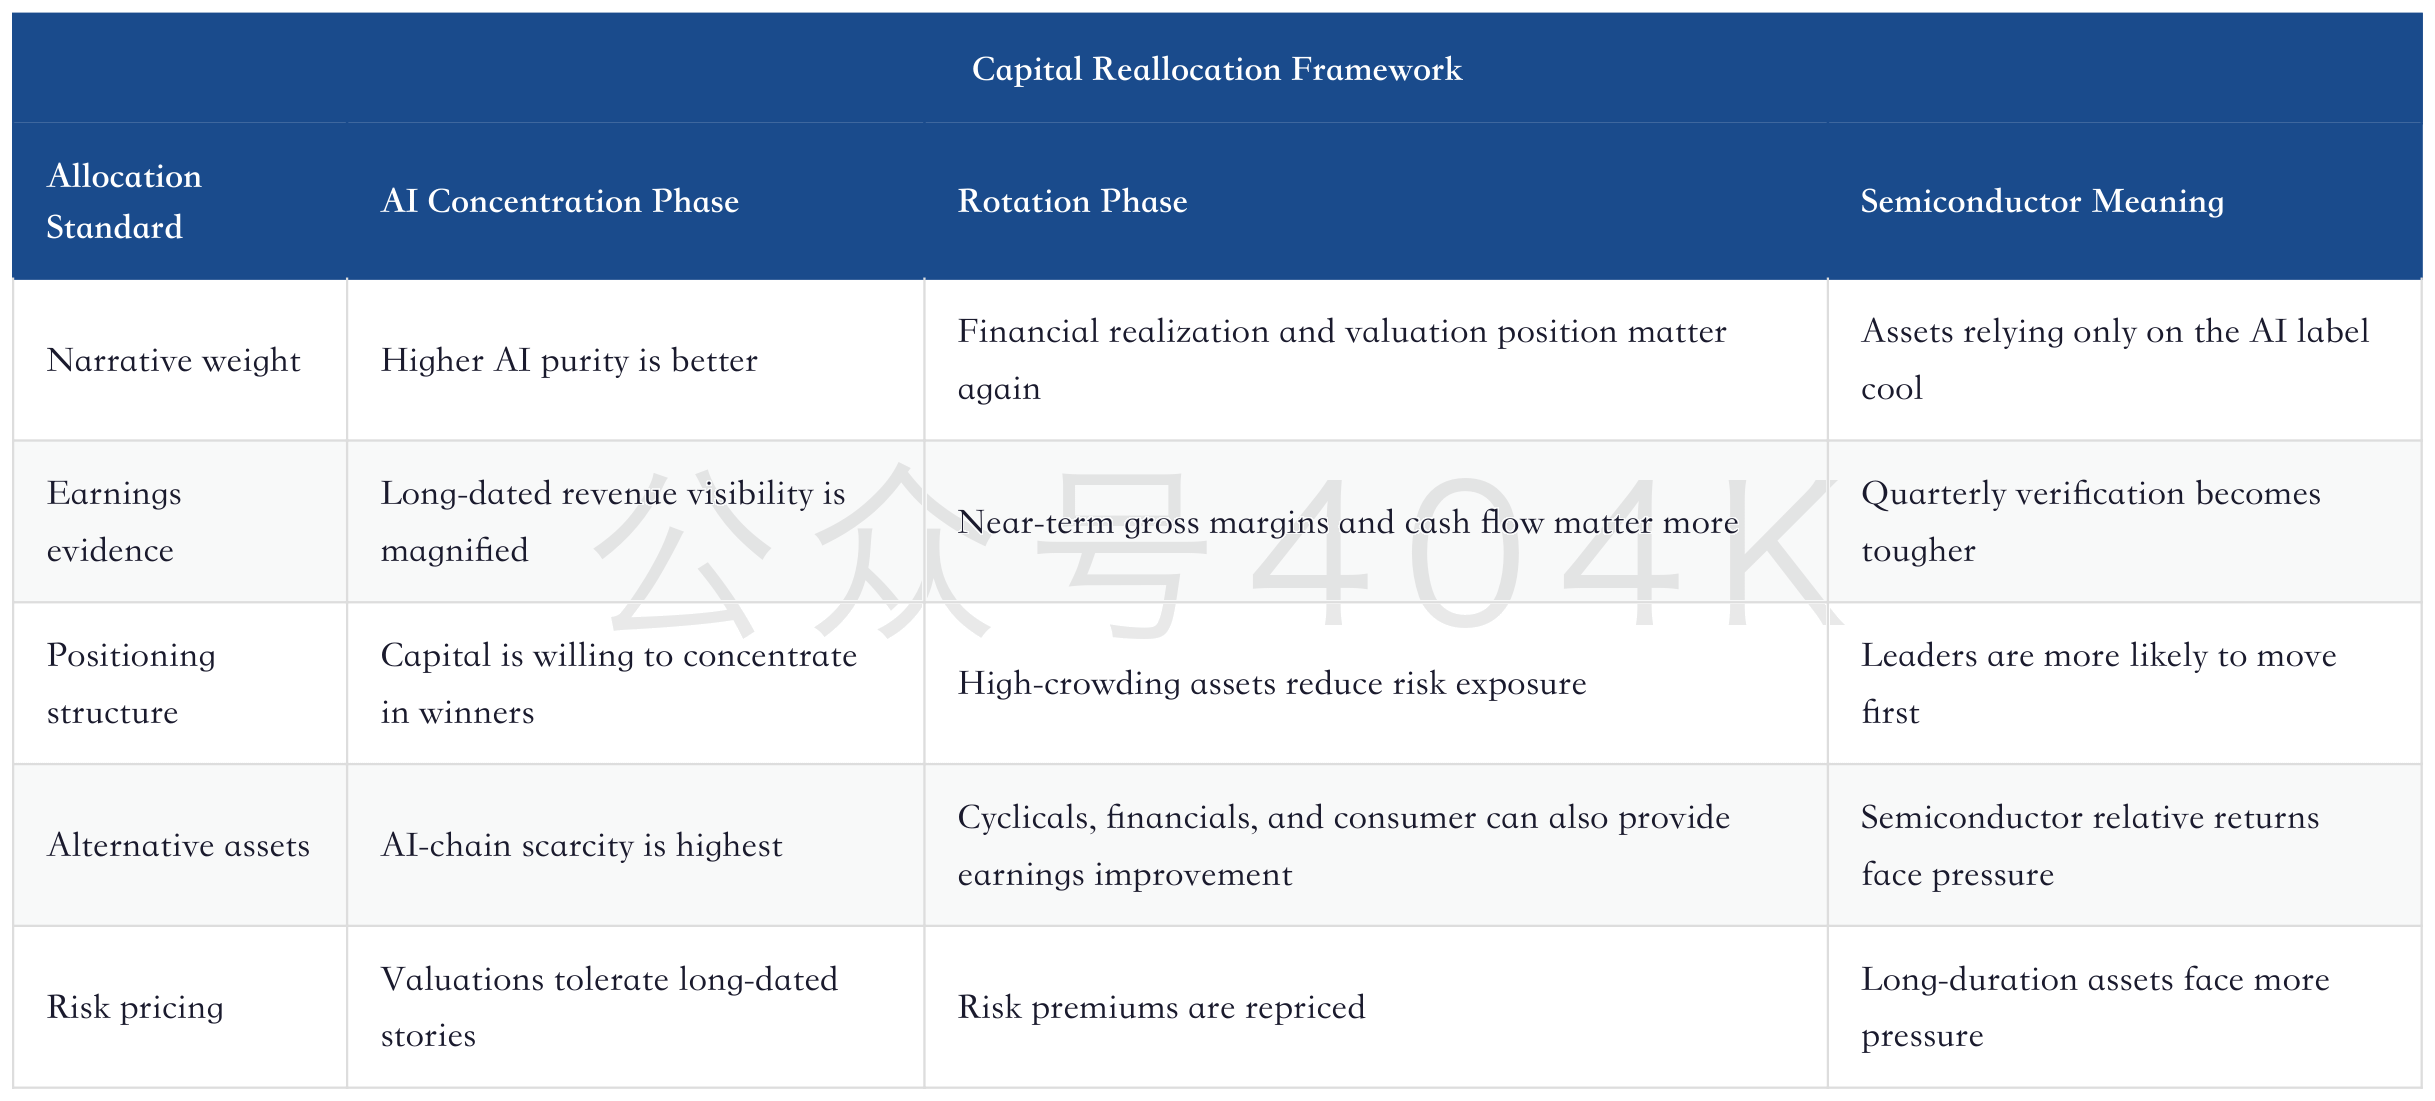
This table shows that current pressure on semiconductors does not come from a single piece of bad news. It comes from a change in the comparison dimension: the market is shifting from "which company looks most like an AI asset" to "which company can still deliver on high expectations." Once the evaluation standard changes, even assets with strong fundamentals will go through valuation digestion.
19. Valuation Floor: Strong Fundamentals Need Higher Cash-Flow Quality
The hardest part of AI semiconductors is that fundamental strength and valuation pressure coexist. Fundamental strength comes from demand and supply constraints; valuation pressure comes from earnings expectations already being upgraded, positioning already being concentrated, and long-dated stories already being discounted. Research cannot look at only one side. Looking only at fundamentals underestimates crowded-trade drawdown; looking only at trading pressure misses true bottleneck assets.
The valuation floor must return to cash-flow quality. If a semiconductor company is only growing revenue quickly, but inventory, receivables, capex, and customer concentration are all rising at the same time, the market will apply a higher discount. If a company can simultaneously deliver stable orders, improving gross margins, cash flow keeping up, healthy inventory, and clear capacity discipline, its valuation is more likely to survive rotation. This floor applies to memory, equipment, optical interconnects, PCB, and passive components.
Cash-flow quality also determines how "peak profits" are priced. In the mid-to-late stage of a cyclical rally, the market often asks whether profits are at a peak. If price increases are accompanied by cash-flow improvement and long-term agreements, the peak-profit discount falls; if price increases are accompanied by inventory accumulation and customer pull-ins, the peak-profit discount rises. Morgan Stanley's warning about a semiconductor momentum top is also a reminder for the market to recheck this discount.
