
Morgan Stanley CPO Glass-Bridge Deep Dive Update: GlassBridge Substitution Anxiety, TSMC 25kwpm PIC, and FAU Supply-Chain Repricing
目录
Too Long; Didn’t Read
1. Glass Bridges Push the CPO Debate to the Packaging Interface Layer
2. The Near-Term Main Line Remains TSMC COUPE and Grating Coupling
III. TSMC PIC Capacity Determines the Upper Limit for CPO Shipments
IV. Insertion Testing Is an Underappreciated Mass-Production Gate
V. Supply Chain Ranking: FAU Monetizes First, GlassBridge Pushes Out the Longer-Term Ceiling
VI. FOCI: 2026 as Transition, 2027 as the Start of the Revenue Slope
VII. AllRing: Advanced Packaging Base Makes CPO Equipment Easier to Monetize
VIII. Three Worldviews: GlassBridge Rapidly Substitutes, COUPE Mass Production on Schedule, Testing Bottlenecks Slow the Ramp
IX. Investment Conclusion: CPO Enters Second-Order Trading
X. Risks and Falsification Checklist
本内容基于公开资料和研报数据整理,不构成任何投资建议,不代表任何个人观点,仅供学习参考,请理性阅读
This CPO update brings optical-module trading back to mass-production details: glass bridges create long-term substitution pressure, while in 2026-27 investors should focus more on TSMC PIC capacity, post-SoIC test efficiency, FAU/equipment supply-chain revenue conversion, and when GlassBridge moves from samples to a customer-standard interface.
Too Long; Didn’t Read
GlassBridge first changes long-term imagination. It integrates glass waveguides, pluggable connections, and passive alignment into a unified interface solution, addressing high channel count, testability, reworkability, and reflow compatibility. But it is currently closer to edge coupling and linear fiber layouts, making it difficult to directly replace the main grating-coupling path still being advanced by TSMC COUPE, NVIDIA, AMD, and Ayar Labs in the near term.
The CPO mass-production gate is TSMC PIC. Morgan Stanley expects TSMC PIC capacity to rise from roughly 500 wafers per month today to 10kwpm in 2Q26, 15kwpm in 4Q26, and at least 25kwpm in 2028. Only if downstream assembly yield improves from 20% to 50% can actual optical-engine shipments move from the million-unit level toward the tens-of-millions level.
Test efficiency is the hidden bottleneck. Post-SoIC Insertion 2 testing has improved from one wafer per day in 2H25 to one wafer every six hours today, with a target of one wafer every 3-4 hours over the next 6-12 months. This determines the order slope for equipment and fixture companies such as Chroma ATE, MPI Corporation, WinWay Technology, and AllRing Tech as CPO moves from samples and NRE to MP.
The FAU supply chain still has a two-year window. Morgan Stanley believes NVIDIA’s Spectrum CPO switch will be FOCI’s main source of mass-production revenue in 2026. FOCI has roughly 40% share in NVIDIA CPO FAU, and NVIDIA’s contribution to FOCI revenue could rise from 18% in 2026 to 80% in 2028. Glass bridges will cap the upper end of valuation, but in the near term look more like a long-term risk item.
AllRing’s execution quality is closer to advanced packaging. AllRing’s CoWoS business remains its base, while CPO equipment revenue contribution is expected to rise from 11% in 2026 to 26% in 2028, with CPO equipment gross margin reaching 55-60%. These companies earn money from the certainty of packaging expansion, optical-engine coupling, and AOI, and are not entirely dependent on a single optical route.
Investment ranking is entering Phase 2. Phase 1 bought CPO concepts and optical-module beta. Phase 2 should rank names by mass-production gates: first TSMC PIC expansion, Insertion testing, and Spectrum/Quantum/Rubin Ultra nodes; then whether suppliers such as FOCI, TFC Communication, AllRing, MPI Corporation, and WinWay Technology can turn share into revenue and profit.
1. Glass Bridges Push the CPO Debate to the Packaging Interface Layer
The most valuable part of this report is that it moves the CPO discussion from “will optical modules be replaced?” to “how does light connect to the silicon photonics chip?” Over the past year, the market has become more familiar with system-level terms such as 800G, 1.6T, 3.2T, LPO, CPO, and NPO. But the details that often block mass production are more granular: how fiber arrays are fixed, how PICs are tested, how optical engines align with switch chips, packages, and board-level interconnects, and whether failed parts can be reworked.
The emergence of GlassBridge makes this issue sharper. Traditional FAU places fibers into V-grooves and then aligns them with the PIC through glass, silicon, or quartz substrates. Its advantages are maturity, low loss, and customizability; its disadvantages are that as channel count and density rise, assembly, alignment, and consistency become increasingly difficult. GlassBridge packages glass waveguides, connectors, and passive alignment into a bridge-type structure, aiming to improve manufacturability and serviceability in high-density fiber access.
This is not a simple case of “new solution eats old solution.” GlassBridge is more like turning the CPO/NPO interface from a one-time assembly component into a system-level connection architecture: it can be tested first and connected later, and it is easier to rework and standardize as a platform interface. But CPO’s biggest commercial issue today remains mass-production ramp, not conceptual sophistication. Near-term trading should not only focus on whose route sounds more elegant, but on who can enter real customer nodes such as TSMC COUPE, NVIDIA Spectrum/Quantum, AMD MI500, and Ayar Labs.
AI Network Interconnect Hardware Part 1: The Value Migration Behind 1.6T/3.2T, and Who Benefits Most Across Switching, Copper Interconnect, Optical Interconnect, and the Physical Layer
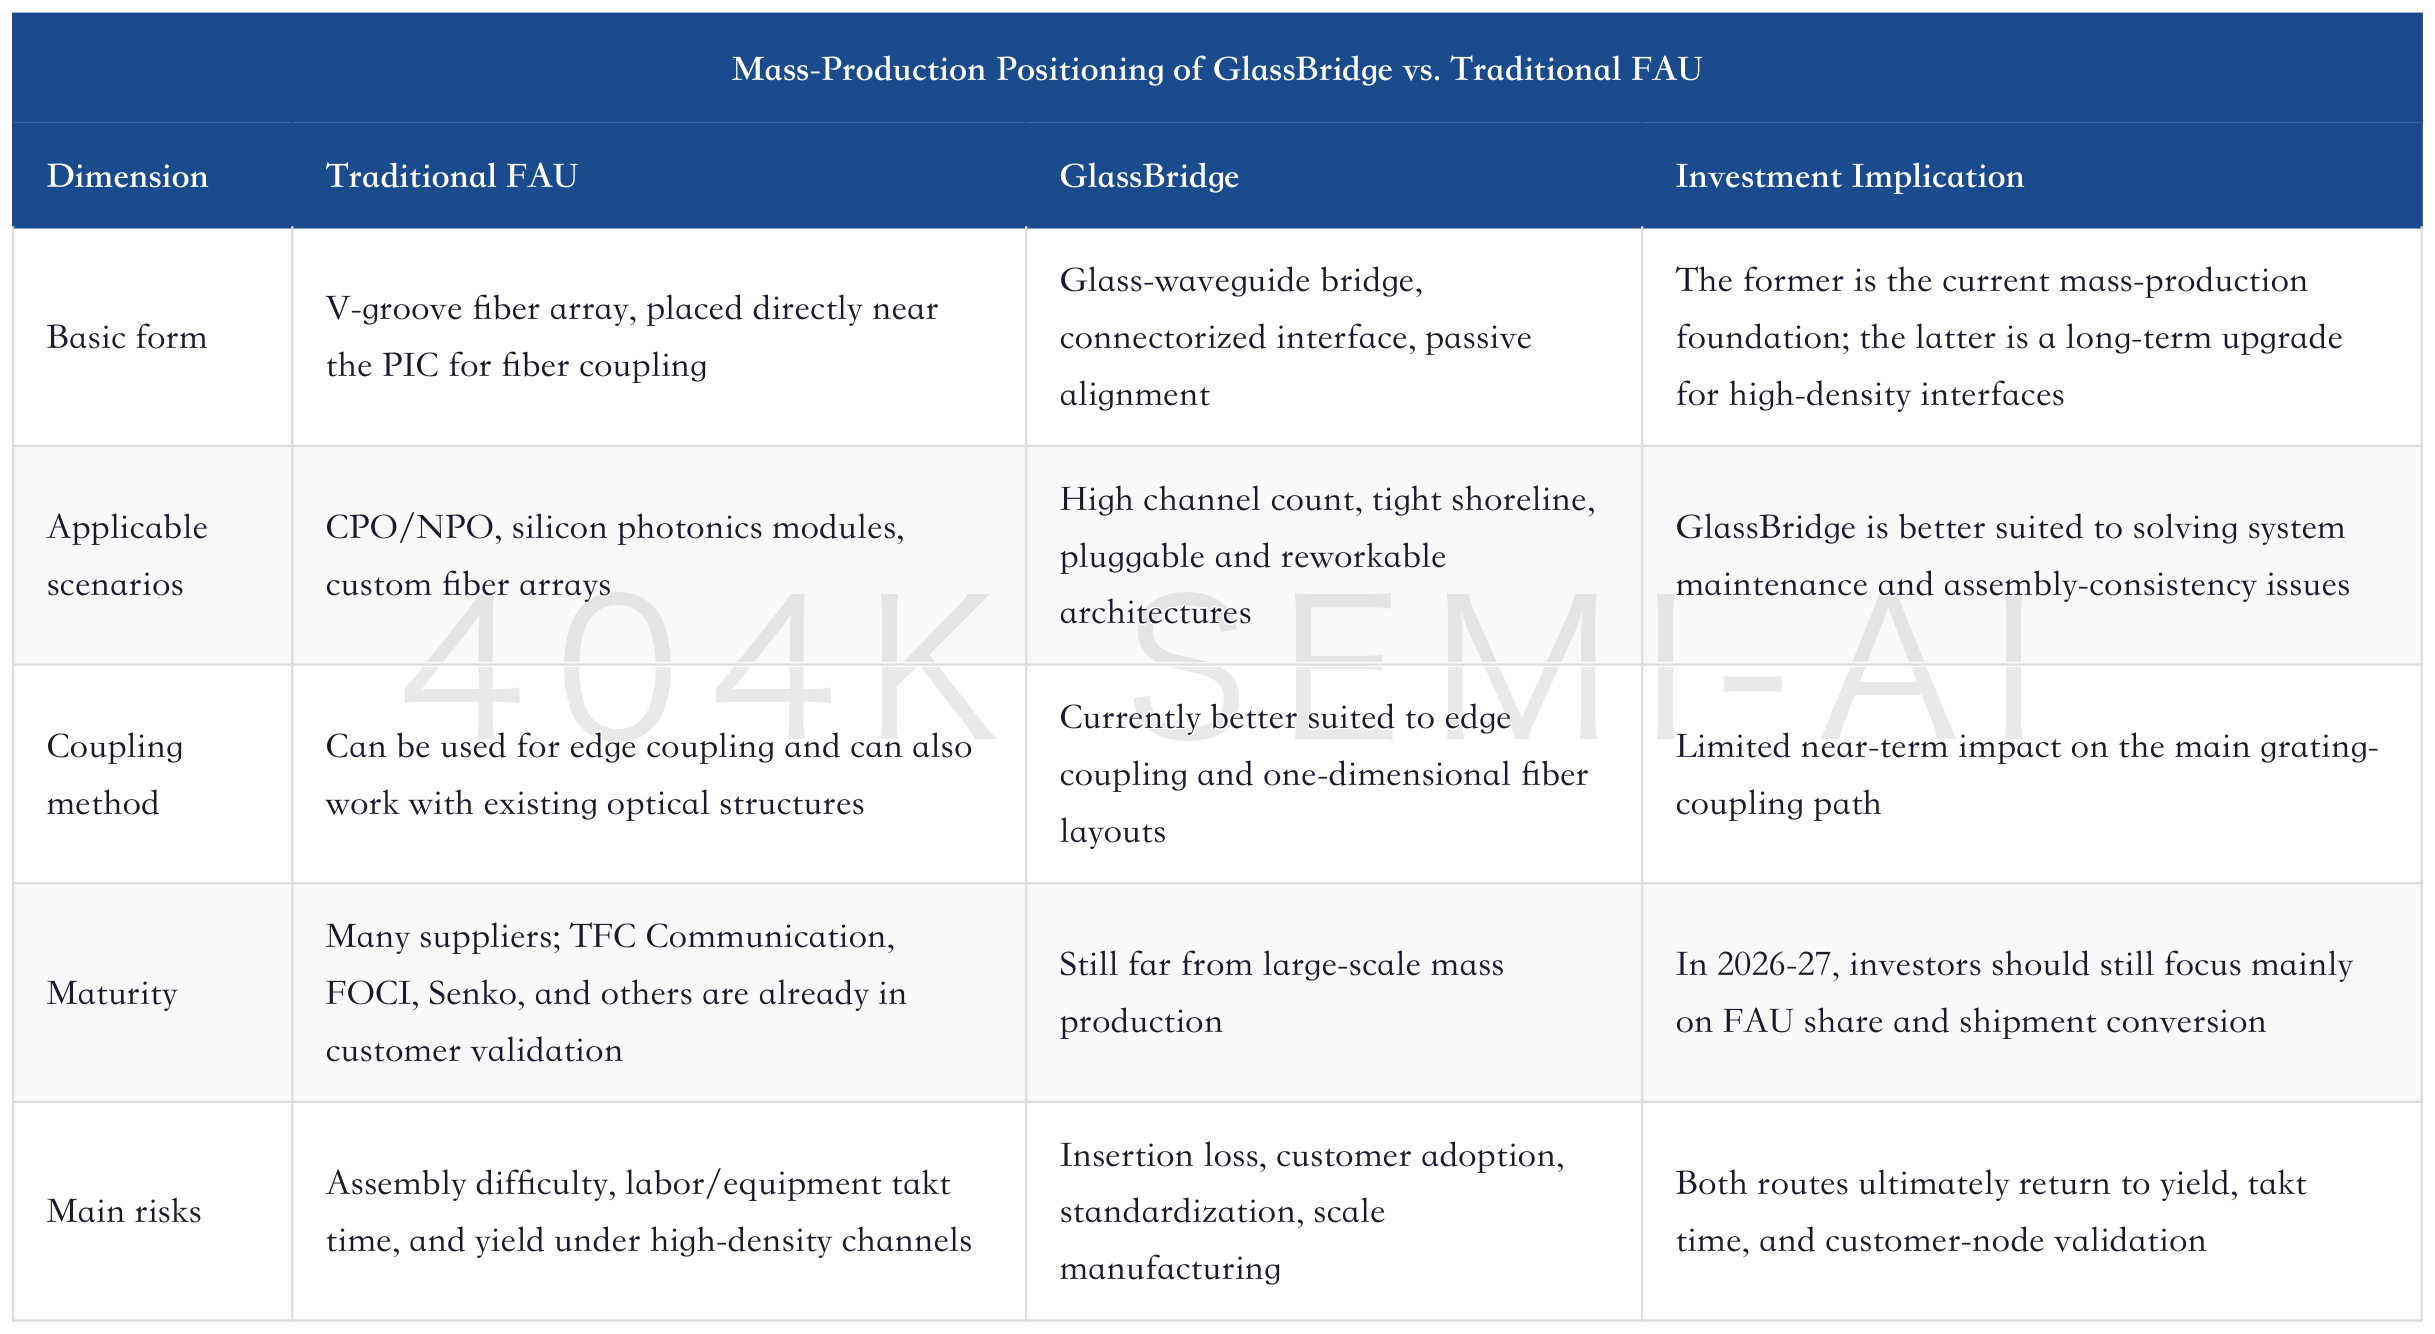
For investment, the first-order impact of GlassBridge is to compress the long-term valuation fantasy for traditional FAU. As long as the market believes CPO will move toward high-channel-count, serviceable, and reconfigurable system interfaces, FAU suppliers cannot price themselves only on “I am exclusive” or “I am scarce.” The second-order impact is more important: it reminds the market that CPO is not a single-device substitution, but a migration of packaging, testing, optics, connectors, and system architecture together. Whoever secures a mass-production insertion point gets the profit.
2. The Near-Term Main Line Remains TSMC COUPE and Grating Coupling
Morgan Stanley’s attitude toward GlassBridge is actually restrained: the solution is strong, but it remains some distance from large-scale mass production. This judgment is critical for trading, because if investors treat glass bridges as a variable that will replace FAU at scale in 2026, they will prematurely cut off the mass-production window for FAU suppliers such as TFC Communication, FOCI, and Senko.
The more realistic main line today is TSMC COUPE. The report argues that TSMC COUPE and the routes pursued by NVIDIA, AMD, Ayar Labs, and others are more likely to continue using grating coupling over the next few years because it is easier to enter near-term mass production. GlassBridge’s current position is more like a high-density bridging solution within edge coupling, first solving some interface pain points before seeing whether it can expand into more system architectures.
One point the market can easily misread is that GlassBridge does not naturally equal lower insertion loss. Corning’s public materials on O-band fiber-to-PIC coupling have cited an insertion-loss figure of about 1.5 dB, while traditional FAU components can achieve much lower insertion loss under specific processes and assembly conditions. Which one is ultimately better depends on total system loss, assembly takt time, reworkability, yield, customer reliability standards, and total system cost, not on comparing a single optical parameter in isolation.
CPO Bull-Market Expectations Cool: Architecture Debate Cannot Stop Optical Content Growth as AI Clusters Enter the Optical Interconnect Era
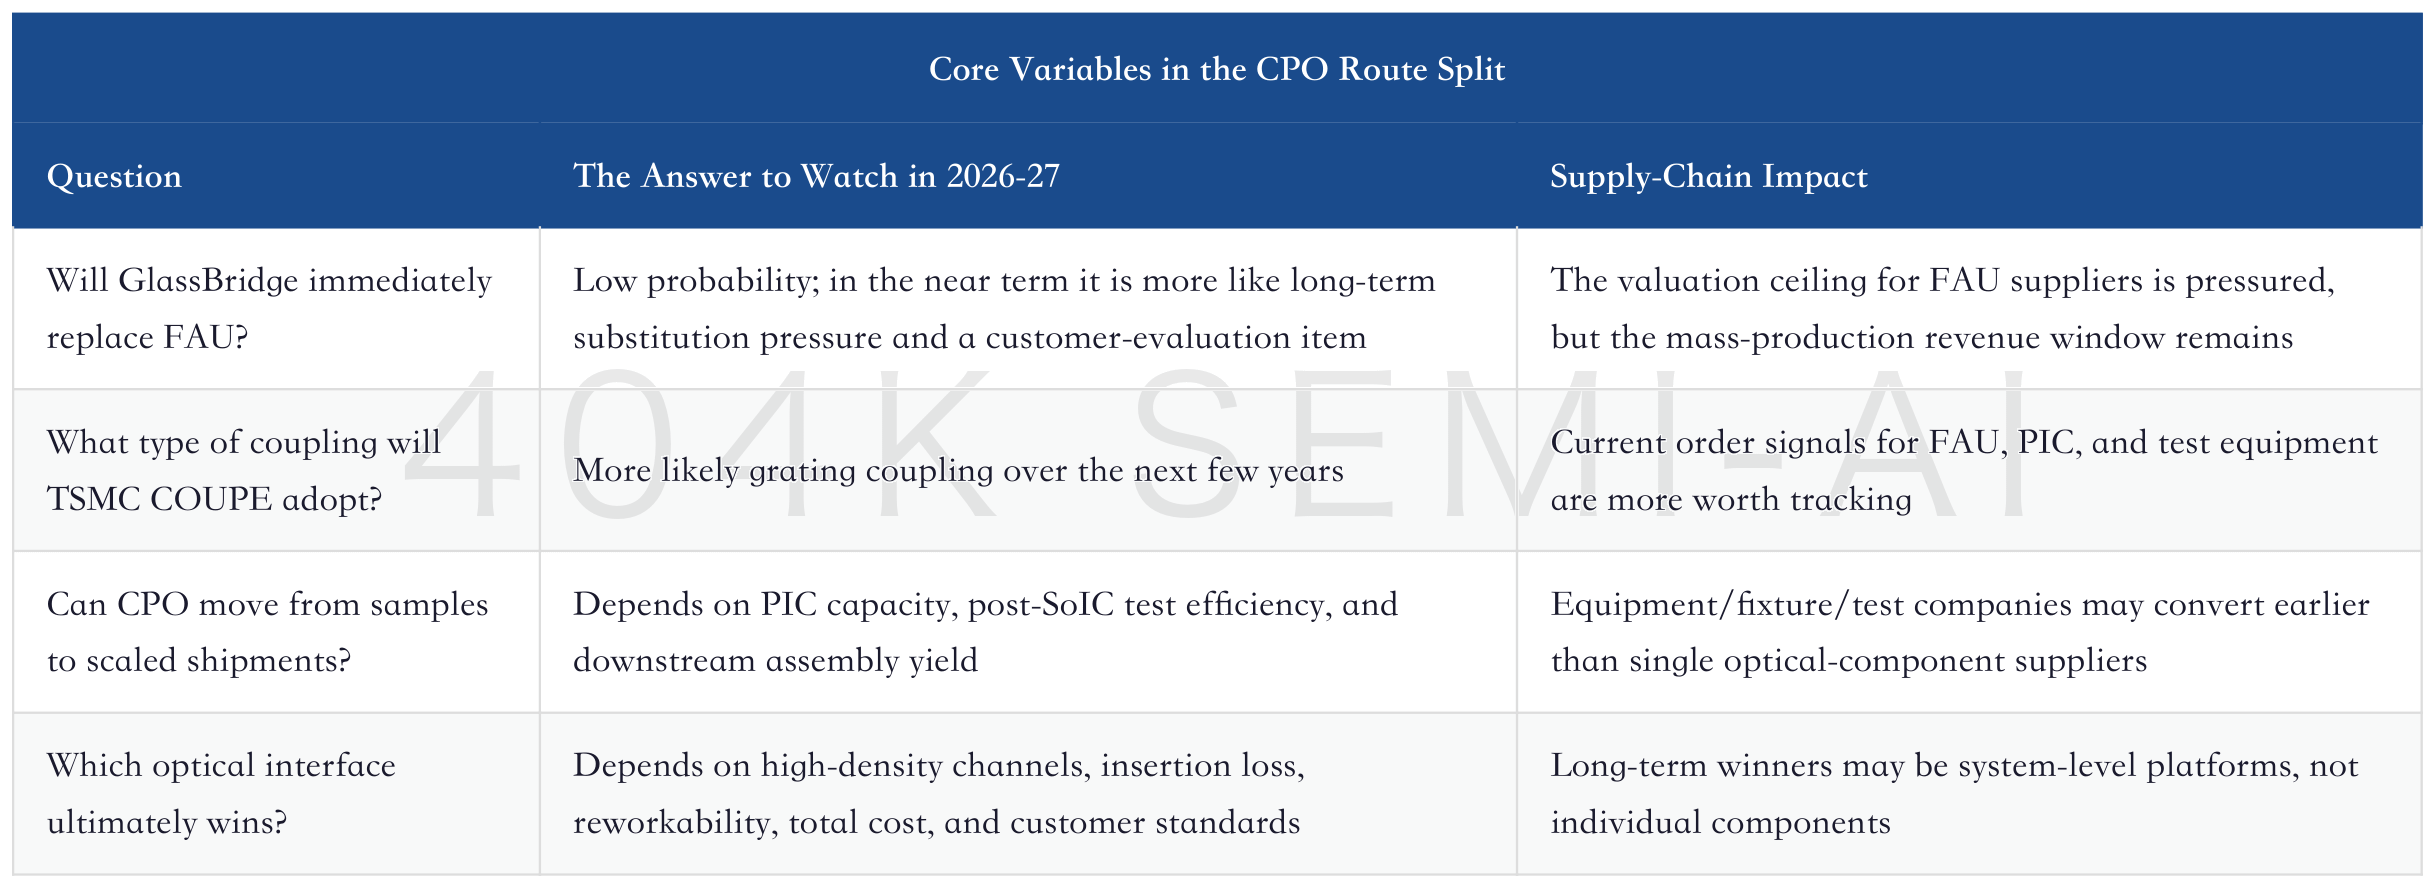
Under this framework, CPO trading needs to move from “will optical modules be replaced by CPO?” to “which nodes become orders first?” The first step is scale-out switching such as NVIDIA Spectrum CPO switches and Broadcom Tomahawk. The second step is scale-up or chiplet/OIO nodes such as AMD MI500, Ayar Labs, and AWS Trainium. The third step is the longer-term Feynman Ultra, Rubin Ultra follow-on generations, and higher-density connection solutions. Glass bridges have more imagination in the third step, while in the first and second steps they still need validation through customer roadmaps.
III. TSMC PIC Capacity Determines the Upper Limit for CPO Shipments
The supply ceiling for CPO starts with TSMC’s PIC capacity. The cadence in the report is clear: current PIC capacity is about 500 wafers per month, with a plan to reach 10kwpm in 2Q26, 15kwpm in 4Q26, and at least 25kwpm by 2028. This may look like just wafer capacity, but in practice it determines whether optical engines can move from engineering samples into volume shipment.
Morgan Stanley breaks down this logic with a bottom-up calculation: each wafer yields about 648 dies, SoIC yield is assumed at 50%, and if downstream assembly yield remains only 20%, 25kwpm of PIC capacity does not translate directly into 97 million optical engine shipments. Only when assembly yield improves to 50% could actual optical engine shipments approach 48.6 million units. CPO only has real supply elasticity when capacity and yield are considered together.
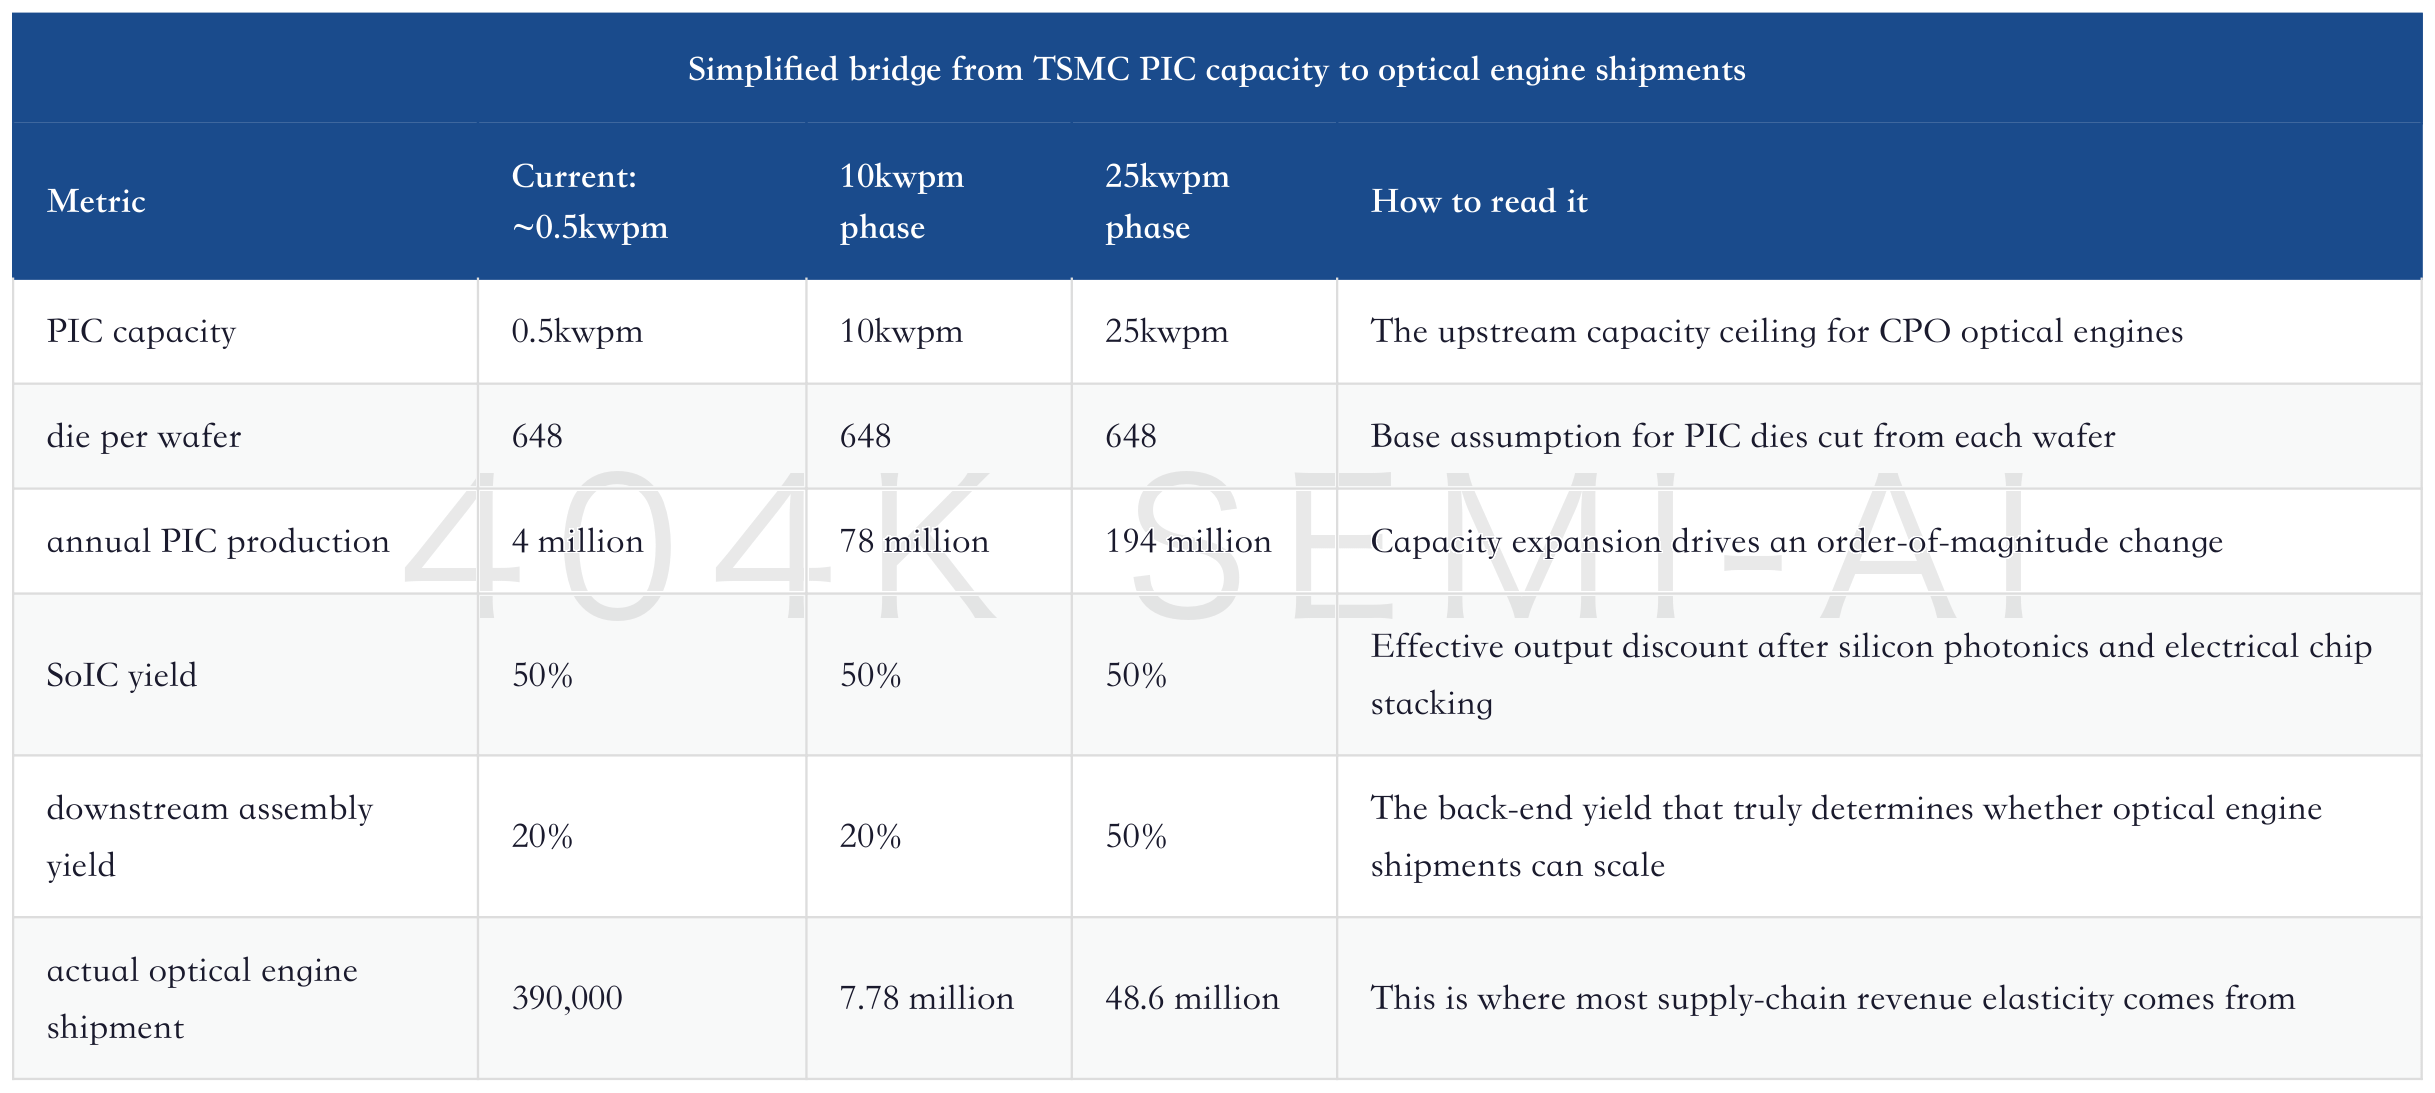
This calculation has two valuation implications. First, CPO in 2026 is still ramping from 100T switches and small-batch customer nodes; suppliers should not all be fully valued in advance using a long-term 2030 assumption of 200k CPO switch shipments. Second, as long as TSMC’s PIC capacity and downstream assembly yield are delivered quarter by quarter, supply-chain revenue should see stepwise upward revisions, especially for companies tied to mass-production bottlenecks such as FAU, optical engine testing, AOI, dispensing, sockets, and handlers.
The CPO switch shipment curve also supports this cadence. The report expects about 23k CPO switches in 2026, mainly 100T, with NVIDIA Spectrum taking the majority share; shipments rise to 59k in 2027 and about 200k by 2030. This curve is not linear. The key inflection depends on system adoption across Spectrum, Quantum, Tomahawk, Rubin Ultra, MI500/MI600, and cloud vendors’ in-house ASICs. If a supply-chain company only receives NRE and small-batch samples, it is hard to support a high valuation; if it enters MP on mainstream platforms, the valuation model changes materially.
IV. Insertion Testing Is an Underappreciated Mass-Production Gate
Many CPO discussions focus on the optical components themselves, but this report goes into considerable detail on testing. The real challenge in CPO is that electrical, optical, and high-speed signal quality must be verified at different stages: before packaging, after packaging, at the finished optical engine level, and at the switch system level. Traditional optical modules can undergo extensive module-level testing. CPO places the optical engine close to the switch ASIC, moving the test window forward and increasing rework cost, which makes wafer-level and package-level testing capabilities more valuable.
The most important step is Insertion 2: wafer-level E/O, O/E, O/O, and high-speed S-parameter testing after SoIC. The report notes that throughput at this stage has improved from one wafer per day in 2H25 to about one wafer every six hours today, with a target of one wafer every three to four hours over the next six to twelve months. This change is more concrete than simply talking about CPO mass production, because it directly determines whether TSMC’s PIC capacity expansion can be converted into deliverable optical engines.
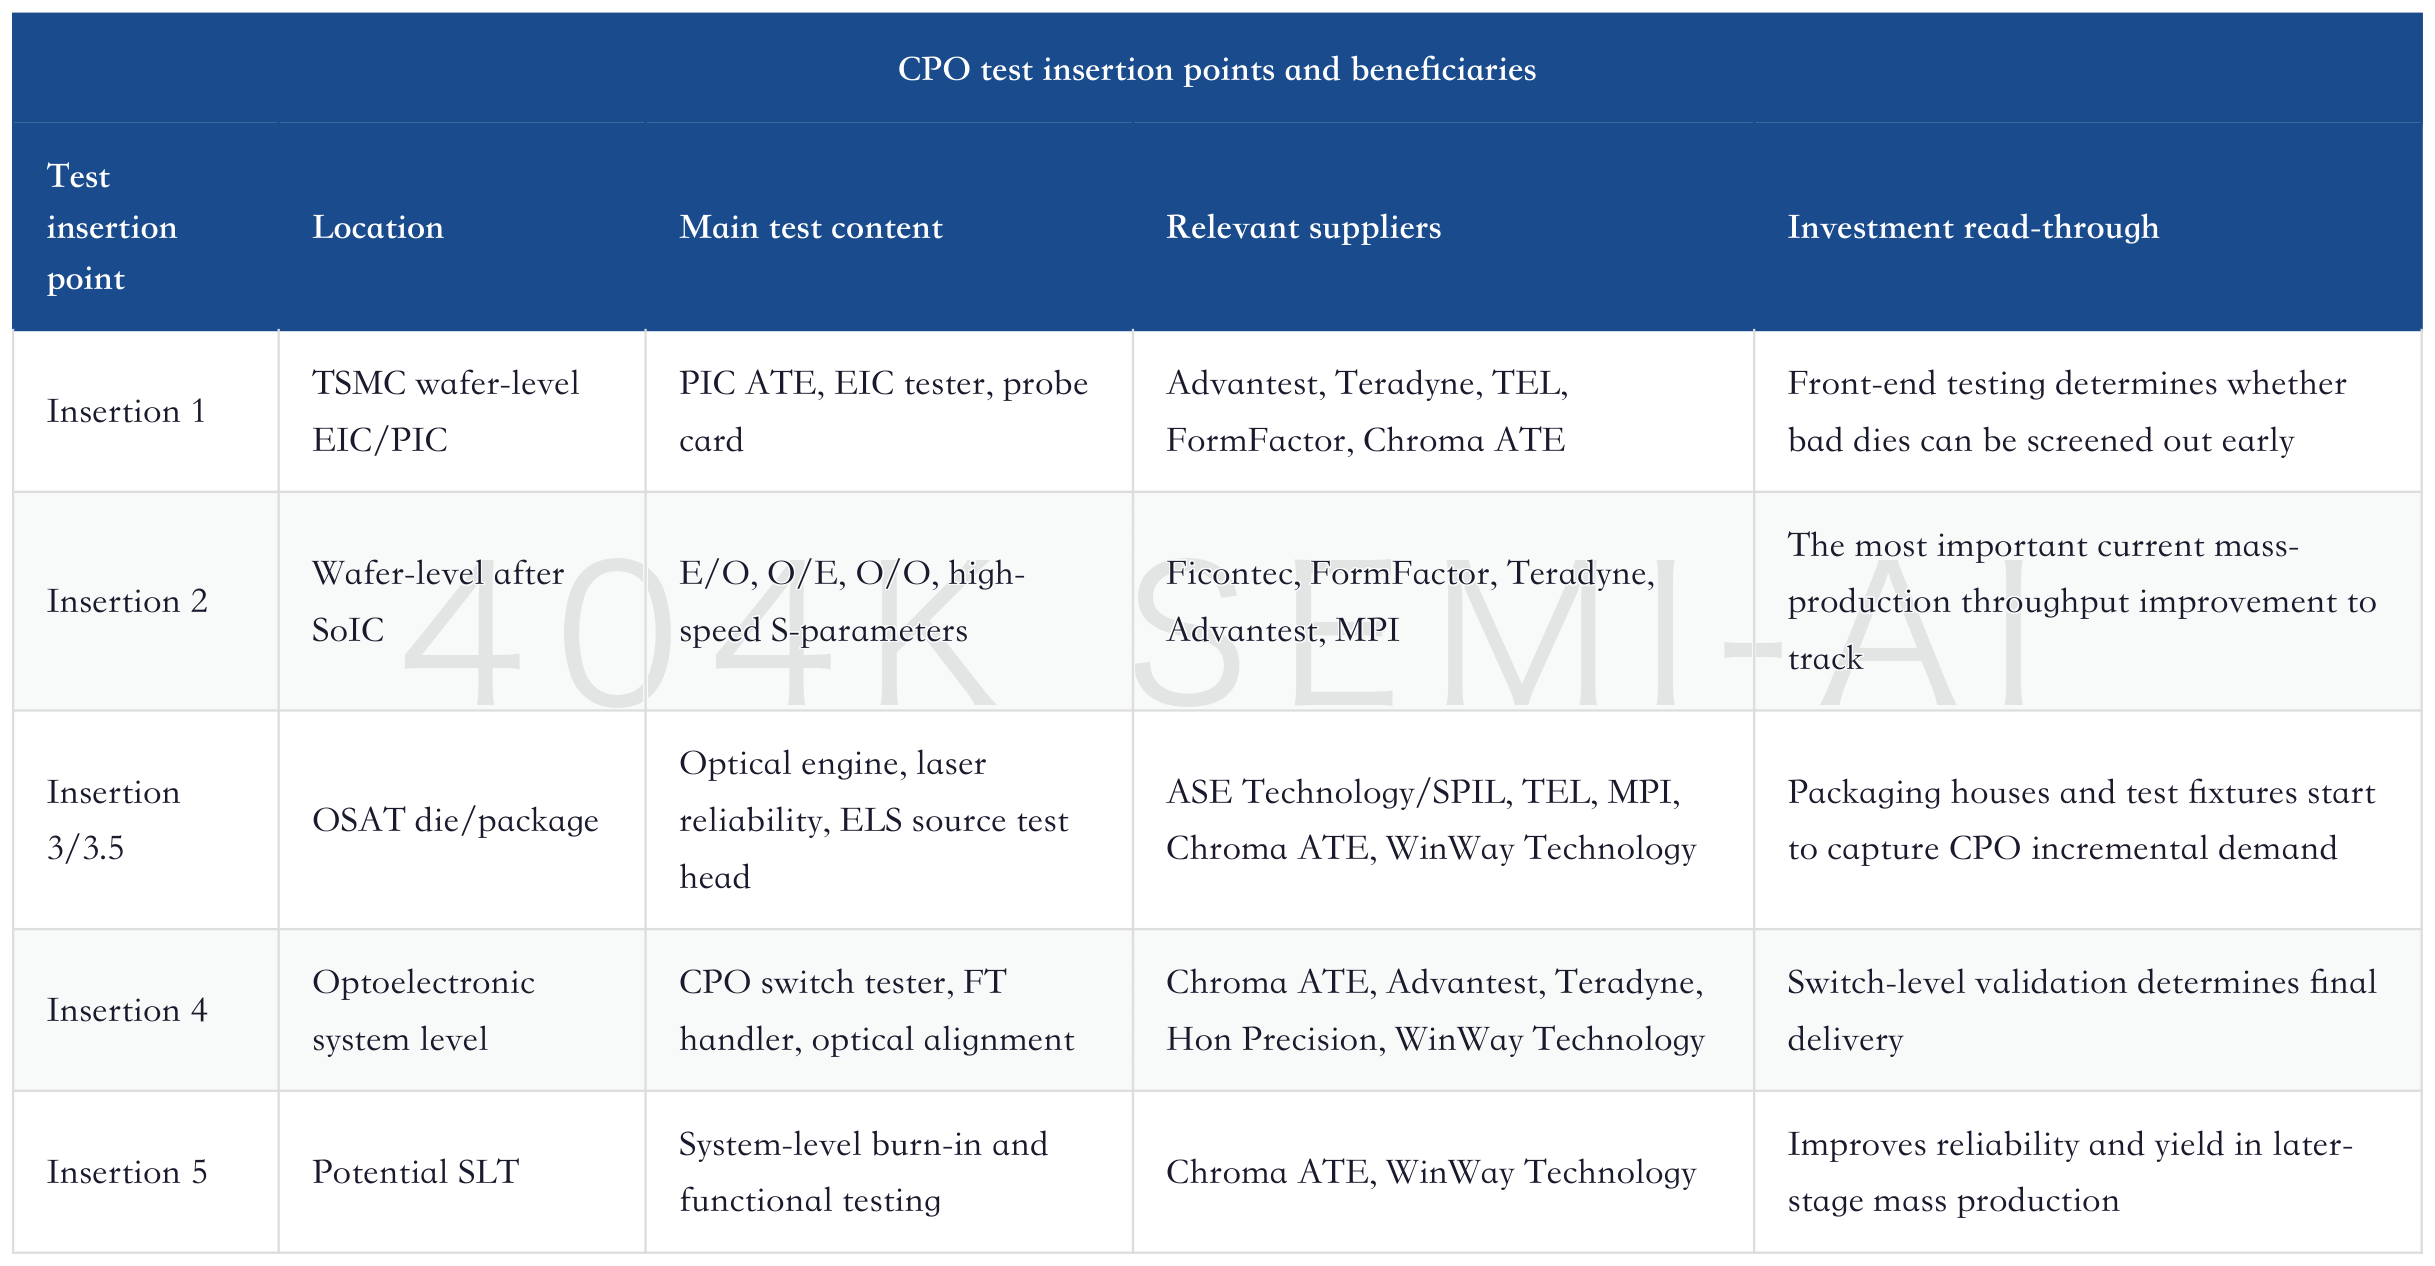
This is also why the CPO trade should not be limited to leading optical module vendors. At the mass-production stage, supply-chain profits may be redistributed along the testing difficulty curve: Chroma ATE, which can build optical engine testers; FormFactor/MPI, which can provide probe cards and test interfaces; WinWay Technology, which can make high-end sockets; and Hon Precision, which can provide optical alignment and handlers, should all gain stronger pricing power in customer validation. They may not all have the greatest revenue elasticity, but they are closer to the mass-production bottleneck.
If there is only one CPO progress metric to watch over the next two to three quarters, priority should go to evidence that Insertion 2 is moving from six hours per wafer toward three to four hours per wafer. It matters more than customer demos, and it says more about the approach of mass production than claims that a certain architecture has been validated. As long as this throughput continues to improve, CPO orders from 2H26 into 2027 will become more credible.
V. Supply Chain Ranking: FAU Monetizes First, GlassBridge Pushes Out the Longer-Term Ceiling
In Morgan Stanley’s Asia CPO supply-chain list, TSMC, ASE Technology Holding, FOCI, AllRing, MPI Corp., WinWay Technology, and Hon Precision are positioned more positively, while Tianfu Communication is also viewed as a competitive representative in high-end FAU. The logic behind this ranking is straightforward: in 2026-27, CPO is still moving from engineering samples to mass production, and the companies that actually make money are those entering customer BOMs, NRE, MP, and equipment procurement.
The FAU supply chain still has a two-year window. The report explicitly notes that FOCI’s CPO MP revenue will start in July 2026 and scale in 2027, with early contribution mainly from Spectrum CPO switches. Tianfu Communication, FOCI, and Senko are among the core FAU supplier combinations for NVIDIA’s 2026 scale-out CPO. For FAU companies, GlassBridge is pressure on the valuation ceiling, not a signal of a 2026 revenue collapse.
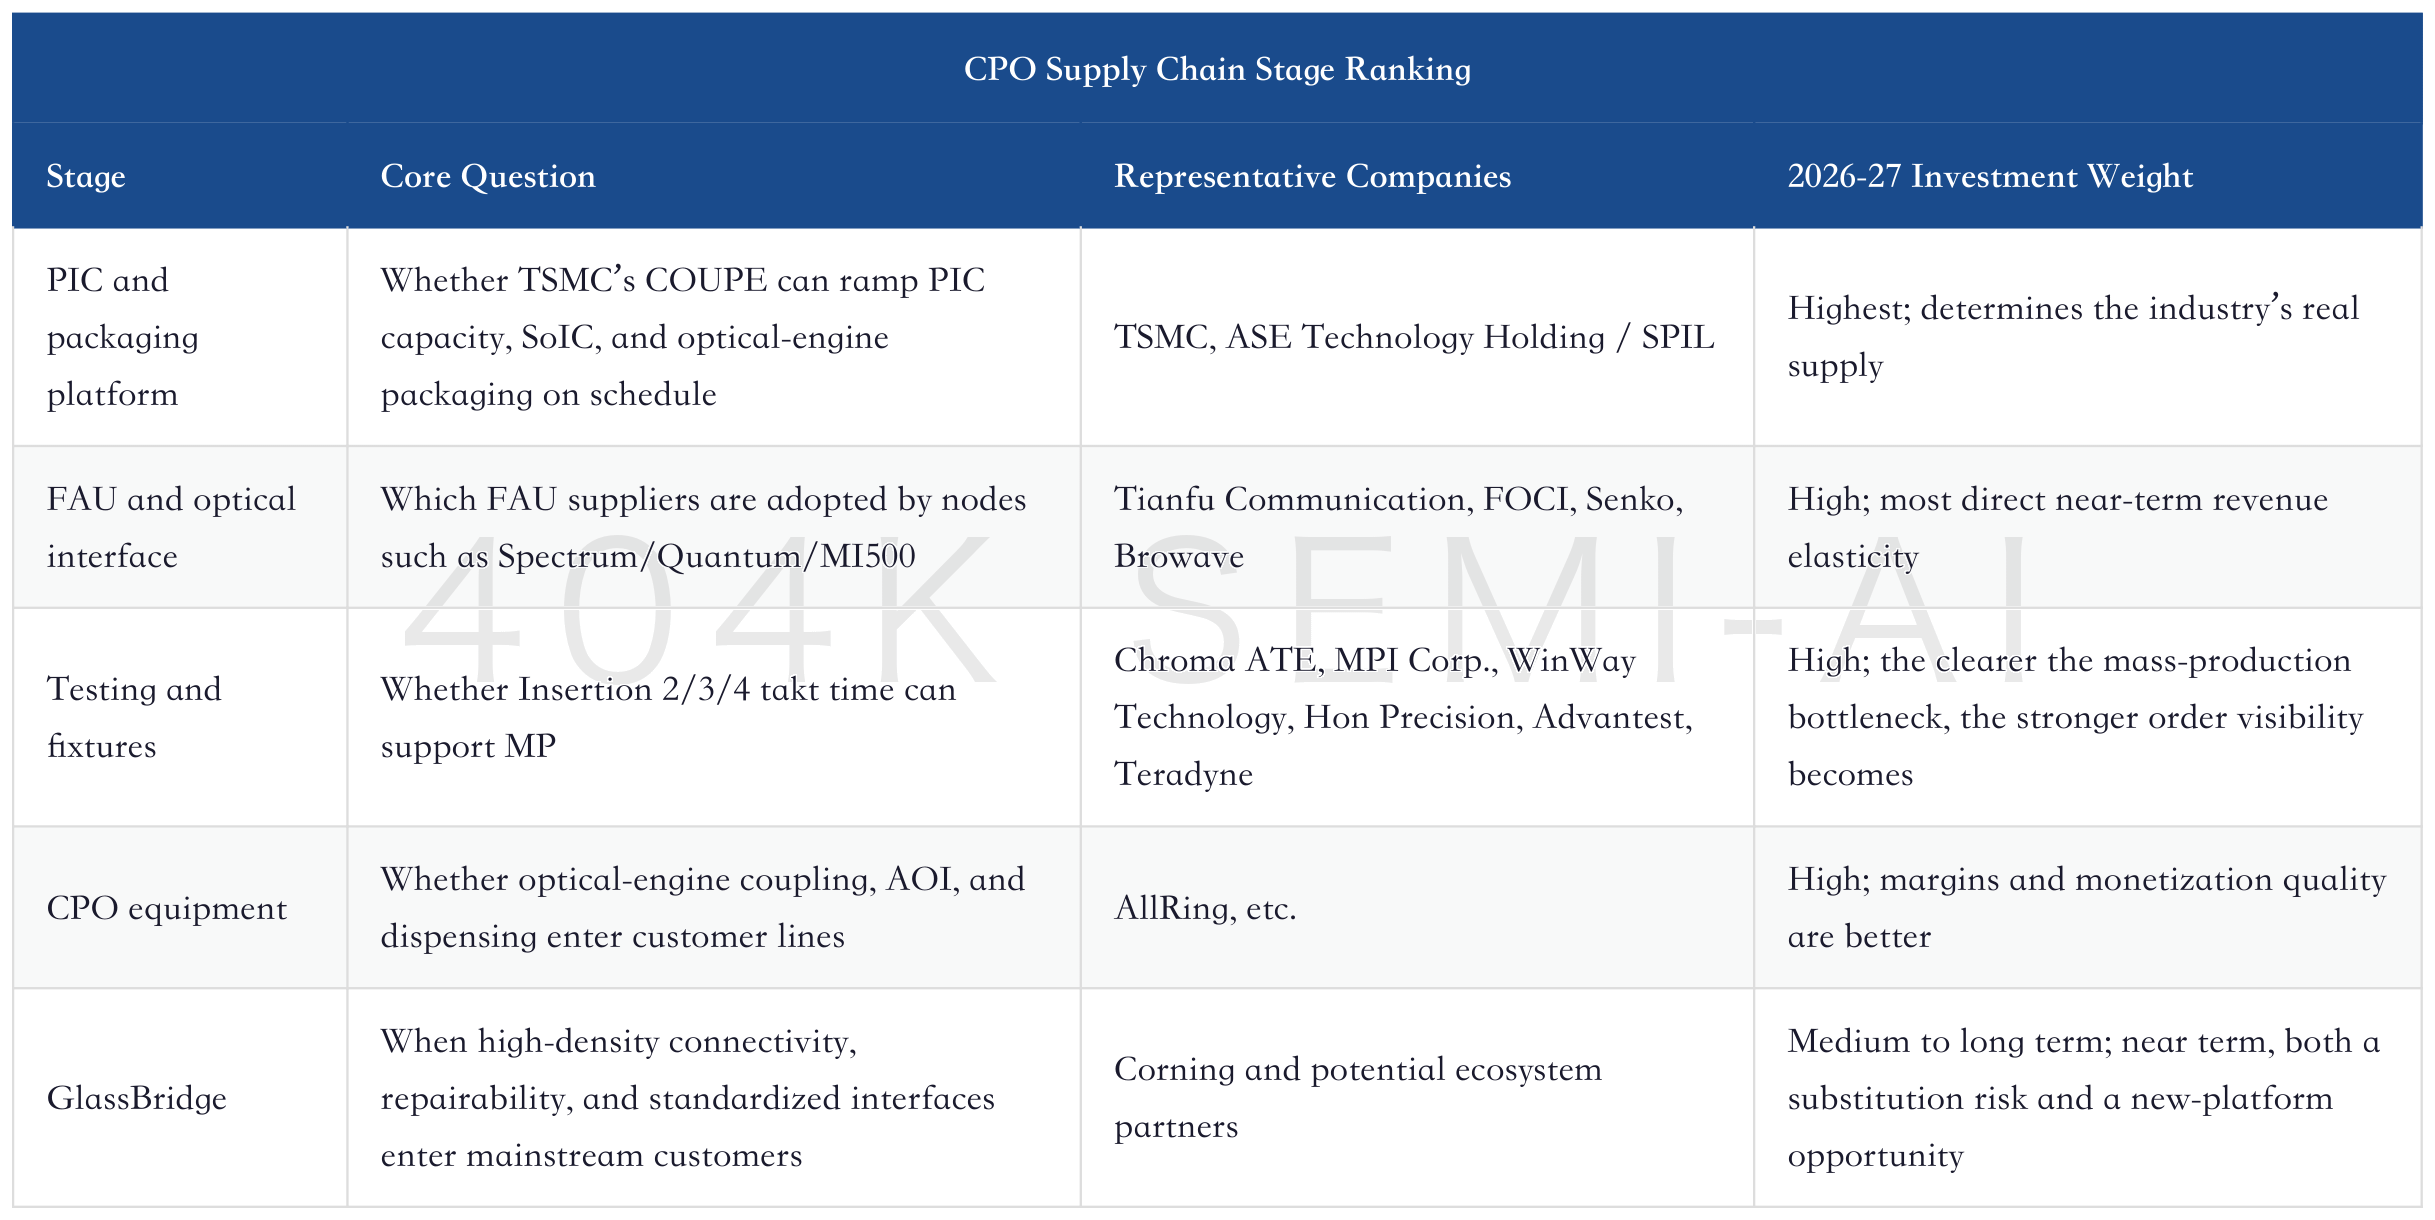
This ranking also explains why companies all labeled CPO trade on completely different logic. Tianfu Communication and FOCI are more like “FAU share and customer qualification” trades; AllRing is more like an “advanced packaging equipment and CPO back-end equipment” trade; MPI Corp., WinWay Technology, and Hon Precision are more like “test takt time and mass-production fixture” trades; GlassBridge-related companies are more like “next-generation interface standard” trades. Bundling these companies into one CPO concept basket makes it easy to misjudge both upside elasticity and risk.
VI. FOCI: 2026 as Transition, 2027 as the Start of the Revenue Slope
FOCI’s model is very typical: 2026 still carries transition pressure, while the revenue slope in 2027-28 is steep. Morgan Stanley lowered 2026 revenue and EPS, mainly because of the timing of mass-production revenue, product mix, and early cost pressure; however, its longer-term judgment for 2027-28 was not meaningfully cut. The target price remains NT$708, and the rating remains Overweight.
The report’s core assumption is that 2026 mainstream scale-out Spectrum-X CPO optical-engine production will be about 600k-1mn units, corresponding to roughly 20k CPO switches. Tianfu Communication, FOCI, and Senko are the main FAU suppliers, with FOCI at about 40% share. NVIDIA’s contribution to FOCI revenue is expected to rise from 18% in 2026 to 42% in 2027 and 80% in 2028. This curve means the core investment point for FOCI is not 2026 profit, but main-customer volume ramp in 2027 and customer diversification in 2028.
