
MLCC Deep Update: The Real Signal After May Trade Data Cooled, and How Taiwan IT Demand Can Take Over from the Auto Recovery
目录
Too Long; Didn't Read
1. May Cooling Is Seasonal: Structural Divergence Is the New Information
2. Automotive Chain Retreat: The Strong Rebound in European and US Automotive MLCCs Did Not Continue
3. Taiwan Takes Over: IT Applications Remain a Leading Indicator of AI Server Demand
4. From April Strength to May Divergence: How Monthly Data Revise the Previous Bullish MLCC Framework
5. Company Ranking: Murata Is the Anchor, Taiyo Yuden Is the Beta, and TDK, Samsung Electro-Mechanics, and Yageo Each Depend on One Variable
6. A-Share Mapping: Three-Circle Group, Sinocera, Jiemei Technology, and Fenghua Advanced Technology Need to Be Viewed in Layers
7. Tracking List: Can October-December Become the Next Price-Negotiation Window?
8. Risks and Falsification: Which Data Would Prove This Round Is Only a Short-Term Front-Run
9. Conclusion: May Makes the MLCC Logic Narrower and Clearer
本内容基于公开资料和研报数据整理,不构成任何投资建议,不代表任何个人观点,仅供学习参考,请理性阅读
Japan's May MLCC trade data narrows the bullish evidence. The aggregate pullback was seasonal, the retreat in the automotive chain needs attention, and IT plus AI server demand is still extending through Taiwan. Near-term share prices have already discounted part of the story. The next validation points are the October-December price negotiations and 2027 high-end supply-demand conditions.
Too Long; Didn't Read
The May cooling is seasonal. Japan's May MLCC export volume and value were 83.837bn units and $411mn, down 9.9% and 11.8% MoM, respectively, broadly in line with the typical May pullback over the past 10 years. The real focus is whether value, ASP, and the three-month moving average continue to move higher. ASP is still positive YoY, which means the price trend has not clearly broken.
The automotive chain is the biggest weak spot this month. JPM uses Europe and the US as the main observation regions for automotive MLCCs. May export volume and value fell 22.4% and 25.1% MoM, respectively, clearly weaker than seasonality. The rapid March-April recovery in automotive demand did not continue, with Europe and the US weakening at the same time. If no recovery is visible in June-July, the automotive chain will become a negative check on the MLCC cycle assessment.
Taiwan is where the IT chain is taking over. JPM combines China, Hong Kong, Taiwan, South Korea, Vietnam, the Philippines, and India into a region with a high IT weighting. In May, value in this region rose 13.0% YoY, clearly better than the automotive chain. Taiwan export volume and value increased 37.9% and 17.3% MoM, respectively. This is more consistent with the rhythm of the AI server supply chain and is the most important bullish evidence to retain from this month's data.
The pricing window will likely move later. JPM maintains Murata Manufacturing and Taiyo Yuden as its preferred MLCC names, with a stronger preference for Murata. It also explicitly notes that the April-June rally in MLCC stocks has already reflected part of the demand expansion from AI server applications over the next three to four years. A more reasonable near-term view is that share prices enter range-bound consolidation, the probability of July-September price hikes is low, and the next more important inflection window is October-December. From an investment perspective, Taiwan's strong May data should not be equated directly with immediate price hikes. It should be treated as evidence that demand for high-end specifications is still transmitting into the supply chain.
Company ranking needs to shift from capacity to effective capacity. Murata remains the global pricing anchor for high-end MLCCs, with advantages in advanced processes, quality capability, and product roadmap. Taiyo Yuden has greater earnings beta, but near-term valuation is also more dependent on price-hike expectations being realized. TDK's appeal lies in its high-end component portfolio and customer structure. Samsung Electro-Mechanics is more closely tied to the Korean AI/server chain, while Yageo is more affected by low-to-mid-capacitance products and channel inventory. A-share mapping cannot be ranked simply by "who makes MLCCs." Three-Circle Group should be viewed through high-end MLCCs and the electronic ceramics platform; Sinocera through ceramic powders and electronic pastes; Jiemei Technology through release films/carrier tapes and other material links; and Fenghua Advanced Technology through the cycle beta of domestic MLCCs.
May raised the validation threshold. The data revise the framework from "synchronous recovery across all applications" to "AI/IT lifts the high end, autos drag, pricing waits for negotiations." If IT-region value remains above seasonality in June-August, Taiwan continues to show YoY and value resilience, and automotive stops deteriorating, then the October-December price-hike logic and the 2027 supply-demand tightening logic still hold. If Taiwan value weakens, ASP turns negative YoY, and autos continue to deteriorate, high-end product tightness will be pushed out and the high valuations of related stocks will need to be digested first.
1. May Cooling Is Seasonal: Structural Divergence Is the New Information
The first message from May MLCC trade data is simple: aggregate volume fell sequentially, in line with seasonality.
Japan's May MLCC export volume and value both retreated from a strong April, with the MoM decline close to the May seasonal pattern over the past 10 years. ASP softened only modestly and still maintained positive YoY growth. Together with the impact of Japan's Golden Week, the May pullback should not be read directly as a demand inflection point.
JPM's aggregate view can be condensed into one sentence: May retreated from a strong April, but the trendline was not broken. The original report used a short phrase, "seasonal trends." This reminds us that a single-month MoM decline is not enough to negate a moderate upward line that has already lasted for several months.
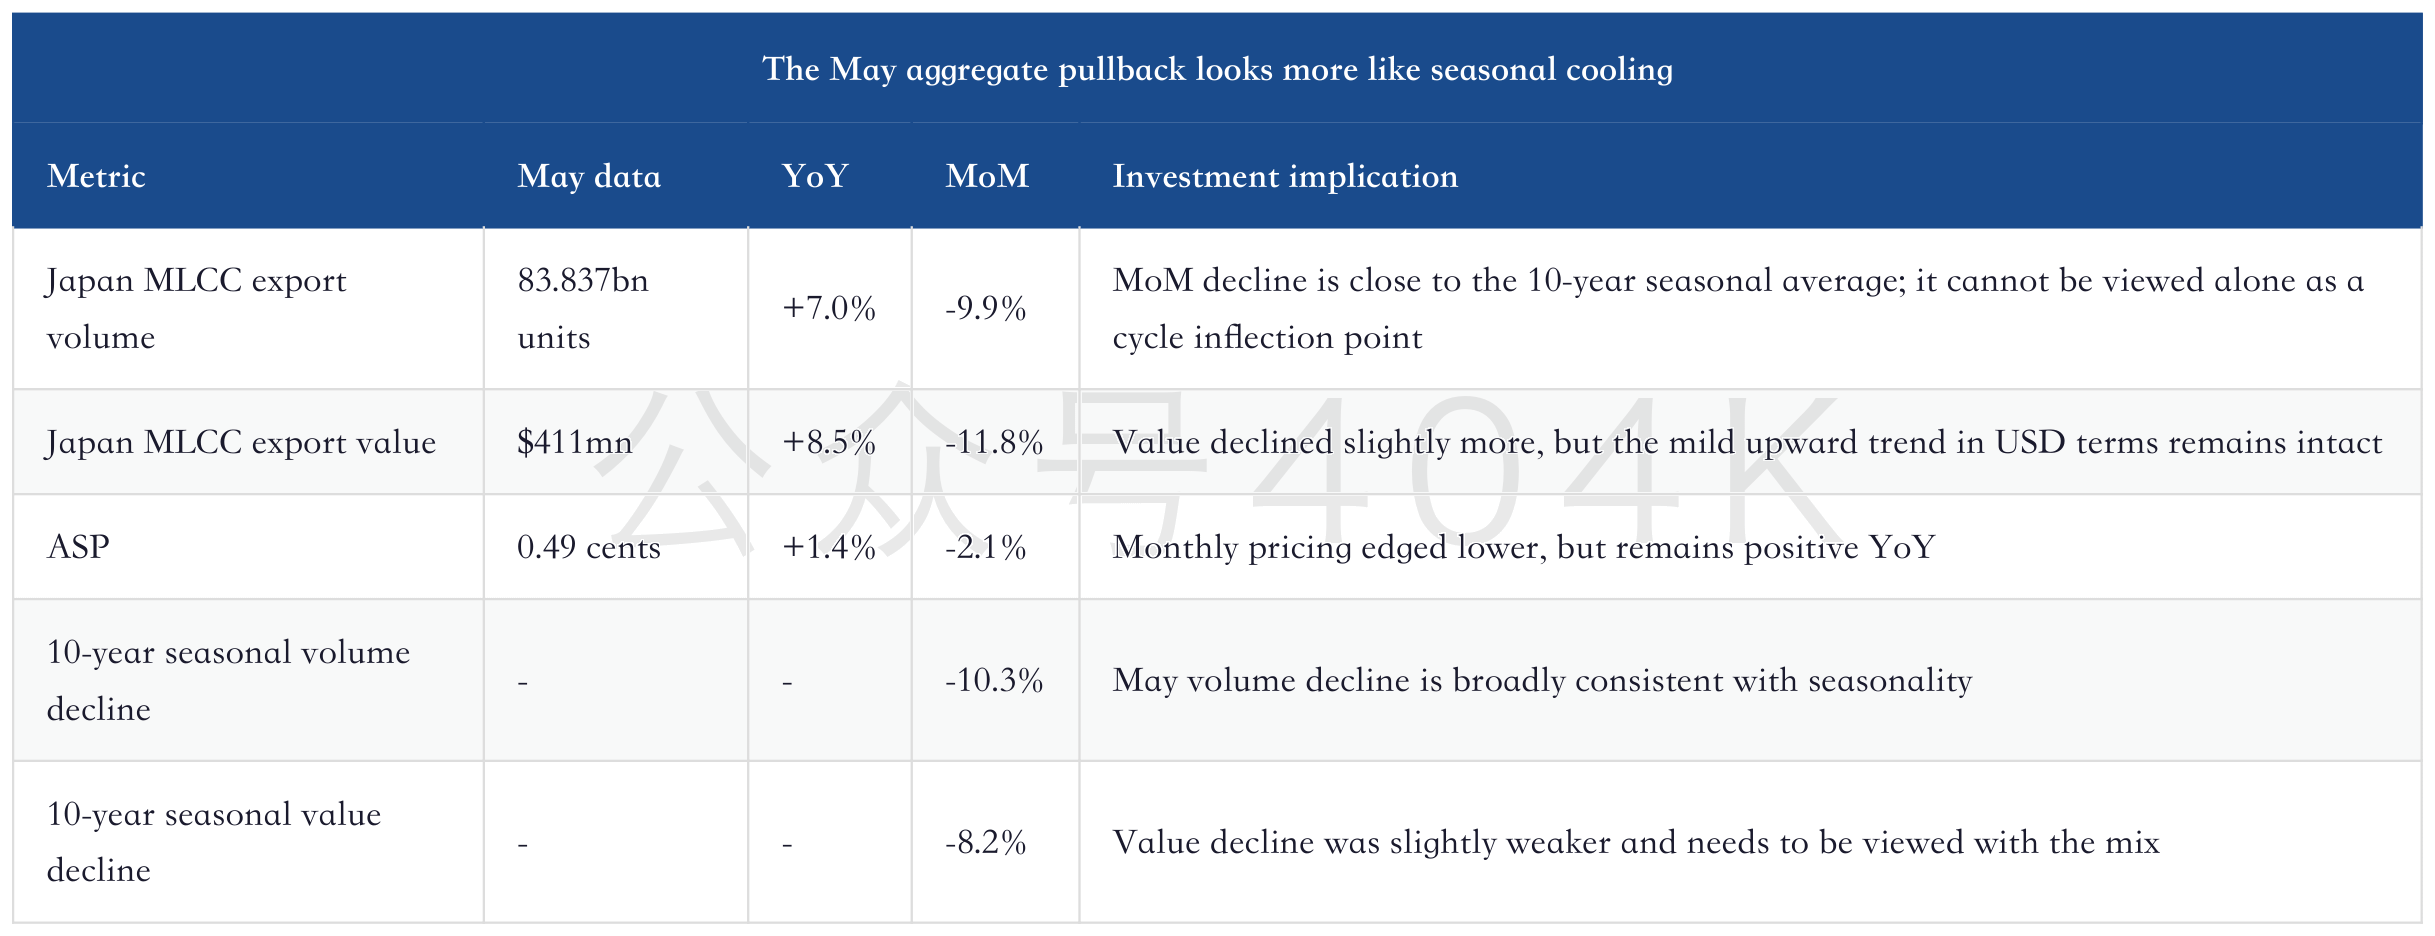
This set of data revises the rhythm of the previous two MLCC deep-dive reports, not the overall direction. Our earlier core discussion was that AI servers are pushing MLCCs from ordinary cyclical products toward an effective-capacity bottleneck. The key variable is whether high-end specification demand can continue absorbing available capacity. A single-month MoM move in aggregate exports does not determine the long-term logic.
MLCC Deep Dive: JPMorgan Sharply Raises Forecasts, from Cyclical Repair to Structural Re-Rating, as AI Servers Rewrite the Supply-Demand Gap
May data still support this framework, but not indiscriminate optimism. The automotive chain fell very clearly, the IT region was steadier, and Taiwan was stronger than other regions. In other words, the MLCC business has not become a case of all applications raising prices together. Rather, high-end AI/IT chains continue to lift marginal demand, while traditional autos and some regions expose weaknesses first.
2. Automotive Chain Retreat: The Strong Rebound in European and US Automotive MLCCs Did Not Continue
The automotive chain is the most uncomfortable part of the May data.
JPM uses exports to Europe and the US as an approximate gauge of automotive MLCCs. In May, volume, value, and ASP in this segment all weakened, and the MoM declines in volume and value were both clearly worse than the past 10-year seasonality. The auto-chain signal is worse than the aggregate signal and needs to be considered separately.
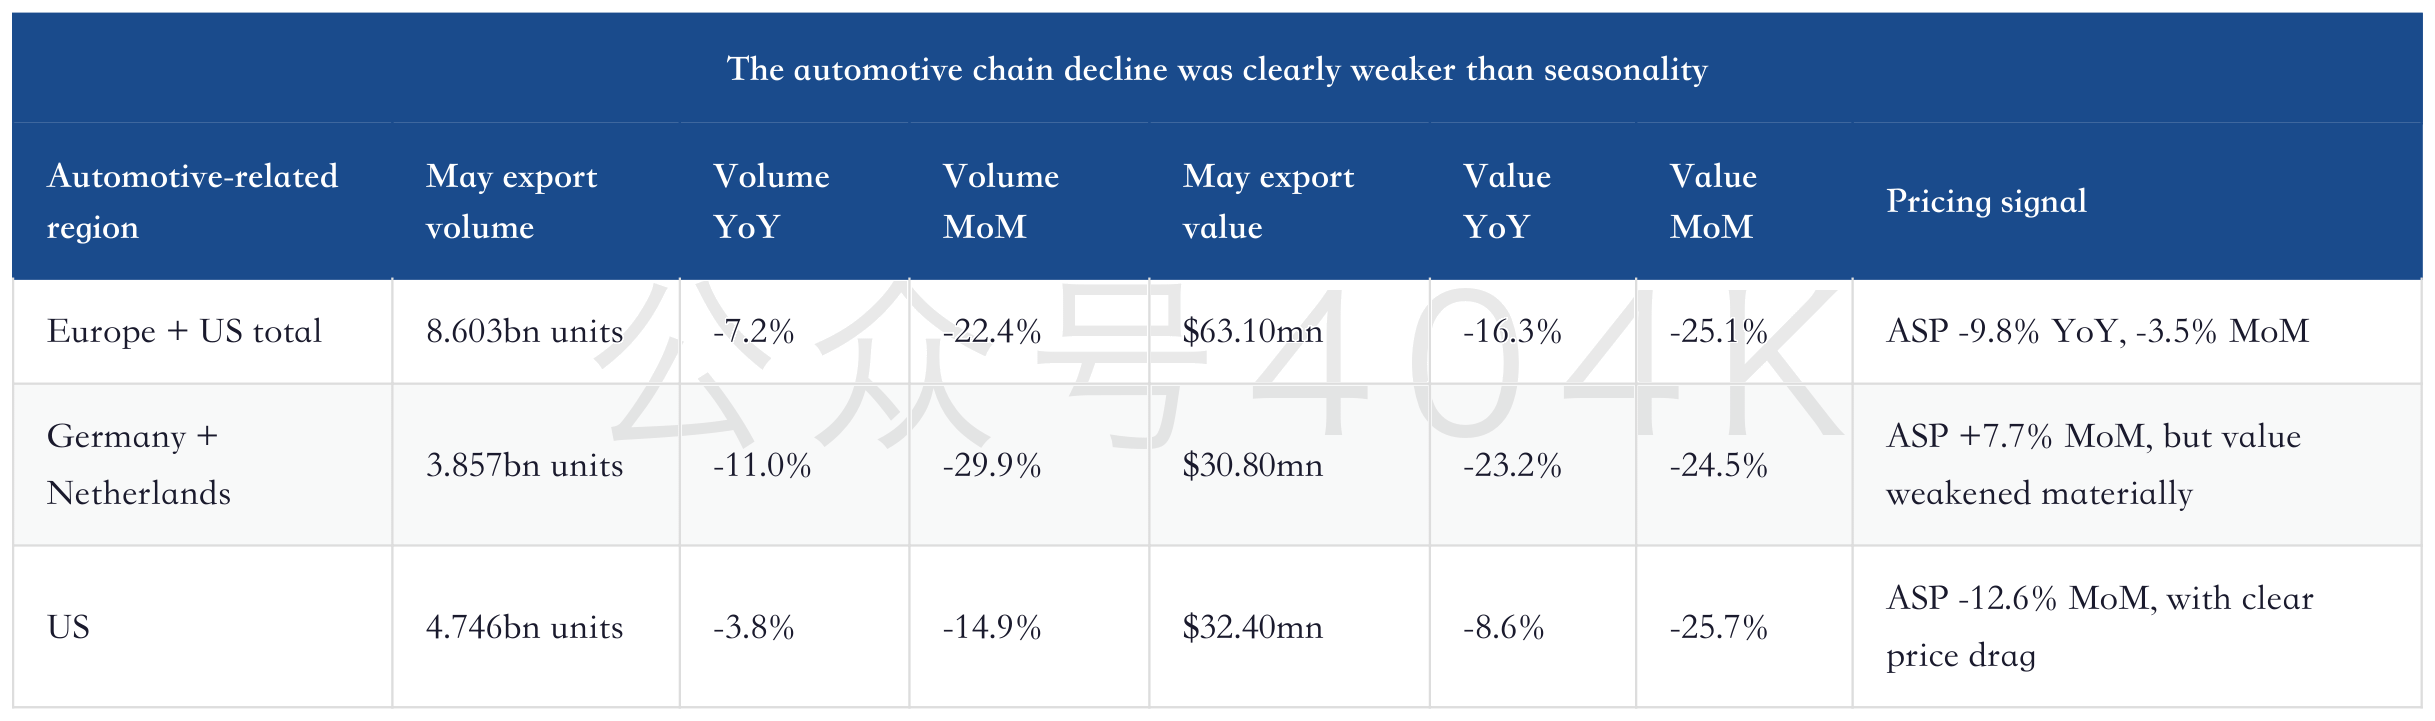
This is a data set that must be taken seriously. Automotive exports in April had given the impression that demand recovery was spreading. May shows the recovery did not continue on inertia. European volume fell 30% MoM and value fell 25%; US volume fell 15% MoM and value fell 26%. Neither direction was strong.
The core issue for automotive MLCCs extends from quantity to value and ASP. Automotive applications usually have higher unit prices, higher reliability requirements, and longer customer qualification cycles. If this region continues to weaken, the high-value part of industry revenue will be restrained, and price-hike expectations will also be discounted.
From an investment perspective, the automotive chain should be treated as a negative check, while the main line remains AI/IT high-end products. AI servers can drive high-end multilayer, high-capacitance, high-reliability products, but if automotive remains weak, it will limit the speed at which industry pricing spreads. Put differently, high-end products can be tight, while broad industry price hikes may still not arrive immediately.
3. Taiwan Takes Over: IT Applications Remain a Leading Indicator of AI Server Demand
The strongest new evidence in May came from Taiwan.
JPM combines China, Hong Kong, Taiwan, South Korea, Vietnam, the Philippines, and India into a region with a high weighting in IT applications. In May, this region's volume and value fell sequentially, but still grew YoY, and ASP was also positive YoY. Compared with aggregate data and autos, the IT region's pricing and value were steadier.
Taiwan's data were particularly striking. In May, Japan's MLCC export volume and value to Taiwan both increased against seasonality, while value also continued to maintain double-digit YoY growth. Volume and value strengthened together. That is the most important structural signal this month.
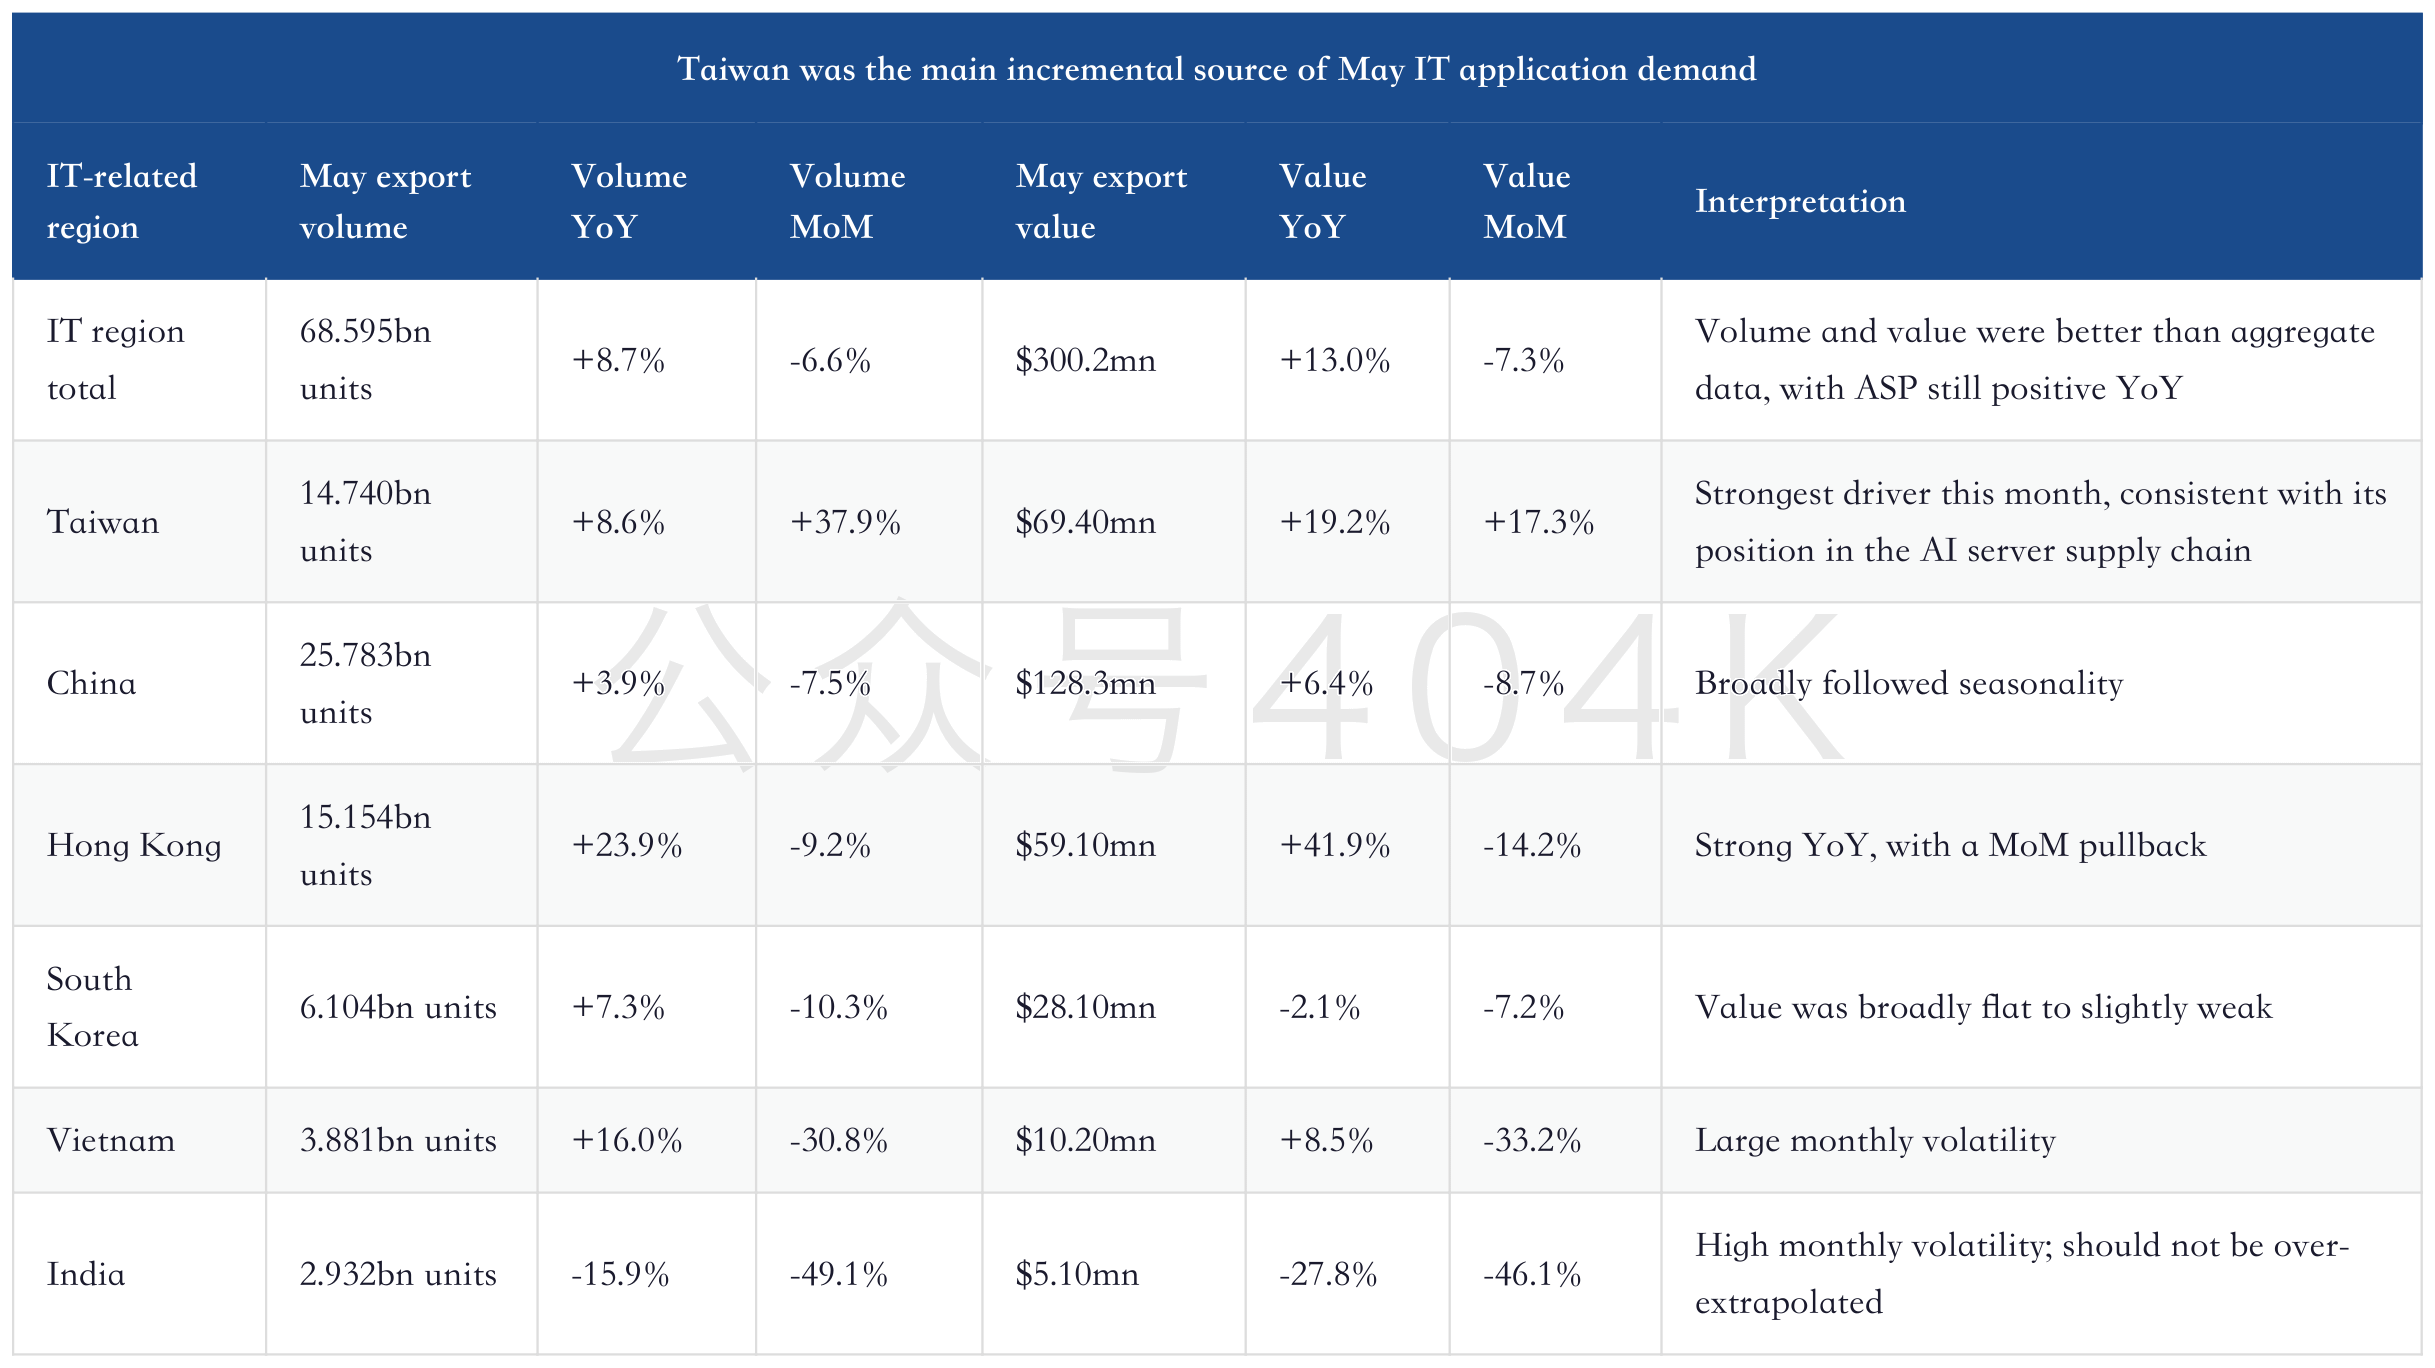
Why does Taiwan matter? Because assembly, boards, server ODMs, and high-end component pull-in for the AI server supply chain are more likely to be reflected earlier in this direction. A single MLCC has little value, but server motherboards, accelerator cards, power modules, and high-speed computing platforms will significantly increase the use of high-reliability, high-capacitance, and miniaturized MLCCs. For MLCC manufacturers, strengthening value in Taiwan matters more than small fluctuations in aggregate volume.
Japan Electronic Components Deep Dive: AI Servers Push MLCCs from Cyclicals Toward Compute Infrastructure
One misread should be avoided here: strength in Taiwan does not mean all AI server MLCCs are already tight enough to trigger immediate price hikes. Taiwan ASP fell 15.0% MoM in May, which shows that product mix, customer pull-in rhythm, and FX can all affect monthly pricing. A more prudent reading is that AI/IT demand is still taking over, but pricing power needs further validation from the negotiation window and supply-chain inventory.
4. From April Strength to May Divergence: How Monthly Data Revise the Previous Bullish MLCC Framework
May data revise the bullish MLCC framework from "broad demand repair" to "high-end structural demand continues, while traditional applications contribute unevenly."
The easiest point for the market to get excited about was that AI servers pulled high-end MLCC demand for the next several years into current orders. In JPM's long-term model in mid-June, it had already materially raised 2025-2028 industry revenue CAGR, supply-demand gap, and ASP upside, and it expects adjusted effective capacity to tighten again in 2027-2028. May trade data are only a monthly thermometer. The thermometer shows that the heat source is still there, but the heat has not spread evenly.
MLCC Deep Update: AI Servers Push Cyclicals Toward a Power-Supply Bottleneck; Who Can Turn Price Hikes into Profits
The supply bottleneck in MLCCs is mainly effective capacity. High-end MLCCs require more layers, thinner dielectric, more stable sintering, and stricter reliability control. After the same line shifts toward high-end specifications, yield, takt time, and usable output all change. Higher AI server demand looks like using a few more capacitors, but in reality it occupies the high-end effective capacity that is hardest to replicate.
This is also why the May aggregate volume decline cannot directly overturn the long-term logic. If low-end consumer electronics, ordinary industrial demand, or the automotive chain is weak, but high-end AI/IT specifications continue to absorb production lines, the industry may still enter a tight balance for high-end products in 2027. Conversely, if Taiwan and other IT regions also begin to weaken, the supply-demand tightening timetable must move later.
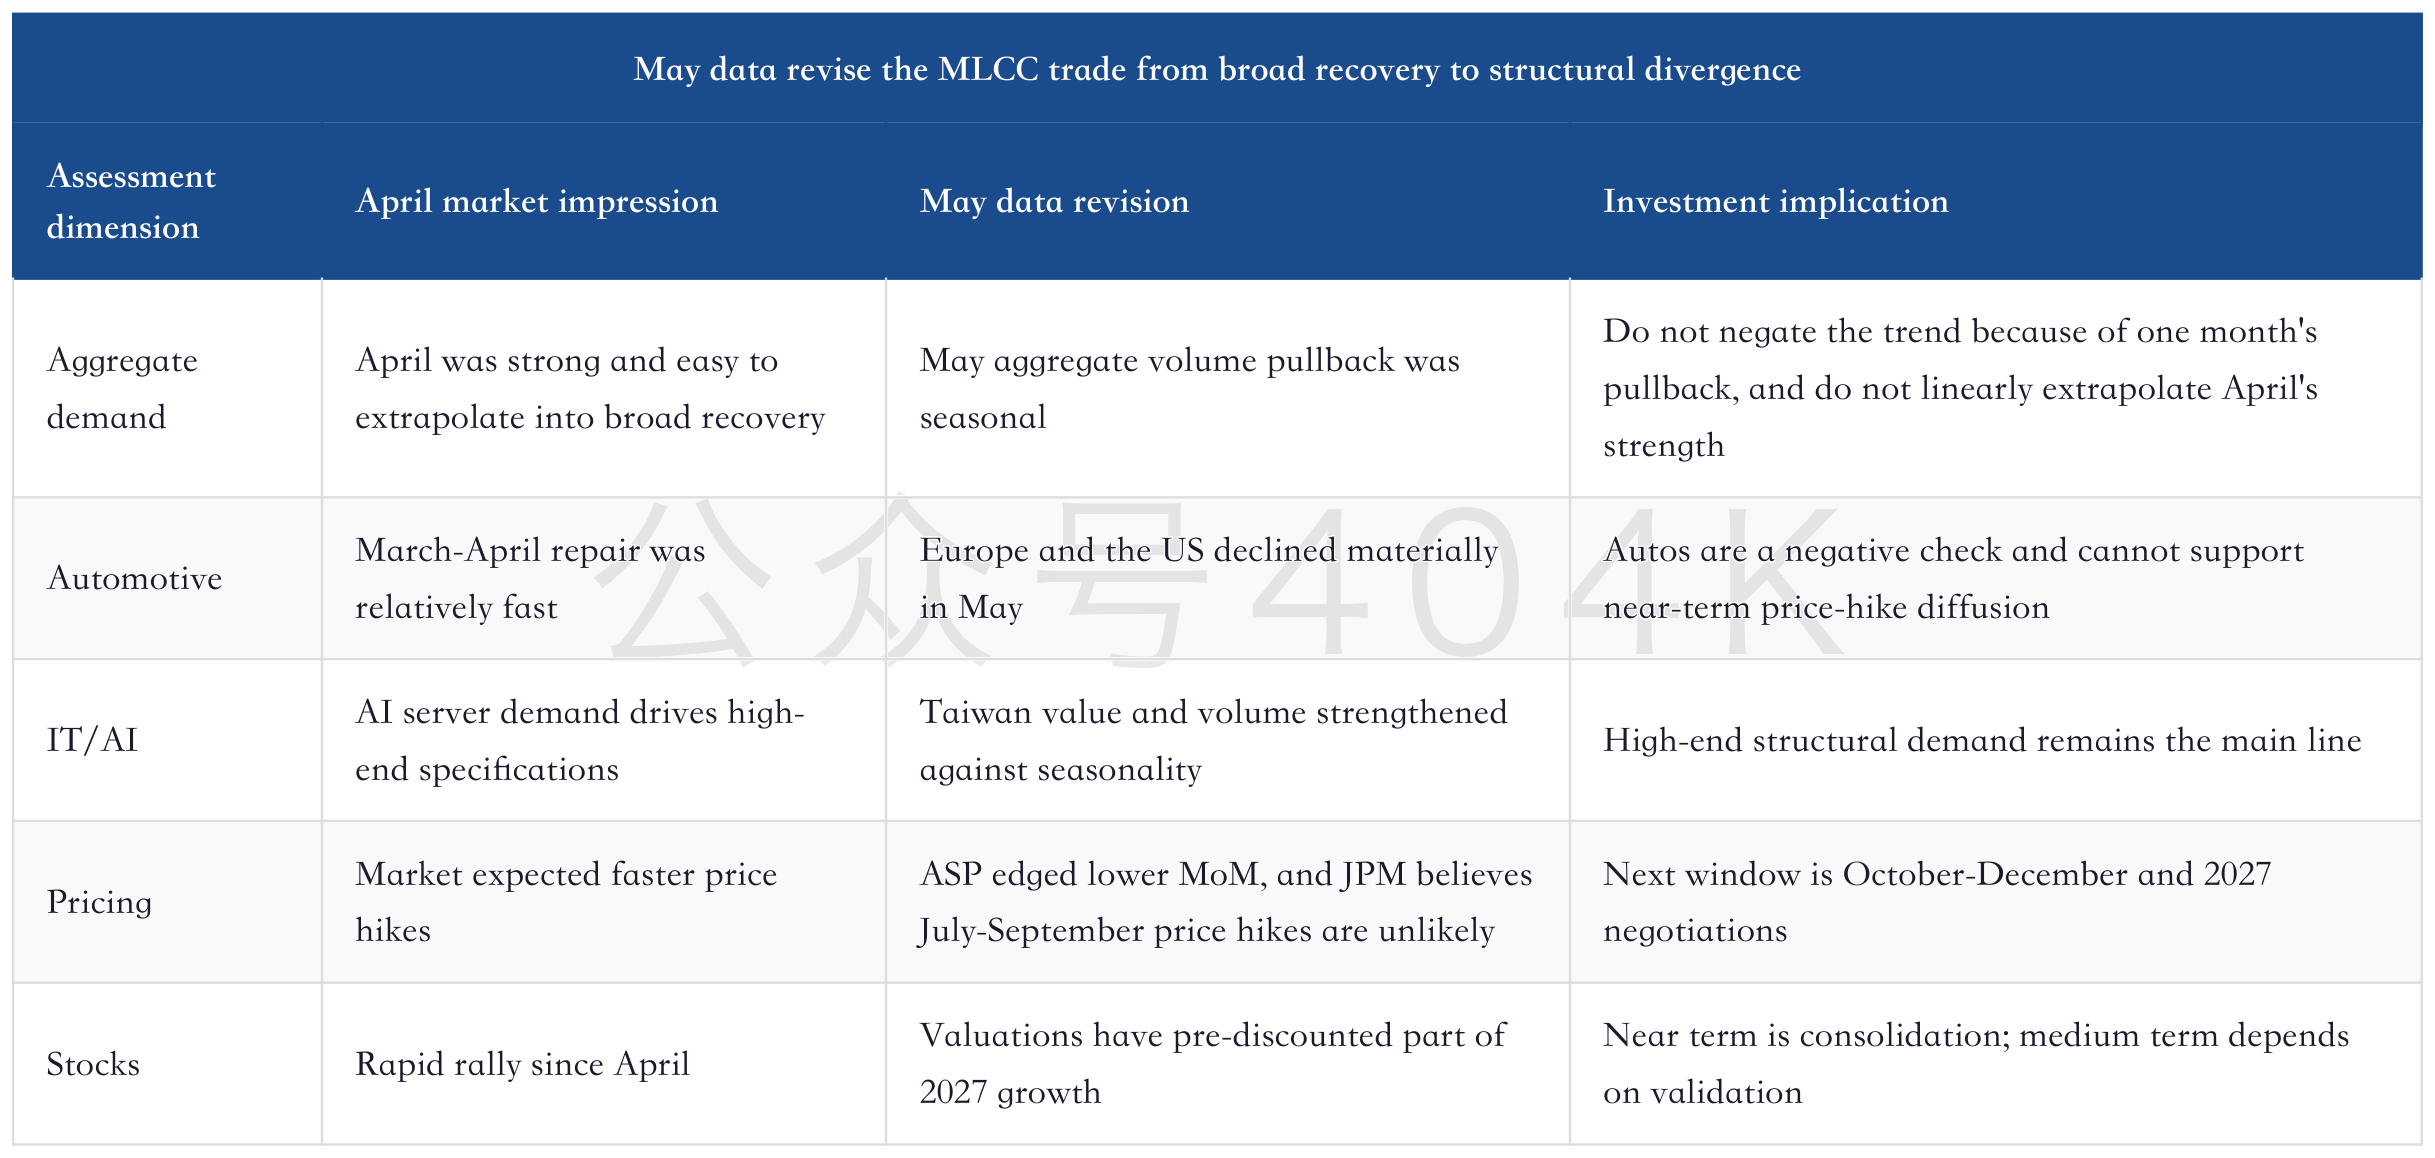
The conclusion from this table is direct: the near-term win rate for MLCC stocks depends on whether the expectation gap can still widen; the medium-term win rate depends on whether effective capacity truly tightens. May data are mildly positive for the medium-term logic and more restrained for near-term trading rhythm.
5. Company Ranking: Murata Is the Anchor, Taiyo Yuden Is the Beta, and TDK, Samsung Electro-Mechanics, and Yageo Each Depend on One Variable
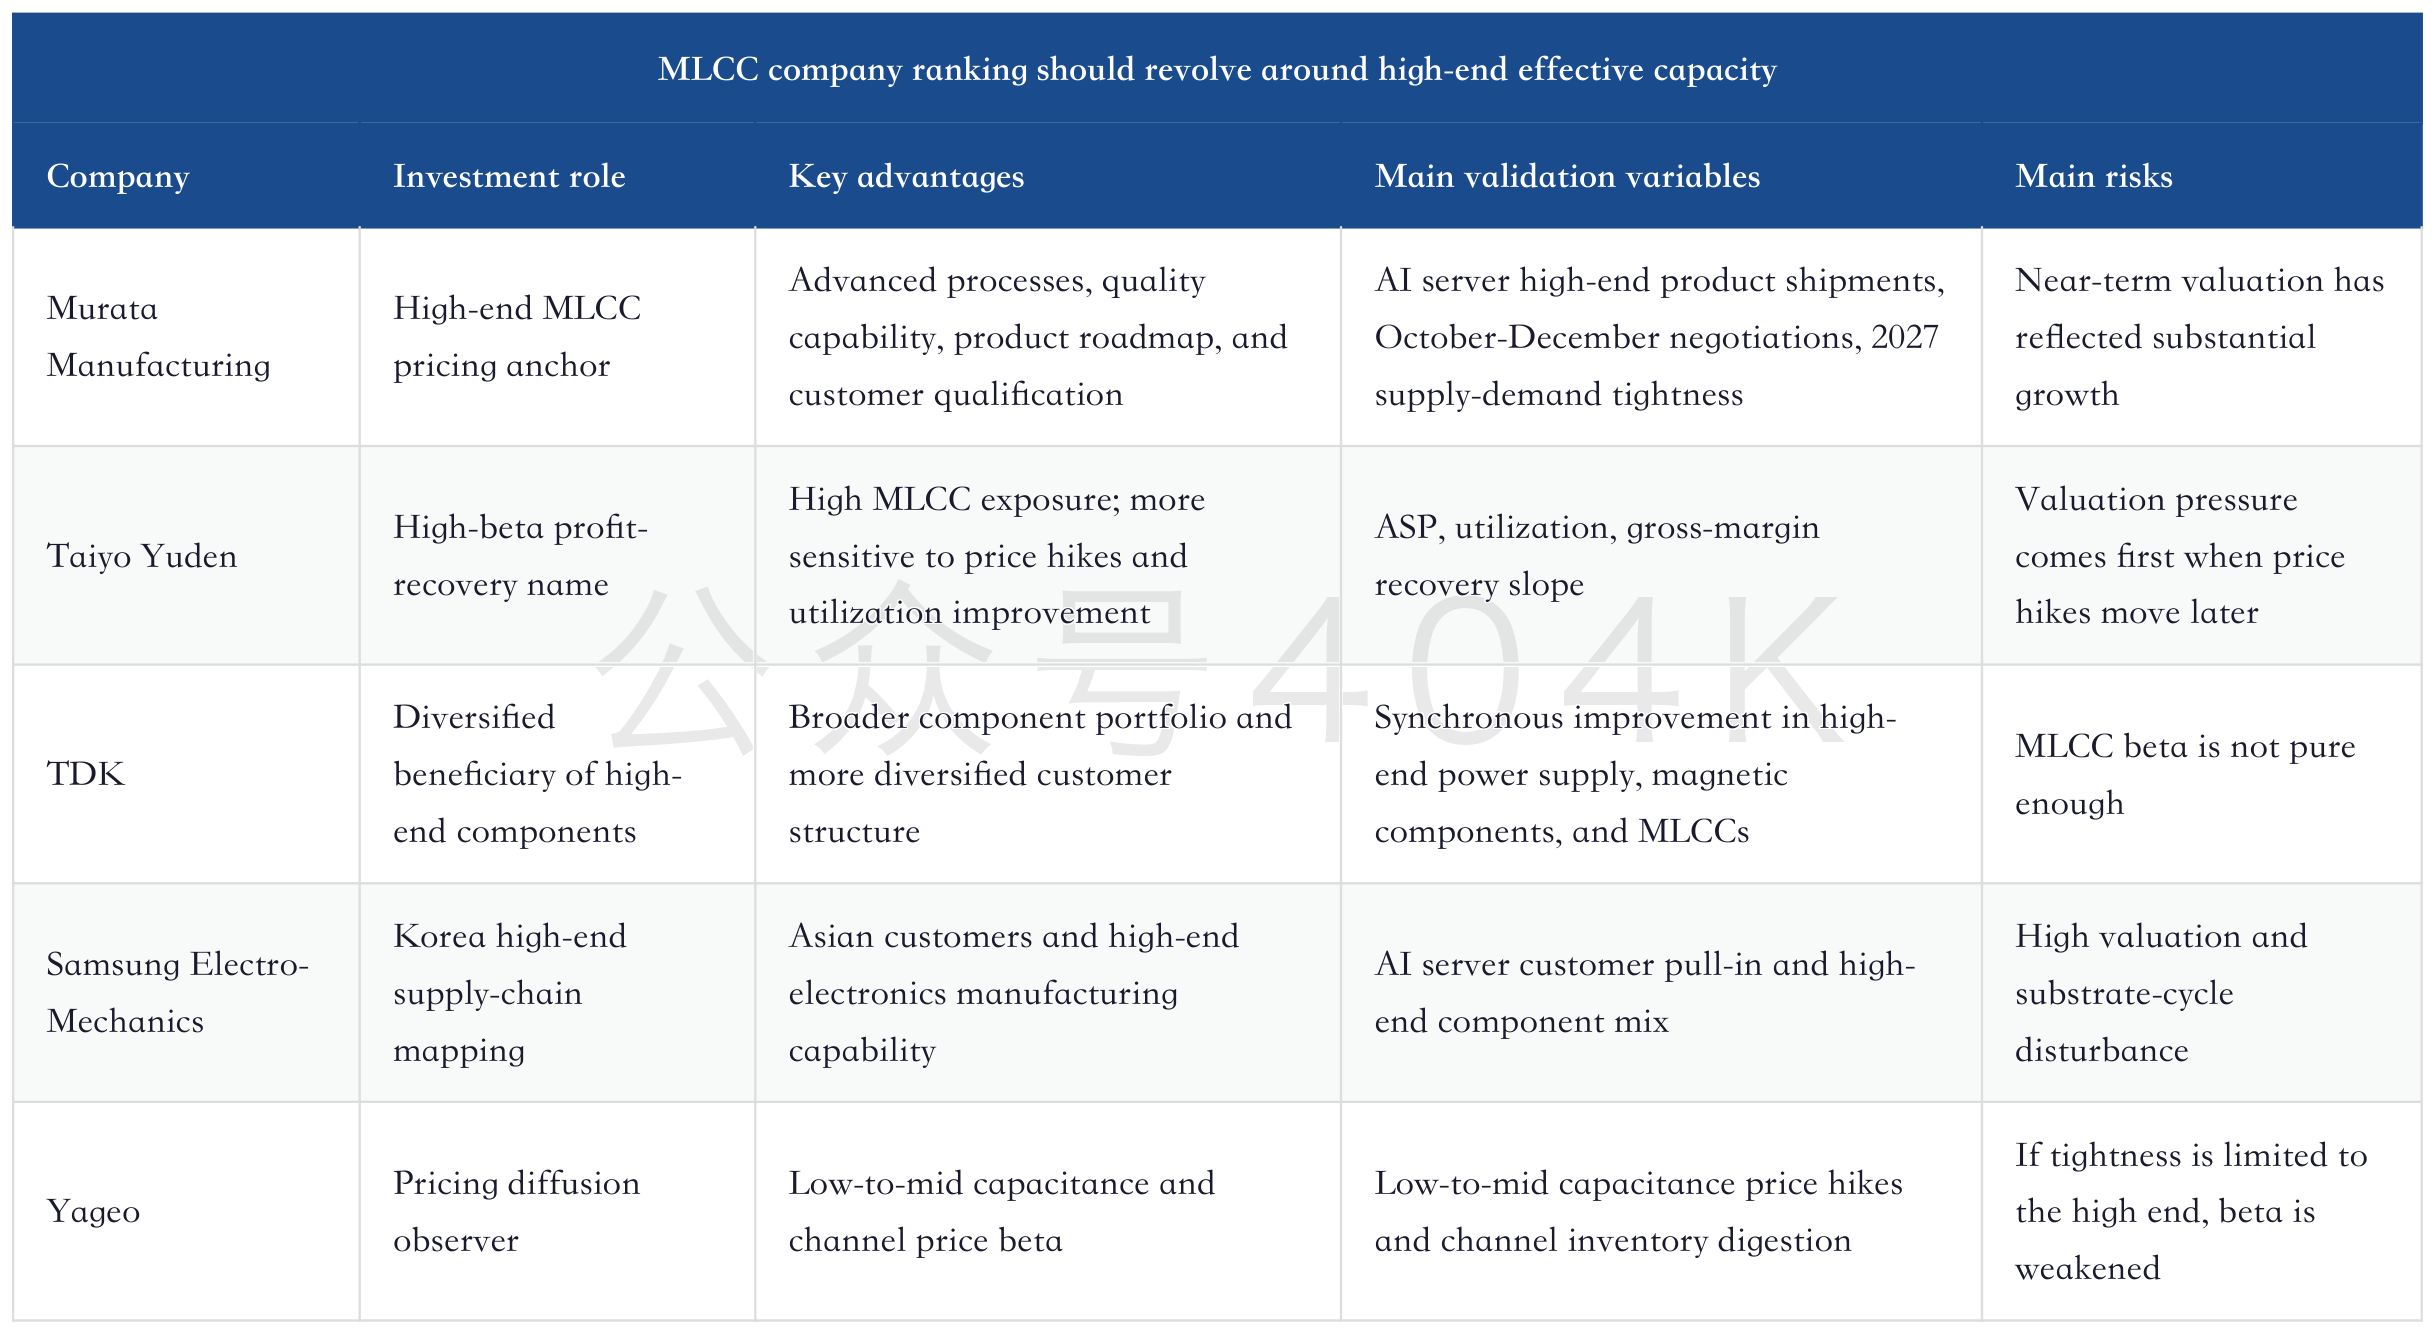
Company ranking needs to be upgraded from "who is an MLCC company" to "who can turn high-end effective capacity into profit."
JPM maintains Murata Manufacturing and Taiyo Yuden as its preferred MLCC names, with a stronger preference for Murata. This preference is reasonable. Murata's advantages lie in the combination of advanced production technology, quality capability, product roadmap, and customer qualification. The value of AI server MLCCs is not in the quantity of ordinary products, but in capacitance, reliability, size, temperature, and supply stability. The higher end the product moves, the less willing customers are to hand risk to new entrants.
Taiyo Yuden has greater beta. Its operating leverage in MLCCs is higher, so demand improvement and price increases will feed through to the income statement faster. But beta also means valuation is more dependent on price hikes being realized. If there are no price hikes in July-September and no clear progress in October-December negotiations, high-beta names such as Taiyo Yuden are more likely to digest expectations first.
TDK's issue is different. TDK is a diversified component company, with magnetic components, batteries, and other electronic components also in its portfolio. As a result, its MLCC beta is not as direct as Taiyo Yuden's. The benefit is that its customer and product structures are more diversified. If the AI server and high-end power-supply chains continue to upgrade, TDK can benefit from multiple component lines.
Samsung Electro-Mechanics is more closely tied to the Korean server and high-end electronics supply chain. Its advantages are Asian customers and high-end electronic component manufacturing capability. The risks are that valuation is already high and profit recovery requires coordination among high-end MLCCs, substrates, and customer pull-in cadence. Yageo is more of an observer of pricing diffusion. Low-to-mid-capacitance products and channel inventory have a larger impact on it. If price hikes spread from the high end to low-to-mid products, Yageo's beta will become more visible; if price hikes remain limited to tight high-end specifications, Murata and Taiyo Yuden have the advantage.
Murata Manufacturing Deep Dive: AI Server MLCCs, from Small Components to a Profit Gate
At this stage, the steadier ranking is: Murata for certainty, Taiyo Yuden for beta, TDK for a diversified high-end component portfolio, Samsung Electro-Mechanics for Korean AI/server-chain mapping, and Yageo for whether price hikes can spill over into low-to-mid capacitance products. May data did not change this ranking. It only makes the near-term trade require more patience.
6. A-Share Mapping: Three-Circle Group, Sinocera, Jiemei Technology, and Fenghua Advanced Technology Need to Be Viewed in Layers
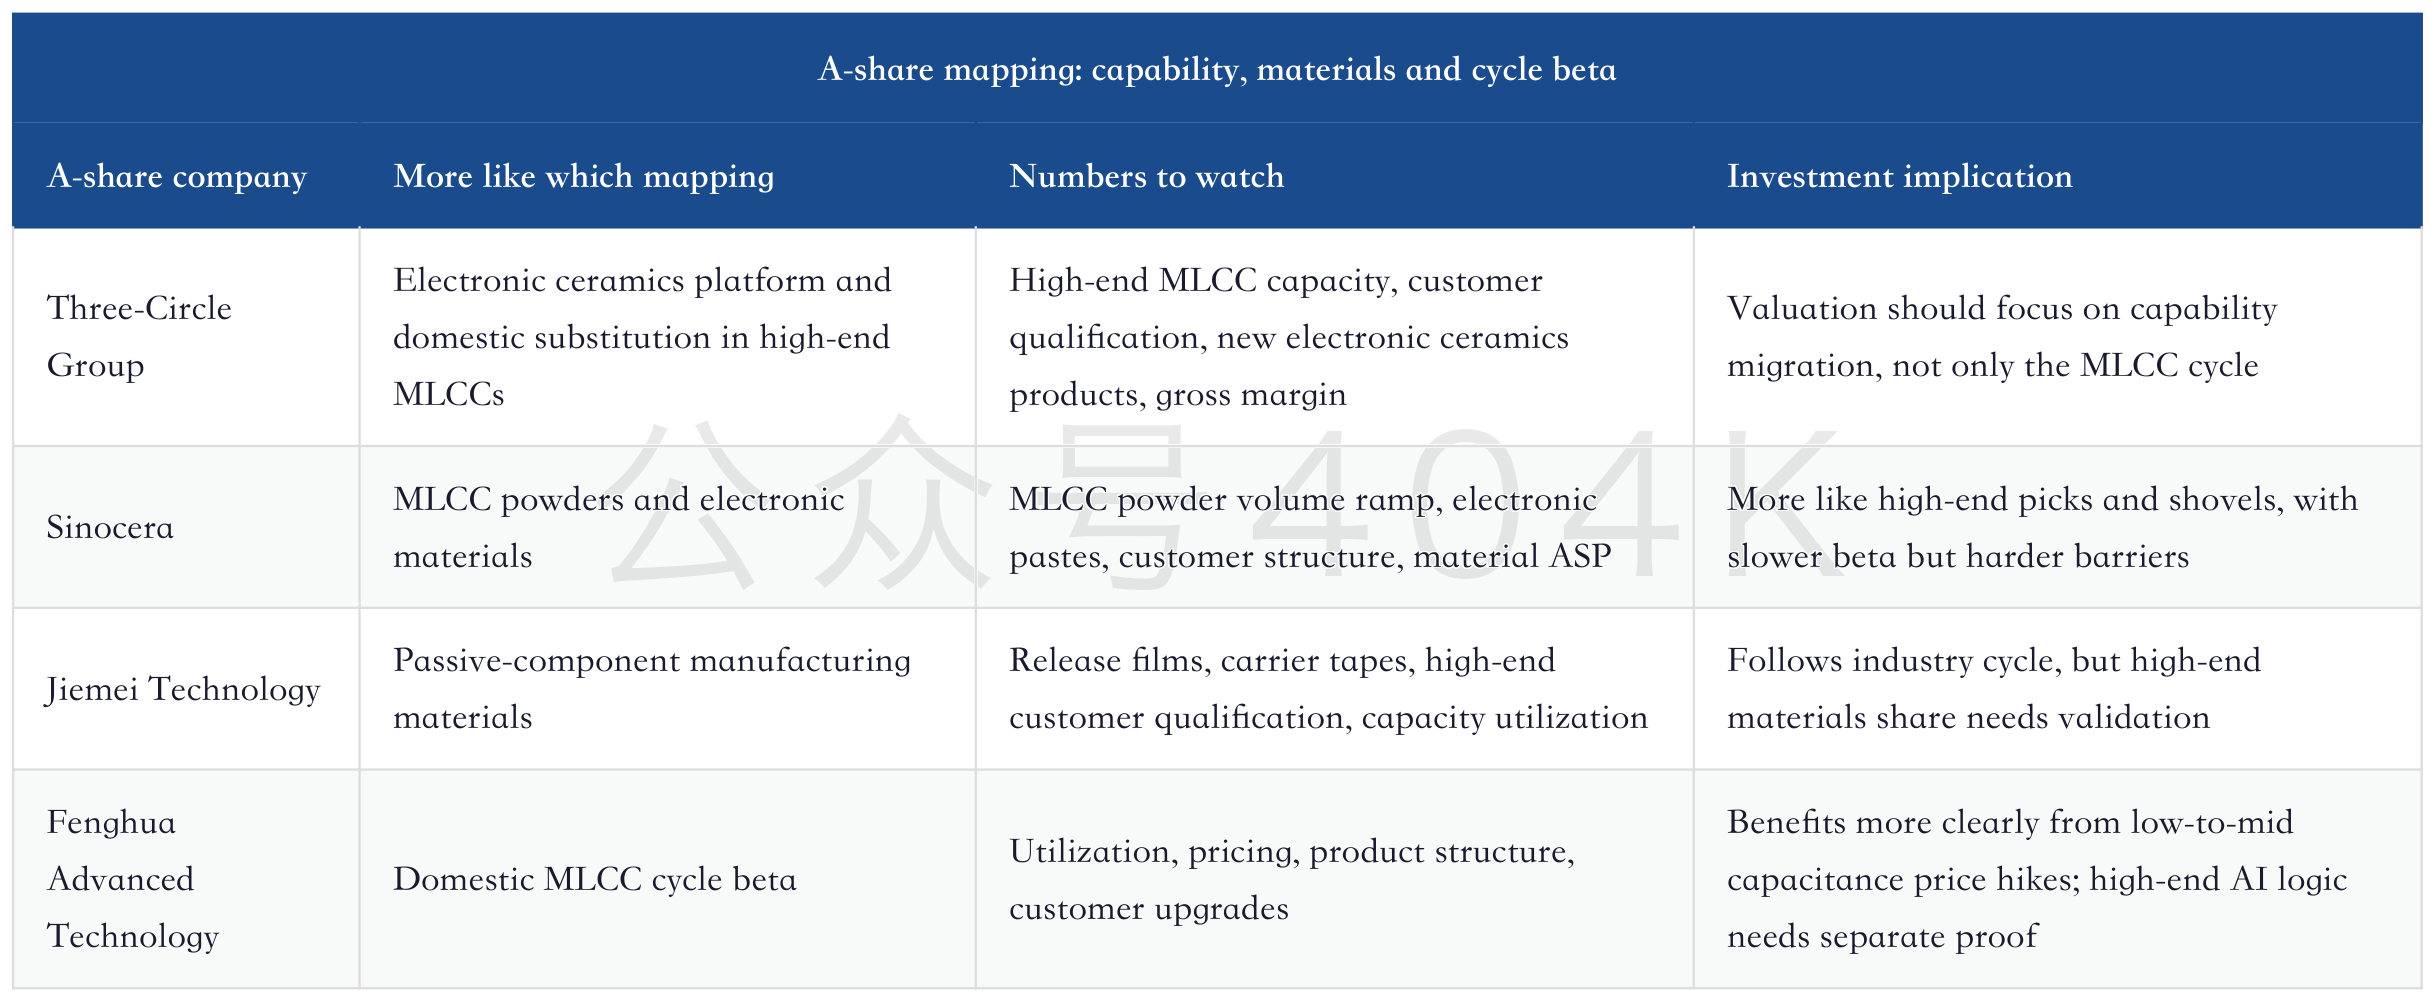
A-share MLCC mapping cannot be written as one basket.
The main line for Three-Circle Group is its electronic ceramics platform and domestic substitution in high-end MLCCs. Its truly valuable part is whether its materials, processes, customer qualification, and electronic ceramics platform capabilities can migrate into higher-end passive components. The lesson from AI servers is that the value of high-end ceramic components is no longer judged only by unit price, but by reliability, qualification barriers, and the premium customers are willing to pay for stable supply.
Sinocera is more upstream materials-oriented. MLCC ceramic powders, electronic pastes, dielectric materials, and process stability determine the underlying performance of high-end MLCCs. If high-end MLCC demand continues to upgrade, powders and pastes will move from cyclical materials to a prerequisite for moving upmarket. Its beta may be less direct than that of MLCC device manufacturers, but its business quality is closer to a picks-and-shovels model.
The observation point for Jiemei Technology is material links such as release films and carrier tapes. MLCC shipments and high-end specification upgrades will affect material usage, quality requirements, and customer qualification. It is a material name indirectly mapped to AI server MLCCs and has tracking value within the passive-component cycle and high-end manufacturing materials chain.
Fenghua Advanced Technology is more about the cycle beta of domestic MLCCs. If low-to-mid capacitance pricing and utilization improve, Fenghua Advanced Technology will benefit more directly. But if this round of tightness is mainly concentrated in high-end AI server specifications, Fenghua Advanced Technology needs to prove that its product structure, customers, and high-end qualifications can keep up, rather than relying only on an industry price-hike narrative.
Three-Circle Group Deep Dive: From Electronic Ceramics Platform to High-End MLCCs, How AI Servers Re-Rate Domestic Ceramic Component Capabilities
Sinocera Deep Update: From MLCC Powders to Electronic Pastes, AI Servers Rewrite the Value of MLCC Powders and Re-Rate High-End Ceramic Materials
The correct use of A shares is layered tracking, avoiding buying everything when one name rises. If Taiwan remains strong in June-August and October-December price negotiations show tightness in high-end products, names tied to high-end upgrades such as Three-Circle Group and Sinocera will have stronger explanatory power. If price hikes spread to low-to-mid capacitance products, Fenghua Advanced Technology and channel beta will become more visible. If only Japanese high-end leaders capture the benefits, the A-share mapping needs to be discounted.
7. Tracking List: Can October-December Become the Next Price-Negotiation Window?
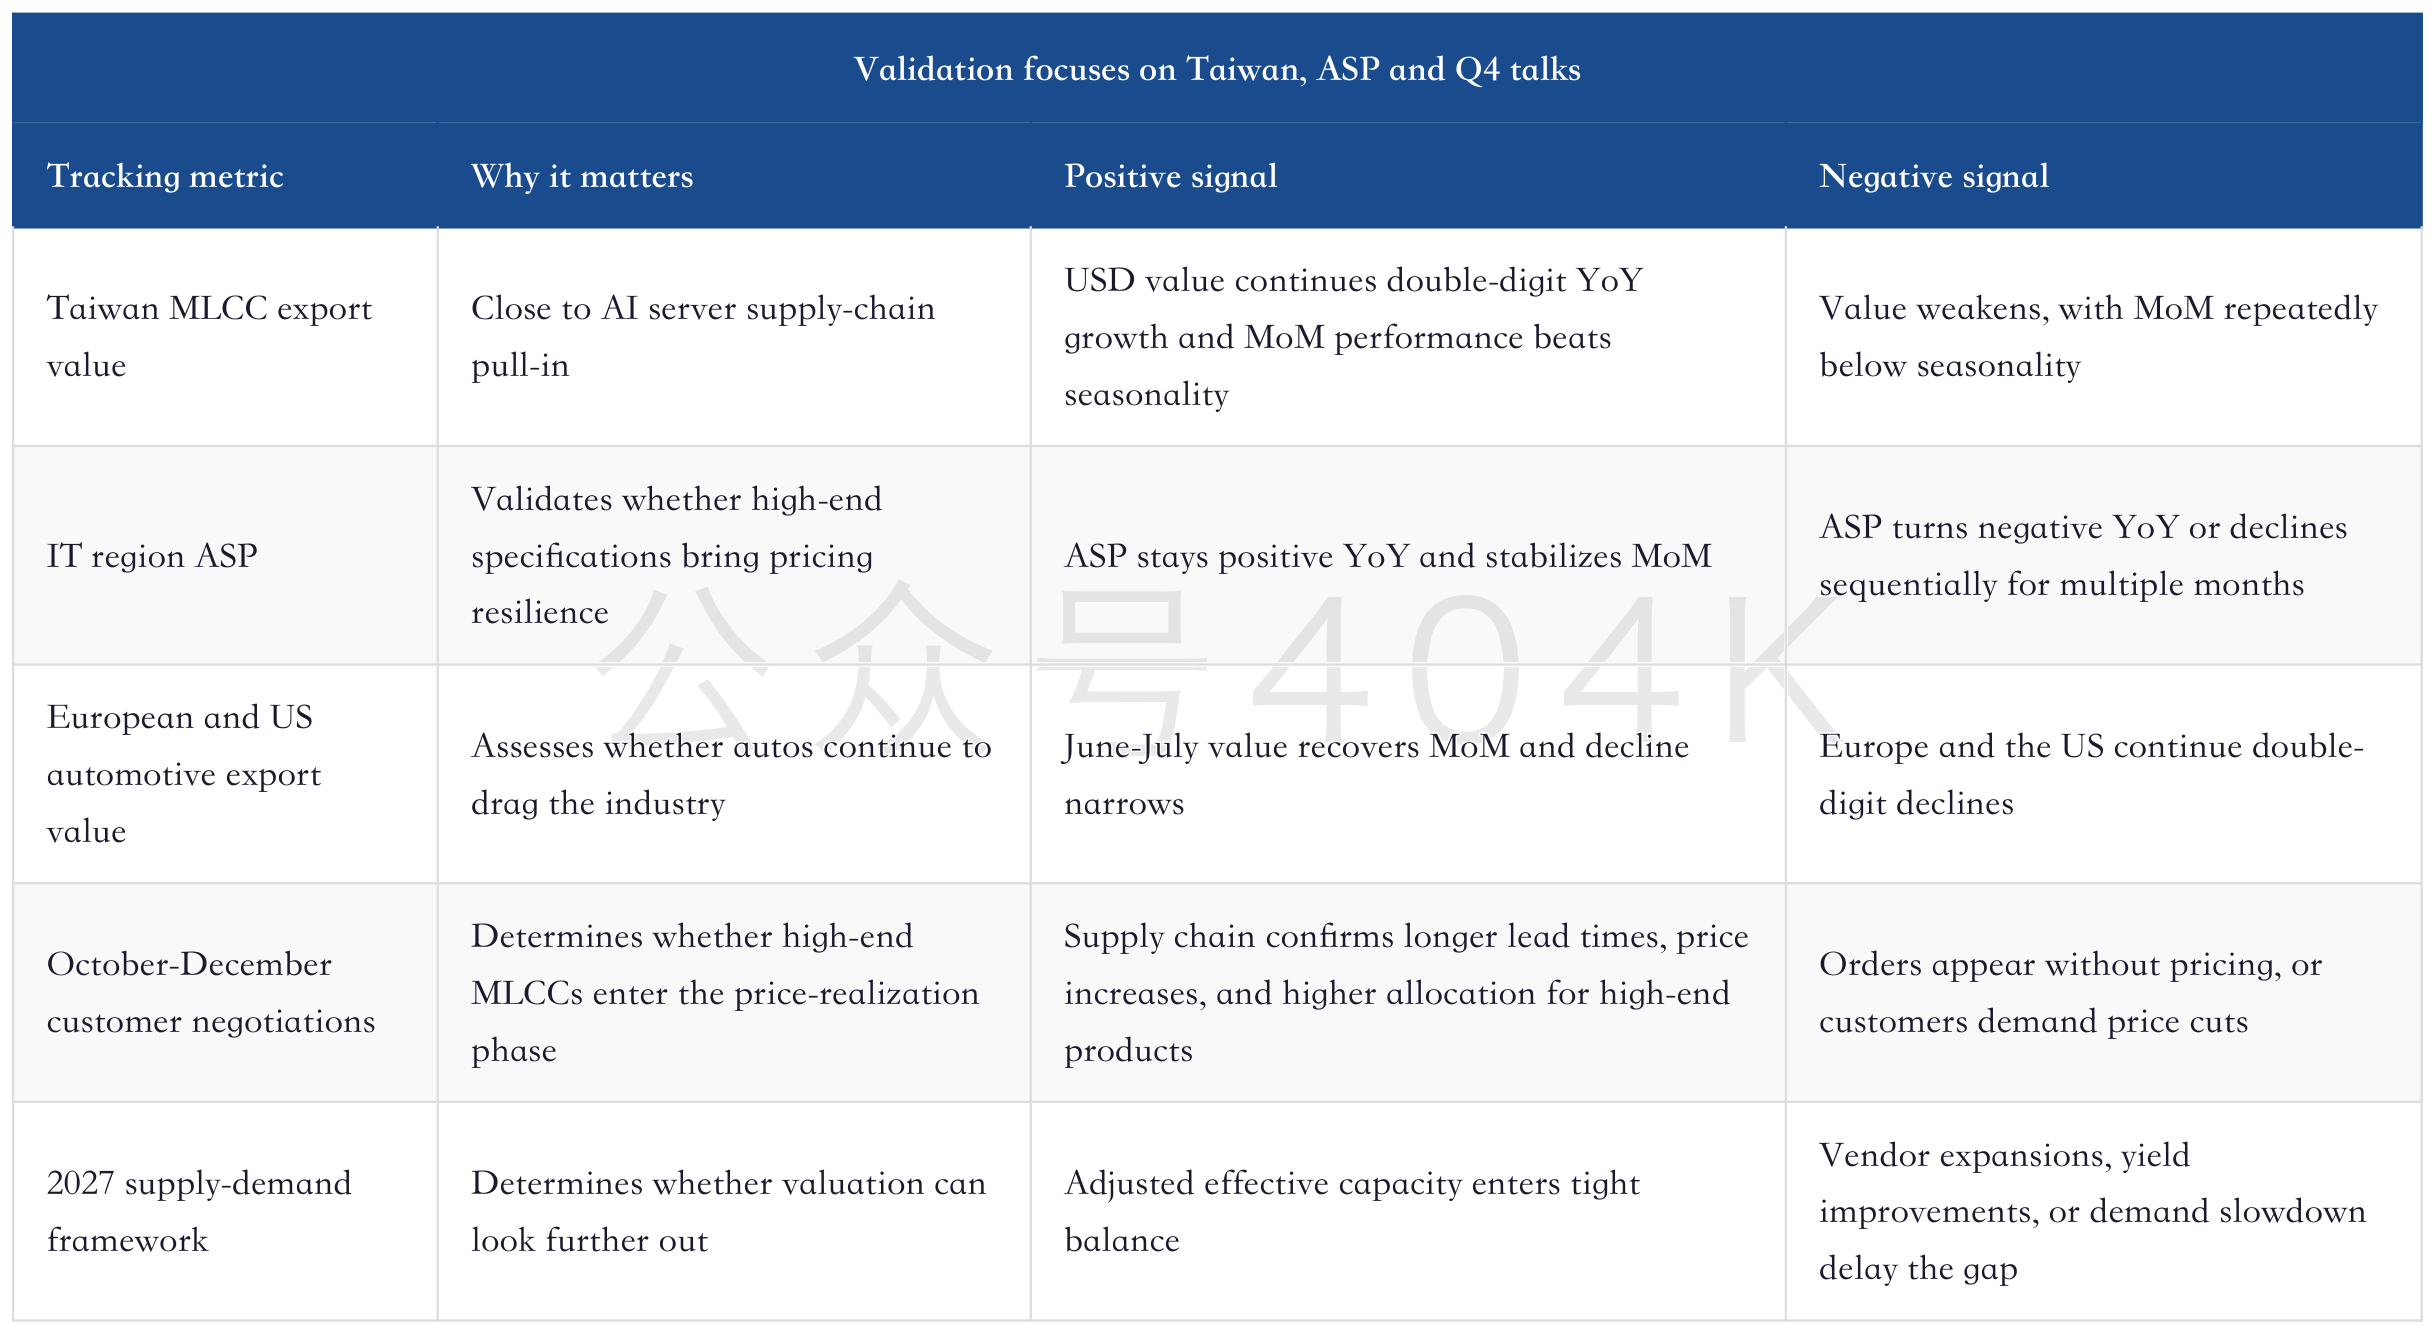
The next key validation point is not one month of June data, but the October-December price-negotiation window.
JPM is restrained on the near-term rhythm: the probability of MLCC price hikes in July-September is low, and the next inflection may come in October-December. This view is consistent with May data. The IT region remains strong, but ASP has not yet formed a clear monthly upward trend. The automotive chain is weak, which also makes it difficult for suppliers to quickly push price hikes from high-end specifications to a broader customer base.
There is no need to look for a new story every day to track this MLCC cycle. Watch four sets of numbers.
Japan Electronic Components Deep Update: Morgan Stanley Asia Investor Survey, How AI Servers Widen the MLCC-ABF Valuation Gap
If high-end AI server MLCC negotiations strengthen in October-December, the logic for Murata and Taiyo Yuden will move from "expected price hikes" to "orders and pricing realization." At that point, the market will revisit 2027 profit beta rather than focusing only on 2026 P/E.
If there are no price hikes in October-December, MLCCs may still be a good industry, but the stocks will first need to go through a valuation digestion period. JPM's valuation table shows that Murata's FY26E P/E is already above 60x and Taiyo Yuden's FY26E P/E is above 100x. Although FY27E will fall significantly as profits recover, this means the market has already priced in 2027 repair. For high-valuation cyclical growth stocks, a delayed validation point is itself a risk.
8. Risks and Falsification: Which Data Would Prove This Round Is Only a Short-Term Front-Run
The biggest risk in this MLCC trade is that the market prematurely trades "high-end structural tightness" as an "industry-wide price-hike cycle."
May data have not yet falsified the high-end logic, but they have reminded us that demand is not even. Automotive declines, MoM ASP pullback, and low probability of July-September price hikes all indicate that the industry has not entered a state where all customers are scrambling for products. The more share prices rise in advance, the clearer the falsification checklist needs to be.
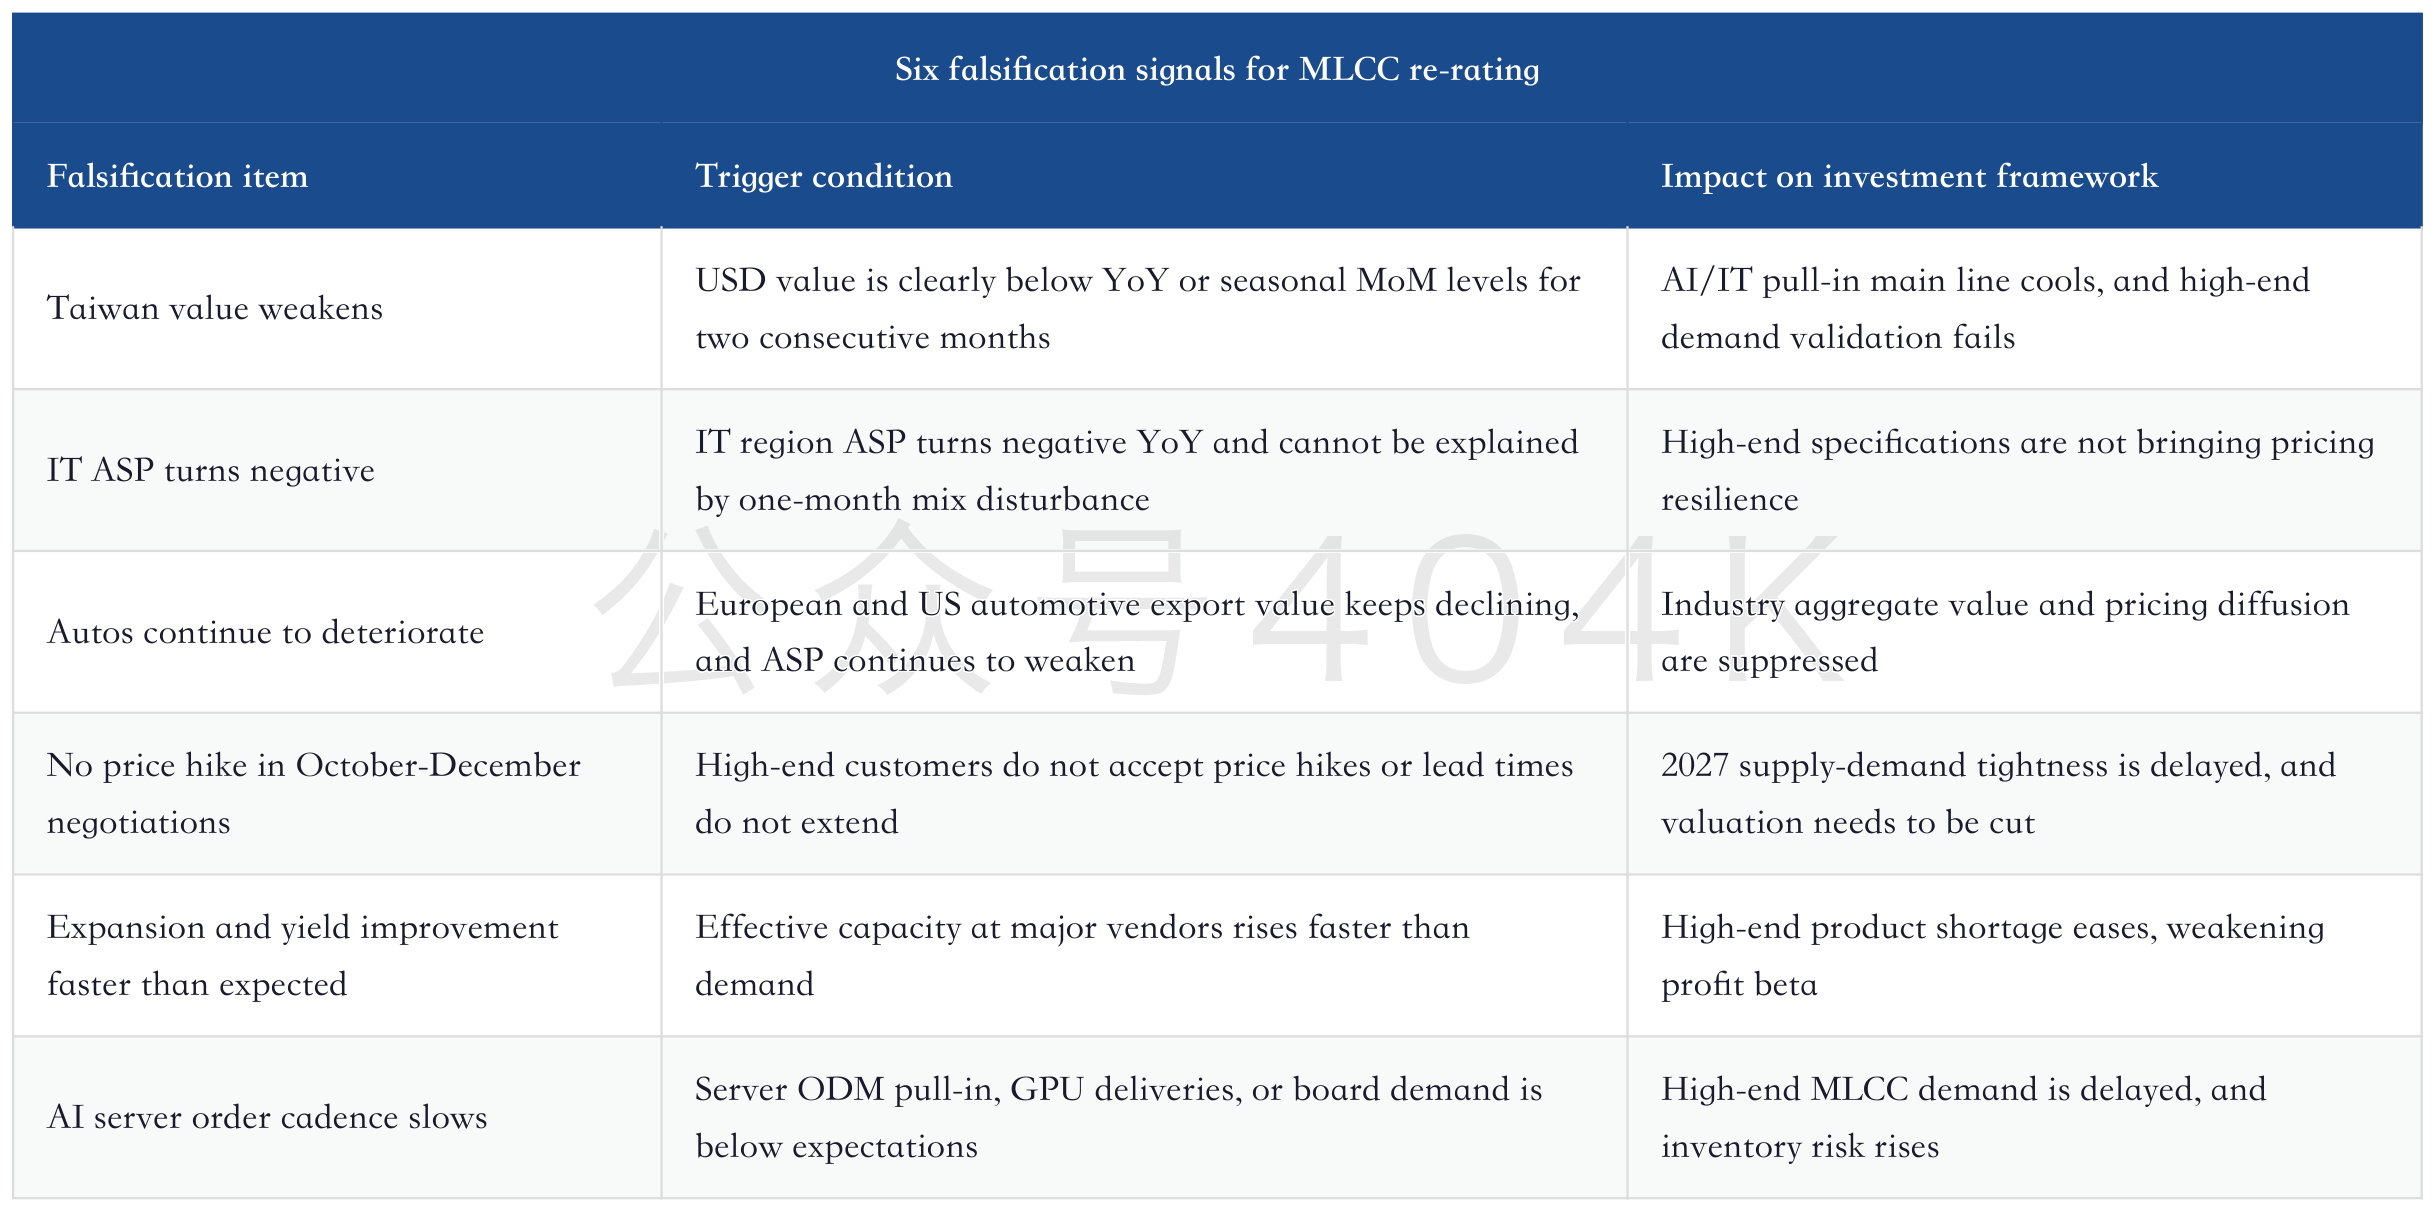
There is another risk from the trade itself. JPM explicitly mentioned that MLCC stocks have rallied rapidly since April and have reflected part of the market's expectation that AI server application demand pulled forward three to four years of growth within the short April-June period. This wording is restrained but useful for investment: the industry logic can remain intact while stocks consolidate first.
Yageo Deep Update: AI Demand Begins Tightening MLCC Supply; How Low-to-Mid Capacitance Price Hikes Rewrite the 2027-2028 Income Statement
The better approach is to wait for the validation chain to become complete. In June-August, watch Taiwan and IT-region value. In September-October, watch inventory and lead times. In October-December, watch high-end product price negotiations. In 2027, watch whether the effective-capacity gap enters the supply chain's visible range. Only when these steps connect can MLCCs move from an "AI server thematic trade" to a "high-end effective-capacity re-rating."
9. Conclusion: May Makes the MLCC Logic Narrower and Clearer
Japan's May MLCC trade data did not negate the structural re-rating brought by AI servers, but it narrowed the main line.
Aggregate volume declined in line with seasonality, the auto-chain decline exceeded seasonality, the IT region remained resilient, and Taiwan was the strongest driver this month. Pricing was not materially damaged, but it has also not entered a broad uptrend. JPM remains bullish on Murata and Taiyo Yuden, while also warning that July-September price hikes are unlikely and share prices may consolidate near term. This combination is more credible than simple optimism.
For investment, the key MLCC question now becomes "which companies can turn AI demand into high-end effective capacity and pricing power." Murata remains the anchor with the highest certainty. Taiyo Yuden offers higher profit beta. TDK, Samsung Electro-Mechanics, and Yageo have different mappings. For A shares, investors need to distinguish Three-Circle Group's high-end electronic ceramics platform, Sinocera's materials prerequisite, Jiemei Technology's manufacturing materials chain, and Fenghua Advanced Technology's cycle beta.
There is no need to change the narrative frequently from here. Keep tracking Taiwan value, IT-region ASP, European and US automotive repair, October-December price negotiations, and the 2027 effective-capacity gap, and the MLCC thesis remains testable. If these numbers connect, May was only a seasonal pullback. If these numbers break, the April-June share-price rally will be proven to have front-loaded too much.MLCC Deep Update: The Real Signal After May Trade Data Cooled, and How Taiwan IT Demand Can Take Over from the Auto Recovery
目录
Too Long; Didn’t Read
1. May Cooling Is Seasonal: Structural Divergence Is the New Information
2. Automotive Chain Retreat: The Strong Rebound in European and US Automotive MLCCs Did Not Continue
3. Taiwan Takes Over: IT Applications Remain a Leading Indicator of AI Server Demand
4. From April Strength to May Divergence: How Monthly Data Revise the Previous Bullish MLCC Framework
5. Company Ranking: Murata Is the Anchor, Taiyo Yuden Is the Beta, and TDK, Samsung Electro-Mechanics, and Yageo Each Depend on One Variable
6. A-Share Mapping: Three-Circle Group, Sinocera, Jiemei Technology, and Fenghua Advanced Technology Need to Be Viewed in Layers
7. Tracking List: Can October-December Become the Next Price-Negotiation Window?
8. Risks and Falsification: Which Data Would Prove This Round Is Only a Short-Term Front-Run
9. Conclusion: May Makes the MLCC Logic Narrower and Clearer
本内容基于公开资料和研报数据整理,不构成任何投资建议,不代表任何个人观点,仅供学习参考,请理性阅读
Japan’s May MLCC trade data narrows the bullish evidence. The aggregate pullback was seasonal, the retreat in the automotive chain needs attention, and IT plus AI server demand is still extending through Taiwan. Near-term share prices have already discounted part of the story. The next validation points are the October-December price negotiations and 2027 high-end supply-demand conditions.
Too Long; Didn’t Read
The May cooling is seasonal. Japan’s May MLCC export volume and value were 83.837bn units and $411mn, down 9.9% and 11.8% MoM, respectively, broadly in line with the typical May pullback over the past 10 years. The real focus is whether value, ASP, and the three-month moving average continue to move higher. ASP is still positive YoY, which means the price trend has not clearly broken.
The automotive chain is the biggest weak spot this month. JPM uses Europe and the US as the main observation regions for automotive MLCCs. May export volume and value fell 22.4% and 25.1% MoM, respectively, clearly weaker than seasonality. The rapid March-April recovery in automotive demand did not continue, with Europe and the US weakening at the same time. If no recovery is visible in June-July, the automotive chain will become a negative check on the MLCC cycle assessment.
Taiwan is where the IT chain is taking over. JPM combines China, Hong Kong, Taiwan, South Korea, Vietnam, the Philippines, and India into a region with a high IT weighting. In May, value in this region rose 13.0% YoY, clearly better than the automotive chain. Taiwan export volume and value increased 37.9% and 17.3% MoM, respectively. This is more consistent with the rhythm of the AI server supply chain and is the most important bullish evidence to retain from this month’s data.
The pricing window will likely move later. JPM maintains Murata Manufacturing and Taiyo Yuden as its preferred MLCC names, with a stronger preference for Murata. It also explicitly notes that the April-June rally in MLCC stocks has already reflected part of the demand expansion from AI server applications over the next three to four years. A more reasonable near-term view is that share prices enter range-bound consolidation, the probability of July-September price hikes is low, and the next more important inflection window is October-December. From an investment perspective, Taiwan’s strong May data should not be equated directly with immediate price hikes. It should be treated as evidence that demand for high-end specifications is still transmitting into the supply chain.
Company ranking needs to shift from capacity to effective capacity. Murata remains the global pricing anchor for high-end MLCCs, with advantages in advanced processes, quality capability, and product roadmap. Taiyo Yuden has greater earnings beta, but near-term valuation is also more dependent on price-hike expectations being realized. TDK’s appeal lies in its high-end component portfolio and customer structure. Samsung Electro-Mechanics is more closely tied to the Korean AI/server chain, while Yageo is more affected by low-to-mid-capacitance products and channel inventory. A-share mapping cannot be ranked simply by “who makes MLCCs.” Three-Circle Group should be viewed through high-end MLCCs and the electronic ceramics platform; Sinocera through ceramic powders and electronic pastes; Jiemei Technology through release films/carrier tapes and other material links; and Fenghua Advanced Technology through the cycle beta of domestic MLCCs.
May raised the validation threshold. The data revise the framework from “synchronous recovery across all applications” to “AI/IT lifts the high end, autos drag, pricing waits for negotiations.” If IT-region value remains above seasonality in June-August, Taiwan continues to show YoY and value resilience, and automotive stops deteriorating, then the October-December price-hike logic and the 2027 supply-demand tightening logic still hold. If Taiwan value weakens, ASP turns negative YoY, and autos continue to deteriorate, high-end product tightness will be pushed out and the high valuations of related stocks will need to be digested first.
1. May Cooling Is Seasonal: Structural Divergence Is the New Information
The first message from May MLCC trade data is simple: aggregate volume fell sequentially, in line with seasonality.
Japan’s May MLCC export volume and value both retreated from a strong April, with the MoM decline close to the May seasonal pattern over the past 10 years. ASP softened only modestly and still maintained positive YoY growth. Together with the impact of Japan’s Golden Week, the May pullback should not be read directly as a demand inflection point.
JPM’s aggregate view can be condensed into one sentence: May retreated from a strong April, but the trendline was not broken. The original report used a short phrase, “seasonal trends.” This reminds us that a single-month MoM decline is not enough to negate a moderate upward line that has already lasted for several months.
This set of data revises the rhythm of the previous two MLCC deep-dive reports, not the overall direction. Our earlier core discussion was that AI servers are pushing MLCCs from ordinary cyclical products toward an effective-capacity bottleneck. The key variable is whether high-end specification demand can continue absorbing available capacity. A single-month MoM move in aggregate exports does not determine the long-term logic.
MLCC Deep Dive: JPMorgan Sharply Raises Forecasts, from Cyclical Repair to Structural Re-Rating, as AI Servers Rewrite the Supply-Demand Gap
May data still support this framework, but not indiscriminate optimism. The automotive chain fell very clearly, the IT region was steadier, and Taiwan was stronger than other regions. In other words, the MLCC business has not become a case of all applications raising prices together. Rather, high-end AI/IT chains continue to lift marginal demand, while traditional autos and some regions expose weaknesses first.
2. Automotive Chain Retreat: The Strong Rebound in European and US Automotive MLCCs Did Not Continue
The automotive chain is the most uncomfortable part of the May data.
JPM uses exports to Europe and the US as an approximate gauge of automotive MLCCs. In May, volume, value, and ASP in this segment all weakened, and the MoM declines in volume and value were both clearly worse than the past 10-year seasonality. The auto-chain signal is worse than the aggregate signal and needs to be considered separately.
This is a data set that must be taken seriously. Automotive exports in April had given the impression that demand recovery was spreading. May shows the recovery did not continue on inertia. European volume fell 30% MoM and value fell 25%; US volume fell 15% MoM and value fell 26%. Neither direction was strong.
The core issue for automotive MLCCs extends from quantity to value and ASP. Automotive applications usually have higher unit prices, higher reliability requirements, and longer customer qualification cycles. If this region continues to weaken, the high-value part of industry revenue will be restrained, and price-hike expectations will also be discounted.
From an investment perspective, the automotive chain should be treated as a negative check, while the main line remains AI/IT high-end products. AI servers can drive high-end multilayer, high-capacitance, high-reliability products, but if automotive remains weak, it will limit the speed at which industry pricing spreads. Put differently, high-end products can be tight, while broad industry price hikes may still not arrive immediately.
3. Taiwan Takes Over: IT Applications Remain a Leading Indicator of AI Server Demand
The strongest new evidence in May came from Taiwan.
JPM combines China, Hong Kong, Taiwan, South Korea, Vietnam, the Philippines, and India into a region with a high weighting in IT applications. In May, this region’s volume and value fell sequentially, but still grew YoY, and ASP was also positive YoY. Compared with aggregate data and autos, the IT region’s pricing and value were steadier.
Taiwan’s data were particularly striking. In May, Japan’s MLCC export volume and value to Taiwan both increased against seasonality, while value also continued to maintain double-digit YoY growth. Volume and value strengthened together. That is the most important structural signal this month.
Why does Taiwan matter? Because assembly, boards, server ODMs, and high-end component pull-in for the AI server supply chain are more likely to be reflected earlier in this direction. A single MLCC has little value, but server motherboards, accelerator cards, power modules, and high-speed computing platforms will significantly increase the use of high-reliability, high-capacitance, and miniaturized MLCCs. For MLCC manufacturers, strengthening value in Taiwan matters more than small fluctuations in aggregate volume.
Japan Electronic Components Deep Dive: AI Servers Push MLCCs from Cyclicals Toward Compute Infrastructure
One misread should be avoided here: strength in Taiwan does not mean all AI server MLCCs are already tight enough to trigger immediate price hikes. Taiwan ASP fell 15.0% MoM in May, which shows that product mix, customer pull-in rhythm, and FX can all affect monthly pricing. A more prudent reading is that AI/IT demand is still taking over, but pricing power needs further validation from the negotiation window and supply-chain inventory.
4. From April Strength to May Divergence: How Monthly Data Revise the Previous Bullish MLCC Framework
May data revise the bullish MLCC framework from “broad demand repair” to “high-end structural demand continues, while traditional applications contribute unevenly.”
The easiest point for the market to get excited about was that AI servers pulled high-end MLCC demand for the next several years into current orders. In JPM’s long-term model in mid-June, it had already materially raised 2025-2028 industry revenue CAGR, supply-demand gap, and ASP upside, and it expects adjusted effective capacity to tighten again in 2027-2028. May trade data are only a monthly thermometer. The thermometer shows that the heat source is still there, but the heat has not spread evenly.
MLCC Deep Update: AI Servers Push Cyclicals Toward a Power-Supply Bottleneck; Who Can Turn Price Hikes into Profits
The supply bottleneck in MLCCs is mainly effective capacity. High-end MLCCs require more layers, thinner dielectric, more stable sintering, and stricter reliability control. After the same line shifts toward high-end specifications, yield, takt time, and usable output all change. Higher AI server demand looks like using a few more capacitors, but in reality it occupies the high-end effective capacity that is hardest to replicate.
This is also why the May aggregate volume decline cannot directly overturn the long-term logic. If low-end consumer electronics, ordinary industrial demand, or the automotive chain is weak, but high-end AI/IT specifications continue to absorb production lines, the industry may still enter a tight balance for high-end products in 2027. Conversely, if Taiwan and other IT regions also begin to weaken, the supply-demand tightening timetable must move later.
The conclusion from this table is direct: the near-term win rate for MLCC stocks depends on whether the expectation gap can still widen; the medium-term win rate depends on whether effective capacity truly tightens. May data are mildly positive for the medium-term logic and more restrained for near-term trading rhythm.
5. Company Ranking: Murata Is the Anchor, Taiyo Yuden Is the Beta, and TDK, Samsung Electro-Mechanics, and Yageo Each Depend on One Variable
Company ranking needs to be upgraded from “who is an MLCC company” to “who can turn high-end effective capacity into profit.”
JPM maintains Murata Manufacturing and Taiyo Yuden as its preferred MLCC names, with a stronger preference for Murata. This preference is reasonable. Murata’s advantages lie in the combination of advanced production technology, quality capability, product roadmap, and customer qualification. The value of AI server MLCCs is not in the quantity of ordinary products, but in capacitance, reliability, size, temperature, and supply stability. The higher end the product moves, the less willing customers are to hand risk to new entrants.
Taiyo Yuden has greater beta. Its operating leverage in MLCCs is higher, so demand improvement and price increases will feed through to the income statement faster. But beta also means valuation is more dependent on price hikes being realized. If there are no price hikes in July-September and no clear progress in October-December negotiations, high-beta names such as Taiyo Yuden are more likely to digest expectations first.
TDK’s issue is different. TDK is a diversified component company, with magnetic components, batteries, and other electronic components also in its portfolio. As a result, its MLCC beta is not as direct as Taiyo Yuden’s. The benefit is that its customer and product structures are more diversified. If the AI server and high-end power-supply chains continue to upgrade, TDK can benefit from multiple component lines.
Samsung Electro-Mechanics is more closely tied to the Korean server and high-end electronics supply chain. Its advantages are Asian customers and high-end electronic component manufacturing capability. The risks are that valuation is already high and profit recovery requires coordination among high-end MLCCs, substrates, and customer pull-in cadence. Yageo is more of an observer of pricing diffusion. Low-to-mid-capacitance products and channel inventory have a larger impact on it. If price hikes spread from the high end to low-to-mid products, Yageo’s beta will become more visible; if price hikes remain limited to tight high-end specifications, Murata and Taiyo Yuden have the advantage.
Murata Manufacturing Deep Dive: AI Server MLCCs, from Small Components to a Profit Gate
At this stage, the steadier ranking is: Murata for certainty, Taiyo Yuden for beta, TDK for a diversified high-end component portfolio, Samsung Electro-Mechanics for Korean AI/server-chain mapping, and Yageo for whether price hikes can spill over into low-to-mid capacitance products. May data did not change this ranking. It only makes the near-term trade require more patience.
6. A-Share Mapping: Three-Circle Group, Sinocera, Jiemei Technology, and Fenghua Advanced Technology Need to Be Viewed in Layers
A-share MLCC mapping cannot be written as one basket.
The main line for Three-Circle Group is its electronic ceramics platform and domestic substitution in high-end MLCCs. Its truly valuable part is whether its materials, processes, customer qualification, and electronic ceramics platform capabilities can migrate into higher-end passive components. The lesson from AI servers is that the value of high-end ceramic components is no longer judged only by unit price, but by reliability, qualification barriers, and the premium customers are willing to pay for stable supply.
Sinocera is more upstream materials-oriented. MLCC ceramic powders, electronic pastes, dielectric materials, and process stability determine the underlying performance of high-end MLCCs. If high-end MLCC demand continues to upgrade, powders and pastes will move from cyclical materials to a prerequisite for moving upmarket. Its beta may be less direct than that of MLCC device manufacturers, but its business quality is closer to a picks-and-shovels model.
The observation point for Jiemei Technology is material links such as release films and carrier tapes. MLCC shipments and high-end specification upgrades will affect material usage, quality requirements, and customer qualification. It is a material name indirectly mapped to AI server MLCCs and has tracking value within the passive-component cycle and high-end manufacturing materials chain.
Fenghua Advanced Technology is more about the cycle beta of domestic MLCCs. If low-to-mid capacitance pricing and utilization improve, Fenghua Advanced Technology will benefit more directly. But if this round of tightness is mainly concentrated in high-end AI server specifications, Fenghua Advanced Technology needs to prove that its product structure, customers, and high-end qualifications can keep up, rather than relying only on an industry price-hike narrative.
Three-Circle Group Deep Dive: From Electronic Ceramics Platform to High-End MLCCs, How AI Servers Re-Rate Domestic Ceramic Component Capabilities
Sinocera Deep Update: From MLCC Powders to Electronic Pastes, AI Servers Rewrite the Value of MLCC Powders and Re-Rate High-End Ceramic Materials
The correct use of A shares is layered tracking, avoiding buying everything when one name rises. If Taiwan remains strong in June-August and October-December price negotiations show tightness in high-end products, names tied to high-end upgrades such as Three-Circle Group and Sinocera will have stronger explanatory power. If price hikes spread to low-to-mid capacitance products, Fenghua Advanced Technology and channel beta will become more visible. If only Japanese high-end leaders capture the benefits, the A-share mapping needs to be discounted.
7. Tracking List: Can October-December Become the Next Price-Negotiation Window?
The next key validation point is not one month of June data, but the October-December price-negotiation window.
JPM is restrained on the near-term rhythm: the probability of MLCC price hikes in July-September is low, and the next inflection may come in October-December. This view is consistent with May data. The IT region remains strong, but ASP has not yet formed a clear monthly upward trend. The automotive chain is weak, which also makes it difficult for suppliers to quickly push price hikes from high-end specifications to a broader customer base.
There is no need to look for a new story every day to track this MLCC cycle. Watch four sets of numbers.
Japan Electronic Components Deep Update: Morgan Stanley Asia Investor Survey, How AI Servers Widen the MLCC-ABF Valuation Gap
If high-end AI server MLCC negotiations strengthen in October-December, the logic for Murata and Taiyo Yuden will move from “expected price hikes” to “orders and pricing realization.” At that point, the market will revisit 2027 profit beta rather than focusing only on 2026 P/E.
If there are no price hikes in October-December, MLCCs may still be a good industry, but the stocks will first need to go through a valuation digestion period. JPM’s valuation table shows that Murata’s FY26E P/E is already above 60x and Taiyo Yuden’s FY26E P/E is above 100x. Although FY27E will fall significantly as profits recover, this means the market has already priced in 2027 repair. For high-valuation cyclical growth stocks, a delayed validation point is itself a risk.
8. Risks and Falsification: Which Data Would Prove This Round Is Only a Short-Term Front-Run
The biggest risk in this MLCC trade is that the market prematurely trades “high-end structural tightness” as an “industry-wide price-hike cycle.”
May data have not yet falsified the high-end logic, but they have reminded us that demand is not even. Automotive declines, MoM ASP pullback, and low probability of July-September price hikes all indicate that the industry has not entered a state where all customers are scrambling for products. The more share prices rise in advance, the clearer the falsification checklist needs to be.
There is another risk from the trade itself. JPM explicitly mentioned that MLCC stocks have rallied rapidly since April and have reflected part of the market’s expectation that AI server application demand pulled forward three to four years of growth within the short April-June period. This wording is restrained but useful for investment: the industry logic can remain intact while stocks consolidate first.
Yageo Deep Update: AI Demand Begins Tightening MLCC Supply; How Low-to-Mid Capacitance Price Hikes Rewrite the 2027-2028 Income Statement
The better approach is to wait for the validation chain to become complete. In June-August, watch Taiwan and IT-region value. In September-October, watch inventory and lead times. In October-December, watch high-end product price negotiations. In 2027, watch whether the effective-capacity gap enters the supply chain’s visible range. Only when these steps connect can MLCCs move from an “AI server thematic trade” to a “high-end effective-capacity re-rating.”
9. Conclusion: May Makes the MLCC Logic Narrower and Clearer
Japan’s May MLCC trade data did not negate the structural re-rating brought by AI servers, but it narrowed the main line.
Aggregate volume declined in line with seasonality, the auto-chain decline exceeded seasonality, the IT region remained resilient, and Taiwan was the strongest driver this month. Pricing was not materially damaged, but it has also not entered a broad uptrend. JPM remains bullish on Murata and Taiyo Yuden, while also warning that July-September price hikes are unlikely and share prices may consolidate near term. This combination is more credible than simple optimism.
For investment, the key MLCC question now becomes “which companies can turn AI demand into high-end effective capacity and pricing power.” Murata remains the anchor with the highest certainty. Taiyo Yuden offers higher profit beta. TDK, Samsung Electro-Mechanics, and Yageo have different mappings. For A shares, investors need to distinguish Three-Circle Group’s high-end electronic ceramics platform, Sinocera’s materials prerequisite, Jiemei Technology’s manufacturing materials chain, and Fenghua Advanced Technology’s cycle beta.
There is no need to change the narrative frequently from here. Keep tracking Taiwan value, IT-region ASP, European and US automotive repair, October-December price negotiations, and the 2027 effective-capacity gap, and the MLCC thesis remains testable. If these numbers connect, May was only a seasonal pullback. If these numbers break, the April-June share-price rally will be proven to have front-loaded too much.