
MLCC Deep Dive Update: Agentic AI, Rubin Racks, and the High-End Capacitor Supply Gap
目录
Too Long; Didn’t Read
1. Core View: MLCC Is Not a New Story, but a New Bottleneck After AI Hardware Value Diffusion
2. Agentic AI Pushes MLCC from Server Motherboards to Rack Systems
III. The Key to the Supply Gap Is Not Nominal Capacity, but Capacity Derating
IV. Pricing Mechanism: Not Broad-Based Price Hikes, but High-End Specifications Escaping Annual Price-Downs
V. Company Ranking: Murata Is the Pricing Anchor, Samsung Electro-Mechanics Offers Dual-Cycle Upside, and Yageo Captures Spillover
VI. Domestic China Chain: Sinocera Materials for Powder, Three-Circle Group for High-Capacitance MLCCs; Do Not Treat Mapping as Substitution
7. Silicon Capacitors and iPaS Are Not the Enemy; They Will Expand the Power Integrity Market
8. Investment Framework: Look First at Pricing, Then Gross Margin, and Finally Whether Valuation Is Overdrawn
9. Conclusion: The MLCC Cycle Is Not Over, but the Game Has Become Harder
本内容基于公开资料和研报数据整理,不构成任何投资建议,不代表任何个人观点,仅供学习参考,请理性阅读
AI servers are no longer only repricing GPUs and HBM. Agentic AI is pushing bottlenecks toward power integrity, board-level materials, and high-end passive components. The key for MLCC is not unit volume, but the repricing of high-end effective capacity, ASP discipline, and supply-chain priority. The investment focus is shifting to who can convert supply-demand gaps into profit.
Too Long; Didn’t Read
MLCC revaluation is entering a second phase. Before June, the market mainly traded the idea that “AI servers also need MLCCs.” After July, the more important trade should be whether high-end effective capacity is sufficient. UBS’s latest APAC technology strategy defines Agentic AI as the key inflection point for AI adoption in 2026. Memory, advanced packaging, PCB, ABF, and MLCC are all being driven by the power-density theme. MLCC is therefore no longer a side story of consumer-electronics restocking, but a new constraint after AI hardware value expands from chips into power delivery, board-level systems, and rack systems.
The supply gap matters more than the demand story. JPMorgan’s long-term Asia MLCC model expects the industry to shift from roughly 10% oversupply in 2025 to around 6% shortage in 2028. It forecasts an industry TAM CAGR of about 24% from 2025 to 2028, with ASP upside in the high-50% range over the same period. The key is not just server pull-in, but the capacity loss caused by high-capacitance, high-voltage, miniaturized, side-gap, and 1005-47uF AI specifications. Some AI server-grade products have assembly yields only one-third to one-sixth those of standard MLCCs.
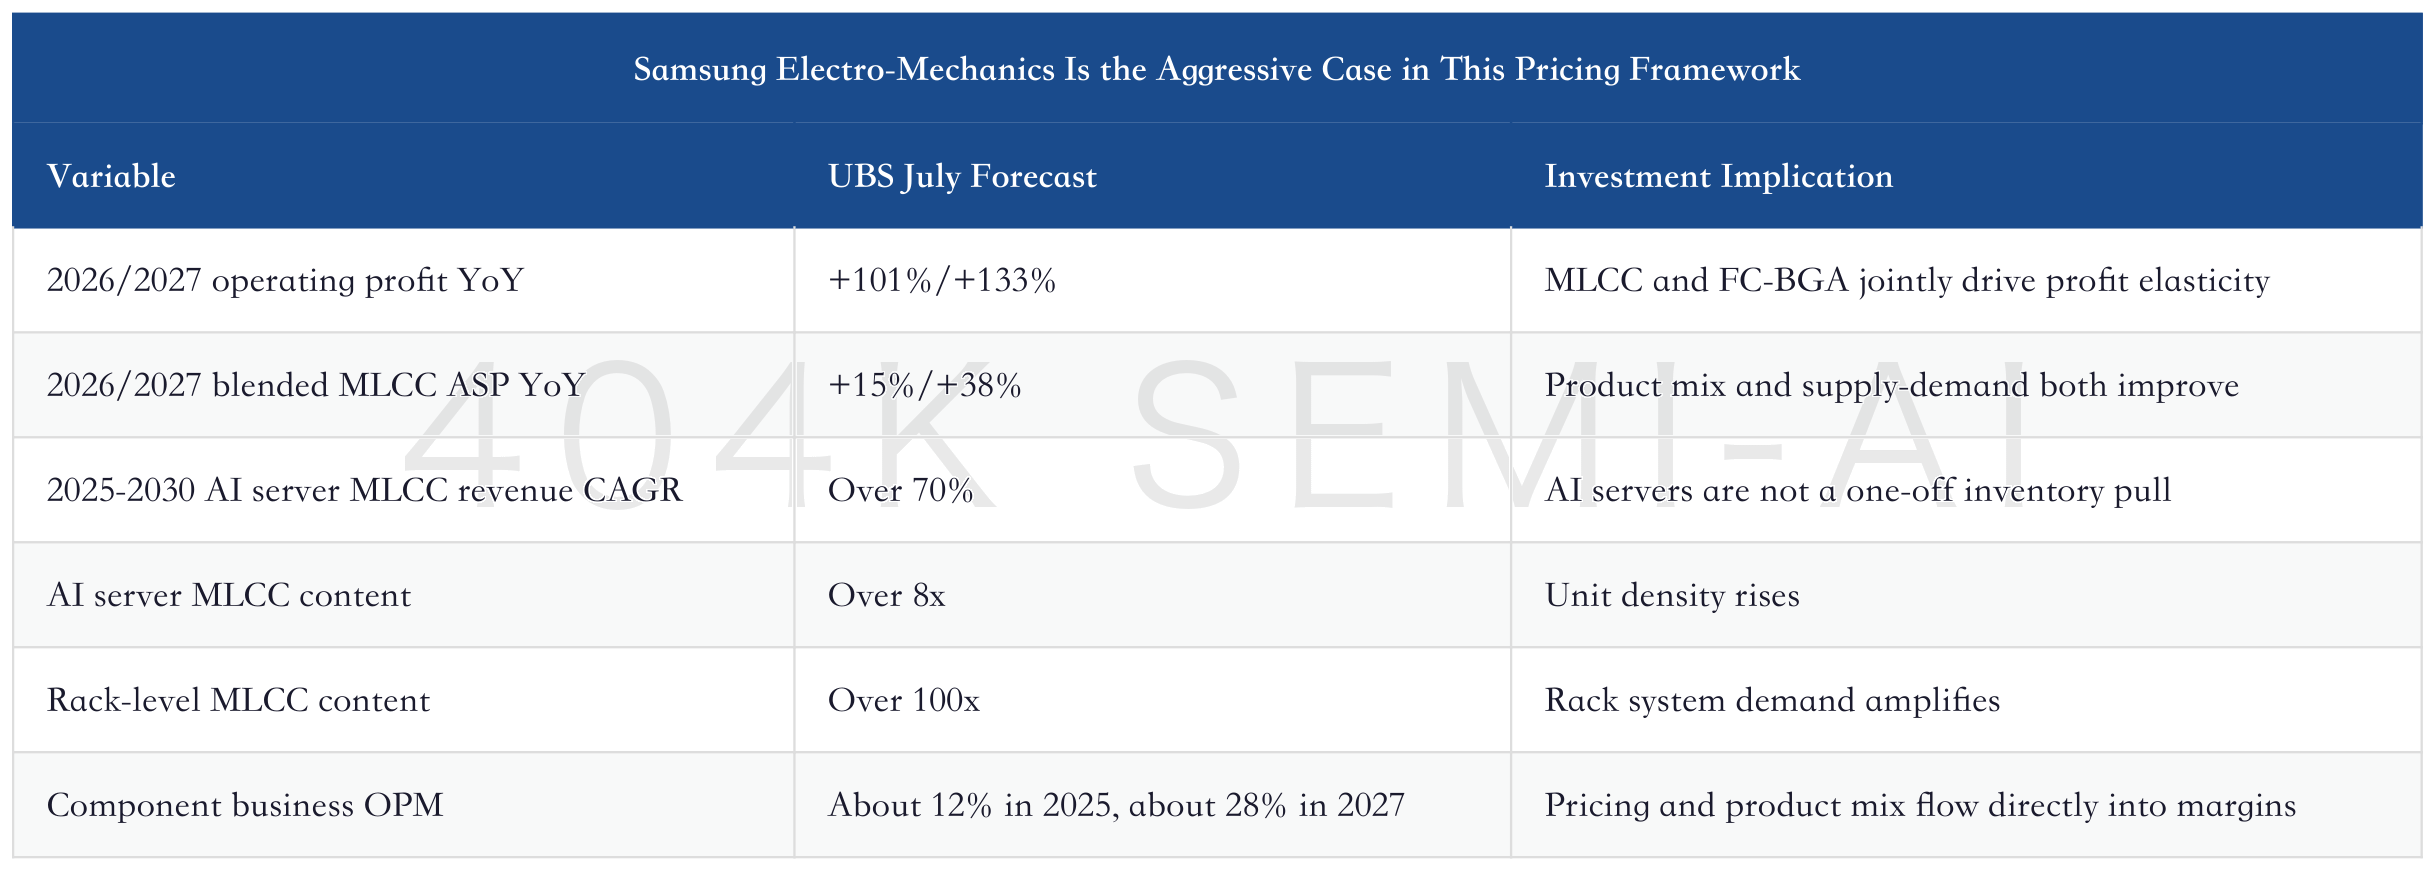
The pricing mechanism is stratifying. Standard consumer-electronics MLCCs may still see annual price declines. The real strength is in specifications used for AI servers, high-end autos, data-center power supplies, and networking equipment. UBS expects Samsung Electro-Mechanics’ blended MLCC ASP to rise 15%/38% YoY in 2026/2027, and believes tight high-end supply-demand conditions after 2H26 could lead to price increases for the same specifications. Citi upgraded Murata to Buy, also mainly because AI server product mix is lifting unit prices and margins.
Companies should be divided into three groups. Murata Manufacturing is the technology and pricing anchor, and is the best company for observing the margin slope of AI server MLCCs. Samsung Electro-Mechanics has three-way resonance across MLCC, FC-BGA, and silicon capacitors, with stronger earnings elasticity but also greater dependence on delivery against expectations. Yageo benefits from spot and direct-customer price increases in low-to-mid capacitance products after high-end AI capacity crowds out supply. TDK is more of a steady diversified platform. Taiyo Yuden has high demand elasticity, but productivity and high-end yield determine the ceiling of its revaluation.
The China mapping cannot be copied mechanically. For Sinocera, the core focus is its 5,000-ton AI-grade MLCC powder capacity expansion, 50-100nm hydrothermal barium titanate powder, and price transmission upstream. For Chaozhou Three-Circle, the focus is high-capacitance MLCC volume ramp, SOFC orders, and domestic substitution. Both are driven by the high-end ceramic materials chain, but they cannot yet be directly equated with core AI server MLCC suppliers such as Murata and Samsung Electro-Mechanics. Valuation should depend on orders, customer qualification, and product mix, not only industry beta.
The falsification indicators are already clear. Over the next four quarters, focus on five numbers: Japan and Korea MLCC export ASPs; Murata/Samsung Electro-Mechanics’ AI server MLCC revenue share; Samsung Electro-Mechanics’ FC-BGA utilization rate and gross margin; the extent to which Yageo’s low-to-mid capacitance spot prices transmit into contract prices; and Sinocera’s actual AI-grade powder shipments and pricing. If price increases remain only channel rumors, leading companies’ gross margins do not rise, or AI server pull-in is pushed out from after 2H26, this revaluation should cool.
1. Core View: MLCC Is Not a New Story, but a New Bottleneck After AI Hardware Value Diffusion
This MLCC rally is most easily misread as “AI servers use a few more small capacitors.” That view is too shallow. MLCCs are being revalued because, after AI servers enter the Agentic AI stage, compute demand continues to expand from GPU and HBM into CPU, DDR, SSD, PCB, ABF, power delivery, and thermal management. Power integrity becomes the basic reliability constraint for the full server and full rack. Customers will not be willing to take risks on high-end specifications just because MLCCs account for a low share of BOM. On the contrary, components with small dollar value but high failure-cost exposure are more likely to receive a supply-certainty premium.
Historically, MLCC research centered on when smartphone, PC, and auto shipments would recover, when channel inventory would be digested, and when utilization would return to a price-upcycle range. The question has now changed: AI servers, AI networking, BBU, power modules, switches, accelerator cards, CPUs, and ASICs are all increasing power density at the same time. Standard MLCC nameplate capacity is not equivalent to high-end effective capacity for AI servers. High-capacitance, high-voltage, miniaturized, high-reliability specifications located closer to chip loads consume the hardest-to-substitute process windows.
The MLCC investment framework is shifting from cyclical restocking to high-end effective capacity.
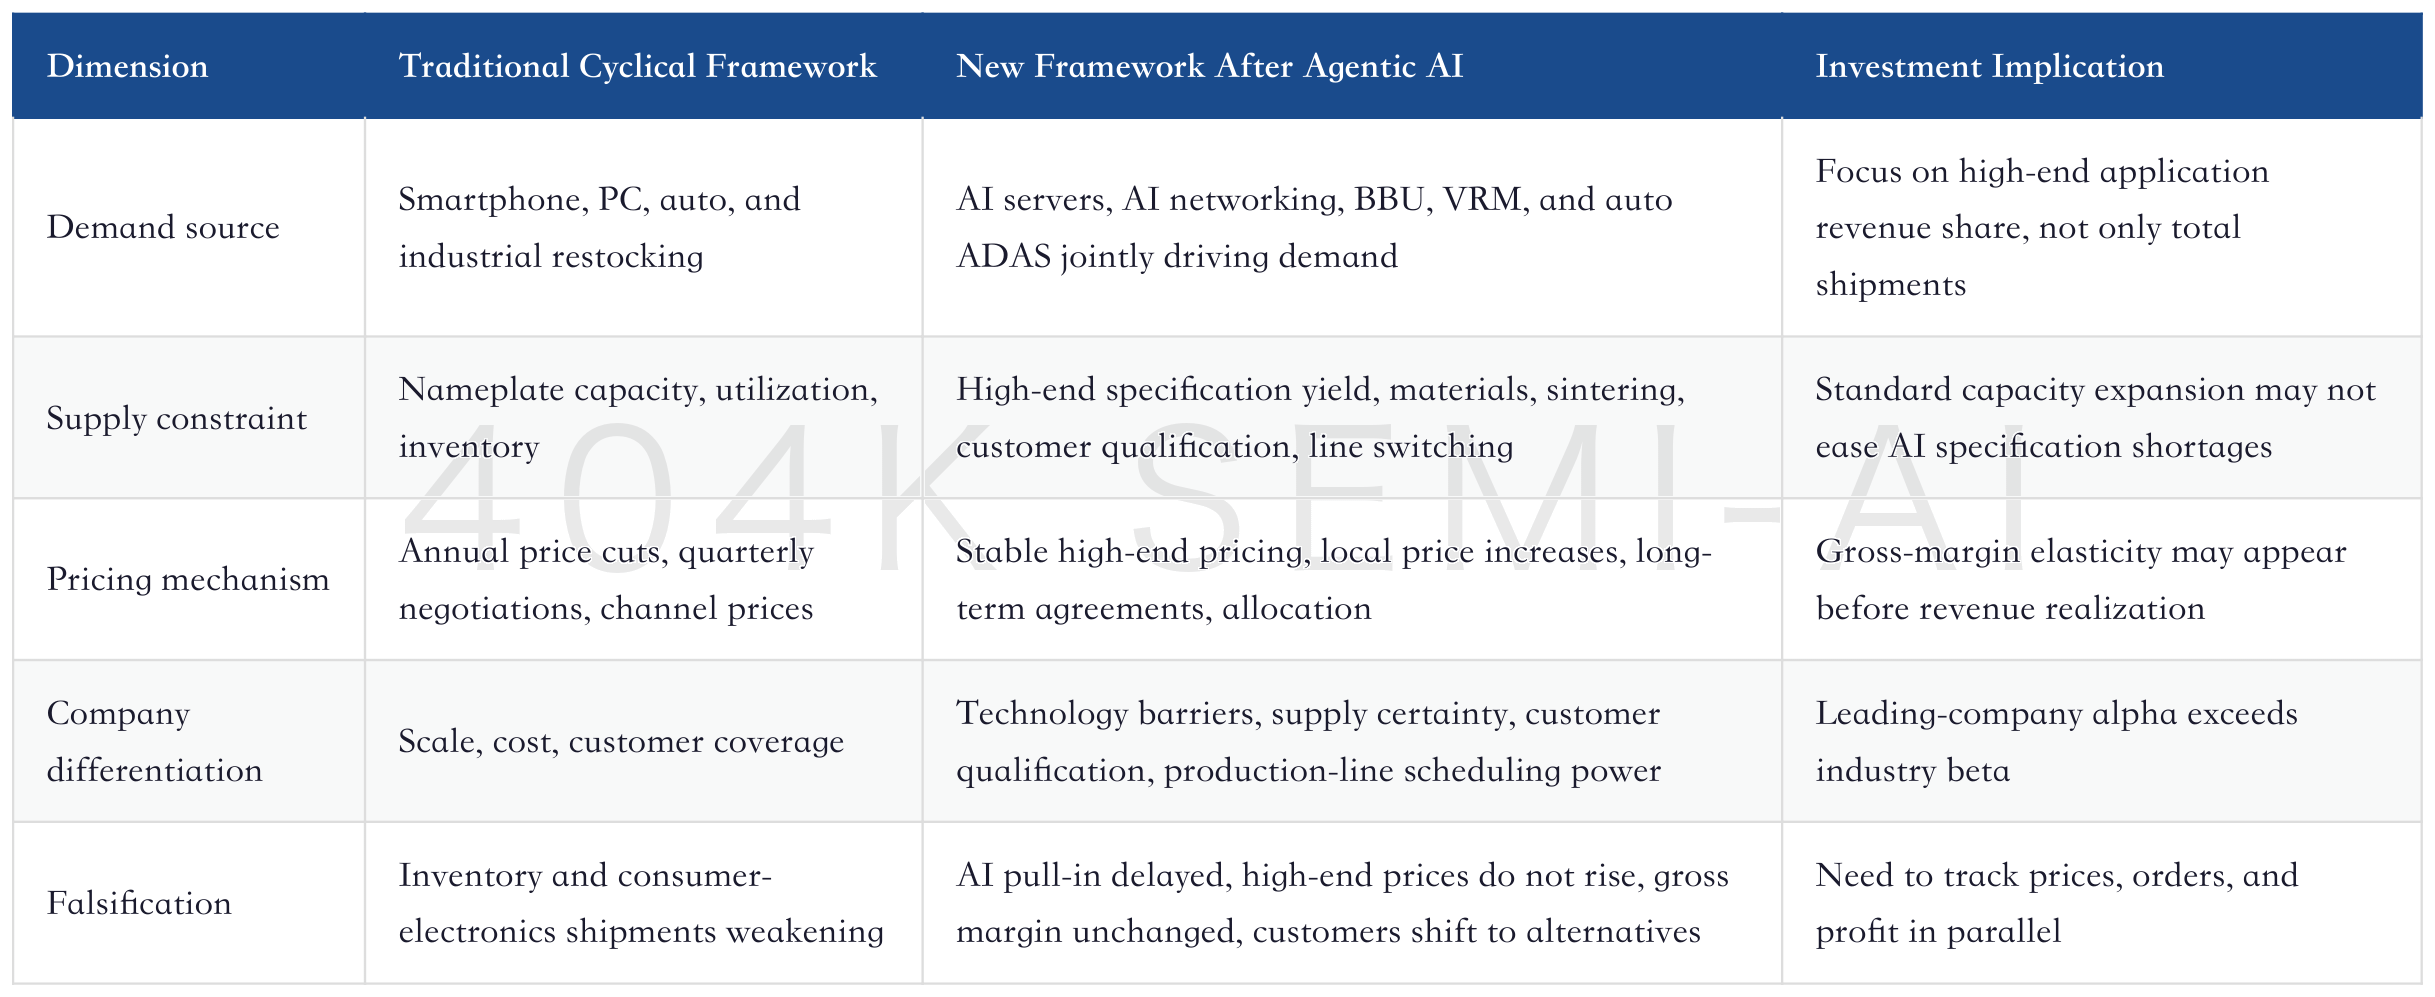
The new information in UBS’s July APAC technology strategy is important. The report lists Agentic AI as the key inflection point for AI adoption in 2026, prefers memory, WFE, OSAT, and server ODMs, and maintains a Neutral view on MLCC. This “industry Neutral, stock-level elasticity” stance is exactly why MLCC can no longer be summarized simply as an “AI beneficiary.” The overall industry is no longer cheap, and standard MLCC remains constrained by consumer electronics and valuation. But there is still new evidence for high-end specifications, FC-BGA resonance, and upstream materials.
The real change is that MLCC has moved from a “substitutable small component” to “low-cost insurance for high-end systems.” In an AI rack, a capacitor is not expensive, but it is responsible for decoupling, filtering, transient response, and power stability. The higher the power consumption of GPUs, CPUs, ASICs, HBM peripherals, power modules, and networking chips, the higher the requirements for consistency, lifespan, and reliability in high-end MLCCs. Saving a few hundred dollars in BOM cannot cover the cost of one outage or repair.
MLCC Deep Dive: JPMorgan Sharply Upgrades, From Cyclical Recovery to Structural Revaluation as AI Servers Rewrite the Supply-Demand Gap
The core question is not proving that MLCC belongs to AI, but answering three harder questions. First, can high-end effective capacity keep up with the combined demand from AI servers and automotive electronics? Second, can pricing transmit from spot and channel markets to direct-customer contracts at leading companies? Third, which companies can convert price increases, product mix, and customer qualification into profit, rather than only enjoying share-price beta?
2. Agentic AI Pushes MLCC from Server Motherboards to Rack Systems
AI server demand for MLCC is not a single-point driver. It starts from GPU boards and continues to spread to CPUs, ASICs, HBM peripherals, VRM, power modules, BBU, switches, network interfaces, optical-module interfaces, backplanes, and rack power systems. In other words, MLCC demand is not as simple as “server units multiplied by component count.” Instead, three layers are upgrading simultaneously: the individual server, the AI cluster network, and rack power delivery.
The hardware value migration in the Rubin era already points in this direction. GPUs remain the largest value pool, but incremental value is spreading from a single chip into memory, PCB, CPO, ABF, connectors, power delivery, and thermal management. MLCC still accounts for a low share of full-rack BOM, but the increase in value per rack is large enough because it follows power density, not traditional consumer-electronics shipments. The higher the power density, the closer decoupling and filtering move to the load, and the more high-end MLCC resembles a “ticket to system reliability.”
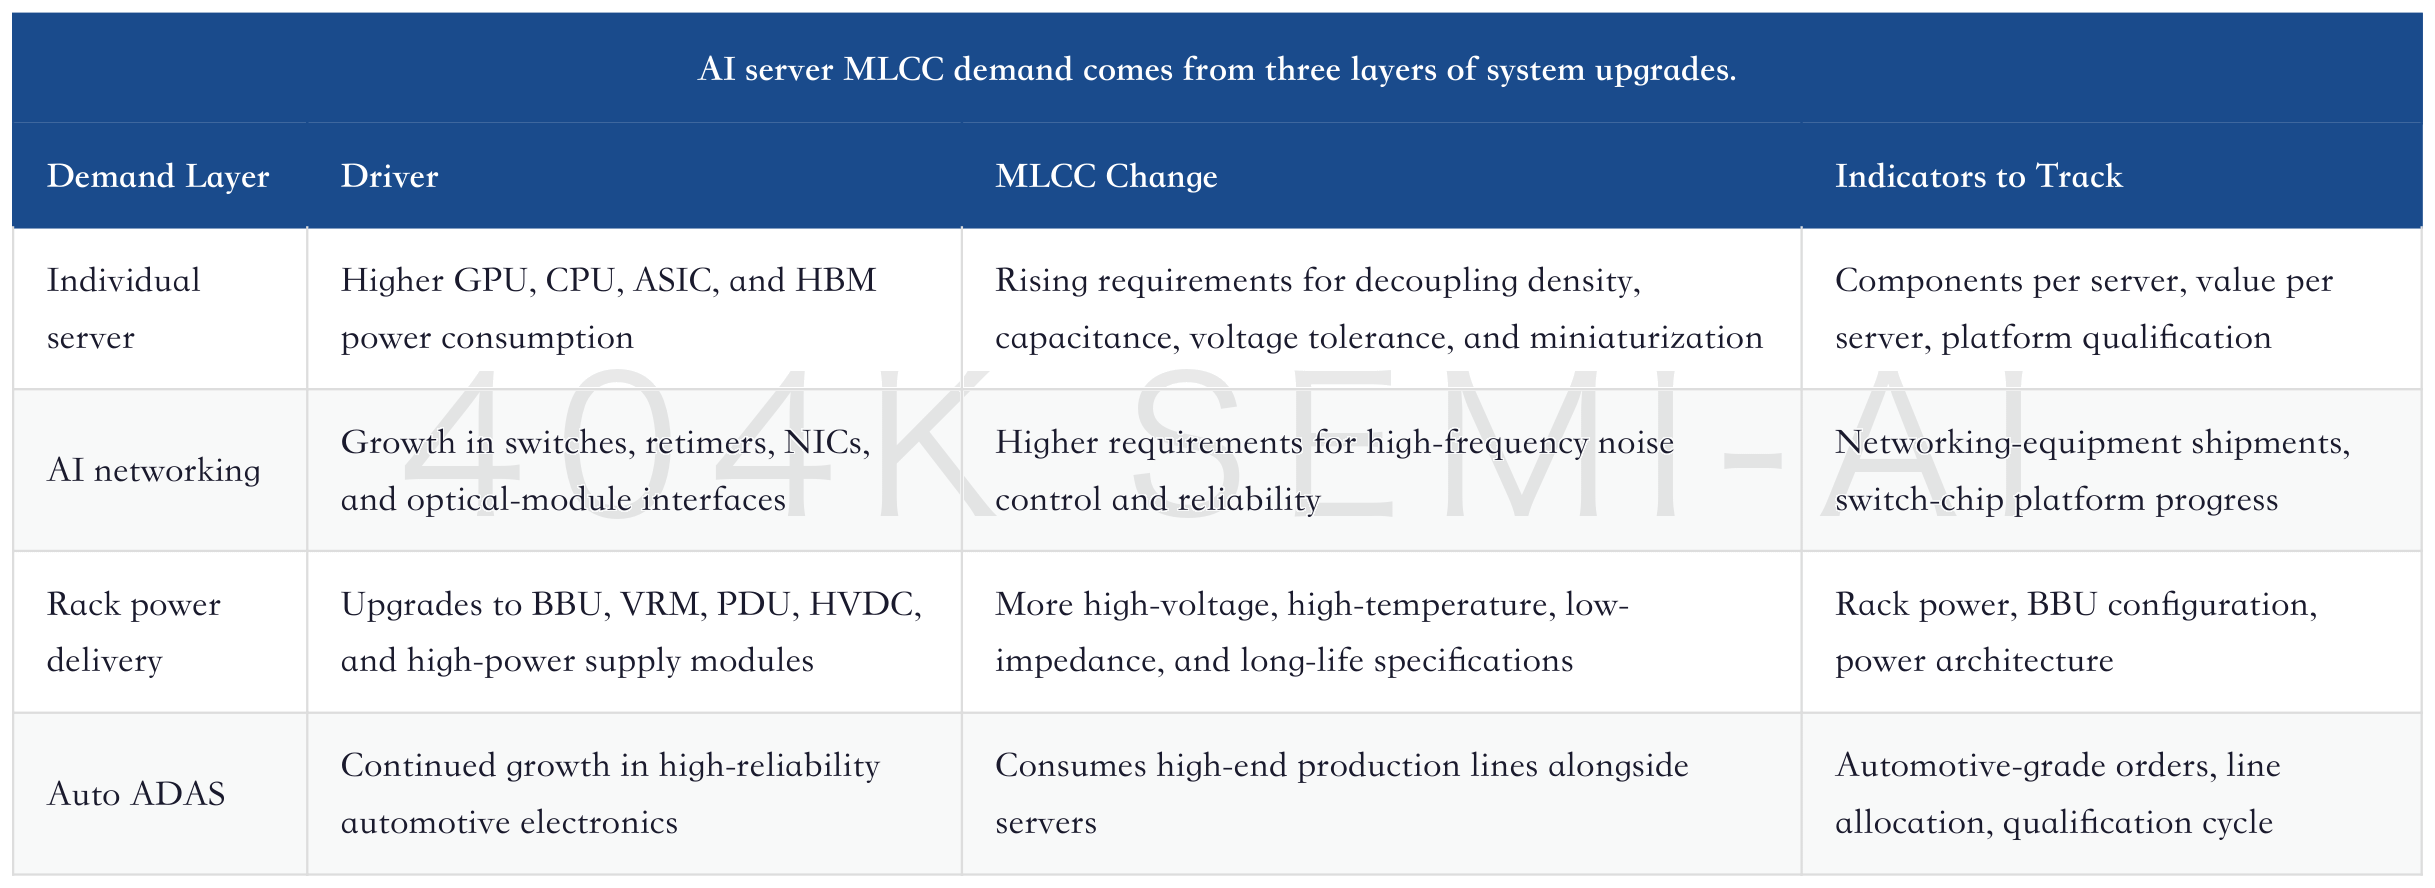
JPMorgan’s late-June Asia passive components, PCB/CCL, substrate, and testing materials put this more directly: the AI server MLCC TAM is in a high-growth phase, high-end MLCC capacity consumption is far above that of standard specifications, and MLCC demand continues to rise from Blackwell to Rubin compute trays. This is consistent with UBS’s July strategy: Agentic AI is not only driving HBM, but tightening every layer of the hardware system.
AI Hardware Deep Dive Update: How PCB, CPO, and MLCC Become the Three Physical Gates of Rubin Racks
This is also why MLCC cannot be analyzed only through smartphone recovery. Smartphone recovery can improve utilization for standard specifications, but AI servers determine pricing discipline for high-end specifications. Automotive ADAS can support high-reliability demand, but AI racks determine incremental elasticity. Networking equipment can broaden the demand boundary, but the final question is still who can reliably deliver high-capacitance, high-voltage, miniaturized products. MLCC industry beta comes from supply-demand, while alpha comes from specifications and customers.
III. The Key to the Supply Gap Is Not Nominal Capacity, but Capacity Derating
Global nominal MLCC capacity is very large. Looking only at total unit output, AI servers seem unlikely to change industry-wide supply and demand. The problem with that view is that it treats all MLCCs as homogeneous products. MLCCs used in ordinary smartphones, home appliances, PCs, automotive, industrial applications, and AI servers differ substantially in materials, size, capacitance, voltage resistance, reliability, yield, and customer qualification. High-end products cannot be ramped immediately by simply switching over ordinary production lines.
J.P. Morgan’s long-term supply-demand model for Asian MLCCs provides a highly useful framework: the industry moves from roughly 10% oversupply in 2025 to roughly 6% shortage in 2028; industry TAM is expected to exceed US$30 billion in 2025-2028, with a CAGR of about 24%; ASPs have upside potential in the high-50% range over the same period. More important than these numbers is the reason: server and automotive demand is increasing the share of large-size, high-capacitance, high-voltage, and high-reliability products, causing effective capacity to fall below nominal capacity.
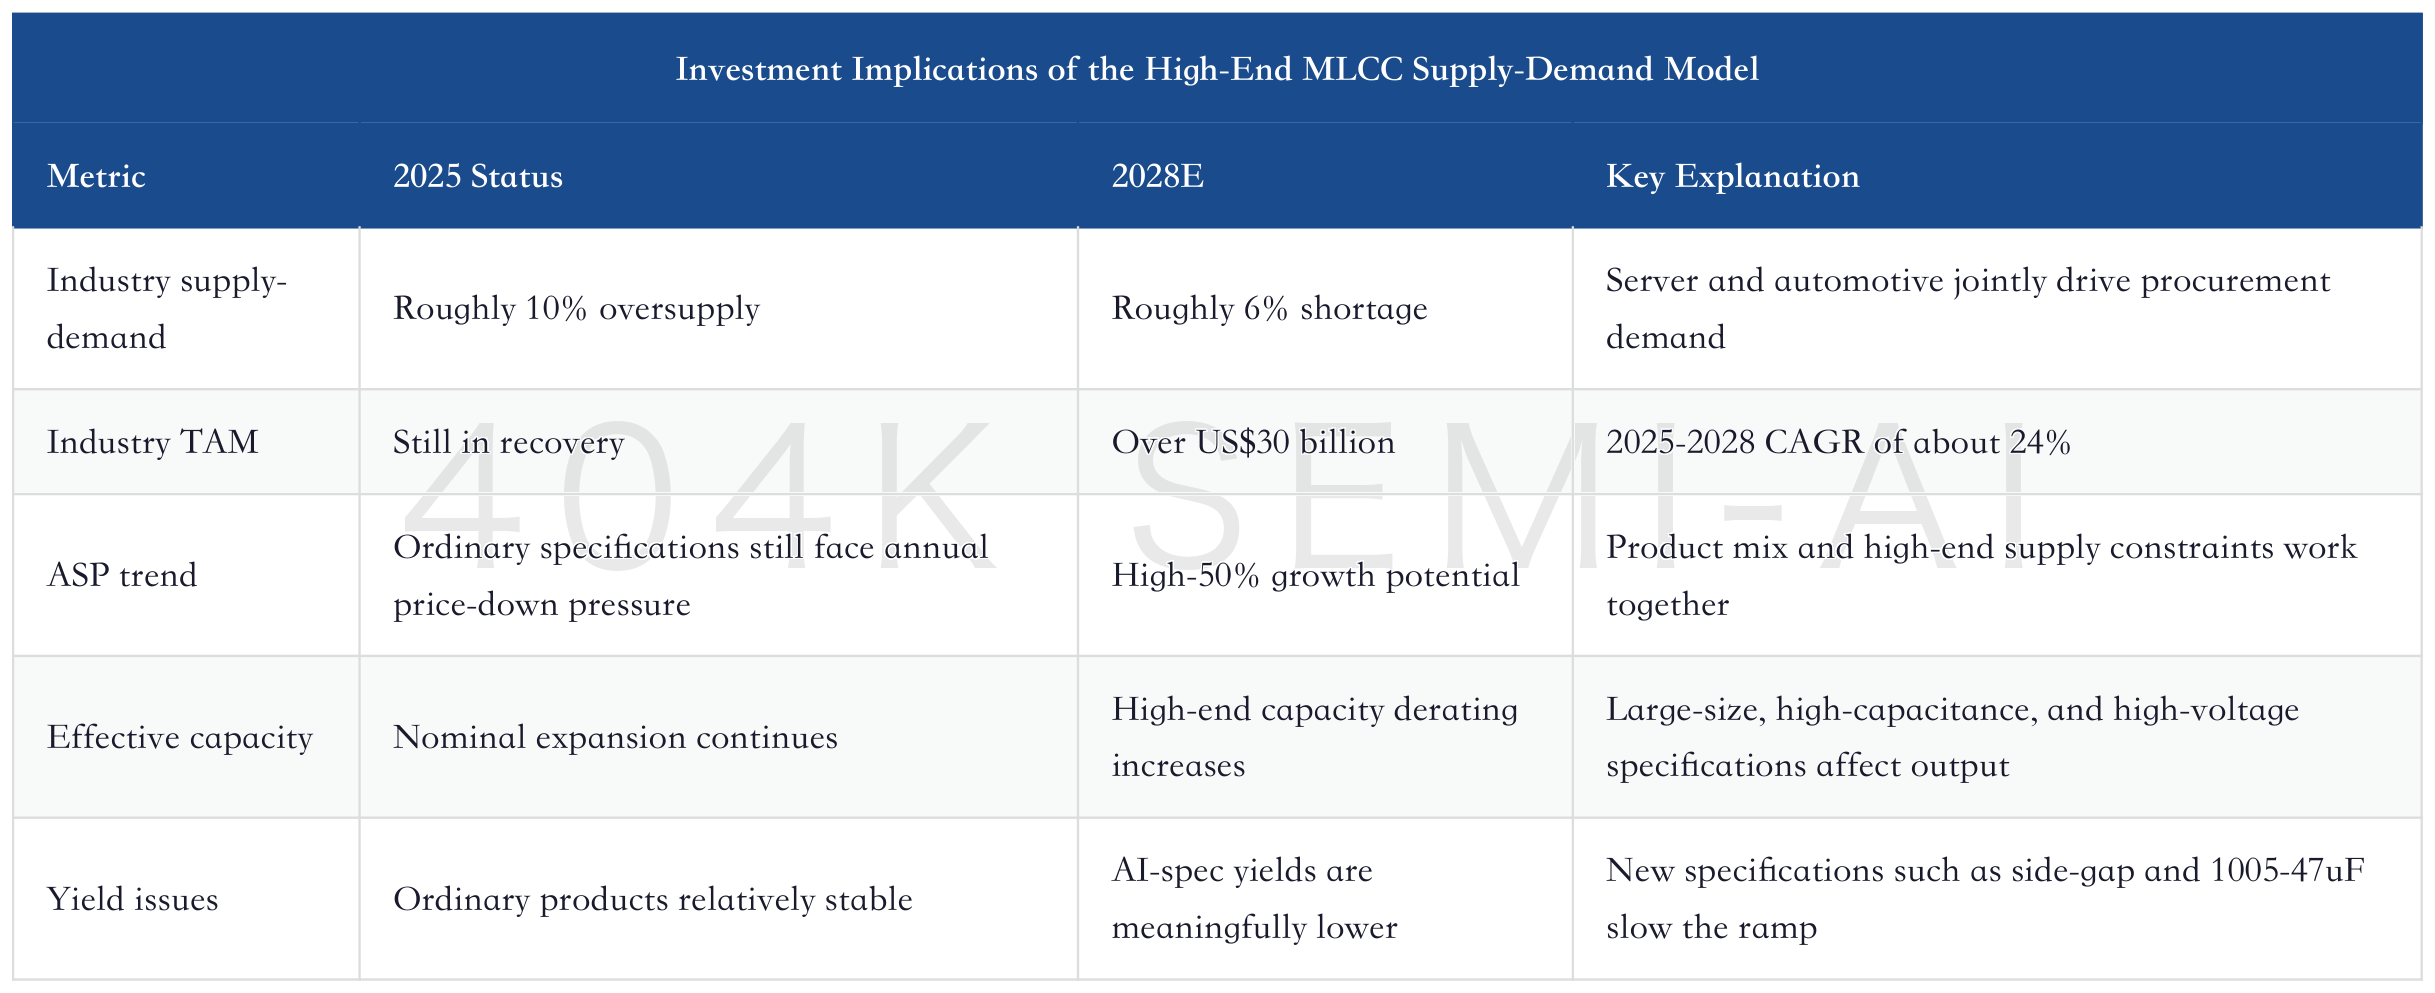
The supply bottleneck for AI server-grade MLCCs can be broken into four layers. The first is materials: ceramic powder particle size, purity, consistency, and electrode materials determine the underlying capability for high-capacitance miniaturization. The second is process: thinning, stacking, sintering, terminal electrodes, and plating all affect consistency. The third is yield: the more complex the high-end specification, the fewer deliverable products each production line produces. The fourth is qualification: AI server customers will not quickly switch to unvalidated suppliers simply because of short-term shortages.
The side-gap construction and 1005-47uF AI server specifications mentioned by J.P. Morgan are typical examples of capacity derating. They are not ordinary SKUs in traditional consumer electronics, but products designed for higher power, higher voltage, and placement closer to the load. Lower assembly yields for high-end products than ordinary products mean that the industry may appear to be expanding capacity, while actual supply growth available for AI servers is much slower.
This is also why “nominal capacity growing about 10% annually” does not imply that “high-end MLCCs will not be in shortage.” If the product mix migrates from ordinary IT specifications to servers and automotive, nominal capacity will be consumed by large-size, high-capacitance, and high-voltage specifications. Capacity derating turns demand growth into pricing elasticity, especially in scenarios where customers are willing to pay for supply certainty.
The supply gap also creates a second-order effect: once high-end specifications occupy production lines, supply of low- and mid-capacitance MLCCs may also tighten. This is where Yageo’s investment logic sits. It may not directly capture all the profits from the highest-end AI server MLCCs, but when high-end capacity is absorbed by cloud AI, spot prices, lead times, and direct-customer pricing for standard MLCCs and low- to mid-capacitance MLCCs all improve. This spillover effect is why Taiwan’s leading passive-component companies are easier for the market to reprice than single high-end suppliers.
IV. Pricing Mechanism: Not Broad-Based Price Hikes, but High-End Specifications Escaping Annual Price-Downs
Historically, MLCCs have often been treated as standard components subject to annual price reductions. Smartphone and PC customers have strong bargaining power, supply of ordinary specifications is ample, and annual price declines are the industry norm. The most important change in this cycle is not that all MLCCs are rising in price together, but that high-end specifications are starting to escape the inertia of annual price-downs. High-reliability specifications for AI servers, automotive ADAS, data-center power, and networking equipment are in a position to secure stable pricing, long-term contracts, allocation, and selective price increases.
UBS’s July strategy forecast for Samsung Electro-Mechanics brings pricing, product mix, and the FC-BGA dual cycle into one income-statement framework. What it really illustrates is that high-end MLCC is not just about revenue growth; pricing discipline and yield constraints can amplify the change into OPM.
Yageo’s pricing signal is more spillover-oriented. Morgan Stanley observed that spot prices for low- and mid-capacitance MLCCs of 1uF and below, such as 0201 and 0402, have already risen meaningfully, with large increases in some SKUs; some direct-customer prices have also seen selective increases of about 30%. Pricing for high-capacitance products has been more restrained: 10uF-22uF has already moved higher, while 47uF and above remains relatively stable, though lead times have started to lengthen. This structure matters: tightness in high-end specifications often shows up first through allocation and lead times, while low- and mid-capacitance specifications are more likely to show pricing elasticity first in the spot market.
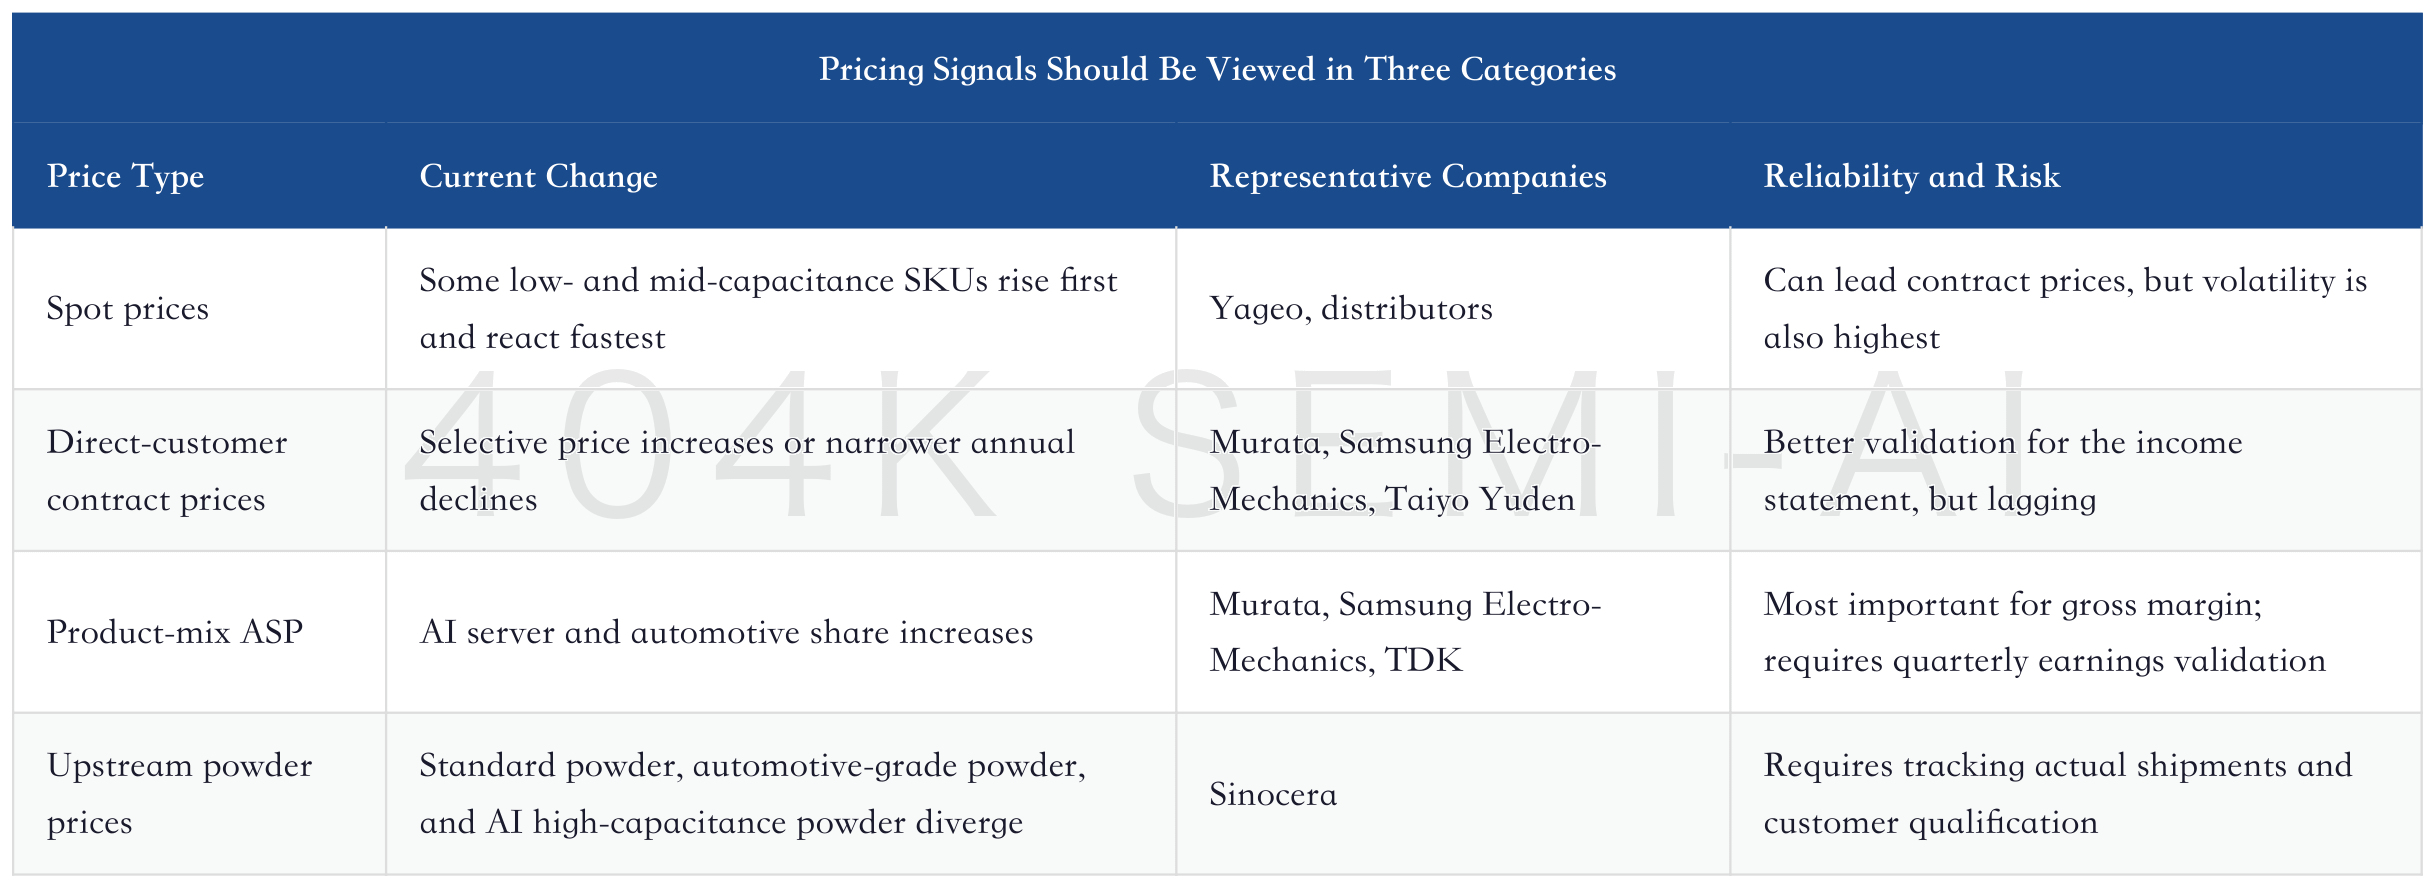
Citi’s upgrade of Murata is also not a simple bet on broad industry price hikes. Citi raised its target price for Murata to JPY 15,000, with the core rationale being higher AI server unit demand and higher high-end MLCC ASPs. Its FY3/27-FY3/29 operating profit forecasts were raised to JPY 440 billion, JPY 630 billion, and JPY 800 billion, respectively. The report explicitly states that current assumptions do not depend on broad price hikes for ordinary products; a price increase of more than 10% across the full product line would be an additional upside scenario. This distinction is crucial: Murata’s main thesis is mix improvement from high-end AI specifications, not low-end pricing rumors.
Murata Manufacturing Deep-Dive Update: Citi Target Price of JPY 15,000, and How AI Server MLCC Revalues the Profit Slope
Therefore, the pricing framework should be viewed as follows: spot prices move first, indicating that the supply chain is beginning to tighten; lead times lengthen, indicating that customers are starting to compete for allocation; direct-customer contract prices change, indicating that supplier bargaining power is rising; gross margin improves, indicating that the cycle has entered the income statement. As long as the cycle remains in the first two steps, it is still an expectations trade; only when contract prices and gross margin are visible does it become industry delivery.
V. Company Ranking: Murata Is the Pricing Anchor, Samsung Electro-Mechanics Offers Dual-Cycle Upside, and Yageo Captures Spillover
This MLCC cycle should not be ranked simply by “who rises the most.” A more useful framework has three groups: first, the technology anchors for high-end AI server specifications, represented by Murata Manufacturing and Samsung Electro-Mechanics; second, beneficiaries of AI crowding-out effects and standard MLCC spillover, represented by Yageo; third, diversified electronic-component platforms, represented by TDK and Taiyo Yuden. Revenue elasticity, margin elasticity, and valuation risk differ materially across companies.
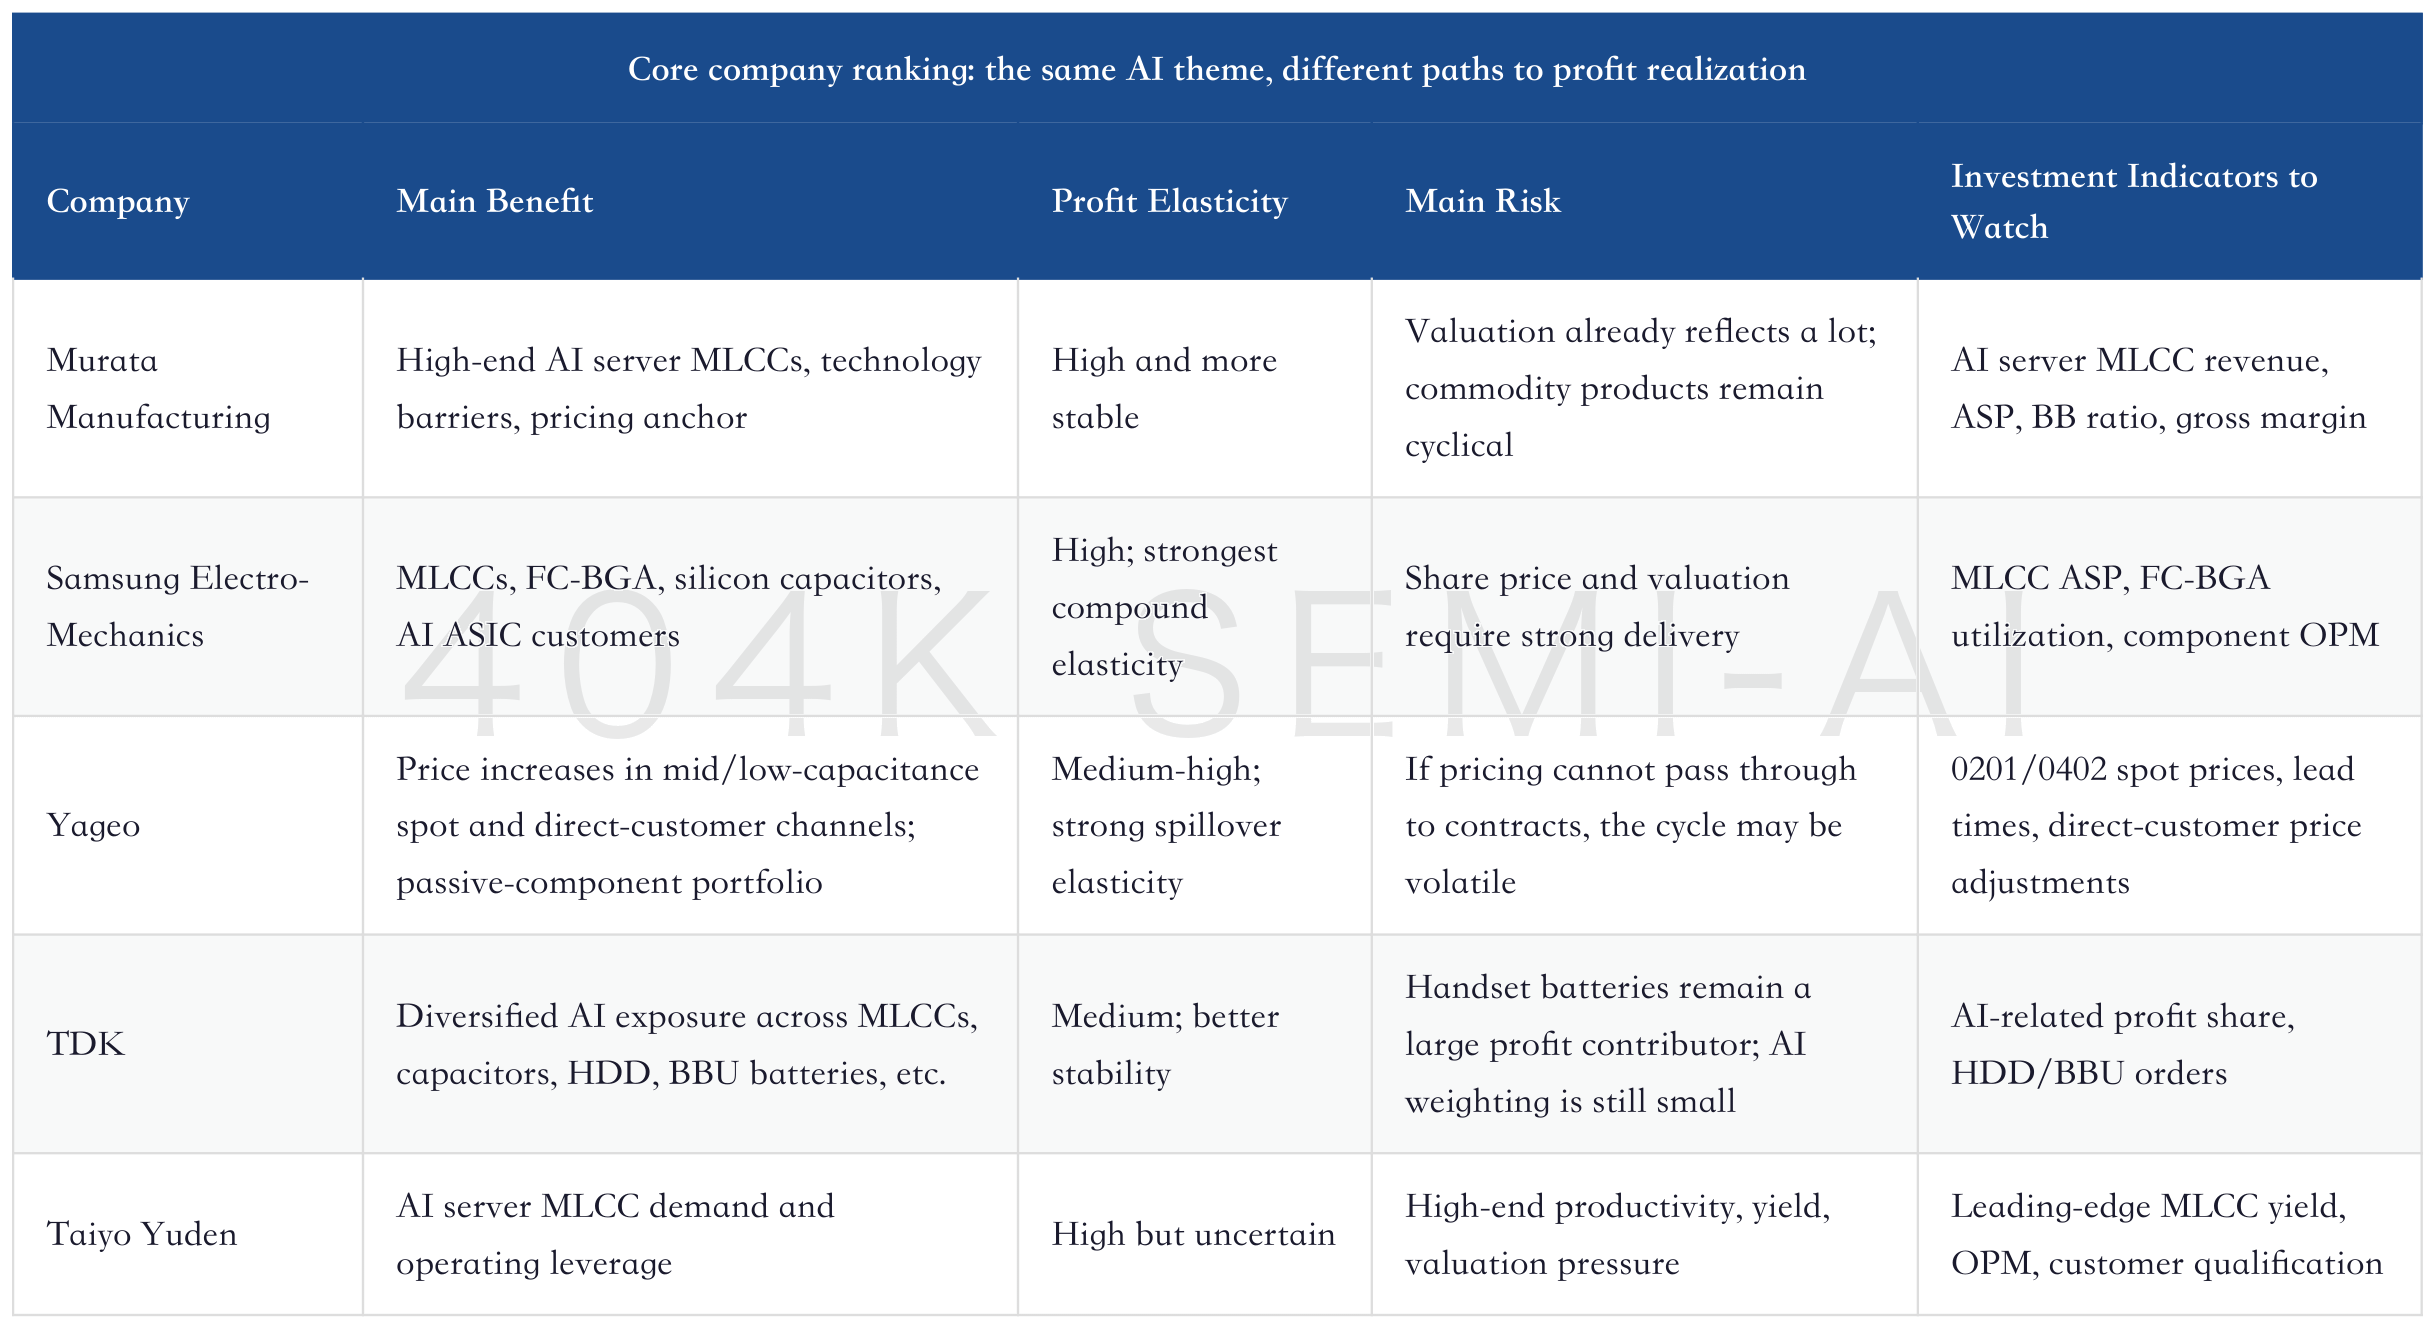
Murata Manufacturing is the clearest pricing anchor. Its advantage is not only market share, but also materials, process technology, yield, customer qualification, and mass-production stability for high-end specifications. Citi’s key assumption in upgrading Murata is that AI server MLCC product-mix improvement will drive roughly 14% ASP growth in FY3/27, with operating profit entering an accelerated growth phase in FY3/27-FY3/29. What is truly worth tracking for Murata is not whether ordinary MLCCs rise in price, but whether high-end AI server MLCCs can continue to lift unit prices and margins.
Samsung Electro-Mechanics is a higher-beta compound asset. UBS’s earlier report had already positioned Samsung Electro-Mechanics as being in the early stage of a multi-year MLCC/FC-BGA upcycle, and its July strategy further raised profit assumptions for AI server MLCCs and FC-BGA. Samsung Electro-Mechanics’ advantage is that it is not a pure MLCC company. AI server customers need MLCCs, ABF/FC-BGA, and potentially silicon capacitor solutions in the future. If AI ASIC, server CPU, and networking customers ramp volume, its profit elasticity will be steeper than that of pure MLCC companies.
