
Microsoft and Meta Earnings Deep Dive: The AI Capex Race, Cloud and Advertising Monetization, and Diverging Margins
目录
Executive Summary
Earnings at a Glance: Strong Growth for Both, but Very Different Cash-Flow Implications
Microsoft: Azure Moves from “Very Strong Demand but Insufficient Supply” to Revenue Acceleration
Copilot: 30 Million Paid Seats Are Only the Beginning; the Real Value Lies in Enterprise Pricing Architecture
Microsoft Margins: AI Infrastructure Has Not Eroded Operating Leverage
Meta: AI Has Materially Improved Advertising, but Investment and One-Time Charges Obscure the Income Statement
Meta’s Real Debate: Beyond Advertising, What Can Support $130–145 Billion in Capital Expenditures?
Sell-Side Divergence: Meta’s Target-Price Dispersion Essentially Reflects the Discount Applied to Long-Term Optionality
Both Are AI Platforms, but Microsoft and Meta Sell Two Different “Outcomes”
Which Metrics Matter Over the Next Four Quarters
Final Assessment: Microsoft Has Entered the AI Return-Validation Phase, While Meta Remains in the AI Asset-Building Phase
本内容基于公开资料和研报数据整理,不构成任何投资建议,不代表任何个人观点,仅供学习参考,请理性阅读
Both companies are investing tens of billions of dollars in AI. Microsoft has already demonstrated returns through cloud revenue and enterprise seats, while Meta is entering a more demanding validation period between advertising growth and free cash flow.
Executive Summary
Microsoft’s most important development this quarter is that, for the first time, its AI investment has created a closed loop across Azure, Copilot, and margins. Fiscal Q4 2026 revenue reached $90.007 billion, up 18% year over year; Azure and other cloud services revenue grew 43%, accelerating 4 percentage points from the previous quarter; and paid Microsoft 365 Copilot seats exceeded 30 million, with approximately 10 million net additions during the quarter. More importantly, operating margin still reached 45.1%, indicating that incremental computing capacity is no longer merely a balance-sheet construction project but is converting into revenue, bookings, and profit.
Meta has likewise demonstrated that AI can strengthen its existing advertising business, but it has not yet demonstrated that massive capex can create a sufficiently large second revenue stream beyond advertising. Q2 revenue reached $60.801 billion, up 28% year over year; ad impressions increased 14%, average price per ad rose 12%, and Advantage+ exceeded $75 billion in annualized revenue. At the same time, quarterly capex, including principal payments on finance leases, reached $31.08 billion, while free cash flow was only $784 million. The core advertising business remains very strong, but the cash payback period has lengthened materially.
The central difference between the two companies is Microsoft’s shorter path to monetization. Microsoft sells computing capacity directly to Azure customers, then embeds AI into enterprise workflows through Microsoft 365 Copilot, GitHub, and Dynamics, enabling revenue to be realized progressively through cloud consumption, seats, and higher-priced suites. Meta first uses computing capacity to improve recommendations and advertising conversion, then develops personal agents, business agents, model APIs, subscriptions, and direct sales of computing capacity. These latter opportunities remain in the product-validation stage.
Microsoft’s key risk is whether high growth can offset depreciation and capacity expansion, while Meta’s key risk is that capex may grow faster than its new revenue streams mature. Microsoft’s capex this quarter, including finance leases, was approximately $41 billion, but operating cash flow reached $55.441 billion, providing relatively ample cash-flow coverage. Meta narrowed its 2026 capex guidance to $130 billion–$145 billion, and multiple institutions expect another substantial increase in 2027. If external AI revenue is delayed, negative free cash flow may persist for longer.
From a valuation perspective, Microsoft is closer to “high visibility and a shorter payback period,” while Meta is closer to “a strong core business financing long-dated optionality.” Price targets for Microsoft in this batch of research reports are concentrated at $570–$640, primarily based on strong Azure growth, accelerating Copilot adoption, and earnings growth above 20%. Meta price targets range from $640–$800, reflecting materially wider disagreement. The key differentiator is not advertising forecasts, but differing assumptions about 2027–2028 capex, free cash flow, and the probability of monetizing new products.
Earnings at a Glance: Strong Growth for Both, but Very Different Cash-Flow Implications
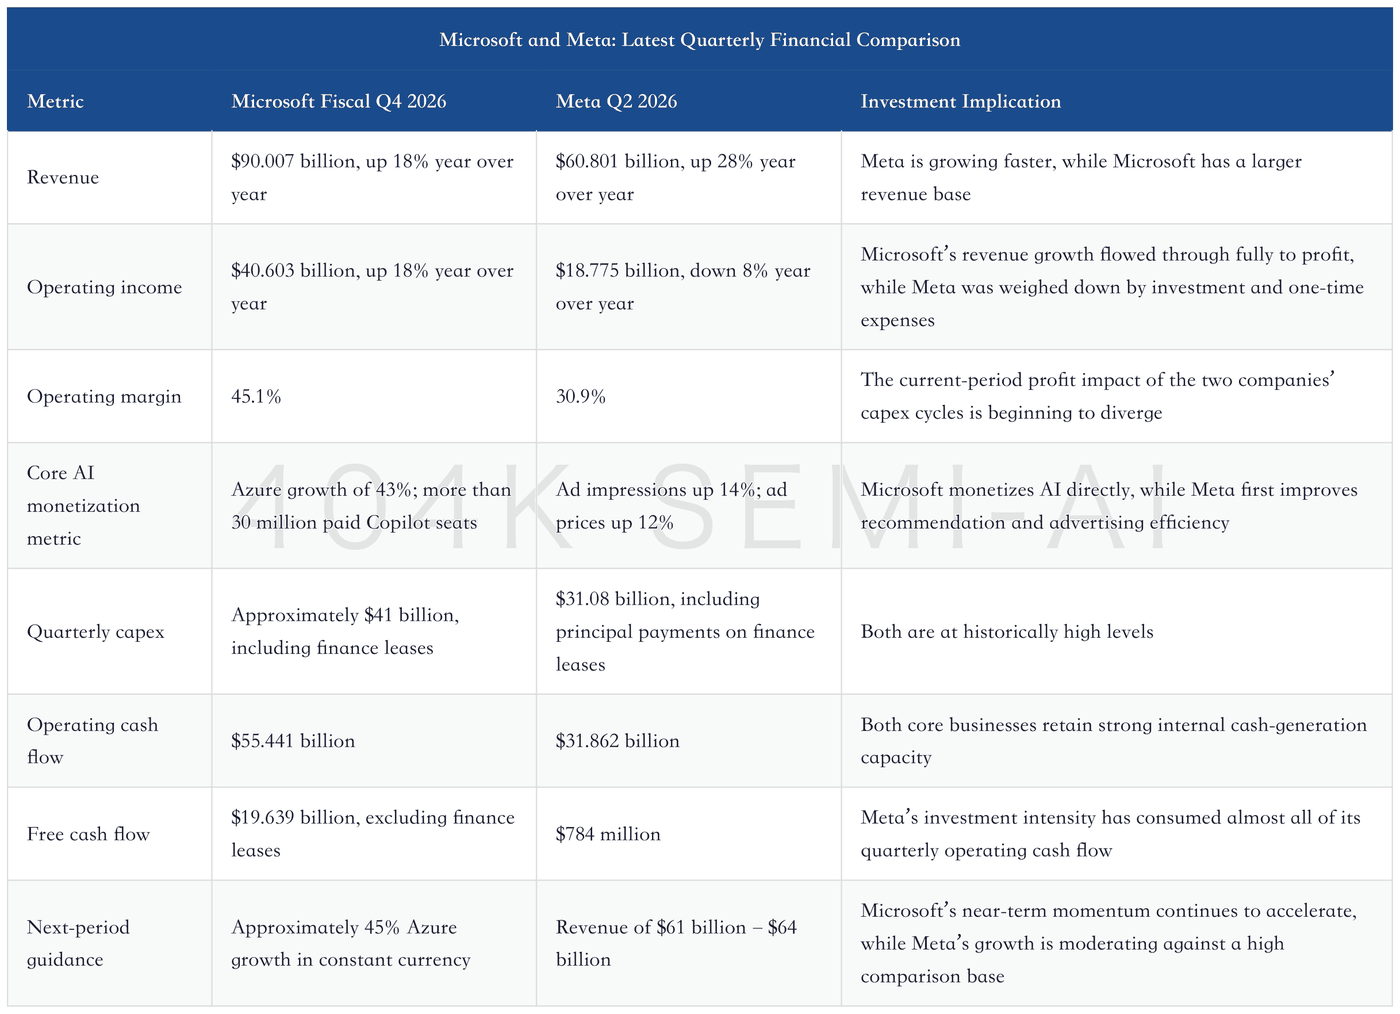
This table can easily create a misleading impression: that Microsoft is simply “more profitable than Meta.” The more important distinction is the length of each company’s path from incremental computing capacity to revenue. Microsoft’s incremental GPUs can begin serving Azure training and inference workloads as soon as they come online, while also driving consumption of platform services and enterprise software. Meta’s incremental GPUs initially support internal recommendations, ad ranking, and product development. Part of the return is reflected in advertising revenue, while the remainder will emerge only after personal agents, business agents, model APIs, or computing services mature.
Capex alone therefore does not indicate overinvestment. What matters is the time lag between incremental capex and incremental revenue, gross profit, and cash flow. Microsoft demonstrated a shorter lag this quarter, while Meta is explicitly asking investors to accept a longer payback period.
Microsoft: Azure Moves from “Very Strong Demand but Insufficient Supply” to Revenue Acceleration
The central debate around Microsoft in recent quarters was not whether customers needed AI, but whether data-center and GPU capacity could come online quickly enough. Demand exceeding supply can produce impressive booking figures without immediately converting into revenue. This quarter, Azure and other cloud services revenue grew 43%, accelerating 4 percentage points from the previous quarter and exceeding market expectations by approximately 3 percentage points. This signals that capacity expansion is genuinely beginning to translate into revenue.
Microsoft Cloud revenue reached $59.3 billion, up 27% year over year, while commercial remaining performance obligations reached $678 billion, up 84%. Remaining performance obligations do not equal near-term revenue and include large, long-duration contracts with customers such as OpenAI. Nevertheless, they demonstrate that customers are willing to commit to Microsoft’s cloud and AI capabilities over a longer time horizon. Compared with quarterly revenue, the backlog provides a better answer to one question: whether current data-center construction is supported by genuine demand. Microsoft’s answer is yes.
Goldman Sachs’ report highlighted two efficiency improvements in particular. First, the time from GPU delivery to deployment has been reduced by nearly 50%, allowing the same equipment to begin generating revenue sooner. Second, Microsoft is improving the economics of each unit of computing capacity through its model mix, internal chips, software and hardware optimization, and pricing design. Enterprises do not need the most expensive frontier model for every request. Simple tasks can be routed to smaller or lower-cost models, while complex tasks use more capable models. For Microsoft, this means the same infrastructure can serve more workloads while maintaining customer experience and gross-margin objectives.
This is why Microsoft’s AI thesis is shifting from “buying more GPUs” to “increasing the revenue and output generated by each GPU.” Looking only at capex, Microsoft’s additions to property and equipment reached $115.948 billion in fiscal 2026, nearly 1.8 times the prior-year level. However, full-year revenue grew 18% to $331.839 billion, operating income increased 21% to $155.237 billion, and operating cash flow reached $182.935 billion. The asset base is expanding rapidly, but profit and cash flow are expanding alongside it.
Copilot: 30 Million Paid Seats Are Only the Beginning; the Real Value Lies in Enterprise Pricing Architecture
Paid Microsoft 365 Copilot seats exceeded 30 million, versus more than 20 million in the previous quarter, representing approximately 10 million additions in a single quarter. This was materially above the approximately 6 million–8 million previously expected by multiple institutions. The significance of this figure lies not only in the number of seats but also in the doubling of the incremental adoption rate. The hardest stage for enterprise AI products is typically not the trial phase, but the transition from small departmental pilots to organization-wide deployment. 10 million net additions in a single quarter indicate that purchasing decisions are crossing this threshold.
Microsoft’s enterprise AI revenue can be divided into three layers. The first consists of standalone Copilot seats, for which customers pay per user. The second comes from enterprises upgrading to higher-priced suites such as E5 and E7, where AI is bundled with security, compliance, and data governance. The third is usage-based pricing: as agents within Copilot, GitHub, and Dynamics begin executing more tasks, revenue no longer depends solely on user numbers but also on workload volume.
Goldman Sachs characterized this shift as enterprises moving from choosing a “frontier model” to choosing a “frontier ecosystem.” Customers do not want to select a model manually for every task, nor do they want to assemble different models, permissions, data, and security systems themselves. Microsoft’s advantage is that it already controls identity, productivity data, development tools, cloud resources, and enterprise distribution channels. Model capabilities remain important, but purchasing decisions will increasingly depend on whether the solution can integrate into existing workflows, control permissions, track costs, and reliably produce results.
This explains why Copilot’s valuation significance exceeds its current revenue contribution. It is not only a new software revenue stream; it may also support higher Microsoft 365 suite pricing, increase Azure inference consumption, and raise customer switching costs. If enterprise AI shifts from conversational tools to task execution, Microsoft can charge both software seat fees and cloud-consumption fees.
However, 30 million seats do not yet directly demonstrate long-term retention or unit economics. Three metrics need to be tracked going forward: whether net paid-seat additions are sustained, whether actual usage intensity per seat increases, and whether usage-based pricing can scale without creating customer anxiety over costs. If seat growth continues but active usage stagnates, Copilot may merely be a contractual bundle. If usage grows but relies heavily on high-cost models, inference costs may also offset revenue growth.
Microsoft Margins: AI Infrastructure Has Not Eroded Operating Leverage
Microsoft reported a gross margin of 67.2% and an operating margin of 45.1% this quarter, both above market expectations. Non-GAAP EPS was $4.74, up 23% year over year, including a $0.27 benefit from discrete items; even excluding this benefit, revenue and operating profit still materially exceeded expectations.
The market had been concerned that data-center depreciation, power, networking, and expensive components would keep cloud gross margins under pressure. That concern has not disappeared. Net property and equipment has increased from $204.966 billion a year ago to $313.076 billion, and depreciation will continue to rise. Management expects the fiscal 2027 operating margin to decline by less than 1 percentage point. This does not mean margins will not decline; it means the decline should remain manageable despite such an aggressive investment cycle.
Microsoft can cushion the margin impact for four reasons: accelerating Azure revenue growth is improving infrastructure utilization; Copilot and premium suites are enhancing the software revenue mix; shorter GPU deployment times are reducing idle capacity; and traditional sales and administrative expenses are growing more slowly than revenue. In other words, Microsoft is not generating profits by cutting R&D;—R&D; expenses continue to grow—but is absorbing infrastructure costs through revenue scale and commercialization efficiency.
The risks are also clear. If commercial bookings growth slows materially relative to cloud revenue, it may indicate that some of this quarter’s revenue acceleration came from the release of supply constraints, while new demand did not accelerate at the same pace. If Azure growth falls back below 40% while depreciation continues to rise, margin pressure will become apparent quickly. Investors need to monitor Azure growth, commercial bookings, the duration structure of remaining performance obligations, and cloud gross margin together, rather than focusing on any single metric.
Meta: AI Has Materially Improved Advertising, but Investment and One-Time Charges Obscure the Income Statement
Meta’s second-quarter revenue was $60.801 billion, up 28% year over year and 27% on a constant-currency basis. Advertising revenue was $59.363 billion, up 27% year over year; ad impressions increased 14%, and the average price per ad rose 12%. This means growth was not driven solely by higher ad volumes, but also by better matching, conversion, and pricing.
AI’s contribution to Meta’s core business is already highly tangible. Recommendation models drove double-digit growth in time spent on Instagram globally, while time spent watching video on Facebook increased 9%; ad-ranking and sequence-learning systems increased Facebook ad clicks by approximately 8.3% and conversions by approximately 15.7%; more than 9 million small businesses used at least one AI creative tool, an increase of 1 million from the previous quarter; and Advantage+ exceeded $75 billion in annualized revenue.
These figures answer the question of whether AI benefits Meta’s existing business: the answer is unequivocally yes. AI improves content relevance and increases time spent; longer engagement creates more ad inventory; better ad models increase clicks and conversions, encouraging advertisers to pay higher prices; and creative generation lowers the barrier for small businesses to produce ads, expanding advertiser coverage. For now, Meta’s AI returns are appearing first in a stronger advertising system rather than in revenue from standalone AI products.
Operating profit was $18.775 billion this quarter, down 8% year over year, while operating margin declined from 43% to 31%. However, this included $2.4 billion in legal-related charges and $1.18 billion in restructuring charges. Simply excluding these two items would produce operating profit of approximately $22.355 billion, implying a margin of approximately 36.8%. The year-over-year decline in profit therefore cannot be attributed entirely to AI investment. Even on an adjusted basis, however, the margin remained materially below the prior-year period, confirming genuine pressure from infrastructure, R&D;, and depreciation.
Page 2 of Meta’s official presentation shows that advertising revenue increased from $46.563 billion in the second quarter of 2025 to $59.363 billion this quarter, with growth across all major user geographies. Page 4 more directly illustrates the divergence between revenue and profit: Family of Apps revenue rose to $60.37 billion, but operating profit declined from $24.971 billion a year earlier to $23.394 billion, while Reality Labs continued to generate an operating loss of $4.619 billion. The core business remains a powerful cash-generating engine, but that cash is being reallocated toward higher R&D;, infrastructure, and other expenses.
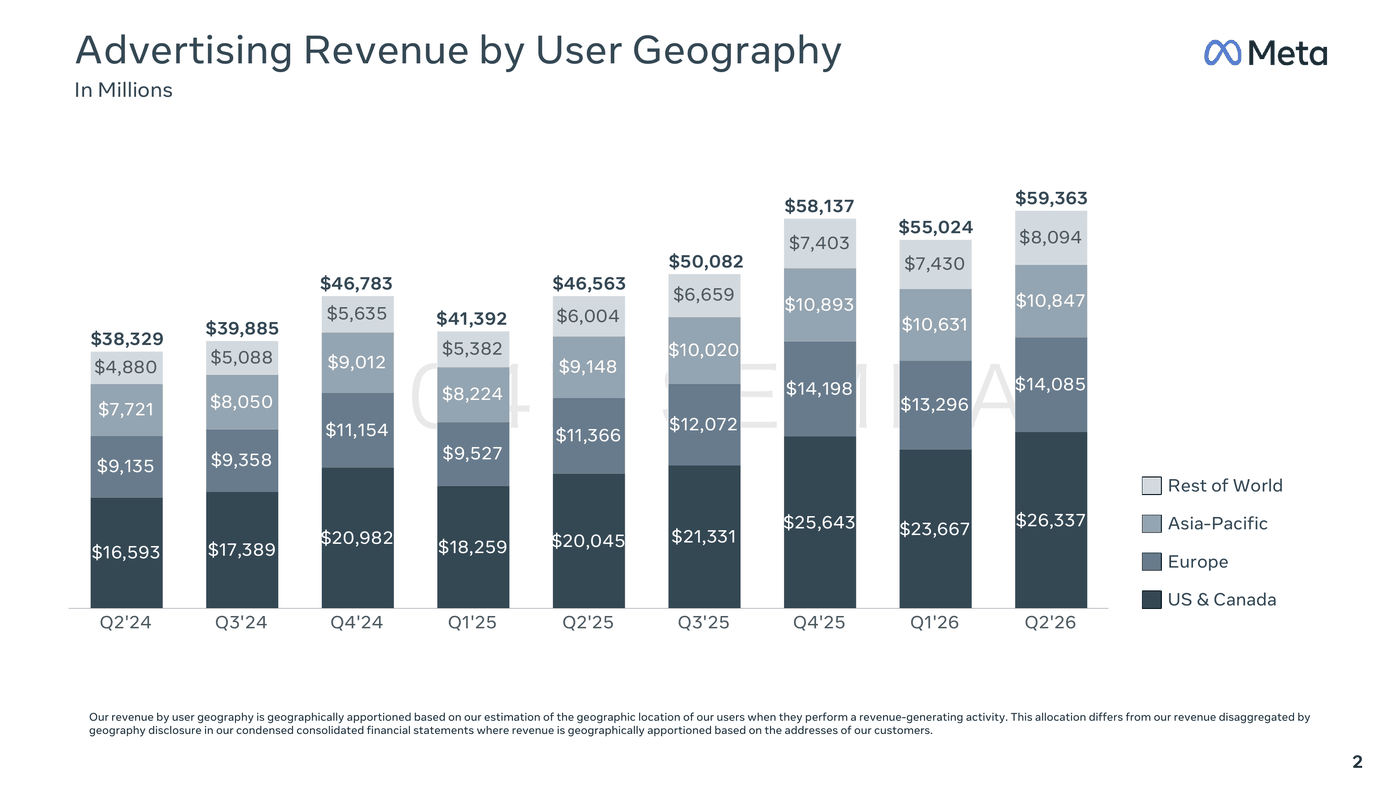
Physical page 2 of Meta’s “Second Quarter 2026 Earnings Presentation,” in units of USD 1,000,000. The chart shows that advertising growth was not driven by a single region, but was broad-based across major geographies.
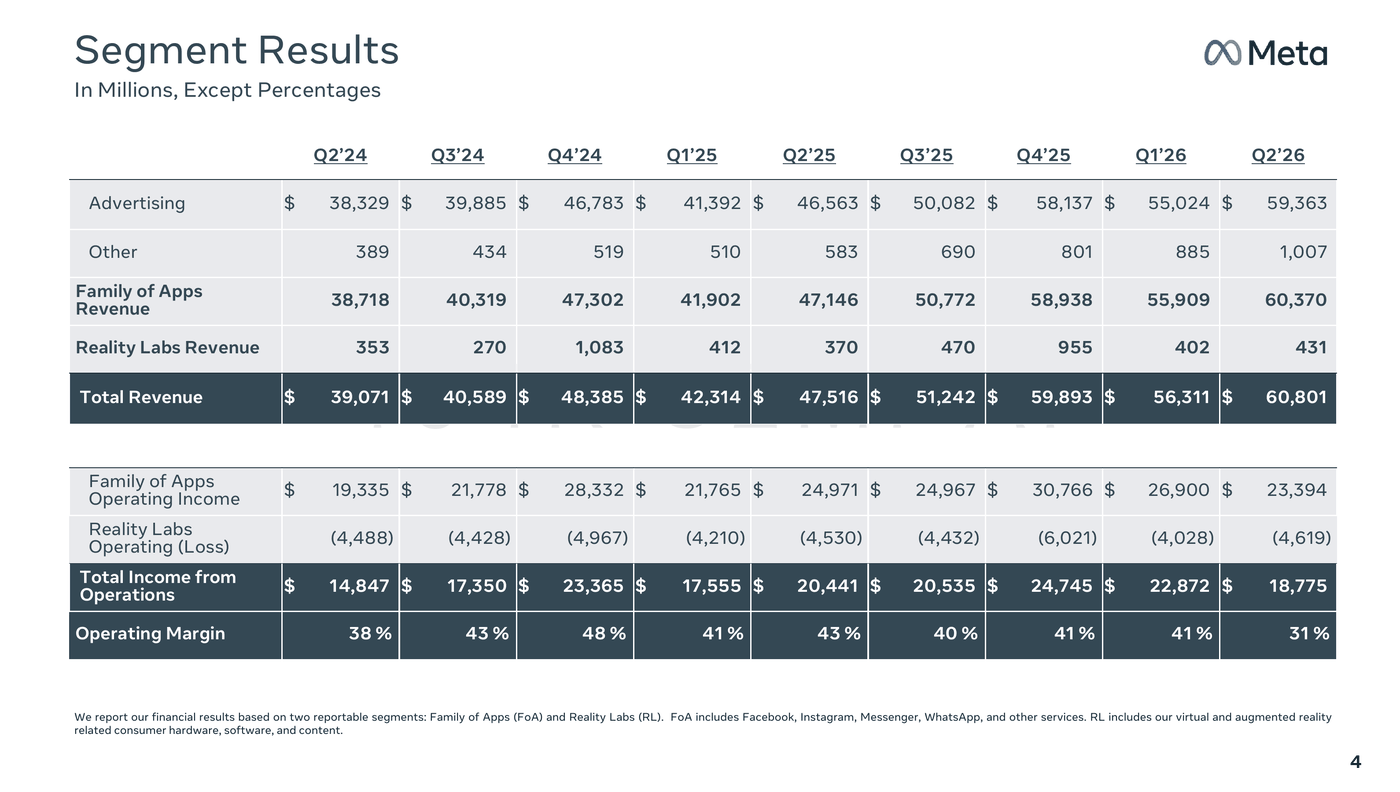
Physical page 4 of Meta’s “Second Quarter 2026 Earnings Presentation,” in units of USD 1000000. The chart shows that Family of Apps revenue continued to grow, while operating profit was affected by expense expansion.
Meta’s Real Debate: Beyond Advertising, What Can Support $130–145 Billion in Capital Expenditures?
Meta narrowed its 2026 capital expenditure guidance to $130–145 billion, raising the lower end of the previous range. Capital expenditures, including principal payments on finance leases, reached $31.08 billion during the quarter; operating cash flow was $31.862 billion, leaving free cash flow of only $784 million. The company also held $90.26 billion in cash, cash equivalents, and marketable securities, but long-term debt had risen to $83.66 billion.
For Meta, continued investment is not an issue of financial capacity, but of return visibility. The core advertising business is sufficient to support near-term investment; the real pressure begins in 2027 and beyond. Citi estimates that Meta’s capital expenditures may reach $205 billion in 2027 and $249 billion in 2028. JPMorgan raised its 2027 estimate to $243 billion and expects free cash flow to be significantly negative in 2027–2028. Institutional estimates vary widely, but the directional conclusion is consistent: if compute infrastructure development continues to accelerate, cash-flow pressure will not end in 2026.
Meta management outlined three categories of potential returns.
The first is continued enhancement of the core business—the most certain source of returns and one that is already materializing. Recommendations, ad ranking, creative generation, and automated campaign placement will all continue to increase advertising revenue. The question is whether advertising-efficiency improvements alone can sustainably cover even larger capital expenditures, given that Meta already generates more than $200 billion in annual revenue; the marginal returns still need to be monitored.
The second is personal agents and consumer products, including Meta AI, smart glasses, new applications, and subscription services. Instagram has reached 2 billion daily active users, while Threads has surpassed 500 million monthly active users. This vast distribution network means new products require almost no customer acquisition from scratch. Morgan Stanley estimates that optionality from compute services, Meta AI search, subscriptions, and model APIs could collectively add approximately $9 to 2028 EPS. However, management has repeatedly described product timelines only as “soon,” and has not yet disclosed revenue scale or paid-conversion metrics.
The third is enterprise offerings, including business agents, model APIs, direct sales of compute capacity, and services for large customers. More than 1 million businesses already use business agents on WhatsApp and Messenger each week, and the company plans to charge based on subscriptions, usage, and message volumes. Compared with consumer agents, this route lends itself more readily to transparent pricing, but Meta must demonstrate capabilities in enterprise sales, service levels, security, and customer support.
Of these three paths, the first is already reflected in the income statement; the second has enormous distribution advantages, but its business model is still taking shape; and the third most closely resembles Microsoft’s business model, but is also the area in which Meta has the least experience. Investors are no longer underwriting whether Meta can build strong models, but whether these products can generate sufficient revenue before depreciation rises rapidly.
Sell-Side Divergence: Meta’s Target-Price Dispersion Essentially Reflects the Discount Applied to Long-Term Optionality
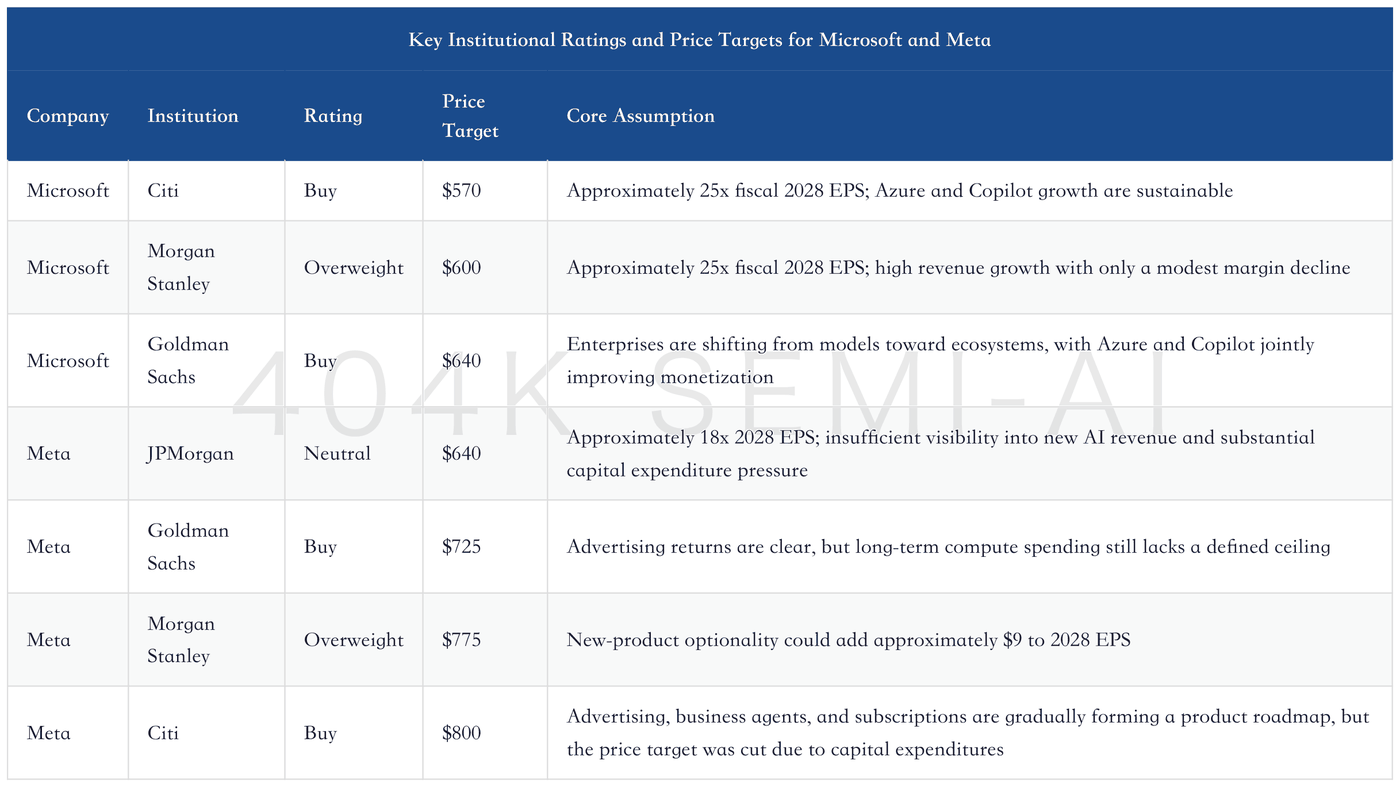
Although the three institutions have different price targets for Microsoft, their core theses are highly consistent: accelerating Azure growth, Copilot adoption, enterprise-suite price increases, and margin resilience. The differences in their price targets mainly reflect valuation multiples and EPS forecasts, rather than fundamental disagreement over the business model.
The divergence on Meta is more substantial. JPMorgan believes advertising returns have been proven, but the timing and scale of revenue from model APIs, business agents, and direct compute sales remain unclear; it therefore cut its price target and maintained a Neutral rating. Morgan Stanley, by contrast, believes the market has already priced in most of the capital expenditures while assigning almost no value to new-product optionality. The two institutions do not differ materially on the core advertising business; their disagreement centers on the probability of long-term product success and the duration of elevated capital expenditures.
This implies that Meta’s share-price sensitivity will be materially greater than Microsoft’s. If Meta reports clear subscription, business-agent, or model-API revenue over the next several quarters, its valuation may quickly begin reflecting that optionality. If its products remain limited to user and testing metrics while capital expenditure guidance continues to rise, the market will move closer to JPMorgan’s framework.
Both Are AI Platforms, but Microsoft and Meta Sell Two Different “Outcomes”
Microsoft sells productivity outcomes to enterprises. Customers buy Azure not to own GPUs, but to run models, databases, and applications; they buy Copilot not to chat, but to complete work involving documents, code, customer management, and security. Microsoft can package the underlying compute, model routing, data permissions, and application interfaces, creating monetization points at every layer.
Meta sells conversion outcomes to advertisers. Advertisers do not need to understand recommendation models; they care only about clicks, purchases, and returns. Meta embeds AI behind its content-distribution and advertising systems, with user engagement time and advertising conversions driving revenue. The advantage of this model is that returns can quickly extend across millions of advertisers; the disadvantage is that if new AI products continue primarily to support advertising, the market may question whether capital expenditure exceeds the requirements of a single business model.
The two companies are moving into each other’s domains. Microsoft is expanding into applications and agents through Copilot, while Meta is attempting to enter the enterprise market through model APIs, business agents, and compute services. Microsoft’s advantages are its enterprise relationships and cloud infrastructure; Meta’s advantages are consumer distribution, social data, and its closed-loop advertising feedback system. Future competition will extend beyond model leaderboards to which company can turn models into low-friction, billable, and reusable work or consumption outcomes.
Which Metrics Matter Over the Next Four Quarters
For Microsoft, first, watch whether Azure’s constant-currency growth can remain above 40% and deliver on guidance of approximately 45% for the next quarter. Second, watch paid Microsoft 365 Copilot seats: if net additions remain close to 10 million, enterprise deployments are reaching scale; if they decline materially, investors will need to distinguish between quarterly purchasing patterns and slower adoption. Third, monitor commercial bookings and remaining performance obligations to determine whether revenue acceleration is supported by new demand. Fourth, watch cloud gross margin and operating margin to assess whether utilization, pricing, and software mix can offset depreciation. Fifth, monitor capital expenditure and the GPU deployment cycle; higher investment must translate into faster revenue conversion.
For Meta, first, watch the combination of ad impressions and pricing, as sustaining double-digit growth in both simultaneously will not be easy. Second, monitor time spent on Instagram and Facebook to confirm that recommendation improvements continue to generate incremental gains. Third, track the scale of Advantage+, the number of enterprises using AI creative tools, and paid conversion for business agents; these are the earliest evidence that AI is moving from internal efficiency gains toward standalone product revenue. Fourth, watch whether capital-expenditure guidance is raised again and whether a clear ceiling emerges for 2027 spending. Fifth, monitor free cash flow and net debt to determine whether the company may need more borrowing, off-balance-sheet financing, or slower share repurchases. Sixth, watch Reality Labs losses to ensure that AI investment and long-term hardware projects do not expand cost pressures simultaneously.
Final Assessment: Microsoft Has Entered the AI Return-Validation Phase, While Meta Remains in the AI Asset-Building Phase
The most valuable aspect of Microsoft’s earnings report is not its $90 billion of revenue or 43% Azure growth in isolation, but that three long-running debates were addressed in the same quarter: revenue did accelerate after supply increased, Copilot moved from pilots to large-scale paid adoption, and margins did not lose control amid AI buildout. Microsoft has not yet completed the full validation of returns, and depreciation and capital expenditure will continue to weigh on free cash flow, but it has already demonstrated that commercialization can keep pace with asset expansion.
Meta should not simply be categorized as “spending heavily without returns.” Advertising revenue, user engagement time, clicks, conversions, and the scale of Advantage+ all indicate that AI is creating real economic value. The issue is that capital expenditure is expanding beyond supporting the core advertising business into personal agents, enterprise services, model APIs, and direct sales of compute capacity. The more new directions Meta pursues, the larger the potential market—but the harder the return timeline becomes to estimate.
The two companies therefore should not be compared simply on “whose AI is stronger”; they are at different stages of capital allocation. Microsoft has entered the return-validation phase, and the market will value it based on revenue growth, bookings, seats, and margins. Meta remains in the asset-building and product-discovery phase, with the market using advertising cash flow as the foundation and discounting the optionality of longer-term products.
Based on the current evidence, Microsoft offers greater certainty, with risks concentrated in valuation and infrastructure depreciation. Meta offers greater potential upside elasticity, with risks concentrated in continually rising capital expenditure and delays in emerging revenue curves. For investors, the key is not to chase price movements after a single earnings report, but to require each new round of capital expenditure to correspond to clearer evidence in users, revenue, profit, or cash flow. Whichever company can consistently translate “more compute” into “more billable outcomes” will earn the more durable valuation premium in this AI capital-expenditure race.
Related Reading
Microsoft FY2026 Q4 Deep Dive: Azure Growth Rises to 43%, Cloud Gross Margin Falls to 65%