
Contents
1. August Quarter: Upside Driven Almost Exclusively by Pricing
2. LTAs Mute Operating Leverage: Spot Prices Gain 10%, Blended ASP Rises High Single Digits
3. Why the Deficit Is Still Widening: Server Demand, HBM Price Premiums, and Chinese Supply
4. Earnings Outlook: UBS's Above-Consensus Forecasts Stem from Cycle Duration
5. Share Repurchases: Where Does the Cash Go After December 9?
6. Valuation: Unchanged $1,625 Price Target, Completely Overhauled Assumptions
7. Key Risks to the Duration Thesis
8. What to Watch on September 30
This content is compiled from publicly available information and research reports. It does not constitute investment advice or represent any individual's views. For educational reference only; please read critically.
404K SEMI-AI
Micron is scheduled to report its August quarter (FQ4) results on September 30. UBS estimates revenue of ~$52.4 billion and a gross margin of 87.6%, both tracking above company guidance. However, long-term agreements (LTAs) are beginning to cap upward revision momentum. Market debate has pivoted from the magnitude of near-term price hikes to cycle duration and the pace of capital returns.
1. August Quarter: Upside Driven Almost Exclusively by Pricing
Micron enters the print from an exceptionally elevated baseline. In FQ3 2026 (ended May 28, 2026), revenue surged to $41.456 billion, compared to $9.301 billion a year earlier. GAAP gross profit reached $35.056 billion and net income totaled $28.243 billion, versus just $1.885 billion in the prior-year period. DRAM revenue hit $31.328 billion and NAND revenue reached $9.943 billion, both more than quadrupling year-over-year. On a non-GAAP basis (excluding stock-based compensation and other items), gross margin was 84.9% and diluted EPS came in at $25.11.
By segment, FQ3 revenue broke down as follows:
Cloud Memory Business Unit (CMBU): $13.769 billion
Core Data Center Business Unit: $11.524 billion
Mobile & Client Business Unit: $11.521 billion
Automotive & Embedded Business Unit: $4.634 billion
Mobile & Client has reached revenue parity with Core Data Center, underscoring that pricing strength extends well beyond AI-server-specific product lines.
For the August quarter, Micron guided revenue to $50.0 billion ± $1.0 billion, gross margin to ~86%, and EPS to $31.00 ± $1.00. In its September 23 preview, UBS modeled revenue at ~$52.434 billion (topping the high end of guidance), gross margin at 87.6% (~160 bps above guidance), and EPS at $32.50. Consensus stands at $50.45 billion, 85.1%, and $31.16, respectively. UBS also models quarterly free cash flow at ~$21.7 billion, ahead of the $19.5 billion consensus.
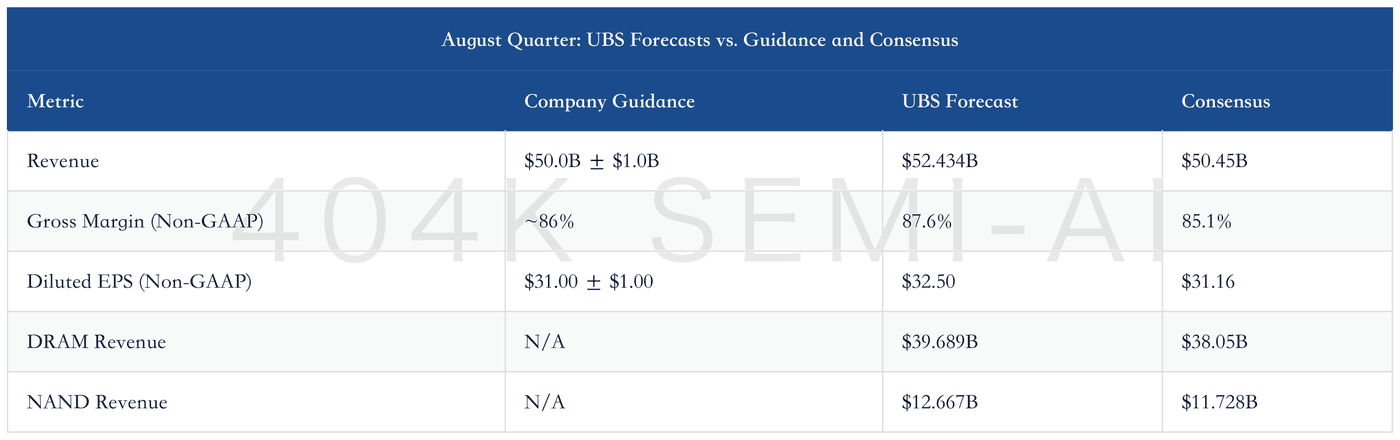
The projected beat is narrowly concentrated. UBS forecasts DRAM revenue of ~$39.7 billion, with bit shipments up just 3% QoQ but ASP surging 23% QoQ against a 3% QoQ increase in unit cost. Within DRAM, standard DDR revenue is projected at ~$36.2 billion, with ASP up 24% QoQ—closely matching UBS's estimate of a ~26% increase in Q3 industry contract prices (including LTAs). HBM revenue is modeled at ~$3.5 billion, reflecting 9% bit growth and a 10% ASP gain. NAND revenue is expected to reach ~$12.7 billion, with bit growth of 4% and ASP up 23%, tracking UBS's estimate of a ~23% rise in industry contract pricing. With volume growth running in the low single digits, the step-function jump in top- and bottom-line performance is driven almost entirely by pricing.
Consequently, beating guidance will not surprise the market so long as price gains fall within these bands. What will dictate share price performance is how many more quarters of pricing power remain, and how much of those gains ultimately convert into net earnings.
2. LTAs Mute Operating Leverage: Spot Prices Gain 10%, Blended ASP Rises High Single Digits
Heading into the FQ3 report in June, investor discussion centered on whether long-term agreements could lock in peak profitability—framed as "whether peak earnings can be capitalized." The prevailing thesis was that Micron could only shed its traditional cyclical discount if customers proved willing to sign extended, higher-priced contracts securing supply through 2027 and 2028.
Micron Deep Dive: Can Peak Margins Be Capitalized? How AI Memory LTAs Rewrite the Cyclical Discount
Micron subsequently disclosed 16 Strategic Customer Agreements (SCAs) in its FQ3 earnings release, securing ~$100 billion in minimum cumulative revenue backed by ~$22 billion in customer cash prepayments and financial commitments. With these contracts executed, the dynamic has inverted: fixed pricing locks in volumes, but caps participation in spot price upside.
