
目录
Executive Summary
The First Counterintuitive Point: Why Did the $1,625 Target Survive the Bad News?
What Is the “Noise” in NAND? Prices Are Rising More Slowly, Not Falling
Why DRAM Matters More: Tightness Is Extending Through 2028, Not Just Another Quarter
Why Lower Vera Rubin 300 Specifications Increase Total HBM Demand
HBM Is Not Free Profit: Why the Pricing Premium Does Not Fully Translate Into Gross Margin
2027 Is Only a Transition Year; the Real Disagreement Is Over 2028
Why the $1,625 Price Target Is Unchanged: Higher Earnings Offset a Lower Multiple
What This Report Changes—and What It Retains
Nine Sets of Public Data That Will Show Which View Is Closer to Reality
本内容基于公开资料和研报数据整理,不构成任何投资建议,不代表任何个人观点,仅供学习参考,请理性阅读
UBS maintains its $1,625 price target, even as it raises 2029 earnings from $121 to $165 and cuts the valuation multiple from 15x to 11x. The target is unchanged, but the underlying investment case has shifted.
Executive Summary
The $1,625 target is unchanged, but its foundation has shifted. The previous framework relied more heavily on a higher valuation multiple; the new framework depends more on 2029 EPS of $165. Earnings have been revised up by approximately 36%, while the applied multiple has fallen by approximately 27%. The key question is no longer the multiple, but whether pricing, yields, and cash flow can deliver the projected long-term earnings quarter by quarter.
NAND is cooling, but it has not entered a downturn. UBS cut its forecast for third-quarter industry NAND contract-price growth from approximately 28% to approximately 20%, and its corresponding Micron forecast from approximately 35% to approximately 23%. It therefore reduced its FY2027 NAND revenue forecast by 17%. However, server and storage SSD demand remains strong, prompting UBS to raise its industry bit-demand growth forecasts for 2026 and 2027 to 23% and 26%. This looks more like a divergence across products and pricing benchmarks than a collapse in demand.
DRAM is the primary driver of the earnings upgrade. UBS expects industry DDR contract prices to rise approximately 20% quarter over quarter in the third quarter, with Micron’s DDR prices increasing approximately 20% and 11% in the third and fourth quarters, respectively. Supply is expected to remain below demand through at least the second quarter of 2028. Long-term agreements limit upside at the peak but also provide greater downside protection, making revenue more visible than in previous spot-driven cycles.
Lower specifications for Vera Rubin 300 do not imply weaker HBM demand. Initial products will use 384GB of HBM4, before transitioning around the third quarter of 2027 to 512GB of HBM4E rather than the previously assumed 768GB. The lower memory content per system, however, allows the supply chain to deliver more complete systems. UBS has therefore raised its 2027 industry HBM demand forecast from approximately 58.7 billion Gb to approximately 61.5 billion Gb.
HBM commands higher prices, but it also carries higher costs. UBS expects HBM4E pricing to exceed $30/GB and forecasts industry HBM average selling prices to rise 79% year over year in 2027, versus 72% for Micron. However, stacking, testing, yields, and advanced packaging make HBM unit costs substantially higher than those of conventional DRAM, so HBM gross margins may not necessarily be higher at the cycle peak. HBM’s value lies in scarcity and long-term orders—not an unconditional margin premium.
The most important issue is not the current quarter, but the enormous gap between UBS and consensus for 2027–2028. UBS’s calendar-year 2027 and 2028 EPS forecasts are 28% and 59% above consensus, respectively. If consensus estimates move higher, the $1,625 target will gain stronger support. If DRAM pricing, HBM4E yields, or capital expenditure prevent earnings from materializing, even 11x may not prove cheap enough.
The First Counterintuitive Point: Why Did the $1,625 Target Survive the Bad News?
The report’s title begins by flagging “some noise in NAND,” but then emphasizes that “DRAM is tighter than previously expected.” At first glance, this may appear to be a simple offset between one improving business and one deteriorating business. The actual shift is more consequential: NAND affects the FY2027 earnings trajectory, while DRAM and HBM lift the earnings platform for 2028–2029—and UBS’s $1,625 target is anchored specifically to calendar-year 2029 earnings.
UBS forecasts Micron revenue of $130.475 billion, $285.138 billion, and $378.906 billion in FY2026, FY2027, and FY2028, respectively, with adjusted EPS of $74.13, $184.89, and $265.65. Relative to its previous model, UBS cut FY2027 revenue and EPS by 3% and 4%, respectively, but raised FY2028 revenue and EPS by 13% and 15%. This is not simply offsetting bad news; it shifts the earnings peak both later and higher.
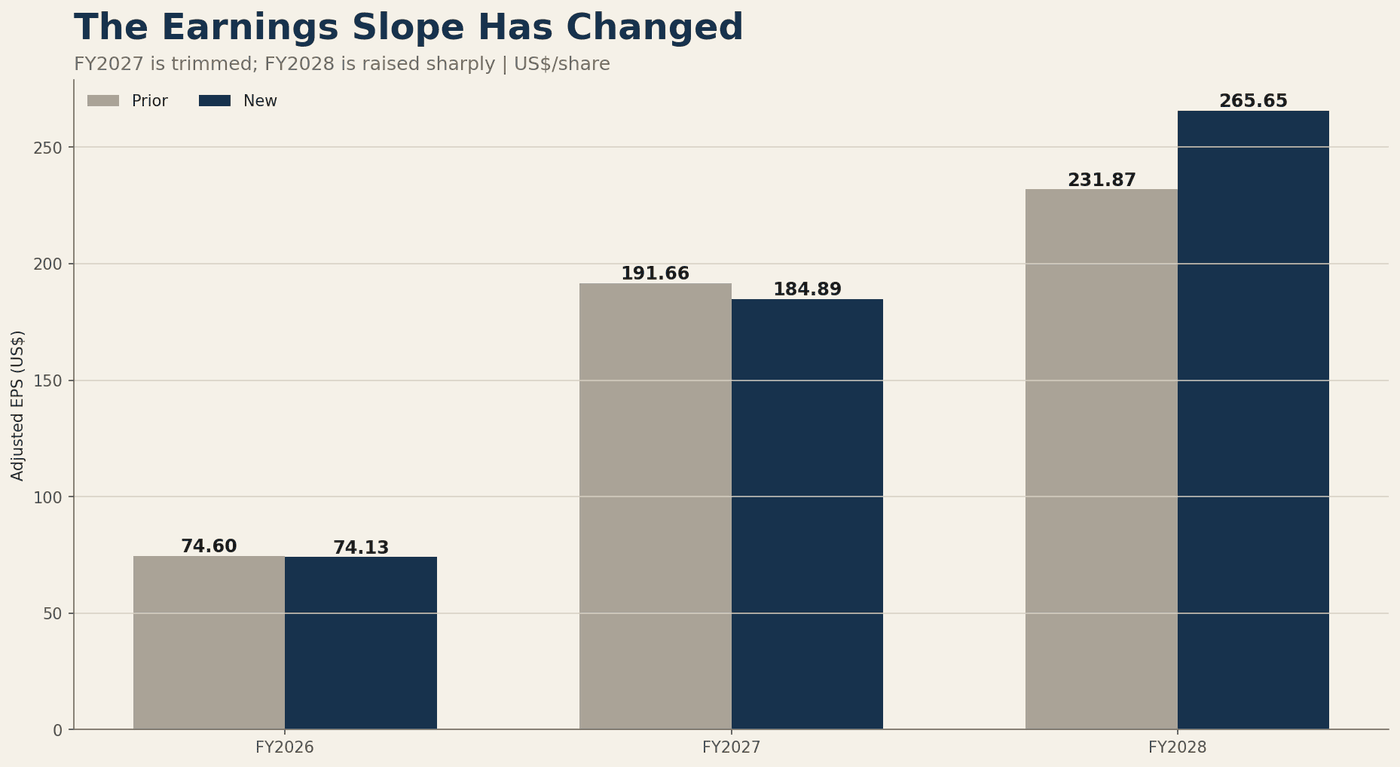
The near-term model also remains robust. UBS forecasts Micron FY2026 fourth-quarter revenue of $51.516 billion, above the company’s guidance midpoint of $50 billion and consensus of $50.452 billion. It expects an 87.7% gross margin, above company guidance of 86% and consensus of 85.1%, while adjusted EPS of $31.94 also exceeds the company’s guidance midpoint of $31. DRAM and NAND bit shipments are both expected to grow approximately 4% quarter over quarter, but pricing remains the real source of earnings growth: DRAM average selling prices are projected to rise approximately 19% sequentially and NAND prices approximately 22.5%.
The report is therefore not arguing that Micron’s near-term outlook has deteriorated. Rather, NAND is less buoyant than previously expected, but the company’s overall earnings exposure to NAND has been more than offset by DRAM and HBM. As long as long-term DRAM pricing and HBM content value continue to increase, the incremental reduction in near-term NAND profit is insufficient to undermine a $1,625 valuation anchored to 2029 earnings.
The correct analytical sequence is to identify which year’s earnings underpin the valuation, determine which products drive those earnings, and only then assess whether quarterly results exceed expectations. Directly offsetting the FY2027 NAND downgrade against the 2029 DRAM/HBM upgrade overlooks both the time-value difference and the shift in business mix.
What Is the “Noise” in NAND? Prices Are Rising More Slowly, Not Falling
UBS had previously expected industry NAND contract prices to rise approximately 28% quarter over quarter in the third quarter; it has now reduced that forecast to approximately 20%. Its corresponding forecast for Micron was cut from approximately 35% to approximately 23%. These remain substantial increases, but they fall short of what the market had already priced in. UBS consequently reduced its Micron NAND revenue forecasts for FY2026, FY2027, and FY2028 by 4%, 17%, and 9%, respectively.
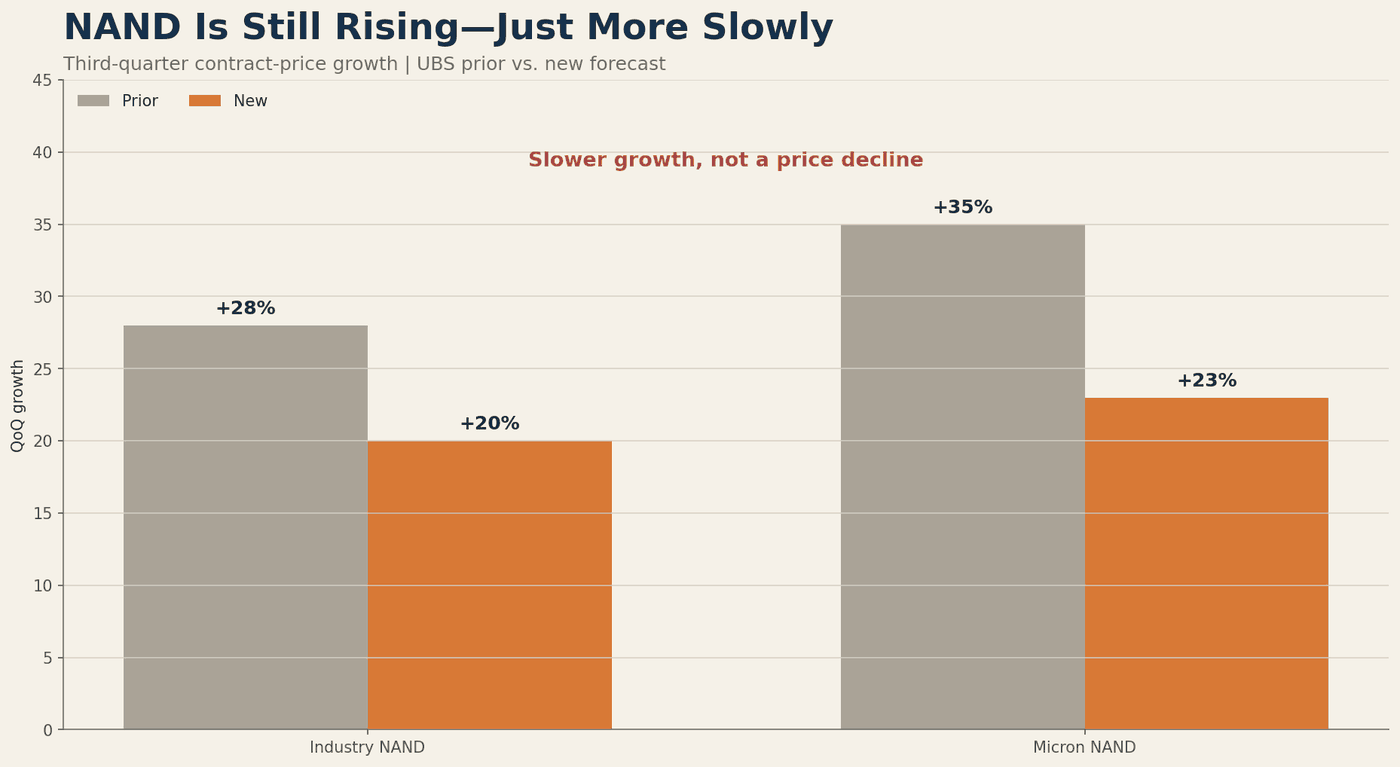
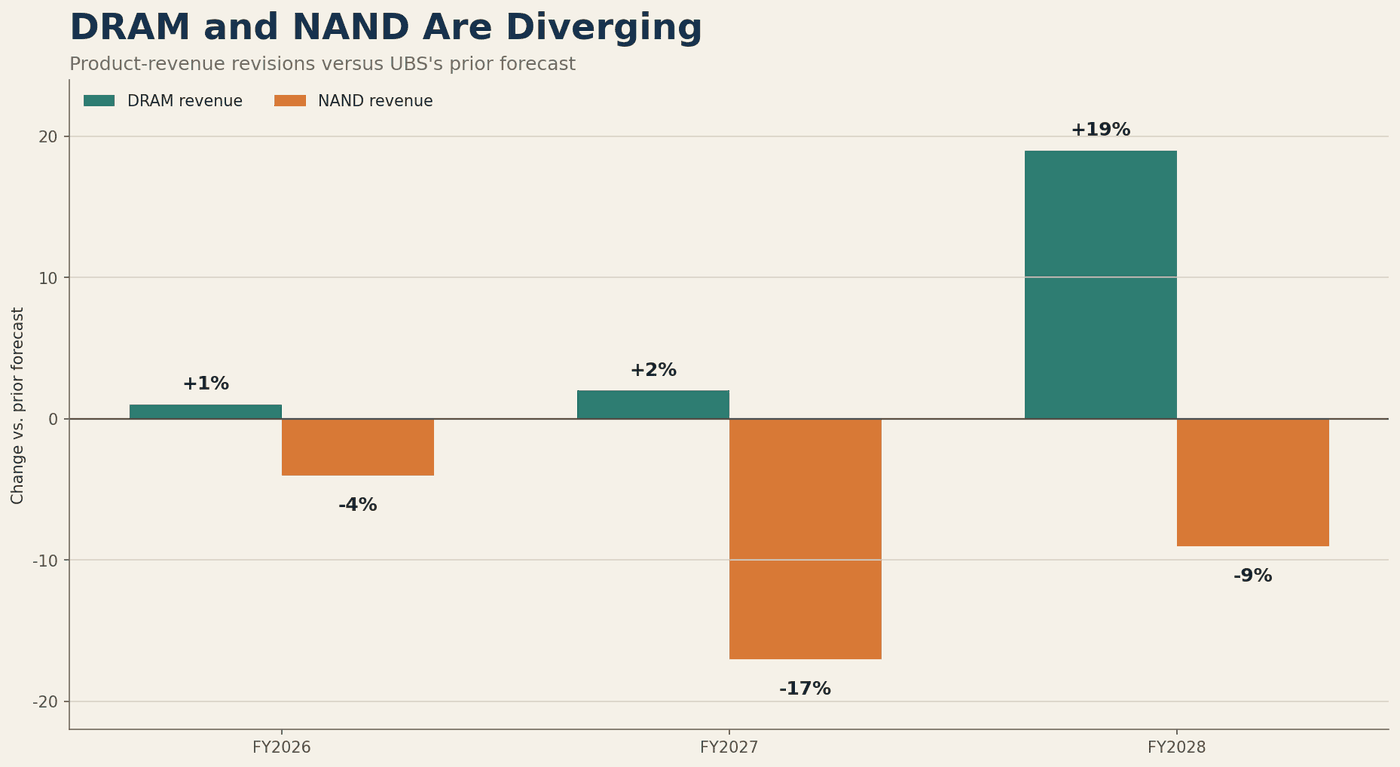
The lower pricing forecast was not accompanied by weaker demand assumptions. UBS instead raised its industry NAND bit-demand growth forecasts for 2026 and 2027 to 23% and 26%, arguing that server and storage SSD demand should be sufficient to offset weakness in smartphones and PCs. In other words, NAND is not becoming harder to sell; its price trajectory is simply less steep than previously estimated.
This is consistent with the earlier view that NAND pricing is diverging across segments: bare-die spot prices, contract prices, enterprise SSD prices, and the storage value of complete systems should not be treated as a single pricing benchmark. Enterprise SSD value reflects controllers, firmware, capacity, reliability, and lengthy qualification processes. Even when bare-die prices weaken in the short term, enterprise SSDs can remain strong because of server demand and product mix. By identifying server and storage SSD demand as key supports, UBS’s latest report reinforces this divergence.
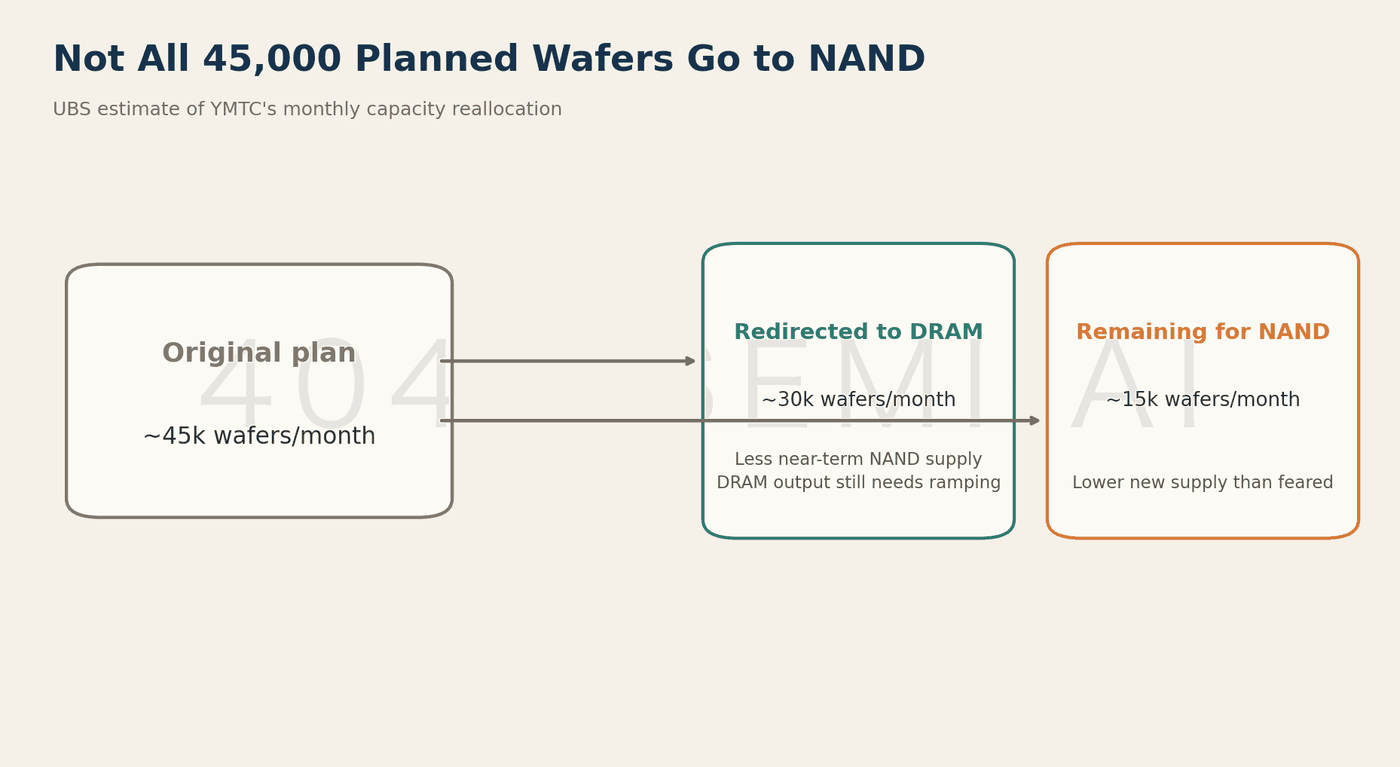
Supply has not suddenly become undisciplined either. UBS estimates that approximately 30,000 wafers per month of the approximately 45,000 wafers per month in planned new capacity at Yangtze Memory Technologies have been redirected to DRAM. This reduces incremental NAND supply while increasing nominal DRAM capacity. However, new DRAM capacity takes time to progress from equipment installation through yield ramp-up and customer qualification. The shift therefore supports near-term NAND pricing without immediately pressuring DRAM prices. UBS continues to place the NAND pricing peak around the fourth quarter of 2027.
A more precise interpretation of “NAND noise” is that the market had assumed all NAND pricing categories would rise too synchronously and too steeply, and those increases now need to be differentiated by segment. As long as enterprise SSD orders, bit demand, and supply discipline do not deteriorate together, a reduction in the expected magnitude of price increases should not be interpreted as evidence that the cycle has peaked.
That conclusion has limits. If contract-price growth not only slows but is accompanied by weaker enterprise SSD orders, downward revisions to bit-shipment growth, rising channel inventories, and simultaneous new-capacity additions, “slower increases” could become “outright declines.” UBS’s current data do not yet indicate that outcome.
Why DRAM Matters More: Tightness Is Extending Through 2028, Not Just Another Quarter
UBS expects industry DDR contract prices, including long-term agreements, to rise approximately 20% QoQ in Q3. Micron’s Q3 DDR prices are likewise expected to increase approximately 20%, followed by another approximately 11% increase in Q4. The report forecasts that DRAM demand will outstrip supply through at least Q2 2028. This matters more than any single quarter’s pricing because it determines whether elevated profitability can persist through the years covered by the model.
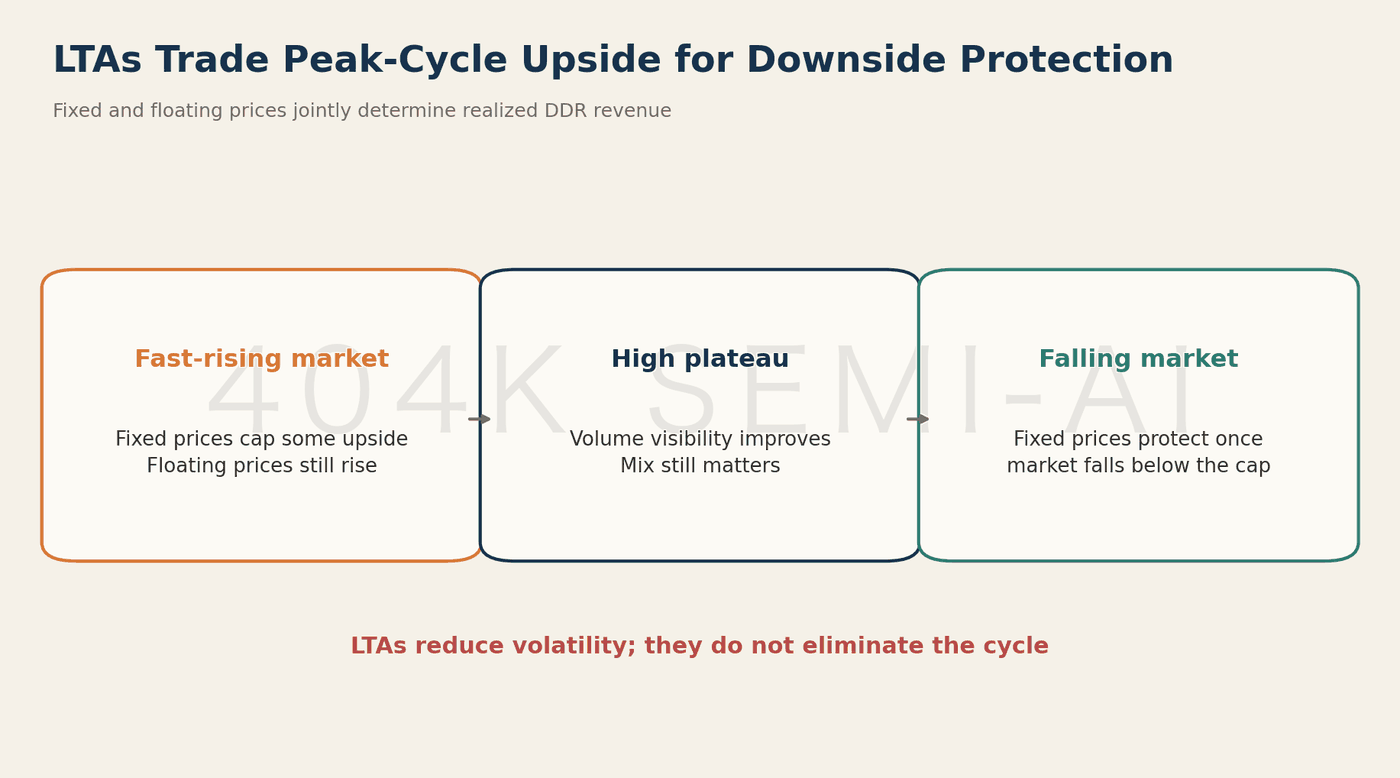
DDR long-term agreements differentiate this cycle from previous ones. UBS divides contract pricing into fixed and floating components: fixed prices provide floors and ceilings, while floating prices move with the market. When market prices rise rapidly, fixed pricing limits some of Micron’s upside, effectively resembling a concession. However, when market prices fall below the contract ceiling in 2029, fixed pricing begins to provide protection. The value of long-term agreements is not permanently higher pricing, but the exchange of some peak-cycle upside for more stable volumes and prices during the downturn.
This structure changes how the market values cyclical stocks. Spot-price models typically apply low multiples to peak earnings because profits rise quickly and disappear just as fast. Greater visibility from long-term agreements allows investors to assess cash flow over a longer horizon. However, these agreements do not eliminate cyclicality: floating prices can still decline, fixed-price coverage is not 100%, customers may adjust purchase volumes, and technology transitions will continue to alter unit costs and product mix.
Concerns about ChangXin Memory Technologies’ capacity expansion should also be assessed against actual output rather than nameplate capacity. UBS expects its share of global DRAM bit supply to rise from 7% in 2025 to 9% in 2027, but believes equipment installation, yield ramp-up, and the technology gap will limit the near-term impact. The most common mistake is to equate announced wafer capacity directly with saleable high-end bit supply. For advanced DDR and HBM, capacity, yields, packaging, qualification, and customer adoption are all indispensable.
The impact of UBS’s DRAM upgrade on Micron outweighs that of its NAND downgrade for straightforward reasons: Micron has a larger DRAM revenue base, incremental pricing carries greater operating leverage, and HBM consumes substantial DRAM wafer capacity and advanced-packaging resources. Commodity DDR and HBM are not independent production lines. The stronger HBM demand becomes, the tighter the effective supply of conventional DRAM, making a positive pricing feedback loop more likely.
Why Lower Vera Rubin 300 Specifications Increase Total HBM Demand
The report’s most counterintuitive revision concerns NVIDIA’s Vera Rubin 300. Because of tight HBM supply, the initial products are planned with 384GB of HBM4, followed by a transition around Q3 2027 to 512GB of HBM4E rather than the previously envisioned 768GB. Memory capacity per system is indeed lower, but using less HBM in each system enables the supply chain to ship more systems.
Assuming a fixed supply constraint, reducing HBM content per system from 768GB to 512GB would theoretically allow the same HBM supply to support approximately 50% more systems. Actual output will also be constrained by GPUs, networking, substrates, power supplies, and system assembly, so it will not mechanically increase by 50%. The direction, however, is clear: HBM content per system and total industry consumption do not have a linear relationship.
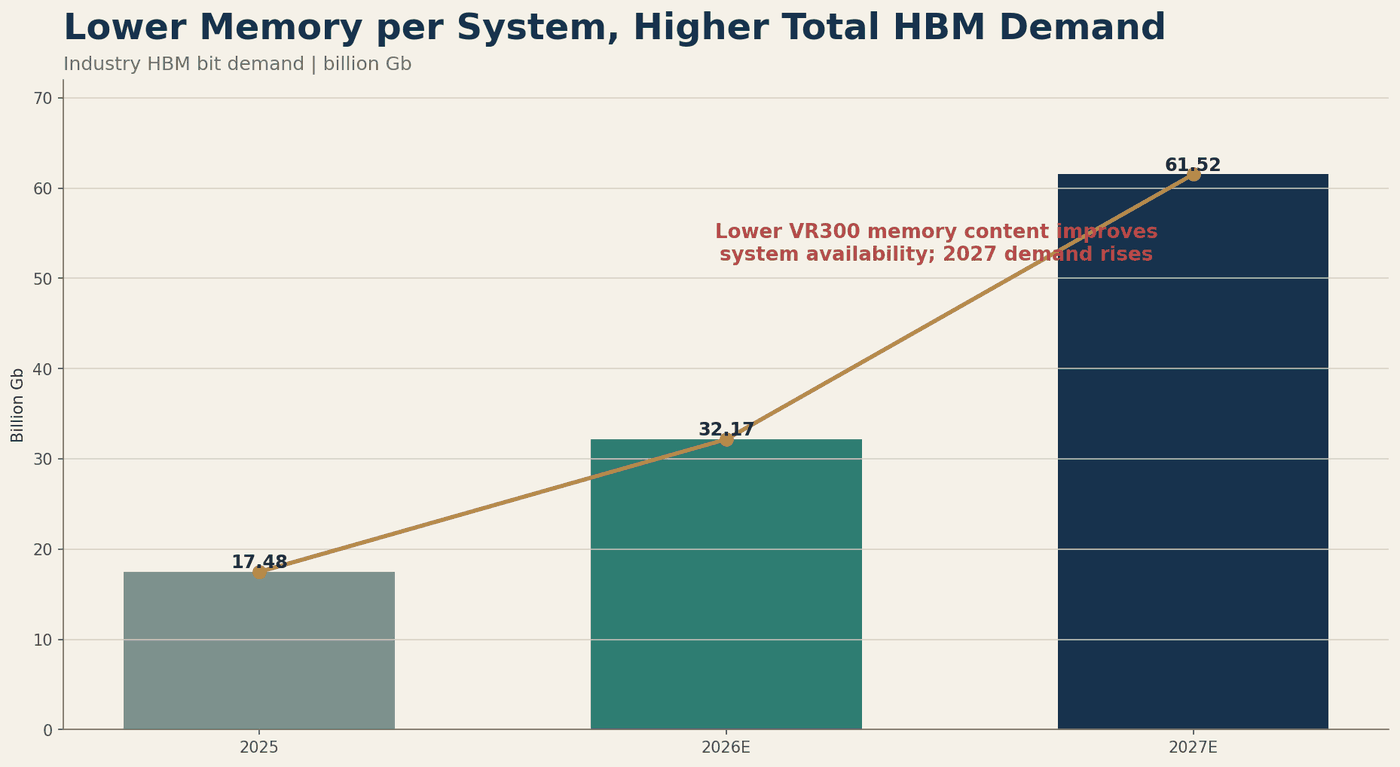
UBS therefore raised its estimate of total industry HBM demand in 2027 from approximately 58.7 billion Gb to approximately 61.5 billion Gb. Modeled demand for 2025, 2026, and 2027 is approximately 17.5 billion Gb, 32.2 billion Gb, and 61.5 billion Gb, respectively—an approximately 2.5-fold increase over two years. NVIDIA remains the largest customer, while internally developed and semi-custom accelerators from Google, AMD, Amazon, and others provide a second source of demand.
The pricing revision is even more significant. UBS expects HBM4E prices could exceed $30/GB. It raised its forecast for industry HBM ASP growth in 2027 from 67% YoY to 79%, and Micron’s own growth forecast from 61% to 72%. This implies that even if Micron’s HBM bit shipments fall slightly below the prior forecast, higher unit value could still offset the shortfall in revenue and profit.
An important implication is that an HBM supplier’s value depends on more than the number of orders secured. It also reflects product generation, stack height, price per unit of capacity, yields, advanced-packaging efficiency, and customer platform timing. Treating all HBM at the same dollar-per-GB value would understate the pricing difference between HBM4E and HBM3E while overstating profitability during low-yield ramp phases.
HBM Is Not Free Profit: Why the Pricing Premium Does Not Fully Translate Into Gross Margin
HBM is often reduced to a simple proposition: because it is far more expensive than conventional DRAM, its gross margin must also be higher. UBS’s product-level model shows why that conclusion does not necessarily hold. In a model snapshot around November 2027, HBM ASP is approximately $29.61/GB versus approximately $18.39/GB for conventional DRAM, or roughly 1.6 times higher. Yet HBM unit cost is approximately $6.51/GB versus approximately $0.96/GB for conventional DRAM—nearly 6.8 times higher.
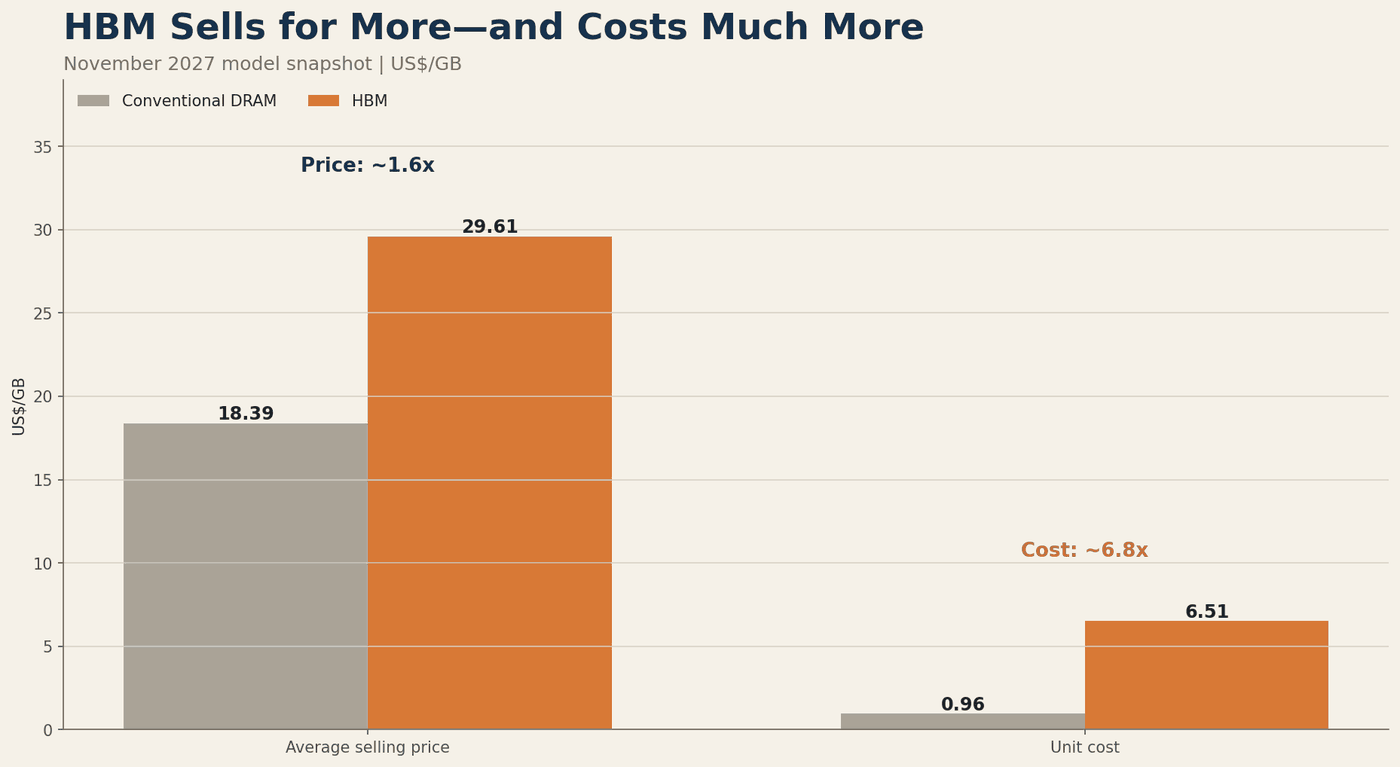
The cost gap has multiple sources. HBM requires more DRAM dies, through-silicon vias, stacking, testing, substrates, and advanced packaging, while yield losses become increasingly magnified as stack height rises. Even at high selling prices, slow yield ramps and expensive packaging capacity can prevent HBM margins from exceeding those of conventional DRAM at the peak of a cycle. UBS models HBM gross margins at approximately 70% to nearly 80%, while conventional DRAM can reach even higher levels during periods of extreme shortage.
This does not diminish HBM’s importance. Its strategic value has three dimensions. First, it provides exposure to AI accelerators, the fastest-growing end market. Second, it consumes more wafer and packaging capacity, indirectly tightening conventional DRAM supply. Third, lengthy qualification cycles and close customer collaboration improve order visibility. Financially, however, HBM is best understood as a high-growth, manufacturing-intensive product with strong customer lock-in—not a super-profit pool unconstrained by costs.
For Micron, the key question is whether HBM4 and HBM4E yields can improve as planned. If prices rise 72% but unit costs increase even faster because of yield, stacking, or packaging issues, revenue could look impressive while profit falls short of the model. Conversely, if yields improve faster than expected, the current HBM gross-margin assumptions may prove conservative. The outcome will be determined not by the consensus view that “HBM demand is strong,” but by whether the pricing or cost curve moves faster.
2027 Is Only a Transition Year; the Real Disagreement Is Over 2028
The gap between UBS and consensus estimates is too large to characterize as merely “slightly more optimistic.” On a calendar-year basis, UBS forecasts 2026 EPS of $106.91, 3.6% above the $103.23 consensus estimate; 2027 EPS of $210.07, 28.2% above the $164.64 consensus estimate; and 2028 EPS of $262.22, 59.1% above the $164.84 consensus estimate.
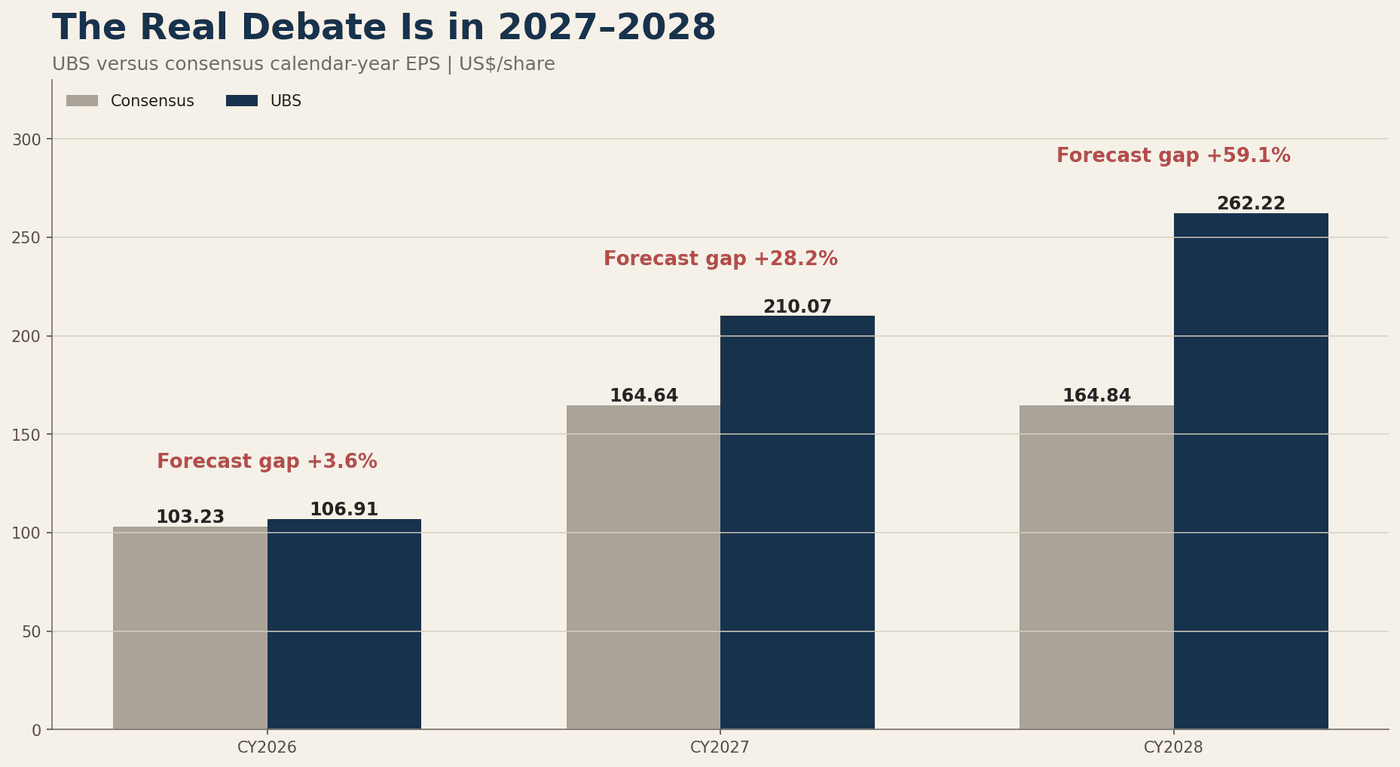
The narrow gap in 2026 indicates little disagreement over the immediate quarters. It begins widening in 2027 as the NAND revision offsets part of the DRAM and HBM upside. By 2028, the difference approaches $100 per share, showing that UBS and consensus are no longer operating with the same cycle assumptions regarding how long supply-demand tightness will persist, how quickly prices will decline, and how much HBM4E will contribute.
This is why focusing solely on the unchanged $1,625 price target is insufficient. UBS’s model must be validated sequentially by quarterly results, contract pricing, and company guidance. Only sustained upward revisions to consensus estimates would naturally narrow the gap between the two earnings trajectories.
Free cash flow provides the most direct test of the model. UBS forecasts Micron’s FY2026, FY2027, FY2028, and FY2029 free cash flow at approximately $50.374 billion, $151.142 billion, $220.163 billion, and $217.464 billion, respectively. Based on the model tables that can be reconciled year by year, cumulative free cash flow from FY2026 through FY2028 is approximately $421.7 billion. This implies that pricing and margins can still generate enormous cash flow even with capital expenditure reaching $47.8 billion in FY2027 and $45.8 billion in FY2028.
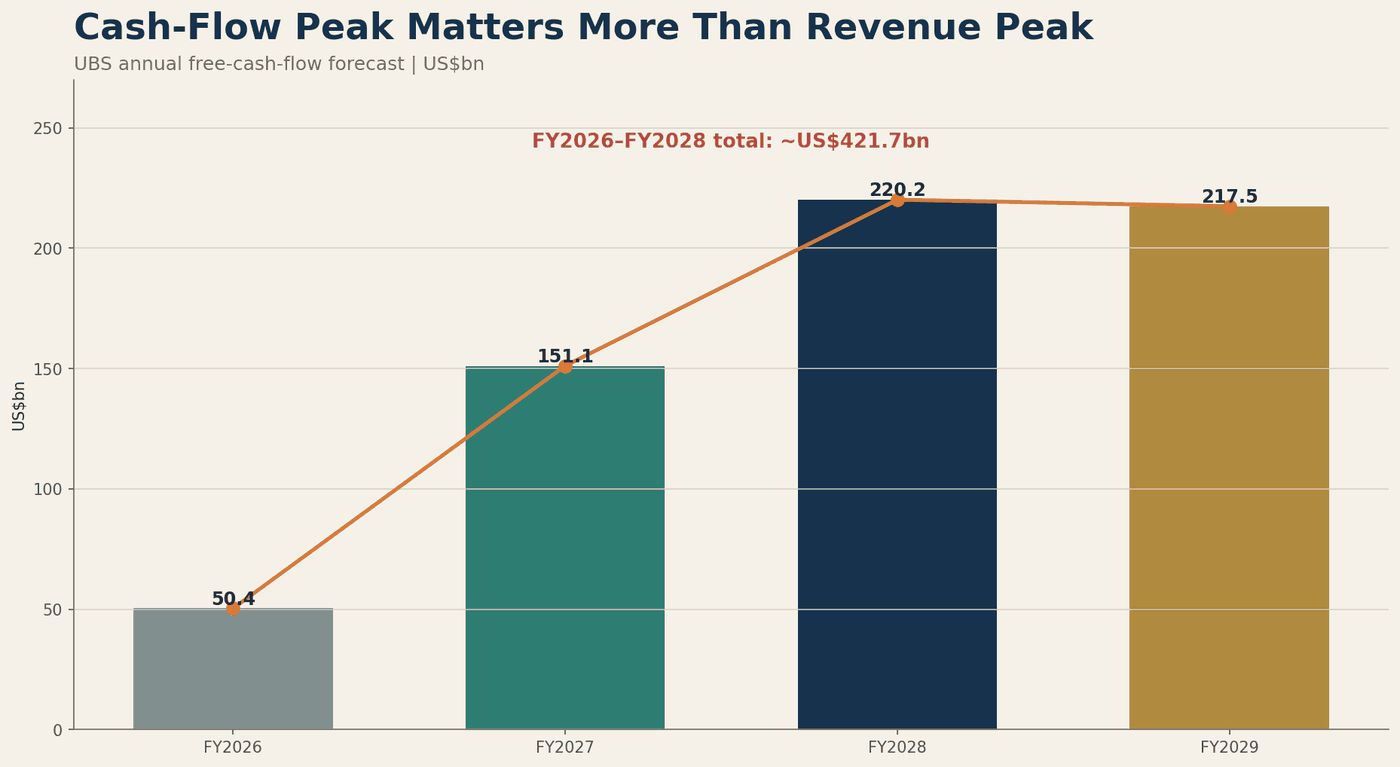
However, the peak in cash flow also exposes the model’s cyclicality. UBS expects revenue to decline from $378.906 billion in FY2028 to $272.457 billion in FY2029, while EPS falls from $265.65 to $190.23. Yet free cash flow declines only modestly, from $220.163 billion to $217.464 billion. If cash flow remains resilient as revenue falls, inventory, capital expenditure, working capital, and tax assumptions must collectively be providing support. Each of these assumptions will need to be reconciled against subsequent financial statements.
Why the $1,625 Price Target Is Unchanged: Higher Earnings Offset a Lower Multiple
UBS previously applied a roughly 15x multiple to approximately $121 in calendar 2029 EPS. It has now raised the EPS estimate to approximately $165 while cutting the multiple to roughly 11x. After discounting both sets of assumptions back to the present, each produces a value near $1,625.
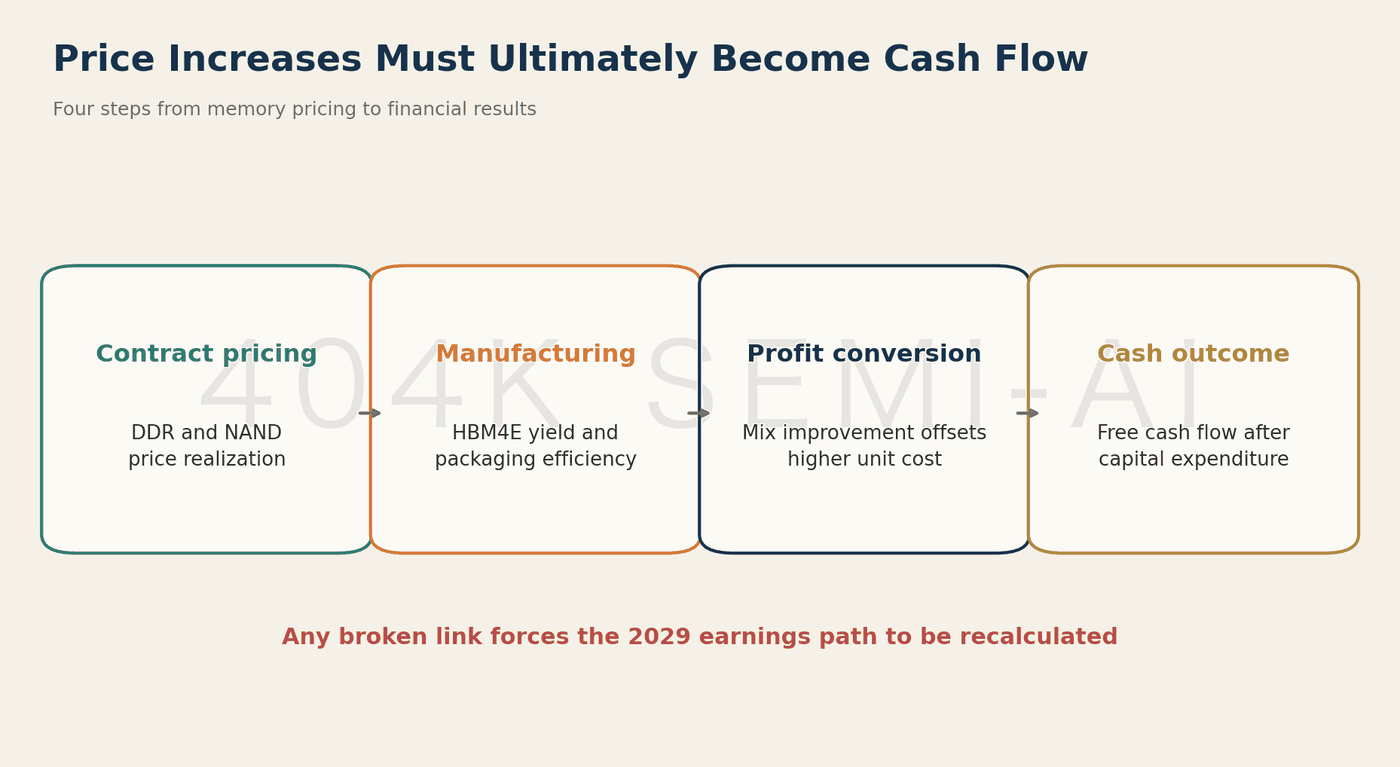
For most readers, the precise multiple is not the key issue. The old framework relied more heavily on the market assigning a higher valuation, while the new framework depends more on Micron actually delivering higher profits. The latter is easier to test against operating data—DDR contract prices, HBM4E pricing, yields, capital expenditure, and free cash flow. A sustained shortfall in any one of these would require the $165 forward EPS estimate to be recalculated.
The report already expects Micron’s revenue and EPS to decline in FY2029 from their FY2028 peaks, so it does not fully perpetuate peak conditions. Even so, post-peak earnings remain far above prior-cycle levels. The $1,625 target is therefore not a static figure detached from operating performance, but a trajectory that must be validated quarter by quarter.
What This Report Changes—and What It Retains
The prior Micron framework rested on three pillars: LTAs reducing cash-flow volatility, HBM4 increasing AI-memory content value, and substantial free cash flow prompting the market to reassess cyclicality. UBS’s latest update does not overturn these pillars; it makes each one more concrete.
First, LTAs are no longer merely an abstract mechanism for “locking in volume.” The combination of fixed and floating pricing suggests Micron may sacrifice some upside at the peak in exchange for better price protection during a downturn. Second, HBM4 is no longer just a volume story. Despite the Vera Rubin 300 specification downgrade, total demand was revised higher, showing that system shipments and memory content per system must be assessed together. Third, UBS’s decision to lower its applied multiple places greater emphasis on the actual delivery of earnings and cash flow.
The divergence within NAND has also received further confirmation. Earlier evidence showed weakening Korean export unit values alongside continued strength in enterprise SSDs, indicating that different pricing benchmarks should not be conflated. UBS has now lowered its NAND contract-price growth assumptions while raising bit-demand forecasts, providing a second set of evidence pointing in the same direction. Together, the two analyses suggest that the near-term NAND risk is primarily a slower rate of price appreciation—not simultaneous deterioration across all products.
There is only one genuinely new development: the $1,625 target now depends less on external multiple expansion and more on earnings delivery. That makes future assessment both simpler and more demanding. Quarterly pricing, yields, revenue, and cash flow are directly observable; if forward earnings are cut, the lower multiple leaves insufficient room to provide another offset.
Nine Sets of Public Data That Will Show Which View Is Closer to Reality
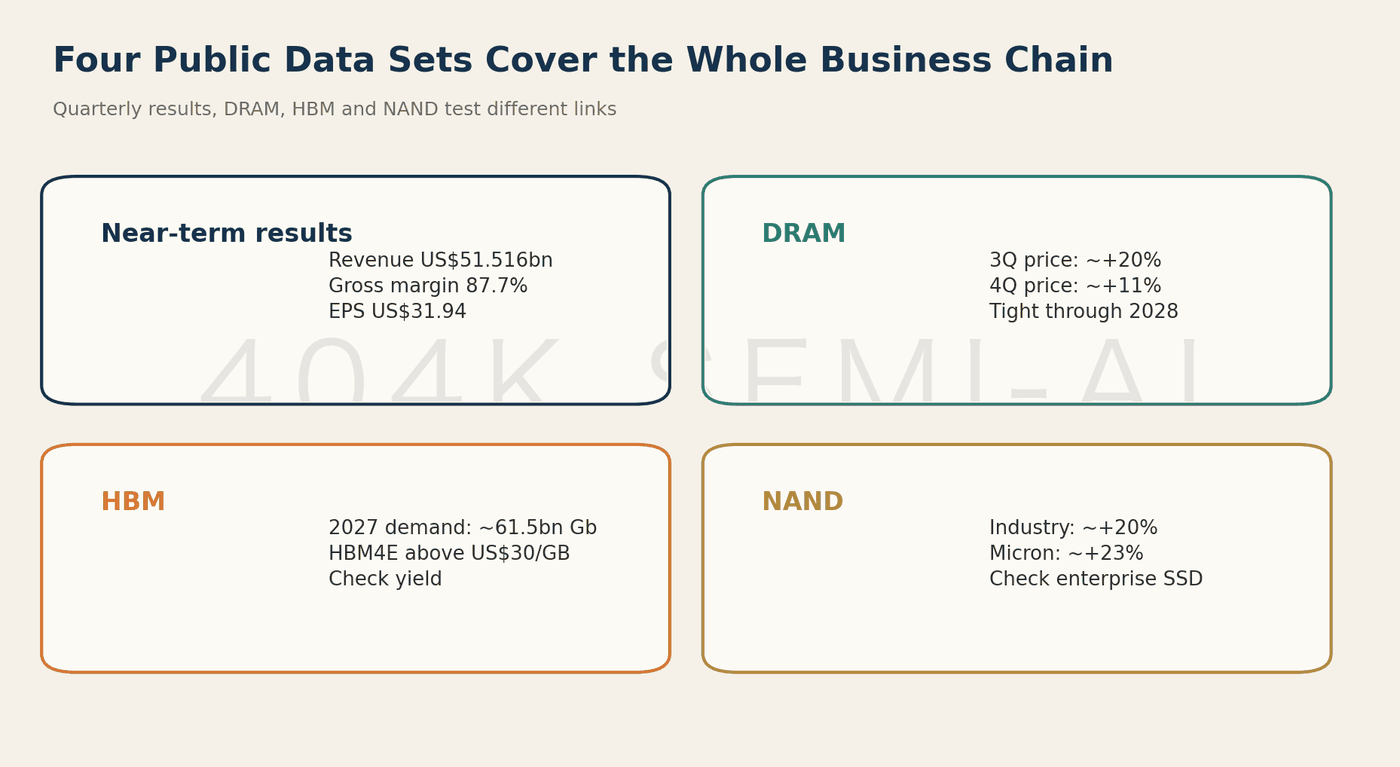
First, watch whether Micron can deliver approximately $51.5 billion in revenue, a gross margin near 87.7%, and EPS close to $31.94 in the fourth quarter of FY2026. If the near-term model is already off track, confidence in the longer-term upgrades will weaken first.
Second, monitor DDR contract prices. Sequential increases of approximately 20% for the industry in the third quarter, approximately 20% for Micron in the third quarter, and approximately 11% for Micron in the fourth quarter are the first hurdle for UBS’s DRAM upgrades. If pricing falls short of these figures, the earnings gap for 2027–2028 will narrow rapidly.
Third, examine the structure of LTAs. Fixed-price coverage, floating-price formulas, floors and ceilings, and renewal periods matter more than simply stating that “LTAs have been signed.” Only as contract terms become clearer is the market likely to reduce the discount applied to peak earnings.
Fourth, track actual Vera Rubin 300 shipments and HBM configurations. The move from 384GB HBM4 to 512GB HBM4E around the third quarter of 2027 is a critical milestone in UBS’s demand model. Any platform delay or further configuration change would require both total-demand and pricing assumptions to be revisited.
Fifth, monitor HBM4E pricing and yields. Pricing above $30/GB demonstrates revenue potential, but yields and stacking and packaging costs determine profitability. Higher pricing without gross-margin expansion usually indicates that cost control or cost improvements have not kept pace, with rising costs offsetting the price increase.
Sixth, track four NAND pricing measures: bare-die spot prices, contract prices, enterprise SSD prices, and the storage value of complete systems. Weakness confined to spot prices while enterprise SSD orders remain stable would still indicate divergence. A cycle reversal becomes more plausible only if all four pricing and order indicators decline together.
Seventh, monitor capital expenditure and actual capacity. UBS models approximately $47.8 billion and $45.8 billion of capital expenditure in FY2027 and FY2028, respectively. These are substantial investments. If new supply comes online faster than demand, both pricing and margins will come under pressure. If spending is concentrated on technology migration and HBM capability, near-term supply elasticity may be lower than the headline figures imply.
Eighth, watch free cash flow. Approximately $421.7 billion in aggregate free cash flow across FY2026–FY2028 is essential to converting high modeled earnings into cash reality. If profit growth fails to translate into cash, the problem will usually lie in inventory, receivables, capital expenditure, or tax assumptions.
Ninth, monitor consensus expectations. UBS’s EPS estimates exceed consensus by 28% in 2027 and 59% in 2028, a gap that cannot persist indefinitely. Either UBS must revise down or the market must revise up. The direction of estimates after each earnings release will say more about whether the $1,625 framework is being validated than any single day’s share-price move.
Taken together, the conclusion is clear: near-term cooling in NAND is real, but for now it merely reduces the slope of 2027 earnings growth. The extension of DRAM tightness, higher HBM4E pricing, and increased system shipments will determine the 2028–2029 earnings plateau. UBS is maintaining its $1,625 target not because the negative developments are irrelevant, but because they occur earlier and carry less weight, while the positive developments arrive later and carry more.
The framework’s greatest strength is that it no longer depends on a high 15x multiple. Its greatest vulnerability is the requirement for EPS to reach $165 in 2029. Determining whether the thesis is right does not require debating whether Micron is an AI company. The test is simply whether contract prices, HBM4E, yields, capital expenditure, and free cash flow emerge quarter by quarter as modeled. The $1,625 target is unchanged; the standard for validating it has changed.
Related Reading
Rubin Ultra HBM Capacity Cut to 192GB: Supply and Power Constraints Drive Roadmap Downgrade