
Meta Update: $534 Billion in AI Capex, Instagram Reels Ad Prices Up 59%, and an $815 Price Target
目录
Key Takeaways
I. Advertising Returns Are the First Test for the Second Quarter
II. Instagram Reels Has Passed the Most Difficult Stage of Monetization
III. $534 Billion in Capital Expenditures Will Pressure Cash Flow First
IV. Free Cash Flow Reveals the Timing Gap in Investment Returns
V. How the $815 Price Target Is Derived
VI. Compute Leasing Does Not Yet Merit a Cloud-Business Valuation
VII. Messaging Provides a Second Monetization Path
VIII. Six Metrics to Watch Over the Next Four Quarters
IX. Conclusion
本内容基于公开资料和研报数据整理,不构成任何投资建议,不代表任何个人观点,仅供学习参考,请理性阅读
Meta’s advertising revenue is still expected to grow by more than 20% in the second quarter, while both pricing and engagement for Instagram Reels continue to improve. The key question is now whether this cycle of AI investment can sustainably lift advertising returns—and prove that incremental compute can generate sufficient revenue and profit before depreciation and capital expenditures weigh on cash flow.
Key Takeaways
The core advertising business continues to accelerate. Goldman Sachs expects Meta’s second-quarter 2026 revenue to reach $60.2 billion, up 26.8% year over year, with full-year revenue growth of 27.0%. Average US advertising CPM rose 26% sequentially and 8% year over year, indicating that growth is being driven not only by users and engagement, but also by advertisers’ willingness to pay more for higher conversion rates.
Reels is beginning to contribute through pricing. Instagram Reels ad prices rose 59% year over year, significantly outpacing the 2% increase for Feed and 11% for Stories. Reels accounts for approximately 52% of time spent on Instagram and nearly 53% of ad impressions. The previous concern that Reels would cannibalize higher-priced Feed ads is now turning into a new source of incremental revenue.
Meta is set to spend $534 billion over the next three years. The model forecasts Meta’s capital intensity rising from 54.9% in 2026 to 60.2% in 2028. While revenue growth should remain sufficient to support operating-profit growth, depreciation and amortization will rapidly catch up, putting pressure on both margins and free cash flow.
Cash flow is the most valuation-sensitive variable. Free cash flow is projected to fall to $29.5 billion in 2027, or just $4.6 billion after stock-based compensation. Revenue is still expected to grow 20.1% that year, while GAAP operating profit reaches $106.8 billion. The income statement appears resilient, but the cash effectively available to shareholders is thin. This disconnect is likely to amplify share-price volatility.
The $815 price target depends on two valuation frameworks holding simultaneously. Goldman Sachs assigns equal 50% weightings to a GAAP operating-profit valuation and a forward free-cash-flow-after-stock-based-compensation valuation. Based on the report’s reference share price of $600.29, the $815 target implies approximately 36% upside.
Compute leasing appears more like a construction timing mismatch. Meta is expected to make some compute capacity available to external customers beginning in the second half of 2026. Goldman Sachs views this primarily as a mismatch between data-center completion schedules and internal model demand, rather than evidence of a sustainable cloud-services advantage. This assessment would need to be revised downward if external leasing continues to expand without a corresponding improvement in internal advertising returns.
I. Advertising Returns Are the First Test for the Second Quarter
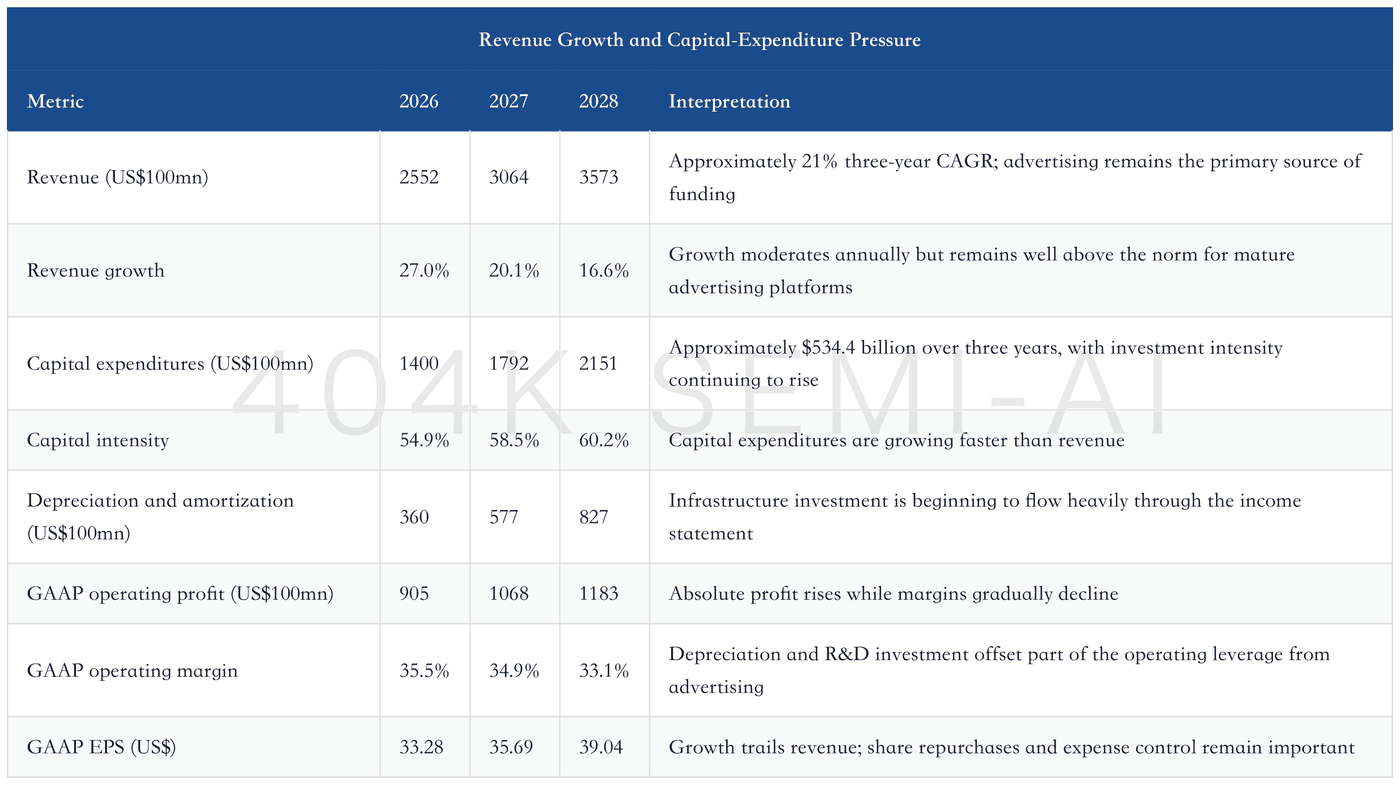
Advertising pricing currently provides the most valuable signal for Meta. Goldman Sachs expects the company to generate second-quarter 2026 revenue of $60.242 billion, up 26.8% year over year, and full-year 2026 revenue of $255.176 billion, up 27.0%. At a time when major global internet platforms are broadly increasing AI investment, Meta’s ability to sustain revenue growth above 20% suggests that improvements in ad ranking, content recommendations, and creative generation are translating into commercial results rather than merely increasing server demand.
US advertising-pricing data tracked by Goldman Sachs show that Meta’s average CPM rose 26% sequentially and 8% year over year. Higher ad prices generally reflect one of two factors: more intense competition among advertisers, or the platform’s ability to deliver better click-through, conversion, and sales returns. It is difficult to isolate these effects based on a single quarter, but when considered alongside Instagram engagement, Reels ad pricing, and company revenue forecasts, improved platform efficiency is the more compelling explanation.
This shift is important for valuation. Meta’s AI capital spending has already entered the $100 billion range, and the market will not reward the company merely for having stronger models or more accurate recommendations. Investors need evidence that each incremental unit of compute generates more ad impressions, higher ad pricing, or lower customer-acquisition costs. Second-quarter revenue growth and ad pricing provide the first meaningful dataset for evaluating returns on this investment.
II. Instagram Reels Has Passed the Most Difficult Stage of Monetization
Reels’ share of traffic and advertising impressions has nearly converged. Industry data cited by Goldman Sachs indicate that Reels accounted for approximately 52% of time spent on Instagram in the first quarter of 2026 and approximately 53% of ad impressions in the fourth quarter of 2025. The close alignment suggests that Meta has largely integrated Reels traffic into its advertising system, with monetization density no longer materially lagging user attention.
The stronger signal comes from pricing. In the second quarter of 2026, Instagram Feed ad prices rose 2% year over year, Stories prices increased 11%, and Reels prices climbed 59%. Reels’ substantial outperformance indicates growing advertiser acceptance of the placement. In its early stages, Reels growth displaced time spent in Feed without monetizing at comparable prices. That drag is now beginning to reverse, allowing engagement growth to translate more directly into revenue.
Time spent on Instagram is also increasing. US users now spend approximately 58 minutes per day on the platform, while global users spend approximately 75 minutes, compared with only 37 minutes and 52 minutes, respectively, in the second quarter of 2021. In the second quarter of 2026, total time spent on Instagram is expected to increase 15% globally and 13% in the US, while global monthly active users grow 3%. With user growth remaining modest, revenue growth increasingly depends on higher time spent per user, greater ad density, and stronger pricing.
These data give Meta three layers of revenue leverage: recommendation systems increase time spent, Reels expands sellable ad inventory, and advertising models monetize those incremental impressions at higher prices. The risk is equally clear. If Reels ad-price growth decelerates sharply while engagement and ad density are already approaching their ceilings, revenue growth will once again become more dependent on macro advertising demand.
III. $534 Billion in Capital Expenditures Will Pressure Cash Flow First
Revenue growth can absorb the investment for now, but cash flow cannot. Meta continues to accelerate construction of data centers, servers, networking equipment, and related infrastructure.
Total three-year investment is projected at approximately $534.4 billion. The model forecasts annual capital intensity rising from 54.9% to 60.2%, with each hardware-refresh cycle requiring more cash.
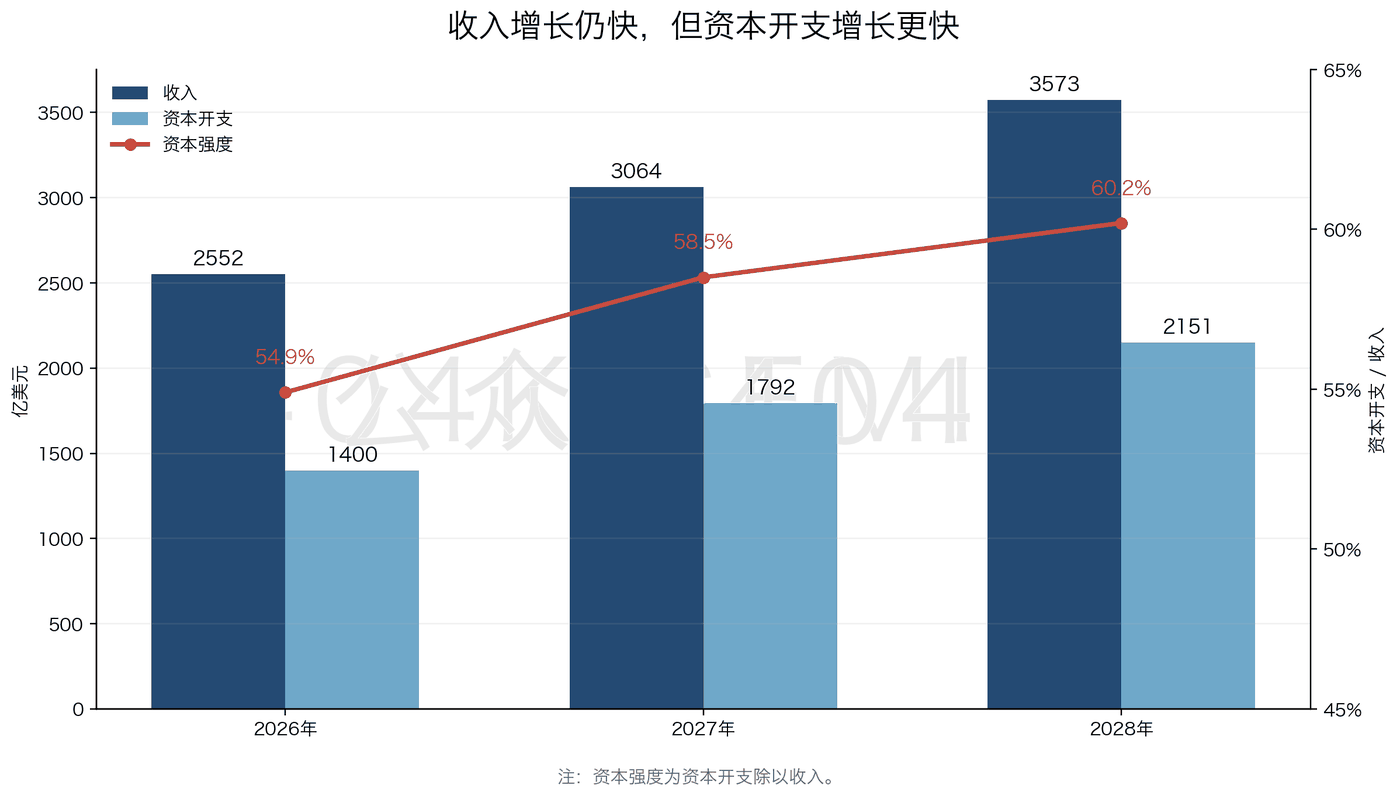
Capital expenditures initially enter the balance sheet and are then depreciated over the useful lives of equipment and data centers. Cash-flow pressure therefore emerges first, followed by increasingly visible margin pressure. The model forecasts depreciation and amortization rising from $36.0 billion in 2026 to $82.7 billion in 2028, nearly doubling. GAAP operating profit continues to grow over the same period, but the operating margin declines progressively.
Microsoft, Google, Meta, and Amazon Q1: AI Demand Holds Up as Capex Surges, Cloud and Advertising Accelerate, and Cash Flow Comes Under Pressure
The timing gap between capital expenditures and depreciation is one of the easiest aspects of the model to underestimate. Equipment purchased in 2026 will continue to generate depreciation charges for years. Even if Meta slows incremental investment in a given year, legacy projects will continue to weigh on margins. Meta must keep incremental gross profit from advertising and messaging ahead of depreciation growth to avoid a simultaneous combination of revenue growth, margin contraction, and declining cash flow.
IV. Free Cash Flow Reveals the Timing Gap in Investment Returns
2027 represents the cash-flow trough in the model. Goldman Sachs expects Meta’s free cash flow to decline to $29.5 billion that year, with only $4.6 billion remaining after stock-based compensation, before gradually recovering. Revenue and operating profit continue to grow, yet cash flow falls materially because capital expenditures precede the realization of incremental revenue.
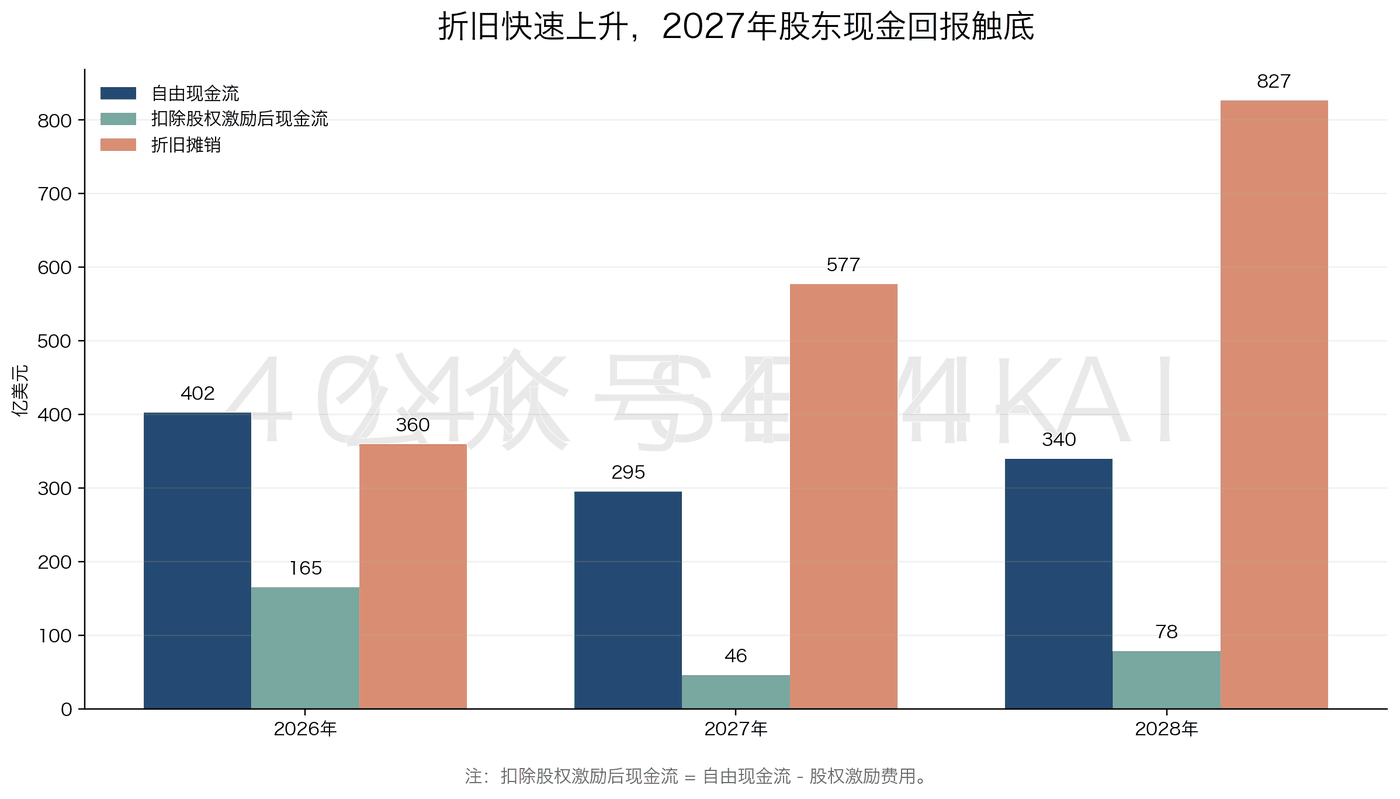
Cash flow after stock-based compensation warrants separate attention. Stock-based compensation does not require a current-period cash payment, but it increases shares outstanding and dilutes per-share value. Deducting it from free cash flow provides a closer approximation of the economic return accruing to common shareholders. At just $4.6 billion in 2027, this metric is extremely thin for a platform company valued at more than $1 trillion, forcing Goldman Sachs to use more distant forward cash flow in its valuation.
For the market to tolerate near-term cash-flow deterioration, two conditions must be met. First, advertising revenue must continue growing at close to 20%, demonstrating that returns from internally deployed compute are real. Second, capital-expenditure growth must gradually fall below revenue growth after 2028, allowing free cash flow to expand again. If either condition fails, a 45x forward cash-flow multiple will appear excessively expensive.
$1.7 Trillion in Backlog, $650 Billion in Capex, and a Seventh Compute Partner: Google, Meta, Microsoft, and Amazon Enter the Era of Long-Term AI Contracts
V. How the $815 Price Target Is Derived
The price target requires both resilient profitability and a recovery in forward cash flow. Goldman Sachs lowered its Meta price target from $830 to $815 while maintaining a Buy rating. The report uses two enterprise-value methodologies, each with a 50% weighting: one based on GAAP operating profit one year beyond the next 12 months, and the other on free cash flow after stock-based compensation four years beyond the next 12 months.
The operating-profit methodology applies a 26x enterprise value-to-GAAP operating profit multiple, up from 24x previously. The forward cash-flow methodology applies a 45x enterprise value-to-free cash flow after stock-based compensation multiple, up from 40x, and discounts the result back three years at a 12% rate. The combination of higher multiples and a lower price target reflects greater caution regarding near-term cash flow and expense pressure, while the valuation framework assigns a higher premium to long-term growth from AI.
