
Memory Pullback: Buy the Dip or Clear Out? Watch These Five Signals First
目录
Too Long; Didn’t Read
1. After the Memory Pullback, Do Not Rush to Ask Whether to Buy or Sell
2. Three Worldviews: Not a Cycle Bottom, Possibly Not the Peak, but Profit Quality Must Be Dissected
III. Where DDR4 Is Actually Tight: Legacy Capacity Has Been Crowded Out by HBM and DDR5, While Customer Migration Is Not That Fast
IV. HBM and DRAM Long-Term Agreements: Highest Purity Does Not Mean Highest Upside
V. Where eSSD Is Actually Expensive: Qualification Slots, Controller Firmware, and LTAs Matter More Than NAND Price Hikes
VI. Where HDD Cash Flow Comes From: Cloud Customers Lock Nearline Capacity, HAMR Determines How Long Profits Can Stay
7. How to Track Representative Companies: Do Not Use the Same Yardstick for Micron, SanDisk, Western Digital, Samsung, and SK Hynix
Target-Price Revisions Cannot Be Ranked Directly; They Must Be Split into Five Layers of Assumptions
A-Share Mapping: Inventory Profit and Platform Profit Must Be Separated
During Pullbacks, Distinguish Between Valuation Compression, Earnings Compression, and Narrative Compression
The Most Important Counterevidence: Inventory, Contracts, Supply, Customers, and Cash Flow
8. How to Validate the Next Four Quarters
9. Five Common Misreadings
10. Portfolio Positioning: Four Asset Types Cannot Use the Same Sizing Logic
XI. Industry Position: Memory Is Not a Supporting Actor in AI Hardware, but the Second Battleground for Profit Allocation
XII. Conclusion: Before Buying In or Exiting, First Check Whether the Five Signals Are Aligned
本内容基于公开资料和研报数据整理,不构成任何投资建议,不代表任何个人观点,仅供学习参考,请理性阅读
After memory stocks rally sharply and then pull back 20%-30%, the key is not to shout “buy the dip” or “clear out,” but to determine whether the pullback is hitting valuation, positioning, or fundamentals. Prices, contracts, inventory, supply, and cash flow are the reference points for Micron, SanDisk, Western Digital, Samsung Electronics, and SK Hynix. They help distinguish valuation retracement from earnings downgrades.
Too Long; Didn’t Read
After memory pulls back 20%-30%, the worst mistake is to decide “buy” or “sell” with one sentence. Prices have already risen through one round, and sell-side estimates have been revised up many times. The pullback itself does not prove the cycle is over. The real focus should be five signals: whether prices have broken, contracts have softened, inventory has piled up, supply has lost control, and cash flow has kept pace with profits.
The first signal is whether pricing and orders have deteriorated. If DDR4, DDR5, NAND, eSSD, and nearline HDD prices still have contract-price support, the pullback is more likely a valuation and positioning adjustment. If customers begin rejecting price hikes, delaying orders, or if eSSD EB or nearline EB growth slows, the pullback may shift from valuation compression to earnings compression.
The second signal is whether long-term agreements and customer qualifications are firm. For Micron, watch SCA/LTA terms. For Micron, SK Hynix, and Samsung Electronics, watch HBM4 qualification and customer share. For SanDisk, watch eSSD qualification and NAND long-term agreements. What truly matters is contract duration, floor price, prepayment, take-or-pay, and cancellation cost, not soft language such as “customer demand is strong.”
The third signal is whether inventory and cash flow are diverging. Memory most easily embeds risk when the income statement looks best. If ASPs rise and gross margins improve, but inventory, receivables, and capex all rise while operating cash flow fails to keep up, earnings quality is starting to deteriorate. Micron, SanDisk, Western Digital, Samsung Electronics, and SK Hynix all need to answer this question through FCF and capex discipline.
The fourth signal is whether supply has begun responding to high profits. For DRAM, watch whether HBM/DDR5 continues to crowd out commodity capacity. For NAND, watch whether 2028 new capacity and WFE are pulled forward. For DDR4, watch whether legacy lines return. For HDD, watch HAMR/Mozaic yields and cost per EB. Once supply expands without constraint, memory returns to the traditional cycle framework.
The fifth signal is whether each company’s own core variables have loosened. For Micron, watch HBM catch-up, SCA/LTA, and conventional DRAM ASPs. For SanDisk, watch eSSD share, NAND long-term agreements, and 2028 supply. For Western Digital, watch nearline HDD, HAMR, and FCF. For Samsung Electronics, watch HBM qualification and full-category profit. For SK Hynix, watch HBM share, yield, and valuation crowding. These are reference indicators, not mechanical buy-or-sell conclusions.
1. After the Memory Pullback, Do Not Rush to Ask Whether to Buy or Sell
After a sharp memory rally, a 20%-30% pullback naturally leads readers to ask: is this the time to buy, or the time to clear out? This question cannot be answered directly, because the same pullback can have completely different drivers. Valuation compression, position unwinds, earnings compression, and narrative compression all look like price declines, but they mean very different things.
If it is only valuation compression, it means the earlier rally was too fast and positioning too crowded, but prices, orders, contracts, and cash flow have not deteriorated. If it is earnings compression, it means customers are rejecting price hikes, contract prices are weakening, orders are delayed, or inventory is worsening, and subsequent EPS may be revised down. If it is narrative compression, it means the larger framework around AI demand, long-term agreements, supply discipline, or cash flow is being questioned. That is more serious than single-quarter volatility.
This report does not try to judge “tomorrow’s move.” A more useful approach is to break the pullback into five reference signals: prices, contracts, inventory, supply, and cash flow. As long as most of these indicators have not deteriorated, the pullback looks more like valuation and positioning volatility. If two or three of them weaken at the same time, the risk may be more than a short-term drawdown.
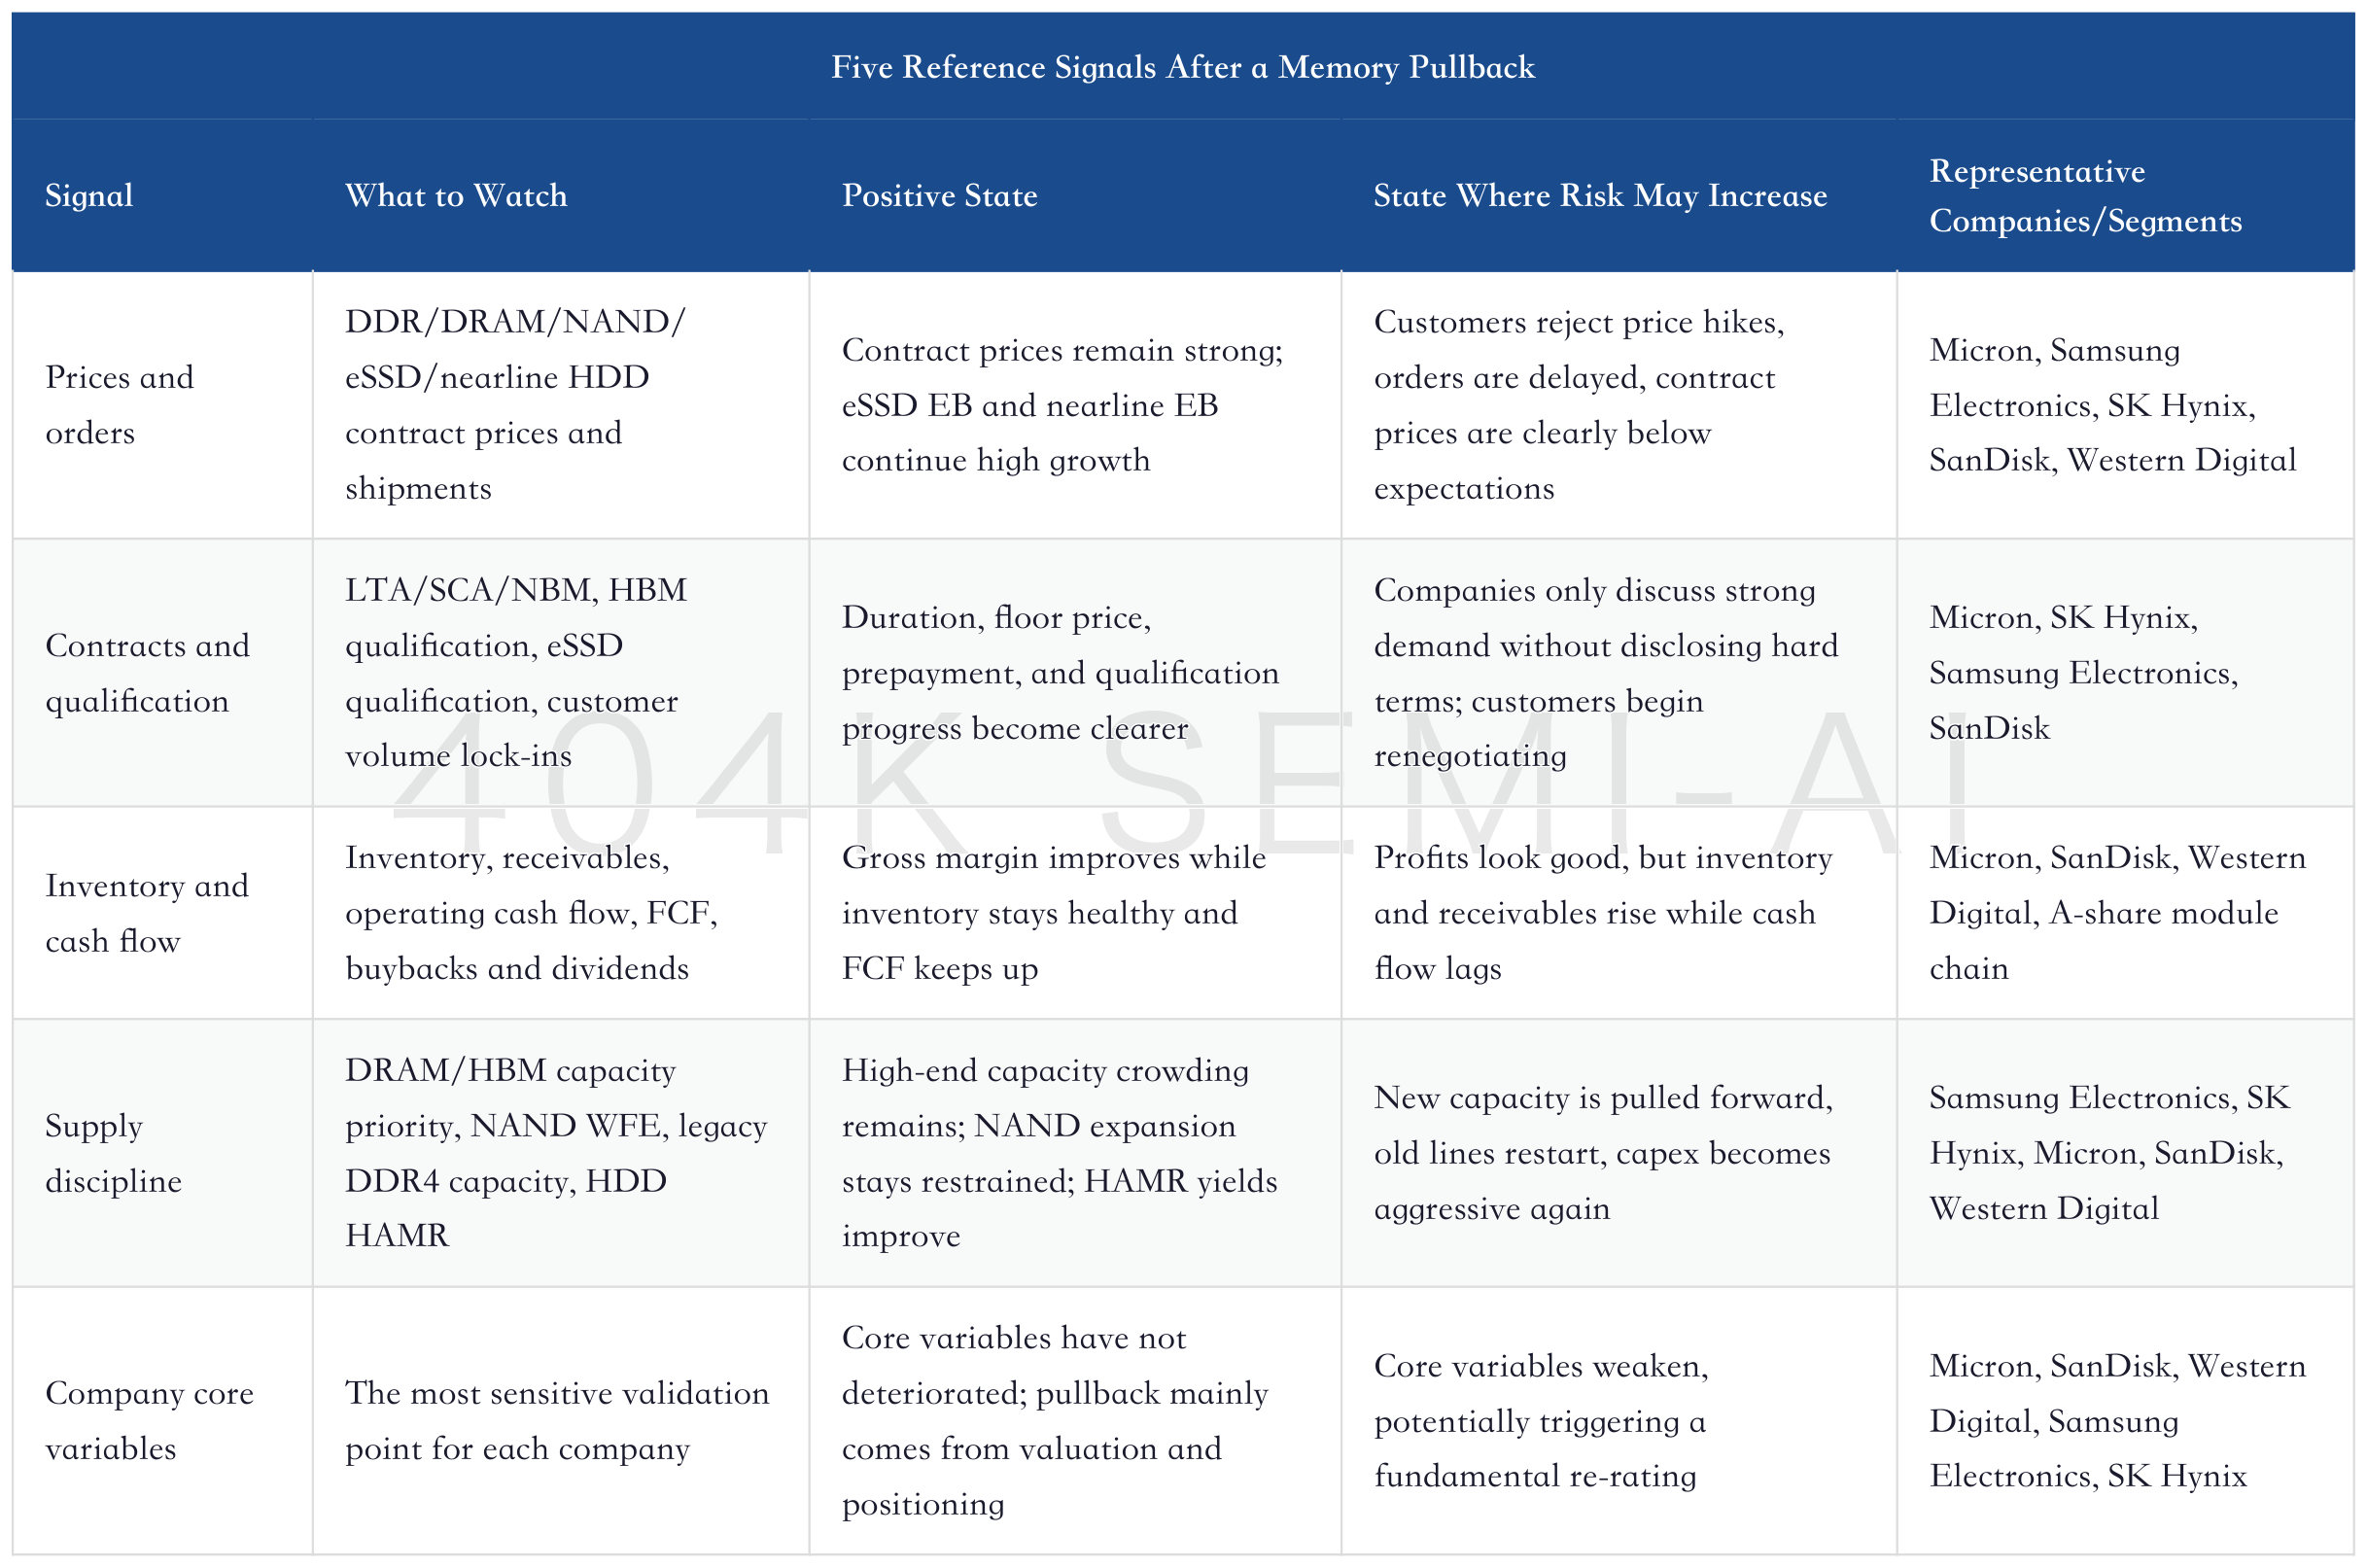
The use of these five signals is simple. Prices prove whether the cycle is still intact. Contracts prove whether customers are truly afraid of shortages. Inventory proves whether demand has been pulled forward. Supply proves whether suppliers will turn high profits into the next round of oversupply. Cash flow proves whether profits are being retained. After a pullback, the real value is not in guessing the bottom, but in seeing whether these five pieces of evidence point in the same direction.
AI Drives a Sector-Wide Re-Rating of Memory: Who Has the Most Pricing Power Across DRAM, NAND, SSD, and HDD, with Samsung, Hynix, SanDisk, Western Digital, and Seagate Earnings Cross-Checking One Another
The earlier discussion explained why DRAM, NAND, SSD, and HDD are all entering the AI data stack. What matters more now is separating the quality of that “benefit.” AI can push demand higher, but only contracts and cash flow can keep the profits.
2. Three Worldviews: Not a Cycle Bottom, Possibly Not the Peak, but Profit Quality Must Be Dissected
The same set of data can be explained by three worldviews. The first is a cycle peak: prices surge, customers pull forward inventory, supplier profits hit highs, and then supply returns, inventory reverses, and valuations contract. The second is structural upcycle: AI lifts the demand center for HBM, DDR5, eSSD, nearline HDD, and mature DDR4, lengthening the industry cycle while still preserving volatility. The third is profit re-rating: customers use long-term agreements, prepayments, and locked orders to buy supply certainty, and memory-company profits begin to receive higher multiples.
These three worldviews are not an abstract debate. They directly determine company ranking. If one believes this is a cycle peak, one should buy the names with the fastest earnings beta, but avoid overstaying. If one believes in structural upcycle, one should buy companies with the highest AI purity and strongest customer qualifications. If one believes in asset re-rating, one should buy companies with hard contracts, strong cash flow, and clear capex discipline.
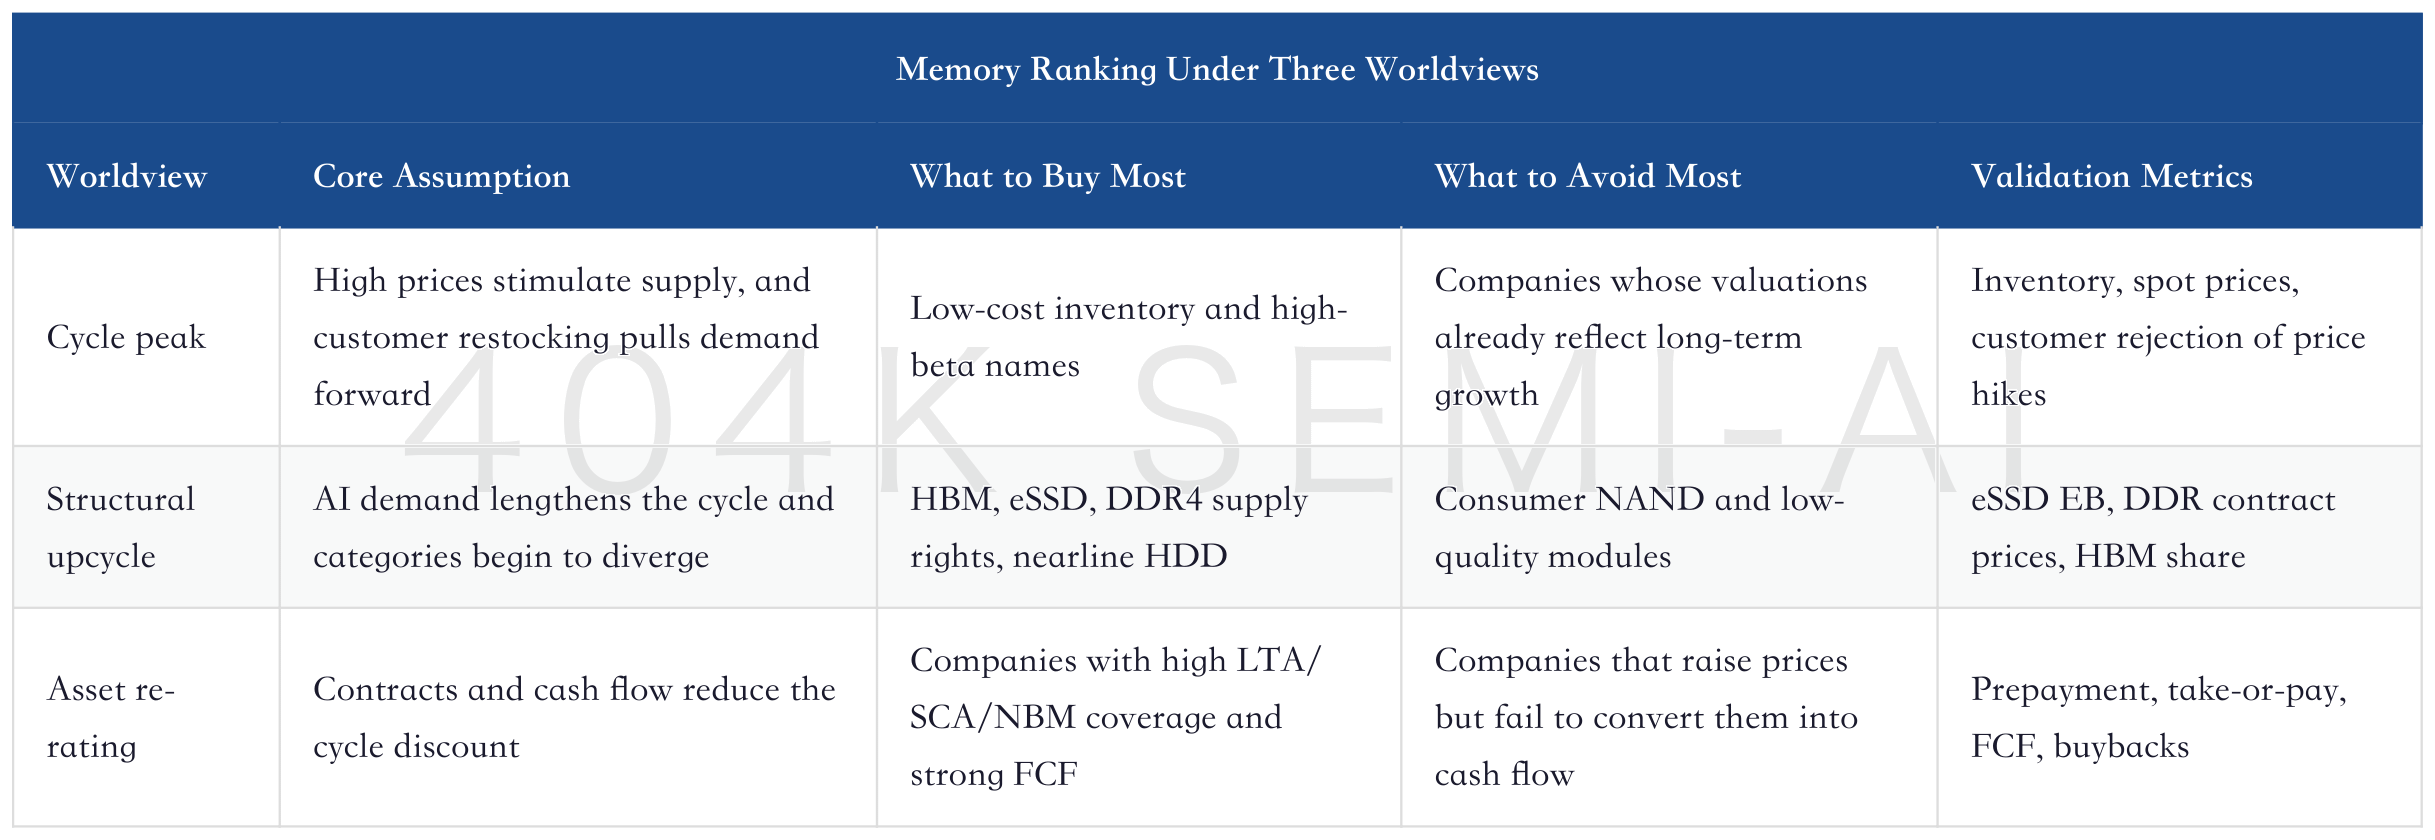
Current evidence is closer to somewhere between the second and third views. Prices have already proven the cycle upturn. AI demand has already proven structural change. Contracts and cash flow are proving asset re-rating, but the validation is not fully complete. In other words, memory can no longer be crudely valued as a “traditional cyclical stock,” but one also cannot declare prematurely that memory has fully escaped the cycle.
This distinction is important. Historically, memory has most often seen its lowest valuation when EPS is at its highest, because the market knows high profits will attract supply. But if LTAs and SCAs genuinely bind customers, prepayments improve cash flow, customer qualifications raise replacement costs, and capex discipline does not lose control, then this round of high profit is no longer just peak profit. It gradually becomes discountable profit.
In-Depth Memory Update: 3Q26 DDR Prices Up 32%, 2027 DRAM Demand +36%, UBS Monthly Report Calibrates the Memory Supercycle
This is also why the July memory monthly report matters. It not only revises up prices, but also places supply-demand gaps, LTA/SCA, capacity conflicts between HBM and conventional DRAM, and cash-flow issues in NAND and HDD into one framework. Price increases are the result. Supply discipline and customer commitments are the cause.
The authenticity of long-term agreements is the most important dividing line at this stage. A real long-term agreement must answer at least five questions: how long the term is, how volume is determined, how price floats, whether there is a downside floor, and how high the customer’s breach cost is. As long as these questions remain unclear, long-term agreements can only count as a qualitative positive. Once these questions enter disclosure, the market has reason to discount future revenue and profit forward.
Prepayment is especially important. In a long-term agreement without prepayment, customers have strong incentives to renegotiate in a downturn. In a long-term agreement with prepayment, customers are effectively exchanging cash for supply certainty, and suppliers can more easily bind future capacity planning to cash flow. For memory stocks, prepayment is not just a balance-sheet item. It is evidence of customer pain. Whether customers are willing to pay in advance directly indicates how large the shortage risk is in their minds.
The pricing mechanism is also critical. Fully fixed pricing looks the firmest, but it is not necessarily best for suppliers because it sacrifices upside leverage. Fully floating pricing looks flexible, but it does not provide enough value to buyers seeking to lock in supply. A more realistic structure is a hybrid of fixed volume, fixed floor price, partial floating price, and shared upside. Such a contract gives customers certainty while allowing memory suppliers to retain profit leverage in a rising-price cycle.
Take-or-pay is another dividing line. A contract with a minimum purchase obligation is completely different from an ordinary long-term purchase intention. Long-term agreements are not new in memory history, but many have been delayed, renegotiated, or softened when prices reversed. Only when customers truly bear cancellation costs do suppliers have reason to allocate capacity for them, and only then does the market have reason to reduce the cycle discount.
Third-party guarantees and capex support also cannot be ignored. Large cloud customers have strong credit, but contract enforceability is not only about credit; it is also about mechanism. The clearer the guarantees, prepayments, supporting capex, supply priority, and delivery terms, the more memory manufacturers resemble order-based producers. The more vague the terms, the more they resemble sentiment commitments at the top of the cycle.
Therefore, the investment value of memory long-term agreements lies not in the words “signed,” but in the hardness of the terms. Whenever any company discloses an LTA, SCA, or NBM in the future, the terms should be dissected first, and valuation considered afterward. Contract duration and coverage determine revenue visibility. Pricing mechanisms determine gross-margin visibility. Prepayment and take-or-pay determine cash-flow visibility. Only when all three are firm is it a true asset re-rating.
III. Where DDR4 Is Actually Tight: Legacy Capacity Has Been Crowded Out by HBM and DDR5, While Customer Migration Is Not That Fast
DDR4 prices are not rising because the product is advanced, but because legacy capacity has been crowded out. Major suppliers have shifted capacity, equipment, engineering resources, and customer priority toward HBM, DDR5, and AI products, slowing the recovery of mature DRAM supply. At the same time, customers in server cache memory, communications, industrial control, automotive, and parts of LPDDR4 cannot migrate immediately. Supply is unwilling to return, demand cannot leave right away, and DDR4 has therefore moved from mature tail-end inventory to a critical mature component.
Nanya Technology being upgraded to Overweight with a target price raised to NT$710 is a concentrated expression of this logic. It is not an HBM company. Precisely because it is not an HBM company, it is a better test of the legacy DRAM shortage. What the market is buying in Nanya is not technology leadership, but how long DDR4/LPDDR4 can keep rising, how large server exposure can become, whether eSSD-grade memory can improve the mix, and whether LTAs can lock in gross-margin repair.
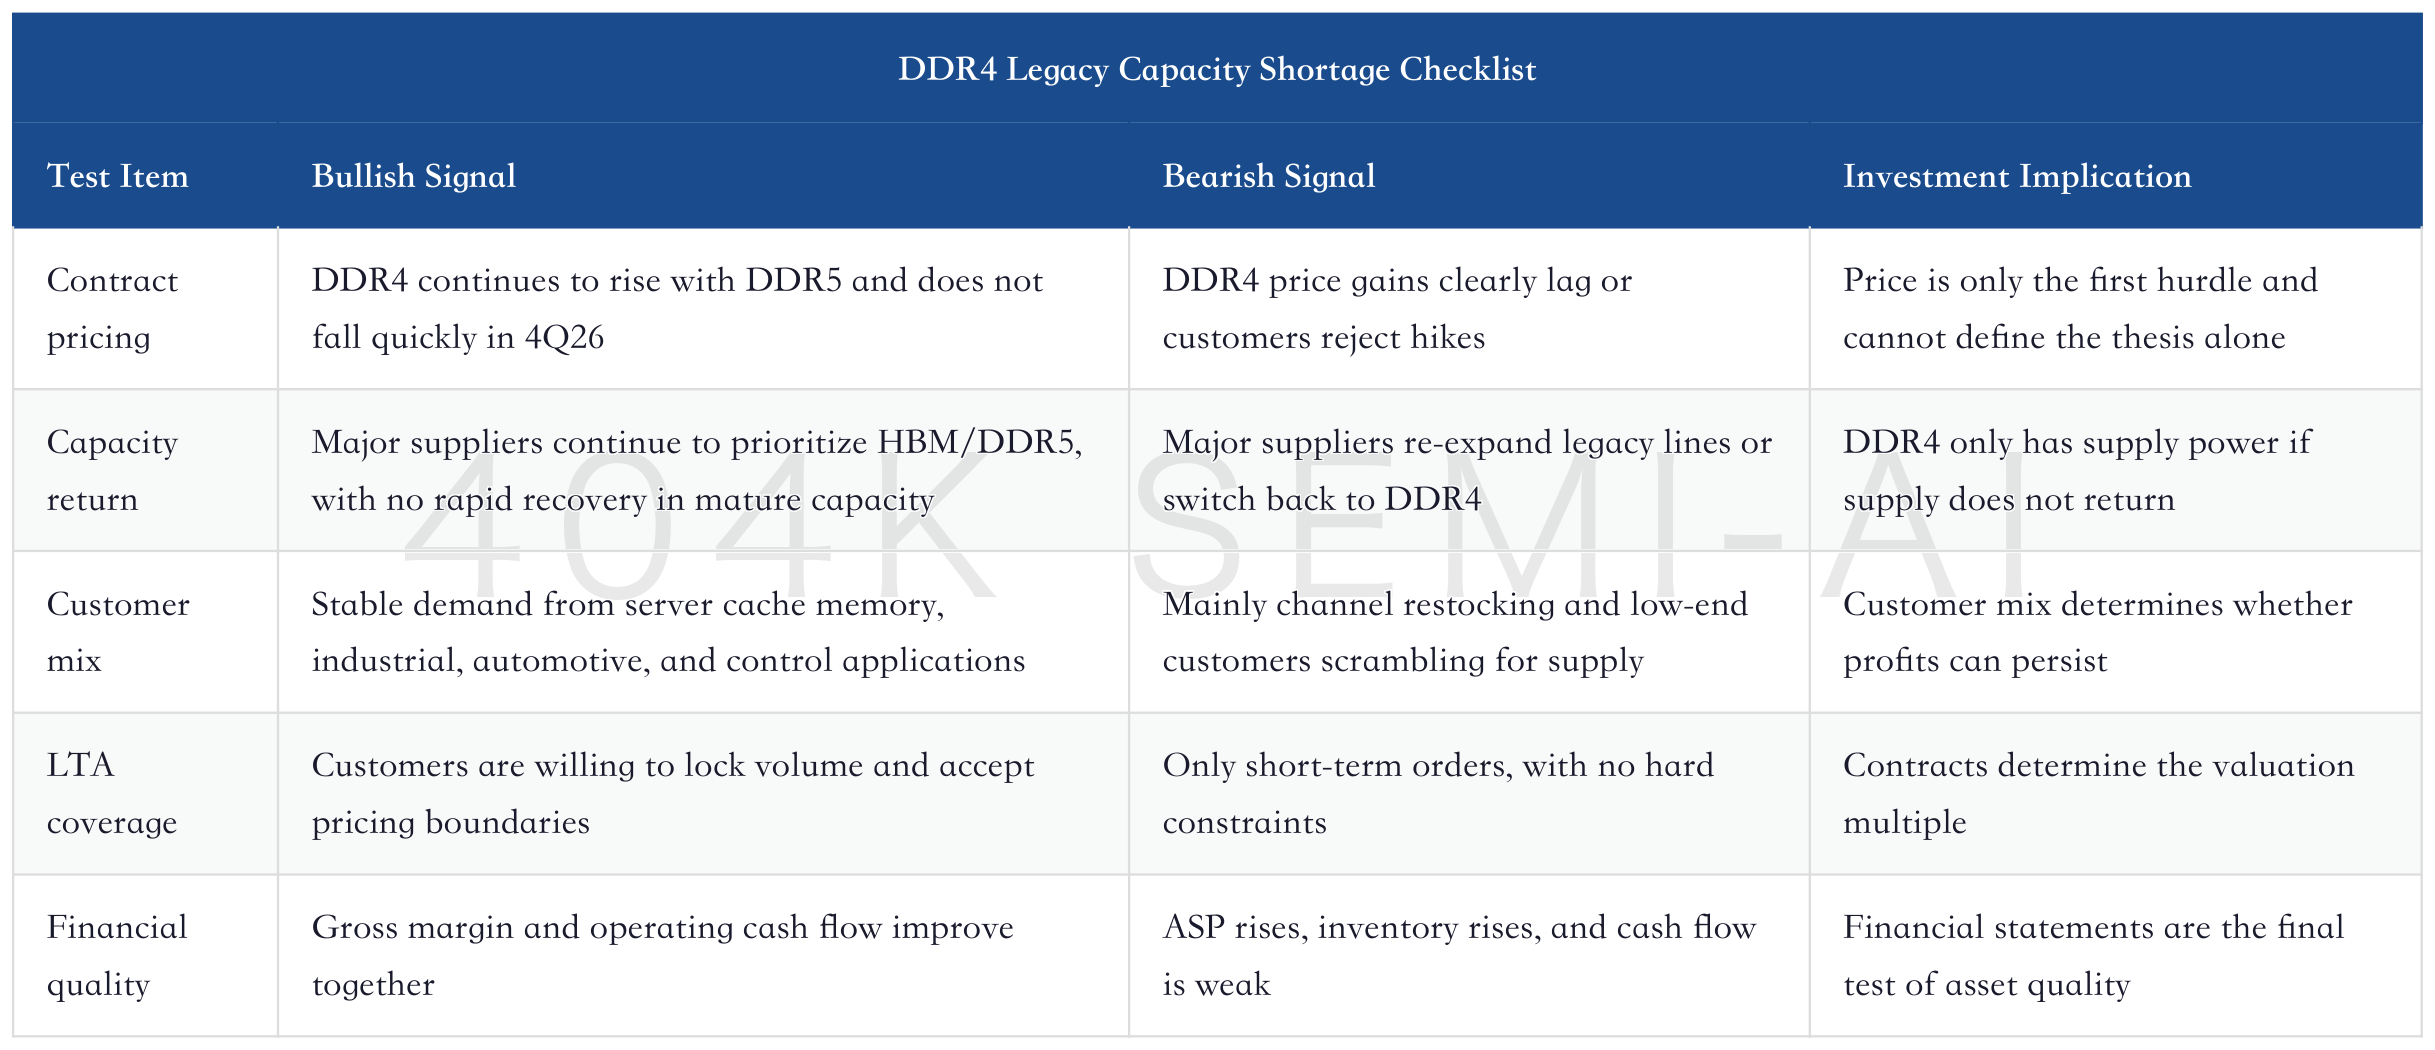
DDR4 is most easily misread as a “laggard product catching up.” That is only half right. DDR4 is indeed not the most advanced product, but value does not come only from advancement. It also comes from customer substitution cost and the speed at which supply can return. When major suppliers actively abandon a mature category while customers still cannot stop using it immediately, it moves from low-end tail-end inventory to a critical mature component.
Nanya Technology Deep Dive: DDR4 EOL, SOCAMM Server Memory, and the NT$710 Target Price; the Three Tests for Revaluing Second-Tier DRAM Makers
But DDR4 also faces two key disconfirming signals. The first is prices rising too quickly, causing customers to pull forward purchases, after which inventory and cash flow deteriorate. The second is suppliers reopening legacy capacity after seeing high profits, breaking supply discipline. As long as these two disconfirming signals do not appear, DDR4 can continue to be viewed as a supply-rights asset. Once they appear, it will quickly revert to traditional cyclical beta.
Mature-memory exposures such as GigaDevice, Winbond, Macronix, Beijing Ingenic, Puya Semiconductor, and Dosilicon should be assessed with the same framework. Not every legacy category deserves a revaluation. Only those legacy categories where customers still need the product, supply cannot return, and profits can be retained deserve one. The logic for NOR and SLC NAND is more “small capacity, but indispensable,” while DDR4 is more “legacy capacity crowded out by AI.” The common denominator is supply power.
IV. HBM and DRAM Long-Term Agreements: Highest Purity Does Not Mean Highest Upside
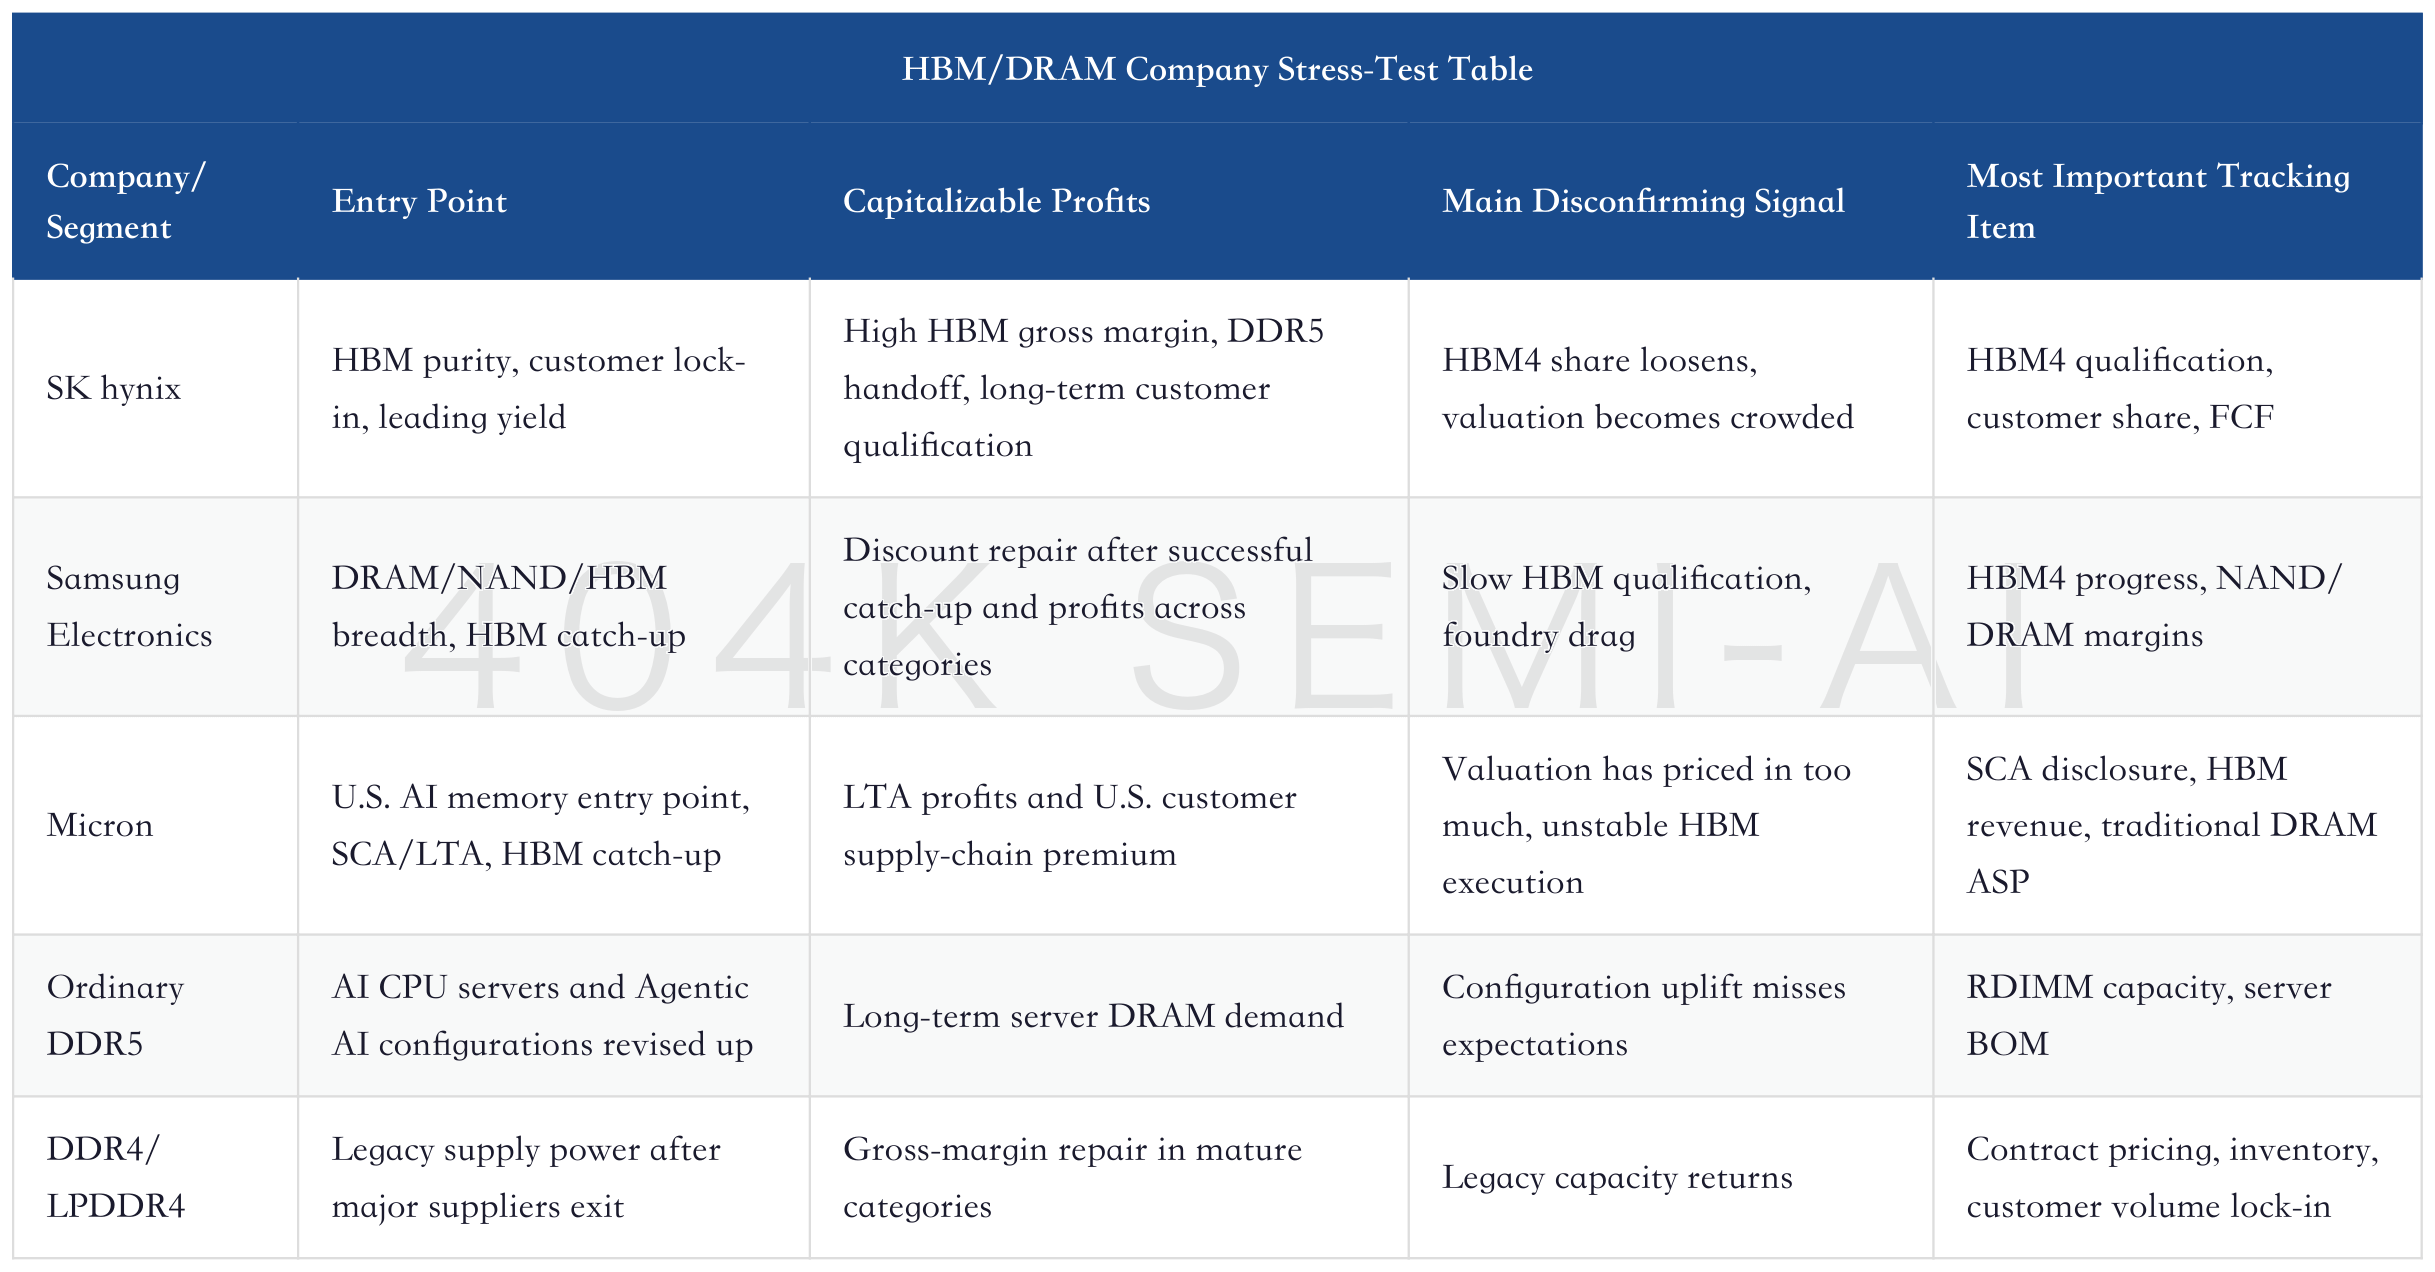
HBM is the highest-AI-purity asset across the memory chain, and it is also the most crowded valuation asset. SK hynix, Samsung Electronics, and Micron are all on this line, but investors are buying different things in each. SK hynix is about leading share and customer lock-in. Samsung Electronics is about catch-up repair and breadth. Micron is about the U.S. AI memory entry point and DRAM/scenario beta.
HBM does not need to prove that demand is strong. What it really needs to prove is share, pricing, yield, advanced packaging, and customer qualification. The stronger HBM becomes, the more it squeezes effective capacity for ordinary DRAM and NAND, thereby supporting DDR5, DDR4, and parts of NAND pricing. This is HBM’s spillover value: it does not only make money itself; it also changes the entire memory supply curve.
JPM’s LTA framework is critical because it breaks “customers want to lock supply” into testable terms: duration, prepayment, price floor, fixed/floating pricing, take-or-pay, third-party guarantees, and capex support. Without these terms, long-term agreements are just verbal comfort. With these terms, LTAs can reduce the cyclical discount.
Micron Earnings Deep Dive: Q3 Results Far Above Expectations, the AI Memory Supercycle Enters the Delivery Phase, and How Much Profit Can LTAs Lock In?
Micron is the key sample in this round of long-term-agreement signals. It may not be the cheapest memory stock, but it best illustrates whether “cyclical EPS can be locked by U.S. AI customers into longer-duration cash flow.” If SCA/LTA terms become increasingly clear and customer prepayments or deferred revenue begin to enter the financial statements, the market will be more willing to reprice Micron from a high-beta cyclical stock into the U.S. AI memory entry point.
The divergence between Samsung Electronics and SK hynix is more like a choice between “purity and odds.” SK hynix has higher purity, but valuation and expectations are also more crowded. Samsung Electronics has lower purity than SK hynix, but if HBM4 qualification advances and NAND and ordinary DRAM recover at the same time, the upside may be higher. In the second half of the memory cycle, the right question is not only who is strongest, but how much of that strength has already been reflected and where the disconfirming signals lie.
SK hynix Deep-Dive Update: Is It Still Expensive? DDR5 Price Hikes Take Over, Korean Exports Surge, and Samsung Catch-Up Risk
The biggest risk on the HBM line is not a sudden disappearance of demand, but a change in competitive structure. As long as Samsung Electronics and Micron catch up faster than expected, SK hynix’s share and pricing assumptions will be revalued. If HBM4 qualification does not proceed smoothly, Samsung Electronics’ discount repair will be delayed. If customers begin to rebalance suppliers, all HBM companies will need their gross-margin and pricing curves reassessed.
HBM will also change ordinary DRAM through capacity squeeze. The market often looks at HBM, DDR5, and DDR4 separately, but manufacturing is not fully independent. HBM consumes advanced DRAM wafers, packaging resources, engineering teams, and customer coordination capacity. To pursue higher profits, suppliers will allocate their best resources to HBM and DDR5. As a result, the stronger high-end products become, the harder it is for mature and ordinary products to recover supply quickly.
This is also one reason DDR4, DDR5, and server DRAM prices can continue to strengthen. They are not all as high-end as HBM, but HBM has changed their supply priority. In the past, when mature DRAM prices rose, investors would ask when suppliers would expand legacy capacity. Now they also need to ask whether suppliers are truly willing to move resources back from HBM and DDR5 to legacy products. As long as the answer is no, mature DRAM still has supply power.
Micron has a dual attribute here. It is an HBM catch-up player, an ordinary DRAM cyclical-beta asset, and an entry point into the U.S. AI supply chain. Its upside comes from the overlap of three factors: a higher HBM revenue mix, strong traditional DRAM pricing, and greater visibility from customer LTAs and SCA. Any one of these alone looks cyclical, but when all three appear at the same time, the market will reconsider normalized profitability.
Samsung Electronics’ complexity also lies here. It is not a single HBM asset, but a combination of DRAM, NAND, HBM, foundry, and consumer electronics. Because it is broad, Samsung’s revaluation will not be as pure as SK hynix’s. Also because it is broad, as long as HBM qualification advances and NAND and ordinary DRAM repair at the same time, the market discount applied to it will decline. What Samsung most needs to prove is that breadth is not low purity, but a defensive and reversal combination under an extended all-category memory cycle.
SK hynix’s test is more direct. It needs to prove that HBM leadership is not a one-generation dividend, but sustained customer lock-in, yield, packaging capability, and product-roadmap leadership. If HBM4 remains ahead while DDR5 and ordinary DRAM prices take over, SK hynix can continue to enjoy high-quality profits. If share begins to loosen, crowded valuation will make the stock highly sensitive to even small disconfirming signals.
V. Where eSSD Is Actually Expensive: Qualification Slots, Controller Firmware, and LTAs Matter More Than NAND Price Hikes
NAND is the category the market most easily likes and doubts at the same time. Investors like it because AI data centers are driving demand for enterprise SSDs, high-capacity QLC, KV cache, RAG, data lakes, and object storage, with demand quality clearly better than handset and PC restocking. They doubt it because NAND has historically had weaker supply discipline. Once prices become too high, new capacity and customer resistance to price hikes can quickly become counterevidence.
The value of eSSD is not putting NAND dies into a drive enclosure. Data center customers want long-term stable supply, firmware reliability, controller capability, power consumption, capacity, error correction, power-loss protection, system compatibility, and failure-rate data. eSSDs that can enter CSP supply chains sell qualification slots and system reliability; NAND that cannot pass qualification remains more exposed to price cycles and channel inventory.
This round of the NAND bull case is no longer about “handset restocking.” AI NAND demand is rising from 205EB in 2025 to 609EB in 2027, and from 18% of total NAND demand to 41%. Enterprise/data-center SSD capacity shipments are up 139% YoY. These numbers show that the center of gravity in NAND demand is shifting from consumer electronics to the data-center capacity layer.
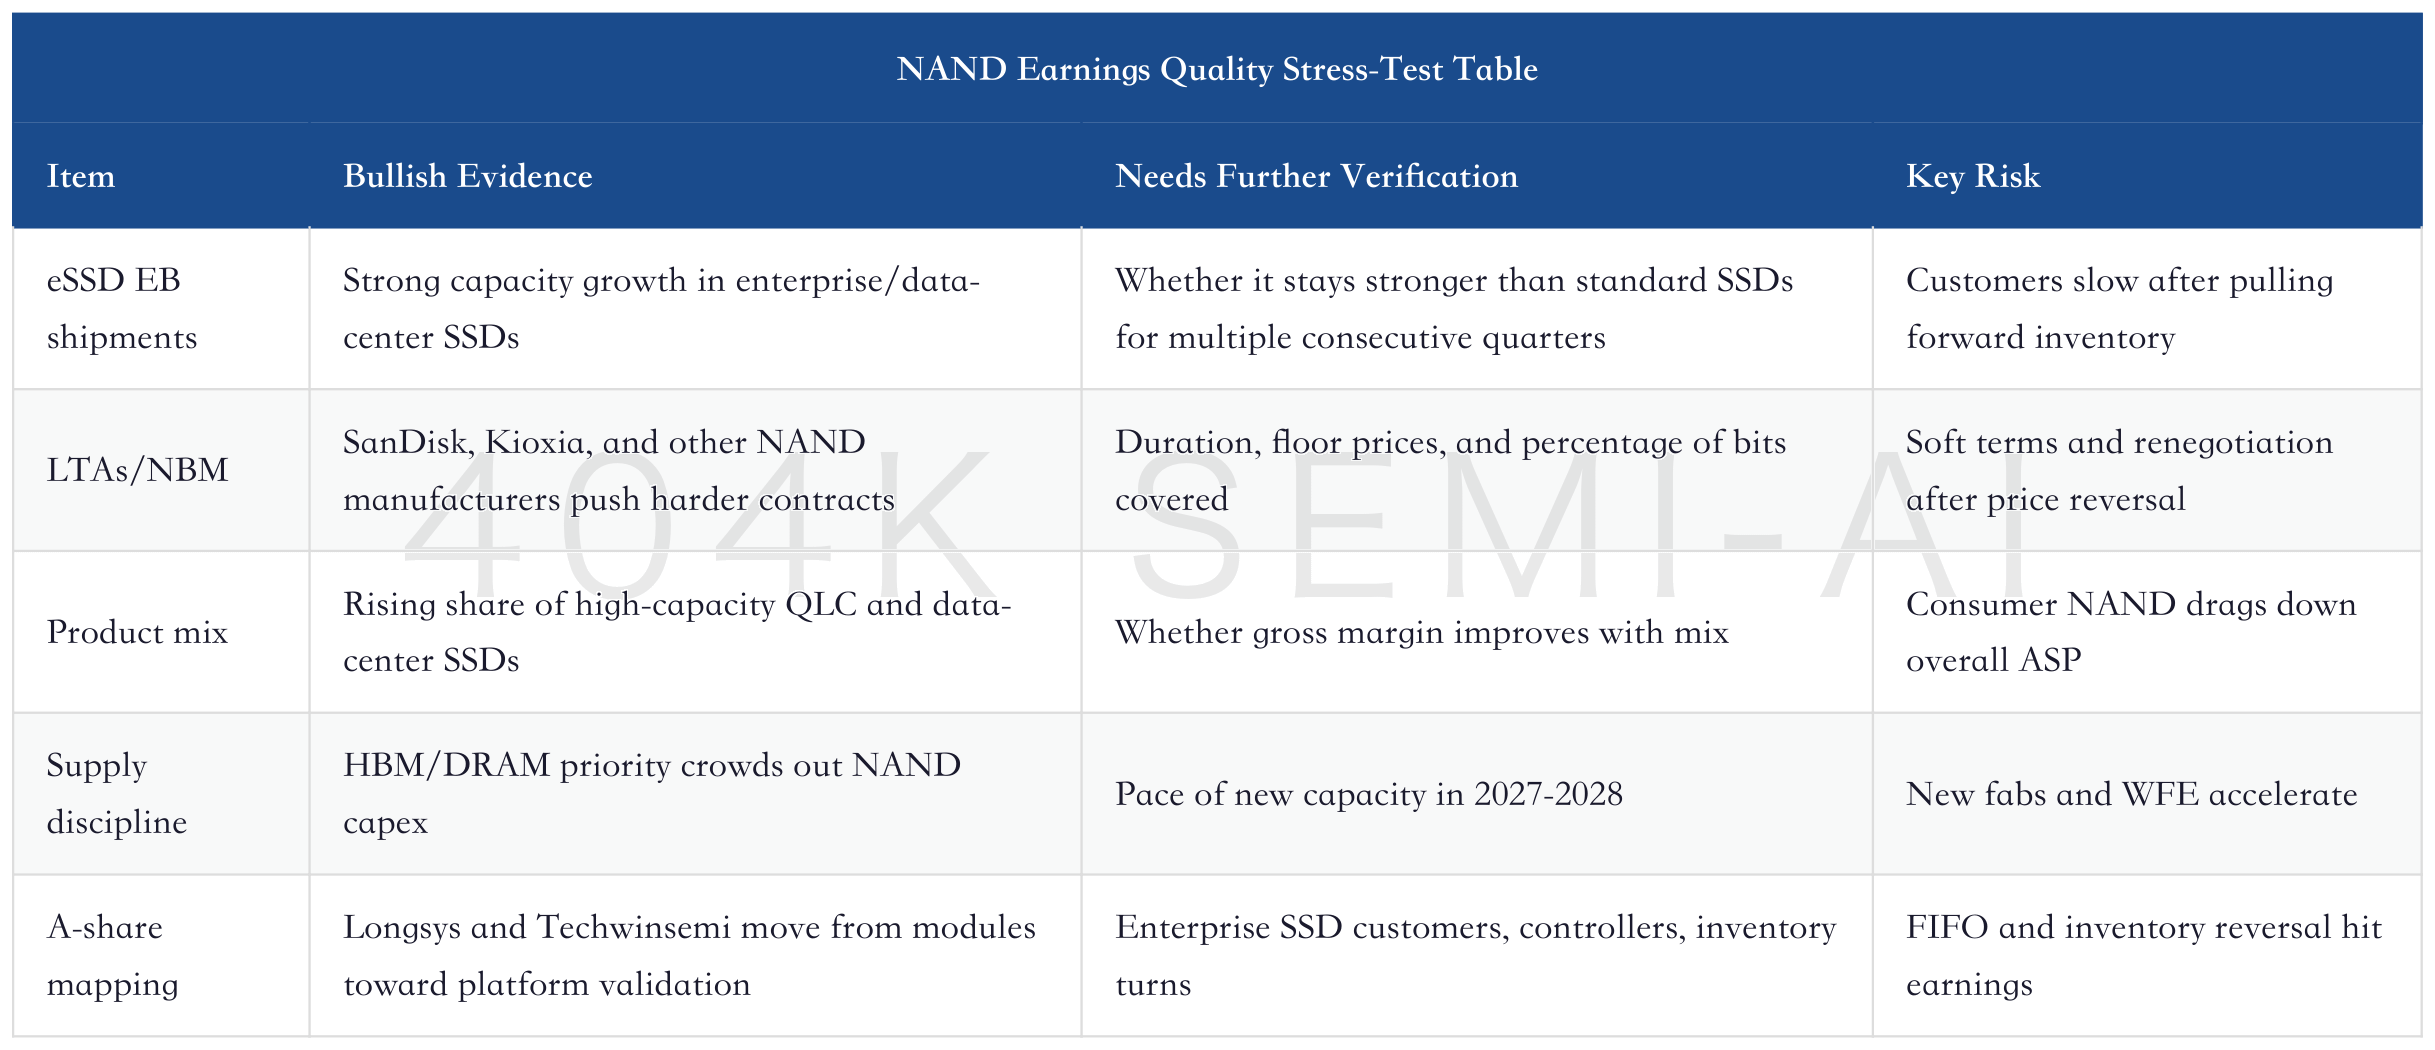
SanDisk and Kioxia are upstream samples for NAND earnings quality. SanDisk’s logic lies in eSSD share recovery, NAND LTAs, and earnings durability; Kioxia’s logic lies in NAND tightness, profit priority, and valuation repair. Neither is a simple price-hike stock. What really needs to be verified is LTAs and customer qualification.
NAND Sector Deep Dive Update: The Triple Test of AI eSSD Shortages, Supply Discipline, and 2028 New Capacity
The A-share mapping requires more caution. If Longsys and Techwinsemi rely only on inventory gains, they remain high-volatility module-chain names. If they can convert price increases into platform capability through enterprise SSDs, controllers, brands, and high-reliability customer qualification, then valuation can improve. In other words, A-share memory is not uninvestable, but inventory profit and platform profit must be separated.
SanDisk Deep Dive Update: Jefferies’ $3,000 Target Price, eSSD Share Recovery, and How NAND LTAs Revalue Earnings Durability
The key counterevidence in the second half of the NAND cycle is 2028. The 2026 and 2027 shortages are increasingly accepted by the market. The real long-term pressure is 2028 new capacity and the slope of AI eSSD demand. If new capacity comes online earlier than expected while eSSD demand does not continue to beat expectations, NAND will be re-discounted as a cycle earlier than DRAM.
This does not mean NAND cannot be bullish now. On the contrary, NAND remains one of the assets in AI storage with the clearest improvement in demand quality. But its valuation should carry a discount: strong demand drives EPS, hard LTAs drive multiples, and 2028 supply risk determines the discount. Without all three, NAND can easily fall back from asset revaluation into a price cycle.
The biggest difference between NAND and DRAM is their history of supply discipline. DRAM has higher concentration, with clearer crowding-out from HBM and advanced DRAM. NAND is more fragmented, has more technology routes, and has larger cycle differences between the consumer and data-center ends. When NAND prices rise, the market usually worries about a supply response sooner, which is reasonable. Therefore, for NAND to receive a higher multiple, it cannot rely only on price hikes. It needs customer structure and contracts.
eSSD qualification is the first gate for capitalizing NAND. Data-center SSDs are not ordinary consumer SSDs. Customer qualification cycles, firmware, controllers, reliability, power consumption, capacity, supply continuity, and other factors all affect adoption. Once a supplier enters high-end customer qualification, it is no longer just selling NAND dies; it is selling system reliability. The real gap among SanDisk, Kioxia, Samsung Electronics, Micron, Longsys, and Techwinsemi will open from here.
High-capacity QLC is the second gate. AI data is not only hot data. More of it is warm data, cold data, retrieval corpora, model versions, logs, and object storage. If high-capacity QLC expands in data centers, NAND demand will shift from the handset and PC cycle to the AI data-lake cycle. The issue is that QLC also needs yield, controllers, customer qualification, and cost curves to work together. Not all NAND suppliers will benefit equally.
LTAs are the third gate. If NAND only raises prices, the market will keep assigning a cycle discount. If NAND can lock in 2027 and 2028 bit demand in advance through NBM, LTAs, RPO, or similar customer commitments, then the cycle discount can decline. This is where the SanDisk investment debate sits: bulls are buying NAND earnings durability and LTAs; bears worry about the historical supply backlash in NAND.
The A-share NAND mapping should also use these three gates. Whether Longsys can move toward an enterprise SSD platform, and whether Techwinsemi’s controller capability can enter higher-quality customers, are not about short-term price increases. The key is qualification, products, and customers. Ordinary module profits come quickly but have low capitalizability; platform profits take longer to materialize but deserve a higher multiple.
VI. Where HDD Cash Flow Comes From: Cloud Customers Lock Nearline Capacity, HAMR Determines How Long Profits Can Stay
HDD looks like the oldest asset, but within this storage cycle it is the easiest to discuss through cash flow. AI data centers do not only need high-performance storage. They also need low-cost, high-capacity, long-term retention. Training data, model versions, logs, RAG knowledge bases, video, and object storage will not all sit in expensive SSDs. Nearline HDDs provide the underlying capacity for AI data retention.
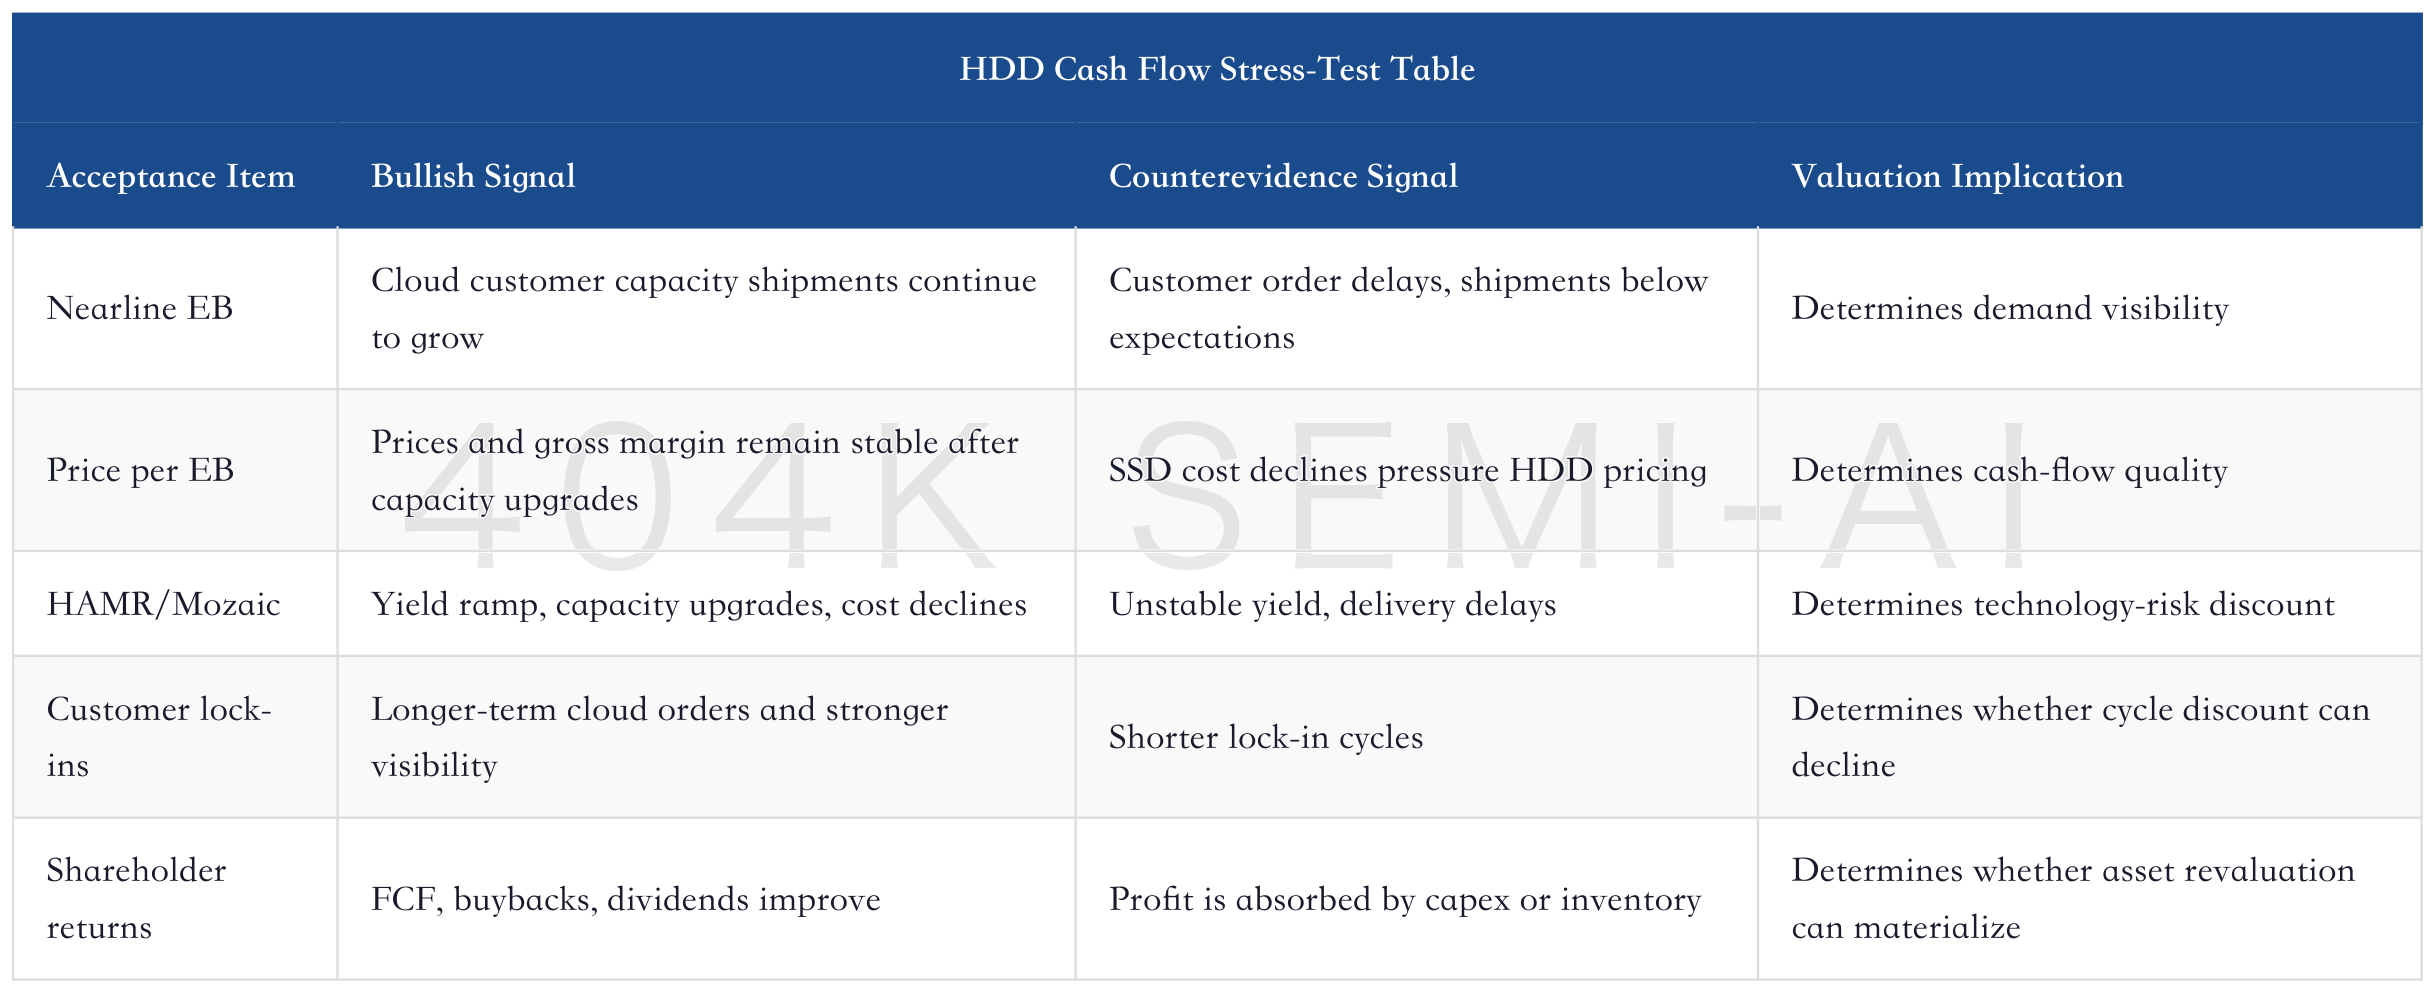
HDD cash flow comes from three specific links. First, cloud customers continue to lock nearline EB to preserve AI data, giving orders better visibility than consumer HDDs. Second, if HAMR/Mozaic and capacity upgrades progress smoothly, higher capacity per disk will improve unit cost and gross profit per EB. Third, duopoly supply discipline makes it easier for Seagate and Western Digital to convert profit into FCF, buybacks, dividends, and deleveraging. HDD does not have the highest growth profile like HBM, but it is easier to use cash flow to prove that the cycle discount should decline.
AI Storage Deep Dive Update: Morgan Stanley’s May HDD and SSD Data Confirm Data-Center Capacity Demand Remains Elevated
There are two misreadings of HDD. The first is treating it as obsolete hard drives and ignoring AI data retention demand for a low-cost capacity layer. The second is treating it as a high-growth technology stock and assigning too high a growth multiple. The more reasonable positioning is as a cash-flow asset: upside may not be the highest, but visibility and return quality are easier to verify.
For Seagate and Western Digital, what matters most next is not how exaggerated revenue growth can become, but whether FCF can stabilize, cloud customer orders can extend, HAMR yield can improve, and buybacks and dividends can continue. If these indicators keep materializing, HDD does not need to be framed as an HBM story to reduce its old-cycle discount.
HDD also has clear counterevidence. If the SSD cost curve falls too quickly, nearline HDD’s total-cost-of-ownership advantage will be compressed. If HAMR yield is unstable, capacity upgrades will be delayed. If cloud capex weakens, order visibility will decline. Once these counterarguments appear, HDD will return to being a traditional cyclical stock rather than an AI cash-flow asset.
HDD can be priced separately also because its competitive structure is simpler than NAND’s. Seagate and Western Digital have clearer industry positions in nearline HDD. Customers are concentrated, but lock-in power is also stronger. As long as cloud customers continue to pursue low-cost, high-capacity retention, HDD is not an old asset immediately displaced by SSD. It is the lowest-cost capacity base in the AI data hierarchy.
Cash flow is the best language for HDD. HBM can talk about technology leadership, eSSD can talk about capacity shipments, DDR4 can talk about supply exit, and HDD should talk most about FCF. If Seagate and Western Digital convert high profits into buybacks, dividends, and balance-sheet improvement, the market will naturally reduce the cycle discount. They do not need to prove they are high-growth companies; they only need to prove they are no longer traditional high-volatility HDD cyclical stocks.
HDD and eSSD are not simple substitutes. Hot data, high IOPS, training, and inference services need SSDs; warm data, data lakes, and retrieval scenarios need high-capacity SSDs; cold data, logs, archives, model versions, and long-term object storage still need nearline HDDs. The more AI data grows, the larger the storage pyramid becomes, and both media types can be strong at the same time. The real risk is not that eSSD must replace HDD, but the long-term balance among SSD cost declines, HDD technology ramps, and cloud-customer TCO.
HDD’s valuation ceiling should also be restrained. It can move from an old cyclical stock to a cash-flow asset, but it should not be treated as an HBM growth stock. The most reasonable valuation expansion comes from FCF visibility, duopoly supply discipline, long-term order lock-ins, and shareholder returns, not unlimited upward revisions to revenue growth. In a portfolio, HDD’s role is more like the defensive cash-flow anchor for the second half of the storage cycle.
7. How to Track Representative Companies: Do Not Use the Same Yardstick for Micron, SanDisk, Western Digital, Samsung, and SK Hynix
The biggest trap in this memory cycle is ranking every company simply by “beneficiary of memory price increases.” Different companies have different profit sources, and the risk signals to watch during pullbacks are also different. Micron is not a pure DRAM stock. SanDisk is not ordinary NAND price beta. Western Digital and Seagate are not high-growth stories. Samsung Electronics and SK Hynix are also not the same HBM trade.
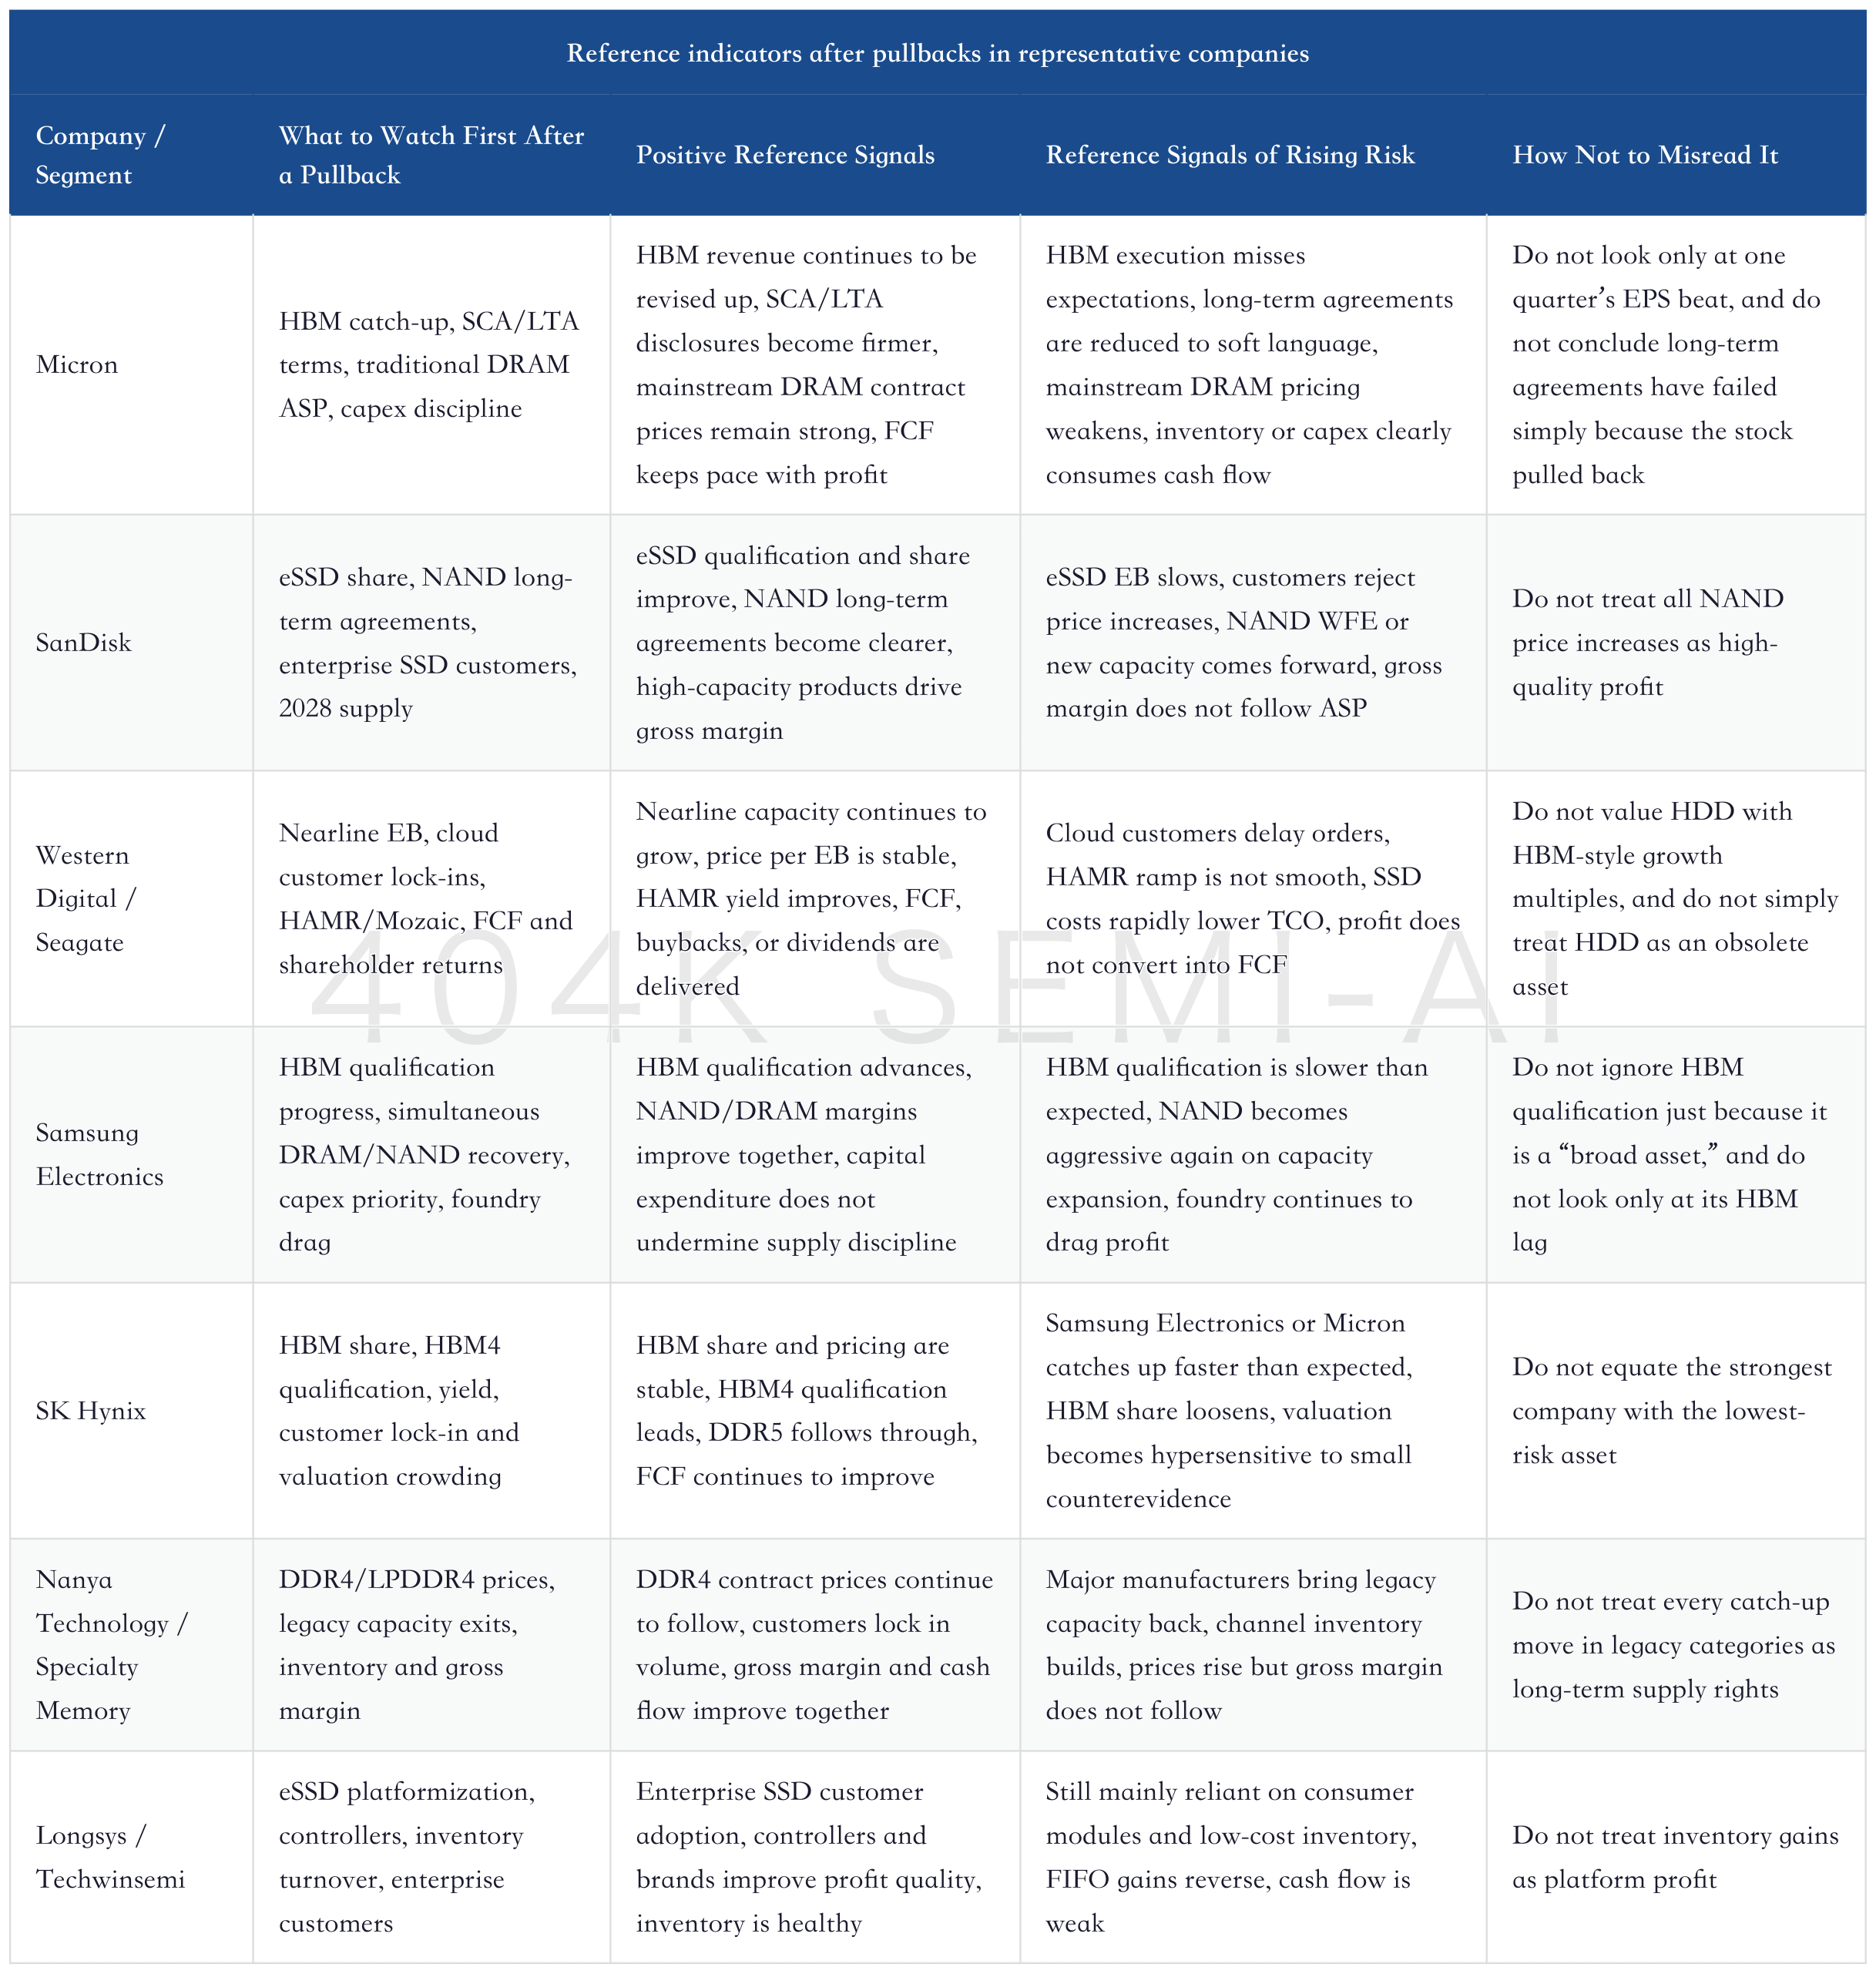
The core purpose of this table is not to provide buy or sell conclusions, but to separate the risk points. If Micron pulls back, first look at whether HBM and long-term agreements are weakening. If SanDisk pulls back, first look at eSSD qualification and NAND supply. If Western Digital pulls back, first look at nearline HDD and FCF. If Samsung Electronics pulls back, first look at whether HBM qualification is progressing. If SK Hynix pulls back, first look at whether share and valuation crowding are both becoming problems.
This also explains why the conclusion may differ even after the same 20%-30% pullback. If the core variables have not deteriorated, the pullback is more likely valuation digestion. If the core variables start to weaken, the pullback may be a fundamental re-rating. Readers do not need to guess the bottom every day. They only need to list each company’s most sensitive indicators and keep tracking whether they are moving in the same direction.
A target-price table is less useful than this reference-indicator table. Target-price increases reflect changes in sell-side models, but target prices are not conclusions. What truly needs to be compared is which model item changed: ASP assumptions, volume assumptions, gross-margin assumptions, long-term agreement coverage, capital expenditure, cash-flow discount rate, or valuation multiple.
Target-Price Revisions Cannot Be Ranked Directly; They Must Be Split into Five Layers of Assumptions
The biggest problem in current memory research reports is that target-price increases are becoming more frequent. Nanya Technology, SK Hynix, Samsung Electronics, Micron, SanDisk, Kioxia, Seagate, and Western Digital have all seen varying degrees of upward revisions. If one looks only at target-price numbers and percentage increases, it is easy to reach the wrong ranking: the company with the largest target-price increase is the most worth buying, and the company with the highest target price has the most upside. That reading is too crude.
A target price is not a research conclusion; it is the composite result of model assumptions. A target-price increase may come from higher ASP assumptions, or from higher volumes, higher gross margin, lower expense ratios, lower long-term capital expenditure, a lower FCF discount rate, or multiple expansion. Different sources correspond to completely different asset characteristics.
The first layer is pricing assumptions. Upward revisions to DDR4, DDR5, HBM, NAND, eSSD, and nearline HDD prices flow into EPS first. Pricing assumptions are the easiest to use to drive target prices, but they are also the easiest for the market to discount, because the higher prices go, the more likely they are to invite customer resistance, supply response, and inventory risk. An upward revision to pricing assumptions can only indicate stronger cycle beta; it cannot directly prove asset re-rating.
The second layer is volume and customer assumptions. If the revision comes from eSSD EB, nearline HDD capacity, HBM shipments, AI server DRAM capacity, or DDR4 server exposure, the quality of the revision is higher. This is because it is not just price going up; the AI data stack is genuinely pulling up product demand. Volume and customer assumptions deserve higher multiples than pricing assumptions, but they still require scrutiny of qualification cycles, customer concentration, and delivery bottlenecks.
The third layer is gross-margin and product-mix assumptions. A higher HBM mix, higher enterprise SSD mix, recovery in DDR4/LPDDR4 gross margin, and nearline HDD capacity upgrades can all make gross margin higher than in a traditional cycle. A gross-margin revision is more important than an ASP revision, because it indicates the company has not given all price increases away to costs, channels, or customers. But gross margin must also be assessed alongside inventory and cash flow. Strong gross margin in one quarter does not necessarily mean good profit quality.
The fourth layer is contract and cash-flow assumptions. LTAs, SCAs, NBMs, prepayments, take-or-pay terms, price floors, cloud customer lock-ins, FCF, buybacks, and dividends are the parts of a target price most worth capitalizing. If a target-price increase comes from a lower discount rate or a higher long-term ROE center, it means analysts are not just looking at this year’s EPS, but are reducing the cycle discount.
The fifth layer is valuation-multiple assumptions. Memory stocks are most prone to controversy at this layer. Bulls will argue that industry cyclicality is declining, long-term agreements improve visibility, and AI customer lock-ins mean P/E should rise. Bears will argue that memory remains a capital-intensive, commoditized cyclical business where supply will return. This debate will not be resolved by saying “AI demand is strong.” It must be resolved through contract disclosures and cash flow.
Once these five layers of assumptions are separated, the quality of many target-price increases becomes clearer. Nanya Technology’s revisions mainly come from legacy DRAM supply rights and DDR4 prices entering the model. Micron’s revisions depend more on SCA/LTA, HBM, and its role as a U.S. AI memory entry point. SanDisk and Kioxia’s revisions lie in NAND/eSSD profit quality. Seagate and Western Digital’s revisions come from a lower HDD cash-flow discount. They all look like memory, but investors are actually buying four different types of profit.
The biggest investment risk is mistaking pricing assumptions for multiple assumptions. When pricing assumptions are revised up, the stock can rise, but the market will keep asking about peak profit. Only when contract and cash-flow assumptions are revised up does valuation have a chance to expand. In other words, target-price increases can be useful, but one must first ask: is this revision to this year’s profit, or to long-term profit quality?
A-Share Mapping: Inventory Profit and Platform Profit Must Be Separated
A-share memory names often perform very strongly during memory upcycles because profit beta arrives quickly. Upstream prices rise, low-cost inventory is revalued, module and channel profits are released, and investors can easily see financial statements improve. But A-share mapping is also the easiest to misread: not all “beneficiaries of memory price increases” deserve asset re-rating.
GigaDevice is closer to supply rights in mature categories. It has NOR, SLC NAND, specialty DRAM, MCU, and customer access. The logic is not single-product price beta, but that legacy categories are becoming harder to replace in AI hardware, industrial, automotive, and control scenarios. If improvements in DRAM, NOR, and SLC NAND prices can flow into gross margin without deterioration in inventory and cash flow, GigaDevice looks more like a legacy-memory supply-rights platform. If it is only a short-term price increase in one or two categories, the market will still treat it as cycle beta.
Longsys and Techwinsemi are more about platform validation. They will of course benefit from NAND prices and inventory, but long-term value is not in inventory. It is in enterprise SSDs, controllers, branded customers, high-reliability scenarios, and customer qualification. Module companies release profit most easily in the short term, and they are also most easily hit by inventory reversal when prices turn. What can truly be capitalized is not inventory gains, but the migration from modules to platforms, from channels to customers, and from low gross margin to high-reliability products.
Ingenic Semiconductor, Puya Semiconductor, and Dosilicon are more about small-capacity and reliability entry points. For Ingenic Semiconductor, watch automotive-grade and industrial customers. For Puya Semiconductor, watch NOR, EEPROM, and MCU-related memory. For Dosilicon, watch SLC NAND, NOR, and specialty memory. They are not pure AI data-center capacity-layer names, but the more complex AI hardware becomes, the more stable demand becomes for boot, control, configuration, and high-reliability memory. Small-capacity categories may not be large, but when customers cannot do without them and supply is not easy to bring back, they can also become high-quality profit sources.
For A-share mapping, four numbers matter most. First, whether gross margin is improving with prices, rather than relying only on revenue expansion. Second, whether inventory turnover is healthy, rather than piling price-increase expectations into high-priced inventory. Third, whether operating cash flow is moving in line with profit, rather than the income statement looking good while cash flow is weak. Fourth, whether customer qualification and product mix are moving up, rather than remaining stuck in consumer modules and channel volatility.
If all four numbers improve together, A-share memory can move from price beta to profit quality. If one only sees prices and revenue, without improvements in gross margin, inventory, cash flow, and customer structure, it can only be viewed as cycle beta. The opportunity in A-share memory is large, but the acceptance threshold should also be more detailed, because inventory and channels amplify cycle beta and also amplify cycle reversal.
During Pullbacks, Distinguish Between Valuation Compression, Earnings Compression, and Narrative Compression
After the memory trade has risen significantly, pullbacks are inevitable. The pullback itself is not important. What matters is what the pullback is attacking. If it is valuation compression, the market believes positives have already been reflected, but fundamentals have not changed. If it is earnings compression, ASP, shipments, gross margin, or customer orders have started to run into problems. If it is narrative compression, the main line of AI demand, long-term agreements, and cash-flow assetization is being questioned.
Valuation compression usually happens when expectations are too crowded. HBM leaders are most likely to face this kind of pullback because they have the highest quality, the most concentrated positioning, and the fullest expectations. If SK Hynix pulls back because of valuation crowding, but HBM share, customer qualification, DDR5 follow-through, and FCF have not changed, the pullback looks more like position rebalancing. If Samsung Electronics pulls back because catch-up expectations have overheated, one should first check whether HBM qualification and NAND/DRAM recovery have changed.
Earnings compression is more serious. DDR4 contract prices falling below expectations, NAND customers rejecting price increases, slower eSSD EB shipments, nearline HDD customer order delays, and deteriorating module inventory turnover are all earnings-level counterevidence. This type of pullback cannot simply be understood as a buying opportunity, because it directly affects EPS and target-price models. When memory stocks suffer earnings compression, the decline usually does not end in one day; it is accompanied by sell-side downward revisions and continued deterioration in inventory data.
Narrative compression is the most dangerous. For example, the market may start to believe AI inference demand is below expectations, cloud capex is slowing because of power, financing, or regulation, LTA terms are actually soft, 2028 new supply is coming forward, or customers are regaining pricing power. These changes compress both valuation and earnings, because they are not just one quarter of data; they shake the premise for asset re-rating.
Therefore, the first question after a pullback is not how much the stock has fallen, but whether the evidence has changed. Price evidence, contract evidence, customer evidence, inventory evidence, cash-flow evidence, and supply evidence: whichever of these six types of evidence has weakened determines the nature of the pullback. If valuation was merely overheated, strong assets can still be watched. If contract and cash-flow evidence weakens, the asset re-rating assumption must be lowered. If supply discipline is broken, the entire memory line must be repriced.
This pullback framework can also help control portfolio rhythm. HBM is suitable as a quality anchor, but one should not add blindly when it is crowded. DDR4 and mature memory are suitable for expectation gaps, but inventory must be watched closely. eSSD is suitable for profit quality, but 2028 supply must be tracked. HDD is suitable as a cash-flow anchor, but should not be assigned growth-stock multiples. Different assets have different entry points and different stop-loss conditions.
The Most Important Counterevidence: Inventory, Contracts, Supply, Customers, and Cash Flow
Memory stocks can easily make investors overexcited because income statements improve very quickly. Once ASP rises, gross margin and EPS are revised up immediately. Companies with low inventory costs may even release substantial profit beta within a single quarter. But the real risk in cyclical stocks often begins when the income statement looks best.
The first type of counterevidence is inventory. In an upcycle, customers place orders early to ensure supply, channels stock up early to earn price spreads, and module makers expand inventory to lock in costs. Looking only at revenue and gross margin can misjudge demand strength. Inventory turnover, operating cash flow, and customer structure must be examined at the same time. Strong prices, healthy inventory, and strong cash flow indicate a high-quality upcycle. Strong prices, heavy inventory, and weak cash flow are classic signals of the late cycle.
The second type of counterevidence is contracts. Terms such as LTA, SCA, and NBM have no magic by themselves. The key is the clauses: how long the term is, whether there are prepayments, how price floors are set, whether there are take-or-pay provisions, how high the cost is for customers to cancel orders, whether third-party guarantees exist, and whether suppliers expand capacity without discipline for the sake of contracts. These questions determine whether long-term agreements are cash-flow assets or letters of intent at the cycle peak.
The third type of counterevidence is supply. DRAM, NAND, and HDD have different supply elasticities. HBM and advanced DRAM are constrained by wafers, packaging, and customer qualification, so supply elasticity is slow. NAND has historically had weaker supply discipline, and 2028 new capacity will enter valuations earlier. HDD has a clearer duopoly and technology roadmap, but HAMR yield is a hard constraint. Being bullish on memory cannot rely only on the demand curve; one must also watch whether supply is starting to respond to prices.
The fourth type of counterevidence is customers. AI customers are now willing to lock in supply because shortages are more frightening than high prices. If AI inference revenue, cloud capex, data-center delivery, grid connection, or GPU/ASIC deployment pace slows, customer acceptance of long-term agreements and high-priced procurement will decline. Demand does not exist in a vacuum. It ultimately has to show up in AI service revenue, compute deployment, and data-center delivery.
The fifth type of counterevidence is cash flow. EPS can be pushed up quickly by prices; FCF is harder to disguise. If manufacturers make money and then restart large-scale capacity expansion, cycle memory will return. If they convert profit into buybacks, dividends, deleveraging, and more restrained capital expenditure, the market will gradually reduce the cycle discount. HDD can most easily provide the answer first on this point, while DRAM and NAND manufacturers must also provide an answer.
8. How to Validate the Next Four Quarters
Over the next four quarters, memory should not be assessed only by price. Price remains the first signal, but it is not the final answer. A more reasonable sequence is: in 3Q26, watch price pass-through; in 4Q26, watch contracts and inventory; in 1H27, watch earnings quality and cash flow; in 2H27, watch supply discipline and 2028 disconfirming evidence.
The most important issue in 3Q26 is whether pricing can continue to pass through. If DDR, NAND, eSSD, NOR, SLC NAND, and nearline HDD quotes remain strong, it means the demand-supply gap is still there. But this is also when investors are most likely to get overexcited, because strong pricing does not automatically prove asset re-rating. It must be checked alongside whether customers are accepting longer contracts, whether channels are overstocking, and whether module-maker and original-manufacturer inventories are healthy.
In 4Q26, the focus shifts from pricing to contracts. Whether Samsung Electronics, SK Hynix, Micron, SanDisk, and Kioxia disclose harder long-term agreements, and whether contract duration, prepayments, price floors, and volume-price mechanisms become clearer, will determine whether the market is willing to keep raising multiples. If companies only disclose “strong customer demand” without disclosing contract enforceability, the valuation benefit from long-term agreements will be discounted.
In 1H27, the focus should be earnings quality. Gross margin, operating margin, operating cash flow, FCF, inventory turnover, and capital expenditure will determine whether the prior year’s price increases have been retained. If DRAM and NAND original manufacturers improve gross margins but also raise capex significantly, the market will worry about the next round of oversupply. If HDD companies continue to improve FCF and buybacks, the cash-flow-asset logic will become more stable.
2H27 and 2028 are the supply stress test. New NAND capacity, DRAM WFE, capital-allocation priorities across HBM and DDR5, restarts of older lines, and new variables such as CXMT will all affect long-term valuation. True bulls are not afraid of supply expansion itself; they are afraid of expansion without customer constraints, price floors, or capital-return discipline.
Compressed into one sentence, the validation framework is: price proves the cycle, contracts prove the structure, cash flow proves the asset, and supply discipline determines whether the cycle comes back.
9. Five Common Misreadings
The first misreading is assuming that memory price increases equal asset re-rating. Price increases are the entry point to the income statement, not the exit point for valuation. Without contracts, customer qualification, and cash flow, the more aggressively prices rise, the more the market will worry about peak earnings.
The second misreading is interpreting strong HBM as meaning all DRAM is risk-free. Strong HBM does compress advanced DRAM capacity and supports DDR5 and some DDR4, but ordinary DRAM still depends on customer mix and inventory. HBM is high-purity; ordinary DRAM requires joint validation by supply-demand and contracts. They cannot be blended into the same asset.
The third misreading is assuming eSSD will directly replace HDD. AI data centers are not a single-medium architecture. Hot data requires eSSD, warm data requires high-capacity SSDs, while cold data and long-term retention still require nearline HDD. Strength in both eSSD and HDD instead shows that the AI data pyramid is expanding.
The fourth misreading is treating all A-share memory names as mappings of overseas original manufacturers. GigaDevice, Longsys, Deyi Micro, Beijing Ingenic, Puya Semiconductor, and Dosilicon each have different logic. Niche memory depends on supply rights and customer entry points; modules/controllers depend on inventory and enterprise SSD platformization. They cannot all be covered by a single “beneficiary of memory price increases” label.
The fifth misreading is thinking 2028 supply risk is too far away. Memory stocks will not wait until supply is actually released before reacting. The market will trade capex, WFE, new fabs, and changes in customer bargaining power in advance. Investors do not need to reject the current opportunity because of 2028 risk, but they must include it in the valuation discount.
10. Portfolio Positioning: Four Asset Types Cannot Use the Same Sizing Logic
The second half of the memory trade cannot be solved by holding only a single leading name. Different assets have different hit rates, payoff profiles, and disconfirming evidence; applying the same sizing logic to all of them will be uncomfortable. HBM is the high-quality core, eSSD is the earnings-quality position, DDR4 and niche memory are expectation-gap beta positions, and HDD is the cash-flow anchor. They are all on the same memory chain, but the appropriate position size and observation period are completely different.
HBM is suitable as a quality core holding, but investors must accept crowding. The advantage of assets such as SK Hynix is high certainty; the disadvantage is that the market also understands them most fully. It is suitable to maintain core exposure while customer qualification, share, the HBM4 roadmap, and FCF continue to deliver. It is not suitable to keep adding unconditionally when valuation is extremely crowded and everyone is looking in only one direction. Quality assets can still fall; when they do, the key is to judge whether fundamentals have changed.
Samsung Electronics and Micron are more suitable as recovery and beta positions. Samsung Electronics is a breadth asset and a catch-up recovery trade; Micron is a U.S. AI memory entry point and long-term-agreement beta trade. Their sizing logic is not “who is strongest,” but “which assumptions are not yet fully priced.” If Samsung’s HBM qualification advances and NAND and DRAM recover together, its discount has room to narrow. If Micron discloses harder SCA/LTA terms and continues to raise HBM revenue expectations, its cycle discount will decline.
eSSD and NAND are suitable as earnings-quality positions, but require forward-looking disconfirming evidence. The advantage of the SanDisk, Kioxia, Longsys, and Deyi Micro line is strong AI capacity demand, fast enterprise SSD growth, and clear product-mix improvement. The risks are also clear: NAND supply discipline, new capacity in 2028, consumer-end resistance to price increases, and inventory. From a sizing perspective, they cannot be treated as growth stocks with no disconfirming evidence. It is more appropriate to raise weight when eSSD EB, long-term agreements, gross margin, and inventory are all improving, and to proactively reduce risk when evidence on capex and new capacity strengthens.
DDR4, NOR, and SLC NAND are suitable as expectation-gap beta positions. Their common feature is “mature but critical.” The market previously assigned them low valuations because they were viewed as legacy categories; now they are being rediscovered because AI is pushing major manufacturers’ capex toward the high end, tightening supply in mature categories. The benefit of expectation-gap positions is large upside beta; the downside is that disconfirming evidence is also direct. Unless price, gross margin, inventory, and customer mix improve at the same time, they should not be treated as high-quality cash-flow assets.
HDD is suitable as a cash-flow anchor. Seagate and Western Digital are not the most exciting names, but they are the most suitable to play the cash-flow role in a portfolio. The key is not how high revenue growth is, but nearline EB, price per EB, HAMR yield, FCF, buybacks, and dividends. If the memory trade moves from price beta to earnings quality, the relative value of HDD-type assets will rise. If the market starts chasing high beta again, HDD may underperform, but on the downside it is also easier to support valuation with cash flow.
The portfolio rhythm can be simplified into three stages. In the first stage, the price-upgrade phase, low-cost inventory, high beta, and legacy-category beta perform best. In the second stage, the earnings-quality phase, HBM, eSSD, and long-term-agreement assets are stronger. In the third stage, the cash-flow validation phase, HDD and original manufacturers that can convert profits into buybacks and dividends have the advantage. The current phase looks more like the second stage: pricing has already been proven, and the market is starting to look for which profits can be retained.
This rhythm also explains why investors cannot only chase the hottest names. The hottest names are often the highest-quality assets, but they are also the most vulnerable to valuation crowding. The cheapest names often have expectation gaps, but require stricter financial validation. A good portfolio should let HBM provide quality, eSSD provide structural growth, DDR4/niche memory provide expectation-gap upside, and HDD provide cash flow, rather than concentrating all positions in one type of profit.
For final validation, each asset type in the portfolio can be asked one question. For HBM, ask whether share and customer qualification are loosening. For DDR4 and niche memory, ask whether price increases are flowing through to gross margin and cash flow. For eSSD, ask whether EB shipments, long-term agreements, and 2028 supply are still moving in the same direction. For HDD, ask whether FCF, buybacks/dividends, and HAMR yield are continuing to deliver. As long as the answers remain broadly positive, pullbacks are more likely position and valuation volatility; only when the answers turn negative does it become fundamental repricing.
This is also how the current memory chain differs from general AI hardware. GPUs, ASICs, optical modules, PCBs, and liquid cooling are more about orders and capacity slopes. Memory must look not only at demand, but also at supply discipline. Because memory has such strong historical memory, any high profit will automatically make the market think of capacity expansion and oversupply. For memory to truly move beyond its old cycle discount, it must prove not only strong AI demand, but also that suppliers are not turning all high profits into the capex for the next round of oversupply.
Therefore, at the portfolio level, the most valuable exercise is not a binary judgment of “fully invested in memory” or “zero memory exposure,” but continuously increasing the weight of high-quality profits and reducing the weight of pure spot profits. In the early stage of price increases, spot profits can make money. In the earnings-quality stage, contracts and customer qualification are more valuable. In the cash-flow stage, FCF and shareholder returns are more valuable. Changing weights across different stages is what prevents a good industry chain from becoming an emotion-driven trade.
XI. Industry Position: Memory Is Not a Supporting Actor in AI Hardware, but the Second Battleground for Profit Allocation
Memory has often been treated as a supporting actor in AI hardware. The market first looks at GPUs, then ASICs, networking, optical modules, PCBs, power, and liquid cooling, while memory is often viewed as “a server BOM component that will go up in price.” That view is no longer sufficient. As AI systems move further toward inference, long context, RAG, agents, and multimodal data, memory and storage look less like ordinary components and more like a constraint layer on compute utilization.
GPUs determine how fast the system can compute. Networking determines how smoothly clusters connect. Power determines whether racks can be deployed. Memory and storage determine whether data can be fed in, whether state can be retained, and whether inference can be served continuously. HBM addresses bandwidth. DDR5 and LPDDR address system memory. Enterprise SSDs address hot data and high-frequency access. HDDs address low-cost long-term retention. NOR and SLC NAND address boot, control, and reliability entry points. Together, these layers form AI data infrastructure.
This is also why profit allocation in memory and storage will become increasingly complex. HBM was the first to be recognized because it is directly tied to GPUs. DDR5 and standard DRAM followed, as memory capacity in CPU servers and AI nodes was revised upward. Next come enterprise SSDs and high-capacity NAND, because inference, RAG, and data lakes need a capacity layer. Finally come nearline HDDs and mature small-capacity storage, because data retention and control entry points will not disappear. Memory and storage are not a single line item, but a multilayer tolling structure across the AI workflow.
From an industry perspective, memory and storage are undergoing two rounds of re-rating. The first is a demand re-rating: the market has realized that AI consumes not only GPUs, but also large amounts of memory and storage capacity. The second is a business-model re-rating: customers are increasingly willing to use long-term agreements, prepayments, qualification, and committed orders to secure supply certainty. The first re-rating lifts prices and EPS. The second is what changes valuation multiples.
The most important change is that customers are beginning to treat “memory and storage shortages” as a systemic risk. In past PC and smartphone cycles, customers could wait for prices to fall, control inventory, and delay procurement. In AI data centers, a shortage of HBM affects GPU delivery, a shortage of DDR5 affects server configurations, a shortage of enterprise SSDs affects inference and retrieval performance, and a shortage of HDDs affects the cost of data retention. Shortages are no longer merely a procurement issue, but an issue for cloud services, AI products, and capex efficiency.
When shortages become a systemic risk, supplier bargaining power changes. Memory suppliers are no longer merely selling standardized chips. They are selling supply certainty, customer qualification, and delivery reliability. Long-term agreements, SCA, NBM, and customer order lock-ins are external expressions of this change in bargaining power. What investors truly need to assess is how long this bargaining power can last, and whether suppliers will again undermine supply discipline because of high profits.
This is also what makes memory and storage different from other AI hardware segments. Optical modules and PCBs are more about product generations and customer share. Power and liquid cooling are more about project delivery and capacity expansion. Memory and storage additionally require cycle memory. The upside is powerful, but historically, high profits have also triggered strong supply responses. To earn a higher valuation, the sector must prove strong demand, firm contracts, restrained supply, and good cash flow at the same time.
If all four conditions hold, memory and storage are not supporting actors in AI hardware, but the second battleground for profit allocation. The first battleground is GPUs and ASICs, which determine the compute budget. The second is memory and storage, which determine the data budget and system efficiency. The larger AI capex becomes, the longer data is retained, and the denser inference calls become, the less memory and storage should be underestimated within the profit pool.
The best state for this industry chain is not that all categories rise together, but that each layer produces verifiable evidence on its own. HBM proves bandwidth monetization through customer qualification and share. DDR4 and niche memory prove supply power through gross margin and inventory. Enterprise SSDs prove capacity-layer profits through exabyte shipments and long-term agreements. HDDs prove cash-flow asset value through FCF and buybacks. The more evidence there is, the more memory and storage look like a group of assets. The less evidence there is, the more they look like a cycle trade.
XII. Conclusion: Before Buying In or Exiting, First Check Whether the Five Signals Are Aligned
After this memory and storage pullback, the least useful response is to immediately call for buying in or exiting. Prices have already risen, target prices have already been chased, and the market now needs to verify whether five signals are aligned: whether pricing has broken, whether contracts have softened, whether inventory is building, whether supply has lost control, and whether cash flow is keeping up with profits.
The best assets are not the categories that have fallen the most, nor the categories that rallied the hardest earlier, but the categories where the core signals have not deteriorated. For HBM, watch share and qualification. For DDR4, watch legacy capacity gaps and inventory. For enterprise SSDs, watch customer qualification and long-term agreements. For HDDs, watch cloud customer order lock-ins and FCF. The same share-price decline can mean completely different things for different companies.
The true topping signals are also clear. First, prices are still rising, but customers begin to reject firmer contracts. Second, inventory and receivables start growing faster than revenue. Third, suppliers reinvest high profits into unconstrained capacity expansion. Fourth, AI data-center delivery, cloud capex, or inference revenue slows meaningfully. Fifth, cash flow fails to keep pace with profits, and buybacks, dividends, and deleveraging do not materialize. As long as these signals do not appear in concentration, memory and storage look more like they are moving from a price trade into a profit-quality trade, rather than simply reaching a cyclical top.
Conversely, if these signals begin to appear at the same time, investors can no longer use “long-term AI demand is strong” to obscure near-term risk. Memory and storage are among the most evidence-driven segments in a highly cyclical industry, and every long-term narrative must face quarterly data. For bulls to keep winning, prices, contracts, inventory, cash flow, and supply discipline must continue to move in the same direction. If two or three of them start to diverge, valuations will react before profits do.
A more practical approach is to divide memory and storage positioning into three reference scenarios: “continue to monitor,” “increase weight,” and “reduce risk.” When at least four of pricing, contracts, inventory, cash flow, and supply discipline are aligned, memory and storage are still in a phase of improving profit quality, and pullbacks are driven more by valuation and positioning than by a fundamental peak. If pricing remains strong but contracts soften, inventory rises, or cash flow weakens, exposure that depends only on spot profits and inventory gains should be reduced. If customer resistance to price hikes, capex restarts, and inventory deterioration appear together, memory and storage should be placed back into a traditional cyclical framework. The advantage of this framework is that investors do not need to guess the top every day; they only need to keep comparing whether the evidence remains aligned.
Therefore, the investment framework for this memory and storage cycle should shift from “who is raising prices” to “whose five signals have not deteriorated.” Pricing is only the entry point. Contracts, customer qualification, inventory, capex, and cash flow are the conclusion. As long as these indicators continue to align, pullbacks look more like valuation and positioning volatility. If prices are strong but contracts are weak, inventory rises while cash flow is poor, and capex loses control while customers begin to reject price increases, that is the real signal of a cyclical top.
The core judgment can be compressed into one sentence: after the memory and storage pullback, do not first ask whether to buy in or exit; first ask whether the five signals have deteriorated. Investors should not be looking at the words “memory and storage,” but at Micron’s HBM and long-term agreements, SanDisk’s enterprise SSDs and NAND supply, Western Digital’s nearline and FCF, Samsung Electronics’ HBM qualification, and SK hynix’s share and valuation crowding.Memory Pullback: Buy the Dip or Clear Out? Watch These Five Signals First
目录
Too Long; Didn’t Read
1. After the Memory Pullback, Do Not Rush to Ask Whether to Buy or Sell
2. Three Worldviews: Not a Cycle Bottom, Possibly Not the Peak, but Profit Quality Must Be Dissected
III. Where DDR4 Is Actually Tight: Legacy Capacity Has Been Crowded Out by HBM and DDR5, While Customer Migration Is Not That Fast
IV. HBM and DRAM Long-Term Agreements: Highest Purity Does Not Mean Highest Upside
V. Where eSSD Is Actually Expensive: Qualification Slots, Controller Firmware, and LTAs Matter More Than NAND Price Hikes
VI. Where HDD Cash Flow Comes From: Cloud Customers Lock Nearline Capacity, HAMR Determines How Long Profits Can Stay
7. How to Track Representative Companies: Do Not Use the Same Yardstick for Micron, SanDisk, Western Digital, Samsung, and SK Hynix
Target-Price Revisions Cannot Be Ranked Directly; They Must Be Split into Five Layers of Assumptions
A-Share Mapping: Inventory Profit and Platform Profit Must Be Separated
During Pullbacks, Distinguish Between Valuation Compression, Earnings Compression, and Narrative Compression
The Most Important Counterevidence: Inventory, Contracts, Supply, Customers, and Cash Flow
8. How to Validate the Next Four Quarters
9. Five Common Misreadings
10. Portfolio Positioning: Four Asset Types Cannot Use the Same Sizing Logic
XI. Industry Position: Memory Is Not a Supporting Actor in AI Hardware, but the Second Battleground for Profit Allocation
XII. Conclusion: Before Buying In or Exiting, First Check Whether the Five Signals Are Aligned
本内容基于公开资料和研报数据整理,不构成任何投资建议,不代表任何个人观点,仅供学习参考,请理性阅读
After memory stocks rally sharply and then pull back 20%-30%, the key is not to shout “buy the dip” or “clear out,” but to determine whether the pullback is hitting valuation, positioning, or fundamentals. Prices, contracts, inventory, supply, and cash flow are the reference points for Micron, SanDisk, Western Digital, Samsung Electronics, and SK Hynix. They help distinguish valuation retracement from earnings downgrades.
Too Long; Didn’t Read
After memory pulls back 20%-30%, the worst mistake is to decide “buy” or “sell” with one sentence. Prices have already risen through one round, and sell-side estimates have been revised up many times. The pullback itself does not prove the cycle is over. The real focus should be five signals: whether prices have broken, contracts have softened, inventory has piled up, supply has lost control, and cash flow has kept pace with profits.
The first signal is whether pricing and orders have deteriorated. If DDR4, DDR5, NAND, eSSD, and nearline HDD prices still have contract-price support, the pullback is more likely a valuation and positioning adjustment. If customers begin rejecting price hikes, delaying orders, or if eSSD EB or nearline EB growth slows, the pullback may shift from valuation compression to earnings compression.
The second signal is whether long-term agreements and customer qualifications are firm. For Micron, watch SCA/LTA terms. For Micron, SK Hynix, and Samsung Electronics, watch HBM4 qualification and customer share. For SanDisk, watch eSSD qualification and NAND long-term agreements. What truly matters is contract duration, floor price, prepayment, take-or-pay, and cancellation cost, not soft language such as “customer demand is strong.”
The third signal is whether inventory and cash flow are diverging. Memory most easily embeds risk when the income statement looks best. If ASPs rise and gross margins improve, but inventory, receivables, and capex all rise while operating cash flow fails to keep up, earnings quality is starting to deteriorate. Micron, SanDisk, Western Digital, Samsung Electronics, and SK Hynix all need to answer this question through FCF and capex discipline.
The fourth signal is whether supply has begun responding to high profits. For DRAM, watch whether HBM/DDR5 continues to crowd out commodity capacity. For NAND, watch whether 2028 new capacity and WFE are pulled forward. For DDR4, watch whether legacy lines return. For HDD, watch HAMR/Mozaic yields and cost per EB. Once supply expands without constraint, memory returns to the traditional cycle framework.
The fifth signal is whether each company’s own core variables have loosened. For Micron, watch HBM catch-up, SCA/LTA, and conventional DRAM ASPs. For SanDisk, watch eSSD share, NAND long-term agreements, and 2028 supply. For Western Digital, watch nearline HDD, HAMR, and FCF. For Samsung Electronics, watch HBM qualification and full-category profit. For SK Hynix, watch HBM share, yield, and valuation crowding. These are reference indicators, not mechanical buy-or-sell conclusions.
1. After the Memory Pullback, Do Not Rush to Ask Whether to Buy or Sell
After a sharp memory rally, a 20%-30% pullback naturally leads readers to ask: is this the time to buy, or the time to clear out? This question cannot be answered directly, because the same pullback can have completely different drivers. Valuation compression, position unwinds, earnings compression, and narrative compression all look like price declines, but they mean very different things.
If it is only valuation compression, it means the earlier rally was too fast and positioning too crowded, but prices, orders, contracts, and cash flow have not deteriorated. If it is earnings compression, it means customers are rejecting price hikes, contract prices are weakening, orders are delayed, or inventory is worsening, and subsequent EPS may be revised down. If it is narrative compression, it means the larger framework around AI demand, long-term agreements, supply discipline, or cash flow is being questioned. That is more serious than single-quarter volatility.
This report does not try to judge “tomorrow’s move.” A more useful approach is to break the pullback into five reference signals: prices, contracts, inventory, supply, and cash flow. As long as most of these indicators have not deteriorated, the pullback looks more like valuation and positioning volatility. If two or three of them weaken at the same time, the risk may be more than a short-term drawdown.
The use of these five signals is simple. Prices prove whether the cycle is still intact. Contracts prove whether customers are truly afraid of shortages. Inventory proves whether demand has been pulled forward. Supply proves whether suppliers will turn high profits into the next round of oversupply. Cash flow proves whether profits are being retained. After a pullback, the real value is not in guessing the bottom, but in seeing whether these five pieces of evidence point in the same direction.
AI Drives a Sector-Wide Re-Rating of Memory: Who Has the Most Pricing Power Across DRAM, NAND, SSD, and HDD, with Samsung, Hynix, SanDisk, Western Digital, and Seagate Earnings Cross-Checking One Another
The earlier discussion explained why DRAM, NAND, SSD, and HDD are all entering the AI data stack. What matters more now is separating the quality of that “benefit.” AI can push demand higher, but only contracts and cash flow can keep the profits.
2. Three Worldviews: Not a Cycle Bottom, Possibly Not the Peak, but Profit Quality Must Be Dissected
The same set of data can be explained by three worldviews. The first is a cycle peak: prices surge, customers pull forward inventory, supplier profits hit highs, and then supply returns, inventory reverses, and valuations contract. The second is structural upcycle: AI lifts the demand center for HBM, DDR5, eSSD, nearline HDD, and mature DDR4, lengthening the industry cycle while still preserving volatility. The third is profit re-rating: customers use long-term agreements, prepayments, and locked orders to buy supply certainty, and memory-company profits begin to receive higher multiples.
These three worldviews are not an abstract debate. They directly determine company ranking. If one believes this is a cycle peak, one should buy the names with the fastest earnings beta, but avoid overstaying. If one believes in structural upcycle, one should buy companies with the highest AI purity and strongest customer qualifications. If one believes in asset re-rating, one should buy companies with hard contracts, strong cash flow, and clear capex discipline.
Current evidence is closer to somewhere between the second and third views. Prices have already proven the cycle upturn. AI demand has already proven structural change. Contracts and cash flow are proving asset re-rating, but the validation is not fully complete. In other words, memory can no longer be crudely valued as a “traditional cyclical stock,” but one also cannot declare prematurely that memory has fully escaped the cycle.
This distinction is important. Historically, memory has most often seen its lowest valuation when EPS is at its highest, because the market knows high profits will attract supply. But if LTAs and SCAs genuinely bind customers, prepayments improve cash flow, customer qualifications raise replacement costs, and capex discipline does not lose control, then this round of high profit is no longer just peak profit. It gradually becomes discountable profit.
In-Depth Memory Update: 3Q26 DDR Prices Up 32%, 2027 DRAM Demand +36%, UBS Monthly Report Calibrates the Memory Supercycle
This is also why the July memory monthly report matters. It not only revises up prices, but also places supply-demand gaps, LTA/SCA, capacity conflicts between HBM and conventional DRAM, and cash-flow issues in NAND and HDD into one framework. Price increases are the result. Supply discipline and customer commitments are the cause.
The authenticity of long-term agreements is the most important dividing line at this stage. A real long-term agreement must answer at least five questions: how long the term is, how volume is determined, how price floats, whether there is a downside floor, and how high the customer’s breach cost is. As long as these questions remain unclear, long-term agreements can only count as a qualitative positive. Once these questions enter disclosure, the market has reason to discount future revenue and profit forward.
Prepayment is especially important. In a long-term agreement without prepayment, customers have strong incentives to renegotiate in a downturn. In a long-term agreement with prepayment, customers are effectively exchanging cash for supply certainty, and suppliers can more easily bind future capacity planning to cash flow. For memory stocks, prepayment is not just a balance-sheet item. It is evidence of customer pain. Whether customers are willing to pay in advance directly indicates how large the shortage risk is in their minds.
The pricing mechanism is also critical. Fully fixed pricing looks the firmest, but it is not necessarily best for suppliers because it sacrifices upside leverage. Fully floating pricing looks flexible, but it does not provide enough value to buyers seeking to lock in supply. A more realistic structure is a hybrid of fixed volume, fixed floor price, partial floating price, and shared upside. Such a contract gives customers certainty while allowing memory suppliers to retain profit leverage in a rising-price cycle.
Take-or-pay is another dividing line. A contract with a minimum purchase obligation is completely different from an ordinary long-term purchase intention. Long-term agreements are not new in memory history, but many have been delayed, renegotiated, or softened when prices reversed. Only when customers truly bear cancellation costs do suppliers have reason to allocate capacity for them, and only then does the market have reason to reduce the cycle discount.
Third-party guarantees and capex support also cannot be ignored. Large cloud customers have strong credit, but contract enforceability is not only about credit; it is also about mechanism. The clearer the guarantees, prepayments, supporting capex, supply priority, and delivery terms, the more memory manufacturers resemble order-based producers. The more vague the terms, the more they resemble sentiment commitments at the top of the cycle.
Therefore, the investment value of memory long-term agreements lies not in the words “signed,” but in the hardness of the terms. Whenever any company discloses an LTA, SCA, or NBM in the future, the terms should be dissected first, and valuation considered afterward. Contract duration and coverage determine revenue visibility. Pricing mechanisms determine gross-margin visibility. Prepayment and take-or-pay determine cash-flow visibility. Only when all three are firm is it a true asset re-rating.
III. Where DDR4 Is Actually Tight: Legacy Capacity Has Been Crowded Out by HBM and DDR5, While Customer Migration Is Not That Fast
DDR4 prices are not rising because the product is advanced, but because legacy capacity has been crowded out. Major suppliers have shifted capacity, equipment, engineering resources, and customer priority toward HBM, DDR5, and AI products, slowing the recovery of mature DRAM supply. At the same time, customers in server cache memory, communications, industrial control, automotive, and parts of LPDDR4 cannot migrate immediately. Supply is unwilling to return, demand cannot leave right away, and DDR4 has therefore moved from mature tail-end inventory to a critical mature component.
Nanya Technology being upgraded to Overweight with a target price raised to NT$710 is a concentrated expression of this logic. It is not an HBM company. Precisely because it is not an HBM company, it is a better test of the legacy DRAM shortage. What the market is buying in Nanya is not technology leadership, but how long DDR4/LPDDR4 can keep rising, how large server exposure can become, whether eSSD-grade memory can improve the mix, and whether LTAs can lock in gross-margin repair.
DDR4 is most easily misread as a “laggard product catching up.” That is only half right. DDR4 is indeed not the most advanced product, but value does not come only from advancement. It also comes from customer substitution cost and the speed at which supply can return. When major suppliers actively abandon a mature category while customers still cannot stop using it immediately, it moves from low-end tail-end inventory to a critical mature component.
Nanya Technology Deep Dive: DDR4 EOL, SOCAMM Server Memory, and the NT$710 Target Price; the Three Tests for Revaluing Second-Tier DRAM Makers
But DDR4 also faces two key disconfirming signals. The first is prices rising too quickly, causing customers to pull forward purchases, after which inventory and cash flow deteriorate. The second is suppliers reopening legacy capacity after seeing high profits, breaking supply discipline. As long as these two disconfirming signals do not appear, DDR4 can continue to be viewed as a supply-rights asset. Once they appear, it will quickly revert to traditional cyclical beta.
Mature-memory exposures such as GigaDevice, Winbond, Macronix, Beijing Ingenic, Puya Semiconductor, and Dosilicon should be assessed with the same framework. Not every legacy category deserves a revaluation. Only those legacy categories where customers still need the product, supply cannot return, and profits can be retained deserve one. The logic for NOR and SLC NAND is more “small capacity, but indispensable,” while DDR4 is more “legacy capacity crowded out by AI.” The common denominator is supply power.
IV. HBM and DRAM Long-Term Agreements: Highest Purity Does Not Mean Highest Upside
HBM is the highest-AI-purity asset across the memory chain, and it is also the most crowded valuation asset. SK hynix, Samsung Electronics, and Micron are all on this line, but investors are buying different things in each. SK hynix is about leading share and customer lock-in. Samsung Electronics is about catch-up repair and breadth. Micron is about the U.S. AI memory entry point and DRAM/scenario beta.
HBM does not need to prove that demand is strong. What it really needs to prove is share, pricing, yield, advanced packaging, and customer qualification. The stronger HBM becomes, the more it squeezes effective capacity for ordinary DRAM and NAND, thereby supporting DDR5, DDR4, and parts of NAND pricing. This is HBM’s spillover value: it does not only make money itself; it also changes the entire memory supply curve.
JPM’s LTA framework is critical because it breaks “customers want to lock supply” into testable terms: duration, prepayment, price floor, fixed/floating pricing, take-or-pay, third-party guarantees, and capex support. Without these terms, long-term agreements are just verbal comfort. With these terms, LTAs can reduce the cyclical discount.
Micron Earnings Deep Dive: Q3 Results Far Above Expectations, the AI Memory Supercycle Enters the Delivery Phase, and How Much Profit Can LTAs Lock In?
Micron is the key sample in this round of long-term-agreement signals. It may not be the cheapest memory stock, but it best illustrates whether “cyclical EPS can be locked by U.S. AI customers into longer-duration cash flow.” If SCA/LTA terms become increasingly clear and customer prepayments or deferred revenue begin to enter the financial statements, the market will be more willing to reprice Micron from a high-beta cyclical stock into the U.S. AI memory entry point.
The divergence between Samsung Electronics and SK hynix is more like a choice between “purity and odds.” SK hynix has higher purity, but valuation and expectations are also more crowded. Samsung Electronics has lower purity than SK hynix, but if HBM4 qualification advances and NAND and ordinary DRAM recover at the same time, the upside may be higher. In the second half of the memory cycle, the right question is not only who is strongest, but how much of that strength has already been reflected and where the disconfirming signals lie.
SK hynix Deep-Dive Update: Is It Still Expensive? DDR5 Price Hikes Take Over, Korean Exports Surge, and Samsung Catch-Up Risk
The biggest risk on the HBM line is not a sudden disappearance of demand, but a change in competitive structure. As long as Samsung Electronics and Micron catch up faster than expected, SK hynix’s share and pricing assumptions will be revalued. If HBM4 qualification does not proceed smoothly, Samsung Electronics’ discount repair will be delayed. If customers begin to rebalance suppliers, all HBM companies will need their gross-margin and pricing curves reassessed.
HBM will also change ordinary DRAM through capacity squeeze. The market often looks at HBM, DDR5, and DDR4 separately, but manufacturing is not fully independent. HBM consumes advanced DRAM wafers, packaging resources, engineering teams, and customer coordination capacity. To pursue higher profits, suppliers will allocate their best resources to HBM and DDR5. As a result, the stronger high-end products become, the harder it is for mature and ordinary products to recover supply quickly.
This is also one reason DDR4, DDR5, and server DRAM prices can continue to strengthen. They are not all as high-end as HBM, but HBM has changed their supply priority. In the past, when mature DRAM prices rose, investors would ask when suppliers would expand legacy capacity. Now they also need to ask whether suppliers are truly willing to move resources back from HBM and DDR5 to legacy products. As long as the answer is no, mature DRAM still has supply power.
Micron has a dual attribute here. It is an HBM catch-up player, an ordinary DRAM cyclical-beta asset, and an entry point into the U.S. AI supply chain. Its upside comes from the overlap of three factors: a higher HBM revenue mix, strong traditional DRAM pricing, and greater visibility from customer LTAs and SCA. Any one of these alone looks cyclical, but when all three appear at the same time, the market will reconsider normalized profitability.
Samsung Electronics’ complexity also lies here. It is not a single HBM asset, but a combination of DRAM, NAND, HBM, foundry, and consumer electronics. Because it is broad, Samsung’s revaluation will not be as pure as SK hynix’s. Also because it is broad, as long as HBM qualification advances and NAND and ordinary DRAM repair at the same time, the market discount applied to it will decline. What Samsung most needs to prove is that breadth is not low purity, but a defensive and reversal combination under an extended all-category memory cycle.
SK hynix’s test is more direct. It needs to prove that HBM leadership is not a one-generation dividend, but sustained customer lock-in, yield, packaging capability, and product-roadmap leadership. If HBM4 remains ahead while DDR5 and ordinary DRAM prices take over, SK hynix can continue to enjoy high-quality profits. If share begins to loosen, crowded valuation will make the stock highly sensitive to even small disconfirming signals.
V. Where eSSD Is Actually Expensive: Qualification Slots, Controller Firmware, and LTAs Matter More Than NAND Price Hikes
NAND is the category the market most easily likes and doubts at the same time. Investors like it because AI data centers are driving demand for enterprise SSDs, high-capacity QLC, KV cache, RAG, data lakes, and object storage, with demand quality clearly better than handset and PC restocking. They doubt it because NAND has historically had weaker supply discipline. Once prices become too high, new capacity and customer resistance to price hikes can quickly become counterevidence.
The value of eSSD is not putting NAND dies into a drive enclosure. Data center customers want long-term stable supply, firmware reliability, controller capability, power consumption, capacity, error correction, power-loss protection, system compatibility, and failure-rate data. eSSDs that can enter CSP supply chains sell qualification slots and system reliability; NAND that cannot pass qualification remains more exposed to price cycles and channel inventory.
This round of the NAND bull case is no longer about “handset restocking.” AI NAND demand is rising from 205EB in 2025 to 609EB in 2027, and from 18% of total NAND demand to 41%. Enterprise/data-center SSD capacity shipments are up 139% YoY. These numbers show that the center of gravity in NAND demand is shifting from consumer electronics to the data-center capacity layer.
SanDisk and Kioxia are upstream samples for NAND earnings quality. SanDisk’s logic lies in eSSD share recovery, NAND LTAs, and earnings durability; Kioxia’s logic lies in NAND tightness, profit priority, and valuation repair. Neither is a simple price-hike stock. What really needs to be verified is LTAs and customer qualification.
NAND Sector Deep Dive Update: The Triple Test of AI eSSD Shortages, Supply Discipline, and 2028 New Capacity
The A-share mapping requires more caution. If Longsys and Techwinsemi rely only on inventory gains, they remain high-volatility module-chain names. If they can convert price increases into platform capability through enterprise SSDs, controllers, brands, and high-reliability customer qualification, then valuation can improve. In other words, A-share memory is not uninvestable, but inventory profit and platform profit must be separated.
SanDisk Deep Dive Update: Jefferies’ $3,000 Target Price, eSSD Share Recovery, and How NAND LTAs Revalue Earnings Durability
The key counterevidence in the second half of the NAND cycle is 2028. The 2026 and 2027 shortages are increasingly accepted by the market. The real long-term pressure is 2028 new capacity and the slope of AI eSSD demand. If new capacity comes online earlier than expected while eSSD demand does not continue to beat expectations, NAND will be re-discounted as a cycle earlier than DRAM.
This does not mean NAND cannot be bullish now. On the contrary, NAND remains one of the assets in AI storage with the clearest improvement in demand quality. But its valuation should carry a discount: strong demand drives EPS, hard LTAs drive multiples, and 2028 supply risk determines the discount. Without all three, NAND can easily fall back from asset revaluation into a price cycle.
The biggest difference between NAND and DRAM is their history of supply discipline. DRAM has higher concentration, with clearer crowding-out from HBM and advanced DRAM. NAND is more fragmented, has more technology routes, and has larger cycle differences between the consumer and data-center ends. When NAND prices rise, the market usually worries about a supply response sooner, which is reasonable. Therefore, for NAND to receive a higher multiple, it cannot rely only on price hikes. It needs customer structure and contracts.
eSSD qualification is the first gate for capitalizing NAND. Data-center SSDs are not ordinary consumer SSDs. Customer qualification cycles, firmware, controllers, reliability, power consumption, capacity, supply continuity, and other factors all affect adoption. Once a supplier enters high-end customer qualification, it is no longer just selling NAND dies; it is selling system reliability. The real gap among SanDisk, Kioxia, Samsung Electronics, Micron, Longsys, and Techwinsemi will open from here.
High-capacity QLC is the second gate. AI data is not only hot data. More of it is warm data, cold data, retrieval corpora, model versions, logs, and object storage. If high-capacity QLC expands in data centers, NAND demand will shift from the handset and PC cycle to the AI data-lake cycle. The issue is that QLC also needs yield, controllers, customer qualification, and cost curves to work together. Not all NAND suppliers will benefit equally.
LTAs are the third gate. If NAND only raises prices, the market will keep assigning a cycle discount. If NAND can lock in 2027 and 2028 bit demand in advance through NBM, LTAs, RPO, or similar customer commitments, then the cycle discount can decline. This is where the SanDisk investment debate sits: bulls are buying NAND earnings durability and LTAs; bears worry about the historical supply backlash in NAND.
The A-share NAND mapping should also use these three gates. Whether Longsys can move toward an enterprise SSD platform, and whether Techwinsemi’s controller capability can enter higher-quality customers, are not about short-term price increases. The key is qualification, products, and customers. Ordinary module profits come quickly but have low capitalizability; platform profits take longer to materialize but deserve a higher multiple.
VI. Where HDD Cash Flow Comes From: Cloud Customers Lock Nearline Capacity, HAMR Determines How Long Profits Can Stay
HDD looks like the oldest asset, but within this storage cycle it is the easiest to discuss through cash flow. AI data centers do not only need high-performance storage. They also need low-cost, high-capacity, long-term retention. Training data, model versions, logs, RAG knowledge bases, video, and object storage will not all sit in expensive SSDs. Nearline HDDs provide the underlying capacity for AI data retention.
HDD cash flow comes from three specific links. First, cloud customers continue to lock nearline EB to preserve AI data, giving orders better visibility than consumer HDDs. Second, if HAMR/Mozaic and capacity upgrades progress smoothly, higher capacity per disk will improve unit cost and gross profit per EB. Third, duopoly supply discipline makes it easier for Seagate and Western Digital to convert profit into FCF, buybacks, dividends, and deleveraging. HDD does not have the highest growth profile like HBM, but it is easier to use cash flow to prove that the cycle discount should decline.
AI Storage Deep Dive Update: Morgan Stanley’s May HDD and SSD Data Confirm Data-Center Capacity Demand Remains Elevated
There are two misreadings of HDD. The first is treating it as obsolete hard drives and ignoring AI data retention demand for a low-cost capacity layer. The second is treating it as a high-growth technology stock and assigning too high a growth multiple. The more reasonable positioning is as a cash-flow asset: upside may not be the highest, but visibility and return quality are easier to verify.
For Seagate and Western Digital, what matters most next is not how exaggerated revenue growth can become, but whether FCF can stabilize, cloud customer orders can extend, HAMR yield can improve, and buybacks and dividends can continue. If these indicators keep materializing, HDD does not need to be framed as an HBM story to reduce its old-cycle discount.
HDD also has clear counterevidence. If the SSD cost curve falls too quickly, nearline HDD’s total-cost-of-ownership advantage will be compressed. If HAMR yield is unstable, capacity upgrades will be delayed. If cloud capex weakens, order visibility will decline. Once these counterarguments appear, HDD will return to being a traditional cyclical stock rather than an AI cash-flow asset.
HDD can be priced separately also because its competitive structure is simpler than NAND’s. Seagate and Western Digital have clearer industry positions in nearline HDD. Customers are concentrated, but lock-in power is also stronger. As long as cloud customers continue to pursue low-cost, high-capacity retention, HDD is not an old asset immediately displaced by SSD. It is the lowest-cost capacity base in the AI data hierarchy.
Cash flow is the best language for HDD. HBM can talk about technology leadership, eSSD can talk about capacity shipments, DDR4 can talk about supply exit, and HDD should talk most about FCF. If Seagate and Western Digital convert high profits into buybacks, dividends, and balance-sheet improvement, the market will naturally reduce the cycle discount. They do not need to prove they are high-growth companies; they only need to prove they are no longer traditional high-volatility HDD cyclical stocks.
HDD and eSSD are not simple substitutes. Hot data, high IOPS, training, and inference services need SSDs; warm data, data lakes, and retrieval scenarios need high-capacity SSDs; cold data, logs, archives, model versions, and long-term object storage still need nearline HDDs. The more AI data grows, the larger the storage pyramid becomes, and both media types can be strong at the same time. The real risk is not that eSSD must replace HDD, but the long-term balance among SSD cost declines, HDD technology ramps, and cloud-customer TCO.
HDD’s valuation ceiling should also be restrained. It can move from an old cyclical stock to a cash-flow asset, but it should not be treated as an HBM growth stock. The most reasonable valuation expansion comes from FCF visibility, duopoly supply discipline, long-term order lock-ins, and shareholder returns, not unlimited upward revisions to revenue growth. In a portfolio, HDD’s role is more like the defensive cash-flow anchor for the second half of the storage cycle.
7. How to Track Representative Companies: Do Not Use the Same Yardstick for Micron, SanDisk, Western Digital, Samsung, and SK Hynix
The biggest trap in this memory cycle is ranking every company simply by “beneficiary of memory price increases.” Different companies have different profit sources, and the risk signals to watch during pullbacks are also different. Micron is not a pure DRAM stock. SanDisk is not ordinary NAND price beta. Western Digital and Seagate are not high-growth stories. Samsung Electronics and SK Hynix are also not the same HBM trade.
The core purpose of this table is not to provide buy or sell conclusions, but to separate the risk points. If Micron pulls back, first look at whether HBM and long-term agreements are weakening. If SanDisk pulls back, first look at eSSD qualification and NAND supply. If Western Digital pulls back, first look at nearline HDD and FCF. If Samsung Electronics pulls back, first look at whether HBM qualification is progressing. If SK Hynix pulls back, first look at whether share and valuation crowding are both becoming problems.
This also explains why the conclusion may differ even after the same 20%-30% pullback. If the core variables have not deteriorated, the pullback is more likely valuation digestion. If the core variables start to weaken, the pullback may be a fundamental re-rating. Readers do not need to guess the bottom every day. They only need to list each company’s most sensitive indicators and keep tracking whether they are moving in the same direction.
A target-price table is less useful than this reference-indicator table. Target-price increases reflect changes in sell-side models, but target prices are not conclusions. What truly needs to be compared is which model item changed: ASP assumptions, volume assumptions, gross-margin assumptions, long-term agreement coverage, capital expenditure, cash-flow discount rate, or valuation multiple.
Target-Price Revisions Cannot Be Ranked Directly; They Must Be Split into Five Layers of Assumptions
The biggest problem in current memory research reports is that target-price increases are becoming more frequent. Nanya Technology, SK Hynix, Samsung Electronics, Micron, SanDisk, Kioxia, Seagate, and Western Digital have all seen varying degrees of upward revisions. If one looks only at target-price numbers and percentage increases, it is easy to reach the wrong ranking: the company with the largest target-price increase is the most worth buying, and the company with the highest target price has the most upside. That reading is too crude.
A target price is not a research conclusion; it is the composite result of model assumptions. A target-price increase may come from higher ASP assumptions, or from higher volumes, higher gross margin, lower expense ratios, lower long-term capital expenditure, a lower FCF discount rate, or multiple expansion. Different sources correspond to completely different asset characteristics.
The first layer is pricing assumptions. Upward revisions to DDR4, DDR5, HBM, NAND, eSSD, and nearline HDD prices flow into EPS first. Pricing assumptions are the easiest to use to drive target prices, but they are also the easiest for the market to discount, because the higher prices go, the more likely they are to invite customer resistance, supply response, and inventory risk. An upward revision to pricing assumptions can only indicate stronger cycle beta; it cannot directly prove asset re-rating.
The second layer is volume and customer assumptions. If the revision comes from eSSD EB, nearline HDD capacity, HBM shipments, AI server DRAM capacity, or DDR4 server exposure, the quality of the revision is higher. This is because it is not just price going up; the AI data stack is genuinely pulling up product demand. Volume and customer assumptions deserve higher multiples than pricing assumptions, but they still require scrutiny of qualification cycles, customer concentration, and delivery bottlenecks.
The third layer is gross-margin and product-mix assumptions. A higher HBM mix, higher enterprise SSD mix, recovery in DDR4/LPDDR4 gross margin, and nearline HDD capacity upgrades can all make gross margin higher than in a traditional cycle. A gross-margin revision is more important than an ASP revision, because it indicates the company has not given all price increases away to costs, channels, or customers. But gross margin must also be assessed alongside inventory and cash flow. Strong gross margin in one quarter does not necessarily mean good profit quality.
The fourth layer is contract and cash-flow assumptions. LTAs, SCAs, NBMs, prepayments, take-or-pay terms, price floors, cloud customer lock-ins, FCF, buybacks, and dividends are the parts of a target price most worth capitalizing. If a target-price increase comes from a lower discount rate or a higher long-term ROE center, it means analysts are not just looking at this year’s EPS, but are reducing the cycle discount.
The fifth layer is valuation-multiple assumptions. Memory stocks are most prone to controversy at this layer. Bulls will argue that industry cyclicality is declining, long-term agreements improve visibility, and AI customer lock-ins mean P/E should rise. Bears will argue that memory remains a capital-intensive, commoditized cyclical business where supply will return. This debate will not be resolved by saying “AI demand is strong.” It must be resolved through contract disclosures and cash flow.
Once these five layers of assumptions are separated, the quality of many target-price increases becomes clearer. Nanya Technology’s revisions mainly come from legacy DRAM supply rights and DDR4 prices entering the model. Micron’s revisions depend more on SCA/LTA, HBM, and its role as a U.S. AI memory entry point. SanDisk and Kioxia’s revisions lie in NAND/eSSD profit quality. Seagate and Western Digital’s revisions come from a lower HDD cash-flow discount. They all look like memory, but investors are actually buying four different types of profit.
The biggest investment risk is mistaking pricing assumptions for multiple assumptions. When pricing assumptions are revised up, the stock can rise, but the market will keep asking about peak profit. Only when contract and cash-flow assumptions are revised up does valuation have a chance to expand. In other words, target-price increases can be useful, but one must first ask: is this revision to this year’s profit, or to long-term profit quality?
A-Share Mapping: Inventory Profit and Platform Profit Must Be Separated
A-share memory names often perform very strongly during memory upcycles because profit beta arrives quickly. Upstream prices rise, low-cost inventory is revalued, module and channel profits are released, and investors can easily see financial statements improve. But A-share mapping is also the easiest to misread: not all “beneficiaries of memory price increases” deserve asset re-rating.
GigaDevice is closer to supply rights in mature categories. It has NOR, SLC NAND, specialty DRAM, MCU, and customer access. The logic is not single-product price beta, but that legacy categories are becoming harder to replace in AI hardware, industrial, automotive, and control scenarios. If improvements in DRAM, NOR, and SLC NAND prices can flow into gross margin without deterioration in inventory and cash flow, GigaDevice looks more like a legacy-memory supply-rights platform. If it is only a short-term price increase in one or two categories, the market will still treat it as cycle beta.
Longsys and Techwinsemi are more about platform validation. They will of course benefit from NAND prices and inventory, but long-term value is not in inventory. It is in enterprise SSDs, controllers, branded customers, high-reliability scenarios, and customer qualification. Module companies release profit most easily in the short term, and they are also most easily hit by inventory reversal when prices turn. What can truly be capitalized is not inventory gains, but the migration from modules to platforms, from channels to customers, and from low gross margin to high-reliability products.
Ingenic Semiconductor, Puya Semiconductor, and Dosilicon are more about small-capacity and reliability entry points. For Ingenic Semiconductor, watch automotive-grade and industrial customers. For Puya Semiconductor, watch NOR, EEPROM, and MCU-related memory. For Dosilicon, watch SLC NAND, NOR, and specialty memory. They are not pure AI data-center capacity-layer names, but the more complex AI hardware becomes, the more stable demand becomes for boot, control, configuration, and high-reliability memory. Small-capacity categories may not be large, but when customers cannot do without them and supply is not easy to bring back, they can also become high-quality profit sources.
For A-share mapping, four numbers matter most. First, whether gross margin is improving with prices, rather than relying only on revenue expansion. Second, whether inventory turnover is healthy, rather than piling price-increase expectations into high-priced inventory. Third, whether operating cash flow is moving in line with profit, rather than the income statement looking good while cash flow is weak. Fourth, whether customer qualification and product mix are moving up, rather than remaining stuck in consumer modules and channel volatility.
If all four numbers improve together, A-share memory can move from price beta to profit quality. If one only sees prices and revenue, without improvements in gross margin, inventory, cash flow, and customer structure, it can only be viewed as cycle beta. The opportunity in A-share memory is large, but the acceptance threshold should also be more detailed, because inventory and channels amplify cycle beta and also amplify cycle reversal.
During Pullbacks, Distinguish Between Valuation Compression, Earnings Compression, and Narrative Compression
After the memory trade has risen significantly, pullbacks are inevitable. The pullback itself is not important. What matters is what the pullback is attacking. If it is valuation compression, the market believes positives have already been reflected, but fundamentals have not changed. If it is earnings compression, ASP, shipments, gross margin, or customer orders have started to run into problems. If it is narrative compression, the main line of AI demand, long-term agreements, and cash-flow assetization is being questioned.
Valuation compression usually happens when expectations are too crowded. HBM leaders are most likely to face this kind of pullback because they have the highest quality, the most concentrated positioning, and the fullest expectations. If SK Hynix pulls back because of valuation crowding, but HBM share, customer qualification, DDR5 follow-through, and FCF have not changed, the pullback looks more like position rebalancing. If Samsung Electronics pulls back because catch-up expectations have overheated, one should first check whether HBM qualification and NAND/DRAM recovery have changed.
Earnings compression is more serious. DDR4 contract prices falling below expectations, NAND customers rejecting price increases, slower eSSD EB shipments, nearline HDD customer order delays, and deteriorating module inventory turnover are all earnings-level counterevidence. This type of pullback cannot simply be understood as a buying opportunity, because it directly affects EPS and target-price models. When memory stocks suffer earnings compression, the decline usually does not end in one day; it is accompanied by sell-side downward revisions and continued deterioration in inventory data.
Narrative compression is the most dangerous. For example, the market may start to believe AI inference demand is below expectations, cloud capex is slowing because of power, financing, or regulation, LTA terms are actually soft, 2028 new supply is coming forward, or customers are regaining pricing power. These changes compress both valuation and earnings, because they are not just one quarter of data; they shake the premise for asset re-rating.
Therefore, the first question after a pullback is not how much the stock has fallen, but whether the evidence has changed. Price evidence, contract evidence, customer evidence, inventory evidence, cash-flow evidence, and supply evidence: whichever of these six types of evidence has weakened determines the nature of the pullback. If valuation was merely overheated, strong assets can still be watched. If contract and cash-flow evidence weakens, the asset re-rating assumption must be lowered. If supply discipline is broken, the entire memory line must be repriced.
This pullback framework can also help control portfolio rhythm. HBM is suitable as a quality anchor, but one should not add blindly when it is crowded. DDR4 and mature memory are suitable for expectation gaps, but inventory must be watched closely. eSSD is suitable for profit quality, but 2028 supply must be tracked. HDD is suitable as a cash-flow anchor, but should not be assigned growth-stock multiples. Different assets have different entry points and different stop-loss conditions.
The Most Important Counterevidence: Inventory, Contracts, Supply, Customers, and Cash Flow
Memory stocks can easily make investors overexcited because income statements improve very quickly. Once ASP rises, gross margin and EPS are revised up immediately. Companies with low inventory costs may even release substantial profit beta within a single quarter. But the real risk in cyclical stocks often begins when the income statement looks best.
The first type of counterevidence is inventory. In an upcycle, customers place orders early to ensure supply, channels stock up early to earn price spreads, and module makers expand inventory to lock in costs. Looking only at revenue and gross margin can misjudge demand strength. Inventory turnover, operating cash flow, and customer structure must be examined at the same time. Strong prices, healthy inventory, and strong cash flow indicate a high-quality upcycle. Strong prices, heavy inventory, and weak cash flow are classic signals of the late cycle.
The second type of counterevidence is contracts. Terms such as LTA, SCA, and NBM have no magic by themselves. The key is the clauses: how long the term is, whether there are prepayments, how price floors are set, whether there are take-or-pay provisions, how high the cost is for customers to cancel orders, whether third-party guarantees exist, and whether suppliers expand capacity without discipline for the sake of contracts. These questions determine whether long-term agreements are cash-flow assets or letters of intent at the cycle peak.
The third type of counterevidence is supply. DRAM, NAND, and HDD have different supply elasticities. HBM and advanced DRAM are constrained by wafers, packaging, and customer qualification, so supply elasticity is slow. NAND has historically had weaker supply discipline, and 2028 new capacity will enter valuations earlier. HDD has a clearer duopoly and technology roadmap, but HAMR yield is a hard constraint. Being bullish on memory cannot rely only on the demand curve; one must also watch whether supply is starting to respond to prices.
The fourth type of counterevidence is customers. AI customers are now willing to lock in supply because shortages are more frightening than high prices. If AI inference revenue, cloud capex, data-center delivery, grid connection, or GPU/ASIC deployment pace slows, customer acceptance of long-term agreements and high-priced procurement will decline. Demand does not exist in a vacuum. It ultimately has to show up in AI service revenue, compute deployment, and data-center delivery.
The fifth type of counterevidence is cash flow. EPS can be pushed up quickly by prices; FCF is harder to disguise. If manufacturers make money and then restart large-scale capacity expansion, cycle memory will return. If they convert profit into buybacks, dividends, deleveraging, and more restrained capital expenditure, the market will gradually reduce the cycle discount. HDD can most easily provide the answer first on this point, while DRAM and NAND manufacturers must also provide an answer.
8. How to Validate the Next Four Quarters
Over the next four quarters, memory should not be assessed only by price. Price remains the first signal, but it is not the final answer. A more reasonable sequence is: in 3Q26, watch price pass-through; in 4Q26, watch contracts and inventory; in 1H27, watch earnings quality and cash flow; in 2H27, watch supply discipline and 2028 disconfirming evidence.
The most important issue in 3Q26 is whether pricing can continue to pass through. If DDR, NAND, eSSD, NOR, SLC NAND, and nearline HDD quotes remain strong, it means the demand-supply gap is still there. But this is also when investors are most likely to get overexcited, because strong pricing does not automatically prove asset re-rating. It must be checked alongside whether customers are accepting longer contracts, whether channels are overstocking, and whether module-maker and original-manufacturer inventories are healthy.
In 4Q26, the focus shifts from pricing to contracts. Whether Samsung Electronics, SK Hynix, Micron, SanDisk, and Kioxia disclose harder long-term agreements, and whether contract duration, prepayments, price floors, and volume-price mechanisms become clearer, will determine whether the market is willing to keep raising multiples. If companies only disclose “strong customer demand” without disclosing contract enforceability, the valuation benefit from long-term agreements will be discounted.
In 1H27, the focus should be earnings quality. Gross margin, operating margin, operating cash flow, FCF, inventory turnover, and capital expenditure will determine whether the prior year’s price increases have been retained. If DRAM and NAND original manufacturers improve gross margins but also raise capex significantly, the market will worry about the next round of oversupply. If HDD companies continue to improve FCF and buybacks, the cash-flow-asset logic will become more stable.
2H27 and 2028 are the supply stress test. New NAND capacity, DRAM WFE, capital-allocation priorities across HBM and DDR5, restarts of older lines, and new variables such as CXMT will all affect long-term valuation. True bulls are not afraid of supply expansion itself; they are afraid of expansion without customer constraints, price floors, or capital-return discipline.
Compressed into one sentence, the validation framework is: price proves the cycle, contracts prove the structure, cash flow proves the asset, and supply discipline determines whether the cycle comes back.
9. Five Common Misreadings
The first misreading is assuming that memory price increases equal asset re-rating. Price increases are the entry point to the income statement, not the exit point for valuation. Without contracts, customer qualification, and cash flow, the more aggressively prices rise, the more the market will worry about peak earnings.
The second misreading is interpreting strong HBM as meaning all DRAM is risk-free. Strong HBM does compress advanced DRAM capacity and supports DDR5 and some DDR4, but ordinary DRAM still depends on customer mix and inventory. HBM is high-purity; ordinary DRAM requires joint validation by supply-demand and contracts. They cannot be blended into the same asset.
The third misreading is assuming eSSD will directly replace HDD. AI data centers are not a single-medium architecture. Hot data requires eSSD, warm data requires high-capacity SSDs, while cold data and long-term retention still require nearline HDD. Strength in both eSSD and HDD instead shows that the AI data pyramid is expanding.
The fourth misreading is treating all A-share memory names as mappings of overseas original manufacturers. GigaDevice, Longsys, Deyi Micro, Beijing Ingenic, Puya Semiconductor, and Dosilicon each have different logic. Niche memory depends on supply rights and customer entry points; modules/controllers depend on inventory and enterprise SSD platformization. They cannot all be covered by a single “beneficiary of memory price increases” label.
The fifth misreading is thinking 2028 supply risk is too far away. Memory stocks will not wait until supply is actually released before reacting. The market will trade capex, WFE, new fabs, and changes in customer bargaining power in advance. Investors do not need to reject the current opportunity because of 2028 risk, but they must include it in the valuation discount.
10. Portfolio Positioning: Four Asset Types Cannot Use the Same Sizing Logic
The second half of the memory trade cannot be solved by holding only a single leading name. Different assets have different hit rates, payoff profiles, and disconfirming evidence; applying the same sizing logic to all of them will be uncomfortable. HBM is the high-quality core, eSSD is the earnings-quality position, DDR4 and niche memory are expectation-gap beta positions, and HDD is the cash-flow anchor. They are all on the same memory chain, but the appropriate position size and observation period are completely different.
HBM is suitable as a quality core holding, but investors must accept crowding. The advantage of assets such as SK Hynix is high certainty; the disadvantage is that the market also understands them most fully. It is suitable to maintain core exposure while customer qualification, share, the HBM4 roadmap, and FCF continue to deliver. It is not suitable to keep adding unconditionally when valuation is extremely crowded and everyone is looking in only one direction. Quality assets can still fall; when they do, the key is to judge whether fundamentals have changed.
Samsung Electronics and Micron are more suitable as recovery and beta positions. Samsung Electronics is a breadth asset and a catch-up recovery trade; Micron is a U.S. AI memory entry point and long-term-agreement beta trade. Their sizing logic is not “who is strongest,” but “which assumptions are not yet fully priced.” If Samsung’s HBM qualification advances and NAND and DRAM recover together, its discount has room to narrow. If Micron discloses harder SCA/LTA terms and continues to raise HBM revenue expectations, its cycle discount will decline.
eSSD and NAND are suitable as earnings-quality positions, but require forward-looking disconfirming evidence. The advantage of the SanDisk, Kioxia, Longsys, and Deyi Micro line is strong AI capacity demand, fast enterprise SSD growth, and clear product-mix improvement. The risks are also clear: NAND supply discipline, new capacity in 2028, consumer-end resistance to price increases, and inventory. From a sizing perspective, they cannot be treated as growth stocks with no disconfirming evidence. It is more appropriate to raise weight when eSSD EB, long-term agreements, gross margin, and inventory are all improving, and to proactively reduce risk when evidence on capex and new capacity strengthens.
DDR4, NOR, and SLC NAND are suitable as expectation-gap beta positions. Their common feature is “mature but critical.” The market previously assigned them low valuations because they were viewed as legacy categories; now they are being rediscovered because AI is pushing major manufacturers’ capex toward the high end, tightening supply in mature categories. The benefit of expectation-gap positions is large upside beta; the downside is that disconfirming evidence is also direct. Unless price, gross margin, inventory, and customer mix improve at the same time, they should not be treated as high-quality cash-flow assets.
HDD is suitable as a cash-flow anchor. Seagate and Western Digital are not the most exciting names, but they are the most suitable to play the cash-flow role in a portfolio. The key is not how high revenue growth is, but nearline EB, price per EB, HAMR yield, FCF, buybacks, and dividends. If the memory trade moves from price beta to earnings quality, the relative value of HDD-type assets will rise. If the market starts chasing high beta again, HDD may underperform, but on the downside it is also easier to support valuation with cash flow.
The portfolio rhythm can be simplified into three stages. In the first stage, the price-upgrade phase, low-cost inventory, high beta, and legacy-category beta perform best. In the second stage, the earnings-quality phase, HBM, eSSD, and long-term-agreement assets are stronger. In the third stage, the cash-flow validation phase, HDD and original manufacturers that can convert profits into buybacks and dividends have the advantage. The current phase looks more like the second stage: pricing has already been proven, and the market is starting to look for which profits can be retained.
This rhythm also explains why investors cannot only chase the hottest names. The hottest names are often the highest-quality assets, but they are also the most vulnerable to valuation crowding. The cheapest names often have expectation gaps, but require stricter financial validation. A good portfolio should let HBM provide quality, eSSD provide structural growth, DDR4/niche memory provide expectation-gap upside, and HDD provide cash flow, rather than concentrating all positions in one type of profit.
For final validation, each asset type in the portfolio can be asked one question. For HBM, ask whether share and customer qualification are loosening. For DDR4 and niche memory, ask whether price increases are flowing through to gross margin and cash flow. For eSSD, ask whether EB shipments, long-term agreements, and 2028 supply are still moving in the same direction. For HDD, ask whether FCF, buybacks/dividends, and HAMR yield are continuing to deliver. As long as the answers remain broadly positive, pullbacks are more likely position and valuation volatility; only when the answers turn negative does it become fundamental repricing.
This is also how the current memory chain differs from general AI hardware. GPUs, ASICs, optical modules, PCBs, and liquid cooling are more about orders and capacity slopes. Memory must look not only at demand, but also at supply discipline. Because memory has such strong historical memory, any high profit will automatically make the market think of capacity expansion and oversupply. For memory to truly move beyond its old cycle discount, it must prove not only strong AI demand, but also that suppliers are not turning all high profits into the capex for the next round of oversupply.
Therefore, at the portfolio level, the most valuable exercise is not a binary judgment of “fully invested in memory” or “zero memory exposure,” but continuously increasing the weight of high-quality profits and reducing the weight of pure spot profits. In the early stage of price increases, spot profits can make money. In the earnings-quality stage, contracts and customer qualification are more valuable. In the cash-flow stage, FCF and shareholder returns are more valuable. Changing weights across different stages is what prevents a good industry chain from becoming an emotion-driven trade.
XI. Industry Position: Memory Is Not a Supporting Actor in AI Hardware, but the Second Battleground for Profit Allocation
Memory has often been treated as a supporting actor in AI hardware. The market first looks at GPUs, then ASICs, networking, optical modules, PCBs, power, and liquid cooling, while memory is often viewed as “a server BOM component that will go up in price.” That view is no longer sufficient. As AI systems move further toward inference, long context, RAG, agents, and multimodal data, memory and storage look less like ordinary components and more like a constraint layer on compute utilization.
GPUs determine how fast the system can compute. Networking determines how smoothly clusters connect. Power determines whether racks can be deployed. Memory and storage determine whether data can be fed in, whether state can be retained, and whether inference can be served continuously. HBM addresses bandwidth. DDR5 and LPDDR address system memory. Enterprise SSDs address hot data and high-frequency access. HDDs address low-cost long-term retention. NOR and SLC NAND address boot, control, and reliability entry points. Together, these layers form AI data infrastructure.
This is also why profit allocation in memory and storage will become increasingly complex. HBM was the first to be recognized because it is directly tied to GPUs. DDR5 and standard DRAM followed, as memory capacity in CPU servers and AI nodes was revised upward. Next come enterprise SSDs and high-capacity NAND, because inference, RAG, and data lakes need a capacity layer. Finally come nearline HDDs and mature small-capacity storage, because data retention and control entry points will not disappear. Memory and storage are not a single line item, but a multilayer tolling structure across the AI workflow.
From an industry perspective, memory and storage are undergoing two rounds of re-rating. The first is a demand re-rating: the market has realized that AI consumes not only GPUs, but also large amounts of memory and storage capacity. The second is a business-model re-rating: customers are increasingly willing to use long-term agreements, prepayments, qualification, and committed orders to secure supply certainty. The first re-rating lifts prices and EPS. The second is what changes valuation multiples.
The most important change is that customers are beginning to treat “memory and storage shortages” as a systemic risk. In past PC and smartphone cycles, customers could wait for prices to fall, control inventory, and delay procurement. In AI data centers, a shortage of HBM affects GPU delivery, a shortage of DDR5 affects server configurations, a shortage of enterprise SSDs affects inference and retrieval performance, and a shortage of HDDs affects the cost of data retention. Shortages are no longer merely a procurement issue, but an issue for cloud services, AI products, and capex efficiency.
When shortages become a systemic risk, supplier bargaining power changes. Memory suppliers are no longer merely selling standardized chips. They are selling supply certainty, customer qualification, and delivery reliability. Long-term agreements, SCA, NBM, and customer order lock-ins are external expressions of this change in bargaining power. What investors truly need to assess is how long this bargaining power can last, and whether suppliers will again undermine supply discipline because of high profits.
This is also what makes memory and storage different from other AI hardware segments. Optical modules and PCBs are more about product generations and customer share. Power and liquid cooling are more about project delivery and capacity expansion. Memory and storage additionally require cycle memory. The upside is powerful, but historically, high profits have also triggered strong supply responses. To earn a higher valuation, the sector must prove strong demand, firm contracts, restrained supply, and good cash flow at the same time.
If all four conditions hold, memory and storage are not supporting actors in AI hardware, but the second battleground for profit allocation. The first battleground is GPUs and ASICs, which determine the compute budget. The second is memory and storage, which determine the data budget and system efficiency. The larger AI capex becomes, the longer data is retained, and the denser inference calls become, the less memory and storage should be underestimated within the profit pool.
The best state for this industry chain is not that all categories rise together, but that each layer produces verifiable evidence on its own. HBM proves bandwidth monetization through customer qualification and share. DDR4 and niche memory prove supply power through gross margin and inventory. Enterprise SSDs prove capacity-layer profits through exabyte shipments and long-term agreements. HDDs prove cash-flow asset value through FCF and buybacks. The more evidence there is, the more memory and storage look like a group of assets. The less evidence there is, the more they look like a cycle trade.
XII. Conclusion: Before Buying In or Exiting, First Check Whether the Five Signals Are Aligned
After this memory and storage pullback, the least useful response is to immediately call for buying in or exiting. Prices have already risen, target prices have already been chased, and the market now needs to verify whether five signals are aligned: whether pricing has broken, whether contracts have softened, whether inventory is building, whether supply has lost control, and whether cash flow is keeping up with profits.
The best assets are not the categories that have fallen the most, nor the categories that rallied the hardest earlier, but the categories where the core signals have not deteriorated. For HBM, watch share and qualification. For DDR4, watch legacy capacity gaps and inventory. For enterprise SSDs, watch customer qualification and long-term agreements. For HDDs, watch cloud customer order lock-ins and FCF. The same share-price decline can mean completely different things for different companies.
The true topping signals are also clear. First, prices are still rising, but customers begin to reject firmer contracts. Second, inventory and receivables start growing faster than revenue. Third, suppliers reinvest high profits into unconstrained capacity expansion. Fourth, AI data-center delivery, cloud capex, or inference revenue slows meaningfully. Fifth, cash flow fails to keep pace with profits, and buybacks, dividends, and deleveraging do not materialize. As long as these signals do not appear in concentration, memory and storage look more like they are moving from a price trade into a profit-quality trade, rather than simply reaching a cyclical top.
Conversely, if these signals begin to appear at the same time, investors can no longer use “long-term AI demand is strong” to obscure near-term risk. Memory and storage are among the most evidence-driven segments in a highly cyclical industry, and every long-term narrative must face quarterly data. For bulls to keep winning, prices, contracts, inventory, cash flow, and supply discipline must continue to move in the same direction. If two or three of them start to diverge, valuations will react before profits do.
A more practical approach is to divide memory and storage positioning into three reference scenarios: “continue to monitor,” “increase weight,” and “reduce risk.” When at least four of pricing, contracts, inventory, cash flow, and supply discipline are aligned, memory and storage are still in a phase of improving profit quality, and pullbacks are driven more by valuation and positioning than by a fundamental peak. If pricing remains strong but contracts soften, inventory rises, or cash flow weakens, exposure that depends only on spot profits and inventory gains should be reduced. If customer resistance to price hikes, capex restarts, and inventory deterioration appear together, memory and storage should be placed back into a traditional cyclical framework. The advantage of this framework is that investors do not need to guess the top every day; they only need to keep comparing whether the evidence remains aligned.
Therefore, the investment framework for this memory and storage cycle should shift from “who is raising prices” to “whose five signals have not deteriorated.” Pricing is only the entry point. Contracts, customer qualification, inventory, capex, and cash flow are the conclusion. As long as these indicators continue to align, pullbacks look more like valuation and positioning volatility. If prices are strong but contracts are weak, inventory rises while cash flow is poor, and capex loses control while customers begin to reject price increases, that is the real signal of a cyclical top.
The core judgment can be compressed into one sentence: after the memory and storage pullback, do not first ask whether to buy in or exit; first ask whether the five signals have deteriorated. Investors should not be looking at the words “memory and storage,” but at Micron’s HBM and long-term agreements, SanDisk’s enterprise SSDs and NAND supply, Western Digital’s nearline and FCF, Samsung Electronics’ HBM qualification, and SK hynix’s share and valuation crowding.