
Memory LTA Deep Dive: $11 Billion in Guarantees, $22 Billion in Cash and Letters of Credit: How Binding Are SanDisk and Micron’s AI Memory Contracts?
目录
Too Long; Didn’t Read
1. What This Report Adds: Decomposing “This Time Is Different” Into Contracts, Buyers, and Demand
2. Microchip Case Study: Loose Orders Cannot Stop an Inventory Collapse
III. Hemlock Case Study: Hard Law, Difficult Cash Recovery
IV. First Layer of Protection in New Memory LTAs: Cash, Letters of Credit, and Third-Party Guarantees
V. Second Layer of Protection: This Time the Buyers Are Cloud Providers, Not Fragile Small and Mid-Sized Customers
VI. Third Layer of Protection: AI Memory Demand Looks More Like a Capacity Bottleneck Than Analog Restocking
VII. The Difference Between SanDisk and Micron: NAND LTAs and DRAM/HBM LTAs Are Not the Same Asset
VIII. Contract Protection Is Not Unlimited: The Three Most Dangerous Falsification Points
IX. Trading Implications: Memory Stocks Move from Price Beta to Contract-Quality Screening
10. The Five Variables to Watch Most Closely From Here
11. Conclusion: Contracts Are Harder, and the Trade Is More Selective
本内容基于公开资料和研报数据整理,不构成任何投资建议,不代表任何个人观点,仅供学习参考,请理性阅读
This Bernstein report frames the new round of memory LTAs through two older cases: Microchip Technology’s loosely constrained orders and Hemlock’s hard contracts. The conclusion is direct: SanDisk and Micron now have more cash, letters of credit, and stronger buyers, which meaningfully raises the profit floor. But contracts can only buffer the cycle; they cannot eliminate it.
Too Long; Didn’t Read
Start with the collateral in this round of LTAs. Most old semiconductor LTAs were merely buyer commitments, leaving suppliers with little more than future litigation rights. The new memory LTAs embed cash deposits, letters of credit, or third-party guarantees into the contract structure upfront. SanDisk and Micron have already secured real funding constraints, turning default costs from paper promises into locked-up capital.
Old LTAs failed at two extremes. Microchip’s PSP and analog-chip NCNR orders were too soft: once customer inventories exploded, customers could delay or suspend orders, and suppliers ultimately had to ship less voluntarily. Hemlock’s polysilicon take-or-pay contracts were too hard: the company could win in court, but cash recovery was diluted once customers went bankrupt. The key change in the new memory LTAs is that legal recourse has been pulled forward into collateral, while buyers are now cloud vendors and AI platforms with stronger balance sheets.
Microchip lost to inventory. Analog and MCU shortages in 2020-2022 led customers to place long-term orders early, but much of the demand came from shortage anxiety and duplicate ordering, not a synchronous increase in real end demand. When consumer and industrial demand cooled, Microchip’s net sales fell more than 42% year over year in Q3 FY25 at the peak of the inventory correction. Analog Devices also went through multiple quarters of revenue contraction. This shows that loose LTAs are poor protection against channel destocking.
Hemlock won lawsuits but struggled to collect cash. Polysilicon LTAs had fixed prices, take-or-pay terms, and liquidated damages, making them legally stronger than the Microchip case. But spot prices fell sharply below contract prices, destroying buyer economics. SolarWorld Sachsen was already insolvent even after a large damages award. Kyocera later exited through a large settlement, showing that hard contracts still fail when buyers lack cash.
AI demand strengthens the incentive to perform. Analog chips are like oxygen: once there is enough, one additional unit has little value. In AI training and inference, HBM, DRAM, and NAND are more like capacity and bandwidth in a compute system. Each additional layer of memory can expand context, concurrency, and model capability. As long as cloud vendors are still competing to deliver stronger AI services, the temptation to default and reclaim deposits will be constrained by supply continuity, system delivery, and future commercial relationships.
Valuation depends on the protection ratio. SanDisk’s $3,000 price target implies that the market is willing to capitalize part of peak earnings. Going forward, investors cannot look only at NAND or DRAM spot prices. They also need to track RPO, cash deposits, letters of credit, guarantee coverage, buyer concentration, AI capex, and inventory days. These variables determine whether LTAs become a profit base or the next cyclical illusion.
1. What This Report Adds: Decomposing “This Time Is Different” Into Contracts, Buyers, and Demand
The value of this report is that it answers a harder question: the semiconductor industry has signed LTAs before, so why are this round of memory LTAs more credible?
Over the past few months, the rally in memory stocks has taken the market to a sensitive point. SanDisk, Micron, Samsung Electronics, SK Hynix, and Kioxia are all being repriced, and investors increasingly care about two questions: first, how long AI demand can last; second, whether suppliers can turn this pricing upcycle into more stable profits. LTAs sit at the intersection of these two questions.
SanDisk Deep-Dive Update: Bernstein’s $3,000 Price Target and How New Memory LTAs Could Rewrite the NAND Cycle Discount
In the last memory rerating, the market mainly focused on prices, shortages, and HBM/NAND supply-demand. This report takes a different angle: it first revisits old semiconductor LTAs and asks why they failed, then examines what protections SanDisk and Micron have added today. This angle matters because memory has never been a non-cyclical industry. Any “earnings capitalization” case must answer whether contracts can survive a downcycle.
The report’s answer has three layers: cash is posted upfront, buyers are stronger, and demand is more structural. Missing any one of the three is not enough. Legal terms alone can become Hemlock-style prolonged litigation. Demand heat alone can become a Microchip-style inventory illusion. High-quality buyers without collateral still do not prove that suppliers have changed the cycle discount.
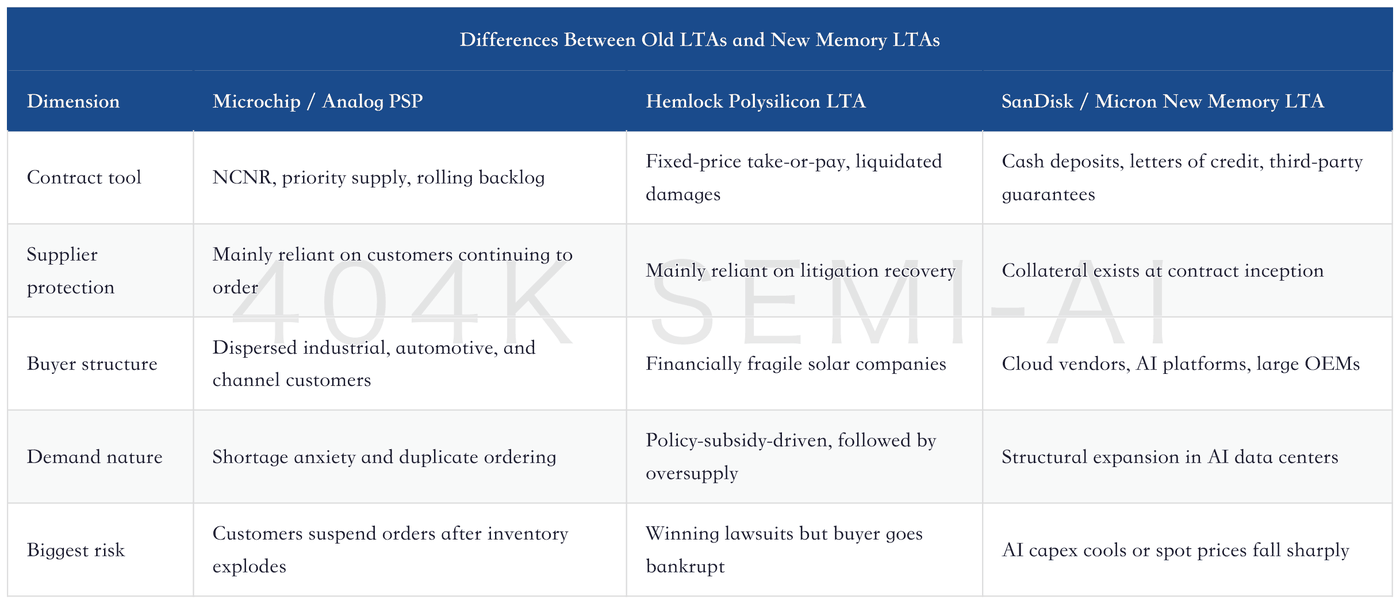
The investment implication behind this table is straightforward. The new memory LTAs push memory one step away from being a pure spot-cycle stock and toward medium- to long-term supply contracts backed by collateral. Valuations can rise, but the degree of uplift depends on collateral coverage and demand durability, not just the headline of a contract.
2. Microchip Case Study: Loose Orders Cannot Stop an Inventory Collapse
The lesson from Microchip is that if customer commitments carry no cash cost, they look like orders in a bull market but can easily become delay requests in a bear market.
During the 2020-2022 shortage in analog chips and MCUs, customers signed large numbers of long-term plans to secure supply. Microchip launched its Preferred Supply Program, under which customers used long-term orders to obtain priority capacity. Similar structures appeared in NCNR orders at analog suppliers such as Analog Devices. On the surface, suppliers had locked in future demand. In practice, customers had not paid enough deposits upfront and did not bear enough default cost.
The problem was the source of demand. During the analog and MCU shortage, many customer orders came from shortage anxiety rather than faster end-market sell-through, leading to early orders, duplicate orders, and inventory hoarding. These orders were naturally prone to reversal. Once consumer electronics, industrial, and automotive demand slowed, customers had both inventory on hand and insufficient capacity on their balance sheets to keep taking deliveries. If suppliers forced shipments, they would damage the channel. If they allowed delays, the LTAs lost their protective force.
Microchip later chose to ship less, and Analog Devices also kept the channel cleaner. This was commercially rational, but it proved the contracts lacked teeth. The report notes that Microchip’s net sales fell more than 42% year over year in Q3 FY25 at the peak of the inventory correction. The magnitude shows that suppliers acknowledged old orders could not be discounted as real end demand.
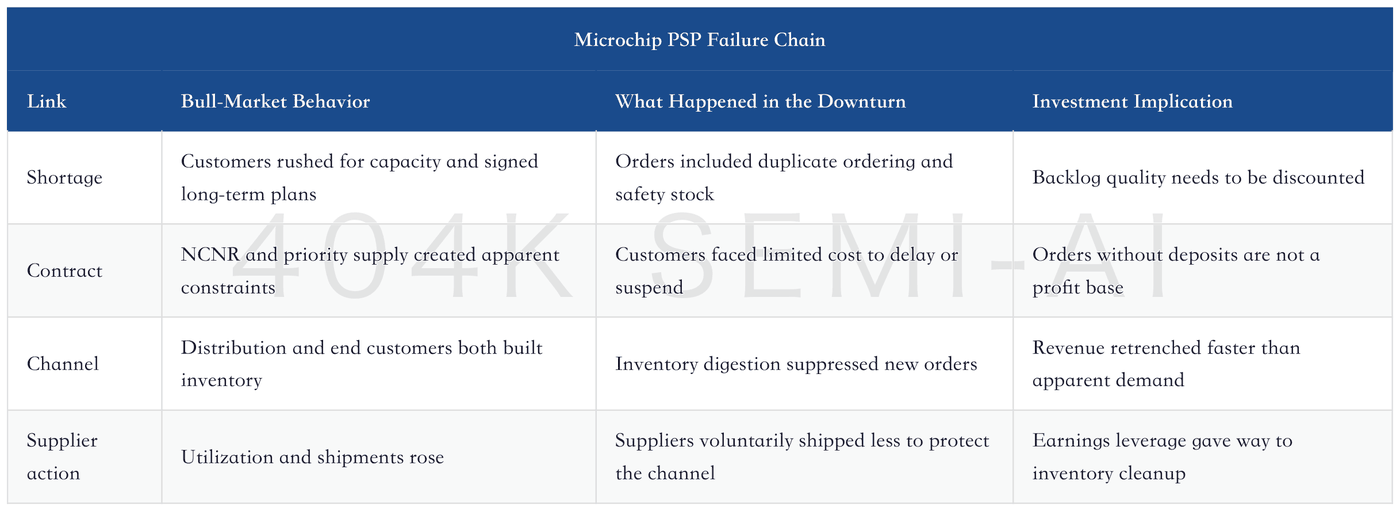
This case is the most relevant warning for memory today. Looking only at how many years customers signed for and how much volume they committed to buy is incomplete. Investors must keep asking: how much money has the customer already posted, where is the capital held, how are remaining performance obligations and guarantee ratios changing, and can the supplier access cash first if the customer defaults? If these questions cannot be answered, the contract looks more like an old semiconductor order than a profit base.
AI Drives an Industry-Wide Memory Rerating: Who Has the Most Pricing Power Across DRAM, NAND, SSD, and HDD, as Samsung, SK Hynix, SanDisk, Western Digital, and Seagate Earnings Cross-Validate the Thesis
III. Hemlock Case Study: Hard Law, Difficult Cash Recovery
The Hemlock case offers another extreme: contracts can be very hard, but once the buyer goes bankrupt, even a legal victory can turn into a low-quality asset.
In the late 2000s, solar subsidies drove polysilicon demand, and Hemlock signed long-term take-or-pay contracts with solar customers. Customers locked in supply at fixed prices, and suppliers appeared to have secured stronger protection. Later, polysilicon prices fell from more than $400/kg to below $15/kg, while many buyers were still locked into contract prices around $40-60/kg. For these solar companies, continued performance directly impaired their ability to survive.
The harder the contract, the more violent the cracks. Buyers were no longer merely delaying orders; they entered arbitration, litigation, restructuring, and bankruptcy. SolarWorld Sachsen was ordered to pay roughly $800 million in damages, but the company was already insolvent, weakening cash recovery. Kyocera paid roughly $450 million in 2018 to settle and exit its remaining commitments. Hemlock’s contracts did have legal teeth, but the path to monetization was too slow, buyer balance sheets were too weak, and suppliers ultimately received cash recoveries diluted by time and bankruptcy.
Hemlock’s protection came too late. The supplier first suffered demand collapse and price collapse, then dragged buyers into court. By the time judgments arrived, buyers no longer had enough cash. This lesson is critical for new Memory LTAs: collateral must exist before default, not be pursued only after default.
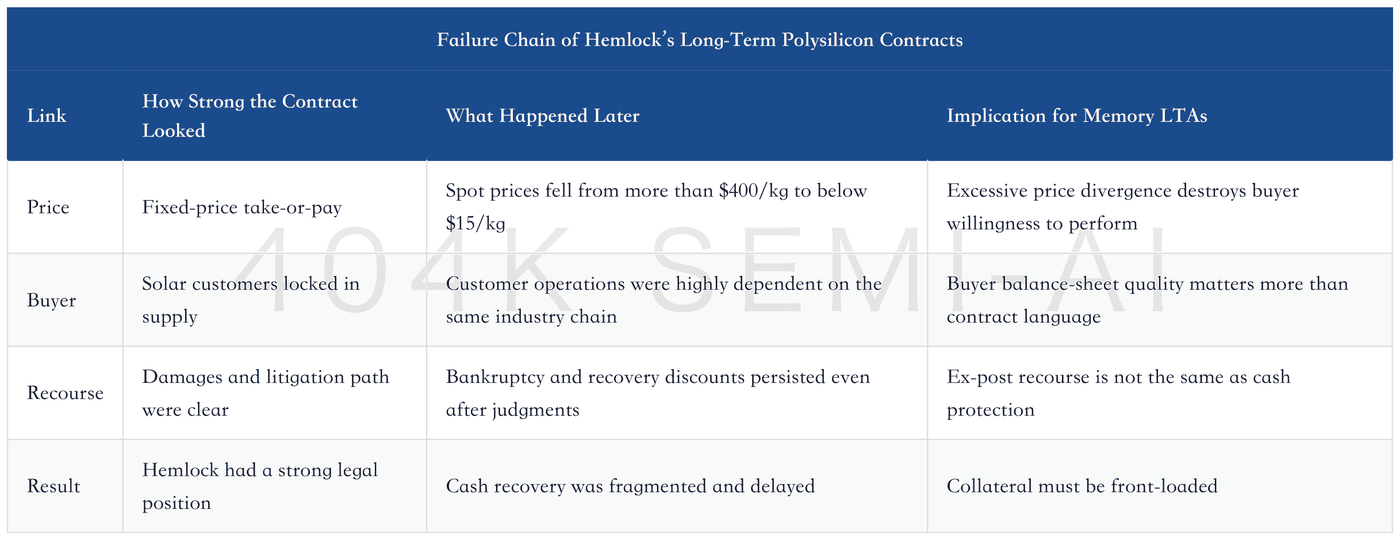
This is why the report views Hemlock as closer to the new Memory LTA structure. Hemlock at least had legal constraints, but lacked immediately accessible security and high-quality counterparties. For new memory contracts to work, they need two things Hemlock did not have: money locked up in advance, and buyers less likely to go bankrupt.
IV. First Layer of Protection in New Memory LTAs: Cash, Letters of Credit, and Third-Party Guarantees
The most important change in new memory long-term agreements is that contract protection has shifted from ex-post litigation to ex-ante collateral.
The disclosed numbers are substantial. Behind SanDisk’s roughly $69 billion of remaining performance obligations, there are more than $11 billion of guarantees, most of which are placed in structures similar to escrow or third-party balance sheets. Micron, meanwhile, has $18 billion of cash deposits and $4 billion of letters of credit. This structure means that if customers default, suppliers do not need to litigate for years first; they can draw on funds that already exist.
This is also different from ordinary prepayments. The report emphasizes that the security is back-end weighted. As contracts are performed year by year and remaining obligations decline, the coverage ratio of fixed or more slowly released security rises. The strongest protection comes in the later years, when the external cycle is more likely to weaken. This design directly targets the memory industry’s pain point: contracts do not need to be proven in bull markets; they are needed in bear markets.
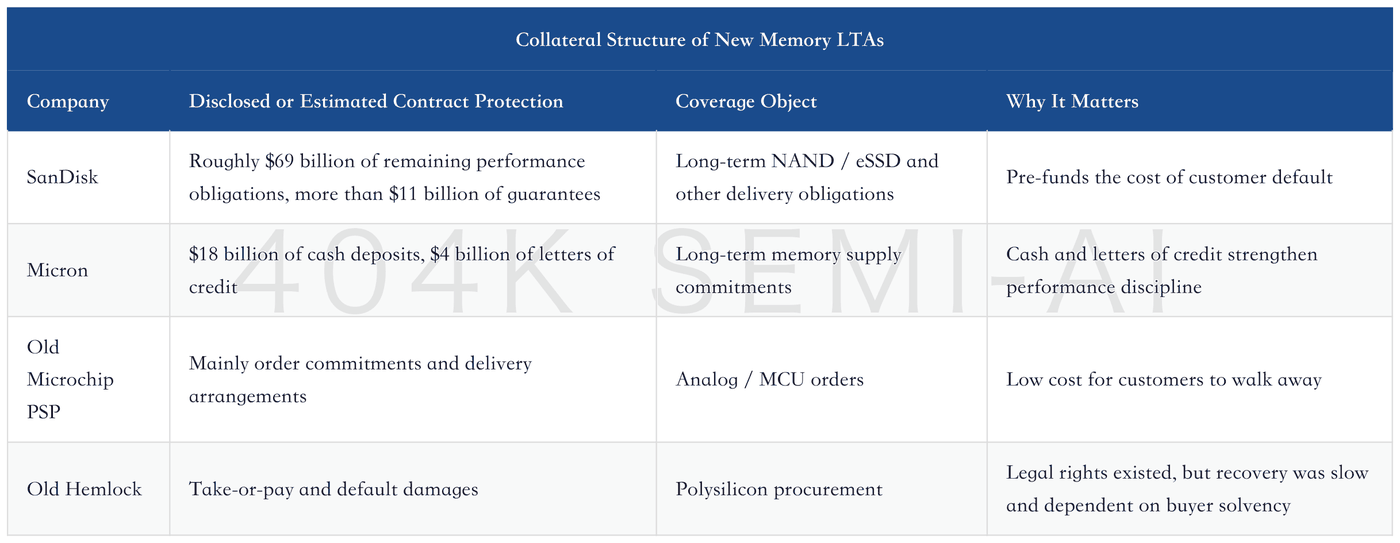
The investment question becomes more specific here. In the past, memory investors mainly watched bit supply, price elasticity, and inventory. Now they also need to watch contract-asset quality: whether guarantee coverage is rising, whether letters of credit truly exist, whether cash deposits are increasing quarter by quarter, and whether the release schedule is back-end weighted. As long as these data points continue to materialize, the market will be willing to reduce the cyclical discount.
Micron Earnings Deep Dive: Q3 Results Far Exceed Expectations, the AI Memory Supercycle Enters the Monetization Phase, How Much Profit Can LTAs Lock In?
V. Second Layer of Protection: This Time the Buyers Are Cloud Providers, Not Fragile Small and Mid-Sized Customers
Whether a contract has value ultimately depends on whether the buyer has money, how much it needs the goods, and how large the loss would be after default.
Microchip faced a large number of industrial, automotive, distribution, and small and mid-sized customers. Customers were fragmented, and it was difficult to pursue individual defaults or delays one by one. Hemlock faced buyers in the solar industry chain, many of whose revenue and gross margins were highly dependent on polysilicon prices. Once spot prices collapsed, continuing to perform at high prices threatened their survival. The common feature of the two old cases was unstable buyer quality.
The buyer profile for new Memory LTAs is clearly different. The report judges that memory LTAs are likely concentrated among a small number of cloud providers, AI platforms, and large OEMs. These buyers have diversified revenue from cloud computing, advertising, software, enterprise services, and other businesses. Memory costs are only one part of AI infrastructure, not a single commodity input that determines corporate survival. Their balance sheets, credit quality, and need for supply continuity are all stronger than those of solar buyers and fragmented industrial customers in the past.
This changes the default game. For cloud providers, missing a batch of high-end memory could affect model training, inference services, customer delivery, and future supplier relationships. Default would also forfeit pledged funds. As long as AI competition remains intense, continued performance is usually more rational than giving up supply. Suppliers therefore do not have to face a huge number of small customers as Microchip did, nor do they have to chase cash only after buyer bankruptcy as Hemlock did.
But strong buyers do not mean zero risk. Cloud providers can also cut capex, delay projects, and push for lower prices. LTAs protect against downside from default and price collapse; they do not guarantee that cloud providers will always expand at the current pace. Valuations should receive a premium, but LTAs should not be treated as risk-free bonds.
VI. Third Layer of Protection: AI Memory Demand Looks More Like a Capacity Bottleneck Than Analog Restocking
The nature of demand determines whether a contract is commercially rational. Demand for Microchip’s analog chips was overestimated during the shortage because customers were buying safety stock. Current AI memory demand is closer to a system-capability bottleneck, because model training and inference depend on capacity, bandwidth, and data residency.
Analog chips have a clear ceiling. Cars, industrial equipment, and home appliances require a certain number of MCUs, analog chips, power chips, and sensors. Once that need is met, buying more does not improve end-product capability. During shortages, customers can place extra orders; once supply recovers, orders fall back. This is the root cause of the Microchip PSP failure: the contracts locked in pulled-forward inventory, not continuously expanding end demand.
The AI memory demand curve is steeper. HBM determines bandwidth for accelerator training and inference. DRAM determines server memory capacity and concurrency. NAND and eSSD support data lakes, KV cache, vector databases, model datasets, and inference cache. Larger memory and storage capacity can support longer context, higher throughput, greater concurrency, and more complex models. As long as cloud providers are still competing on model capability and application latency, memory is not merely a cost item; it is part of product capability.
