
Memory Interface Chip Deep-Dive Update: Why Rambus Still Struggles to Catch Montage Technology in a $20 Billion TAM
目录
TL;DR
I. What Is New in This Report: Strong Industry Beta Does Not Mean Identical Company Alpha
II. Where the $20 Billion TAM Comes From: Three Multipliers, Not One Optimistic Penetration Assumption
III. Specifications Only Determine Eligibility; Joint Customer Validation Determines Market Share
IV. Rambus’s Three Businesses: One High-Growth Engine and Two Stabilizers
V. AI ASIC Is a Large Market, but Rambus May Not Occupy the Strongest Position in the Value Chain
VI. R&D Spending Is Not Inherently Negative, but Revenue Conversion Efficiency Determines Profit Sensitivity
VII. Implications for Montage Technology: Focus Is Both Its Advantage and Its Vulnerability
VIII. Conclusion: The Fastest-Growing Market Does Not Necessarily Produce Companies Growing at the Same Rate
Key References
本内容基于公开资料和研报数据整理,不构成任何投资建议,不代表任何个人观点,仅供学习参考,请理性阅读
A market of approximately $20 billion will benefit all three leaders, but a company’s growth depends not only on how fast the market expands, but also on market share, revenue mix, and R&D; efficiency.
TL;DR
Bernstein has raised its estimate for the global memory interface chip market in 2030 to nearly $20 billion, implying a CAGR of approximately 65% from 2025 to 2030. This new report further explains the differences among companies: despite operating in the same market, why may Rambus still lag Montage Technology in revenue and profit growth?
Rambus is not behind in products. It has built complete chipsets for RDIMM and MRDIMM and is currently the sole supplier of SOCAMM2 interface chips. Bernstein also expects its share of the MRDIMM interface chip market to increase from approximately 2% in 2026 to approximately 18% in 2030. DRAM vendors control module qualification, and long-standing co-development relationships and dual-sourcing preferences have a greater influence on ultimate market share than any individual specification.
Rambus generated $708 million in revenue in 2025, with product revenue accounting for approximately 49% and growing 40.9%. However, DRAM royalties and compute-chip IP still represented nearly 50% combined. The former is constrained by long-term contracts and royalty caps, while the latter competes against integrated ASIC design providers such as Broadcom and Marvell, as well as the ecosystem bundling of Cadence and Synopsys, making it difficult to replicate the rapid growth of memory interface chips across these businesses.
Rambus and Montage Technology had similar revenue in 2025, at approximately $708 million and $759 million, respectively. However, their R&D; expenses were approximately $188 million and $127 million, respectively, equivalent to R&D; expense ratios of 27% and 17%. Rambus uses a higher cost base to support a more diversified technology portfolio, naturally resulting in slower operating leverage.
The upside for Montage Technology comes from its revenue being more concentrated in the increase in MRDIMM content value. Risks include weaker-than-expected MRDIMM penetration, erosion of its second-generation product share, or price competition preventing higher content value from translating into higher profit.
I. What Is New in This Report: Strong Industry Beta Does Not Mean Identical Company Alpha
In its previous industry primer, Bernstein had already explained the recovery in server CPUs, MRDIMM penetration, and rising content value per module. Based solely on these variables, Montage Technology, Renesas Electronics, and Rambus all appear very well positioned: the market is highly concentrated, demand is growing rapidly, and the three companies seemingly need only share an ever-expanding pie.
The July 27 competitive deep dive adds a second layer of analysis: how the pie will be divided and how much profit each company will retain. It selects Rambus as the primary case study because Rambus combines nearly every attractive narrative in this value chain within a single company: it sells memory interface chips, collects DRAM patent royalties, and licenses controller, interconnect, and security IP to compute-chip designers. In theory, it can benefit simultaneously from rising server CPU volumes, memory technology upgrades, and increasing AI ASIC penetration.
However, having more businesses does not necessarily mean growing faster. Rambus’s three businesses have entirely different customers, competitive dynamics, and profit models: the chip business relies on product iteration and module qualification; DRAM royalties depend on long-term agreements; and compute-chip IP depends on design wins and ecosystem positioning. Only the first business can capture the volume and pricing uplift from MRDIMM relatively directly, while the other two dilute company-level growth.
This is also central to understanding Montage Technology’s relative advantage. Montage Technology does not cover as broad a range of technologies as Rambus, but its revenue mix is more focused on interface chips, currently the fastest-growing segment. For a growth stock, being “narrow but deep” is not necessarily a disadvantage. When the industry’s primary growth curve is sufficiently steep, focus can instead mean greater revenue sensitivity and faster profit conversion.
II. Where the $20 Billion TAM Comes From: Three Multipliers, Not One Optimistic Penetration Assumption
Bernstein expects the global memory interface chip market to expand at a CAGR of approximately 65% from 2025 to 2030, reaching approximately $19.9 billion in 2030. The figure appears aggressive, but the model does not rely solely on MRDIMM penetration. Instead, it multiplies three variables that are rising simultaneously:
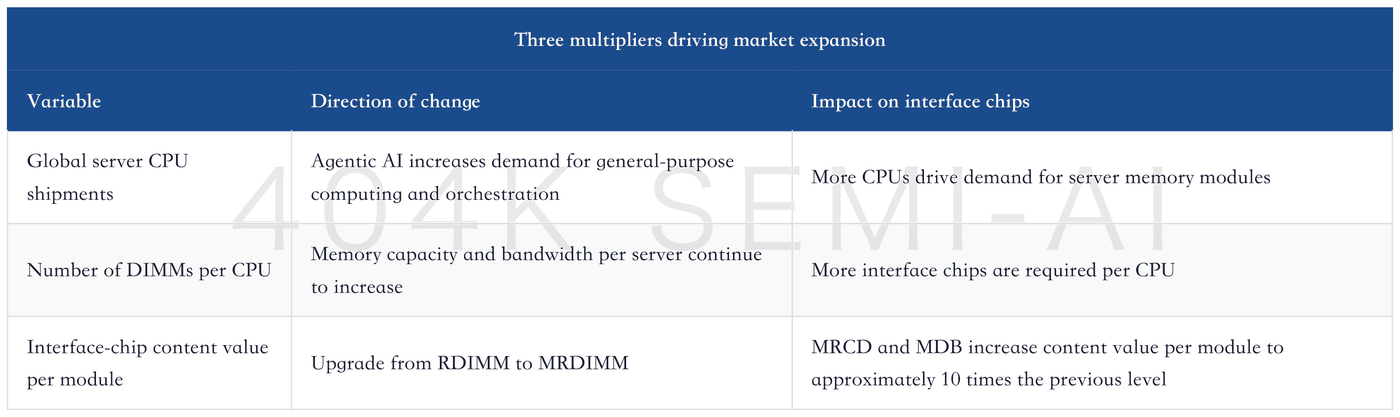
The third factor is what truly changes the slope of the revenue curve. RDIMM primarily relies on chips such as RCD and DB, while MRDIMM adds MRCD and MDB and moves more signal-processing functionality onto the module. Bernstein expects MRCD and MDB combined to contribute approximately 73% of the market’s value in 2030. The main growth over the next five years will come from a step change in interface-chip content value within each module.
The bearish scenario better illustrates the market floor. If server CPU shipments reach only 60 million units and MRDIMM penetration reaches only 10% in 2030, Bernstein still estimates a market of approximately $8 billion. This outcome does not prove that the $20 billion forecast will materialize, but it shows that even limited MRDIMM penetration could make the market significantly larger than prior long-term forecasts.
However, TAM is only the revenue ceiling, not a revenue commitment for any individual company. Market size is determined by “number of CPUs × modules per CPU × chip value per module,” while company revenue must additionally be multiplied by market share and pricing. Those latter two variables are precisely what the competitive-landscape report seeks to highlight for investors.
