
Memory Deep Dive Update: Morgan Stanley Says Buy Legacy Memory, Why DDR4, SLC NAND, and NOR Are Still Rising
目录
Too Long; Didn’t Read
1. What Really Changed in This Morgan Stanley Report
2. DDR4: Why Legacy DRAM Has Regained Pricing Power
3. SLC NAND: Why Enterprise HDDs Are Starting to Compete for Older NAND
4. NOR: Rubin Cabinets and Micron’s Exit Push Supply Toward Taiwanese Vendors
5. This “Legacy Memory” Cycle Is Not the Opposite of HBM, But HBM’s Shadow
VI. Risks and Monitoring: When Legacy Memory Shifts Back From Bottleneck to Cyclical Commodity
本内容基于公开资料和研报数据整理,不构成任何投资建议,不代表任何个人观点,仅供学习参考,请理性阅读
The real change in this Morgan Stanley report is not another round of memory price increases, but the return of DDR4, SLC NAND, and NOR, long overshadowed by HBM, to the center of pricing: enterprise customers are starting to scramble for legacy memory, while supply exits, low inventories, and higher content per AI rack are turning niche memory from a cyclical catch-up trade into a structural bottleneck.
Too Long; Didn’t Read
Legacy memory has become a bottleneck again. Morgan Stanley believes shortages in DDR4, SLC NAND, and NOR will last longer than expected, with enterprise customers now pulling in orders, not just consumer electronics restocking.
DDR4 is the strongest main line. Channel inventory is below two weeks, enterprise customers are worried about supply disruption, 3Q price assumptions have been raised, and Nanya Technology and Winbond Electronics are the most direct beneficiaries.
The NAND change is more enterprise-oriented. MLC shortages are forcing enterprise HDDs to shift toward high-density SLC NAND, with logic across SanDisk, Kioxia, and Macronix mutually reinforcing.
NOR pricing is driven by supply exits. Micron is reducing NOR supply, Rubin rack content is rising, and Morgan Stanley expects 3Q NOR prices to rise 30-40% and continue into 4Q.
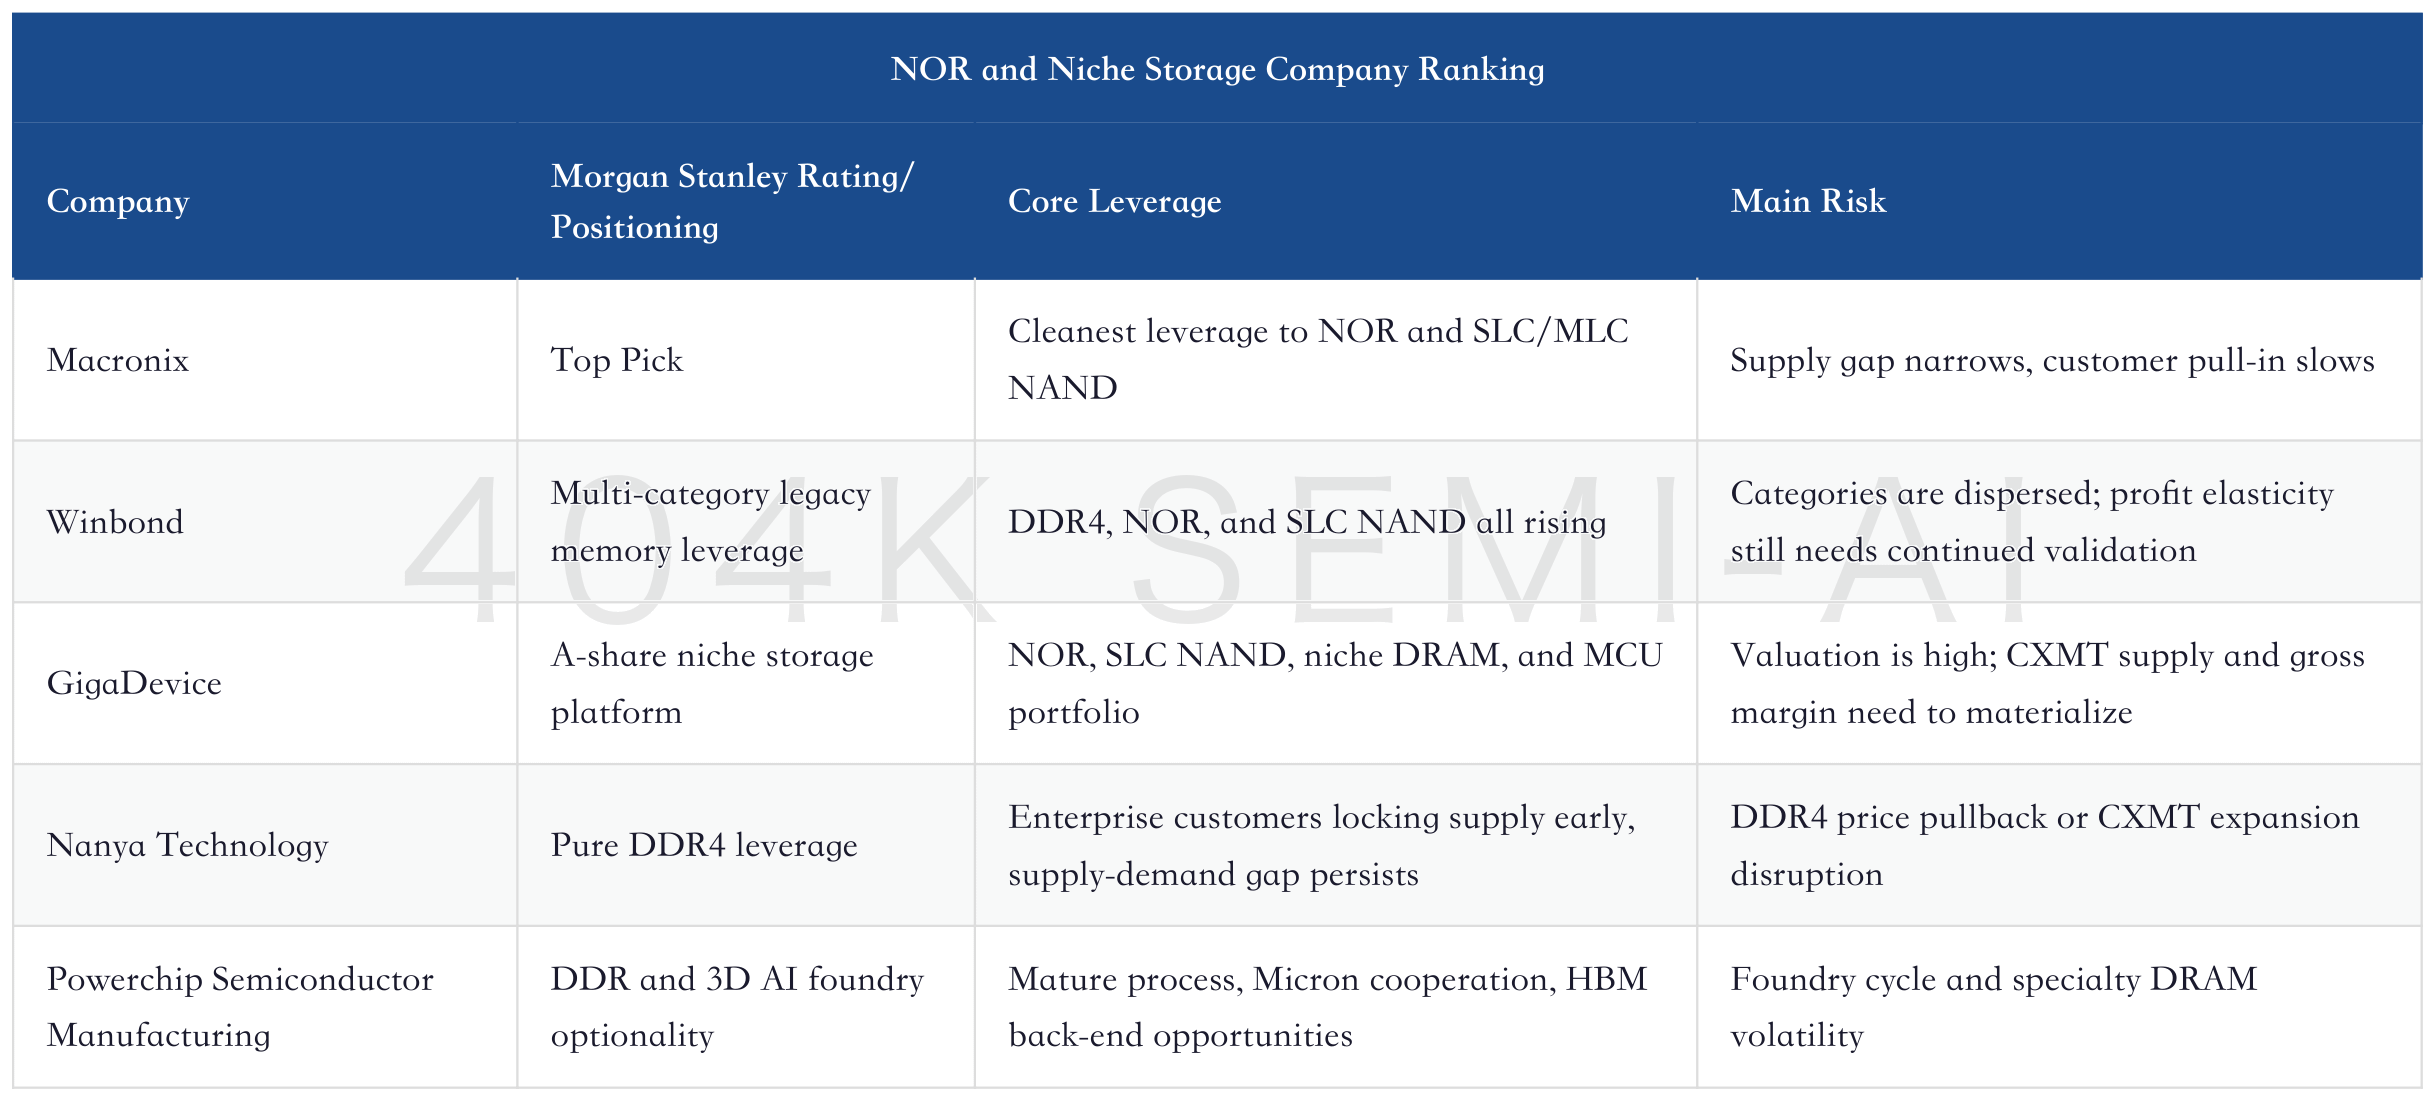
Company ranking depends on category exposure. Macronix is purer; Winbond benefits from DDR4/NOR/SLC; Nanya benefits from DDR4; GigaDevice benefits from a domestic niche memory platform.
This is not the opposite of HBM. AI is pushing major suppliers’ capacity toward HBM and advanced DRAM, which instead crowds out mature memory supply; legacy memory has become the shadow asset of HBM spillover.
The risks are supply and valuation. If prices loosen, customers slow pull-ins, CXMT/YMTC capacity ramps earlier, or AI server momentum slows, high-beta niche memory will be repriced first.
1. What Really Changed in This Morgan Stanley Report
The title of this Morgan Stanley report is “Old Memory: Better to buy more,” which captures the point the market most easily misses: it is not just HBM that is strong now; legacy memory is also being repriced. More precisely, DDR4, SLC/MLC NAND, and NOR flash, once seen as mature, low-growth, and easily replaceable, are becoming key variables in the new round of memory tightness because of supply exits and enterprise customer stockpiling.
Morgan Stanley uses a very direct phrase in the cover summary: Unexpected persistent tightness in legacy memory supply. This does not mean legacy memory has suddenly become high tech, but that AI has rewritten the supply-demand structure. Major manufacturers are directing more capacity, capex, and management attention toward HBM, DDR5, advanced nodes, and enterprise SSDs, crowding out mature categories; at the same time, enterprise customers, data-center HDDs, AI servers, Rubin racks, industrial applications, and automotive applications still need these legacy memory products.
Global Memory Deep Dive: 2Q26 Earnings Divergence, Can Better 3Q Pricing Restart the Memory Stock Re-rating?
The investment implication of this report is not simply that “memory prices are still rising,” but that the memory trade is spreading from HBM, DDR5, and eSSD to legacy memory. HBM is the visible bottleneck; legacy memory is the hidden bottleneck created by crowding out. The former is pulled directly by AI GPUs and ASICs; the latter sees profit leverage amplified by supply exits, panic buying from customers, and low inventories.
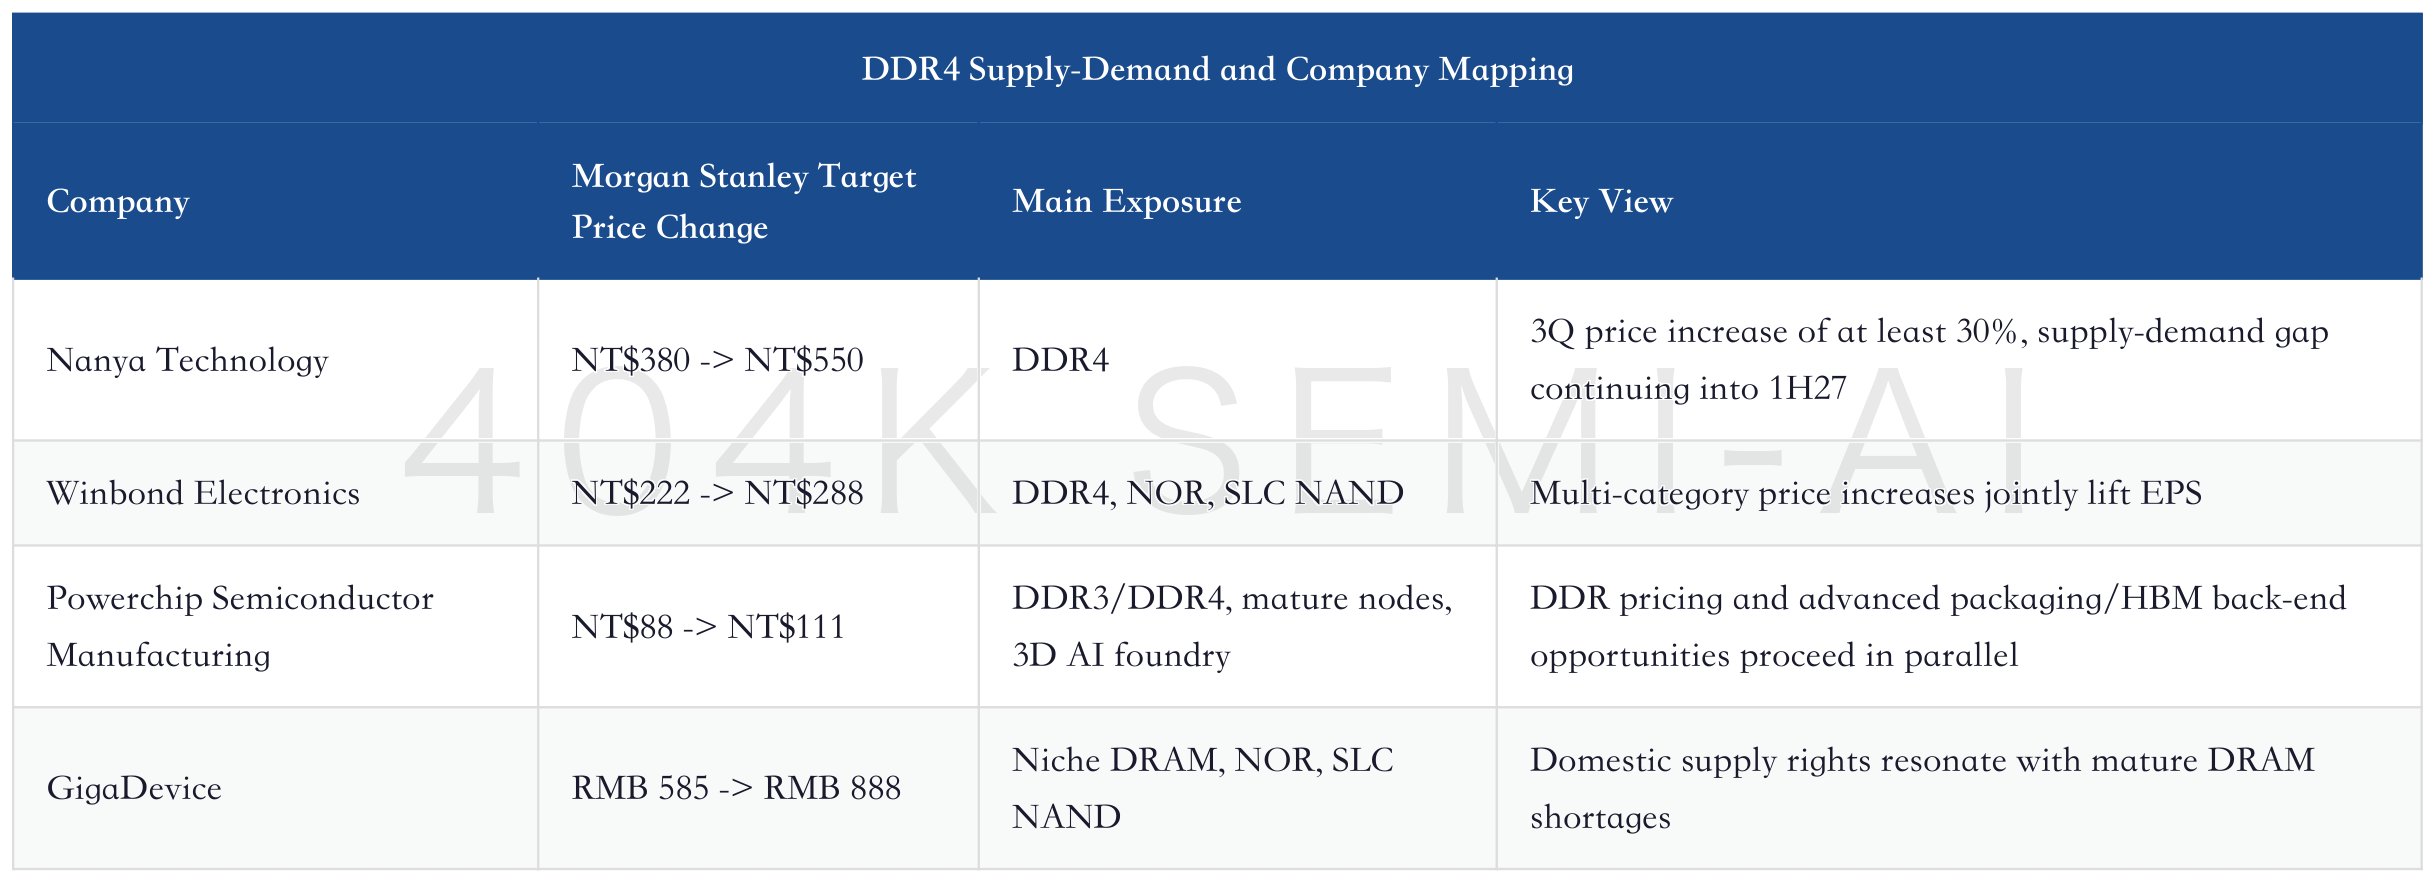
Morgan Stanley’s upward revisions to covered companies also illustrate this point. GigaDevice’s target price was raised from RMB 585 to RMB 888; Winbond Electronics from NT$222 to NT$288; Nanya Technology from NT$380 to NT$550; Macronix from NT$202 to NT$220; and Powerchip Semiconductor Manufacturing from NT$88 to NT$111. They are not the same kind of memory assets, but they all benefit from tighter mature memory supply.
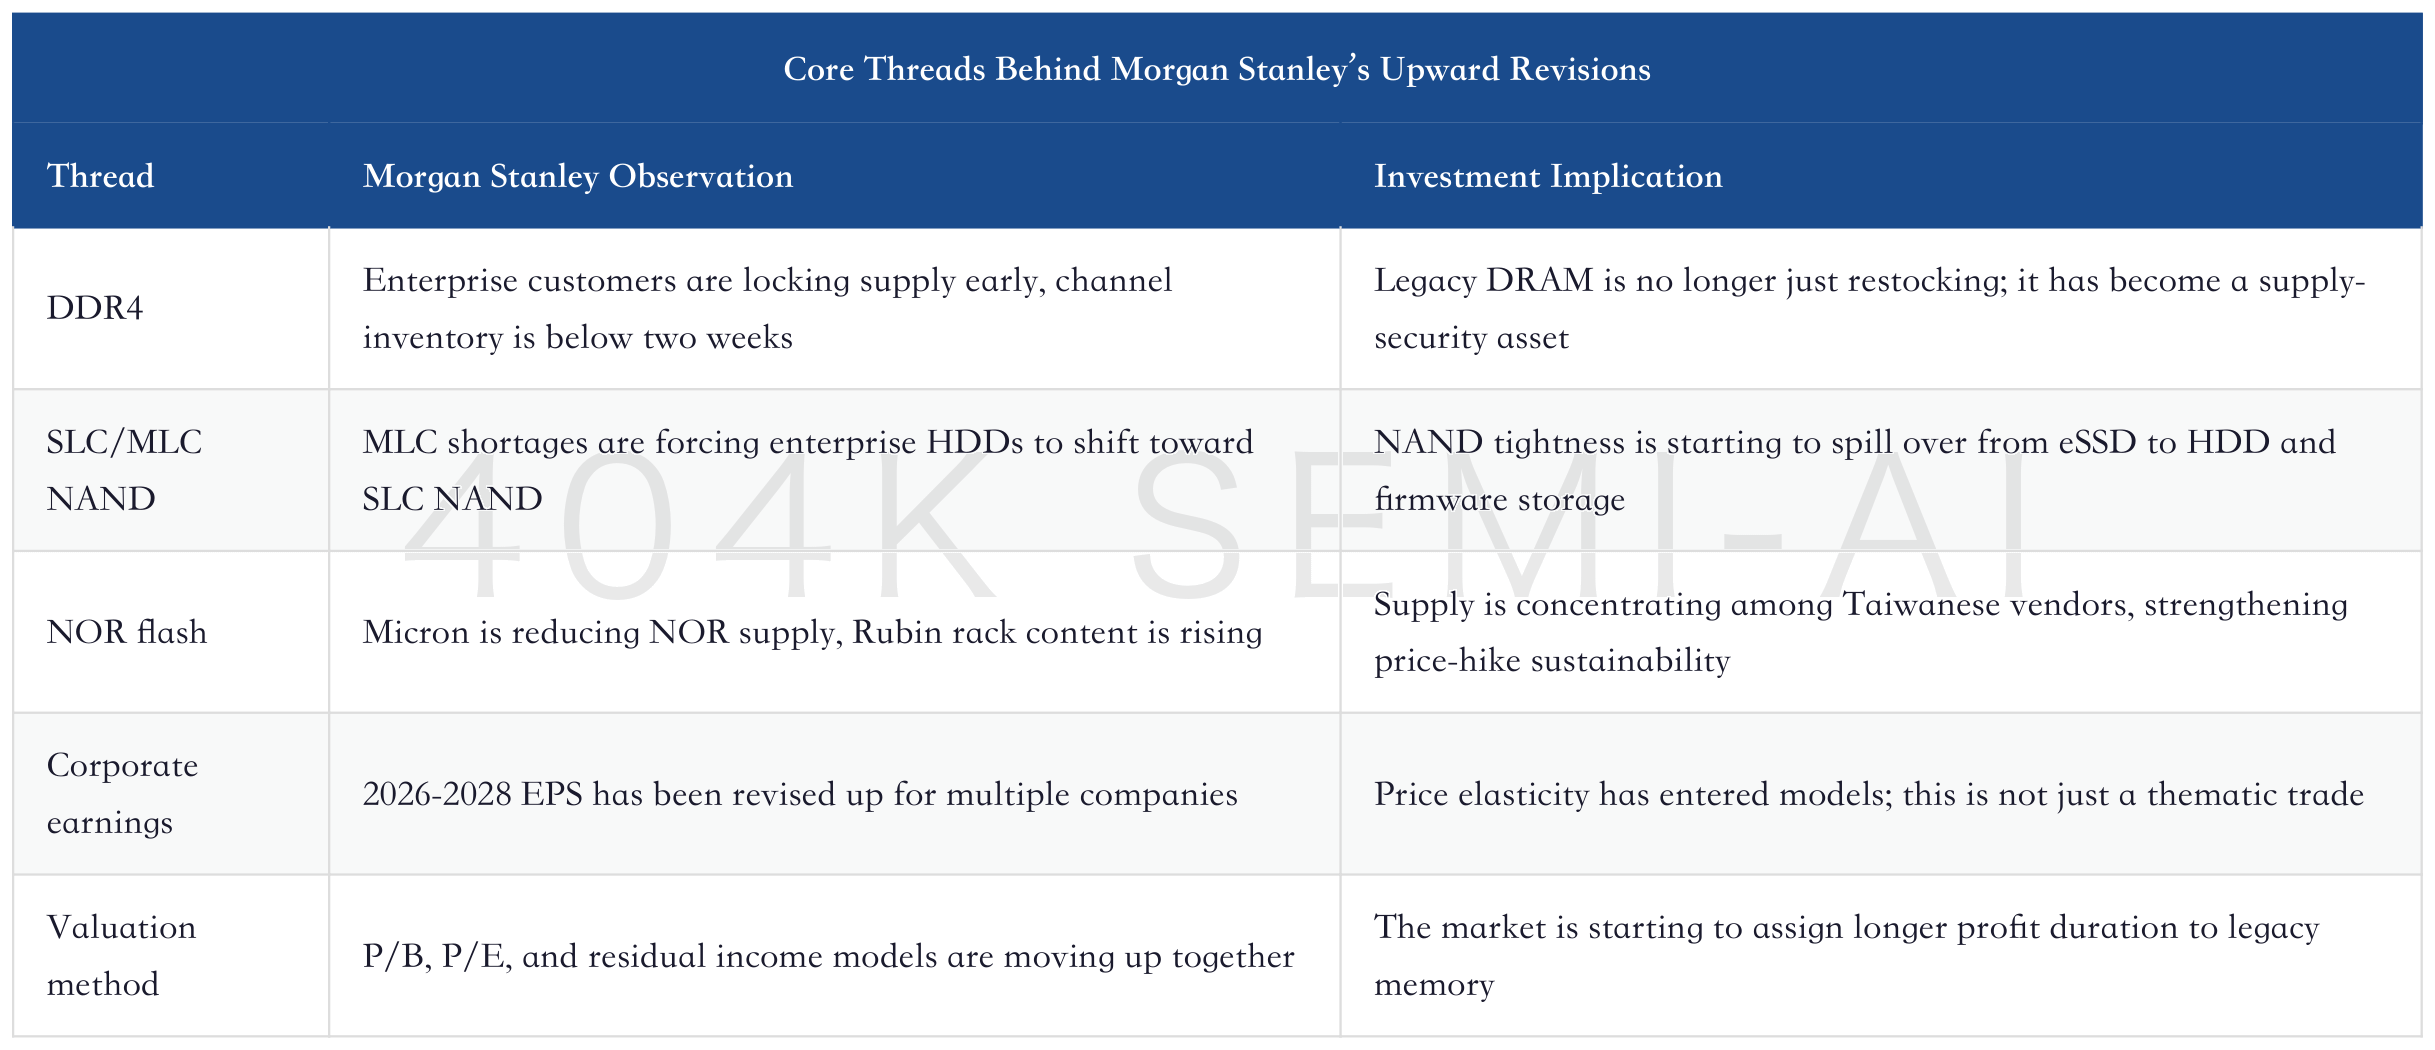
2. DDR4: Why Legacy DRAM Has Regained Pricing Power
DDR4 is the strongest main line in this report. Morgan Stanley believes enterprise customers are locking in supply as early as possible because they fear sustained shortages; channel inventory remains below two weeks, meaning customers have little buffer. DDR4 has already posted double-digit monthly price increases, and Morgan Stanley believes price increases will continue into 4Q.
This is different from a traditional DDR4 restocking cycle. In the past, when DDR4 prices rose, the market usually attributed it to inventory recovery in PCs, smartphones, and consumer electronics. This time, the backdrop is that global DRAM majors continue to push resources toward HBM, DDR5, and AI-server-related products, crowding out mature DDR4 supply. Demand has not disappeared: enterprise customers, industrial, consumer electronics, networking equipment, server peripherals, and local customers still need stable supply.
The Memory Tax Arrives: How AI Is Turning HBM, DRAM, and NAND into a Global Macro Bottleneck
Nanya Technology is the most direct DDR4 beta asset. Morgan Stanley raised Nanya Technology’s target price from NT$380 to NT$550 and lifted 2026/2027/2028 EPS by 7%/15%/14%, respectively. More important is the pricing assumption: the 3Q DDR4 price increase was raised from the previous 20% to at least 30%, with the supply-demand gap unlikely to fully close before 1H27.
Winbond Electronics also benefits from DDR4, but it is not a pure DDR4 company. Morgan Stanley raised Winbond Electronics’ target price from NT$222 to NT$288 and lifted 2026/2027/2028 EPS by 4%/17%/24%, respectively, citing stronger-than-expected pricing across DDR4, NOR flash, and SLC NAND. Winbond’s advantage is more diversified categories; its disadvantage is that valuation must explain volatility across multiple mature memory categories at the same time.
The key to the DDR4 line is not how advanced it is, but that its supply elasticity is declining. As long as major manufacturers keep advanced capacity reserved for HBM and DDR5, new DDR4 supply will not be released as quickly as in the past. Low customer inventories, early orders, and stable long-tail demand are enough to give legacy DRAM pricing power for a period of time.
3. SLC NAND: Why Enterprise HDDs Are Starting to Compete for Older NAND
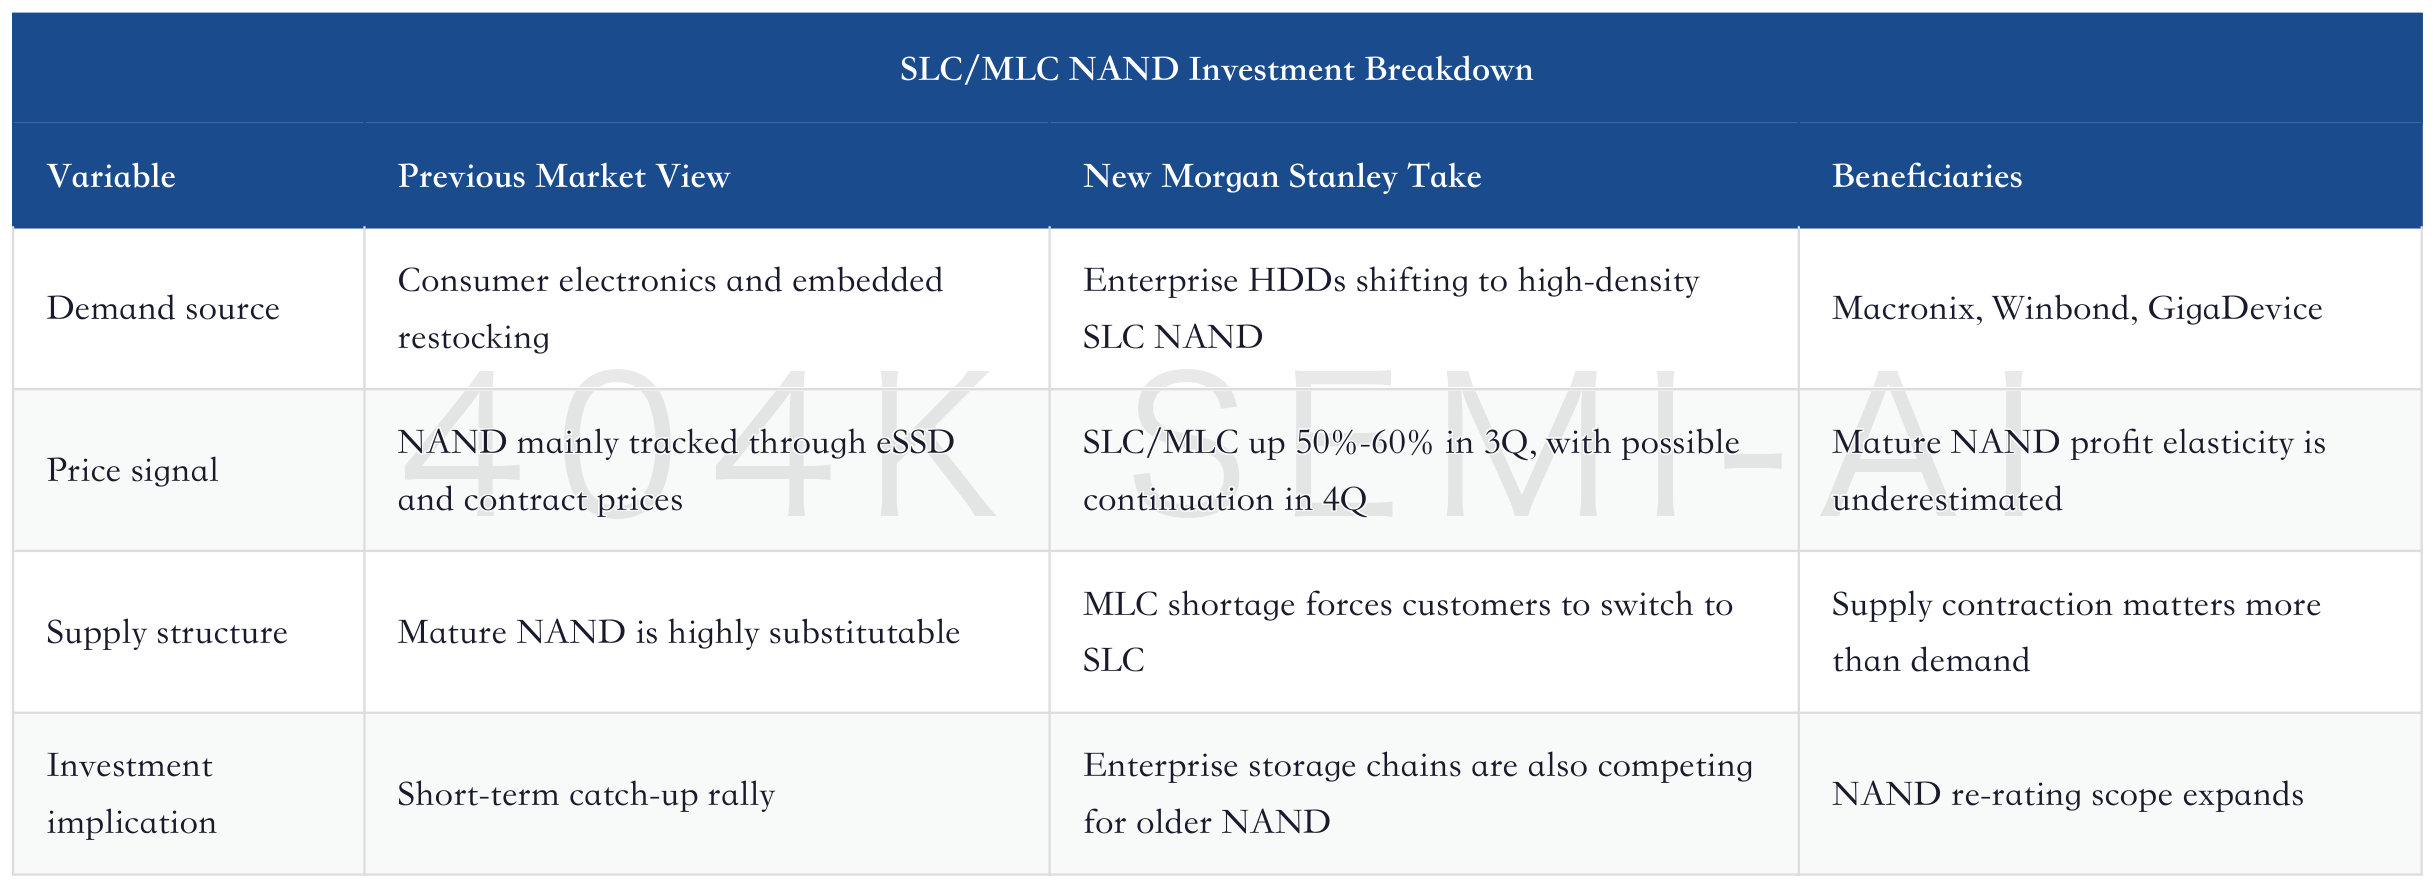
The NAND thread is more interesting. The market is familiar with eSSD, NAND contract prices, and the AI inference data layer, but Morgan Stanley focuses here on enterprise HDD demand for SLC NAND. The report notes that MLC NAND shortages are forcing enterprise HDDs to shift to high-density SLC NAND for firmware, hot data, and defect mapping. The original line can be compressed into one signal: forcing enterprise HDDs to use SLC NAND.
The logic is that enterprise storage is not only SSDs. AI inference, enterprise data lakes, backup, cold data, video, and logs still rely heavily on HDDs; but enterprise HDDs also need NAND internally to store firmware, mapping tables, and hot data. If MLC supply is insufficient, enterprise HDDs will compete for high-density SLC NAND. This would allow mature NAND tightness to spread from eSSD into the HDD supply chain.
SanDisk Deep-Dive Update: Citi Raises Target Price to US$2,500, NAND Shortage Cycle Extends Beyond CY27
Morgan Stanley believes SLC/MLC NAND price elasticity could likely continue into 4Q. Macronix has the cleanest leverage on this line because it is exposed to both the SLC/MLC NAND and NOR supply gaps, and the report names it as a Top Pick.
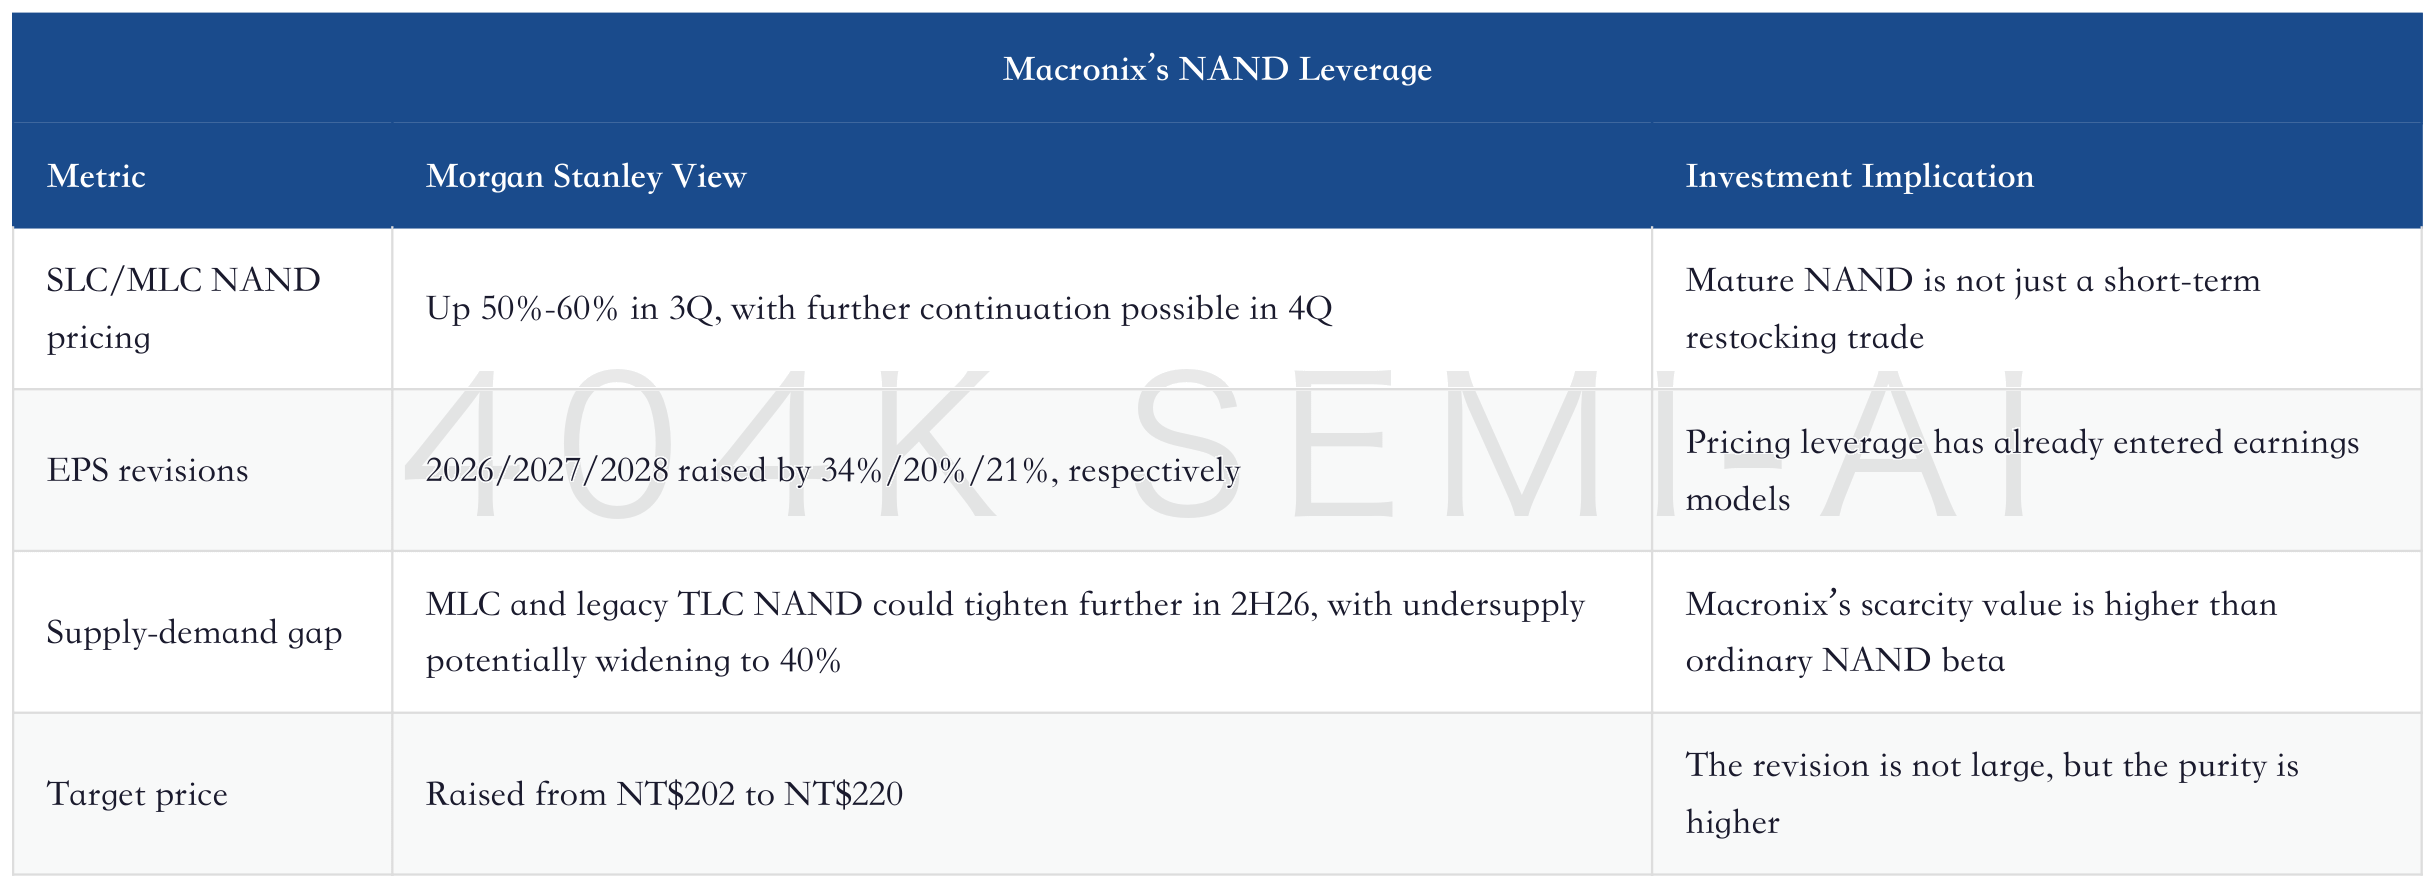
This is also why NAND can no longer be understood only as consumer-electronics restocking. SanDisk, Kioxia, Samsung, SK hynix, Micron, and Macronix sit at different layers: some benefit from enterprise SSD, some from NAND contract prices, some from mature NAND shortages, and some from controllers and the enterprise HDD chain. NAND pricing power is spreading from “data-center SSD” into lower-level storage media.
4. NOR: Rubin Cabinets and Micron’s Exit Push Supply Toward Taiwanese Vendors
NOR flash is the third key thread in this report. Morgan Stanley believes NOR price increases are being led by Macronix, behind which lies supply shifting from NOR to NAND, as well as Micron reducing NOR supply in 2H and reallocating capacity to DRAM and NAND. Meanwhile, after Vera Rubin cabinets ramp in 2H, NOR content will be more than 50% higher than in Grace Blackwell cabinets. Morgan Stanley therefore expects NOR prices to rise 30%-40% in 3Q and continue into 4Q.
This is not a short-term price increase in a small category. NOR has a smaller market size than DRAM/NAND, but its customers are more fragmented, qualification cycles are longer, and product life cycles are more stable. Automotive, industrial, servers, optical modules, networking, AI servers, and edge devices all need NOR to store code, firmware, and boot information. When suppliers exit and customers still need assured supply, price elasticity can be very direct.
GigaDevice Deep Dive: AI Pushes Major Vendors Toward HBM; Who Captures Supply Power in Niche DRAM?
GigaDevice’s logic on this line is more complex. Morgan Stanley raised its target price for GigaDevice from RMB585 to RMB888 and raised 2026/2027/2028 EPS by 30%/46%/53%, respectively. This is not simply because NOR prices are rising. It is because DDR4, NOR flash, and SLC NAND are all stronger than expected, layered on top of domestic niche DRAM supply power, MCU, and edge AI storage platforms. Morgan Stanley’s residual income model target price implies 53x 2026 P/E, above the historical average, indicating a higher premium for a “domestic niche storage platform.”
The core issue in NOR is supply concentration. If Micron reduces NOR supply, global supply will become more dependent on Macronix, Winbond, GigaDevice, and others. Taiwanese vendors therefore gain stronger pricing power, while GigaDevice becomes the main A-share proxy for tight mature-memory supply. This logic does not conflict with HBM; rather, it is the chain reaction after HBM crowds out mature capacity.
5. This “Legacy Memory” Cycle Is Not the Opposite of HBM, But HBM’s Shadow
The market tends to split memory into two categories: HBM as advanced assets, and legacy memory as cyclicals. This classification is technically right, but insufficient for investment purposes. The stronger HBM becomes, the more it absorbs advanced DRAM capacity, capex, and supplier resources. The more major vendors chase HBM, DDR5, and eSSD, the easier it is for mature DDR4, SLC NAND, and NOR supply to be crowded out. Legacy memory is not the opposite of HBM; it is the shadow asset created by HBM-driven resource reallocation.
Micron Earnings Deep Dive: Q3 Results Beat Expectations Sharply, AI Memory Supercycle Enters Monetization Phase; How Much Profit Can LTAs Lock In?
This is also why this Morgan Stanley report can corroborate recent reports on Micron, SanDisk, and global memory. Micron proves that AI memory LTAs and structural tightness in HBM/DRAM are still being monetized. SanDisk proves that NAND shortages may extend beyond CY27. The global memory report proves that 3Q pricing improvement is spreading from HBM to commodity DRAM and NAND. This Morgan Stanley report fills in the final piece of the puzzle: mature DDR4, SLC NAND, and NOR are also being pulled in early by customers.
If the memory cycle is split into three layers, the first layer is HBM and AI DRAM, which most directly benefit from GPU/ASIC. The second layer is commodity DRAM and enterprise SSD, which most directly enter the income statement. The third layer is legacy memory, including DDR4, SLC/MLC NAND, and NOR. This layer historically had the lowest valuation, but when supply is hardest to replenish and customer inventory is lowest, its near-term elasticity can instead be the greatest.
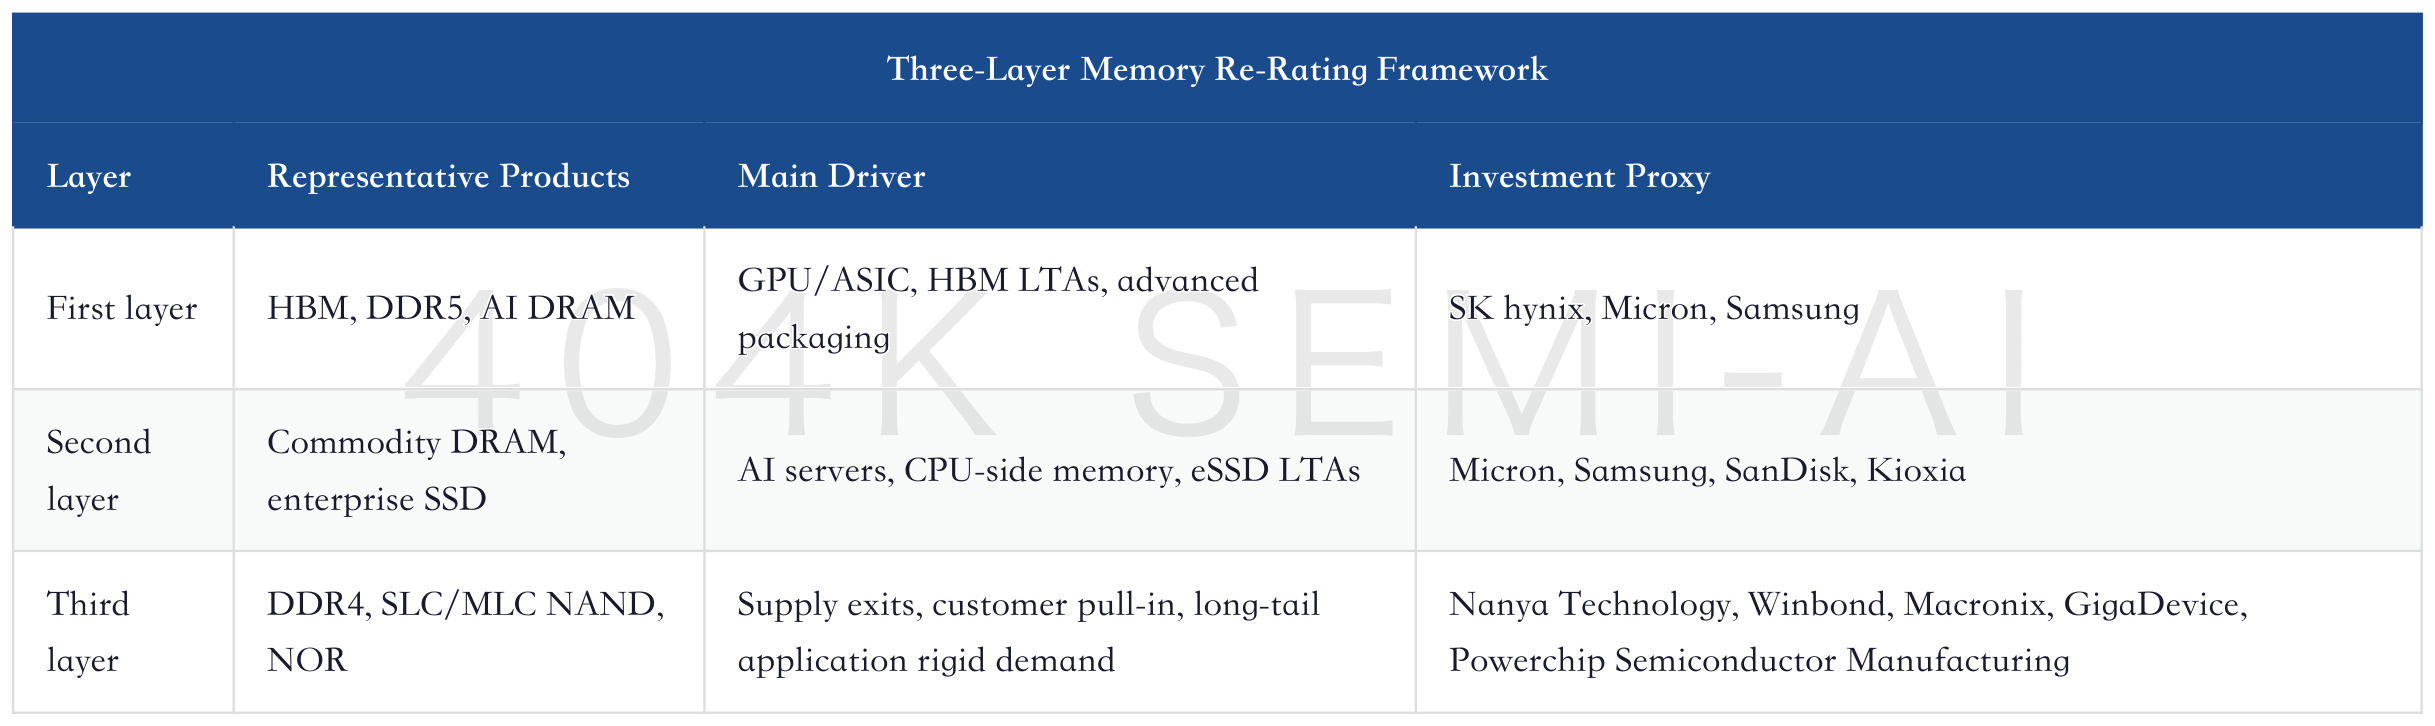
The investment implication of this framework is straightforward: do not only buy the highest-end memory, and do not treat legacy memory as low-quality beta. High-end memory determines the industry direction, while legacy memory determines the near-term earnings slope. If AI continues to occupy major vendors’ resources, legacy memory shortages could last longer than the market expects.
VI. Risks and Monitoring: When Legacy Memory Shifts Back From Bottleneck to Cyclical Commodity
The biggest risk to the legacy-memory trade is that the market extrapolates the supply gap for too long. DDR4, SLC NAND, and NOR are not permanently scarce assets. If prices rise high enough, customers will delay procurement, seek substitutes, and optimize inventory, while suppliers will also reallocate capacity. Niche memory has strong upside elasticity, but drawdowns can also come faster.
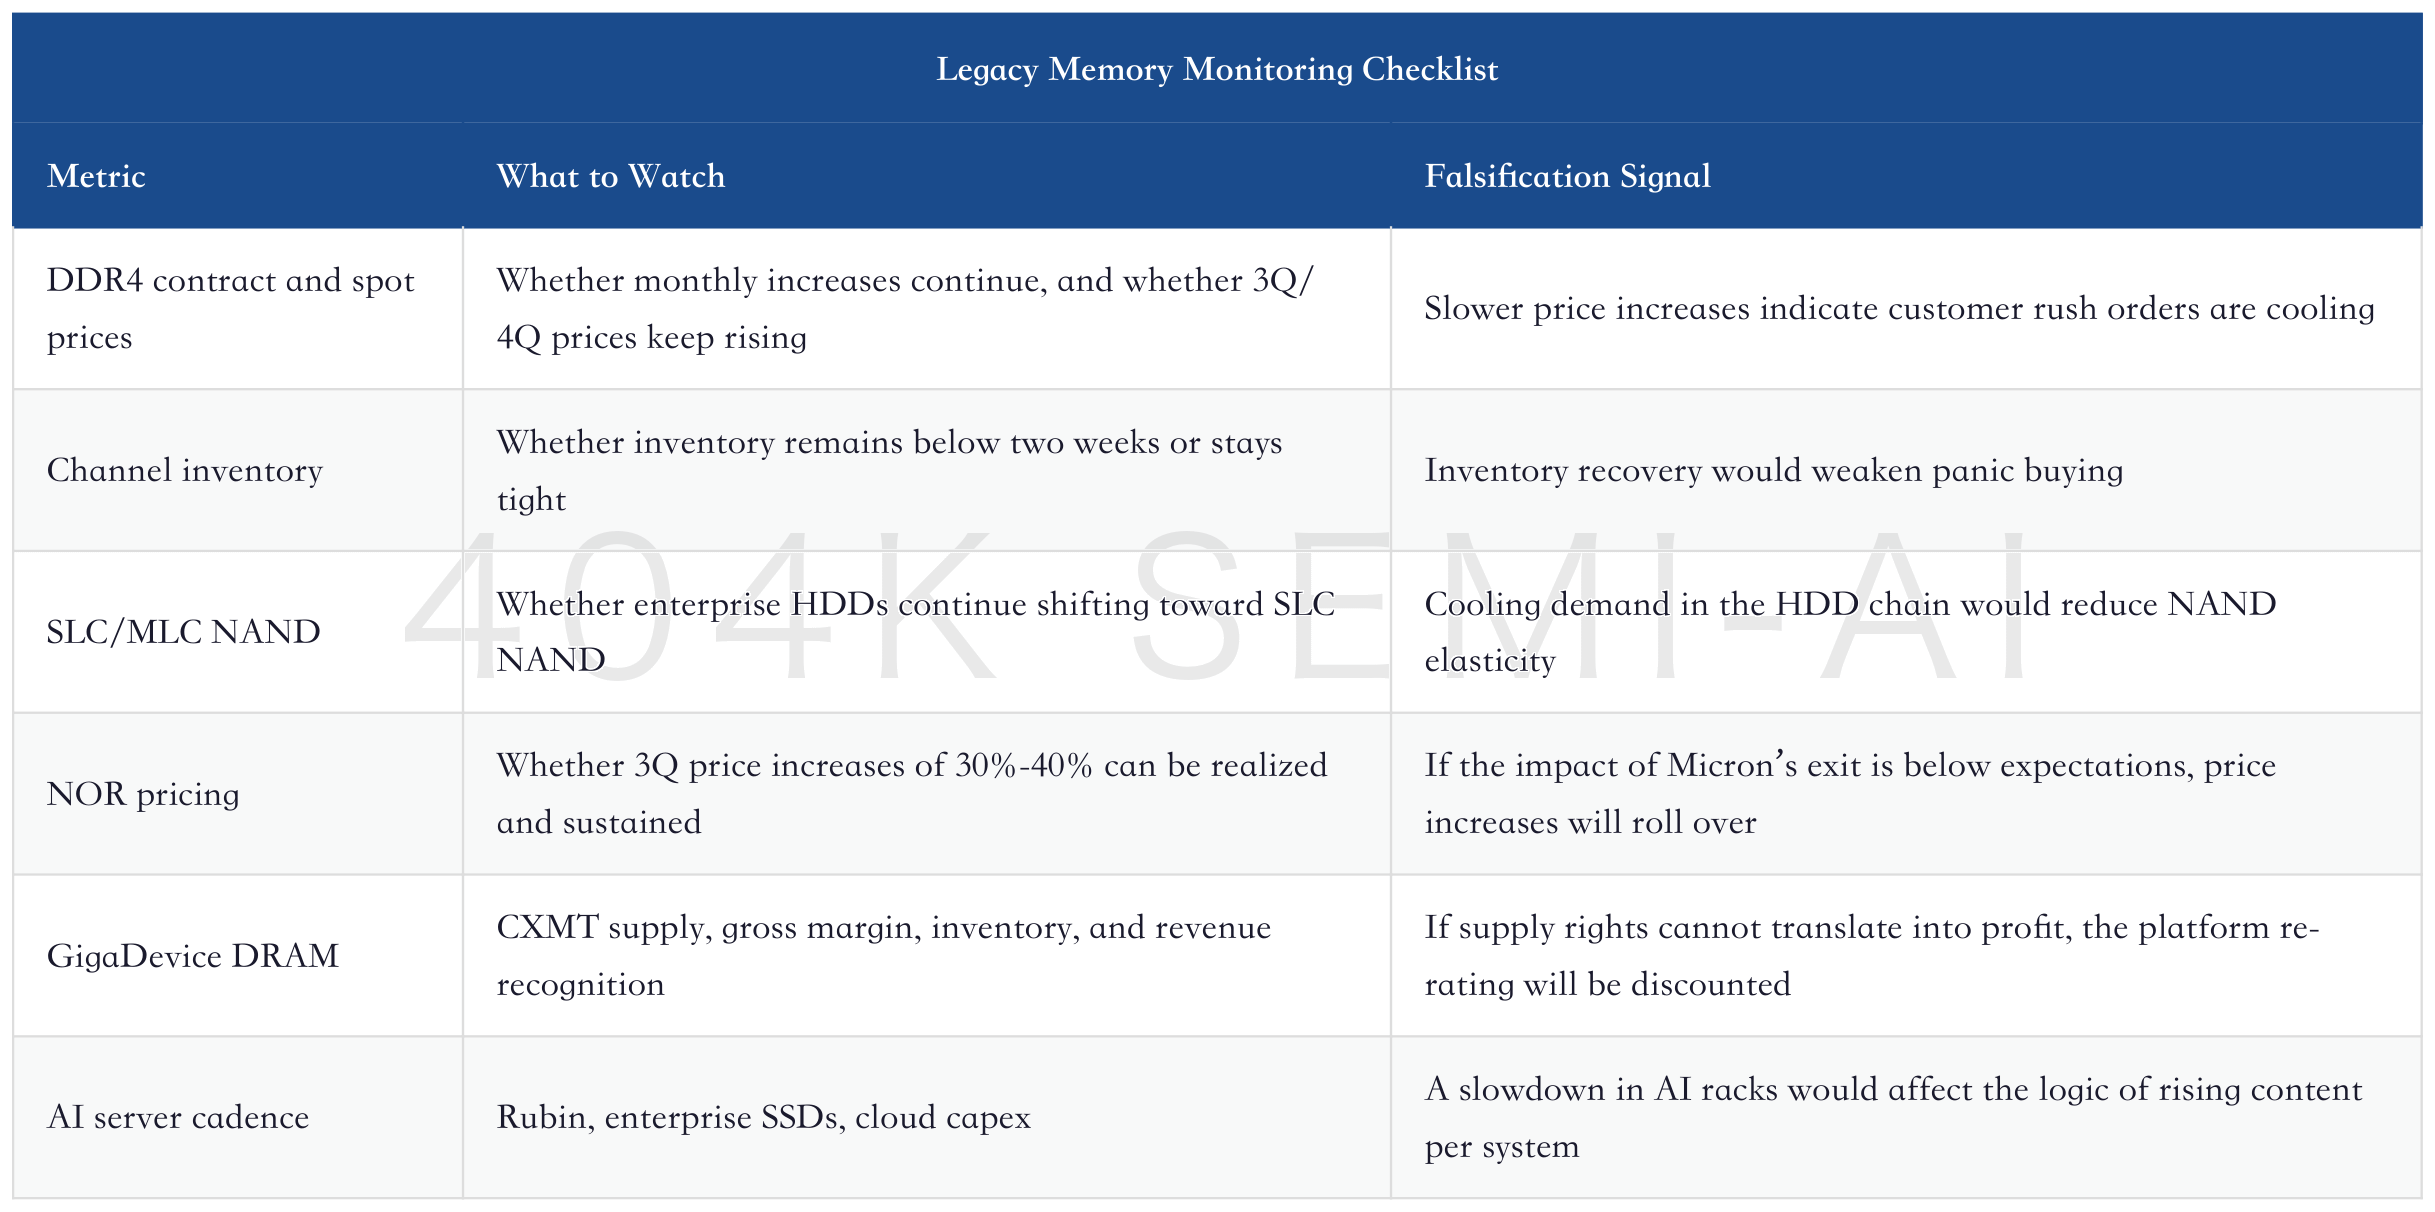
The first risk is pricing. If monthly DDR4 price increases slow, SLC/MLC NAND no longer sustains the strong 3Q rally, or 4Q NOR price negotiations come in below expectations, it would indicate that panic buying by customers is cooling. The second risk is supply. If CXMT, YMTC, Macronix, Winbond, Nanya, and others expand or restart capacity faster than expected, the supply-demand gap will narrow earlier. The third risk is demand. If delivery schedules slow for AI servers, Rubin racks, enterprise HDDs, and industrial customers, legacy memory will again be viewed as cyclical restocking.
The fourth risk is valuation. If companies such as GigaDevice, Nanya Technology, and Winbond Electronics rally to very high valuations first, further support will require continued EPS upgrades. Morgan Stanley has already significantly raised 2026-2028 EPS for multiple companies in this report. What the market will watch next is no longer “whether prices are rising,” but “whether upgrades can continue.”
The conclusion is clear: this Morgan Stanley report pushes the boundary of the memory trade one step further. Previously, when the market bought HBM, Micron, SanDisk, and Kioxia, it was buying the most visible bottleneck in AI memory. Now, when Morgan Stanley calls for buying legacy memory, it is buying the second wave of pricing power after HBM and AI servers have crowded out mature memory supply.
Memory Deep Dive: AI Servers, LTA Long-Term Agreements, and the DRAM/NAND/HBM Margin Re-rating
This legacy-memory cycle should not be framed as “catch-up gains in lagging categories.” It is better understood as spillover validation of the memory supercycle. What investors should really buy is not “legacy,” but categories that remain structurally necessary after supply exits. What investors should really guard against is not that prices have risen too much in the short term, but whether customer rush orders and price upgrades can continue to be validated by earnings reports. If DDR4, SLC NAND, and NOR still maintain strong pricing in 4Q, the memory re-rating will continue spreading from the HBM main line into niche memory. If prices and inventory begin to loosen, legacy memory will return to a cyclical discount faster than HBM.Memory Deep Dive Update: Morgan Stanley Says Buy Legacy Memory, Why DDR4, SLC NAND, and NOR Are Still Rising
目录
Too Long; Didn’t Read
1. What Really Changed in This Morgan Stanley Report
2. DDR4: Why Legacy DRAM Has Regained Pricing Power
3. SLC NAND: Why Enterprise HDDs Are Starting to Compete for Older NAND
4. NOR: Rubin Cabinets and Micron’s Exit Push Supply Toward Taiwanese Vendors
5. This “Legacy Memory” Cycle Is Not the Opposite of HBM, But HBM’s Shadow
VI. Risks and Monitoring: When Legacy Memory Shifts Back From Bottleneck to Cyclical Commodity
本内容基于公开资料和研报数据整理,不构成任何投资建议,不代表任何个人观点,仅供学习参考,请理性阅读
The real change in this Morgan Stanley report is not another round of memory price increases, but the return of DDR4, SLC NAND, and NOR, long overshadowed by HBM, to the center of pricing: enterprise customers are starting to scramble for legacy memory, while supply exits, low inventories, and higher content per AI rack are turning niche memory from a cyclical catch-up trade into a structural bottleneck.
Too Long; Didn’t Read
Legacy memory has become a bottleneck again. Morgan Stanley believes shortages in DDR4, SLC NAND, and NOR will last longer than expected, with enterprise customers now pulling in orders, not just consumer electronics restocking.
DDR4 is the strongest main line. Channel inventory is below two weeks, enterprise customers are worried about supply disruption, 3Q price assumptions have been raised, and Nanya Technology and Winbond Electronics are the most direct beneficiaries.
The NAND change is more enterprise-oriented. MLC shortages are forcing enterprise HDDs to shift toward high-density SLC NAND, with logic across SanDisk, Kioxia, and Macronix mutually reinforcing.
NOR pricing is driven by supply exits. Micron is reducing NOR supply, Rubin rack content is rising, and Morgan Stanley expects 3Q NOR prices to rise 30-40% and continue into 4Q.
Company ranking depends on category exposure. Macronix is purer; Winbond benefits from DDR4/NOR/SLC; Nanya benefits from DDR4; GigaDevice benefits from a domestic niche memory platform.
This is not the opposite of HBM. AI is pushing major suppliers’ capacity toward HBM and advanced DRAM, which instead crowds out mature memory supply; legacy memory has become the shadow asset of HBM spillover.
The risks are supply and valuation. If prices loosen, customers slow pull-ins, CXMT/YMTC capacity ramps earlier, or AI server momentum slows, high-beta niche memory will be repriced first.
1. What Really Changed in This Morgan Stanley Report
The title of this Morgan Stanley report is “Old Memory: Better to buy more,” which captures the point the market most easily misses: it is not just HBM that is strong now; legacy memory is also being repriced. More precisely, DDR4, SLC/MLC NAND, and NOR flash, once seen as mature, low-growth, and easily replaceable, are becoming key variables in the new round of memory tightness because of supply exits and enterprise customer stockpiling.
Morgan Stanley uses a very direct phrase in the cover summary: Unexpected persistent tightness in legacy memory supply. This does not mean legacy memory has suddenly become high tech, but that AI has rewritten the supply-demand structure. Major manufacturers are directing more capacity, capex, and management attention toward HBM, DDR5, advanced nodes, and enterprise SSDs, crowding out mature categories; at the same time, enterprise customers, data-center HDDs, AI servers, Rubin racks, industrial applications, and automotive applications still need these legacy memory products.
Global Memory Deep Dive: 2Q26 Earnings Divergence, Can Better 3Q Pricing Restart the Memory Stock Re-rating?
The investment implication of this report is not simply that “memory prices are still rising,” but that the memory trade is spreading from HBM, DDR5, and eSSD to legacy memory. HBM is the visible bottleneck; legacy memory is the hidden bottleneck created by crowding out. The former is pulled directly by AI GPUs and ASICs; the latter sees profit leverage amplified by supply exits, panic buying from customers, and low inventories.
Morgan Stanley’s upward revisions to covered companies also illustrate this point. GigaDevice’s target price was raised from RMB 585 to RMB 888; Winbond Electronics from NT$222 to NT$288; Nanya Technology from NT$380 to NT$550; Macronix from NT$202 to NT$220; and Powerchip Semiconductor Manufacturing from NT$88 to NT$111. They are not the same kind of memory assets, but they all benefit from tighter mature memory supply.
2. DDR4: Why Legacy DRAM Has Regained Pricing Power
DDR4 is the strongest main line in this report. Morgan Stanley believes enterprise customers are locking in supply as early as possible because they fear sustained shortages; channel inventory remains below two weeks, meaning customers have little buffer. DDR4 has already posted double-digit monthly price increases, and Morgan Stanley believes price increases will continue into 4Q.
This is different from a traditional DDR4 restocking cycle. In the past, when DDR4 prices rose, the market usually attributed it to inventory recovery in PCs, smartphones, and consumer electronics. This time, the backdrop is that global DRAM majors continue to push resources toward HBM, DDR5, and AI-server-related products, crowding out mature DDR4 supply. Demand has not disappeared: enterprise customers, industrial, consumer electronics, networking equipment, server peripherals, and local customers still need stable supply.
The Memory Tax Arrives: How AI Is Turning HBM, DRAM, and NAND into a Global Macro Bottleneck
Nanya Technology is the most direct DDR4 beta asset. Morgan Stanley raised Nanya Technology’s target price from NT$380 to NT$550 and lifted 2026/2027/2028 EPS by 7%/15%/14%, respectively. More important is the pricing assumption: the 3Q DDR4 price increase was raised from the previous 20% to at least 30%, with the supply-demand gap unlikely to fully close before 1H27.
Winbond Electronics also benefits from DDR4, but it is not a pure DDR4 company. Morgan Stanley raised Winbond Electronics’ target price from NT$222 to NT$288 and lifted 2026/2027/2028 EPS by 4%/17%/24%, respectively, citing stronger-than-expected pricing across DDR4, NOR flash, and SLC NAND. Winbond’s advantage is more diversified categories; its disadvantage is that valuation must explain volatility across multiple mature memory categories at the same time.
The key to the DDR4 line is not how advanced it is, but that its supply elasticity is declining. As long as major manufacturers keep advanced capacity reserved for HBM and DDR5, new DDR4 supply will not be released as quickly as in the past. Low customer inventories, early orders, and stable long-tail demand are enough to give legacy DRAM pricing power for a period of time.
3. SLC NAND: Why Enterprise HDDs Are Starting to Compete for Older NAND
The NAND thread is more interesting. The market is familiar with eSSD, NAND contract prices, and the AI inference data layer, but Morgan Stanley focuses here on enterprise HDD demand for SLC NAND. The report notes that MLC NAND shortages are forcing enterprise HDDs to shift to high-density SLC NAND for firmware, hot data, and defect mapping. The original line can be compressed into one signal: forcing enterprise HDDs to use SLC NAND.
The logic is that enterprise storage is not only SSDs. AI inference, enterprise data lakes, backup, cold data, video, and logs still rely heavily on HDDs; but enterprise HDDs also need NAND internally to store firmware, mapping tables, and hot data. If MLC supply is insufficient, enterprise HDDs will compete for high-density SLC NAND. This would allow mature NAND tightness to spread from eSSD into the HDD supply chain.
SanDisk Deep-Dive Update: Citi Raises Target Price to US$2,500, NAND Shortage Cycle Extends Beyond CY27
Morgan Stanley believes SLC/MLC NAND price elasticity could likely continue into 4Q. Macronix has the cleanest leverage on this line because it is exposed to both the SLC/MLC NAND and NOR supply gaps, and the report names it as a Top Pick.
This is also why NAND can no longer be understood only as consumer-electronics restocking. SanDisk, Kioxia, Samsung, SK hynix, Micron, and Macronix sit at different layers: some benefit from enterprise SSD, some from NAND contract prices, some from mature NAND shortages, and some from controllers and the enterprise HDD chain. NAND pricing power is spreading from “data-center SSD” into lower-level storage media.
4. NOR: Rubin Cabinets and Micron’s Exit Push Supply Toward Taiwanese Vendors
NOR flash is the third key thread in this report. Morgan Stanley believes NOR price increases are being led by Macronix, behind which lies supply shifting from NOR to NAND, as well as Micron reducing NOR supply in 2H and reallocating capacity to DRAM and NAND. Meanwhile, after Vera Rubin cabinets ramp in 2H, NOR content will be more than 50% higher than in Grace Blackwell cabinets. Morgan Stanley therefore expects NOR prices to rise 30%-40% in 3Q and continue into 4Q.
This is not a short-term price increase in a small category. NOR has a smaller market size than DRAM/NAND, but its customers are more fragmented, qualification cycles are longer, and product life cycles are more stable. Automotive, industrial, servers, optical modules, networking, AI servers, and edge devices all need NOR to store code, firmware, and boot information. When suppliers exit and customers still need assured supply, price elasticity can be very direct.
GigaDevice Deep Dive: AI Pushes Major Vendors Toward HBM; Who Captures Supply Power in Niche DRAM?
GigaDevice’s logic on this line is more complex. Morgan Stanley raised its target price for GigaDevice from RMB585 to RMB888 and raised 2026/2027/2028 EPS by 30%/46%/53%, respectively. This is not simply because NOR prices are rising. It is because DDR4, NOR flash, and SLC NAND are all stronger than expected, layered on top of domestic niche DRAM supply power, MCU, and edge AI storage platforms. Morgan Stanley’s residual income model target price implies 53x 2026 P/E, above the historical average, indicating a higher premium for a “domestic niche storage platform.”
The core issue in NOR is supply concentration. If Micron reduces NOR supply, global supply will become more dependent on Macronix, Winbond, GigaDevice, and others. Taiwanese vendors therefore gain stronger pricing power, while GigaDevice becomes the main A-share proxy for tight mature-memory supply. This logic does not conflict with HBM; rather, it is the chain reaction after HBM crowds out mature capacity.
5. This “Legacy Memory” Cycle Is Not the Opposite of HBM, But HBM’s Shadow
The market tends to split memory into two categories: HBM as advanced assets, and legacy memory as cyclicals. This classification is technically right, but insufficient for investment purposes. The stronger HBM becomes, the more it absorbs advanced DRAM capacity, capex, and supplier resources. The more major vendors chase HBM, DDR5, and eSSD, the easier it is for mature DDR4, SLC NAND, and NOR supply to be crowded out. Legacy memory is not the opposite of HBM; it is the shadow asset created by HBM-driven resource reallocation.
Micron Earnings Deep Dive: Q3 Results Beat Expectations Sharply, AI Memory Supercycle Enters Monetization Phase; How Much Profit Can LTAs Lock In?
This is also why this Morgan Stanley report can corroborate recent reports on Micron, SanDisk, and global memory. Micron proves that AI memory LTAs and structural tightness in HBM/DRAM are still being monetized. SanDisk proves that NAND shortages may extend beyond CY27. The global memory report proves that 3Q pricing improvement is spreading from HBM to commodity DRAM and NAND. This Morgan Stanley report fills in the final piece of the puzzle: mature DDR4, SLC NAND, and NOR are also being pulled in early by customers.
If the memory cycle is split into three layers, the first layer is HBM and AI DRAM, which most directly benefit from GPU/ASIC. The second layer is commodity DRAM and enterprise SSD, which most directly enter the income statement. The third layer is legacy memory, including DDR4, SLC/MLC NAND, and NOR. This layer historically had the lowest valuation, but when supply is hardest to replenish and customer inventory is lowest, its near-term elasticity can instead be the greatest.
The investment implication of this framework is straightforward: do not only buy the highest-end memory, and do not treat legacy memory as low-quality beta. High-end memory determines the industry direction, while legacy memory determines the near-term earnings slope. If AI continues to occupy major vendors’ resources, legacy memory shortages could last longer than the market expects.
VI. Risks and Monitoring: When Legacy Memory Shifts Back From Bottleneck to Cyclical Commodity
The biggest risk to the legacy-memory trade is that the market extrapolates the supply gap for too long. DDR4, SLC NAND, and NOR are not permanently scarce assets. If prices rise high enough, customers will delay procurement, seek substitutes, and optimize inventory, while suppliers will also reallocate capacity. Niche memory has strong upside elasticity, but drawdowns can also come faster.
The first risk is pricing. If monthly DDR4 price increases slow, SLC/MLC NAND no longer sustains the strong 3Q rally, or 4Q NOR price negotiations come in below expectations, it would indicate that panic buying by customers is cooling. The second risk is supply. If CXMT, YMTC, Macronix, Winbond, Nanya, and others expand or restart capacity faster than expected, the supply-demand gap will narrow earlier. The third risk is demand. If delivery schedules slow for AI servers, Rubin racks, enterprise HDDs, and industrial customers, legacy memory will again be viewed as cyclical restocking.
The fourth risk is valuation. If companies such as GigaDevice, Nanya Technology, and Winbond Electronics rally to very high valuations first, further support will require continued EPS upgrades. Morgan Stanley has already significantly raised 2026-2028 EPS for multiple companies in this report. What the market will watch next is no longer “whether prices are rising,” but “whether upgrades can continue.”
The conclusion is clear: this Morgan Stanley report pushes the boundary of the memory trade one step further. Previously, when the market bought HBM, Micron, SanDisk, and Kioxia, it was buying the most visible bottleneck in AI memory. Now, when Morgan Stanley calls for buying legacy memory, it is buying the second wave of pricing power after HBM and AI servers have crowded out mature memory supply.
Memory Deep Dive: AI Servers, LTA Long-Term Agreements, and the DRAM/NAND/HBM Margin Re-rating
This legacy-memory cycle should not be framed as “catch-up gains in lagging categories.” It is better understood as spillover validation of the memory supercycle. What investors should really buy is not “legacy,” but categories that remain structurally necessary after supply exits. What investors should really guard against is not that prices have risen too much in the short term, but whether customer rush orders and price upgrades can continue to be validated by earnings reports. If DDR4, SLC NAND, and NOR still maintain strong pricing in 4Q, the memory re-rating will continue spreading from the HBM main line into niche memory. If prices and inventory begin to loosen, legacy memory will return to a cyclical discount faster than HBM.