
Memory Deep-Dive Update: Korea's US$3.1tn AI Investment Plan and How to Revalue DRAM, NAND, and the Equipment Chain
目录
Too Long; Didn't Read
1. Start With the Conclusion: Korea Is Turning the Memory Shortage Into a National Capex Cycle
2. What the US$3.1tn Plan Actually Contains
3. Why the Market Is Not Buying It in the Short Term
4. The Supply-Demand Math: Expansion Is Large, but the Gap Is Faster
5. The Equipment Chain Monetizes Before Memory Prices
6. The DRAM, NAND, and HBM Gaps Must Be Viewed Separately
7. Pricing Power Enters a High-Pressure Zone: Customers Start to Push Back
8. Regulatory Risk: Class Actions Can Change the Valuation Discount
9. The Chinese Supply Variable: A Price Buffer, but Unlikely to Fill the High-End Gap in the Short Term
10. Three Worldviews: Supercycle, Capex Catch-Up, and Customer Backlash
11. Segment Ranking: Who Benefits First, and Who Comes Under Pressure First
12. Core Model Table: Transmission From Investment Plan to Income Statement
13. Cross-Checks From JPMorgan, Deutsche Bank, and Morgan Stanley
14. Mapping Korea's Plan to Global Companies
15. Prices, Long-Term Contracts, and Earnings Quality: What to Watch to Judge Cycle Health
16. Where Downstream Backlash Starts
17. Data Framework: Which Numbers to Watch Over the Next Four Quarters
18. Risk List: Where This Thesis Could Be Wrong
19. Return on Capital: The US$3.1tn Plan Ultimately Lands in Depreciation and Cash Flow
20. Timing: Watch Prices in 2026, Orders in 2027, and Supply in 2028
21. Valuation Discount: How the Market Will Reprice the Memory Cycle
22. Conclusion: The Memory Supercycle Enters the "Supply-Franchise Verification Period"
本内容基于公开资料和研报数据整理,不构成任何投资建议,不代表任何个人观点,仅供学习参考,请理性阅读
Korea is putting memory capacity expansion, AI data centers, and Physical AI onto the same capital-spending roadmap. The market is worried in the near term that new supply could undermine pricing, but the research focus should fall on four variables: the supply-demand gap, equipment orders, customer cost pressure, and regulatory risk. This report breaks the US$3.1tn plan into four verification lines: DRAM, NAND, WFE, and power engineering.
Too Long; Didn't Read
Korea plans to elevate the memory shortage into a national capital-spending cycle. The long-term projects disclosed by Samsung, SK, and the Korean government total roughly US$3.1tn, covering fabs, AI data centers, power infrastructure, HBM back-end packaging, Physical AI, and semiconductor engineering capabilities. The stock market is worried in the short term that capacity expansion will pressure prices. For research, the more important question is when added capacity becomes effective supply.
The supply-demand gap remains the main pricing driver in 2026-2027. JPMorgan and Deutsche Bank both expect DRAM and NAND shortages to extend beyond 2027, mainly because AI servers, Agentic AI, and edge devices jointly raise memory capacity demand. Even if new WSPM is revised up meaningfully, advanced nodes, HBM conversion losses, cleanroom constraints, and power bottlenecks will still slow effective supply.
The equipment and engineering chains will recognize orders first. Front-end wafer equipment accounts for the largest share of Korea's long-term plan, followed by cleanrooms, power, EPC, and back-end packaging. Morgan Stanley has already raised its 2026-2027 DRAM WFE forecasts, showing that capex is moving from narrative into orders and deliveries.
Memory vendors are entering a high-pressure pricing-power zone. Pricing disputes between Apple and Micron, BOM pressure in consumer electronics, and US consumer litigation all show that memory price increases have already passed from inside the supply chain to end customers. Pricing power remains in the hands of memory vendors, but customer pushback, regulatory scrutiny, and alternative supply are becoming more important.
Chinese supply is a buffer, but it is unlikely to rewrite the high-end shortage in the short term. Chinese DRAM and NAND capacity expansion will ease part of the pricing pressure in consumer electronics and mature products, but server-grade DRAM, HBM, enterprise SSDs, LPDDR, and high-reliability supply certification cannot be completed overnight. For the global memory cycle, Chinese supply is more like a marginal buffer after prices rise.
The investment mapping should be layered, not limited to memory vendors. Memory manufacturers benefit from ASP and margin expansion; semiconductor equipment benefits from WFE upgrades; power and data-center engineering benefit from AI load buildout; packaging and substrates benefit from higher HBM and advanced-memory complexity. Key follow-up indicators are DRAM/NAND prices, the WSPM cadence, WFE orders, customer disputes, and inventory cash flow.
1. Start With the Conclusion: Korea Is Turning the Memory Shortage Into a National Capex Cycle
The key implication of Korea's latest AI and semiconductor investment plan is that the memory cycle is moving from a pricing cycle into an infrastructure cycle. Over the past two years, the market mainly watched DRAM, HBM, and NAND quotations. It now also needs to track fabs, back-end packaging, AI data centers, power facilities, and semiconductor engineering delivery. Prices remain important, but variables beyond prices are starting to determine the length of the cycle.
The plan is large because Korea is addressing three issues together. The first is insufficient memory supply, especially as AI servers, HBM, LPDDR, enterprise SSDs, and commodity DRAM all consume capacity at the same time. The second is that AI data-center construction requires stable power and infrastructure; memory expansion cannot be separated from grids, land, cleanrooms, and engineering capacity. The third is that Korea needs to maintain its global leadership in memory and avoid having the US, Taiwan, mainland China, and Japan rewrite supply-chain roles in the new AI capex cycle.
The market's short-term response has been cautious, and that is normal. Every major expansion in the history of the memory industry has raised the same question: will today's high prices be pushed down by future capacity? But this time cannot be judged only through the old-cycle framework. In the old cycle, demand mainly came from PCs, smartphones, and conventional servers, and prices would fall quickly once supply came online. In the new cycle, AI training, inference, Agentic AI, Physical AI, sovereign AI, and edge devices are all raising memory capacity requirements, while supply growth and demand growth are racing on the same timetable.
The Memory Tax Has Arrived: How AI Is Turning HBM, DRAM, and NAND Into a Global Macro Bottleneck
The core view of this update is straightforward: Korea's US$3.1tn AI investment plan will raise the long-term supply ceiling, but it will not immediately break the memory shortage in 2026-2027. In the first two years, it is more likely to appear first in orders for equipment, engineering, power, and back-end packaging; in the medium term, it will show up as new wafer supply; only in the long term will it determine whether Korean memory vendors can turn the AI era's high capital intensity into more stable long-term revenue.
In other words, this event should not simply be classified as "capacity expansion is bearish for memory prices." A more accurate research framework has three layers: first, look at prices and judge how long memory vendors can maintain high gross margins; second, look at capex and judge whether orders for the equipment and engineering chains can be delivered; third, look at customers and regulation and judge whether price increases are starting to hurt end demand and social acceptance. Only if all three layers hold can the memory supercycle move from a price-hike story to long-term asset revaluation.
2. What the US$3.1tn Plan Actually Contains
The headline amount in Korea's plan looks exaggerated, but the logic is not complicated once broken down. It consists of three categories of government-led mega projects: semiconductors, AI robotics, and AI data centers. It also includes long-term capex by companies such as Samsung and SK. The focus is a full set of national industrial capabilities: memory manufacturing, packaging, computing power, electricity, and industrial AI.
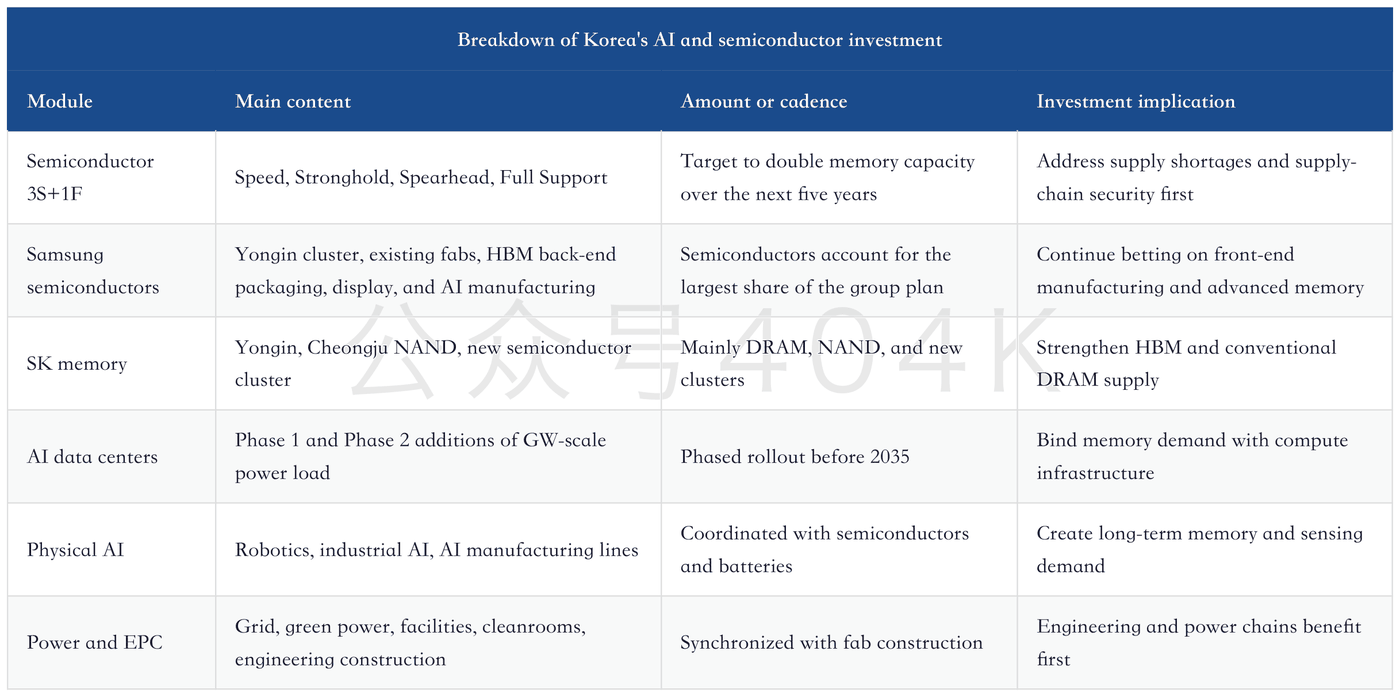
The most important point here is the "pull-forward" of the timetable. Korea plans to move the production timeline for advanced Yongin fabs significantly forward from the mid-to-late 2040s into the 2030s. The signal is clear: Korean memory vendors view memory demand over the next decade as part of AI infrastructure. PC and smartphone restocking alone cannot support capex of this scale.
From a capex structure perspective, front-end wafer equipment is the largest component, cleanrooms and infrastructure sit in the middle, and back-end packaging is smaller in share but more strategic. Front-end equipment determines wafer capacity; cleanrooms and power determine whether fabs can start on time; back-end packaging determines whether HBM, advanced memory, and high-performance-computing customers can receive usable products. The memory industry was often treated in the past as a "price-cycle stock." It now looks increasingly like the intersection of energy, compute, and manufacturing capability.
A US$700bn-Plus AI Wager: SK Hynix, Samsung, and the Korean Government's Aggressive Bet on Compute Infrastructure
This also explains why semiconductors, data centers, and Physical AI all appear in Korea's plan at the same time. Semiconductors provide supply, data centers provide the demand anchor, and Physical AI provides the long-term application scenario. In the traditional memory cycle, demand came from consumer devices. In the AI era, demand comes from compute nodes, inference tasks, robots, and industrial systems. The more demand resembles infrastructure, the more the supply side needs long-term planning.
3. Why the Market Is Not Buying It in the Short Term
Korean memory stocks have reacted cautiously to this type of news, with capacity expansion as the obvious surface reason. The memory industry is most afraid of high prices attracting every vendor to expand capacity, followed a few years later by concentrated supply release and a rapid fall in prices from elevated levels. When investors see a US$3.1tn long-term plan, their first reaction is naturally to worry that today's strong pricing power will be diluted by future capacity.
That concern is reasonable, but it does not directly support a bearish conclusion. Capex has different meanings at different points in the cycle. Early-cycle expansion is usually demand confirmation, showing that customers are willing to sign long-term contracts and that prices can cover investment returns. Late-cycle expansion is more dangerous because it often happens when prices are strongest, profits are best, and companies are most prone to overconfidence. The memory industry today sits between the two: prices and profits are already strong, but the supply gap is also genuinely real.
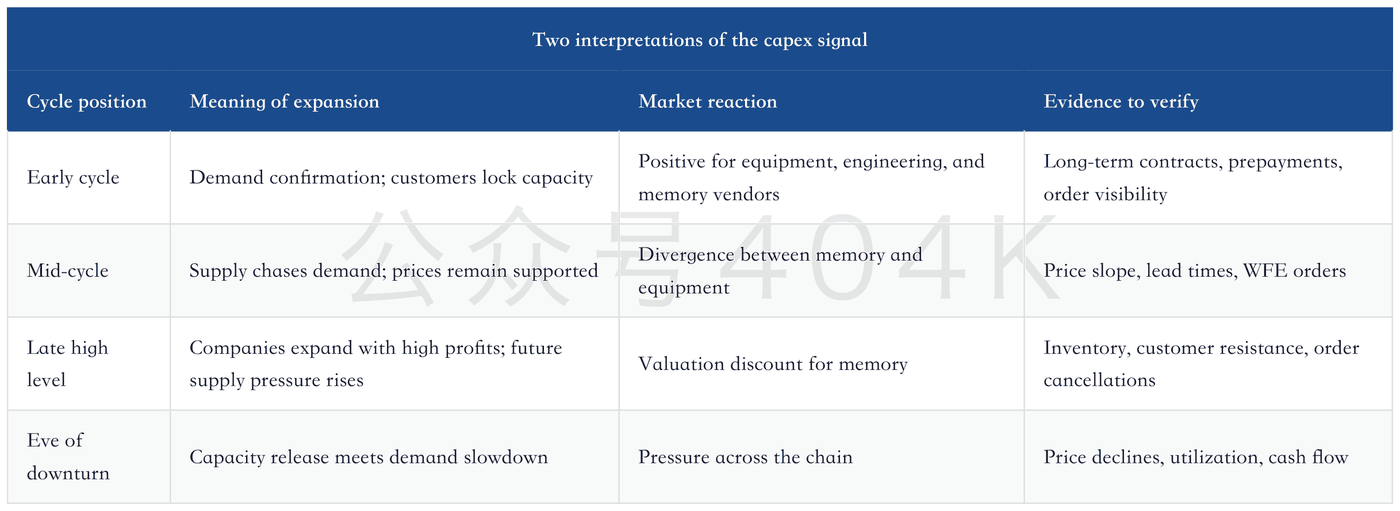
The current stage looks more like a strong mid-cycle. DRAM and NAND prices have already risen, HBM and server memory supply is tight, enterprise SSD demand is improving, and customer acceptance of higher prices is starting to decline. This stage is most likely to produce two types of market action: the equipment chain continues to benefit from upgraded order visibility, while memory vendors start to face valuation discounts because prices are already elevated.
Therefore, the trading implication of this plan is asset divergence. Equipment, EPC, power, and back-end packaging benefit more directly. The benefit to memory vendors depends on price durability, customer contracts, inventory, and regulatory risk. Investors who look only at the words "capacity expansion" will miss opportunities in the equipment chain; investors who look only at the word "shortage" will underestimate future supply and customer-pushback risks.
4. The Supply-Demand Math: Expansion Is Large, but the Gap Is Faster
To judge the memory cycle, the most important step is to separate "planned capacity" from "effective supply." Planned capacity is the fabs, cleanrooms, and equipment budgets announced by companies. Effective supply is the bits that can actually be delivered after construction, equipment installation, yield ramp, and customer certification. The two are usually separated by several years, as well as by power, land, equipment lead times, talent, and customer qualification.
JPMorgan's latest update still shows DRAM and NAND demand growth exceeding shipment growth in 2026 and 2027. Deutsche Bank's DRAM supply-demand model goes further: even after raising new WSPM for the next five years, DRAM shortages may still persist into 2028 or beyond. The reason is that AI servers and Agentic AI are raising demand for conventional DRAM, while HBM consumes advanced wafer resources and creates "lost bits."
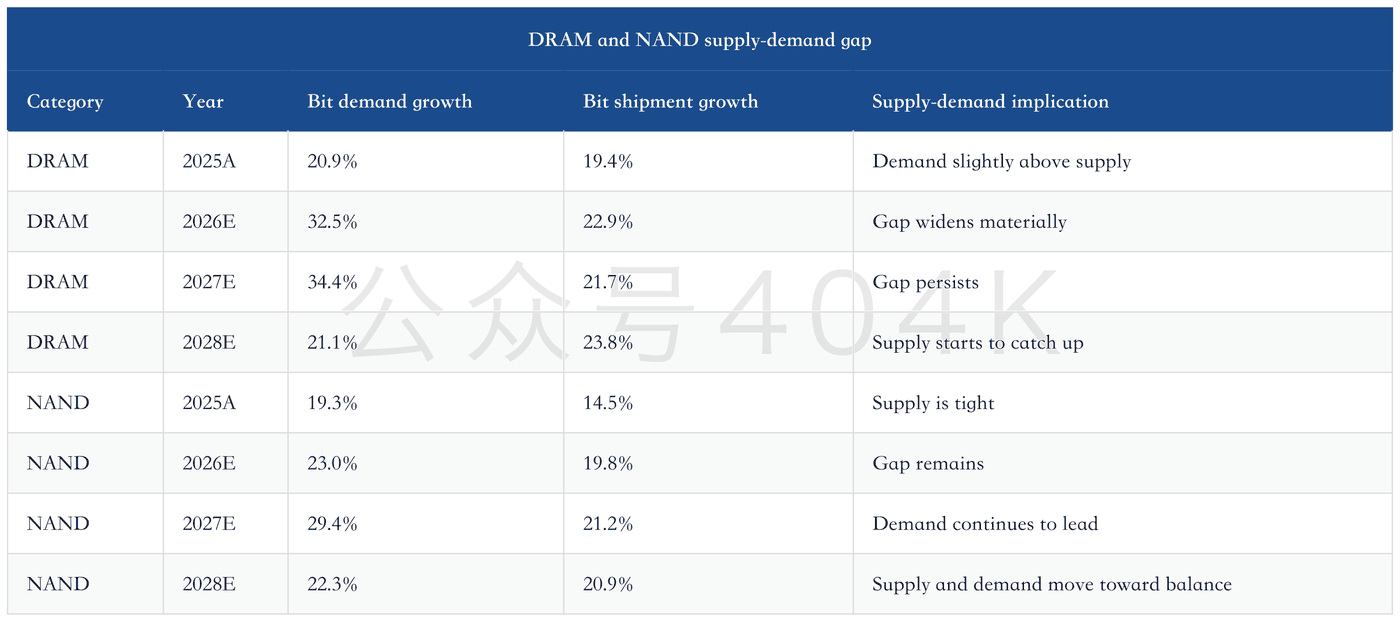
This table explains why the market can worry about expansion while still chasing memory price increases. In 2026-2027, the near-term supply-demand gap is not covered by new capacity. After 2028, the risk of supply catching up will start to enter models more clearly. In other words, the key trading window today is not "whether Korea expands capacity," but "whether that capacity can truly become supply before prices roll over."
Memory Is No Longer Just Cyclical: JPM LTA Breakdown, Agentic AI Memory Multipliers, and the Valuation Rewrite for Samsung and SK Hynix
AI's pull on memory is not limited to HBM. The market previously concentrated AI memory demand too heavily on HBM and overlooked the pull from CPU servers, inference clusters, Agentic AI, edge devices, and enterprise SSDs on conventional DRAM, LPDDR, NAND, and controllers. Deutsche Bank has particularly emphasized higher DRAM capacity in CPU-only AI racks, while JPMorgan also views agents and Physical AI as sources of the next stage of memory demand.
This means memory supply tightness comes from multiple product lines simultaneously consuming equipment, wafers, advanced packaging, and customer budgets. Strong HBM prices will encourage vendors to shift advanced DRAM resources toward HBM, making conventional DRAM supply even tighter. Strong enterprise SSD demand will lift the value of high-layer-count NAND and controllers, while consumer NAND will also be affected by upstream supply discipline. Korea's capacity expansion can ease this problem, but not in 1H26.
5. The Equipment Chain Monetizes Before Memory Prices
If the question is who benefits first from Korea's plan, the answer is likely equipment, cleanrooms, EPC, power, and back-end packaging. The earnings of memory vendors are jointly affected by prices and supply expectations. The equipment chain, by contrast, sees capex budgets, tenders, orders, deliveries, and revenue recognition. The earlier capex starts, the earlier the equipment chain has numbers to verify.
Morgan Stanley has already raised its DRAM WFE forecast. It upgraded DRAM fab equipment spending for 2026 and 2027 and believes total WFE will also rise. This change matters: it shows that AI memory shortages are not only a pricing-side phenomenon, but have already begun to enter revenue models for equipment companies and the supply chain. NAND WFE is also improving, but DRAM remains the more direct source of upward revision.
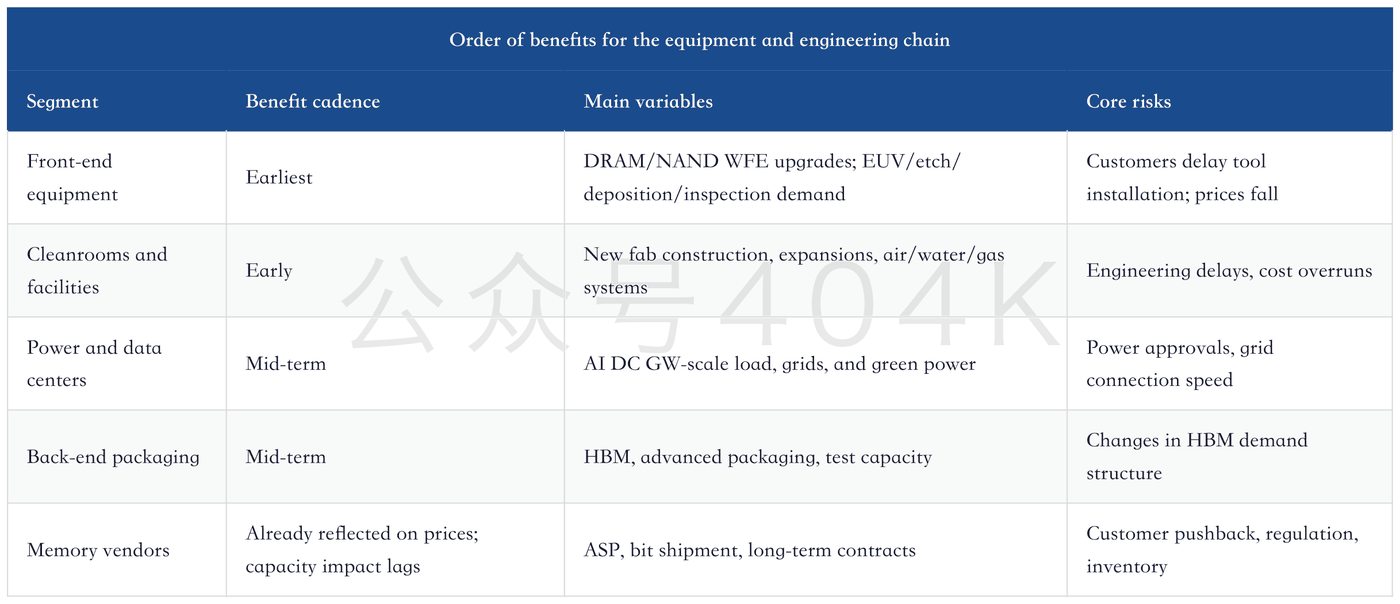
The investment logic for the equipment chain has two layers. The first is near-term orders: higher DRAM WFE directly raises revenue expectations for equipment companies. The second is long-term capital intensity: HBM, advanced DRAM, high-layer-count NAND, and advanced packaging all raise equipment investment per unit of capacity. AI memory does not just require more wafers; it requires more complex processes, stricter yield control, and greater test and packaging capability.
From HBM to WFE: How AI Is Pushing the Memory Cycle Into an Equipment Supercycle, and How Much Further Semiconductor Equipment Can Rise
But the equipment chain cannot be extrapolated without limit. Equipment orders ultimately depend on memory customers' cash flow, price expectations, and long-term demand assumptions. If DRAM or NAND prices fall earlier than expected in 2027, customers may delay some tool installations. If AI capex slows, WFE upgrades will become high-base pressure. The best scenario for the equipment chain is that prices remain strong but do not spiral out of control, customers have enough profit to continue expanding, and downstream buyers are willing to lock supply through long-term contracts.
Therefore, equipment-chain verification should focus on two numbers: orders and shipments. Orders show that customers are willing to invest; shipments show that capacity construction has truly entered execution. Looking only at WFE forecasts can miss engineering and installation cadence; looking only at near-term equipment-company revenue can underestimate the risk that memory customers may later delay expansion.
6. The DRAM, NAND, and HBM Gaps Must Be Viewed Separately
One misconception in this memory upcycle is treating all shortages as the same kind of shortage. DRAM, NAND, and HBM are all tight, but the reasons, beneficiaries, price transmission, and risks are different. HBM is tied to advanced packaging and AI GPUs; DRAM is jointly driven by servers, CPUs, PCs, smartphones, and edge AI; NAND is more affected by enterprise SSDs, QLC, nearline storage substitution, and supply discipline.
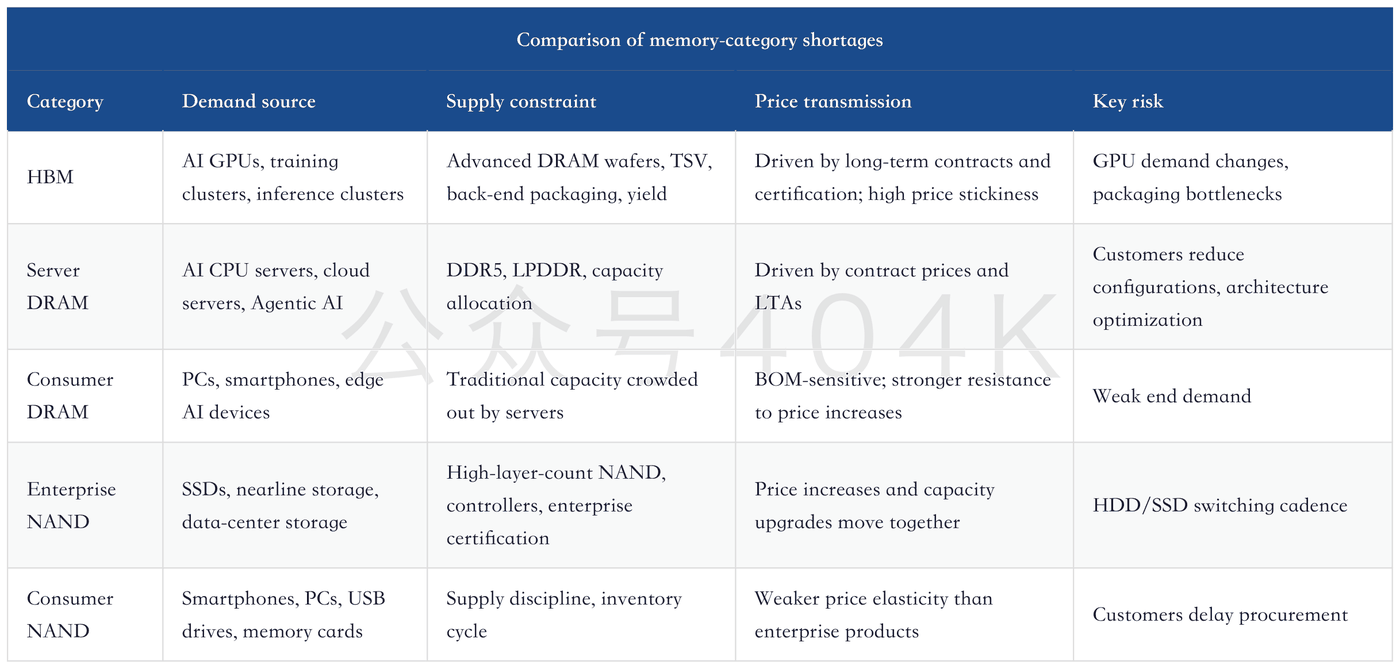
HBM is the strongest narrative, but conventional DRAM is the larger supply-demand account. HBM production consumes advanced DRAM wafers and reduces effective bit supply because of higher complexity. Even though HBM revenue itself is high, it also makes ordinary DRAM tighter. This spillover effect is what the market has repeatedly underestimated over the past two years.
NAND's logic is more about storage architecture. AI data-center training and inference will raise demand for high-speed storage and nearline storage, while enterprise SSD capacity upgrades will also raise the value of high-layer-count NAND. If HDD supply, performance, or lead times cannot meet data-center requirements, part of demand will migrate to SSDs. NAND vendors have restrained capex in recent years, and with demand recovering, price elasticity may be stronger than in the traditional consumer NAND cycle.
Global Memory Deep Dive: 2Q26 Earnings Divergence, and Whether 3Q Pricing Improvement Can Restart Memory-Stock Revaluation
Therefore, Korea's plan affects the three product types differently. For HBM, it strengthens back-end packaging and advanced-memory supply capability. For conventional DRAM, it raises long-term WSPM, but near-term effective supply is still constrained by ramp. For NAND, it may raise enterprise SSD supply, while customer certification and capital discipline may still maintain pricing resilience. Mixing the three together only understates the differentiation.
7. Pricing Power Enters a High-Pressure Zone: Customers Start to Push Back
When memory prices rise to a certain stage, supply-chain tensions shift from "vendor earnings recovery" to "customer cost pressure." The pricing dispute between Apple and Micron is one signal. Smartphone, PC, and consumer-electronics brands are highly sensitive to BOM. When DRAM and flash prices rise rapidly, customers begin to demand longer payment terms, more stable quotations, more supplier choices, and may even shift procurement strategies toward Chinese supply chains.
Suppliers have their own logic as well. During the previous downcycle, memory vendors absorbed losses, production cuts, and inventory write-downs. Now that demand is strong and supply is tight, vendors naturally want to reclaim prices and profits. Customers feel prices are rising too quickly; suppliers feel they were squeezed for too long in the past. This divergence makes contract negotiations tougher. The memory industry is not only a technology business, but also a business of capacity and bargaining power.
Customer pushback affects products differently. AI server and cloud customers are more able to accept price increases for HBM, server DRAM, and enterprise SSDs because memory costs remain necessary relative to system value, model revenue, and compute utilization. Consumer-electronics customers are more sensitive to LPDDR, mobile NAND, and PC DRAM because end-device prices are difficult to raise in step. The higher prices rise, the clearer the demand segmentation becomes.
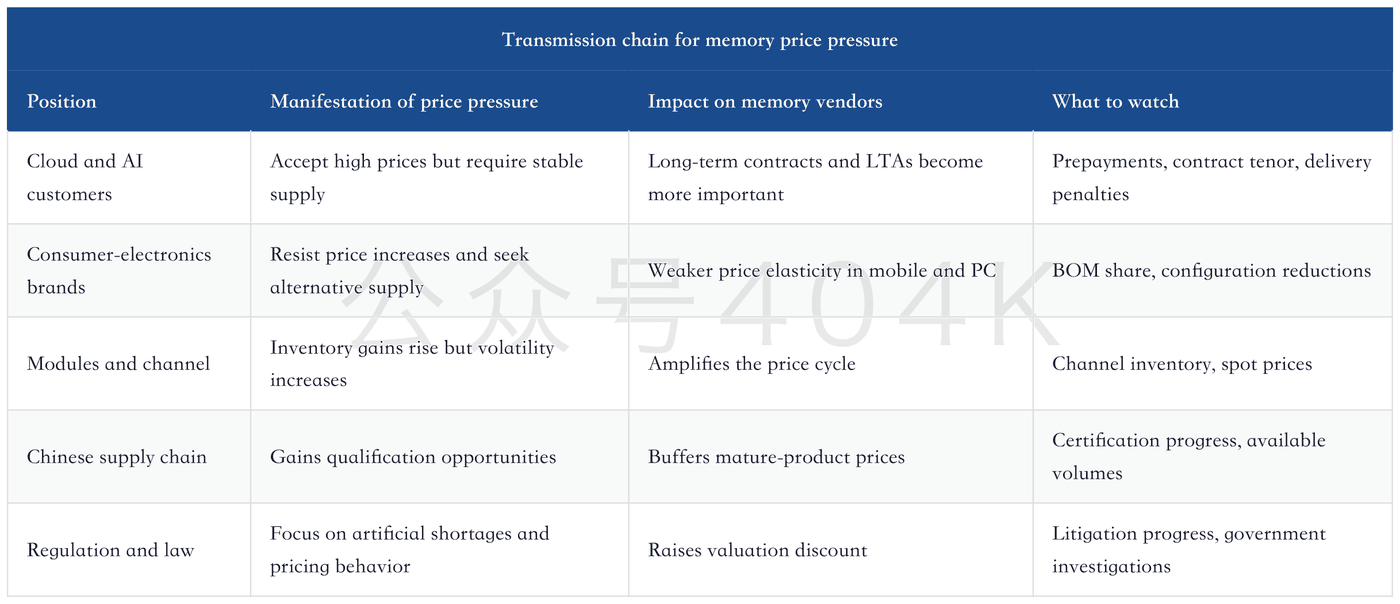
This is also why LPDDR may remain strong, while risks are rising. AI smartphones, edge AI, and high-end consumer electronics will increase memory capacity and support LPDDR prices. But consumer-electronics brands have limited gross margins and pricing power. The faster prices rise, the more incentive customers have to optimize configurations, delay procurement, or qualify alternative suppliers. The best state for memory vendors is to turn high prices into stable cash flow through long-term contracts.
8. Regulatory Risk: Class Actions Can Change the Valuation Discount
US consumer class-action litigation against the three major DRAM vendors remains at the private-litigation stage and has not yet escalated into a government investigation or a concluded antitrust case. But it shows one fact: when memory prices become an important variable in consumer-electronics prices and AI infrastructure costs, industry pricing behavior draws greater public attention. The more memory resembles a strategic resource, the harder it becomes to ignore regulatory and legal risks.
Historically, the DRAM industry has indeed faced antitrust and price-fixing cases. Penalties and guilty pleas in earlier cases left a psychological overhang for today's market; supply-restriction controversies around 2016-2017 did not reach the same conclusion. For investors, the key is whether regulatory risk changes the valuation discount rate. Historical cases only provide a reference point for risk.
This type of risk affects the industry on three levels. The first is sentiment: litigation and media reports make the market worry that price increases are unsustainable. The second is behavior: memory vendors become more cautious in public statements, contract arrangements, and supply discipline. The third is valuation: if government investigations or coordinated customer pushback intensify, the market will apply a higher discount to high gross margins even if near-term profits remain strong.
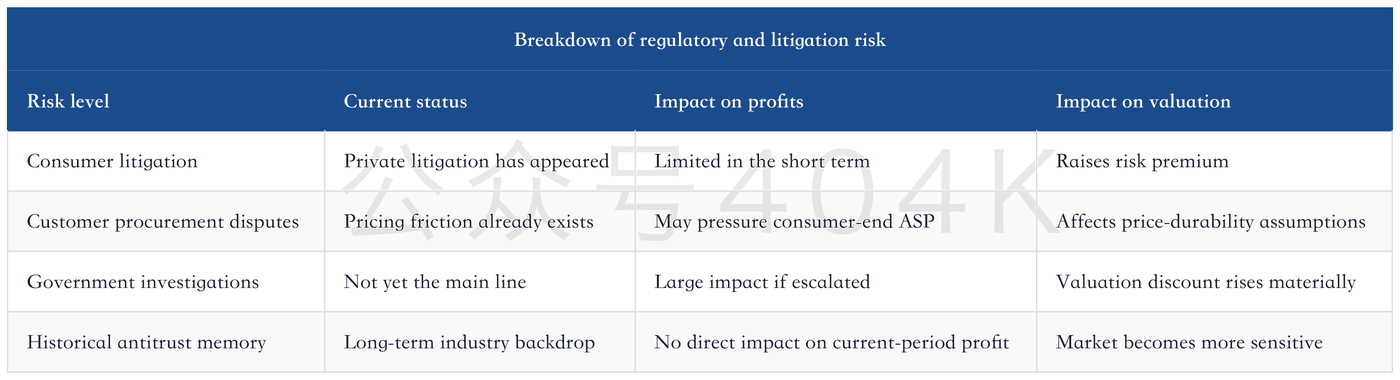
This does not change the near-term supply-demand gap, but it affects the capitalization of long-term pricing power. If memory vendors rely only on price increases, valuations will be constrained by regulation and customer pushback. If they can prove earnings quality through LTAs, prepayments, high-end product certification, and stable supply capability, the market will be more willing to view high gross margins as structural improvement.
9. The Chinese Supply Variable: A Price Buffer, but Unlikely to Fill the High-End Gap in the Short Term
Every time memory prices rise sharply, the market asks whether Chinese supply can change the landscape. This question needs a layered answer. In mature DRAM, consumer NAND, modules, and parts of mobile storage, the Chinese supply chain will gain more customer qualification opportunities and provide a buffer during the price-up phase. But server-grade DRAM, HBM, enterprise SSDs, high-end LPDDR, and AI customer certification require more time.
The most direct role of Chinese supply is to give consumer-electronics customers another bargaining chip. If Apple, US PC brands, and Android smartphone vendors face memory price increases, they can test more suppliers, raise domestic-substitution ratios, or use multi-supplier strategies to pressure prices. But that does not mean the global supply-demand balance immediately reverses. The real shortage is often usable supply for specific specifications, specific reliability requirements, specific delivery schedules, and specific customer certifications.
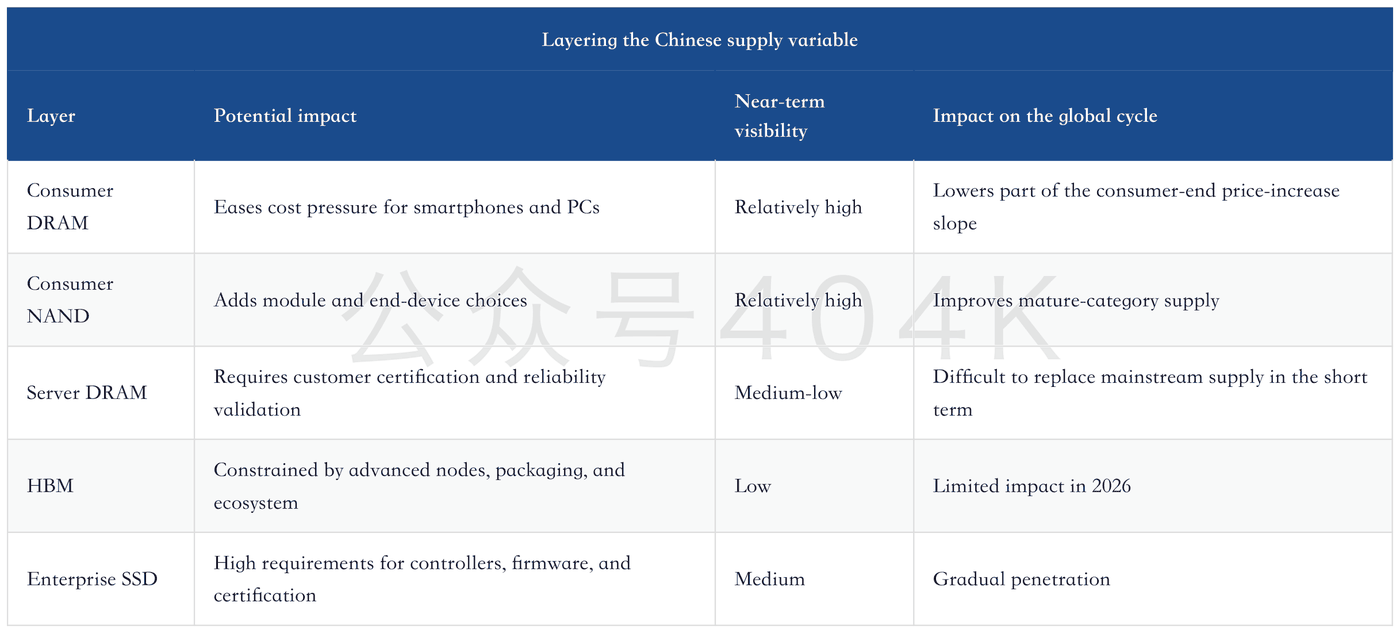
Therefore, Chinese capacity expansion is an important constraint after prices rise, but it is still unlikely to directly fill the global high-end memory gap in 2026. It will make it harder for memory vendors to raise consumer-end prices without limit and will make customer negotiations more complex. But AI server, cloud, and enterprise-storage customers still depend on advanced capacity and long-term contracts from mainstream original vendors. For Chinese supply to truly change the landscape, investors need to see high-end customer certification, volume shipments, and stable yields.
This variable matters for investment judgment. If Chinese supply quickly enters high-end servers and enterprise SSDs, the upward slope of global memory prices will be reduced. If Chinese supply mainly remains in mature and consumer categories, the tight balance in global DRAM and NAND will continue. Over the next few quarters, the most important questions are which customers, which specifications, and what shipment volumes Chinese suppliers enter. Total capacity plans should only be background context.
10. Three Worldviews: Supercycle, Capex Catch-Up, and Customer Backlash
Korea's US$3.1tn plan can be placed into three worldviews. The first is the supercycle worldview: AI demand continues to exceed expectations, memory supply remains structurally insufficient, Korea's expansion only catches up with demand, and both memory vendors and the equipment chain continue to benefit. The second is the capex catch-up worldview: 2026-2027 remains tight, supply gradually catches up after 2028, the equipment chain benefits first, and memory prices later normalize. The third is the customer-backlash worldview: prices rise too quickly, customers reduce configurations, qualify alternative supply, regulatory pressure increases, and memory valuations peak before profits.
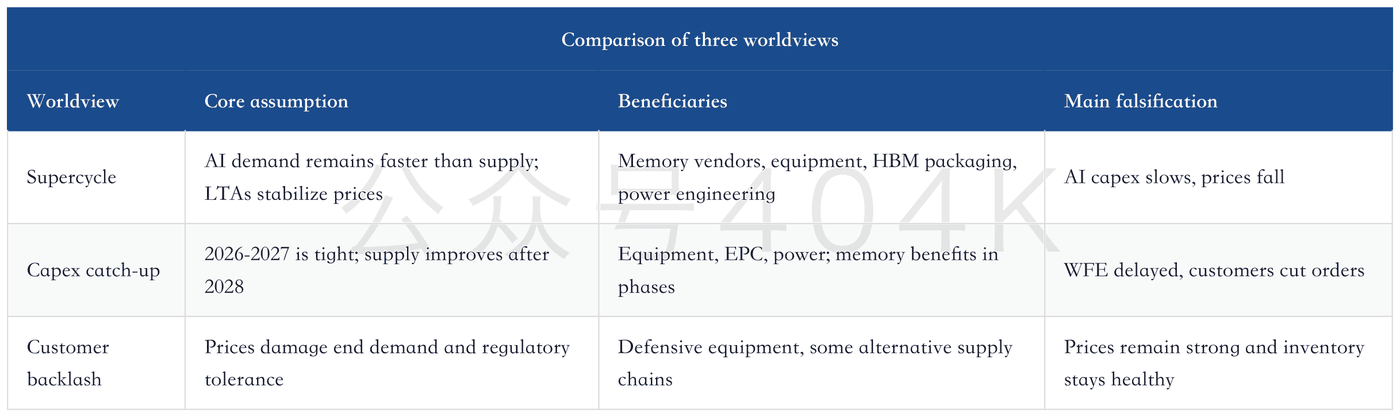
Current evidence is closer to the second worldview, while retaining upside optionality from the first. Supply-demand data support a continued gap in 2026-2027, and WFE upgrades also support capex catch-up. But customer pushback and litigation have already appeared, which means the third worldview cannot be ignored. The real point of debate is around 2028: if new capacity cannot keep up with AI demand, the supercycle continues; if supply catches up while demand slows, prices return to cyclicality.
The Second Engine of the Memory Supercycle: CPU Return, HBM Spillover, and a US$1.7tn TAM Revaluation
This framework is more useful than simply looking at target prices. Memory-vendor valuations come from prices and margins; equipment-company valuations come from capex visibility; engineering-company valuations come from fab and power project execution; customer-side valuations are affected by BOM pressure. A macro plan will have different directions and different rhythms across different assets.
11. Segment Ranking: Who Benefits First, and Who Comes Under Pressure First
From the perspective of verification cadence, semiconductor equipment and the engineering chain see positive feedback first. Memory vendors have already benefited on prices and profits. Consumer-electronics customers come under pressure first. Regulatory risk then accumulates gradually as a valuation discount. This ranking matters because the same event is realized across different segments on different timelines.
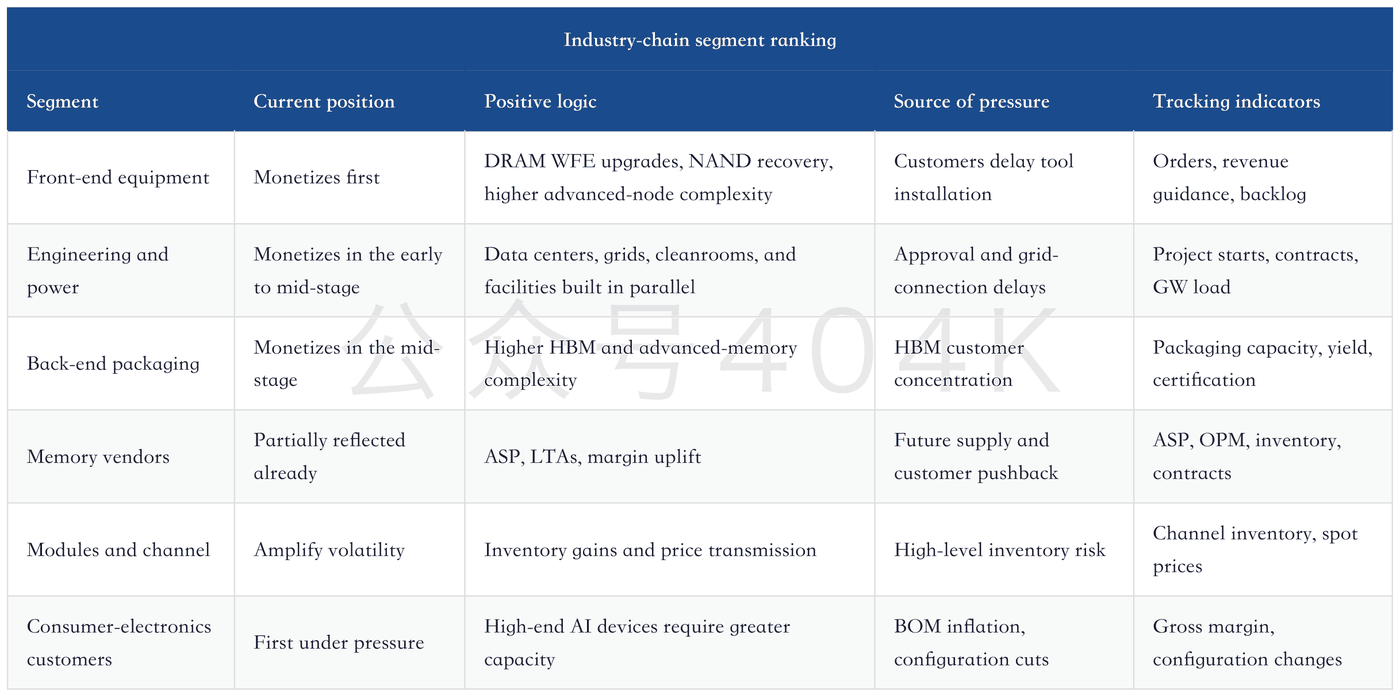
For investors, the most robust approach is to divide this chain into the "price side" and the "capex side." The price side is memory vendors: it has the greatest upside elasticity and is also most easily interrupted by customer pushback and supply expectations. The capex side is equipment, engineering, and power: it is less sensitive to near-term price volatility, but more sensitive to long-term WFE and project-start cadence.
JPMorgan's latest update also points more of the long-term positive impact toward semiconductor equipment, power infrastructure, and semiconductor EPC. That judgment makes sense. If Korea's plan is implemented, the first requirements are to buy equipment, build fabs, connect power, and package products. Memory vendors' prices and profits already reflect part of the expectation in the current cycle, and they now need LTAs and financial quality to prove durability.
Second Upgrade of the AI Hardware Cycle: Asia Tech Repricing in Memory, HBM, PCB, and MLCC
12. Core Model Table: Transmission From Investment Plan to Income Statement
Korea's US$3.1tn plan cannot be equated directly with memory-vendor revenue. It must pass through capex, equipment delivery, capacity ramp, customer certification, price negotiations, and inventory management before it finally enters the income statement. If any link in the middle falls behind, a long-term plan becomes short-term valuation noise.
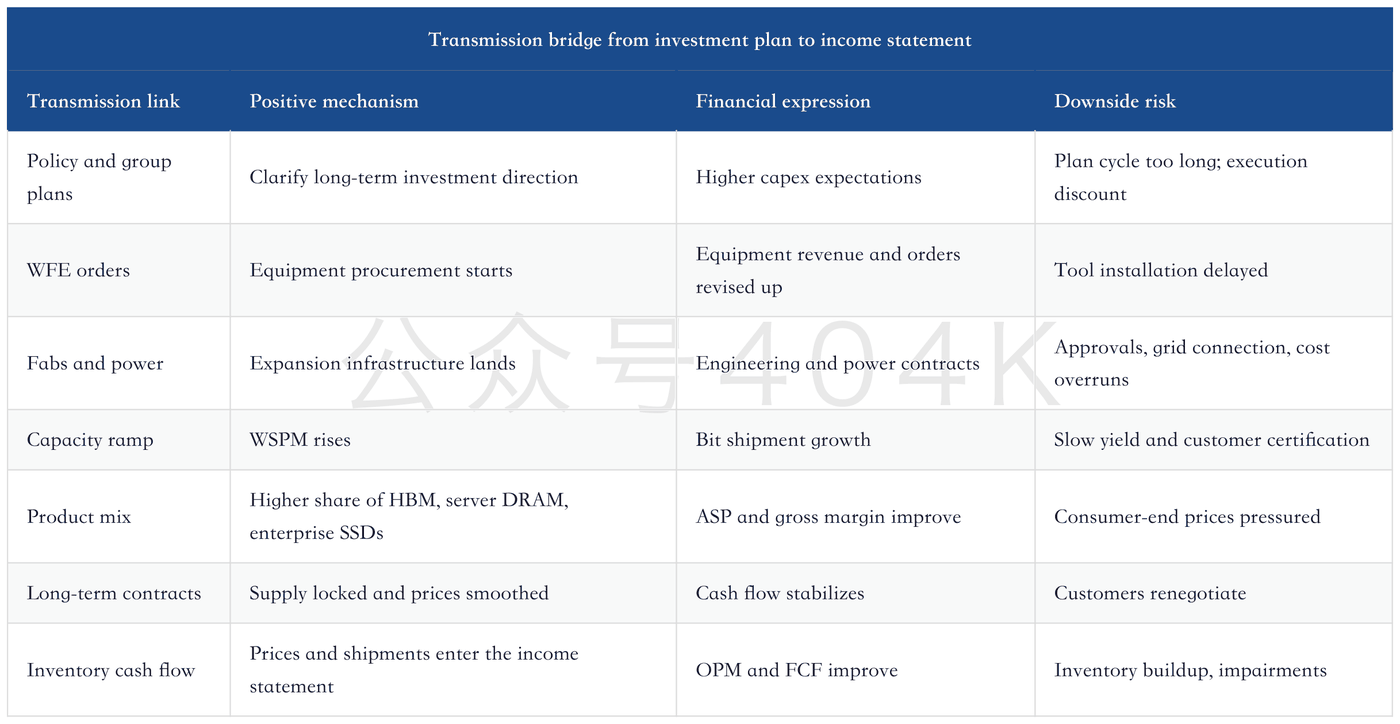
This bridge shows that the quality of the memory cycle should be judged by ASP, shipments, product mix, and cash flow at the same time. A high-quality upcycle should show price increases, shipment growth, product-mix improvement, more long-term contracts, and cash flow keeping pace. A low-quality upcycle may be only a short-term price pull and channel inventory gains. Whether Korea's plan can support long-term revaluation depends on whether it can turn supply shortages into stable contracts and a high-end product mix. A short-term surge in equipment orders alone is not enough.
From a company perspective, Samsung and SK Hynix face different biggest challenges. SK Hynix is stronger in HBM and high-end DRAM, with better pricing power and customer binding. Samsung has broader integrated manufacturing capacity, NAND, and system semiconductor resources, but needs to prove sustained improvement in HBM and advanced-memory competitiveness. Both companies require large-scale capex, but returns on capital depend on customer structure and product mix.
13. Cross-Checks From JPMorgan, Deutsche Bank, and Morgan Stanley
Reports from several institutions have different angles, but their conclusions overlap. JPMorgan focuses on long-term memory TAM and the revaluation of the industry profit pool by AI demand. Deutsche Bank focuses on the DRAM supply-demand model and WSPM expansion. Morgan Stanley focuses on WFE upgrades and allocation across the equipment chain. Putting the three together makes the significance of Korea's plan clearer.
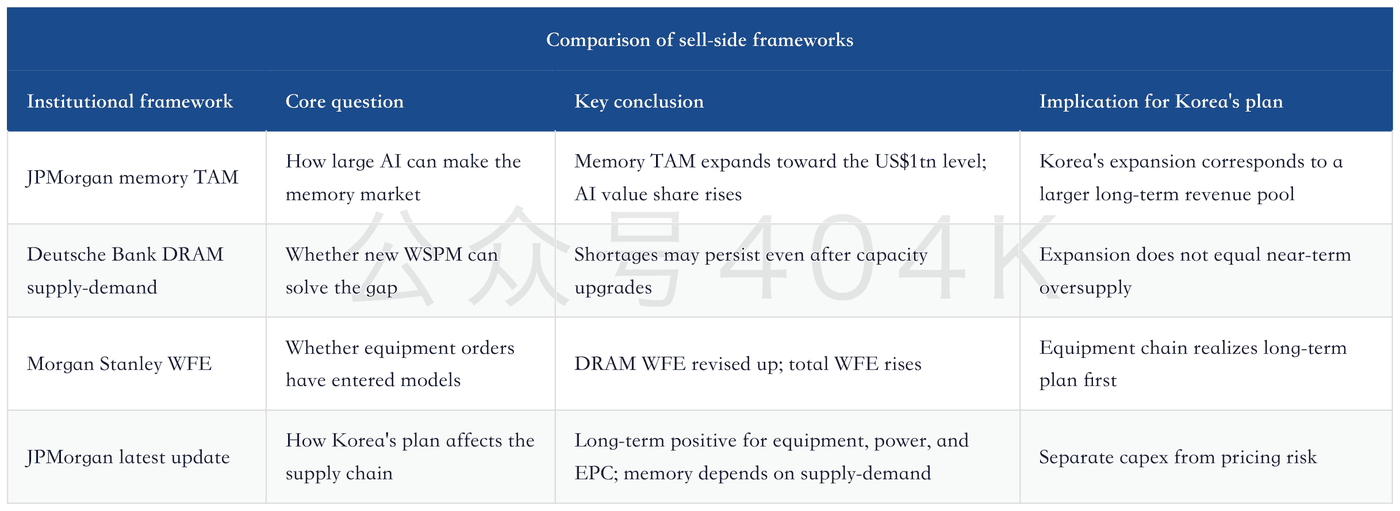
JPMorgan's long-term TAM framework provides the upside ceiling: if AI and Physical AI continue to raise memory-capacity demand, the memory industry's revenue pool will be far above the past 20 years. Deutsche Bank provides medium-term supply-demand evidence: even with higher new WSPM, demand growth may still exceed supply. Morgan Stanley provides equipment-side evidence: WFE forecasts have already started to reflect memory expansion.
The Memory Tax Keeps Rising: Memory Prices May Increase Sequentially for Two Consecutive Quarters in 2H This Year
Together, these three lines of evidence show that it is not suitable to view memory through a single-cycle model today. The traditional model would say prices are high and expansion is large, so a downturn lies ahead. The AI model would say demand is strong and supply is slow, so prices remain strong. The more robust approach is to separate time periods: in 2026-2027, look at prices and equipment orders; after 2028, look at whether new supply or AI demand moves faster.
14. Mapping Korea's Plan to Global Companies
This plan directly targets Korean companies, but its effects will spread across the global supply chain. Samsung and SK Hynix are the core investment entities. Semiconductor equipment companies take front-end spending; power and EPC companies take fab and data-center construction; packaging and materials companies take higher HBM and advanced-memory complexity; customers face higher memory procurement costs.
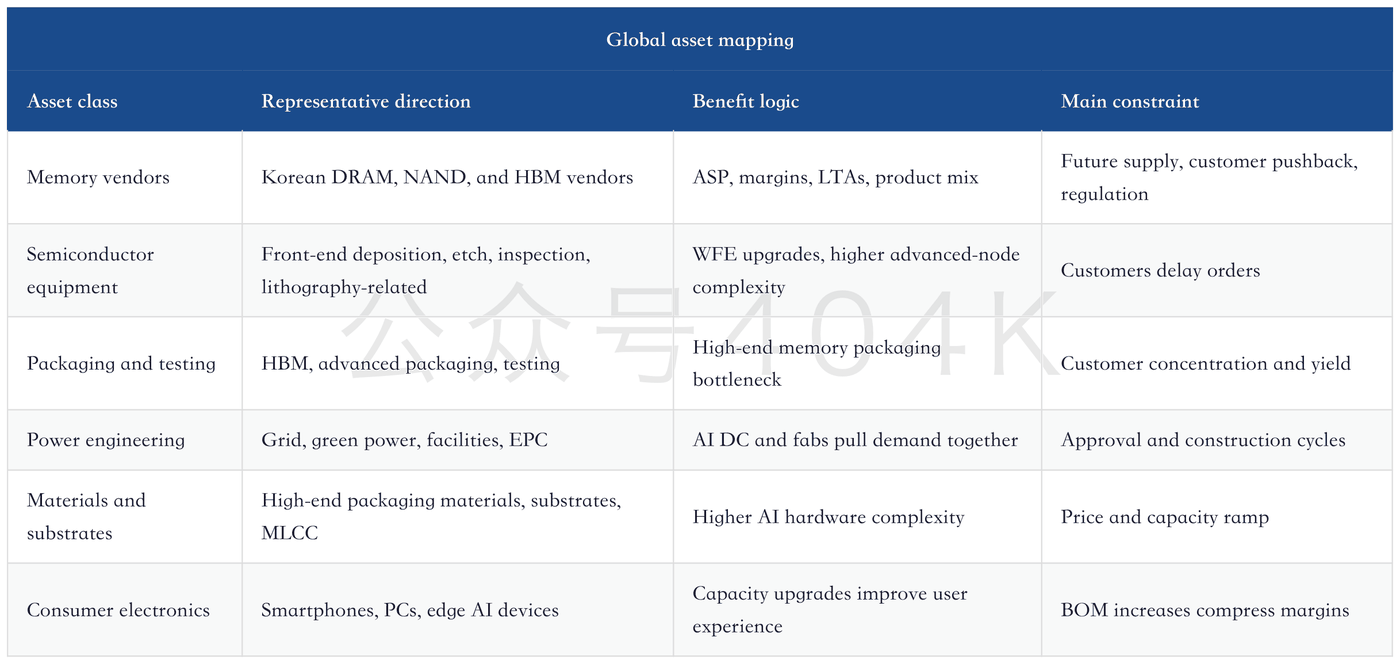
In this mapping, power and EPC should not be overlooked. AI data centers and memory fabs are both high-power-consumption and high-capital-intensity projects. Chip equipment alone cannot complete the buildout. Korea's plan places data-center GW-scale load and semiconductor capacity together, which means grids, green power, facilities systems, cooling, construction engineering, and supply-chain management all become part of semiconductor investment.
For memory vendors, the long-term plan is both an opportunity and a commitment. The opportunity is that demand is large enough for capex to have customer and national-strategy support. The commitment is that companies must bear higher depreciation, higher capital intensity, and longer construction cycles. If prices remain elevated, returns on capital are strong. If prices fall too quickly, depreciation and utilization will in turn pressure profits.
15. Prices, Long-Term Contracts, and Earnings Quality: What to Watch to Judge Cycle Health
The easiest mistake in memory is to look only at prices. Price increases can lift revenue and gross margins, but they do not alone prove cycle health. A healthy upcycle requires three conditions: customers are willing to sign long-term contracts, inventory has not lost control, and operating cash flow keeps up with profit. If only spot prices rise while channel inventory accumulates and customers delay orders, the cycle will be very fragile.
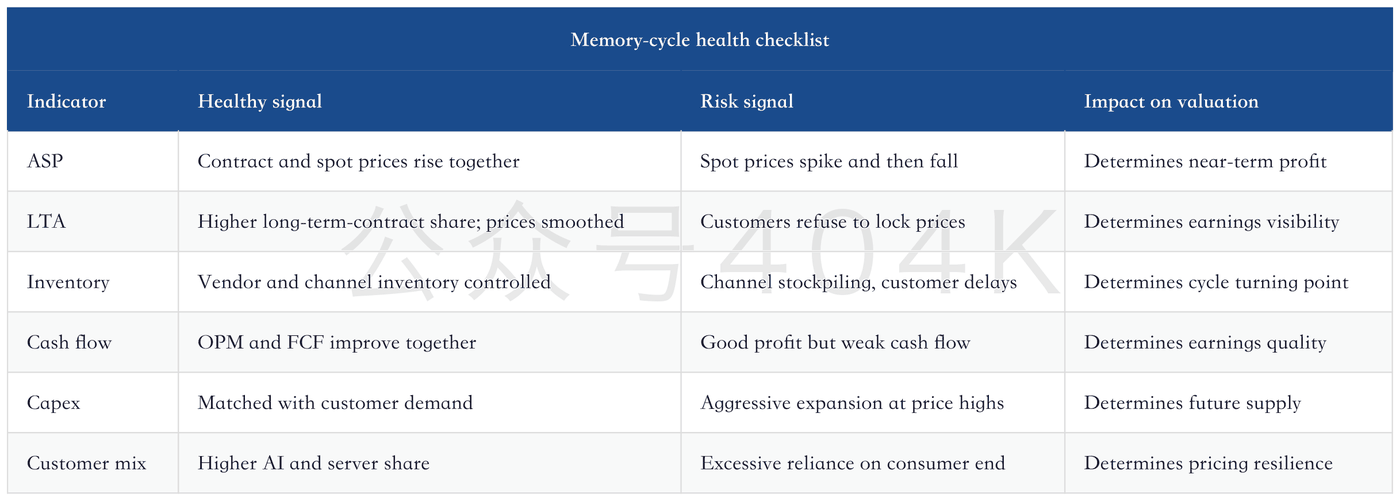
The strongest current signals are ASP and customer long-term contracts. The areas requiring the most caution are customer cost pressure and future capex. AI customers are willing to pay for stable supply, while consumer-electronics customers are more sensitive. The behavior of the two customer groups will differentiate memory vendors' product lines: HBM and server DRAM have higher earnings quality, while consumer DRAM and NAND price elasticity is more easily suppressed by customers.
Long-term contracts are one of the biggest differences between this cycle and past cycles. If memory vendors can use LTAs to bind prices, capacity, and customers, industry earnings will be smoother. If customers only accept high prices under shortage pressure, prices can fall very quickly once supply improves. The larger Korea's plan becomes, the more it needs matching long-term orders and customer commitments; otherwise capex can easily turn into future depreciation pressure.
16. Where Downstream Backlash Starts
Memory price increases usually hurt consumer electronics first, where gross margins are thinner, configurations are adjustable, and end demand is not strong. Smartphone and PC vendors can respond by reducing capacity, delaying upgrades, adjusting model mix, or pressuring suppliers on price. AI server and cloud customers have a harder time doing this because memory capacity directly affects model efficiency, server utilization, and overall TCO.
The downstream backlash chain roughly proceeds as follows: first procurement disputes and longer negotiations, then rising channel inventory, then end-device configuration reductions, and finally cuts to vendor orders and prices. The first-layer signals are already visible. The next question is whether they transmit into inventory and configurations. If they remain negotiation friction, memory vendors still have pricing power. If end-device configuration cuts and inventory buildup appear, cycle risk will rise materially.
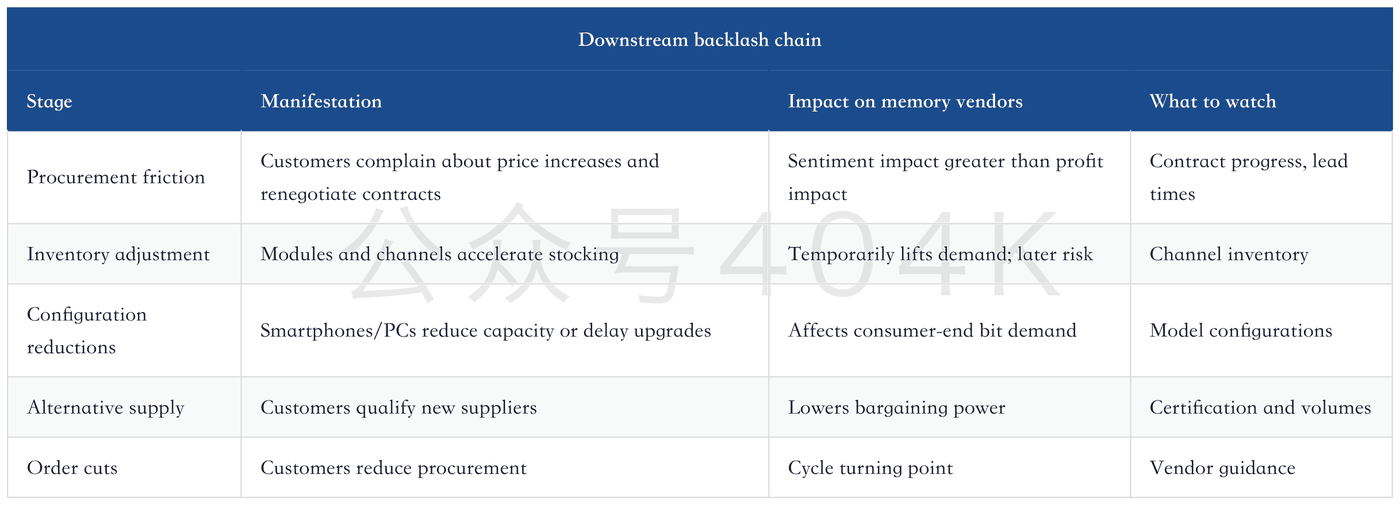
This is also why the next few quarters cannot be judged only by memory prices. Continued price increases are clearly positive for profits, but if customer configuration reductions, inventory increases, and weaker cash flow appear at the same time, the market will discount valuations early. Conversely, if price increases are accompanied by more long-term contracts, healthy inventory, and improved cash flow, then price increases look more like structural revaluation.
17. Data Framework: Which Numbers to Watch Over the Next Four Quarters
Korea's plan spans a long period, so each judgment cannot rely on the long-term total investment amount. Over the next four quarters, the useful data are short-cycle indicators: prices, orders, inventory, WFE, customer contracts, and cash flow. These data can show whether the long-term plan is becoming real revenue.
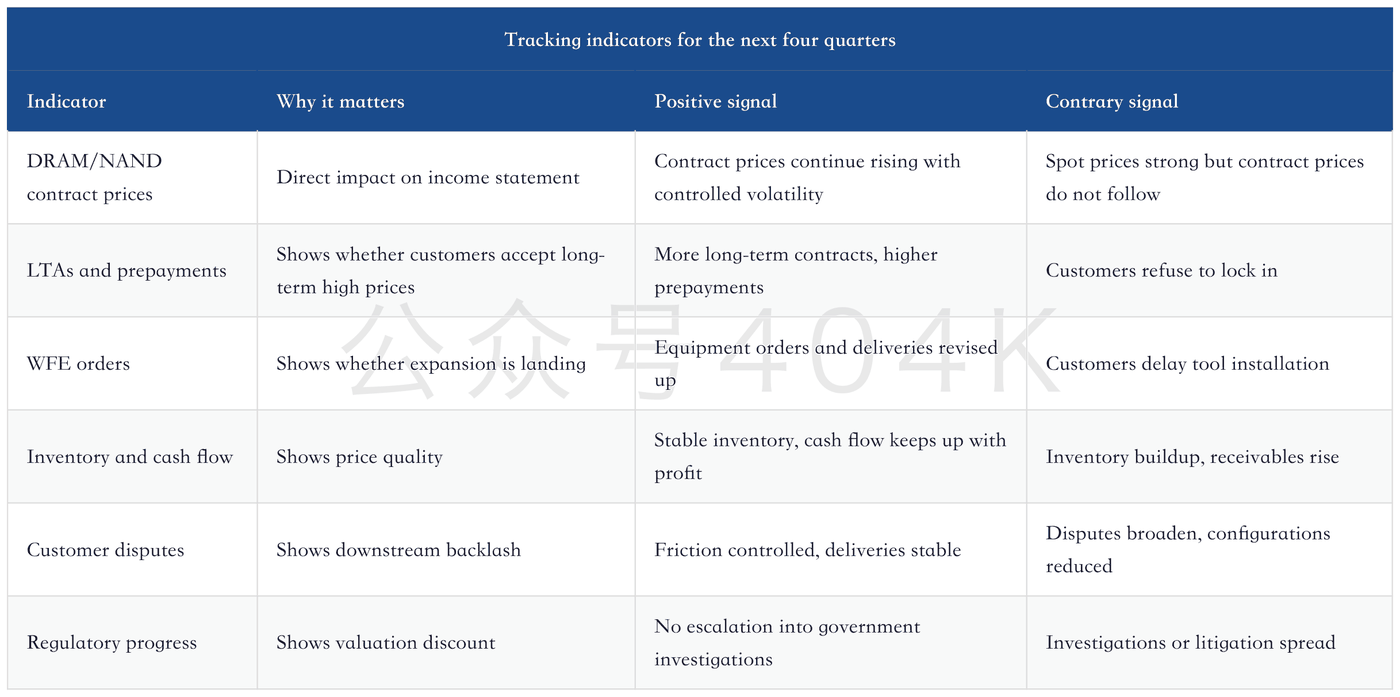
The order of these indicators also matters. Prices and orders change first; inventory and cash flow lag; customer configurations and regulatory risk lag further. Investment judgment needs to respect this time difference. If prices begin to fall while inventory is still rising, risk will amplify quickly. If prices remain strong, inventory is healthy, and WFE orders continue to be revised up, the cycle will last longer than the traditional model suggests.
For the equipment chain, WFE orders and customer installation cadence are most important. For memory vendors, ASP and LTAs are most important. For downstream customers, BOM and gross margins are most important. For engineering and power companies, project starts and grid connection are most important. Different assets have different verification indicators; the whole chain cannot be judged by the same price table.
18. Risk List: Where This Thesis Could Be Wrong
This update can be wrong in three main ways. First, AI demand could be lower than expected. If cloud vendors or AI application ROI deteriorates, memory demand will fall back from high growth, pressuring both prices and WFE. Second, supply could be released faster than expected. If related capacity in Korea, China, Japan, and the US accelerates simultaneously, supply risk around 2028 could enter valuations earlier. Third, customer and regulatory backlash could exceed expectations. If pricing disputes intensify, memory vendors' high gross margins will be offset by a higher discount rate.
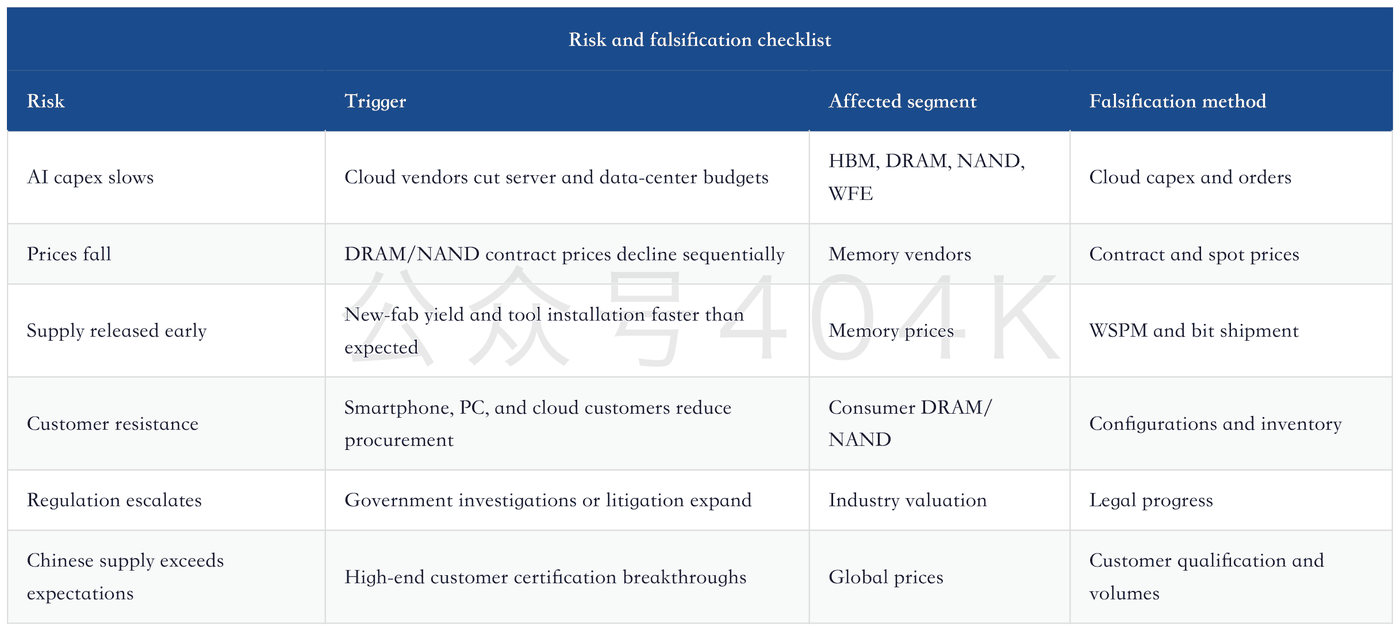
Another easily overlooked risk is architecture optimization. Customers will seek ways to reduce memory dependence, such as model compression, memory-expansion technologies, system-architecture adjustments, software optimization, and combinations of different storage tiers. If memory prices are too high, customers' incentive to optimize becomes stronger. This will not eliminate demand in the short term, but it will affect long-term capacity assumptions and the valuation ceiling.
Therefore, Korea's plan itself is only the beginning of higher capital intensity. It raises the verification requirements for the memory cycle. Memory vendors must prove that high prices can last. Equipment companies must prove that WFE orders are supported by customer demand. Customers must prove that AI commercialization can absorb higher BOM. The regulatory environment must prove that high profits will not be interrupted by legal risk.
19. Return on Capital: The US$3.1tn Plan Ultimately Lands in Depreciation and Cash Flow
Large investment plans are exciting, but they also make it easy to overlook depreciation. For memory vendors, capex creates real fixed costs. Once fabs, equipment, cleanrooms, and back-end packaging are built, they create years of depreciation pressure. Capex becomes a larger profit pool only if AI demand continues to absorb new supply and the product mix is high-end enough. Otherwise, today's expansion becomes fixed cost in a future downcycle.
This is why the memory industry often makes its most dangerous investment decisions during periods of high profit. High prices make companies more willing to expand, high gross margins make capital markets willing to provide capital, and customer shortages make long-term demand look certain. But fab construction cycles are long, and by the time capacity is truly released, the demand environment may have changed. Korea's plan has the advantage of being tied to AI data centers and national infrastructure, but that is also its weakness: the larger the project, the longer the execution cycle and the more future variables.
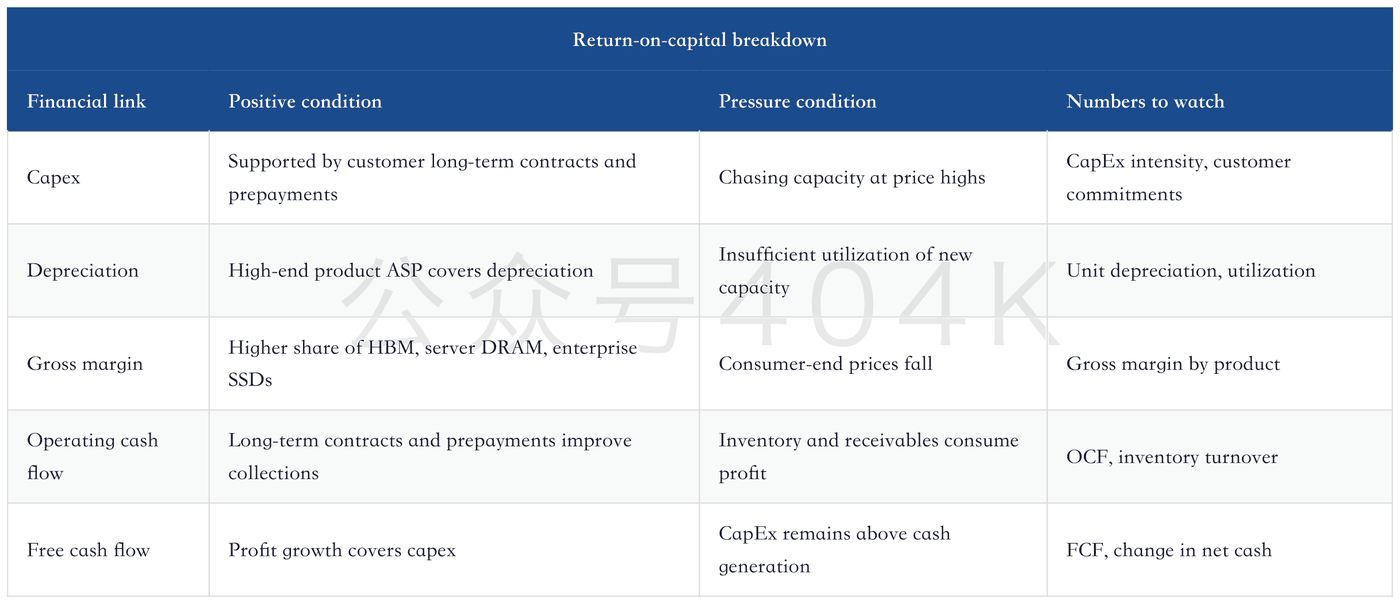
From this perspective, risk-reward is not fully synchronized between the equipment chain and memory vendors. Equipment companies receive orders first, and capex upgrades directly enter revenue expectations. Memory vendors enjoy prices first, while also bearing future depreciation and utilization risk. Engineering, power, and facilities companies sit between the two: project starts bring orders, but cost control and construction cycles affect margins.
For Korea's plan to become a genuine industry revaluation, three financial conditions must be met. First, memory vendors must maintain high cash flow during expansion and avoid letting capex tighten balance sheets. Second, after new capacity begins production, customer demand and product mix must absorb depreciation, especially with server DRAM, HBM, and enterprise NAND maintaining high shares. Third, long-term contracts and prepayment mechanisms must be mature enough that the industry is no longer fully dependent on spot prices.
It is also necessary to distinguish between the revenue pool and shareholder returns. JPMorgan's long-term framework emphasizes that the future memory revenue pool may expand sharply. That is an industry-level opportunity. But shareholder returns depend on each company's capital discipline, product mix, customer stickiness, and cash-flow management during expansion. A larger revenue pool does not automatically mean higher returns for every company. The real value lies in maintaining technology leadership, customer binding, and return on capital inside a large revenue pool.
Over the next few quarters, the most useful financial verification will be three small sets of numbers: first, whether memory vendors' depreciation, inventory, and operating cash flow are healthy together; second, whether equipment-company orders convert into revenue and gross profit; third, whether AI customers' long-term contracts can cover high capital intensity. If all three hold, Korea's plan will reinforce memory-asset revaluation. If only capex rises, the market will treat it as the next round of supply pressure.
20. Timing: Watch Prices in 2026, Orders in 2027, and Supply in 2028
The greatest danger in this thesis is mixing variables from different years. The core of 2026 is prices and customer contracts; the core of 2027 is equipment orders and engineering construction; the core after 2028 is new supply and depreciation pressure. If 2030s fab plans are used directly to explain 2026 prices, investors will become bearish too early. If 2026 price strength is extrapolated directly to 2030, investors will underestimate capex and supply release.
The memory industry's cadence usually has five steps. First, prices rise and vendor margins improve rapidly. Second, customers lock supply, and LTAs, prepayments, and long-term purchase agreements increase. Third, vendors raise capex, and equipment and engineering companies receive orders first. Fourth, capacity ramps and new WSPM enters bit supply. Fifth, prices are repriced, and the market checks whether new supply, customer demand, and depreciation pressure are aligned.
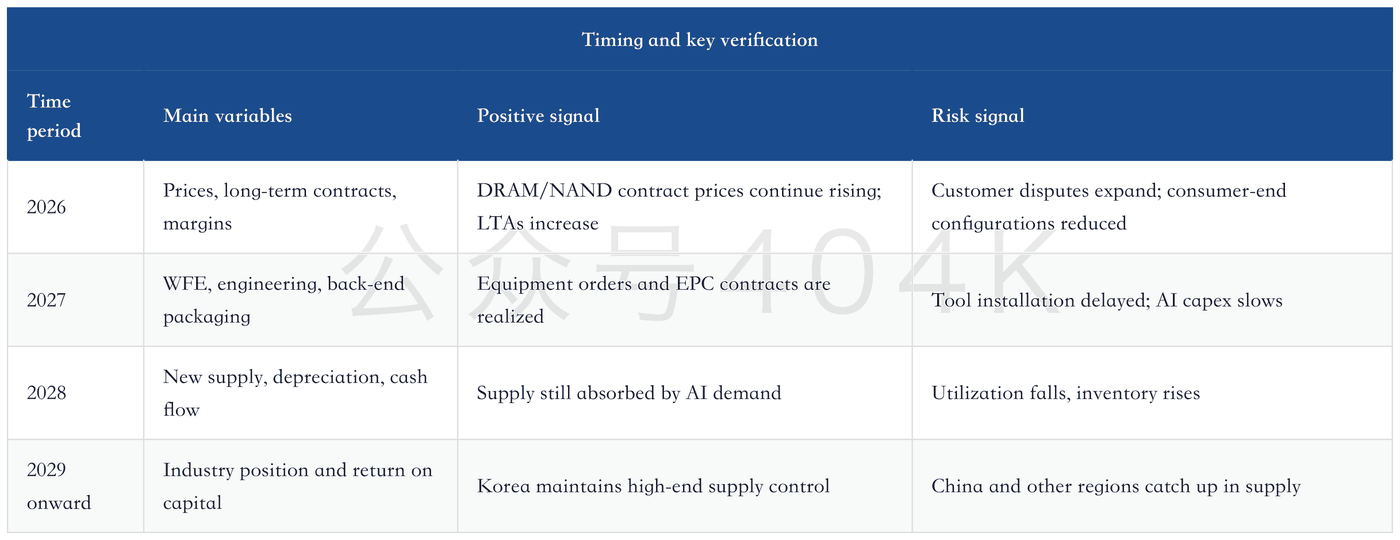
This cadence matters for valuation. In 2026, memory vendors are more like earnings-upgrade assets, with the market watching ASP, OPM, and cash flow. In 2027, equipment orders and capex will become the market's main line, while memory-vendor valuations start to discuss supply release. In 2028, whether new capacity can be absorbed by AI demand will determine whether the industry enters a longer supercycle or returns to a traditional cyclical downturn.
The equipment chain runs earlier. Once equipment orders are confirmed, revenue and backlog appear earlier than new wafer capacity. Engineering and power projects also appear before memory bit supply because fabs must first complete facilities, cleanrooms, power, and water-treatment systems. Back-end packaging sits between the two: it must follow HBM customer demand and is also affected by advanced-memory yield and packaging capacity.
The customer-side cadence is later, but it can change market sentiment early. Customer procurement disputes, BOM pressure, and litigation will not immediately change memory-vendor profits, but they will raise valuation discounts. If customer pushback stays at the negotiation level, vendors can still maintain pricing. If customers start adjusting configurations, cutting orders, and qualifying alternative supply, the price cycle will flatten earlier.
Therefore, research on this thesis needs a dashboard by year. In 2026, first check whether prices continue to flow through the income statement. In 2027, check whether WFE and engineering orders are realized. In 2028, check whether new capacity, utilization, and depreciation are absorbed by demand. As long as years and variables are matched clearly, Korea's US$3.1tn plan will not be misread as a single positive or single negative.
21. Valuation Discount: How the Market Will Reprice the Memory Cycle
The biggest change in memory valuation is that the market is moving from a "peak-earnings discount" toward a coexistence of "supply-franchise premium" and "regulatory discount." In traditional memory cycles, the higher profits became, the more the market worried about the downturn, so P/E multiples were often low. The difference in the AI era is that if customers lock supply through long-term contracts, peak profits are no longer merely a one-quarter price spike and may instead become multi-year cash flow.
Valuation re-rating requires three pieces of evidence. First, the supply franchise is durable, expressed through customer long-term contracts, prepayments, stable delivery, and product certification. Second, returns on capital are durable, expressed through high-margin products covering depreciation and capex. Third, regulatory and customer pressure is manageable, expressed through pricing disputes not escalating into demand destruction. Without any one of these pieces of evidence, the market will treat high profits as a cyclical peak.
The valuation discount can be broken into five variables. Earnings visibility depends on LTAs and customer supply locks; if customers refuse to lock prices, the central P/E level will fall. Return on capital depends on whether high-end products can cover depreciation; excessive CapEx intensity will lower ROIC assumptions. Supply discipline depends on whether new capacity is released according to demand; large-scale disorderly expansion will amplify the cycle discount again.
The other two variables come from customers and regulation. Customer acceptance depends on whether AI value can absorb BOM increases; if end-device configurations are reduced, the revenue slope will be affected first. Regulatory risk depends on whether litigation expands and whether pricing is transparent; if investigations or penalties escalate, the market will immediately raise the risk premium. Together, these five variables determine whether memory vendors' high profits can move from cyclical peak to long-term cash flow.
This also explains why valuation logic differs across assets even when all are bullish on memory. Memory vendors need to prove through earnings quality that this cycle is longer. Equipment companies need orders to prove that capex is supported by demand. Power and EPC companies need project starts to prove that AI infrastructure construction is real. Customer-side companies need to prove that memory BOM increases will not consume their own gross margins. Every segment benefits from AI, but the pricing variables are entirely different.
The most reasonable valuation stance today is to give full weight to near-term earnings upgrades while retaining room for long-term supply and regulatory discounts. If prices, LTAs, WFE, and cash flow are all strong in 2026-2027, memory vendors will continue to earn premiums. If prices are strong but customer pushback and inventory rise at the same time, the market will compress valuations early. If equipment orders are strong but memory prices are weak, the equipment chain will continue to outperform memory vendors.
Therefore, the long-term value of Korea's US$3.1tn plan is not in the total amount itself, but in whether it can push Korea's memory industry from cyclical price assets toward AI infrastructure supply-franchise assets. Supply-franchise assets can command higher valuations, but they also carry higher capital intensity, greater regulatory attention, and stronger customer bargaining power. That balance is the core of the memory trade over the next several years.
22. Conclusion: The Memory Supercycle Enters the "Supply-Franchise Verification Period"
Korea's US$3.1tn AI investment plan pushes the memory industry from a simple price-increase logic into a supply-franchise verification period. In the short term, DRAM and NAND supply-demand gaps still support prices, while equipment and engineering chains see capex upgrades first. In the medium term, new WSPM, HBM back-end packaging, AI data centers, and power construction will determine whether supply can catch up with demand. In the long term, customer pushback, regulatory risk, and Chinese supply will determine whether high profits can be capitalized.
The final judgment of this report can be condensed into one sentence: Korea's plan uses decade-scale capex to compete for memory supply franchise in the AI era, and it will not immediately break the memory shortage in the short term. This supply franchise will appear first in equipment, facilities, power, and EPC orders; then in advanced-memory and NAND capacity; and finally in the industry profit pool and valuation framework.
For investment research, the most important point is not to read a long-term plan as a single-direction event. A bullish view on memory prices requires verification of the 2026-2027 supply-demand gap and LTAs. A bullish view on the equipment chain requires verification of WFE orders and tool installation. A bullish view on engineering and power requires verification of data-center and fab starts. Concern about a cycle reversal requires watching customer pushback, inventory, and regulation. Only if these indicators improve together can the memory supercycle move from a price trade to asset revaluation.
All follow-up judgments should return to five verification lines: first, whether DRAM and NAND prices continue rising and contract prices can keep up; second, whether WFE orders and Korean projects proceed as planned; third, whether memory vendors' inventory and cash flow are healthy; fourth, whether customer cost pressure remains only at the negotiation level; and fifth, whether regulation and litigation do not escalate. As long as these five lines do not weaken at the same time, Korea's US$3.1tn plan will remain one of the most important long-term variables in the AI hardware cycle.Memory Deep-Dive Update: Korea’s US$3.1tn AI Investment Plan and How to Revalue DRAM, NAND, and the Equipment Chain
目录
Too Long; Didn’t Read
1. Start With the Conclusion: Korea Is Turning the Memory Shortage Into a National Capex Cycle
2. What the US$3.1tn Plan Actually Contains
3. Why the Market Is Not Buying It in the Short Term
4. The Supply-Demand Math: Expansion Is Large, but the Gap Is Faster
5. The Equipment Chain Monetizes Before Memory Prices
6. The DRAM, NAND, and HBM Gaps Must Be Viewed Separately
7. Pricing Power Enters a High-Pressure Zone: Customers Start to Push Back
8. Regulatory Risk: Class Actions Can Change the Valuation Discount
9. The Chinese Supply Variable: A Price Buffer, but Unlikely to Fill the High-End Gap in the Short Term
10. Three Worldviews: Supercycle, Capex Catch-Up, and Customer Backlash
11. Segment Ranking: Who Benefits First, and Who Comes Under Pressure First
12. Core Model Table: Transmission From Investment Plan to Income Statement
13. Cross-Checks From JPMorgan, Deutsche Bank, and Morgan Stanley
14. Mapping Korea’s Plan to Global Companies
15. Prices, Long-Term Contracts, and Earnings Quality: What to Watch to Judge Cycle Health
16. Where Downstream Backlash Starts
17. Data Framework: Which Numbers to Watch Over the Next Four Quarters
18. Risk List: Where This Thesis Could Be Wrong
19. Return on Capital: The US$3.1tn Plan Ultimately Lands in Depreciation and Cash Flow
20. Timing: Watch Prices in 2026, Orders in 2027, and Supply in 2028
21. Valuation Discount: How the Market Will Reprice the Memory Cycle
22. Conclusion: The Memory Supercycle Enters the “Supply-Franchise Verification Period”
本内容基于公开资料和研报数据整理,不构成任何投资建议,不代表任何个人观点,仅供学习参考,请理性阅读
Korea is putting memory capacity expansion, AI data centers, and Physical AI onto the same capital-spending roadmap. The market is worried in the near term that new supply could undermine pricing, but the research focus should fall on four variables: the supply-demand gap, equipment orders, customer cost pressure, and regulatory risk. This report breaks the US$3.1tn plan into four verification lines: DRAM, NAND, WFE, and power engineering.
Too Long; Didn’t Read
Korea plans to elevate the memory shortage into a national capital-spending cycle. The long-term projects disclosed by Samsung, SK, and the Korean government total roughly US$3.1tn, covering fabs, AI data centers, power infrastructure, HBM back-end packaging, Physical AI, and semiconductor engineering capabilities. The stock market is worried in the short term that capacity expansion will pressure prices. For research, the more important question is when added capacity becomes effective supply.
The supply-demand gap remains the main pricing driver in 2026-2027. JPMorgan and Deutsche Bank both expect DRAM and NAND shortages to extend beyond 2027, mainly because AI servers, Agentic AI, and edge devices jointly raise memory capacity demand. Even if new WSPM is revised up meaningfully, advanced nodes, HBM conversion losses, cleanroom constraints, and power bottlenecks will still slow effective supply.
The equipment and engineering chains will recognize orders first. Front-end wafer equipment accounts for the largest share of Korea’s long-term plan, followed by cleanrooms, power, EPC, and back-end packaging. Morgan Stanley has already raised its 2026-2027 DRAM WFE forecasts, showing that capex is moving from narrative into orders and deliveries.
Memory vendors are entering a high-pressure pricing-power zone. Pricing disputes between Apple and Micron, BOM pressure in consumer electronics, and US consumer litigation all show that memory price increases have already passed from inside the supply chain to end customers. Pricing power remains in the hands of memory vendors, but customer pushback, regulatory scrutiny, and alternative supply are becoming more important.
Chinese supply is a buffer, but it is unlikely to rewrite the high-end shortage in the short term. Chinese DRAM and NAND capacity expansion will ease part of the pricing pressure in consumer electronics and mature products, but server-grade DRAM, HBM, enterprise SSDs, LPDDR, and high-reliability supply certification cannot be completed overnight. For the global memory cycle, Chinese supply is more like a marginal buffer after prices rise.
The investment mapping should be layered, not limited to memory vendors. Memory manufacturers benefit from ASP and margin expansion; semiconductor equipment benefits from WFE upgrades; power and data-center engineering benefit from AI load buildout; packaging and substrates benefit from higher HBM and advanced-memory complexity. Key follow-up indicators are DRAM/NAND prices, the WSPM cadence, WFE orders, customer disputes, and inventory cash flow.
1. Start With the Conclusion: Korea Is Turning the Memory Shortage Into a National Capex Cycle
The key implication of Korea’s latest AI and semiconductor investment plan is that the memory cycle is moving from a pricing cycle into an infrastructure cycle. Over the past two years, the market mainly watched DRAM, HBM, and NAND quotations. It now also needs to track fabs, back-end packaging, AI data centers, power facilities, and semiconductor engineering delivery. Prices remain important, but variables beyond prices are starting to determine the length of the cycle.
The plan is large because Korea is addressing three issues together. The first is insufficient memory supply, especially as AI servers, HBM, LPDDR, enterprise SSDs, and commodity DRAM all consume capacity at the same time. The second is that AI data-center construction requires stable power and infrastructure; memory expansion cannot be separated from grids, land, cleanrooms, and engineering capacity. The third is that Korea needs to maintain its global leadership in memory and avoid having the US, Taiwan, mainland China, and Japan rewrite supply-chain roles in the new AI capex cycle.
The market’s short-term response has been cautious, and that is normal. Every major expansion in the history of the memory industry has raised the same question: will today’s high prices be pushed down by future capacity? But this time cannot be judged only through the old-cycle framework. In the old cycle, demand mainly came from PCs, smartphones, and conventional servers, and prices would fall quickly once supply came online. In the new cycle, AI training, inference, Agentic AI, Physical AI, sovereign AI, and edge devices are all raising memory capacity requirements, while supply growth and demand growth are racing on the same timetable.
The Memory Tax Has Arrived: How AI Is Turning HBM, DRAM, and NAND Into a Global Macro Bottleneck
The core view of this update is straightforward: Korea’s US$3.1tn AI investment plan will raise the long-term supply ceiling, but it will not immediately break the memory shortage in 2026-2027. In the first two years, it is more likely to appear first in orders for equipment, engineering, power, and back-end packaging; in the medium term, it will show up as new wafer supply; only in the long term will it determine whether Korean memory vendors can turn the AI era’s high capital intensity into more stable long-term revenue.
In other words, this event should not simply be classified as “capacity expansion is bearish for memory prices.” A more accurate research framework has three layers: first, look at prices and judge how long memory vendors can maintain high gross margins; second, look at capex and judge whether orders for the equipment and engineering chains can be delivered; third, look at customers and regulation and judge whether price increases are starting to hurt end demand and social acceptance. Only if all three layers hold can the memory supercycle move from a price-hike story to long-term asset revaluation.
2. What the US$3.1tn Plan Actually Contains
The headline amount in Korea’s plan looks exaggerated, but the logic is not complicated once broken down. It consists of three categories of government-led mega projects: semiconductors, AI robotics, and AI data centers. It also includes long-term capex by companies such as Samsung and SK. The focus is a full set of national industrial capabilities: memory manufacturing, packaging, computing power, electricity, and industrial AI.
The most important point here is the “pull-forward” of the timetable. Korea plans to move the production timeline for advanced Yongin fabs significantly forward from the mid-to-late 2040s into the 2030s. The signal is clear: Korean memory vendors view memory demand over the next decade as part of AI infrastructure. PC and smartphone restocking alone cannot support capex of this scale.
From a capex structure perspective, front-end wafer equipment is the largest component, cleanrooms and infrastructure sit in the middle, and back-end packaging is smaller in share but more strategic. Front-end equipment determines wafer capacity; cleanrooms and power determine whether fabs can start on time; back-end packaging determines whether HBM, advanced memory, and high-performance-computing customers can receive usable products. The memory industry was often treated in the past as a “price-cycle stock.” It now looks increasingly like the intersection of energy, compute, and manufacturing capability.
A US$700bn-Plus AI Wager: SK Hynix, Samsung, and the Korean Government’s Aggressive Bet on Compute Infrastructure
This also explains why semiconductors, data centers, and Physical AI all appear in Korea’s plan at the same time. Semiconductors provide supply, data centers provide the demand anchor, and Physical AI provides the long-term application scenario. In the traditional memory cycle, demand came from consumer devices. In the AI era, demand comes from compute nodes, inference tasks, robots, and industrial systems. The more demand resembles infrastructure, the more the supply side needs long-term planning.
3. Why the Market Is Not Buying It in the Short Term
Korean memory stocks have reacted cautiously to this type of news, with capacity expansion as the obvious surface reason. The memory industry is most afraid of high prices attracting every vendor to expand capacity, followed a few years later by concentrated supply release and a rapid fall in prices from elevated levels. When investors see a US$3.1tn long-term plan, their first reaction is naturally to worry that today’s strong pricing power will be diluted by future capacity.
That concern is reasonable, but it does not directly support a bearish conclusion. Capex has different meanings at different points in the cycle. Early-cycle expansion is usually demand confirmation, showing that customers are willing to sign long-term contracts and that prices can cover investment returns. Late-cycle expansion is more dangerous because it often happens when prices are strongest, profits are best, and companies are most prone to overconfidence. The memory industry today sits between the two: prices and profits are already strong, but the supply gap is also genuinely real.
The current stage looks more like a strong mid-cycle. DRAM and NAND prices have already risen, HBM and server memory supply is tight, enterprise SSD demand is improving, and customer acceptance of higher prices is starting to decline. This stage is most likely to produce two types of market action: the equipment chain continues to benefit from upgraded order visibility, while memory vendors start to face valuation discounts because prices are already elevated.
Therefore, the trading implication of this plan is asset divergence. Equipment, EPC, power, and back-end packaging benefit more directly. The benefit to memory vendors depends on price durability, customer contracts, inventory, and regulatory risk. Investors who look only at the words “capacity expansion” will miss opportunities in the equipment chain; investors who look only at the word “shortage” will underestimate future supply and customer-pushback risks.
4. The Supply-Demand Math: Expansion Is Large, but the Gap Is Faster
To judge the memory cycle, the most important step is to separate “planned capacity” from “effective supply.” Planned capacity is the fabs, cleanrooms, and equipment budgets announced by companies. Effective supply is the bits that can actually be delivered after construction, equipment installation, yield ramp, and customer certification. The two are usually separated by several years, as well as by power, land, equipment lead times, talent, and customer qualification.
JPMorgan’s latest update still shows DRAM and NAND demand growth exceeding shipment growth in 2026 and 2027. Deutsche Bank’s DRAM supply-demand model goes further: even after raising new WSPM for the next five years, DRAM shortages may still persist into 2028 or beyond. The reason is that AI servers and Agentic AI are raising demand for conventional DRAM, while HBM consumes advanced wafer resources and creates “lost bits.”
This table explains why the market can worry about expansion while still chasing memory price increases. In 2026-2027, the near-term supply-demand gap is not covered by new capacity. After 2028, the risk of supply catching up will start to enter models more clearly. In other words, the key trading window today is not “whether Korea expands capacity,” but “whether that capacity can truly become supply before prices roll over.”
Memory Is No Longer Just Cyclical: JPM LTA Breakdown, Agentic AI Memory Multipliers, and the Valuation Rewrite for Samsung and SK Hynix
AI’s pull on memory is not limited to HBM. The market previously concentrated AI memory demand too heavily on HBM and overlooked the pull from CPU servers, inference clusters, Agentic AI, edge devices, and enterprise SSDs on conventional DRAM, LPDDR, NAND, and controllers. Deutsche Bank has particularly emphasized higher DRAM capacity in CPU-only AI racks, while JPMorgan also views agents and Physical AI as sources of the next stage of memory demand.
This means memory supply tightness comes from multiple product lines simultaneously consuming equipment, wafers, advanced packaging, and customer budgets. Strong HBM prices will encourage vendors to shift advanced DRAM resources toward HBM, making conventional DRAM supply even tighter. Strong enterprise SSD demand will lift the value of high-layer-count NAND and controllers, while consumer NAND will also be affected by upstream supply discipline. Korea’s capacity expansion can ease this problem, but not in 1H26.
5. The Equipment Chain Monetizes Before Memory Prices
If the question is who benefits first from Korea’s plan, the answer is likely equipment, cleanrooms, EPC, power, and back-end packaging. The earnings of memory vendors are jointly affected by prices and supply expectations. The equipment chain, by contrast, sees capex budgets, tenders, orders, deliveries, and revenue recognition. The earlier capex starts, the earlier the equipment chain has numbers to verify.
Morgan Stanley has already raised its DRAM WFE forecast. It upgraded DRAM fab equipment spending for 2026 and 2027 and believes total WFE will also rise. This change matters: it shows that AI memory shortages are not only a pricing-side phenomenon, but have already begun to enter revenue models for equipment companies and the supply chain. NAND WFE is also improving, but DRAM remains the more direct source of upward revision.
The investment logic for the equipment chain has two layers. The first is near-term orders: higher DRAM WFE directly raises revenue expectations for equipment companies. The second is long-term capital intensity: HBM, advanced DRAM, high-layer-count NAND, and advanced packaging all raise equipment investment per unit of capacity. AI memory does not just require more wafers; it requires more complex processes, stricter yield control, and greater test and packaging capability.
From HBM to WFE: How AI Is Pushing the Memory Cycle Into an Equipment Supercycle, and How Much Further Semiconductor Equipment Can Rise
But the equipment chain cannot be extrapolated without limit. Equipment orders ultimately depend on memory customers’ cash flow, price expectations, and long-term demand assumptions. If DRAM or NAND prices fall earlier than expected in 2027, customers may delay some tool installations. If AI capex slows, WFE upgrades will become high-base pressure. The best scenario for the equipment chain is that prices remain strong but do not spiral out of control, customers have enough profit to continue expanding, and downstream buyers are willing to lock supply through long-term contracts.
Therefore, equipment-chain verification should focus on two numbers: orders and shipments. Orders show that customers are willing to invest; shipments show that capacity construction has truly entered execution. Looking only at WFE forecasts can miss engineering and installation cadence; looking only at near-term equipment-company revenue can underestimate the risk that memory customers may later delay expansion.
6. The DRAM, NAND, and HBM Gaps Must Be Viewed Separately
One misconception in this memory upcycle is treating all shortages as the same kind of shortage. DRAM, NAND, and HBM are all tight, but the reasons, beneficiaries, price transmission, and risks are different. HBM is tied to advanced packaging and AI GPUs; DRAM is jointly driven by servers, CPUs, PCs, smartphones, and edge AI; NAND is more affected by enterprise SSDs, QLC, nearline storage substitution, and supply discipline.
HBM is the strongest narrative, but conventional DRAM is the larger supply-demand account. HBM production consumes advanced DRAM wafers and reduces effective bit supply because of higher complexity. Even though HBM revenue itself is high, it also makes ordinary DRAM tighter. This spillover effect is what the market has repeatedly underestimated over the past two years.
NAND’s logic is more about storage architecture. AI data-center training and inference will raise demand for high-speed storage and nearline storage, while enterprise SSD capacity upgrades will also raise the value of high-layer-count NAND. If HDD supply, performance, or lead times cannot meet data-center requirements, part of demand will migrate to SSDs. NAND vendors have restrained capex in recent years, and with demand recovering, price elasticity may be stronger than in the traditional consumer NAND cycle.
Global Memory Deep Dive: 2Q26 Earnings Divergence, and Whether 3Q Pricing Improvement Can Restart Memory-Stock Revaluation
Therefore, Korea’s plan affects the three product types differently. For HBM, it strengthens back-end packaging and advanced-memory supply capability. For conventional DRAM, it raises long-term WSPM, but near-term effective supply is still constrained by ramp. For NAND, it may raise enterprise SSD supply, while customer certification and capital discipline may still maintain pricing resilience. Mixing the three together only understates the differentiation.
7. Pricing Power Enters a High-Pressure Zone: Customers Start to Push Back
When memory prices rise to a certain stage, supply-chain tensions shift from “vendor earnings recovery” to “customer cost pressure.” The pricing dispute between Apple and Micron is one signal. Smartphone, PC, and consumer-electronics brands are highly sensitive to BOM. When DRAM and flash prices rise rapidly, customers begin to demand longer payment terms, more stable quotations, more supplier choices, and may even shift procurement strategies toward Chinese supply chains.
Suppliers have their own logic as well. During the previous downcycle, memory vendors absorbed losses, production cuts, and inventory write-downs. Now that demand is strong and supply is tight, vendors naturally want to reclaim prices and profits. Customers feel prices are rising too quickly; suppliers feel they were squeezed for too long in the past. This divergence makes contract negotiations tougher. The memory industry is not only a technology business, but also a business of capacity and bargaining power.
Customer pushback affects products differently. AI server and cloud customers are more able to accept price increases for HBM, server DRAM, and enterprise SSDs because memory costs remain necessary relative to system value, model revenue, and compute utilization. Consumer-electronics customers are more sensitive to LPDDR, mobile NAND, and PC DRAM because end-device prices are difficult to raise in step. The higher prices rise, the clearer the demand segmentation becomes.
This is also why LPDDR may remain strong, while risks are rising. AI smartphones, edge AI, and high-end consumer electronics will increase memory capacity and support LPDDR prices. But consumer-electronics brands have limited gross margins and pricing power. The faster prices rise, the more incentive customers have to optimize configurations, delay procurement, or qualify alternative suppliers. The best state for memory vendors is to turn high prices into stable cash flow through long-term contracts.
8. Regulatory Risk: Class Actions Can Change the Valuation Discount
US consumer class-action litigation against the three major DRAM vendors remains at the private-litigation stage and has not yet escalated into a government investigation or a concluded antitrust case. But it shows one fact: when memory prices become an important variable in consumer-electronics prices and AI infrastructure costs, industry pricing behavior draws greater public attention. The more memory resembles a strategic resource, the harder it becomes to ignore regulatory and legal risks.
Historically, the DRAM industry has indeed faced antitrust and price-fixing cases. Penalties and guilty pleas in earlier cases left a psychological overhang for today’s market; supply-restriction controversies around 2016-2017 did not reach the same conclusion. For investors, the key is whether regulatory risk changes the valuation discount rate. Historical cases only provide a reference point for risk.
This type of risk affects the industry on three levels. The first is sentiment: litigation and media reports make the market worry that price increases are unsustainable. The second is behavior: memory vendors become more cautious in public statements, contract arrangements, and supply discipline. The third is valuation: if government investigations or coordinated customer pushback intensify, the market will apply a higher discount to high gross margins even if near-term profits remain strong.
This does not change the near-term supply-demand gap, but it affects the capitalization of long-term pricing power. If memory vendors rely only on price increases, valuations will be constrained by regulation and customer pushback. If they can prove earnings quality through LTAs, prepayments, high-end product certification, and stable supply capability, the market will be more willing to view high gross margins as structural improvement.
9. The Chinese Supply Variable: A Price Buffer, but Unlikely to Fill the High-End Gap in the Short Term
Every time memory prices rise sharply, the market asks whether Chinese supply can change the landscape. This question needs a layered answer. In mature DRAM, consumer NAND, modules, and parts of mobile storage, the Chinese supply chain will gain more customer qualification opportunities and provide a buffer during the price-up phase. But server-grade DRAM, HBM, enterprise SSDs, high-end LPDDR, and AI customer certification require more time.
The most direct role of Chinese supply is to give consumer-electronics customers another bargaining chip. If Apple, US PC brands, and Android smartphone vendors face memory price increases, they can test more suppliers, raise domestic-substitution ratios, or use multi-supplier strategies to pressure prices. But that does not mean the global supply-demand balance immediately reverses. The real shortage is often usable supply for specific specifications, specific reliability requirements, specific delivery schedules, and specific customer certifications.
Therefore, Chinese capacity expansion is an important constraint after prices rise, but it is still unlikely to directly fill the global high-end memory gap in 2026. It will make it harder for memory vendors to raise consumer-end prices without limit and will make customer negotiations more complex. But AI server, cloud, and enterprise-storage customers still depend on advanced capacity and long-term contracts from mainstream original vendors. For Chinese supply to truly change the landscape, investors need to see high-end customer certification, volume shipments, and stable yields.
This variable matters for investment judgment. If Chinese supply quickly enters high-end servers and enterprise SSDs, the upward slope of global memory prices will be reduced. If Chinese supply mainly remains in mature and consumer categories, the tight balance in global DRAM and NAND will continue. Over the next few quarters, the most important questions are which customers, which specifications, and what shipment volumes Chinese suppliers enter. Total capacity plans should only be background context.
10. Three Worldviews: Supercycle, Capex Catch-Up, and Customer Backlash
Korea’s US$3.1tn plan can be placed into three worldviews. The first is the supercycle worldview: AI demand continues to exceed expectations, memory supply remains structurally insufficient, Korea’s expansion only catches up with demand, and both memory vendors and the equipment chain continue to benefit. The second is the capex catch-up worldview: 2026-2027 remains tight, supply gradually catches up after 2028, the equipment chain benefits first, and memory prices later normalize. The third is the customer-backlash worldview: prices rise too quickly, customers reduce configurations, qualify alternative supply, regulatory pressure increases, and memory valuations peak before profits.
Current evidence is closer to the second worldview, while retaining upside optionality from the first. Supply-demand data support a continued gap in 2026-2027, and WFE upgrades also support capex catch-up. But customer pushback and litigation have already appeared, which means the third worldview cannot be ignored. The real point of debate is around 2028: if new capacity cannot keep up with AI demand, the supercycle continues; if supply catches up while demand slows, prices return to cyclicality.
The Second Engine of the Memory Supercycle: CPU Return, HBM Spillover, and a US$1.7tn TAM Revaluation
This framework is more useful than simply looking at target prices. Memory-vendor valuations come from prices and margins; equipment-company valuations come from capex visibility; engineering-company valuations come from fab and power project execution; customer-side valuations are affected by BOM pressure. A macro plan will have different directions and different rhythms across different assets.
11. Segment Ranking: Who Benefits First, and Who Comes Under Pressure First
From the perspective of verification cadence, semiconductor equipment and the engineering chain see positive feedback first. Memory vendors have already benefited on prices and profits. Consumer-electronics customers come under pressure first. Regulatory risk then accumulates gradually as a valuation discount. This ranking matters because the same event is realized across different segments on different timelines.
For investors, the most robust approach is to divide this chain into the “price side” and the “capex side.” The price side is memory vendors: it has the greatest upside elasticity and is also most easily interrupted by customer pushback and supply expectations. The capex side is equipment, engineering, and power: it is less sensitive to near-term price volatility, but more sensitive to long-term WFE and project-start cadence.
JPMorgan’s latest update also points more of the long-term positive impact toward semiconductor equipment, power infrastructure, and semiconductor EPC. That judgment makes sense. If Korea’s plan is implemented, the first requirements are to buy equipment, build fabs, connect power, and package products. Memory vendors’ prices and profits already reflect part of the expectation in the current cycle, and they now need LTAs and financial quality to prove durability.
Second Upgrade of the AI Hardware Cycle: Asia Tech Repricing in Memory, HBM, PCB, and MLCC
12. Core Model Table: Transmission From Investment Plan to Income Statement
Korea’s US$3.1tn plan cannot be equated directly with memory-vendor revenue. It must pass through capex, equipment delivery, capacity ramp, customer certification, price negotiations, and inventory management before it finally enters the income statement. If any link in the middle falls behind, a long-term plan becomes short-term valuation noise.
This bridge shows that the quality of the memory cycle should be judged by ASP, shipments, product mix, and cash flow at the same time. A high-quality upcycle should show price increases, shipment growth, product-mix improvement, more long-term contracts, and cash flow keeping pace. A low-quality upcycle may be only a short-term price pull and channel inventory gains. Whether Korea’s plan can support long-term revaluation depends on whether it can turn supply shortages into stable contracts and a high-end product mix. A short-term surge in equipment orders alone is not enough.
From a company perspective, Samsung and SK Hynix face different biggest challenges. SK Hynix is stronger in HBM and high-end DRAM, with better pricing power and customer binding. Samsung has broader integrated manufacturing capacity, NAND, and system semiconductor resources, but needs to prove sustained improvement in HBM and advanced-memory competitiveness. Both companies require large-scale capex, but returns on capital depend on customer structure and product mix.
13. Cross-Checks From JPMorgan, Deutsche Bank, and Morgan Stanley
Reports from several institutions have different angles, but their conclusions overlap. JPMorgan focuses on long-term memory TAM and the revaluation of the industry profit pool by AI demand. Deutsche Bank focuses on the DRAM supply-demand model and WSPM expansion. Morgan Stanley focuses on WFE upgrades and allocation across the equipment chain. Putting the three together makes the significance of Korea’s plan clearer.
JPMorgan’s long-term TAM framework provides the upside ceiling: if AI and Physical AI continue to raise memory-capacity demand, the memory industry’s revenue pool will be far above the past 20 years. Deutsche Bank provides medium-term supply-demand evidence: even with higher new WSPM, demand growth may still exceed supply. Morgan Stanley provides equipment-side evidence: WFE forecasts have already started to reflect memory expansion.
The Memory Tax Keeps Rising: Memory Prices May Increase Sequentially for Two Consecutive Quarters in 2H This Year
Together, these three lines of evidence show that it is not suitable to view memory through a single-cycle model today. The traditional model would say prices are high and expansion is large, so a downturn lies ahead. The AI model would say demand is strong and supply is slow, so prices remain strong. The more robust approach is to separate time periods: in 2026-2027, look at prices and equipment orders; after 2028, look at whether new supply or AI demand moves faster.
14. Mapping Korea’s Plan to Global Companies
This plan directly targets Korean companies, but its effects will spread across the global supply chain. Samsung and SK Hynix are the core investment entities. Semiconductor equipment companies take front-end spending; power and EPC companies take fab and data-center construction; packaging and materials companies take higher HBM and advanced-memory complexity; customers face higher memory procurement costs.
In this mapping, power and EPC should not be overlooked. AI data centers and memory fabs are both high-power-consumption and high-capital-intensity projects. Chip equipment alone cannot complete the buildout. Korea’s plan places data-center GW-scale load and semiconductor capacity together, which means grids, green power, facilities systems, cooling, construction engineering, and supply-chain management all become part of semiconductor investment.
For memory vendors, the long-term plan is both an opportunity and a commitment. The opportunity is that demand is large enough for capex to have customer and national-strategy support. The commitment is that companies must bear higher depreciation, higher capital intensity, and longer construction cycles. If prices remain elevated, returns on capital are strong. If prices fall too quickly, depreciation and utilization will in turn pressure profits.
15. Prices, Long-Term Contracts, and Earnings Quality: What to Watch to Judge Cycle Health
The easiest mistake in memory is to look only at prices. Price increases can lift revenue and gross margins, but they do not alone prove cycle health. A healthy upcycle requires three conditions: customers are willing to sign long-term contracts, inventory has not lost control, and operating cash flow keeps up with profit. If only spot prices rise while channel inventory accumulates and customers delay orders, the cycle will be very fragile.
The strongest current signals are ASP and customer long-term contracts. The areas requiring the most caution are customer cost pressure and future capex. AI customers are willing to pay for stable supply, while consumer-electronics customers are more sensitive. The behavior of the two customer groups will differentiate memory vendors’ product lines: HBM and server DRAM have higher earnings quality, while consumer DRAM and NAND price elasticity is more easily suppressed by customers.
Long-term contracts are one of the biggest differences between this cycle and past cycles. If memory vendors can use LTAs to bind prices, capacity, and customers, industry earnings will be smoother. If customers only accept high prices under shortage pressure, prices can fall very quickly once supply improves. The larger Korea’s plan becomes, the more it needs matching long-term orders and customer commitments; otherwise capex can easily turn into future depreciation pressure.
16. Where Downstream Backlash Starts
Memory price increases usually hurt consumer electronics first, where gross margins are thinner, configurations are adjustable, and end demand is not strong. Smartphone and PC vendors can respond by reducing capacity, delaying upgrades, adjusting model mix, or pressuring suppliers on price. AI server and cloud customers have a harder time doing this because memory capacity directly affects model efficiency, server utilization, and overall TCO.
The downstream backlash chain roughly proceeds as follows: first procurement disputes and longer negotiations, then rising channel inventory, then end-device configuration reductions, and finally cuts to vendor orders and prices. The first-layer signals are already visible. The next question is whether they transmit into inventory and configurations. If they remain negotiation friction, memory vendors still have pricing power. If end-device configuration cuts and inventory buildup appear, cycle risk will rise materially.
This is also why the next few quarters cannot be judged only by memory prices. Continued price increases are clearly positive for profits, but if customer configuration reductions, inventory increases, and weaker cash flow appear at the same time, the market will discount valuations early. Conversely, if price increases are accompanied by more long-term contracts, healthy inventory, and improved cash flow, then price increases look more like structural revaluation.
17. Data Framework: Which Numbers to Watch Over the Next Four Quarters
Korea’s plan spans a long period, so each judgment cannot rely on the long-term total investment amount. Over the next four quarters, the useful data are short-cycle indicators: prices, orders, inventory, WFE, customer contracts, and cash flow. These data can show whether the long-term plan is becoming real revenue.
The order of these indicators also matters. Prices and orders change first; inventory and cash flow lag; customer configurations and regulatory risk lag further. Investment judgment needs to respect this time difference. If prices begin to fall while inventory is still rising, risk will amplify quickly. If prices remain strong, inventory is healthy, and WFE orders continue to be revised up, the cycle will last longer than the traditional model suggests.
For the equipment chain, WFE orders and customer installation cadence are most important. For memory vendors, ASP and LTAs are most important. For downstream customers, BOM and gross margins are most important. For engineering and power companies, project starts and grid connection are most important. Different assets have different verification indicators; the whole chain cannot be judged by the same price table.
18. Risk List: Where This Thesis Could Be Wrong
This update can be wrong in three main ways. First, AI demand could be lower than expected. If cloud vendors or AI application ROI deteriorates, memory demand will fall back from high growth, pressuring both prices and WFE. Second, supply could be released faster than expected. If related capacity in Korea, China, Japan, and the US accelerates simultaneously, supply risk around 2028 could enter valuations earlier. Third, customer and regulatory backlash could exceed expectations. If pricing disputes intensify, memory vendors’ high gross margins will be offset by a higher discount rate.
Another easily overlooked risk is architecture optimization. Customers will seek ways to reduce memory dependence, such as model compression, memory-expansion technologies, system-architecture adjustments, software optimization, and combinations of different storage tiers. If memory prices are too high, customers’ incentive to optimize becomes stronger. This will not eliminate demand in the short term, but it will affect long-term capacity assumptions and the valuation ceiling.
Therefore, Korea’s plan itself is only the beginning of higher capital intensity. It raises the verification requirements for the memory cycle. Memory vendors must prove that high prices can last. Equipment companies must prove that WFE orders are supported by customer demand. Customers must prove that AI commercialization can absorb higher BOM. The regulatory environment must prove that high profits will not be interrupted by legal risk.
19. Return on Capital: The US$3.1tn Plan Ultimately Lands in Depreciation and Cash Flow
Large investment plans are exciting, but they also make it easy to overlook depreciation. For memory vendors, capex creates real fixed costs. Once fabs, equipment, cleanrooms, and back-end packaging are built, they create years of depreciation pressure. Capex becomes a larger profit pool only if AI demand continues to absorb new supply and the product mix is high-end enough. Otherwise, today’s expansion becomes fixed cost in a future downcycle.
This is why the memory industry often makes its most dangerous investment decisions during periods of high profit. High prices make companies more willing to expand, high gross margins make capital markets willing to provide capital, and customer shortages make long-term demand look certain. But fab construction cycles are long, and by the time capacity is truly released, the demand environment may have changed. Korea’s plan has the advantage of being tied to AI data centers and national infrastructure, but that is also its weakness: the larger the project, the longer the execution cycle and the more future variables.
From this perspective, risk-reward is not fully synchronized between the equipment chain and memory vendors. Equipment companies receive orders first, and capex upgrades directly enter revenue expectations. Memory vendors enjoy prices first, while also bearing future depreciation and utilization risk. Engineering, power, and facilities companies sit between the two: project starts bring orders, but cost control and construction cycles affect margins.
For Korea’s plan to become a genuine industry revaluation, three financial conditions must be met. First, memory vendors must maintain high cash flow during expansion and avoid letting capex tighten balance sheets. Second, after new capacity begins production, customer demand and product mix must absorb depreciation, especially with server DRAM, HBM, and enterprise NAND maintaining high shares. Third, long-term contracts and prepayment mechanisms must be mature enough that the industry is no longer fully dependent on spot prices.
It is also necessary to distinguish between the revenue pool and shareholder returns. JPMorgan’s long-term framework emphasizes that the future memory revenue pool may expand sharply. That is an industry-level opportunity. But shareholder returns depend on each company’s capital discipline, product mix, customer stickiness, and cash-flow management during expansion. A larger revenue pool does not automatically mean higher returns for every company. The real value lies in maintaining technology leadership, customer binding, and return on capital inside a large revenue pool.
Over the next few quarters, the most useful financial verification will be three small sets of numbers: first, whether memory vendors’ depreciation, inventory, and operating cash flow are healthy together; second, whether equipment-company orders convert into revenue and gross profit; third, whether AI customers’ long-term contracts can cover high capital intensity. If all three hold, Korea’s plan will reinforce memory-asset revaluation. If only capex rises, the market will treat it as the next round of supply pressure.
20. Timing: Watch Prices in 2026, Orders in 2027, and Supply in 2028
The greatest danger in this thesis is mixing variables from different years. The core of 2026 is prices and customer contracts; the core of 2027 is equipment orders and engineering construction; the core after 2028 is new supply and depreciation pressure. If 2030s fab plans are used directly to explain 2026 prices, investors will become bearish too early. If 2026 price strength is extrapolated directly to 2030, investors will underestimate capex and supply release.
The memory industry’s cadence usually has five steps. First, prices rise and vendor margins improve rapidly. Second, customers lock supply, and LTAs, prepayments, and long-term purchase agreements increase. Third, vendors raise capex, and equipment and engineering companies receive orders first. Fourth, capacity ramps and new WSPM enters bit supply. Fifth, prices are repriced, and the market checks whether new supply, customer demand, and depreciation pressure are aligned.
This cadence matters for valuation. In 2026, memory vendors are more like earnings-upgrade assets, with the market watching ASP, OPM, and cash flow. In 2027, equipment orders and capex will become the market’s main line, while memory-vendor valuations start to discuss supply release. In 2028, whether new capacity can be absorbed by AI demand will determine whether the industry enters a longer supercycle or returns to a traditional cyclical downturn.
The equipment chain runs earlier. Once equipment orders are confirmed, revenue and backlog appear earlier than new wafer capacity. Engineering and power projects also appear before memory bit supply because fabs must first complete facilities, cleanrooms, power, and water-treatment systems. Back-end packaging sits between the two: it must follow HBM customer demand and is also affected by advanced-memory yield and packaging capacity.
The customer-side cadence is later, but it can change market sentiment early. Customer procurement disputes, BOM pressure, and litigation will not immediately change memory-vendor profits, but they will raise valuation discounts. If customer pushback stays at the negotiation level, vendors can still maintain pricing. If customers start adjusting configurations, cutting orders, and qualifying alternative supply, the price cycle will flatten earlier.
Therefore, research on this thesis needs a dashboard by year. In 2026, first check whether prices continue to flow through the income statement. In 2027, check whether WFE and engineering orders are realized. In 2028, check whether new capacity, utilization, and depreciation are absorbed by demand. As long as years and variables are matched clearly, Korea’s US$3.1tn plan will not be misread as a single positive or single negative.
21. Valuation Discount: How the Market Will Reprice the Memory Cycle
The biggest change in memory valuation is that the market is moving from a “peak-earnings discount” toward a coexistence of “supply-franchise premium” and “regulatory discount.” In traditional memory cycles, the higher profits became, the more the market worried about the downturn, so P/E multiples were often low. The difference in the AI era is that if customers lock supply through long-term contracts, peak profits are no longer merely a one-quarter price spike and may instead become multi-year cash flow.
Valuation re-rating requires three pieces of evidence. First, the supply franchise is durable, expressed through customer long-term contracts, prepayments, stable delivery, and product certification. Second, returns on capital are durable, expressed through high-margin products covering depreciation and capex. Third, regulatory and customer pressure is manageable, expressed through pricing disputes not escalating into demand destruction. Without any one of these pieces of evidence, the market will treat high profits as a cyclical peak.
The valuation discount can be broken into five variables. Earnings visibility depends on LTAs and customer supply locks; if customers refuse to lock prices, the central P/E level will fall. Return on capital depends on whether high-end products can cover depreciation; excessive CapEx intensity will lower ROIC assumptions. Supply discipline depends on whether new capacity is released according to demand; large-scale disorderly expansion will amplify the cycle discount again.
The other two variables come from customers and regulation. Customer acceptance depends on whether AI value can absorb BOM increases; if end-device configurations are reduced, the revenue slope will be affected first. Regulatory risk depends on whether litigation expands and whether pricing is transparent; if investigations or penalties escalate, the market will immediately raise the risk premium. Together, these five variables determine whether memory vendors’ high profits can move from cyclical peak to long-term cash flow.
This also explains why valuation logic differs across assets even when all are bullish on memory. Memory vendors need to prove through earnings quality that this cycle is longer. Equipment companies need orders to prove that capex is supported by demand. Power and EPC companies need project starts to prove that AI infrastructure construction is real. Customer-side companies need to prove that memory BOM increases will not consume their own gross margins. Every segment benefits from AI, but the pricing variables are entirely different.
The most reasonable valuation stance today is to give full weight to near-term earnings upgrades while retaining room for long-term supply and regulatory discounts. If prices, LTAs, WFE, and cash flow are all strong in 2026-2027, memory vendors will continue to earn premiums. If prices are strong but customer pushback and inventory rise at the same time, the market will compress valuations early. If equipment orders are strong but memory prices are weak, the equipment chain will continue to outperform memory vendors.
Therefore, the long-term value of Korea’s US$3.1tn plan is not in the total amount itself, but in whether it can push Korea’s memory industry from cyclical price assets toward AI infrastructure supply-franchise assets. Supply-franchise assets can command higher valuations, but they also carry higher capital intensity, greater regulatory attention, and stronger customer bargaining power. That balance is the core of the memory trade over the next several years.
22. Conclusion: The Memory Supercycle Enters the “Supply-Franchise Verification Period”
Korea’s US$3.1tn AI investment plan pushes the memory industry from a simple price-increase logic into a supply-franchise verification period. In the short term, DRAM and NAND supply-demand gaps still support prices, while equipment and engineering chains see capex upgrades first. In the medium term, new WSPM, HBM back-end packaging, AI data centers, and power construction will determine whether supply can catch up with demand. In the long term, customer pushback, regulatory risk, and Chinese supply will determine whether high profits can be capitalized.
The final judgment of this report can be condensed into one sentence: Korea’s plan uses decade-scale capex to compete for memory supply franchise in the AI era, and it will not immediately break the memory shortage in the short term. This supply franchise will appear first in equipment, facilities, power, and EPC orders; then in advanced-memory and NAND capacity; and finally in the industry profit pool and valuation framework.
For investment research, the most important point is not to read a long-term plan as a single-direction event. A bullish view on memory prices requires verification of the 2026-2027 supply-demand gap and LTAs. A bullish view on the equipment chain requires verification of WFE orders and tool installation. A bullish view on engineering and power requires verification of data-center and fab starts. Concern about a cycle reversal requires watching customer pushback, inventory, and regulation. Only if these indicators improve together can the memory supercycle move from a price trade to asset revaluation.
All follow-up judgments should return to five verification lines: first, whether DRAM and NAND prices continue rising and contract prices can keep up; second, whether WFE orders and Korean projects proceed as planned; third, whether memory vendors’ inventory and cash flow are healthy; fourth, whether customer cost pressure remains only at the negotiation level; and fifth, whether regulation and litigation do not escalate. As long as these five lines do not weaken at the same time, Korea’s US$3.1tn plan will remain one of the most important long-term variables in the AI hardware cycle.