
Memory Deep Dive Update: 3Q26 DDR Price Increase of 32%, 2027 DRAM Demand +36%; UBS Monthly Report Calibrates the Memory Supercycle
目录
Too Long; Didn’t Read
I. This Monthly Report Is Not a Repeat of the July 4 Report; It Moves from Framework to Validation
II. 3Q26 Price Revisions Are the Hardest New Evidence in This Monthly Report
III. The Key to the DRAM Model Is Not a Strong 2026, but Continued Acceleration in 2027
IV. The Key HBM Update Is Not Volume, but Customer Diversification from Nvidia to TPU and ASIC
V. LTA Moves From Valuation Concept to 3Q26 Negotiation Variable
VI. NAND Signals in the Monthly Report Are Strong, but Sustainability Still Requires Stricter Scrutiny Than DDR
VII. Vendor Ranking: Samsung Electronics Is Breadth, SK Hynix Is Purity, Micron Technology Is the SCA Case Study, and Kioxia Holdings Is NAND Beta
VIII. The Stronger the Bull Case, the Less Customer Affordability Risk Can Be Downplayed
IX. Over the Next Four Quarters, Trading Memory Needs to Move from “Watching Prices” to “Watching the Evidence Chain”
本内容基于公开资料和研报数据整理,不构成任何投资建议,不代表任何个人观点,仅供学习参考,请理性阅读
UBS’s July memory monthly report does not introduce a new logic. Instead, it pushes the AI memory framework from the July 4 deep dive into the price-verification phase: 3Q26 DDR and NAND estimates are revised up again, while the 2027 DRAM demand gap, multi-customer HBM procurement, and LTA terms are beginning to determine whether memory stocks can shift from a cyclical trade to a cash-flow re-rating.
Too Long; Didn’t Read
The difference is at the evidence level. The July 4 report mainly answered “why memory is no longer just an HBM trade,” reframing the industry around Agentic AI, server DDR, KV cache, and LTAs. UBS’s July monthly report answers: “Is this framework being validated by the monthly model?” The most direct change is that 3Q26 DDR contract pricing has been revised up from +17% to +32%, and 3Q26 NAND from +17% to +30%. The narrative is starting to enter the single-quarter income statement.
DDR is the strongest new evidence. DRAM and NAND each already rose about +67% in 2Q26, and the monthly report further raises 3Q26 and 4Q26 DDR price increases to +32% and +18%. This shows that customer LTA negotiations have not immediately capped prices. Instead, they confirm that server DDR supply-demand is tighter than the market previously assumed. If 3Q26 pricing lands as modeled, memory-stock trading will shift from “how large is AI demand” to “how much more EPS needs to be revised up.”
2027 is not a natural cooling-off year. UBS expects DRAM bit demand to grow +36.2% in 2027, while supply grows only +19.3%. After factoring in inventory digestion, the sufficiency ratio is close to -1.2%; without assuming downstream inventory is drawn down, the gap worsens to -13.6%. This matters more than “a 2026 price surge” because it extends the cycle peak from a one-year earnings spike into supply-demand pressure that lasts at least into 2027.
HBM is becoming multi-customer validation. The monthly report modestly raises 2026/2027 HBM demand to 33.1bn Gb and 58.7bn Gb, while including Nvidia, Google TPU, AMD, AWS, and OpenAI in the procurement model. This does not weaken Nvidia’s role. It turns HBM from a single GPU supply-chain anchor into multi-customer validation driven jointly by GPUs, TPUs, in-house ASICs, and cloud providers’ own compute demand.
LTAs are entering the negotiation-detail phase. The July 4 report treated LTAs as a change in the valuation framework. The monthly report moves them into contract terms: Micron’s SCA already includes price floors and ceilings; some Korean vendors’ five-year contracts have about 60%-70% of volumes fixed; Samsung wants to tie 50%-70% of DDR5 shipments to LTAs. The value of LTAs is not that they lift peak pricing higher, but that they make trough cash flow more predictable.
The biggest risk is also sharper. UBS expects memory industry revenue to reach US$992bn in 2026 and US$1.763tn in 2027, approaching US$1.2tn in FCF. The stronger the bull case, the higher the required absorption capacity from cloud and AI customers. Four numbers need monitoring next: whether 3Q26 DDR/NAND pricing materializes, whether LTAs include real prepayments and cancellation protection, whether Google/ASIC HBM procurement lands, and whether hyperscaler capex continues to be absorbed by memory.
I. This Monthly Report Is Not a Repeat of the July 4 Report; It Moves from Framework to Validation
The July 4 memory deep dive focused on why the memory industry is no longer just an HBM story after UBS APAC Tech Strategy placed memory at the top of its Asia-Pacific technology ranking. It linked Agentic AI, CPU/head node, server DDR, KV cache, eSSD, and LTAs into a broad framework, answering why memory can evolve from a cyclical-beta asset into an AI data-center capacity, bandwidth, and cash-flow asset.
The value of UBS’s July 3 Memory Semis Monthly is not to re-explain that framework, but to add monthly validation. Its title is Further pricing upside amidst LTA negotiations. The focus is not a grand narrative, but 3Q26/4Q26 pricing, the 2027 supply-demand gap, HBM customer breakdown, LTA terms, and vendor share. In other words, the previous report was more of an investment framework; this monthly report is more of a model update.
Memory Deep Dive: Memory Stocks Pull Back, but DRAM Prices Surge, NAND Enters Restocking, and KV Cache Pushes AI Demand Toward SSDs
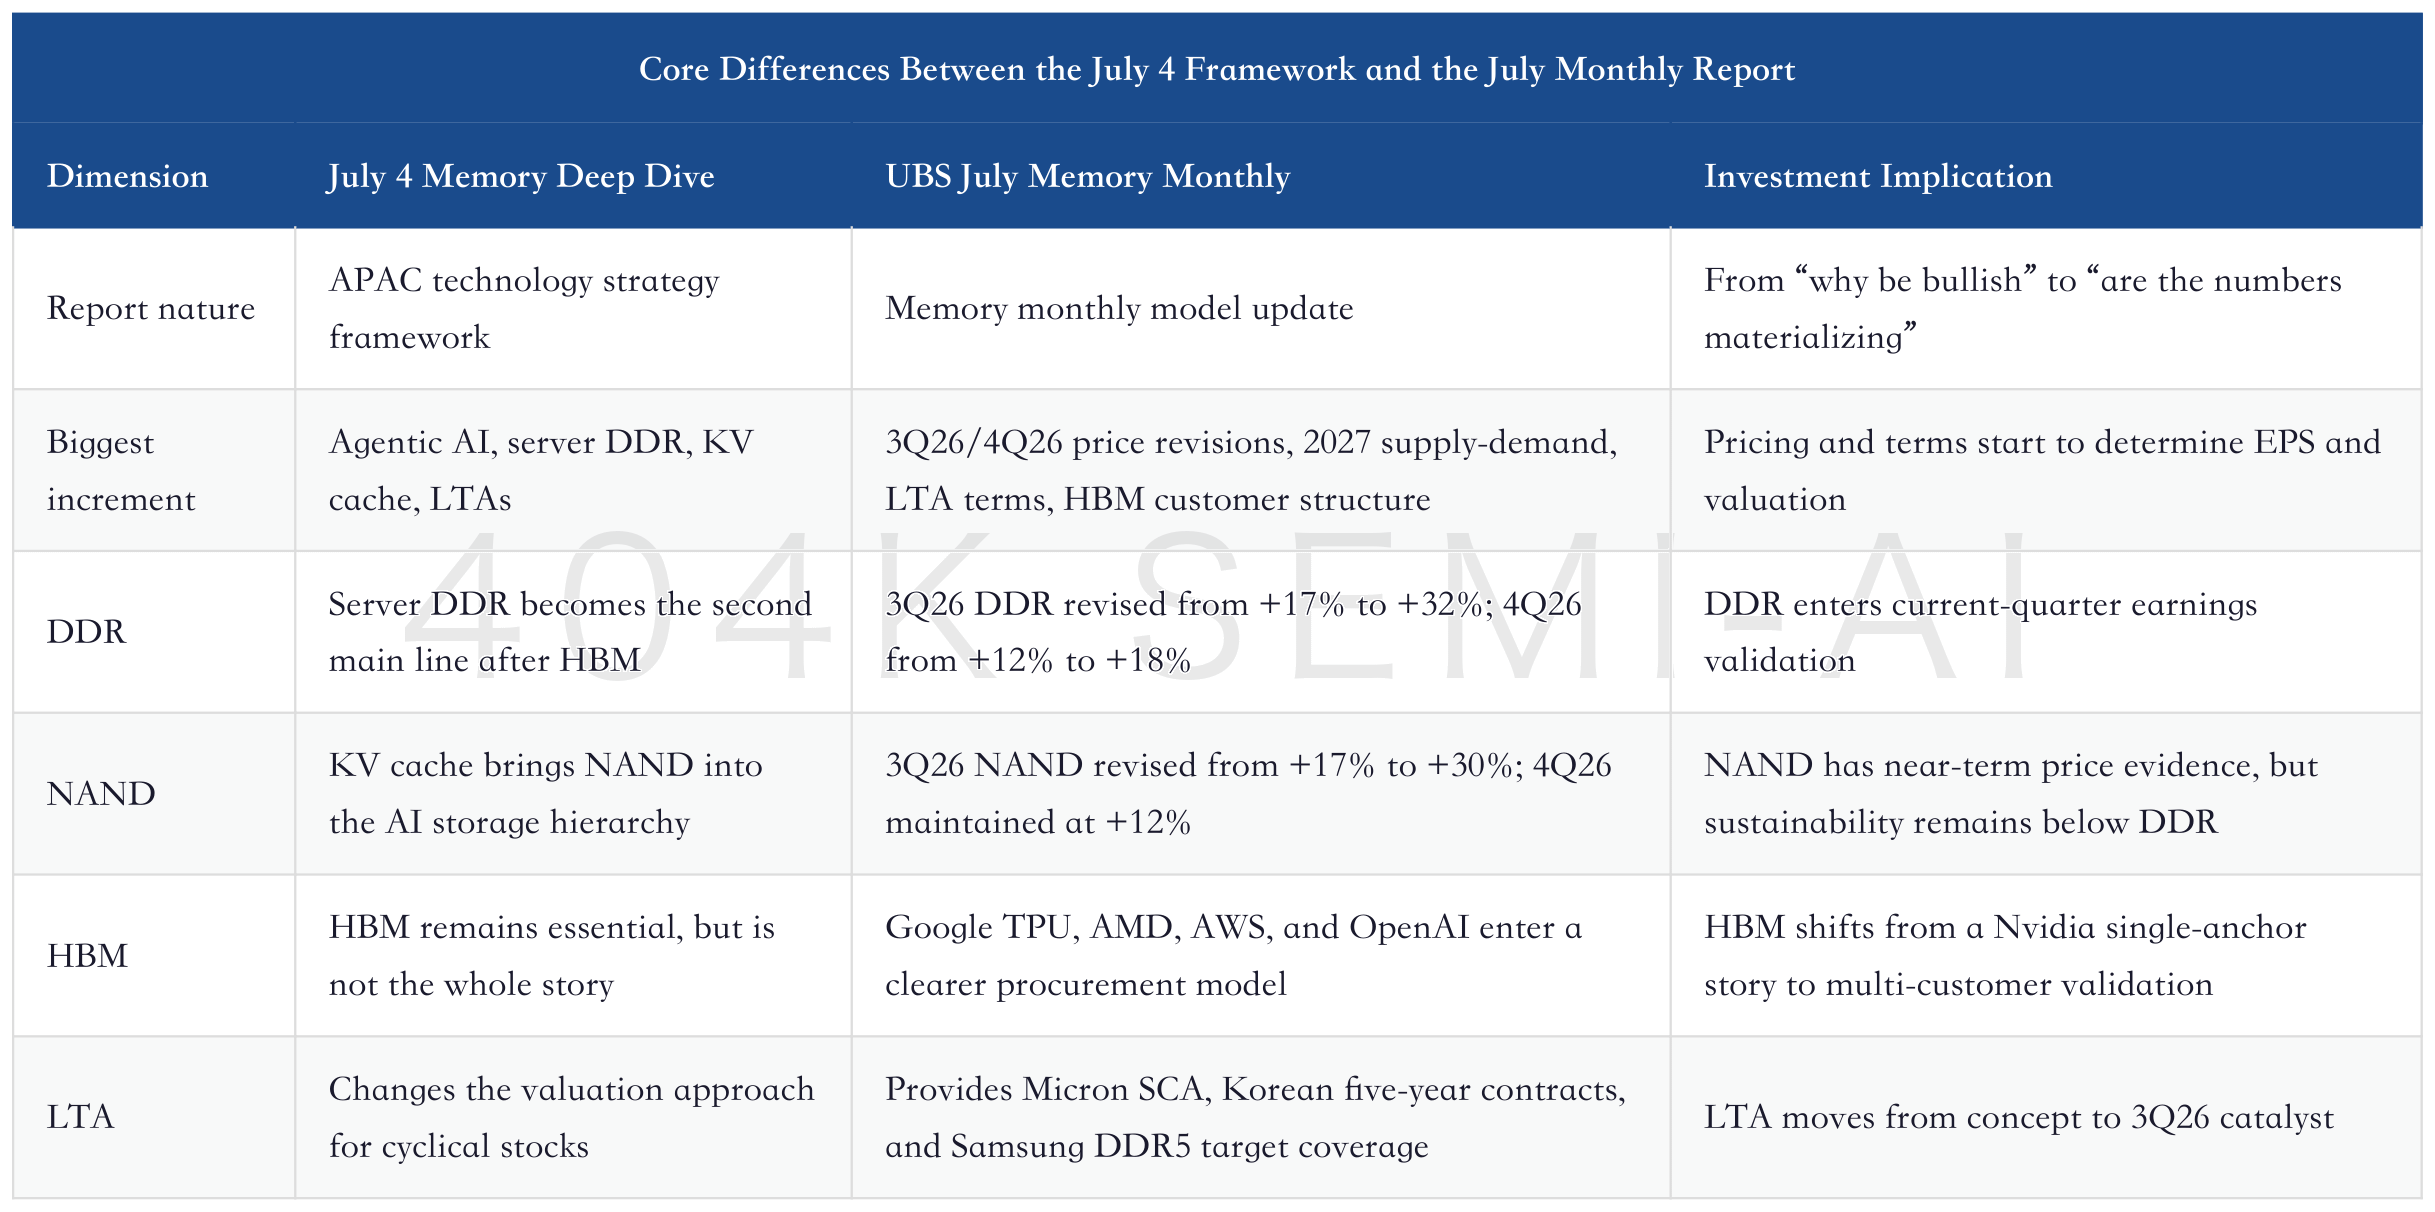
This also determines how this report should be written. The overall memory framework has already been covered, so there is no need to retell the full industry logic of HBM, DDR, NAND, and SSD from the beginning. The more important task is to answer three questions: whether price revisions are strong enough, whether the 2027 demand gap can still support high profitability, and whether LTAs are capping peak profits or lifting the valuation floor.
AI Drives a Full Memory Industry Re-Rating: Who Has the Most Pricing Power Across DRAM, NAND, SSD, and HDD, and How Samsung, SK Hynix, SanDisk, Western Digital, and Seagate Earnings Cross-Validate One Another
II. 3Q26 Price Revisions Are the Hardest New Evidence in This Monthly Report
The easiest mistake in reading a memory report is to interpret “still bullish” as sentiment. The real value of the monthly report is that it raises the price path, and specifically raises the most sensitive periods: 3Q26 and 4Q26. 2Q26 already saw one round of price increases. If 3Q26 is revised up sharply again, this is not a one-off spike caused by inventory shortages.
UBS raises near-term pricing for both DDR and NAND, but the implications differ. DDR is lifted in both 3Q26 and 4Q26, showing that server memory shortages are still spreading. NAND is concentrated mainly in 3Q26, indicating that near-term beta has emerged, while sustainability in the later period still requires further validation from enterprise SSD and KV cache.
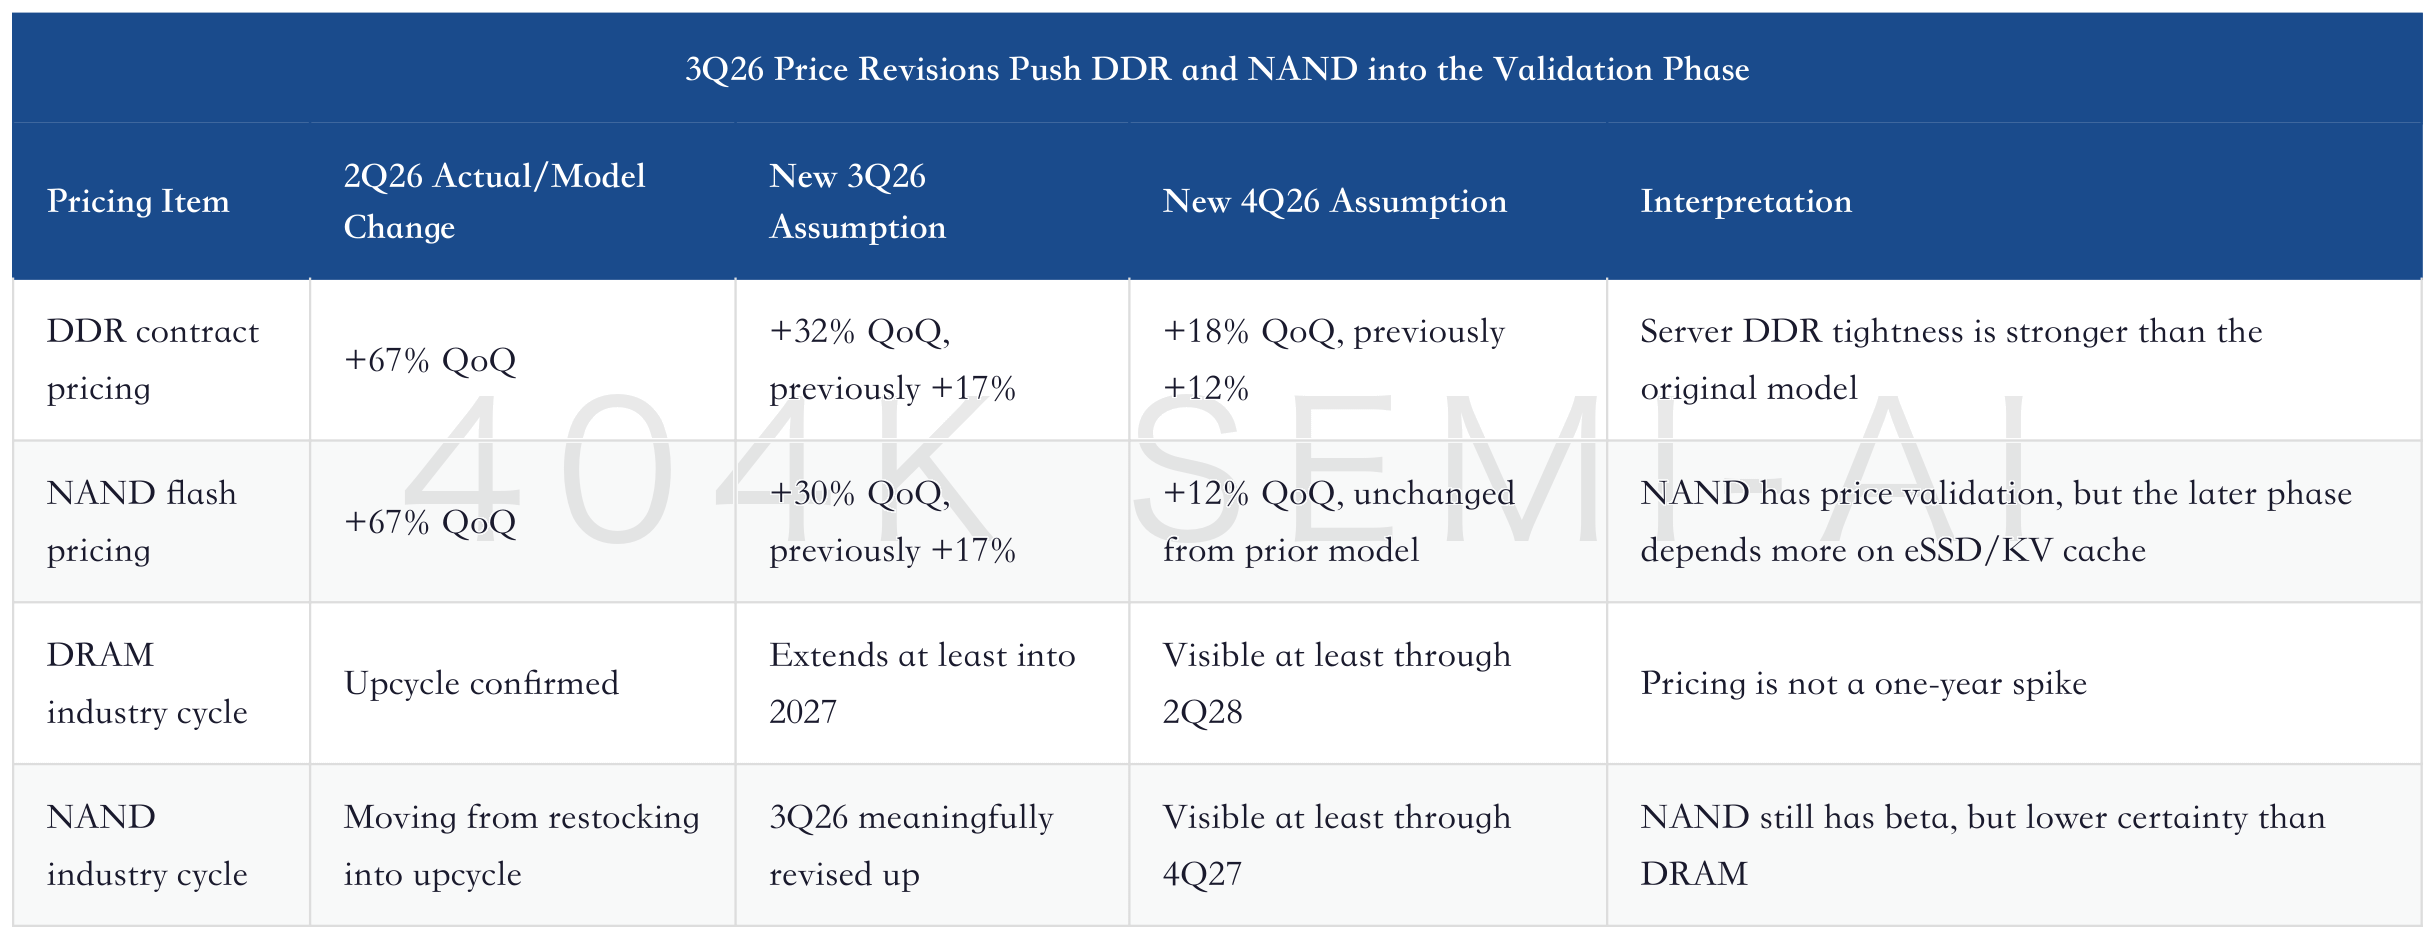
This table matters more than simply saying “memory prices will keep rising.” Looking only at 2Q26, the market could explain it as low inventory, customer restocking, or traditional cyclical recovery. But if 3Q26 is revised up again, and while LTA negotiations are progressing, it shows memory vendors are not immediately sacrificing short-term pricing because of long-term agreements. Customers want to lock in supply, while vendors are also trying to embed higher price bands into medium-term contracts.
Price revisions also change the stock-price rhythm. After their June highs, memory stocks pulled back by about 17% on average. The market worried that prices had risen too quickly, customers could not absorb them, and valuations had already priced them in. UBS’s response is not the empty line that “pullbacks are opportunities,” but a sharper view: if 3Q26 DDR and NAND prices land according to the new assumptions, earnings forecasts will continue to move higher, and the pullback looks more like a digestion of crowded positioning than a cyclical peak.
III. The Key to the DRAM Model Is Not a Strong 2026, but Continued Acceleration in 2027
The July 4 piece already noted that the DRAM cycle could extend into 2Q28. The new value in UBS’s monthly report is that it makes the 2027 supply-demand pressure more specific. The market has already partly accepted a strong 2026; whether 2027 remains strong is the key to whether valuation can shift from a “peak earnings discount” to “through-cycle cash flow.”
UBS expects DRAM bit end demand to grow +36.2% in 2027, while supply grows only +19.3%. The inventory-adjusted sufficiency ratio is only -1.2%, which looks close to balance; but without assuming downstream inventory digestion and customer inventory rebuilding, the 2027 shortfall would worsen to -13.6%. This shows that the truly sensitive variable in the model is not capacity, but whether customers are willing to accept higher inventory and higher memory costs.
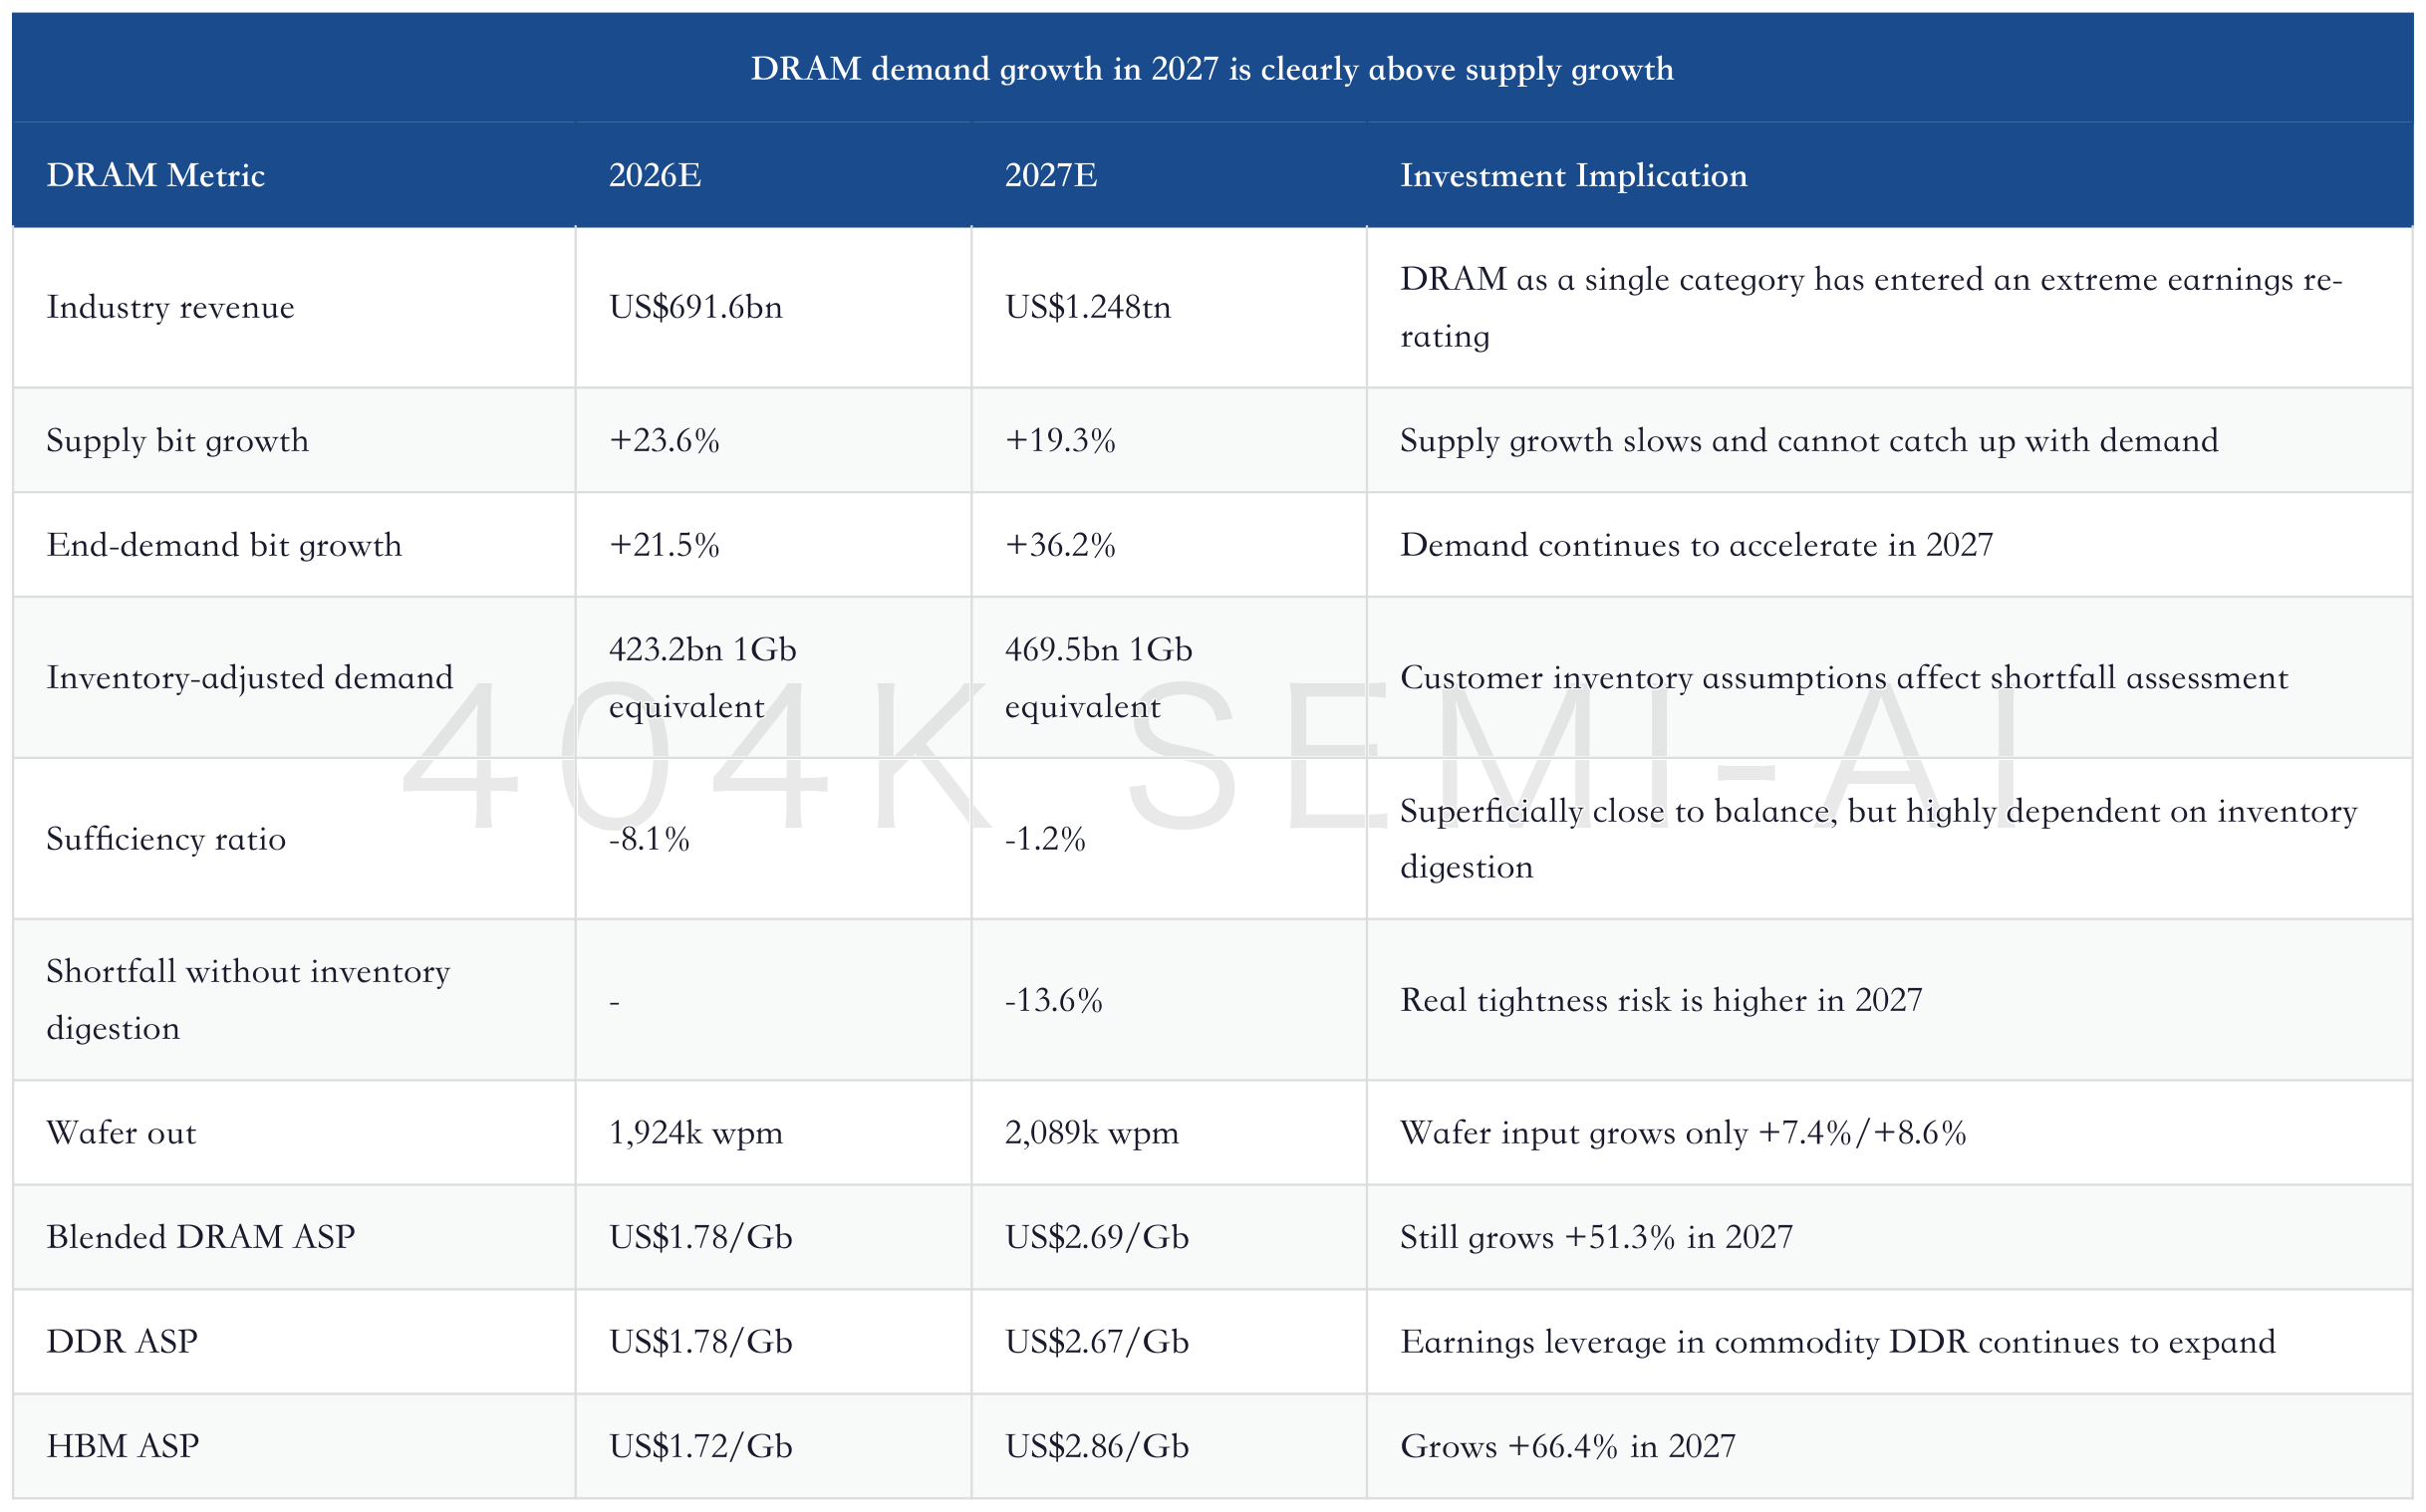
Within this set of numbers, the most easily underestimated item is DDR ASP, not HBM ASP. The market has become used to treating HBM as the core profit driver for memory leaders, but UBS’s monthly report continues to raise DDR pricing leverage. DDR ASP rises +341.4% YoY in 2026 and another +49.4% in 2027. This is not a small restocking cycle in traditional servers, but a higher pricing center driven jointly by AI inference, CPU/head nodes, general servers, and LTAs.
The Second Engine of the Memory Supercycle: CPU Return, HBM Spillover, and a US$1.7tn TAM Re-rating
This is also why memory stocks cannot be assessed using only one-year PE. If prices surge in 2026 and naturally cool in 2027, the market should discount peak earnings. But if demand is still accelerating in 2027, prices are still moving higher from elevated levels, and LTAs lock in part of demand and pricing, valuation cannot focus only on “whether next year is the peak.” It must instead assess whether the industry has slow enough supply release before 2028.
DRAM supply constraints are not just verbal constraints. UBS’s wafer-out forecast is only single-digit growth, indicating that new supply cannot quickly come down through wafer expansion as in old cycles. HBM consumes advanced DRAM capacity; DDR5 and high-end server memory require qualification; and equipment lead times plus engineering resources will also slow capacity release. Rising prices will stimulate expansion, but the feedback time for capacity expansion is far slower than the stock-price reaction.
IV. The Key HBM Update Is Not Volume, but Customer Diversification from Nvidia to TPU and ASIC
UBS still acknowledges that HBM is necessary for AI compute. The report has a short line: HBM remains a Must Have. That statement is not new. The real novelty in the monthly report comes afterward: the HBM demand model is no longer just a function of Nvidia GPUs, but breaks out Google TPU, AMD, AWS, and OpenAI.
The monthly report raises 2026 HBM demand to 33.1bn Gb and 2027 demand to 58.7bn Gb. The magnitude is not astonishing, indicating that the market already understands the overall HBM volume story fairly well. More importantly, the HBM-equivalent procurement corresponding to Google TPU rises from 4.2m units in 2026 to 9.1m units in 2027, while AMD and AWS 2027 procurement is also revised upward. HBM is starting to move from a single GPU ecosystem into a phase where multiple accelerator roadmaps compete for memory.
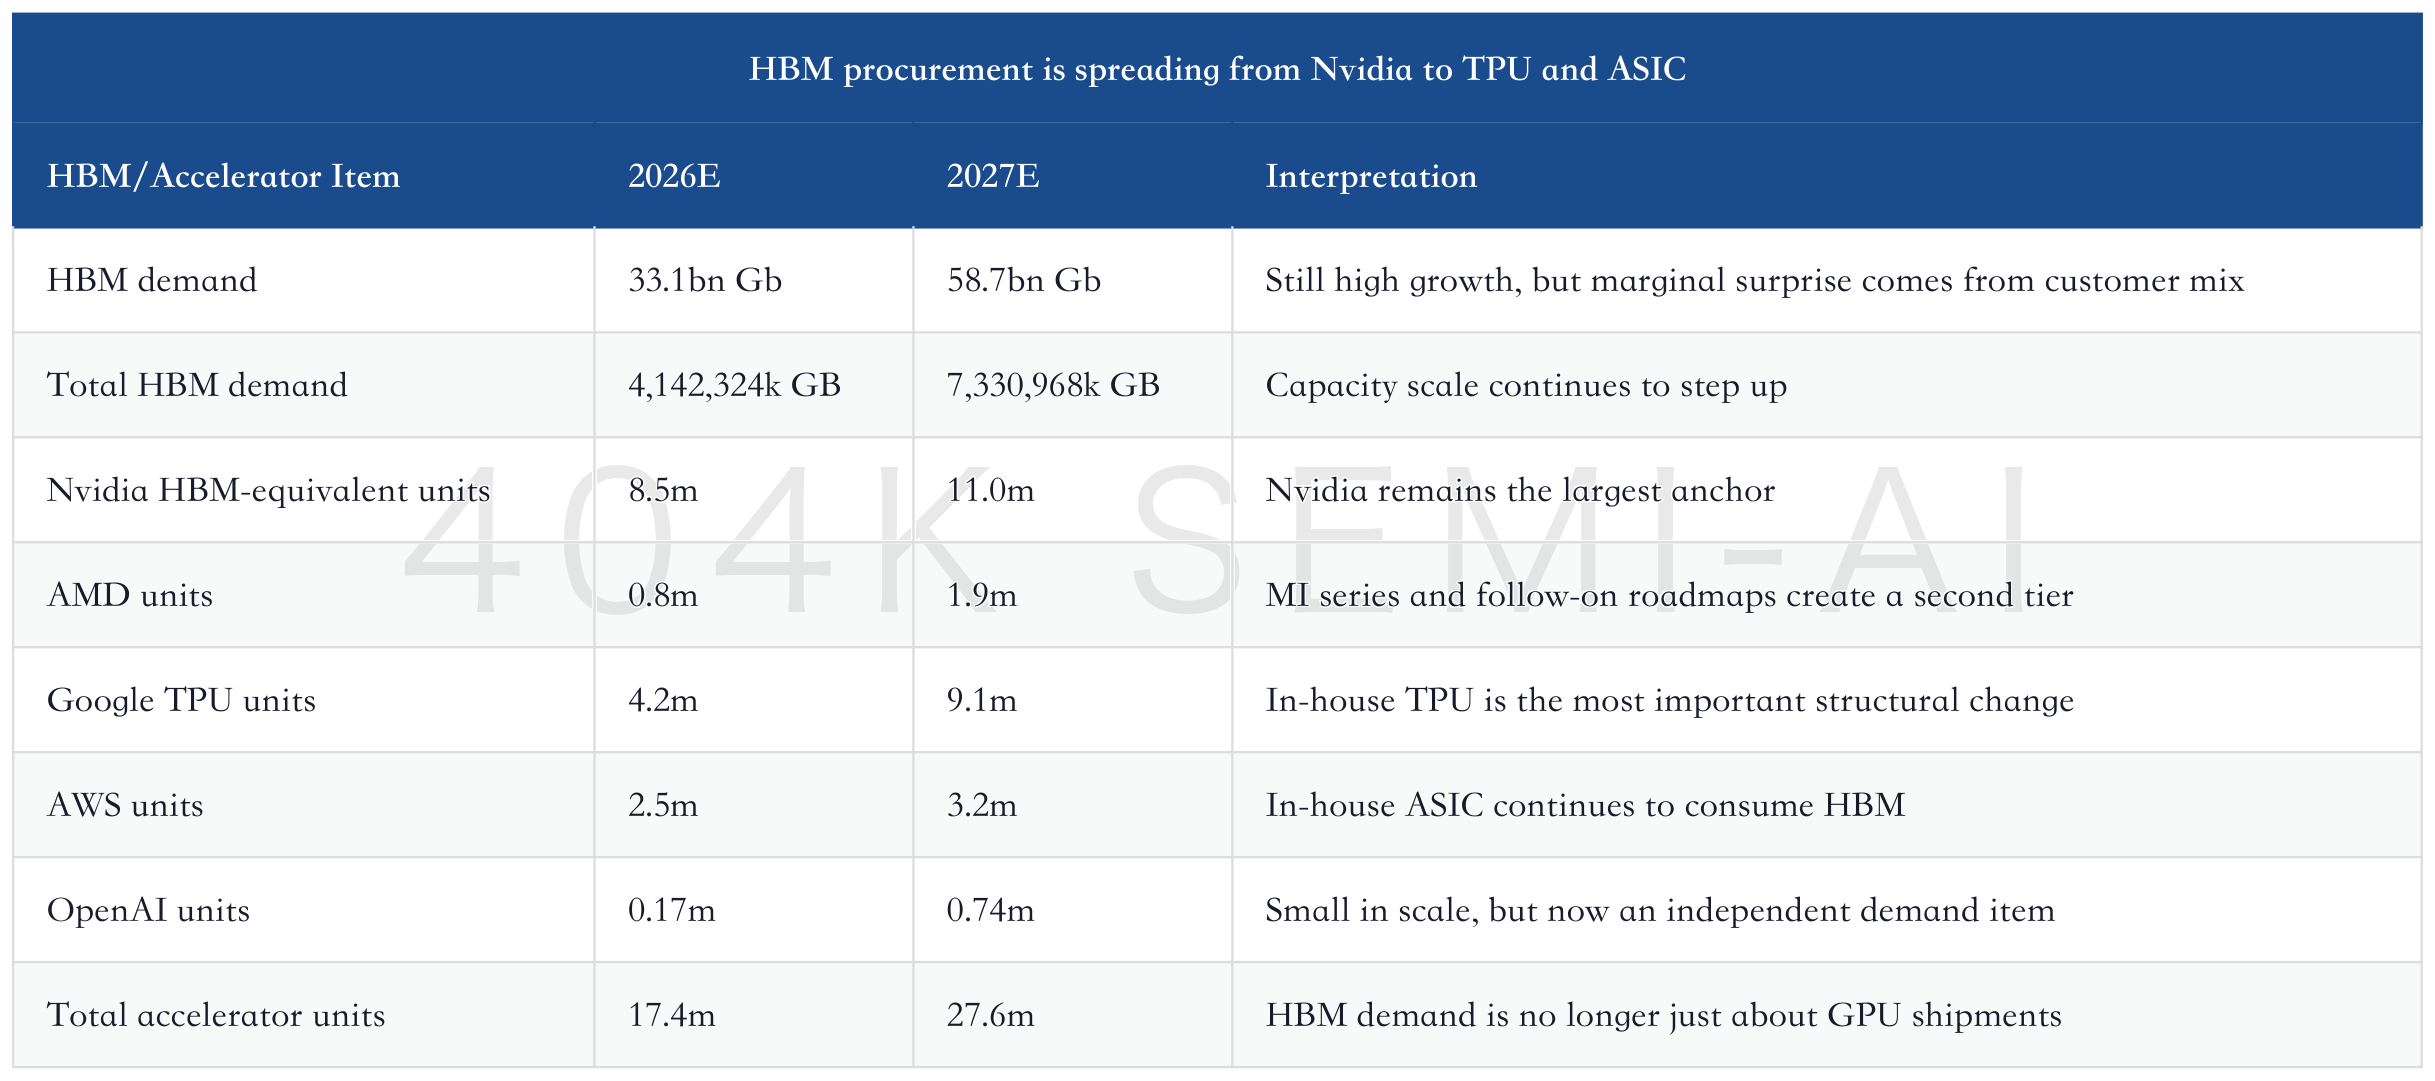
This explains why SK hynix remains a high-purity position, but Samsung Electronics and Micron Technology should not simply be viewed as laggards. If HBM scarcity is only about Nvidia high-end GPUs, SK hynix is the purest play. But if Google TPU, AWS in-house ASIC, AMD, and OpenAI all enter multi-customer procurement, the supply chain will value qualification breadth, capacity flexibility, product mix, and customer coverage more. Samsung Electronics’ breadth becomes more valuable, and Micron Technology’s SCA and access to U.S. customers also become more meaningful.
SK hynix Deep Update: Is It Still Expensive? DDR5 Takes Over Price Hikes, Korean Exports Surge, and Samsung Catch-up Risk
HBM multi-customer adoption will also make valuation disagreements more complex. Previously, judging HBM required asking only three questions: who wins Nvidia orders, whether the HBM3E/HBM4 specification transition can lead, and whether yield can ramp. Now investors also need to ask about HBM capacity, bandwidth, and qualification timing for Google TPU, AWS ASIC, and other in-house chips. If procurement from these customers becomes more diversified, leader purity remains valuable, but the optionality for second suppliers and broad product-line vendors will also increase.
UBS’s discussion of Meta selling part of its compute resources should also be viewed within this framework. The monthly report does not think this will materially affect HBM procurement. It looks more like monetizing older assets while continuing to advance Blackwell, Rubin, and MTIA-related deployments. In other words, short-term compute-asset turnover does not mean HBM demand has peaked. The real thing to watch is whether the memory configuration of next-generation accelerators and in-house ASICs is revised down.
V. LTA Moves From Valuation Concept to 3Q26 Negotiation Variable
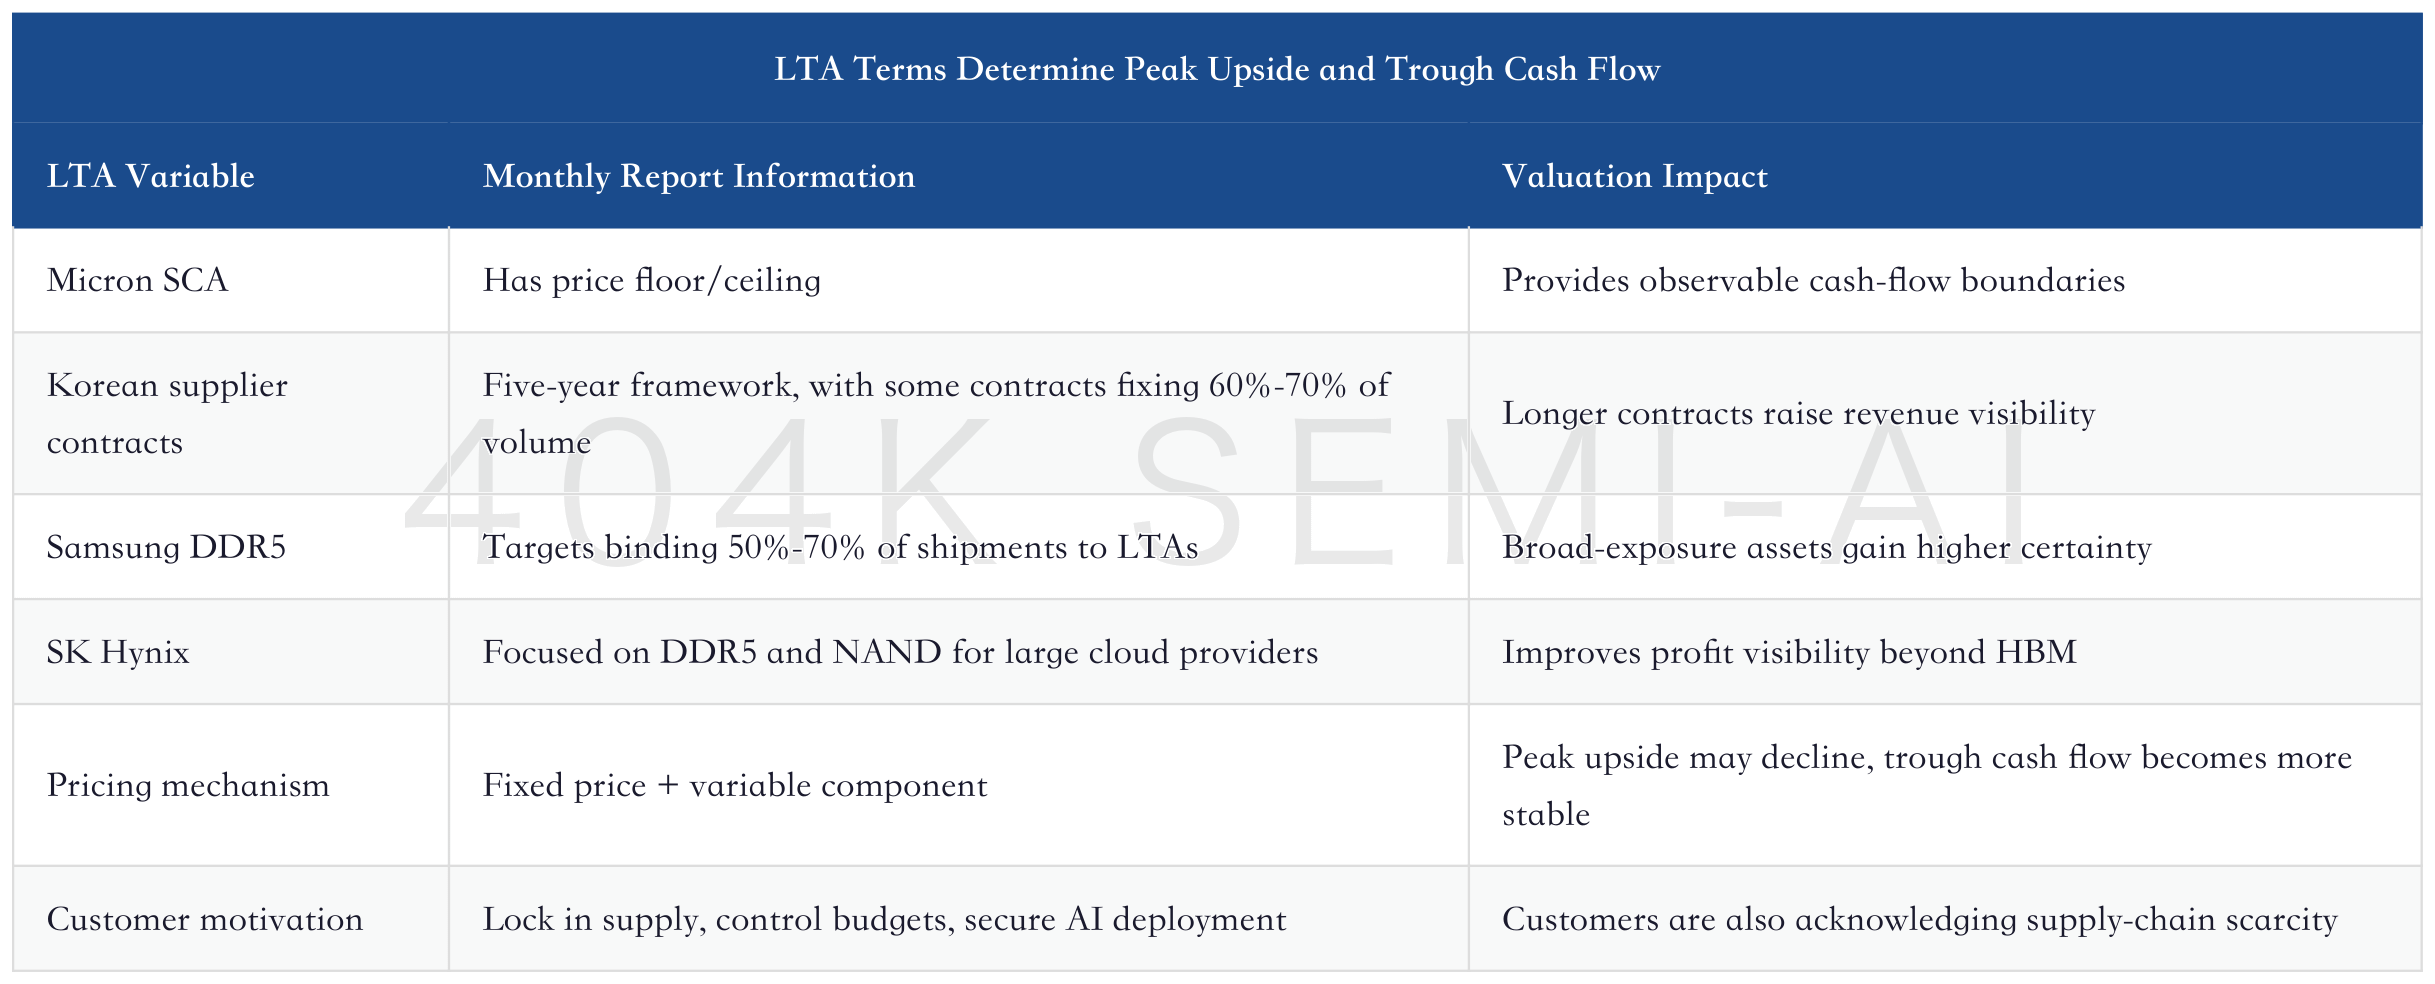
The July 4 piece had already framed LTA as central to the valuation change: long-term agreements may cap peak-cycle pricing, but they lift trough-cycle profits, allowing the market to capitalize part of the high earnings base. What the UBS monthly report adds is contractual granularity. LTA is no longer just “customers locking in supply”; it is a contract structure that includes price floors and ceilings, fixed volumes, variable volumes, duration, and customer commitments.
Micron Technology’s SCA remains the clearest sample, already with a price floor and price ceiling. Korean suppliers, by contrast, are negotiating toward five-year contracts, with some agreements fixing roughly 60%-70% of volume and leaving another portion variable. Samsung Electronics is expected to advance more revised LTAs with major customers in 3Q26, focused on DDR5, and hopes to bind 50%-70% of shipments to LTAs. SK Hynix’s negotiations focus on DDR5 and NAND flash for large hyperscalers.
Memory Is No Longer Just a Cyclical Stock: JPM LTA Breakdown, Agentic AI Memory Multipliers, and the Valuation Rewrite for Samsung and SK Hynix
It is important to distinguish between two types of LTA. A high-quality LTA gives the supplier clear volume, prepayments or cancellation protection, and acceptance of a reasonable price band, allowing memory makers to secure predictable cash flow. A low-quality LTA lets customers use long-term supply commitments to suppress peak prices without providing sufficient financial protection. The former lifts valuation; the latter caps upside. The UBS monthly report is relatively optimistic, but the real validation is not whether an LTA exists. It is whether the terms contain mechanisms that protect supplier capex.
This is also the biggest difference between LTAs and the traditional memory cycle. In a traditional memory cycle, prices rise, suppliers expand capacity, customers wait for prices to fall, and supply-demand eventually reverses. If LTA quality is high enough, supplier capacity expansion is no longer driven entirely by spot-price signals, but by medium-term customer commitments. It does not guarantee the cycle will not turn down, but it can raise the floor for revenue and cash flow in the downturn.
VI. NAND Signals in the Monthly Report Are Strong, but Sustainability Still Requires Stricter Scrutiny Than DDR
NAND is the line in this monthly report most likely to be repriced by the market. The July 4 piece had already incorporated KV cache, TLC SSD, QLC SSD, and enterprise SSD into the AI logic for NAND. The UBS monthly report provides more direct pricing evidence: 3Q26 NAND flash pricing was revised up from +17% to +30%, while 4Q26 remains at +12%.
