
Memory Deep Dive: Samsung’s KRW 89.4 Trillion Profit Beat, the World’s Most Profitable Company, and Why the Stock Keeps Pulling Back
目录
Too Long; Didn’t Read
I. The Contradiction in This Pullback: Profits Beat Expectations, but the Stock Market Is Asking About Slope
II. What Morgan Stanley’s Report Really Adds
III. Samsung’s 2Q26 Preliminary Results: Fundamentals Did Not Deteriorate; the Bar Was Raised
IV. Peak Rate of Change Is Not the Same as Cycle Peak
V. The Price Table Shows DRAM and Legacy Memory Remain Strong, While NAND Requires Structural Selectivity
VI. Why LTAs Have Not Directly Re-Rated Memory Stocks
VII. Three Scenarios Around Reported Earnings: How the Pullback Will Be Validated
VIII. Company Ranking: Who Is Exposed to Rate of Change, Inventory, and Cloud Guidance
IX. Cloud Providers Are the Real Referee for the Next Round
What to Watch After the Pullback: Five Signals Separate Rotation from a Peak
10. Positioning, Misjudgment, and Conclusion: Which Signals Should Actually Trigger a De-Rating
Common Misjudgments: Do Not Treat the Size of the Decline as a Margin of Safety
Conclusion: A Pullback Is Not a Signal to Liquidate; Divergence in Fundamentals and Guidance Is
本内容基于公开资料和研报数据整理,不构成任何投资建议,不代表任何个人观点,仅供学习参考,请理性阅读
Samsung’s 2Q26 preview has brought the contradiction in the memory pullback to the surface: operating profit of roughly KRW 89.4 trillion, fundamentals still strong, yet Morgan Stanley is warning that price change rates, LTA valuation discounts, and cloud-provider guidance are now determining whether capital keeps chasing the rally. This update breaks down what the pullback is really pricing in, and which signals could turn volatility into risk.
Too Long; Didn’t Read
Samsung’s preview first raised the fundamental floor. Preliminary 2Q26 revenue was roughly KRW 171 trillion and operating profit roughly KRW 89.4 trillion, above Morgan Stanley’s pre-report expectation of about KRW 85 trillion, showing that memory price increases, AI memory, and semiconductor profit conversion remain very strong. The share-price pullback is not because profits suddenly deteriorated, but because the market has started asking how much longer such strong profits can keep being revised upward at the same slope.
Morgan Stanley’s core point is not a bearish call on memory, but a warning that the rate of change is peaking. The report compresses the current memory debate into three questions: whether cloud providers really have excess compute, why LTAs have not driven a valuation rerating, and whether price and earnings revisions are approaching their steepest phase. The conclusion is that near-term volatility may continue, but if AI capex and cloud-provider guidance are not revised down, the pullback looks more like de-crowding within a structural bull market.
The price table still supports DRAM over NAND. Morgan Stanley raised its 3Q26E price-increase assumptions for PC DRAM, server DRAM, and conventional DRAM to roughly 13-18% or 15-20%, and raised enterprise SSDs from 13-18% to 18-23%. But for NAND, 4Q26E is essentially down to only 0-5% or flat. Capital allocation will naturally favor DRAM, legacy memory, and HBM spillover, while conventional NAND and the module chain face a higher burden of proof.
LTAs have not immediately rerated because the market still fears two things. First, past long-term agreements were renegotiated, or forced customers to absorb inventory they did not need. Second, peak profits in memory have historically been undermined by high capex and inventory. For today’s LTAs to translate into higher valuations, they need to prove at the same time that customer demand is real, contracts are sufficiently firm, inventory is not piling up, and cash flow can be retained.
Company ranking during the pullback needs a new table. Samsung Electronics and SK Hynix are the fundamental anchors; Micron is the high-beta validator; SanDisk and Kioxia need to prove that eSSD and long-term agreements can offset forward NAND supply; Western Digital and Seagate Technology are more about HDD cash flow; module/controller mappings such as Longsys and DML need to first be assessed through inventory and enterprise SSD qualification. The closer a company is to real AI spending and supply bottlenecks, the less it should fear the pullback; the more it depends on inventory elasticity, the more exposed it is to drawdowns.
The next step is not to rely on a simple “buy the dip” or “clear out” call, but to watch whether five signals move in the same direction: cloud providers’ 2Q results and 3Q capex guidance, 3Q DRAM/NAND contract pricing, SK Hynix management commentary on July 29, whether LTAs bring cash flow rather than inventory, and whether module and channel inventory begins to deteriorate. If all five signals remain aligned, the memory pullback is just a change of hands; if cloud capex and contract prices weaken at the same time, concerns over a cycle peak will become more concrete.
I. The Contradiction in This Pullback: Profits Beat Expectations, but the Stock Market Is Asking About Slope
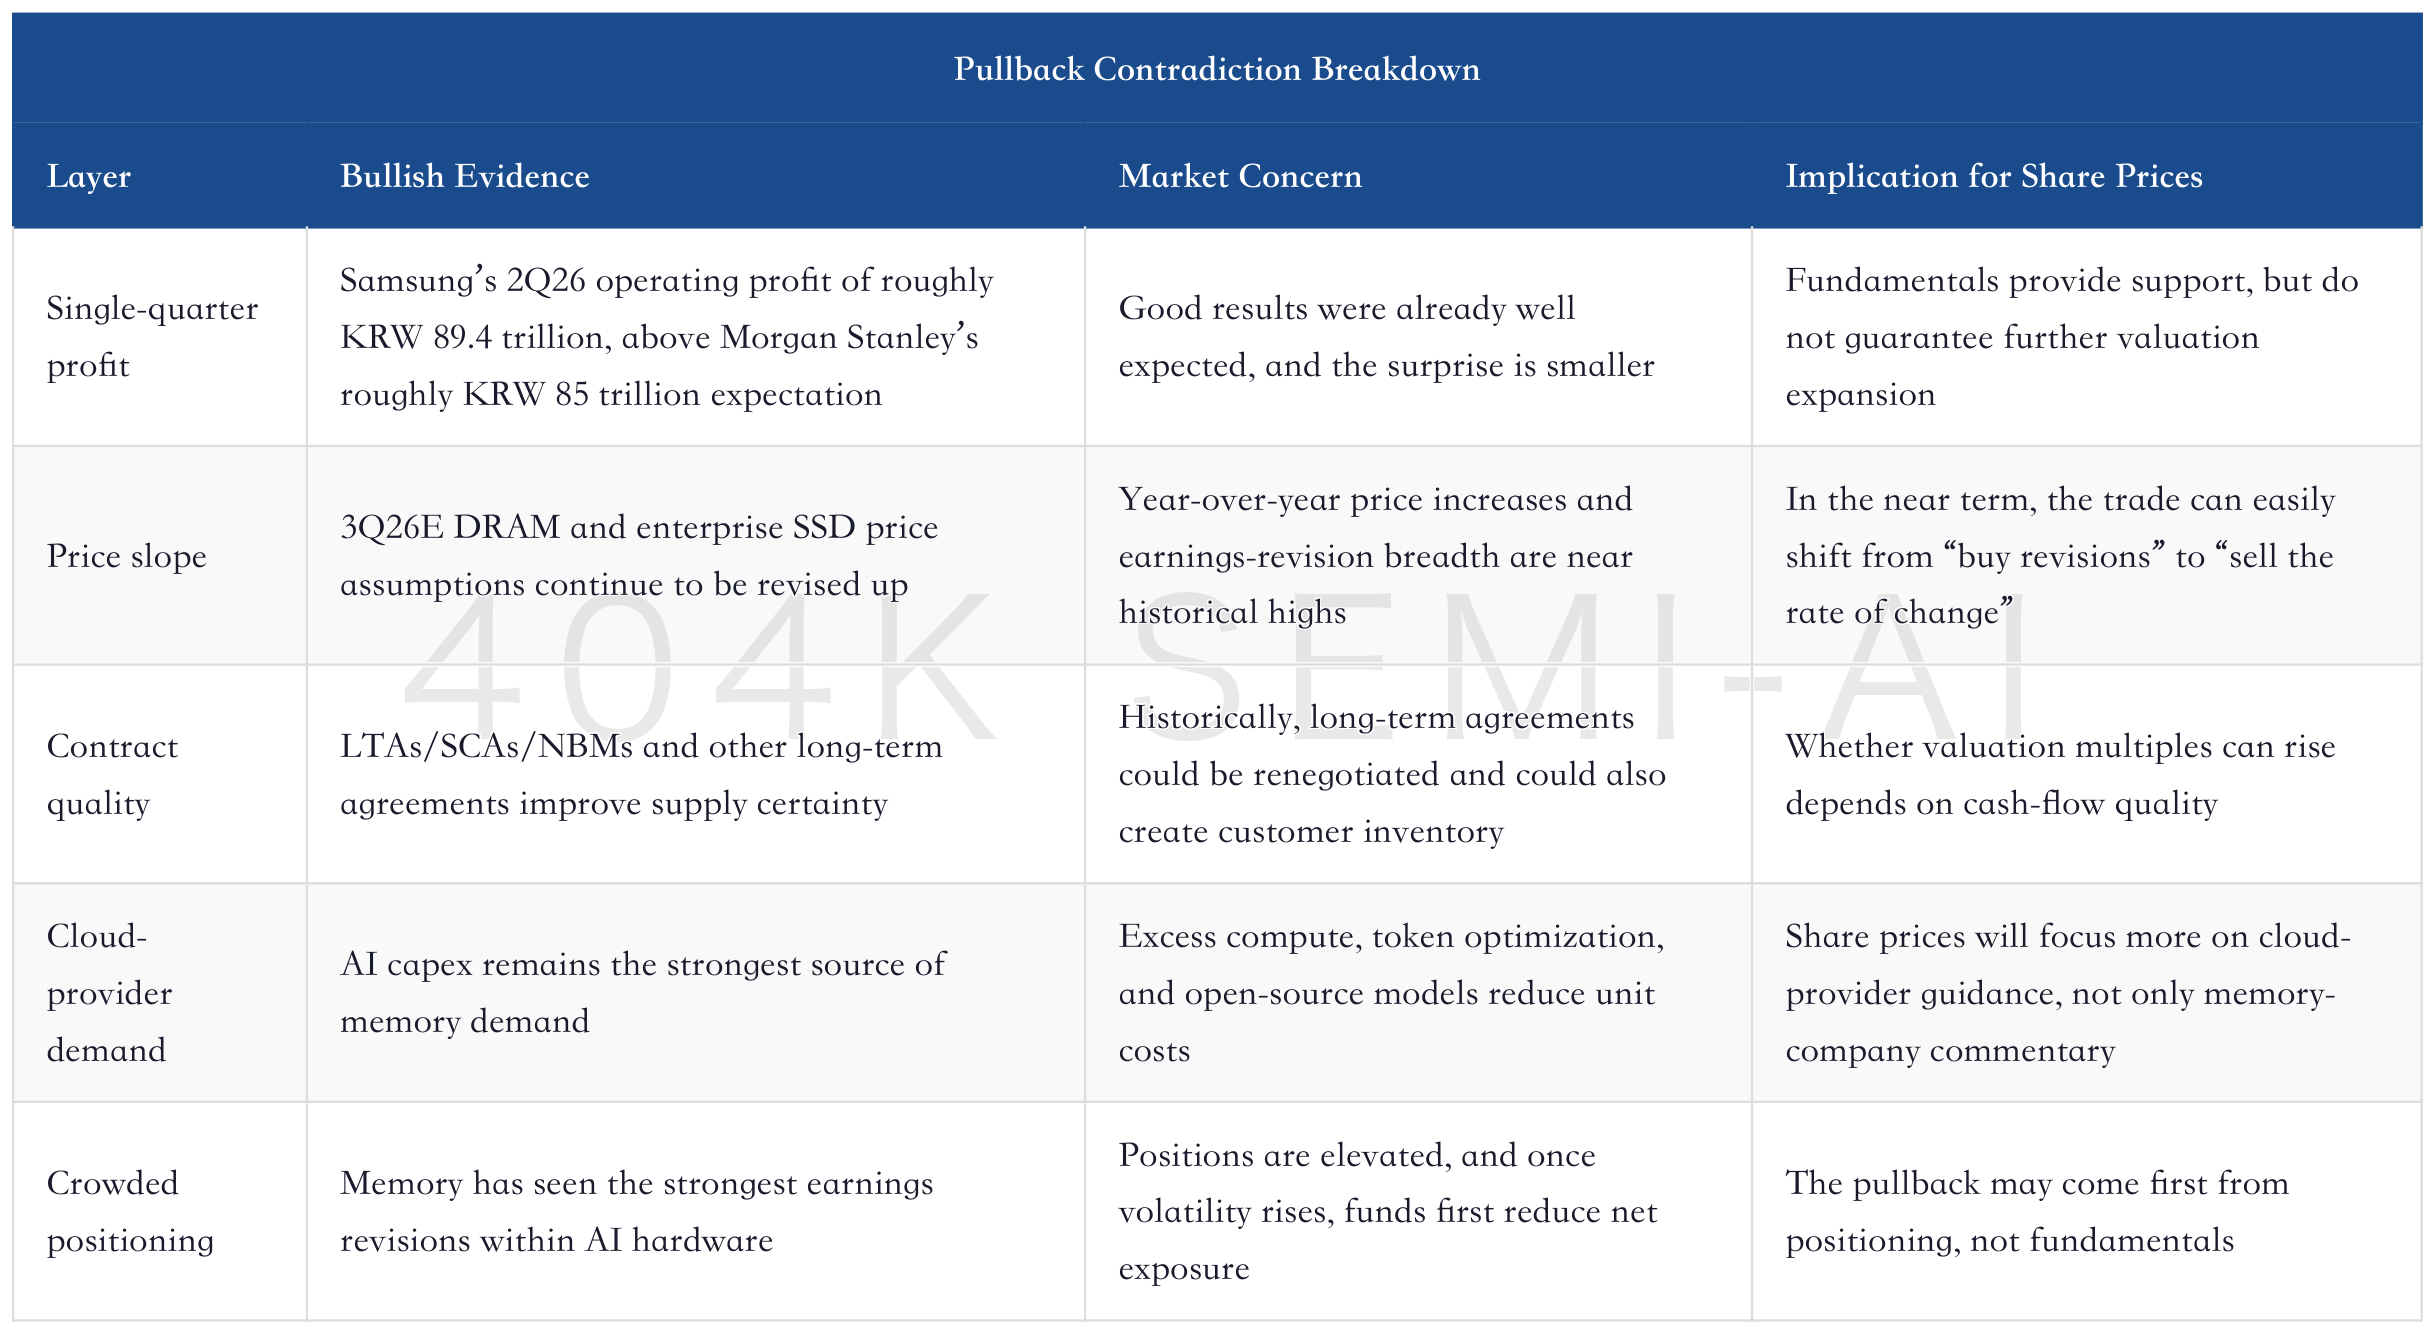
The hardest part of judging memory stocks now is that profits and share prices no longer move to the same rhythm. Samsung Electronics’ 2Q26 preview showed roughly KRW 171 trillion in revenue and roughly KRW 89.4 trillion in operating profit. Operating profit was above Morgan Stanley’s expectation of roughly KRW 85 trillion, and continues to prove that AI memory, DRAM price increases, and semiconductor profit conversion remain strong. Looking only at these two numbers, it is hard to argue that fundamentals have turned worse.
But share prices are not trading on one quarter’s profit; they are trading on how much room is left for the next upward revision. Over the past several months, memory stocks have already traded through price increases, HBM, LTAs, NAND shortages, eSSDs, and HDD cash flow. Morgan Stanley’s “Changing Tides” is not saying the cycle is over. It is warning that the market has shifted from “will profits explode?” to “can the profit slope keep accelerating?”
That is the real contradiction in the pullback. Fundamentals are still strong, yet share prices have started worrying about three things: first, the year-over-year increases in DRAM and NAND prices, inventory, and the breadth of earnings revisions are close to their steepest phase; second, LTAs and long-term agreements have not immediately lifted valuation multiples, showing that the market is still applying a cycle discount; third, if cloud providers begin discussing compute monetization, token-cost optimization, or 3Q guidance that is not strong enough, memory, as a beneficiary of AI spending, will be the first area where positions are reduced.
Memory Pullback: Buy the Dip or Clear Out? Watch These Five Signals First
The previous note framed the question as “buy the dip or clear out.” This update can go one level deeper: the prerequisite for buying is not that the share price has fallen, but that after the decline, cloud capex, contract prices, long-term agreements, inventory, and cash flow still point in the same direction. The prerequisite for clearing out is also not that the stock has risen too much, but that these indicators begin to diverge.
II. What Morgan Stanley’s Report Really Adds
Morgan Stanley has not removed memory from the structural bull market. The report still opens with a long-term bullish view, based on more than 35-40% earnings growth in 2027 and the ramp of Agentic AI. What is truly new is the near-term trading judgment: memory remains a cyclical industry, and although this cycle has AI-driven structural change, year-over-year pricing, inventory, and earnings-revision breadth are already close to a “peak rate of change.”
This sentence is crucial. It does not mean prices have already peaked, nor that profits have already peaked. It means the acceleration in price and profit upgrades is starting to be discounted by the market in advance. Share-price pullbacks amid strong fundamentals often happen at this stage: profits remain strong, target prices continue to be revised up, but marginal surprises begin to fade, and capital rotates out of the most crowded areas into more lagging AI hardware or semiconductor equipment.
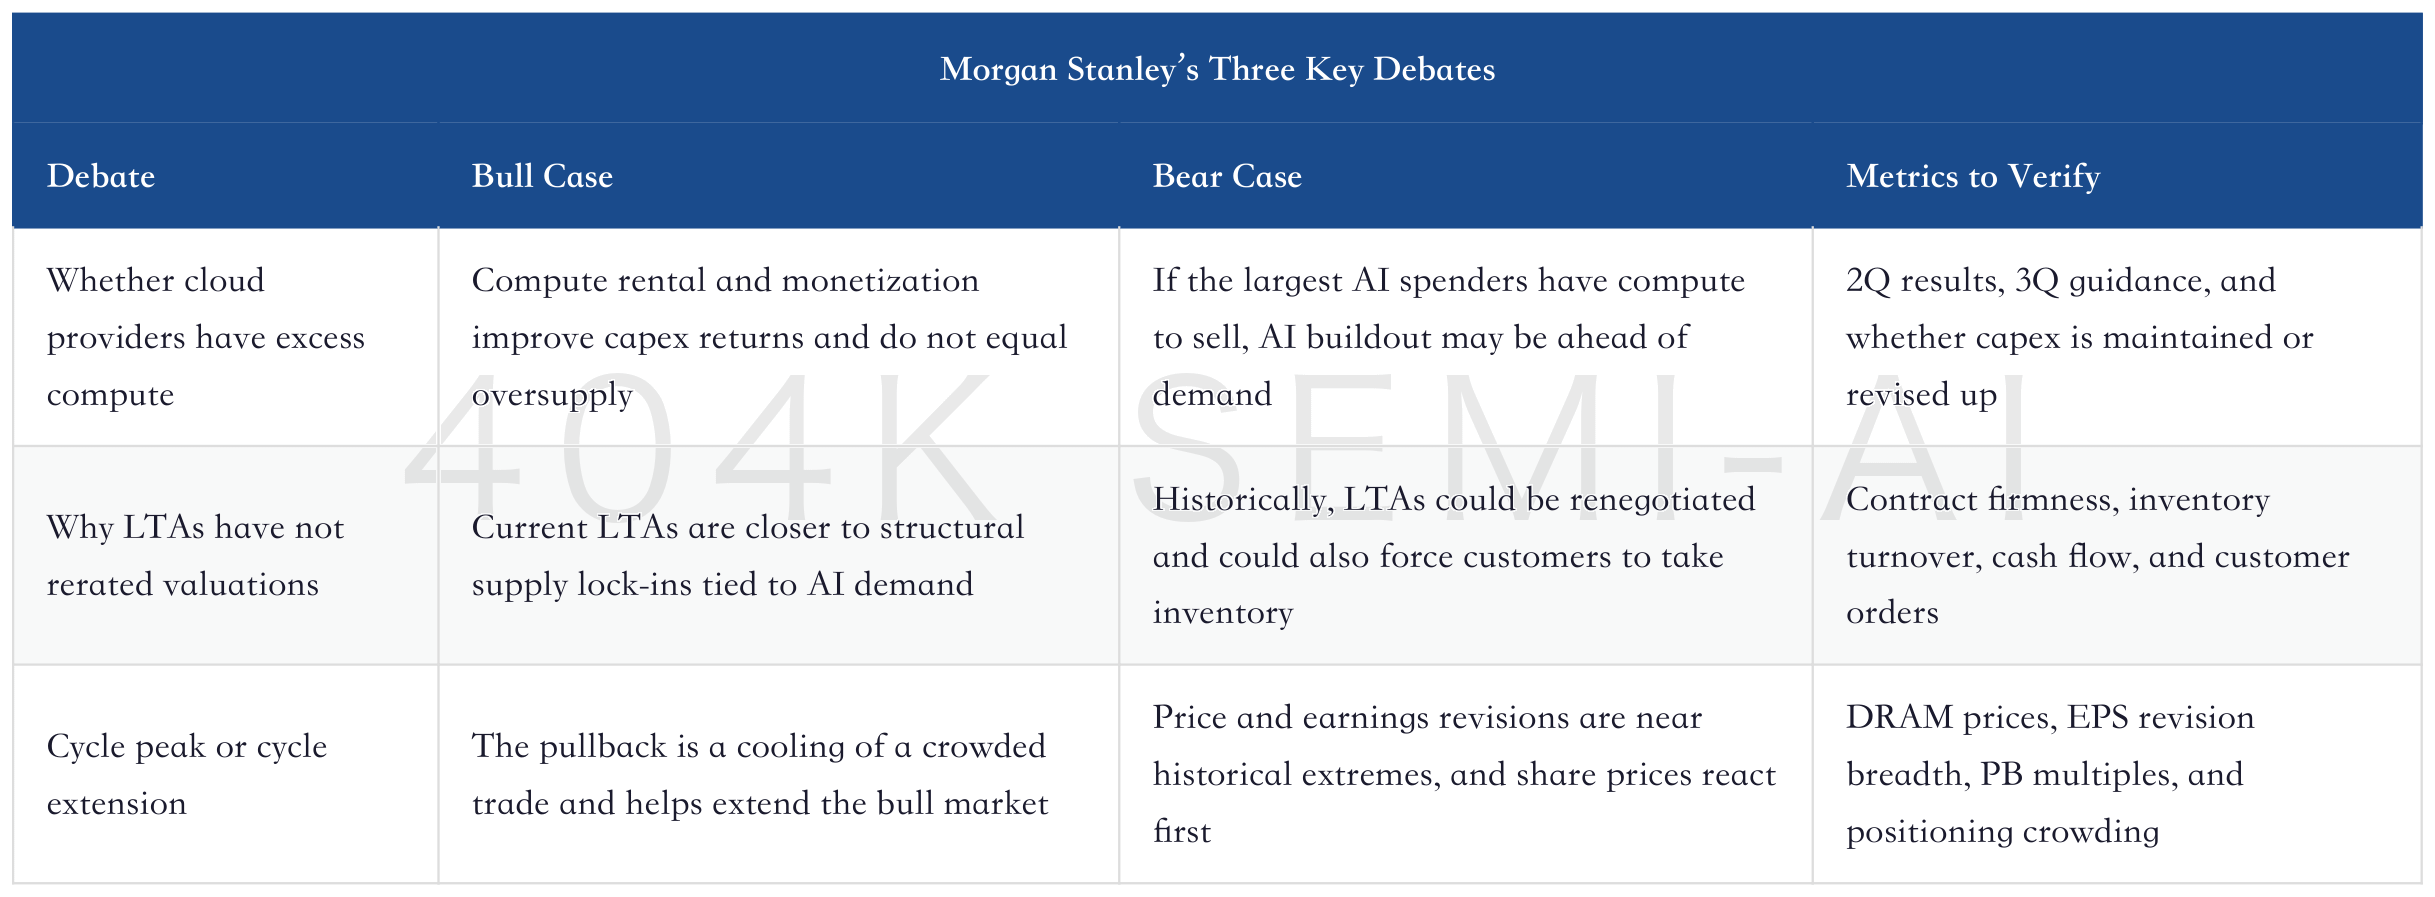
The most valuable part of the report is that it turns the “pullback” from an emotional issue into a verification issue. In the past, as long as the market saw DRAM and NAND prices rising, it was willing to assign memory stocks higher target prices. Now the question is which price increases can continue to flow into the income statement, which profits can become cash flow, and which cash flows can reduce the cycle discount.
The whole-industry rerating framework remains intact, but at the current stage the analysis needs to move from “who has the most pricing power” to “whose pricing power is still accelerating.” Samsung’s preview shows aggregate profits remain strong; Morgan Stanley’s report warns that in the near term, memory stocks may no longer reward every price increase, but instead reward the profits most capable of enduring a slowdown in the rate of change.
III. Samsung’s 2Q26 Preliminary Results: Fundamentals Did Not Deteriorate; the Bar Was Raised
Samsung Electronics released its 2Q26 preliminary results after this report, which actually made Morgan Stanley’s framework more useful. In the report, Morgan Stanley expected Samsung’s 2Q26 operating profit to be about KRW 85 trillion; the preliminary figure came in at about KRW 89.4 trillion, implying stronger actual profit. This number proves at least three things: first, AI and memory price increases are still flowing through semiconductor P&Ls; second, Samsung’s breadth of assets is being monetized; third, the near-term pullback is hard to simply attribute to “fundamentals collapsing.”
The real question becomes: after being this strong, how much stronger does the next print need to be? Samsung’s preliminary releases typically only provide group revenue and operating profit, not DS, Memory, HBM, NAND, eSSD, foundry losses, capex, or cash flow. So they can only answer “is there profit,” not “what is the quality of that profit.” Those details have to wait for the formal earnings release and management commentary.
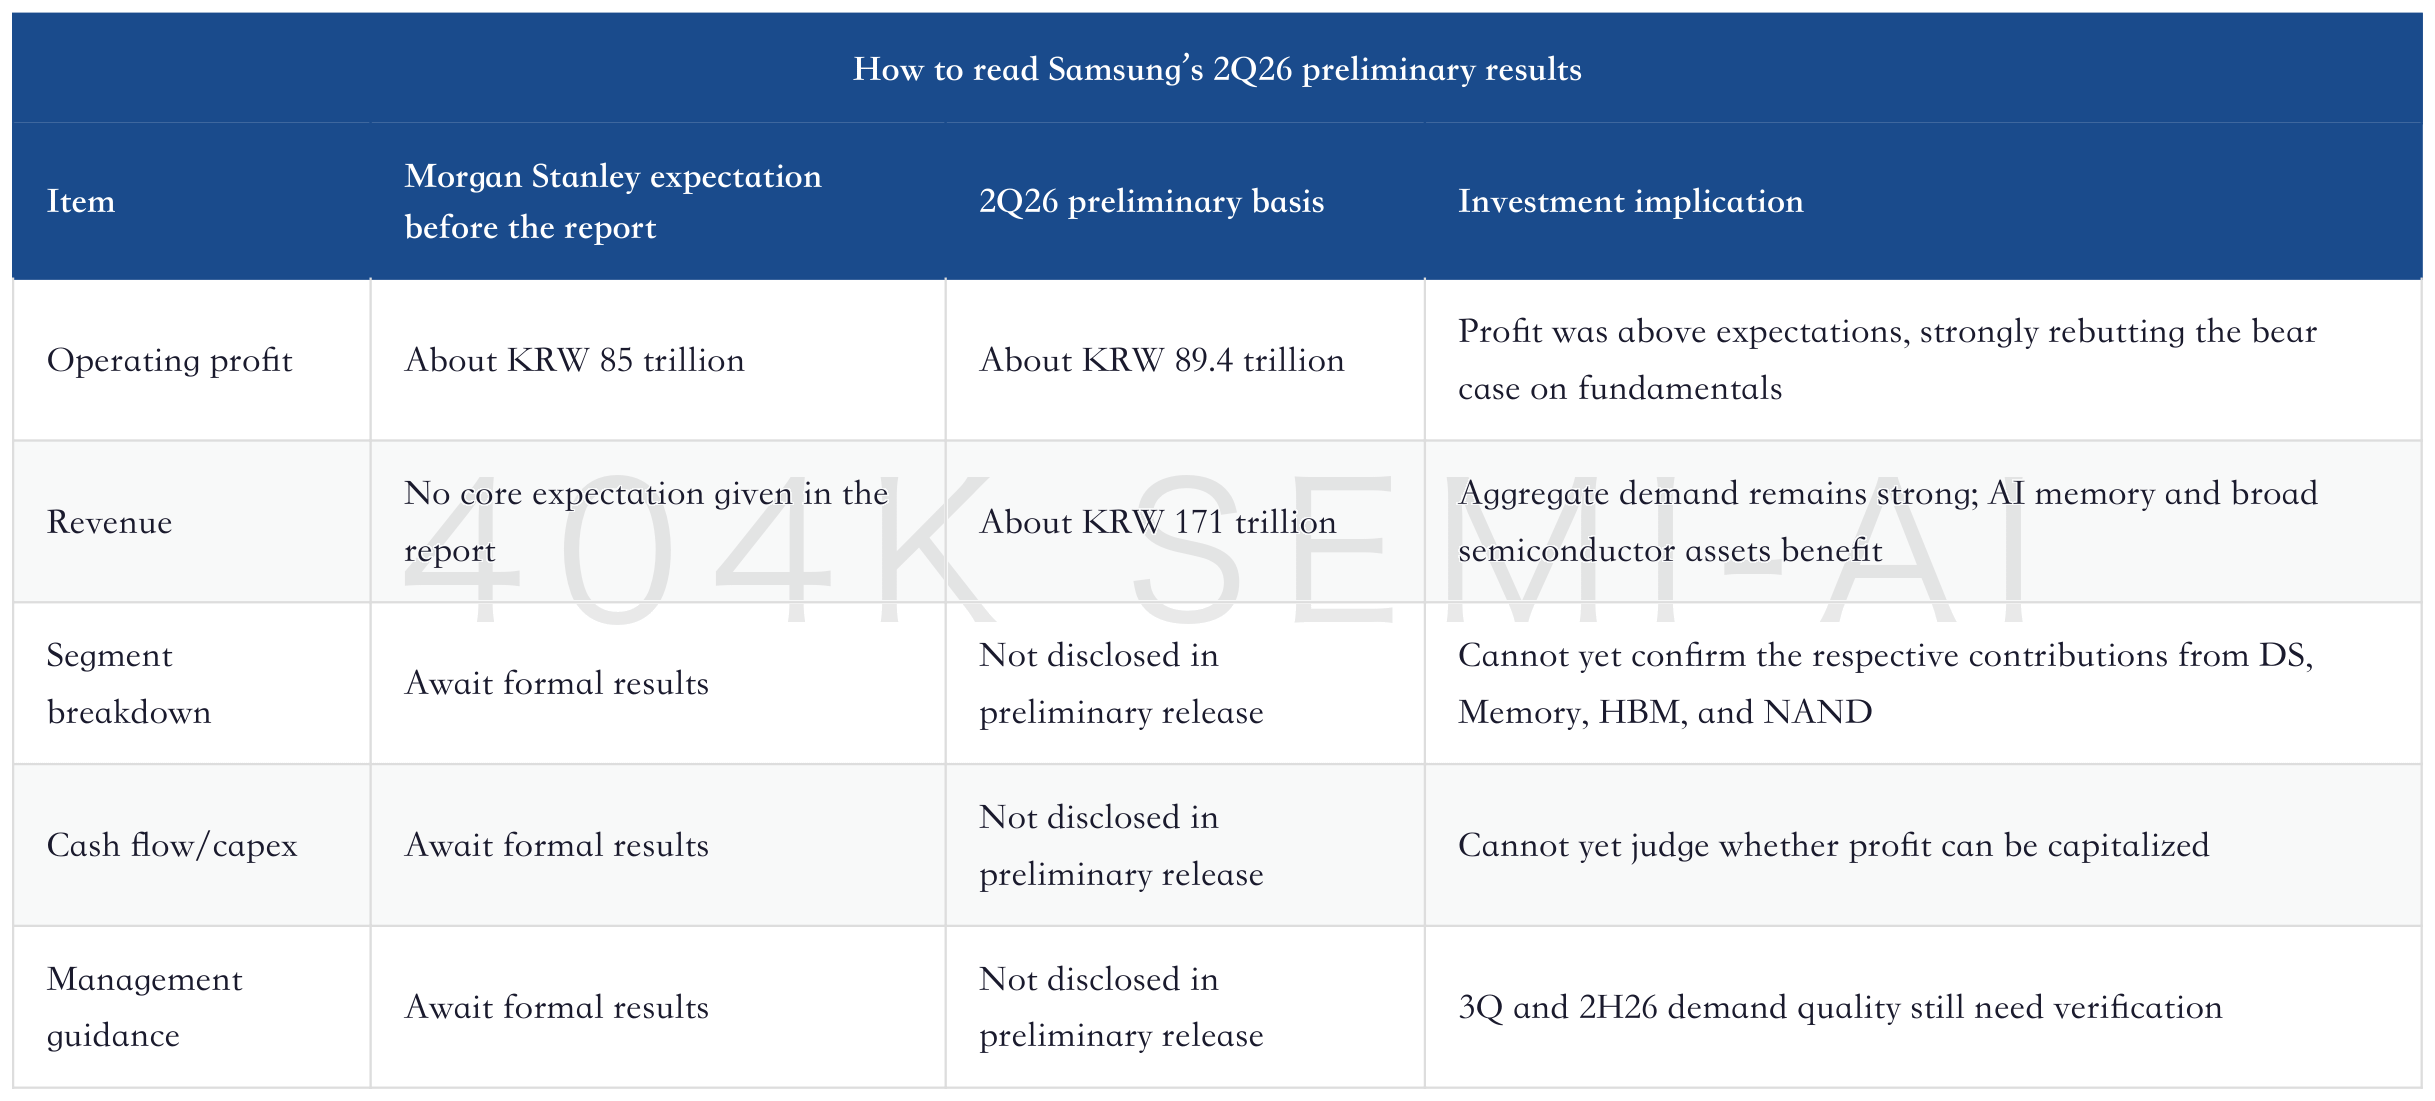
This is also why memory stocks can still be volatile after Samsung’s preliminary beat. A strong preliminary release only shows that the current quarter is strong. What the market worries about is 3Q guidance, cloud vendor capex, HBM and DDR5 capital spending, forward NAND supply, inventory, and LTA execution. The stronger Samsung is, the higher the market’s demands will be for the subsequent formal earnings call.
The first thing to watch in the formal results is the semiconductor segment. If Samsung group profit beats expectations, the market will immediately ask where the profit came from: Memory pricing, HBM shipments, NAND recovery, narrowing foundry losses, or seasonal improvement in end-device businesses. Only when DS and Memory are clear profit engines will memory stocks treat this preliminary release as an industry signal. If the profit beat mainly comes from non-memory factors, the market will treat it as company-specific improvement at Samsung rather than continued upside in the memory cycle.
The second thing to watch is the relationship between HBM and traditional DRAM. Samsung’s challenge is not a lack of memory capacity, but whether HBM certification, yield, customer share, and advanced packaging cadence can catch up with expectations. If the formal commentary shows HBM improvement while traditional DRAM prices remain strong, Samsung becomes a combination of “catch-up plus cycle.” If traditional DRAM is strong but HBM remains slow, Samsung still has profit leverage, but its valuation will be capped by SK Hynix’s purity.
The third thing to watch is NAND and eSSD. Morgan Stanley’s price table has already raised its 3Q26E price-increase assumptions for enterprise SSD, but NAND’s slope into 4Q26E is weaker than DRAM’s. If Samsung only sees ordinary price increases in NAND, the market will not assign a high multiple. If it can show traction from eSSD, high-capacity products, QLC, and data-center customers, then NAND profit quality has a chance to be re-rated.
The fourth thing to watch is capital spending. The biggest risk to strong profit is that it gets offset by aggressive capex. If Samsung ramps investment simultaneously in HBM, DRAM, NAND, and foundry, the market will worry that supply discipline is weakening. If capex is directed more toward HBM, advanced DRAM, and products with clear customer lock-in, while mature DRAM and ordinary NAND remain restrained, the credibility of an extended memory cycle will be higher.
The fifth thing to watch is inventory and cash flow. The preliminary release cannot provide inventory or cash-flow data; the formal financial statements will give the market harder evidence. If inventory turnover is stable, operating cash flow improves, and semiconductor profit is not swallowed by inventory and receivables, memory profit will be easier to capitalize. If profit is strong but inventory rises in tandem, the market will interpret this strong profit as high-inventory risk near a cyclical peak.
Samsung’s advantage is breadth. SK Hynix’s advantage is HBM purity, Micron’s advantage is high beta to DRAM and its position as a U.S. AI memory entry point, while Samsung has DRAM, NAND, HBM, foundry, and end-demand all in one P&L.; Breadth can amplify profit in an upcycle, and it also provides defense when the market questions single-product HBM share.
IV. Peak Rate of Change Is Not the Same as Cycle Peak
The most easily misread phrase in Morgan Stanley’s report is “peak rate of change.” If translated literally as “the rate of change has peaked,” it sounds bearish; but in cyclical stocks, it is not the same as “the cycle has peaked.” Peak rate of change means price increases and earnings upgrades are moving from their steepest phase into a slower phase. Cycle peak means prices, profits, and demand have begun to reverse. The gap between the two can be long, or it can simply be one round of position rotation.
The report provides a very useful historical reference: since the generative AI rally began in 2022, DRAM stocks have already gone through three major pullbacks, including one profit-taking drawdown of about 32%, one “Liberation Day” drawdown of about 20%, and one geopolitical-conflict shock of about 15%, while the current pullback is about 17%. These pullbacks did not end the AI memory bull market; instead, they became mid-cycle position resets before subsequent gains.
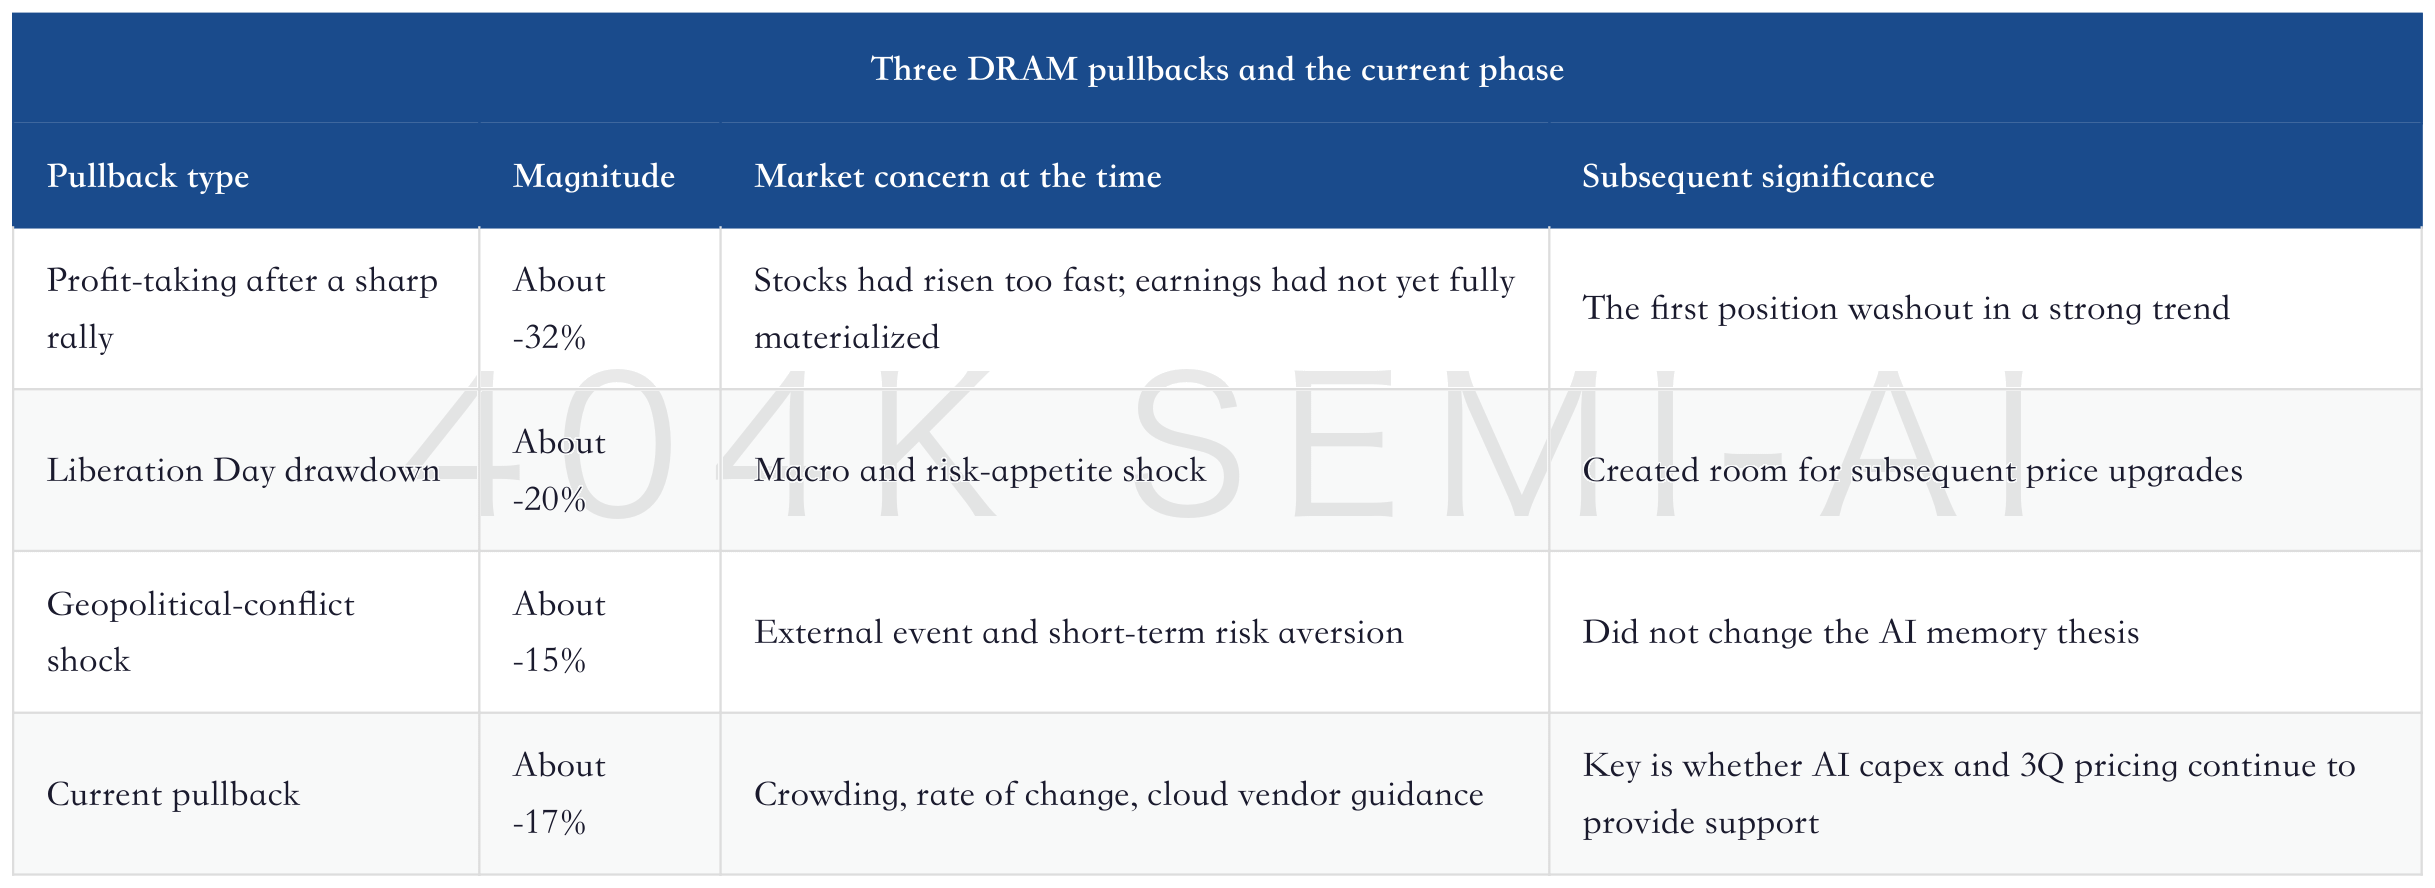
The implication of this table is straightforward: the pullback itself is not the signal; fundamentals after the pullback are the signal. If the pullback occurs while Samsung profit beats expectations, DRAM prices continue to be revised up, SK Hynix management maintains that 3Q commodity memory is strong, and cloud vendor capex is not revised down, then the pullback looks more like de-crowding. If the pullback is accompanied by weaker 3Q cloud vendor guidance, contract prices below expectations, inventory build, and aggressive capex upgrades, then it starts to look closer to a cycle top.
Memory stocks are prone to this kind of “strong earnings but stock down” pattern because memory is a high-beta cyclical industry. The market assigns very high leverage in the early stage of earnings upgrades, then starts worrying in advance about the next reversal when earnings upgrades reach an extreme. AI changes cycle duration and profit quality, but it does not eliminate cyclicality altogether.
The earlier global memory divergence already gave the same clue: 2Q26 is about earnings, 3Q26 is about pricing, and after 4Q26 the question is whether profit can be retained. Morgan Stanley is simply pushing this line to a sharper point: 3Q pricing and cloud vendor guidance will determine whether the pullback is healthy or dangerous.
V. The Price Table Shows DRAM and Legacy Memory Remain Strong, While NAND Requires Structural Selectivity
The hardest underlying evidence in Morgan Stanley’s report is its DRAM and NAND price forecast table. It did not cut all prices. Instead, it raised forecasts for multiple categories in 3Q26E. The new 3Q26E forecasts for PC DRAM, server DRAM, graphics DRAM, consumer DRAM, conventional DRAM, enterprise SSD, and client SSD are generally higher than the old forecasts.
This shows the market is not worried that “memory prices are about to collapse.” It is worried that “prices continue to rise, but the slope of price increases no longer matches the slope of stock prices.” This is important. If price forecasts were cut, that would be a fundamentals issue. If price forecasts continue to be raised while stocks pull back, that is more likely about valuation, positioning, and the future slope.
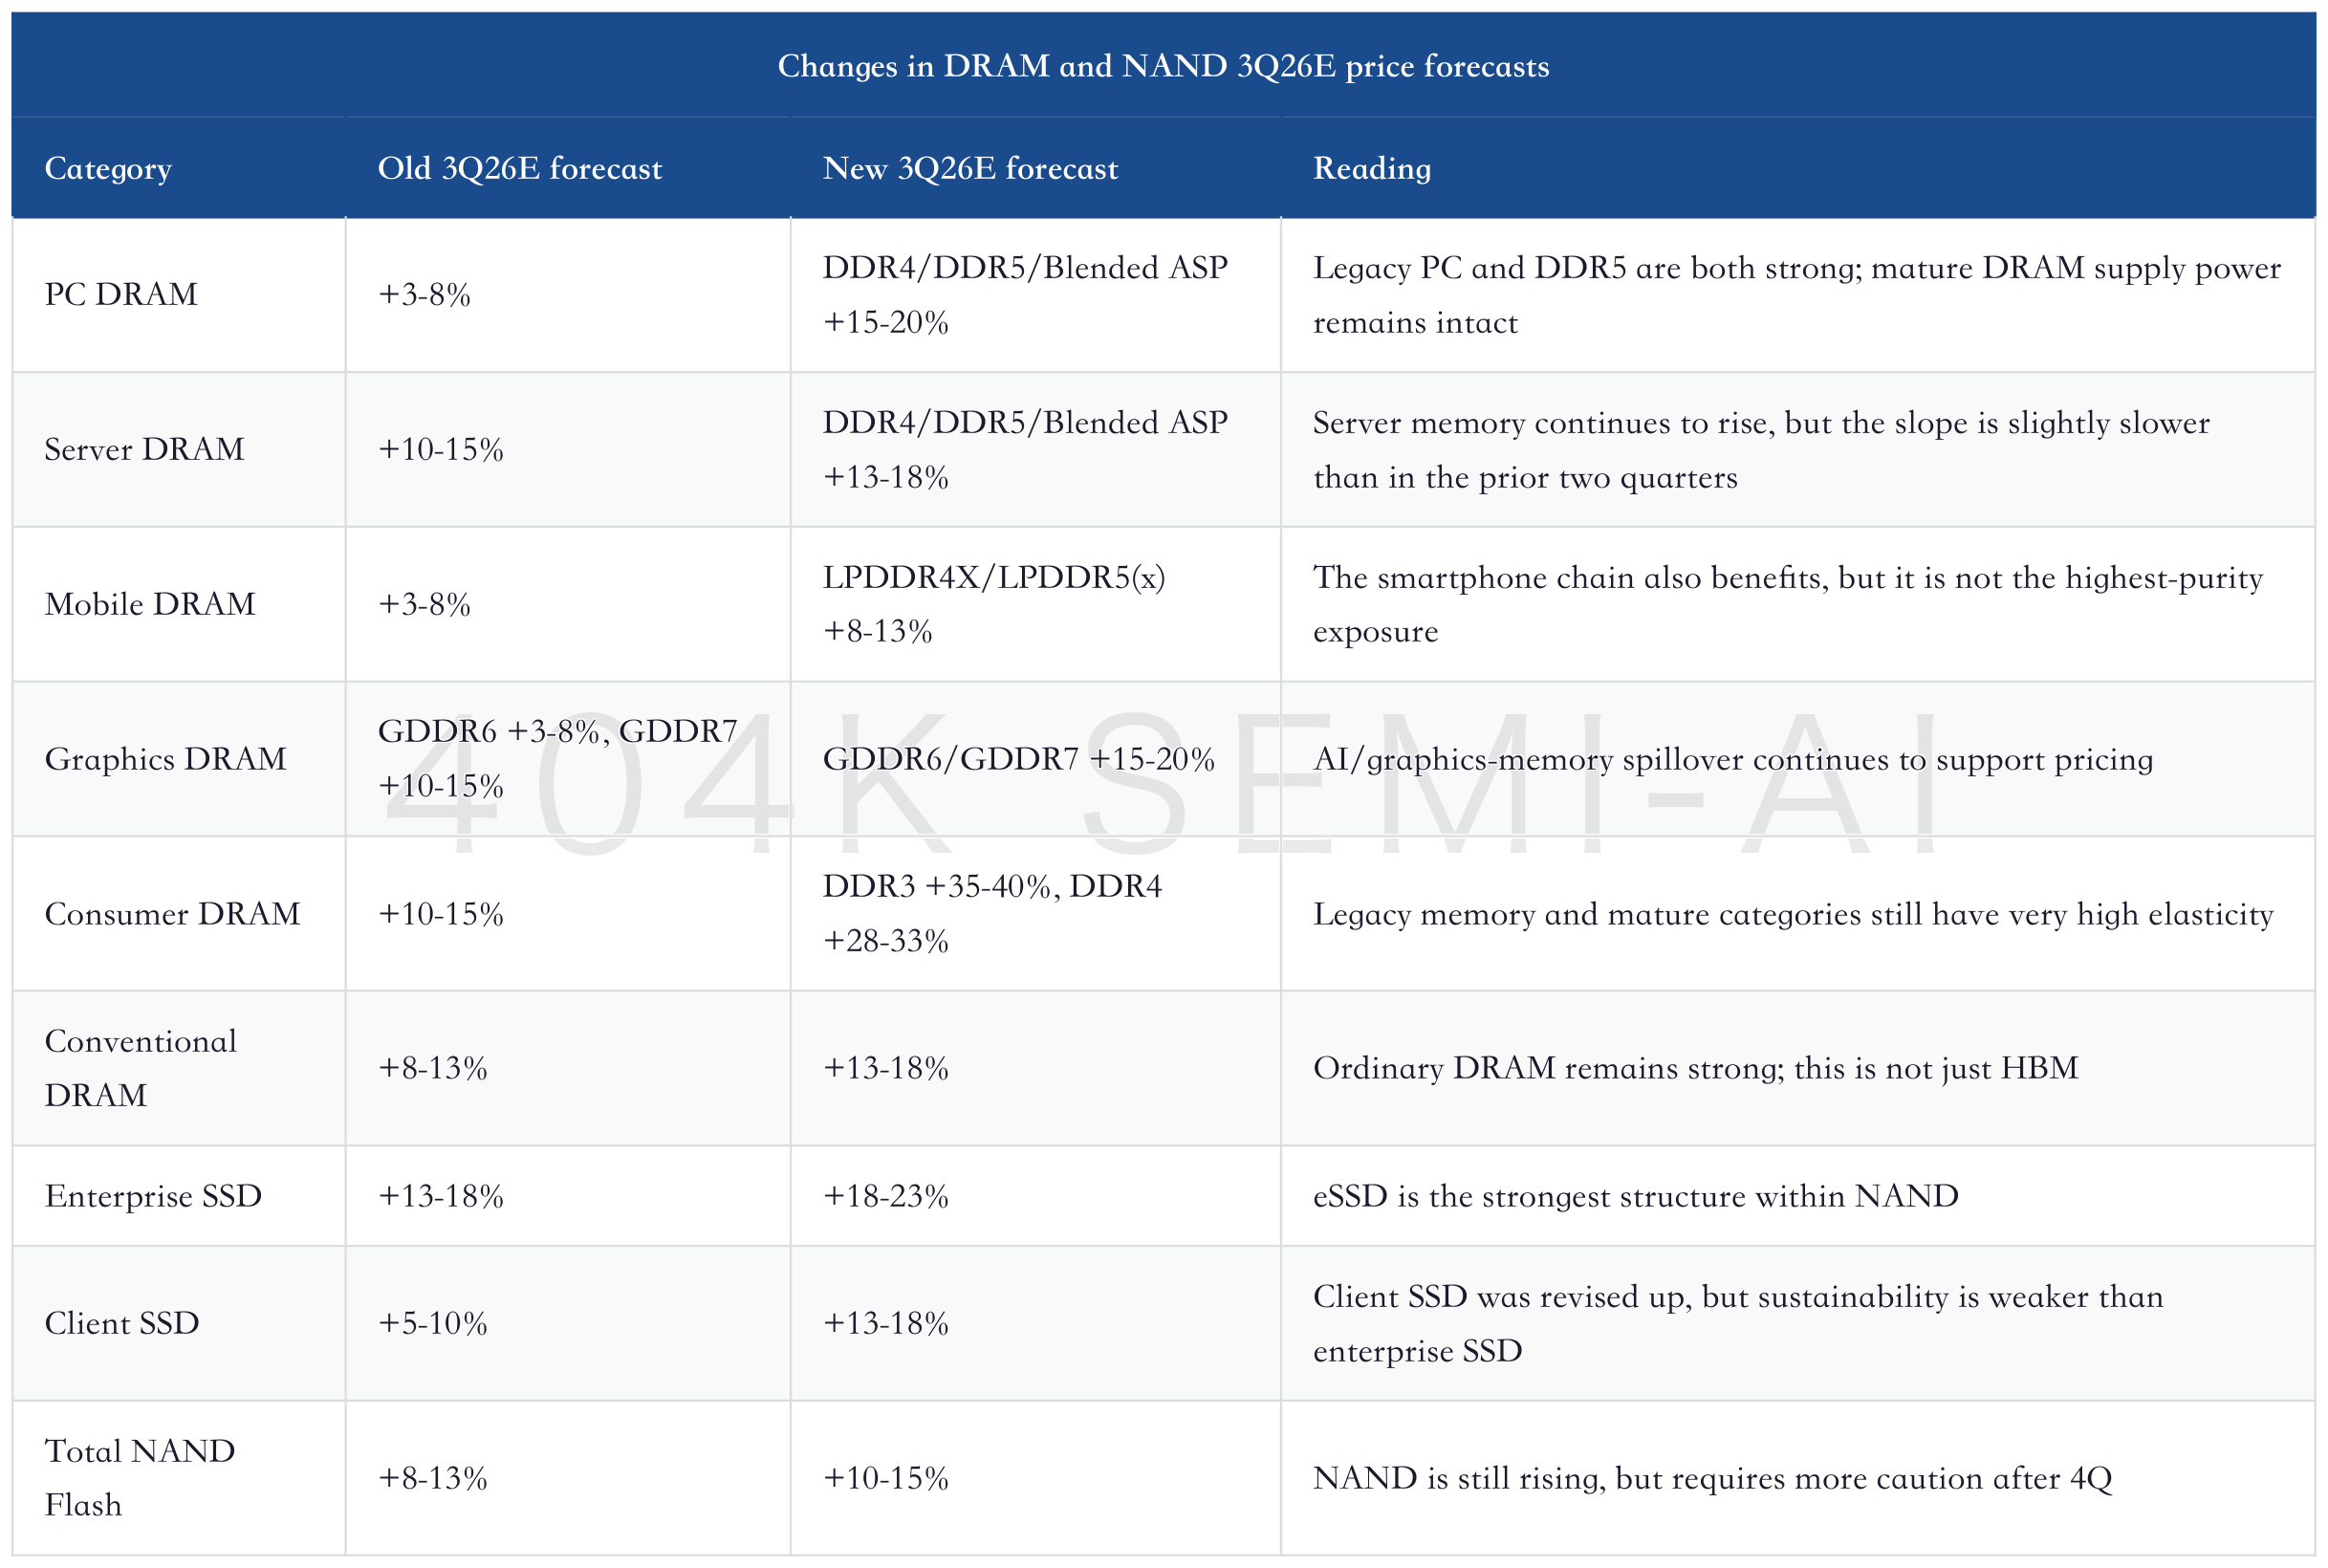
The ranking makes Morgan Stanley’s preference clear: DRAM and legacy memory ahead of NAND, with memory module makers ranked lowest. In plain terms, buying memory cannot just mean buying the two words “price increase.” Investors need to buy the parts behind those price increases that are hardest to replace, closest to AI spending, and least likely to turn into inventory.
Legacy memory is not low-end leftover inventory. It is supply power squeezed out after large manufacturers shifted capex toward HBM, DDR5, and advanced products. The upward revision to 3Q26E price increases for DDR3 and DDR4 in consumer DRAM shows that mature categories still have pricing elasticity. The question is not whether these products have value, but which companies can turn pricing elasticity into gross margin and cash flow.
VI. Why LTAs Have Not Directly Re-Rated Memory Stocks
The biggest puzzle for memory bulls is this: LTAs, SCAs, and NBMs are clearly increasing, so why have valuation multiples not directly moved higher the way they have for AI software or GPUs? Morgan Stanley’s explanation is pragmatic: the market does not disbelieve AI demand; it still remembers past cycles when long-term agreements were renegotiated, customers were forced to take inventory, and inventory eventually came back to hurt profits.
This also explains why memory stocks look “not expensive.” It is not that the market cannot see the profits; it is that the market is discounting those profits as cyclical. For valuations to truly move up a tier, long-term agreements cannot remain only in headlines. They must flow through all three statements: higher gross margins on the income statement, healthy inventory on the balance sheet, and profit converting into free cash flow on the cash-flow statement.
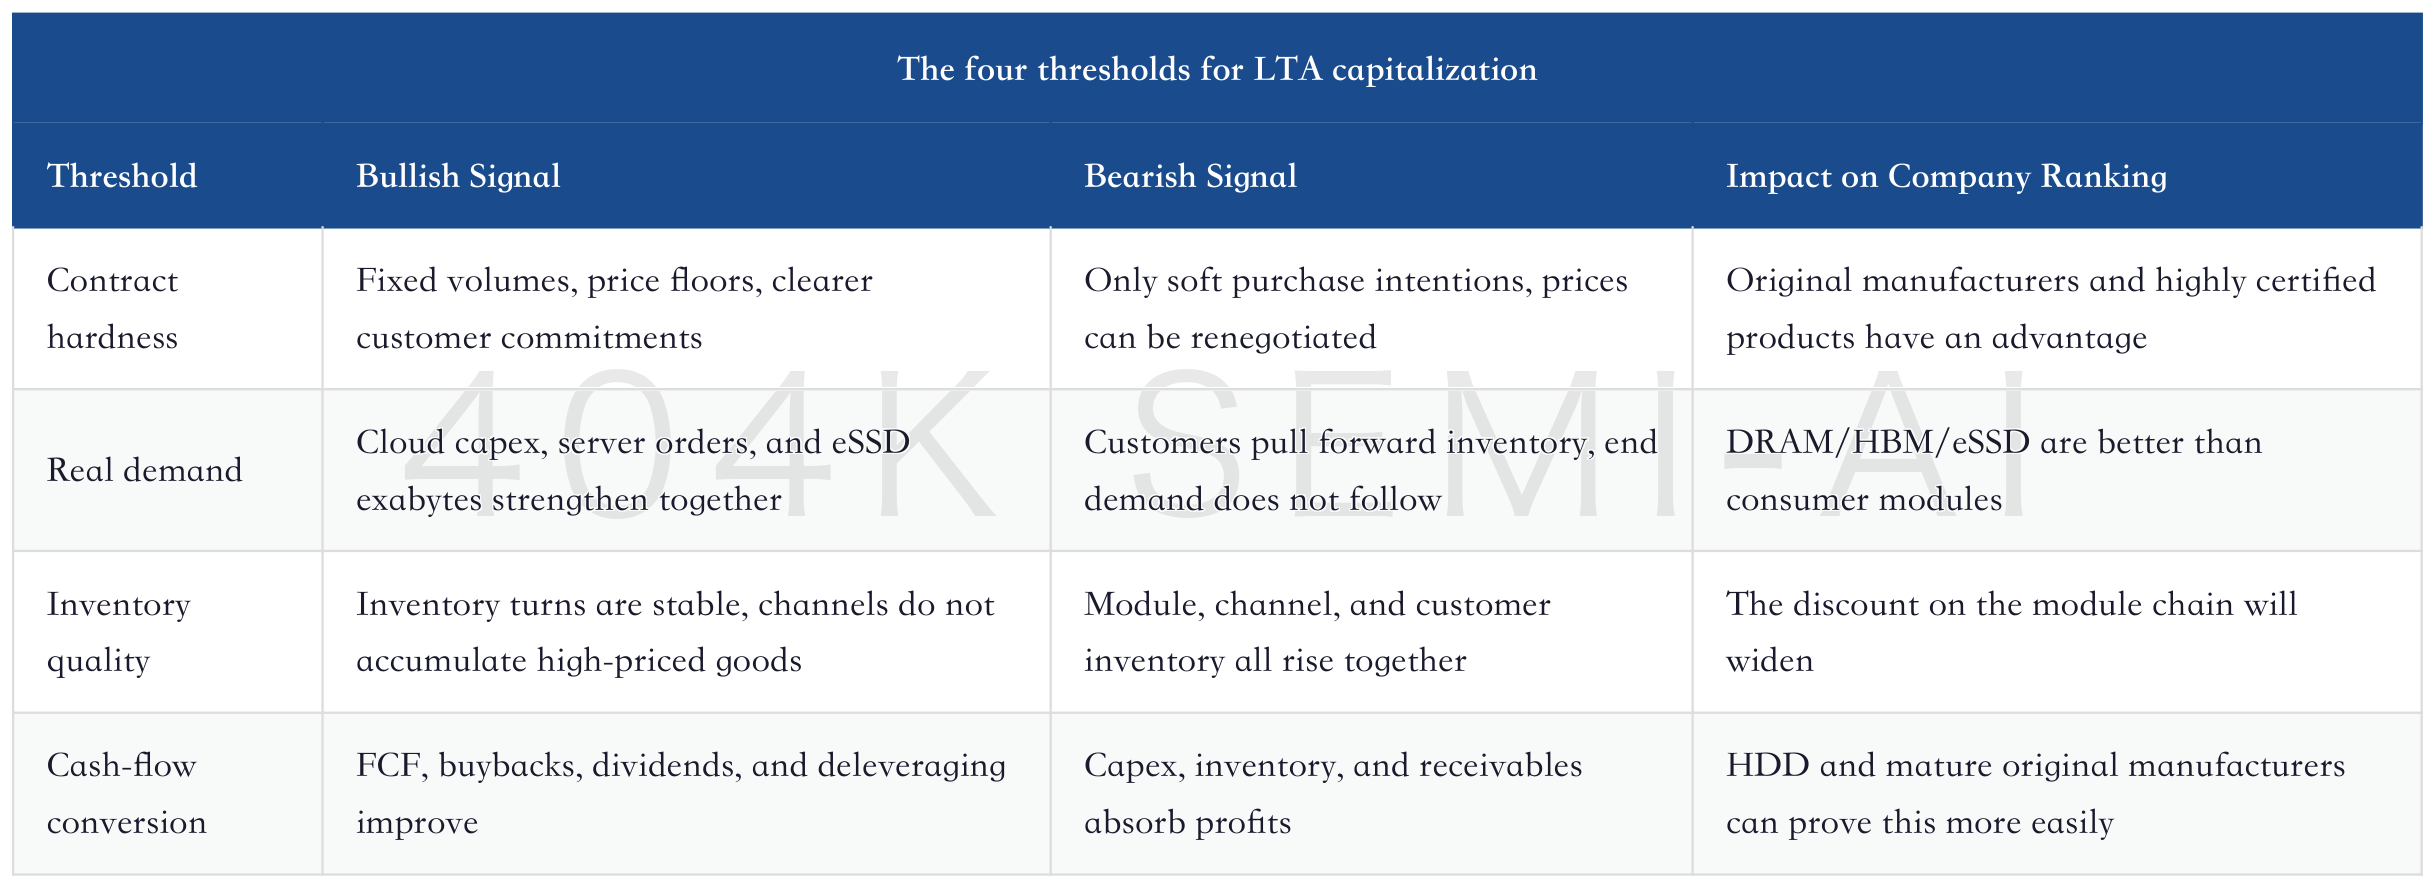
This is also why Morgan Stanley prefers DRAM and legacy memory, rather than modules. Original manufacturers and key legacy categories can directly secure supply rights and pricing. Module companies may benefit in the short term from low-cost inventory, but once the price slope slows, inventory gains can easily become inventory risk. Companies such as Longsys and Techwinsemi are not uninvestable, but they first need to prove controller capability, enterprise SSD certification, and customer mix, rather than relying only on NAND price increases.
Memory Is No Longer Just Cyclical: JPM LTA Breakdown, Agentic AI Memory Multipliers, and a Samsung/Hynix Valuation Rewrite
The key to LTAs is not the contract label, but whether the contract can reduce the cyclical discount applied to peak earnings. The market’s current answer remains restrained: it is willing to revise EPS upward, but is not rushing to assign higher multiples. That restraint is precisely the room for future re-rating, provided reported results and cash flow continue to validate the thesis.
VII. Three Scenarios Around Reported Earnings: How the Pullback Will Be Validated
The most important task next is not guessing one day’s price move, but putting the information before and after reported earnings into a scenario framework. Samsung’s preliminary results have already shown strong profits. SK Hynix will provide a cleaner memory read-through on July 29. Cloud vendors’ 2Q results and 3Q guidance will determine the demand side. If these signals move in the same direction, the pullback is only a positioning reset. If they diverge, share prices will continue to digest valuations through volatility. If they weaken together, concerns about a cycle peak will become more solid.
The first scenario is “strong profits, strong guidance, strong contracts.” Samsung’s reported results show solid contributions from Memory and DS. SK Hynix confirms strong 3Q commodity memory, continued progress on multiple LTAs, and only a modest upward revision to forward capex. Cloud vendors maintain or raise AI capex. Under this combination, the share-price pullback looks more like a position clean-up. Capital will return to DRAM, HBM, eSSD, and HDD cash-flow anchors, and the valuation discount will gradually narrow.
In this scenario, three types of companies benefit most. The first is companies with high HBM and DRAM purity: SK Hynix, Micron, and Samsung Electronics, because they can directly benefit from memory pricing and customer lock-ins. The second is companies with stronger eSSD and NAND profit quality, such as SanDisk, Kioxia, and the high-end enterprise SSD chain, because data-center capacity demand will continue to constrain supply. The third is HDD cash-flow companies. If Seagate Technology and Western Digital continue to see nearline capacity demand and cloud customer lock-ins, the pullback will look more like a re-rating of cash-flow assets.
The second scenario is “strong profits, average guidance, contracts still to be validated.” This is the most likely neutral scenario. 2Q profits remain strong, but management no longer further raises guidance for 3Q and 2H26. Cloud vendors do not meaningfully cut capex, but they also do not give the market a new surprise. In this case, memory stocks will not be invalidated by fundamentals, but valuations will enter a phase of consolidation and rotation. Capital will move from the most crowded pure-play assets into lagging segments, or from higher-beta companies toward companies with clearer cash flow.
In this scenario, stock selection matters more than direction. Samsung Electronics has already delivered a strong preliminary result, so if reported earnings do not contain new segment-level upside, the stock may need to digest it. If SK Hynix only meets expectations, valuation crowding will limit near-term upside. Micron may continue to follow DRAM pricing, but the market will scrutinize SCAs and cash flow more strictly. SanDisk and Kioxia need to prove through eSSD and long-term agreements that NAND is not merely seeing an ordinary price hike. Western Digital and Seagate Technology will gain relative defensiveness from cash-flow visibility.
The third scenario is “strong profits, weakening guidance, inventory emerging.” This is the scenario that would require a real downgrade. It may not begin with the income statement, but with cloud capex, customer resistance to price hikes, inventory turns, new NAND supply, and capex commentary. Historically, the most dangerous phase for memory is often not when profits are weakest, but when profits are very strong while the market starts to see profit quality deteriorate.
If the third scenario materializes, the risk ranking will be clear. Inventory-beta names and the module chain would be cut first, because the market would worry about high-priced inventory and consumer-end resistance to price hikes. Next would be ordinary NAND and companies lacking eSSD certification, because the price slope after 4Q is weaker than DRAM. Then would come high-valuation purity assets, because any uncertainty around share, yield, or capex would be amplified. Only companies with real long-term agreements, customer certifications, and cash flow can preserve valuations under this pressure.
These three scenarios also explain why the headline cannot simply say “cycle peak.” The current evidence has not proven a cycle peak, but it is already enough to show that the market is no longer rewarding upside indiscriminately. Memory is moving from a one-way trade on estimate upgrades to a scenario-based trade on quality. Whether to add after the pullback depends on which scenario a company falls into, not on how far the stock has retreated from its high.
VIII. Company Ranking: Who Is Exposed to Rate of Change, Inventory, and Cloud Guidance
The worst thing to do in a pullback is to put all memory companies in the same basket. Samsung Electronics, SK Hynix, Micron, SanDisk, Western Digital, Seagate Technology, Longsys, and Techwinsemi are all called memory names on the surface, but their true sources of risk are completely different. The ranking clues in Morgan Stanley’s report are “where money is being spent” and “where the bottleneck is.”
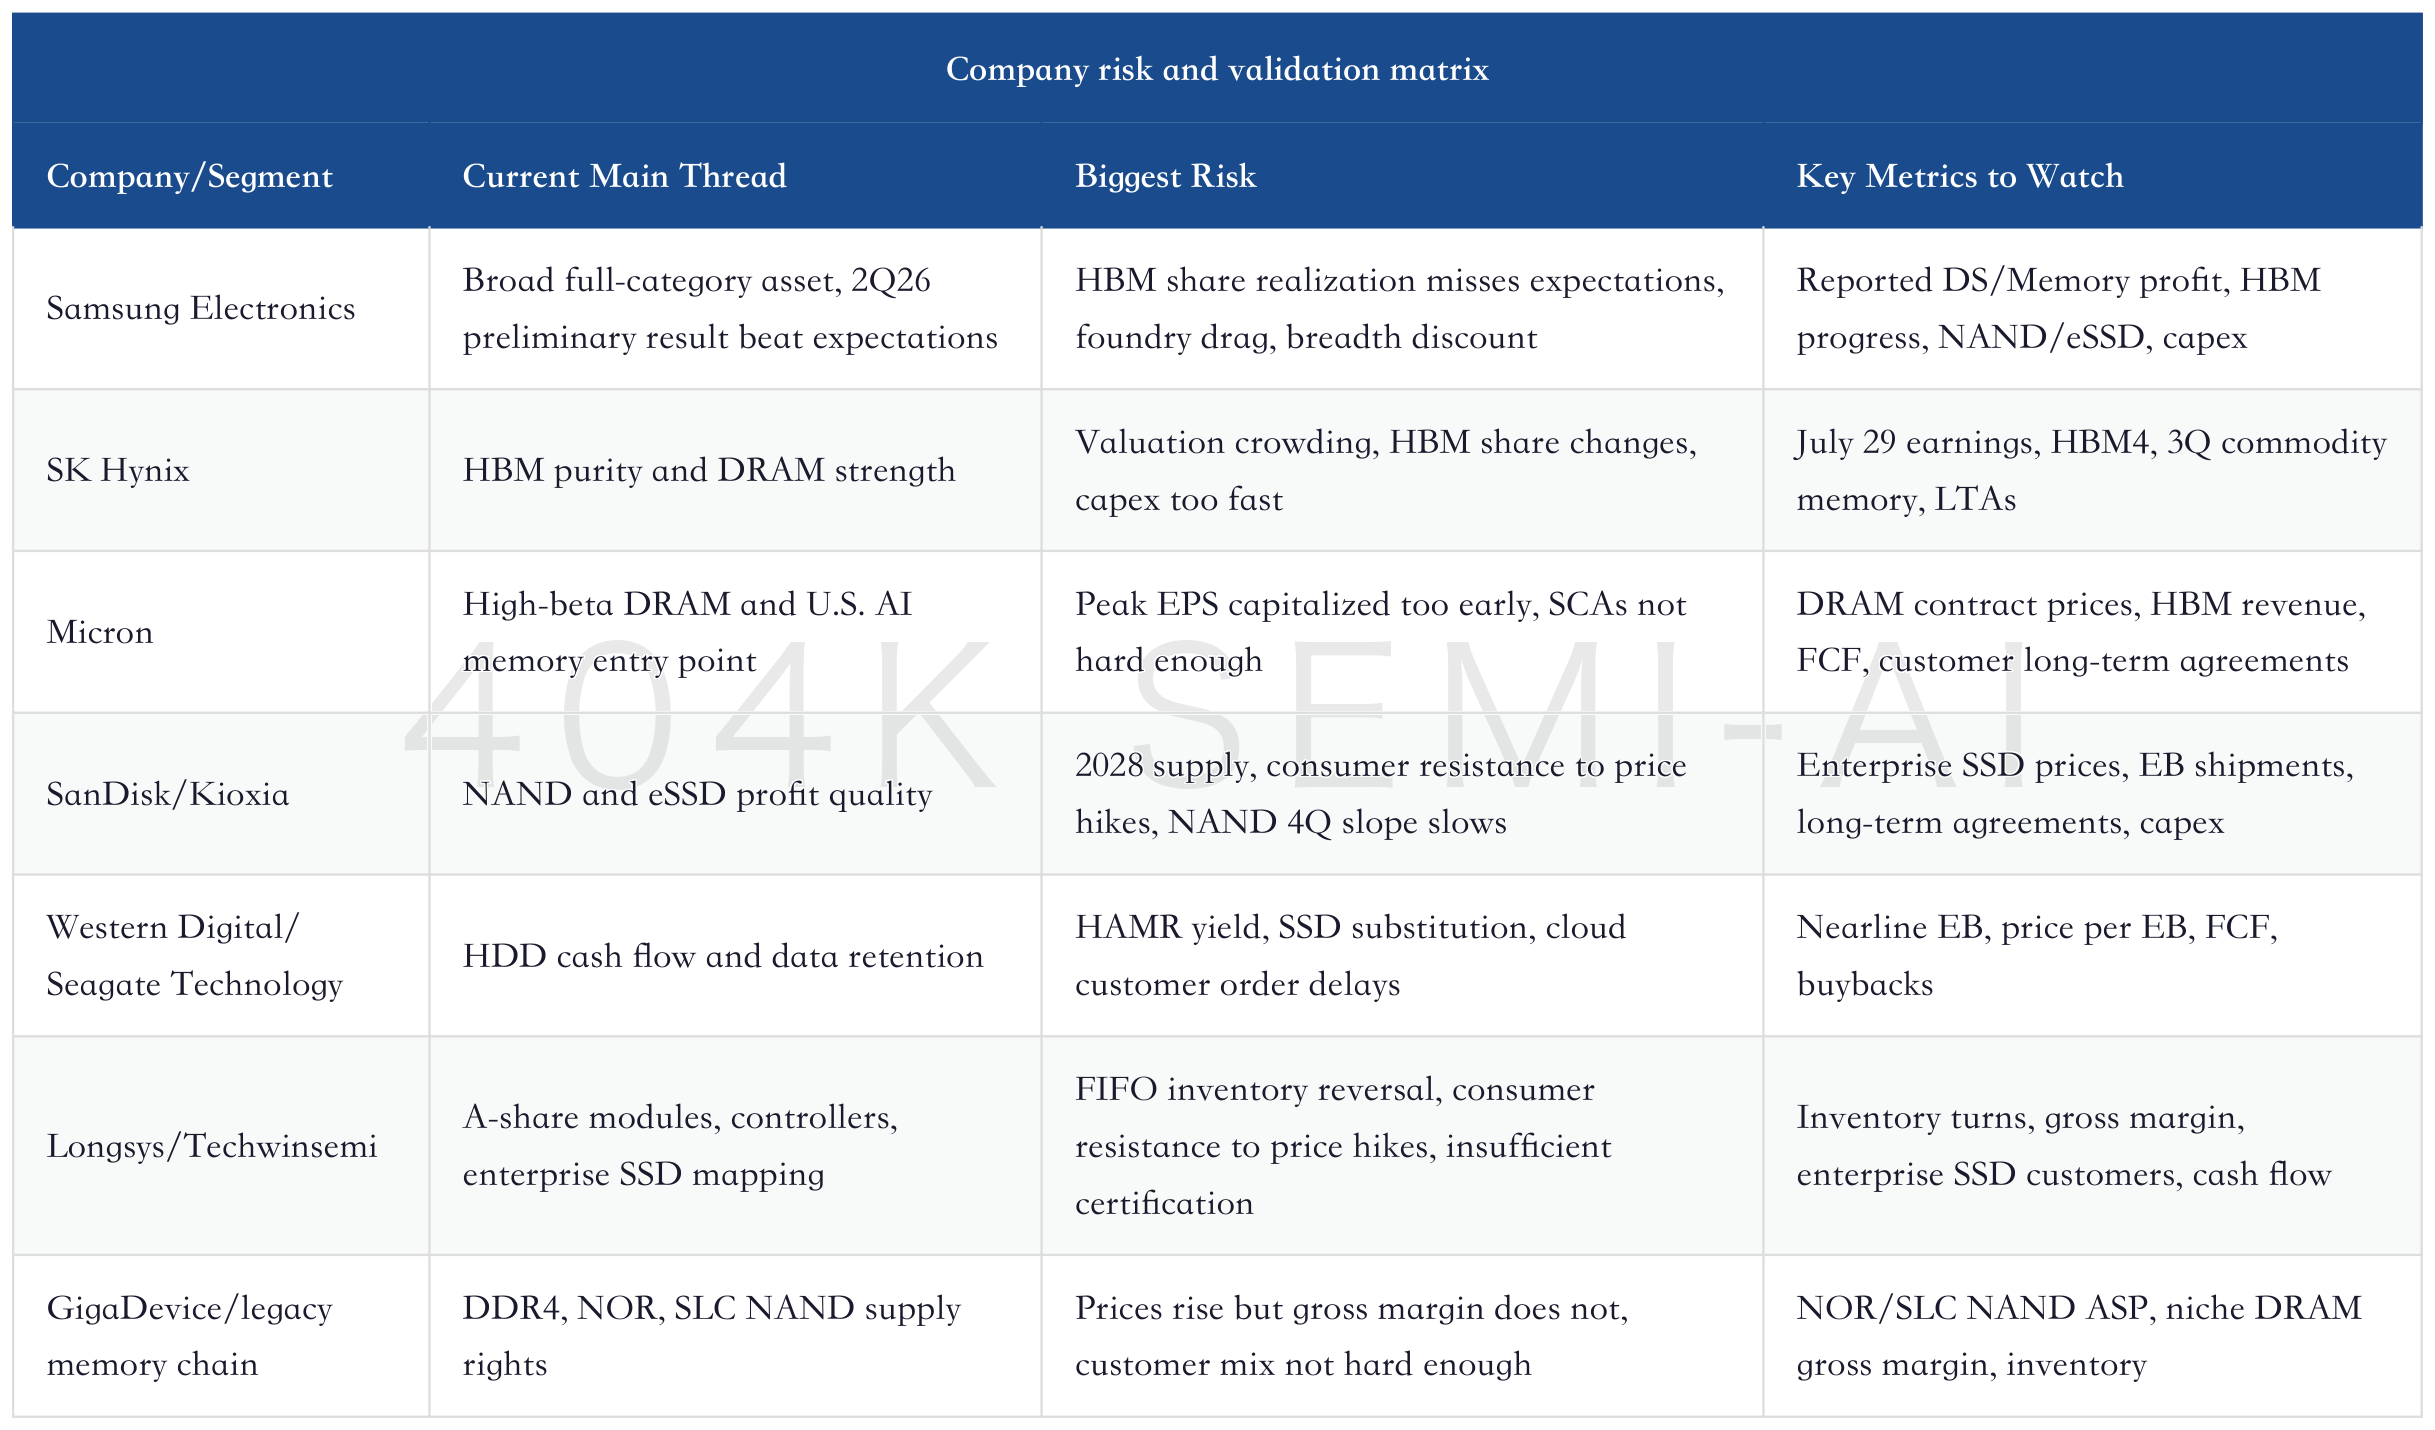
Samsung Electronics is now the fundamental anchor. Its preliminary result was stronger than Morgan Stanley expected, showing that the broad asset base is delivering, but segment details are still not visible at the preliminary stage. The most important items in reported earnings are DS and Memory profit contribution, whether HBM and high-end DRAM continue to advance, and whether NAND moves from price upgrades to profit quality. If reported earnings are strong only because of price, while capex accelerates materially, the market will instead worry about the next supply cycle.
SK Hynix is the purity anchor. Morgan Stanley expects its 2Q26 operating profit to be close to market expectations of about KRW65 trillion, with management commentary broadly in line with consensus. The focus is strong 3Q26 commodity memory, multiple LTA commitments, and only a modest upward revision to forward capex. For SK Hynix, weak earnings are not the biggest risk. The bigger risk is very strong earnings but an overly crowded valuation, where any wording around HBM share or capex is amplified.
SK Hynix Deep Update: Is It Still Expensive? DDR5 Takes Over Price Increases, Korean Exports Surge, and Samsung Catch-Up Risk
Micron is the high-beta validation case. It has already used earnings to prove that the AI memory cycle has entered the delivery phase, but the challenge for Micron is that the market will trade it as peak EPS. As long as DRAM and HBM continue to be revised upward, Micron has strong upside. Once SCAs are not hard enough, cash flow does not follow, or capex accelerates, the market will reapply a cyclical discount.
Micron Earnings Deep Dive: Q3 Results Beat Sharply, AI Memory Supercycle Enters Delivery Phase, How Much Profit Can Long-Term Agreements Lock In?
The common issue for SanDisk, Kioxia, Western Digital, and Seagate Technology is that profit quality must be separated clearly. For SanDisk and Kioxia, the focus is NAND/eSSD. For Western Digital and Seagate Technology, the focus is HDD cash flow. In Morgan Stanley’s price table, enterprise SSD 3Q26E was revised up to 18-23%, showing that eSSD remains strong. But Total NAND Flash is only 0-5% by 4Q26E, showing that ordinary NAND’s forward slope is weaker than DRAM. HDD does not rely on price slope; it relies on cloud customer lock-ins and cash flow to prove that the cyclical discount is falling.
SanDisk Deep Update: Jefferies’ $3,000 Target Price, eSSD Share Recovery, and How NAND LTAs Re-Rate Profit Durability
Micron’s risk points require more detailed scrutiny. Micron is not Samsung, and it is not SK Hynix. Its biggest attraction is high beta, and its biggest risk is also high beta. If DRAM contract prices continue to deliver according to Morgan Stanley’s new forecasts, HBM revenue keeps ramping, and SCAs and customer lock-ins are hard enough, Micron will remain a highly elastic part of the memory rally. If 3Q pricing falls short of the new forecast, HBM catch-up does not exceed expectations, and capex and inventory move first, Micron will be more easily discounted by the market on peak EPS than broader assets.
The risk for SanDisk and Kioxia is not “whether NAND prices rise,” but “whether the quality of the price increase is high enough.” Enterprise SSD price increases and eSSD EB growth can support profits, but ordinary NAND, the handset chain, and client SSDs are more likely to face customer resistance to price hikes. If enterprise SSD remains strong, long-term agreements are hard, and customer certifications advance, NAND-purity assets still have re-rating room. If Total NAND’s slope falls after 4Q, expectations for 2028 new supply are pulled forward, and consumer-end inventory spills over, NAND stocks will be the first to face valuation pressure.
The risk points for Western Digital and Seagate Technology are more like those of cash-flow assets. HDD companies do not need to prove they are HBM-style growth stocks. They need to prove that nearline HDD demand, cloud customer lock-ins, price per EB, and HAMR yield can make FCF more stable. If capacity shipments continue to grow, FCF improves, and buybacks and dividends are supported, they will be more resilient in a memory pullback. If the SSD cost curve declines rapidly, or HAMR yield affects deliveries, the cyclical discount on HDD will widen again.
Samsung Electronics and SK Hynix also face different risks. Samsung’s risks are insufficiently fast HBM catch-up, foundry drag, and a breadth discount. SK Hynix’s risks are HBM share changes, valuation crowding, and overly high capex expectations. Samsung’s advantage is that the preliminary result has already shown very strong group profits. As long as reported earnings show Memory quality and HBM progress, it can continue to serve as the industry’s fundamental anchor. SK Hynix’s advantage is the highest HBM purity, but that also makes the market more likely to assess it by the strictest standards.
A-shares and the module chain require special attention to inventory. Longsys, Techwinsemi, and related controller/module companies may have significant earnings elasticity in an upcycle, but they are not original manufacturers and cannot simply benefit from the same reduction in cyclical discount. What they need to prove is not “upstream price increases,” but enterprise SSD customers, controller capability, branded channels, inventory turns, and operating cash flow. If that evidence fails to keep up, profits generated only by low-cost inventory will be discounted by the market.
IX. Cloud Providers Are the Real Referee for the Next Round
One important line in Morgan Stanley’s report is that market reaction at this stage depends more on cloud providers’ results and guidance than on memory companies’ own bullish commentary. The reason is simple: memory companies are naturally bullish in an upcycle; customers and cloud providers determine whether demand can continue to materialize. If cloud providers maintain or raise capex, pullbacks in memory are opportunities to look for entry points. If cloud-provider guidance weakens, even optimistic memory-company commentary will be hard to offset.
The cloud-provider question has become more complicated. The market has begun debating whether the largest AI spenders have compute capacity to sell. Bears will interpret this as AI overbuild; bulls will interpret it as cloud providers monetizing compute and improving returns on capex. The two interpretations are very different. The real answer is not in headlines, but in 2Q results, 3Q guidance, capex plans, AI service revenue, GPU/ASIC deployment pace, and customer demand.
Another new variable is token-cost optimization. In the past, many enterprises encouraged employees to use more AI and generate more tokens; this was token maxing. Now some enterprises are routing simple queries to cheaper open-source models and complex tasks to frontier models; this is token minimization. It may not reduce total AI demand, but it could change the slope of compute and storage demand. For memory, the key is not the decline in token unit cost, but whether AI application penetration can unlock larger demand at lower cost.
So cloud-provider earnings over the next few weeks should be assessed on three levels. First, whether absolute capex is being revised down. Second, whether AI services and enterprise demand are supporting continued buildout by management teams. Third, whether low-cost models and orchestration layers are expanding AI usage rather than merely reducing unit costs. If all three are positive, memory bulls will regain control of the narrative. If capex is cut, bears will push the “compute overcapacity” narrative to the front.
On cloud-provider earnings calls, the most important thing to listen for is not a single line that “AI demand remains strong,” but whether management ties demand to orders and deployment schedules. For example: whether GPU cluster delivery remains constrained, whether both internal model training and external cloud-customer inference are increasing, whether AI service revenue can already partly cover capital expenditure, and whether enterprise customers are moving from pilots into production. If these comments become more specific, the credibility of memory demand will be higher. If all that remains is broad bullish language while capex and order commentary turn cautious, memory stocks will first face valuation compression.
It is also important to listen to how cloud providers describe “efficiency gains.” Efficiency improvement itself is not negative. Cheaper models, better orchestration layers, and higher GPU utilization can reduce per-inference cost and may also expand total usage. For memory, the real dividing line is whether total data volume, total request volume, and total workloads continue to increase. If efficiency gains bring more applications and more data retention, eSSD and HDD still benefit. If efficiency gains simply lead enterprises to reduce compute procurement, the slope of storage demand will decline as well.
The third detail is the structure of AI infrastructure. GPU and ASIC expansion directly drives HBM and advanced DRAM. Server-cluster expansion drives DDR5, SSDs, and networking equipment. Data lakes, RAG, logs, and model-version management drive eSSD and nearline HDD. If cloud providers only emphasize training clusters and not inference, enterprise applications, and data platforms, storage demand will tilt more toward HBM and high-end DRAM. If inference and data platforms also expand in parallel, the evidence for the capacity layer and HDD cash flow will be firmer.
The fourth detail is customer type. Internal AI use, external cloud customers, enterprise SaaS customers, AI startups, and government/industry customers do not pull storage demand in the same way. Internal training is more biased toward HBM and high-speed storage. External inference is more biased toward continuous service and capacity expansion. Enterprise customers care more about stability and data retention. If cloud providers disclose demand from a broader customer base rather than a small number of large-model customers, the durability of the memory cycle will be stronger.
