
Memory Deep Dive: Micron’s 40% Buyback Potential, Cash Flow Re-Rating, and Cyclical Risks
目录
TL;DR
I. Four Preconditions for 40% Buyback Potential
II. Where the Funding for 40% Comes From: Breaking Down $400 Billion and 47%
III. Why UBS Believes Micron Should Not Be Valued Solely as a Traditional Cyclical Stock
IV. HBM Is the Entry Point for a Valuation Reset, While Commodity DRAM and NAND Remain the Cash-Flow Foundation
V. Capital Expenditure Is the Most Important—and Most Easily Underestimated—Counterargument to the 40% Buyback Case
VI. How Actual Buybacks Would Change Micron’s Cyclical Profile
VII. Why 40% Is Difficult to Achieve as Stated but Still Matters for Valuation
VIII. Memory Cash Flow in Cross-Section: Why Micron Stands Out
IX. +25.7 Crowding: A Good Company Is Not the Same as a Good Trade
X. Three Scenarios: When Is a 40% Buyback Most Realistic?
XI. The 12 Most Important Indicators to Track Over the Next 12 Months
XII. Conclusion: Micron’s Re-Rating Will Be Complete When Cash Actually Becomes Fewer Shares
本内容基于公开资料和研报数据整理,不构成任何投资建议,不代表任何个人观点,仅供学习参考,请理性阅读
The most important change at Micron is that the memory upcycle is beginning to flow from the income statement into cash flow—and could ultimately translate into large-scale share repurchases.
TL;DR
UBS estimates that after Micron’s (MU) share-repurchase restrictions expire on December 9, 2026, the company could theoretically repurchase more than 40% of its shares by the end of 2028 if it uses all subsequent free cash flow for buybacks and its share price remains at the report-date level. This is a scenario analysis, not a buyback plan announced by Micron.
The 40% figure is not arbitrary. UBS expects Micron to generate more than $400 billion in cumulative free cash flow through 2028, while a cross-sectional chart shows cumulative free cash flow equivalent to approximately 47% of its report-date market capitalization. Both figures are exceptionally strong, but each must be understood using the original report’s methodology; they should not be mechanically reconciled without accounting for the forecast period and market-date assumptions.
Cash-flow realization depends on product-mix improvements driven by HBM, high-capacity server DRAM, low-power memory, and advanced NAND, as well as industry supply discipline. Peak earnings can break through the traditional cycle only if structural and contracted profits account for a larger share of total earnings.
Micron trades at approximately 4.01x forward-12-month EV/revenue, versus about 3.67x for SK Hynix, a gap of roughly 0.3x. UBS argues that Micron has historically commanded a premium and that its DRAM density, 200-plus-layer NAND, low-power memory, energy efficiency, and cost per bit support a re-rating. However, the 0.3x gap alone does not establish undervaluation.
The memory sector’s cumulative free cash flow through 2028 is approximately 28% of market capitalization, versus about 47% for Micron, 20% for Western Digital, and 17% for Seagate Technology, making memory the strongest cash-flow sector in UBS’s coverage. At the same time, the sector’s crowding score is approximately +19.3, versus about +25.7 for Micron. Strong cash flow and elevated crowding coexist, meaning that even a correct fundamental thesis can suffer severe drawdowns.
Micron’s true validation chain is “pricing and shipment growth—higher operating cash flow—controlled capital expenditure—free cash flow realization—actual buybacks.” If any link breaks, the 40% buyback case reverts from a capital-return thesis to a theoretical ceiling in the model.
I. Four Preconditions for 40% Buyback Potential
The most important point in this UBS report on Micron is not that the stock trades about 0.3x cheaper than SK Hynix, nor that cumulative free cash flow through 2028 is expected to exceed $400 billion. It is how these two factors could ultimately translate into shareholder returns.
The original report is explicit: Micron remains subject to share-repurchase restrictions until December 9, 2026. Once those restrictions expire, if the company uses all subsequent free cash flow for buybacks, then at the report-date share price it could theoretically repurchase more than 40% of its shares by the end of 2028.
This statement depends on four conditions. If any one is not met, the 40% figure no longer applies.
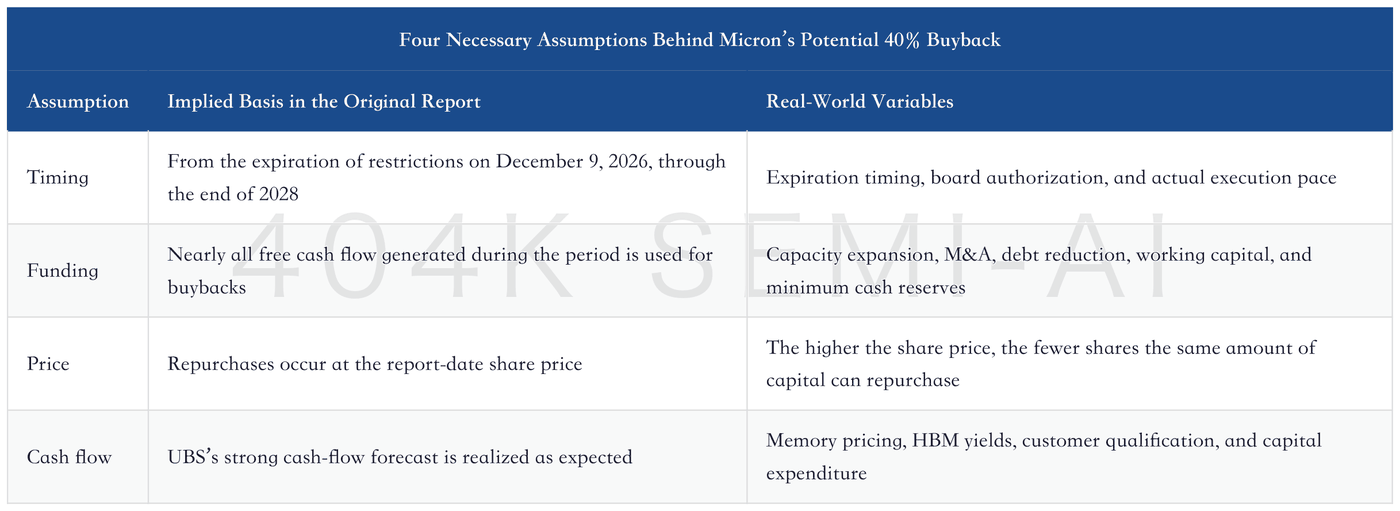
Therefore, “repurchasing more than 40% of the company’s shares” is not the same as “committing cash equivalent to 40% of market capitalization.” The former is a theoretical share count derived from fixed assumptions for the share price, cash flow, and an extreme capital-allocation policy. The latter could be misread as a confirmed funding plan. Micron has made no such corporate commitment in this report.
The analysis remains important, however. It reveals how the memory cycle is changing. Previously, the market focused only on how high earnings per share could rise. It is now asking how much cash the upcycle can generate and whether that cash can directly reduce the share count. If buybacks actually occur, cyclical profits would translate through a lower share count into a higher EPS base for the next cycle—creating more lasting value than a one-off earnings peak.
II. Where the Funding for 40% Comes From: Breaking Down $400 Billion and 47%
The printed figure on the first page of the UBS report projects that Micron will generate more than $400 billion in cumulative free cash flow through 2028. A cross-sectional chart in the report also shows Micron’s cumulative free cash flow over the same period at approximately 47% of its report-date market capitalization, placing it among the highest in UBS’s coverage.
These two figures may appear directly reconcilable, but they should not be treated that way. The $400 billion figure is the cumulative absolute free cash flow generated by UBS’s model, while the 47% figure uses report-date market capitalization as the denominator. The precise forecast starting point, quarterly distribution, share-price date, net debt, and methodological adjustments could all affect the result. This report treats them as two pieces of evidence pointing in the same direction—that UBS expects Micron to generate exceptionally strong cash flow—rather than combining them into a new formula that has not been validated against the original model.
The sources of free cash flow can be divided into four layers:
Memory pricing. Tight DRAM and NAND supply-demand balances raise average selling prices, providing the most direct source of earnings leverage.
Product mix. A higher contribution from HBM, high-capacity server DRAM, low-power memory, and premium NAND improves revenue per unit and gross margins.
Operating leverage. Fabs have high fixed costs, so rising revenue and utilization can drive even faster earnings growth.
Capital discipline. Earnings become free cash flow only when capital expenditure and working-capital growth remain below operating cash-flow growth.
The first three layers explain why earnings grow; the fourth determines why shareholders ultimately receive cash. This is also one of the most frequently overlooked aspects of the memory industry: a company can report record earnings yet fail to generate comparable free cash flow because of large-scale capacity expansion, equipment prepayments, and inventory accumulation.
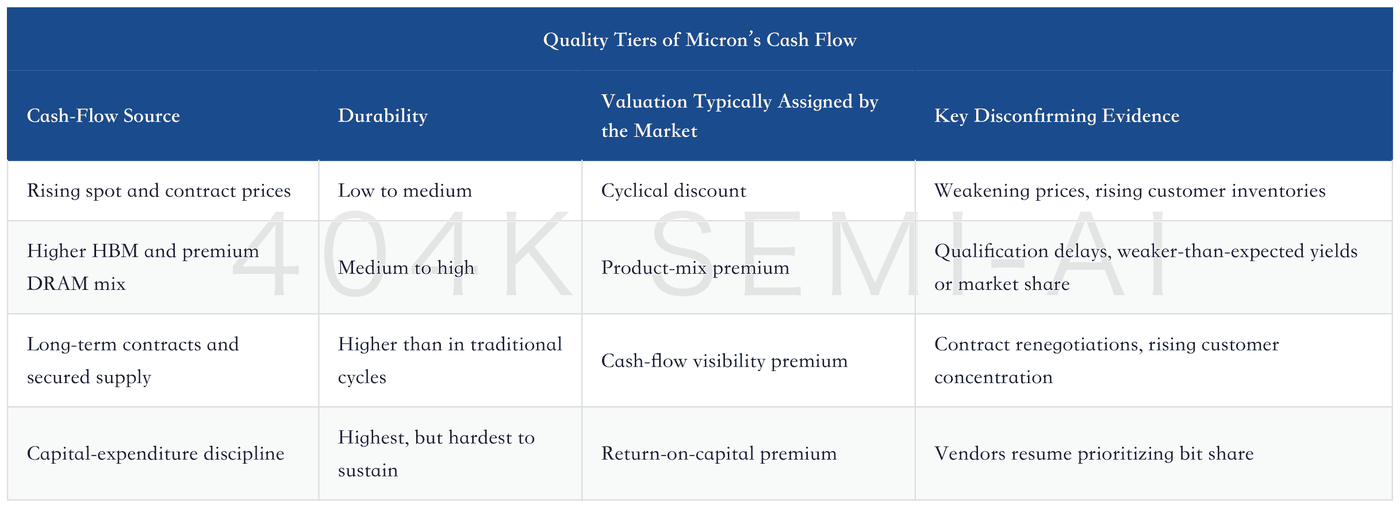
Whether Micron can be re-rated depends on whether the latter three cash-flow categories increase their contribution. If free cash flow is driven primarily by short-term price increases, cumulative free cash flow equivalent to 47% of market capitalization may instead indicate that the market is still discounting the next downturn. Only if product mix, contracts, and capital discipline improve together can this ratio support buybacks and long-term per-share value creation.
III. Why UBS Believes Micron Should Not Be Valued Solely as a Traditional Cyclical Stock
UBS’s chart shows Micron trading at approximately 4.01x forward-12-month EV/revenue, versus about 3.67x for SK Hynix, a gap of roughly 0.3x. The report argues that this gap is below the premium Micron has historically commanded over SK Hynix.
Part of the historical premium may reflect differences in how the US and South Korean capital markets value cyclical stocks, but UBS’s core rationale remains technology and cost. At its 1-alpha and 1-beta DRAM nodes, Micron achieved meaningful density improvements without immediately relying on extreme ultraviolet lithography. It is also competitive in transitions to 200-plus-layer NAND, low-power memory, energy efficiency, and cost per bit.
