
Memory Deep Dive: Memory Stocks Pull Back, but DRAM Prices Are Surging, NAND Is Moving Past Restocking, and KV Cache Is Pushing AI Demand Toward SSDs
目录
Too Long; Didn’t Read
1. UBS’s Shift Is Not Simply More Optimism on HBM; It Puts Memory First in Asia-Pacific Technology
2. Agentic AI Expands Memory Demand From Beside the GPU to Beside the CPU
III. NAND Logic Shifts from Inventory Replenishment to KV Cache Tiering
IV. LTA Shifts the Valuation Anchor for Cyclicals from Peak Earnings to Cash-Flow Visibility
V. Price Increases and Revenue Scale Are Equally Aggressive, and This Is Also the Most Fragile Point
VI. In Single-Stock Ranking, Samsung Electronics Is the Most Comprehensive, SK Hynix the Purest, Nanya Technology the Most Leveraged, and Kioxia Holdings the Most Exposed to NAND Beta
VII. Trading This Memory Cycle Requires Tracking Three Worldviews at Once
VIII. Why UBS Is Willing to Extend the Cycle to 2028
IX. How This Re-Rating Differs from Previous Price-Up Cycles
X. A-Share/Hong Kong Mapping: Do Not Mechanically Equate the Global Memory View with All Domestic Memory Stocks
XI. The Key to Valuation Rerating Is Splitting Profit Elasticity into Four Accounts
XII. Falsification Checklist: Where This Super Cycle Would First Show Cracks
13. How to Validate UBS’s Framework Through Upcoming Earnings
14. Stress Test: Which Discounted Variables Would Hurt UBS’s Model Most
15. Portfolio Ranking: Buy Certainty First, Then Elasticity
XVI. Conclusion: UBS Is Buying Not Price Increases, but an Upgrade in the Asset Attributes of the Memory Industry
本内容基于公开资料和研报数据整理,不构成任何投资建议,不代表任何个人观点,仅供学习参考,请理性阅读
Memory stocks have pulled back in the near term, but UBS is raising both its pricing and demand tables: DRAM/DDR prices rise sharply across multiple quarters in 2026, HBM ASP still grows 61% YoY in 2027, and NAND is being pulled back into the AI trade by KV cache and SSD demand. The key debate is whether cloud providers can absorb this round of price repricing.
Too Long; Didn’t Read
UBS puts memory in the top slot. Within Asia-Pacific technology, UBS ranks Memory above WFE, OSATs, and server ODMs, while remaining cautious on PCs, smartphones, and displays. The implication is that memory is no longer just the high-beta segment within the semiconductor cycle; it is the hardware category most directly absorbing incremental capex during the diffusion phase of agentic AI.
The pricing table is more aggressive than the demand table. In UBS’s model, DRAM blended ASP, including HBM, rises 80.5% QoQ in 1Q26 and another 53.4% in 2Q26. Looking only at DDR ASP, the increases are even higher, at 97% and 60% respectively. This is not a one- or two-quarter repair cycle. Prices surge in 2026 and continue to rise sequentially in 2027.
The DRAM cycle is extended to 2Q28. UBS expects the DRAM upcycle to last until 2Q28 and the NAND upcycle until 4Q27, while raising 2026 DRAM bit end-demand growth to 21% and 2027 growth to 36%. The key point is not only that 2026 is strong, but that 2027 continues to accelerate, meaning the market’s prior cycle framework, which discounted peak earnings in 2026, is no longer sufficient.
The demand theme is expanding from HBM to DDR. HBM remains essential for AI parallel computing, but UBS’s real new call is on server DDR. Agentic AI will lift demand for CPUs and head nodes. UBS expects server DDR bit demand to grow 45% in 2026 and 72% in 2027, with server DRAM rising from 33% of total DRAM bits in 2025 to 60% in 2027.
The new variable for NAND is KV cache. UBS believes AI inference will create large amounts of KV cache, with active data staying in faster storage layers, while inactive cache and idle cache move down to TLC SSDs and QLC SSDs respectively. Corresponding server SSD bit demand grows 56% in 2026 and 47% in 2027, while NAND bit end-demand growth rises from 20% in 2026 to 23% in 2027. This shows NAND is no longer relying only on traditional restocking.
LTAs change how memory is valued. UBS expects enhanced LTAs to cover 30%-40% of industry shipments, with 20%-30% entering fixed volume-price structures. Long-term agreements may suppress the most extreme contract prices in the upcycle, but they raise the bottom in the downcycle and reduce earnings and cash-flow volatility. For companies such as Samsung, SK Hynix, Micron, and Kioxia, the valuation anchor shifts from single-year PE and PB toward through-cycle ROE and FCF visibility.
1. UBS’s Shift Is Not Simply More Optimism on HBM; It Puts Memory First in Asia-Pacific Technology
The most important change in this UBS strategy report is that memory has been upgraded from “a high-beta sub-theme in the AI supply chain” to the top priority in Asia-Pacific technology portfolios. In the opening Q&A;, the report gives a clear preference ranking: Memory > WFE > OSATs > Server ODMs, while remaining cautious on PCs, smartphones, and displays. This ranking matters more than simply raising the target price on a single memory stock, because it represents a change in sector weighting.
Under the old framework, memory stocks mainly rose for three reasons: HBM shortages, DRAM contract-price recovery, and NAND inventory drawdown. The new framework adds three variables: agentic AI drives CPUs and head nodes, server DDR becomes the largest incremental driver, and KV cache pulls SSDs and NAND back into the AI trade. UBS’s change in view effectively rewrites memory from an auxiliary material beside GPUs into the memory and storage foundation of AI data centers themselves.
AI Drives a Sector-Wide Revaluation of Memory: Who Has the Most Pricing Power Across DRAM, NAND, SSD, and HDD, as Samsung, SK Hynix, SanDisk, Western Digital, and Seagate Earnings Corroborate One Another
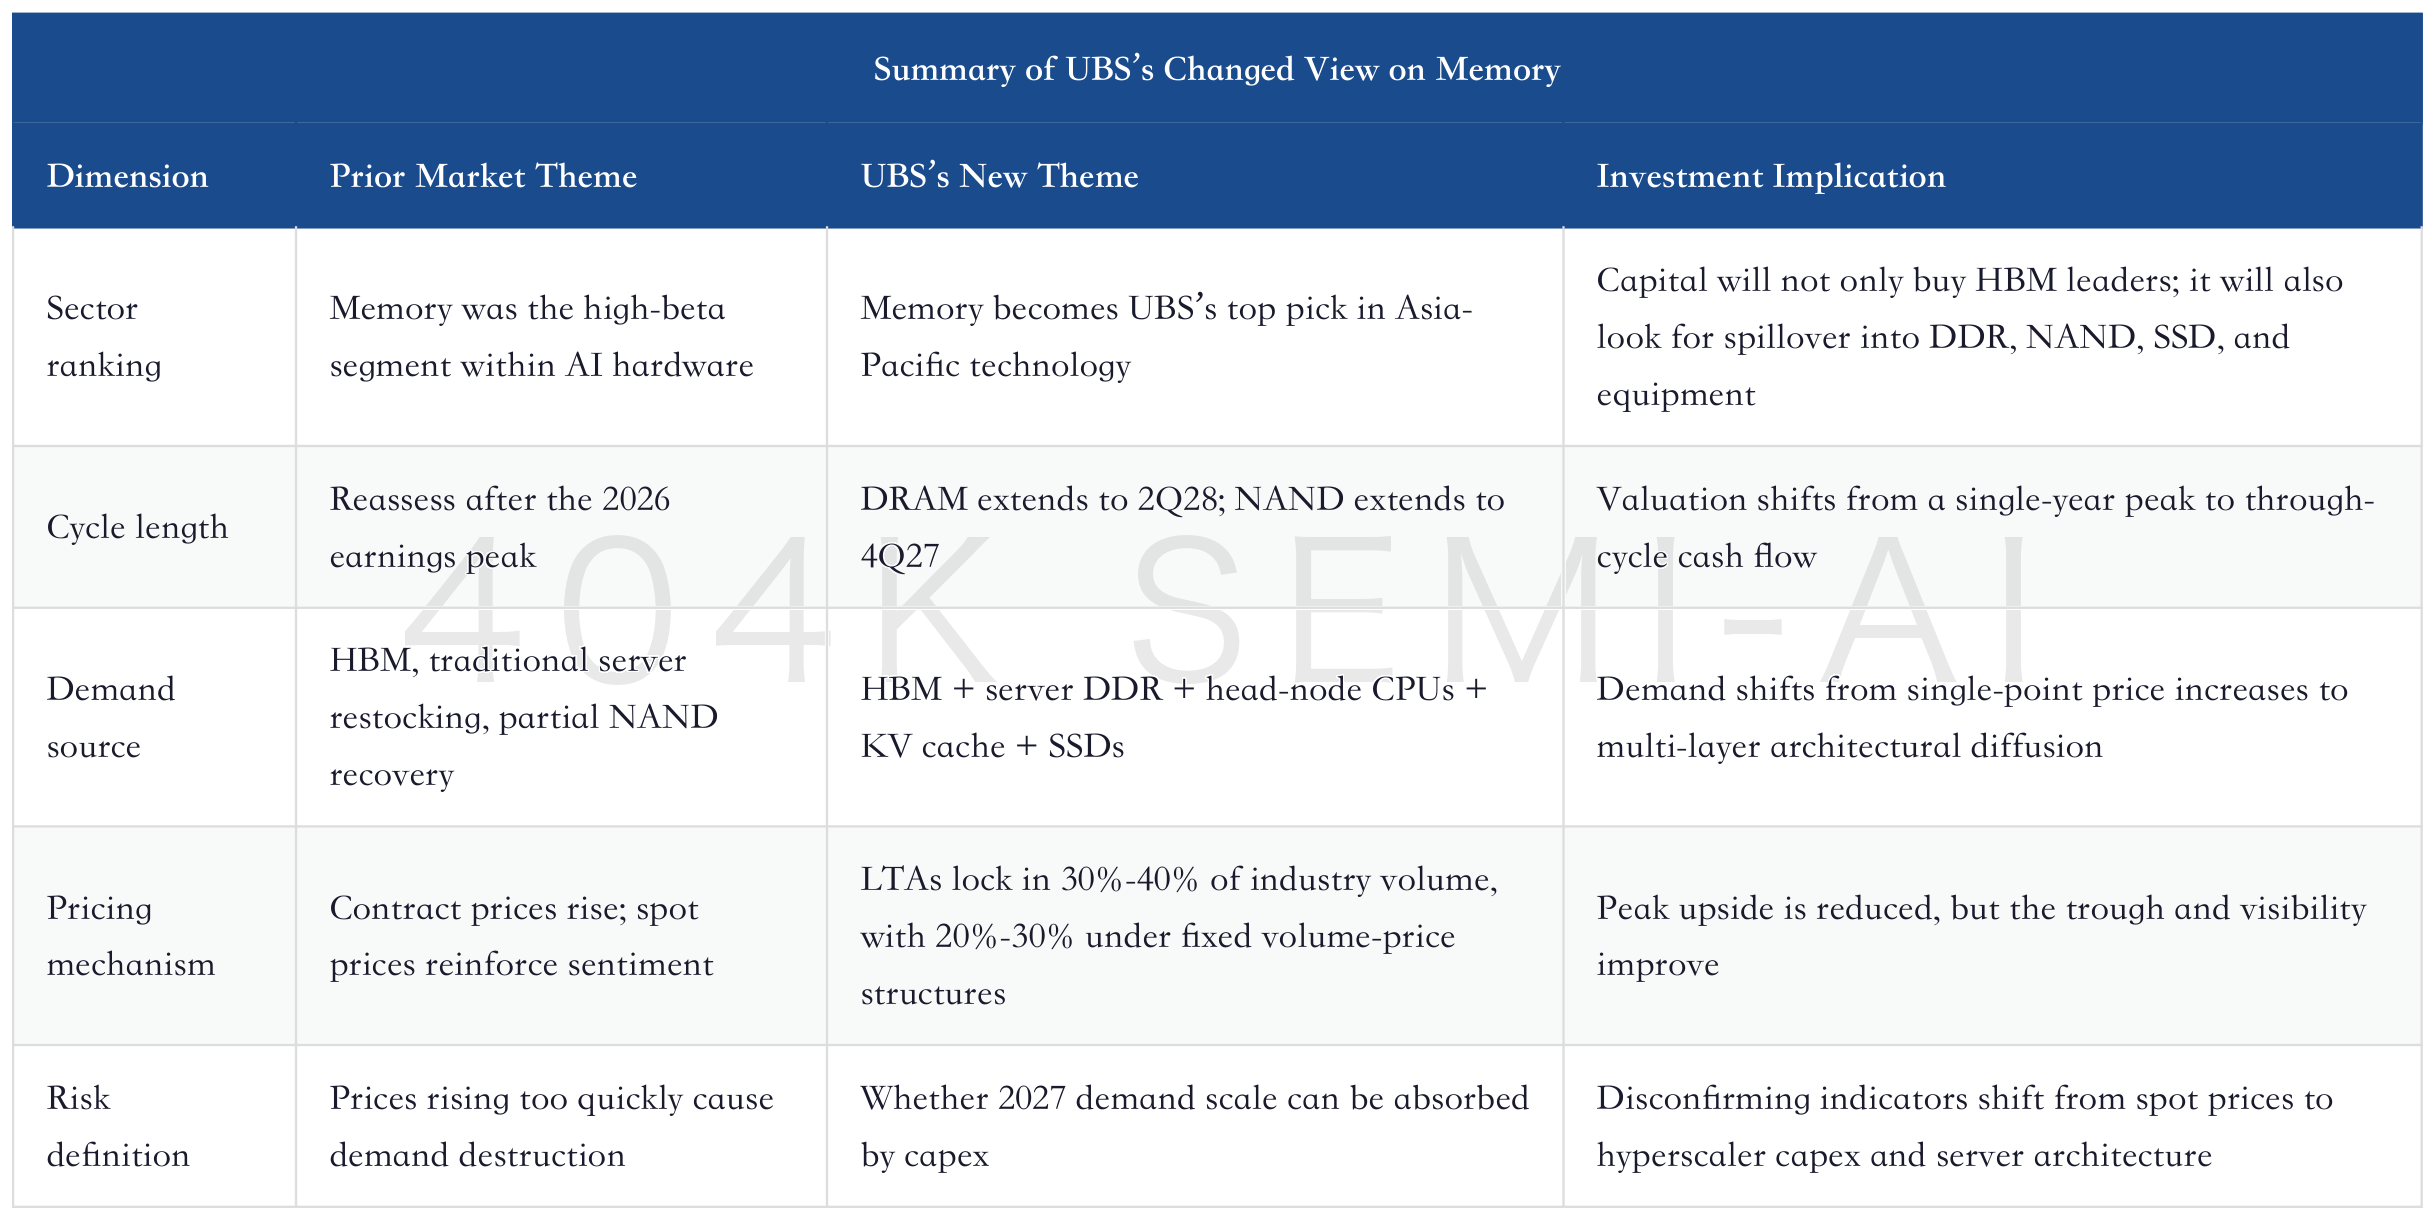
This is why the UBS report should not be read simply as “memory prices keep rising.” It is closer to a valuation-framework reset. While acknowledging tight supply and demand, UBS puts the biggest question on sustainability: if industry revenue really approaches $1.6 trillion in 2027, the market needs to believe cloud capex, AI inference workloads, server DDR, HBM, and SSD demand can all materialize at the same time.
The price increases are the most direct evidence for this framework. UBS is not betting on a brief spike in spot prices, but continuously lifting the contract-price center of gravity. 2026 is the surge; 2027 is continued upward movement from a high base. The full quarterly path below is much clearer than a standalone statement that “memory prices are rising.”
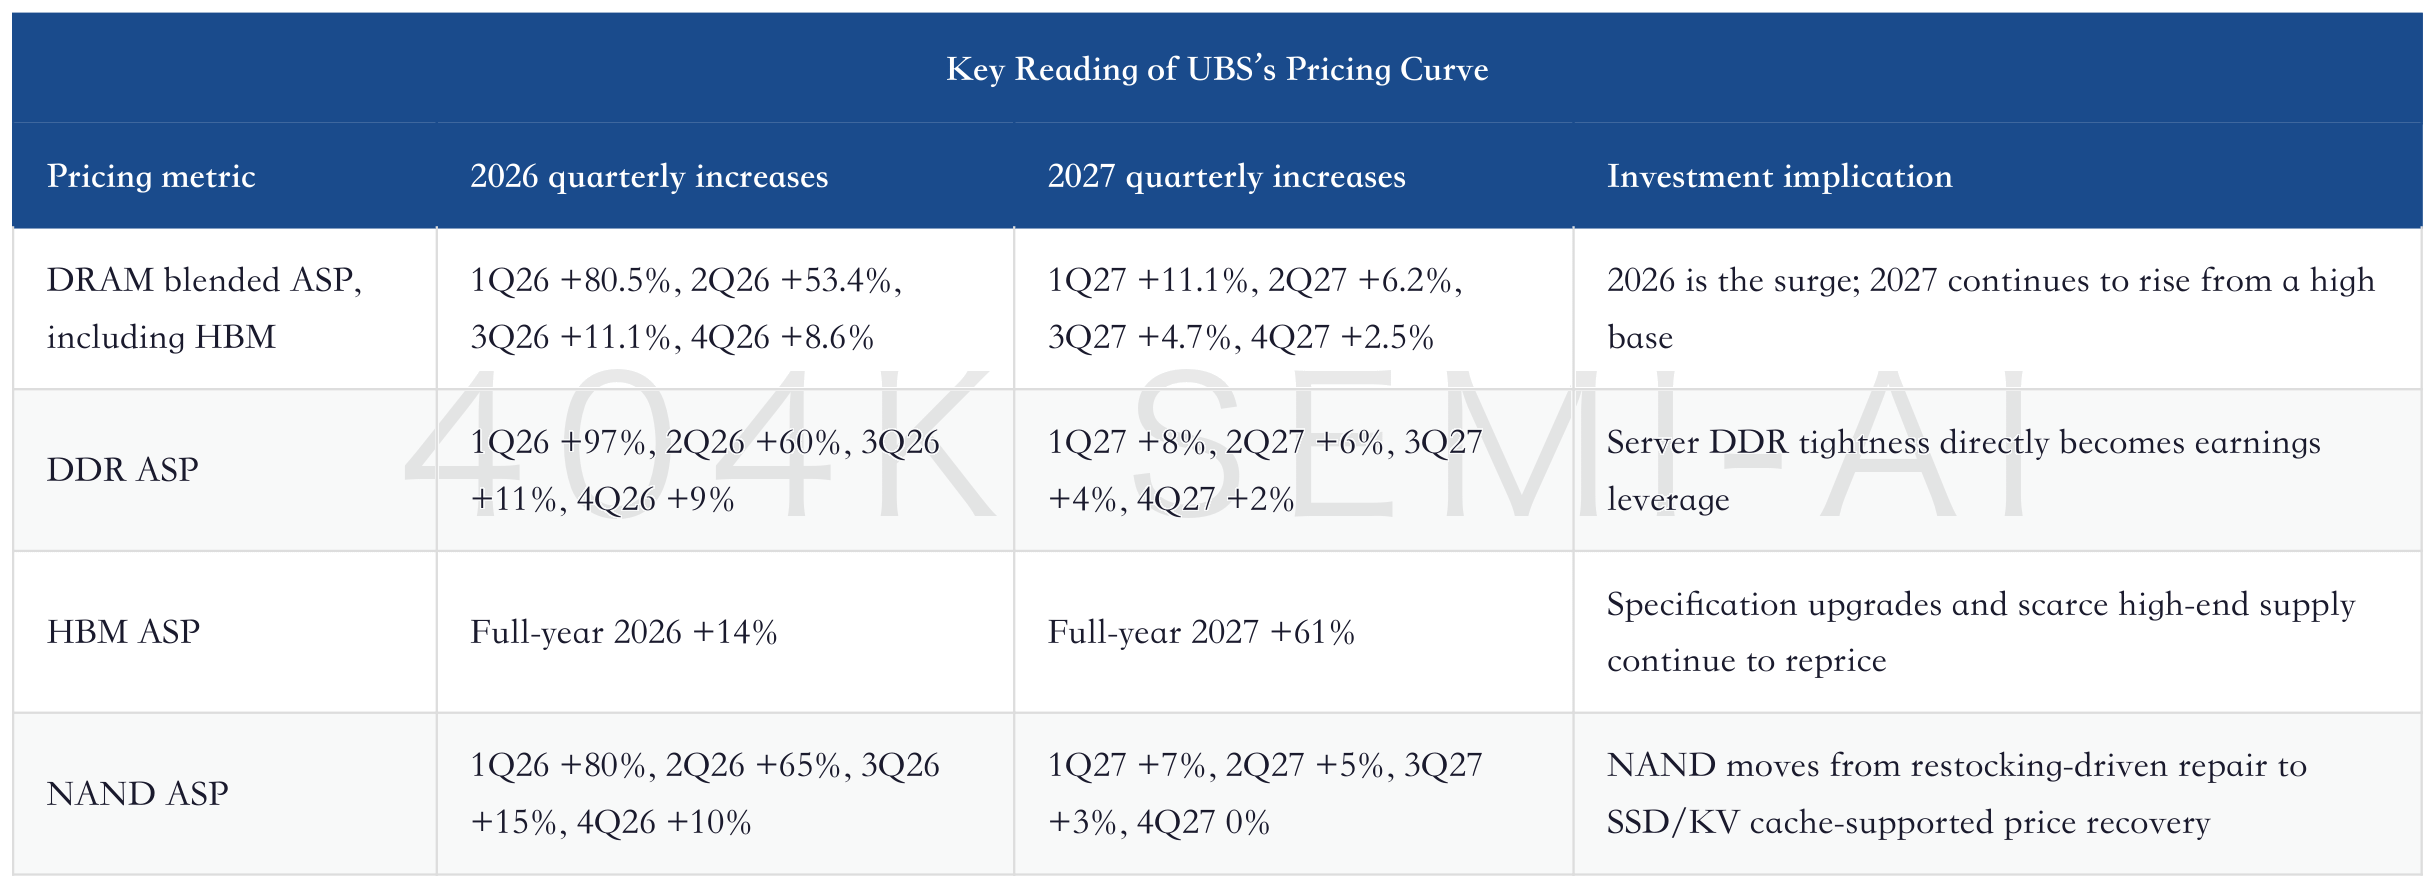
This table also explains why LTAs are not simply a negative. Without long-term agreements, peak prices could be more extreme, but customer affordability and cloud-provider budgets would become issues more quickly. With three- to five-year LTAs, peak price increases are trimmed somewhat, but trough cash flow becomes more stable. What UBS really wants to buy is the simultaneous emergence of price spikes and cash-flow visibility.
2. Agentic AI Expands Memory Demand From Beside the GPU to Beside the CPU
UBS’s understanding of agentic AI is clear: agent workflows are not one-time generation, but sequential computing, tool calling, resource access, orchestration, prioritization, and result correction. This process requires more CPU participation and more head-node CPUs in both conventional servers and AI servers. With more CPUs, DDR demand is not peripheral; it becomes the next main theme.
The most important sentence in the report is: HBM remains a Must Have. This confirms that HBM is not being replaced, but it also implies UBS is not putting all incremental demand on HBM. HBM handles parallel computing, DDR supports CPUs/head nodes and broader inference workflows, and NAND/SSDs support KV cache tiering. Memory demand is split into three layers, rather than remaining a single HBM story.
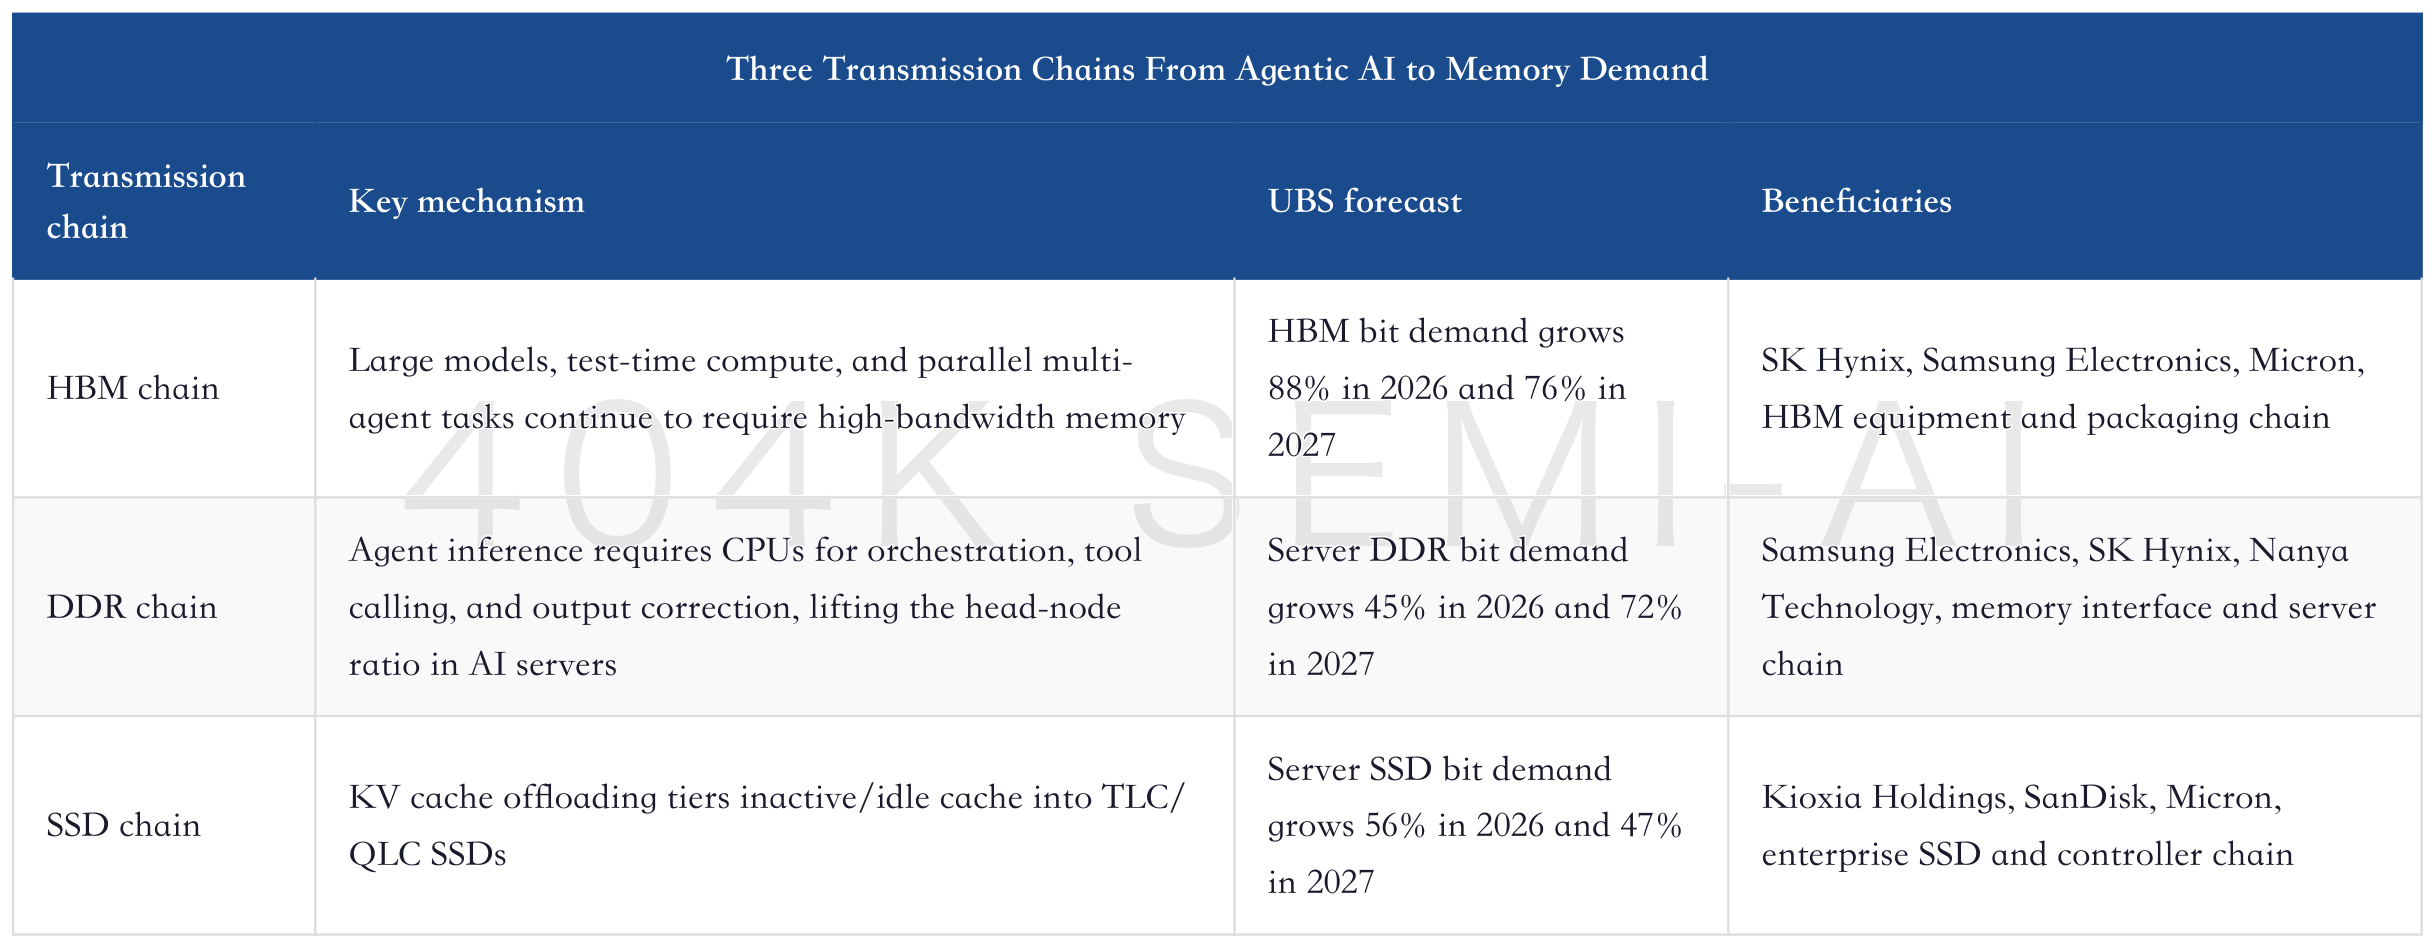
This DDR chain is the most easily underestimated part of UBS’s view. The market has historically understood AI servers as GPUs plus HBM, with CPUs and DDR treated as supporting costs. UBS is now clearly shifting the computing center of gravity in agentic inference toward CPUs. If this assumption proves correct, DDR is no longer just part of the traditional server refresh cycle; it is part of the AI inference architecture.
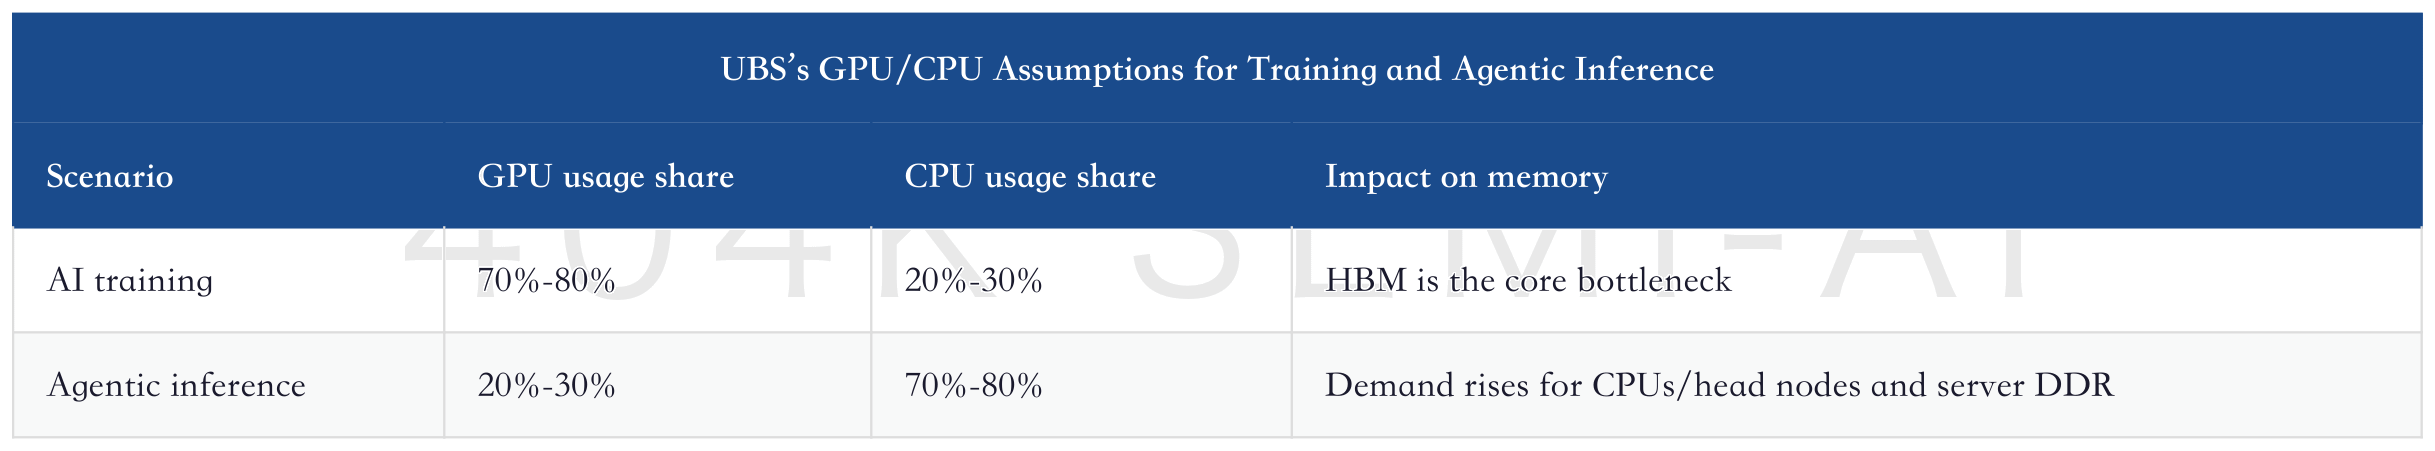
This also explains why UBS raises the head-node CPU ratio from 29% in 2025 to 41% in 2027. CPU/head node is not a variable that appears in ordinary memory-cycle models, but it directly determines the slope of server DDR demand. Revenue leverage in the memory industry is starting to be jointly determined by GPU count, CPU count, HBM capacity, DDR capacity, and SSD capacity.
The Second Engine of the Memory Supercycle: CPU Comeback, HBM Spillover, and a $1.7 Trillion TAM Revaluation
III. NAND Logic Shifts from Inventory Replenishment to KV Cache Tiering
The NAND story used to be more easily treated by the market as a “weaker version of DRAM.” It rose when DRAM rose, and was more easily questioned during pullbacks, because consumer electronics, smartphones, and PCs have limited tolerance for NAND price increases. UBS’s new explanation for NAND this time is KV cache.
The more AI inference grows, the more KV cache data is generated. Cloud providers cannot keep all cache in the most expensive and fastest memory tier. UBS’s view is that CSPs will tier storage according to compute needs: more active data stays in higher-performance tiers, inactive KV cache moves down to high-speed TLC NAND SSDs, and idle cache moves down to higher-density QLC SSDs. NAND therefore moves from the framework of “capacity storage” into “AI inference cost optimization.”
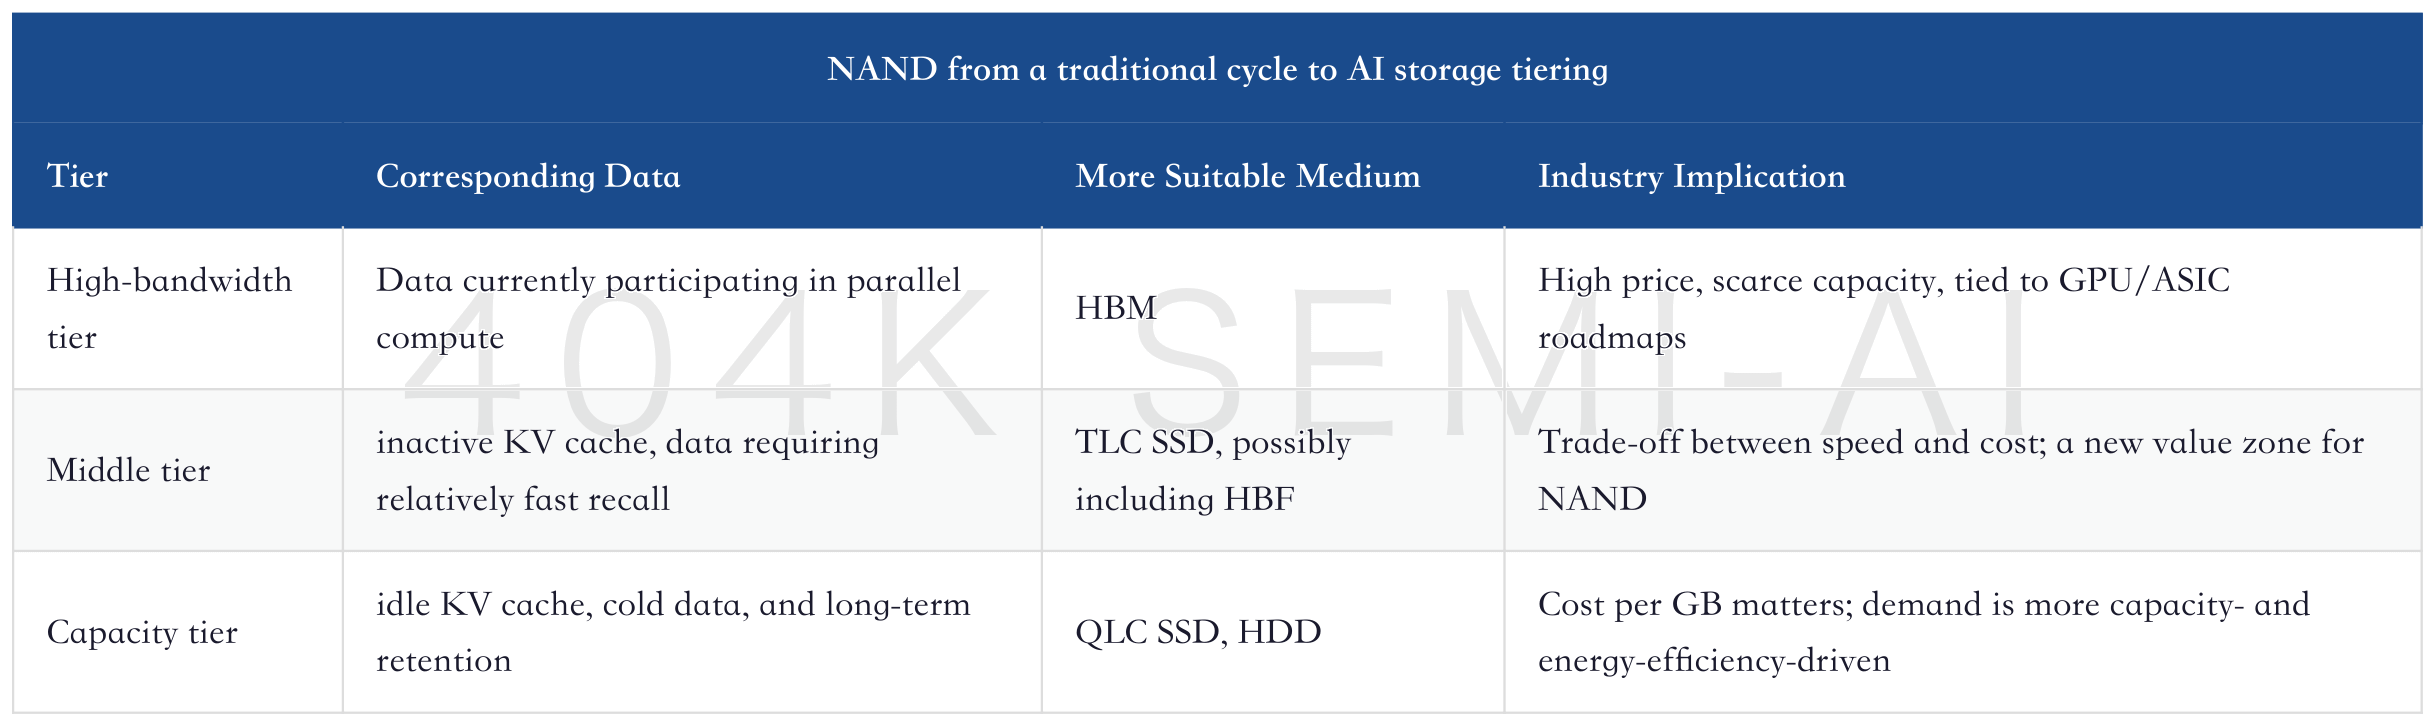
UBS also mentions HBF, or High-Bandwidth Flash. This product is not positioned to replace HBM, but to sit between HBM and high-density SSDs. Its significance is not how much revenue it contributes today, but that storage tiering is becoming more granular. The higher AI inference costs become, the more cloud providers will look for an intermediate tier that is cheaper than HBM and faster than ordinary SSDs.
For NAND vendors, this is more valuable than traditional inventory replenishment. Traditional restocking depends on pricing and inventory; AI SSD demand depends on workloads and architecture choices. The former is shorter-term; the latter is longer-term. UBS extending the NAND cycle to 4Q27 is essentially an acknowledgment that KV cache, server SSDs, and storage SSDs may pull part of NAND’s demand curve out of the consumer electronics cycle.
IV. LTA Shifts the Valuation Anchor for Cyclicals from Peak Earnings to Cash-Flow Visibility
UBS’s second change this time is putting enhanced LTA at the center of industry economics. LTA is not simply “large customers locking in supply.” It changes the price curve: giving up some extreme upside premium during upcycles, suffering less price collapse during downcycles, and ultimately gaining more stable FCF and ROE.
One short phrase in the report on LTA is critical: lower peak memory contract pricing. This is not a bad thing, but the cost of a change in valuation framework. For cyclical stocks, peak earnings are often discounted because the market worries they cannot last. Long-term agreements weaken the peak, but if they can raise the trough, the market has reason to assign a higher mid-cycle valuation.
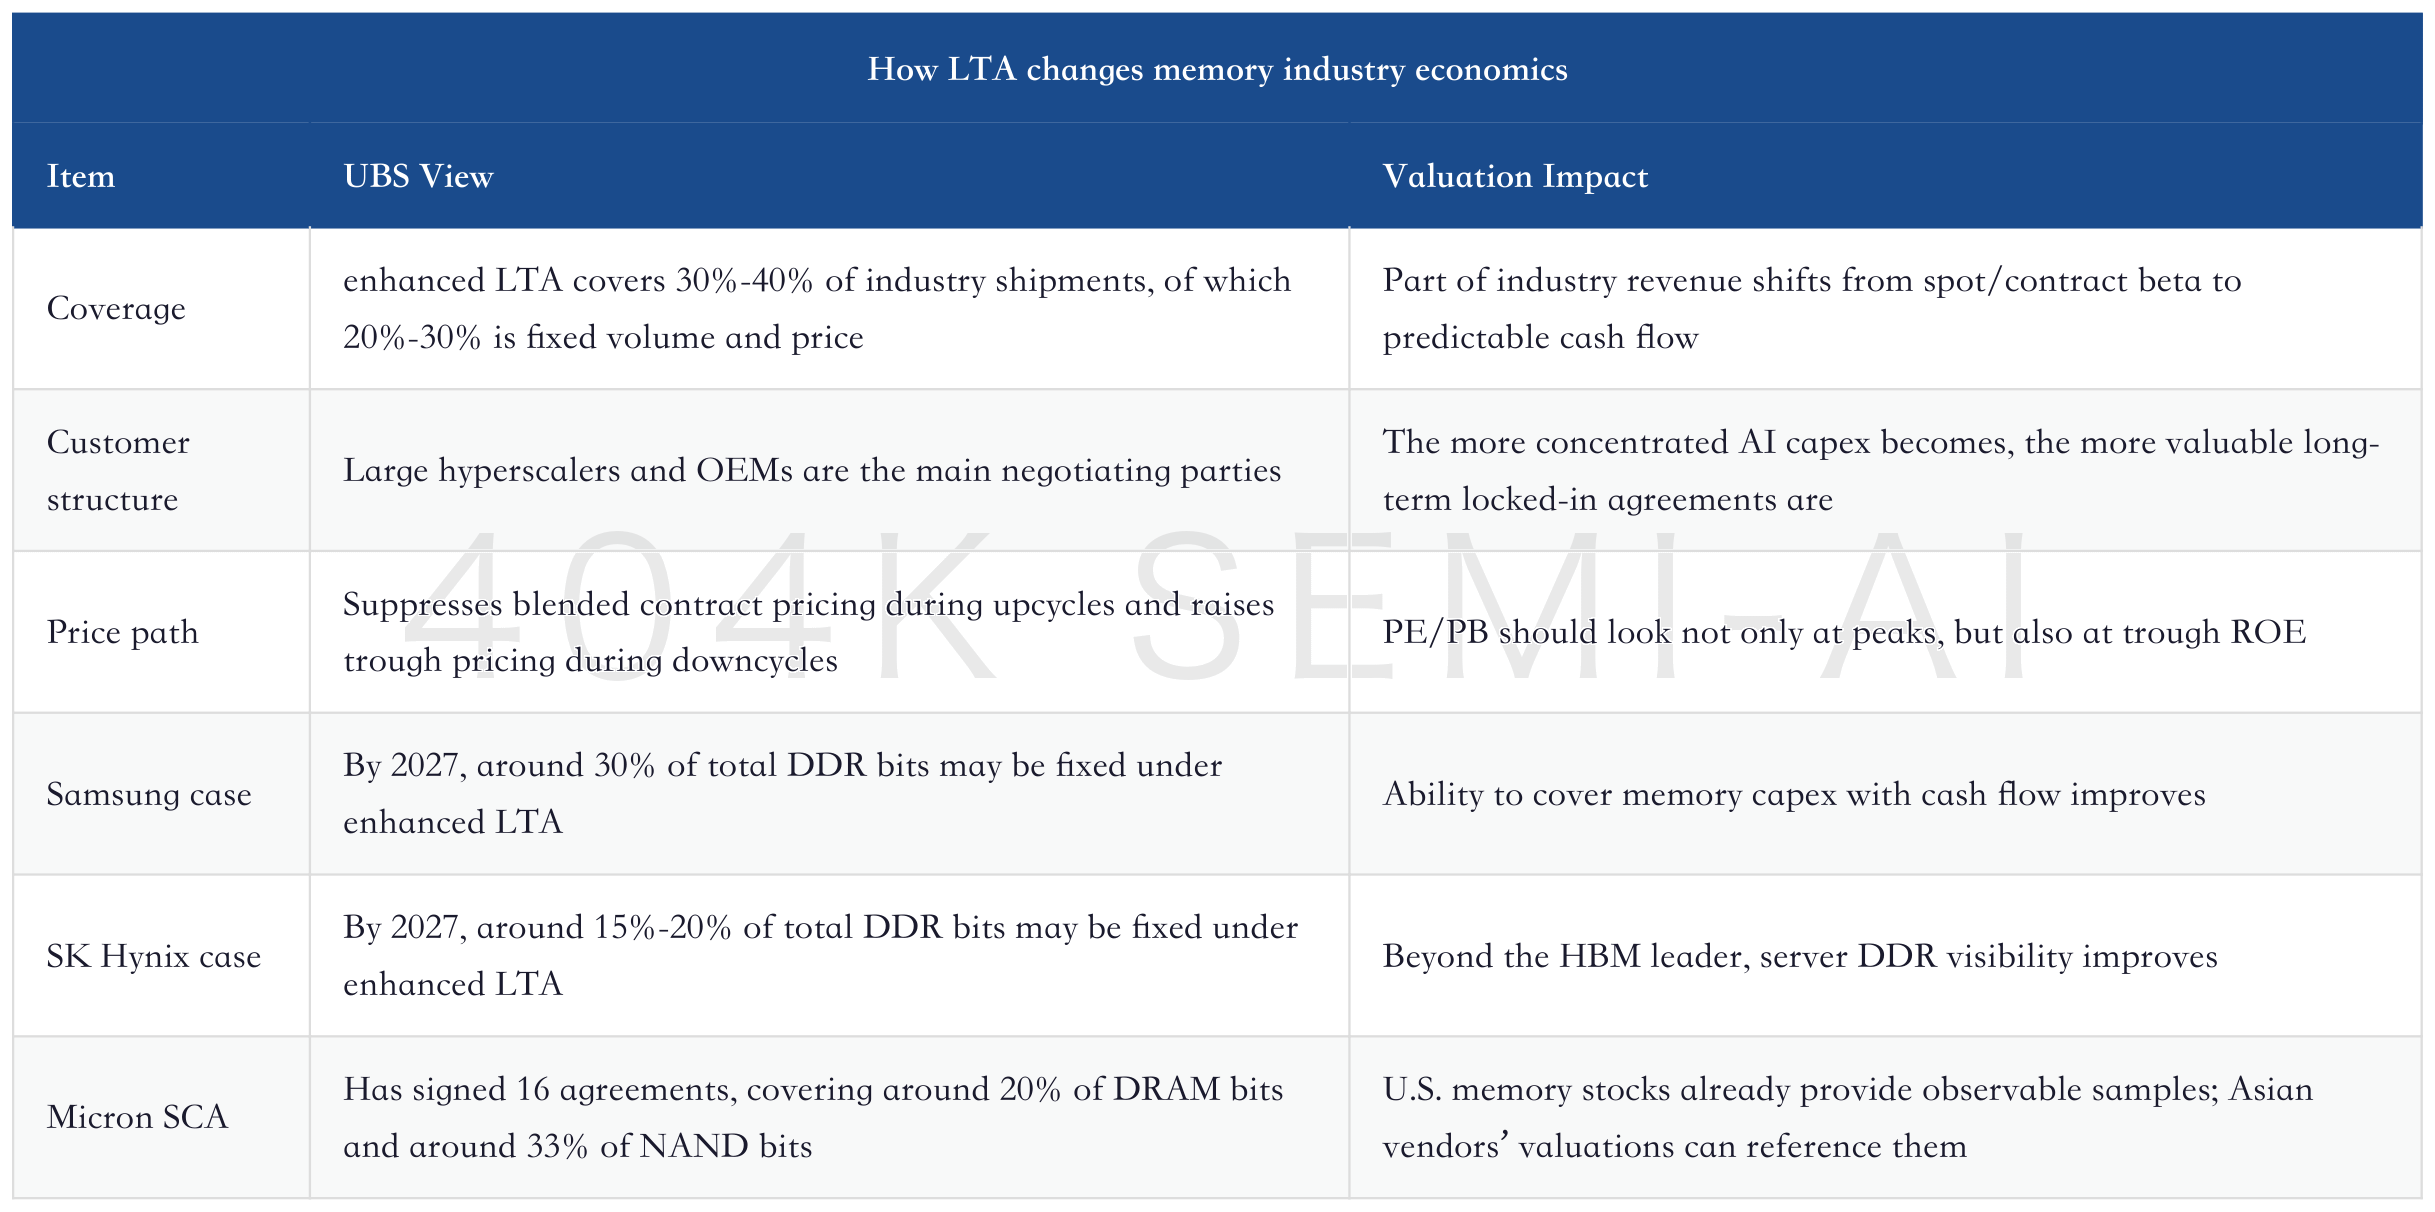
LTA also has a deeper implication: it binds memory vendors more tightly to cloud providers. In the past, memory vendors’ capex was more like a lagged response to price signals: expand capacity in upcycles and cut back in downturns. Now, if cloud providers are willing to offer 3-5 year volume-and-price arrangements, memory vendors can have greater confidence in expanding HBM, DDR, and NAND-related capacity.
This also matters for the equipment chain. UBS believes that even if memory makers raise capex/WFE, DRAM supply still cannot catch up with demand in the short term, because equipment lead times, supply chains, and engineering installation resources will all become bottlenecks. In other words, memory leads, WFE catches up, but the equipment catch-up does not weaken the memory thesis; it adds a slow-moving variable to the capacity release timetable.
V. Price Increases and Revenue Scale Are Equally Aggressive, and This Is Also the Most Fragile Point
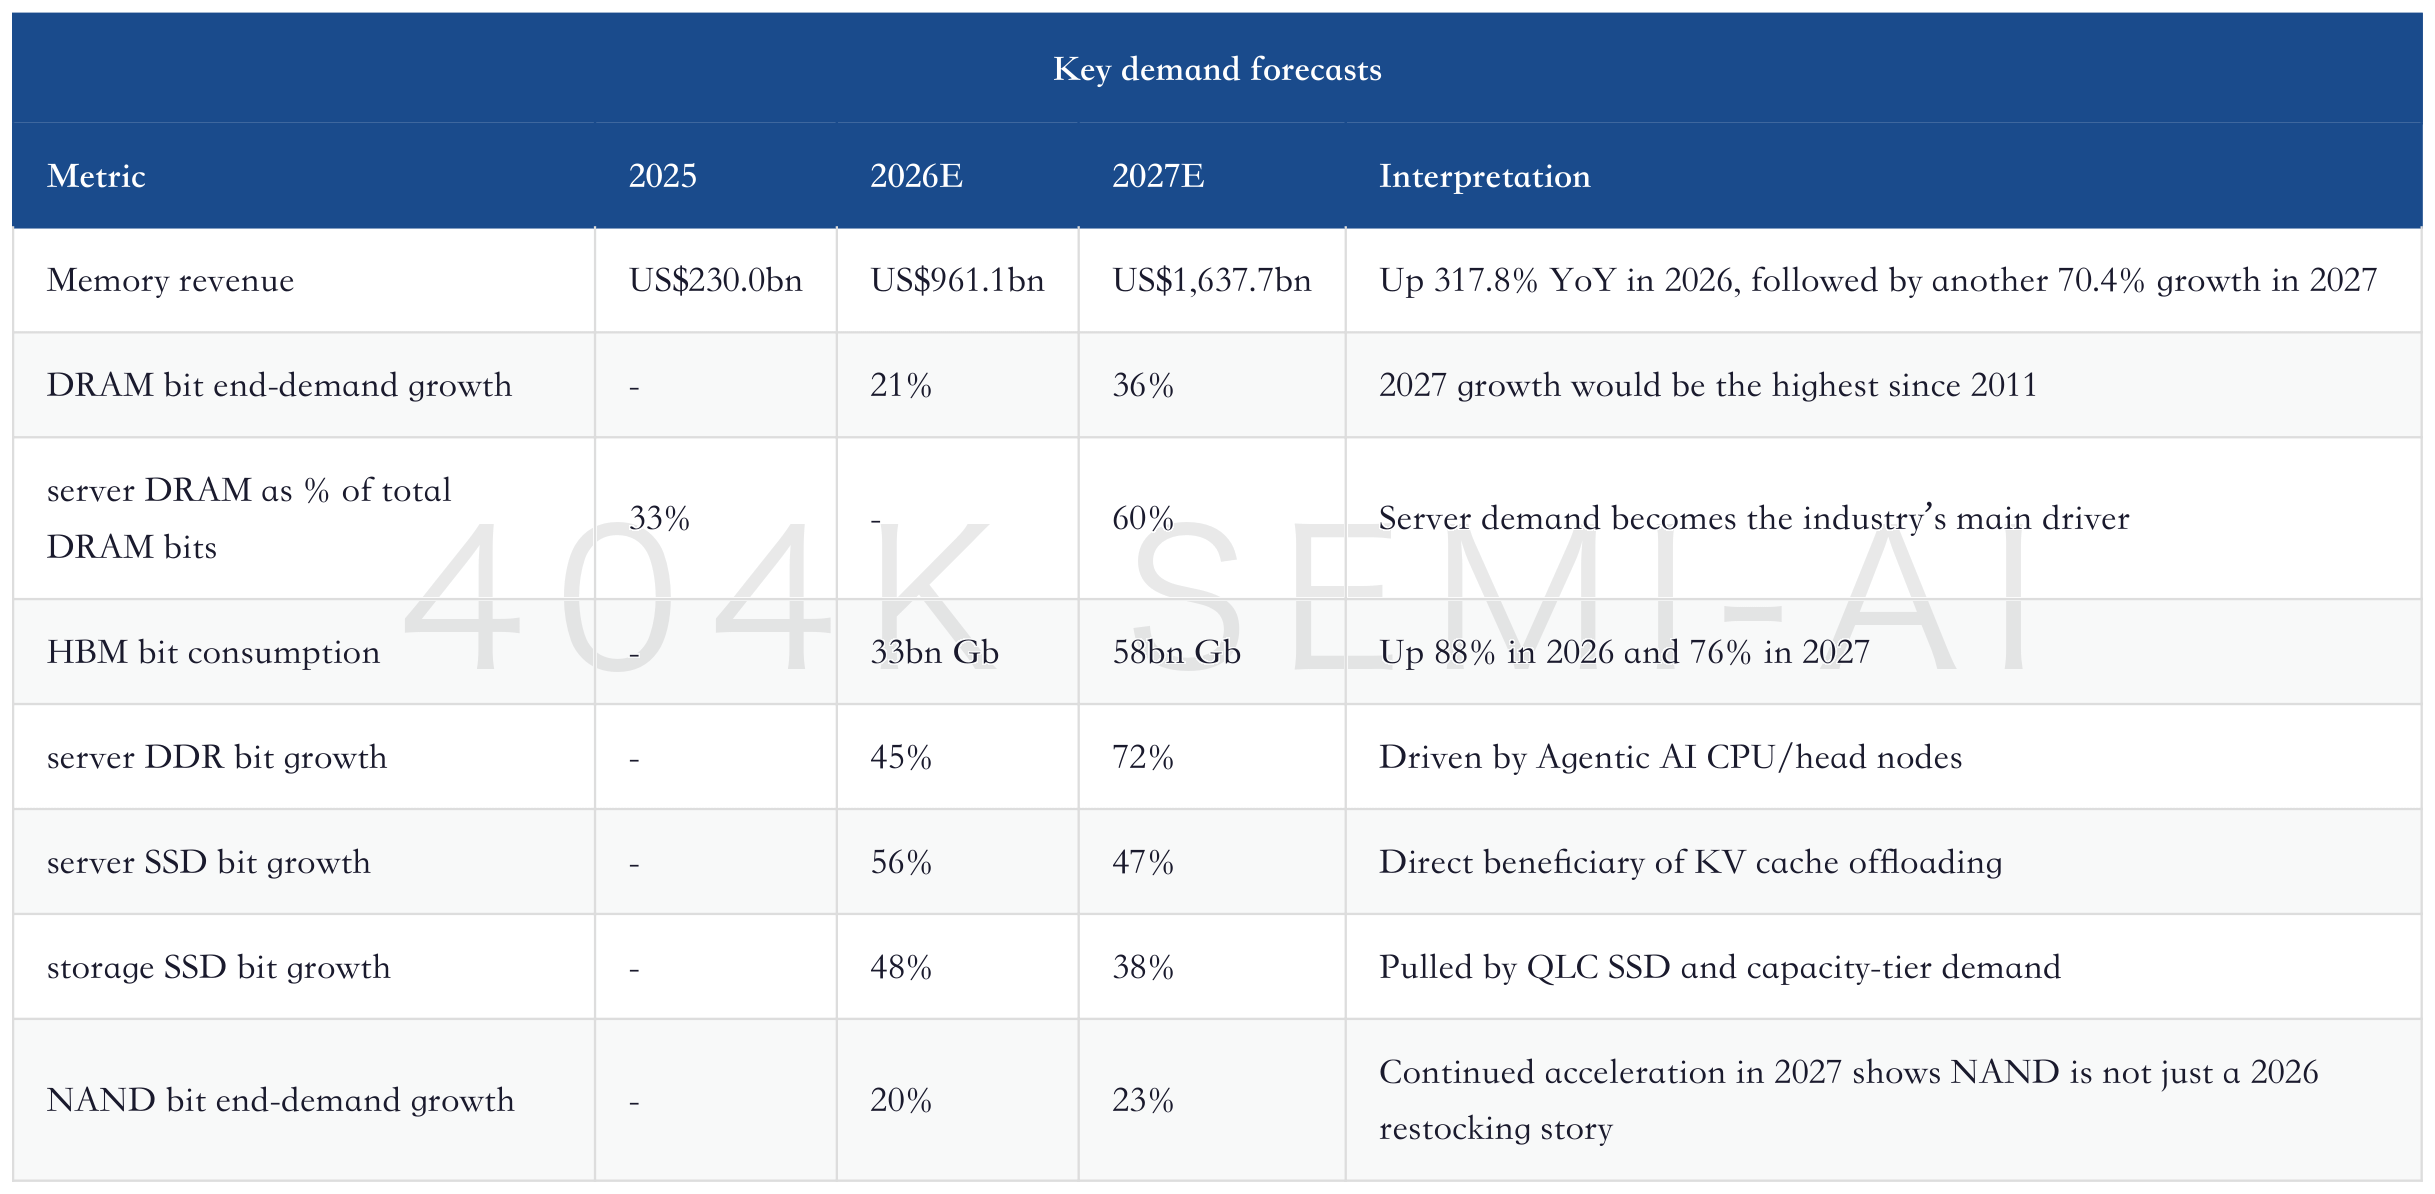
UBS’s demand numbers are very strong. DRAM bit end demand grows 21% in 2026 and 36% in 2027; HBM bit consumption rises from 33bn Gb in 2026 to 58bn Gb in 2027; server DDR, server SSD, and storage SSD all maintain high growth through 2026-2027. Together, these figures support its upward revision to the cycle duration, and also support the highly aggressive price table above.
But what really stands out is the revenue scale. UBS expects memory revenue to jump from US$230.0bn in 2025 to US$961.1bn in 2026 and then to US$1,637.7bn in 2027. This is far above the previous-cycle peak of around US$153.8bn in 2018. The report itself states the risk directly: Demand sustainability is a key question.
The hyperscaler memory spend numbers better illustrate the risk. UBS expects Top 11 hyperscaler capex to grow from US$508.0bn in 2025 to US$1.073tn in 2027, but total memory spend to rise from US$72.8bn to US$856.7bn, with its share of capex increasing from 14% to 80%. This is not a small amount of crowding-out; it is a restructuring of the entire AI data center cost structure.
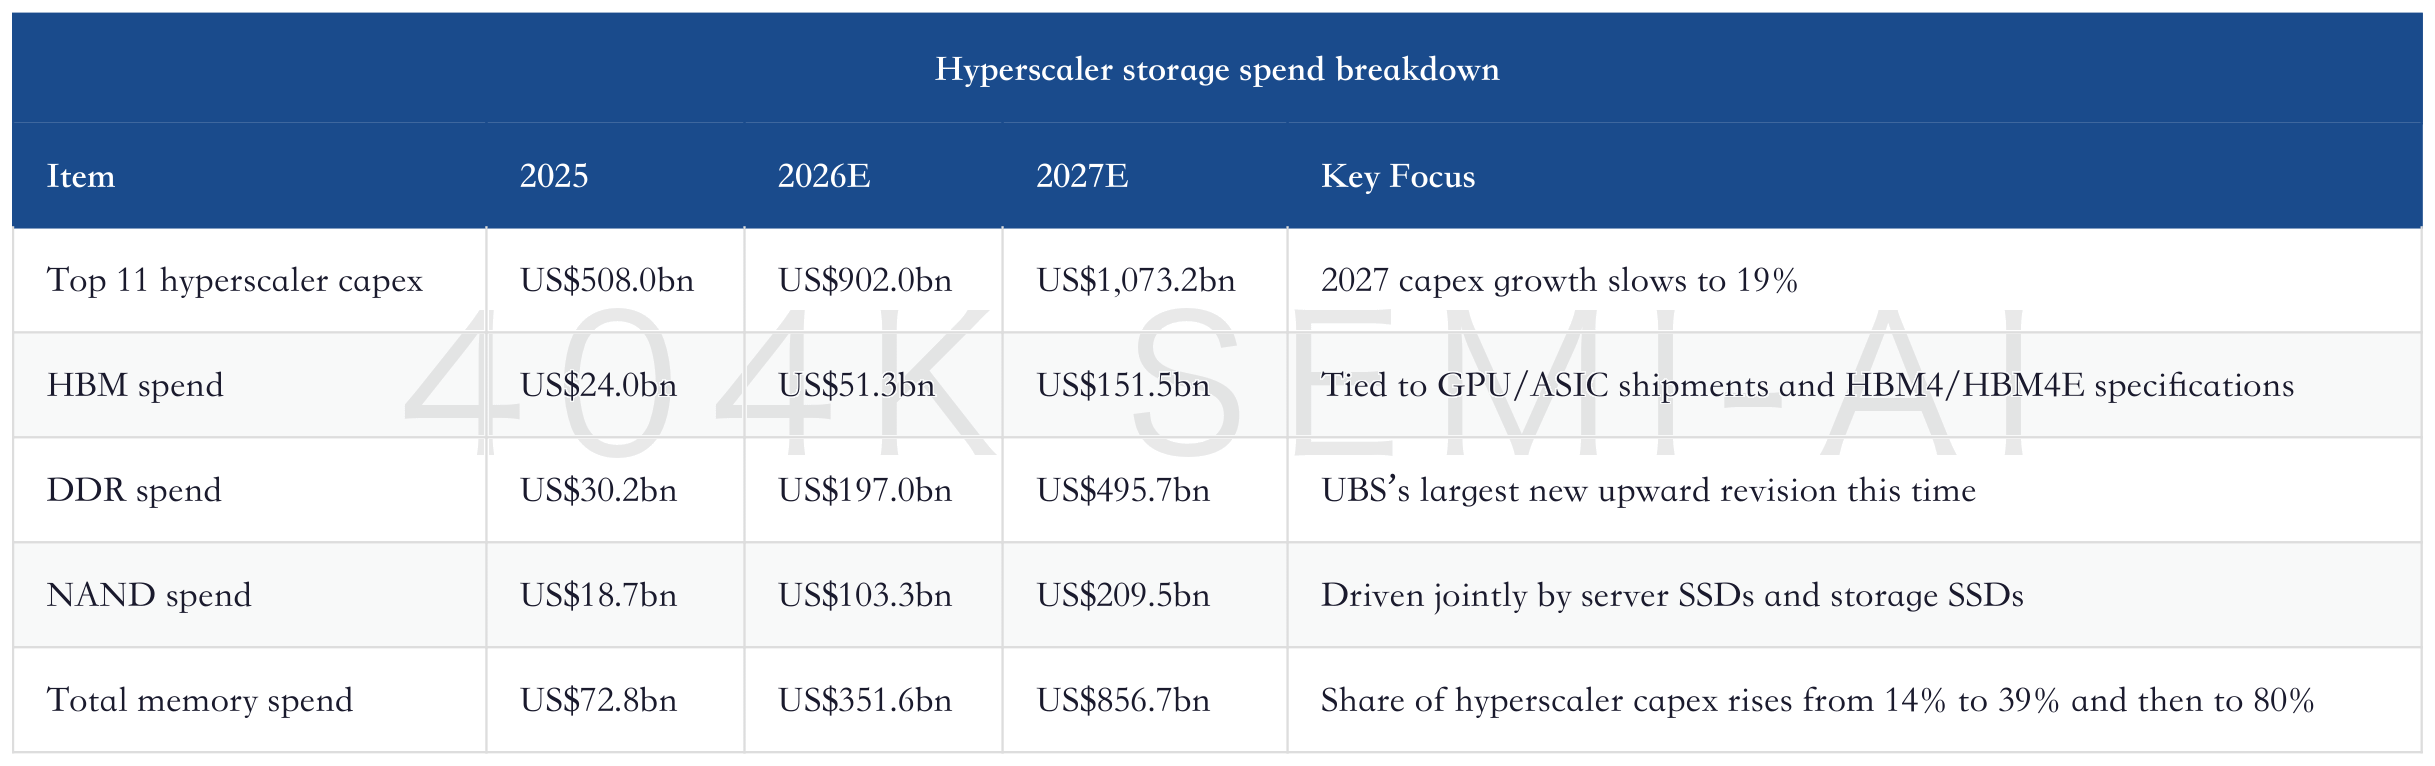
This table determines the difficulty of subsequent trading. Buying memory is not just about whether prices have risen; it requires judging whether cloud providers are willing to let memory consume such a high share of capex. If cloud capex slows in 2027 while HBM, DDR, and NAND prices continue to rise, the bottleneck in compute deployment will shift from GPU supply to memory cost.
VI. In Single-Stock Ranking, Samsung Electronics Is the Most Comprehensive, SK Hynix the Purest, Nanya Technology the Most Leveraged, and Kioxia Holdings the Most Exposed to NAND Beta
UBS’ preference across memory stocks is fairly clear. Samsung Electronics, SK Hynix, Nanya Technology, and Kioxia Holdings are all rated Buy. They are not the same trade: Samsung Electronics is a full-stack beneficiary; SK Hynix is the HBM leader; Nanya Technology offers supply-demand gap leverage in niche DRAM; and Kioxia Holdings is a NAND/eSSD and pure-play NAND LTA incentive story.
The beneficiaries should not simply be ranked by pricing leverage, but by “which demand chain is most likely to be realized.” If HBM4/HBM4E specifications continue to move higher, SK Hynix and Samsung Electronics are the most direct beneficiaries. If head-node CPUs and server DDR become the main upside surprise, Samsung Electronics, SK Hynix, Nanya Technology, and the memory-interface chain are more sensitive. If KV cache/SSD becomes a cost-optimization path for AI inference, Kioxia Holdings, SanDisk, Micron, and the enterprise SSD controller chain should see stronger marginal change.
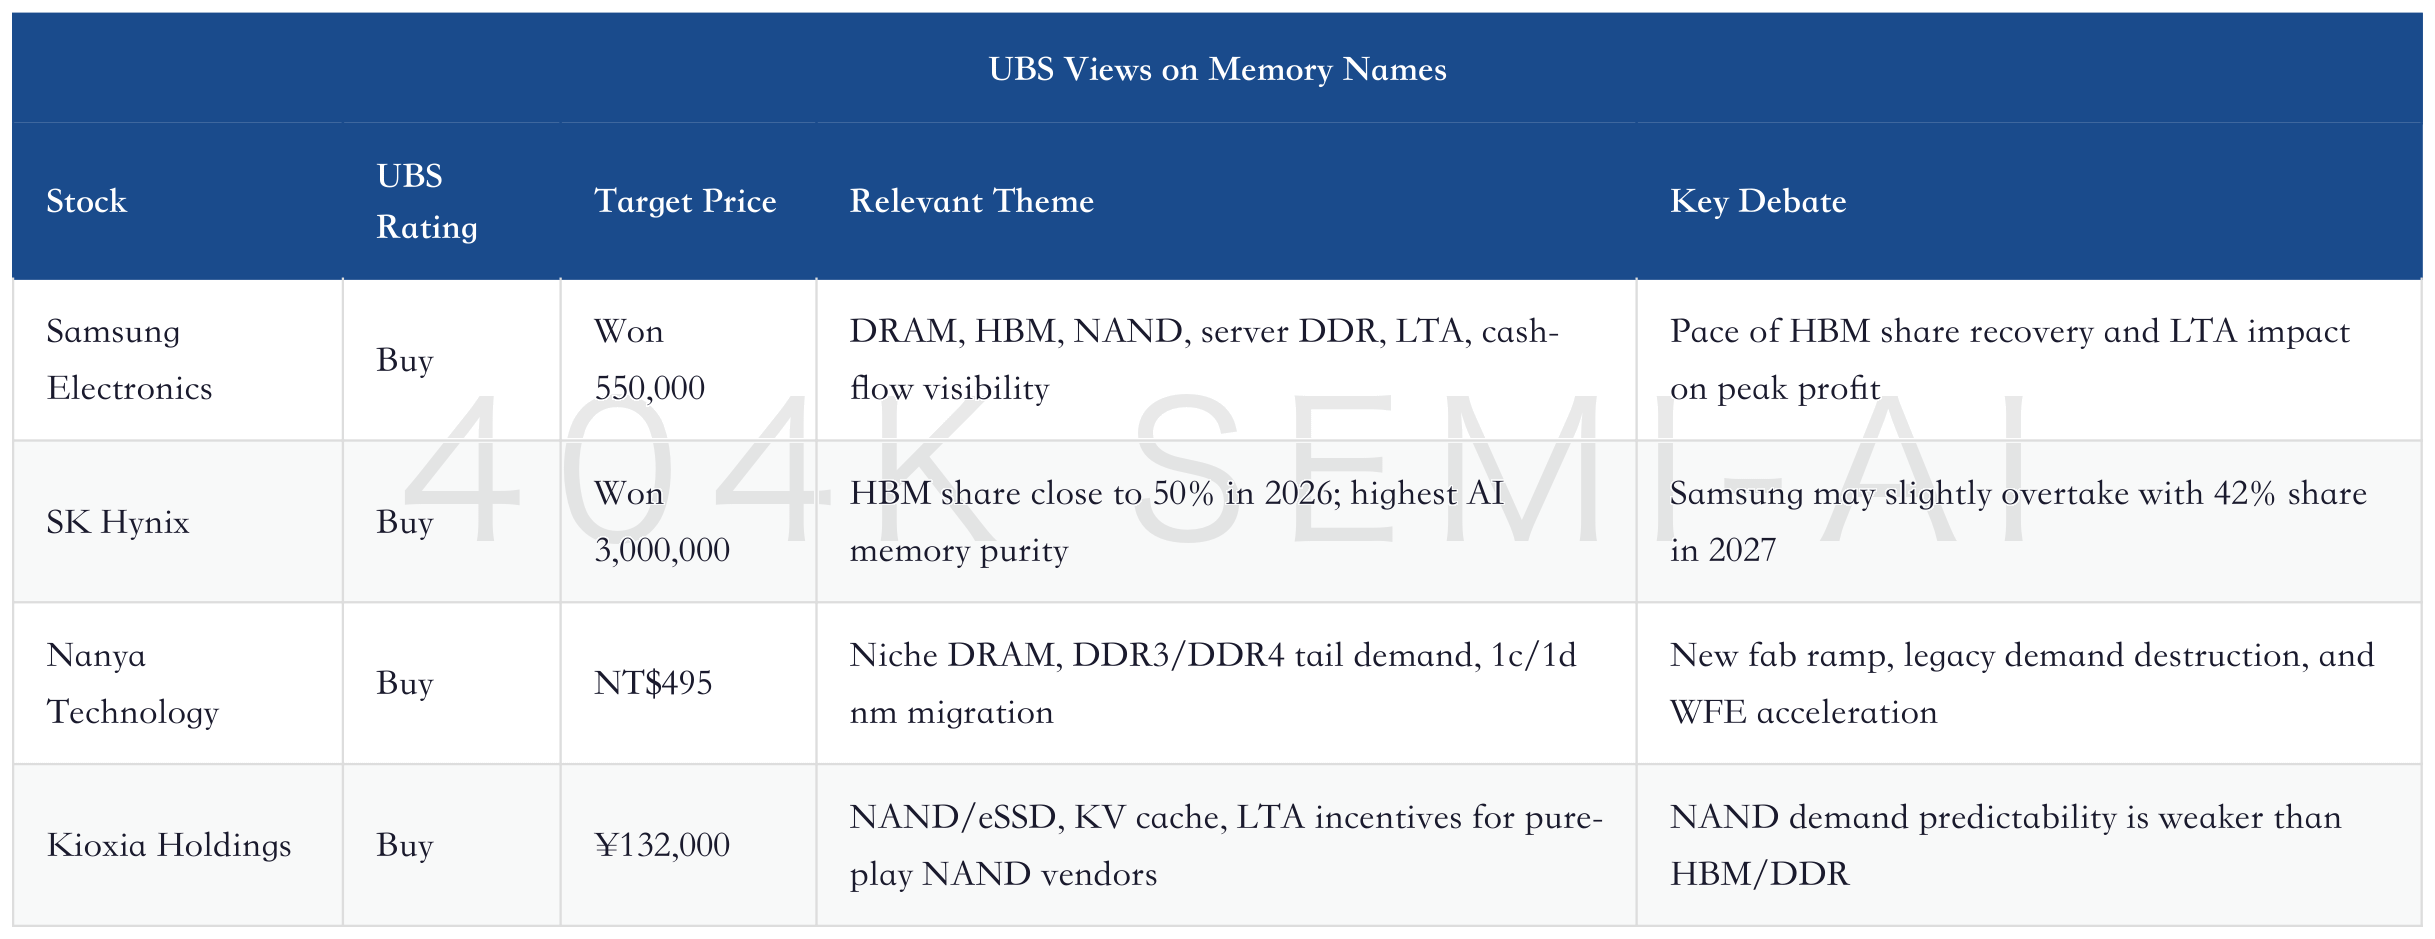
The Nanya Technology section is especially illustrative of how UBS judges the strength of this cycle. The report directly calls this a “once-in-30-years” memory cycle, because HBM is consuming DDR capacity, the traditional server refresh remains strong, and incremental wafer capacity is being directed mainly toward HBM. This combination allows niche DRAM to share in the supply-demand gap, rather than letting only HBM leaders make money.
For Kioxia Holdings, the logic requires more caution. UBS believes Samsung Electronics and SK Hynix may be unwilling to commit too much NAND volume under LTAs, because they need to prioritize wafer capacity for HBM, while NAND demand is less predictable than HBM/DDR. Conversely, pure-play NAND vendors have stronger incentives to seek LTAs. Kioxia Holdings’ leverage comes from this: it is not the strongest AI memory company, but it may be the purest beta to NAND pricing and the enterprise SSD cycle.
VII. Trading This Memory Cycle Requires Tracking Three Worldviews at Once
UBS’ report presents an optimistic worldview, but this cycle cannot be traded solely on the optimistic script. The problem with the memory industry is that demand, pricing, capacity, customer budgets, and technology roadmaps are interlocked. If one link slows, valuations can be compressed back into cyclical-stock territory.
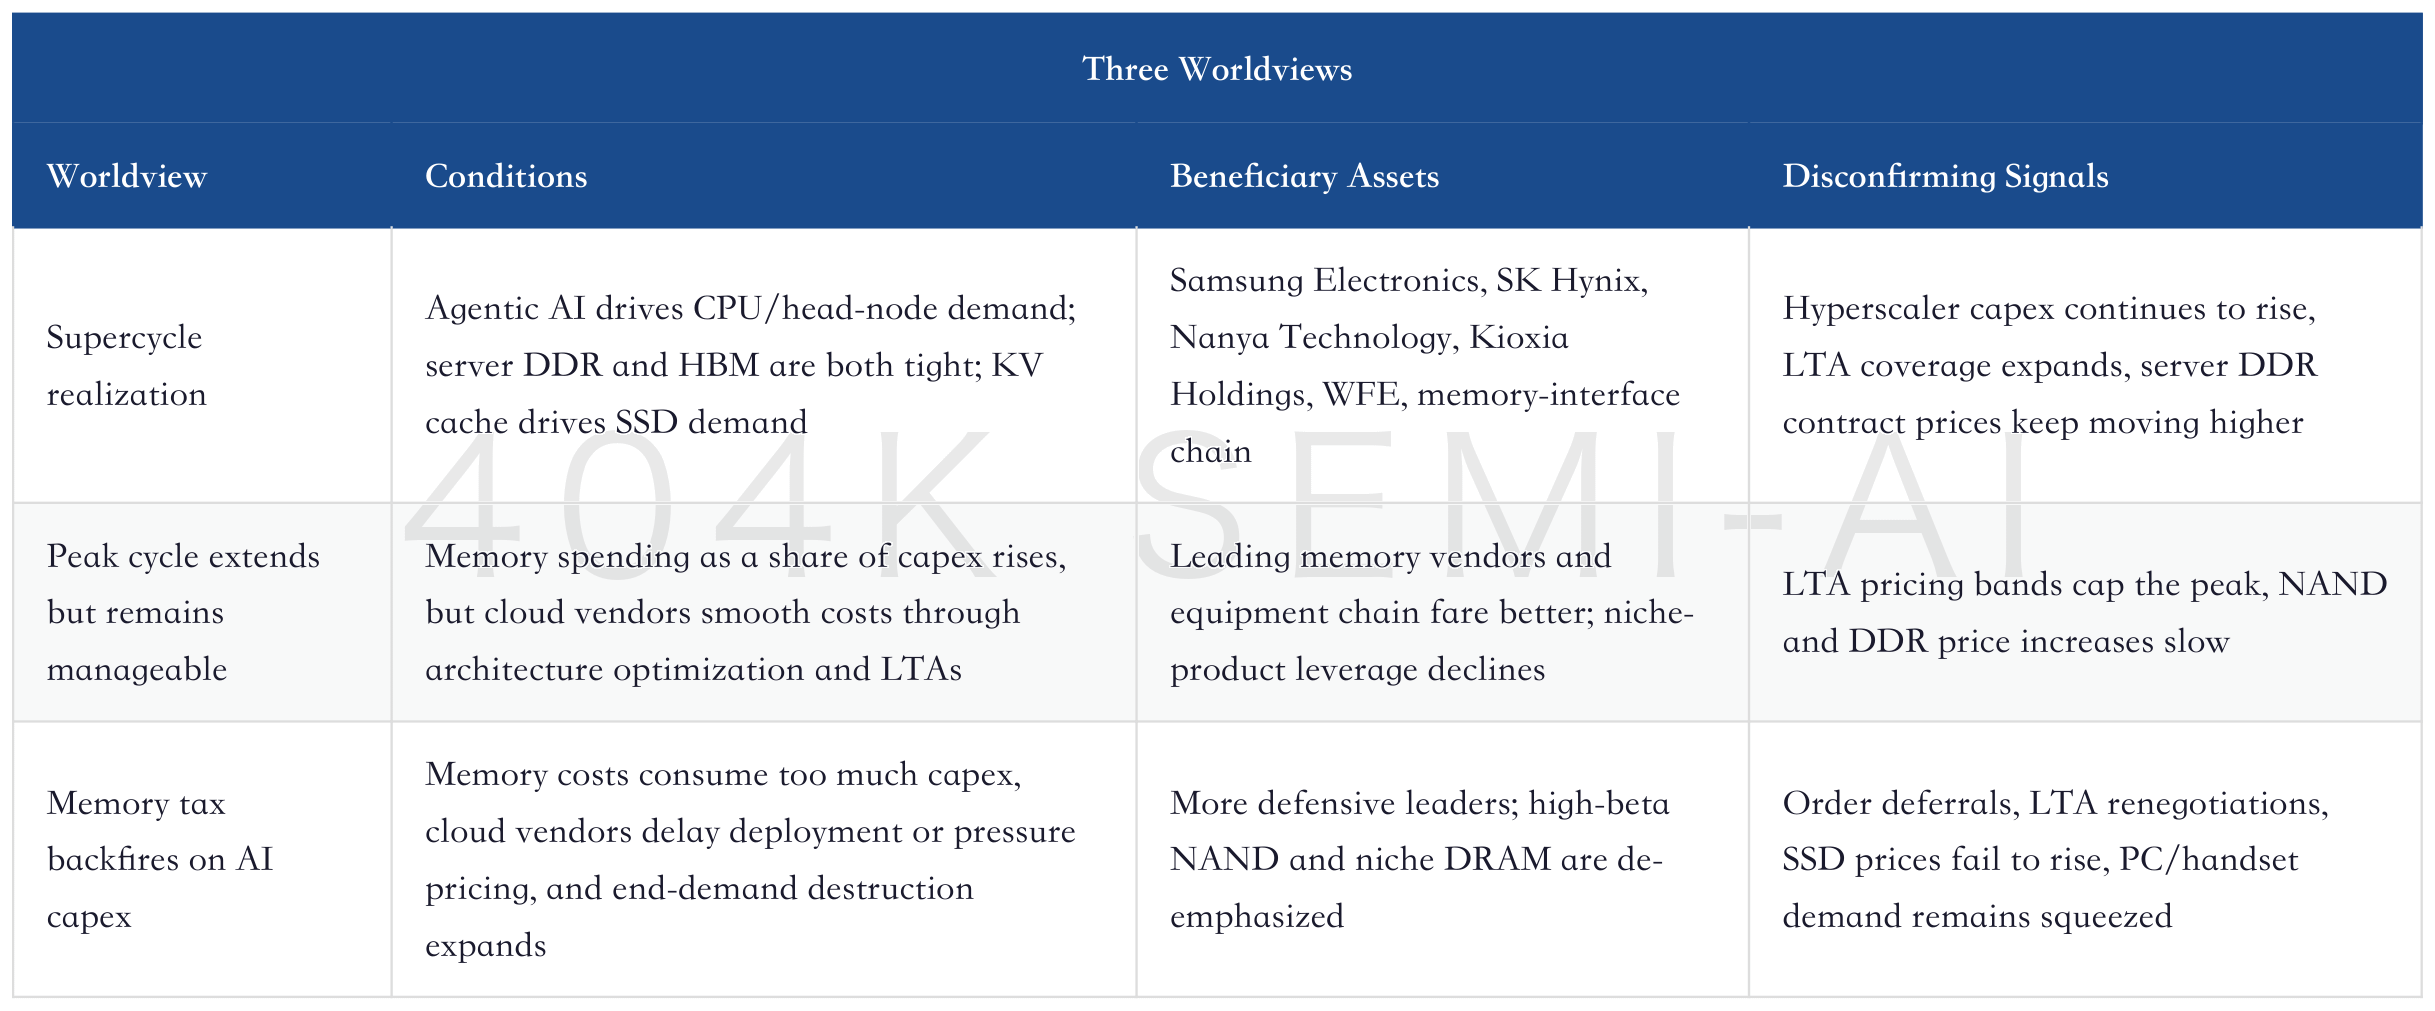
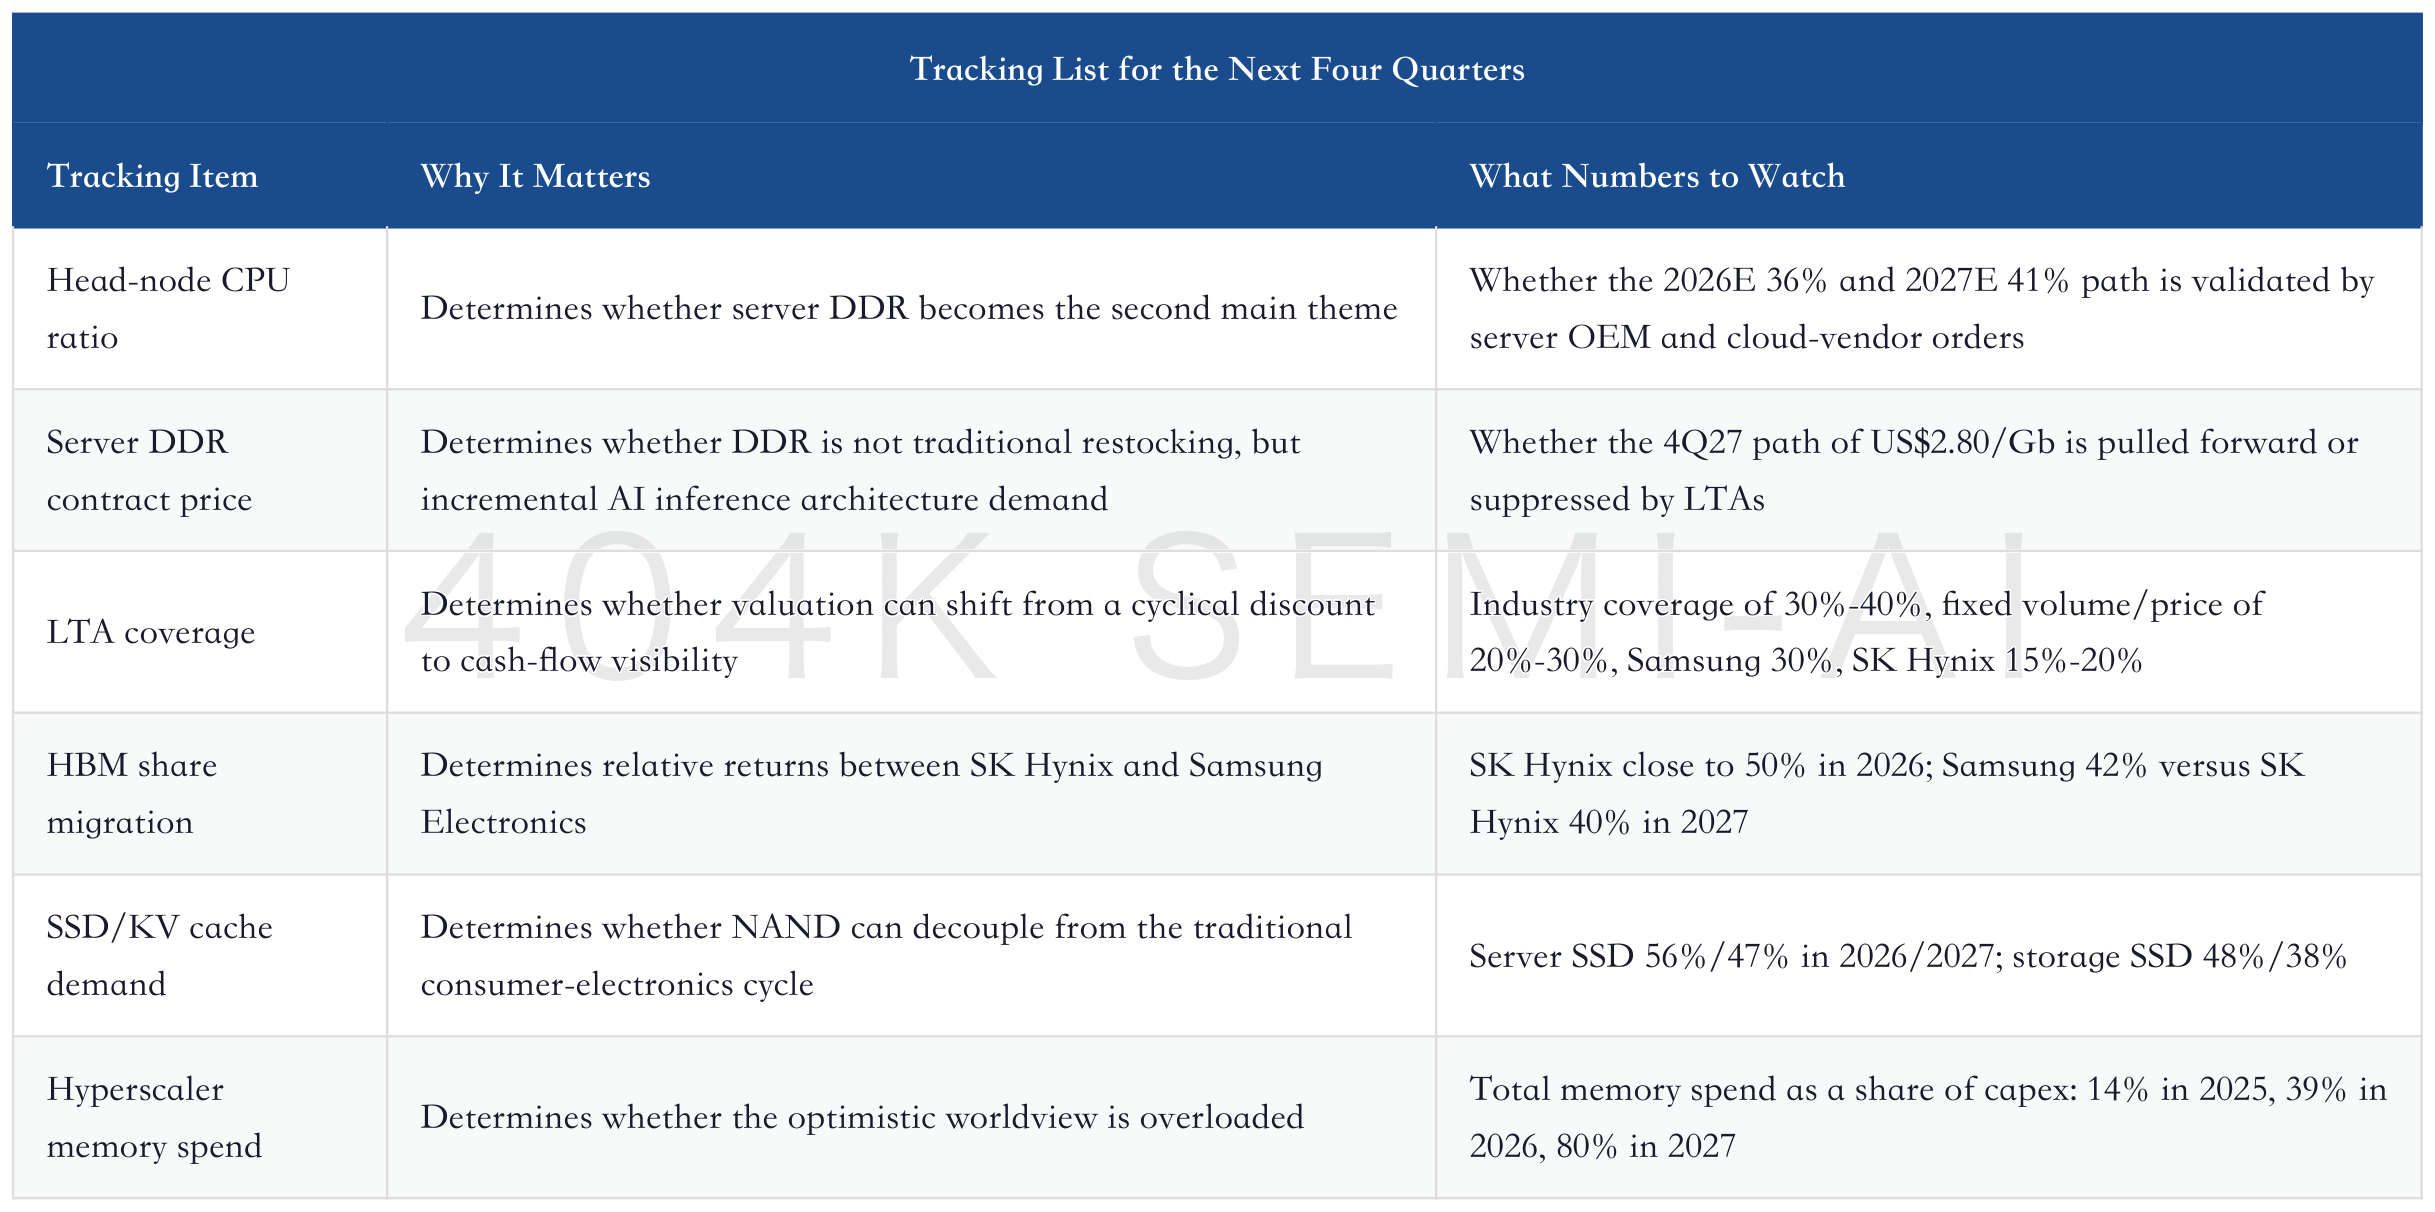
The real tracking indicators also need to expand beyond spot prices. Looking only at DRAM spot or NAND contract prices is no longer enough to explain this cycle. Four variables matter more: whether the head-node CPU ratio keeps rising, whether server DDR LTA coverage expands, whether HBM4/HBM4E specifications and share transition proceed as planned, and whether KV cache truly becomes incremental demand for TLC/QLC SSDs.
VIII. Why UBS Is Willing to Extend the Cycle to 2028
UBS is willing to see the DRAM cycle lasting until 2Q28 not because it simply believes prices will keep rising, but because it sees that supply cannot respond immediately. Memory expansion does not mean equipment purchases translate into instant shipments. Equipment lead times, supply chains, cleanrooms, process migration, engineering staff, and yield ramp all widen the time gap between demand and supply.
This is also one of the biggest differences between this cycle and the 2017-2018 cycle. In the previous cycle, demand was more driven by smartphones, PCs, servers, and cloud-computing restocking, and the supply side could eventually ease the gap through traditional DRAM and NAND capacity expansion. This time, more incremental capacity is being absorbed by HBM, which also consumes advanced packaging, testing, yield, and front-end wafer resources. Capacity is not simply being added; it is being reallocated across products.
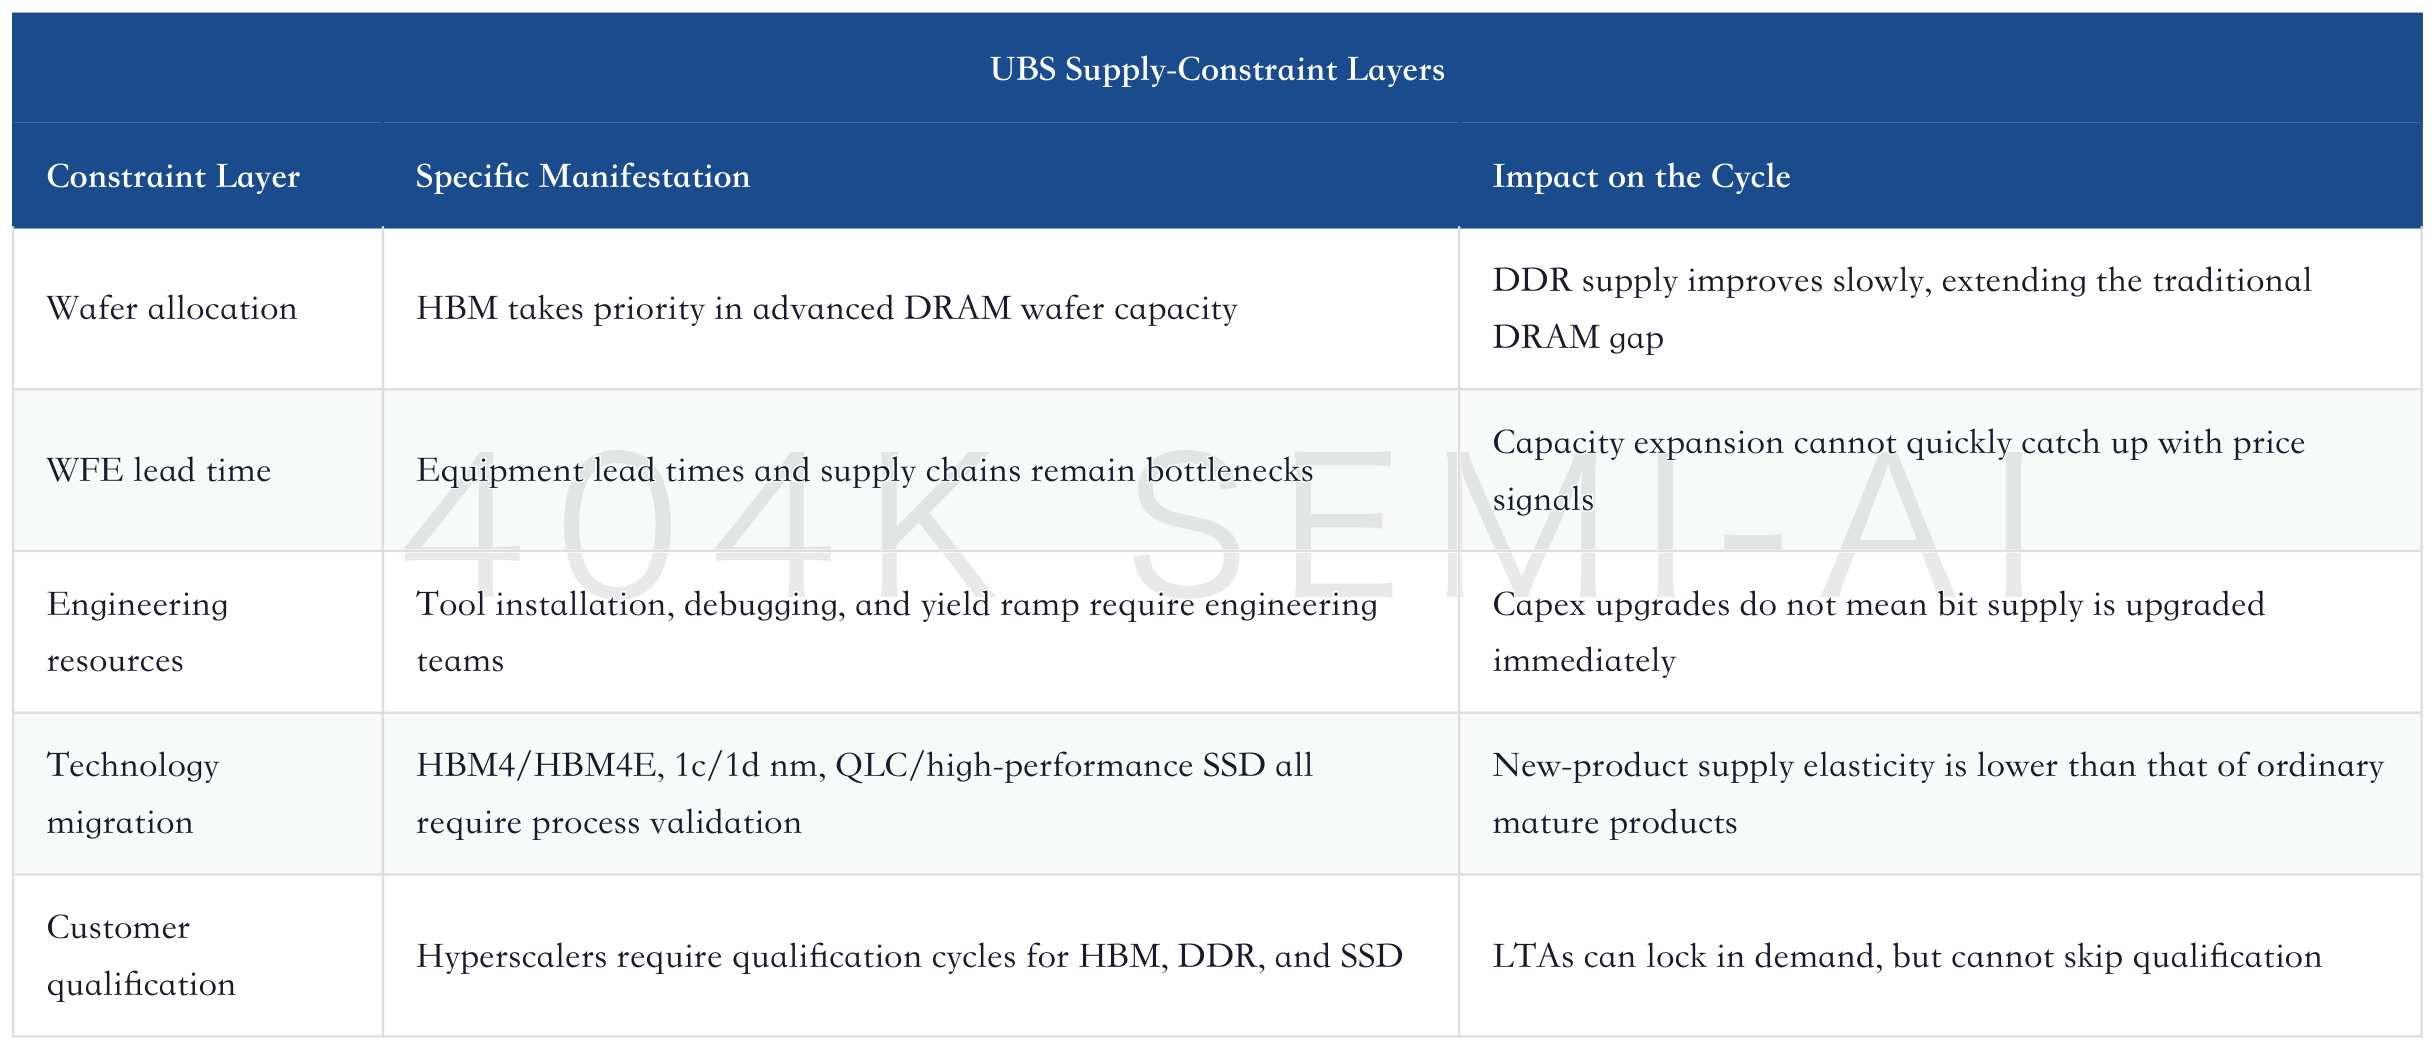
These supply constraints will make price signals stronger. In a normal cycle, price increases attract capacity expansion, and capacity expansion suppresses pricing. UBS’ emphasis this time is that the feedback loop from capacity expansion has slowed. Even if DRAM vendors are willing to add WFE, incremental wafers are more likely to serve HBM first. Traditional DDR, server DDR, and niche DRAM may therefore remain tight.
Nanya Technology’s logic can be viewed within this framework. It is not an HBM leader, but UBS still rates it Buy and believes niche DRAM can benefit from DDR3/DDR4 tail demand, 1c/1d nm migration, and new-fab pull-through. The reason is that after large vendors’ capacity is pulled toward HBM and high-end server DDR, supply release in traditional and niche DRAM will also slow. Niche vendors are not the strongest demand link, but they may be the link where supply spillover is slowest.
The equipment chain is an extension of the same logic. When UBS says WFE stocks need to catch up, it is not because equipment automatically comes next after memory has risen. Rather, the capacity bottleneck in memory itself raises visibility for equipment orders. DRAM capex, HBM advanced packaging, NAND/eSSD expansion, testing, and back-end resources will all diffuse outward along the memory cycle.
But the equipment chain’s rally is likely to lag by half a step. Memory stocks first trade on profit leverage; equipment stocks trade on orders and deliveries. If prices rise too quickly in 2026, the market will buy memory first. If supply bottlenecks have not been resolved in 2027, WFE and advanced-packaging equipment will receive stronger second-order confirmation. This is why UBS ranks memory above WFE, but still recommends revisiting semicap.
IX. How This Re-Rating Differs from Previous Price-Up Cycles
The core issue in a traditional memory cycle is simple: inventories fall, prices rise, vendor profitability recovers, and then the market worries about capacity expansion and demand destruction. UBS’ framework this time is more complex. It does not deny the cyclical nature of the industry, but argues that three structural variables have been added on top of the cycle: AI architecture change, LTAs changing cash flow, and cloud-vendor budgets changing the industry ceiling.
These three structural variables increase memory’s valuation elasticity and also make disconfirmation more demanding. In the past, as long as DRAM contract prices rose for several consecutive periods, memory stocks could rally first. Now the market asks more questions: whether price increases are coming from AI servers rather than consumer-electronics restocking; whether LTAs make the profit floor higher; and whether cloud vendors are willing to tolerate memory spend taking a rising share of capex.
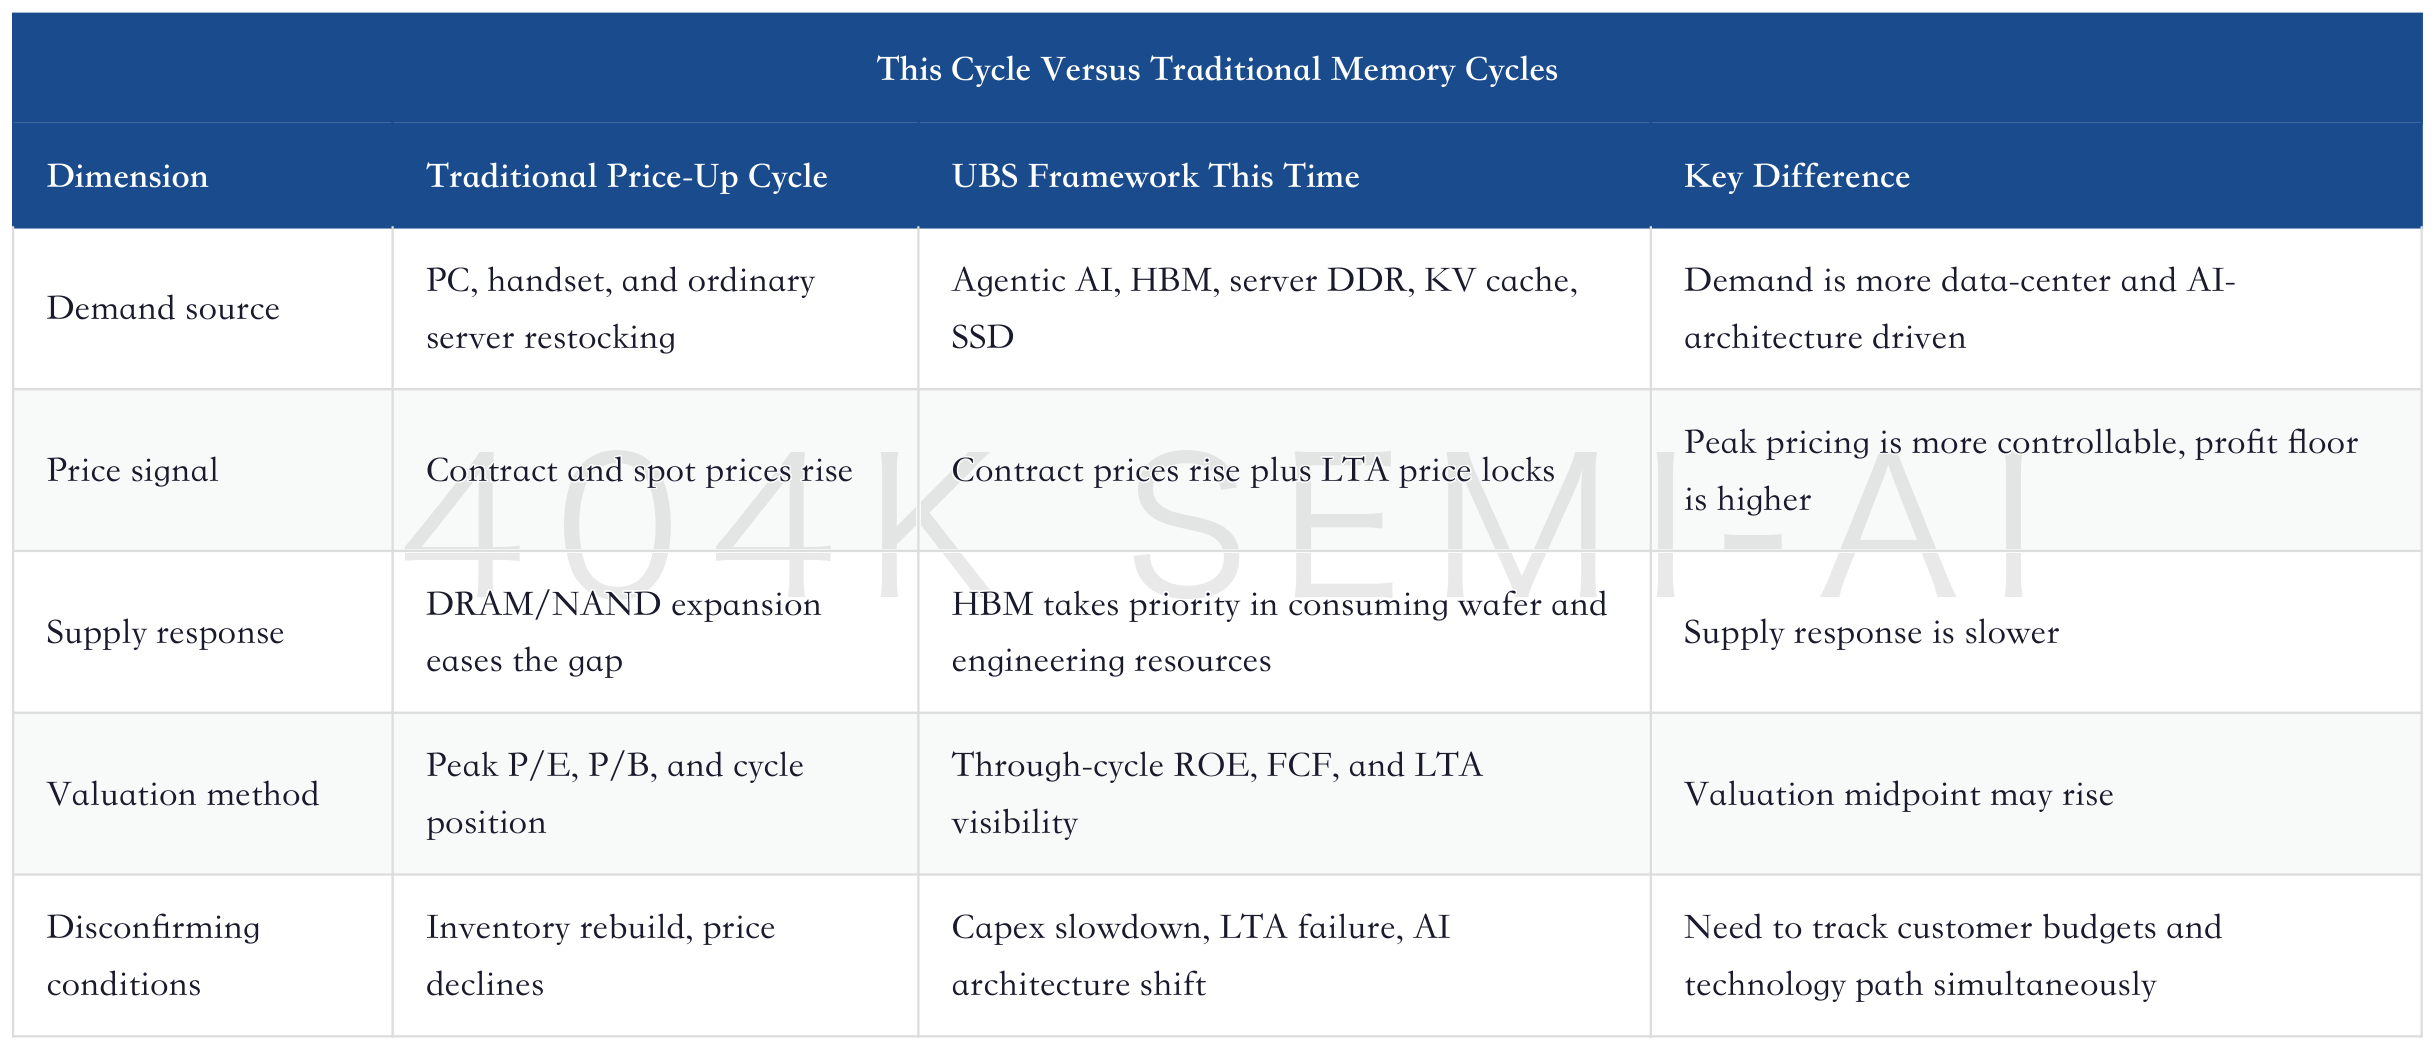
The easiest mistake is to treat all price increases as an “old cycle.” If it is just handset and PC restocking, the faster prices rise, the faster demand is destroyed, and the easier it is for valuations to be discounted. UBS is underwriting a different path this time: price increases come from data-center architecture upgrades, end customers are cash-rich hyperscalers, and part of volume and pricing is locked in by LTAs. If this premise holds, the market cannot simply cap valuations using the previous cycle peak.
The second common mistake is to view LTAs as a negative that weakens upside leverage. In the short term, long-term agreements do make the extreme pricing in an upcycle less sharp. Over the long term, they give the market a reason to re-rate. What cyclical stocks fear most is poor earnings visibility. LTAs turn part of the invisible into the visible, raising trough profits and cash flow. Valuation multiples may not be based on the highest EPS, but on how long high profits can last and how far the trough can fall.
The third mistake is looking only at HBM leaders. HBM is the clearest supply bottleneck, but UBS’ more important move this time is to include DDR and SSD in the AI trade as well. If the only-HBM logic holds, SK Hynix is the purest name. If the DDR/head-node logic holds, Samsung Electronics, Nanya Technology, memory interfaces, and the server chain should catch up. If the KV cache/SSD logic holds, Kioxia Holdings, SanDisk, Micron, and the enterprise SSD supply chain should have greater leverage.
X. A-Share/Hong Kong Mapping: Do Not Mechanically Equate the Global Memory View with All Domestic Memory Stocks
UBS covers core global memory assets such as Samsung Electronics, SK Hynix, Nanya Technology, and Kioxia Holdings. When mapping this view to A-shares and Hong Kong stocks, it is not enough to say, “memory prices are rising, so all memory stocks rise.” The domestic chain is more fragmented, and the channels of benefit differ: some companies are in memory modules and enterprise SSDs, some in niche DRAM/NOR, some in memory interfaces, and some in semiconductor equipment and materials.
Longsys and DML Technology are closer to the NAND/SSD and module chain. They benefit not from HBM itself, but from NAND prices, enterprise SSD demand, controller capability, and upgrades in brand and customer mix. If UBS’s KV cache/SSD logic materializes, enterprise SSD and memory-module platforms will gain better revenue elasticity. If only HBM and server DDR rise, module makers will still face upstream cost pressure and a test of their ability to pass costs downstream.
Montage Technology is closer to the server DDR and memory-interface chain. UBS’s upward revision to CPU/head node and server DDR has greater mapping relevance for memory-interface ICs, MRDIMM, CXL, Retimer, and related directions. Montage does not sell DRAM directly; it sits in the upgrade path of DDR5, server memory bandwidth, and interconnects. If agentic inference raises the weighting of CPU and DDR, the value of interfaces and interconnects should rise with it.
GigaDevice represents another type of elasticity in niche DRAM and NOR. After major manufacturers shift resources toward HBM and high-end server DDR, part of the traditional and niche demand will be left to non-leading vendors. This logic is similar to Nanya Technology, but domestic companies still need to be assessed by product mix, customer qualification, cost curve, and price pass-through. Niche memory is not a blind price-hike trade; the real question is whether the supply gap can land in the relevant product lines.
Naura Technology, AMEC, Changchuan Technology, and other equipment and testing-chain companies benefit from capacity expansion and domestic capacity construction. UBS emphasizes WFE lead time and engineering-resource bottlenecks, implying higher visibility for equipment orders. For the domestic equipment chain, the key is not global memory prices themselves, but whether advanced memory, mature DRAM, NAND, packaging/testing, and local capacity construction can generate continuous orders.
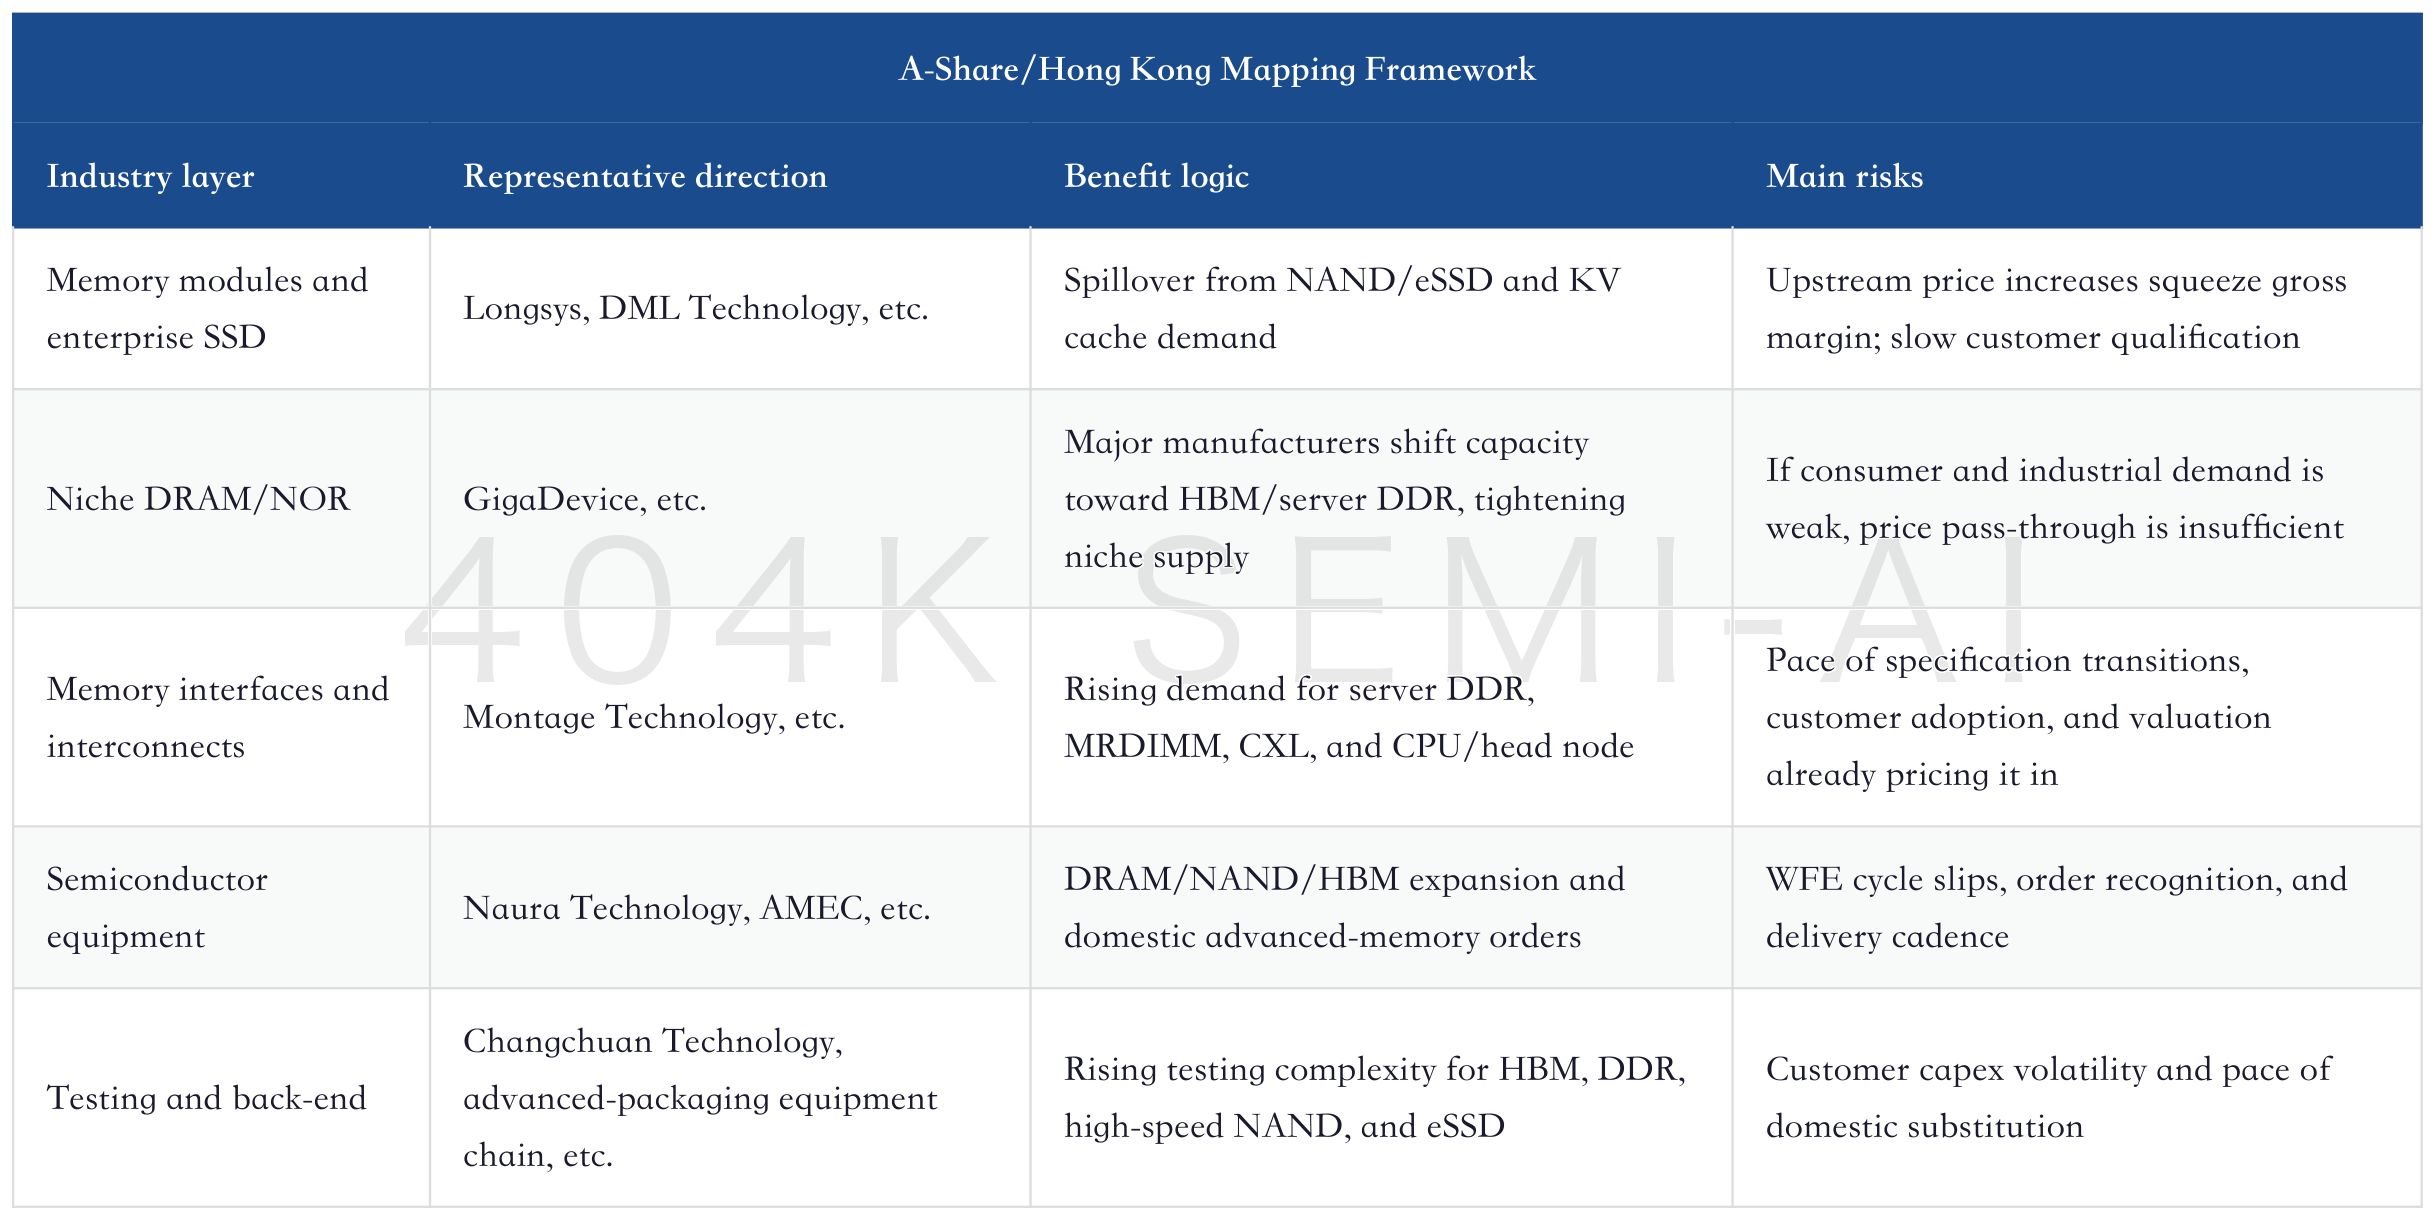
There is an important boundary to this mapping: UBS’s global memory super cycle does not mean that profits for all domestic memory stocks will scale linearly. Upstream wafer-fab price increases can be positive for module-maker revenue, but they can also create gross-margin pressure. Only companies with controllers, enterprise customers, brand channels, supply-chain bargaining power, or product-upgrade capability can retain the cycle dividend in their income statements.
Another boundary is nomenclature and data scope. Global reports often use Samsung Electronics, SK Hynix, Nanya, Kioxia Holdings, and Micron Technology as core samples. When mapping to domestic companies, one must return to formal security names and specific businesses. Longsys is Longsys, DML Technology is DML Technology, and Montage Technology is Montage Technology; English abbreviations from foreign broker reports should not be mixed with domestic companies. This is an easy mistake when reading cross-market memory reports.
XI. The Key to Valuation Rerating Is Splitting Profit Elasticity into Four Accounts
Memory-stock valuation should not only look at “how much prices have risen.” Price is certainly important, but this cycle needs to be split into four accounts: the price account, the share account, the long-term-agreement account, and the capex account. These four accounts answer different questions; together, they determine whether valuation can shift from cyclical stock to cash-flow asset.
The price account looks at ASPs for DRAM, HBM, NAND, and SSD. UBS expects HBM blended ASP to grow 14% in 2026 and 61% in 2027, and server DDR contract prices to potentially reach US$2.80/Gb by 4Q27. This account determines the near-term profit slope and the part of market sentiment most sensitive to change.
The share account looks at who gains more share in HBM and high-end products. SK Hynix is close to 50% HBM share in 2026, while Samsung Electronics may narrowly overtake it in 2027 by 42% to 40%. This account determines who can achieve higher earnings elasticity within the same industry upcycle. Changes in HBM share matter more for relative stock performance than total industry demand.
