
目录
1. Robust Revenue Growth, Yet Operating Profit Still Misses Expectations
2. AIDC Power Volume Ramps Up, but Profit Realization Remains Anchored in 2027
3. Vera Rubin Advances Thesis to Delivery; Liquid Cooling and ASICs Will Dictate the Next Trajectory
IV. Legacy Businesses Are Still Growing, but Gross Margins Reveal Pricing Pressure
V. Cash Flow: The Critical Verification Beyond the Profit Narrative
VI. Near-Term Cuts vs. Long-Term Hikes: The Timing Gap in the Earnings Inflection
VII. Target Price Raised to RMB 120: Why Goldman Sachs Stays Neutral
8. Six Key Metrics to Track Going Forward
本内容基于公开资料和研报数据整理,不构成任何投资建议,不代表任何个人观点,仅供学习参考,请理性阅读
Megmeet has begun delivering Vera Rubin power supplies, moving its AIDC growth thesis into the stage of physical validation. However, 2Q operating profit significantly missed expectations, as legacy business gross margins, cash flow pressures, and an elevated valuation continue to constrain near-term upside.
1. Robust Revenue Growth, Yet Operating Profit Still Misses Expectations
For Megmeet's 2Q results, the metric requiring the closest examination is operating profit rather than top-line growth. Revenue reached RMB 3.273 billion (+39% YoY), missing Goldman Sachs' estimate by just 1%. Gross profit came in at RMB 685 million (+37% YoY), 10% below Goldman Sachs' forecast. Operating profit was only RMB 92 million; despite an 89% YoY increase, it missed Goldman Sachs' estimate by 47% and Visible Alpha consensus by 53%.
Net profit reached RMB 137 million (+107% YoY), missing Goldman Sachs' estimate by a mere 2%. This divergence between operating profit and net profit demonstrates that focusing solely on headline net income risks overstating core operational quality. Goldman Sachs flagged operating profit as the primary shortfall because it directly captures the combined impact of core gross margins and operating expenses.
Second-quarter gross margin was 21%, trailing Goldman Sachs' forecast by 2 percentage points. Operating margin was 3%, also 2 percentage points below estimate, while net margin was 4%, in line with Goldman Sachs' expectations. Rapid revenue growth failed to convert proportionally into operating profit, as incremental product mix, margin erosion in legacy segments, and cost-passthrough friction weighed on near-term earnings elasticity.
Operating expense discipline demonstrated emerging economies of scale. The SG&A; expense ratio dropped to 16%, down 2 percentage points YoY and 1 percentage point QoQ. In other words, while operating leverage exists, the benefits of lower overhead were largely offset by gross margin pressure. Going forward, only when gross margins stabilize can expense reductions translate visibly into profit growth.
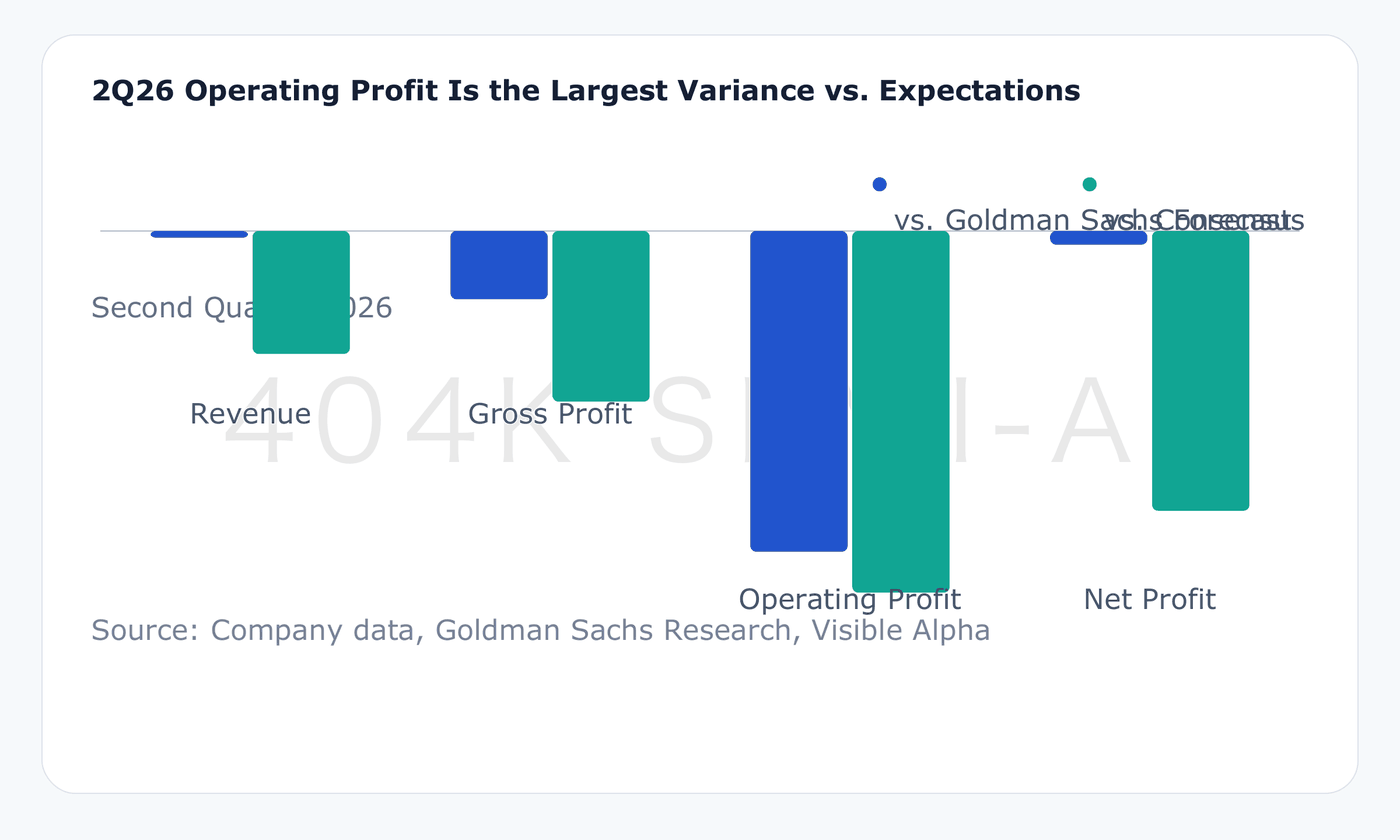
These figures establish the report's first key takeaway: while incremental revenue from AIDC has materialized, profit conversion remains in its early stages. Investors must evaluate top-line growth and earnings quality separately rather than assuming they will materialize in tandem.
Second-quarter revenue missed consensus by 18%, whereas operating profit missed by 53%—a pronounced negative leverage effect. Top-line variance explains only part of the earnings gap, with gross margins and business mix exerting far greater drag. To rebuild market expectations, sustaining high top-line growth alone will not suffice; gross profit and operating profit growth must realign with revenue momentum.
Net profit missed consensus by 41%, also reflecting a wide gap with operating profit. Because the report does not break down all non-operating items, it is unclear which specific gains offset the shortfall. A more reliable analytical approach is to treat operating margin as the true gauge of core operating health and net profit as the bottom-line output; a genuine inflection in earnings quality requires concurrent improvement across both metrics.
In the upcoming quarter, if revenue continues to grow while gross margins remain stuck around 21%, lower expense ratios will provide only a limited buffer. Only if gross margins rebound alongside an expanding operating margin will it signal that an improved AIDC product mix or legacy price adjustments are taking effect. This serves as the primary benchmark to determine whether 2Q's profit gap was a transient fluctuation or a structural headwind.
2. AIDC Power Volume Ramps Up, but Profit Realization Remains Anchored in 2027
The power supply segment is currently Megmeet's strongest growth engine. In 1H26, power supply revenue reached RMB 1.841 billion (+59% YoY), with 2Q revenue at RMB 1.024 billion (+54% YoY). While Goldman Sachs clearly identifies AIDC power supplies as the core driver, the report notes that the company has not disclosed absolute AIDC power revenue.
This informational boundary is critical. Power supply segment revenue cannot be equated directly with AIDC revenue, nor does rapid segment growth prove that Vera Rubin has entered high-volume mass production. Although the market has visibility into the new strategic direction, it still lacks verifiable quarterly data on AIDC revenue, shipment volumes, customer mix, and product breakdown.
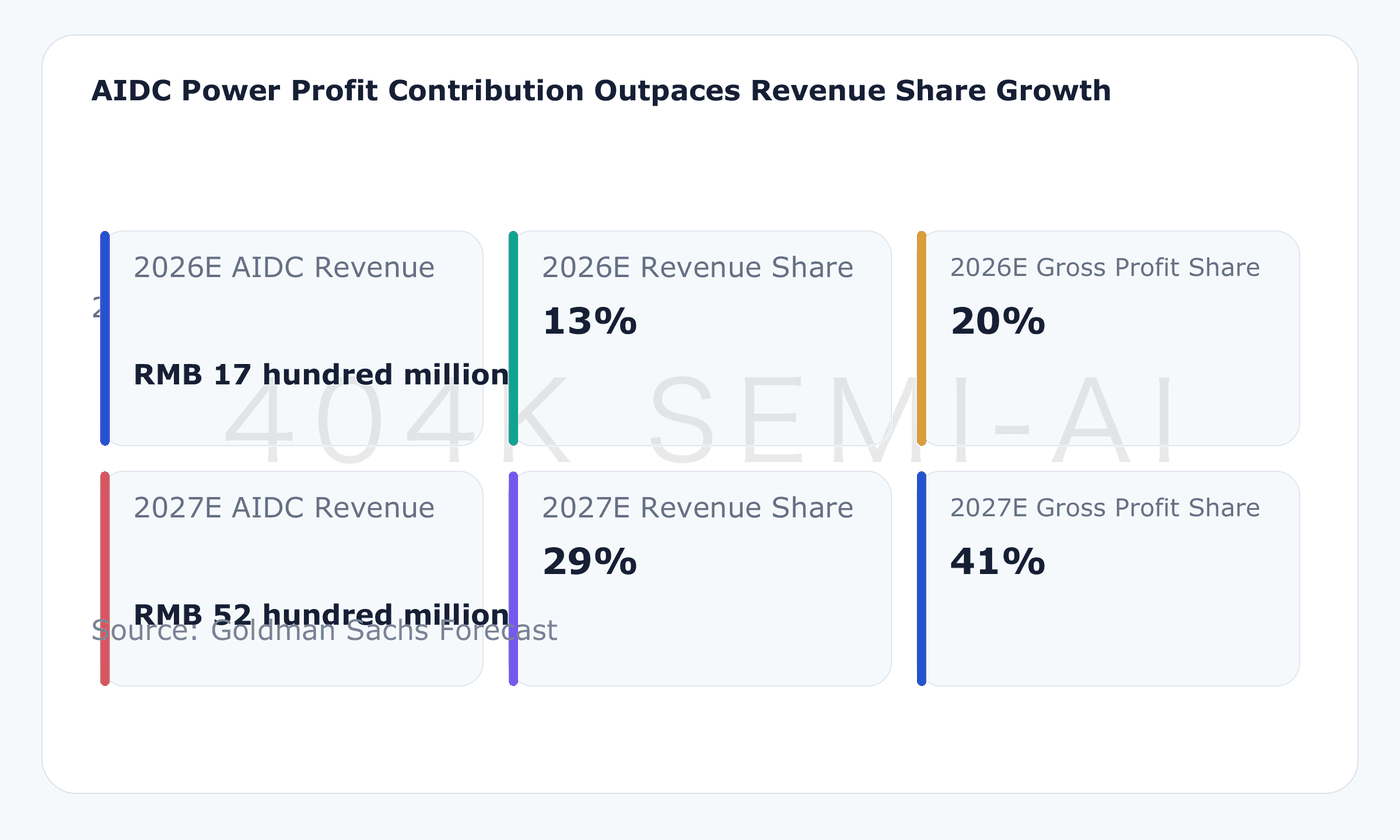
Goldman Sachs' projections illustrate why the market is focused on this segment: the firm expects Megmeet's AIDC power supply revenue to reach RMB 1.7 billion in 2026 and RMB 5.2 billion in 2027. This represents a near-tripling of revenue within one year, lifting its share of total revenue from 13% to 29%.
AIDC's impact on profit structure could be even more decisive. Goldman Sachs projects the business to contribute 20% and 41% of total gross profit in 2026 and 2027, respectively. The fact that the 2027 gross profit share significantly exceeds its revenue share implies that, if realized as projected, the AIDC mix will become a key driver of corporate margins and operating leverage.
A 29% revenue share versus a 41% gross profit contribution carries a clear implication: by 2027, Goldman Sachs' model relies on AIDC to drive the company's profit mix upgrade. Even if legacy businesses continue to expand, without a corresponding recovery in their gross margins, overall profit improvement will become increasingly dependent on AIDC.
This structural shift requires four conditions to hold simultaneously: customer orders must convert into shipments on schedule, manufacturing yields must support mass production, dollar-per-watt pricing cannot deteriorate rapidly, and component supply must remain stable. Deviation in any of these factors could delay the RMB 5.2 billion revenue or the 41% gross profit contribution.
Goldman Sachs did not disclose customer concentration or platform share, noting only that Megmeet has entered the NVIDIA ecosystem and is advancing custom ASIC projects with multiple US cloud service providers (CSPs). This confirms expanding pipeline opportunities, but does not prove the company has locked in a sticky, long-term market share. Re-qualification cycles across platform upgrades will continue to dictate competitive positioning in next-generation products.
This explains why Goldman Sachs can maintain near-term caution while upgrading long-term forecasts. The year 2026 remains a period of order conversion, product validation, and capacity ramp-ups, where incremental revenue may not immediately offset gross margin pressure in legacy segments. Only by 2027, if AIDC revenue and gross profit shares approach forecast levels, will the overall profit structure undergo a meaningful transformation.
The assumption of high AIDC gross margins is also conditional. The report notes that price-per-watt pricing is sensitive to near-term supply-demand dynamics and component availability. As product volumes scale, increased competition, client pricing power, and supply easing could alter pricing. Current forecasts reflect Goldman Sachs' assessment of order visibility, product mix, and operating leverage rather than locked-in profitability.
3. Vera Rubin Advances Thesis to Delivery; Liquid Cooling and ASICs Will Dictate the Next Trajectory
Progress on Vera Rubin has shifted Megmeet from merely "entering the AI server power supply chain" to "commencing initial deliveries." The company has delivered air-cooled Vera Rubin power supplies to customers, with liquid-cooled versions scheduled for 4Q26 to 1Q27. However, the report does not disclose air-cooled shipment volumes; thus, current visibility confirms supplier status rather than the magnitude of revenue contribution.
Management expects new AIDC orders to grow significantly sequentially in 2H26 and accelerate rapidly in 2027. Within the product mix, demand share for Vera Rubin is expected to rise, while contributions from GB200 and GB300 decline. This shift underscores that Megmeet must continually pass qualification cycles on new-generation platforms, as legacy platform orders do not automatically convert into next-generation share.
Megmeet is also advancing custom ASIC projects with multiple US CSPs, involving ~5.5 kW power supply solutions. While ASIC initiatives could reduce reliance on single GPU platform release cycles, customer validation, mass-production yields, and datacenter buildout schedules will continue to influence quarterly shipments. A time lag remains between order placement and recognized revenue.
The 800V DC architecture provides a longer-term product roadmap. Megmeet is developing power racks, 800V-to-50V power shelves, and DC-DC power bricks, with plans to introduce solid-state transformers in 1H27. However, management notes that because safety standards remain incomplete, 800V DC is unlikely to become mainstream across the industry by 2027, and widespread adoption of solid-state transformers may not occur until after 2029.
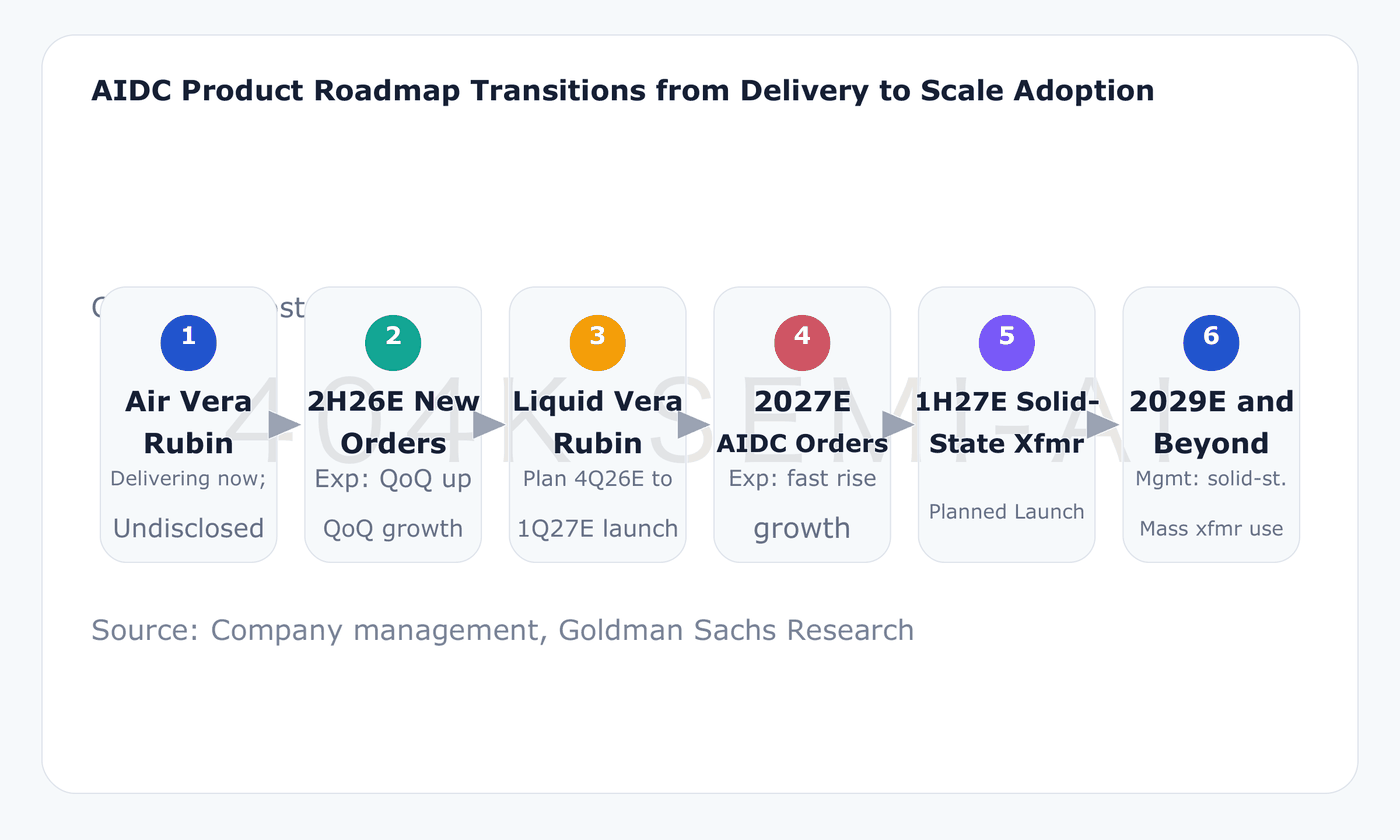
This timeline reminds investors to distinguish among three phases: sampling and qualification, initial deliveries, and high-volume mass production. While Megmeet has crossed the first two stages for certain products, commercial-scale mass production still requires verification via quarterly revenue and shipment data. Any estimate that equates "initial deliveries" directly with "meaningful profit contribution" overlooks customer deployment schedules and volume ramp execution risks.
The path from orders to profit is also mediated by customer datacenter buildout timelines. The report explicitly highlights that quarterly shipments and sales will depend on facility construction progress. Even if underlying annual demand remains intact, fluctuations in facility handovers, server deployments, and customer acceptance can cause noticeable quarterly revenue volatility.
Product efficiency and portfolio breadth will determine whether the company can defend its market share. Goldman Sachs notes that Megmeet's high-efficiency product lineup still lags behind Tier-1 incumbents like Delta Electronics. As new entrants proliferate, competition will evolve from "supply availability" to whether a vendor can simultaneously meet benchmarks across efficiency, reliability, delivery, and cost.
The 800V DC architecture and solid-state transformers are best viewed as long-term call options rather than foundational revenue drivers for 2027. Management itself has not brought forward its timeline for industry-wide 800V DC adoption. Factoring this revenue into near-term valuations prematurely conflates product introduction with commercial adoption at scale.
IV. Legacy Businesses Are Still Growing, but Gross Margins Reveal Pricing Pressure
Megmeet's legacy businesses are not in broad contraction; rather, the core challenge lies in the quality of growth. In 1H26, home appliance revenue grew 19% YoY, accelerating to 40% YoY in 2Q26. While recovering overseas demand provided support, domestic momentum was constrained by a soft real estate market.
The new energy vehicle (NEV) and rail transit components segment grew revenue by 11% and 9% YoY in 1H26 and 2Q26, respectively, while industrial automation grew 15% and 13% YoY over the same periods. Although all three legacy segments maintained positive top-line growth, their 1H26 gross margins came in at 18%, 13%, and 28%—contracting by 4, 1, and 1 percentage points YoY, respectively.
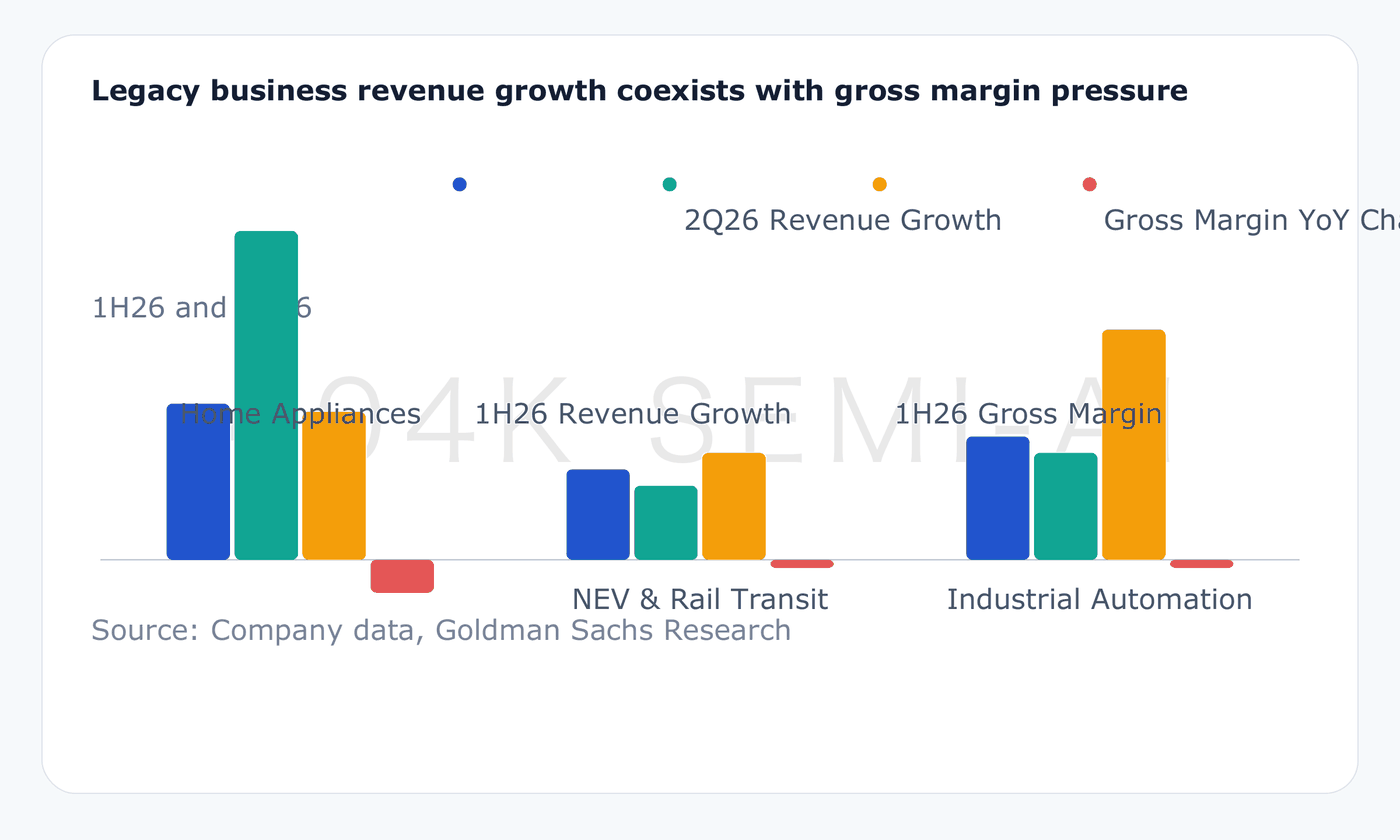
Rising raw material costs, sluggish domestic demand, and RMB appreciation have combined to pressure margins. Although Megmeet issued a company-wide price increase notice in June, customer pushback has been relatively mild overseas but significantly stiffer domestically, particularly within the automotive sector. The price hike notice itself does not guarantee an immediate margin rebound, as actual realization depends on customer acceptance and the timing of contract renewals.
These legacy operations will dictate whether AIDC growth successfully translates into corporate-level profit expansion. If legacy gross margins continue to slide, incremental gross profit from AIDC will merely plug legacy earnings deficits. Only if price increases take hold and raw material cost pressures subside will incremental AIDC contributions lift company-wide margins.
The proportion of overseas revenue represents another critical variable. Management expects roughly 20% of AIDC orders from 2H26 through 2027 to come from China and 80% from overseas, targeting an increase in overall overseas sales to 50%–60% by 2027. While overseas clients present less friction on pricing pass-through, expanding international operations introduces heightened demands on customer qualification, foreign exchange management, and global fulfillment.
There are three potential pathways for legacy business recovery: first, a rebound in domestic demand that improves capacity utilization and product mix; second, gradual price increases that offset raw material inflation; and third, an expanding overseas revenue share that leverages smoother cost pass-through to alleviate margin pressure.
These three pathways operate on differing timelines. Raw material prices and currency exchange rates can fluctuate rapidly, whereas customer price adjustments require contractual renewal cycles, and domestic demand recovery remains dependent on broader macroeconomic conditions. Upgrading full-year gross margin expectations based solely on a single price-hike announcement overlooks these timing lags.
The 40% YoY revenue surge in home appliances in 2Q26 alongside a 4-percentage-point YoY drop in 1H26 gross margin underscores that rapid top-line growth does not inherently deliver stronger profitability. In upcoming segment disclosures, revenue growth and gross margins must be assessed in tandem; viewing either metric in isolation risks reaching premature conclusions regarding fundamental recovery.
V. Cash Flow: The Critical Verification Beyond the Profit Narrative
In 1H26, Megmeet generated just RMB 30mn in operating cash flow (OCF), down sharply from RMB 192mn in the prior-year period. Over the same timeframe, capital expenditures reached RMB 190mn, up 9% YoY, as the company continued expanding manufacturing capacity across China and Thailand while building R&D; and testing facilities for AIDC products.
The report did not provide a full breakdown of the OCF decline, making it impossible to assign the drop entirely to accounts receivable, inventory, or any single line item. What is clear is that the company is going through a phase where accounting profit and capital deployment are disconnected. Rapidly expanding AIDC orders are likely front-loading cash requirements for raw material procurement, qualification, capacity expansion, and customer fulfillment.
Operating cash flow does not need to match net profit in every individual quarter, but sustained divergence raises the cost of expansion. Because Megmeet's forward valuation prices in aggressive volume scaling, cash conversion cannot remain absent indefinitely. Going forward, key metrics to track include the OCF-to-net-profit ratio, working capital shifts across inventory and receivables, and whether capital investments generate visible output.
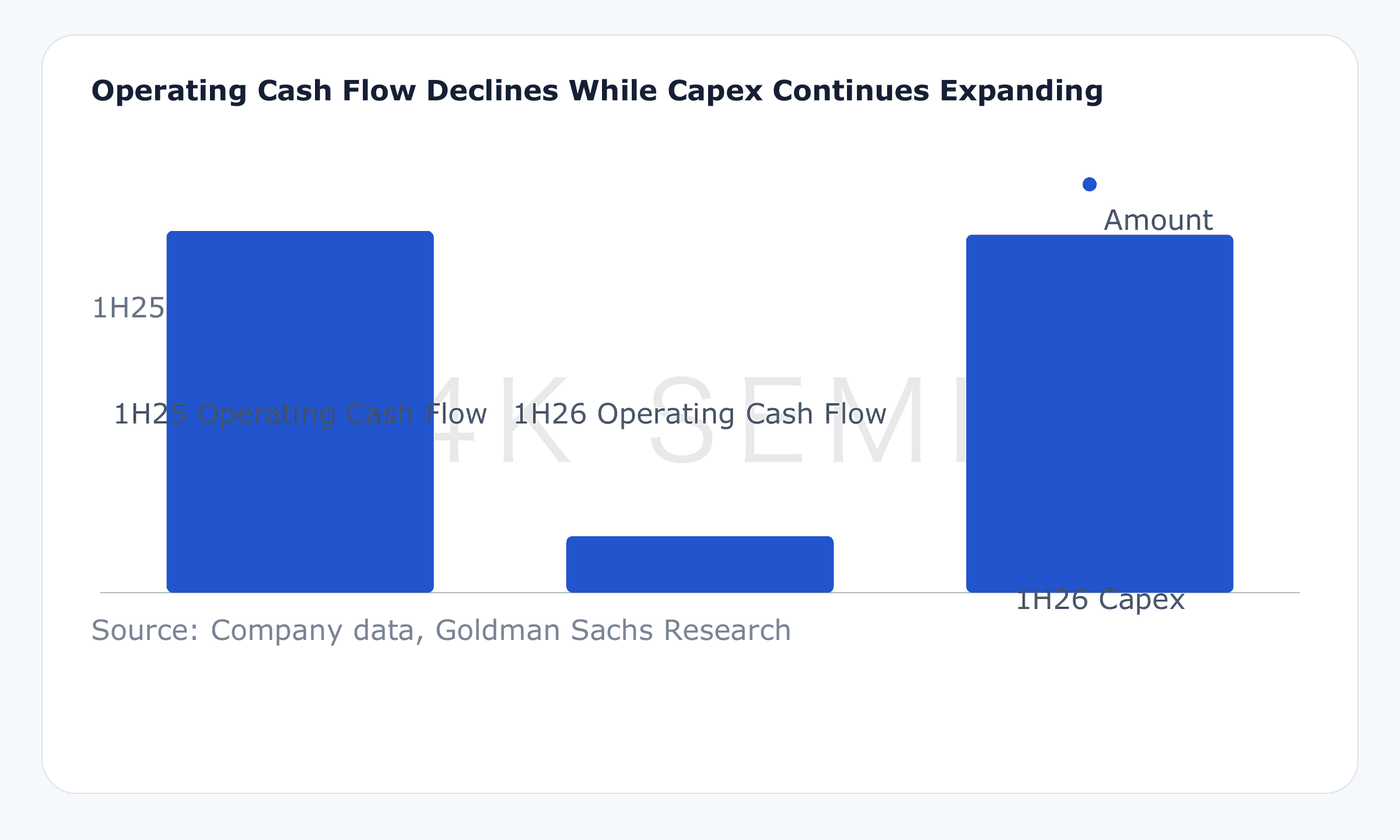
Cash flow also dictates valuation margin of safety. If earnings growth relies on persistent capital outlays, enterprise value will appreciate at a slower pace than the income statement suggests. Only if OCF improves substantially as AIDC revenue ramps up can the market confirm that this is a scalable, cash-generative business rather than growth existing solely within order books and earnings models.
In 1H26, OCF covered only ~16% of capex. While this does not directly indicate poor return on investment—since new capacity and R&D; facilities require lead time before generating revenue—it highlights that free cash flow is under significant strain, placing elevated demands on financing capabilities and working capital management during this expansionary phase.
Leading indicators for cash flow can be divided into two clusters: working capital metrics (inventory levels, accounts receivable, and cash collections) and capex conversion (when capacity under construction transfers into fixed assets and begins shipping). The report lacked these granular details, leaving upcoming earnings reports to provide the requisite evidence.
If AIDC revenue ramps alongside a corresponding rebound in OCF, the capacity expansion thesis will gain substantial credibility. Conversely, if revenue expands while cash flow continues to deteriorate, investors will need to determine whether customer payment terms, inventory pre-stocking, and capacity ramp-ups are tying up capital over the long run—a dynamic that erodes the enterprise value created by each dollar of reported net income.
VI. Near-Term Cuts vs. Long-Term Hikes: The Timing Gap in the Earnings Inflection
Goldman Sachs trimmed its 2026 and 2027 net profit forecasts for Megmeet by 10% and 6%, respectively. The downgrades reflect weaker-than-expected legacy operations, sustained gross margin headwinds, and the reality that initial AIDC volume ramps remain insufficient to fully offset these legacy drags.
Concurrently, Goldman Sachs raised its 2028–2030 net profit forecasts by an average of 11%, driven by expanding AIDC scale and operating leverage. These revisions delineate a clear timing divergence: visibility over the next two years has weakened, even as the long-term earnings ceiling has been lifted.
Goldman Sachs forecasts Megmeet's revenue to reach RMB 12.661bn in 2026, RMB 17.643bn in 2027, and RMB 25.898bn in 2028, with corresponding EPS of RMB 0.98, RMB 2.35, and RMB 4.16. Both top-line revenue and EPS require two consecutive years of hyper-growth to gradually compress the current valuation.
The stock trades at projected P/E multiples of ~128.2x for 2026 and 53.7x for 2027, before easing to 30.3x in 2028. Valuation multiple compression depends almost entirely on denominator expansion—specifically, rapid EPS acceleration. Any delay across order conversion, product mix, gross margins, or mass-production timelines will lengthen the multiple digestion period.
Based on Goldman Sachs' projections, revenue is set to grow ~39% YoY in 2027 and another ~47% YoY in 2028. EPS growth is modeled even faster, surging ~140% YoY in 2027 and ~77% YoY in 2028. The model implicitly assumes that profit growth will significantly outpace revenue expansion, predicated on product mix optimization and operating leverage.
This earnings trajectory is highly sensitive to gross margins. If revenue meets expectations but gross margins undershoot model assumptions, operating expense dilution may not suffice to offset the gap. Conversely, if AIDC gross profit contribution rises while legacy margins stabilize, earnings growth could significantly outrun revenue growth.
The downward revisions to near-term estimates also steepen the climb toward the 2028 target. With the 2026 EPS baseline lowered to RMB 0.98, reaching RMB 4.16 over the subsequent two years requires a more than three-fold cumulative increase. While achievable, any quarterly execution slippage will be amplified across long-term valuation multiples.
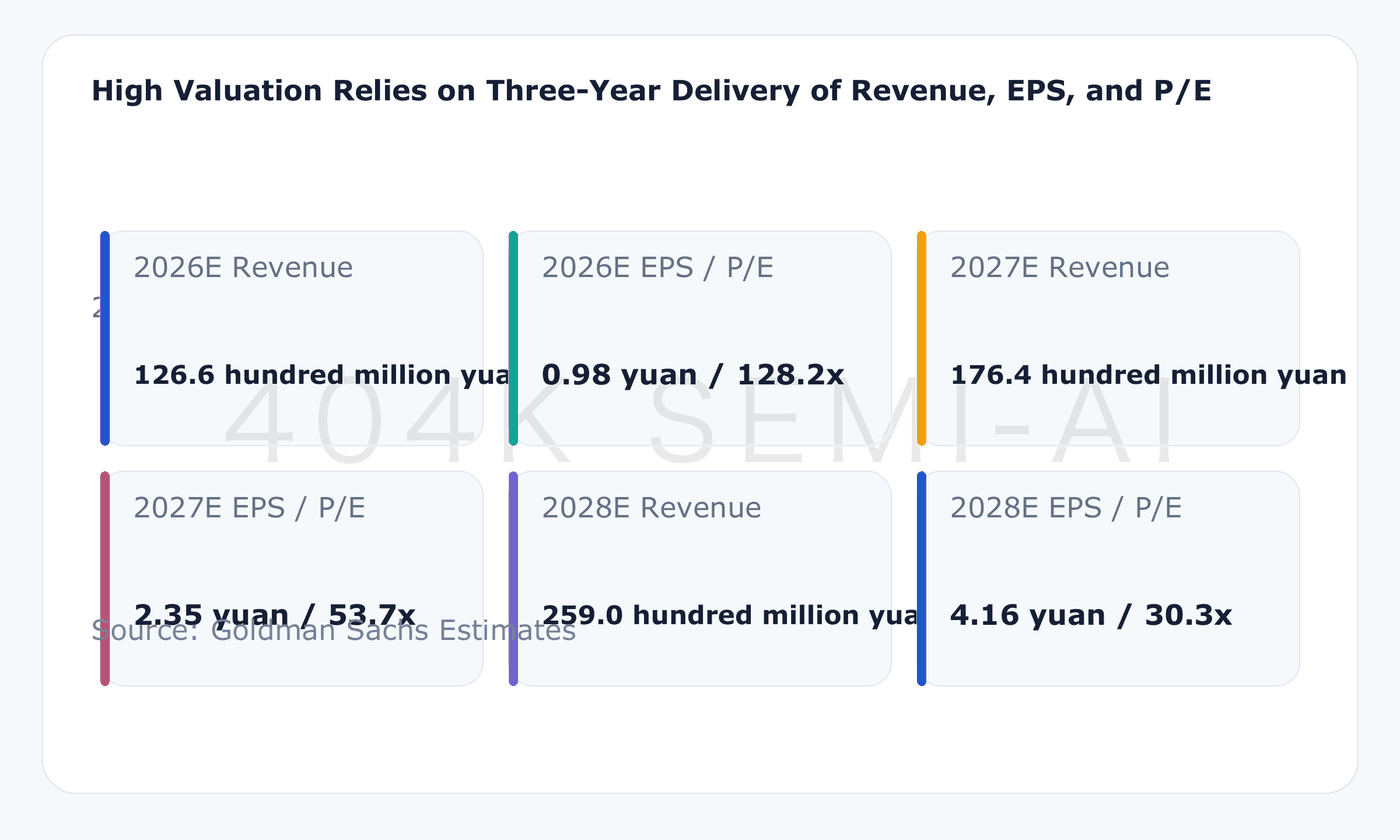
These projections also establish explicit criteria for thesis falsification. If 2027 AIDC revenue falls materially below RMB 5.2bn, or if its gross profit contribution fails to approach 41%, the upward revisions to long-term earnings will require re-evaluation. Furthermore, if legacy gross margins fail to bottom out, incremental AIDC profit gains will continue to be diluted.
VII. Target Price Raised to RMB 120: Why Goldman Sachs Stays Neutral
Goldman Sachs raised its 12-month target price from RMB 112 to RMB 120, applying a 32x 2028E P/E multiple discounted back to 2027 at an 11% cost of equity. The higher target price primarily reflects upgraded long-term earnings forecasts rather than increased optimism regarding near-term operating performance.
Prior to the report's release, Megmeet closed at RMB 125.95, roughly 4.7% above Goldman Sachs' target price. Consequently, the target price increase offers no upside headroom. Goldman's Neutral rating signals that growth upside is roughly balanced against rich valuation multiples and execution risks.
A 32x 2028E P/E multiple embeds aggressive growth assumptions. The median 2026E and 2027E P/E across Goldman Sachs' China Industrial Tech coverage universe sits at ~26x and ~23x, compared to ~128x and ~54x for Megmeet over the same periods. Megmeet must deliver significantly faster earnings growth simply to digest this steep valuation premium.
Megmeet's 2026E P/E is nearly five times the coverage median, and remains more than double in 2027E. This premium prices in global AIDC supply chain entry, Vera Rubin deliveries, and long-term margin expansion. If only a fraction of these catalysts materialize, the valuation premium will lack sufficient fundamental earnings support.
Valuing the company on 2028 earnings and discounting back to 2027 creates substantial reliance on long-dated assumptions. As the forecast horizon extends, uncertainties around order volumes, competition, pricing, and technology roadmaps increase significantly. While an 11% cost of equity accounts for the time horizon and execution risks, it cannot eliminate the forecasting error embedded in the earnings estimates themselves.
The risk-reward profile can be categorized into three scenarios: a bull case where Vera Rubin and ASIC projects ramp faster than anticipated and drive an earlier mix shift toward AIDC gross profits; a base case where AIDC expands as scheduled but persistent legacy headwinds delay overall profit improvement; and a bear case where qualification, mass production, or customer rollout timelines slip alongside valuation multiple contraction.
Goldman Sachs did not provide standalone target prices for each scenario, outlining only the primary valuation drivers. Consequently, RMB 120 is best interpreted as the output of a specific set of baseline assumptions rather than a fixed anchor immune to fundamental shifts. Maintaining a Neutral rating reflects this balance between conflicting forces.
The valuation framework hinges on three key variables: first, whether 2028E EPS of RMB 4.16 is delivered; second, whether the market remains willing to assign a 32x forward P/E; and third, whether an 11% cost of equity sufficiently reflects customer concentration, mass-production, and technology roadmap risks. Any compression in these assumptions would directly impair the target price.
A Neutral rating does not represent a rejection of the AIDC business. Rather, it indicates that positive drivers must translate into quantifiable revenue, earnings, and cash flow to support the growth expectations already embedded in the stock price. With the market already paying a premium for long-term growth, every subsequent quarter will serve as a critical checkpoint for execution.
8. Six Key Metrics to Track Going Forward
Evaluating Megmeet's forward trajectory hinges on six sets of publicly reported figures rather than unverified order flows and technical narratives.
First, absolute AIDC power supply revenue and its share of total power supply revenue. Current reports only identify AIDC as the primary growth driver without disclosing absolute figures. This metric will determine whether the RMB 1.7 billion and RMB 5.2 billion revenue forecasts materialize on schedule.
Second, quarterly shipments of air-cooled Vera Rubin products, along with the validation and mass-production status of liquid-cooled versions in 4Q26 to 1Q27. Product launches, customer qualification, and revenue recognition must be evaluated as separate milestones.
Third, power supply segment gross margin and corporate blended gross margin. If AIDC's gross profit contribution increases, blended gross margin should gradually find support. Conversely, if power supply revenue grows while blended gross margin continues to compress, legacy business margin pressure and AIDC pricing dynamics must be closely scrutinized.
Fourth, the effective implementation of price hikes across home appliances, NEVs/rail transit, and industrial automation. Post-hike gross margin trajectory is far more informative than price-increase notices alone, with domestic customer acceptance being particularly critical.
Fifth, the relationship among operating cash flow, capex, and net income. If top-line expansion is accompanied by persistent cash flow weakness, the quality of business expansion warrants caution. Operating cash flow must improve alongside the AIDC volume ramp to prove that order growth is converting into realized economic returns.
Sixth, execution against 2027 revenue and EPS forecasts. Goldman Sachs' projected RMB 17.643 billion in revenue and RMB 2.35 in EPS represent the critical stepping stones for valuation to compress from 128x to 54x P/E. Any significant deviation will disrupt the market's pace of digesting current multiples.
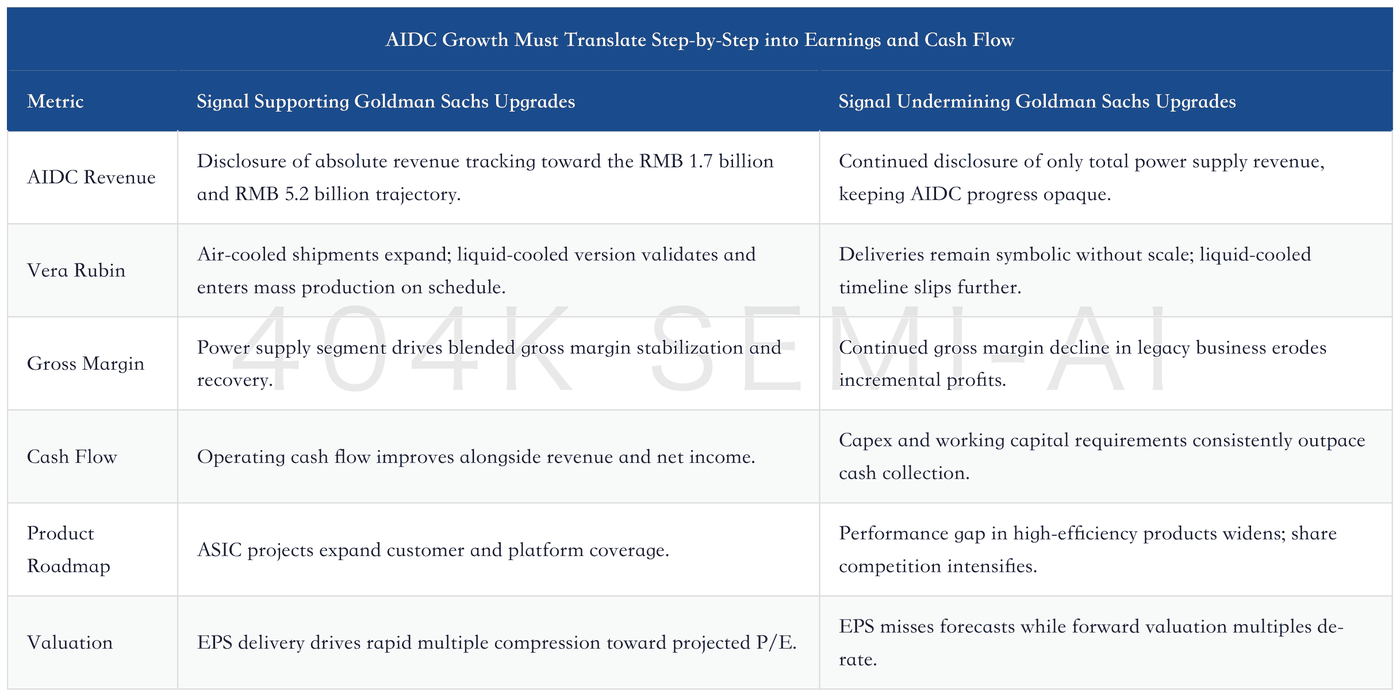
This checklist places technology, orders, and financials along a single validation chain. Improvement in any single metric is insufficient to confirm the overarching thesis: expanding air-cooled shipments must translate into revenue, revenue growth must flow through to gross profit, and gross margin expansion must ultimately convert into cash flow.
The primary value of Goldman Sachs' report lies in mapping near-term earnings gaps and long-term product opportunities onto the same timeline. Second-quarter results show that the company has not yet escaped legacy business headwinds, while Vera Rubin deliveries demonstrate tangible progress in its new growth vector. Both realities coexist, and any conclusion focusing solely on one remains incomplete.
Investors should dynamically update their assessment over the coming quarters rather than placing an all-or-nothing bet on 2028 outcomes. If AIDC revenue, liquid-cooled product milestones, segment gross margins, and operating cash flows improve in sequence, the case for forward earnings upgrades will strengthen. Conversely, if two or more of these metrics consistently disappoint, market expectations for both growth velocity and valuation multiples must be adjusted downward.
Megmeet has secured a critical entry ticket into next-generation AI server power supply competition, and the commencement of air-cooled Vera Rubin deliveries marks substantial progress. However, the company's ultimate intrinsic value depends on whether this entry ticket can consistently translate into sustained orders, gross profit, and cash flow. Legacy gross margin drag, volume execution risks, and elevated valuation leave little margin for error—explaining why Goldman Sachs maintained a Neutral rating even after raising its long-term price target.