
目录
TL;DR
What Does a 129-Basis-Point Underweight Actually Mean?
Why Nvidia Becomes Harder for Active Portfolios to Match as It Rises
Why Capital Is Crowding into Storage and Equipment
Premium Positioning Is Both the Core Earnings Thesis and a Crowded Trade
Mega-Cap Underweights Do Not Imply Rejection of the Fundamentals
Software Positioning Is Soft; What Is Really Missing Is Proof of Revenue
Where These Positioning Signals Are Most Likely to Mislead
Which Numbers Could Change the View in the Next Round
本内容基于公开资料和研报数据整理,不构成任何投资建议,不代表任何个人观点,仅供学习参考,请理性阅读
The same active managers are embracing storage and semiconductor equipment while remaining underweight Nvidia and other stocks with the largest index weights. The explanation lies at the intersection of benchmark weights, earnings delivery, and crowding risk.
TL;DR
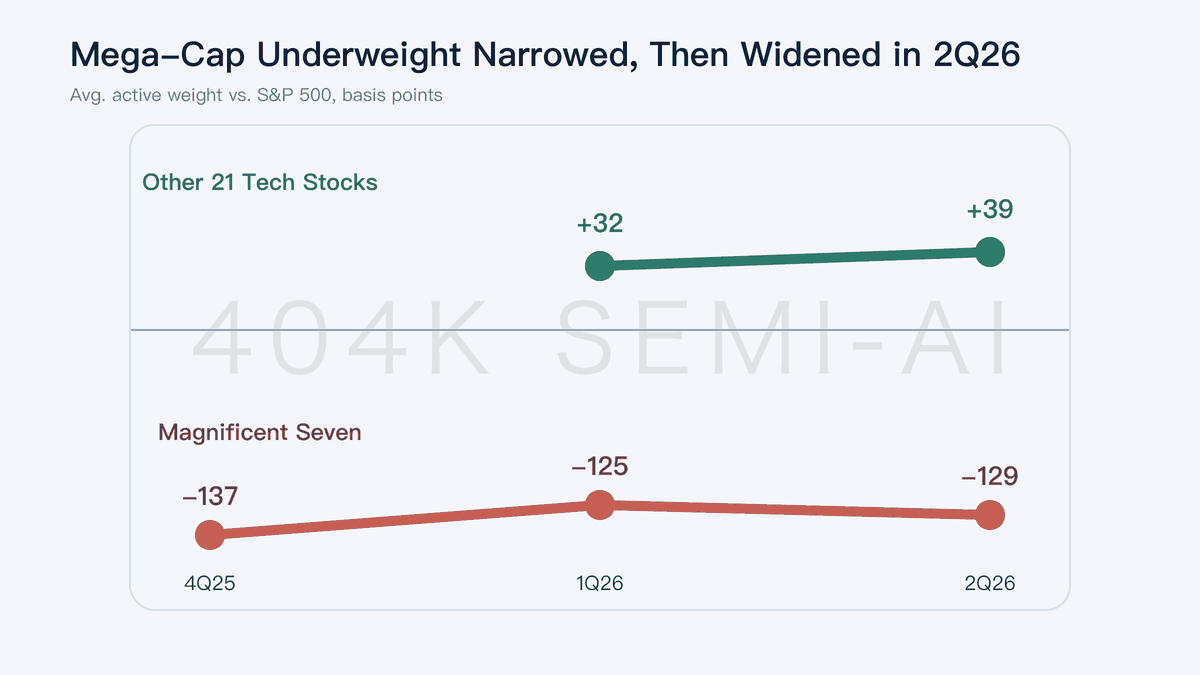
Technology positioning has become increasingly polarized. Morgan Stanley compared the portfolios of the 100 largest active managers at the end of 2Q26 with S&P; 500 weights. The seven largest technology stocks were underweight by an average of 129 basis points, widening from 125 basis points in 1Q26; the other 21 companies were overweight by an average of 39 basis points, up from 32 basis points.
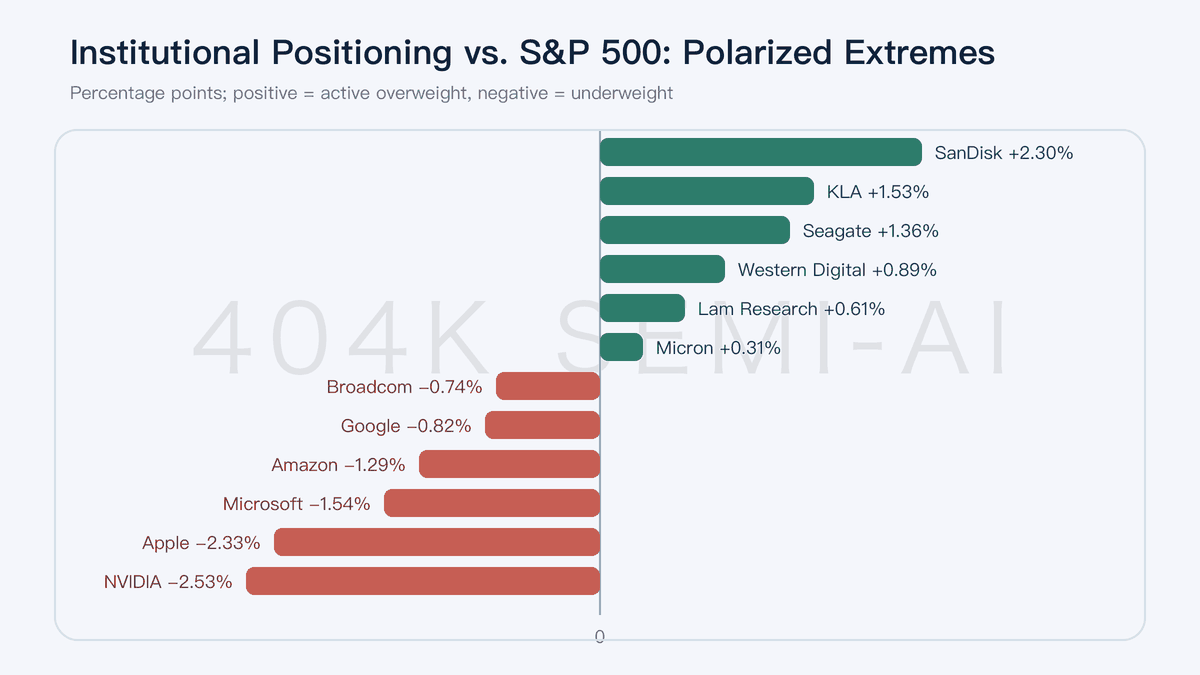
At the two extremes, Nvidia was underweight by 2.53%, Apple by 2.33%, Microsoft by 1.54%, and Amazon by 1.29%, while SanDisk was overweight by 2.30%, KLA by 1.53%, Seagate Technology by 1.36%, and Western Digital by 0.89%. Active risk budgets are increasingly concentrated in supply-constrained areas such as storage, hard drives, process control, and semiconductor equipment.
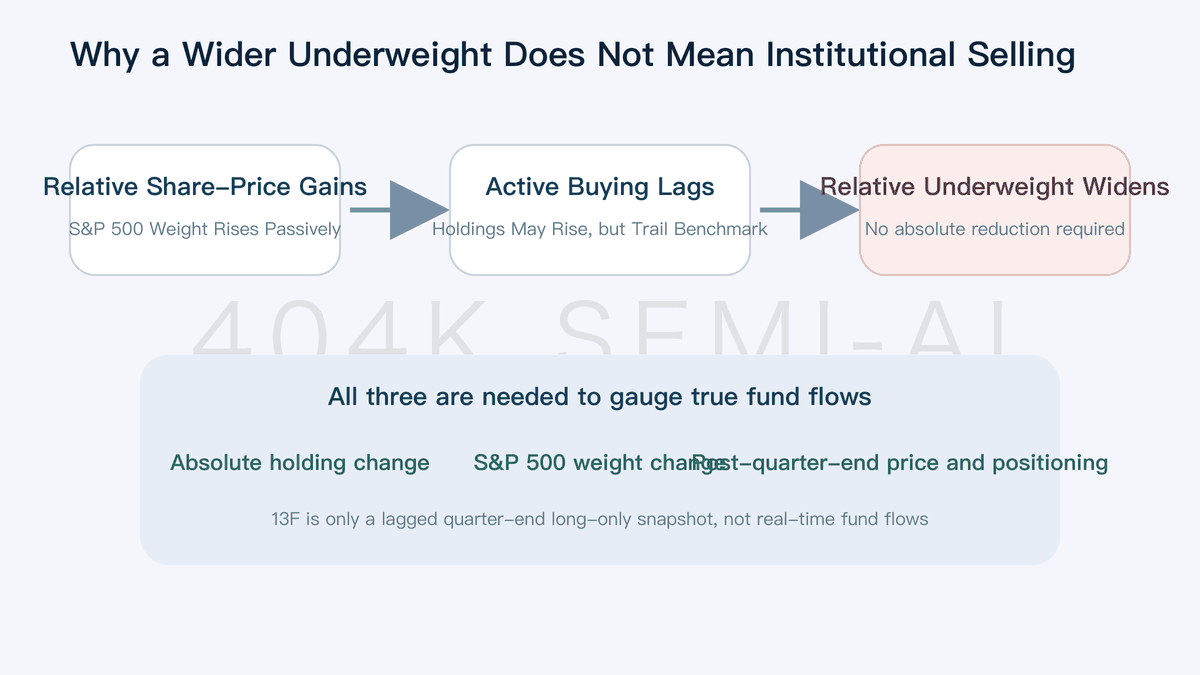
The data measure positioning relative to benchmarks, not real-time fund flows. An underweight may reflect an outright reduction in holdings, or simply that a stock’s benchmark weight rose faster after outperforming. An overweight may signal earnings conviction, but it may also indicate crowded expectations. Nvidia’s positioning gap creates scope for catch-up buying, while SanDisk’s overweight requires continued fundamental delivery.
What Does a 129-Basis-Point Underweight Actually Mean?
Morgan Stanley’s metric is not institutional ownership as a percentage of shares outstanding. It is the average portfolio weight among active managers minus the same company’s weight in the S&P; 500. If a company represents 7% of the index but averages only 5% across the 100 largest active portfolios, the relative gap is negative 2 percentage points. The metric measures how much risk active managers are taking relative to the benchmark, not how many shares the market as a whole owns.
This distinction is critical. An average underweight of 129 basis points across the seven largest technology stocks does not mean every company was sold, nor does it imply that institutions have turned bearish on long-term AI demand. When a large benchmark constituent rises, its index weight increases automatically. Even if active funds add to their absolute holdings, the relative underweight can still widen if they do not add quickly enough. Conversely, a smaller company may develop a substantial relative overweight after receiving only a limited amount of active capital.
The historical trajectory shows that the gap has not deteriorated in a straight line. The average underweight among the seven largest technology stocks was 137 basis points in 4Q25, narrowed to 125 basis points in 1Q26, and then widened again to 129 basis points in 2Q26. The other 21 technology stocks moved from a 32-basis-point average overweight in 1Q26 to 39 basis points. In other words, 2Q26 did not see a broad reduction in technology exposure. Instead, active portfolios continued reallocating risk budgets away from the largest index constituents and toward second-tier AI infrastructure and semiconductor-equipment companies.
Company-level changes make this pattern even clearer. Nvidia’s underweight widened from 2.39% in 1Q26 to 2.53%, Apple’s edged up from 2.32% to 2.33%, and Amazon’s increased from 1.24% to 1.29%; Microsoft’s, however, narrowed from 1.86% to 1.54%. If active funds were uniformly reducing mega-cap technology risk, Microsoft would not have improved against the trend. A more plausible explanation is that, even under the same concentration constraints, portfolio managers continue to differentiate based on earnings visibility, market pricing, and product cycles. Microsoft’s enterprise distribution and Azure revenue are relatively straightforward to model. Nvidia has the strongest demand, but also faces the greatest pressure from its benchmark weight and single-stock exposure limits.
The report also presents an important quantitative finding that should not be overextended: after controlling for market capitalization and earnings surprises, lower active ownership has a statistically significant relationship with subsequent share-price performance, suggesting that such stocks may benefit from technical upside pressure. However, the report does not disclose the regression coefficients, forecast horizon, significance levels, out-of-sample results, or implementation costs. The appropriate interpretation is therefore that an extreme underweight increases the probability of future catch-up—not that underweight stocks inevitably rise. Positioning creates conditions for incremental flows; it is not a judgment of fundamental value.
Why Nvidia Becomes Harder for Active Portfolios to Match as It Rises
Nvidia was underweight by 2.53% in 2Q26, 14 basis points wider than the 2.39% gap in 1Q26 and already near the extreme of the report’s historical series. This can easily be misread as institutional selling, but a sounder interpretation requires tracking two variables simultaneously: Nvidia’s changing weight in the S&P; 500 and the change in active portfolios’ absolute holdings. If share-price appreciation increases its benchmark weight while active funds cannot add proportionately because of single-company risk limits, industry-exposure restrictions, or already substantial positions, the underweight gap will widen mechanically.
These constraints are particularly powerful for mega-cap technology stocks. An index does not manage concentration risk; it simply increases weights according to its rules. Active funds, by contrast, must control single-stock, sector, and factor exposures. The more central Nvidia becomes to the index, the more likely portfolio managers are to remain structurally underweight while simultaneously maintaining a bullish view of the company. Apple’s 2.33% underweight, Microsoft’s 1.54% underweight, and Amazon’s 1.29% underweight reflect similar benchmark constraints, although their fundamental trajectories differ.
Divergence within 2Q26 further confirms that this was not a uniform shift toward a negative view. Microsoft’s relative gap improved by 31 basis points quarter on quarter, making it the only one among the seven largest technology stocks to narrow materially. Nvidia deteriorated by 14 basis points, Google by 19 basis points, while Meta, Broadcom, and Tesla also weakened further. Active capital is reprioritizing within mega-cap technology rather than mechanically treating all seven companies as a single asset class. Microsoft’s release of Azure capacity, enterprise-software distribution, and Copilot monetization may be easier for institutions to translate into visible earnings. Nvidia’s GPU demand is stronger, yet its larger benchmark weight and more concentrated absolute ownership make matching the index more difficult.
This also explains how “highest conviction” and “largest underweight” can coexist. Morgan Stanley maintains a positive research view on Nvidia and assigns it a reference price of $288, 27.9% above the share price cited in the report; its model forecasts revenue growth of 82.0% in 2026 and 52.4% in 2027. If these assumptions materialize, the underweight gap could create pressure for catch-up buying. If cloud capital spending slows, customers expand their internally developed chips, or GPU supply and demand rebalance more quickly, the underweight may simply prove to be the result of prudent concentration management.
Why Capital Is Crowding into Storage and Equipment
The companies with the strongest incremental positioning changes in 2Q26 were almost all exposed to supply bottlenecks in AI infrastructure. KLA’s relative positioning improved by 102 basis points, Seagate Technology’s by 52 basis points, and Western Digital’s by 48 basis points; Lam Research, Applied Materials, and Micron Technology were also overweight. By contrast, Advanced Micro Devices (AMD) deteriorated by 26 basis points, Intuit by 22 basis points, Intel by 20 basis points, Google by 19 basis points, and Nvidia by 14 basis points.
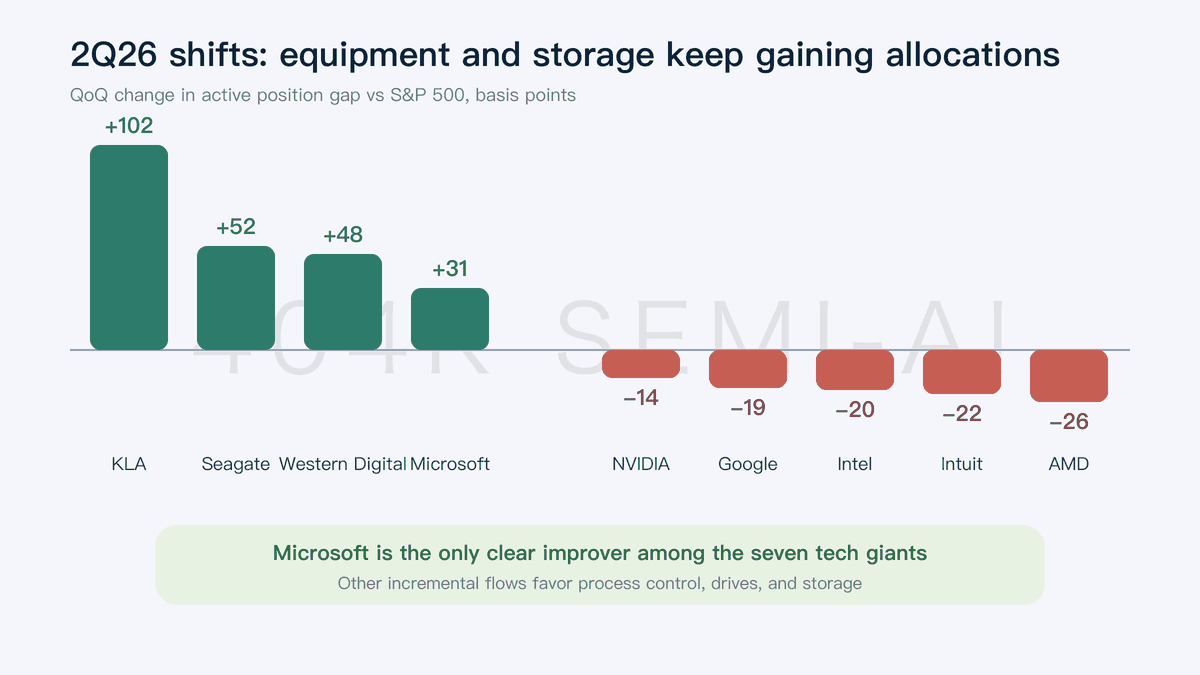
This ranking reflects differences in the certainty of AI capital-spending returns in 2026. Cloud platforms and software companies must demonstrate that enormous compute investments can translate into revenue and profit. Memory, hard-drive, and semiconductor-equipment companies see orders, pricing, and utilization rates earlier. HBM increases wafer consumption; enterprise SSDs and high-capacity hard drives support training, inference, and cold data; and rising complexity in advanced logic and DRAM increases process-control and etch intensity. As long as capital spending continues to expand, these companies gain revenue visibility first.
KLA’s 102-basis-point improvement is particularly noteworthy because its thesis does not depend on a single increase in memory pricing. Instead, greater process complexity drives demand for inspection and metrology. Larger advanced-logic die sizes, HBM stacking, and more complex DRAM processes all increase defect-inspection intensity, giving KLA exposure to both logic and memory capital spending. The cases for Seagate Technology and Western Digital are more direct: AI-generated data increases demand for nearline hard-drive capacity, while disciplined industry supply makes capacity growth more likely to translate into pricing and profits. Rising allocations to both groups indicate that institutions are simultaneously betting on “more data” and “more process steps required to manufacture the infrastructure that handles that data.”
Advanced Micro Devices’ 26-basis-point deterioration provides a counterexample. AMD is also an AI beneficiary, but the market now requires GPU products such as MI450 to prove their performance, software ecosystems, and breadth of customer adoption. At the same time, the report assumes substantial data-center revenue growth, while inventory is also increasing rapidly. When the earnings case depends on several demanding assumptions holding simultaneously, institutions may be reluctant to add further risk beyond benchmark weights. Active managers are therefore selecting not for an AI label, but for the sequencing of revenue realization and the cost of failure.
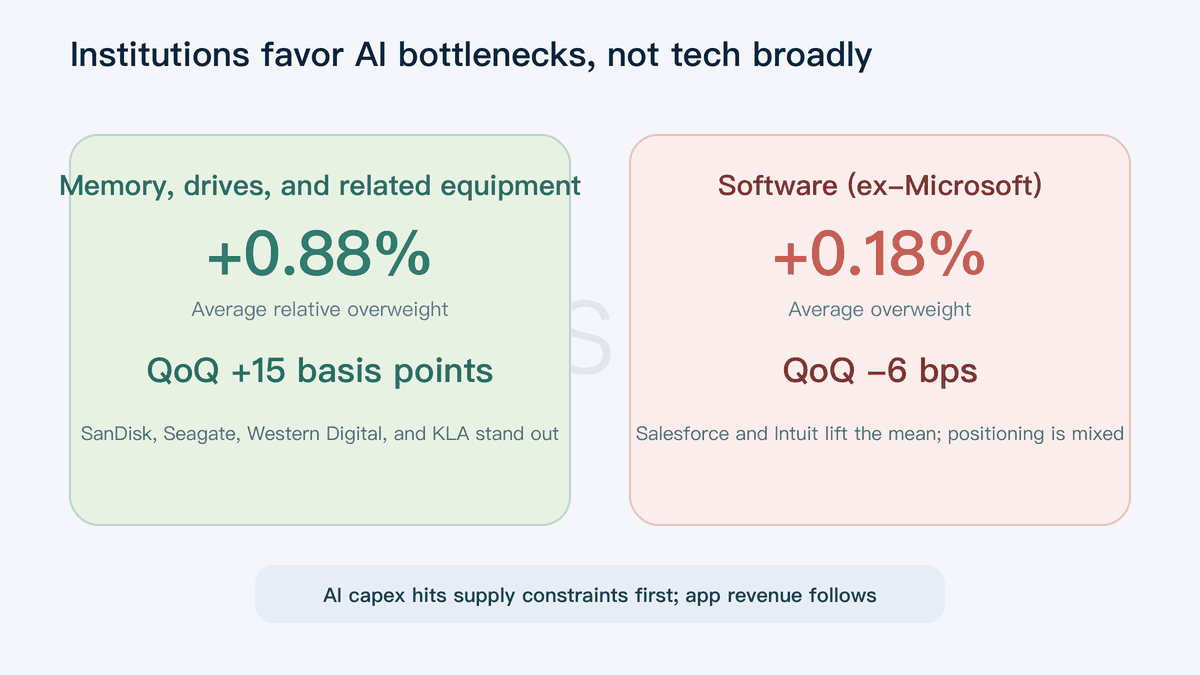
The report calculates an average overweight of 0.88% for memory, hard-drive, and related-equipment companies, up 15 basis points quarter on quarter. Software excluding Microsoft was overweight by only 0.18% on average, down 6 basis points. Even that figure overstates the software consensus because Salesforce’s 0.56% overweight and Intuit’s 0.23% overweight lift the average; Oracle was overweight by 0.02%, Palo Alto Networks by 0.05%, while IBM was underweight by 0.05%. Institutions are not abandoning software altogether. They are waiting for AI to move from usage, seat counts, and feature demonstrations to measurable incremental revenue.
Classification discipline is also essential. KLA, Lam Research, and Applied Materials are semiconductor-equipment companies, not memory producers; they benefit from process complexity, process-control intensity, and wafer-fabrication-equipment spending. Grouping them with SanDisk, Seagate Technology, Western Digital, and Micron Technology is valid only under the broader label of “the storage value chain and related equipment,” not as a generic memory-demand category. Their positioning moves in the same direction, but their earnings drivers are different.
Premium Positioning Is Both the Core Earnings Thesis and a Crowded Trade
SanDisk presents the clearest contradiction. After relisting in Q1 2025 and gaining benchmark weight following its inclusion in the S&P; 500 in Q4 2025, active portfolios remained 2.30% overweight—about 1.5 times KLA’s second-place overweight. The report argues that cloud demand, enterprise SSDs, and limited new capacity have raised normalized NAND profitability. Yet its $1,750 reference price is only 6.6% above the cited share price. The most crowded position offers the least price upside, suggesting that much of the good news is already priced in.
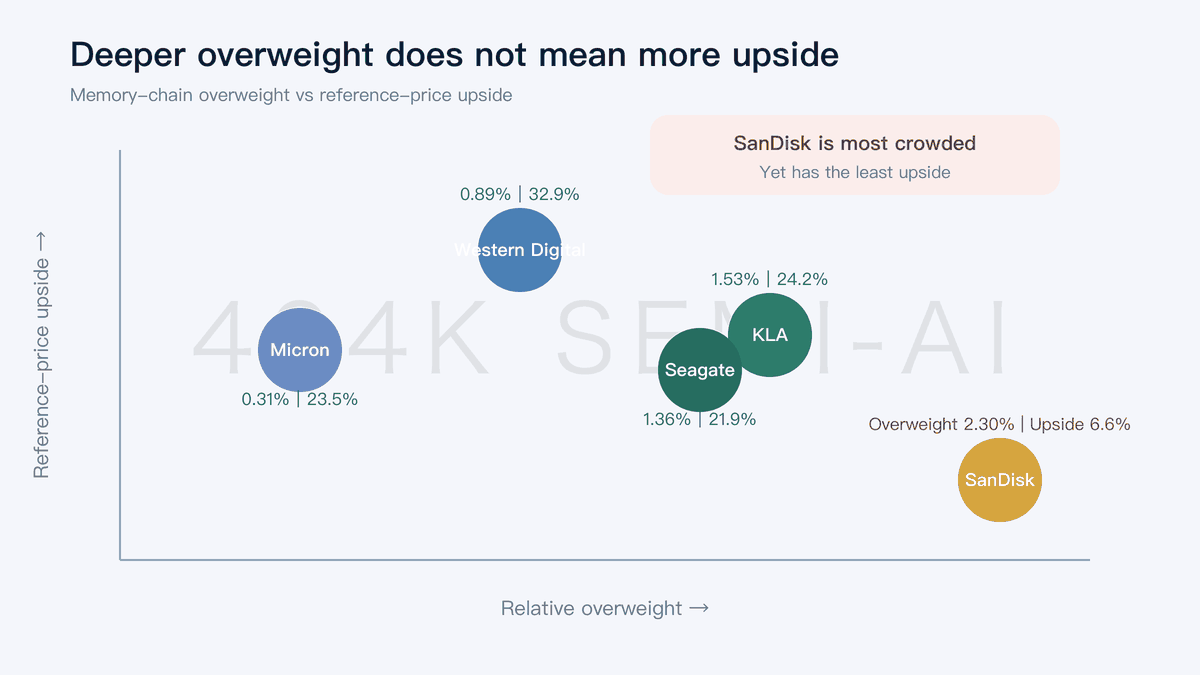
Western Digital is 0.89% overweight with approximately 32.9% reference-price upside; Seagate Technology is 1.36% overweight with approximately 21.9% upside; Micron Technology is 0.31% overweight with approximately 23.5% upside; and KLA is 1.53% overweight with approximately 24.2% upside. These figures are not directly comparable because the valuation methods and fiscal years differ, but they reveal distinct risk-reward profiles within the same AI-infrastructure theme. SanDisk has the strongest positioning signal but the smallest price cushion, while Western Digital and Micron are less extremely positioned and offer greater cyclical leverage in their earnings assumptions.
The deeper risk lies in the shape of the forecasts. Operating projections for Micron Technology, Western Digital, Seagate Technology, and SanDisk all show profits surging around 2027 before growth moderates or earnings decline. This is not conventional, steady compounding. Rather, AI is raising the storage cycle’s peak and extending its duration. If supply discipline persists in HBM, enterprise SSDs, and high-capacity hard drives, earnings can absorb the overweight positioning. If customer restocking ends, the industry resumes capacity expansion, or prices fall faster, crowded positions will amplify multiple compression.
The four companies also cannot be assessed against the same cyclical yardstick. Micron Technology’s thesis centers on its DRAM, HBM, and NAND product mix, with earnings sensitive to pricing, yields, and high-end market share. SanDisk is more concentrated in NAND and enterprise SSDs, and its valuation depends on cloud demand and free-cash-flow conversion. Seagate Technology and Western Digital are driven primarily by high-capacity hard drives, capacity per drive, HAMR or UltraSMR qualification, and industry supply discipline. All benefit from higher unit pricing and richer product mix, but they differ in technology qualification, customer concentration, and the speed of capacity responses. Only by separating these variables can investors determine whether an overweight reflects rational pricing of a structural profit pool or double-counting of a cyclical peak.
The equipment companies follow a somewhat different logic. KLA’s gross margin is projected to remain broadly stable above 62%, with growth driven more by rising inspection intensity as advanced logic, HBM, and DRAM processes become more complex than by pricing alone. Lam Research depends on NAND and logic equipment spending, while Applied Materials benefits from DRAM and architectural shifts such as GAA and backside power delivery. These companies are also exposed to capital-spending cycles, but additional process steps and market-share gains may provide more durable structural support. An overweight is therefore not inherently dangerous; the risk arises when crowded positioning, peaking earnings expectations, and a lack of price cushion coincide.
Mega-Cap Underweights Do Not Imply Rejection of the Fundamentals
Viewing portfolio gaps alongside the company risk-reward appendix yields a more useful conclusion: an institutional underweight can coexist with a positive analyst view because the two answer different questions. The positioning gap asks how far active funds remain below the benchmark, while the company model asks whether future earnings support the current share price.
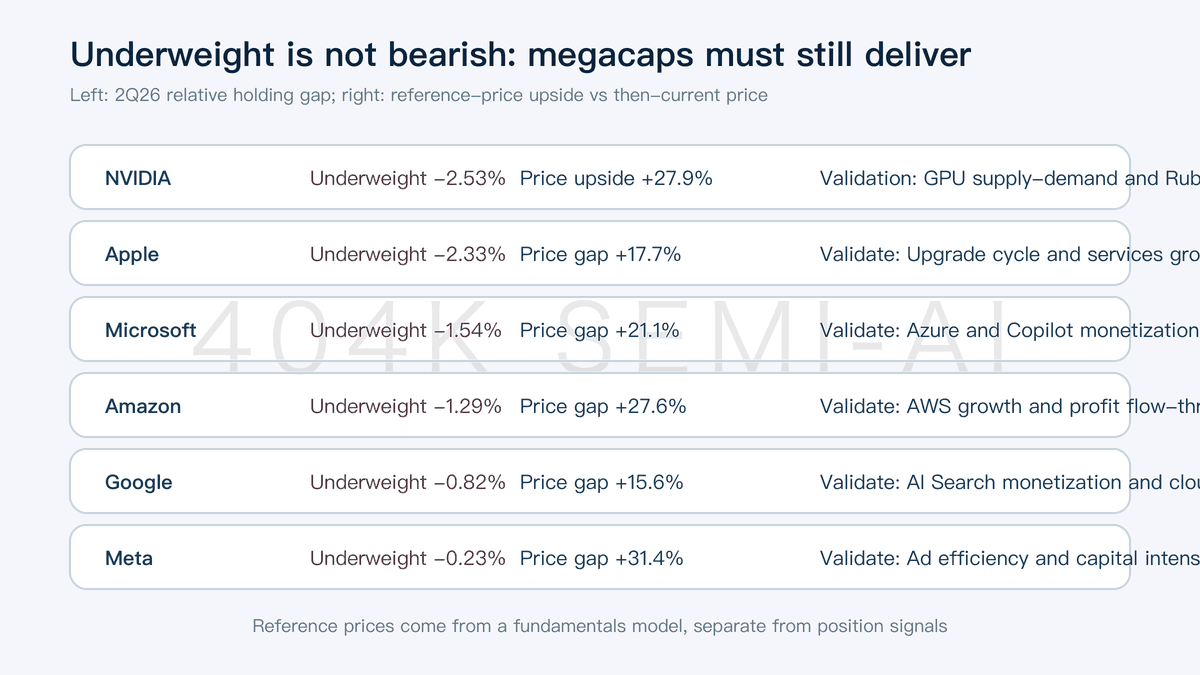
For Nvidia, the key validation points are Blackwell, Rubin, GPU supply and demand, and the durability of cloud capital expenditure. For Microsoft, they are Azure growth, premium Microsoft 365 offerings, and paid Copilot adoption. Amazon must demonstrate that AWS revenue growth can translate into profit. Google must show that AI search can increase engagement without materially impairing monetization, while also unlocking cloud profitability. Meta needs to prove that AI-driven advertising efficiency can offset the capital intensity of its data centers. Apple’s thesis differs from those of the cloud platforms and depends mainly on two consecutive years of iPhone replacement demand, services growth, and pricing power.
Morgan Stanley’s reference-price upside also shows that institutional underweights do not necessarily reflect a negative research view: approximately 27.9% for Nvidia, 21.1% for Microsoft, 27.6% for Amazon, 15.6% for Google, 31.4% for Meta, and 17.7% for Apple. These potential gains, however, rest on demanding earnings assumptions. The Amazon model projects AWS growth of 37.4% in 2026 and 40.8% in 2027; the Apple model projects iPhone revenue growth of 20.7% and 18.9%, respectively; and the Meta model assumes approximately 27% advertising revenue growth in 2026. If any one of these assumptions fails, underweight positioning will not automatically translate into a catch-up trade.
The common challenge for mega-cap companies is that revenue growth and capital intensity no longer move in tandem. Nvidia sells GPUs and systems to customers, which bear most of the capital expenditure. Microsoft, Amazon, Google, and Meta, by contrast, must first build data centers, purchase GPUs, and invest more in power and networking before waiting for cloud revenue, advertising efficiency, or subscription monetization. Even if revenue meets expectations, depreciation, energy costs, and infrastructure operations could depress free cash flow. Active funds are therefore asking two questions at once: how much incremental revenue AI will generate, and how much capital must be committed to capture it. The former drives the growth narrative; the latter determines the market multiple.
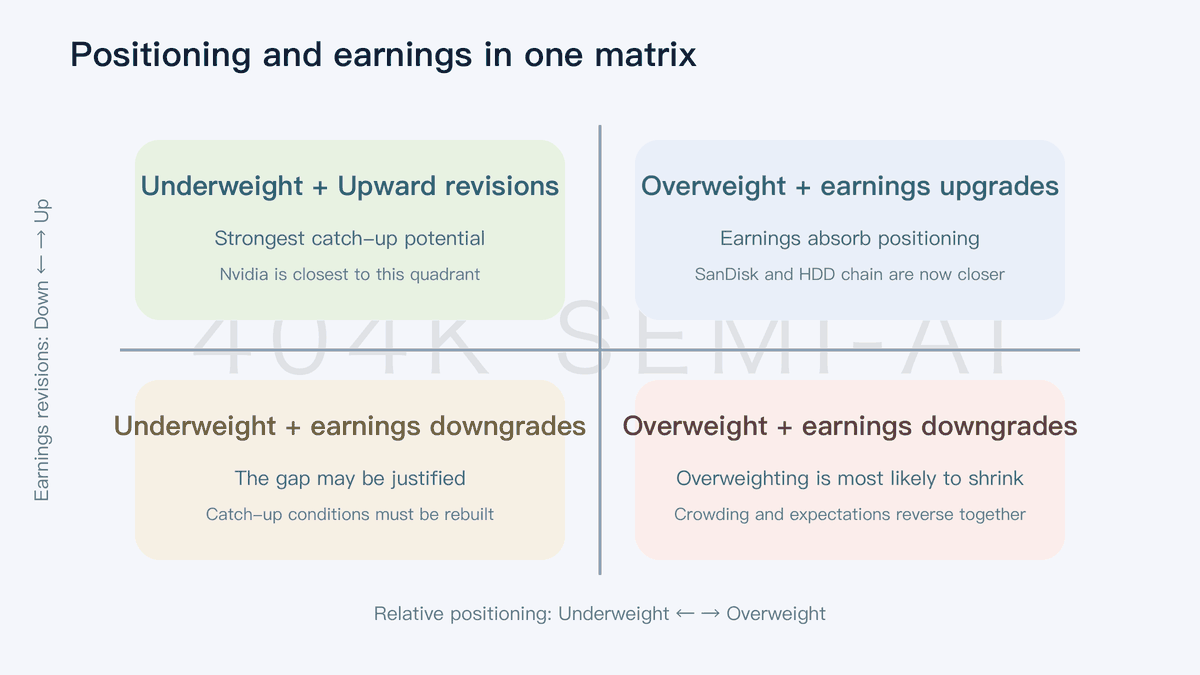
Combining positioning with earnings revisions produces four regimes. An underweight with upward earnings revisions offers the clearest scope for catch-up. An underweight with downward revisions may be justified. An overweight with continued upward revisions can be absorbed by performance. An overweight accompanied by downward revisions is most vulnerable to rapid position compression. Nvidia currently looks closer to the first regime, while SanDisk and the hard-drive companies fall into the third. Both still require confirmation from the next quarter’s data; a single quarterly snapshot should not be treated as a permanent label.
Potential conflicts of interest must also be considered. Page 60 of the report discloses that Morgan Stanley acted as financial adviser on Google’s acquisition of Wiz, with part of its fee contingent on completion of the transaction. Subsequent disclosures also list equity holdings, investment-banking relationships, and other business ties between the research firm and numerous covered companies. This does not mean the analysis is necessarily distorted, but it does underscore that reference prices and research views are only inputs; they cannot confer “certainty” on positioning signals.
Software Positioning Is Soft; What Is Really Missing Is Proof of Revenue
Excluding Microsoft, software remains modestly overweight rather than outright underweight. The issue is that marginal positioning has declined and the overweight is concentrated in only a few companies. Adobe is 0.09% overweight, ServiceNow 0.15%, Palo Alto Networks 0.05%, and Oracle 0.02%—all far below the overweights at both ends of the storage supply chain. Institutions clearly acknowledge that these companies retain moats in distribution, data, and workflows, but they have not expanded risk budgets as aggressively as they have in pursuit of constrained memory supply.
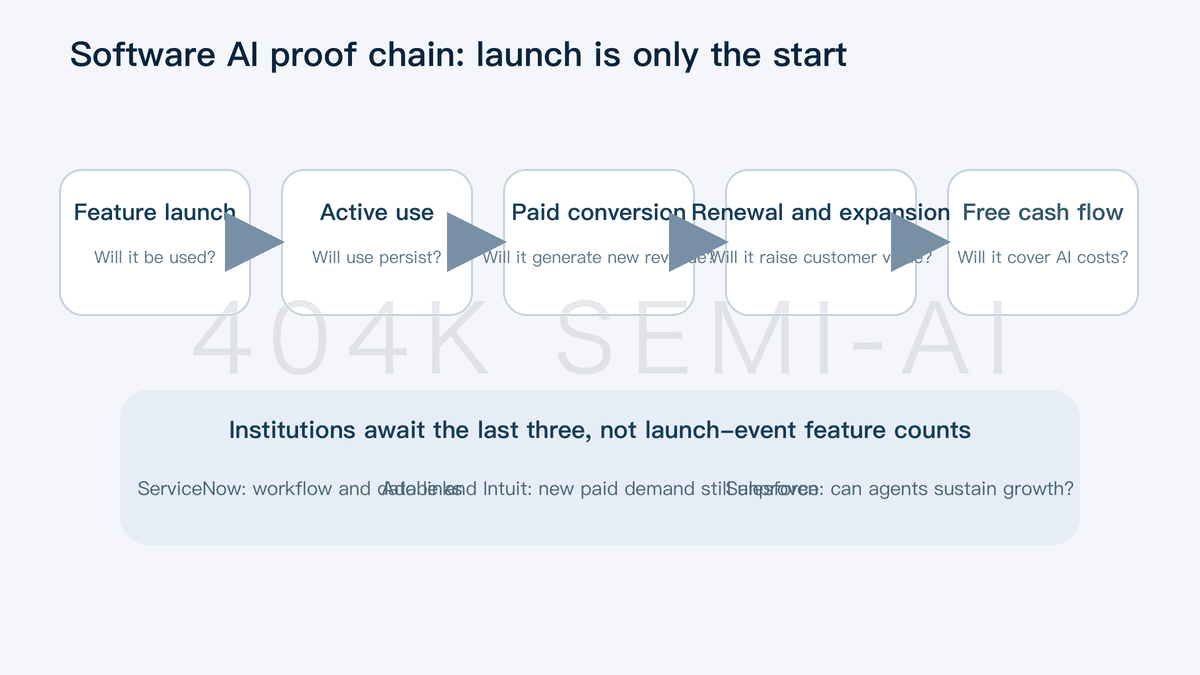
The reason is that AI’s economic impact on software remains unsettled. Adobe must prove that freemium traffic can convert into paying users rather than being diverted to AI-native tools. Intuit must show that AI can drive enterprise suites, assisted tax preparation, and high-value services rather than merely increasing costs. Salesforce must use Agentforce and Data Cloud to stabilize revenue growth. ServiceNow must translate its advantages in agent orchestration, workflows, and systems integration into approximately 20% growth in subscriptions and free cash flow. Software supply can expand almost instantly; the constraint is not capacity, but customers’ willingness to keep paying.
Oracle is the clearest crossover case. The report assigns it a $207 reference price, more than 41% above the cited share price, yet retains a Neutral view because GPU-cloud expansion brings financing obligations, margin pressure, and exceptionally high execution risk. In the model, total revenue growth rises to 38.7% while the operating margin falls to 38.5%. Rapid growth in AI-infrastructure revenue does not automatically translate into high-quality shareholder earnings. This is precisely why institutions remain restrained on software and cloud platforms.
Another challenge for software AI is revenue substitution. Generative AI may support higher prices and new modules, but it could also reduce seat counts, compress professional services, or allow customers to accomplish the same work with fewer employees. Usage-based pricing can increase revenue elasticity, but it also makes customer budgets less predictable. Institutions therefore prefer to see net-new revenue, renewal rates, and free-cash-flow margins improve together rather than overweighting a company in advance based on the number of features announced at product launches. ServiceNow receives comparatively greater recognition because its workflows, data connectivity, and enterprise distribution provide a clearer path to monetization. Adobe, Intuit, and Salesforce still need to prove that AI is not merely cannibalizing their existing products.
Where These Positioning Signals Are Most Likely to Mislead
First, 13F filings are lagging snapshots. Quarter-end positions are disclosed only after the quarter closes, and this report was published on August 17. Any earnings releases, share-price moves, or portfolio adjustments during that interval are absent from the data. Nor do 13F filings fully capture short positions, many derivatives, overseas securities, or intra-quarter trading. A “2.53% underweight” therefore should not be characterized as a real-time net short.
Second, relative weights conflate market-price effects with active decisions. If a company’s shares rally sharply and its S&P; 500 weight rises, the underweight can widen even if institutions leave their absolute holdings unchanged; if the stock underperforms, the underweight may narrow mechanically. Determining whether portfolio managers have genuinely changed their views requires separating absolute holdings, benchmark weights, and share-price effects. The report’s quarter-over-quarter changes are useful for identifying anomalies, but insufficient on their own to reconstruct fund flows.
Third, the sample is the average portfolio of the 100 largest active managers. An average can obscure wide differences across strategies and does not reveal whether the distribution is dominated by a handful of very large funds. The appendix’s “share of active institutional owners” is a separate metric: it measures the proportion of institutional holders that are actively managed and cannot substitute for the weighting gap relative to the S&P; 500.
Fourth, the historical statistical relationship is not fully disclosed. The report states that low ownership is significantly associated with future returns after controlling for market capitalization and earnings surprises, but provides no coefficients, out-of-sample stability analysis, or cost assumptions. Market structure has changed since 2009, and index concentration in the Magnificent Seven is far higher than in the earlier years. Historical efficacy does not imply equal predictive strength under today’s concentration levels.
The correct approach, therefore, is not to draw contrarian conclusions from the rankings alone. Extreme underweights should be viewed as potential catch-up demand, while extreme overweights imply a higher earnings hurdle; financial results and industry data must then determine which side is more likely to deliver. Positioning reveals where expectations are concentrated, but it cannot replace analysis of revenue, profit, cash flow, and market pricing.
Which Numbers Could Change the View in the Next Round
The next step is not to wait for share prices to validate the thesis, but for the evidence chain to update. If third-quarter underweights in mega-caps such as NVIDIA, Microsoft, and Amazon begin to narrow while cloud capital spending and earnings forecasts continue to rise, active managers are catching up with fundamentals. If underweights keep widening as earnings estimates decline, technical support will weaken. For the memory value chain, the durability of overweights will depend on HBM and NAND pricing, enterprise SSD demand, HDD capacity growth, HAMR qualification, and the resilience of wafer-fab equipment orders.
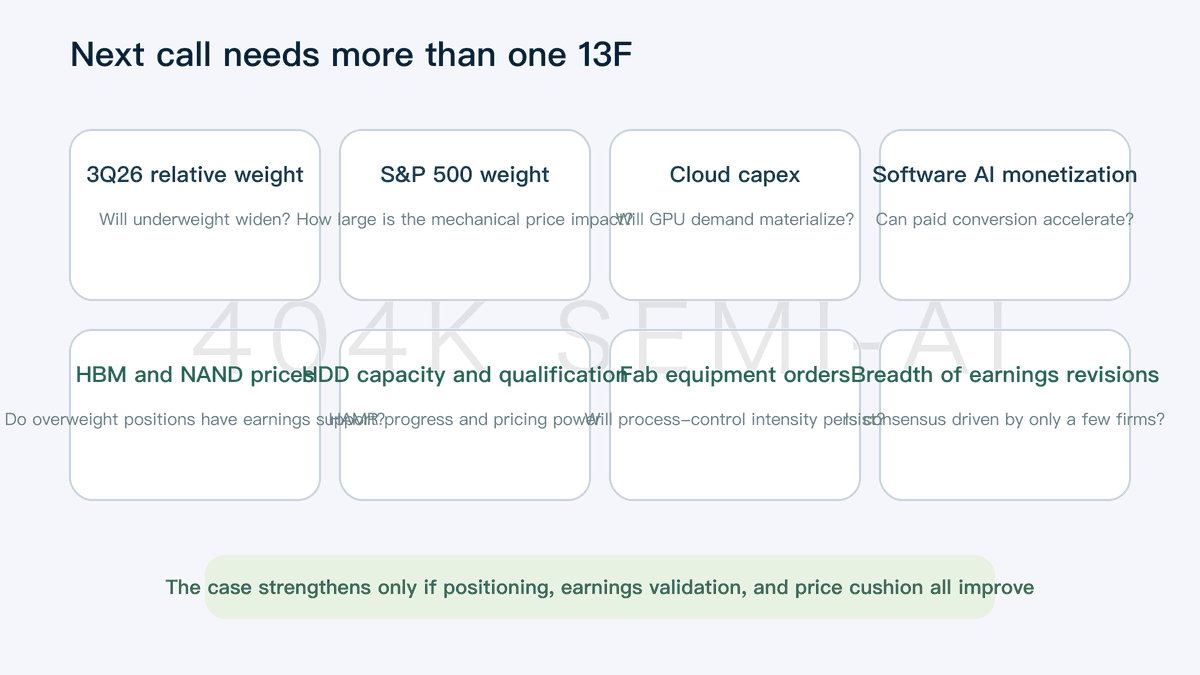
In software, paid conversion matters more than the number of product launches: how much incremental revenue, remaining performance obligations, and free cash flow are actually generated by Copilot, Agentforce, Now Assist, Adobe AI features, and Oracle’s GPU cloud? If software AI revenue begins growing faster than compute costs, currently weak positioning could become a new source of catch-up demand. If AI continues to manifest primarily as capital expenditure and depreciation, capital will remain concentrated in supply bottlenecks.
The report ultimately identifies not a simple rotation, but the order in which the AI value chain is being priced: active managers are paying first for scarce supply, process control, and storage capacity, while waiting for mega-cap platforms and software companies to demonstrate returns on investment. NVIDIA’s 2.53% underweight and Sandisk’s 2.30% overweight mark the two extremes of this sequence. The eventual winners will not be those ranking highest in portfolio weights, but those able to sustain earnings growth above the expectations already embedded in prices and positioning.