
目录
Table of Contents
I. Q2 Re-steepens the Growth Trajectory
II. Data Center Drives Virtually All Incremental Growth
III. How Custom Silicon and High-Speed Interconnects Flow into Revenue
IV. Operating Expense Leverage Drives Margin Expansion
V. Cash Flow Has Yet to Match Profit Acceleration
VI. SBC, Dilution, and Post-M&A Balance Sheet Structure
VII. Key Valuation Drivers and Monitoring Framework for Marvell
本内容基于公开资料和研报数据整理,不构成任何投资建议,不代表任何个人观点,仅供学习参考,请理性阅读
Marvell Technology delivered accelerating Q2 revenue alongside strong Q3 guidance, with Data Center expanding to 79% of total sales. While top-line growth is visibly materializing, gross margin trajectory, cash conversion, and equity compensation costs will dictate the true earnings quality of this expansion.
Table of Contents
[I. Q2 Re-steepens the Growth Trajectory](#i-q2-re-steepens-the-growth-trajectory)
[II. Data Center Drives Virtually All Incremental Growth](#ii-data-center-drives-virtually-all-incremental-growth)
[III. How Custom Silicon and High-Speed Interconnects Flow into Revenue](#iii-how-custom-silicon-and-high-speed-interconnects-flow-into-revenue)
[IV. Margin Expansion Driven Primarily by Operating Leverage](#iv-margin-expansion-driven-primarily-by-operating-leverage)
[V. Cash Flow Lags Earnings Acceleration for Now](#v-cash-flow-lags-earnings-acceleration-for-now)
[VI. SBC, Dilution, and the Post-Acquisition Balance Sheet](#vi-sbc-dilution-and-the-post-acquisition-balance-sheet)
[VII. Valuation Framework: What Metrics Should Price Marvell Next?](#vii-valuation-framework-what-metrics-should-price-marvell-next)
I. Q2 Re-steepens the Growth Trajectory
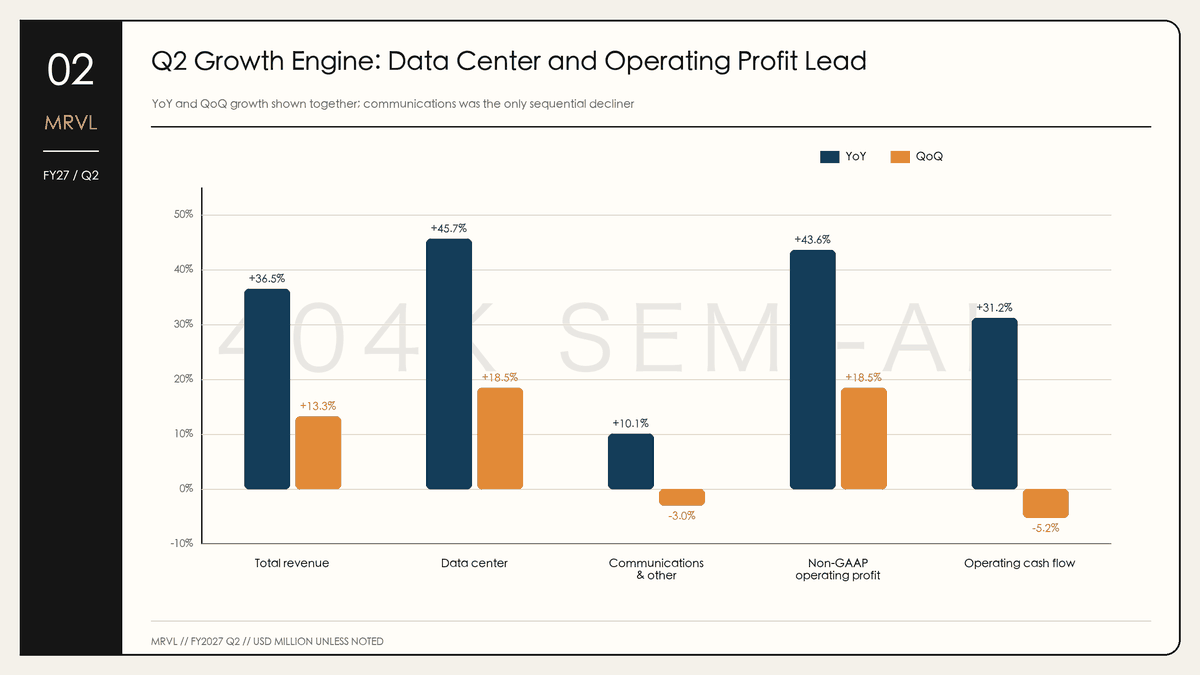
In Q2 FY2027, Marvell Technology (NASDAQ: MRVL) generated revenue of $2.7393 billion, up 36.5% YoY and 13.3% QoQ, coming in approximately $39 million above the midpoint of prior guidance. While the magnitude of the beat itself was modest, the critical takeaway is that growth is not slowing down even against a rising baseline. Following double-digit sequential growth in Q2, management guided Q3 revenue to a midpoint of $3.15 billion, implying an additional 15.0% QoQ increase. If achieved at the midpoint, revenue will have surged from approximately $2.417 billion in Q1 to $3.15 billion in Q3, adding nearly $733 million in incremental quarterly revenue over just six months.
Q2 non-GAAP operating profit reached $1.0032 billion, up 43.6% YoY and 18.5% QoQ, yielding non-GAAP EPS of $0.94. Operating profit outgrew revenue on both a YoY and QoQ basis, demonstrating clear operating leverage as volume growth diluted operating expense ratios. On a GAAP basis, operating profit was $459.7 million with an operating margin of 16.8%, and EPS stood at $0.33. While both GAAP and non-GAAP metrics improved, their trajectories and underlying drivers diverge substantially, as detailed later in this report.
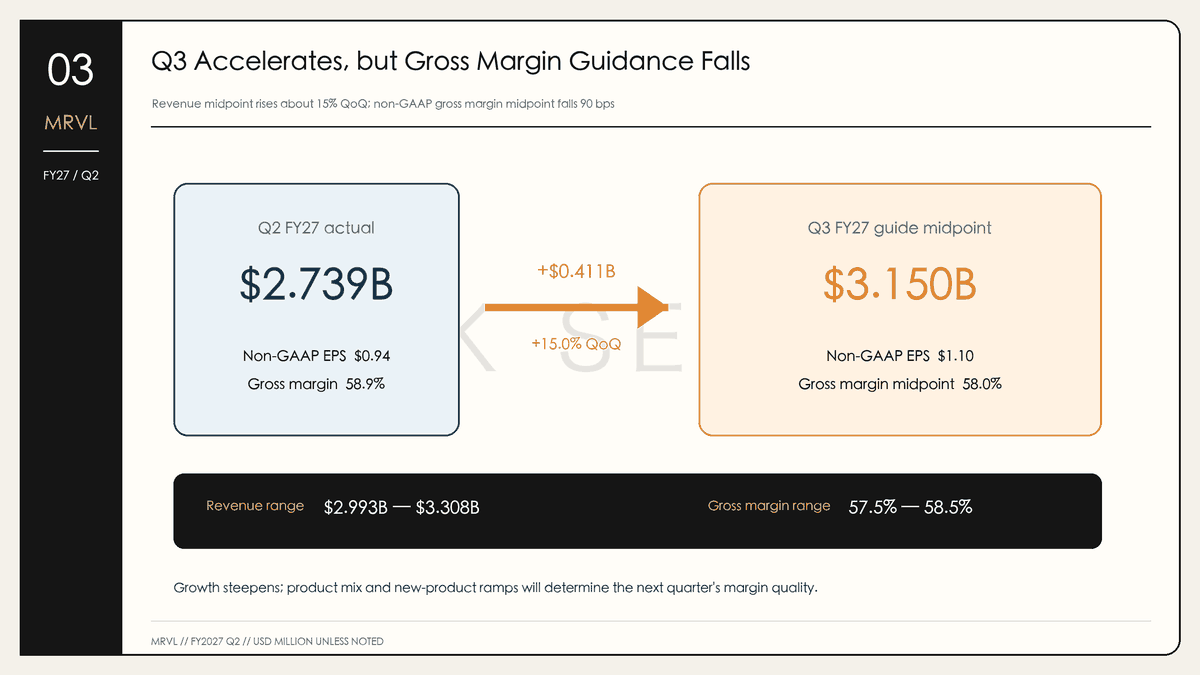
The Q3 guidance elevates this print from a solid single quarter to an inflection point of accelerating multi-quarter expansion. Revenue is guided to $2.9925B–$3.3075B (midpoint $3.15B), with non-GAAP EPS guided to a midpoint of $1.10, representing approximately 17% sequential growth over Q2. Consequently, market focus will shift from whether Q2 beat expectations to whether Marvell can defend its earnings quality as top-line growth ramps sharply in Q3.
However, one critical set of margin figures warrants close scrutiny. Q2 non-GAAP gross margin came in at 58.9%, flat QoQ but down approximately 0.5 percentage points YoY. For Q3, non-GAAP gross margin guidance is set at 57.5%–58.5% (midpoint 58.0%), down roughly 0.9 percentage points from Q2. Accelerating revenue growth coupled with declining gross margin guidance typically signals shifts in product mix, customer mix, or early-stage ramp costs. While focusing solely on EPS creates an impression of broad-based operational acceleration, incorporating gross margin dynamics calls for a more measured conclusion: revenue visibility has strengthened, but unit profitability remains to be proven through volume production.
Management also noted that AI-related bookings were "exceptionally strong," revenue growth is expected to accelerate over the remainder of the fiscal year, and full-year revenue outlooks for both FY2027 and FY2028 were revised upward. However, the disclosures did not provide specific full-year revenue figures before and after the revisions. As such, while the directional improvement is confirmed, qualitative commentary should not be conflated with undisclosed annual growth rates or specific valuation targets.
II. Data Center Drives Virtually All Incremental Growth
Q2 Data Center revenue reached $2.1715 billion, up 45.7% YoY and 18.5% QoQ, representing 79% of total revenue—up from ~76% in the prior quarter and ~74% in the year-ago period. Notably, the sequential increase in Data Center revenue exceeded the company's total sequential top-line gain, as Communications and Other revenue totaled $567.8 million—up 10.1% YoY but down 3.0% QoQ. In other words, Data Center drove virtually 100% of sequential growth in Q2, while non-data-center segments acted as a minor drag.
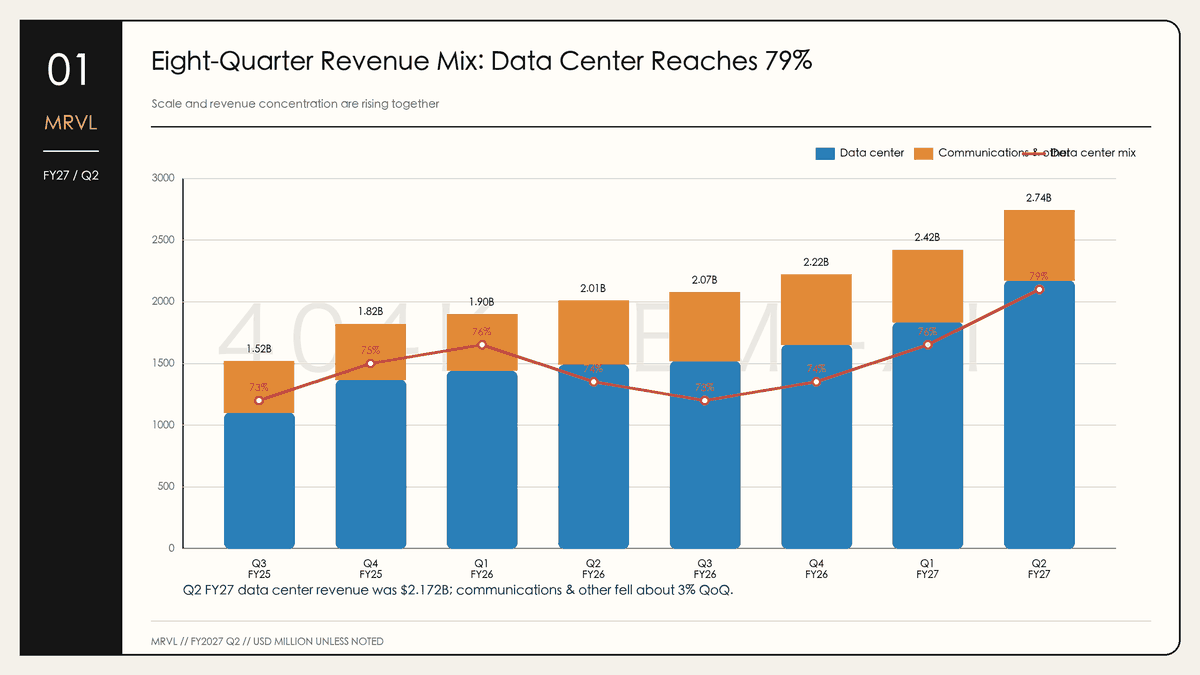
An eight-quarter historical view illustrates a structural transformation in Marvell’s revenue mix. Total revenue expanded from approximately $1.516 billion in Q3 FY2025 to $2.739 billion this quarter, with Data Center revenue surging from ~$1.101 billion to $2.172 billion. Over the same timeframe, Communications and Other revenue hovered between $400 million and $600 million. The upward shift in the company’s revenue baseline has been driven almost exclusively by Data Center, lifting its revenue contribution from the low-70% range to nearly 80%.
This structural shift carries two major implications. First, Marvell has transitioned from a diversified multi-market semiconductor supplier into a pure-play vector on hyperscale data center capex. As cloud hyperscalers scale AI clusters, demand across high-speed interconnects, switching, electro-optics, and custom compute magnifies the company's operating leverage and revenue elasticity. Second, revenue concentration is rising. If ramp schedules for major custom programs slip or a single key customer adjusts procurement, non-data-center segments lack the scale to cushion the resulting volatility.
A 79% Data Center revenue share should not be conflated with 79% pure AI exposure. Marvell’s reported Data Center segment encompasses general compute, standard connectivity, and storage workloads beyond AI training clusters. Furthermore, management did not provide a granular breakdown of AI revenue, custom ASIC revenue, customer concentration, or specific product lines. Treating the entire Data Center segment as AI would overstate verifiable AI exposure while obscuring traditional enterprise and cloud data center dynamics.
Current disclosures support the conclusion that AI has become the primary catalyst behind Data Center acceleration, as substantiated by Q2 results and Q3 guidance. However, investors still cannot quantitatively isolate the respective contributions of AI interconnects, custom ASICs, and traditional data center products. The top-line acceleration is real, but revenue attribution remains coarse.
III. How Custom Silicon and High-Speed Interconnects Flow into Revenue
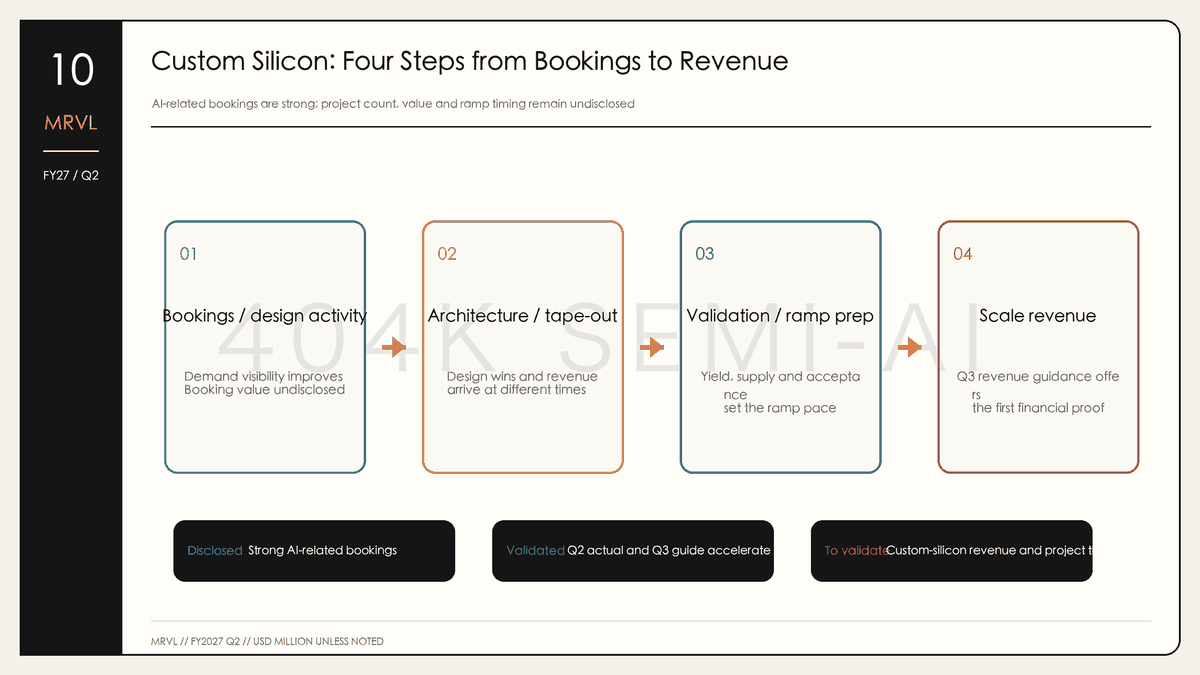
Management characterized the two AI growth vectors as being at distinct developmental stages. Data center connectivity remains robust today, indicating that high-speed optical and copper interconnects already contributed meaningfully to Q2 revenue. In contrast, the custom silicon (ASIC) business is expected to "accelerate significantly" in the second half of FY2027, with the bulk of its volume ramp slated for future quarters. This distinction is critical: connectivity delivers immediate near-term growth, while custom silicon is positioned to extend the duration of the cycle.
The lifecycle of custom silicon—from design win to revenue recognition—involves co-architecture, tape-out, silicon validation, manufacturing ramp preparation, and customer deployment. Strong early bookings or design activity do not immediately translate into concurrent quarterly revenue. While management’s emphasis on robust AI bookings provides a positive demand signal, the guided 15% sequential revenue growth in Q3 provides initial financial validation of booking-to-revenue conversion. Continued monitoring will be required around ramp timing, silicon yields, supply chain assurance, and customer acceptance milestones.
The thesis for high-speed interconnects is more direct. As AI clusters expand in scale, east-west and north-south data traffic between compute engines, racks, and datacenters surges exponentially. Because bandwidth, latency, power consumption, and reach dictate overall system efficiency, interconnects have evolved from auxiliary components into the primary physical bottleneck of computing architectures. Marvell’s revenue opportunity across electro-optics, PAM4 DSPs, switching, and custom interconnect solutions is driven by a dual multiplier: higher port density per accelerator and continuous port-speed upgrades.
However, top-line acceleration and gross margin compression may stem from the exact same dynamic. When large custom programs transition to high-volume manufacturing, segment revenue scales rapidly, but early yield curves, hyperscaler pricing terms, and product mix can dilute corporate average gross margins. A shifting mix between merchant connectivity products and custom silicon can create a divergence between revenue growth and gross margins. The sequential dip in Q3 gross margin guidance likely offers an early indicator of this production mix shift. Without a granular gross margin bridge from management, this remains a working thesis to monitor.
This growth trajectory faces four key constraints: first, heightened customer concentration amplifies the revenue impact of individual project schedules; second, hyperscalers developing internal chip design capabilities require suppliers to continuously defend their performance moat and execution value; third, packaging capacity, advanced node availability, and component supply may constrain ramp velocity; and fourth, export controls and trade policy shifts could alter the serviceable addressable market (SAM). While none of these factors necessarily derails the multi-year secular trend, any one of them could introduce quarterly lumpiness and deviation from a linear growth path.
Management has positioned its October 6, 2026 Investor Day as the next major communication milestone. The most valuable incremental data points will be custom silicon program counts and ramp schedules, connectivity product mix, customer concentration, and a quantitative revenue bridge for FY2027–FY2028. Absent granular disclosure, market consensus ranges for out-year earnings power will remain wide.
IV. Operating Expense Leverage Drives Margin Expansion
In Q2, non-GAAP gross margin was flat sequentially at 58.9%, while non-GAAP operating margin rose to 36.6%. The divergence stems from operating expenses growing more slowly than revenue. Non-GAAP OpEx came in at $610.8 million, up 24.0% YoY and 5.9% QoQ, notably lagging revenue growth of 36.5% YoY and 13.3% QoQ. As scale expanded, R&D; and SG&A; expenses were diluted across a larger revenue base, unlocking clear operating leverage.
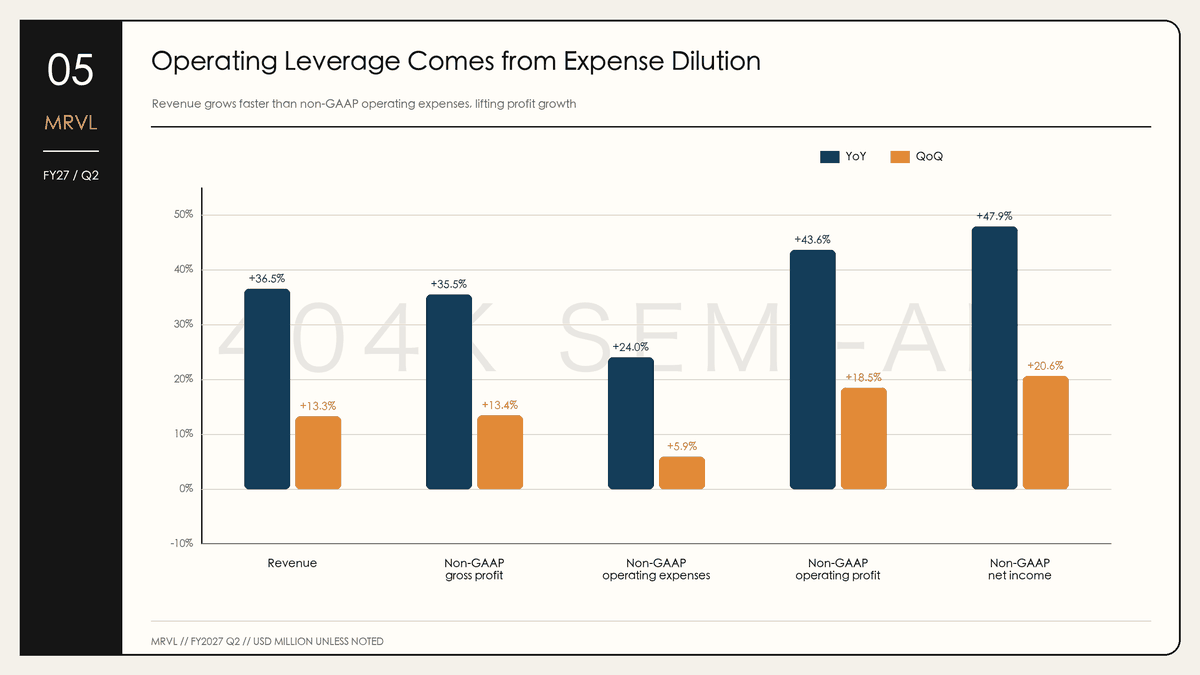
This margin improvement carries genuine economic value. For semiconductor companies, substantial R&D; investments in design platforms and customer engagements are incurred upfront, well ahead of revenue recognition. Consequently, as mass-production programs ramp concurrently, incremental revenue does not require a proportional increase in period OpEx. In Q2, non-GAAP operating profit grew 43.6% YoY and 18.5% QoQ—both outpacing top-line growth—demonstrating this operating leverage model in action.
However, operating leverage cannot fully neutralize gross margin risks. While the midpoint of Q3 revenue guidance implies an increase of approximately $411 million QoQ, the midpoint for non-GAAP gross margin dips to 58.0%. On a static calculation, a 90 bps margin contraction offsets a portion of the incremental gross profit from top-line expansion. While Marvell could still deliver EPS growth via continued OpEx ratio reductions, this earnings structure becomes more sensitive to top-line scale and increasingly reliant on Q3 revenue landing near or above the midpoint.
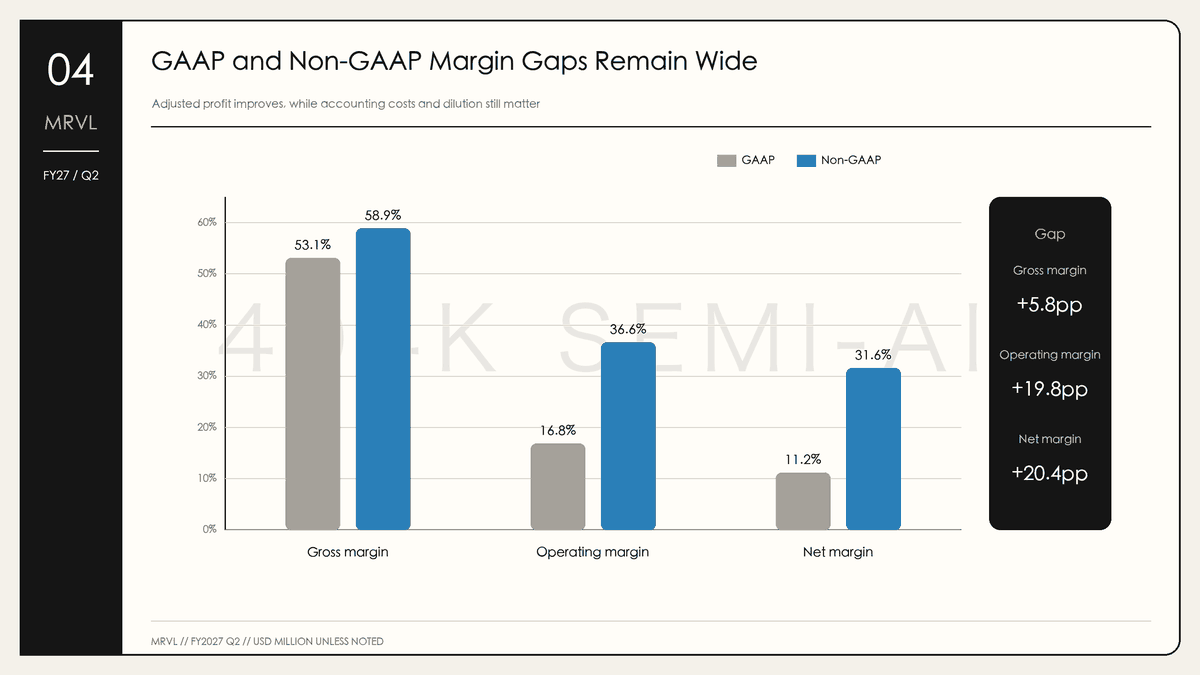
The substantial divergence between GAAP and non-GAAP metrics also warrants scrutiny. In Q2, GAAP gross margin was 53.1% (5.8 percentage points below non-GAAP), GAAP operating margin was 16.8% (19.8 percentage points lower), and GAAP net margin was ~11.2% (~20.4 percentage points lower). These variances primarily reflect stock-based compensation (SBC), intangible asset amortization, and acquisition-related integration costs. While non-GAAP figures highlight underlying operational momentum, GAAP metrics reflect the full accounting burden borne by shareholders.
Consequently, Marvell's Q2 income statement reveals a three-tiered dynamic: top-line revenue is accelerating; adjusted operating income is expanding even faster thanks to economies of scale; and GAAP profitability remains depressed by SBC and M&A-related; charges. As long as top-line growth remains elevated, both profit tiers can improve. However, should revenue growth decelerate, the buffer from OpEx leverage will diminish, and the wide GAAP/non-GAAP gap will re-emerge as a source of valuation discount.
V. Cash Flow Has Yet to Match Profit Acceleration
Q2 operating cash flow was $605.5 million, up 31.2% YoY but down 5.2% QoQ. With capital expenditures at $126.7 million, the analytical proxy for free cash flow (operating cash flow less CapEx) stood at approximately $478.8 million, up 15.6% YoY but down 0.9% QoQ. Note that this FCF proxy is calculated for analytical clarity and is not a management-defined metric in company disclosures.
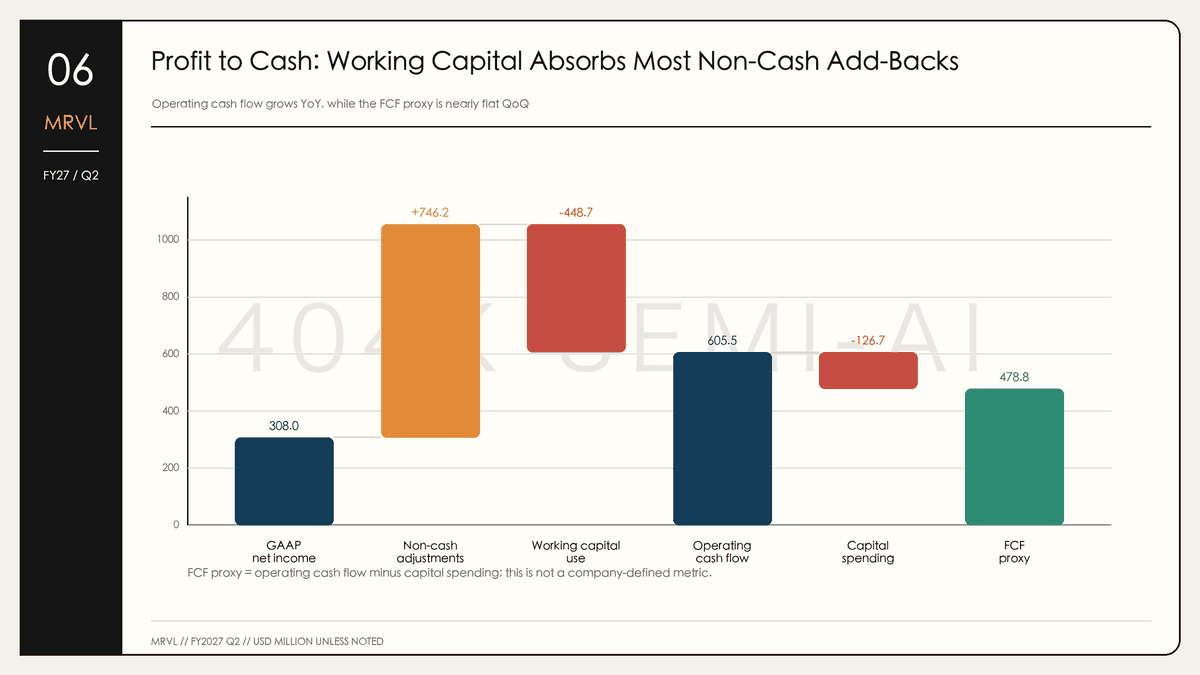
The cash flow lag relative to profit growth was primarily caused by working capital absorption. In Q2, while non-cash items added approximately $746.2 million back to operating cash flow, working capital changes consumed roughly $448.7 million. Specifically, an increase in accounts receivable resulted in a cash outflow of ~$346.6 million, and prepaid expenses and other assets drained ~$305.2 million, partially offset by other working capital items.
Accounts receivable surged 52.8% YoY, notably outpacing the 36.5% revenue growth. While this divergence likely reflects back-end-loaded quarter-end shipments, customer payment schedules, or payment terms typical of rapid growth phases—and a single quarter does not signify structural collection deterioration—it indicates that cash conversion has not kept pace with earnings growth. If Q3 revenue expands another 15% while receivables continue to outstrip sales significantly, cash flow pressure will transition from a timing anomaly into a structural trend requiring justification.
Verifying cash flow quality hinges on three key metrics: first, whether operating cash flow rebounds relative to non-GAAP net income; second, whether accounts receivable growth realigns with revenue growth; and third, whether the FCF proxy inflects upward as Q3 earnings reach new highs. If these three indicators improve, the current working capital drag can be justified as front-loaded investment for growth. Conversely, if revenue and adjusted profits continue to rise while cash flow stagnates, the market will discount the multiple applied to accounting earnings.
VI. SBC, Dilution, and Post-M&A; Balance Sheet Structure
Q2 stock-based compensation (SBC) totaled $326.2 million, up ~112% YoY and representing 11.9% of quarterly revenue. The diluted weighted-average share count reached 921.2 million, up 5.8% YoY from 870.4 million in the prior-year period. While SBC is excluded from non-GAAP net income, it dilutes future EPS via share count expansion and reduces existing shareholders' proportional claim on company growth.
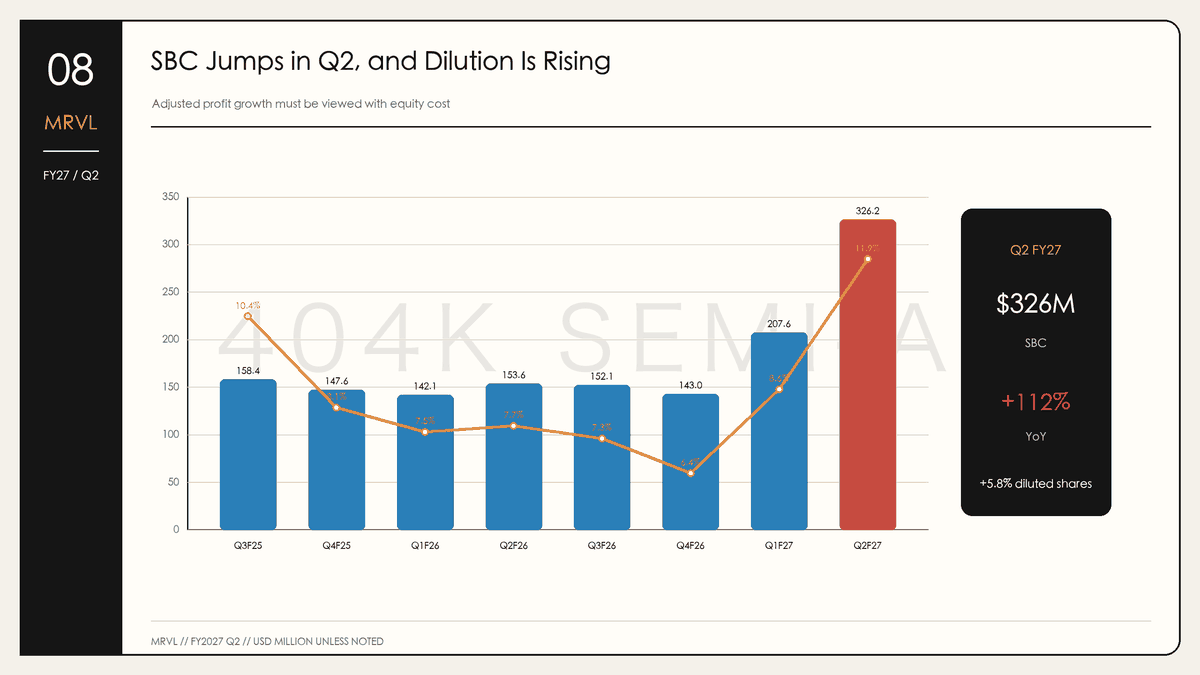
This is precisely why EPS trajectory cannot be assessed solely through net income totals. Although Q2 non-GAAP EPS was strong at $0.94, per-share growth would have been materially higher had share count remained flat. Going forward, evaluating whether operating leverage genuinely accrues to shareholders requires tracking non-GAAP net income alongside SBC as a percentage of revenue and diluted share growth. The ideal scenario combines rapid revenue expansion with declining SBC intensity and moderating share dilution; if all three expand in tandem, per-share value creation will be partially diluted.
Marvell closed the quarter with $3.9328 billion in cash and cash equivalents against $4.9629 billion in long-term debt, yielding a net debt position of approximately $1.0301 billion. While liquidity appears ample on the surface, the elevated cash balance was bolstered by financing activities, including $2.0 billion in convertible preferred stock. As such, the cash increase cannot be attributed entirely to Q2 operating free cash flow.
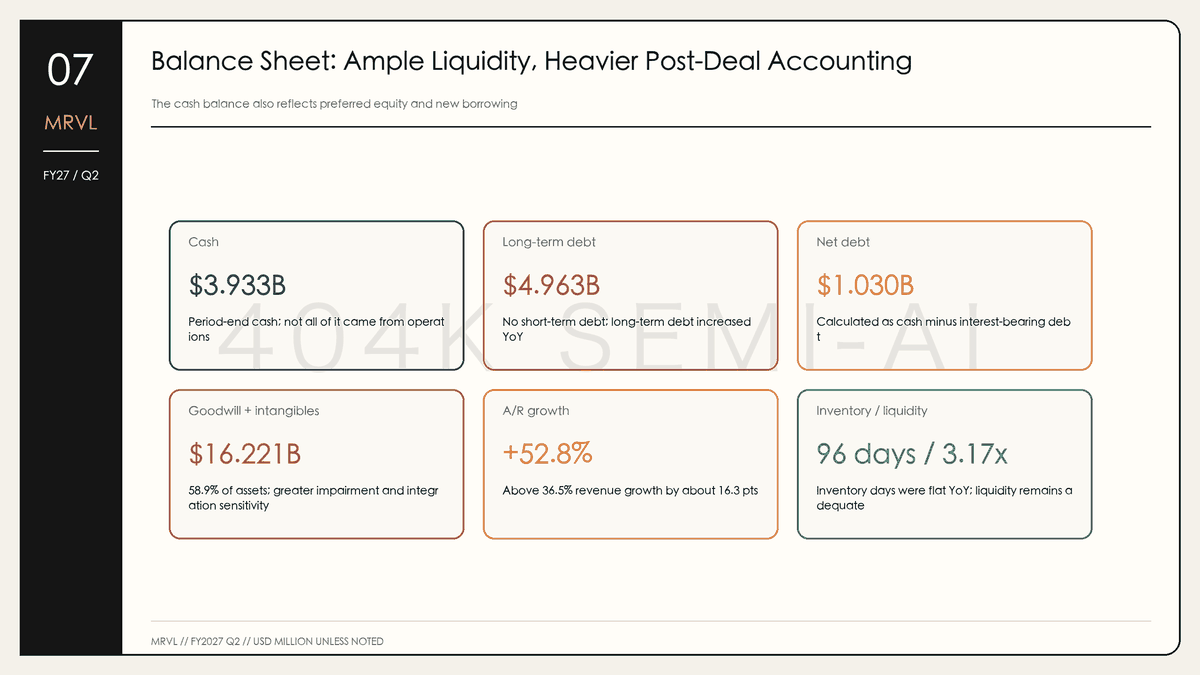
Goodwill stood at $13.8739 billion and intangible assets at $2.3466 billion, totaling $16.2205 billion and accounting for approximately 58.9% of total assets. This asset profile reflects Marvell’s historical M&A; strategy to expand its technology and product portfolio. However, it also means GAAP earnings will continue to bear long-term amortization drag and carry impairment risks should acquired assets underperform. Together with SBC, acquisition-related integration costs represent the primary driver of the persistent GAAP vs. non-GAAP earnings spread.
Days sales of inventory (DSI) stood at ~96 days with an inventory turnover of ~3.17x, showing no severe imbalance for now; however, inventory must be monitored alongside accounts receivable during this steep revenue ramp. While building inventory ahead of demand and accumulating receivables post-shipment are standard dynamics during rapid expansion, the crucial question is whether these working capital assets convert into revenue and cash as scheduled. Should customer programs face delays, working capital drag and balance-sheet risks will compound simultaneously.
VII. Key Valuation Drivers and Monitoring Framework for Marvell
While current disclosures support upward earnings revisions, they remain insufficient to justify a rigid point price target. Without disclosures on prevailing share price, consensus estimates, segment long-term margins, or quantified custom silicon pipeline revenue, applying an arbitrary P/E multiple would project false precision. A more rigorous approach is to identify which fundamental validation trajectory Marvell follows, thereby determining whether its growth justifies multiple expansion, maintenance, or compression.
The revenue validation track is the most straightforward. The Q3 revenue guidance midpoint of $3.150 billion serves as the baseline benchmark for the upcoming quarter. The high end of the range ($3.3075 billion) would signal that AI connectivity and custom silicon ramps are exceeding plan, while the low end ($2.9925 billion) would indicate ongoing growth but slower project execution. Monitoring whether Data Center revenue holds at or above ~79% of total sales will confirm whether top-line expansion remains decisively driven by AI infrastructure.
The gross margin track determines the quality of top-line expansion. Q3 non-GAAP gross margin guidance is 57.5% to 58.5%. If revenue tracks toward the high end while gross margin approaches 58.5%, it will demonstrate that scale is ramping without compromising unit economics. If revenue increases while gross margin slides toward 57.5%, the market will scrutinize custom ASIC dilution, customer pricing power, and product mix headwinds. If both revenue and gross margin miss guidance ranges, the growth narrative will face material downward revisions.
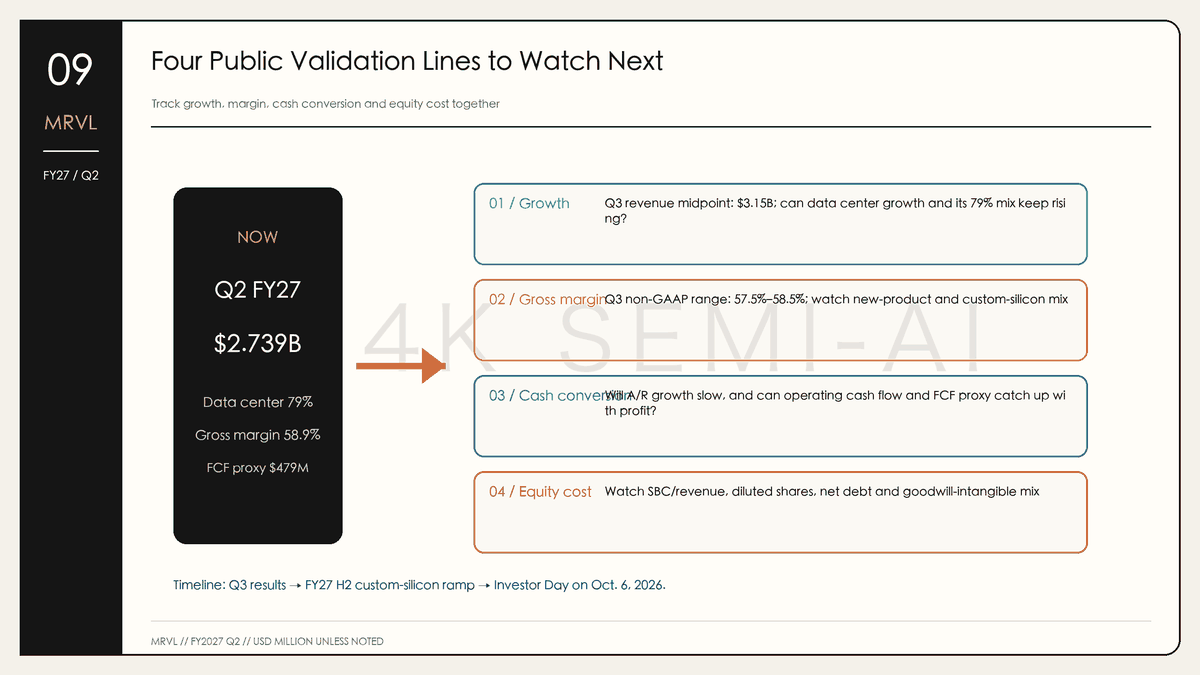
The cash conversion track distinguishes temporary working capital buildup during expansion from chronic earnings quality lag. Q3 operating cash flow, accounts receivable growth, and the FCF proxy must be evaluated in tandem. If revenue hits record highs while cash conversion improves, Q2's cash drag will be confirmed as a timing issue. However, if revenue hits record highs while receivables continue to outpace sales, valuation multiples should reflect a discount for collection and working capital uncertainty.
The equity dilution track determines how effectively top-line growth translates into per-share value. SBC has reached 11.9% of revenue, and diluted share count is up 5.8% YoY, alongside a capital structure carrying substantial goodwill, intangibles, debt, and convertible preferred shares. While continued non-GAAP EPS growth is essential, moderating SBC intensity and slowing share dilution are equally critical; otherwise, operating leverage will be partially absorbed by dilution and financing costs.
This framework yields three distinct scenarios. In the Bull Case, Q3 revenue lands near or above $3.3075 billion, gross margin approaches 58.5%, cash conversion rebounds, and the upcoming Investor Day provides quantified evidence for custom silicon ramps and FY2028 growth, prompting dual upgrades in earnings estimates and valuation multiples. In the Base Case, revenue hovers near $3.150 billion, gross margin remains around 58.0%, and cash flow steadily catches up, with share price returns primarily driven by earnings growth. In the Bear Case, revenue tracks toward the low end of guidance, gross margin falls below 57.5%, or receivables consistently outgrow revenue, leading the market to reprice risks around customer concentration, program timing, and earnings quality.
The most significant takeaway from Q2 is that Marvell’s reported revenue and forward guidance confirm AI demand has transitioned from bookings and design wins into scaled financial monetization. With Data Center revenue reaching 79% of total sales, Q3 guidance midpoint projecting another 15% QoQ revenue growth, and custom silicon scheduled to accelerate in 2H, these catalysts collectively raise the company's growth ceiling over the next two years.
Yet the same quarterly report clearly delineates operational boundaries: gross margins are not expanding alongside revenue and guidance implies a sequential dip at the midpoint; operating cash flow fell QoQ amid substantial working capital absorption; and SBC and share count continue to climb, alongside a balance sheet heavily weighted toward goodwill and intangibles. Marvell’s investment narrative has pivoted from "whether demand exists" to "whether growth converts into high-quality earnings." Going forward, every incremental revenue beat will require corroboration from gross margin resilience, cash flow conversion, and per-share value creation.
Related Reading
Arm FY2027 Q1 Deep Dive: Data Center Royalties More Than Double, AGI CPU Demand Exceeds $2 Billion