
Luxshare Precision Deep-Dive Update: JPMorgan Raises Target Price to RMB97; After the iPhone Mispricing, Optical Modules Begin to Enter the P&L;
目录
Too Long; Didn’t Read
1. JPMorgan’s Update Addresses a Near-Term Mispricing
2. Near-Term Debate: iPhone Demand Has Not Been Directly Broken by Higher Memory Prices
III. JPMorgan’s RMB97 Target Price Is Below Goldman’s RMB106, but the Direction Is Consistent
IV. Optical Modules Are the Biggest New Variable in This Report
V. The Value of the Communications Business Lies in Turning the Physical Layer into a Bundled Sale
VI. Earnings Upgrades Are Not Large, but the Structural Signal Matters More
VII. What the RMB97 Target Price Means: A Conservative Re-rating, Not an End-Point Price
VIII. Luxshare Precision Now Has Three Profit Pools
IX. Biggest Risk: Slow Optical-Module Ramp, or Revenue Growth Without Gross Margin
X. What to Track Over the Next Four Quarters
XI. Three Scenarios: The RMB97 Target Price Corresponds to a Somewhat Optimistic Base Case
XII. Investment Conclusion: The Apple Chain Stabilizes the Base, Optical Modules Determine the Next Leg of Upside
本内容基于公开资料和研报数据整理,不构成任何投资建议,不代表任何个人观点,仅供学习参考,请理性阅读
JPMorgan raised its target price for Luxshare Precision from RMB82 to RMB97, focusing on two variables: iPhone demand and the ramp-up of optical modules. The former explains whether the near-term pullback has been excessive; the latter determines whether the communications business can truly lift margins. After Goldman Sachs recently raised its target price, JPMorgan’s value lies in validating the cadence, valuation discipline, and the numbers to watch in the next round of earnings.
Too Long; Didn’t Read
Today’s pullback looks more like emotional extrapolation. After Apple raised MacBook and iPad prices, the market worried that higher memory prices would pressure iPhone demand, and Luxshare Precision was sold off aggressively. JPMorgan’s supply-chain checks show that iPhone is not on the price-hike list, and next year’s shipments and premium-model mix are better than feared.
JPMorgan raised its target price to RMB97. The valuation still uses 22x rolling forward P/E, below Goldman Sachs’ RMB106, but the direction is consistent. Both institutions are repricing Luxshare from an Apple-chain assembler into a complex hardware platform.
Optical modules enter earnings forecasts. JPMorgan expects 800G, 1.6T, and high-spec optical modules to begin ramping from the second half, with communications revenue CAGR of roughly 76% in 2025-2028, and optical modules contributing higher profit in 2027/2028.
iPhone remains the cash-flow base. A stronger Pro Max mix, higher assembly share, and a sharp YoY increase in 1Q26 JV income can cushion end-demand concerns while providing cash flow and customer endorsement for new-business investment.
The debate is around earnings quality. Revenue growth is now jointly endorsed by Goldman Sachs and JPMorgan. The next step is to watch communications gross margin, optical-module customer qualifications, whether server assembly drags on margins, and whether free cash flow can keep pace with expansion.
Trading discipline depends on four numbers. Going forward, track iPhone shipments and Pro Max mix, communications revenue growth, optical-module profit contribution, and whether 2028 EPS can approach JPMorgan’s forecast. If delivery continues, the target-price logic becomes more stable.
1. JPMorgan’s Update Addresses a Near-Term Mispricing
This Luxshare Precision update does not need to retell the company’s full story. The May deep dive already made clear that Luxshare Precision is migrating the precision manufacturing, global delivery, and customer collaboration capabilities it developed in the Apple chain into AI servers, automotive electronics, and high-speed connectivity. On June 24, Goldman Sachs raised its target price to RMB106 and incorporated data centers, automotive electronics, and ODM into its 2026-2028 model.
Luxshare Precision Deep Dive: From Apple-Chain Precision Manufacturing to AI Servers and Automotive Electronics Platforms; How High-Speed Connectivity Revalues Manufacturing Assets
Luxshare Precision Deep-Dive Update: Goldman Sachs Raises Target Price to RMB106; AI Servers and Automotive Electronics Are Rewriting the Valuation
The value of JPMorgan’s report is narrower and more timely. It answers a direct question: after Apple’s price-hike news, the market extrapolated MacBook and iPad price increases into weaker iPhone demand, and Luxshare Precision fell roughly 9% that day. Was that reaction excessive?
JPMorgan’s answer is clear: yes. It maintained an Overweight rating and raised its target price from RMB82 to RMB97. The target price is less aggressive than Goldman Sachs’ RMB106, but it adds a near-term validation line for Luxshare Precision: iPhone demand is not as weak as the market fears, and optical modules will begin volume ramp-up from 2H26. Together, the two can support earnings forecasts.
Luxshare’s share price fell c.9% today, vs a 2% sector index correction. We attribute this to rising market concerns on iPhone volume drop, after Apple announced it would raise prices of Macbooks and iPads. In our view, investors overreacted given iPhones are not on the price hike list.
This passage identifies the core of the trade. The market reaction came from sentiment transmission along Apple’s price-hike chain, not a sudden deterioration in company fundamentals. To address rising memory costs, Apple raised MacBook and iPad prices. Investors worried that this pressure would continue into iPhone and depress end-unit sales. As a core Apple-chain supplier, Luxshare Precision was naturally sold first.
But JPMorgan’s supply-chain conclusion does not support that bearish extrapolation. iPhone has not yet been included on the price-hike list, 2026 shipments are more resilient than market expectations, and the premium-model mix is also better. Luxshare Precision has a higher share in Pro Max assembly, so an improved premium mix directly raises JV income and earnings quality. 1Q26 iPhone assembly JV income rose 160% YoY, showing that the base business can still contribute incremental profit to the P&L.;
The core judgment of this update is direct: Luxshare Precision’s near-term pullback has given the market an opportunity to recalibrate the model. The Apple chain has not stalled, optical modules are starting to be included in earnings forecasts, and target-price upgrades have moved from a single-institution judgment to multi-institution validation. The market should next watch whether four numbers in JPMorgan’s model show up in earnings: 2026 EPS of RMB2.93, 2027 EPS of RMB3.86, 2028 EPS of RMB5.14, and roughly 76% revenue CAGR for the communications business in 2025-2028.
2. Near-Term Debate: iPhone Demand Has Not Been Directly Broken by Higher Memory Prices
The most sensitive near-term variable for Luxshare Precision remains Apple. No matter how much the company expands into AI servers, automotive electronics, and optical modules, Apple-related business still determines cash flow, capacity utilization, and market sentiment. Today’s pullback shows that any negative signal in the Apple chain will first be reflected in Luxshare’s share price.
This concern comes from higher memory prices. After memory costs rose, Apple increased MacBook and iPad selling prices. The market worried about two consequences: first, weaker consumer acceptance; second, that Apple would also later raise iPhone prices, depressing iPhone sales. Luxshare Precision was hit because investors treated the entire Apple hardware chain as the same demand-risk exposure.
JPMorgan’s supply-chain checks reached a different conclusion. It emphasized three points: iPhone has not yet raised prices; iPhone shipments are stronger than expected; and the product mix is skewing toward premium models. For Luxshare Precision, the third point is most important because the company has a relatively high share in Pro Max assembly. If both shipments and premium mix improve, JV income and margins are supported.
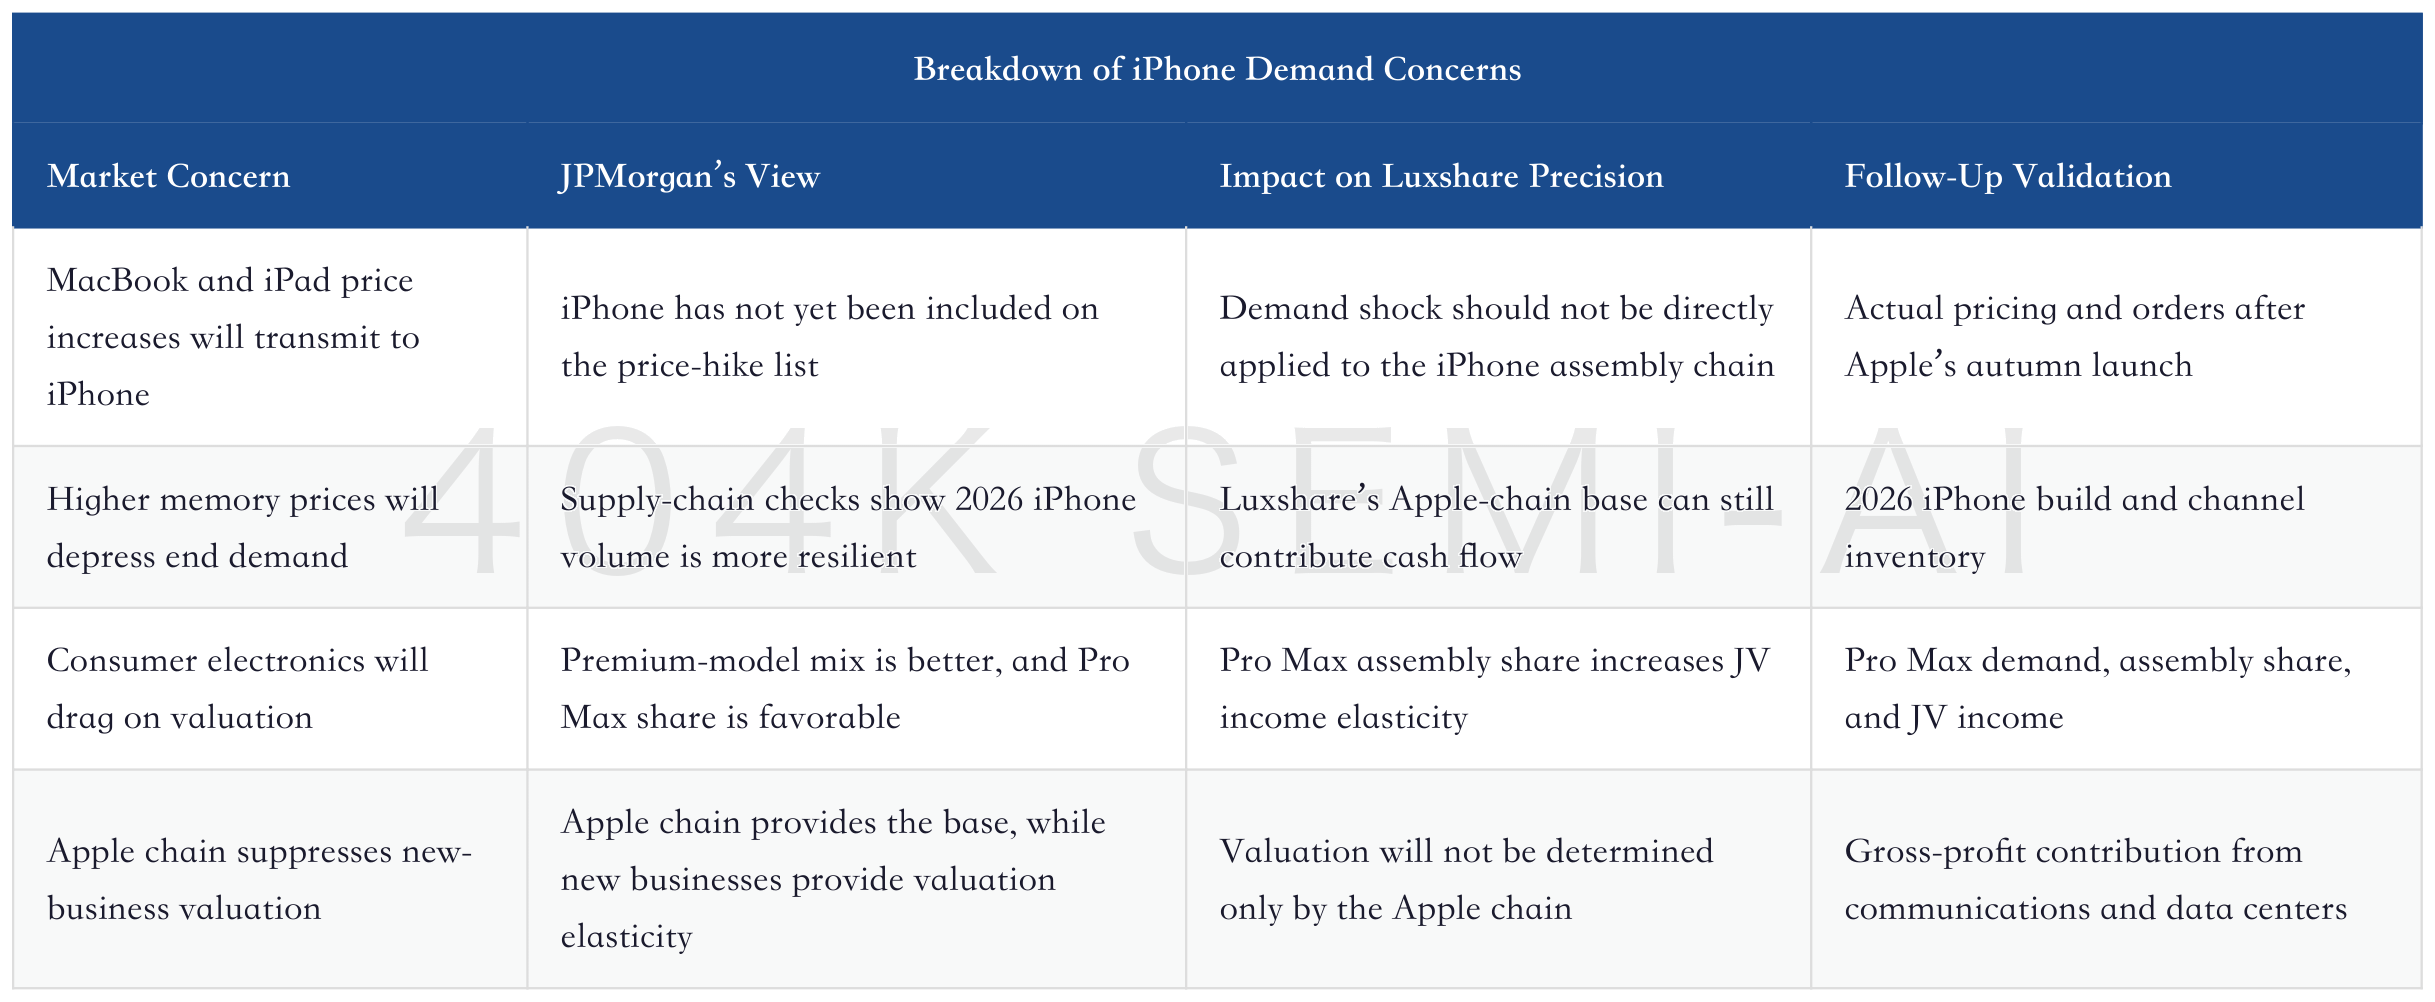
The investment implication of this table is clear. Luxshare Precision does not now need an “Apple demand surge” to support valuation. It only needs the Apple chain to remain stable and provide a cash-flow base for new businesses. Valuation elasticity comes from communications and data centers, especially high-speed interconnects and optical modules. If the Apple chain has not collapsed, the market should not directly price Luxshare Precision as being in a consumer-electronics downcycle simply because of MacBook and iPad price-hike news.
We expect the iPhone assembly business to continue to drive Luxshare’s growth. Meanwhile, we see strong growth momentum in the auto and communication segments. We model a 31% earnings CAGR for 2025-28E.
This passage gives JPMorgan’s overall positioning of Luxshare Precision. iPhone assembly continues to drive growth, automotive and communications businesses provide incremental upside, and earnings CAGR is expected to reach 31% in 2025-2028. This mix is stronger than a pure Apple-chain story and more stable than a pure AI concept. Its value lies in the fact that the base and the upside do not sit in the same business line.
The easiest mistake for investors to make is to set the Apple chain against AI-driven increments. A more effective view is this: the Apple chain provides Luxshare Precision with funding, manufacturing discipline, and customer trust; communications and data centers determine valuation uplift; automotive electronics lengthen the customer cycle and reduce single-end-market risk. As long as the Apple chain has not clearly deteriorated, the near-term pullback should be judged by new-business validation, rather than through a blanket bearish consumer-electronics lens.
III. JPMorgan’s RMB97 Target Price Is Below Goldman’s RMB106, but the Direction Is Consistent
The difference between Goldman Sachs’ and JPMorgan’s target prices is not complicated. Goldman is more willing to incorporate data centers, automotive electronics, ODM, and MacBook share gains into a more aggressive revenue bridge and earnings bridge. JPMorgan is more restrained, still applying 22x 12-month forward rolling P/E, while raising its target price from RMB82 to RMB97. The commonality between the two models is more important than the difference in target prices: both institutions acknowledge that Luxshare Precision’s valuation anchor is moving higher.
JPMorgan’s model lays out a three-year growth curve, which goes beyond a single year of profit recovery. Revenue, profit, and EPS rise year by year, while margins improve in the later two years. The conclusion comes first; the specific figures are checked in the table below.
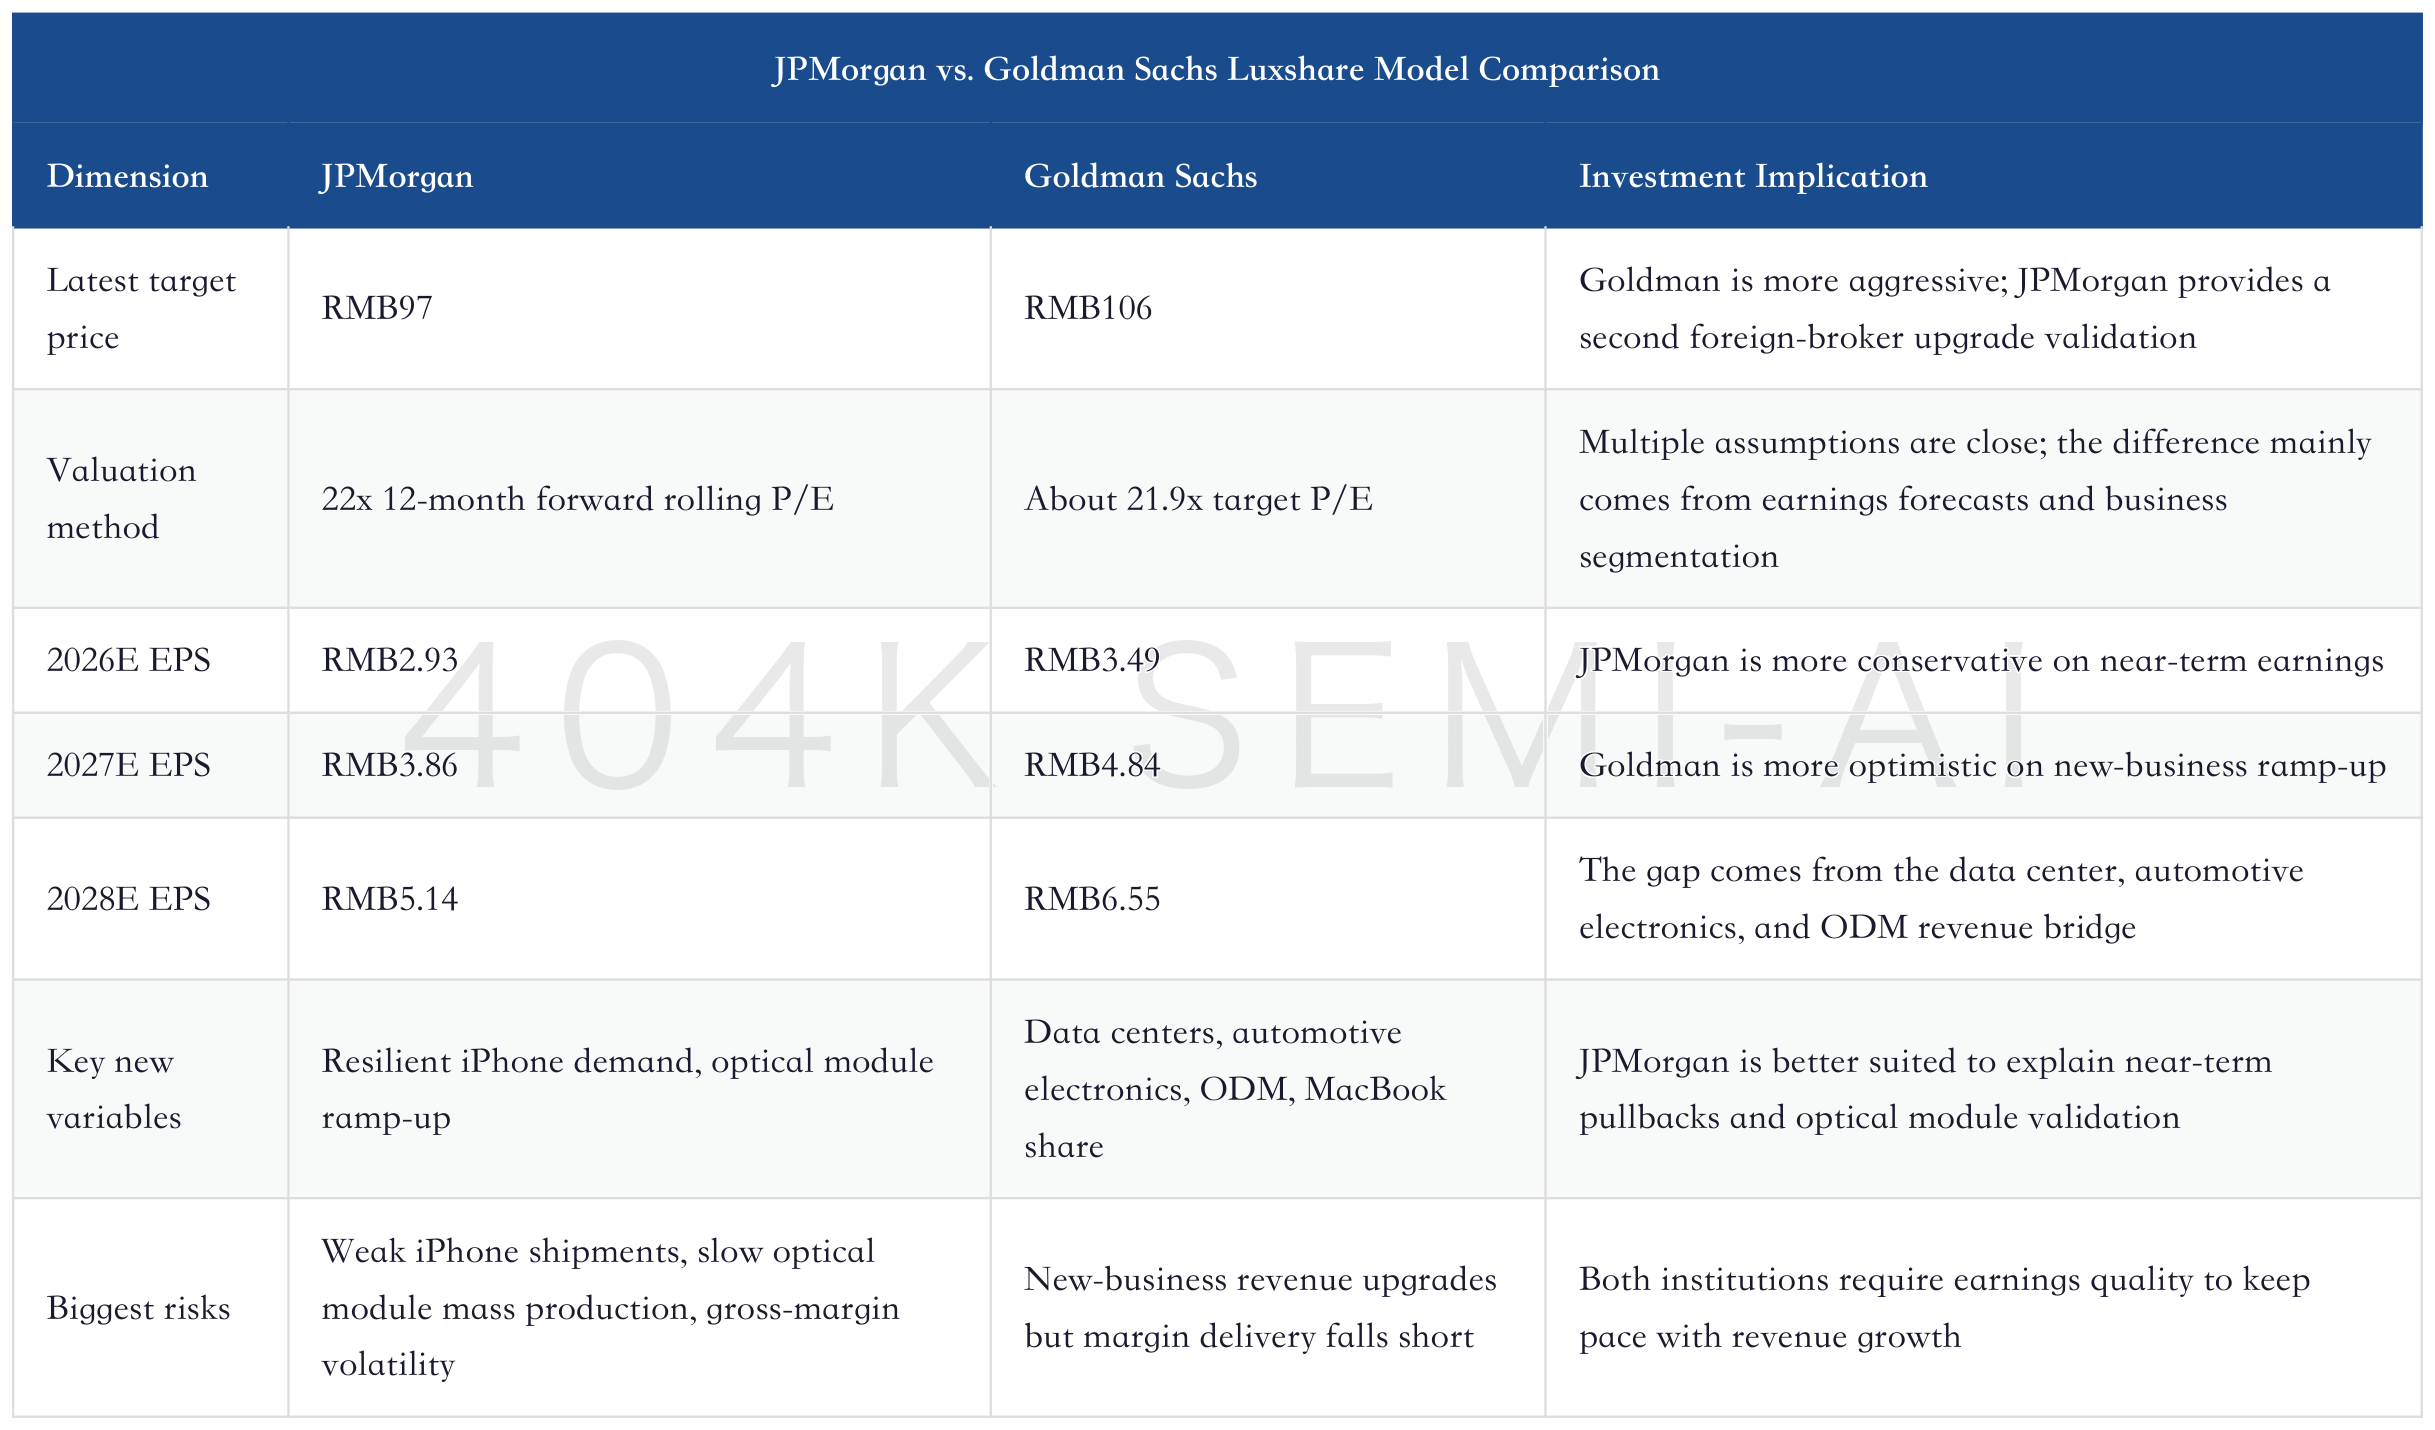
The conclusion from this table is straightforward. JPMorgan’s RMB97 target is not a “bearish view on Luxshare.” It is a more conservative validation case. If Luxshare Precision only delivers iPhone resilience and an optical module ramp-up over the next few quarters, JPMorgan’s model is easier to validate first. If data centers, automotive electronics, and ODM all materialize at the same time, Goldman’s RMB106 logic becomes stronger.
This also provides a better sequence for trading and research. Step one is to see whether JPMorgan’s model can be delivered: iPhone not deteriorating, optical modules entering the income statement, and EPS being revised up. Step two is to see whether Goldman’s model can be delivered: data centers, automotive electronics, and ODM jointly contributing to margin improvement. The first step proves that the pullback was excessive; the second proves that the asset profile is moving higher.
IV. Optical Modules Are the Biggest New Variable in This Report
Optical modules are the most important part of JPMorgan’s report. Goldman Sachs had also mentioned optical modules previously, but Goldman’s main line was broader, including AI server copper connectivity, server assembly, automotive electronics, Leoni, ODM, and MacBook. This time, JPMorgan places optical modules in a more prominent position and provides a profit-contribution forecast: optical modules are expected to contribute 10% of profit in 2027 and 16% in 2028.
This information is critical. In the past, when the market looked at Luxshare Precision’s communications business, it focused more on connectors, cables, copper connectivity, server components, power supply, and liquid cooling. For Luxshare, optical modules have long looked like an option: large addressable space, but customer validation and mass-production timing still need to be proven. JPMorgan incorporating optical modules into its 2027/2028 profit contribution means the sell side is starting to move this line item forward from a “long-dated option” to a “medium-term earnings item.”
Optical module set to be key growth engine. Luxshare has established a comprehensive communication product portfolio, spanning connectors, optical modules, power and thermal management solutions. Among these, we view optical modules as a pivotal growth engine.
JPMorgan’s core logic is that Luxshare Precision has already built a communications product portfolio covering connectors, optical modules, power, and thermal management, while maintaining long-term cooperation with global technology leaders. After 800G, 1.6T, and high-specification optical modules begin volume shipments from the second half of 2026, both revenue and margins in the communications business should be pulled higher. JPMorgan expects the communications business to deliver a revenue CAGR of about 76% from 2025 to 2028, far above the company’s overall revenue growth.
This logic should be distinguished from pure optical module companies. Companies such as Eoptolink, Zhongji Innolight, and TFC Communication benefit more directly from 800G and 1.6T shipments, with purer revenue and profit elasticity. Luxshare Precision’s advantage lies in its portfolio: connectors, cables, optical modules, power, thermal management, and server components all sit within the same customer demand chain. Its single-item optical module purity is lower, but its customer delivery scope is broader.
The key to Luxshare Precision’s optical module logic is not whether it can become a pure optical module company. The key is whether optical modules can upgrade the communications business from “connectivity and components” to “AI data center physical-layer integrated supply.” If optical modules, copper connectivity, power, and liquid cooling can be cross-introduced among the same customers, Luxshare Precision’s valuation will move one step closer from consumer electronics manufacturing toward an AI infrastructure hardware platform.
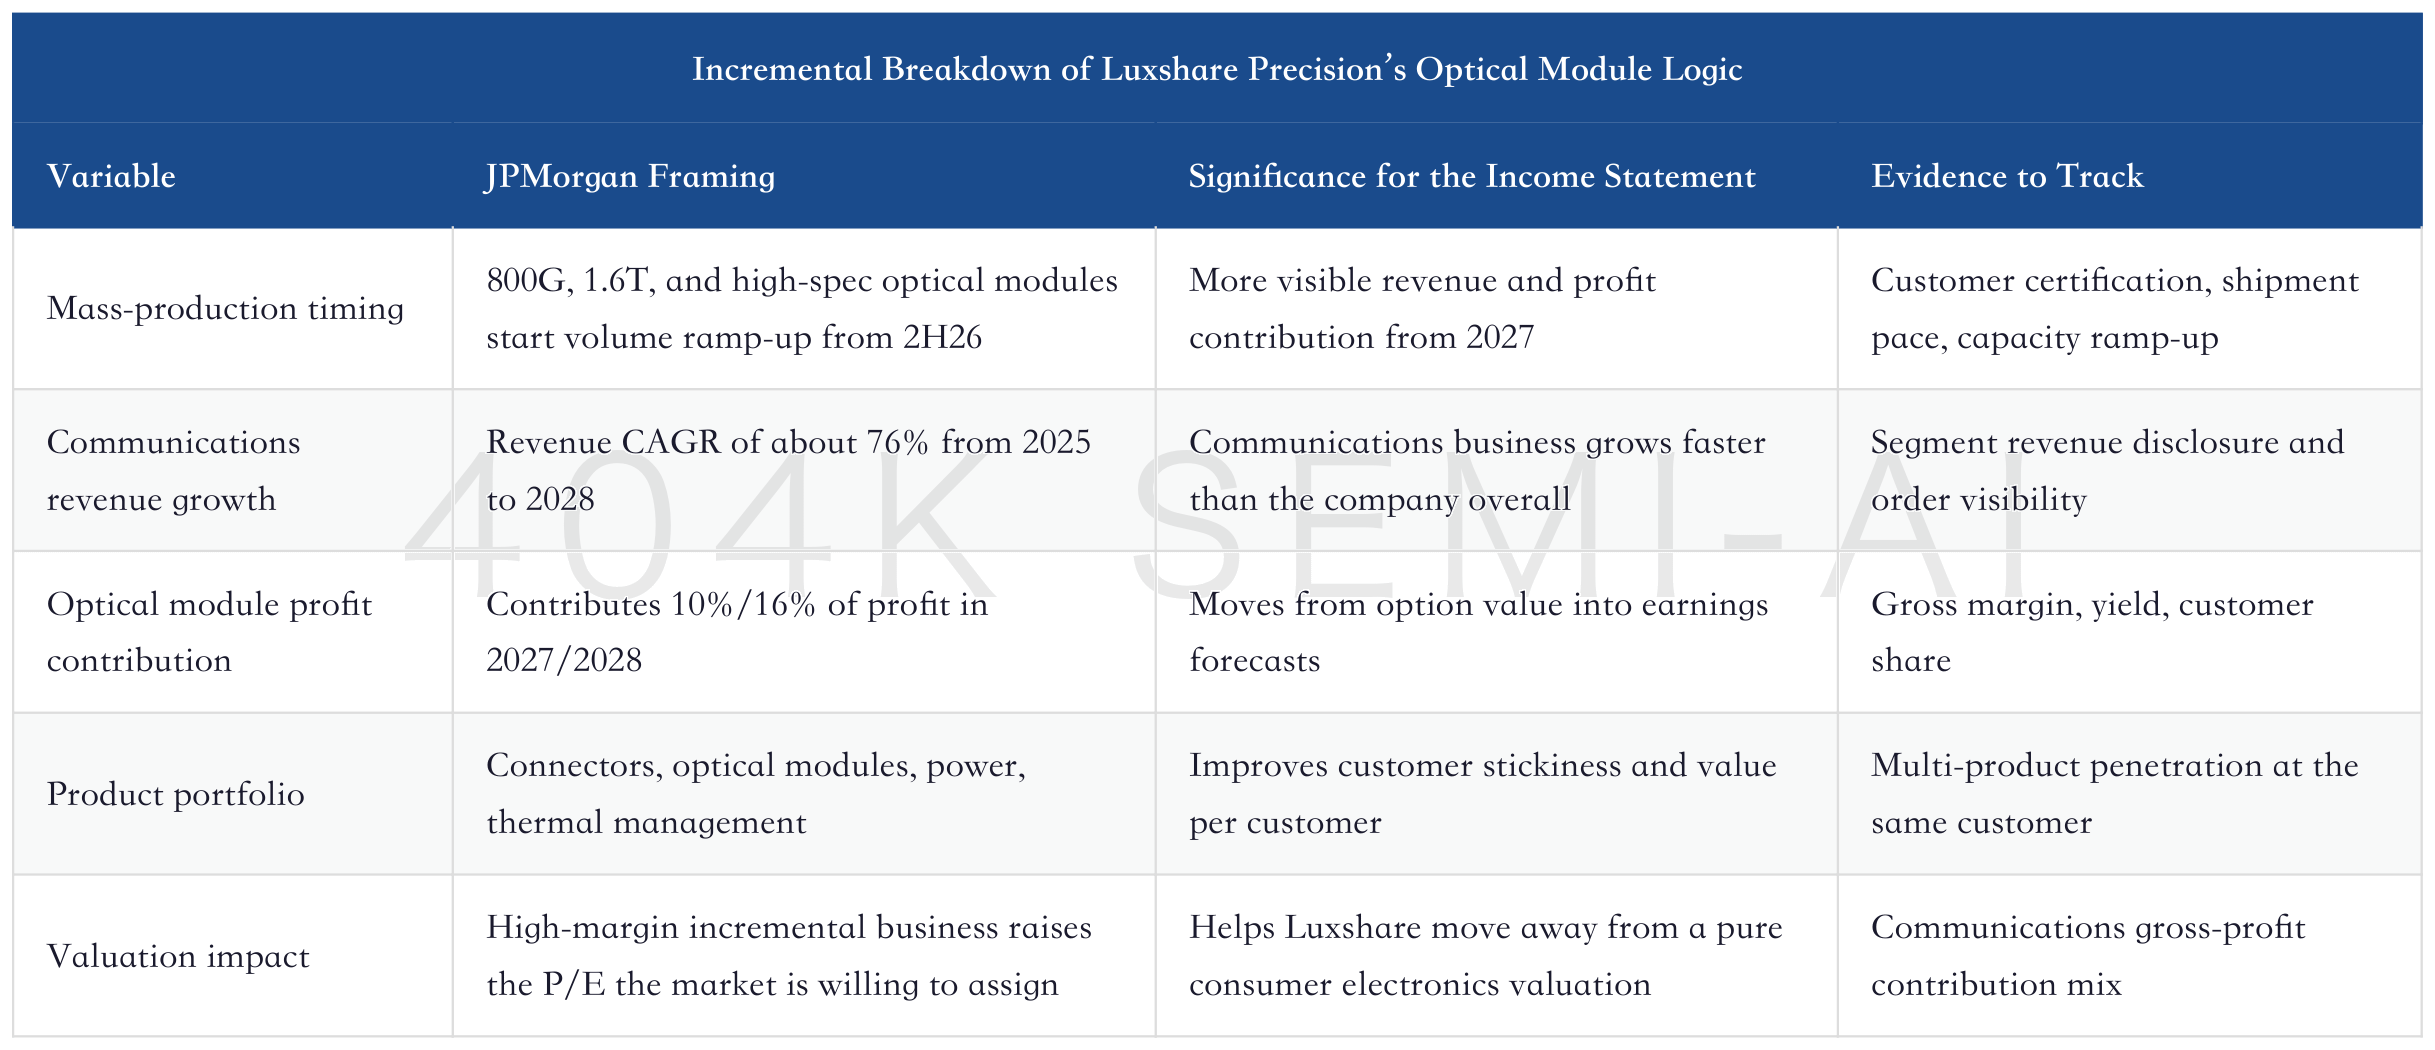
This table also shows the risks. Optical modules do not naturally materialize just because the industry is strong. They must go through customer certification, product reliability testing, yield improvement, cost control, and capacity ramp-up. Luxshare Precision’s market position in optical modules still cannot be directly equated with leaders such as Eoptolink and Zhongji Innolight. From an investment perspective, it should be viewed as an incremental source of profit elasticity, not directly as the entire reason for the company’s re-rating.
V. The Value of the Communications Business Lies in Turning the Physical Layer into a Bundled Sale
The long-term value of Luxshare Precision’s communications business does not come from any single product. The physical-layer upgrade in AI data centers will simultaneously drive high-speed copper interconnects, backplanes, cables, optical modules, power supplies, liquid cooling, and server components. Luxshare Precision has exposure across all these areas. Its bundled capability is what differentiates it from pure-play optical-module or connector companies.
The Second Re-rating of the AI Server Materials Chain: From Passive Components to PCB/CCL, ABF Substrates, and Testing Equipment
Over the past few months, the AI server materials chain has repeatedly validated the same point: GPU capex spills over into the physical layer. GPUs and ASICs receive orders first; then networking, PCBs, connectors, optical modules, power supplies, liquid cooling, testing equipment, and materials begin to be repriced. Luxshare Precision sits at the intersection of connectivity and system delivery.
Foxconn Industrial Internet’s value is more skewed toward rack-level delivery, while Luxshare Precision’s value is more skewed toward a combination of connectors, optical modules, power supplies, and thermal management. Both benefit from AI server capex, but they play different roles. Foxconn Industrial Internet solves the question of whether full racks can be delivered on schedule; Luxshare Precision solves whether high-speed signals, power, and cooling can run stably. Both links are becoming more expensive in AI clusters.
Foxconn Industrial Internet Deep Dive: From AI Server ODM Leader to Rack-Level Delivery Platform, and How Blackwell, ASICs, and Networking Revalue Manufacturing Assets
The impact of the communications business on Luxshare Precision’s valuation can be broken into three layers.
The first layer is revenue growth. JPMorgan expects communications revenue to compound at roughly 76% from 2025 to 2028, far above the company overall. This growth rate will lift the market’s perception of the company’s growth profile.
The second layer is gross-margin improvement. The communications business is usually higher-margin than consumer-electronics assembly. If optical modules, high-speed interconnects, power supplies, and liquid cooling can scale, they will increase gross-profit contribution. The real reason the market is willing to assign a higher valuation is that these businesses can change the profit structure.
The third layer is customer stickiness. AI data-center customers do not look only at single-product pricing; they also look at reliability, delivery capability, and multi-product coordination. If Luxshare Precision can introduce connectors, cables, optical modules, power supplies, and thermal management into the same customer, both value per customer and switching costs will rise.
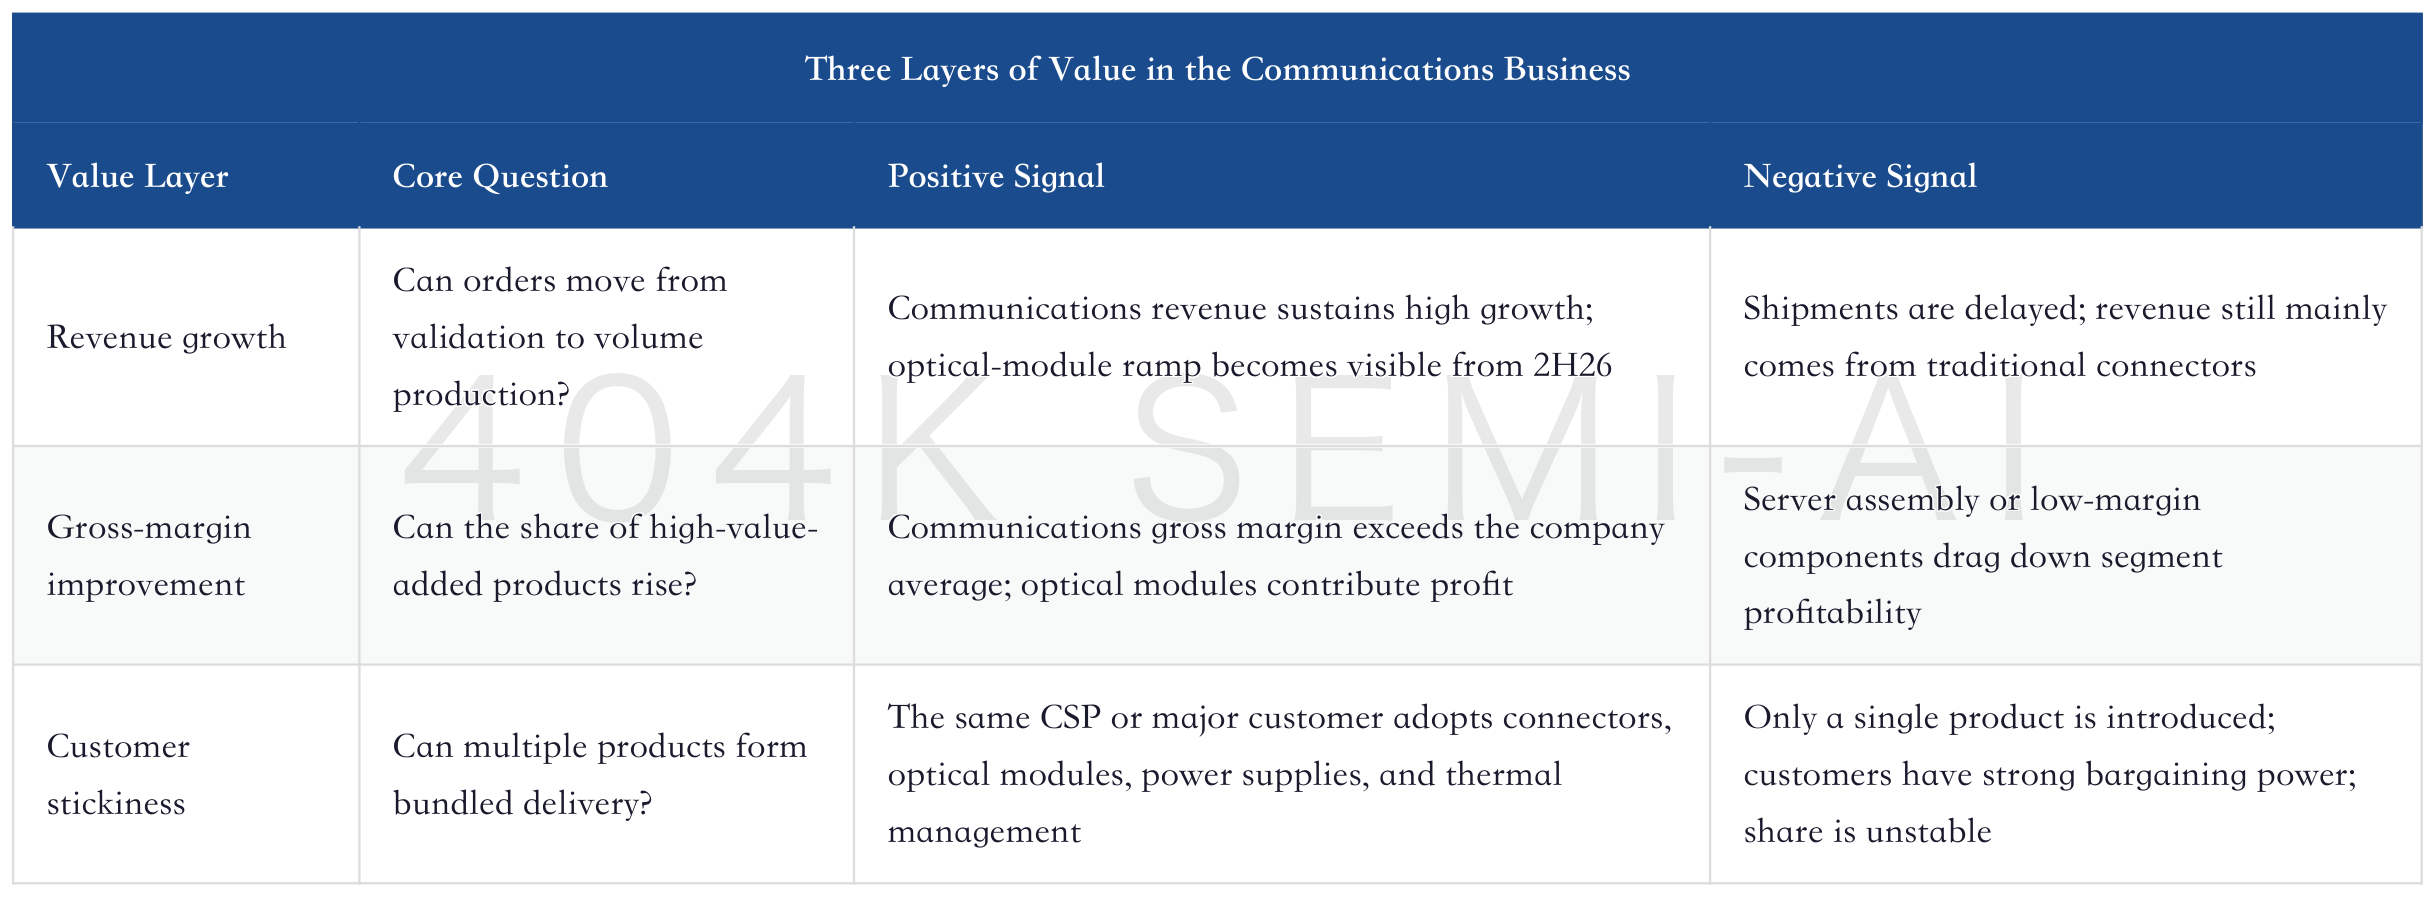
These three layers must be viewed together. Looking only at revenue growth can easily misread low-margin expansion as a re-rating. Looking only at gross-margin improvement without revenue scale will lead the market to treat it as small-business volatility. Looking only at customer cooperation without financial contribution leaves valuation stuck at the concept stage. What Luxshare Precision really needs to prove is that the communications business can contribute revenue, gross margin, and customer stickiness at the same time.
VI. Earnings Upgrades Are Not Large, but the Structural Signal Matters More
JPMorgan’s earnings upgrades this time are not aggressive. Its 2026/2027/2028 earnings forecasts were raised by 1%, 4%, and 11%, respectively. On the surface, the upgrades are less aggressive than Goldman Sachs. But on closer look, the 11% upgrade for 2028 shows that longer-term upside mainly comes from optical modules and the communications business, not near-term iPhone improvement.
JPMorgan’s revenue and profit path is clear: revenue continues to expand, profit grows faster, and net margin and operating margin gradually improve in the latter two years. The specific figures are in the table; the key point in the text is the margin inflection.
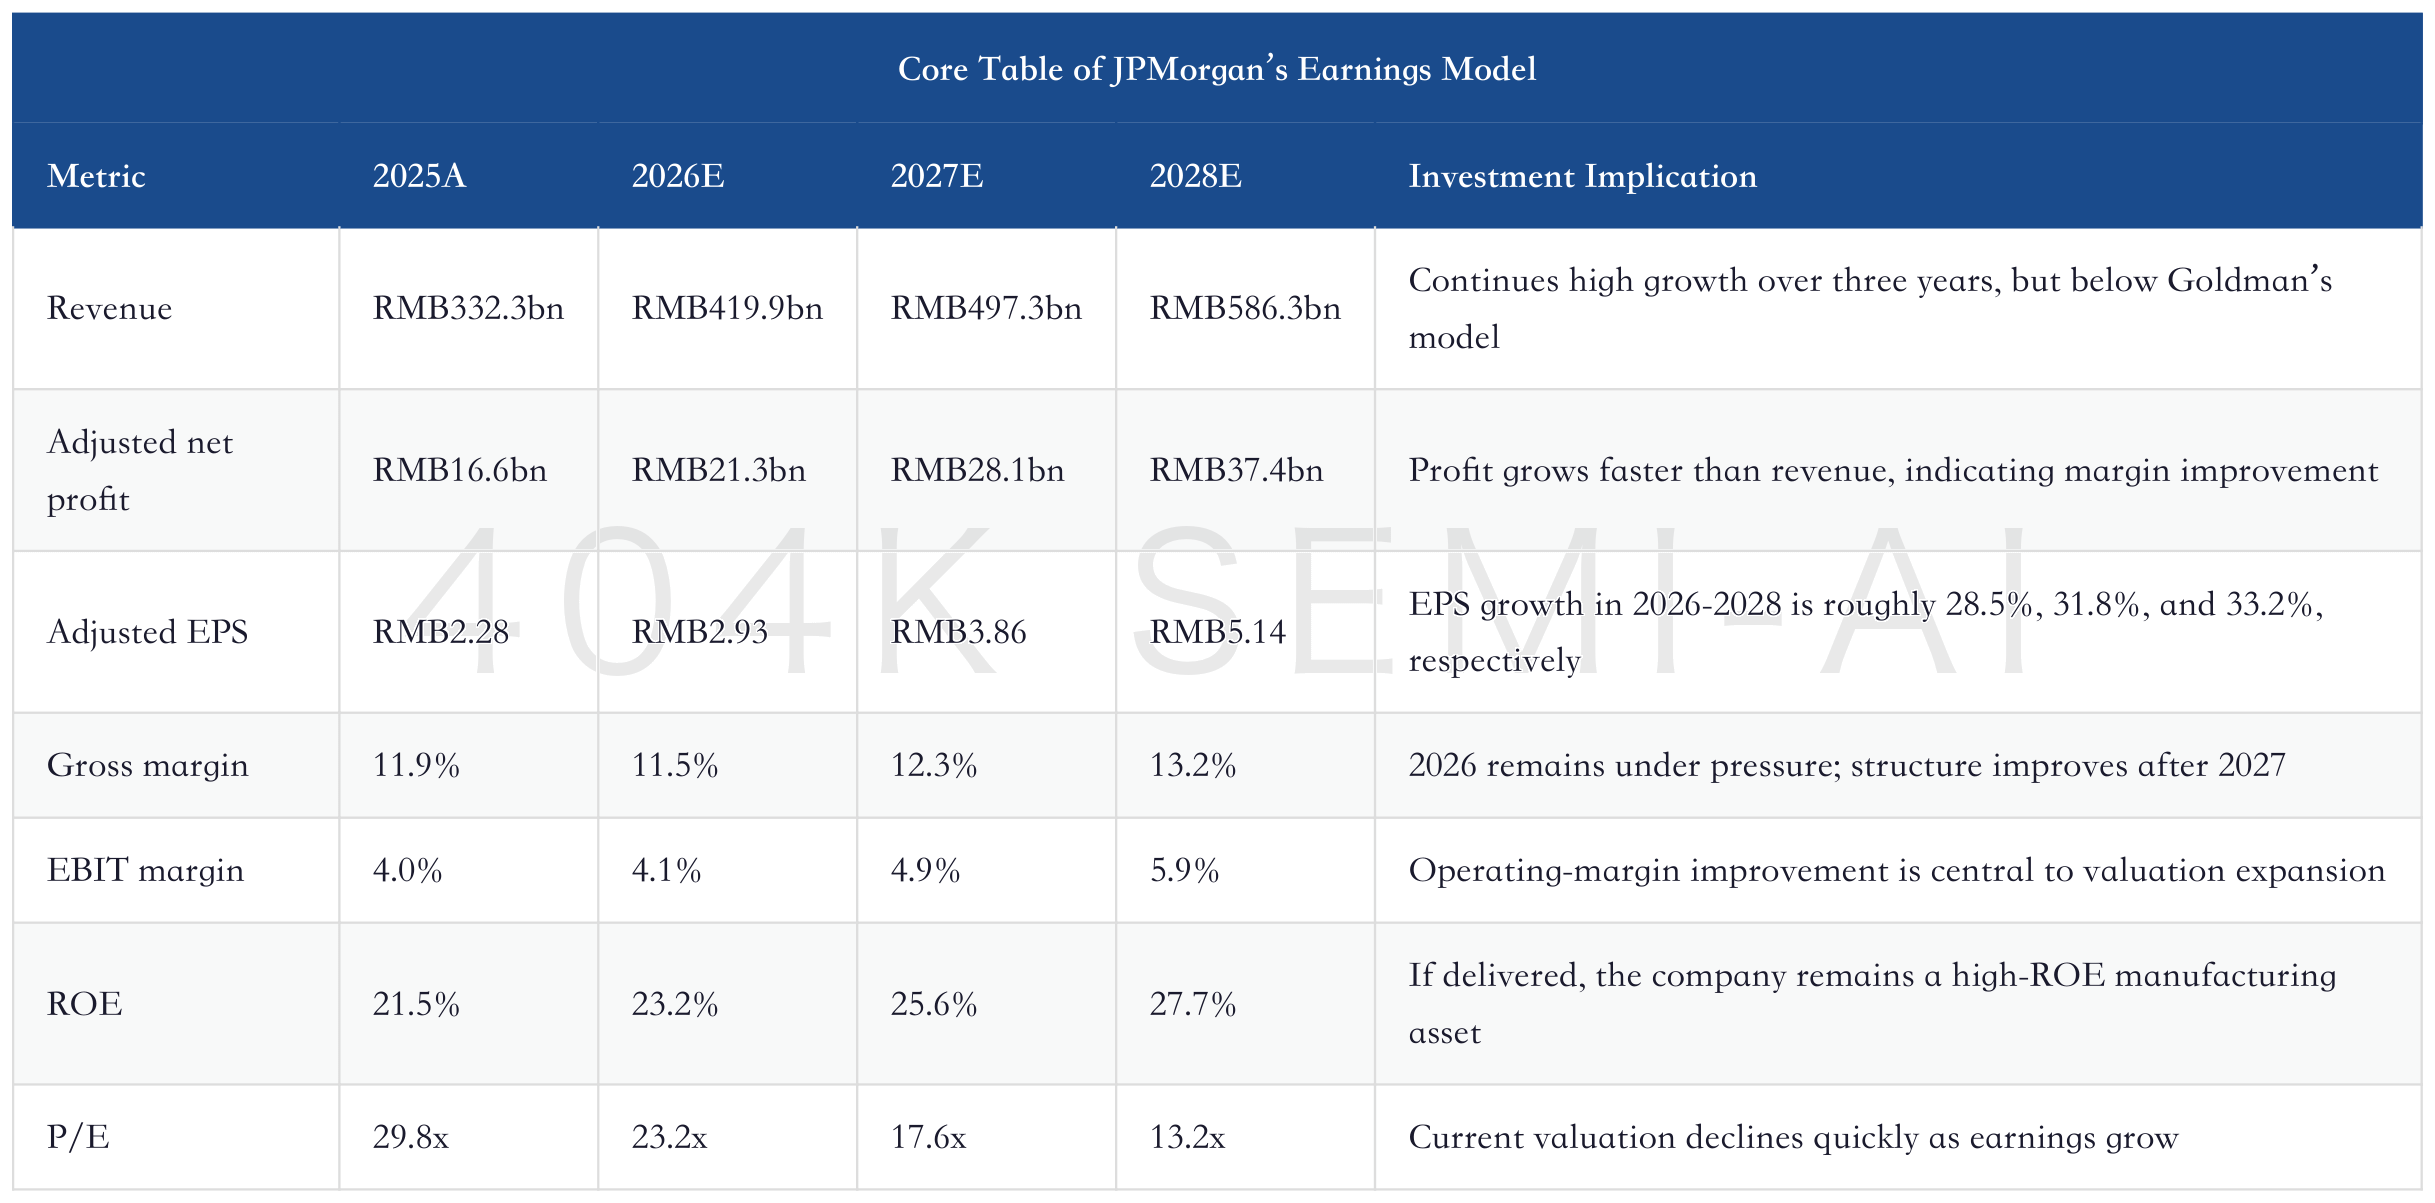
The key in this table is the margin path. JPMorgan does not assume new businesses immediately release high gross margin. It provides a relatively restrained path: the short term is still affected by product mix and expenses, while the medium term relies on communications, optical modules, and high-end businesses to lift margins.
This is also where JPMorgan’s model is more stable. It does not fully price in all AI server and automotive-electronics opportunities at once, nor does it directly lift optical-module gross margins to a very high level. It simply pulls optical modules from a long-dated option into 2027/2028 profit contribution, leading to a clear upward revision to longer-term earnings forecasts. For the market, this model is easier to validate quarter by quarter.
