
目录
Table of Contents
1. Q2 Revenue of RMB 90.6B Confirms Resilient Demand
2. Consumer Electronics: Anchoring Cash Flow and Baseline Profitability
3. Communications Segment Accelerates, but Margins Lag
4. How to Interpret the 12-Million-Unit Capacity Target
5. Margin Inflection Driven by Multiple Structural Shifts
6. Key Assumptions Underpinning the RMB 86 Price Target
7. Cash Flow and Debt Profile Dictate Expansion Quality
8. Seven Key Signals to Monitor Over the Next Four Quarters
本内容基于公开资料和研报数据整理,不构成任何投资建议,不代表任何个人观点,仅供学习参考,请理性阅读
Bernstein’s RMB 86 price target rests on a clear premise: consumer electronics defends baseline profitability through 2026, while high-margin interconnect products take over as the primary growth engine in 2027. The 12-million-unit capacity represents only an upper ceiling for supply; ultimate execution depends on delivering 2.5 million shipments, recovering communications gross margins, and generating robust cash flows.
Table of Contents
1. Q2 Revenue of RMB 90.6B Confirms Resilient Demand
2. Consumer Electronics: Anchoring Cash Flow and Baseline Profitability
3. Communications Segment Accelerates, but Margins Lag
4. How to Interpret the 12-Million-Unit Capacity Target
5. Margin Inflection Driven by Multiple Structural Shifts
6. The Core Assumptions Behind Bernstein's RMB 86 Price Target
7. Cash Flow and Leverage Dictate the Quality of Expansion
8. Seven Key Signals to Watch Over the Next Four Quarters
1. Q2 Revenue of RMB 90.6B Confirms Resilient Demand
Luxshare Precision reported Q2 2026 revenue of RMB 90.616 billion (+8% QoQ, +44% YoY), beating consensus expectations by 5.7%. Net profit attributable to the parent company reached RMB 4.183 billion (+14.3% QoQ), missing institutional consensus by 3.5%. These figures reflect two distinct realities: robust order intake and shipment execution that have yet to fully translate into bottom-line profit expansion.
The 1H 2026 interim report provides a complete financial picture: revenue reached RMB 174.504 billion (+40.16% YoY), attributable net profit rose 18.04% to RMB 7.843 billion, while recurring net profit grew just 6.47% to RMB 5.962 billion. The company disclosed FX losses of RMB 1.986 billion from foreign currency balance sheet exposures, partially offset by RMB 1.297 billion in hedging gains classified under non-recurring items. This accounting presentation masked the net hedging benefit in recurring earnings, underscoring foreign exchange volatility as a primary variable governing earnings quality.
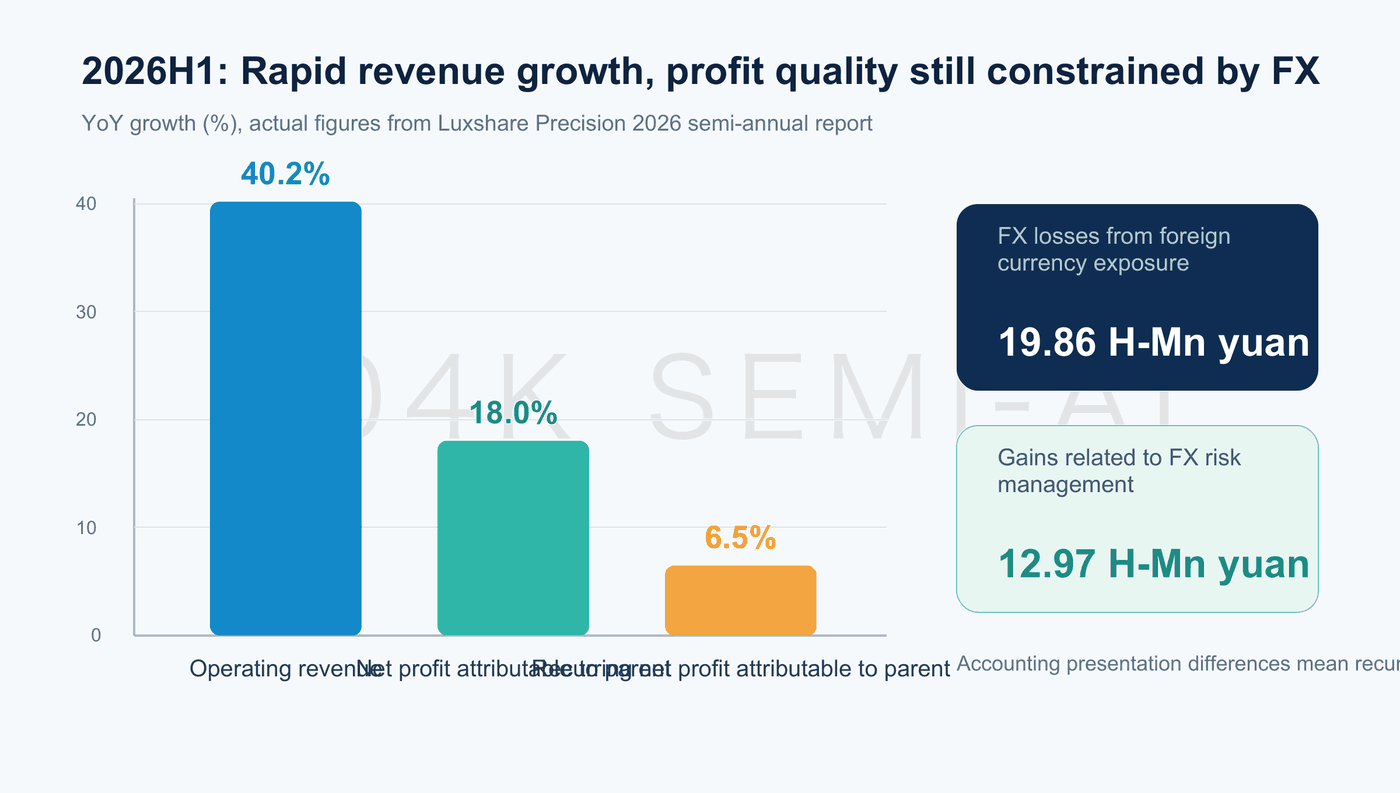
Figure 1: Divergence between top-line and bottom-line growth rates. Source: Luxshare Precision 1H 2026 Interim Report. Data period: 1H 2026.
Gross margins showed no broad-based deterioration. Blended gross margin for 1H 2026 expanded by 17 bps YoY to 11.78%. In Q2, gross margin softened by 30 bps QoQ to 11.6%, matching consensus expectations. The near-term margin pressure stems primarily from product mix, ramp-up costs in nascent divisions, and FX headwinds—rather than structural degradation in core manufacturing capabilities.
2. Consumer Electronics: Anchoring Cash Flow and Baseline Profitability
Consumer electronics generated RMB 122.476 billion in 1H 2026 (+19.27% YoY), accounting for 70.18% of total revenue, with segment gross margin easing 13 bps YoY to 10.25%. Amid muted global smartphone and PC demand, growth was driven by market share gains, new ODM/JDM programs, non-Apple customer expansion, and consolidation effects. While this business sustains plant utilization, supply chain bargaining power, and R&D; funding, it is unlikely to drive significant valuation multiple expansion on its own.
Bernstein forecasts Apple-related revenue to grow at a ~3% CAGR through 2028, compared to >20% for non-Apple consumer electronics. Additional profit upside stems from iPhone assembly at Luxsan, where net margins are projected to expand from 1.3% toward 1.7%, contributing nearly RMB 5.0 billion in adjusted operating profit to Luxshare by 2028. This margin trajectory does not rely on a broad end-market rebound, but rather on yield stability, program scale, and operational cost discipline.
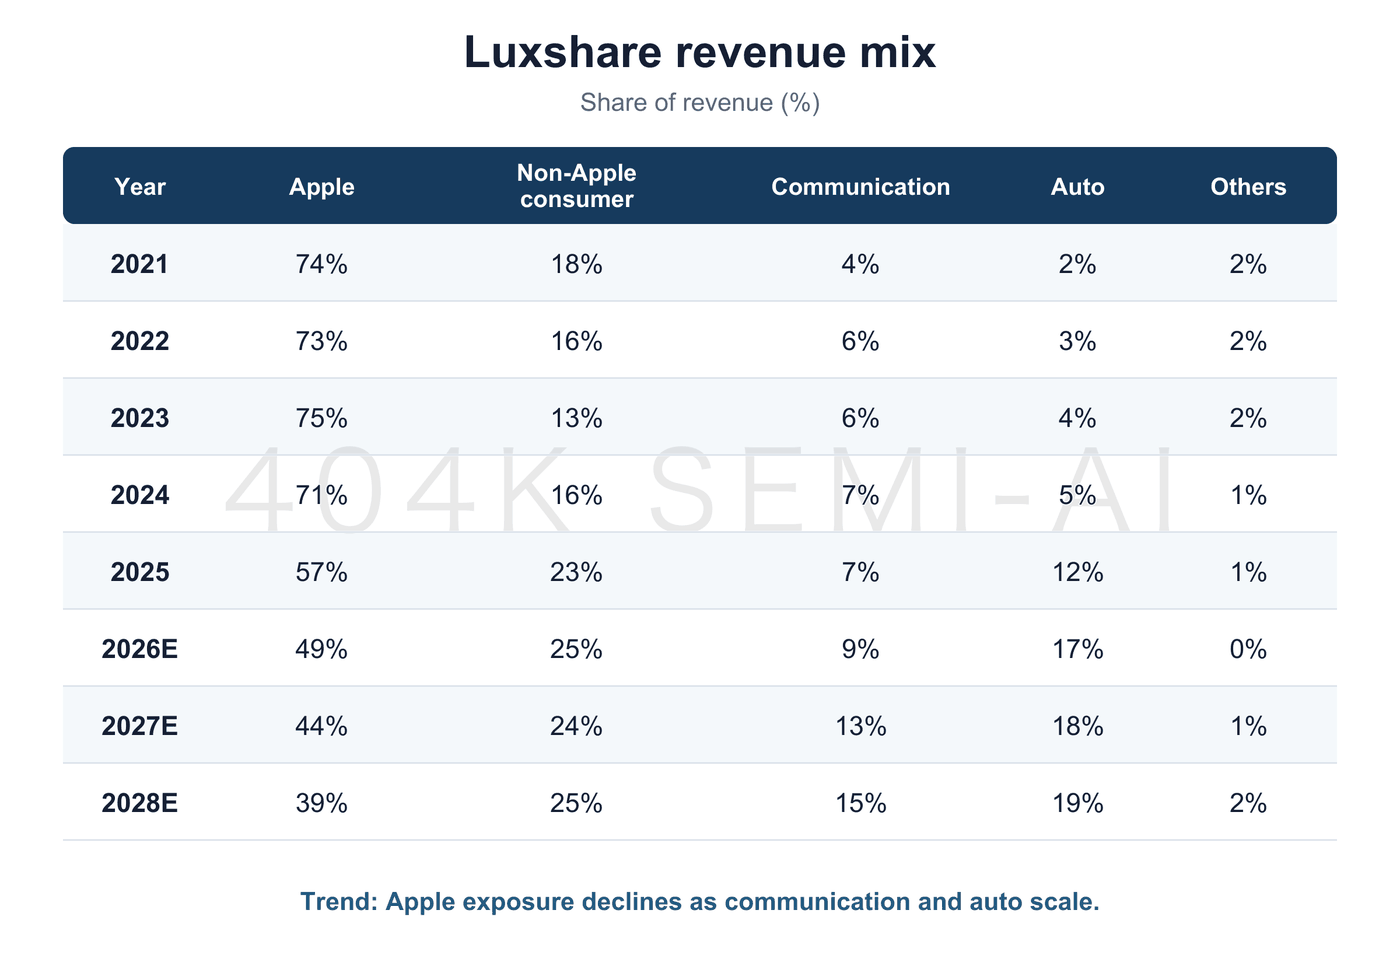
Figure 2: Apple revenue contribution declines as communications and automotive expand. Source: Bernstein. Data period: 2021A-2028E.
As illustrated, Apple's revenue contribution is projected to decline from 74% in 2021 to 39% by 2028, while communications and automotive are expected to rise to 15% and 19%, respectively. This diversification moderates single-customer concentration and product-cycle risk, though it introduces execution challenges around automotive integration, data center certifications, and cross-border operations. The ultimate success of this diversification must be judged by segment margins and free cash flow generation, not merely revenue mix.
3. Communications Segment Accelerates, but Margins Lag
In 1H 2026, communications and data center revenue surged 49.66% YoY to RMB 16.609 billion, increasing its revenue share to 9.52%. However, segment gross margin contracted 248 bps YoY to 17.29%. This divergence between top-line expansion and gross margin indicates that current growth remains diluted by server assembly, lower-margin legacy products, and initial ramp-up costs on new manufacturing lines.
Bernstein outlines a clear re-rating roadmap for the communications segment. Deliveries of copper Cable Cartridge assemblies are slated to commence in Q4 2026, followed by volume shipments of 1.6T optical transceivers in early 2027. By mid-2027, the company aims to operate 10 automated production lines with an aggregate annual capacity of 12 million units. While server assembly provides customer access and operational scale, high-value components—copper interconnects, optical modules, thermal solutions, and power supplies—drive content per box and margin expansion.
