
目录
Executive Summary
First $1 Billion Quarter: The Real Inflection Is Earlier-Than-Expected Margin Delivery
Why the $7.2 Billion GAAP Loss Cannot Be Read at Face Value
Components and Systems Are Accelerating Together, Making Growth More Durable
OCS Is the First Second Growth Engine to Materialize—but It Is Not Yet a De-Risked Platform
Why In-Rack Optics Extends the Growth Cycle Through 2028
Both Banks See Upside—So Why Are Their Price Targets $280 Apart?
Since the Previous Report, How Many of the Five Gates Have Opened?
Six Sets of Publicly Disclosed Numbers to Watch
本内容基于公开资料和研报数据整理,不构成任何投资建议,不代表任何个人观点,仅供学习参考,请理性阅读
Lumentum (NASDAQ: LITE) has surpassed $1 billion in quarterly revenue for the first time, while non-GAAP gross margin reached 50.4%. Near-term growth is now firmly in the numbers. Whether the market can continue pricing in future growth depends on NPO, CPO, and intra-rack optical switching translating into firm orders in 2027–2028.
Executive Summary
Fiscal 4Q26 revenue reached $1.0063 billion, up 24.5% quarter over quarter and 109.3% year over year, marking Lumentum’s first $1 billion quarter. Non-GAAP gross margin was 50.4% and operating margin 36.6%, demonstrating that growth did not come at the expense of profitability.
The midpoint of next quarter’s revenue guidance is $1.25 billion, with a 40% midpoint for non-GAAP operating margin. The revenue model that was originally expected to take 9–12 months has been achieved roughly two quarters early. Components and systems are each expected to contribute approximately 50% of the sequential increase, with growth spanning multiple product lines.
The strongest near-term second growth engine is the optical circuit switching (OCS) business. Quarterly revenue will exceed $100 million for the first time next quarter—and management expects it to be materially higher. Pump-laser output is slated to rise to 4 times its current level over the next several quarters, supported by long-term agreements that are mostly three years in duration and include pricing provisions.
Intra-rack optics remains at the “roadmap established, revenue limited” stage. External laser sources (ELS) have secured an initial order; high-power lasers for CPO/NPO are expected to begin high-volume shipments in 2H27; and intra-rack OCS points to 2028. Existing GPUs/XPUs generally cannot be retrofitted, so adoption must await new chips and rack architectures.
Two investment banks sharply raised their earnings forecasts but reached different conclusions. JPMorgan applies approximately 30 times CY2028 EPS to derive a $1,280 price target. Morgan Stanley applies 25 times approximately $40 of earnings power to reach $1,000—and wants to see a firm NPO contract first. The core disagreement is how much the longer-dated opportunity should be worth today.
First $1 Billion Quarter: The Real Inflection Is Earlier-Than-Expected Margin Delivery
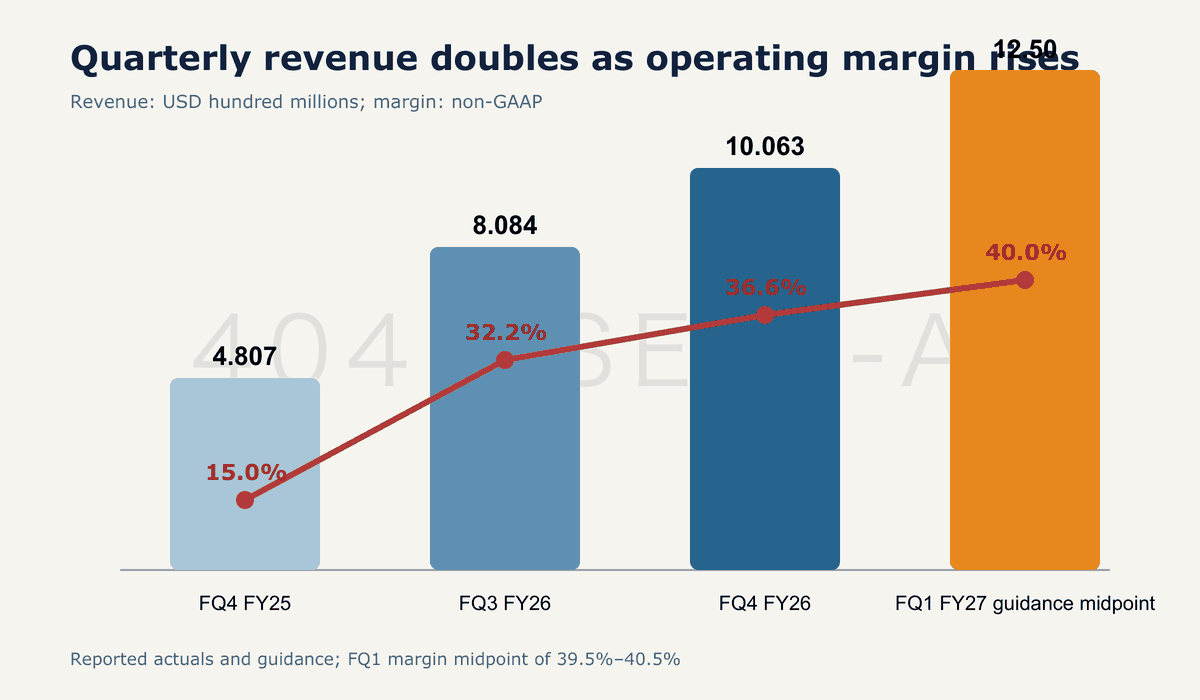
Lumentum reported quarterly revenue of $1.0063 billion, slightly above the midpoint of its $0.960 billion–$1.01 billion guidance, while lifting non-GAAP gross margin to 50.4% and operating margin to 36.6%. Versus a year earlier, revenue rose 109.3% and operating margin expanded by 2,160 basis points. Sequentially, revenue increased 24.5% and operating margin improved by 440 basis points. Non-GAAP EPS of $3.23 also exceeded the upper end of the company’s $2.85–$3.05 guidance range.
The central change is that margins have reached their targets well ahead of revenue. Management’s previous framework called for non-GAAP gross margin to exceed 50% only as quarterly revenue approached $2 billion, with operating margin at approximately 38%–42%. Revenue is currently only half that longer-term level, yet gross margin has already crossed the threshold. The 40% midpoint of next quarter’s operating-margin guidance also sits squarely within the prior model’s target range. On the earnings call, management further indicated that the future operating-margin framework should treat 42% as closer to the midpoint, effectively raising the long-term margin platform by approximately 100–200 basis points.
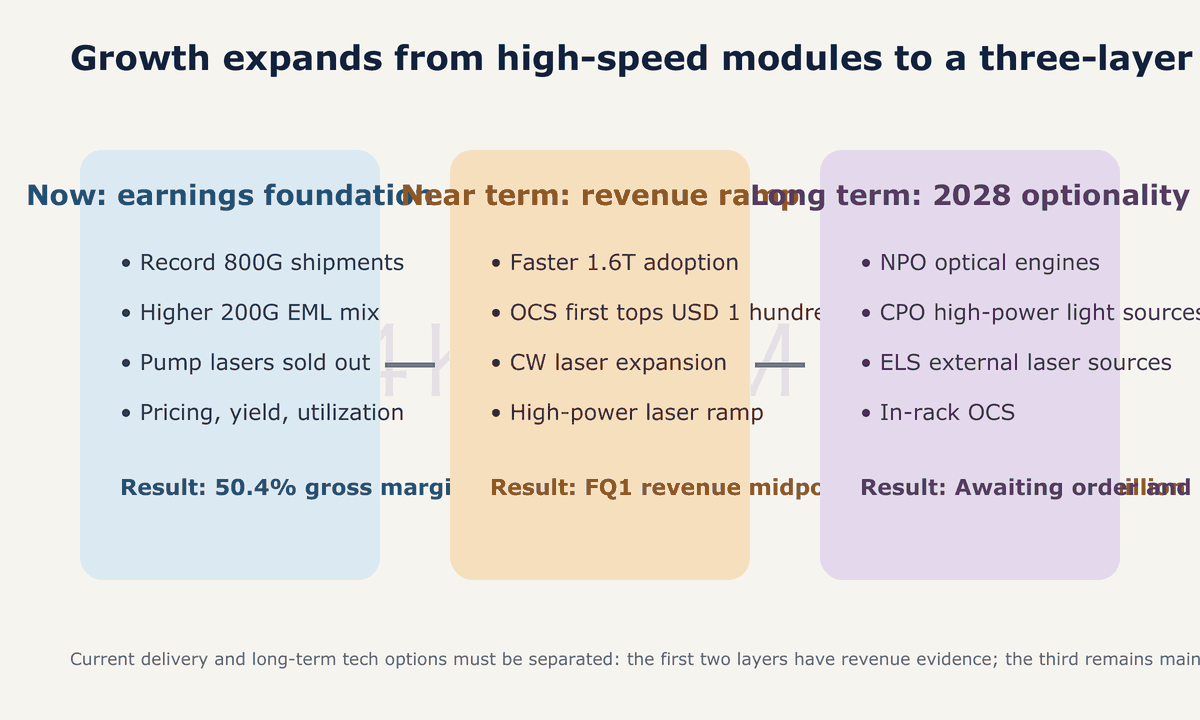
Pricing alone does not explain the improvement. 800G modules and 100G-per-lane EMLs remain the primary shipment drivers, while 200G-per-lane EMLs now account for more than 25% of EML revenue. Pump lasers remain sold out; 1.6T products carry higher average selling prices; optical-module yields and capacity utilization continue to improve; and OCS is ramping faster than previously expected. The combination of pricing, mix, yields, and fixed-cost absorption is producing operating leverage in which earnings grow faster than revenue.
Guidance for the next quarter reinforces that conclusion: revenue of $1.225 billion–$1.275 billion, implying approximately 24% sequential growth at the midpoint; non-GAAP operating margin of 39.5%–40.5%; and EPS of $4.05–$4.35. At the midpoint, EPS would increase by another approximately 30% sequentially. A one-off pull-forward of shipments would struggle to explain simultaneous, sustained acceleration in revenue, margins, and EPS.
Why the $7.2 Billion GAAP Loss Cannot Be Read at Face Value
The company reported a GAAP net loss of $7.1617 billion, or $84.65 per share, seemingly at odds with its strong operating performance. The key reconciliation in the official income statement is a $7.7566 billion one-time, non-cash debt-extinguishment loss related to the conversion of certain convertible notes into equity. Before this capital-structure accounting impact, quarterly GAAP operating income was still $279.3 million. Non-GAAP net income was $326.3 million, or $3.23 per share.
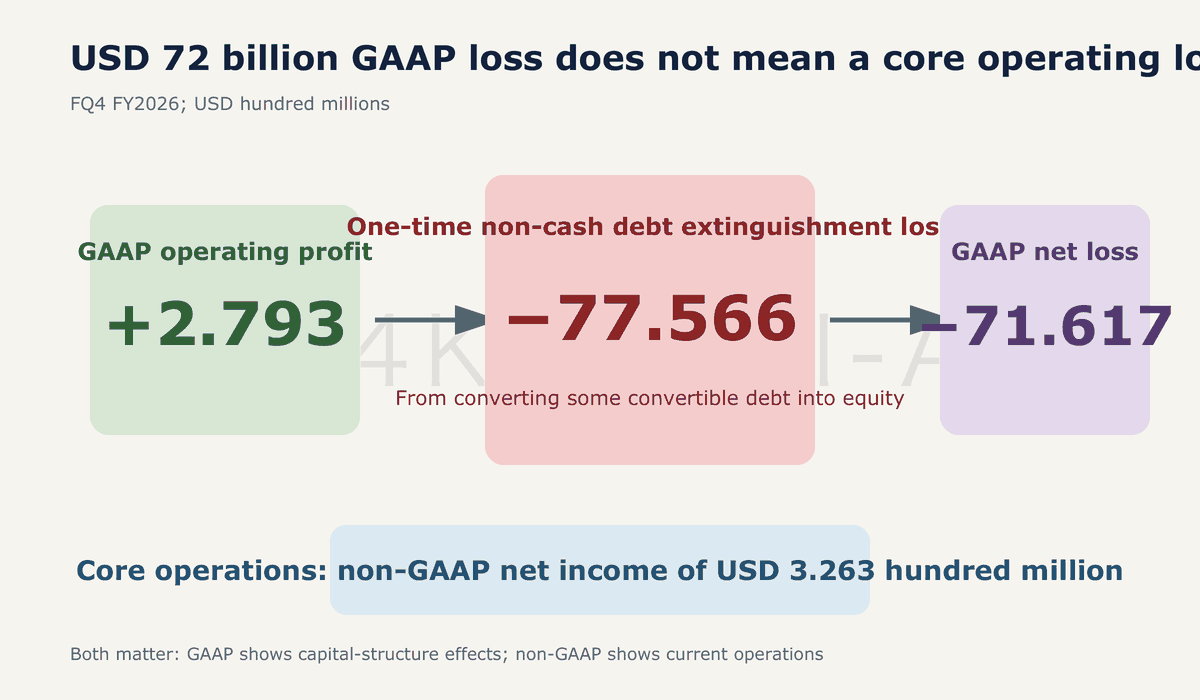
This does not mean GAAP figures can be ignored. The debt-to-equity conversion reduced debt by approximately $1.1 billion but also increased potential equity dilution. The official non-GAAP diluted share count was 101.1 million, materially above the 84.60 million shares used for the GAAP loss calculation. The accounting treatment of common and preferred shares, convertible notes, and capped-call transactions on the balance sheet will all affect future EPS. The correct interpretation is that the core business was clearly profitable this quarter and that a $7.1617 billion non-cash accounting event was the primary driver of the net loss—but the capital-structure changes and dilution remain real costs.
Cash flow also shows that reported profit does not yet translate into effortless cash generation. FY2026 revenue was $3.014 billion and non-GAAP net income was $782.3 million, but the official cash-flow statement showed approximately negative $19 million of operating cash flow and $411.5 million of capital expenditures.
Cash and short-term investments totaled approximately $2.7 billion at quarter-end, up approximately $1.9 billion from the end of the prior fiscal year, primarily reflecting financing and capital-structure changes. Meanwhile, accounts receivable increased from $250 million to $520.3 million, and inventories rose from $470.1 million to $691.6 million. Lumentum is deploying working capital and capital expenditure to secure capacity, so cash-conversion quality must be assessed alongside margins.
Components and Systems Are Accelerating Together, Making Growth More Durable
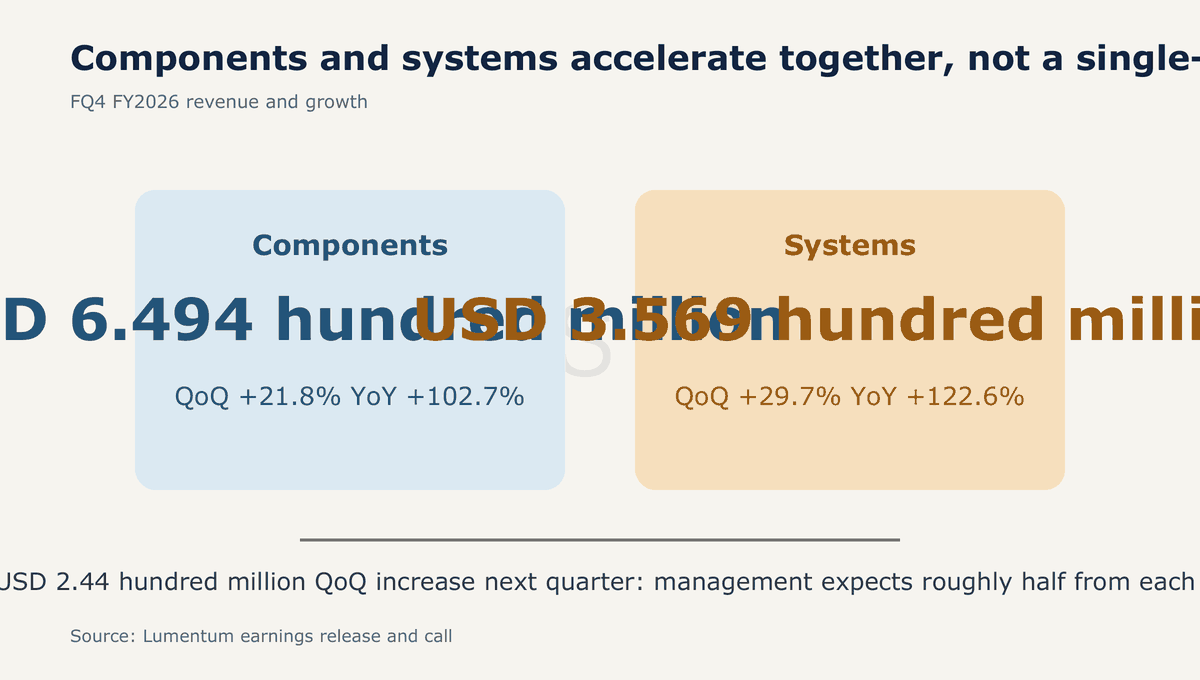
Components revenue was $649.4 million, representing 64.5% of total revenue and increasing 21.8% sequentially and 102.7% year over year. Systems revenue was $356.9 million, or 35.5% of total revenue, up 29.7% sequentially and 122.6% year over year. Of the approximately $244 million sequential revenue increase expected next quarter, management anticipates roughly half will come from components and half from systems, with the latter driven primarily by 1.6T transceivers and OCS.
Within components, EMLs and continuous-wave lasers (CW lasers) are no longer a simple substitution trade-off. In the 1.6T generation, silicon-photonics architectures will increase demand for CW lasers. By shrinking die sizes and improving efficiency and specification consistency, Lumentum has brought CW-laser margins significantly closer to EML margins; both are above the corporate average. Meanwhile, 200G-per-lane EMLs now account for more than 25% of EML revenue, but the company does not expect them to exceed 50% of shipment volume until mid-2027. The EML upgrade cycle therefore remains in its first half rather than approaching a peak.
Supply constraints remain significant. Lumentum expects EML unit shipments to grow by more than 50% year over year by December 2026, yet supply is still expected to trail demand at that point. Demand for high-power lasers is also rising faster than planned capacity additions. Over the past 3 months, the company added AXT as an indium-phosphide substrate supplier, keeping near-term supply manageable. However, management acknowledged that if the demand trajectory persists, additional suppliers may be needed within one or two quarters. This underpins pricing power but also represents the most immediate execution risk.
Pump lasers offer a different form of visibility. Fiscal fourth-quarter shipments increased by more than 80% year over year, market share stood at approximately 70%–80%, and output is planned to expand to 4 times its current level over the next several quarters. Unlike unconstrained demand forecasts, this ramp is supported by long-term agreements with multiple networking-equipment vendors. Most contracts run for 3 years, many include take-or-pay and price-adjustment provisions, and customers are also sharing part of the capital expenditure required for expansion. This provides a firmer demand foundation for capacity investment, although it does not eliminate risks related to equipment installation, packaging and testing, or yield ramp-up.
OCS Is the First Second Growth Engine to Materialize—but It Is Not Yet a De-Risked Platform
Optical circuit switching (OCS) reconfigures GPU clusters through optical paths rather than continuous optical-electrical conversion, reducing power consumption and enabling reconfigurable network topologies. Lumentum’s internally manufactured OCS shipments doubled sequentially in the fiscal fourth quarter. OCS revenue will exceed $100 million for the first time next quarter, with management emphasizing that it will be “significantly above” that level. The target of more than $400 million in OCS revenue in the second half of 2026 remains on track.
This business matters because it moves Lumentum beyond optical components and into the network-control layer. The company is shipping to multiple customers and developing higher-port-count, lower-port-count, and entry-level products. Although one major customer retains an internal OCS source, Lumentum expects to surpass that source and become the customer’s largest supplier in early 2027. It has also begun expanding through contract manufacturing to address early supply-chain constraints.
At least three uncertainties remain. First, management said the $400 million half-year target was “on track,” not materially ahead of plan. Second, the largest customer still has in-house production capability, and expected share gains have yet to become a confirmed outcome. Third, in-rack OCS for scale-up architectures requires substantial redesign, with the real opportunity emerging in 2028. Revenue above $100 million in the near term is verifiable; the 2028 in-rack opportunity remains a design option. The two should not be conflated.
Why In-Rack Optics Extends the Growth Cycle Through 2028
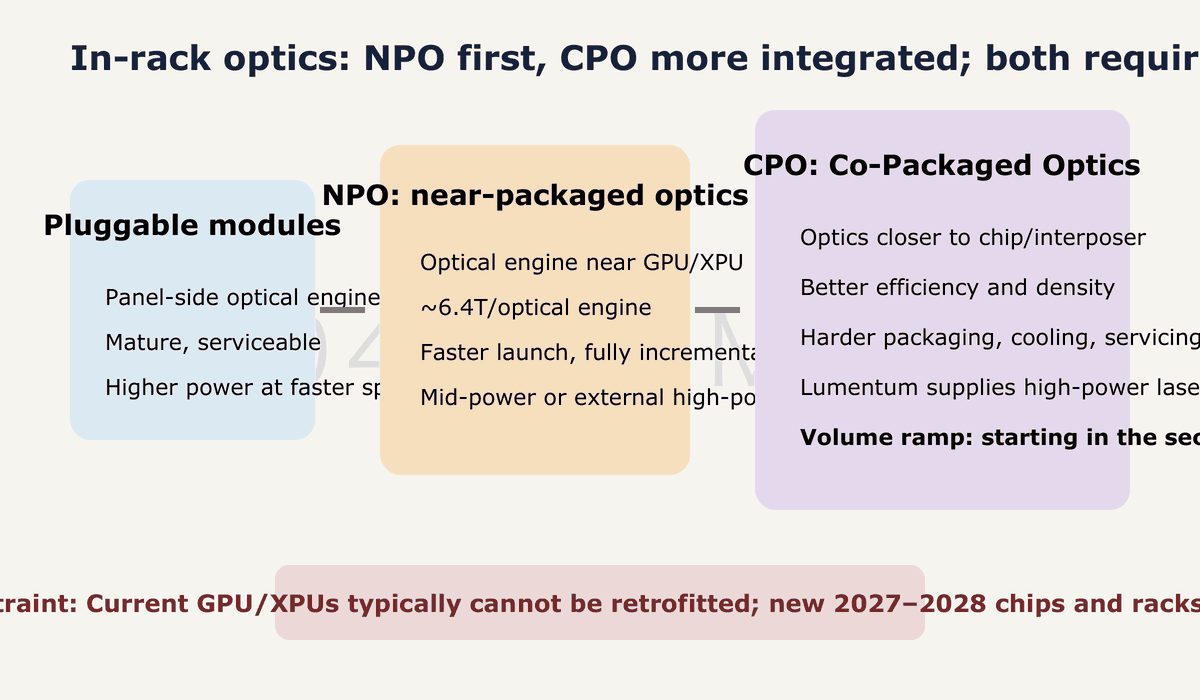
Today, optical interconnects in data centers are used primarily between racks. As bandwidth and power requirements rise across GPU/XPU clusters, optics are moving inside the rack and even closer to the chip package. Near-packaged optics (NPO) places optical engines on the board near the GPU/XPU. Co-packaged optics (CPO) integrates optics more tightly near the substrate or interposer, delivering greater energy efficiency but adding complexity in packaging, thermal management, and servicing.
Management’s roadmap is that “NPO will arrive sooner, while CPO remains the more comprehensive end state.” A single NPO optical engine provides approximately 6.4T of bandwidth, equivalent to 4 1.6T modules. It can use either integrated medium-power lasers or high-power lasers housed in external laser source (ELS) modules. Lumentum covers approximately 120, 150, and 400 mW products, which share common designs and processes and therefore allow the company to participate across multiple architectures.
The current evidence falls into three tiers. First, plans at the largest CPO customer remain on track, with stronger demand signals. Second, Lumentum has secured its first ELS module order, with delivery planned for the second half of 2027. Third, leading NPO programs are also expected to begin around the second half of 2027, with better visibility for the high-power approach than for integrated medium-power lasers. ELS modules carry substantially higher selling prices than standalone laser chips, with gross margins above the company average but below those of discrete lasers—trading slightly lower unit margins for a much larger revenue opportunity.
The binding constraint is system architecture. Existing GPUs/XPUs/TPUs generally cannot be retrofitted directly for NPO or CPO; deployment requires new chip and rack designs arriving between mid-2027 and early 2028. Customer engagement, samples, or initial orders therefore cannot be counted prematurely as 2026 revenue. The hard evidence investors need is contract value, customer count, mass-production yields, and actual shipments in the second half of 2027.
Both Banks See Upside—So Why Are Their Price Targets $280 Apart?
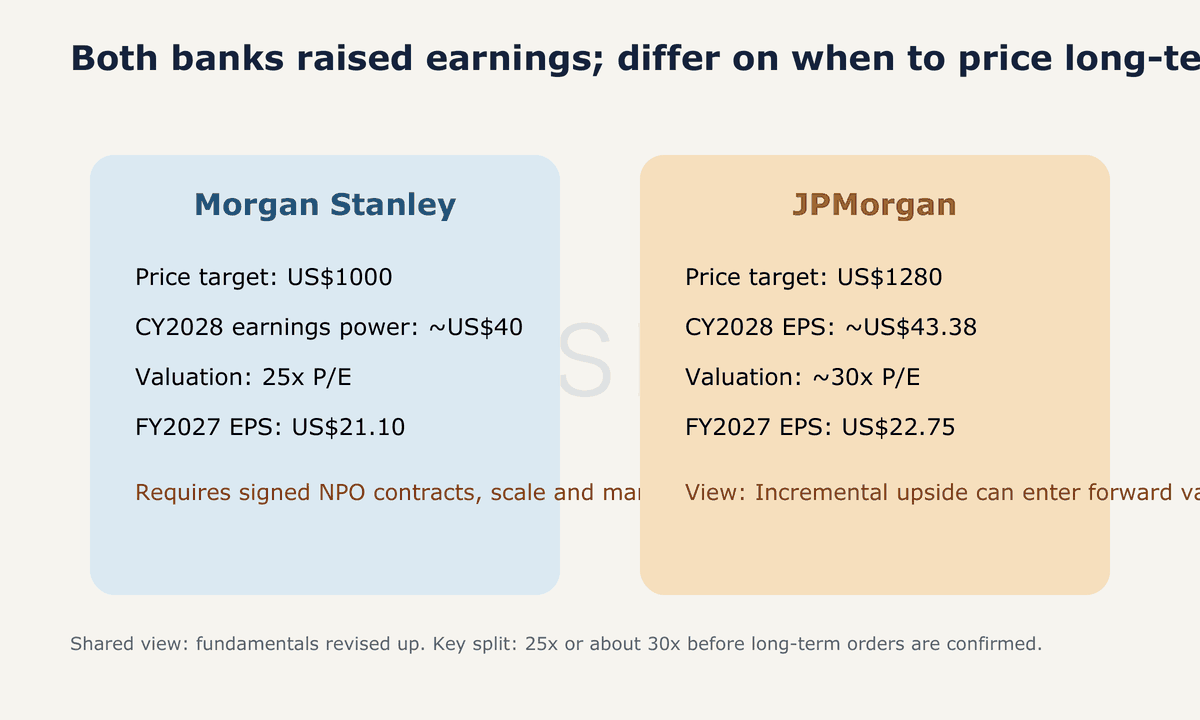
JPMorgan and Morgan Stanley are largely aligned on the operating outlook. JPMorgan raised its FY2027 revenue and adjusted EPS forecasts to $6.36 billion and $22.75, respectively, with FY2028 estimates of $9.774 billion and $37.00.
Morgan Stanley forecasts FY2027 revenue of $6.224 billion and EPS of $21.10, followed by $10.027 billion and $34.64 in FY2028. Both expect rapid revenue growth and continued margin expansion, and both extrapolate this quarter’s gross-margin performance into the longer term.
The divergence has two main dimensions. The first is margin intensity. JPMorgan forecasts an FY2028 adjusted operating margin of 46.5%, rising to 48.3% in FY2029—above management’s long-term framework of 40% to 44% as cited by the bank. Morgan Stanley projects 43.8% and 45.2% for FY2028 and FY2029, respectively: still bullish, but closer to management’s range. The second is how much future earnings the market should capitalize before orders are confirmed. JPMorgan derives its $1,280 target from approximately $43.38 in CY2028 EPS and an earnings multiple of approximately 30x. Morgan Stanley applies a 25x multiple to approximately $40 of CY2028 earnings power to reach $1,000.
Morgan Stanley’s caution does not reflect low earnings estimates. Its FY2027 revenue, EBITDA, and EPS forecasts were all above the prevailing consensus, yet it maintained an Equal-weight rating because its base case already assumes simultaneous ramps across EML, OCS, CPO, and other businesses. In its view, the next information capable of materially resetting market pricing would be a formal NPO contract, including its scale, timing, and margin profile. JPMorgan is more willing to incorporate CW lasers, ELS, NPO, and in-rack OCS into its long-term framework ahead of formal awards.
The two valuation frameworks can be reduced to one sentence: the $1,000 case requires “contracts before multiple,” while the $1,280 case allows investors to assign part of the multiple based on technology positioning and demand signals. These are two sets of assumptions that subsequent evidence can test. If formal NPO programs, multi-customer OCS adoption, and high-power lasers materialize on schedule, the higher multiple becomes easier to justify. If technology transitions slip, EML supply-demand conditions loosen earlier than expected, or customers increase internal production, both earnings and valuation multiples could be revised lower.
Since the Previous Report, How Many of the Five Gates Have Opened?
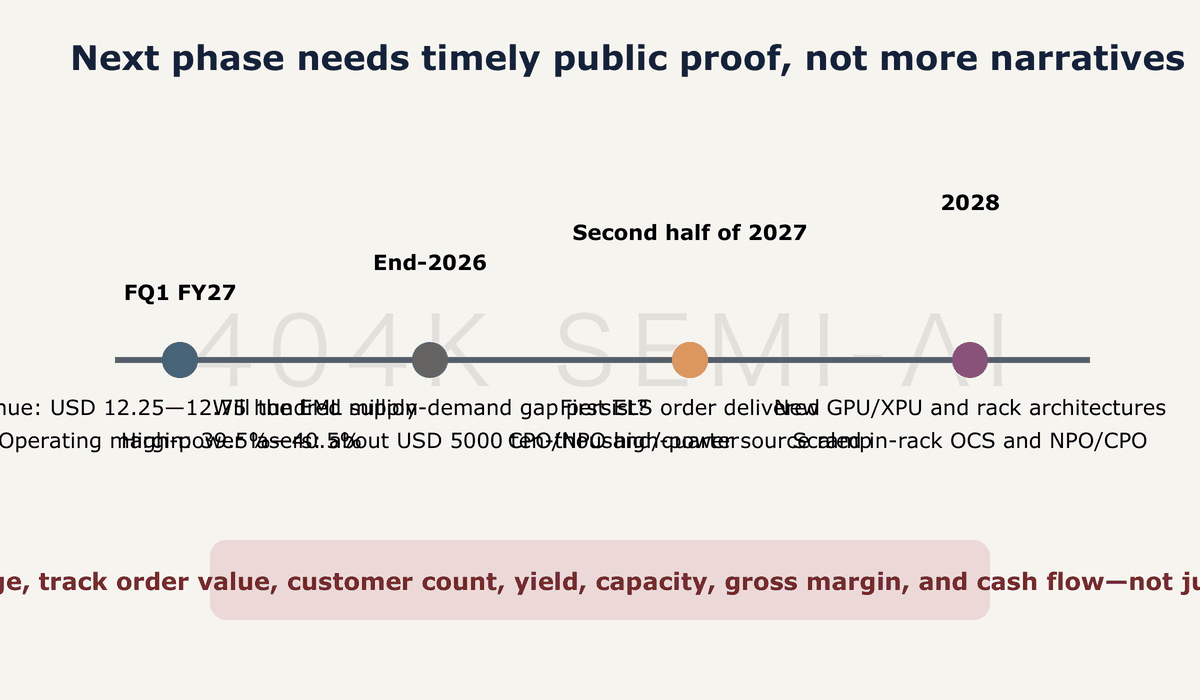
The previous in-depth Lumentum report organized the validation framework around five gates: quarterly revenue, 1.6T, EML/InP, OCS, and CPO/ELS. This quarter’s results have opened the first three and a half.
The quarterly-revenue gate is fully open: revenue exceeded $1 billion for the first time, and next-quarter guidance points to a midpoint of $1.25 billion. The 1.6T gate has entered the delivery phase: products are already shipping and will accelerate in the first quarter of FY2027, although management has not disclosed when 1.6T will surpass 800G. The EML/InP gate remains strong: the 200G mix is rising, year-end unit volumes are expected to grow more than 50% year over year, and shortages have not eased. The counterpoint is that Lumentum has proactively added substrate suppliers, indicating that the shortage is also constraining deliveries.
The OCS gate is mostly open. Next quarter’s first-ever revenue above $100 million will constitute financial-statement-level evidence, while multi-customer adoption and contract-manufacturing expansion are also progressing. However, the major customer’s internal source and the 2028 in-rack design opportunity still require validation. The CPO/ELS gate is only slightly open: the first ELS order and stronger demand signals are encouraging, but large-scale revenue will not arrive until the second half of 2027.
This quarter therefore advances the Lumentum thesis from “AI optical demand is very strong” to “that demand can convert into high-margin revenue.” It does not yet prove that in-rack optics will succeed in 2028. Over the next several quarters, investors must determine whether the NPO and CPO opportunities not yet reflected in reported results convert into orders, revenue, and cash flow on schedule.
Six Sets of Publicly Disclosed Numbers to Watch
First, whether Lumentum can deliver first-quarter FY2027 revenue within the $1.225 billion to $1.275 billion range while maintaining a non-GAAP operating margin of 39.5% to 40.5%. Second, after quarterly OCS revenue exceeds $100 million, whether the company also discloses customer count, supply share, and gross margin—instead of relying solely on volume growth from one customer.
Third, whether the per-channel 200G EML mix, internal CW utilization, and EML lead times continue to support gross margins above 50%. If incremental capacity qualifies earlier, pricing and mix could weaken before revenue does. Fourth, whether the 4x expansion in pump-laser capacity materializes under long-term agreements, and whether customers’ capital-expenditure contributions reduce cash pressure.
Fifth, whether quarterly high-power laser revenue can approach the approximately $50 million cited by management by the end of 2026 and exceed $100 million for the first time in the third quarter of FY2027. Sixth, whether ELS, NPO, and CPO produce verifiable order values, shipments, and customer breadth in the second half of 2027.
Lumentum’s greatest strength today is that near-term profitability has already exceeded its previous targets. Its greatest vulnerability is that long-dated valuation expectations are running ahead of formal orders. As long as OCS, 1.6T, and high-margin lasers continue converting $1.25 billion in quarterly revenue into an operating margin above 40%, the 2028 options have time to mature. Conversely, if margins retreat, cash flow remains negative, or in-rack architectures are delayed, the market will compress the multiple first and wait for the long-term thesis to re-establish its credibility.
Related Reading
Microsoft FY2026 Q4 Deep Dive: Azure Growth Rises to 43%, Cloud Gross Margin Falls to 65%