
Longsys Deep-Dive Update: How Morgan Stanley's RMB673 Target Price, AI NAND Shortage, and TCM Model Revalue Its Enterprise SSD Platform
目录
Too Long; Didn’t Read
I. RMB673 Target Price: What Exactly Did Morgan Stanley Change?
II. Why the Target Price Can Jump from RMB300 to RMB673
III. Product-Line Breakdown: The Upgrade Is Not a Single-Category Bet
IV. 2027E EPS Is the Core of the RMB673 Valuation
V. Why Morgan Stanley Prefers Original Manufacturers, While Still Upgrading Longsys
VI. Cash Flow and Inventory: The Hard Constraints Behind High Profit
VII. The Rating Remains Equal-weight: Morgan Stanley Has Not Made Longsys a Top Pick
VIII. Valuation Methodology: RMB673 Is Not Simply a High P/E Multiple
IX. AI NAND Shortage Is the Primary Driver of Upward Revisions
X. Cross-Checks From the Past Week: Morgan Stanley Is Not the Only One Revising NAND Upward
XI. Longsys' Advantage: Not an Ordinary Low-Cost Inventory Module Maker
XII. Why the TCM Model Has Become the Core of the Model
XIII. Enterprise SSD Is the Main Battleground for Whether the Valuation Holds
XIV. Self-Developed Controllers: Gross-Margin Protection, Not a Universal Answer
XV. The Consumer End Is Not the Core Logic; It Is Instead a Source of Risk
XVI. 2028 Supply Risk: Yangtze Memory Is a Variable, Not Only a Positive
XVII. Bull-Bear Scenarios: RMB 673 Is Not the Most Optimistic Target Price
18. Differences Versus the Previous Longsys Deep Dive
19. How to Understand This Upgrade Near the Current Share Price
20. Four Tracking Indicators
21. Bottom-Line Judgment: Validate Delivery First, Then Discuss the Valuation Ceiling
22. Conclusion: The RMB673 Target Price Is Longsys’s New Threshold
本内容基于公开资料和研报数据整理,不构成任何投资建议,不代表任何个人观点,仅供学习参考,请理性阅读
Morgan Stanley raised its Longsys target price from RMB300 to RMB673. The real change is not a short-term price-hike assumption, but the incorporation of the 2027 NAND shortage, TCM model, enterprise SSD platform capability, and 2028 supply discipline into the earnings base. It also shifts the market focus from memory price increases to whether EPS can be delivered.
Too Long; Didn’t Read
Morgan Stanley is not making a minor model tweak this time; it is rewriting Longsys’s earnings peak. The target price more than doubles to RMB673, mainly because EPS over the next three years has been systematically lifted. 2027E EPS of RMB42.62 becomes the valuation anchor, implying roughly 15.8x P/E.
A target-price increase does not mean a rating upgrade. Morgan Stanley still rates Longsys Equal-weight because the current share price already discounts substantial NAND upside expectations, and Morgan Stanley prefers original manufacturers over module makers. Longsys’s opportunity lies in a re-rating of its earnings base; its risks lie in shipment volume, inventory, and 2028 supply discipline.
The first pillar of the model upgrade is the AI NAND shortage. Morgan Stanley expects AI-related NAND demand to rise from 205EB in 2025 to 609EB in 2027, with its share of total NAND demand rising from 18% to 41%. Goldman Sachs on Kioxia, Citi on SanDisk, and Korean memory price trackers have all provided evidence in the same direction over the past week. Industry tightness is not an isolated model output.
The second pillar is the TCM model and in-house controllers. Longsys is not merely a traditional module maker that hoards low-cost inventory and resells it. TCM transfers part of the inventory burden to customers, while in-house controller and firmware capabilities raise the value of customized services. This explains why Morgan Stanley lifted its long-term gross-margin assumption from about 18% to the 25%-38% range.
The largest debate is 2028. If AI SSD demand continues to grow rapidly and original manufacturers maintain supply discipline, Longsys can scale enterprise SSDs, in-house controllers, and the Lexar brand into platform assets. If new capacity from YMTC and others ramps too quickly, NAND may shift from shortage to surplus, making Longsys’s high EPS look more like a cyclical peak.
Four numbers now need tracking for Longsys: whether 2026 gross margin can approach Morgan Stanley’s new 55% assumption; whether enterprise storage can continue to grow faster than the company overall; whether inventory and operating cash flow can improve from the high-pressure state in 1Q26; and whether 2027 long-term contract pricing can remain supportive after consumer-end price increases slow.
I. RMB673 Target Price: What Exactly Did Morgan Stanley Change?
The most eye-catching number in Morgan Stanley’s update on Longsys is the target-price increase from RMB300 to RMB673. The scale is too large to be explained simply as “memory prices are rising, so the target price is higher.” The real point is that Morgan Stanley has rewritten Longsys’s earnings cycle from a brief price rebound into a NAND profit re-rating that lasts at least until 2027.
More precisely, this upgrade has three layers.
First, 2026 earnings are no longer just inventory gains. They are treated as a super-profit year driven jointly by the AI NAND shortage, consumer-end price catch-up, and product mix. Morgan Stanley raised Longsys’s 2026E revenue to RMB65.852bn, net profit to RMB23.974bn, and EPS to RMB59.86. This is already far above the company’s full-year 2025 net profit attributable to shareholders of RMB1.423bn, meaning the model treats 2026 as a very steep segment of the memory upcycle.
Second, 2027 is no longer treated as the starting point of a cyclical decline. Morgan Stanley had previously been more concerned about a downturn beginning in 2H27. It now pushes the downturn to 2H28 and raises 2027E EPS to RMB42.62. The RMB673 target price is essentially priced around this 2027E EPS, equal to about 15.8x 2027E P/E.
Third, 2028 remains clearly contested. Morgan Stanley does not write 2028 as a year of certain continued strength. Instead, it leaves the question to supply discipline: if AI NAND continues to absorb new capacity, Longsys’s profit platform can be sustained; if new Chinese capacity comes online faster than AI demand, NAND prices will fall again and Longsys will return to a cyclical-stock framework.
Longsys Deep Dive: From Storage Modules to an Enterprise SSD Platform, and How the AI NAND Upcycle Revalues Controllers and Brand Assets
This also explains why Morgan Stanley sharply raised the target price while keeping the rating at Equal-weight. The model has become more optimistic, but the price already reflects part of that optimism. Longsys still has re-rating potential, but the re-rating has entered a phase with a high delivery bar.
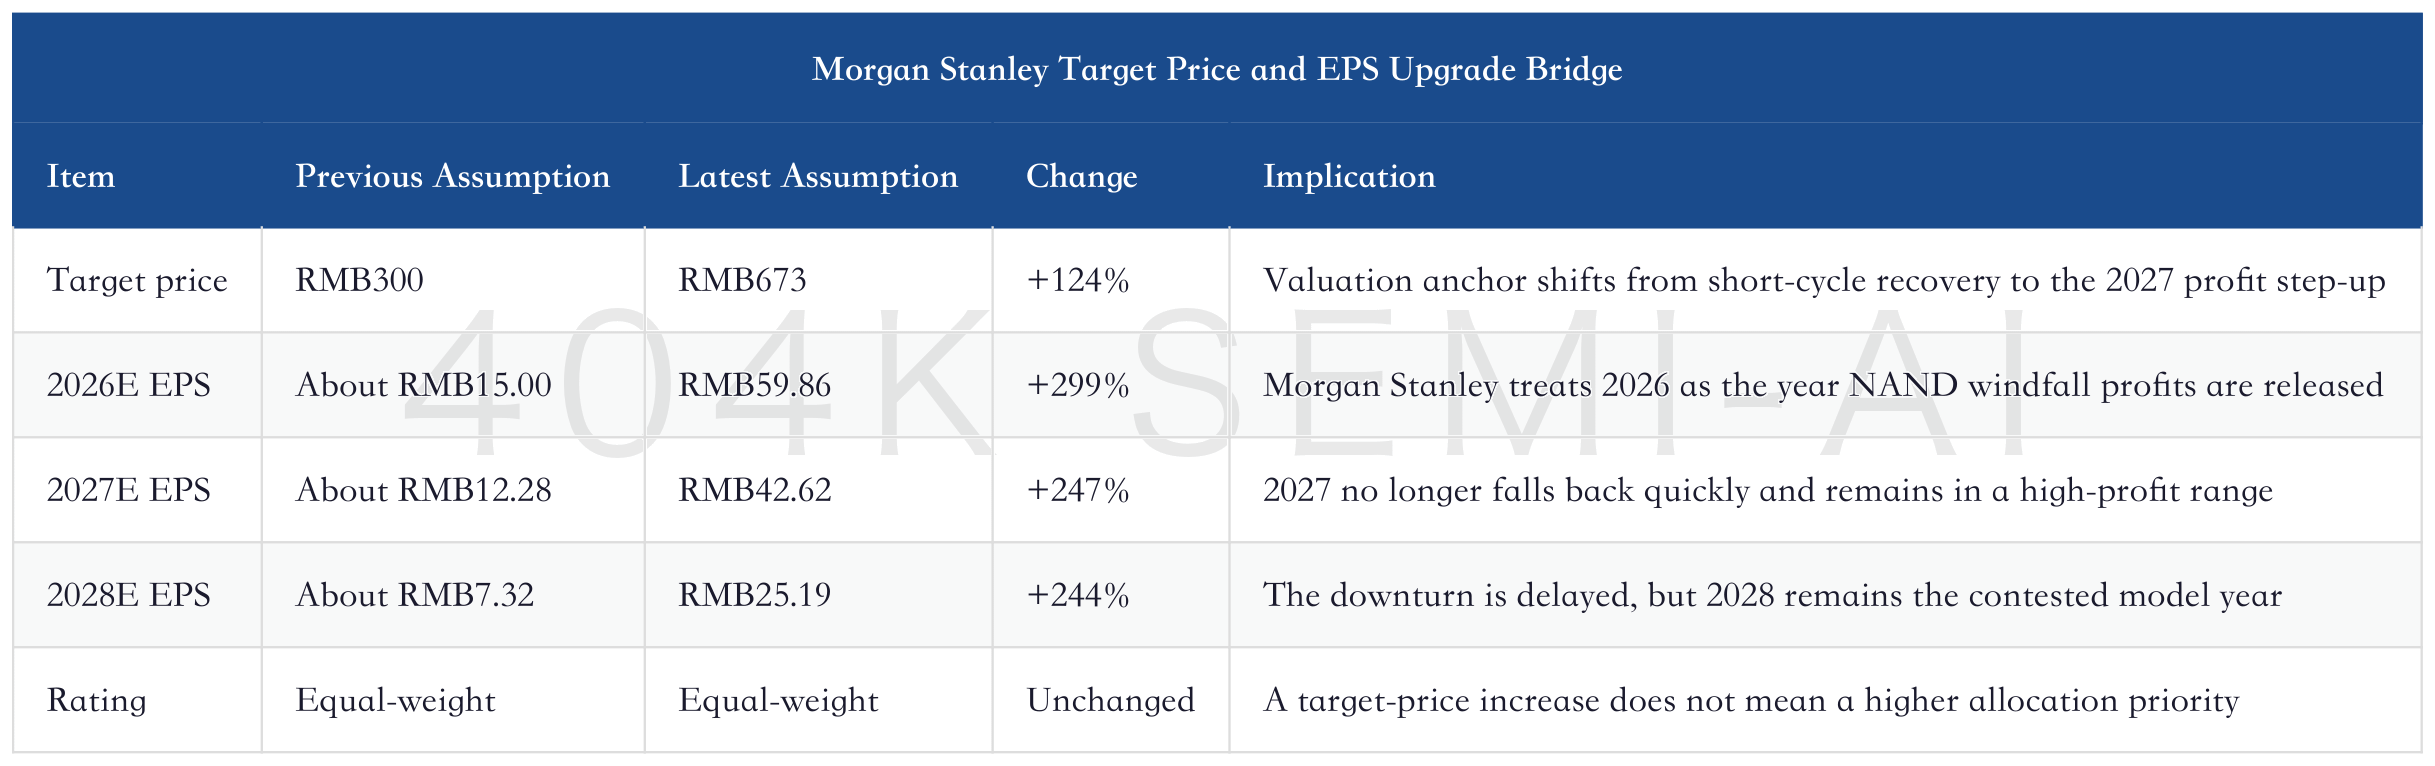
The most important figure in this table is not the target price itself, but 2027E EPS. If RMB42.62 is achievable, RMB673 is not expensive. If 2026 is the cyclical peak and inventory and pricing pressure arrive earlier in 2027, RMB673 becomes a very high delivery hurdle.
II. Why the Target Price Can Jump from RMB300 to RMB673
Morgan Stanley’s target-price increase mainly comes from rewriting three assumptions: higher revenue, higher gross margin, and a later earnings downturn.
On revenue, almost all of Longsys’s core products were revised upward. Embedded storage, mobile storage, SSDs, and memory modules all benefit from NAND price revaluation in 2026-2027. In the past, the market viewed Longsys as “storage modules plus branded channels”: revenue elasticity was strong, but gross margin and cash flow were easily consumed by the inventory cycle. This time, Morgan Stanley is more willing to view the company as a storage platform supported by enterprise SSDs, in-house controllers, TCM, and brand capabilities.
The gross-margin revision is more aggressive. Morgan Stanley raised Longsys’s 2026E gross margin to 55%, with 2027E at 35% and 2028E still at 27%. The implication is that Longsys is not merely using low-cost inventory to capture one round of price increases, but has some profit protection from customer structure, product mix, and transaction model.
On the profit cycle, Morgan Stanley pushed downside pressure from 2027 to 2028. Previously, it was easy to reach a simple conclusion on Longsys: when memory prices rise, earnings elasticity is very high; when memory prices fall, inventory and gross margin are both hurt. The new model becomes: windfall profits in 2026, still high levels in 2027, and only in 2028 does the market truly test whether supply expansion and AI demand can remain matched.
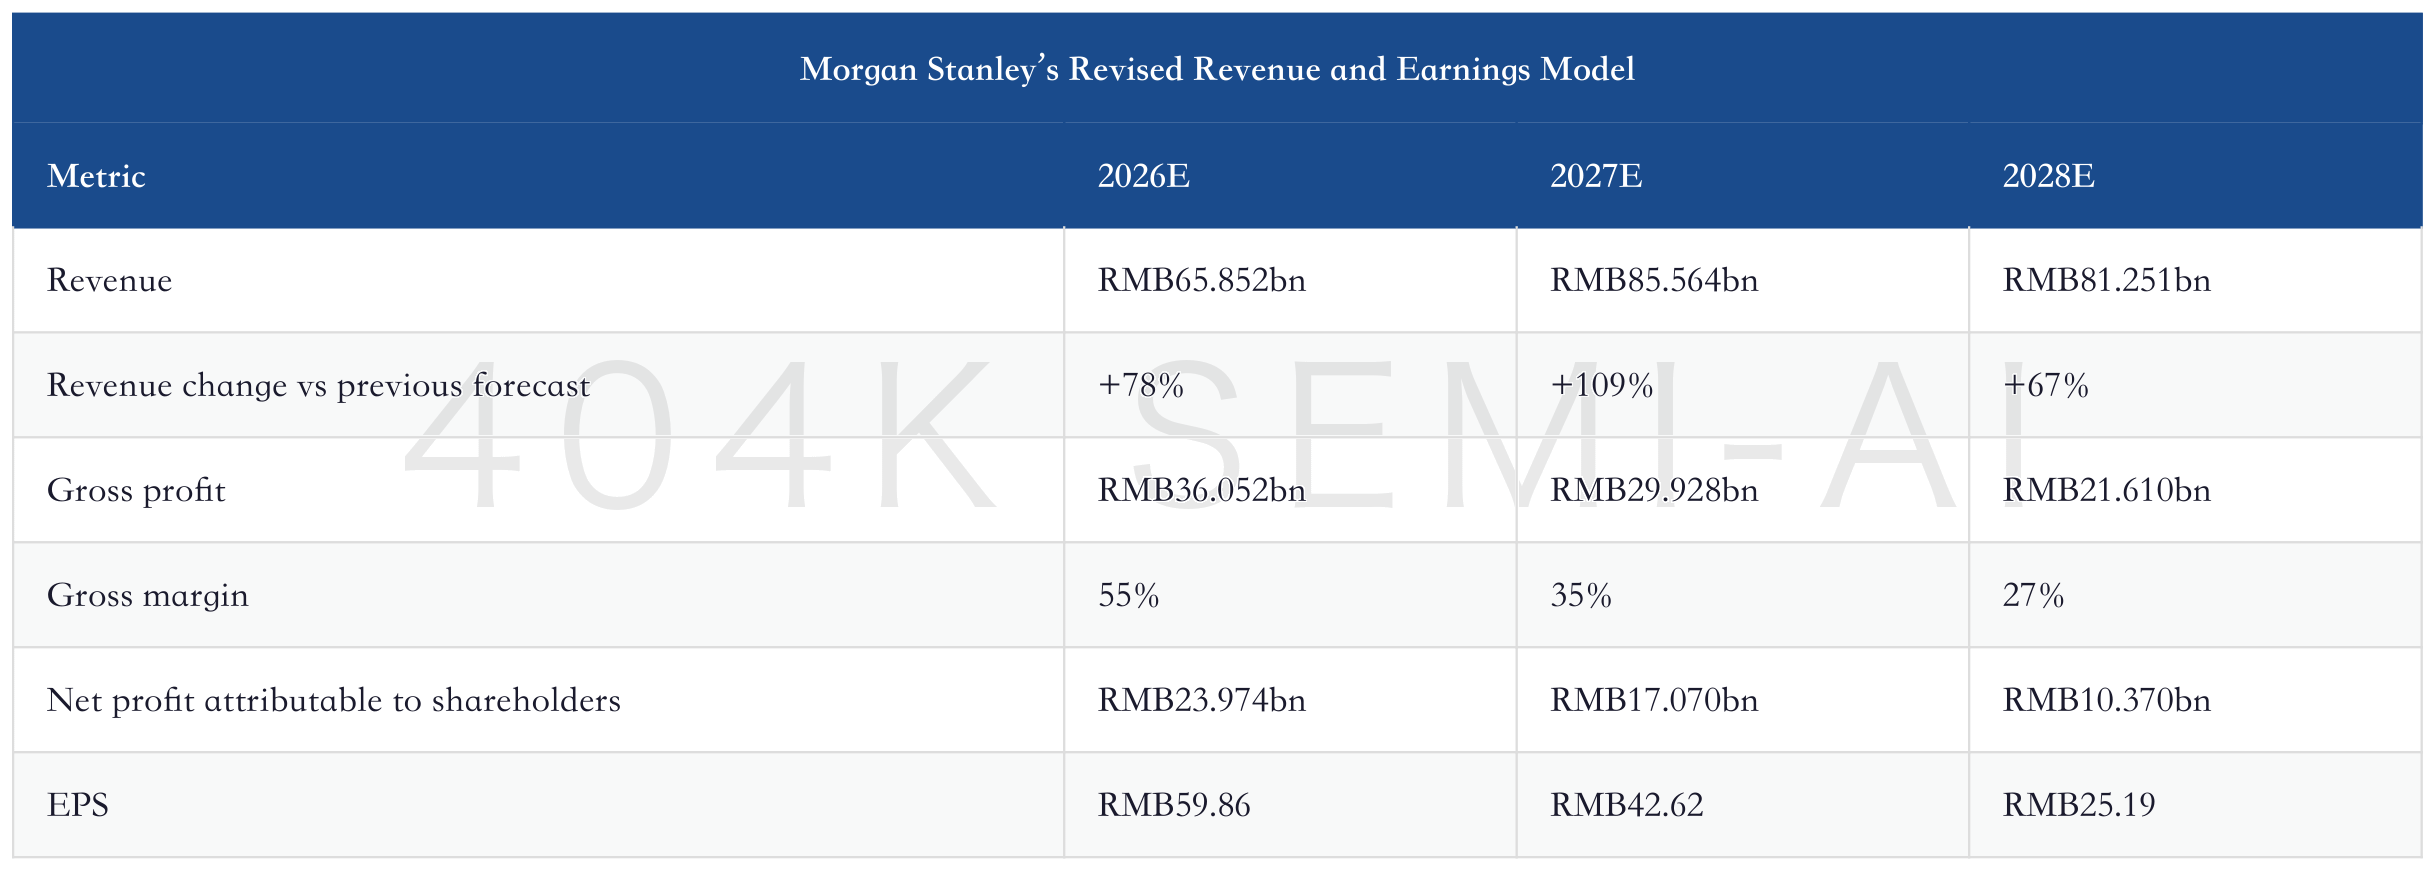
This data set makes Longsys’s valuation question very sharp: if 2026 net profit can really reach RMB23.974bn, the market can no longer value the company using the 2025 earnings base. But if the path of gross margin falling from 55% to 35% and then to 27% arrives early, the current share price will quickly shift from “re-rating” to “trading the cyclical peak.”
So Morgan Stanley is not saying Longsys is a risk-free re-rating. It is saying the risk-reward baseline has moved higher. Under the old model, Longsys needed to prove it was not an ordinary module maker. Under the new model, Longsys needs to prove that 2026 profits are not a one-off inventory dividend.
III. Product-Line Breakdown: The Upgrade Is Not a Single-Category Bet
Morgan Stanley’s move to lift Longsys’s target price to RMB673 does not rely only on price elasticity in one product line. Embedded storage, mobile storage, SSDs, and memory modules are all included in the upside model, but each line plays a different role.
Embedded storage is the base business and also where in-house controllers can most easily show value. Smartphone, AI device, automotive, and wearable customers have higher requirements for power consumption, reliability, capacity, packaging, and firmware adaptation. If Longsys can continue to secure customer projects with UFS 4.1, ePOP, HLC, and customized firmware, embedded-storage gross margin should not be understood only through ordinary NAND spreads.
Mobile storage and the Lexar brand are scale and channel assets. This segment can amplify earnings elasticity, but it is also the most constrained by consumer-end price ceilings. Morgan Stanley’s assumptions of 60% gross margin for mobile storage in 2026E and 42% in 2027E are strong. The implied premise is that low-cost inventory, brand premium, and channel pricing can all be realized at the same time. Once consumer customers cut orders, this line’s profitability will be the first to face market skepticism.
SSD is the key for Longsys to move from module elasticity toward platform assets. Consumer SSDs can provide scale, but enterprise SSDs are what may provide a higher valuation. Morgan Stanley raises SSD revenue from RMB14.462bn in 2026 to RMB21.115bn in 2027. Behind this is not just ordinary PC SSD unit-price upside, but the imagination space from AI infrastructure, enterprise customers, and high-spec customization.
Memory modules are the smallest in scale, but their significance is not absolute profit. The question is whether the company can turn its storage product lines into a more complete customer entry point. Servers, PCs, edge AI, and high-end terminals require not only NAND, but also DRAM modules, RDIMM, SOCAMM, MRDIMM, and CXL-related products. If Longsys can connect these product lines with enterprise customers, its valuation will move closer to that of a platform-type storage solution provider.
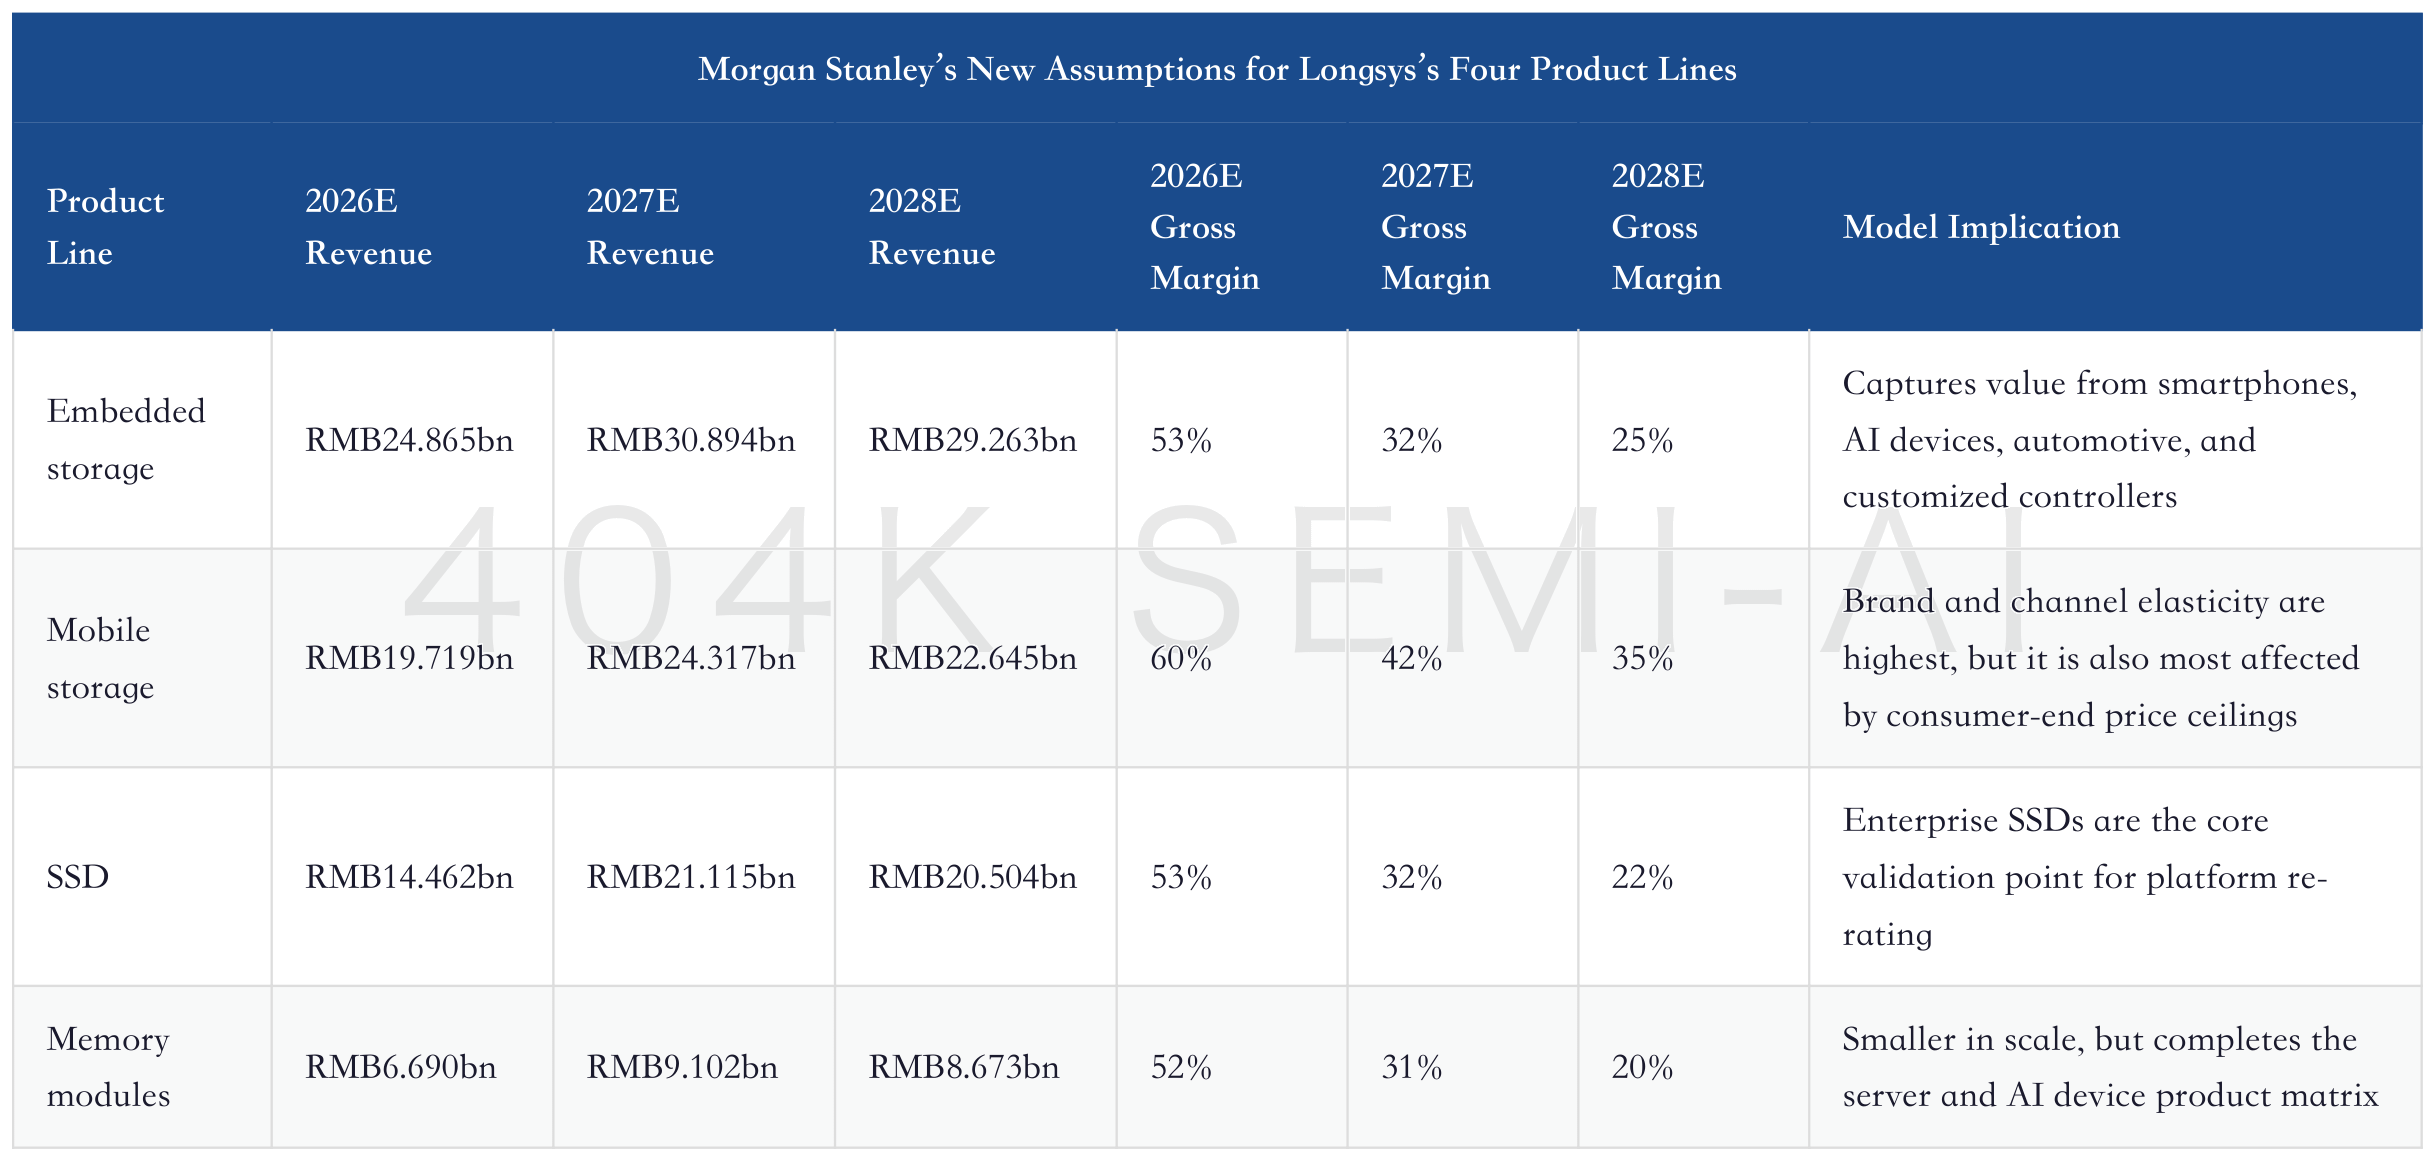
This breakdown has two key points. First, almost every category is assigned an extremely high gross margin in 2026, showing that Morgan Stanley views the year as one where pricing, inventory, and product mix resonate together. Second, gross margins fall meaningfully in 2027 and 2028, showing that Morgan Stanley does not assume Longsys can permanently maintain 2026 windfall margins, but instead treats high margins as a cycle that gradually normalizes.
In other words, the RMB673 target price is not built on “Longsys will earn RMB24bn every year from now on,” but on “after the 2026 profit surge, Longsys can still retain a sufficiently high profit step-up in 2027.” The real market debate is not whether 2026 can be very strong, but whether 2027 EPS of RMB42.62 is credible.
IV. 2027E EPS Is the Core of the RMB673 Valuation
Often, when the market sees a target-price increase, it naturally focuses on the nearest year of earnings. For Longsys, this time cannot be assessed only on 2026. 2026E EPS of RMB59.86 is high, but it is too easy for the market to treat it as a cyclical peak. What really determines whether the RMB673 target price can hold is 2027E EPS of RMB42.62.
The reason is simple. If looking only at 2026E EPS, Longsys’ valuation multiple appears very low, and the market may easily conclude that the share price still has room to rise. But if 2026 profit is viewed as unsustainable, the low multiple itself has little meaning. Morgan Stanley’s choice to use 2027E EPS as the target-price anchor is telling the market that Longsys’ profit step-up should extend at least into 2027, rather than reflecting only a one-year surge in 2026.
The valuation multiple implied by the base-case target price is not extreme, provided that 2027 remains a combination of NAND tightness, high gross margins, and enterprise product ramp-up. If 2027E EPS is meaningfully below Morgan Stanley’s assumptions, RMB673 would quickly shift from a reasonable valuation to a high-multiple price, and valuation pressure would rise immediately.
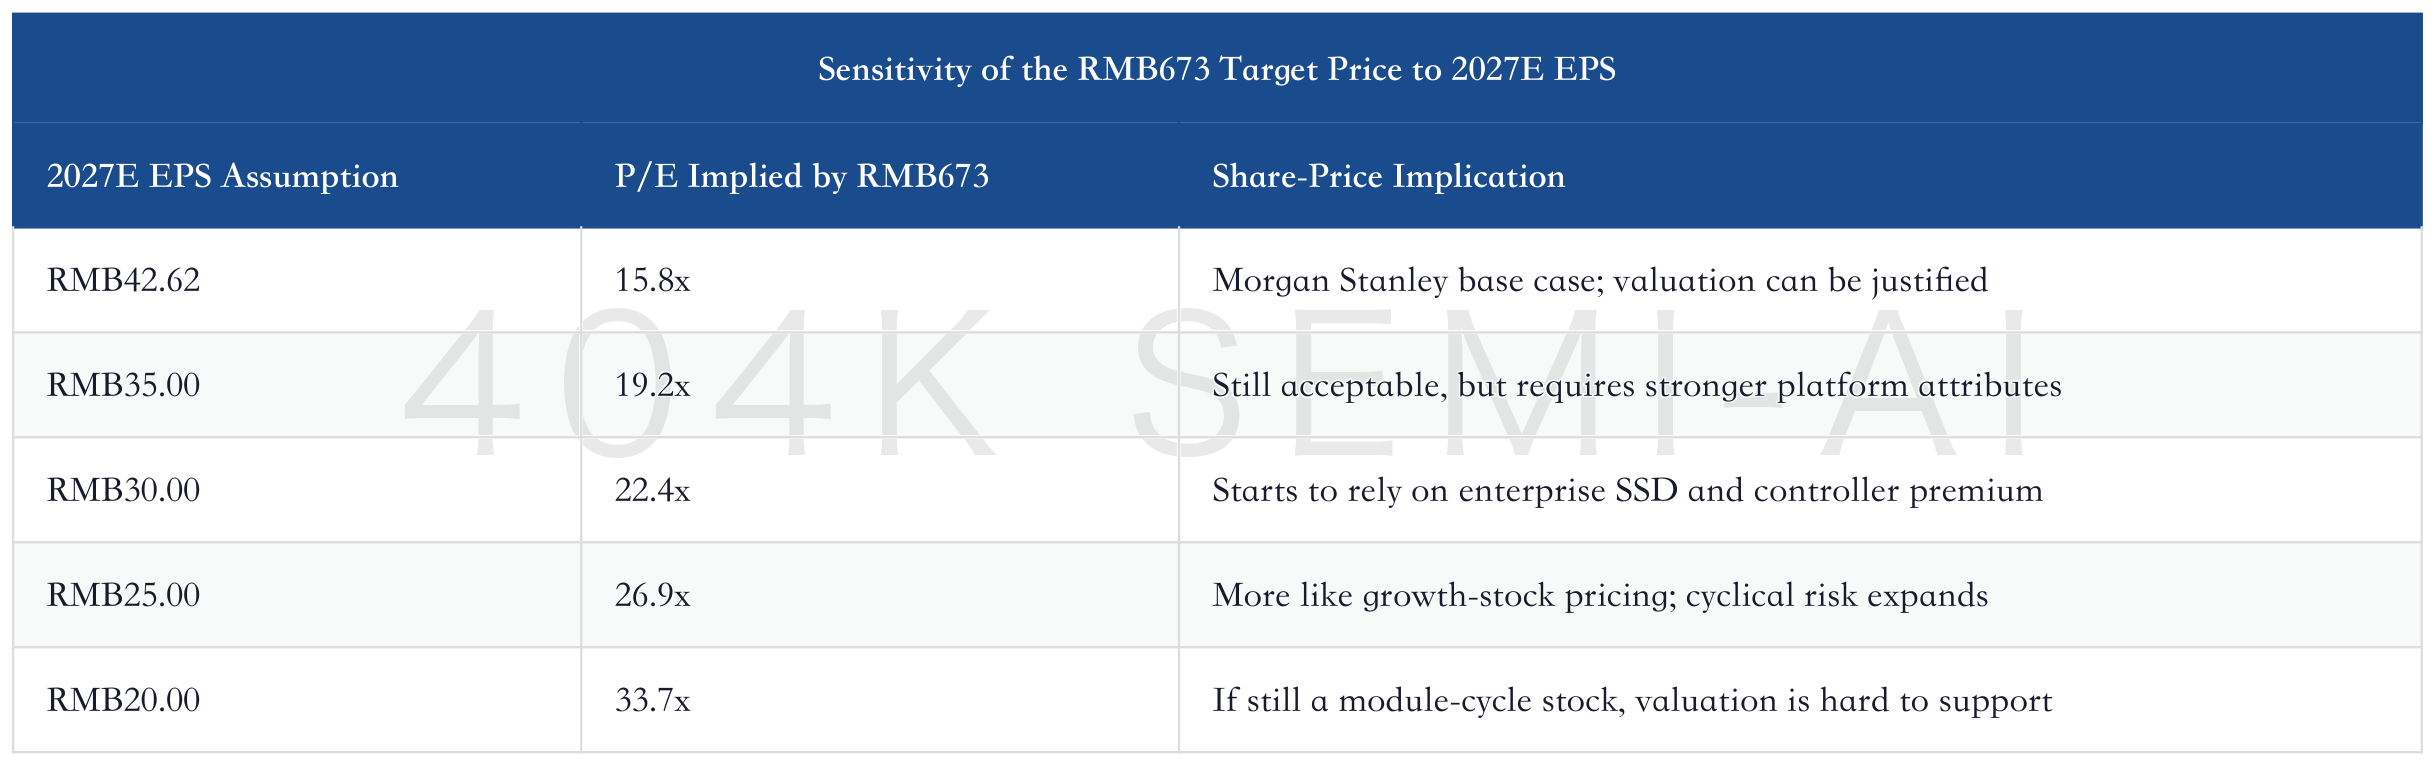
This is also why subsequent earnings reports will become highly sensitive. If Longsys only earns a one-off high profit in 2026, the share price will struggle to enjoy a high valuation for long. Only if 2027 can still prove that enterprise products, TCM, and long-term customer agreements support the profit step-up will the RMB673 target price have a real foundation.
V. Why Morgan Stanley Prefers Original Manufacturers, While Still Upgrading Longsys
Morgan Stanley’s preference in the NAND supply chain is clear: it favors original manufacturers over module makers. This is because AI demand first changes original manufacturers’ pricing power, capacity allocation power, and long-term contract negotiation power. Module makers benefit, but they are not the source of supply.
Applied to Longsys, this becomes a very practical question: why should Longsys receive a large upward revision among module makers? The answer is not “because NAND prices are rising,” but “because Longsys has more profit-retention tools than ordinary module makers.”
First is inventory-cycle management. In an upcycle, Longsys can amplify profit through higher inventory, but this advantage is not free. The higher the inventory, the greater the benefit when prices continue to rise, and the greater the pressure when prices weaken. Morgan Stanley is willing to revise upward because the industry shortage in 2026-2027 extends the window for inventory gains.
Second is the TCM model. Ordinary module makers carry more inventory and price volatility on their own books, while TCM ties customer demand, specification customization, and supply assurance more tightly together. It cannot eliminate the cycle, but it can allow Longsys to obtain a more stable profit allocation among high-spec customers.
Third is enterprise and controller capability. As original manufacturers tilt more supply toward CSPs, ordinary consumer module makers will be squeezed. If Longsys can use enterprise SSDs, self-developed controllers, and firmware services to enter higher-spec scenarios, it can reduce the degree of pressure.
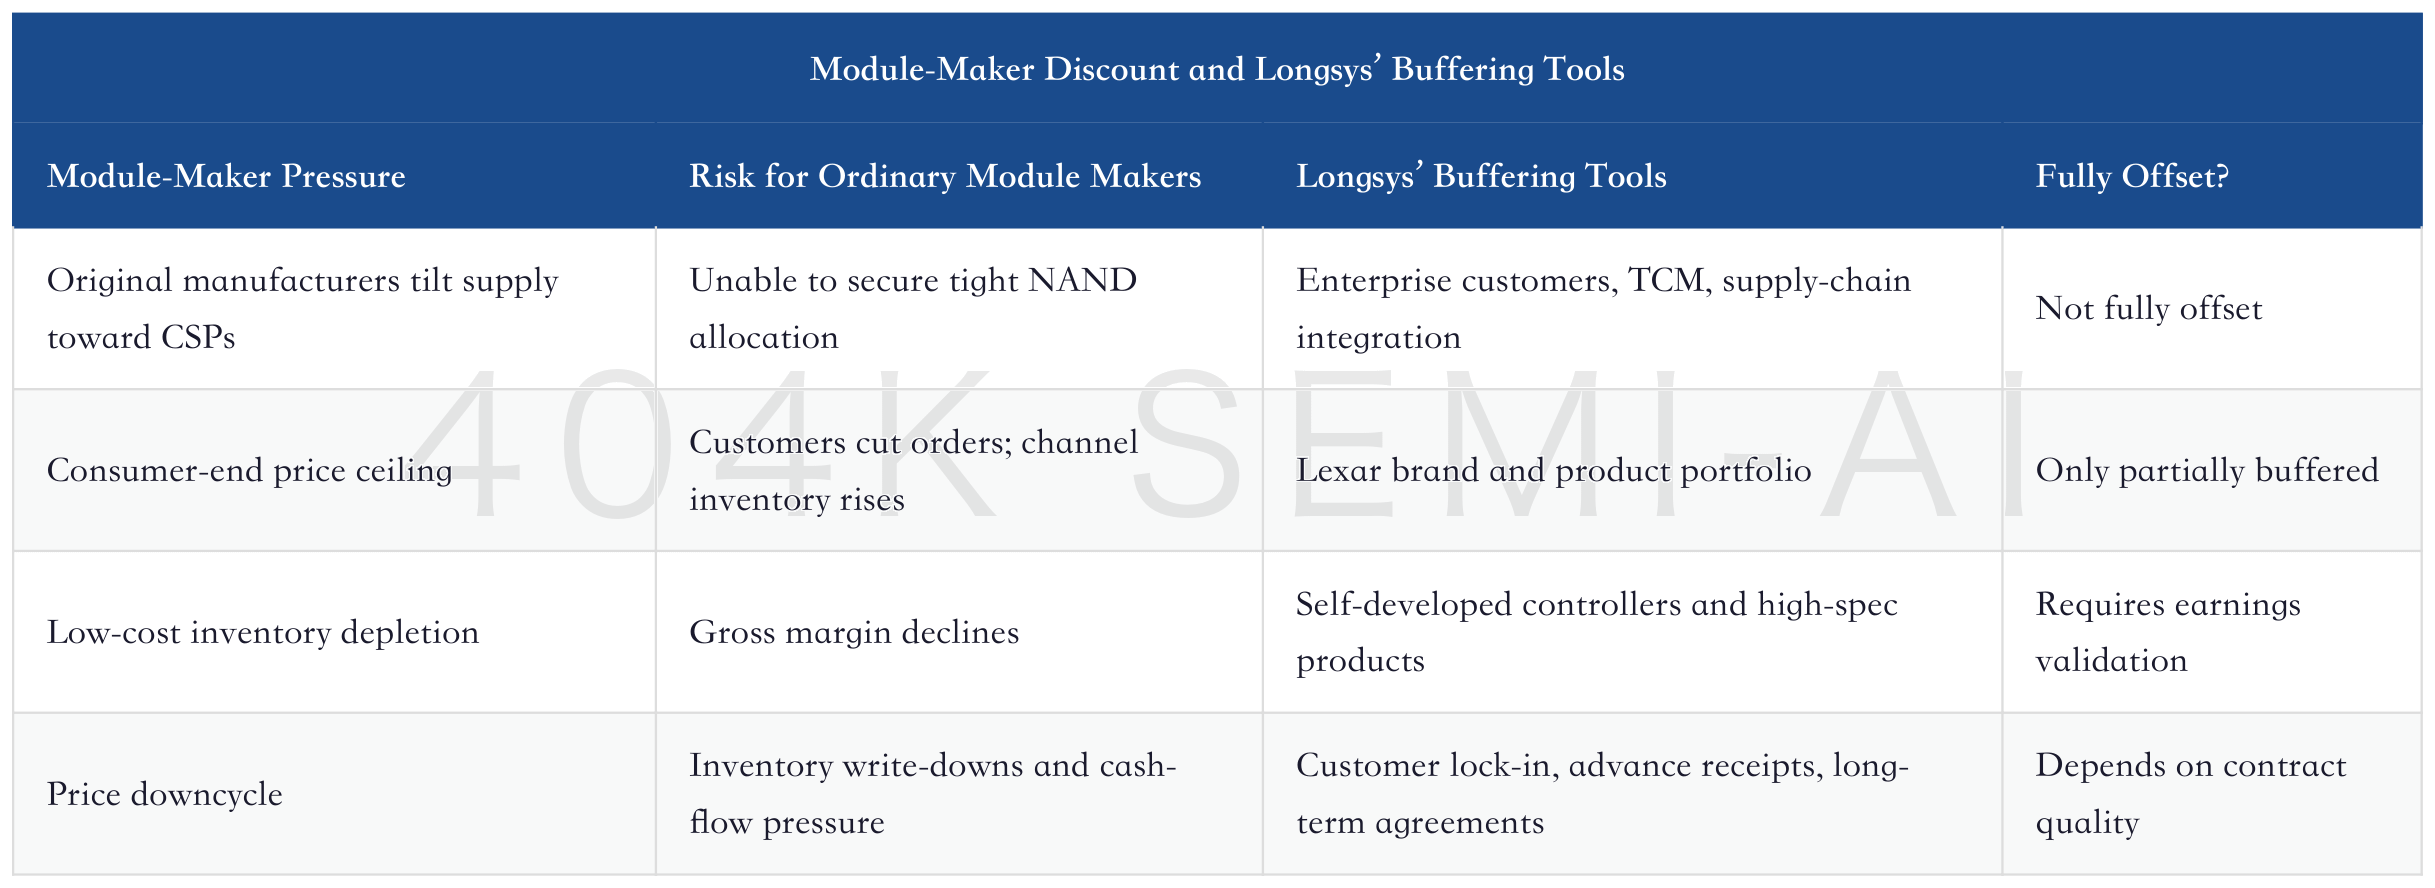
This table explains Morgan Stanley’s seemingly contradictory stance: Longsys deserves an upgrade because it is not an ordinary module maker; Longsys remains Equal-weight because it is still a module maker.
VI. Cash Flow and Inventory: The Hard Constraints Behind High Profit
Longsys’ income statement is already very strong, but cash flow and inventory cannot be ignored. In 1Q26, the company generated revenue of RMB9.909 billion and net profit attributable to shareholders of RMB3.862 billion, an extremely strong profit release. At the same time, operating cash flow was negative, inventory rose to RMB17.961 billion, and prepayments also increased significantly. This shows that the company is making substantial purchases and building inventory for the upcycle.
In a storage upcycle, high inventory is not inherently bad. Low-cost inventory can translate into gross margin during a price-rise period, prepayments can lock in supply, and contract liabilities can reflect customers locking in goods in advance. The issue is that all these metrics must be tied to price direction. If prices continue to rise, they are profit leverage; if prices weaken, they become cash-flow and write-down risks.
This is also why Morgan Stanley raised the target price substantially but did not upgrade the rating. To prove that Longsys is not simply earning a one-off inventory gain, it must deliver better cash-flow quality over the next several quarters. If the income statement rises first and cash flow later catches up, that is a healthy upcycle. If the income statement is strong, inventory continues to rise, and cash flow remains negative, the market will start to worry that peak profit is unsustainable.
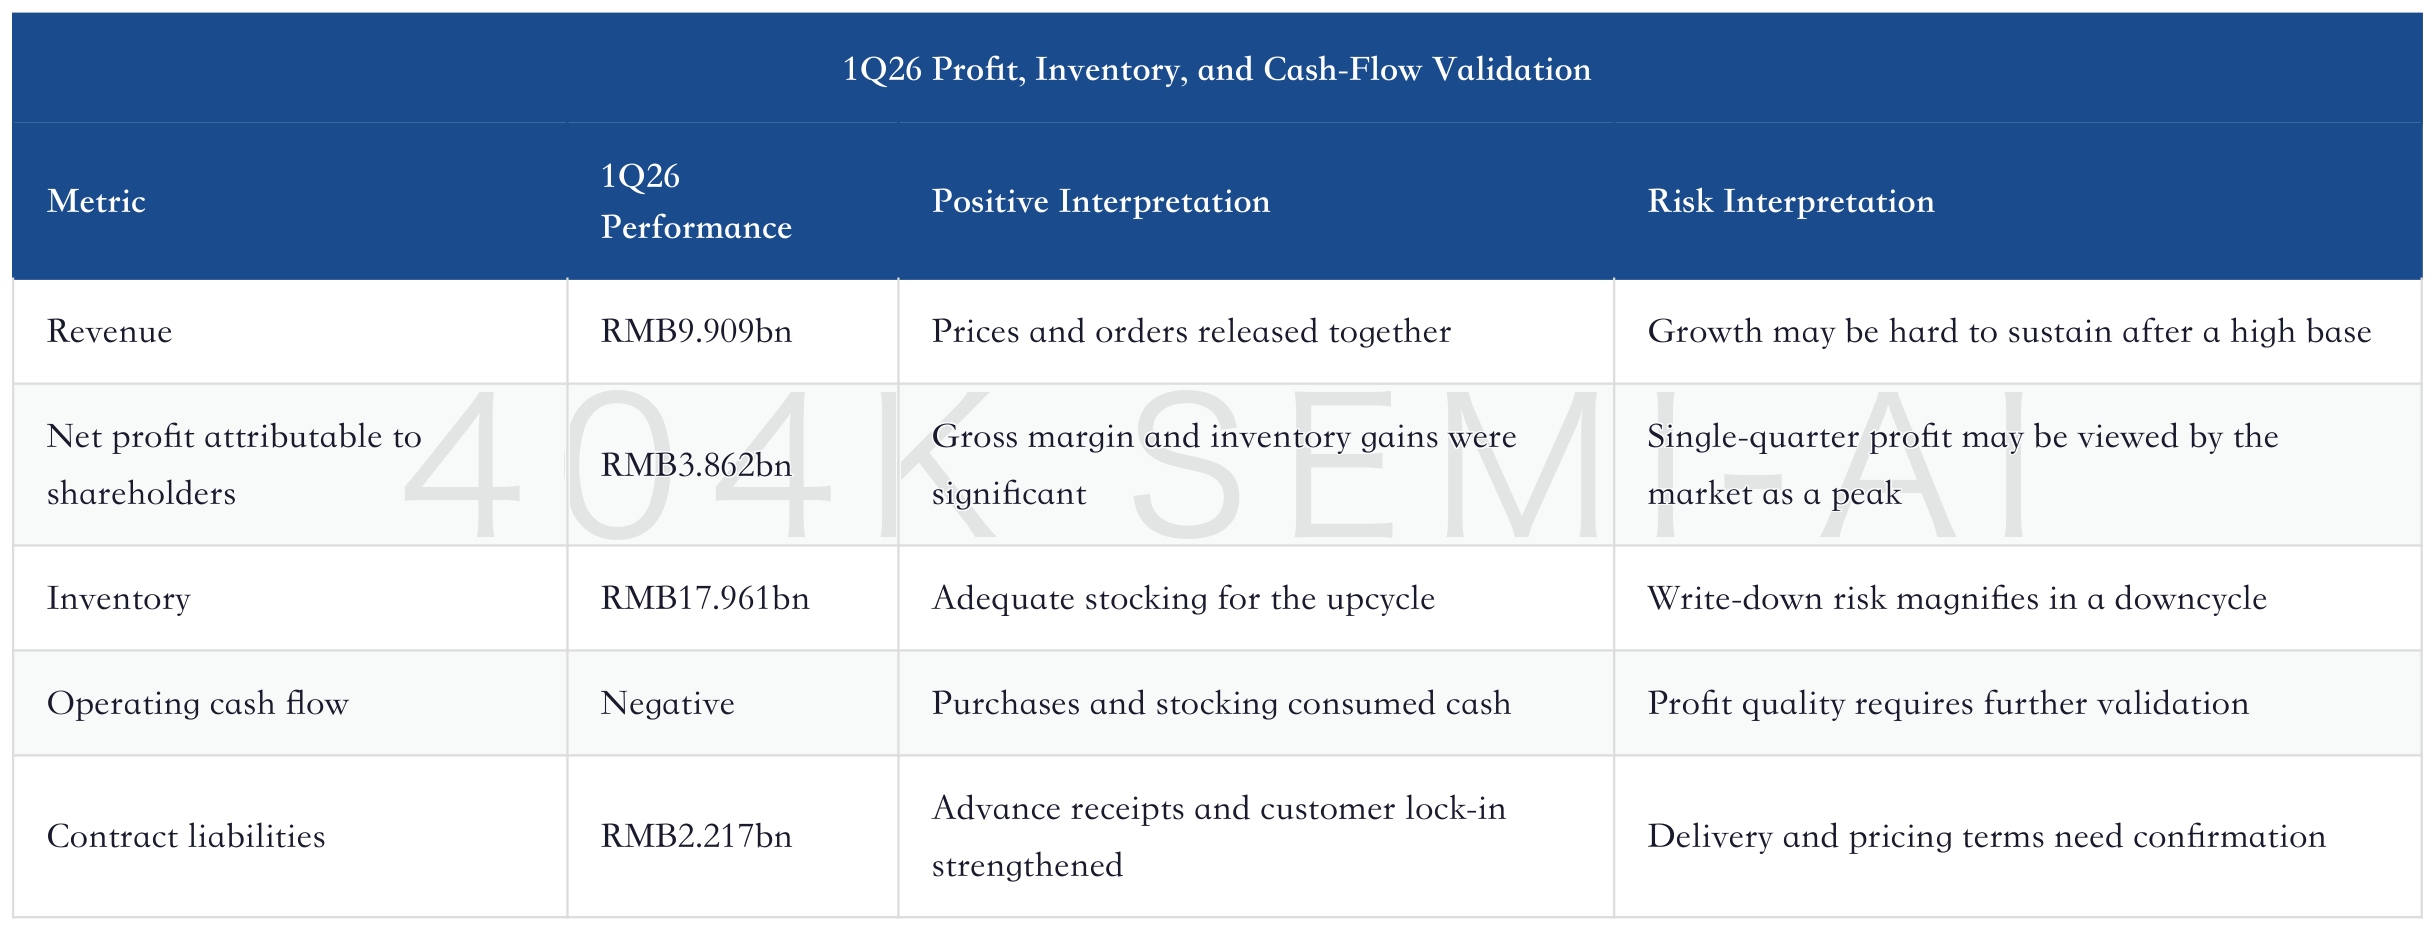
The ideal earnings combination for Longsys going forward would be high gross margins, rising enterprise revenue, stable or increasing contract liabilities, and improving operating cash flow. The least ideal combination would be a still-strong income statement alongside further inventory build, persistently negative operating cash flow, and shrinking consumer-end orders. The former would support the RMB673 target price; the latter would lead the market to price in a bear-case scenario early.
VII. The Rating Remains Equal-weight: Morgan Stanley Has Not Made Longsys a Top Pick
The easiest point to misread this time is equating a “large target-price increase” directly with “strong bullishness.” Morgan Stanley’s actual signal is more restrained: the target price has increased, but the rating has not been upgraded, and the allocation order still does not put module makers ahead of NAND original manufacturers.
The reason is direct. AI is indeed driving NAND shortages, but profit-retention ability is uneven across the NAND supply chain. Original manufacturers control wafer supply, long-term contract pricing, and the pace of capacity. Module makers are more exposed to customer orders, inventory, procurement rhythm, and the consumer-end price ceiling. In the early stage of price increases, module makers can amplify profit with low-cost inventory. In the second half of a price-rise cycle, low-cost inventory is consumed, customer orders shrink, and original manufacturers tilt supply toward CSPs, putting both shipment volume and gross margin for module makers to the test.
This is why Morgan Stanley raised Longsys’ target price while still preferring NAND suppliers. Longsys was upgraded because it has three things beyond an ordinary module vendor: enterprise SSD penetration, self-developed controllers, and the TCM model. But these capabilities have not fully offset the inherent issues of a module maker: it does not decide supply, it does not decide pricing, and the tightest AI SSD allocation may not necessarily prioritize module makers.
In investment terms, Longsys has not moved directly from a “cyclical stock” to a “platform growth stock.” Rather, it has been upgraded from an “ordinary storage-module cyclical stock” to a “high-beta cyclical stock with platform attributes.” This distinction is important. The former looks only at price; the latter also looks at product mix and customer stickiness. But as long as NAND prices decline, the latter cannot escape the cycle either.
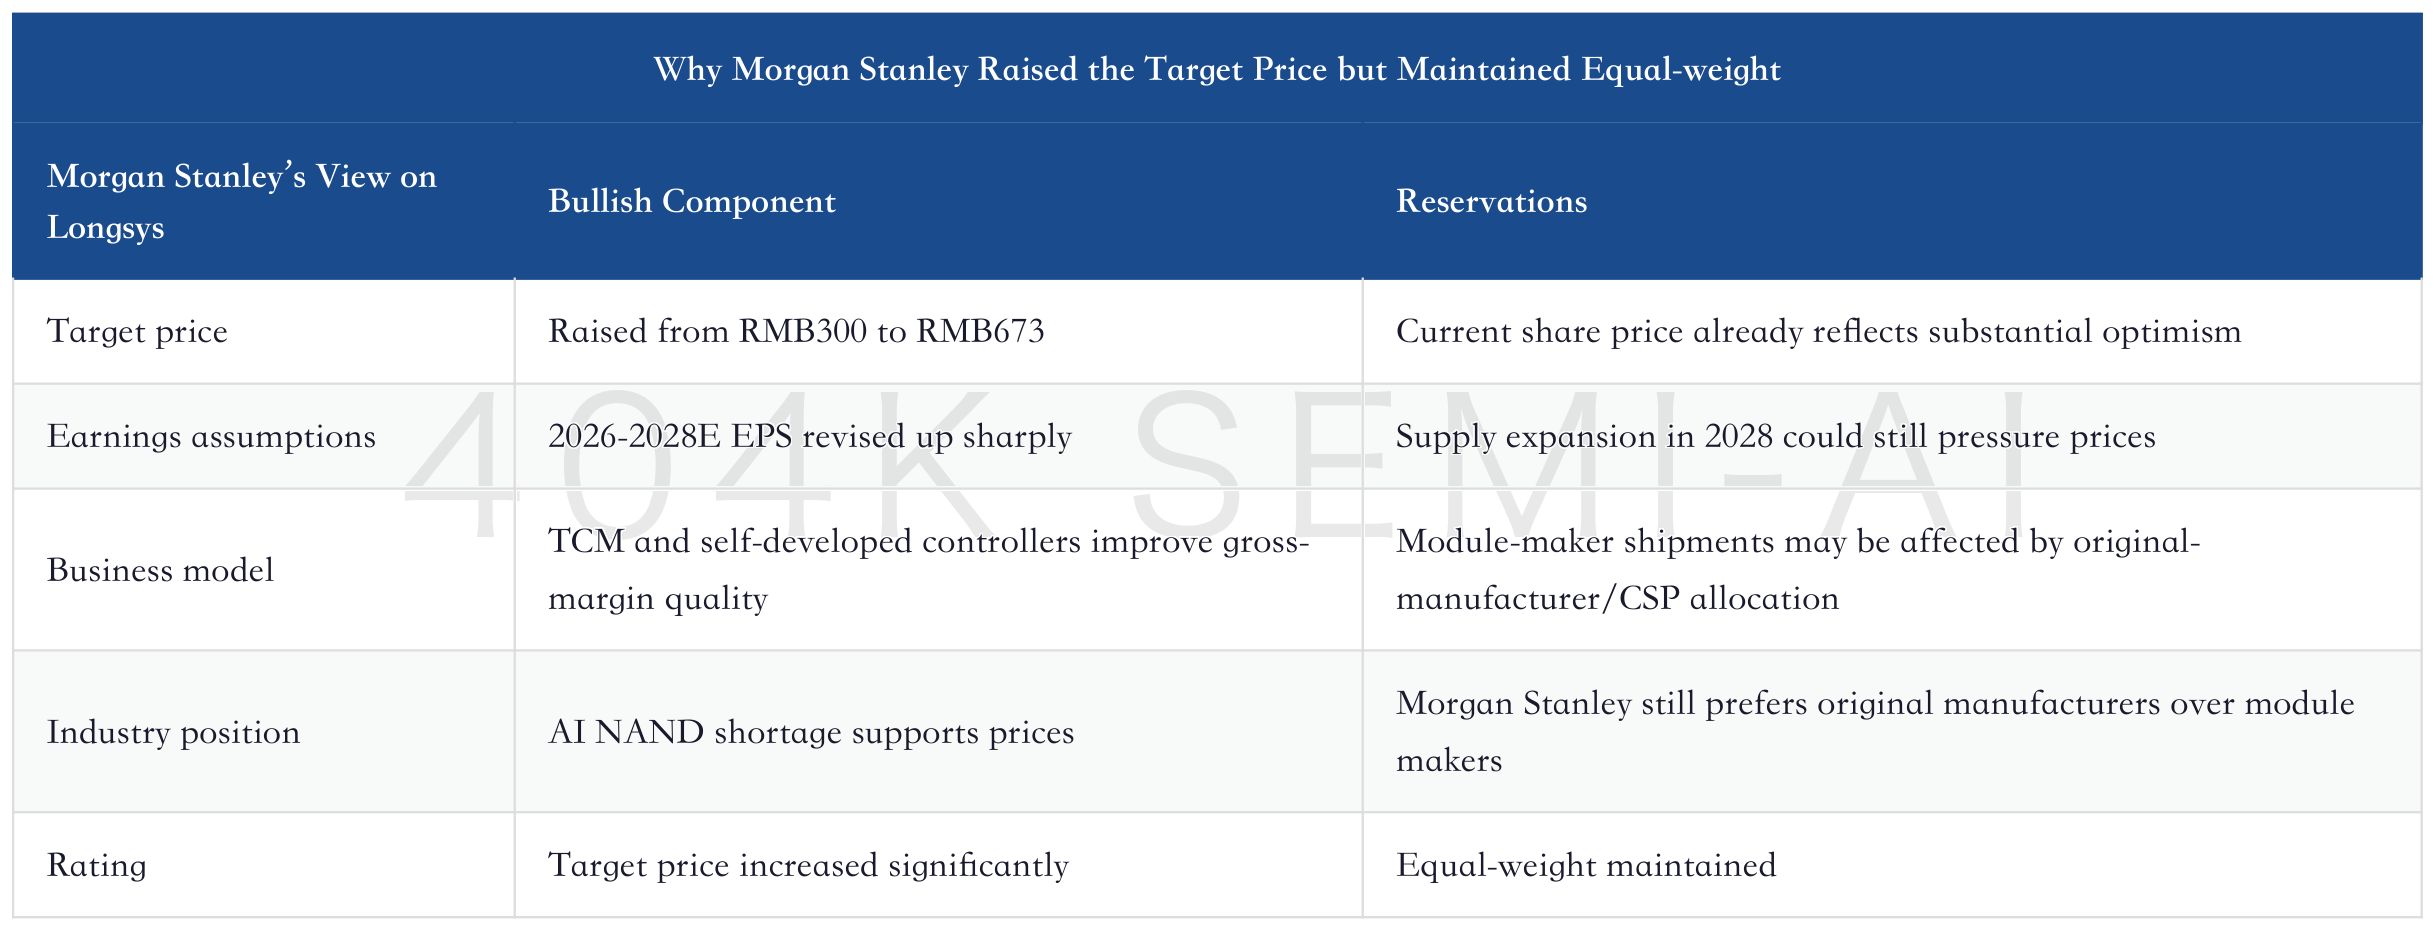
This rating is a reminder: the upward revision to Longsys’ target price reflects an upward reassessment of the fundamentals model; the unchanged rating reflects the fact that the share price and supply-chain position still require a discount.
VIII. Valuation Methodology: RMB673 Is Not Simply a High P/E Multiple
Morgan Stanley uses a residual income model for Longsys, rather than simply multiplying 2027E EPS by a multiple. The residual income model focuses on whether a company can continue generating profit above its cost of capital. For a storage company like Longsys, whose profit is highly volatile, this method better captures the cyclical debate than a single-year P/E multiple: if high profit lasts for only one year, residual income decays quickly; if high profit can be maintained into 2027 or longer, valuation will be systematically lifted.
In Morgan Stanley’s base model, the cost of equity is 9.10%, the risk-free rate is 2.5%, the risk premium is 5.5%, beta is 1.2, and the perpetual growth rate is 6.3%. These parameters themselves are not aggressive. What really pushes up the target price is the profit forecast. In other words, the core of the RMB673 target price is not a sudden decline in the cost of capital, but the much thicker residual income after 2026-2027 profit was revised up sharply.
This also makes Longsys’ valuation risk clearer. The P/E multiple can look very low, but the residual income model penalizes profit declines. If gross margin quickly returns to the level of an ordinary module maker after 2028, the current high profit merely pulls forward future value. If enterprise SSDs, controllers, and TCM allow the company’s ROE to remain on a higher step, the residual income model will assign a higher fair value than it would to a traditional cyclical stock.
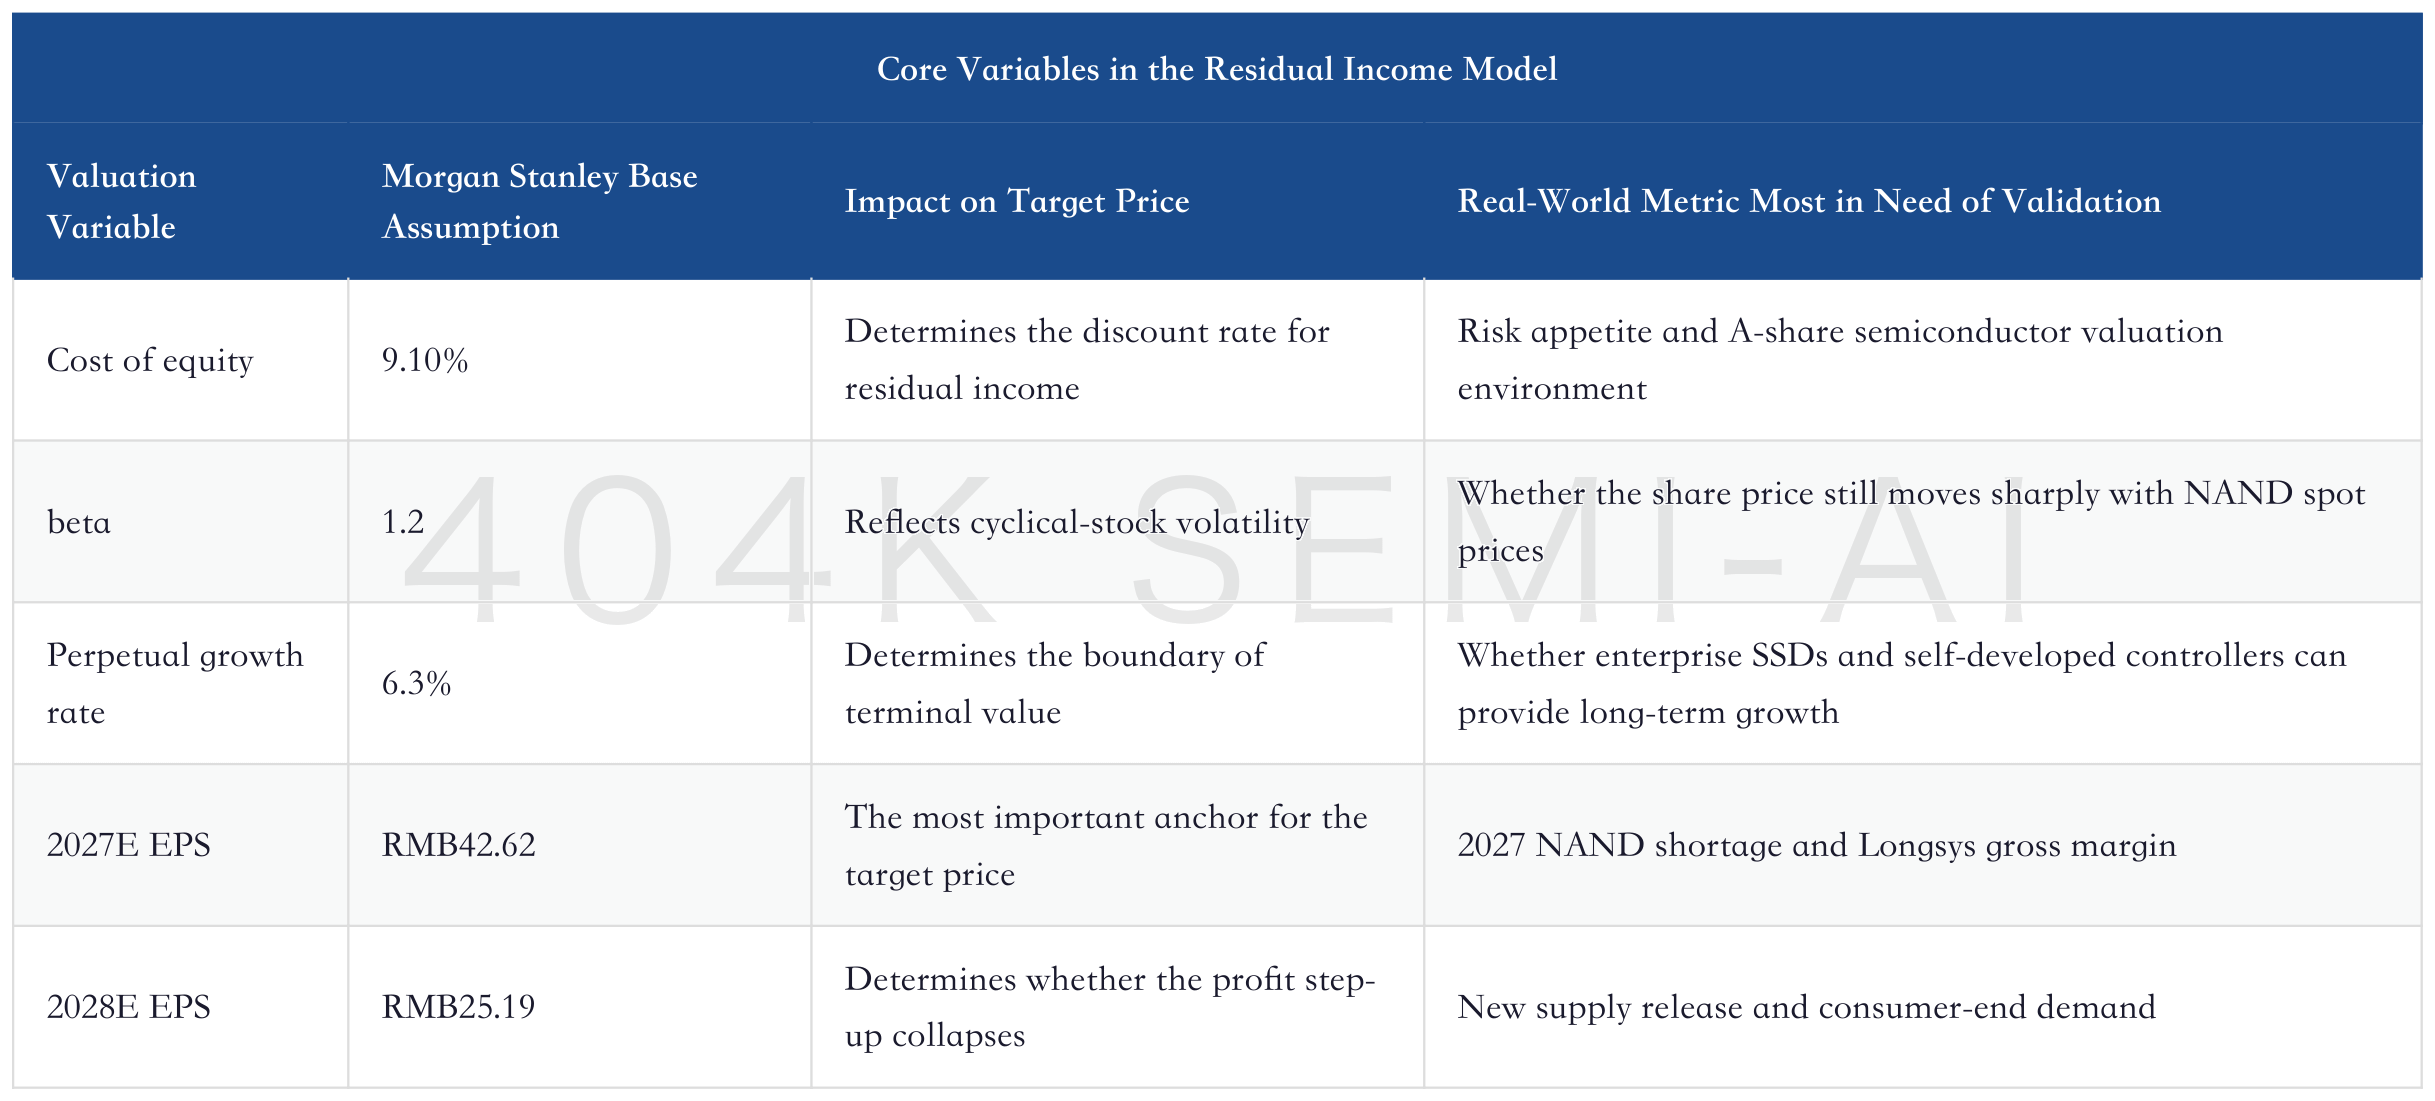
This table points to a more practical issue: for Longsys, a cheap valuation multiple is no longer enough. It must prove that high ROE is not a short-term result of the inventory cycle. If ROE falls quickly after 2026, residual income will be compressed again. If high profit can still be maintained in 2027, the market will accept that Longsys is no longer just an ordinary module-cycle stock.
Therefore, the RMB673 target price is not as simple as “assigning Longsys a higher P/E.” It reflects Morgan Stanley lifting Longsys’ profit step-up over the next two years and then discounting that excess profit through a residual income model. What investors really need to judge is whether this excess profit is one-off or sustainable.
IX. AI NAND Shortage Is the Primary Driver of Upward Revisions
Morgan Stanley's model rewrite for Longsys is based on a global NAND supply-demand table. AI servers, training clusters, inference clusters, and long-term agreements with cloud vendors are consuming more NAND supply, especially enterprise SSDs and high-performance storage tied to AI infrastructure. Traditional consumer segments such as smartphones, PCs, and channel modules still represent scale, but pricing power is being squeezed by AI demand.
Morgan Stanley expects AI-related NAND demand to rise from 205EB in 2025 to 400EB in 2026 and 609EB in 2027, with its share of global NAND demand increasing from 18% to 41%. This is not a small structural change. It means NAND is no longer priced only as a smartphone, PC, and ordinary consumer SSD cycle; it is beginning to be repriced by data-center capex.
How to Bypass the Memory Tax: NAND, CXL, and PIM Are Being Repriced, and the Industrial Logic Behind Storage-Tier Reconstruction
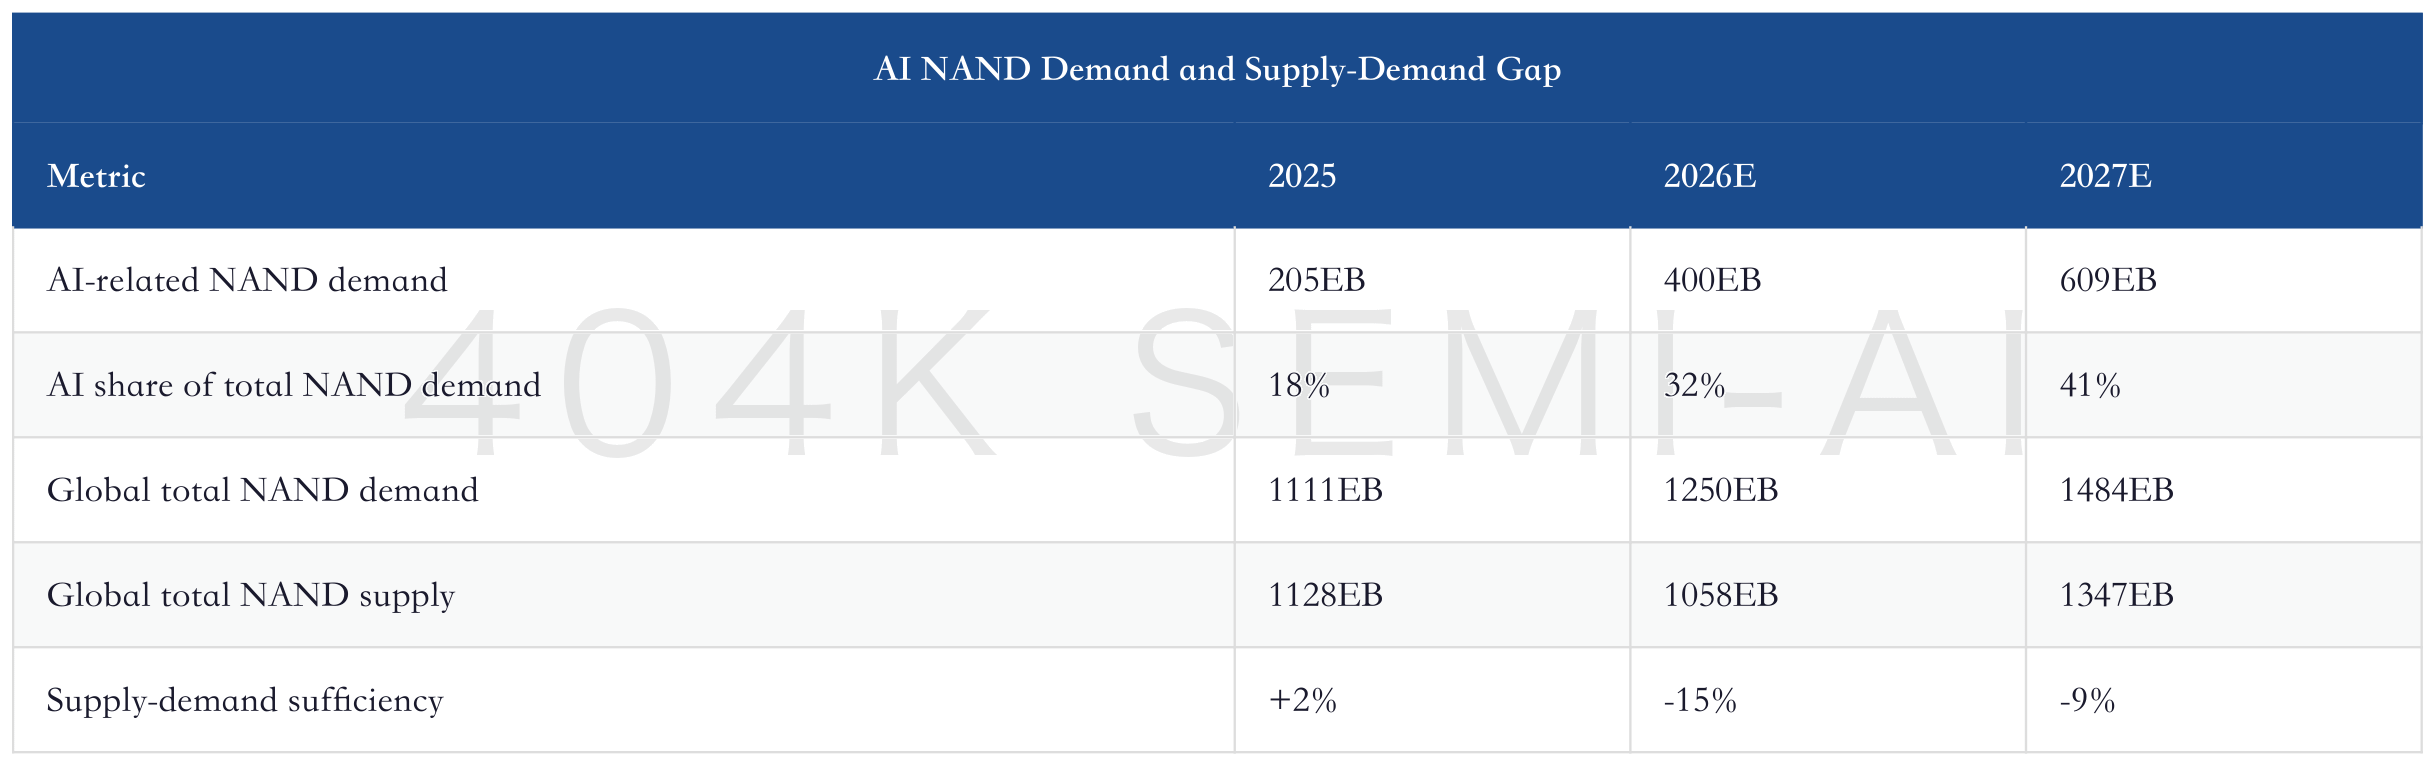
This table explains why Longsys is being repriced. A 15% supply-demand gap in 2026 means prices are not merely rising modestly; customers will have to accept higher contract prices. A continued 9% gap in 2027 means price increases are not a one-quarter impulse. As long as the supply-demand gap persists, Longsys, as a company with high inventory, high turnover, and high product elasticity, will see both revenue and gross margin amplified.
But this table also explains why the rating was not upgraded. The AI NAND shortage primarily benefits original manufacturers, because they control wafers and long-term agreements. Longsys benefits from rising prices, but it does not control supply. The real question is not whether Longsys can benefit, but how much profit it can retain.
This is also the biggest difference between Longsys and original manufacturers. The core variables for original manufacturers are wafer prices and capacity discipline. The core variables for Longsys are procurement costs, inventory cycles, customer mix, product ASP, and the share of high-end products. Once AI pulls up NAND prices, Longsys has substantial earnings elasticity, but the quality of its earnings must be explained by TCM, enterprise SSDs, and controller capabilities.
X. Cross-Checks From the Past Week: Morgan Stanley Is Not the Only One Revising NAND Upward
This Longsys target-price upgrade cannot be assessed by looking only at Morgan Stanley's single model. Looking at several NAND-related reports from the past week together, the conclusion is clear: AI/eSSD demand is still tightening supply, and original manufacturers and leading SSD assets continue to see earnings revisions. At the same time, the slope of consumer NAND price increases has begun to fall below that of the server side, meaning module makers' “price” and “volume” will diverge.
Goldman Sachs' update on Kioxia confirms earnings on the original-manufacturer side. Goldman Sachs raised Kioxia's target price to JPY116,000. The core assumption is that tight NAND supply-demand will last at least until mid-2027, and that major memory companies are prioritizing investment in DRAM and HBM, making it hard for new NAND capacity to increase meaningfully before 2028. This judgment is consistent with Morgan Stanley's supply-demand table: AI demand is absorbing high-spec NAND first, while original manufacturers prefer to defend pricing and margins.
Citi's update on SanDisk confirms downstream AI storage demand. Citi raised SanDisk's target price to USD2,500, based on Micron's earnings validation of NAND ASP and bit shipments, as well as demand for KV cache, tiered storage, and high-performance SSDs in AI inference. SanDisk and Kioxia are both original-manufacturer or quasi-original-manufacturer assets. Their earnings revisions show that this NAND cycle is not ordinary consumer restocking.
Korean storage price tracking provides signals of divergence. Under TrendForce's framework, overall NAND ASP in 3Q26 is expected to rise 10%-15% QoQ, while enterprise SSDs are expected to rise 18%-23% QoQ. However, price increases for mobile NAND and consumer-related categories are clearly below eSSD. This gap is critical: whether Longsys can support a RMB673 target price does not depend on all NAND rising together, but on whether enterprise and customized products can grow faster than the consumer side.
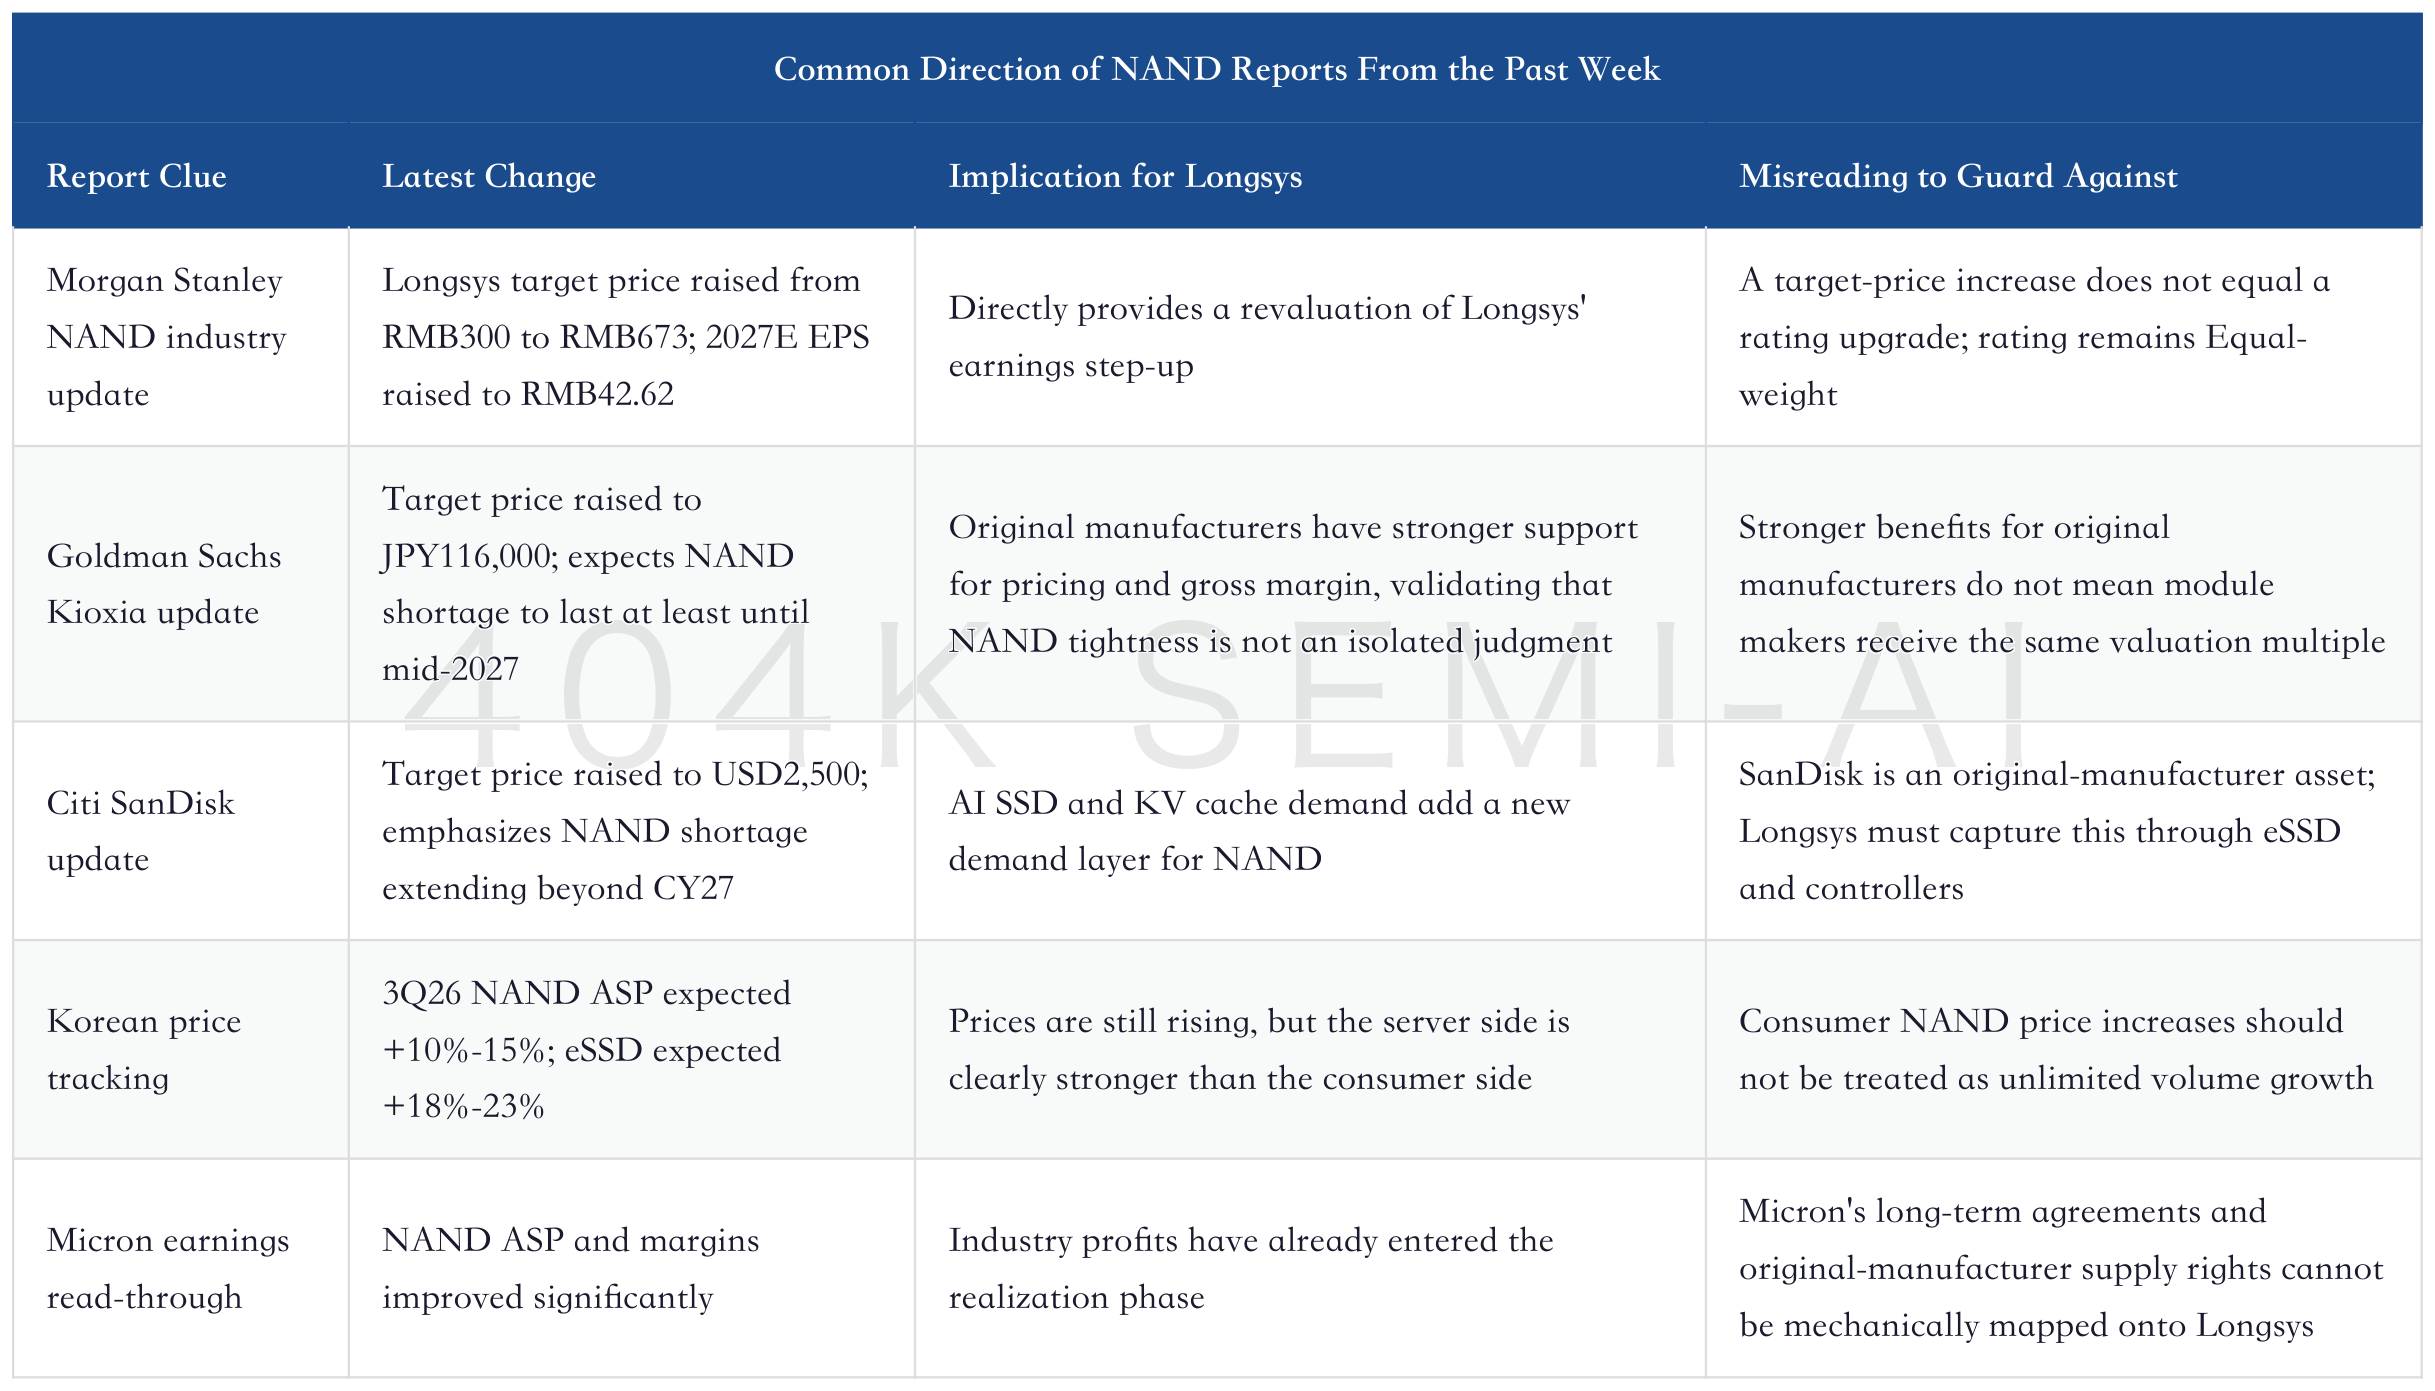
This cross-check table also explains why Morgan Stanley maintained an Equal-weight rating. Evidence on the original-manufacturer side is getting stronger, so Longsys' target price naturally needs to be revised up. But original manufacturers still have the firmest pricing, strongest long-term agreements, and greatest capacity-allocation power. Longsys needs to convert this NAND shortage into its own earnings quality through TCM, enterprise SSDs, and controllers.
Therefore, the focus of this update is not “Longsys also rises with NAND.” The more accurate judgment is: NAND tightness has raised Longsys' earnings ceiling, and multiple reports over the past week confirm that this ceiling has moved up. But the consumer-side price ceiling and original-manufacturer supply tilt have also raised the bar for Longsys' execution.
XI. Longsys' Advantage: Not an Ordinary Low-Cost Inventory Module Maker
If Longsys is viewed only as a traditional module maker, Morgan Stanley's RMB673 target price looks overly aggressive. The business model of a traditional module maker is clear: accumulate low-cost inventory during downcycles, sell at higher prices during upcycles, and earn the pricing spread. But this profit is not sustainable. Once low-cost inventory is depleted, customer demand slows, and original-manufacturer supply prices rise, gross margin will fall quickly.
Longsys has been revised up sharply this time because Morgan Stanley believes it is no longer entirely this type of model. TCM shifts part of the inventory and price-volatility pressure forward to customers. Enterprise SSDs and embedded storage improve product specifications. Self-developed controllers and firmware capabilities increase the value of customized services. The Lexar brand provides overseas consumer and channel assets. Together, these factors are why the gross-margin assumption has been raised.
The company's official data also support this change. In 2025, revenue and net profit attributable to shareholders recovered significantly. Enterprise storage grew much faster than the overall business. Controller chip deployment volume, validation of the 5nm UFS 4.1 controller, and the 2026 scaling plan all give Longsys more product-structure explanatory power than ordinary module makers.
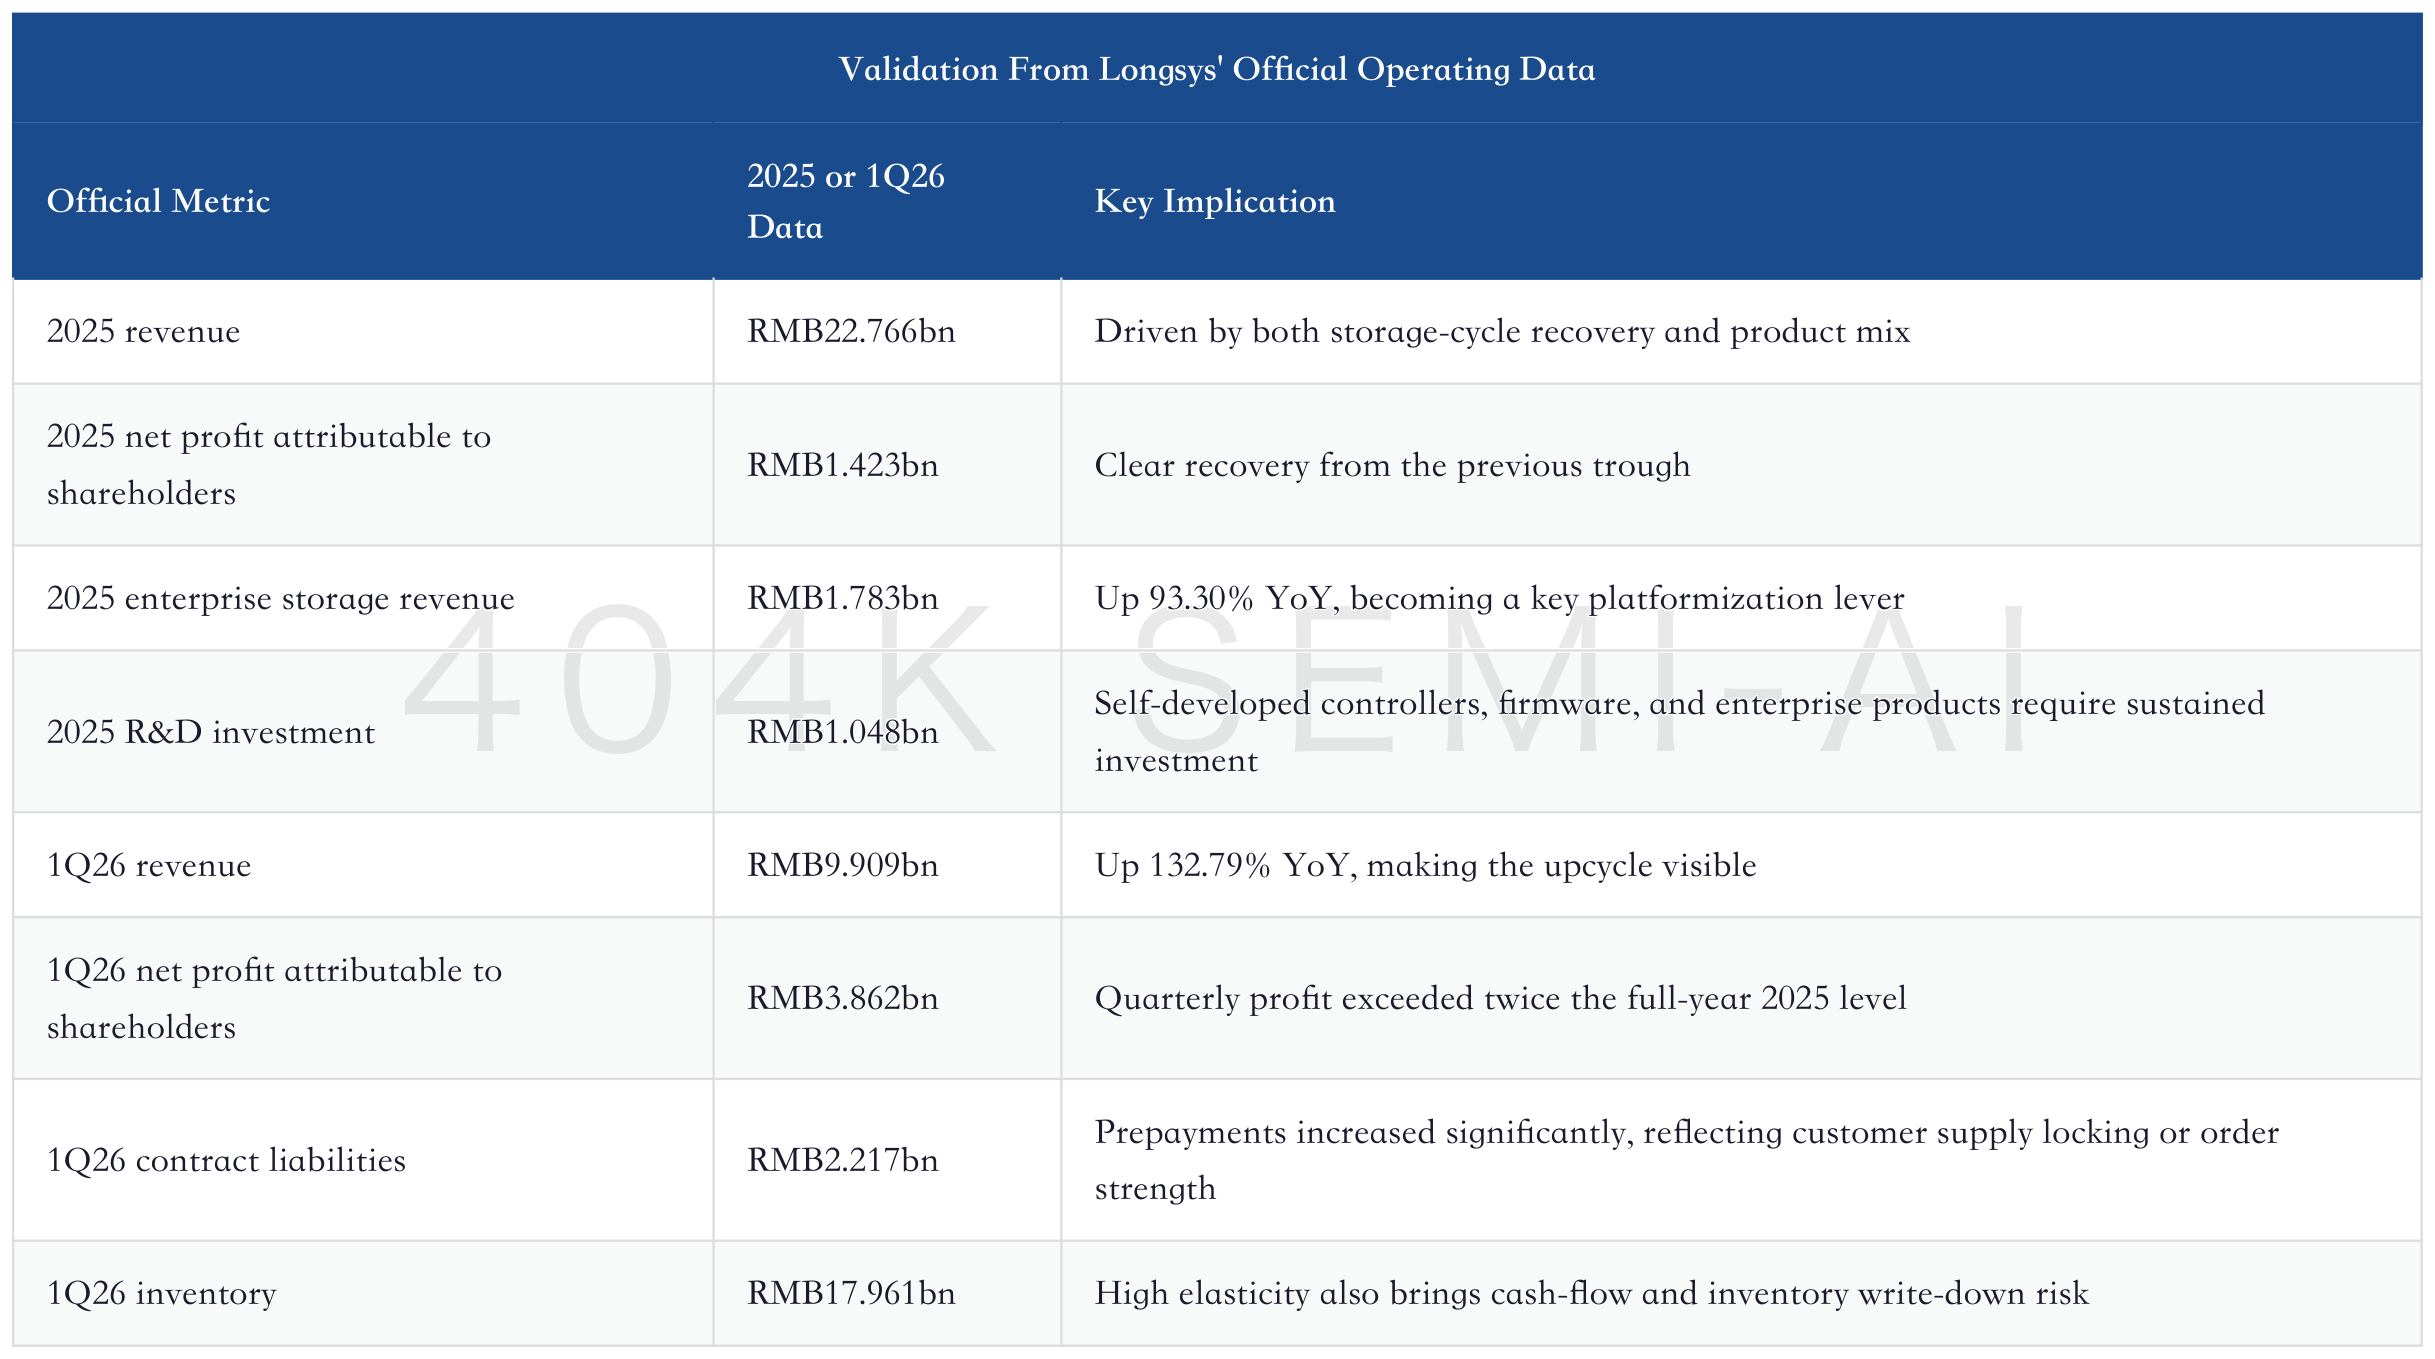
This official data set shows both sides of Longsys. On the positive side, 1Q26 earnings have already validated the explosiveness of the pricing cycle, and the sharp increase in contract liabilities shows customers are willing to lock in supply in advance. On the pressure side, inventory rose to RMB17.961bn and operating cash flow was negative, showing the company still carries heavy inventory and procurement pressure.
Therefore, Longsys is not simply “the more prices rise, the better.” In the early stage of price increases, high inventory is an earnings lever. In the late stage of price increases, high inventory becomes a risk lever. The significance of TCM is to reduce risk in the second half, but this still needs to be validated by subsequent financial reports.
XII. Why the TCM Model Has Become the Core of the Model
A large part of Morgan Stanley's upward revision to Longsys' long-term gross-margin assumption comes from TCM. In the past, the market's biggest concern when assessing module makers was that “inventory gains are not sustainable.” If a company only relies on low-cost procurement and selling into price increases, the gross-margin peak will inevitably be short, and it can easily be swallowed by the next round of price declines.
The TCM model changes profit attribution and risk sharing. It does not free Longsys from the storage cycle. Instead, when customer demand is clear, customization is stronger, and supply is tight, it allows Longsys to transfer part of the inventory pressure and price-volatility pressure to customers. Customers lock in supply, while Longsys locks in service value and processing value. Customers assume more stocking responsibility, and Longsys' gross margin is not fully exposed to spot-price volatility.
Whether this model can work depends on whether customers truly cannot do without Longsys' services. If the products are only ordinary SSDs or ordinary memory modules, customers have no reason to give module makers much profit. If the products are enterprise SSDs, embedded storage, automotive, AI devices, wearables, and customized firmware, Longsys' controller, firmware, testing and validation, and supply-chain integration capabilities have higher value.
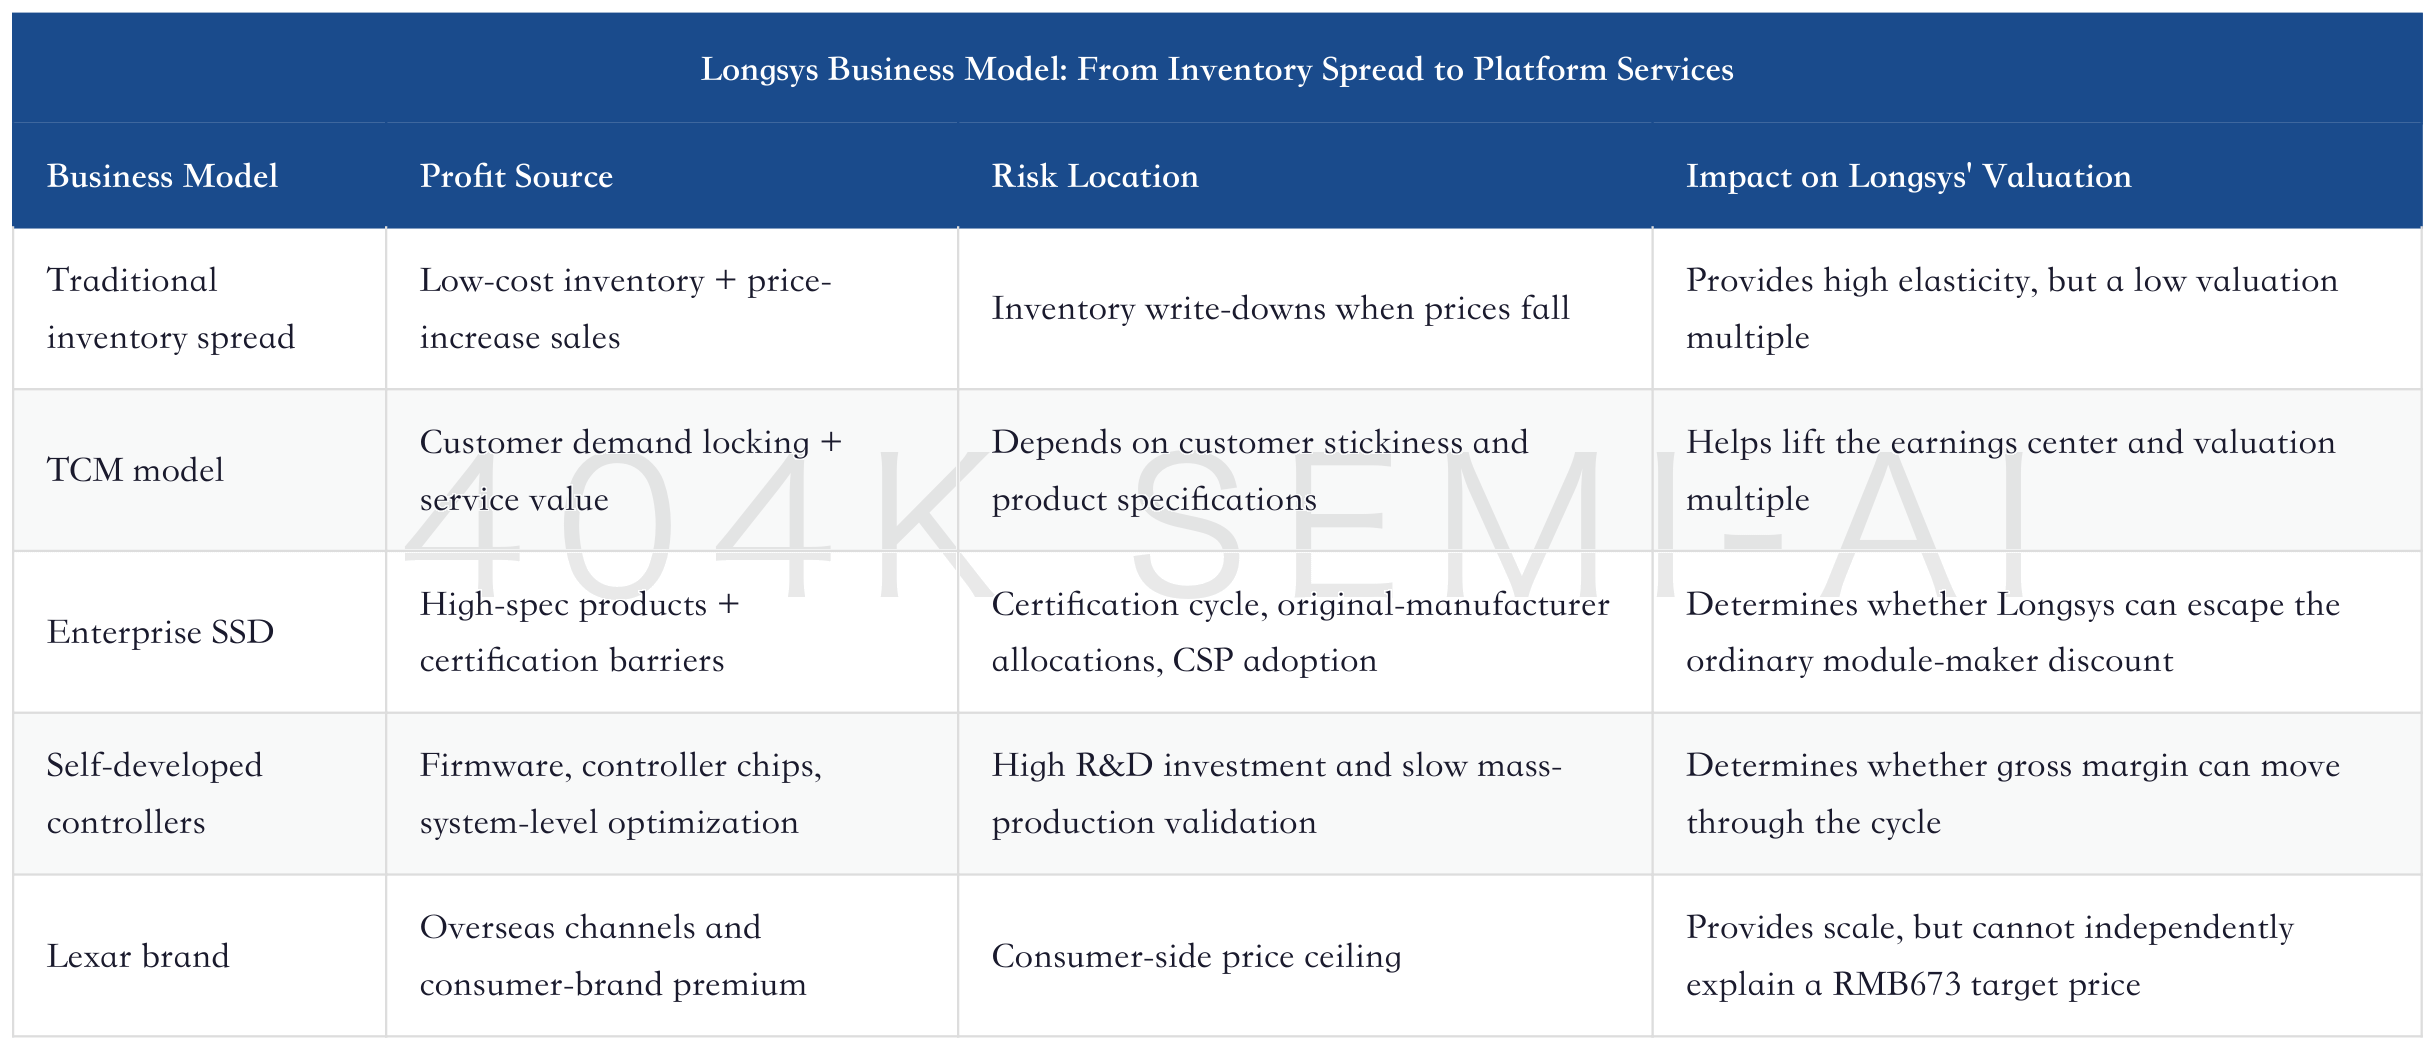
The key to TCM is not the name, but whether it can move Longsys from an “inventory trader” to a “storage solutions provider.” If it can, gross margin can be more stable than that of traditional module makers. If it cannot, the market will still discount 2026's high profits as a cyclical peak.
XIII. Enterprise SSD Is the Main Battleground for Whether the Valuation Holds
For Longsys to support a RMB 673 target price, it cannot rely only on consumer-end price increases. The problem on the consumer side is clear: smartphone and PC demand has not accelerated in tandem, channel inventory is relatively high, customers tend to cut orders after prices rise, and module makers’ low-cost inventory will also be gradually consumed. What can truly lift the profit center is enterprise SSD and storage tied to AI infrastructure.
The most important direction in Morgan Stanley’s industry report is that AI is pulling NAND out of the consumer electronics cycle and turning it into part of cloud vendors’ capex. AI servers require higher-capacity, more stable and more reliable enterprise SSDs. Training, inference, data preprocessing, logs, recovery, control planes and system disks all consume more NAND. Even if Longsys is not an original manufacturer, as long as it can raise specifications in enterprise SSD, RDIMM, embedded and automotive storage, it can participate in the cycle better than ordinary consumer module makers.
AI Hardware Restocking Deep Dive: Capacitors Hit New Highs, Nearline HDD Capacity Up 31% YoY, Enterprise SSD Capacity Up 139% YoY; How Data-Center Demand Spreads to Components and Storage
The company’s annual report discloses that Longsys already has eSSD and RDIMM design capabilities, product portfolios and scaled supply capability. SOCAMM has already been powered on, while MRDIMM and CXL2.0 modules are also progressing. In 1Q26, the company said customized edge AI storage products had already been supplied to North American smart-vehicle and autonomous-driving technology customers; ePOP4x had entered a North American wearable technology customer; and mSSD had entered introduction testing at leading PC customers and is expected to begin large-scale replacement of traditional SSDs in 2026.
These developments matter for valuation. If Longsys only makes consumer SSDs, the share price can only be assessed through NAND prices. If enterprise SSD and edge AI storage continue to scale, the share price can be assessed through customer mix and platform capability.
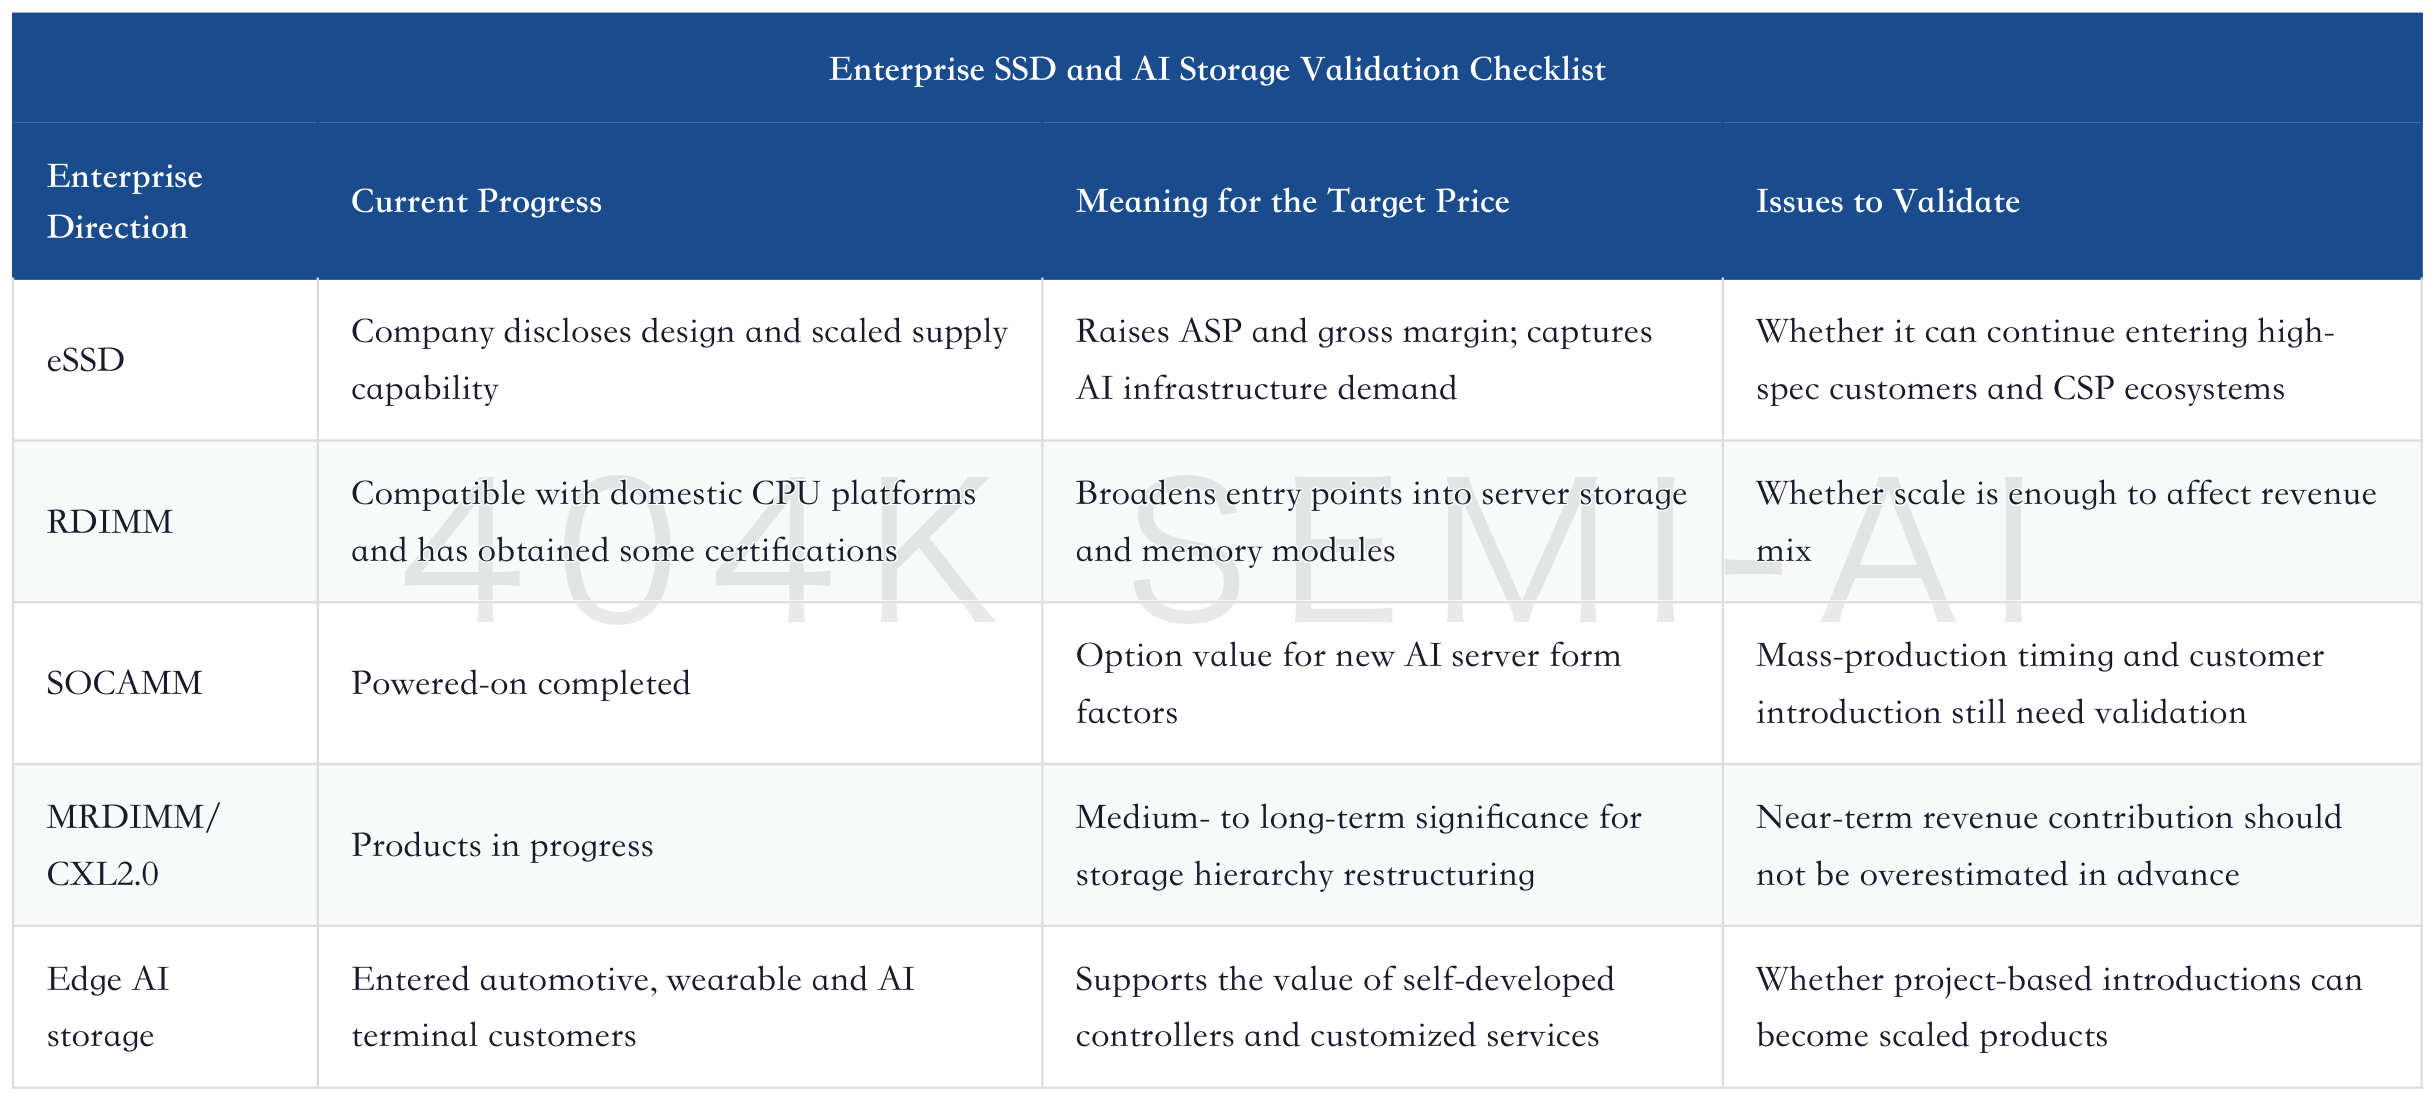
Whether enterprise SSD can scale is the most important quality test for the RMB 673 target price. NAND price increases can explain short-term profit; enterprise SSD is what can explain a higher valuation multiple.
XIV. Self-Developed Controllers: Gross-Margin Protection, Not a Universal Answer
In Longsys’s earlier investment thesis, self-developed controllers have always been a key variable. Morgan Stanley’s upward revision to its long-term gross-margin assumptions this time is also related to controllers, firmware and customized services. A controller is not simply a cost item. It determines product compatibility, performance, power consumption, stability, certification cycle and customer substitutability.
The company’s disclosed 5nm UFS 4.1 controller, HLC technology and SPU architecture all point in the same direction: Longsys is trying to connect NAND, controllers, firmware, packaging and application scenarios, rather than only doing procurement and assembly. HLC makes NAND more like an extension of DRAM, SPU supports high-capacity SSDs and higher NAND I/O, and the UFS 4.1 controller serves high-end smartphones and AI terminals.
The investment implication is that Longsys has the opportunity to turn “buying NAND” into “defining products.” If Longsys can define products, it has gross-margin protection. If it is only buying NAND and then assembling modules, the value of controllers will be drowned out by the pricing cycle.
SanDisk Deep-Dive Update: AI Demand, NBM Long-Term Agreements and NAND Profit Durability
But controllers should not be mythologized. In Morgan Stanley’s industry report, the controller companies that benefit more directly are independent controller suppliers and parts of the AI boot-drive chain. Longsys’s controller value is mainly reflected in the gross margin of its own products, customer customization and platform capability. It does not mean the company can directly enjoy the entire controller TAM. Put differently, Longsys’s controller capability is a reason for the valuation discount to narrow, not a reason to detach from the NAND cycle.
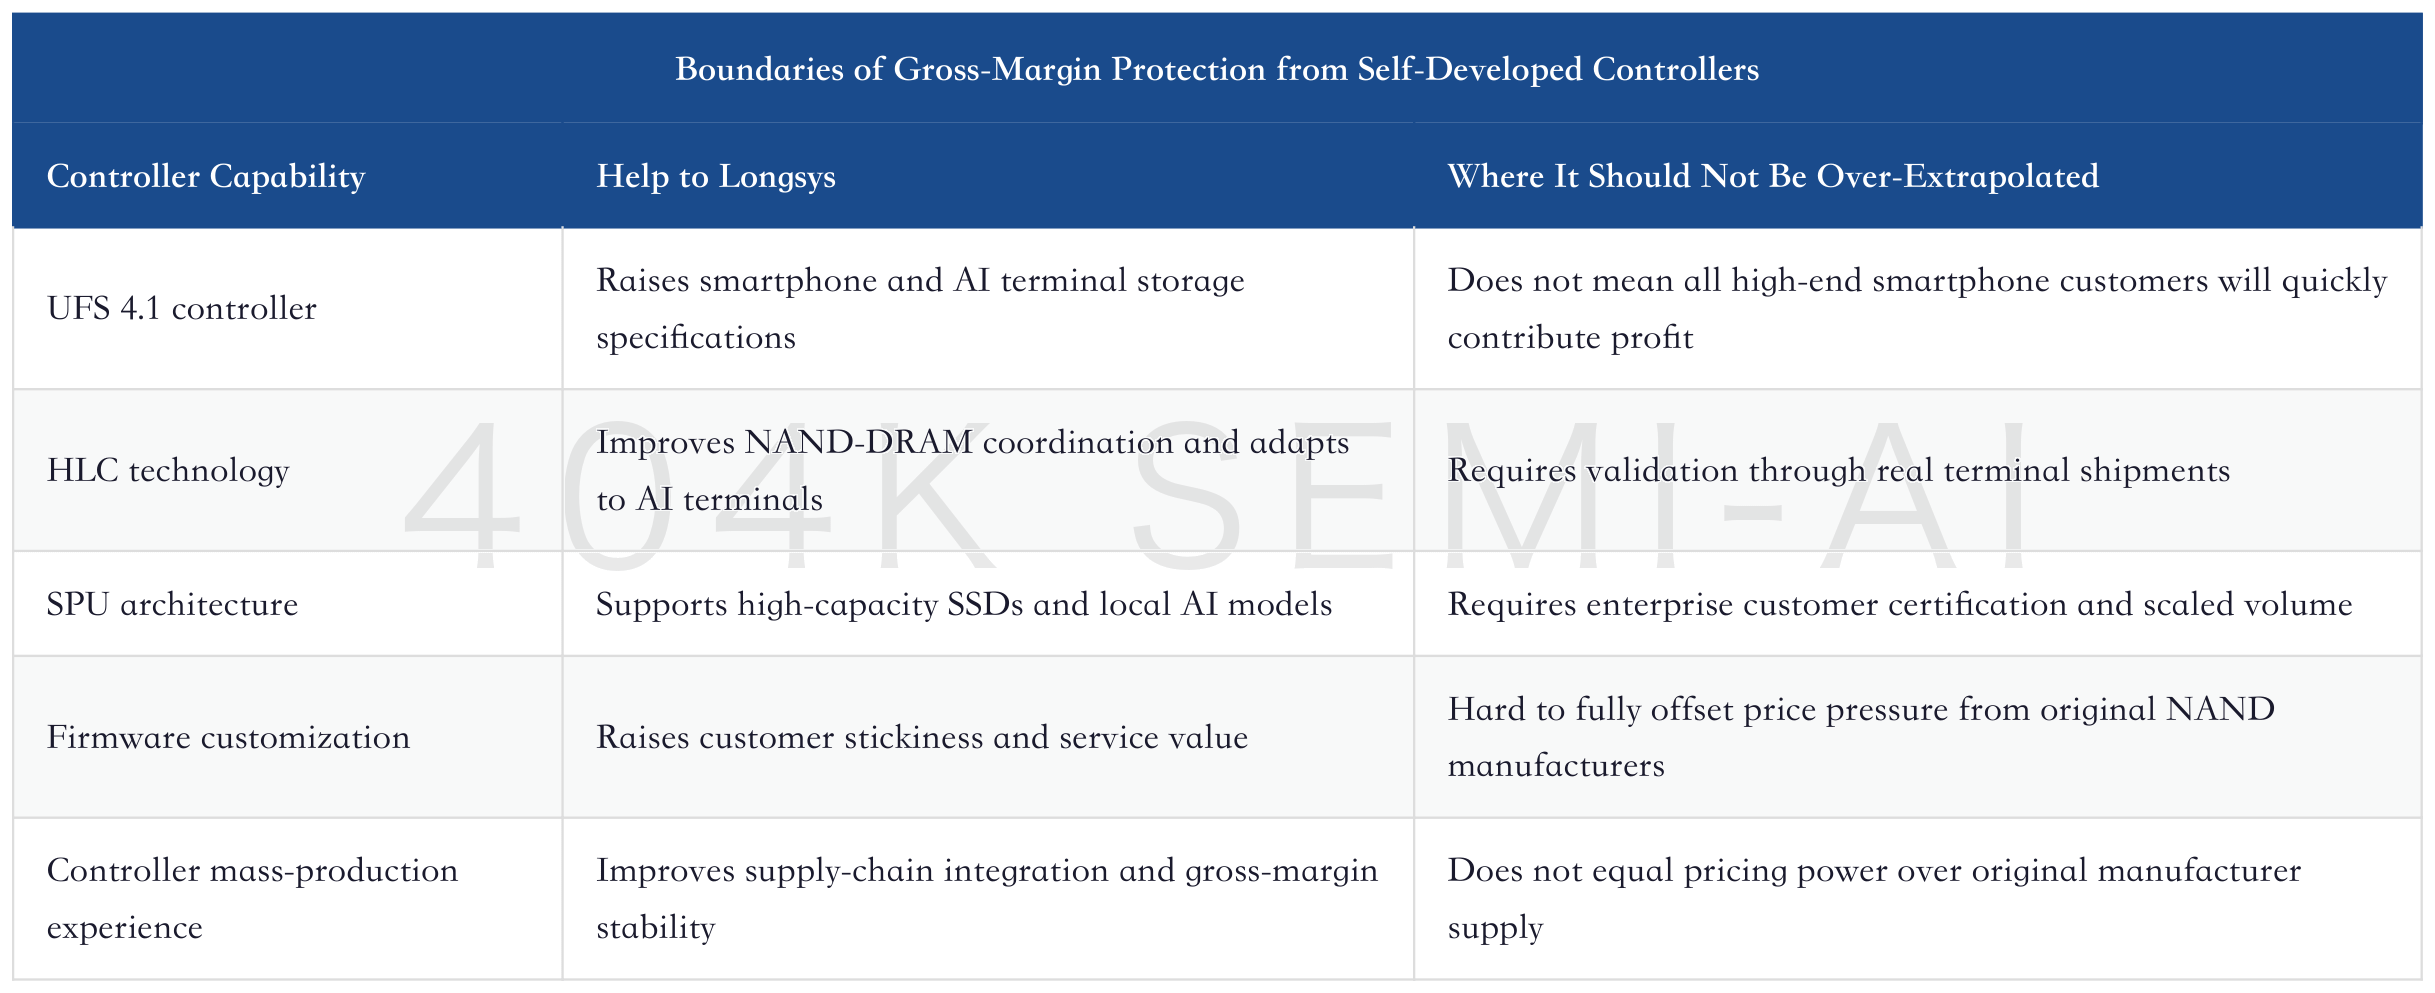
Controllers make Longsys more than a module maker, but it still needs to prove through financial results that controllers can retain profit. The most direct validation is whether gross margin can remain significantly above the previous cycle after low-cost inventory is gradually consumed.
XV. The Consumer End Is Not the Core Logic; It Is Instead a Source of Risk
Morgan Stanley’s NAND industry report draws a clear distinction between AI and the consumer end. On the AI side, CSP demand remains strong and long-term agreements support pricing. On the consumer side, module-maker and channel inventory is rising, smartphone and PC customers are beginning to weigh volume against profit after price increases, and some orders have already been cut.
This matters for Longsys. Longsys has the Lexar brand, as well as consumer SSDs, memory cards, portable storage and embedded products. Consumer-end price increases will directly lift revenue and gross margin. But the consumer end is not the highest-quality part of this target-price upgrade. The faster consumer prices rise, the more easily customers cut volume; the higher channel inventory is, the closer prices are to the ceiling.
Morgan Stanley’s view is that consumer-grade NAND prices may soon hit an upper bound, while original manufacturers will allocate more capacity to AI and server customers. This means module makers will face a combination of rising procurement costs, cautious ordering from consumer customers, and enterprise customers that may not grant sufficient allocation. Longsys is still being upgraded because Morgan Stanley believes its product mix and TCM mechanism can buffer this pressure set.
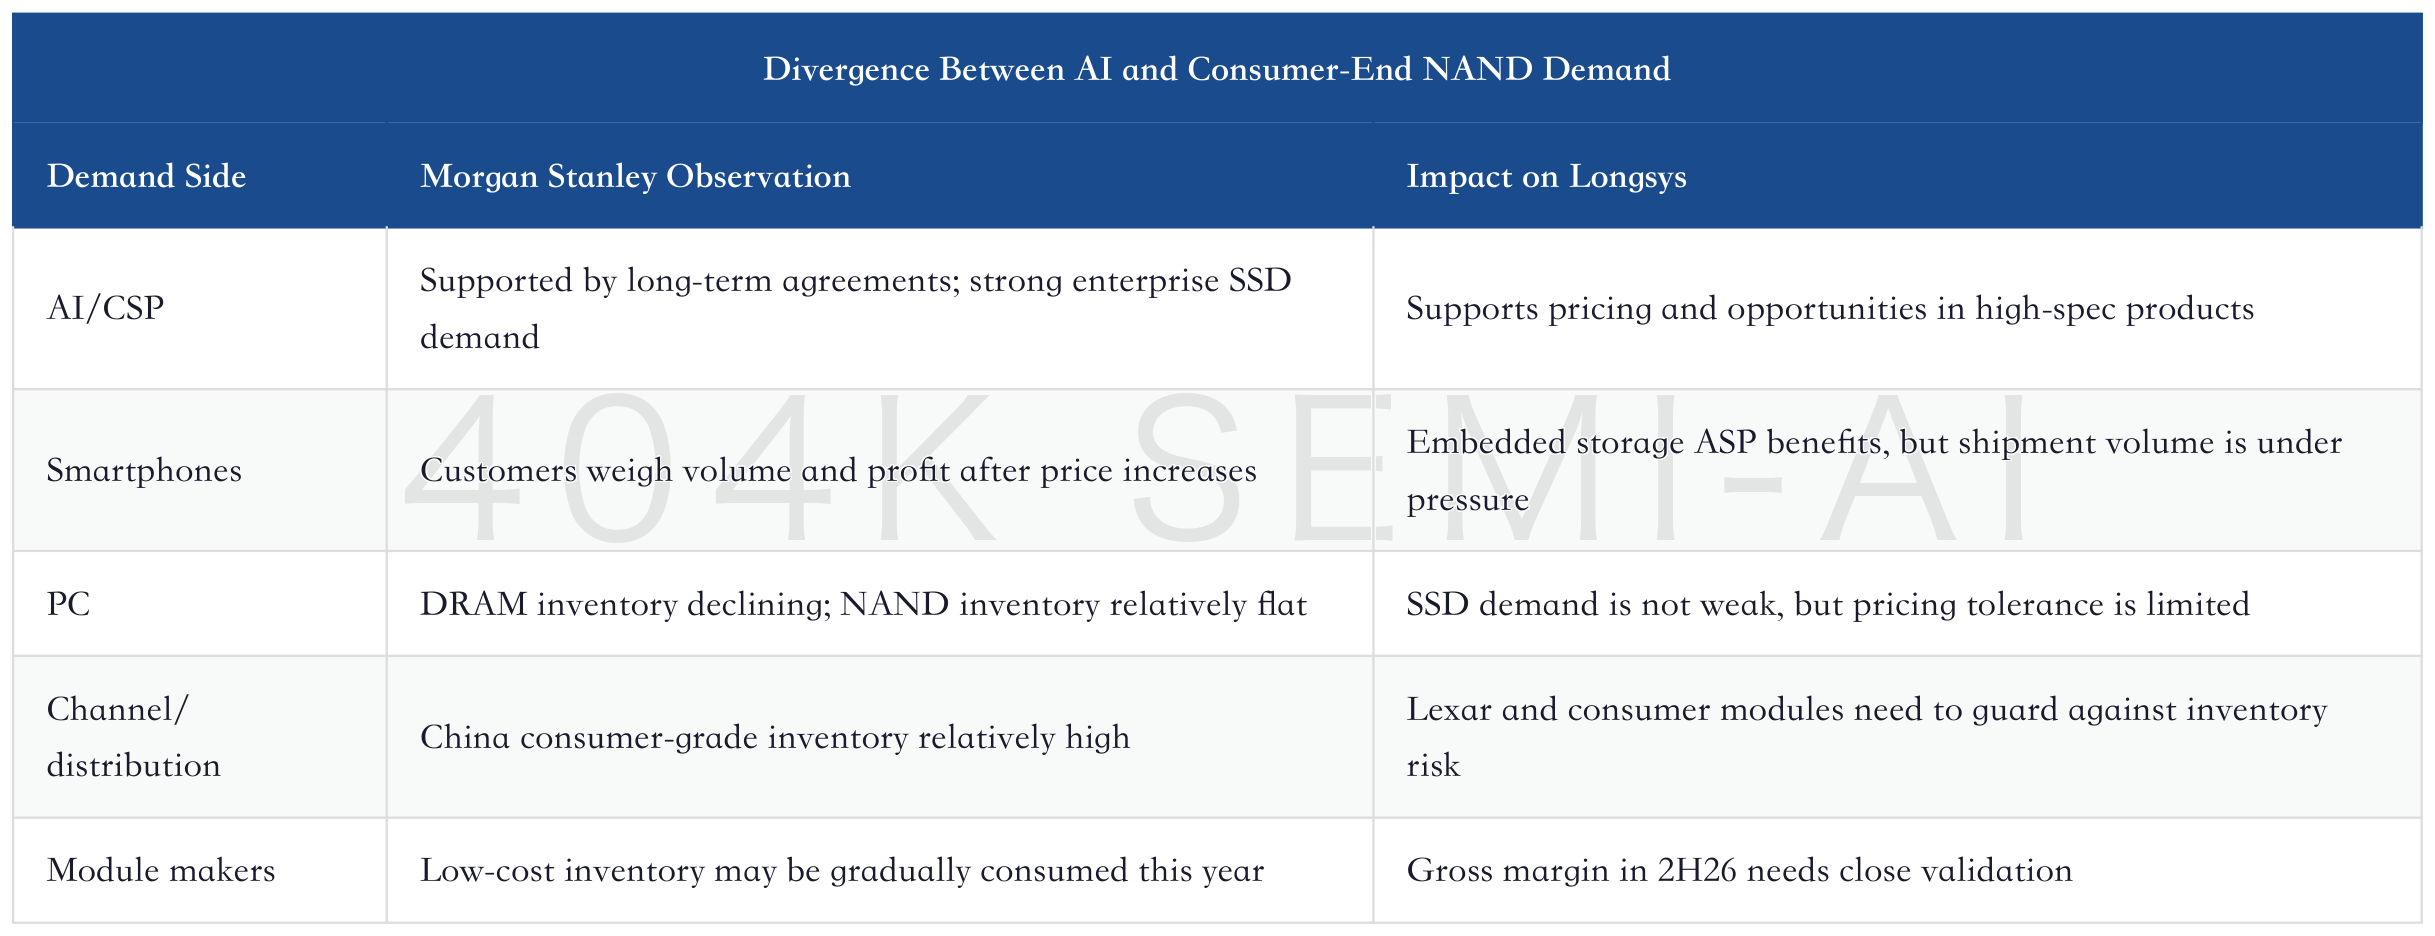
Therefore, the investment judgment on Longsys cannot only look at “NAND price increases.” If price increases come from AI demand and are retained as gross margin through enterprise products and TCM, that is high-quality pricing. If price increases mainly come from consumer-end restocking and inventory gains, that is high-beta but low-multiple.
XVI. 2028 Supply Risk: Yangtze Memory Is a Variable, Not Only a Positive
Morgan Stanley pushes back the timing of Longsys’s earnings downside to 2028, with the core premise that NAND remains in shortage in 2026-2027. But there is an unavoidable variable in 2028: new capacity, especially new NAND capacity in China.
For Longsys, increased Chinese NAND supply has dual implications. On the positive side, Longsys can obtain more local supply, improving procurement security and shipment volume. On the risk side, if new capacity is released too quickly, industry pricing may move from shortage to surplus, compressing Longsys’s profit margin.
Morgan Stanley conducted scenario analysis for 2028. If AI SSD demand continues to grow rapidly and capacity expansions by Yangtze Memory and others remain disciplined, NAND may still be tight. If AI demand growth slows while new capacity is released quickly, the industry will re-enter a loose-supply environment.
Kioxia Deep-Dive Update: JPY 155,000 Target Price, NAND Cash Flow and AI SSD Re-Rating
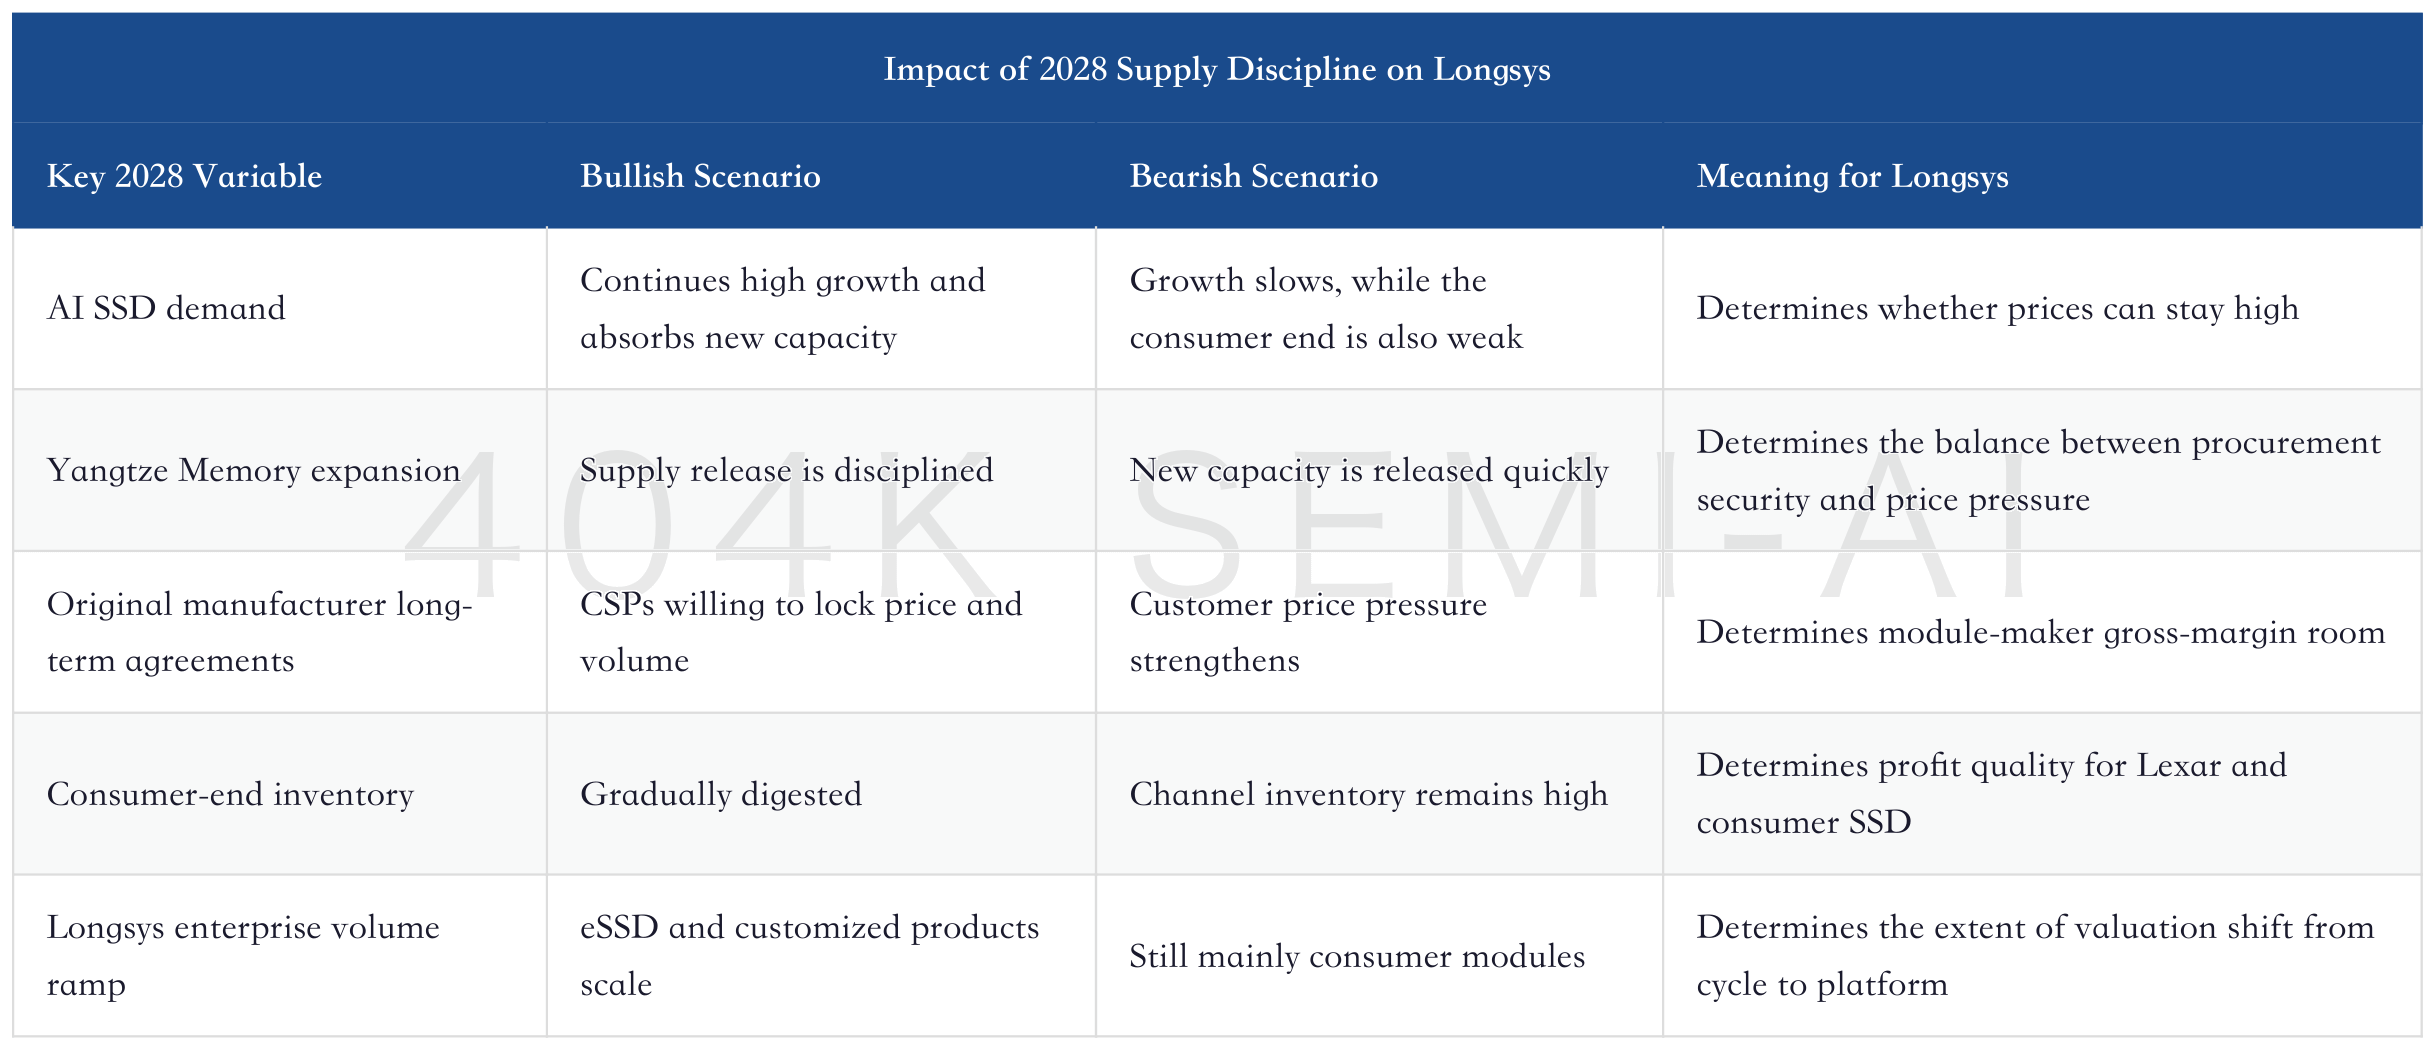
2028 is the real exam for Longsys’s re-rating. High profit in 2026 can be explained by inventory and price increases; high profit in 2027 can be explained by the industry gap; by 2028, the question is whether Longsys has truly built high-spec customer and product barriers.
XVII. Bull-Bear Scenarios: RMB 673 Is Not the Most Optimistic Target Price
Morgan Stanley’s target price for Longsys is not a point forecast, but a middle choice among three scenarios. The bull-case target price is RMB 852, the base case is RMB 673, and the bear case is RMB 587. The upside and downside appear asymmetric, but note that the bear case is not a zero-profit scenario. It is a scenario in which prices and valuation multiples reset lower.
The base case corresponds to: AI NAND demand supports pricing in 2026-2027; Longsys raises its profit center through TCM, enterprise SSD, self-developed controllers and overseas brands; and pricing downside pressure begins only in 2028. In this scenario, the RMB 673 target price corresponds to 15.8x 2027E P/E.
The bull case corresponds to: AI investment continues to accelerate, CSPs continue to lock in NAND, edge AI demand from smartphones and PCs recovers, supply discipline holds, and Longsys not only benefits from prices but also expands its share in enterprise and high-end products. In this scenario, the target price is RMB 852, corresponding to about 20x 2027E P/E.
The bear case corresponds to: edge AI demand is weaker than expected, supply expansion outpaces demand around 2028, NAND prices decline earlier, and Longsys’s high profit is viewed by the market as a cyclical peak. In this scenario, the target price is RMB 587, and valuation shifts toward book value and a cycle-trough framework.
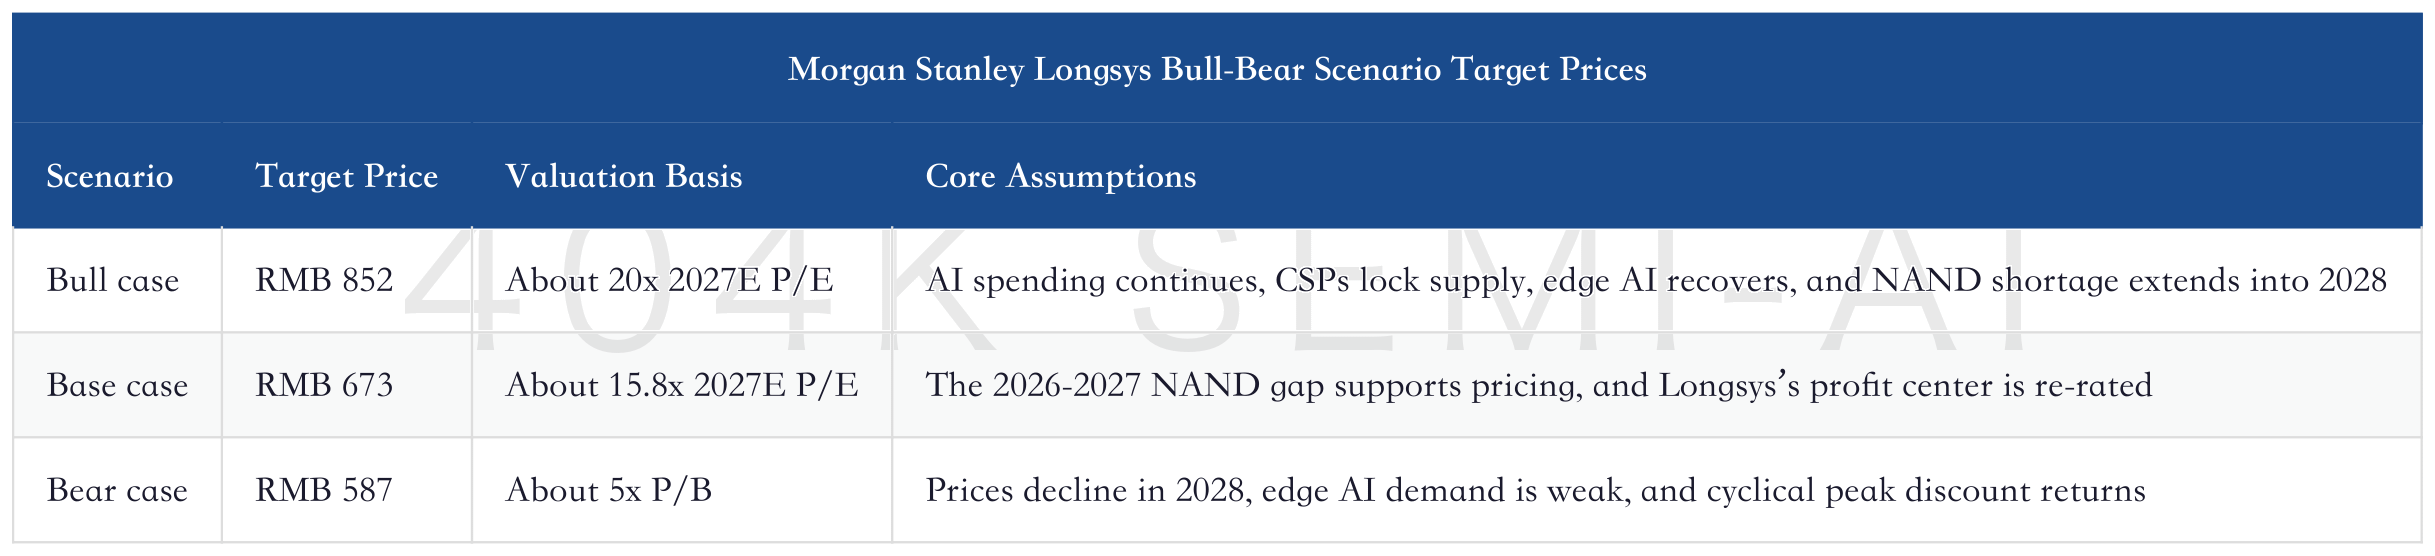
The key information in this scenario set is that Morgan Stanley has not completely denied cycle risk. It simply believes that under the new AI NAND supply-demand assumptions, Longsys’s base-case profit level has been systematically lifted.
18. Differences Versus the Previous Longsys Deep Dive
The previous Longsys deep dive focused on explaining why the company should not be valued only as a “storage module vendor”: enterprise SSDs, self-developed controllers, the Lexar brand, AI devices, and the domestic storage supply chain were all lifting the company’s asset attributes. At that point, the framework was more about structural re-rating.
This Morgan Stanley target-price upgrade converts that structural framework into a financial model. The old thesis answered “why Longsys is more than just a module vendor”; the new thesis answers “how much EPS and target price this change can be worth.”
The difference is that the old thesis focused on asset attributes, emphasizing the transition from storage modules to platform capabilities; the new thesis focuses on profit delivery, directly laying out 2026-2028 revenue, gross margin, net profit, and target-price scenarios. For investment judgment, this step matters more, because the market no longer lacks a Longsys narrative. What it lacks is proof that earnings can support a high share price.
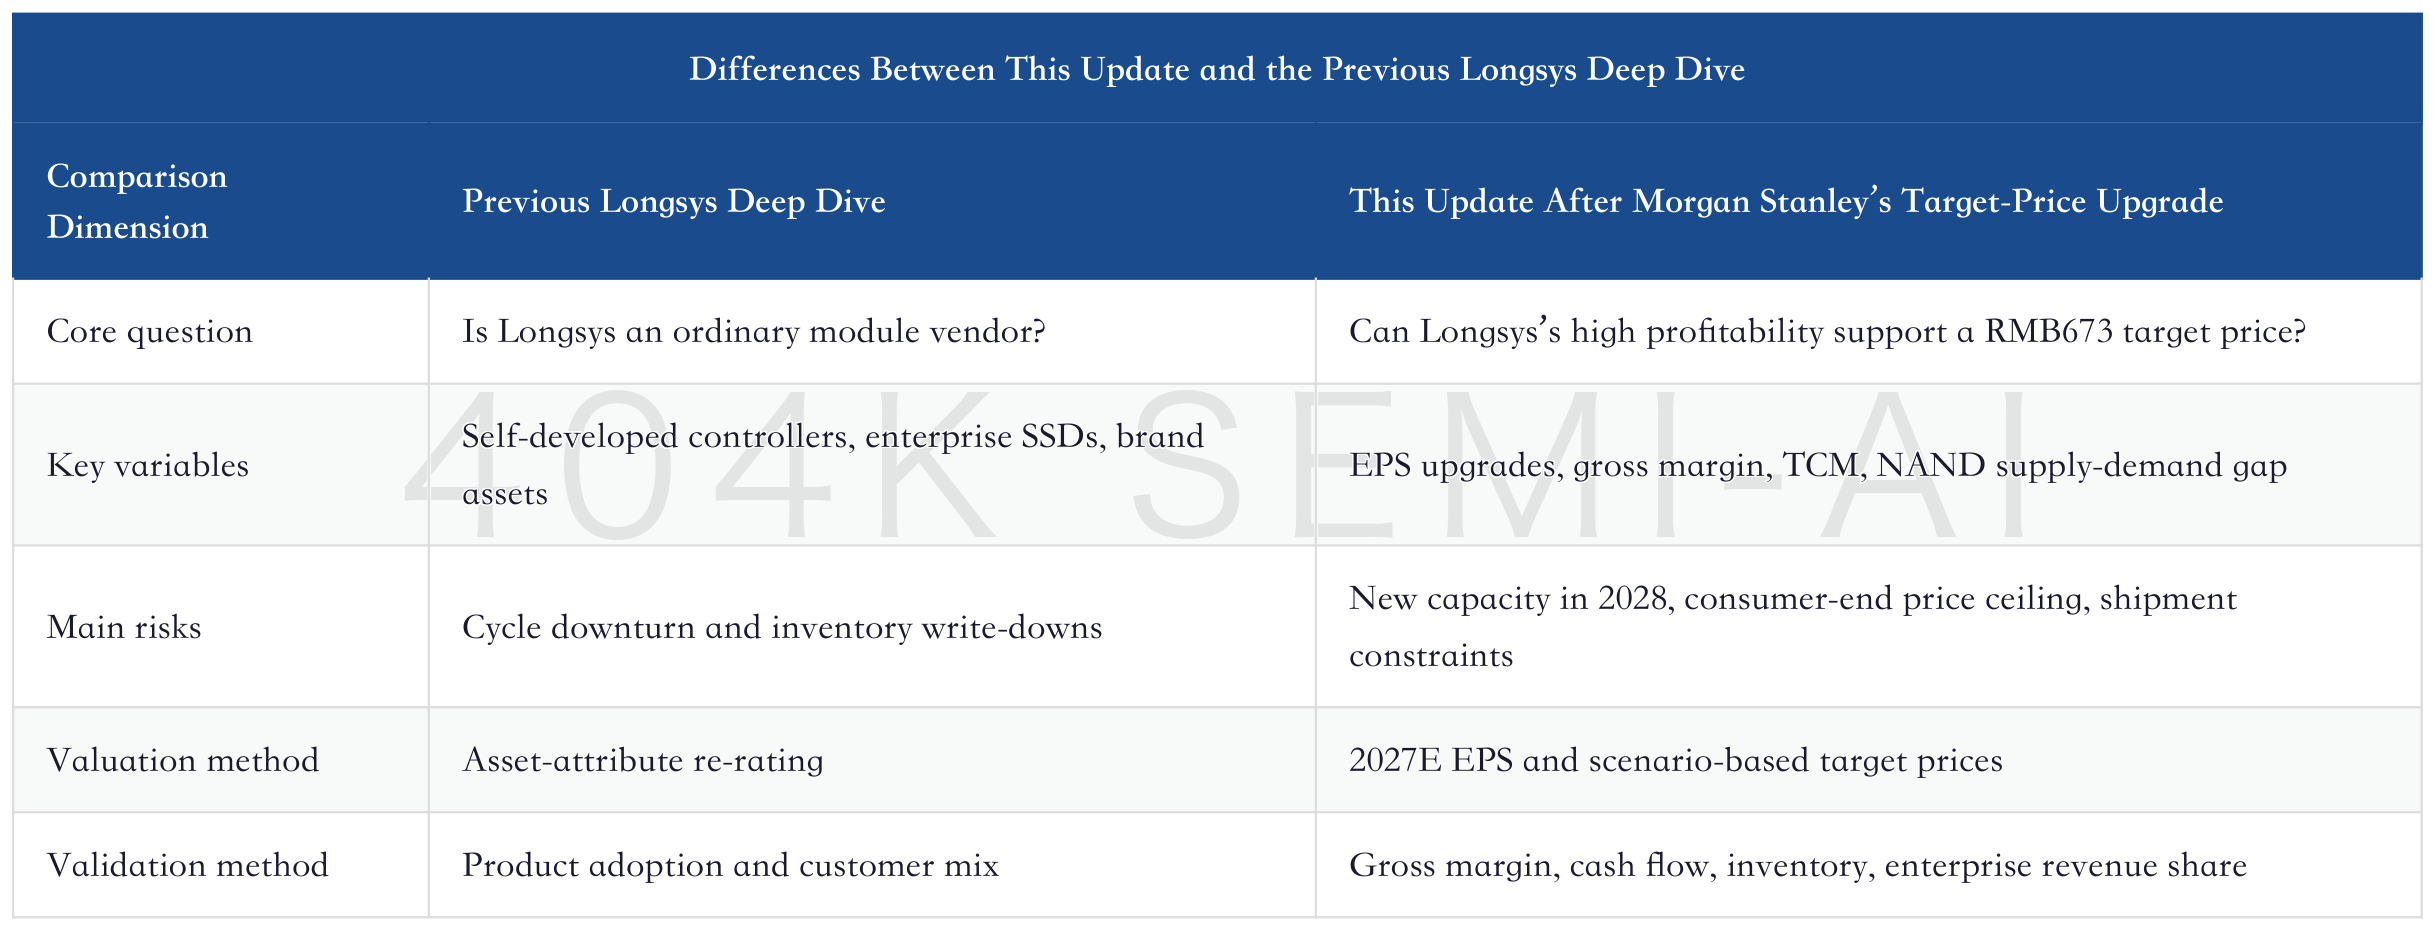
In other words, the research focus on Longsys has shifted from “whether the story makes sense” to “whether the model can be delivered.” That is more demanding for the share price, and also more valuable.
19. How to Understand This Upgrade Near the Current Share Price
Based on the share-price reference in Morgan Stanley’s report, Longsys was trading at about RMB599 at the time, versus a target price of RMB673, implying roughly 12% upside on the surface. That is not a large margin, but the change behind the model is significant. This combination is common: fundamental expectations have been raised sharply, but the share price has already priced in most of it.
Therefore, the RMB673 target price is more like a new valuation anchor than a simple near-term upside estimate. It tells the market that if 2027E EPS can really reach RMB42.62, Longsys should no longer be discounted under the old module-vendor framework. But it also reminds the market that if the share price is already close to the base-case target, further upside requires evidence closer to the bull-case scenario.
What evidence could push Longsys from RMB673 toward RMB852? First, the AI NAND shortage persists into 2028, and new capacity does not undermine pricing. Second, enterprise SSD and customized storage revenue continue to grow faster than the company overall. Third, after low-cost inventory is gradually consumed, gross margin can still remain far above the level of the previous cycle. Fourth, operating cash flow improves from the pressure of high inventory.
What evidence would pull Longsys toward the bear-case scenario? First, consumer-grade NAND prices fail to rise, and smartphone and PC customers cut orders. Second, original manufacturers reserve more supply for CSPs, leaving module vendors unable to secure enough high-quality supply. Third, new supply before 2028 weakens pricing expectations. Fourth, inventory and cash-flow pressure deteriorate before the income statement does.
The follow-up catalysts and risk watchlist can be compressed into six items. Continued gross-margin beats in 2Q26/3Q26 would be the most direct positive signal, with the focus on whether margins approach or exceed Morgan Stanley’s high gross-margin assumption; a rising enterprise storage revenue share would also be positive, with attention on progress in eSSD, RDIMM, and edge AI storage customers; continued growth in contract liabilities would be somewhat positive, but it must be checked whether this represents customer lock-in or delivery pressure; continued rapid inventory growth is a double-edged sword, serving as leverage in an upcycle and risk in a downcycle; operating cash-flow improvement is the cleanest positive validation, proving that profit is not being entirely absorbed by inventory; weakening NAND spot and contract prices would be the most direct negative signal, compressing both gross margin and valuation multiples.
The main misread to avoid at this stage is interpreting a “sharp target-price upgrade” as “share-price risk has disappeared.” The reality is the opposite: the higher the target price, the higher the market’s requirements for Longsys’s subsequent financial reports.
20. Four Tracking Indicators
Longsys should not be tracked only through NAND spot prices from here. NAND prices are important, of course, but looking only at price can easily pull Longsys back into an ordinary cyclical-stock framework. A better approach is to break the target-price model into four financial and business indicators.
First, gross margin. Morgan Stanley’s 2026E gross-margin assumption of 55% is very high, which means the market will treat Longsys’s quarterly gross margin as a core validation item. If gross margin remains strong, it means TCM, product mix, and inventory costs are still contributing; if gross margin falls quickly, the target-price model will be directly weakened.
Second, enterprise storage revenue. Enterprise storage revenue was RMB1.783 billion in 2025, up 93.30% year on year. If this segment continues to grow faster than the company overall, Longsys has a chance to move from a consumer module stock into an enterprise storage platform. If growth slows, the market will still price the company as a cyclical-beta stock.
Third, inventory and operating cash flow. Inventory was RMB17.961 billion in 1Q26, and operating cash flow was negative. This is not simply negative, because stocking up in an upcycle naturally consumes cash. But if inventory keeps rising and operating cash flow does not improve, the market will worry that the income statement is leading while cash flow lags, and that subsequent inventory write-down losses may emerge.
Fourth, long-term agreements and customer advances. Contract liabilities were RMB2.217 billion in 1Q26, indicating signs of customers locking in supply ahead of time. If contract liabilities and customer agreements continue to improve, that would support Morgan Stanley’s judgment on the 2027 supply-demand gap; if customers shift to wait-and-see mode, the consumer-end price ceiling will appear faster.
The validation logic for these indicators is also clear. If gross margin remains high, it shows TCM and product mix are effective; if it falls quickly, it shows the inventory benefit is not sustainable. If enterprise storage continues to grow faster than the company overall, Longsys has a chance to move beyond consumer-module-driven growth; if it slows, the company will still be priced as a cyclical-beta stock. If inventory and operating cash flow improve at the same time, earnings quality will be more solid; if inventory continues to build and cash flow remains under pressure, the market will begin to worry about late-cycle risk. If contract liabilities and LTAs continue to strengthen, it means customers’ willingness to lock in supply remains strong; if customers cut orders or wait, the consumer-end price ceiling will arrive earlier. If 2028 supply remains disciplined, AI can continue to absorb new capacity; if new supply pushes NAND prices lower, the RMB673 target price will need to be discounted again.
These four indicators turn the RMB673 target price into a verifiable framework, rather than something that exists only inside a brokerage model.
21. Bottom-Line Judgment: Validate Delivery First, Then Discuss the Valuation Ceiling
After Morgan Stanley’s target-price upgrade, Longsys’s share-price pricing will shift from “whether there is operating leverage” to “how long that leverage can last.” The company has already proved that it is highly sensitive to rising NAND prices. What it has not fully proved is whether, as low-cost inventory is gradually consumed, consumer-end price increases approach the ceiling, and original manufacturers prioritize supply allocation to AI customers, Longsys can still retain profit through TCM, enterprise SSDs, and controllers.
The more appropriate tracking sequence is to validate financial delivery first, then discuss the valuation ceiling. If gross margin, contract liabilities, and enterprise revenue all remain strong over the next two quarters, RMB673 will become a conservative base case, and the market will then open up the RMB852 bull-case scenario. If profit is strong but cash flow and inventory continue to deteriorate, the target-price upgrade will instead become a risk warning, because the market will worry that the profit peak has arrived too quickly and may also fade quickly.
Therefore, the best state for Longsys now is not simply the highest possible single-quarter profit, but simultaneous improvement in profit, cash flow, and business mix. As long as these three conditions do not hold at the same time, the RMB673 target price remains only Morgan Stanley’s base-case scenario, not a pass for unconditional share-price upside.
This is also the real meaning of Morgan Stanley maintaining a Neutral rating: the earnings model has clearly moved higher, but delivery evidence still needs to be filled in, especially around 2027 EPS and 2028 supply discipline.
After the target-price upgrade, every Longsys quarterly report will become a re-pricing event for this model.
22. Conclusion: The RMB673 Target Price Is Longsys’s New Threshold
Morgan Stanley raised its target price for Longsys from RMB300 to RMB673. The most important implication is not that the “target price doubled,” but that Longsys’s valuation framework has been pushed to a higher threshold: the market is no longer only asking whether storage prices have risen, but whether Longsys can convert NAND price increases, the TCM model, enterprise SSDs, and self-developed controllers into a sustainable profit center.
After this update, the Longsys research framework can be summarized in three sentences.
First, 2026 earnings leverage has been raised significantly. Morgan Stanley’s 2026E EPS of RMB59.86 and 55% gross margin are very strong upcycle assumptions. If subsequent financial reports deliver, Longsys can no longer be valued under the old module-vendor framework.
Second, 2027 is the core year for the target price. The RMB673 target price is essentially anchored to 2027E EPS of RMB42.62, rather than only looking at 2026 windfall profits. As long as NAND remains in shortage in 2027, enterprise SSDs continue to scale, and TCM protects gross margin, Longsys’s re-rating will have a financial foundation.
Third, 2028 will determine whether this re-rating is a cyclical illusion. If new capacity is released too quickly, AI NAND demand slows, and consumer-end inventory pressures pricing, Longsys may still return to cyclical-stock logic. If supply discipline continues and enterprise SSD and controller capabilities stand firm, Longsys will truly complete the shift from module beta to platform asset.
Therefore, RMB673 is not the finish line, but a new exam. Longsys has received an entry ticket to higher profit assumptions. The next step is to use gross margin, cash flow, enterprise revenue, and customer LTAs to prove that this is not another inventory-cycle peak, but an upward shift in the profit center of a storage platform company.Longsys Deep-Dive Update: How Morgan Stanley’s RMB673 Target Price, AI NAND Shortage, and TCM Model Revalue Its Enterprise SSD Platform
目录
Too Long; Didn’t Read
I. RMB673 Target Price: What Exactly Did Morgan Stanley Change?
II. Why the Target Price Can Jump from RMB300 to RMB673
III. Product-Line Breakdown: The Upgrade Is Not a Single-Category Bet
IV. 2027E EPS Is the Core of the RMB673 Valuation
V. Why Morgan Stanley Prefers Original Manufacturers, While Still Upgrading Longsys
VI. Cash Flow and Inventory: The Hard Constraints Behind High Profit
VII. The Rating Remains Equal-weight: Morgan Stanley Has Not Made Longsys a Top Pick
VIII. Valuation Methodology: RMB673 Is Not Simply a High P/E Multiple
IX. AI NAND Shortage Is the Primary Driver of Upward Revisions
X. Cross-Checks From the Past Week: Morgan Stanley Is Not the Only One Revising NAND Upward
XI. Longsys’ Advantage: Not an Ordinary Low-Cost Inventory Module Maker
XII. Why the TCM Model Has Become the Core of the Model
XIII. Enterprise SSD Is the Main Battleground for Whether the Valuation Holds
XIV. Self-Developed Controllers: Gross-Margin Protection, Not a Universal Answer
XV. The Consumer End Is Not the Core Logic; It Is Instead a Source of Risk
XVI. 2028 Supply Risk: Yangtze Memory Is a Variable, Not Only a Positive
XVII. Bull-Bear Scenarios: RMB 673 Is Not the Most Optimistic Target Price
18. Differences Versus the Previous Longsys Deep Dive
19. How to Understand This Upgrade Near the Current Share Price
20. Four Tracking Indicators
21. Bottom-Line Judgment: Validate Delivery First, Then Discuss the Valuation Ceiling
22. Conclusion: The RMB673 Target Price Is Longsys’s New Threshold
本内容基于公开资料和研报数据整理,不构成任何投资建议,不代表任何个人观点,仅供学习参考,请理性阅读
Morgan Stanley raised its Longsys target price from RMB300 to RMB673. The real change is not a short-term price-hike assumption, but the incorporation of the 2027 NAND shortage, TCM model, enterprise SSD platform capability, and 2028 supply discipline into the earnings base. It also shifts the market focus from memory price increases to whether EPS can be delivered.
Too Long; Didn’t Read
Morgan Stanley is not making a minor model tweak this time; it is rewriting Longsys’s earnings peak. The target price more than doubles to RMB673, mainly because EPS over the next three years has been systematically lifted. 2027E EPS of RMB42.62 becomes the valuation anchor, implying roughly 15.8x P/E.
A target-price increase does not mean a rating upgrade. Morgan Stanley still rates Longsys Equal-weight because the current share price already discounts substantial NAND upside expectations, and Morgan Stanley prefers original manufacturers over module makers. Longsys’s opportunity lies in a re-rating of its earnings base; its risks lie in shipment volume, inventory, and 2028 supply discipline.
The first pillar of the model upgrade is the AI NAND shortage. Morgan Stanley expects AI-related NAND demand to rise from 205EB in 2025 to 609EB in 2027, with its share of total NAND demand rising from 18% to 41%. Goldman Sachs on Kioxia, Citi on SanDisk, and Korean memory price trackers have all provided evidence in the same direction over the past week. Industry tightness is not an isolated model output.
The second pillar is the TCM model and in-house controllers. Longsys is not merely a traditional module maker that hoards low-cost inventory and resells it. TCM transfers part of the inventory burden to customers, while in-house controller and firmware capabilities raise the value of customized services. This explains why Morgan Stanley lifted its long-term gross-margin assumption from about 18% to the 25%-38% range.
The largest debate is 2028. If AI SSD demand continues to grow rapidly and original manufacturers maintain supply discipline, Longsys can scale enterprise SSDs, in-house controllers, and the Lexar brand into platform assets. If new capacity from YMTC and others ramps too quickly, NAND may shift from shortage to surplus, making Longsys’s high EPS look more like a cyclical peak.
Four numbers now need tracking for Longsys: whether 2026 gross margin can approach Morgan Stanley’s new 55% assumption; whether enterprise storage can continue to grow faster than the company overall; whether inventory and operating cash flow can improve from the high-pressure state in 1Q26; and whether 2027 long-term contract pricing can remain supportive after consumer-end price increases slow.
I. RMB673 Target Price: What Exactly Did Morgan Stanley Change?
The most eye-catching number in Morgan Stanley’s update on Longsys is the target-price increase from RMB300 to RMB673. The scale is too large to be explained simply as “memory prices are rising, so the target price is higher.” The real point is that Morgan Stanley has rewritten Longsys’s earnings cycle from a brief price rebound into a NAND profit re-rating that lasts at least until 2027.
More precisely, this upgrade has three layers.
First, 2026 earnings are no longer just inventory gains. They are treated as a super-profit year driven jointly by the AI NAND shortage, consumer-end price catch-up, and product mix. Morgan Stanley raised Longsys’s 2026E revenue to RMB65.852bn, net profit to RMB23.974bn, and EPS to RMB59.86. This is already far above the company’s full-year 2025 net profit attributable to shareholders of RMB1.423bn, meaning the model treats 2026 as a very steep segment of the memory upcycle.
Second, 2027 is no longer treated as the starting point of a cyclical decline. Morgan Stanley had previously been more concerned about a downturn beginning in 2H27. It now pushes the downturn to 2H28 and raises 2027E EPS to RMB42.62. The RMB673 target price is essentially priced around this 2027E EPS, equal to about 15.8x 2027E P/E.
Third, 2028 remains clearly contested. Morgan Stanley does not write 2028 as a year of certain continued strength. Instead, it leaves the question to supply discipline: if AI NAND continues to absorb new capacity, Longsys’s profit platform can be sustained; if new Chinese capacity comes online faster than AI demand, NAND prices will fall again and Longsys will return to a cyclical-stock framework.
Longsys Deep Dive: From Storage Modules to an Enterprise SSD Platform, and How the AI NAND Upcycle Revalues Controllers and Brand Assets
This also explains why Morgan Stanley sharply raised the target price while keeping the rating at Equal-weight. The model has become more optimistic, but the price already reflects part of that optimism. Longsys still has re-rating potential, but the re-rating has entered a phase with a high delivery bar.
The most important figure in this table is not the target price itself, but 2027E EPS. If RMB42.62 is achievable, RMB673 is not expensive. If 2026 is the cyclical peak and inventory and pricing pressure arrive earlier in 2027, RMB673 becomes a very high delivery hurdle.
II. Why the Target Price Can Jump from RMB300 to RMB673
Morgan Stanley’s target-price increase mainly comes from rewriting three assumptions: higher revenue, higher gross margin, and a later earnings downturn.
On revenue, almost all of Longsys’s core products were revised upward. Embedded storage, mobile storage, SSDs, and memory modules all benefit from NAND price revaluation in 2026-2027. In the past, the market viewed Longsys as “storage modules plus branded channels”: revenue elasticity was strong, but gross margin and cash flow were easily consumed by the inventory cycle. This time, Morgan Stanley is more willing to view the company as a storage platform supported by enterprise SSDs, in-house controllers, TCM, and brand capabilities.
The gross-margin revision is more aggressive. Morgan Stanley raised Longsys’s 2026E gross margin to 55%, with 2027E at 35% and 2028E still at 27%. The implication is that Longsys is not merely using low-cost inventory to capture one round of price increases, but has some profit protection from customer structure, product mix, and transaction model.
On the profit cycle, Morgan Stanley pushed downside pressure from 2027 to 2028. Previously, it was easy to reach a simple conclusion on Longsys: when memory prices rise, earnings elasticity is very high; when memory prices fall, inventory and gross margin are both hurt. The new model becomes: windfall profits in 2026, still high levels in 2027, and only in 2028 does the market truly test whether supply expansion and AI demand can remain matched.
This data set makes Longsys’s valuation question very sharp: if 2026 net profit can really reach RMB23.974bn, the market can no longer value the company using the 2025 earnings base. But if the path of gross margin falling from 55% to 35% and then to 27% arrives early, the current share price will quickly shift from “re-rating” to “trading the cyclical peak.”
So Morgan Stanley is not saying Longsys is a risk-free re-rating. It is saying the risk-reward baseline has moved higher. Under the old model, Longsys needed to prove it was not an ordinary module maker. Under the new model, Longsys needs to prove that 2026 profits are not a one-off inventory dividend.
III. Product-Line Breakdown: The Upgrade Is Not a Single-Category Bet
Morgan Stanley’s move to lift Longsys’s target price to RMB673 does not rely only on price elasticity in one product line. Embedded storage, mobile storage, SSDs, and memory modules are all included in the upside model, but each line plays a different role.
Embedded storage is the base business and also where in-house controllers can most easily show value. Smartphone, AI device, automotive, and wearable customers have higher requirements for power consumption, reliability, capacity, packaging, and firmware adaptation. If Longsys can continue to secure customer projects with UFS 4.1, ePOP, HLC, and customized firmware, embedded-storage gross margin should not be understood only through ordinary NAND spreads.
Mobile storage and the Lexar brand are scale and channel assets. This segment can amplify earnings elasticity, but it is also the most constrained by consumer-end price ceilings. Morgan Stanley’s assumptions of 60% gross margin for mobile storage in 2026E and 42% in 2027E are strong. The implied premise is that low-cost inventory, brand premium, and channel pricing can all be realized at the same time. Once consumer customers cut orders, this line’s profitability will be the first to face market skepticism.
SSD is the key for Longsys to move from module elasticity toward platform assets. Consumer SSDs can provide scale, but enterprise SSDs are what may provide a higher valuation. Morgan Stanley raises SSD revenue from RMB14.462bn in 2026 to RMB21.115bn in 2027. Behind this is not just ordinary PC SSD unit-price upside, but the imagination space from AI infrastructure, enterprise customers, and high-spec customization.
Memory modules are the smallest in scale, but their significance is not absolute profit. The question is whether the company can turn its storage product lines into a more complete customer entry point. Servers, PCs, edge AI, and high-end terminals require not only NAND, but also DRAM modules, RDIMM, SOCAMM, MRDIMM, and CXL-related products. If Longsys can connect these product lines with enterprise customers, its valuation will move closer to that of a platform-type storage solution provider.
This breakdown has two key points. First, almost every category is assigned an extremely high gross margin in 2026, showing that Morgan Stanley views the year as one where pricing, inventory, and product mix resonate together. Second, gross margins fall meaningfully in 2027 and 2028, showing that Morgan Stanley does not assume Longsys can permanently maintain 2026 windfall margins, but instead treats high margins as a cycle that gradually normalizes.
In other words, the RMB673 target price is not built on “Longsys will earn RMB24bn every year from now on,” but on “after the 2026 profit surge, Longsys can still retain a sufficiently high profit step-up in 2027.” The real market debate is not whether 2026 can be very strong, but whether 2027 EPS of RMB42.62 is credible.
IV. 2027E EPS Is the Core of the RMB673 Valuation
Often, when the market sees a target-price increase, it naturally focuses on the nearest year of earnings. For Longsys, this time cannot be assessed only on 2026. 2026E EPS of RMB59.86 is high, but it is too easy for the market to treat it as a cyclical peak. What really determines whether the RMB673 target price can hold is 2027E EPS of RMB42.62.
The reason is simple. If looking only at 2026E EPS, Longsys’ valuation multiple appears very low, and the market may easily conclude that the share price still has room to rise. But if 2026 profit is viewed as unsustainable, the low multiple itself has little meaning. Morgan Stanley’s choice to use 2027E EPS as the target-price anchor is telling the market that Longsys’ profit step-up should extend at least into 2027, rather than reflecting only a one-year surge in 2026.
The valuation multiple implied by the base-case target price is not extreme, provided that 2027 remains a combination of NAND tightness, high gross margins, and enterprise product ramp-up. If 2027E EPS is meaningfully below Morgan Stanley’s assumptions, RMB673 would quickly shift from a reasonable valuation to a high-multiple price, and valuation pressure would rise immediately.
This is also why subsequent earnings reports will become highly sensitive. If Longsys only earns a one-off high profit in 2026, the share price will struggle to enjoy a high valuation for long. Only if 2027 can still prove that enterprise products, TCM, and long-term customer agreements support the profit step-up will the RMB673 target price have a real foundation.
V. Why Morgan Stanley Prefers Original Manufacturers, While Still Upgrading Longsys
Morgan Stanley’s preference in the NAND supply chain is clear: it favors original manufacturers over module makers. This is because AI demand first changes original manufacturers’ pricing power, capacity allocation power, and long-term contract negotiation power. Module makers benefit, but they are not the source of supply.
Applied to Longsys, this becomes a very practical question: why should Longsys receive a large upward revision among module makers? The answer is not “because NAND prices are rising,” but “because Longsys has more profit-retention tools than ordinary module makers.”
First is inventory-cycle management. In an upcycle, Longsys can amplify profit through higher inventory, but this advantage is not free. The higher the inventory, the greater the benefit when prices continue to rise, and the greater the pressure when prices weaken. Morgan Stanley is willing to revise upward because the industry shortage in 2026-2027 extends the window for inventory gains.
Second is the TCM model. Ordinary module makers carry more inventory and price volatility on their own books, while TCM ties customer demand, specification customization, and supply assurance more tightly together. It cannot eliminate the cycle, but it can allow Longsys to obtain a more stable profit allocation among high-spec customers.
Third is enterprise and controller capability. As original manufacturers tilt more supply toward CSPs, ordinary consumer module makers will be squeezed. If Longsys can use enterprise SSDs, self-developed controllers, and firmware services to enter higher-spec scenarios, it can reduce the degree of pressure.
This table explains Morgan Stanley’s seemingly contradictory stance: Longsys deserves an upgrade because it is not an ordinary module maker; Longsys remains Equal-weight because it is still a module maker.
VI. Cash Flow and Inventory: The Hard Constraints Behind High Profit
Longsys’ income statement is already very strong, but cash flow and inventory cannot be ignored. In 1Q26, the company generated revenue of RMB9.909 billion and net profit attributable to shareholders of RMB3.862 billion, an extremely strong profit release. At the same time, operating cash flow was negative, inventory rose to RMB17.961 billion, and prepayments also increased significantly. This shows that the company is making substantial purchases and building inventory for the upcycle.
In a storage upcycle, high inventory is not inherently bad. Low-cost inventory can translate into gross margin during a price-rise period, prepayments can lock in supply, and contract liabilities can reflect customers locking in goods in advance. The issue is that all these metrics must be tied to price direction. If prices continue to rise, they are profit leverage; if prices weaken, they become cash-flow and write-down risks.
This is also why Morgan Stanley raised the target price substantially but did not upgrade the rating. To prove that Longsys is not simply earning a one-off inventory gain, it must deliver better cash-flow quality over the next several quarters. If the income statement rises first and cash flow later catches up, that is a healthy upcycle. If the income statement is strong, inventory continues to rise, and cash flow remains negative, the market will start to worry that peak profit is unsustainable.
The ideal earnings combination for Longsys going forward would be high gross margins, rising enterprise revenue, stable or increasing contract liabilities, and improving operating cash flow. The least ideal combination would be a still-strong income statement alongside further inventory build, persistently negative operating cash flow, and shrinking consumer-end orders. The former would support the RMB673 target price; the latter would lead the market to price in a bear-case scenario early.
VII. The Rating Remains Equal-weight: Morgan Stanley Has Not Made Longsys a Top Pick
The easiest point to misread this time is equating a “large target-price increase” directly with “strong bullishness.” Morgan Stanley’s actual signal is more restrained: the target price has increased, but the rating has not been upgraded, and the allocation order still does not put module makers ahead of NAND original manufacturers.
The reason is direct. AI is indeed driving NAND shortages, but profit-retention ability is uneven across the NAND supply chain. Original manufacturers control wafer supply, long-term contract pricing, and the pace of capacity. Module makers are more exposed to customer orders, inventory, procurement rhythm, and the consumer-end price ceiling. In the early stage of price increases, module makers can amplify profit with low-cost inventory. In the second half of a price-rise cycle, low-cost inventory is consumed, customer orders shrink, and original manufacturers tilt supply toward CSPs, putting both shipment volume and gross margin for module makers to the test.
This is why Morgan Stanley raised Longsys’ target price while still preferring NAND suppliers. Longsys was upgraded because it has three things beyond an ordinary module vendor: enterprise SSD penetration, self-developed controllers, and the TCM model. But these capabilities have not fully offset the inherent issues of a module maker: it does not decide supply, it does not decide pricing, and the tightest AI SSD allocation may not necessarily prioritize module makers.
In investment terms, Longsys has not moved directly from a “cyclical stock” to a “platform growth stock.” Rather, it has been upgraded from an “ordinary storage-module cyclical stock” to a “high-beta cyclical stock with platform attributes.” This distinction is important. The former looks only at price; the latter also looks at product mix and customer stickiness. But as long as NAND prices decline, the latter cannot escape the cycle either.
This rating is a reminder: the upward revision to Longsys’ target price reflects an upward reassessment of the fundamentals model; the unchanged rating reflects the fact that the share price and supply-chain position still require a discount.
VIII. Valuation Methodology: RMB673 Is Not Simply a High P/E Multiple
Morgan Stanley uses a residual income model for Longsys, rather than simply multiplying 2027E EPS by a multiple. The residual income model focuses on whether a company can continue generating profit above its cost of capital. For a storage company like Longsys, whose profit is highly volatile, this method better captures the cyclical debate than a single-year P/E multiple: if high profit lasts for only one year, residual income decays quickly; if high profit can be maintained into 2027 or longer, valuation will be systematically lifted.
In Morgan Stanley’s base model, the cost of equity is 9.10%, the risk-free rate is 2.5%, the risk premium is 5.5%, beta is 1.2, and the perpetual growth rate is 6.3%. These parameters themselves are not aggressive. What really pushes up the target price is the profit forecast. In other words, the core of the RMB673 target price is not a sudden decline in the cost of capital, but the much thicker residual income after 2026-2027 profit was revised up sharply.
This also makes Longsys’ valuation risk clearer. The P/E multiple can look very low, but the residual income model penalizes profit declines. If gross margin quickly returns to the level of an ordinary module maker after 2028, the current high profit merely pulls forward future value. If enterprise SSDs, controllers, and TCM allow the company’s ROE to remain on a higher step, the residual income model will assign a higher fair value than it would to a traditional cyclical stock.
This table points to a more practical issue: for Longsys, a cheap valuation multiple is no longer enough. It must prove that high ROE is not a short-term result of the inventory cycle. If ROE falls quickly after 2026, residual income will be compressed again. If high profit can still be maintained in 2027, the market will accept that Longsys is no longer just an ordinary module-cycle stock.
Therefore, the RMB673 target price is not as simple as “assigning Longsys a higher P/E.” It reflects Morgan Stanley lifting Longsys’ profit step-up over the next two years and then discounting that excess profit through a residual income model. What investors really need to judge is whether this excess profit is one-off or sustainable.
IX. AI NAND Shortage Is the Primary Driver of Upward Revisions
Morgan Stanley’s model rewrite for Longsys is based on a global NAND supply-demand table. AI servers, training clusters, inference clusters, and long-term agreements with cloud vendors are consuming more NAND supply, especially enterprise SSDs and high-performance storage tied to AI infrastructure. Traditional consumer segments such as smartphones, PCs, and channel modules still represent scale, but pricing power is being squeezed by AI demand.
Morgan Stanley expects AI-related NAND demand to rise from 205EB in 2025 to 400EB in 2026 and 609EB in 2027, with its share of global NAND demand increasing from 18% to 41%. This is not a small structural change. It means NAND is no longer priced only as a smartphone, PC, and ordinary consumer SSD cycle; it is beginning to be repriced by data-center capex.
How to Bypass the Memory Tax: NAND, CXL, and PIM Are Being Repriced, and the Industrial Logic Behind Storage-Tier Reconstruction
This table explains why Longsys is being repriced. A 15% supply-demand gap in 2026 means prices are not merely rising modestly; customers will have to accept higher contract prices. A continued 9% gap in 2027 means price increases are not a one-quarter impulse. As long as the supply-demand gap persists, Longsys, as a company with high inventory, high turnover, and high product elasticity, will see both revenue and gross margin amplified.
But this table also explains why the rating was not upgraded. The AI NAND shortage primarily benefits original manufacturers, because they control wafers and long-term agreements. Longsys benefits from rising prices, but it does not control supply. The real question is not whether Longsys can benefit, but how much profit it can retain.
This is also the biggest difference between Longsys and original manufacturers. The core variables for original manufacturers are wafer prices and capacity discipline. The core variables for Longsys are procurement costs, inventory cycles, customer mix, product ASP, and the share of high-end products. Once AI pulls up NAND prices, Longsys has substantial earnings elasticity, but the quality of its earnings must be explained by TCM, enterprise SSDs, and controller capabilities.
X. Cross-Checks From the Past Week: Morgan Stanley Is Not the Only One Revising NAND Upward
This Longsys target-price upgrade cannot be assessed by looking only at Morgan Stanley’s single model. Looking at several NAND-related reports from the past week together, the conclusion is clear: AI/eSSD demand is still tightening supply, and original manufacturers and leading SSD assets continue to see earnings revisions. At the same time, the slope of consumer NAND price increases has begun to fall below that of the server side, meaning module makers’ “price” and “volume” will diverge.
Goldman Sachs’ update on Kioxia confirms earnings on the original-manufacturer side. Goldman Sachs raised Kioxia’s target price to JPY116,000. The core assumption is that tight NAND supply-demand will last at least until mid-2027, and that major memory companies are prioritizing investment in DRAM and HBM, making it hard for new NAND capacity to increase meaningfully before 2028. This judgment is consistent with Morgan Stanley’s supply-demand table: AI demand is absorbing high-spec NAND first, while original manufacturers prefer to defend pricing and margins.
Citi’s update on SanDisk confirms downstream AI storage demand. Citi raised SanDisk’s target price to USD2,500, based on Micron’s earnings validation of NAND ASP and bit shipments, as well as demand for KV cache, tiered storage, and high-performance SSDs in AI inference. SanDisk and Kioxia are both original-manufacturer or quasi-original-manufacturer assets. Their earnings revisions show that this NAND cycle is not ordinary consumer restocking.
Korean storage price tracking provides signals of divergence. Under TrendForce’s framework, overall NAND ASP in 3Q26 is expected to rise 10%-15% QoQ, while enterprise SSDs are expected to rise 18%-23% QoQ. However, price increases for mobile NAND and consumer-related categories are clearly below eSSD. This gap is critical: whether Longsys can support a RMB673 target price does not depend on all NAND rising together, but on whether enterprise and customized products can grow faster than the consumer side.
This cross-check table also explains why Morgan Stanley maintained an Equal-weight rating. Evidence on the original-manufacturer side is getting stronger, so Longsys’ target price naturally needs to be revised up. But original manufacturers still have the firmest pricing, strongest long-term agreements, and greatest capacity-allocation power. Longsys needs to convert this NAND shortage into its own earnings quality through TCM, enterprise SSDs, and controllers.
Therefore, the focus of this update is not “Longsys also rises with NAND.” The more accurate judgment is: NAND tightness has raised Longsys’ earnings ceiling, and multiple reports over the past week confirm that this ceiling has moved up. But the consumer-side price ceiling and original-manufacturer supply tilt have also raised the bar for Longsys’ execution.
XI. Longsys’ Advantage: Not an Ordinary Low-Cost Inventory Module Maker
If Longsys is viewed only as a traditional module maker, Morgan Stanley’s RMB673 target price looks overly aggressive. The business model of a traditional module maker is clear: accumulate low-cost inventory during downcycles, sell at higher prices during upcycles, and earn the pricing spread. But this profit is not sustainable. Once low-cost inventory is depleted, customer demand slows, and original-manufacturer supply prices rise, gross margin will fall quickly.
Longsys has been revised up sharply this time because Morgan Stanley believes it is no longer entirely this type of model. TCM shifts part of the inventory and price-volatility pressure forward to customers. Enterprise SSDs and embedded storage improve product specifications. Self-developed controllers and firmware capabilities increase the value of customized services. The Lexar brand provides overseas consumer and channel assets. Together, these factors are why the gross-margin assumption has been raised.
The company’s official data also support this change. In 2025, revenue and net profit attributable to shareholders recovered significantly. Enterprise storage grew much faster than the overall business. Controller chip deployment volume, validation of the 5nm UFS 4.1 controller, and the 2026 scaling plan all give Longsys more product-structure explanatory power than ordinary module makers.
This official data set shows both sides of Longsys. On the positive side, 1Q26 earnings have already validated the explosiveness of the pricing cycle, and the sharp increase in contract liabilities shows customers are willing to lock in supply in advance. On the pressure side, inventory rose to RMB17.961bn and operating cash flow was negative, showing the company still carries heavy inventory and procurement pressure.
Therefore, Longsys is not simply “the more prices rise, the better.” In the early stage of price increases, high inventory is an earnings lever. In the late stage of price increases, high inventory becomes a risk lever. The significance of TCM is to reduce risk in the second half, but this still needs to be validated by subsequent financial reports.
XII. Why the TCM Model Has Become the Core of the Model
A large part of Morgan Stanley’s upward revision to Longsys’ long-term gross-margin assumption comes from TCM. In the past, the market’s biggest concern when assessing module makers was that “inventory gains are not sustainable.” If a company only relies on low-cost procurement and selling into price increases, the gross-margin peak will inevitably be short, and it can easily be swallowed by the next round of price declines.
The TCM model changes profit attribution and risk sharing. It does not free Longsys from the storage cycle. Instead, when customer demand is clear, customization is stronger, and supply is tight, it allows Longsys to transfer part of the inventory pressure and price-volatility pressure to customers. Customers lock in supply, while Longsys locks in service value and processing value. Customers assume more stocking responsibility, and Longsys’ gross margin is not fully exposed to spot-price volatility.
Whether this model can work depends on whether customers truly cannot do without Longsys’ services. If the products are only ordinary SSDs or ordinary memory modules, customers have no reason to give module makers much profit. If the products are enterprise SSDs, embedded storage, automotive, AI devices, wearables, and customized firmware, Longsys’ controller, firmware, testing and validation, and supply-chain integration capabilities have higher value.
The key to TCM is not the name, but whether it can move Longsys from an “inventory trader” to a “storage solutions provider.” If it can, gross margin can be more stable than that of traditional module makers. If it cannot, the market will still discount 2026’s high profits as a cyclical peak.
XIII. Enterprise SSD Is the Main Battleground for Whether the Valuation Holds
For Longsys to support a RMB 673 target price, it cannot rely only on consumer-end price increases. The problem on the consumer side is clear: smartphone and PC demand has not accelerated in tandem, channel inventory is relatively high, customers tend to cut orders after prices rise, and module makers’ low-cost inventory will also be gradually consumed. What can truly lift the profit center is enterprise SSD and storage tied to AI infrastructure.
The most important direction in Morgan Stanley’s industry report is that AI is pulling NAND out of the consumer electronics cycle and turning it into part of cloud vendors’ capex. AI servers require higher-capacity, more stable and more reliable enterprise SSDs. Training, inference, data preprocessing, logs, recovery, control planes and system disks all consume more NAND. Even if Longsys is not an original manufacturer, as long as it can raise specifications in enterprise SSD, RDIMM, embedded and automotive storage, it can participate in the cycle better than ordinary consumer module makers.
AI Hardware Restocking Deep Dive: Capacitors Hit New Highs, Nearline HDD Capacity Up 31% YoY, Enterprise SSD Capacity Up 139% YoY; How Data-Center Demand Spreads to Components and Storage
The company’s annual report discloses that Longsys already has eSSD and RDIMM design capabilities, product portfolios and scaled supply capability. SOCAMM has already been powered on, while MRDIMM and CXL2.0 modules are also progressing. In 1Q26, the company said customized edge AI storage products had already been supplied to North American smart-vehicle and autonomous-driving technology customers; ePOP4x had entered a North American wearable technology customer; and mSSD had entered introduction testing at leading PC customers and is expected to begin large-scale replacement of traditional SSDs in 2026.
These developments matter for valuation. If Longsys only makes consumer SSDs, the share price can only be assessed through NAND prices. If enterprise SSD and edge AI storage continue to scale, the share price can be assessed through customer mix and platform capability.
Whether enterprise SSD can scale is the most important quality test for the RMB 673 target price. NAND price increases can explain short-term profit; enterprise SSD is what can explain a higher valuation multiple.
XIV. Self-Developed Controllers: Gross-Margin Protection, Not a Universal Answer
In Longsys’s earlier investment thesis, self-developed controllers have always been a key variable. Morgan Stanley’s upward revision to its long-term gross-margin assumptions this time is also related to controllers, firmware and customized services. A controller is not simply a cost item. It determines product compatibility, performance, power consumption, stability, certification cycle and customer substitutability.
The company’s disclosed 5nm UFS 4.1 controller, HLC technology and SPU architecture all point in the same direction: Longsys is trying to connect NAND, controllers, firmware, packaging and application scenarios, rather than only doing procurement and assembly. HLC makes NAND more like an extension of DRAM, SPU supports high-capacity SSDs and higher NAND I/O, and the UFS 4.1 controller serves high-end smartphones and AI terminals.
The investment implication is that Longsys has the opportunity to turn “buying NAND” into “defining products.” If Longsys can define products, it has gross-margin protection. If it is only buying NAND and then assembling modules, the value of controllers will be drowned out by the pricing cycle.
SanDisk Deep-Dive Update: AI Demand, NBM Long-Term Agreements and NAND Profit Durability
But controllers should not be mythologized. In Morgan Stanley’s industry report, the controller companies that benefit more directly are independent controller suppliers and parts of the AI boot-drive chain. Longsys’s controller value is mainly reflected in the gross margin of its own products, customer customization and platform capability. It does not mean the company can directly enjoy the entire controller TAM. Put differently, Longsys’s controller capability is a reason for the valuation discount to narrow, not a reason to detach from the NAND cycle.
Controllers make Longsys more than a module maker, but it still needs to prove through financial results that controllers can retain profit. The most direct validation is whether gross margin can remain significantly above the previous cycle after low-cost inventory is gradually consumed.
XV. The Consumer End Is Not the Core Logic; It Is Instead a Source of Risk
Morgan Stanley’s NAND industry report draws a clear distinction between AI and the consumer end. On the AI side, CSP demand remains strong and long-term agreements support pricing. On the consumer side, module-maker and channel inventory is rising, smartphone and PC customers are beginning to weigh volume against profit after price increases, and some orders have already been cut.
This matters for Longsys. Longsys has the Lexar brand, as well as consumer SSDs, memory cards, portable storage and embedded products. Consumer-end price increases will directly lift revenue and gross margin. But the consumer end is not the highest-quality part of this target-price upgrade. The faster consumer prices rise, the more easily customers cut volume; the higher channel inventory is, the closer prices are to the ceiling.
Morgan Stanley’s view is that consumer-grade NAND prices may soon hit an upper bound, while original manufacturers will allocate more capacity to AI and server customers. This means module makers will face a combination of rising procurement costs, cautious ordering from consumer customers, and enterprise customers that may not grant sufficient allocation. Longsys is still being upgraded because Morgan Stanley believes its product mix and TCM mechanism can buffer this pressure set.
Therefore, the investment judgment on Longsys cannot only look at “NAND price increases.” If price increases come from AI demand and are retained as gross margin through enterprise products and TCM, that is high-quality pricing. If price increases mainly come from consumer-end restocking and inventory gains, that is high-beta but low-multiple.
XVI. 2028 Supply Risk: Yangtze Memory Is a Variable, Not Only a Positive
Morgan Stanley pushes back the timing of Longsys’s earnings downside to 2028, with the core premise that NAND remains in shortage in 2026-2027. But there is an unavoidable variable in 2028: new capacity, especially new NAND capacity in China.
For Longsys, increased Chinese NAND supply has dual implications. On the positive side, Longsys can obtain more local supply, improving procurement security and shipment volume. On the risk side, if new capacity is released too quickly, industry pricing may move from shortage to surplus, compressing Longsys’s profit margin.
Morgan Stanley conducted scenario analysis for 2028. If AI SSD demand continues to grow rapidly and capacity expansions by Yangtze Memory and others remain disciplined, NAND may still be tight. If AI demand growth slows while new capacity is released quickly, the industry will re-enter a loose-supply environment.
Kioxia Deep-Dive Update: JPY 155,000 Target Price, NAND Cash Flow and AI SSD Re-Rating
2028 is the real exam for Longsys’s re-rating. High profit in 2026 can be explained by inventory and price increases; high profit in 2027 can be explained by the industry gap; by 2028, the question is whether Longsys has truly built high-spec customer and product barriers.
XVII. Bull-Bear Scenarios: RMB 673 Is Not the Most Optimistic Target Price
Morgan Stanley’s target price for Longsys is not a point forecast, but a middle choice among three scenarios. The bull-case target price is RMB 852, the base case is RMB 673, and the bear case is RMB 587. The upside and downside appear asymmetric, but note that the bear case is not a zero-profit scenario. It is a scenario in which prices and valuation multiples reset lower.
The base case corresponds to: AI NAND demand supports pricing in 2026-2027; Longsys raises its profit center through TCM, enterprise SSD, self-developed controllers and overseas brands; and pricing downside pressure begins only in 2028. In this scenario, the RMB 673 target price corresponds to 15.8x 2027E P/E.
The bull case corresponds to: AI investment continues to accelerate, CSPs continue to lock in NAND, edge AI demand from smartphones and PCs recovers, supply discipline holds, and Longsys not only benefits from prices but also expands its share in enterprise and high-end products. In this scenario, the target price is RMB 852, corresponding to about 20x 2027E P/E.
The bear case corresponds to: edge AI demand is weaker than expected, supply expansion outpaces demand around 2028, NAND prices decline earlier, and Longsys’s high profit is viewed by the market as a cyclical peak. In this scenario, the target price is RMB 587, and valuation shifts toward book value and a cycle-trough framework.
The key information in this scenario set is that Morgan Stanley has not completely denied cycle risk. It simply believes that under the new AI NAND supply-demand assumptions, Longsys’s base-case profit level has been systematically lifted.
18. Differences Versus the Previous Longsys Deep Dive
The previous Longsys deep dive focused on explaining why the company should not be valued only as a “storage module vendor”: enterprise SSDs, self-developed controllers, the Lexar brand, AI devices, and the domestic storage supply chain were all lifting the company’s asset attributes. At that point, the framework was more about structural re-rating.
This Morgan Stanley target-price upgrade converts that structural framework into a financial model. The old thesis answered “why Longsys is more than just a module vendor”; the new thesis answers “how much EPS and target price this change can be worth.”
The difference is that the old thesis focused on asset attributes, emphasizing the transition from storage modules to platform capabilities; the new thesis focuses on profit delivery, directly laying out 2026-2028 revenue, gross margin, net profit, and target-price scenarios. For investment judgment, this step matters more, because the market no longer lacks a Longsys narrative. What it lacks is proof that earnings can support a high share price.
In other words, the research focus on Longsys has shifted from “whether the story makes sense” to “whether the model can be delivered.” That is more demanding for the share price, and also more valuable.
19. How to Understand This Upgrade Near the Current Share Price
Based on the share-price reference in Morgan Stanley’s report, Longsys was trading at about RMB599 at the time, versus a target price of RMB673, implying roughly 12% upside on the surface. That is not a large margin, but the change behind the model is significant. This combination is common: fundamental expectations have been raised sharply, but the share price has already priced in most of it.
Therefore, the RMB673 target price is more like a new valuation anchor than a simple near-term upside estimate. It tells the market that if 2027E EPS can really reach RMB42.62, Longsys should no longer be discounted under the old module-vendor framework. But it also reminds the market that if the share price is already close to the base-case target, further upside requires evidence closer to the bull-case scenario.
What evidence could push Longsys from RMB673 toward RMB852? First, the AI NAND shortage persists into 2028, and new capacity does not undermine pricing. Second, enterprise SSD and customized storage revenue continue to grow faster than the company overall. Third, after low-cost inventory is gradually consumed, gross margin can still remain far above the level of the previous cycle. Fourth, operating cash flow improves from the pressure of high inventory.
What evidence would pull Longsys toward the bear-case scenario? First, consumer-grade NAND prices fail to rise, and smartphone and PC customers cut orders. Second, original manufacturers reserve more supply for CSPs, leaving module vendors unable to secure enough high-quality supply. Third, new supply before 2028 weakens pricing expectations. Fourth, inventory and cash-flow pressure deteriorate before the income statement does.
The follow-up catalysts and risk watchlist can be compressed into six items. Continued gross-margin beats in 2Q26/3Q26 would be the most direct positive signal, with the focus on whether margins approach or exceed Morgan Stanley’s high gross-margin assumption; a rising enterprise storage revenue share would also be positive, with attention on progress in eSSD, RDIMM, and edge AI storage customers; continued growth in contract liabilities would be somewhat positive, but it must be checked whether this represents customer lock-in or delivery pressure; continued rapid inventory growth is a double-edged sword, serving as leverage in an upcycle and risk in a downcycle; operating cash-flow improvement is the cleanest positive validation, proving that profit is not being entirely absorbed by inventory; weakening NAND spot and contract prices would be the most direct negative signal, compressing both gross margin and valuation multiples.
The main misread to avoid at this stage is interpreting a “sharp target-price upgrade” as “share-price risk has disappeared.” The reality is the opposite: the higher the target price, the higher the market’s requirements for Longsys’s subsequent financial reports.
20. Four Tracking Indicators
Longsys should not be tracked only through NAND spot prices from here. NAND prices are important, of course, but looking only at price can easily pull Longsys back into an ordinary cyclical-stock framework. A better approach is to break the target-price model into four financial and business indicators.
First, gross margin. Morgan Stanley’s 2026E gross-margin assumption of 55% is very high, which means the market will treat Longsys’s quarterly gross margin as a core validation item. If gross margin remains strong, it means TCM, product mix, and inventory costs are still contributing; if gross margin falls quickly, the target-price model will be directly weakened.
Second, enterprise storage revenue. Enterprise storage revenue was RMB1.783 billion in 2025, up 93.30% year on year. If this segment continues to grow faster than the company overall, Longsys has a chance to move from a consumer module stock into an enterprise storage platform. If growth slows, the market will still price the company as a cyclical-beta stock.
Third, inventory and operating cash flow. Inventory was RMB17.961 billion in 1Q26, and operating cash flow was negative. This is not simply negative, because stocking up in an upcycle naturally consumes cash. But if inventory keeps rising and operating cash flow does not improve, the market will worry that the income statement is leading while cash flow lags, and that subsequent inventory write-down losses may emerge.
Fourth, long-term agreements and customer advances. Contract liabilities were RMB2.217 billion in 1Q26, indicating signs of customers locking in supply ahead of time. If contract liabilities and customer agreements continue to improve, that would support Morgan Stanley’s judgment on the 2027 supply-demand gap; if customers shift to wait-and-see mode, the consumer-end price ceiling will appear faster.
The validation logic for these indicators is also clear. If gross margin remains high, it shows TCM and product mix are effective; if it falls quickly, it shows the inventory benefit is not sustainable. If enterprise storage continues to grow faster than the company overall, Longsys has a chance to move beyond consumer-module-driven growth; if it slows, the company will still be priced as a cyclical-beta stock. If inventory and operating cash flow improve at the same time, earnings quality will be more solid; if inventory continues to build and cash flow remains under pressure, the market will begin to worry about late-cycle risk. If contract liabilities and LTAs continue to strengthen, it means customers’ willingness to lock in supply remains strong; if customers cut orders or wait, the consumer-end price ceiling will arrive earlier. If 2028 supply remains disciplined, AI can continue to absorb new capacity; if new supply pushes NAND prices lower, the RMB673 target price will need to be discounted again.
These four indicators turn the RMB673 target price into a verifiable framework, rather than something that exists only inside a brokerage model.
21. Bottom-Line Judgment: Validate Delivery First, Then Discuss the Valuation Ceiling
After Morgan Stanley’s target-price upgrade, Longsys’s share-price pricing will shift from “whether there is operating leverage” to “how long that leverage can last.” The company has already proved that it is highly sensitive to rising NAND prices. What it has not fully proved is whether, as low-cost inventory is gradually consumed, consumer-end price increases approach the ceiling, and original manufacturers prioritize supply allocation to AI customers, Longsys can still retain profit through TCM, enterprise SSDs, and controllers.
The more appropriate tracking sequence is to validate financial delivery first, then discuss the valuation ceiling. If gross margin, contract liabilities, and enterprise revenue all remain strong over the next two quarters, RMB673 will become a conservative base case, and the market will then open up the RMB852 bull-case scenario. If profit is strong but cash flow and inventory continue to deteriorate, the target-price upgrade will instead become a risk warning, because the market will worry that the profit peak has arrived too quickly and may also fade quickly.
Therefore, the best state for Longsys now is not simply the highest possible single-quarter profit, but simultaneous improvement in profit, cash flow, and business mix. As long as these three conditions do not hold at the same time, the RMB673 target price remains only Morgan Stanley’s base-case scenario, not a pass for unconditional share-price upside.
This is also the real meaning of Morgan Stanley maintaining a Neutral rating: the earnings model has clearly moved higher, but delivery evidence still needs to be filled in, especially around 2027 EPS and 2028 supply discipline.
After the target-price upgrade, every Longsys quarterly report will become a re-pricing event for this model.
22. Conclusion: The RMB673 Target Price Is Longsys’s New Threshold
Morgan Stanley raised its target price for Longsys from RMB300 to RMB673. The most important implication is not that the “target price doubled,” but that Longsys’s valuation framework has been pushed to a higher threshold: the market is no longer only asking whether storage prices have risen, but whether Longsys can convert NAND price increases, the TCM model, enterprise SSDs, and self-developed controllers into a sustainable profit center.
After this update, the Longsys research framework can be summarized in three sentences.
First, 2026 earnings leverage has been raised significantly. Morgan Stanley’s 2026E EPS of RMB59.86 and 55% gross margin are very strong upcycle assumptions. If subsequent financial reports deliver, Longsys can no longer be valued under the old module-vendor framework.
Second, 2027 is the core year for the target price. The RMB673 target price is essentially anchored to 2027E EPS of RMB42.62, rather than only looking at 2026 windfall profits. As long as NAND remains in shortage in 2027, enterprise SSDs continue to scale, and TCM protects gross margin, Longsys’s re-rating will have a financial foundation.
Third, 2028 will determine whether this re-rating is a cyclical illusion. If new capacity is released too quickly, AI NAND demand slows, and consumer-end inventory pressures pricing, Longsys may still return to cyclical-stock logic. If supply discipline continues and enterprise SSD and controller capabilities stand firm, Longsys will truly complete the shift from module beta to platform asset.
Therefore, RMB673 is not the finish line, but a new exam. Longsys has received an entry ticket to higher profit assumptions. The next step is to use gross margin, cash flow, enterprise revenue, and customer LTAs to prove that this is not another inventory-cycle peak, but an upward shift in the profit center of a storage platform company.