
目录
The Real Signal from Q2: Headline Profit Grew, but Underlying Operations Remained Weak
The Revenue Mix Is Changing, with Margin Improvement Preceding Revenue Growth
Among the Four Growth Drivers, Foldables and Liquid Cooling Have the Clearest Timelines
Why Citi Cut Revenue Forecasts but Raised Medium-Term Earnings
Different A-Share and H-Share Ratings Reflect Valuation, Not Fundamentals
The Strongest Counterargument: Recovery Requires Multiple Projects to Deliver on Schedule
Five Sets of Numbers to Watch Next—The Fourth Quarter Is the Critical Window
本内容基于公开资料和研报数据整理,不构成任何投资建议,不代表任何个人观点,仅供学习参考,请理性阅读
Lingyi iTech has a foundation for a fourth-quarter earnings recovery, driven primarily by a better product mix and new-business ramp-ups. However, the decline in second-quarter recurring profit means this thesis still needs to be validated through shipments, expense ratios, and gross margins from September through December.
The Real Signal from Q2: Headline Profit Grew, but Underlying Operations Remained Weak
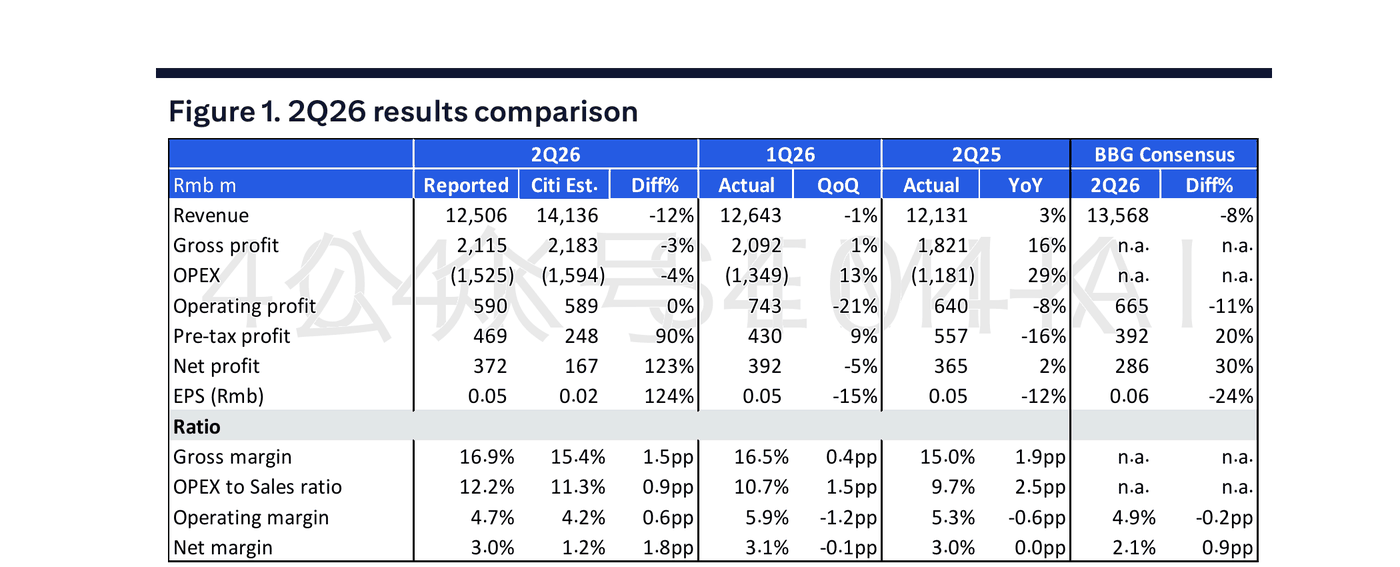
The most important second-quarter signal was the combination of weaker-than-expected revenue and a better-than-expected gross margin. Lingyi iTech reported revenue of RMB12.506 billion, up 3% year on year but down 1% quarter on quarter. Revenue was 12% below Citi’s forecast and 8% below consensus. Demand timing, foreign-exchange movements, and new-product ramp-ups have yet to lift revenue to the level previously anticipated by the market.
Gross margin sent the opposite signal. It reached 16.9% in the second quarter, up 1.9 percentage points year on year and 0.4 percentage points quarter on quarter, and 1.5 percentage points above Citi’s forecast. The company has scaled back its low-margin imaging and display Top Module business and redirected resources toward thermal management, batteries, and power products. This reallocation has already improved profitability per unit of revenue.
Reported net profit alone does not reflect operating quality. Second-quarter net profit attributable to shareholders was RMB372 million, up 2% year on year and superficially ahead of expectations. However, this included RMB123 million in fair-value gains and RMB97 million in investment income, while RMB119 million in asset impairments or write-offs weighed on earnings. Citi calculated recurring net profit at only RMB150 million, down 40% year on year. The report did not provide a complete reconciliation for nonrecurring items, taxes, and other differences, so recurring profit cannot be derived by mechanically netting the disclosed items.
Operating profit also indicates that the recovery remains incomplete. Second-quarter operating profit was RMB590 million, down 8% year on year, while the operating margin fell 0.6 percentage points to 4.7%. The operating expense ratio rose to 12.2%, up 2.5 percentage points year on year and 1.5 percentage points quarter on quarter. Much of the benefit from the higher gross margin was absorbed by rising expenses and insufficient revenue.
The company also provided figures excluding foreign-exchange effects: on this basis, second-quarter revenue would have reached RMB13.1 billion and net profit RMB1 billion. These figures suggest substantial currency pressure, but they represent a counterfactual management-adjusted view. Reported revenue of RMB12.506 billion and attributable net profit of RMB372 million remain the starting point for assessing the period’s operating performance; the two sets of figures are not interchangeable.
The second quarter therefore leaves three clear conclusions: revenue recovered more slowly than expected; the product-mix shift did lift gross margin; and recurring and operating profit have yet to improve in tandem. For the material fourth-quarter recovery forecast by Citi to emerge, at least two of the three variables—revenue, gross margin, and the expense ratio—must continue to improve.
The Revenue Mix Is Changing, with Margin Improvement Preceding Revenue Growth
Lingyi iTech’s core capability is integrating materials, precision functional components, modules, and assembly services on a single manufacturing platform. Traditional electronic-device operations still account for the overwhelming majority of the business, while incremental growth is coming from higher content per device and expansion in automotive, liquid cooling, power, and robotics. The second-quarter gross-margin improvement is an early indication that the changing revenue mix has begun to flow through the income statement.
In the first half of 2026, the electronic-device business generated RMB20.5 billion in revenue, down 2% year on year and representing 82% of total revenue. Gross margin rose 0.6 percentage points year on year to 17.5%. Revenue from the traditional business did not grow, but profitability improved modestly. The company’s deliberate withdrawal from low-margin processes helps explain how weak revenue and a higher gross margin could occur simultaneously.
The automotive and advanced air mobility business delivered a different growth profile. First-half revenue reached RMB3.5 billion, up 198% year on year and accounting for 14% of total revenue, while gross margin increased 6.3 percentage points to 14.1%. Its gross margin remains below that of the electronic-device business, but the gap has narrowed materially. If scale and yields continue to improve, automotive’s profit contribution should rise faster than its share of revenue.
The segment data also require careful treatment. RMB12.506 billion is revenue for the second quarter alone, whereas RMB20.5 billion and RMB3.5 billion are first-half segment figures; the latter two cannot be treated as the second-quarter revenue mix. The report did not provide complete segment profit forecasts, customer order volumes, or capacity-utilization data. At this stage, the direction of the mix shift can be confirmed, but the figures are insufficient to build a precise segment valuation model.
The value of the revenue-mix shift is that the same RMB100 million of revenue can generate different levels of gross profit. As low-margin assembly revenue contracts and higher-margin thermal management, liquid cooling, and precision components increase their share, the overall gross margin can rise even if total revenue falls short of the original forecast. Citi’s outlook for 2027–2028 relies primarily on this structural shift continuing.
This strategy will also create near-term friction. New-project launches require upfront R&D;, engineering, and sales investment, while the associated revenue and profit often emerge several quarters later. The higher second-quarter expense ratio and lower operating margin show that the company remains in a transition phase in which the gross-margin mix is improving but the expense burden remains heavy. The genuine inflection point will come when incremental gross profit consistently covers expense growth.
Among the Four Growth Drivers, Foldables and Liquid Cooling Have the Clearest Timelines
The first driver of the fourth-quarter recovery is foldable and premium smartphones. The company supplies components including precision hinge structures, display support plates, ultra-thin vapor chambers, and steel battery-shell modules. According to management discussions cited by Citi, content value per device for these products is several times that of other handset models. Mass-production ramp-up is scheduled for the third and fourth quarters of 2026, with volumes expected to increase month by month from September through December.
