
Legacy Storage Re-Rating: DDR4, NOR, SLC NAND and eSSD, Which Segments Are Moving from Cyclicals to AI Data Assets
目录
TL;DR
I. This Is Not Another Storage Upcycle, but a Re-Segmentation of Legacy Assets
II. DDR4’s Value Is Not That It Is Behind, but That Major Suppliers Have Actively Abandoned It
III. The Re-Rating of NOR and SLC NAND Comes from Small-Capacity Entry Points, Not Large-Capacity Narratives
IV. eSSD Is the Core of NAND’s Shift from a Price Trade to a Profit-Quality Trade
V. HDD Is the Most Easily Overlooked Cash-Flow Asset
VI. LTAs, Inventory, and Cash Flow: Can Legacy Storage Be Capitalized?
VII. Company Ranking: Purity, Beta, Certainty, and Crowding Should Not Be Mixed Together
8. Three Worldviews: Cycle Peak, Structural Upswing, Asset Re-Rating
Verification Calendar, Portfolio Mapping, and Common Misreadings: Use Data to Decide How Far This Theme Can Run
A-Shares and Overseas Mapping: Four Ways to Own the Same Memory Theme
Five Common Misreadings: Do Not Recast Legacy Memory as a Single Cyclical Trade
Conclusion: Legacy Memory Is Not Backward Capacity, But the Second-Layer Toll Point of AI Infrastructure
本内容基于公开资料和研报数据整理,不构成任何投资建议,不代表任何个人观点,仅供学习参考,请理性阅读
The AI storage trade has moved past the question of “whether prices will rise.” The next question is which legacy categories can turn shortage into asset-like characteristics. DDR4, NOR, SLC NAND, eSSD and HDD share one feature: HBM and AI servers have rewritten their supply-demand coordinates, pushing them into a phase where profit quality must be verified.
TL;DR
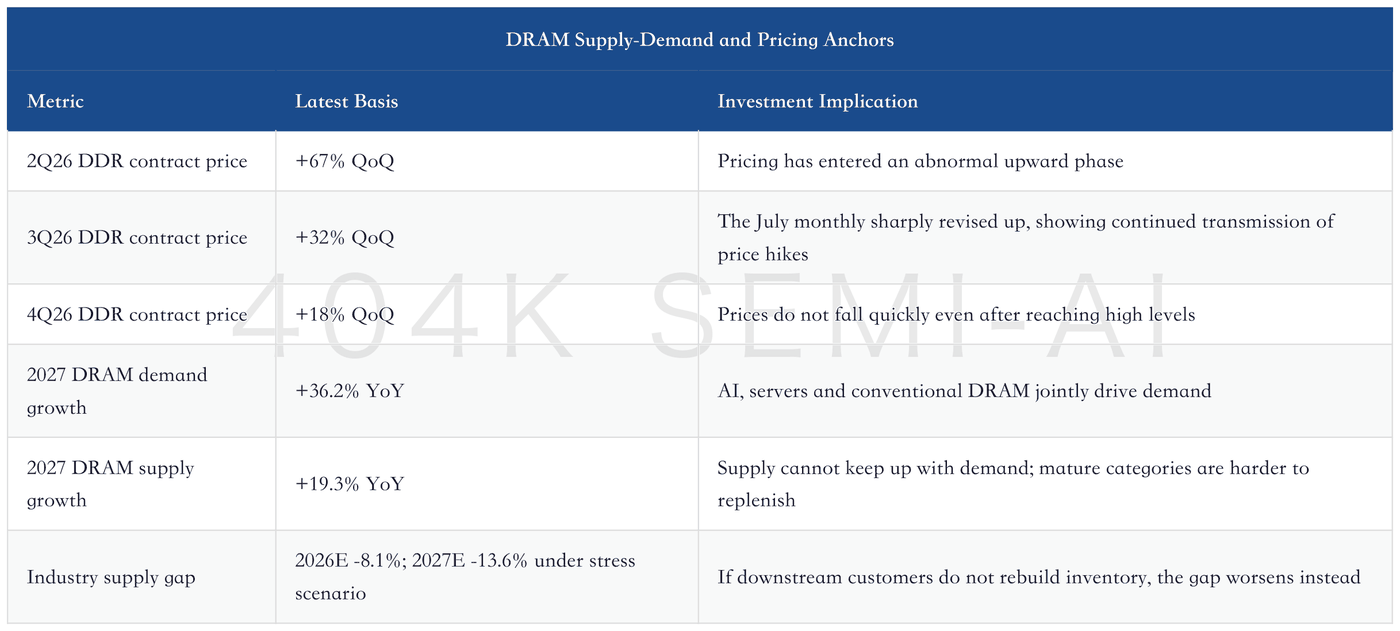
Legacy storage is changing its valuation anchor. The July storage monthly raised its 3Q26 DDR contract-price forecast to +32% and expects 2027 DRAM demand to grow +36.2% versus supply growth of +19.3%. This gap cannot be explained by one quarter of inventory replenishment. What the market really needs to re-rate is not “storage price increases,” but the repricing of legacy assets such as DDR4, NOR, SLC NAND, eSSD and nearline HDD after major suppliers shifted capacity toward HBM, DDR5 and AI products.
DDR4 is the first test case. Taiwan’s Nanya Technology was upgraded to Overweight, with its target price raised to NT$710. The key is not that it has suddenly become a high-end HBM company, but that DDR4/LPDDR4 shortages, server cache memory and LTA negotiations have restored pricing power to legacy DRAM. If DDR4 can hold through 2027, this cycle is not traditional inventory restocking, but long-term crowding out of mature-node capacity by AI.
NOR and SLC NAND look more like supply rights. GigaDevice’s re-rating logic already shows that NOR, SLC NAND and niche DRAM are not low-end leftovers, but code-storage and control-entry assets inside AI servers, optical modules, autos and industrial equipment. Their upside does not come from large total volume, but from overseas leaders reducing investment in mature categories, allowing companies with stable supply and customer access to gain scarce pricing power.
eSSD determines NAND profit quality. NAND has shifted from broad-based price increases to structural divergence. Enterprise/data-center SSD capacity shipments rose +139% YoY, and AI-related NAND demand is moving toward 41% of total demand by 2027. This shows that the core NAND thesis is shifting from smartphones and consumer SSDs to the data-center capacity layer. The differences among SanDisk, Kioxia, Samsung, Micron, Longsys and Techwinsemi depend on who can convert eSSD certification, long-term agreements and controller capability into durable profit.
HDD provides the cash-flow anchor. AI data retention means nearline HDD is no longer just an old hard-drive cycle. May nearline HDD capacity rose +31% YoY, and long-term visibility from cloud customers has pushed companies such as Seagate and Western Digital into the cash-flow-asset discussion. HDD’s risks are also clearer: HAMR yield, price per EB, customer lock-ins and capex discipline will determine whether HDD becomes a less cyclical cash-flow asset or is pulled back into traditional-asset status by SSDs and price cycles.
This trade must be bought on evidence. The biggest risk in legacy storage re-rating is focusing only on target-price hikes. The truly useful indicators are five: the DDR4/DDR5 contract-price spread, eSSD EB shipments, hardness of LTA/SCA terms, NAND/DRAM capex structure, and inventory plus customer pushback against price hikes. As long as evidence continues to point to supply discipline and data-center demand, legacy storage is not “catch-up upside in lagging categories,” but a second-layer toll point in AI infrastructure.
I. This Is Not Another Storage Upcycle, but a Re-Segmentation of Legacy Assets
Storage price increases are no longer new information. DRAM, NAND, HBM, SSD and HDD have all been traded by the market, and investment banks have repeatedly raised target prices for strong companies. The new question is more specific: which price increases can become capitalizable profit, and which are merely high-beta numbers at a cyclical peak.
This question will determine how storage assets are ranked. Storage is not one single line item. It is five categories of assets being reshaped by the AI data stack at the same time: DDR4/LPDDR4 represents mature DRAM supply rights; NOR and SLC NAND are code-storage and control-entry assets; eSSD is the data-center capacity layer; nearline HDD is data-retention cash flow; and HBM is the purest bandwidth toll point. All benefit from AI, but their valuation logic is completely different.
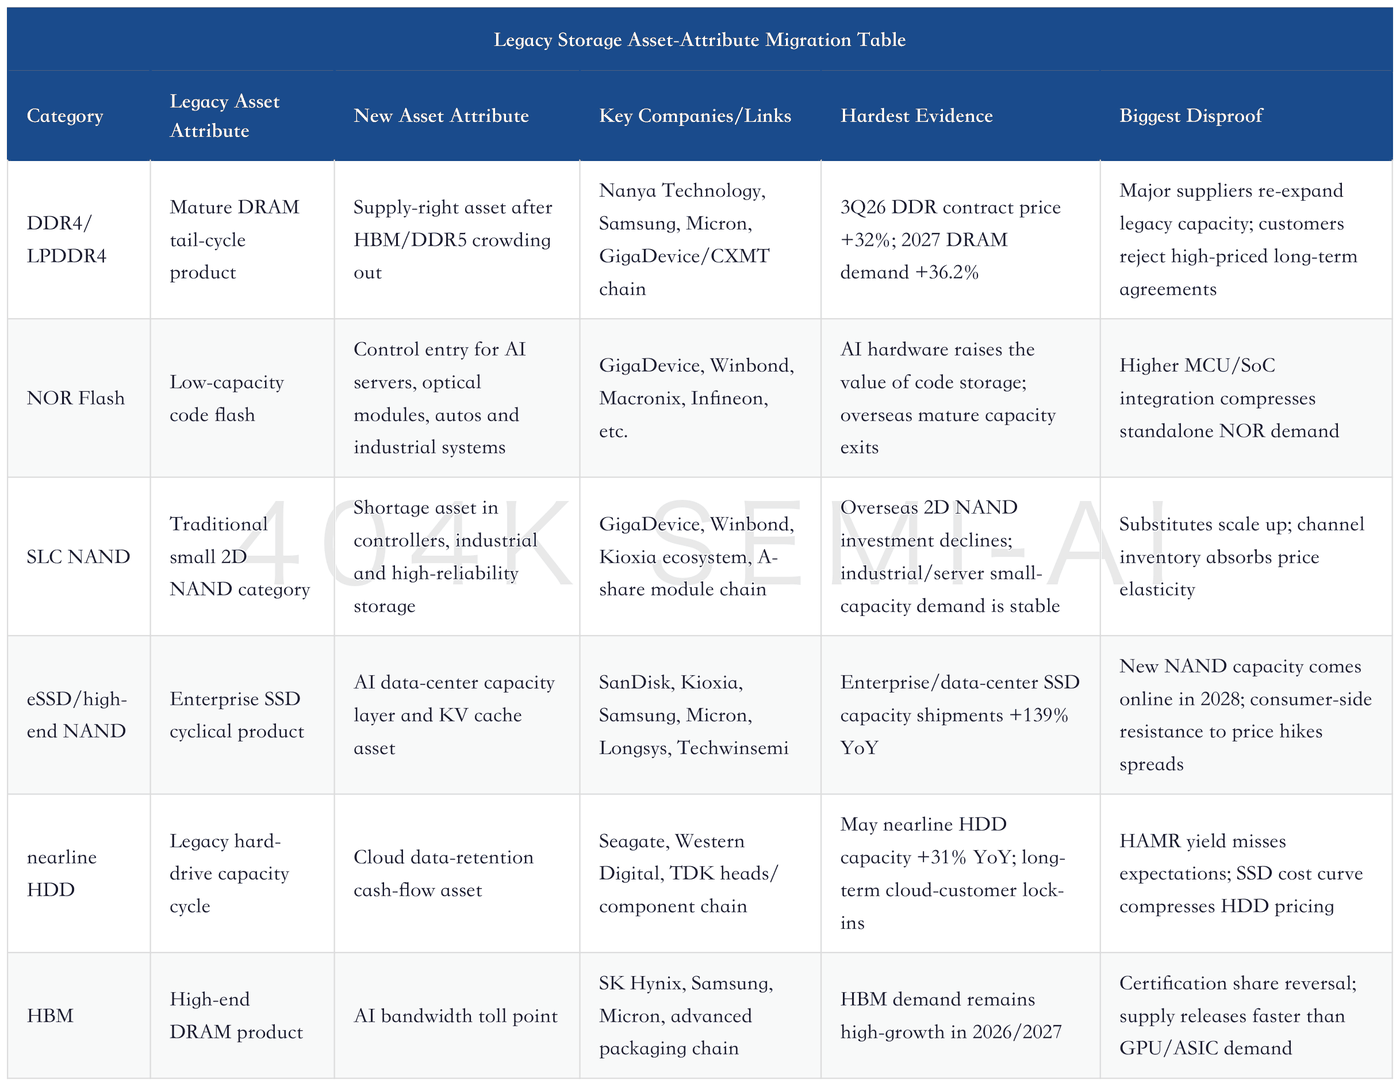
The point of this table is not to label all storage as good assets. Quite the opposite: it separates storage into distinct assets. DDR4 is a supply crowding-out trade; NOR and SLC NAND are mature-category supply-right trades; eSSD is a data-center capacity-layer trade; HDD is a cash-flow-visibility trade; and HBM is a bandwidth-purity trade. If investors buy the wrong asset attribute, they will receive very different volatility and valuation discounts within the same storage bull market.
AI Drives a Sector-Wide Storage Re-Rating: Who Has the Most Pricing Power in DRAM, NAND, SSD and HDD, with Samsung, SK Hynix, SanDisk, Western Digital and Seagate Earnings Cross-Checking One Another
The earlier overall framework already discussed how the AI data stack pushes DRAM, NAND, SSD and HDD into the same shortage cycle. What is now more important is segmentation: with the same shortage, which categories can retain profit, and which can only enjoy temporary price elasticity.
II. DDR4’s Value Is Not That It Is Behind, but That Major Suppliers Have Actively Abandoned It
DDR4 looks like an old product, but that is exactly why it is being repriced. Major suppliers are prioritizing cleanrooms, engineering resources and capex for HBM, DDR5 and advanced nodes. Mature DRAM supply has therefore become harder to restore quickly. Once supply is crowded out, legacy categories are no longer lagging capacity, but “old-asset toll points” with customers and no new supply.
The July storage monthly sent a strong signal: price forecast upgrades and supply-demand gaps appeared at the same time. More importantly, the gap has widened beyond what an ordinary inventory cycle can explain. Mature DRAM supply rights are being repriced. The specific numbers are shown below.
Nanya Technology is the clearest test case. JPMorgan upgraded Nanya Technology from Neutral to Overweight and raised its target price from NT$230 to NT$710, not because it suddenly seized the HBM crown, but because legacy DRAM is also re-rated in an upcycle. The report specifically emphasized that DDR4 supply-demand would rise with DDR5 and the overall DRAM market, while shortages in server cache memory and opportunities in eSSD-grade memory would improve product mix.
This matters for Taiwan’s Nanya Technology, and also for A-share niche storage. As long as the legacy DRAM shortage holds, the market will reprice GigaDevice, the CXMT chain, MCU external storage, and industrial/auto-grade storage entry points. These businesses used to be viewed as mature cyclicals. Now they have become supply receivers after major suppliers shifted capex elsewhere.
Nanya Technology Deep Dive: DDR4 EOL, SOCAMM Server Memory and the NT$710 Target Price; the Three Tests for Re-Rating Second-Tier DRAM Makers
DDR4’s risks are also direct. First, prices rising too quickly may force customers to place orders early, making the short term look strong while pulling demand forward. Second, if legacy categories are forcibly expanded, supply discipline after 2027 will be damaged. Third, although Nanya Technology and Chinese vendors benefit from the legacy DRAM shortage, if technology migration and customer certification cannot keep up, upside will remain at the price layer rather than becoming a long-term valuation layer.
So DDR4 is not simply “catch-up upside in a lagging product.” The three numbers truly worth tracking are the DDR4/DDR5 contract-price spread, LTA coverage ratio, and the use of legacy DRAM in server and eSSD cache memory. If these three numbers continue to strengthen, DDR4 will be one of the most easily underestimated lines in the legacy storage re-rating.
III. The Re-Rating of NOR and SLC NAND Comes from Small-Capacity Entry Points, Not Large-Capacity Narratives
NOR and SLC NAND are often underestimated because they lack the appeal of HBM and the capacity story of eSSD. But the more complex AI hardware becomes, the more it needs stable boot, configuration, control, and highly reliable small-capacity storage. GPU servers, optical modules, switches, automotive electronics, and industrial control systems all depend on this type of code-storage entry point.
GigaDevice’s target-price upgrade has brought this logic to the foreground. Morgan Stanley raised its target price for GigaDevice to RMB888, with a bull-case valuation of RMB1,542. The key is not simply the MCU business, but placing DRAM, NOR, SLC NAND, and customized storage into the same legacy-memory supply gap. After overseas leaders redirected resources toward HBM, DDR5, and high-end NAND, supply control in mature categories has instead concentrated in the hands of companies still willing to keep making these products.
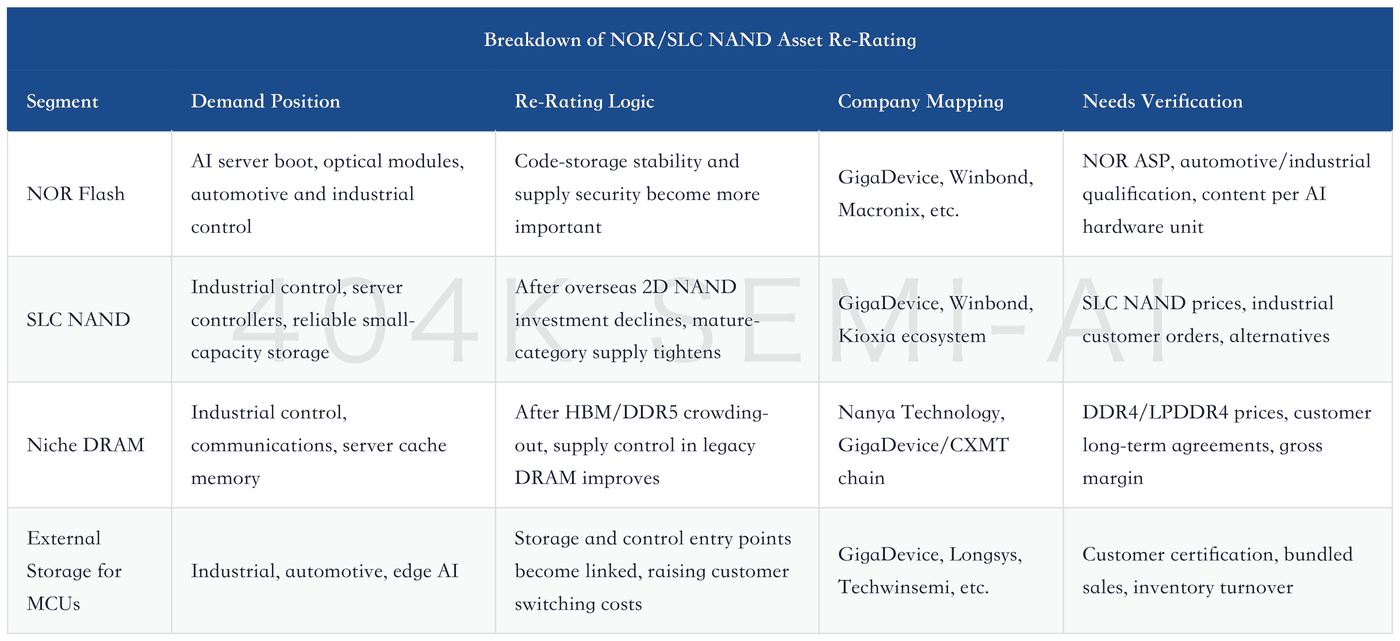
This logic differs from large-capacity NAND. The value of eSSD comes from exabyte-scale capacity demand; the value of NOR and SLC NAND comes from being “small in volume but indispensable.” In an AI server, the dollar content of NOR may not be large, but if supply is tight, certification cycles are long, and replacement costs are high, small categories can also generate highly elastic profits.
GigaDevice Deep-Dive Update: Morgan Stanley’s RMB888 Target Price and RMB1,542 Bull Case; How the Legacy-Memory Gap Re-Rates DRAM and NOR
This is also why memory should not be viewed through the traditional “high-end/low-end” binary. HBM is the highest-end product, but it is not the only monetization point. NOR and SLC NAND are not high-end, yet they may have stronger pricing stickiness because of supply contraction and fragmented applications. Mature categories are most vulnerable to being overlooked. By the time financial results show gross margins stepping up, the share price has usually already moved first.
The risk is that demand elasticity on this track is not as strong as in HBM and eSSD. For NOR and SLC NAND to be re-rated, prices, product mix, customer certification, and gross margins must all improve at the same time. If the market only sees price increases without improvement in customer structure and gross margins, it will still treat the move as a short-cycle catch-up trade.
IV. eSSD Is the Core of NAND’s Shift from a Price Trade to a Profit-Quality Trade
The NAND industry is no longer in a phase where “all NAND rises together.” Price elasticity has begun to diverge across consumer NAND, mobile NAND, client SSDs, and enterprise SSDs. The strongest variable is eSSD capacity demand from AI data centers. AI training, inference, KV cache, RAG, data lakes, and object storage all require a larger capacity layer. As a result, NAND is shifting from a consumer-electronics cyclical product into a data-center capacity asset.
The latest NAND industry update provides hard evidence. Morgan Stanley estimates AI NAND demand will rise from 205EB in 2025 to 609EB in 2027, increasing from 18% to 41% of total NAND demand. JPM’s May data also showed enterprise/data-center SSD capacity shipments of 41.4EB, up 139% YoY, far above ordinary SSD unit-shipment performance. This shows that the quality of NAND demand is changing; it is no longer just about smartphone and PC restocking.
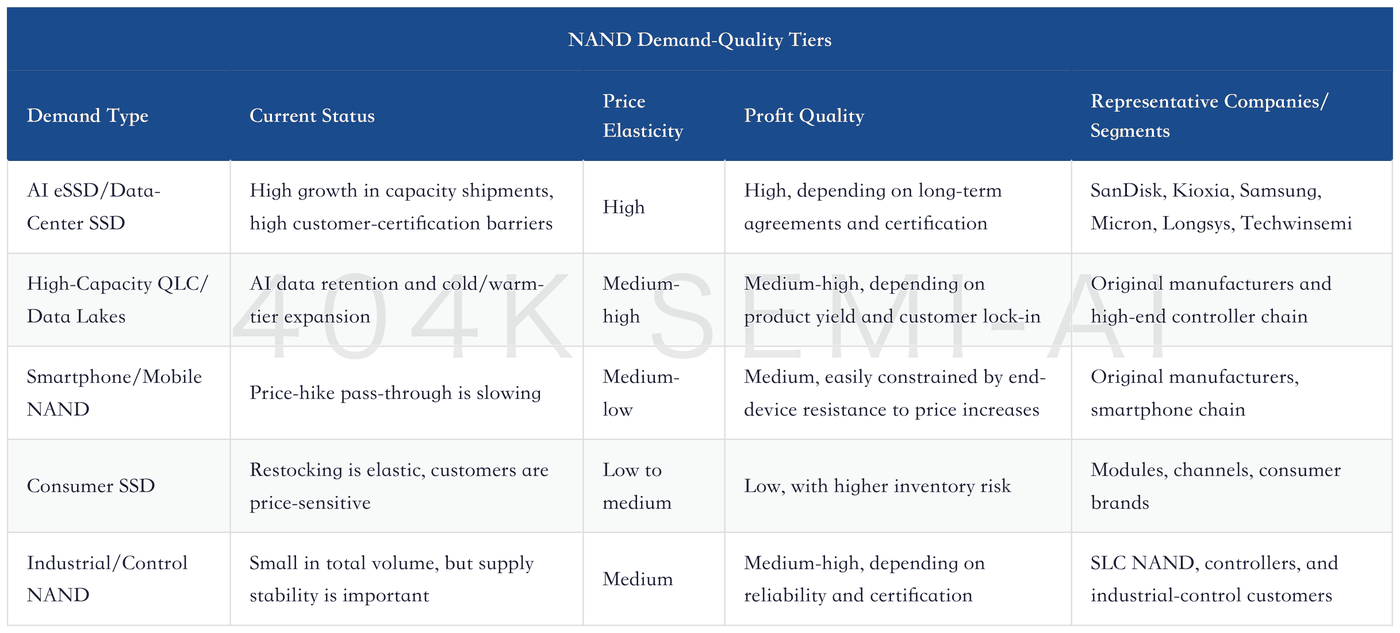
This table explains why SanDisk, Kioxia, and the high-end eSSD chain receive higher valuations, while ordinary modules and the consumer chain are more easily discounted. Even when NAND prices rise, whether customers are willing to sign long-term agreements, whether products can enter data centers, and whether they can pass high-reliability certification determine whether profits are short-term price elasticity or long-term cash flow.
NAND Industry Deep-Dive Update: The Threefold Verification of AI eSSD Shortages, Supply Discipline, and New Capacity in 2028
SanDisk and Kioxia are more about original-manufacturer profit quality, while Longsys and Techwinsemi are more about A-share mapping. SanDisk has been assigned a higher target price by the market because its eSSD share recovery, NAND long-term agreements, and profit durability are being reassessed. If Longsys can move from modules toward an enterprise SSD platform, its asset attributes will shift from an inventory cycle to a brand and controller platform. If Techwinsemi delivers on controller capability and customer certification, its elasticity will be stronger than that of ordinary module makers.
SanDisk Deep-Dive Update: Jefferies’ US$3,000 Target Price; How eSSD Share Recovery and NAND Long-Term Agreements Re-Rate Profit Durability
Longsys Deep-Dive Update: Morgan Stanley’s RMB673 Target Price; How the AI NAND Gap and TCM Model Re-Rate the Enterprise SSD Platform
The counterevidence window for eSSD is 2028. If new NAND capacity is released in a concentrated way while AI SSD demand growth slows, the industry will quickly move from shortage back to surplus. For bulls to keep winning, eSSD EB shipments must continue growing rapidly, NAND capex must remain squeezed by DRAM/HBM, long-term agreement terms must be sufficiently firm, and consumer-end inventory must not lose control.
So NAND is not uninvestable, but investors can no longer buy it with the single word “price hikes.” What matters now is profit quality: who has eSSD, who has long-term agreements, who has high-capacity products, who has customer certification, and who can convert profits into cash and returns before 2028.
V. HDD Is the Most Easily Overlooked Cash-Flow Asset
HDD looks older, but its role in the AI data stack is clearer: low cost, large capacity, and suitable for long-term retention. Data generated by AI training and inference, model versions, logs, video, RAG knowledge bases, and enterprise data lakes will not all sit in expensive high-performance SSDs. Nearline HDD handles large-scale data retention. Its value comes from long-duration cloud capacity demand, not the short-cycle consumer electronics cycle.
May HDD and SSD data provided a direct validation: nearline HDD capacity was +31% YoY, while enterprise/data-center SSD capacity was +139% YoY. The former shows cloud data retention is still expanding; the latter shows the high-performance capacity tier is stronger. The two are not simple substitutes. Together, they form the hot/cold tiering of the AI data stack.
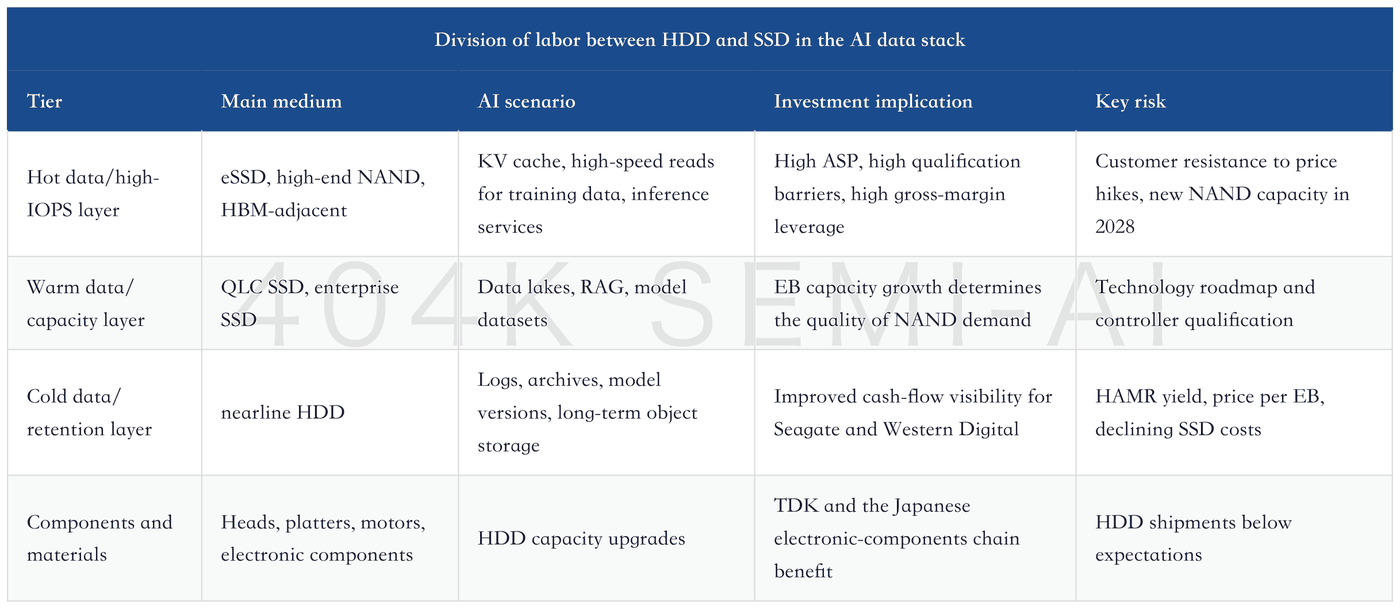
The core debate around Seagate and Western Digital is not whether HDD will suddenly become a growth stock, but whether their cash flows can reduce the cyclical discount. As long as cloud customers lock in orders, capacity pricing, HAMR/Mozaic yields, and capex discipline hold, HDD may shift from an “old hard-drive cyclical stock” into an “AI data-retention cash-flow asset.”
Deep Update on AI Storage: Morgan Stanley’s May HDD and SSD Data Confirm Data-Center Capacity Demand Remains Elevated
This theme will also spill over into components. TDK, magnetic heads, platters, and related electronic components will gain another layer of leverage from HDD capacity upgrades. It is not as crowded a market trade as HBM, but it may continue to show up in earnings as steadier orders and margin improvement.
The risks should not be ignored. The long-term HDD thesis requires HAMR yields to materialize, cloud customers to keep purchasing, and the SSD price curve not to suddenly breach nearline HDD’s total cost of ownership. If these conditions loosen, HDD will revert to a traditional cyclical asset, and valuation expansion will not be sustained.
VI. LTAs, Inventory, and Cash Flow: Can Legacy Storage Be Capitalized?
For legacy storage to move from a cyclical stock into an asset re-rating, the key is not price increases themselves, but whether profits after those increases can be locked in through contracts and cash flow. In every major storage cycle historically, the market first gives EPS leverage, then questions peak profits, and finally returns to inventory and capex. Only when contracts, customers, and cash flow suppress earnings volatility does the valuation multiple have a real chance to rise.
This is also why the discussion of LTAs and SCAs in the July storage monthly is important. An LTA is not a simple sales contract. It determines whether customers are willing to accept tougher volume-price arrangements in exchange for supply certainty. An SCA is not an ordinary procurement clause either. It places price floors, price ceilings, and volume commitments in a clearer framework. For memory manufacturers, the harder the contract, the smaller the discount applied to peak profits. For downstream customers, the harder the contract, the earlier inventory and cost pressure becomes explicit.
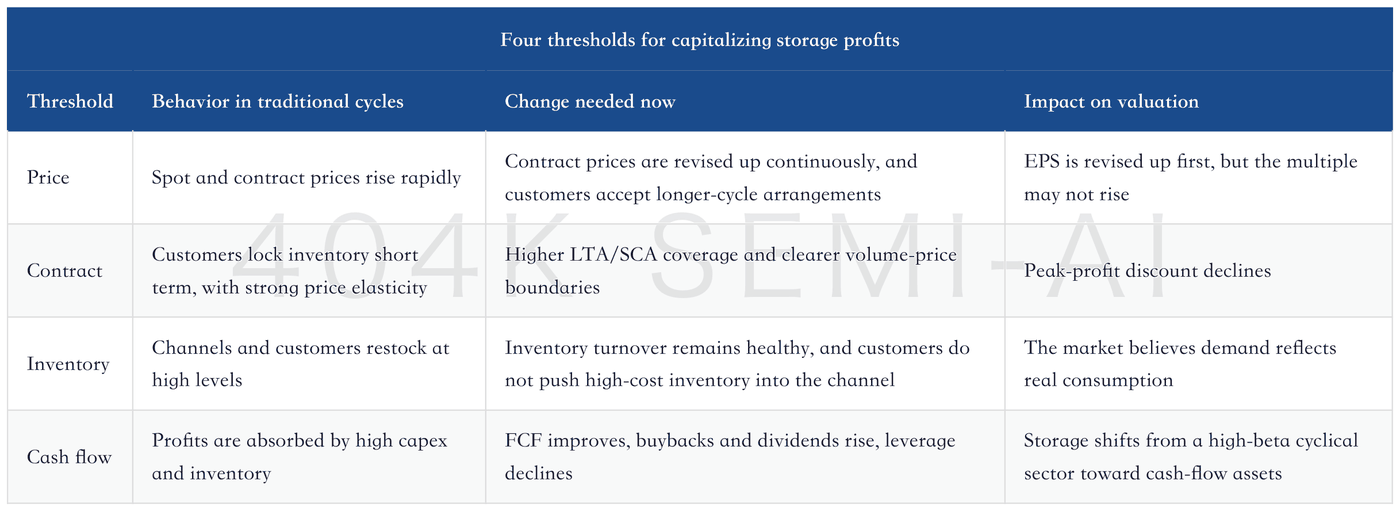
DDR4, NOR, SLC NAND, eSSD, and HDD are not in the same position across these four thresholds. DDR4 has passed the price threshold first; the next steps are the contract and inventory thresholds. NOR and SLC NAND have somewhat lower price elasticity, but stronger customer qualification and replacement costs. The key is whether gross margins can improve at the same time. eSSD has the strongest demand, but customer concentration and new capacity in 2028 will repeatedly test contract rigidity. HDD does not have the highest price elasticity, but it can most easily provide cash-flow evidence through FCF and shareholder returns.
This explains why the market assigns very different multiples to different companies even when they all benefit from price increases. HBM can command a high multiple through bandwidth scarcity. eSSD needs customer qualification and long-term agreements to prove profit durability. DDR4 needs to prove that major vendors’ exit is not a short-term move. HDD needs to prove that cloud capacity purchasing is not a one-quarter pull-in. Without contracts and cash flow, price increases are only P&L; leverage. With contracts and cash flow, price increases have a chance to become an asset attribute.
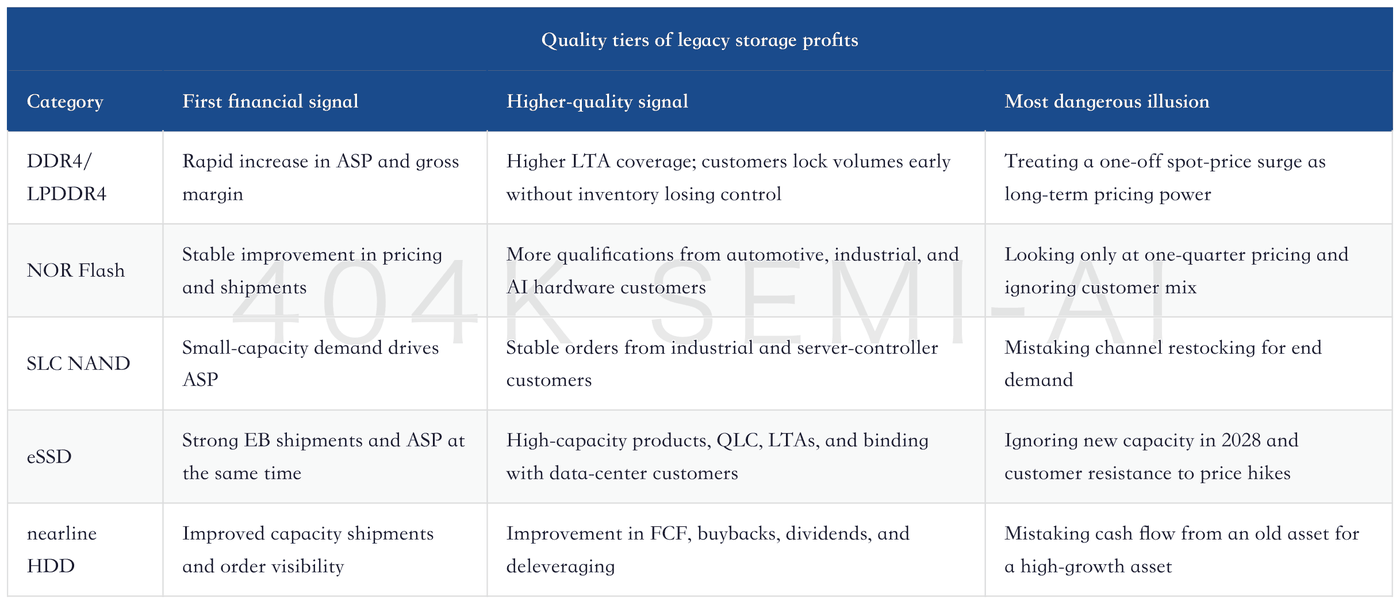
Inventory is the most easily overlooked counterevidence. In an upcycle, customers place orders early to lock supply, channels stock in advance to secure availability, and companies also expand procurement to secure raw materials and capacity. If demand is genuinely strong, inventory turnover will not deteriorate meaningfully. If prices rise too quickly, inventory will first accumulate at module makers, channels, and small-to-mid-sized customers. The biggest risk to a storage re-rating is not that prices fail to rise, but that prices rise, inventory rises too, and operating cash flow fails to follow.
Cash flow is the final judge. If all the money earned by manufacturers goes back into capex, it means the industry is still sowing the seeds for the next round of oversupply. Only if part of the profit is converted into buybacks, dividends, deleveraging, and more restrained capacity discipline will the market reduce the cyclical discount. HDD companies can provide evidence most easily on this front, but DRAM and NAND manufacturers must also prove capex is not losing control again.
From this perspective, the legacy storage re-rating is not about “the older, the better,” but about whether old assets can form irreplaceable supply rights. If DDR4 is only about price elasticity, its valuation will quickly be capped by post-2027 supply and customer resistance to price hikes. If DDR4 can be locked in by LTAs, server cache memory, and major vendors’ EOL actions, it becomes a supply-rights asset. If NOR and SLC NAND are merely small-category price increases, the market will not assign very high multiples. If they are bound to AI servers, optical modules, automotive, and industrial-control customers, the valuation logic will move closer to that of a customer-access asset.
VII. Company Ranking: Purity, Beta, Certainty, and Crowding Should Not Be Mixed Together
The most common mistake in re-rating legacy memory is ranking all companies by target-price upside. A faster-rising target price does not mean the highest earnings quality; greater share-price beta does not mean the hardest asset attributes. A more reasonable ranking method is to place companies across four dimensions: AI purity, control over legacy-category supply, earnings durability, and difficulty of disconfirmation.
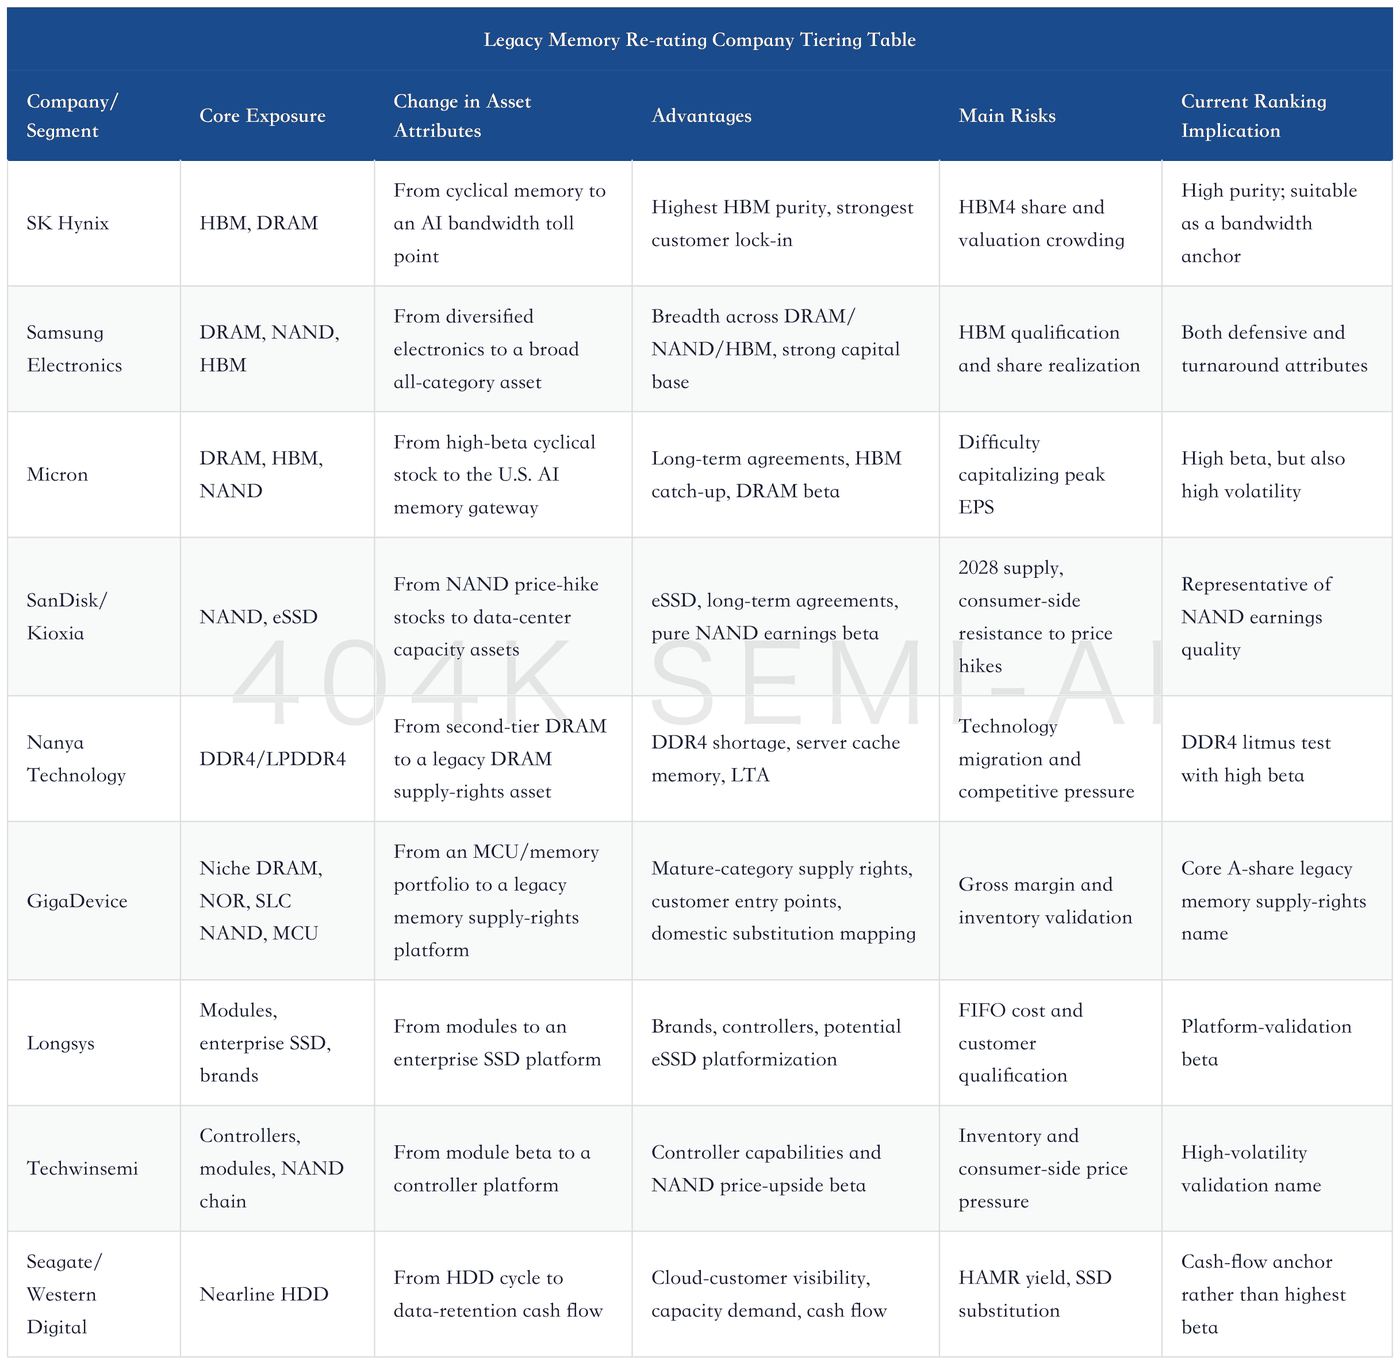
This table is intended to solve two problems. The first is “what kind of purity to buy.” If investors want the highest AI purity, HBM remains the anchor; if they want expectation gaps in legacy assets, DDR4, NOR, and SLC NAND offer greater beta; if they want earnings-quality validation, eSSD and HDD are easier to assess through monthly shipments, long-term agreements, and cash flow. The second is “what counter-evidence to use.” Different companies cannot be evaluated using the same checklist, otherwise HBM companies’ share issues, NAND companies’ supply issues, and HDD companies’ cash-flow issues will be mixed together.
SK Hynix is the bandwidth anchor. It is not a legacy memory company, but it must be included in the ranking table because HBM determines the valuation ceiling for memory. As long as SK Hynix maintains its lead in HBM3E, HBM4, and customer qualification, the market will link high-quality memory profits with AI bandwidth. Its risk is not whether demand exists, but share, yield, pricing, and valuation crowding. When HBM is too hot, the expectation gap in legacy memory can become more attractive instead.
Samsung Electronics is a breadth asset. Samsung has DRAM, NAND, HBM, foundry, and system semiconductors at the same time. Its advantage is breadth, and its drawback is also breadth. If it succeeds in catching up on HBM qualification, Samsung will have both turnaround beta and support from the DRAM/NAND upcycle; if HBM continues to lag, the market will apply a breadth discount. For the legacy memory framework, Samsung is more of an observation window into industry supply discipline, because its capex and product priorities will affect supply and demand in DRAM, NAND, and mature categories.
Micron is the U.S. AI memory gateway. Micron’s advantages lie in DRAM-cycle beta, HBM catch-up, customer relationships, and discussions around SCA/LTA terms. Its issue is that the market can capitalize peak EPS too early, then discount it back using a cyclical framework. For Micron, investors should not only look at target prices, but also whether HBM revenue mix, mainstream DRAM contract prices, NAND profits, cash flow, and capex discipline are improving at the same time.
SanDisk and Kioxia represent NAND earnings quality. Their re-rating should not be assessed only by NAND ASP, but also by data-center SSDs, high-capacity QLC drives, customer long-term agreements, and new capacity in 2028. SanDisk is closer to a pure NAND re-rating, while Kioxia is closer to NAND supply discipline and valuation repair. Their risks are concentrated in the same place: if new supply in 2028 runs ahead of AI eSSD demand, the market will compress valuation first and revise earnings later.
Nanya Technology is the DDR4 litmus test. JPM upgraded it to Overweight and raised its target price to NT$710; what the market is really trading is legacy DRAM supply rights. Nanya is not an HBM company, and precisely because it is not an HBM company, it is better suited to validate whether second-tier DRAM makers can regain pricing power through legacy categories after major manufacturers abandon DDR4/LPDDR4. For Nanya, the most important variables are DDR4/LPDDR4 pricing, server exposure, eSSD-grade memory, and LTA, rather than misreading it as a substitute for high-end memory.
GigaDevice is the core A-share legacy memory supply-rights name. It combines niche DRAM, NOR, SLC NAND, MCU, and customer entry points within one company, with beta coming from multi-category resonance. The market has already seen Morgan Stanley raise its target price to RMB888 and assign a bull-case value of RMB1,542, but what really needs to be validated is gross margin, inventory, DRAM revenue mix, NOR/SLC NAND pricing, and customer projects. This is not a trade driven by only one price variable; it must use quarterly data to prove that the legacy memory shortage can flow into the financial statements.
Longsys and Techwinsemi are platform-validation beta names. If Longsys can connect brands, controllers, and enterprise SSD customer qualification, its valuation will migrate from the module inventory cycle toward an enterprise SSD platform. If Techwinsemi can convert controller capabilities and NAND price hikes into customer wins, its beta will be stronger than that of ordinary module makers. Their shared risks are inventory, FIFO cost, and consumer-side resistance to price hikes. The A-share module chain most easily delivers large earnings beta in an upcycle, and is also most easily hit by inventory when prices reverse.
Seagate and Western Digital are cash-flow anchors. They may not deliver the highest revenue growth, but they may provide the clearest FCF, buybacks, and cloud-customer visibility. The more stable nearline HDD’s role in AI data retention becomes, the more willing the market will be to reduce the cyclical discount applied to legacy hard drives. HDD companies should not be measured using HBM growth multiples; investors should instead focus on capacity shipments, price per EB, HAMR yield, customer order lock-ins, and shareholder returns.
The core of company ranking is not to arrive at a single answer, but to establish a way to read capital rotation. In the early stage of a memory rally, the market buys the highest beta; in the middle stage, it buys earnings quality; in the late stage, it buys cash flow and shareholder returns. HBM, DDR4, NOR, SLC NAND, eSSD, and HDD will each take turns outperforming at different stages. If the stage is misread, what investors buy may not be asset re-rating, but high volatility at the end of the cycle.
8. Three Worldviews: Cycle Peak, Structural Upswing, Asset Re-Rating
There are now three worldviews around the memory rally. The first sees this as only a strong cycle: price increases will eventually draw in supply, and the market will return to oversupply after 2027 or 2028. The second sees AI driving a structural upswing, but with divergence by product category; only HBM, eSSD, and some legacy DRAM can enjoy a longer cycle. The third is more aggressive, arguing that LTAs/SCAs, cloud customer lock-ins, supply discipline, and data-center capacity demand will allow some memory profits to receive higher capitalization multiples.
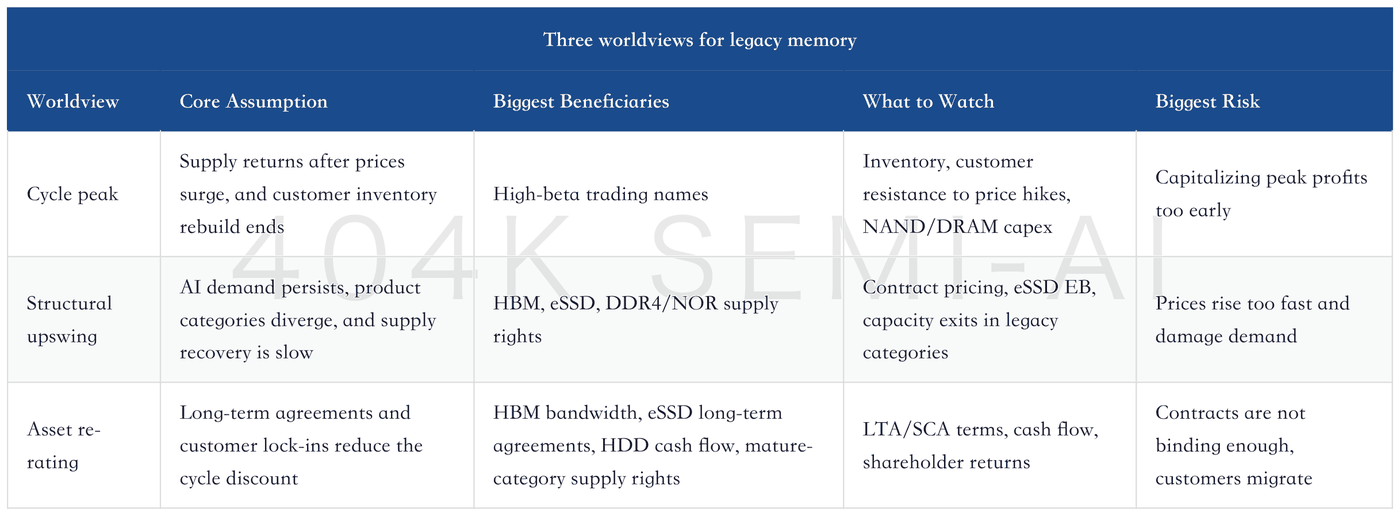
Current evidence is closer to somewhere between the second and third worldviews. Upward revisions to DDR and NAND pricing, the DRAM supply-demand gap, high eSSD capacity growth, nearline HDD capacity growth, and the sharp target-price increase for Nanya Technology all show that this is not a normal restocking cycle. But whether it can become a true asset re-rating still depends on contract terms, customer lock-ins, and cash-flow returns.
The operating implications of the three worldviews differ greatly. If one believes in a cycle peak, the most important thing is not to overstate forward profits, and exposure should be reduced when prices and inventory expectations are extremely optimistic. If one believes in a structural upswing, memory needs to be split into product categories, and investors should only own assets with slow supply, firm demand, and strong customer qualification. If one believes in asset re-rating, one needs to accept a higher valuation center, while also requiring companies to provide harder evidence on contracts and cash flow.
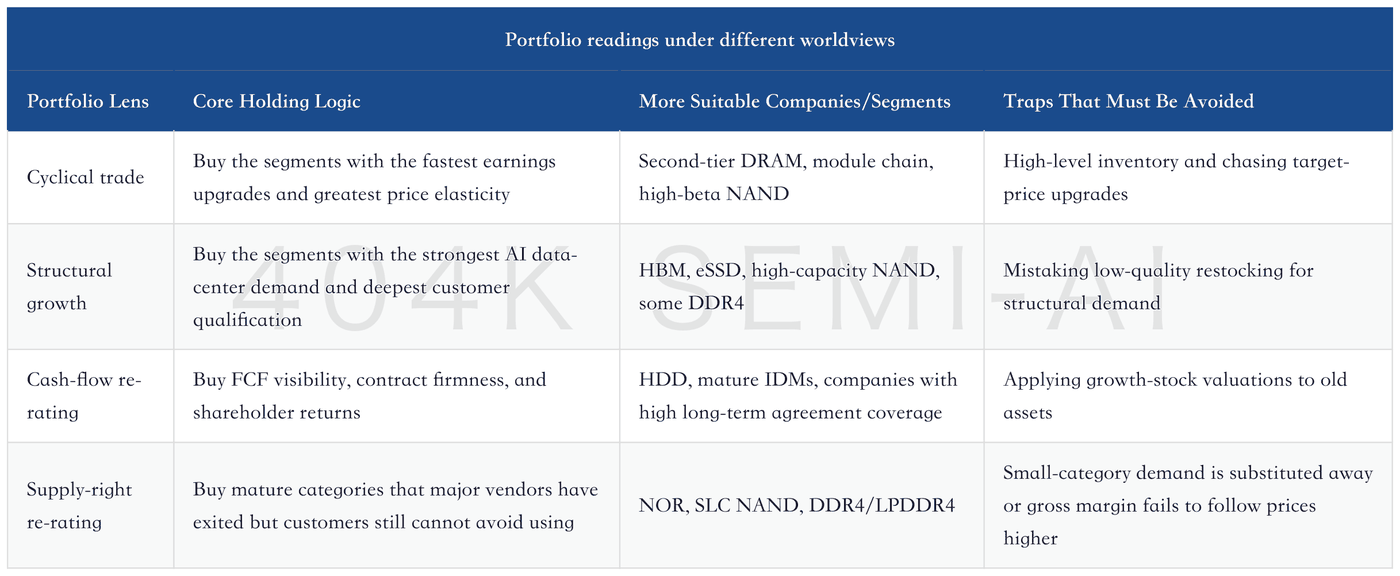
The most dangerous approach is to price all data under the third worldview. The biggest lesson in memory history is that high profits attract supply and substitution. What is different now is that HBM and the DRAM/HBM priority have indeed squeezed NAND and mature DRAM supply, AI data centers have indeed raised capacity demand, and long-term agreements are indeed becoming more binding. But all of these need continuous verification.
There is also an easily overlooked divergence: memory is not one demand curve. HBM is constrained by GPU and ASIC shipments, customer qualification, and advanced packaging; DDR4 is affected by major vendors’ EOL decisions and server cache memory; NAND is affected by eSSD and new capacity in 2028; HDD is affected by cloud customer data retention and HAMR yield; NOR/SLC NAND is affected by fragmented end markets and reliability qualification. Combining these variables into “memory price increases” obscures the real risks.
Therefore, every time a target price is revised upward, it should first be broken down into three layers. The first layer is the price assumption: which type of ASP did the institution raise? The second is volume and customers: is demand coming from data centers, consumer end markets, industrial end markets, or channels? The third is the multiple assumption: did the institution raise long-term ROE, PBR, PE, or terminal value? Only when all three layers improve at the same time is it an asset re-rating; if only price improves, it is cyclical elasticity.
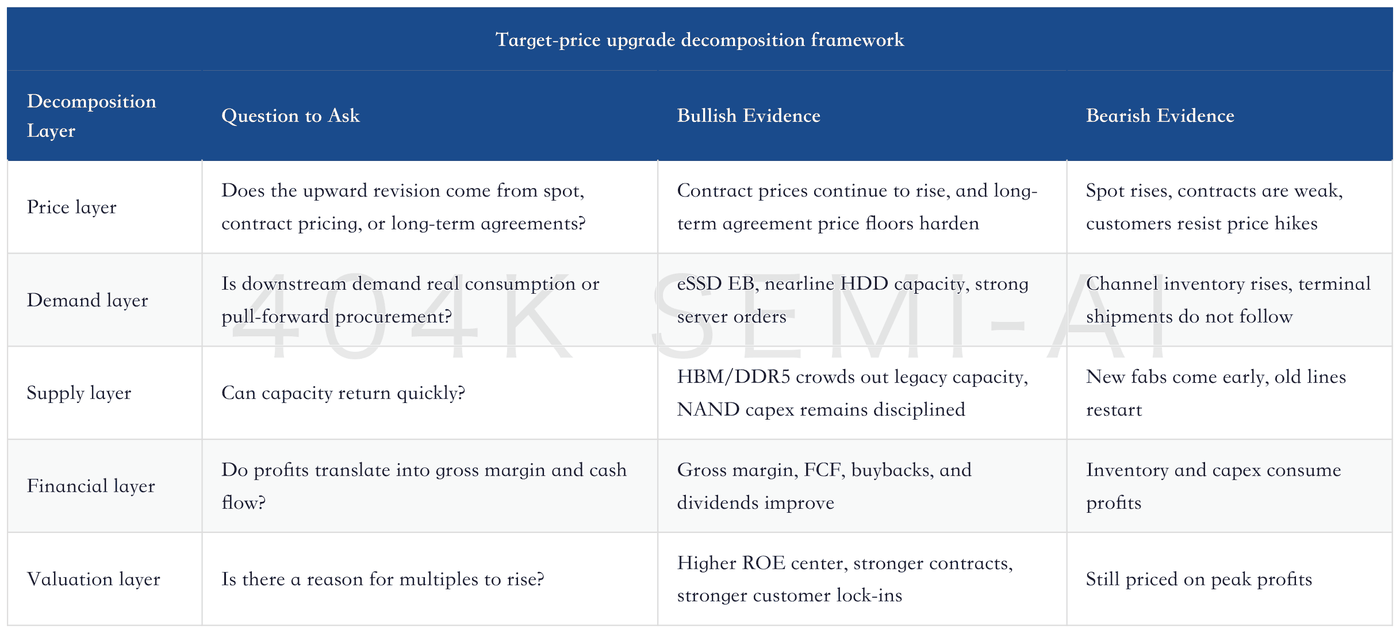
This framework helps avoid being misled by a single number. A target-price upgrade itself is not the answer; the assumptions inside the target price are the answer. The significance of Nanya Technology at NT$710 is that DDR4 supply rights have been written back into the model. The significance of GigaDevice at RMB888 is that legacy memory gaps in DRAM, NOR, and SLC NAND are beginning to enter the income statement. The significance of a high target price for SanDisk is that NAND long-term agreements and eSSD share have been capitalized. The significance of target-price upgrades for HDD companies is that the cash-flow discount has declined. The numbers differ, and so do the underlying asset attributes.
Verification Calendar, Portfolio Mapping, and Common Misreadings: Use Data to Decide How Far This Theme Can Run
What needs to be watched next in legacy memory re-rating is not share prices, but data. Share prices will move in advance and research target prices will continue to chase, but the real determinant of whether the re-rating can continue is verifiable indicators. Without these indicators, legacy memory will quickly fall back from asset re-rating into a repeated narrative.
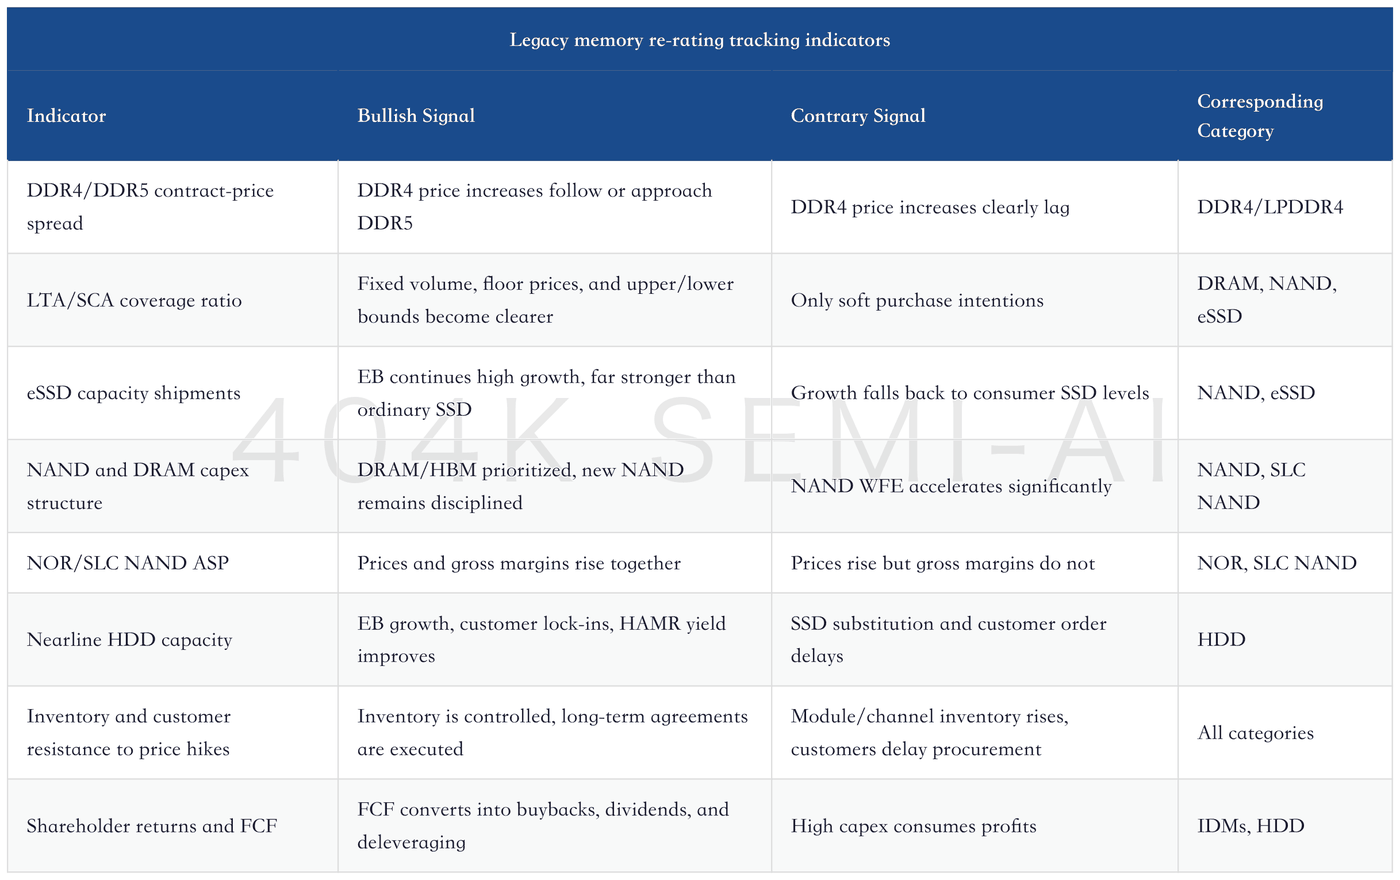
More important is the order of verification. Memory prices move first, customer orders are confirmed afterward, gross margin then appears in financial reports, and inventory and cash flow finally provide quality judgment. If investors only watch prices, they will get excited too early; if they wait only for cash flow, they may miss the early part of the rally. The steadier approach is to split the verification points by quarter.
The next four quarters can be assessed by time window. In 3Q26, first watch whether prices can continue to transmit, with the focus on DDR/NAND contract pricing, eSSD quotes, and NOR and SLC NAND ASP, corresponding to Nanya Technology, GigaDevice, SanDisk, and Kioxia; if contract pricing falls short of expectations or customers resist price hikes, that is the first contrary signal. In 4Q26, watch whether contracts and inventory match, with the focus on LTA/SCA terms, customer inventory, module inventory, and server orders, corresponding to Micron, Samsung Electronics, SK hynix, Longsys, and Techwinsemi; if inventory rises faster than revenue, or long-term agreement terms weaken, it means price elasticity has not translated into profit quality.
In 1H27, watch whether profit quality can materialize, with the focus on gross margin, operating margin, FCF, and capex structure, corresponding to IDMs, HDD companies, and A-share niche memory names; if gross margin does not follow prices higher, or capex restarts too quickly, the market will reapply a cyclical discount. In 2H27, watch whether supply discipline can extend into 2028, with the focus on new-fab progress, NAND WFE, and HBM/DDR5 capex priority, corresponding to NAND IDMs, the equipment chain, and the module chain; if new supply for 2028 comes early, or AI eSSD demand slows, long-term valuations will be compressed first.
This verification calendar has two uses. First, it can judge the stage of the rally. If prices remain strong in 3Q26 but inventory deteriorates in 4Q26, the rally is still at the cyclical-elasticity stage. If prices, contracts, inventory, and gross margin gradually take turns supporting the thesis, the structural upswing becomes more credible. If cash flow and shareholder returns also begin to improve, asset re-rating is truly established. Second, it can rank companies. Nanya Technology and GigaDevice should first be assessed on prices and legacy-category gross margins; SanDisk and Kioxia first on eSSD and long-term agreements; Seagate and Western Digital first on capacity shipments and FCF; SK hynix, Samsung, and Micron still on HBM, DRAM, and capex priority.
Legacy memory re-rating also needs a risk checklist. Market sentiment is now very hot, and any risk will be ignored in the short term. But risks do not disappear; they only appear at different times. The earliest to appear are usually customer resistance to price hikes and inventory; the slowest are supply recovery and capex. The later the risk, the easier it is for the market to assign high valuations in the early stage; once risks arrive early, valuation drawdowns will also be faster.
