
Leader Harmonic Deep Dive: 80-90% Humanoid Robot Share, 1.44 Million Sets of Harmonic Reducer Capacity, and a RMB138 Valuation Anchor
目录
Too Long; Didn’t Read
1. What This Company Actually Sells: The Precision Transmission Gatekeeper Inside Robot Joints
II. Why It Is Being Repriced Now: From Industrial Robot Components to Humanoid Robot Joint Supplier
III. The Value of High Share: Customer Validation, Process Closed Loop, and Pricing Discipline
IV. Capacity, ASP, and Gross Margin: Three Calculations Behind 1.44 Million Units of Annualized Capacity
V. Sell-Side Divergence: What RMB138, RMB264, RMB269, and RMB496 Are Really Betting On
VI. My Scenario Framework: First Acknowledge a Good Company, Then Ask Whether the Price Is Good
VII. Company and Peer Ranking: Leader Harmonious Drive Is Strong in Rotary Joints, Not the Entire Robotics Chain
8. Capability Transfer: From Industrial Robots to Humanoid Robots, How Old Assets Become New Assets
9. SKF Joint Venture and Overseas Customers: The Global Supplier Option Is Still in the Validation Phase
10. Financial Quality: Growth Has Emerged, but Cash Flow and Gross Margin Still Need Further Validation
11. The Next Four Quarters: What Really Matters Is Not Trade Shows, but These Numbers
XII. Falsification Checklist: Signals That Market Pricing Has Gone Too Far
XIII. Data Definitions: Which Numbers Come from the Company and Which Come from Sell-Side Assumptions
14. Final Investment Judgment: From the Real Industry Bottleneck to Real Financial Validation
本内容基于公开资料和研报数据整理,不构成任何投资建议,不代表任何个人观点,仅供学习参考,请理性阅读
The most valuable part of Leader Harmonic is not the “robotics concept,” but its hard-to-replace harmonic reducer capability inside rotary joints. The company is moving from an industrial robot component supplier to a capacity bottleneck in China’s humanoid robot joint supply chain. The investment debate is also centered on whether capacity, share, ASP, and terminal valuation can all be realized at the same time.
Too Long; Didn’t Read
This is a robot joint bottleneck company. Leader Harmonic Drive Systems (688017.SH) mainly sells harmonic reducers, integrated electromechanical modules, planetary roller screws, and precision components. In 2025, industrial and embodied-intelligence robot components have become the main revenue line, while harmonic reducer sales have grown rapidly, indicating that the company has moved from an industrial robot recovery story to the front row of humanoid robot volume ramp-up.
High share is a real advantage; a full valuation is a real constraint. Goldman Sachs’ research indicates the company has about 80-90% share among domestic humanoid robots using harmonic reducers, up from roughly 70% last year. But the same model gives a RMB138 target price, implying about 71.7% downside versus a RMB488 share price, because 2026E/2027E P/E has already reached 411x/276x.
Capacity ramp determines the revenue slope. The company’s capacity was about 600k-700k units by end-2025. Goldman Sachs’ figures show monthly capacity of about 80k units in June 2026, with a year-end target of 120k units, implying annualized capacity of 1.44mn units. If domestic humanoid robots reach 200k units in 2027 due to subsidies or major customer orders, Leader Harmonic will have a chance to convert the “joint bottleneck” into revenue elasticity.
Pricing discipline matters more than price hikes. Management is not rushing to raise prices on scarce capacity. Instead, it prefers to maintain leading share at lower prices and compress the returns available to new entrants. This will cap near-term gross margin imagination, but can strengthen long-term customer lock-in. In 2025, the company’s overall gross margin was 36.91%, and robot component gross margin was 34.88%. The key issue ahead is whether price declines can be absorbed by yield improvement, automation, and scale.
Sell-side divergence is essentially divergence on the terminal number of robots. Goldman Sachs at RMB138, Morgan Stanley at RMB269, JPMorgan at RMB264, and Citi at RMB496 are not fundamentally disagreeing on whether 2026 revenue grows. They are assigning completely different probability weights to humanoid robot shipments before 2030, the number of harmonic reducers per unit, module ASP, overseas customer adoption, and exit multiples.
Investors should track four numbers. Over the next four quarters, the most important metrics are whether monthly capacity approaches 120k units, whether harmonic reducer sales continue to outperform the industrial robot cycle, whether the revenue contribution from integrated electromechanical modules rises, and whether operating cash flow and inventory can withstand capacity expansion. Looking only at trade shows, customer lists, or concept heat will underestimate valuation drawdown risk.
1. What This Company Actually Sells: The Precision Transmission Gatekeeper Inside Robot Joints
Leader Harmonic is not a full robot company, nor is it an upstream concept stock built only on a long-term vision. It sells the core components inside robot joints that provide speed reduction, transmission, and precision retention. The most important product is the harmonic reducer. The value of a harmonic reducer is not in its appearance, but in compact size, high reduction ratio, low backlash, long life, and batch consistency. Whether a robot can walk, grasp, rotate, or carry steadily ultimately comes down to the torque, precision, and service life of every joint.
The company’s full name is Suzhou Leader Harmonic Drive Systems Co., Ltd., with the securities abbreviation Leader Harmonic. It listed on the STAR Market in 2020. Company filings define the business as the R&D;, design, production, and sale of precision transmission devices, used in industrial robots, CNC machine tools, medical devices, semiconductor production equipment, new energy equipment, and other scenarios. This definition looks broad, but profit elasticity mainly comes from two lines: harmonic reducer demand driven by the recovery in industrial robots, and incremental demand for rotary joints as humanoid robots move from prototypes to small-batch production.
There are two especially important types of joints in the robot value chain. One is the rotary joint, centered on harmonic reducers, frameless torque motors, encoders, torque sensors, and controllers. The other is the linear joint, with common routes including planetary roller screws, ball screws, and other linear actuators. Leader Harmonic’s main battlefield is rotary joints. Its advantage is turning harmonic reducers into scalable, highly consistent industrial products, while extending into integrated electromechanical modules. Planetary roller screws are also an area the company is building out, but current revenue and visibility are still not comparable to harmonic reducers.
This is why the market is repricing Leader Harmonic. When the industrial robot cycle turns up, harmonic reducer demand recovers. When humanoid robots enter small-batch delivery, each robot may require multiple rotary joints, and the number of harmonic reducers per unit can move from single digits to more than 10. The supply-chain bottleneck shifts from “whether there is a prototype” to “whether there are stable, cheap joints that can be delivered at scale.” Leader Harmonic sits in this position, so its share price is no longer being valued like a traditional machinery component company, but on long-term humanoid robot penetration.
The company’s 2025 data already shows this change in asset characteristics. Revenue, net profit attributable to shareholders, recurring net profit, and operating cash flow all recovered together; the specific numbers are checked in the financial tables below. Compared with 2024, when revenue grew slowly and attributable net profit declined, 2025 was clearly not just a low-base rebound, but a simultaneous improvement in downstream order structure and capacity utilization.
The product mix tells the same story. Industrial and embodied-intelligence robot components have become the largest revenue pool. Machinery equipment components are still growing. CNC machine tools and medical devices mainly reflect the spillover of precision transmission capability. By product category, harmonic reducers and metal components determine the revenue base, while integrated electromechanical products determine the future ASP ceiling. The specific figures are shown below.
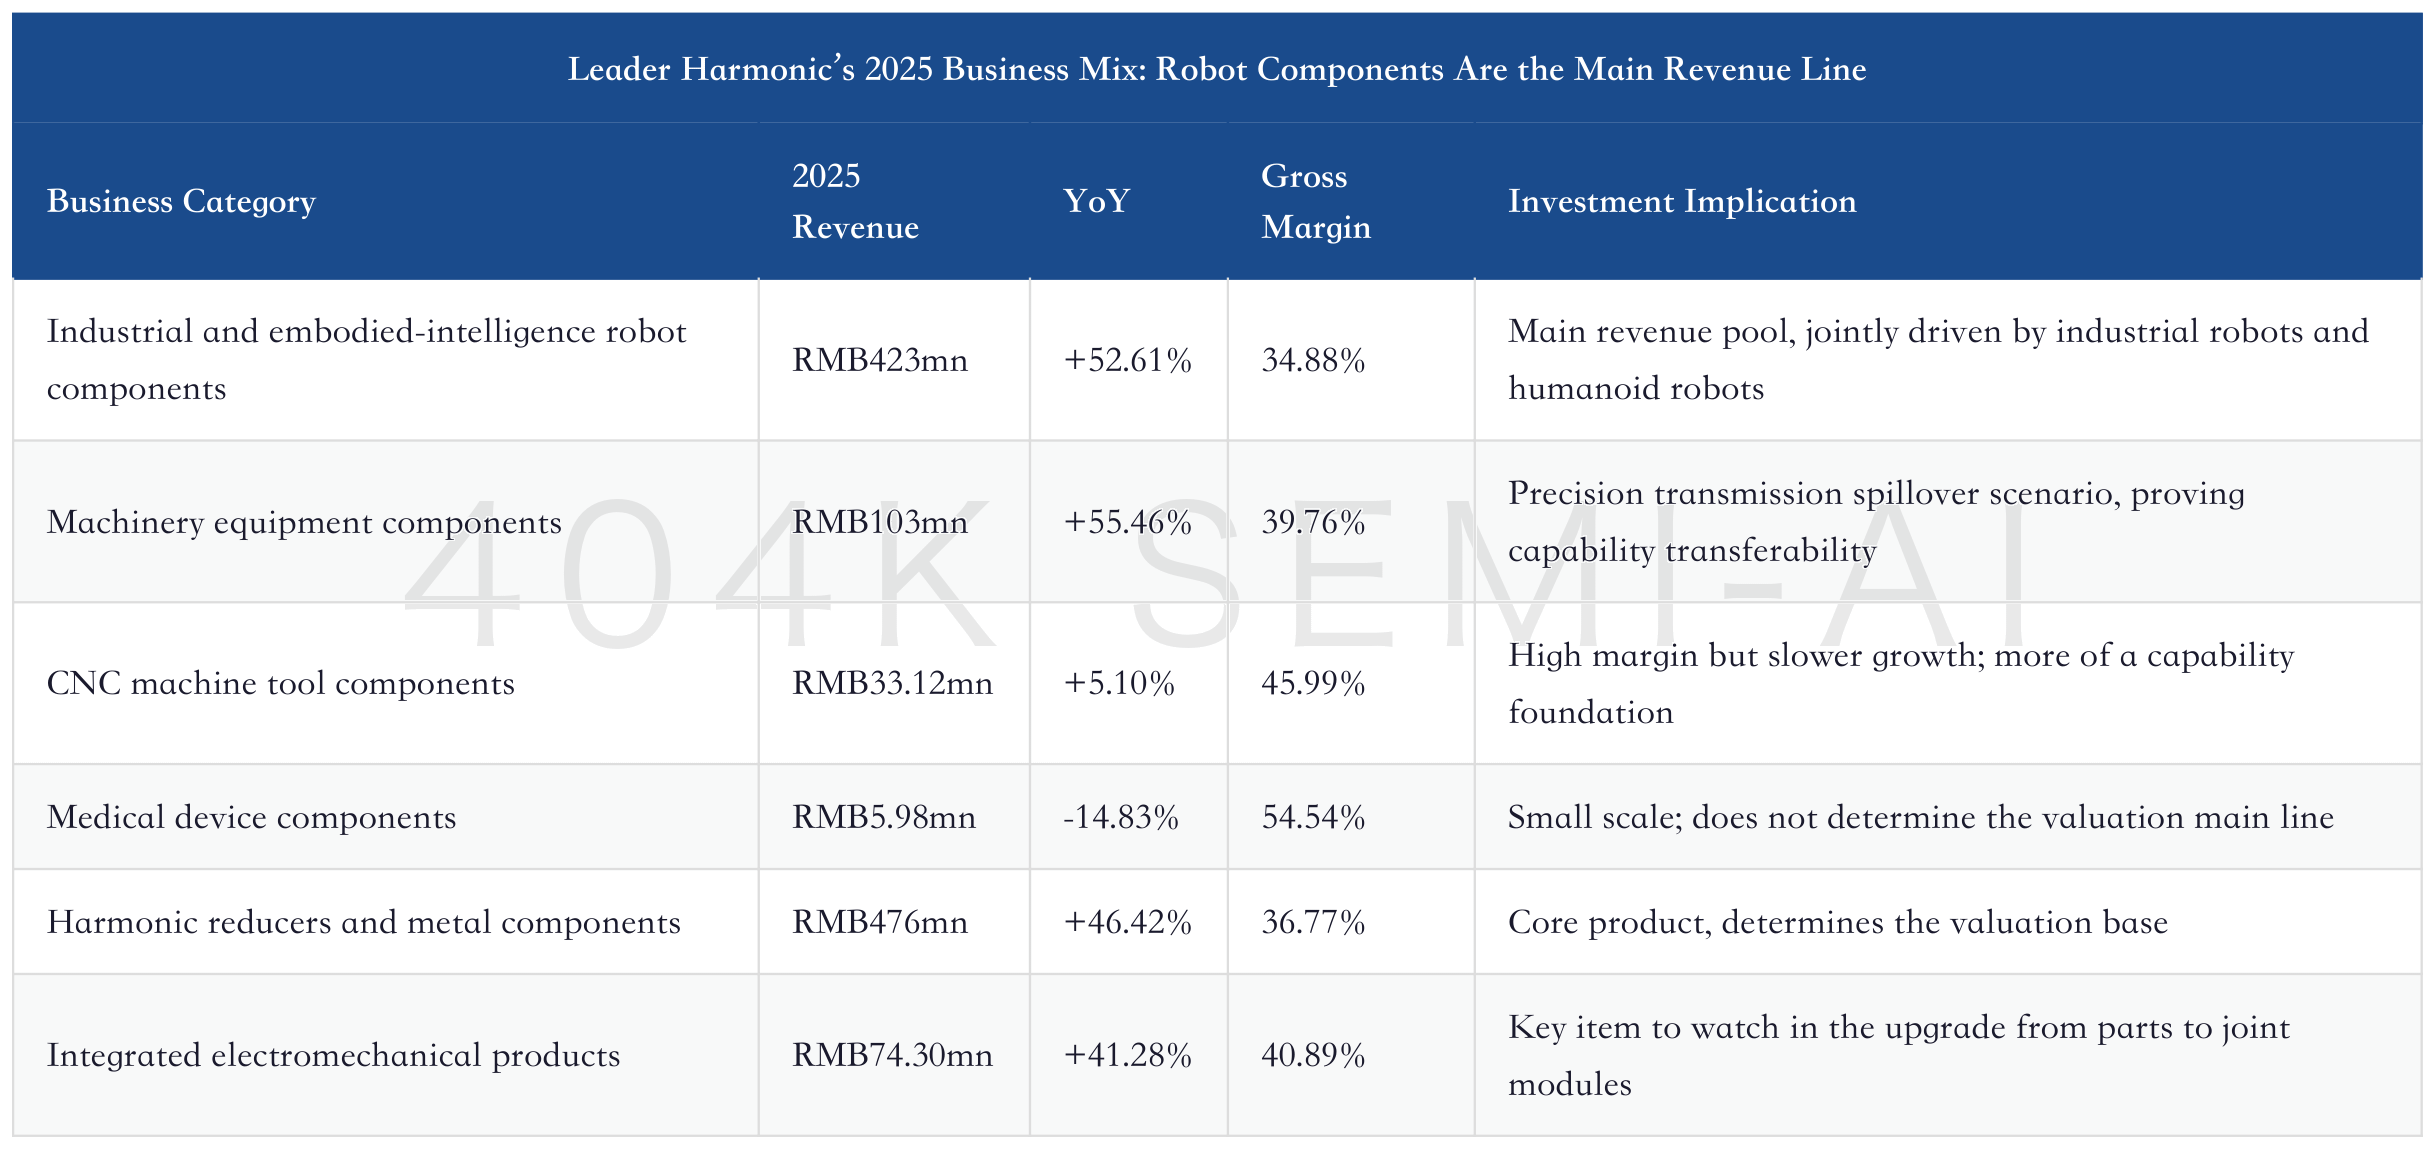
What truly requires attention is sales volume and inventory. In 2025, the company produced 433,655 harmonic reducers, up 72.27% YoY; sold 425,158 units, up 72.48% YoY; and held inventory of 18,238 units, down 6.34% YoY. Sales volume grew faster than revenue, meaning demand volume has already arrived, but pricing and product mix have not simply pushed up gross margin. Metal component sales reached 712,038 units, while integrated electromechanical product sales reached 12,178 sets, up 72.10% YoY. If humanoid robots ramp from here, sales volume, module mix, and ASP will together determine profit elasticity.
In other words, Leader Harmonic’s corporate profile is very clear: it is not a full-machine brand and does not rely on application scenarios to tell a story; it is not simply outsourced assembly and does not rely on short-term pricing arbitrage. Its core assets are precision transmission manufacturing capability, customer validation track record, batch delivery experience, and sustained cost-reduction capability. This asset has already been validated in the industrial robot era and may be repriced in the humanoid robot era. But repricing is not free: the market has already asked it to deliver higher shipments, larger share, and more stable gross margin.
II. Why It Is Being Repriced Now: From Industrial Robot Components to Humanoid Robot Joint Supplier
The first basis for Leaderdrive’s current re-rating is the recovery in the traditional industrial robot cycle. Downstream applications for industrial robots include autos, 3C, lithium batteries, photovoltaics, metalworking, semiconductor equipment, and other sectors. Over the past few years, volatility in manufacturing capex, price competition, and domestic substitution have acted together, allowing domestic harmonic reducer manufacturers to gain share while also bearing pressure from price declines. In 2024, the company’s revenue grew only 8.77%, while net profit attributable to shareholders was still declining, indicating that the industrial robot cycle alone is not enough to support a very high valuation.
Starting in 2025, the situation changed. The company’s annual report attributed revenue and profit growth to increased market share in industrial robots, growth in the embodied-intelligence robot business, and improved production efficiency. This wording is important because it is not only about industry recovery, but also about the simultaneous emergence of three variables: “share,” “new scenarios,” and “efficiency.” Recovery in industrial robot demand supports production-line utilization, embodied-intelligence orders provide incremental growth, and production-efficiency gains offset price pressure. Together, these three factors allow profit growth to significantly outpace revenue growth.
The 2026 first-quarter report continued to validate this point. Revenue, net profit attributable to shareholders, and EPS all maintained high growth. R&D; investment continued to increase but at a slower pace than revenue, indicating that scale effects are beginning to be released. Operating cash flow weakened temporarily, related to capacity expansion, inventory build, and supply-chain prepayments. This cannot be ignored. High-growth companies often show attractive income statements but pressured cash flow during capacity ramp-up periods, and Leaderdrive has also entered this stage.
The second basis is that China’s humanoid robot supply chain has begun to see genuine small-batch orders. Goldman Sachs’ July survey indicated that China’s humanoid robot shipments could exceed 50,000 units in 2026, with a base-case assumption of about 51,000 units. If subsidies and local demonstration projects similar to those in the early EV period emerge later, domestic humanoid robot shipments in 2027 could approach about 200,000 units, while Goldman Sachs’ base, bull, and blue-sky scenarios are 76,000, 148,000, and 220,000 units, respectively. This is a wide range, showing that the industry itself remains highly early-stage, but the direction has already shifted from “whether there are prototypes” to “who can secure sustainable orders.”
Leaderdrive is well positioned in this chain. Goldman Sachs’ survey shows that the company has about 80-90% share among domestic humanoid robots using harmonic reducers, up from about 70% the previous year. Citi’s June report also put the company’s domestic share in humanoid robot harmonic reducers at a high level of about 90%, and mentioned domestic customers such as AgiBot and UBTECH. JPMorgan’s March report emphasized from the perspective of orders and customers that the company’s contribution from humanoid robots has clearly increased, and that it has cooperative relationships with leading domestic OEMs.
The third basis is that capacity planning has moved from “shortage” to “quantifiable.” According to Goldman Sachs, the company’s capacity was about 600,000-700,000 units by the end of 2025. Monthly capacity was about 70,000 units in May 2026 and about 80,000 units in June, with a target of 120,000 units per month by the end of 2026, corresponding to annualized capacity of 1.44 million units. Citi’s June report similarly noted that management was more confident in 2026 revenue approaching RMB1 billion, with the core assumption also being capacity rising from about 50,000 units per month in 1Q26 to about 120,000 units per month by year-end, and at least 2 million units of annual capacity in 2027.
Capacity data cannot be assessed only by volume; the equipment cycle behind it also matters. Goldman Sachs noted that delivery lead times for high-end machine tools have extended to 12 months, indicating that precision transmission capacity expansion is not simply a matter of buying equipment, hiring workers, and opening lines. Harmonic reducers require machining, heat treatment, tooth profiles, flexsplines, circular splines, assembly, inspection, and life-cycle validation. Robot customers care especially about batch consistency and reliability. Ramping capacity too quickly can sacrifice yield, while ramping too slowly can miss the customer adoption window. Leaderdrive’s advantage is that it went through industrial robot volume validation earlier, but in the short term it still needs to balance speed and quality.
Another variable in capacity is capital-expenditure efficiency. Goldman Sachs’ survey indicates that the company’s capex per unit of capacity is trending down from about RMB1,000 toward below RMB500. This is important. If investment per unit of capacity declines, Leaderdrive can support higher shipments with less capital, and long-term free cash flow will be better than for asset-heavy companies that simply pile on equipment. Conversely, if expansion brings depreciation, labor, inventory, and yield pressure, gross margin will be diluted first, and valuation will revert to the logic of a manufacturing cyclical stock.
Leaderdrive’s operating inflection point: revenue and profit recovery has already occurred, while cash flow has entered the capacity-expansion validation period
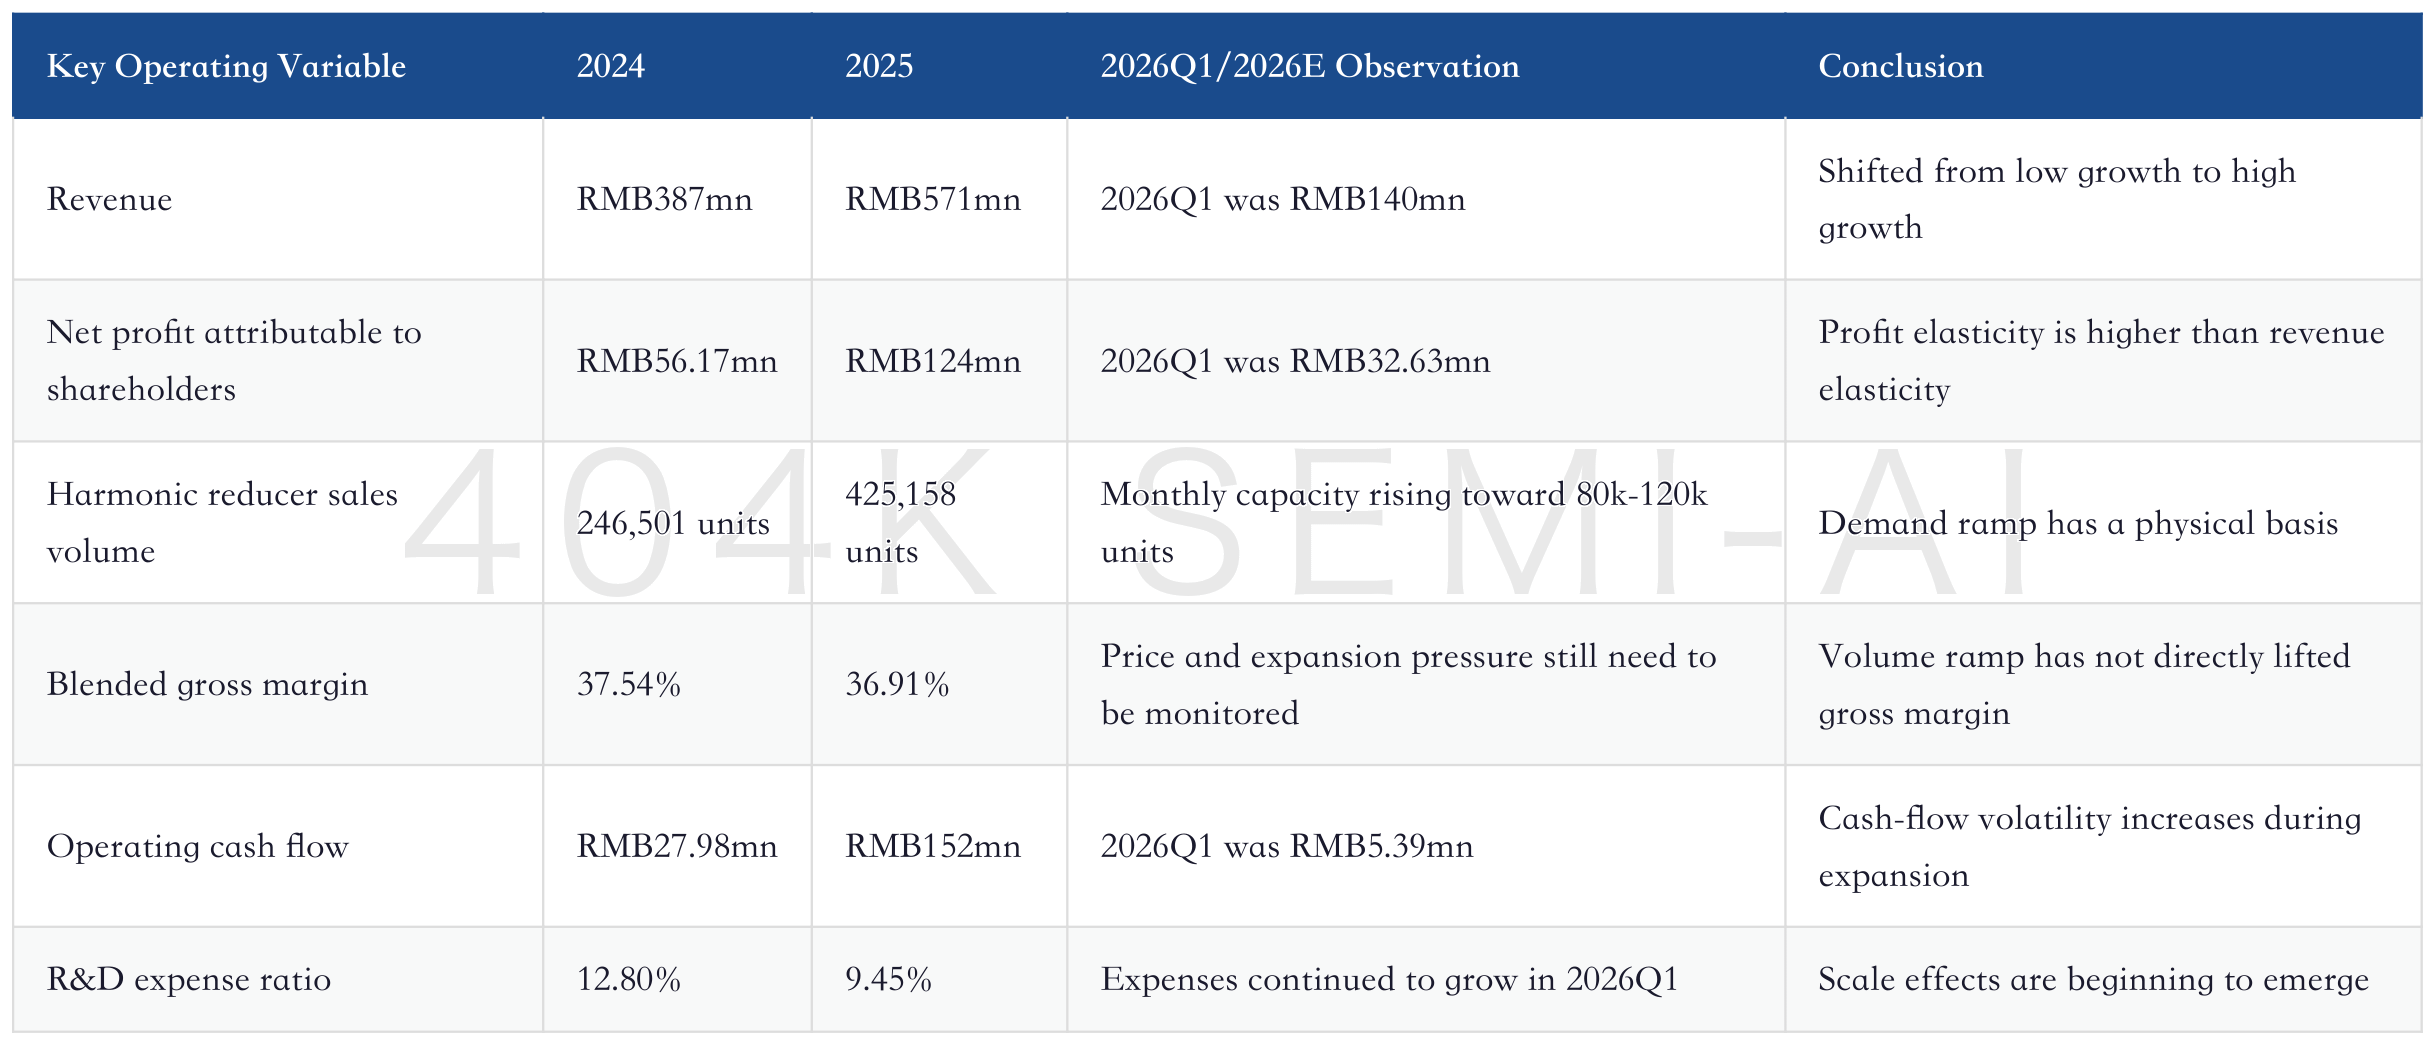
Therefore, Leaderdrive’s re-rating is not pure storytelling. Official data have already proven that revenue, profit, sales volume, and operating cash flow all improved in 2025; the first quarter also showed that high growth did not immediately disappear. The issue is that the current share price is no longer being priced on 2025 net profit of RMB124 million, but on humanoid robot shipments, the company’s share, capacity utilization, and product ASP over the next few years. If any one of these variables misses expectations, the valuation pullback could be rapid.
III. The Value of High Share: Customer Validation, Process Closed Loop, and Pricing Discipline
Leaderdrive’s greatest strength is that it has turned harmonic reducers from laboratory and small-batch engineering parts into industrial products capable of sustained shipment. The company’s annual report says it was among the earlier domestic companies to industrialize and scale up production of harmonic reducers, and emphasizes that its self-developed precision transmission devices broke the monopoly of international brands. More notably, the company has incorporated key links such as flexsplines, circular splines, and wave generators into its own process system, forming relatively strong vertical integration capabilities. Precision transmission is not just about buying materials and equipment; the core lies in the accumulation of machining, assembly, inspection, life-cycle validation, and customer operating-condition data.
Humanoid robots have similar requirements for harmonic reducers as industrial robots, but with less room for error. Industrial robots typically operate in fixed factory environments, with relatively clear loads, speeds, and operating conditions. Humanoid robots face walking, handling, falls, impact, dust, temperature and humidity changes, and unstructured scenarios. If one joint fails, the entire machine experience collapses. OEMs may try multiple suppliers in the early stage, but in true mass production they are more inclined to choose suppliers that have passed life-cycle testing, have stable supply, controllable yield, and are willing to co-develop cost reductions. Leaderdrive’s high share comes from this validation barrier.
The company’s customer structure is also changing. Among traditional industrial robot customers, Leaderdrive has already covered major domestic robot manufacturers and has begun entering some customers of the four major foreign robot makers. Goldman Sachs’ survey noted that the company is one of the main harmonic gear suppliers to the world’s four largest industrial robot manufacturers, with quality close to international brands and lower pricing; it has small-batch business with Yaskawa and ABB, and has been testing with FANUC for about 1.5 years, with plans to sell through Japanese channels in 2026. Foreign customer validation cycles are long, but once introduced, they imply a higher level of endorsement for product reliability.
On the humanoid robot side, domestic customers are more important. Domestic OEMs iterate quickly, have a strong willingness to localize supply chains, and prototypes and small-batch orders can provide faster feedback to upstream suppliers. Goldman Sachs, Citi, and JPMorgan all view leading domestic customers as the basis for Leaderdrive’s current share. Overseas customers have not yet reached the stage of definite large orders. Goldman Sachs clearly cautioned that major North American orders have not yet been concretely landed. Overseas customers are more focused on integrated rotary modules, meaning the combination of reducer, motor, force sensor, and encoder, with a cost target of about RMB2,000-3,000 per set, while reliability improvement and cost reduction are still needed.
This distinction is important. Domestic customers bring Leaderdrive near-term shipments, while overseas customers determine the valuation ceiling. If the company only maintains high share in domestic small-batch humanoid robots, revenue will grow, but it will be hard to support extremely high long-term multiples. If it enters global leading humanoid robot platforms, especially the main actuator chain of a major North American customer, the valuation anchor would be completely different. Current materials show that the overseas direction has testing, inquiries, and module demand, but not yet enough certainty to say that “large-scale mass-production orders have been secured.”
Pricing discipline is another key factor. Goldman Sachs’ survey shows that the company does not plan to raise prices significantly despite tight capacity in 2026. Management is more inclined to maintain a dominant position through stable pricing and reduce the entry returns for new entrants. This does not sound like short-term profit maximization, but it fits the long-term approach of an upstream core-component supplier. What the early-stage industry fears most is suppliers raising prices and preventing OEM costs from coming down, while also attracting multiple competitors through high gross margins. If Leaderdrive can actively reduce costs, stabilize prices, and bind customers, long-term share is more important than short-term gross margin.
But pricing discipline also means investors cannot linearly extrapolate margins. In 2025, the company’s blended gross margin was 36.91%, slightly lower than in 2024. The gross margin of harmonic reducers and metal components was 36.77%, higher than the overall 34.88% for robot components, but there was no sharp gross-margin increase due to demand shortages. The company’s annual report also cautioned that if product prices decline, raw-material prices rise, capacity release increases depreciation, labor costs increase, or product mix changes, gross margin may fluctuate or even decline. High growth and gross-margin pressure can exist at the same time.
Leaderdrive moat breakdown: customer validation and process closed loop support high share
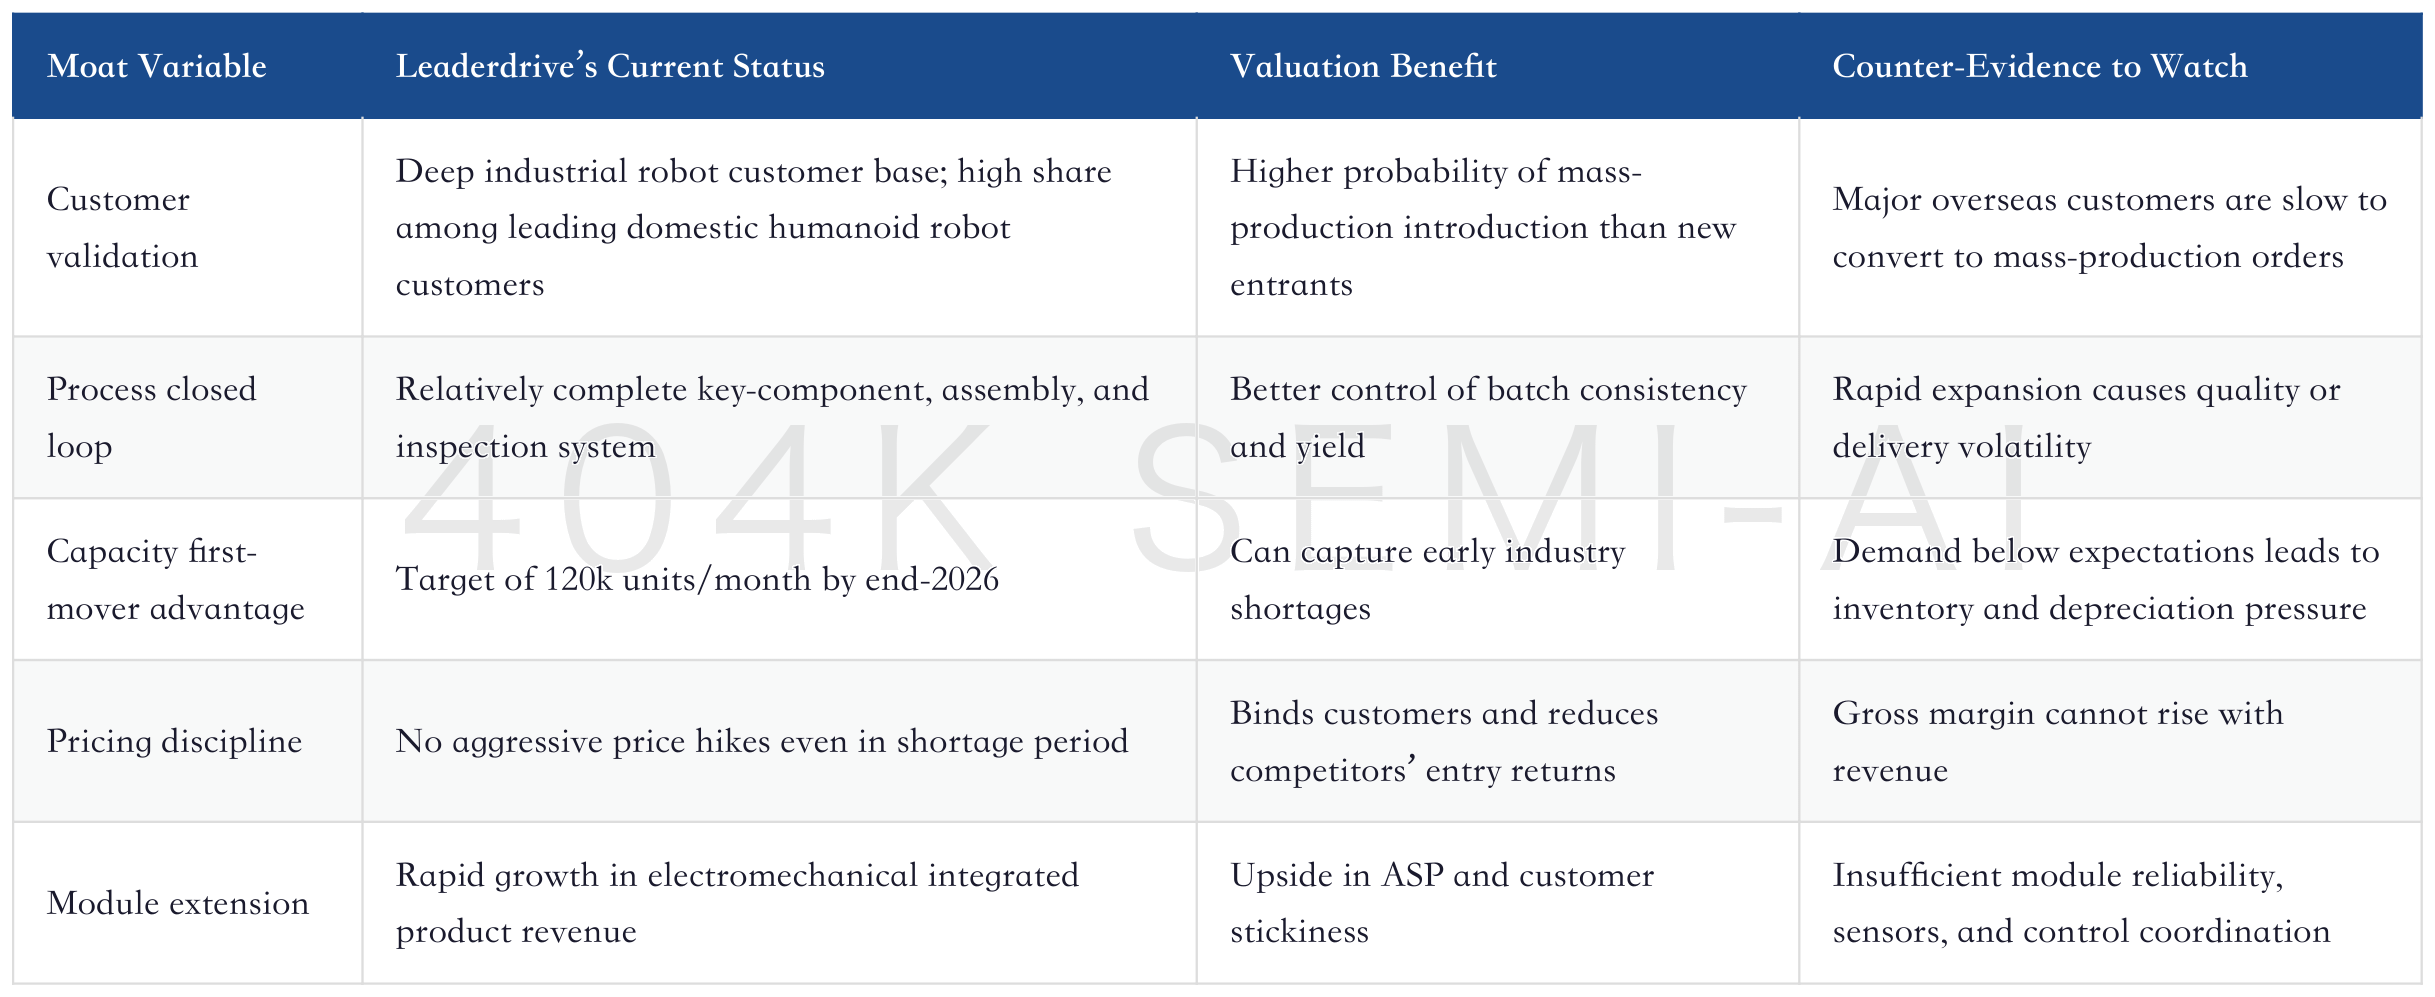
For a company like Leaderdrive, its strength and risk are essentially the same thing: the more it resembles the standard supplier for humanoid robot joints, the higher the valuation; but the more it enters standardized, scaled supply, the more prices need to decline, and the harder it becomes to maintain early-stage high gross margins. The truly positive outcome is not “capacity shortages bring price increases,” but “prices decline while unit costs fall faster, and both customer count and order volume expand.” That is the path from component manufacturer to platform-type precision transmission supplier.
IV. Capacity, ASP, and Gross Margin: Three Calculations Behind 1.44 Million Units of Annualized Capacity
For Leader Harmonious Drive’s short- to medium-term model, the first calculation is capacity. Harmonic reducer sales reached 425,200 units in 2025. The company targets monthly capacity of 120,000 units by end-2026; if the ramp proceeds smoothly, annualized capacity would reach 1.44 million units. That would be a clear step-change versus 2025 sales and would also map to potential domestic humanoid robot shipments in 2027. Assuming a high-DOF humanoid robot uses more than 10 harmonic reducers, 200,000 robots could correspond to demand for more than 2 million harmonic reducers. Adding demand from factory robots and collaborative robots, it would be difficult for any single supplier to fully cover the market.
The issue is that capacity is not revenue; utilization is revenue. If domestic humanoid robot shipments in 2026 are only around 50,000 units, incremental harmonic reducer demand would likely be in the hundreds of thousands of units. Leader Harmonious Drive would still benefit, but revenue elasticity would mainly come from recovery in industrial robots and collaborative robots. If shipments approach 150,000-200,000 units in 2027, driven by policy subsidies, demonstration projects, and major-customer orders, harmonic reducer demand would cross one million units, and Leader Harmonious Drive’s early capacity advantage would become a real revenue slope. If 2027 shipments fall below Goldman Sachs’ base case of 76,000 units, the current valuation would look too crowded.
The second calculation is ASP. Goldman Sachs’ valuation sensitivity sets a wide range of 2030 assumptions: from roughly RMB700 for a single harmonic gear to roughly RMB2,500 for an integrated actuator. This range itself shows that the market cannot value the company on “volume” alone. If Leader Harmonious Drive only sells individual harmonic reducers, ASP will be affected by cost reduction, domestic competition, and customer price pressure. If it can sell integrated rotary modules, unit value will be higher and customer stickiness stronger. But a module is not simply several components assembled together; it requires motors, encoders, force sensors, control algorithms, thermal management, and lifetime validation to all pass together.
Citi is more optimistic, partly because it views the company as shifting from a component supplier toward a humanoid robot joint-system supplier. J.P. Morgan also noted that mechatronic modules have higher ASPs in humanoid robots and collaborative robots, and that body harmonic reducers and smaller hand reducers sit in different price bands. The company’s mechatronics product revenue was RMB74.3 million in 2025, still small in scale, but gross margin was 40.89%, higher than harmonic reducers and metal components. If the revenue mix from modules increases later, revenue quality would improve beyond pure volume growth.
The third calculation is gross margin. In 2025, the company’s consolidated gross margin was 36.91%, robot-component gross margin was 34.88%, and mechatronics product gross margin was 40.89%. These figures show that the company is not a high-margin software or platform company; it remains, in essence, a precision-manufacturing company. Goldman Sachs assumes a 25% net margin in 2030, which is not an easy number. To achieve that level, the company would need to deliver scaled cost reduction, yield improvement, more automation, product-mix upgrade, and a lower expense ratio at the same time; relying only on price increases would not be sustainable.
Capacity expansion will also affect cash flow and the balance sheet. Goldman Sachs’ model shows a significant increase in 2026E capex, with free cash flow potentially turning negative for a period. The company’s decline in cash and increase in inventory in 1Q26 also reflect the cash absorption from expansion and inventory preparation. This is not necessarily bad; expansion and inventory buildup often consume cash. But it reminds investors that before humanoid robots scale, Leader Harmonious Drive first bears manufacturing capacity-expansion risk.
Leader Harmonious Drive model variables: shipments, value content, and gross margin jointly determine valuation elasticity
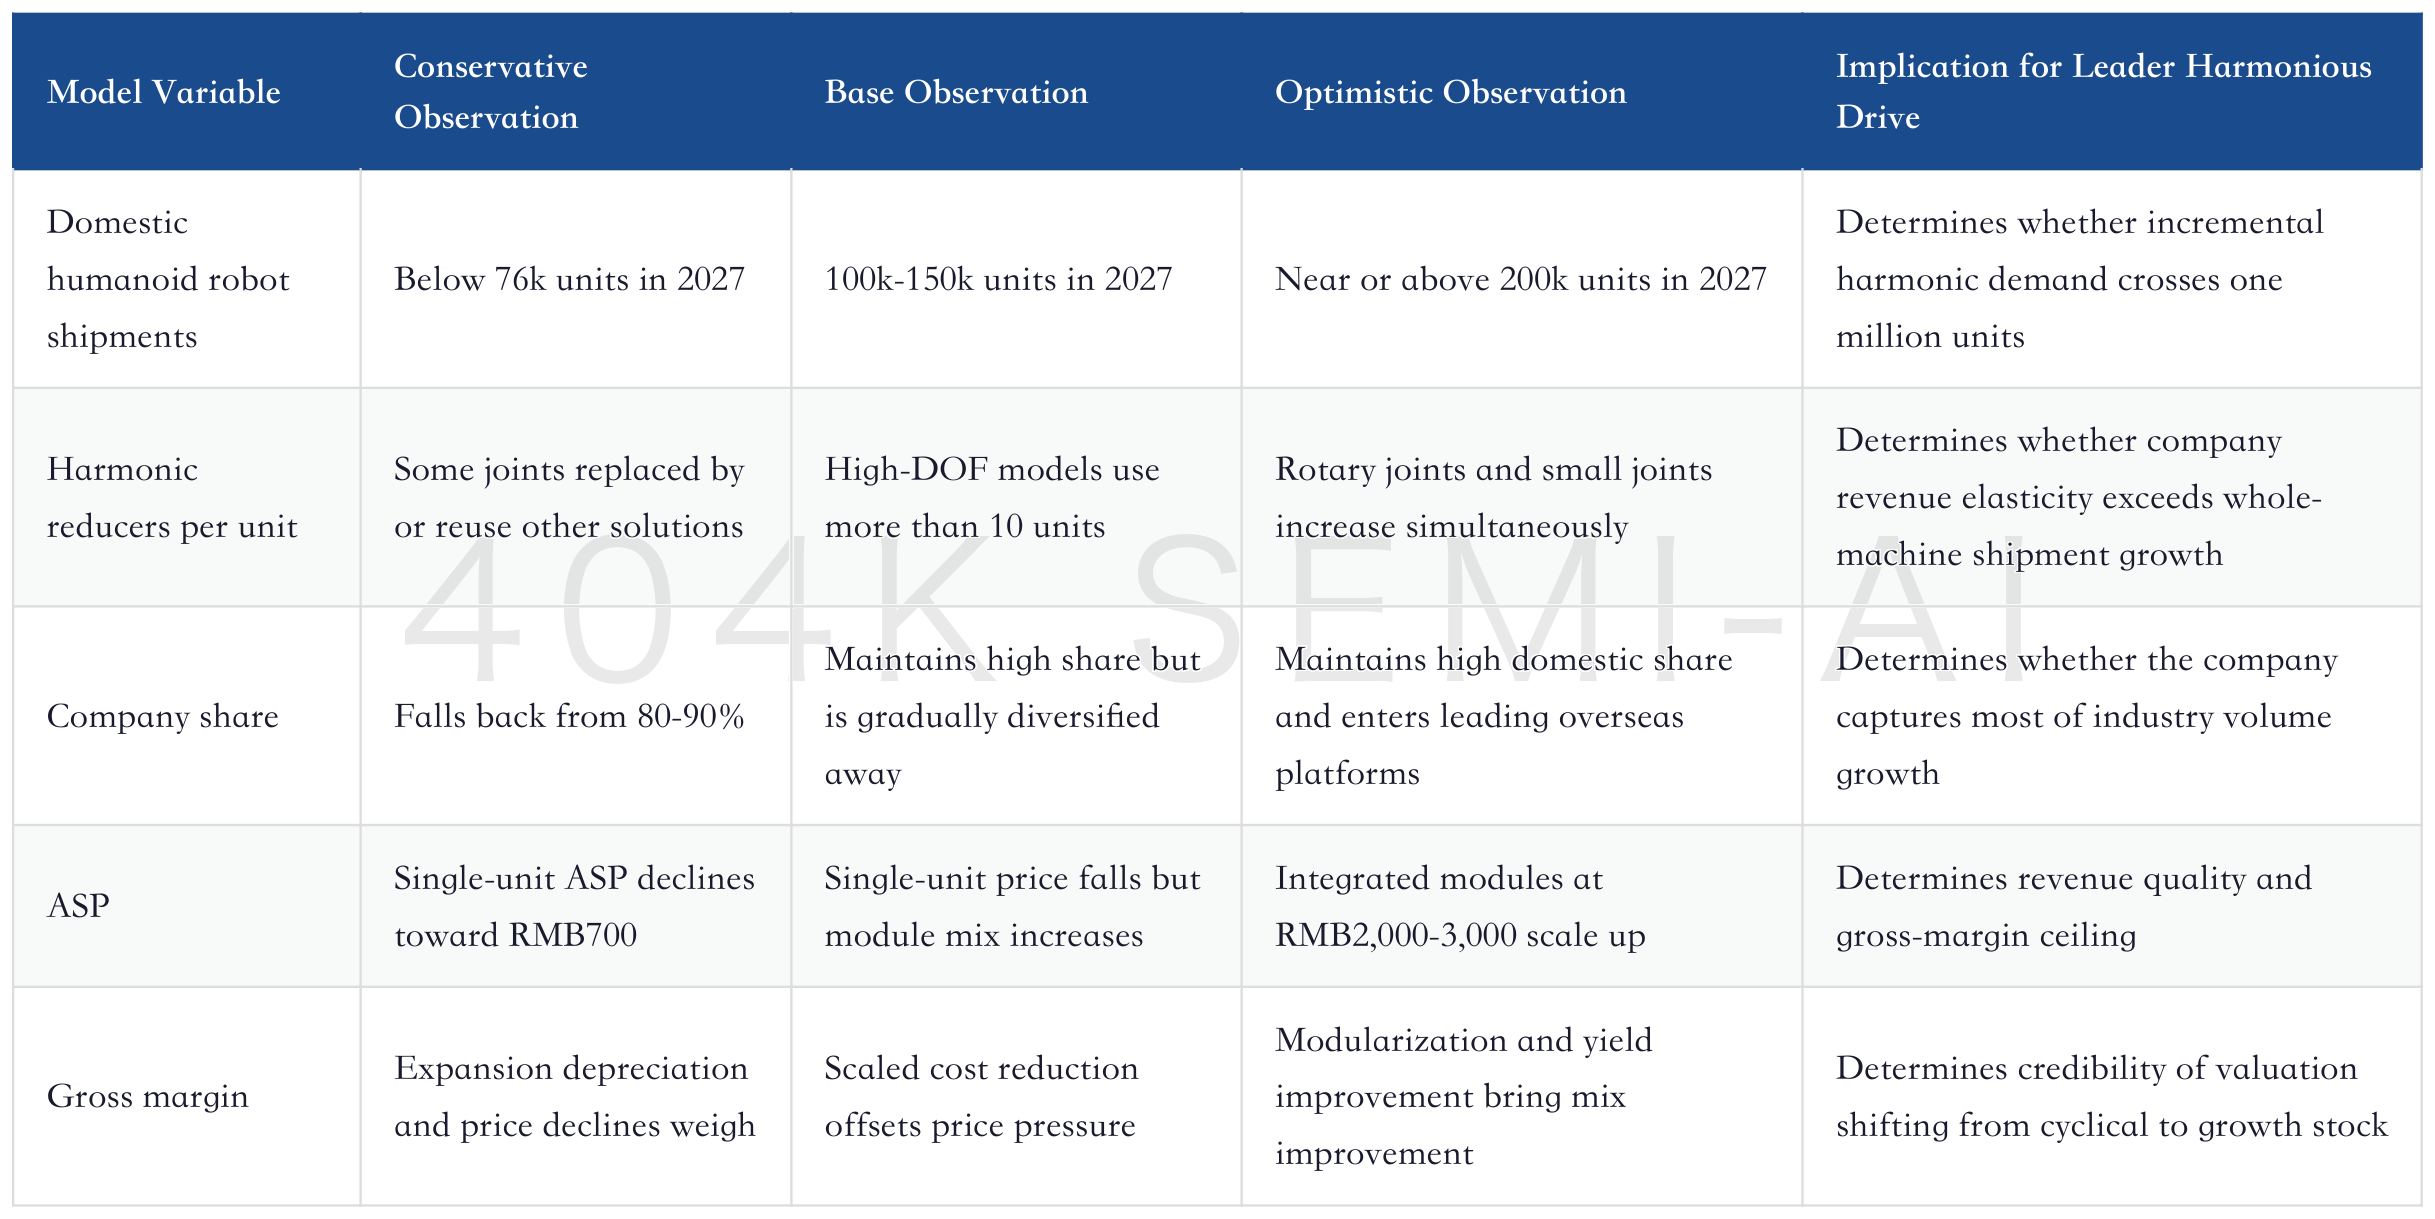
There is tension among capacity, ASP, and gross margin. The faster capacity expands, the greater the revenue elasticity, but depreciation, inventory, and management complexity also rise. The higher the ASP, the stronger the profit elasticity, but customers have more incentive to pressure pricing or develop in-house alternatives. The more stable the gross margin, the easier it is for valuation to rise, but sustaining gross margin requires long-term engineering capability. Leader Harmonious Drive does have opportunities, but it needs to deliver acceptable answers across all three calculations at the same time.
V. Sell-Side Divergence: What RMB138, RMB264, RMB269, and RMB496 Are Really Betting On
For the same company, sell-side target prices differ sharply. Goldman Sachs has a Neutral rating and RMB138 target price; J.P. Morgan set RMB264 in March; Morgan Stanley’s June base-case DCF was roughly RMB269; Citi raised its target price to RMB496 in June. The gap is not because analysts do not know how much the company earned in 2025. It reflects completely different probability weights on long-term robot volumes, company share, ASP, gross margin, and exit valuation multiples.
Goldman Sachs’ core point is “valuation sensitivity.” With the share price around RMB488 and market cap around RMB89.5 billion, Goldman Sachs believes the stock already discounts very high humanoid robot expectations. Under its model, 2026E and 2027E EPS are roughly RMB1.14 and RMB1.67, corresponding to 2026E/2027E P/E of 411x/276x. Even though Goldman Sachs’ own earnings forecasts are 9% and 11% above Wind consensus, they are still insufficient to support the current price. Goldman Sachs’ RMB138 target price is based on a 45x 2030E P/E, discounted back to 2027 using an 11.5% cost of equity.
Citi sits at the other end. Citi raised its target price to RMB496, citing stronger visibility in industrial robots and humanoid robots, management’s higher confidence in revenue approaching RMB1 billion in 2026, capacity ramping faster than previously expected, and clearer contribution from domestic humanoid robot customers. Its 2026E/2027E/2028E revenue forecasts are roughly RMB980 million/RMB1.439 billion/RMB1.931 billion, with net profit of roughly RMB192 million/RMB283 million/RMB387 million, and the target price is anchored to a very high 2027E P/E. Citi is not denying that valuation is expensive; it believes an early-stage humanoid robot theme can give a leader a very high forward multiple.
J.P. Morgan is in the moderately positive middle. Its March report raised the target price to RMB264, emphasizing better-than-expected 2025 results, full capacity utilization, recovery in industrial robot demand, and rising humanoid robot revenue contribution. J.P. Morgan puts more weight on the company already securing demand from leading domestic humanoid robot customers, and believes the company still has room to increase both domestic harmonic reducer share and global share. Its risk warnings are also clear: slowing industrial automation, intensifying competition, pricing pressure, and raw-material costs could weigh on gross margin.
Morgan Stanley is closer to a catalyst framework. Its June report did not fully bake in all optimistic assumptions at once, but put subsequent events in key positions: mass-production pace at leading overseas OEMs, domestic OEM listings and orders, exhibitions such as the World Robot Conference, real commercialization orders, and 2Q26 results disclosure. Its base-case DCF is roughly RMB269, with assumptions that, like Goldman Sachs, emphasize cash flow, discount rate, and terminal penetration. It also warns that the progress of leading U.S. humanoid robot players may periodically fall short of market expectations, and that 2027 is more critical than 2026.
Leader Harmonious Drive sell-side divergence: target-price gaps come from terminal robot volumes and module value content
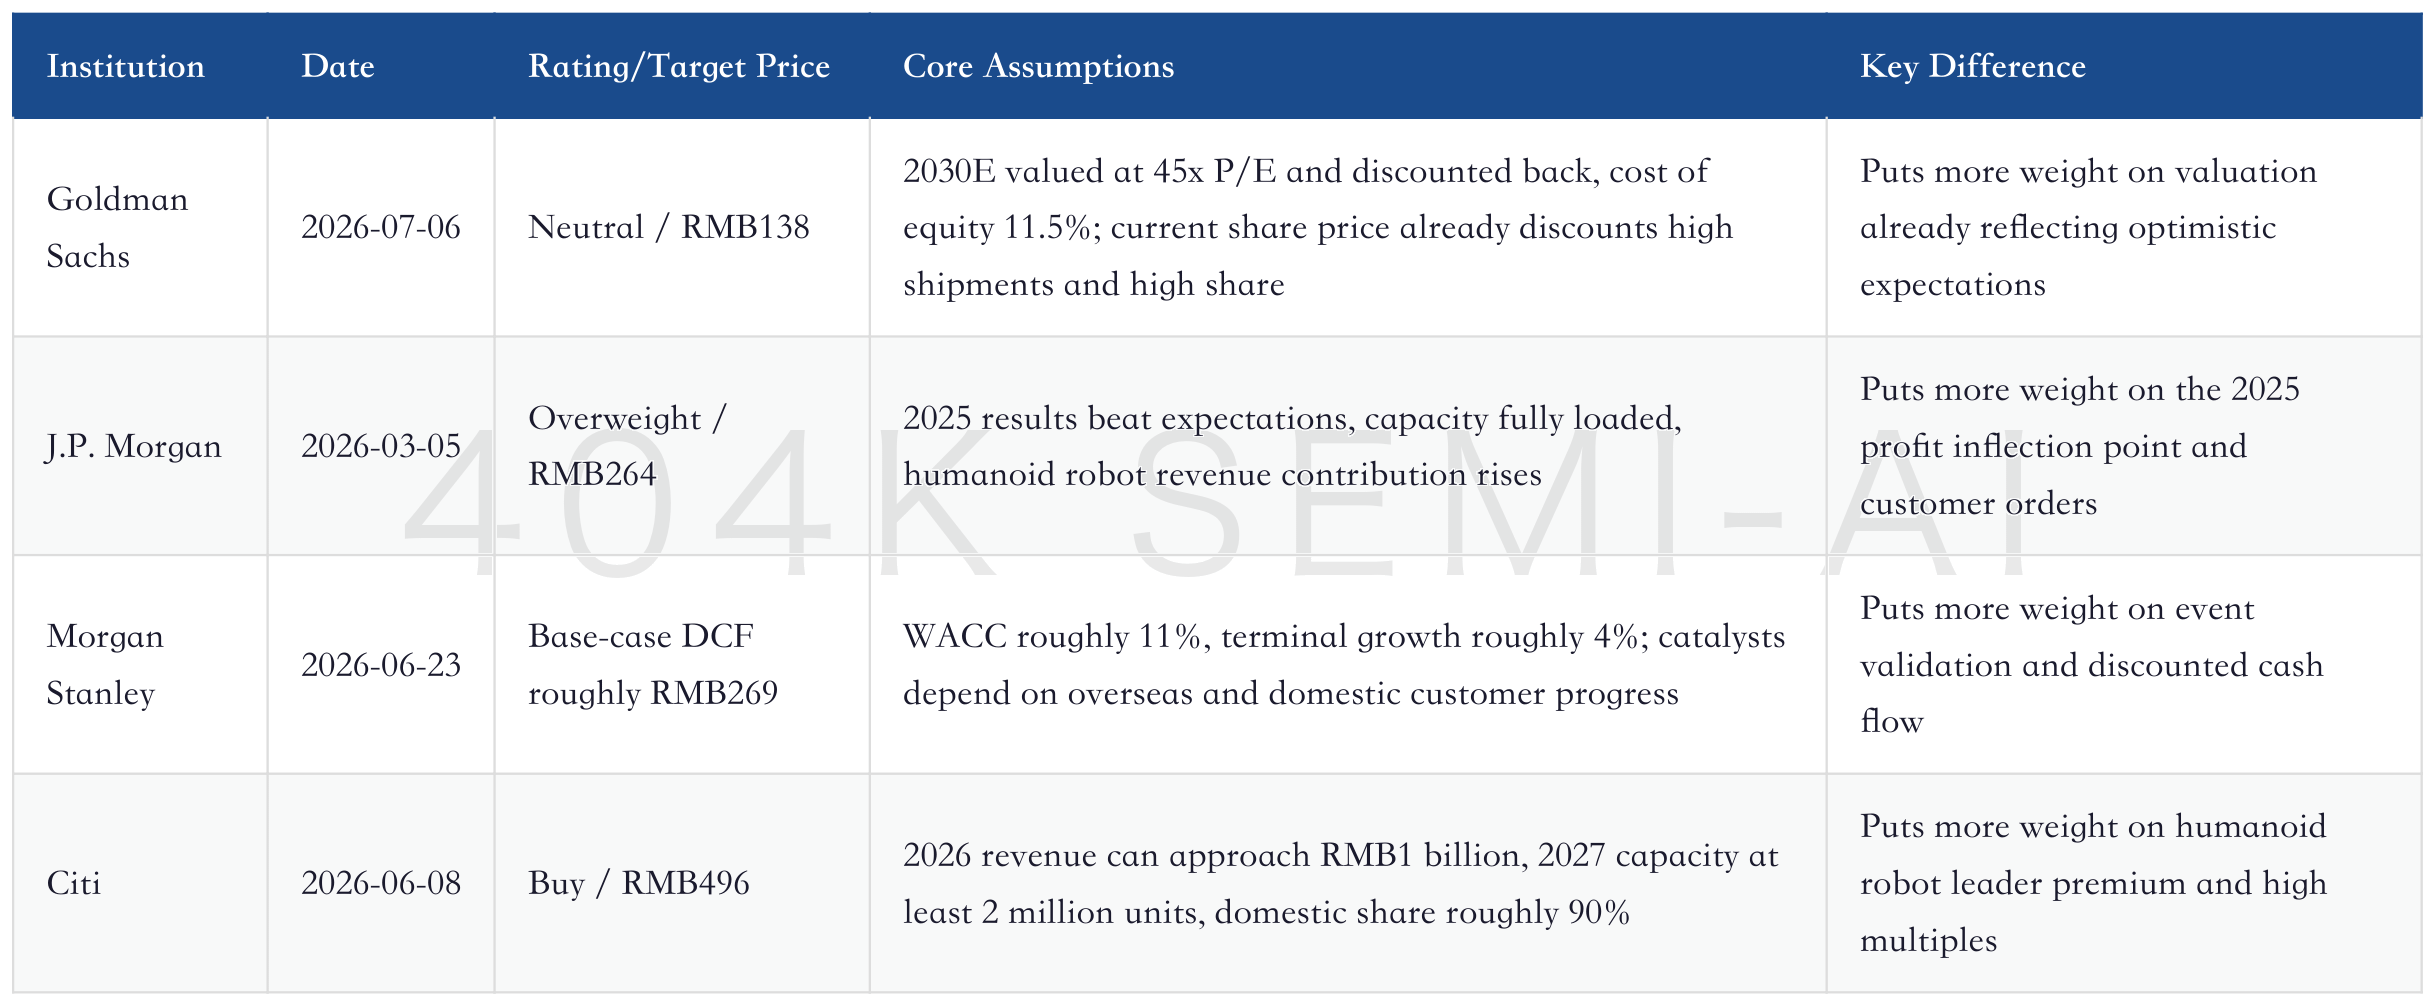
These differences can be compressed into one sentence: Goldman Sachs asks “how much future has the current share price already bought,” while Citi asks “if that future really arrives, can the leader become even more expensive.” J.P. Morgan and Morgan Stanley sit in the middle, emphasizing the earnings inflection point and catalyst validation, respectively. The real question for investors is not which target price is higher, but which worldview they believe.
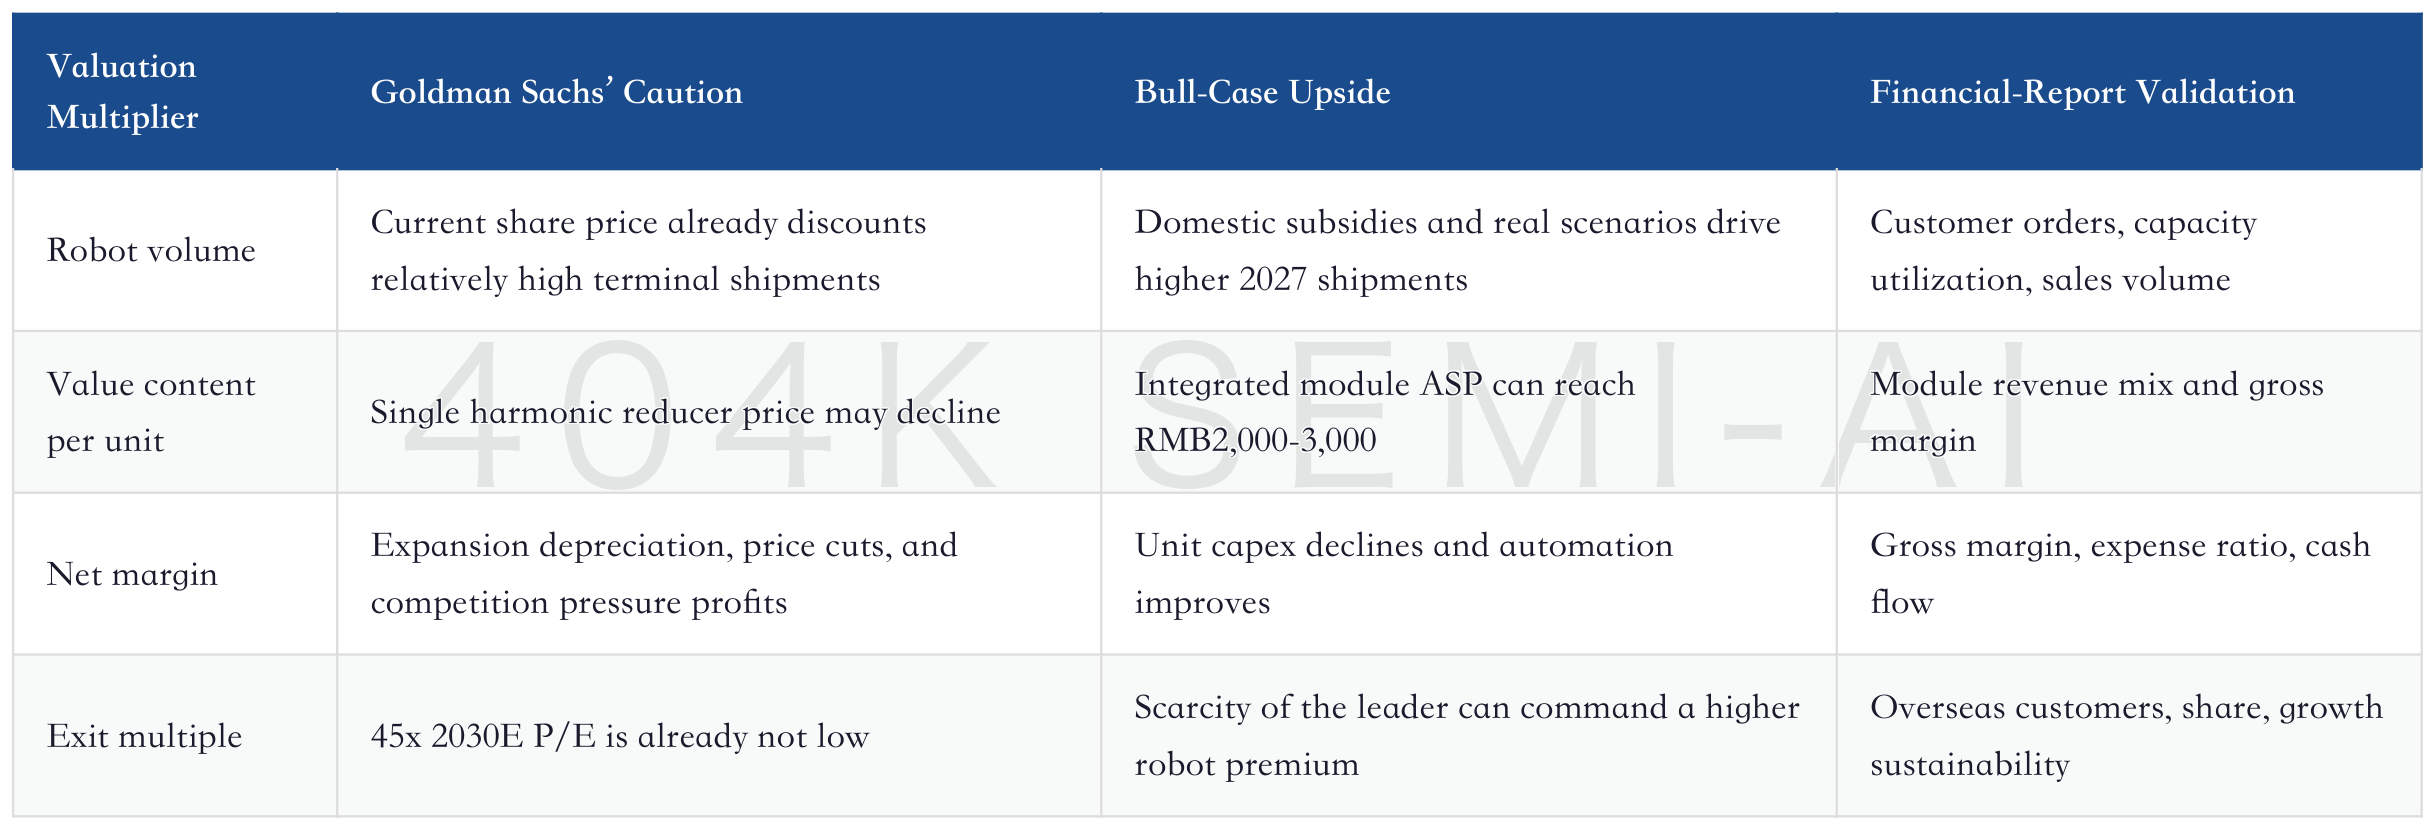
Valuation sensitivity can be broken into four multipliers. The first is robot volume: whether 2027 and 2030 mean hundreds of thousands, millions, or tens of millions of units. The second is value content per unit: how many harmonic reducers a humanoid robot uses, and whether Leader Harmonious Drive sells individual components or modules. The third is net margin: after price declines, depreciation, and yield ramp, whether the company can preserve a long-term net margin of around 25%. The fourth is the exit multiple: whether the market in 2030 will still be willing to assign 45x P/E or even higher to core robot components. If any one multiplier is revised down, the target price will move materially lower.
This is why Goldman Sachs’ target price looks low, but its logic is not contradictory. Goldman Sachs is not denying the company’s share in domestic humanoid robots, nor is it denying the capacity ramp. It is warning that the current price has already placed several multipliers at high levels simultaneously. Citi’s RMB496 target price, by contrast, assigns higher probabilities to these multipliers, especially domestic customer orders, capacity expansion, and the sustainability of high multiples. The gap between the two target prices is not mainly about tens of millions of renminbi of 2026 revenue, but whether the company can upgrade from “selling harmonic gears” to “selling robot joint modules” before 2030.
Leader Harmonious Drive valuation multipliers: any downward revision to a variable amplifies target-price divergence
The first worldview is recovery as an industrial robot leader. Leader Harmonious Drive is the domestic harmonic reducer leader. As the industrial robot cycle recovers, domestic share rises, and utilization improves, revenue and profit maintain high growth, but humanoid robots remain only an option for now. In this worldview, the company should trade above traditional machinery components, but it is hard to sustain a P/E in the hundreds over the long term.
The second worldview is a domestic humanoid robot joint bottleneck. Domestic OEMs move into small-batch production and demonstration projects, Leader Harmonious Drive maintains 80-90% high share, most of its 2026-2027 capacity is absorbed, harmonic reducer sales continue to grow at roughly a doubling pace, and the mechatronics module mix increases. In this worldview, the company is not an ordinary cyclical stock, but the scarcest rotary-joint asset in the domestic humanoid robot supply chain. Valuation can remain high, but it requires continuous validation through financial results.
The third worldview is becoming a leading global humanoid robot supplier. The company not only maintains domestic share, but also enters leading overseas platforms. Module ASP is materially higher than individual reducers, and long-term shipments are modeled against robot penetration in the millions or even tens of millions of units. In this worldview, the current share price may not be excessive and may even have further upside. But this is the most demanding worldview: it requires overseas orders, reliability, cost, customer qualification, and supply-chain compliance to all pass simultaneously.
Leader Harmonious Drive’s current issue is that market pricing already partly sits between the second and third worldviews, while the company’s financials have only proven the early stage from the first to the second. 2025 and 1Q26 proved that revenue, profit, and sales volume are all accelerating. Goldman Sachs and Citi proved that capacity and share have strong elasticity. But major overseas customers, large-scale module revenue, stable gross margin, and cash-flow improvement have not all been realized at the same time. This mismatch is the source of valuation sensitivity.
VI. My Scenario Framework: First Acknowledge a Good Company, Then Ask Whether the Price Is Good
The core investment judgment on Leader Harmonious Drive can be split into two layers. At the company level, it is indeed among the scarcest assets in China’s precision transmission segment for robotics. In humanoid-robot rotary joints in particular, its current share, customers, capacity, and process know-how are clearer than most peers. At the stock level, it is not cheap. It may already be discounting a fairly optimistic humanoid-robot penetration rate beyond 2027. A good company and a good price are not the same thing.
In the conservative scenario, Leader Harmonious Drive can still grow, but valuation needs to return to cash flow and the industrial-robot cycle. Domestic humanoid-robot shipments reach about 50,000 units in 2026 and only approach Goldman Sachs’ base-case 76,000 units in 2027; the company’s share falls from 80-90% to about 70%; harmonic-drive ASP per unit gradually declines, mechatronic integrated modules ramp slowly; industrial robots recover, but competition intensifies. In this scenario, the company’s 2026-2028 revenue can still grow, but the market would shift from valuing it as a “million-unit robot option” back to a “precision machinery growth stock,” with the target price closer to Goldman Sachs’ conservative framework.
In the base scenario, humanoid robots enter genuine small-batch capacity expansion. Domestic shipments reach the 100,000-150,000-unit range in 2027, with local subsidies and industry demonstration projects driving continued orders from leading customers; Leader Harmonious Drive maintains a relatively high share, its 120,000 units/month capacity at end-2026 gradually fills up, and 2027 capacity expands to more than 2 million units; the revenue contribution from mechatronic integrated modules rises, but pricing also declines in line with customers’ cost-reduction schedules. In this scenario, revenue and profit could be meaningfully above what the traditional industrial-robot cycle would imply, and valuation can sustain a high-growth premium, but cash flow and gross margin should not be ignored.
In the optimistic scenario, both domestic and overseas markets open up. Domestic humanoid-robot shipments approach or exceed 200,000 units, driven by policy, factory scenarios, and service scenarios, while leading overseas OEMs begin clear mass-production procurement. The company upgrades from a supplier of individual harmonic reducers to a supplier of integrated rotary modules. Value per set is no longer just around RMB700 for a gear, but moves toward RMB2,000-3,000 for a module. In this scenario, Leader Harmonious Drive has the opportunity to move from being a core components leader in China’s industrial-robot market to becoming a key supplier in the global humanoid-robot joint supply chain, giving Citi-style high target prices stronger support.
Leader Harmonious Drive Scenario Framework: The Gap Between Base and Optimistic Depends on Order Validation
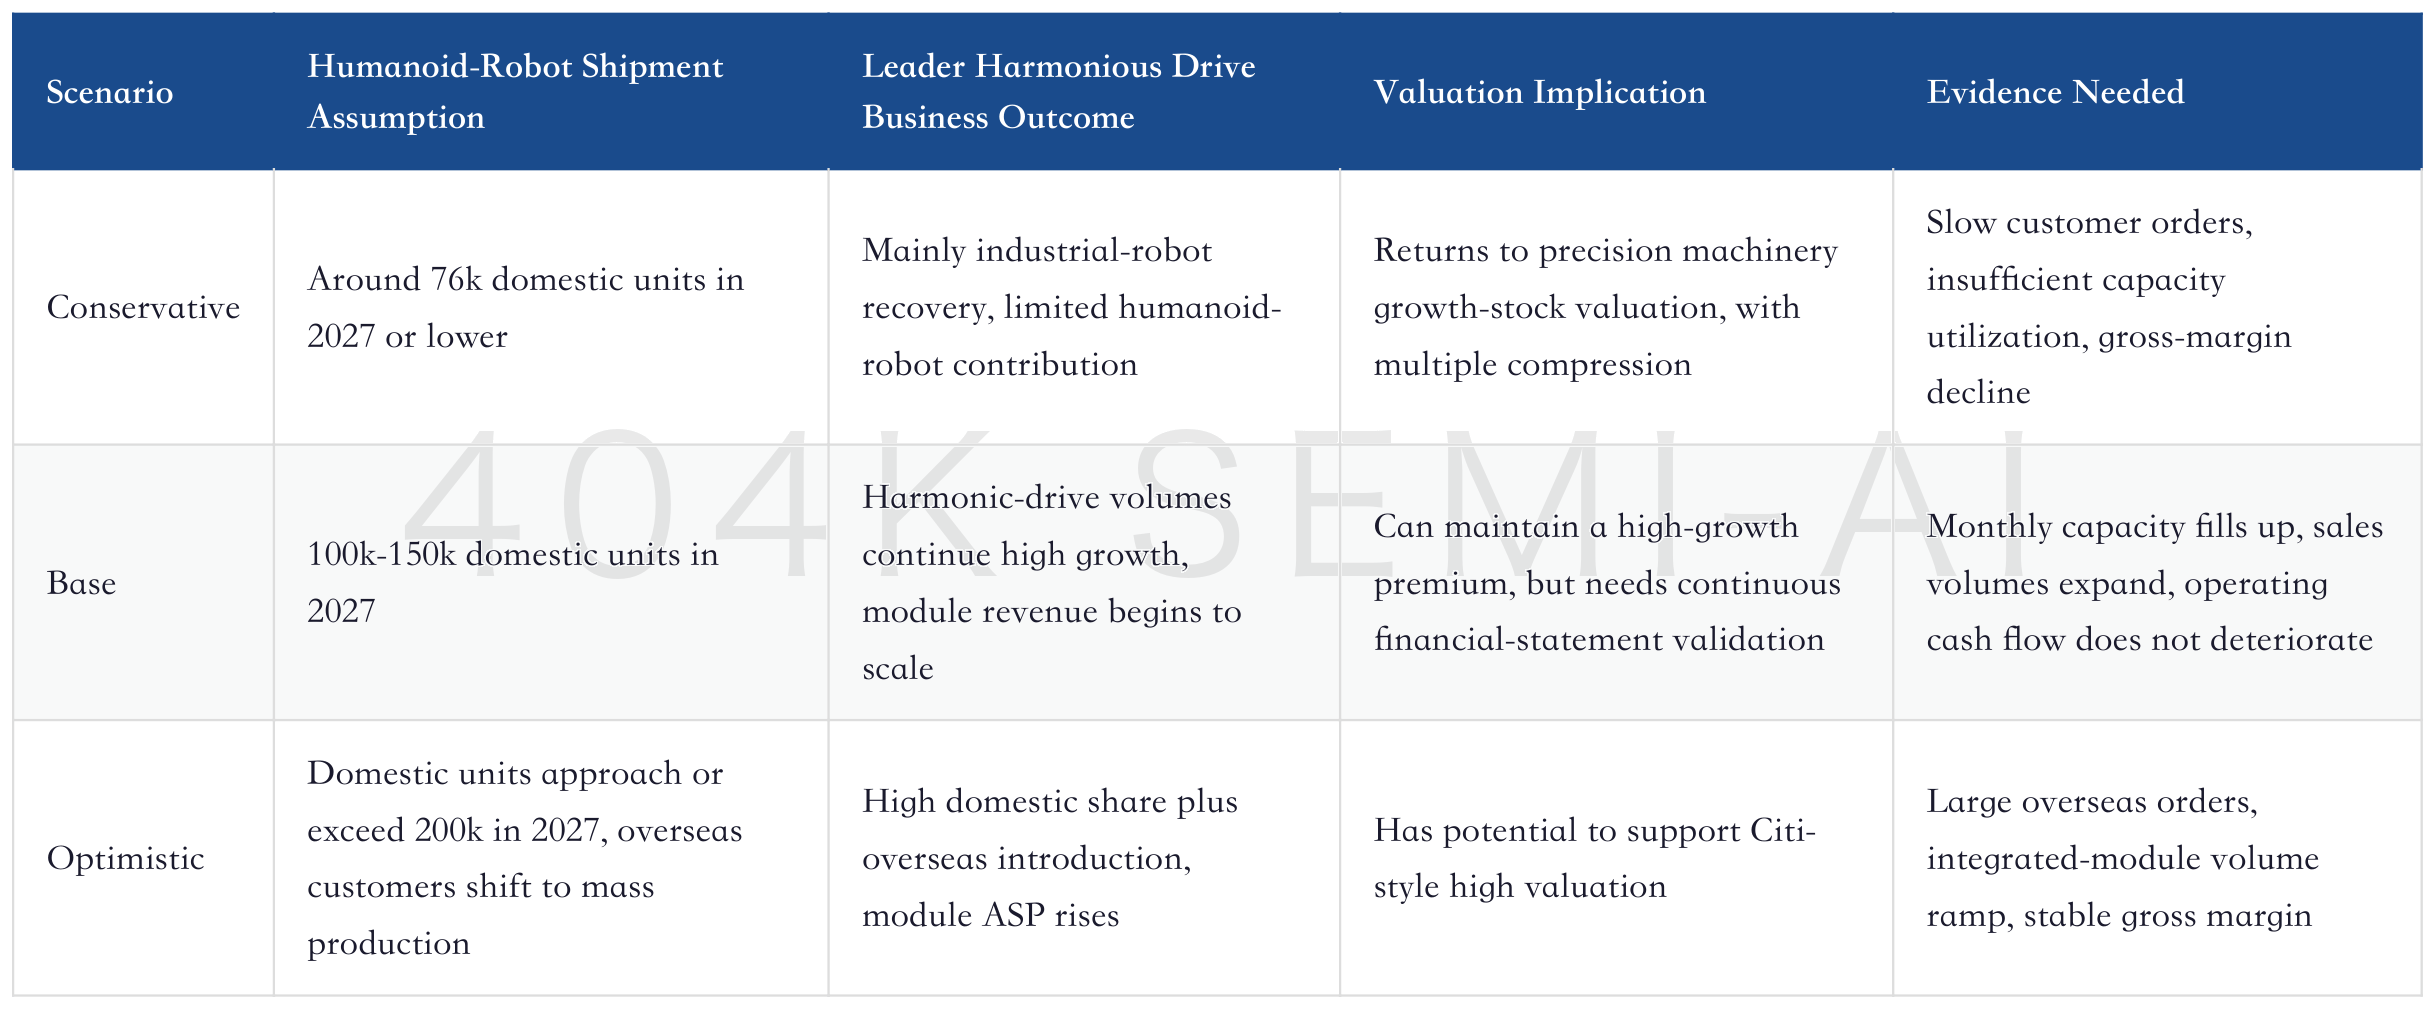
I am more inclined to observe Leader Harmonious Drive somewhere between the base and optimistic scenarios, rather than immediately taking the most optimistic view. There are three reasons. First, the company is indeed ahead in share and capacity for humanoid-robot rotary joints, so it should not be valued like an ordinary machinery stock. Second, the 2025 and 2026Q1 financials have already shown that demand is not a castle in the air; volumes and profit are both improving. Third, the current market cap already requires the company to deliver very strong orders and profit realization around 2027. If overseas customers or domestic subsidies fall short of expectations, valuation will fall first and then wait for fundamentals to catch up.
This judgment may look conservative, but it is more useful for investing. The truly attractive time to buy Leader Harmonious Drive may not be when the news flow is hottest, but when financial statements confirm monthly capacity ramp-up, volume expansion, a rising module-revenue contribution, no collapse in gross margin, and operating cash flow that can still absorb capacity expansion. Conversely, if the stock is already trading on the optimistic scenario while the financials only deliver the base or even conservative scenario, a short-term drawdown does not require fundamentals to worsen. It only requires expectations to move from “extremely optimistic” back to “optimistic.”
VII. Company and Peer Ranking: Leader Harmonious Drive Is Strong in Rotary Joints, Not the Entire Robotics Chain
The humanoid-robot supply chain is easily turned into one large table, but real investing requires separating the links. Leader Harmonious Drive is strong in harmonic reducers and rotary joints. That does not mean it is strong in all actuators, nor does it necessarily capture the largest profit pool in the complete robot. Linear actuators, ball screws, dexterous hands, sensors, motors, controllers, and complete systems all have different players. The company’s greatest value lies in having established share and delivery capability in rotary joints, where batch reliability is needed earliest.
Compared with Hengli Hydraulic, Leader Harmonious Drive is more focused on rotary joints, while Hengli Hydraulic attracts more discussion in humanoid-robot linear actuators and ball-screw-related segments. Morgan Stanley has emphasized in the humanoid-robot supply chain that Hengli Hydraulic has strong share in linear-actuator-related products for leading overseas customers and has a Mexico capacity footprint. The two companies are not simple substitutes. They represent two paths: rotary joints and linear actuators. If rotary joints account for a higher share of future humanoid-robot leg, waist, and arm designs, Leader Harmonious Drive benefits more. If linear actuators gain more advantage in core load-bearing joints, Hengli Hydraulic has greater upside.
Compared with Shuanghuan Driveline, Leader Harmonious Drive benefits more directly from harmonic reducers, while Shuanghuan Driveline is strong in gears and precision transmission processing and also participates in new reducer directions. Shuanghuan Driveline’s advantage is broad transferability of manufacturing capabilities and stronger precision-gear experience that can be reused across autos and robotics. Leader Harmonious Drive’s advantage is that its products are more directly embedded in robot rotary joints, making revenue mapping clearer. The difference is that Leader Harmonious Drive has higher “purity,” while Shuanghuan Driveline has more of a “manufacturing platform” attribute.
Compared with actuator-chain companies such as Sanhua Intelligent Controls and Tuopu Group, Leader Harmonious Drive is more like a core components supplier than a multi-component system integrator. Sanhua Intelligent Controls and Tuopu Group are strong in the automotive supply chain, actuator assemblies, thermal management, or manufacturing platforms. They may unlock new growth through humanoid robots in the future, but their profit mapping will also be affected by the auto business. Leader Harmonious Drive’s advantage is a more concentrated main line; its disadvantage is that valuation is more easily affected by ASP and share volatility in a single product.
Compared with domestic reducer or actuator-related companies such as Zhongda Leader and Fengli Intelligent, Leader Harmonious Drive is ahead in scale, customer validation, and capacity expansion, but its valuation is also fuller. Smaller companies may have greater upside, but they need to prove product reliability, customer introduction, and mass-production capability. Leader Harmonious Drive has already proven part of this first, and the market has also priced it highly in advance. This ranking is not simply about who is better, but about who is in which link, at what valuation, and under what validation pressure.
Robot Joint Supply Chain Ranking: Leader Harmonious Drive Is Strong in Rotary-Joint Purity
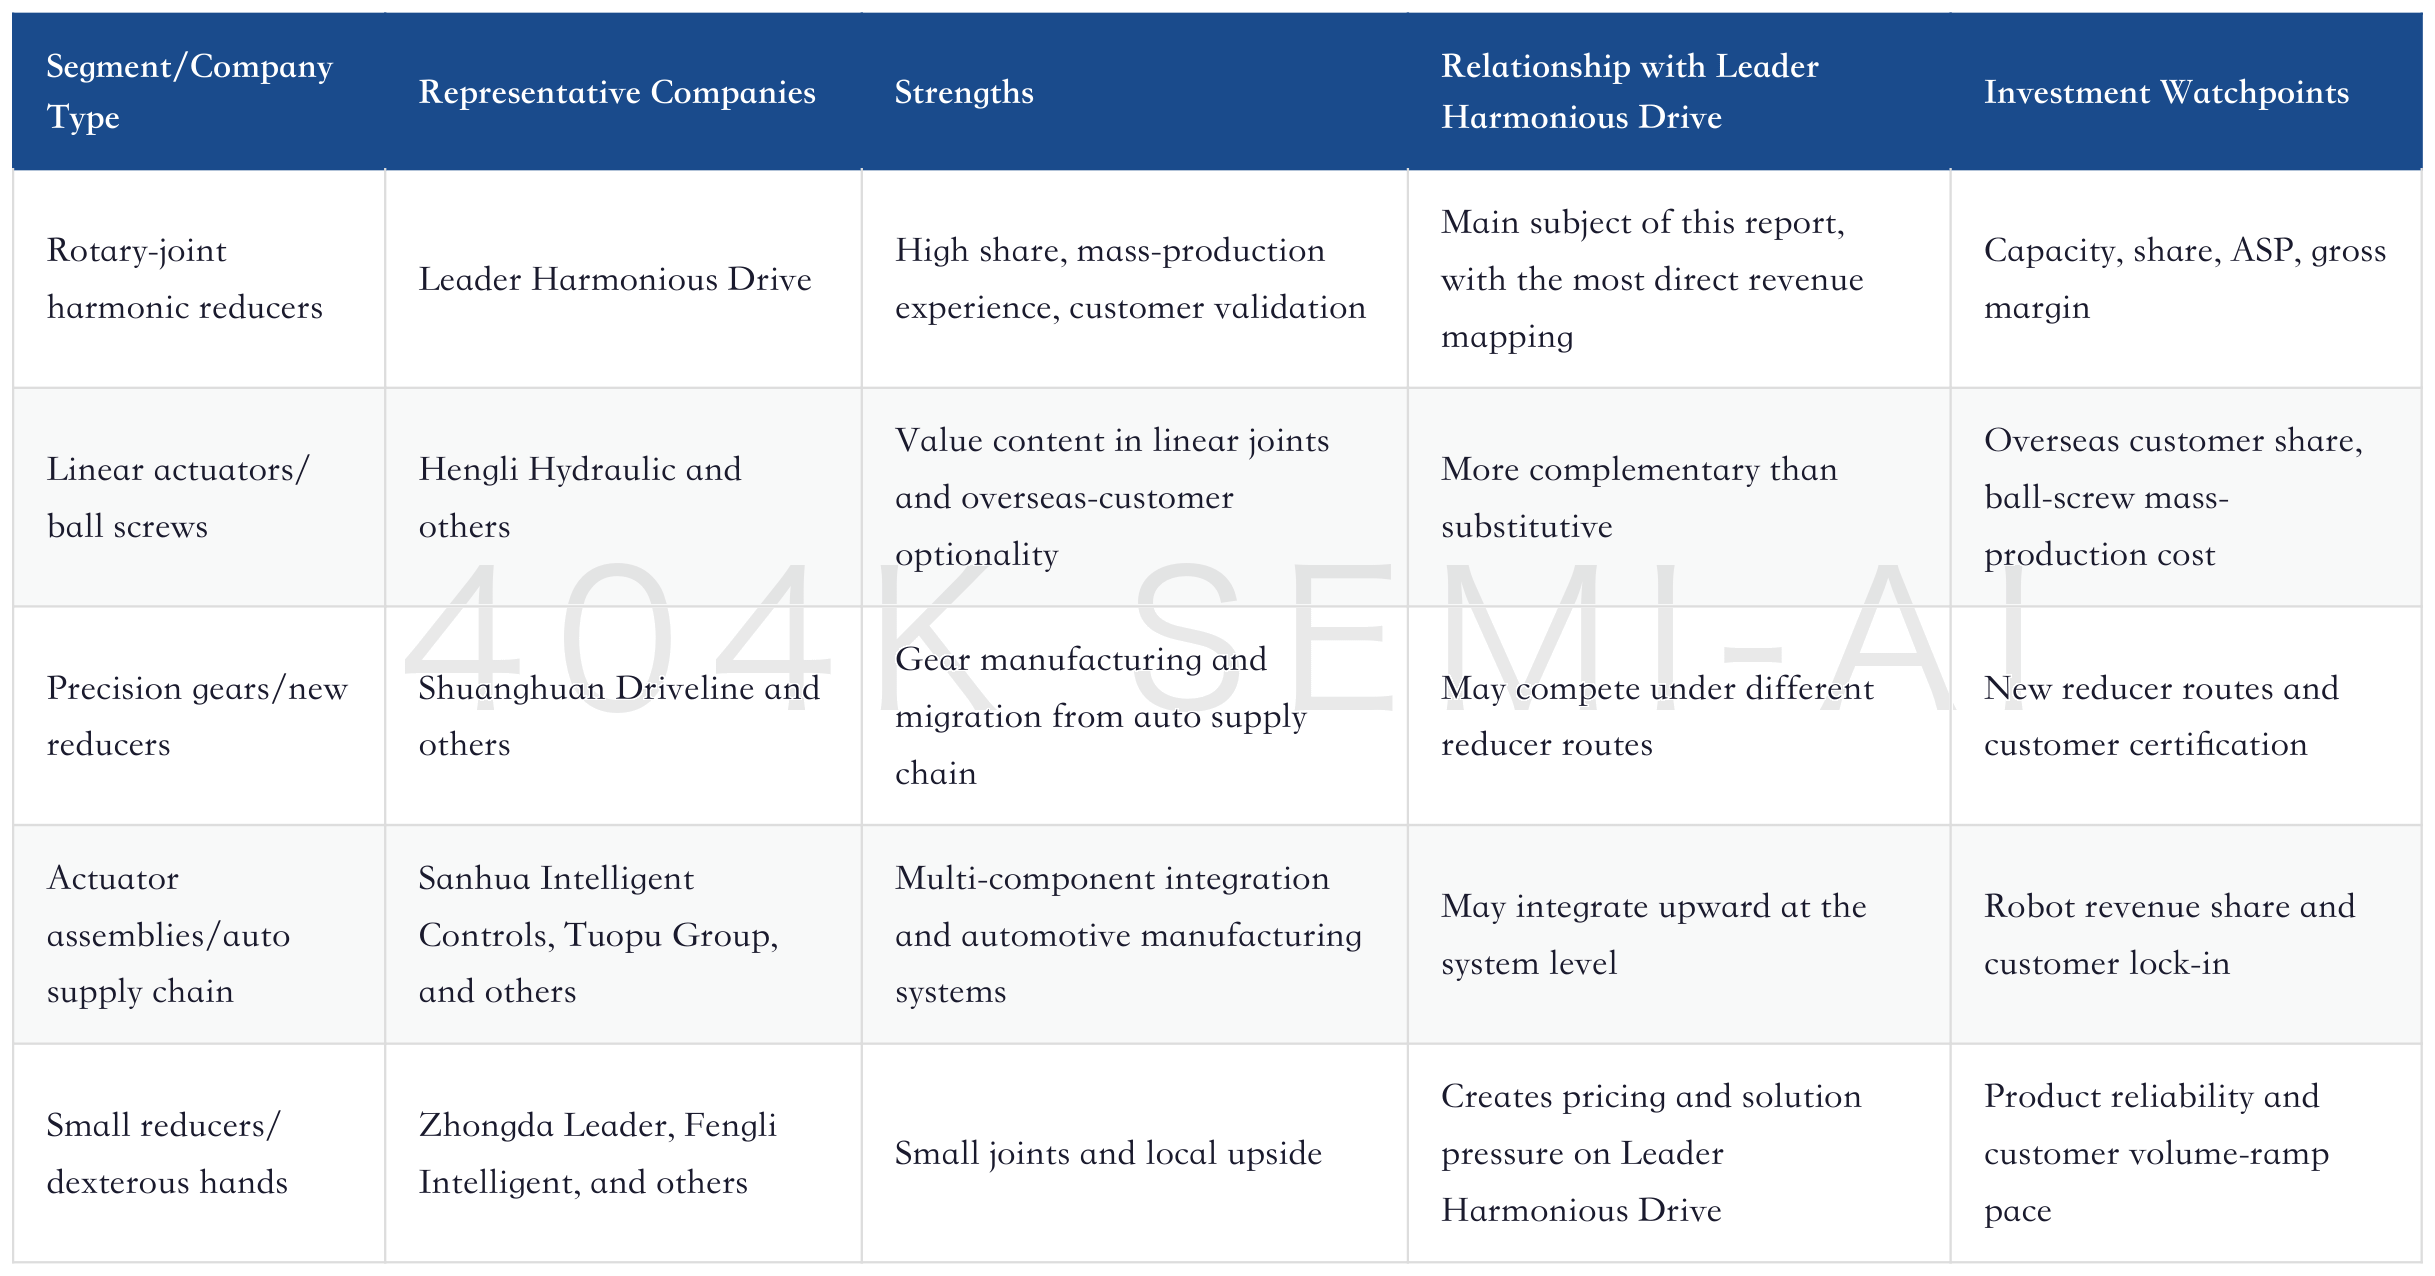
This ranking shows that Leader Harmonious Drive is not the only answer in the entire humanoid-robot supply chain, but it is one of the clearest domestic leaders in rotary joints. Investors should avoid two extremes: one is counting all robot orders as Leader Harmonious Drive revenue; the other is denying the company’s supply-chain position simply because valuation is expensive. A more reasonable approach is to track the company within the framework of “a high-purity rotary-joint leader whose valuation is extremely dependent on long-term volume ramp-up.”
8. Capability Transfer: From Industrial Robots to Humanoid Robots, How Old Assets Become New Assets
Leaderdrive’s most important capability transfer is moving its mass-manufacturing experience from the industrial-robot era into the humanoid-robot era. Industrial robots already impose demanding requirements on harmonic reducers: low backlash, high rigidity, long life, and stable repeat positioning accuracy. Humanoid robots do not lower those requirements; they further add load, shock, lightweighting, and cost constraints. Companies that can supply industrial-robot customers stably at least qualify for the humanoid-robot supplier list.
