
Largan Precision Deep Dive: 10-Channel Fiber Arrays, PMLA Micro-Optics, and the Gate to CPO Mass Production in 2H27
目录
Executive Summary
I. Understanding Largan Precision: Optical Components Generate 99.48% of Revenue, While High-End Specifications and Yield Drive Profit
II. What Does a 49.4% Gross Margin Indicate? High-End Lens Yields Have Stabilized Despite Lower Revenue
III. Smartphone Lenses Can Still Grow: Optical Complexity per Handset Matters More Than Global Shipments
IV. Defining Largan’s CPO Position Precisely: Sell Fiber-Array Components First, Then Pursue Incremental Micro-Optics Content
V. Grating Coupling vs. GlassBridge: Competing Architectures Will Not Automatically Eliminate the Value of Fiber Arrays
VI. Five Gates from Samples to Revenue: 2H27 Is Only the Earliest Window
VII. Sell-Side Debate Has Shifted from “Can It Be Done?” to “When Will Mass Production Begin, and Will Largan Sell Components or Complete Units?”
VIII. Core Model: Smartphone Lenses Provide the Floor; CPO Enters the Income Statement in 2028
IX. Peer Comparison: Largan Leads in Premium Smartphone Lenses but Remains a CPO Follower
X. Valuation Debate: The Smartphone Franchise Provides Most of the Base Value; CPO Optionality Determines the Upside
XI. Three Worldviews: One Company, Three Completely Different Valuation Frameworks
XII. Falsification Checklist: Which Numbers Would Require a Downgrade
XIII. What to Watch Over the Next Four Quarters: Breaking the Narrative into Verifiable Actions
XIV. Conclusion: Anchor the Core Business on a 49.4% Gross Margin, Then Price CPO Through Mass-Production Gates
本内容基于公开资料和研报数据整理,不构成任何投资建议,不代表任何个人观点,仅供学习参考,请理性阅读
Largan Precision’s smartphone lens business has demonstrated its ability to maintain a 49.4% gross margin despite a revenue decline. Its CPO business has just moved beyond the demonstration stage into sampling, validation, and production-line scheduling. Further valuation upside depends on whether the 10-channel fiber array can convert customer qualification into revenue in 2H27, while variable-aperture and periscope upgrades in smartphones must continue to support cash flow.
Executive Summary
Smartphone lenses remain the earnings foundation. Optical components accounted for 99.48% of revenue in 2025, and the company expects high-end camera phones to remain its largest mass-produced product in 2026. Second-quarter revenue fell 12% sequentially, yet gross margin held at 49.4%, indicating that current value creation comes from complex lenses, yield, and automation; total smartphone volumes mainly determine the slope of seasonality.
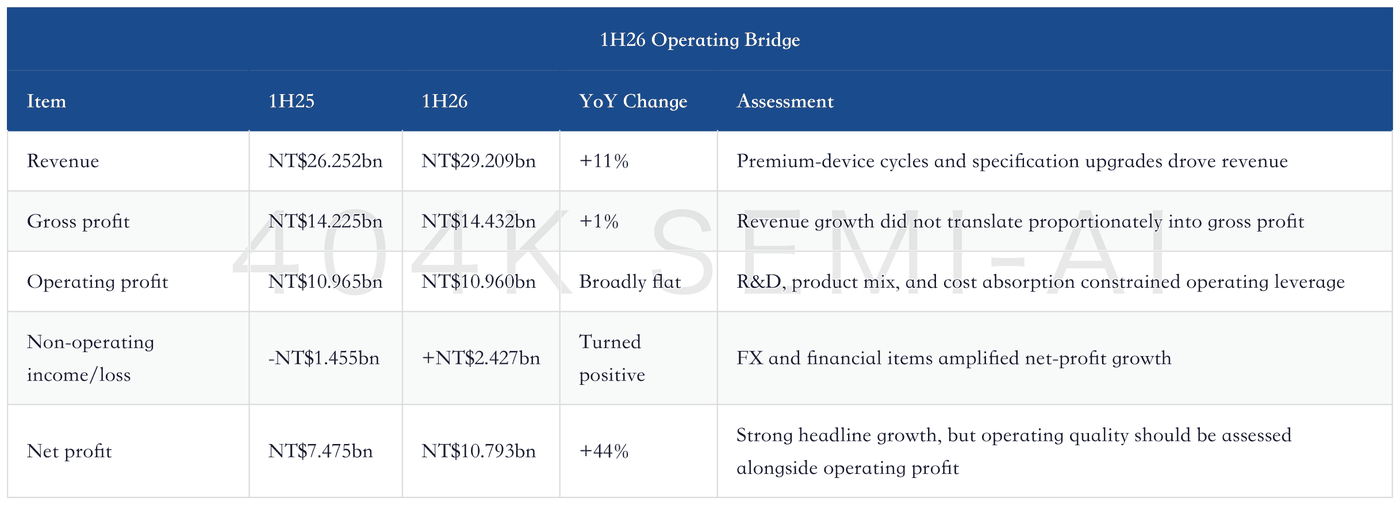
Second-quarter margins are more informative than revenue growth. Revenue reached NT$13.665 billion in 2Q26, up 17% year over year, while operating margin was 37.7%, broadly unchanged from the first quarter. The 44% year-over-year increase in first-half net profit benefited from a low comparison base due to FX losses in the prior-year period. Investors should focus on operating profit, the mix of lenses above 20MP, and periscope yields rather than EPS growth alone.
CPO has entered the customer-validation schedule. The company plans to deliver fiber-array samples in July 2026. Customer validation typically takes several weeks, the pilot line is scheduled for completion by the end of the third quarter, and a mass-production line could be established as early as mid-2027. One customer has entered a development track targeting mass production, while others are at the proof-of-concept stage. Evidence of commercialization has increased materially, but orders, yields, and market share remain unsecured.
The current product scope is a 10-channel fiber-array component. Largan will initially supply fiber-array-unit manufacturers with a single-row, 10-channel fiber array while continuing to develop glass-molded microlens-prism arrays. It does not currently intend to displace incumbent unit assemblers directly. Expanding from one row to two or four would increase content per system. If the company remains a supplier of basic components over the long term, revenue and valuation would be lower than under a complete-unit scenario.
2H27 is the first revenue gate. Goldman Sachs expects CPO revenue to begin earlier, while Citi, JPMorgan, and UBS moved closer after their July updates to a schedule of small-volume shipments in 2H27 followed by a ramp in 2028. The base-case model assumes only limited revenue in 2027 and reassesses 2028 based on customer count, channel count, average selling price, and market share, avoiding the premature treatment of a long-term addressable market as confirmed company orders.
The NT$3,950 share price already reflects some probability of CPO success. Based on the July 9, 2026 share price, the market valuation is already above a conservative range for a pure smartphone-lens cash cow. Target prices of NT$5,000–6,231 respectively depend on sum-of-the-parts valuation, higher P/E multiples, or faster CPO contribution. Each round of sample feedback, pilot-line progress, and mass-production capex will change the probability weighting assigned to this opportunity.
I. Understanding Largan Precision: Optical Components Generate 99.48% of Revenue, While High-End Specifications and Yield Drive Profit
Largan sells the capability to mass-produce technically demanding lenses. Largan Precision (Taiwan Stock Exchange: 3008) is vertically integrated across design, tooling, injection or glass molding, coating, assembly, and inspection, with a long-standing focus on optical precision in compact form factors. Customers pay not only for several lens elements, but also for thinner assemblies, larger apertures, higher resolution, more complex zoom paths, and stable yields across production runs numbering in the tens of millions.
The company’s scale is not supported by business diversification. Optical-component revenue totaled NT$60.828 billion in 2025, accounting for 99.48% of total revenue; other businesses contributed just 0.52%. The annual report lists applications spanning smartphones, tablets, notebook computers, automotive systems, medical devices, augmented reality, and virtual reality, but high-end camera phones remained the largest mass-produced product that year. This mix supports high margins while also making the company highly sensitive to premium-smartphone customers, flagship launch cycles, and lens specifications.
Largan generated revenue of NT$61.148 billion in 2025, up 3% year over year. Net profit attributable to owners of the parent fell 18% to NT$21.275 billion, with EPS of NT$159.41. The divergence between revenue growth and lower profit primarily reflected non-operating FX effects and weaker gross margin in the core business. Operational analysis should focus on gross and operating profit, as movements in the New Taiwan dollar can amplify or depress net profit.
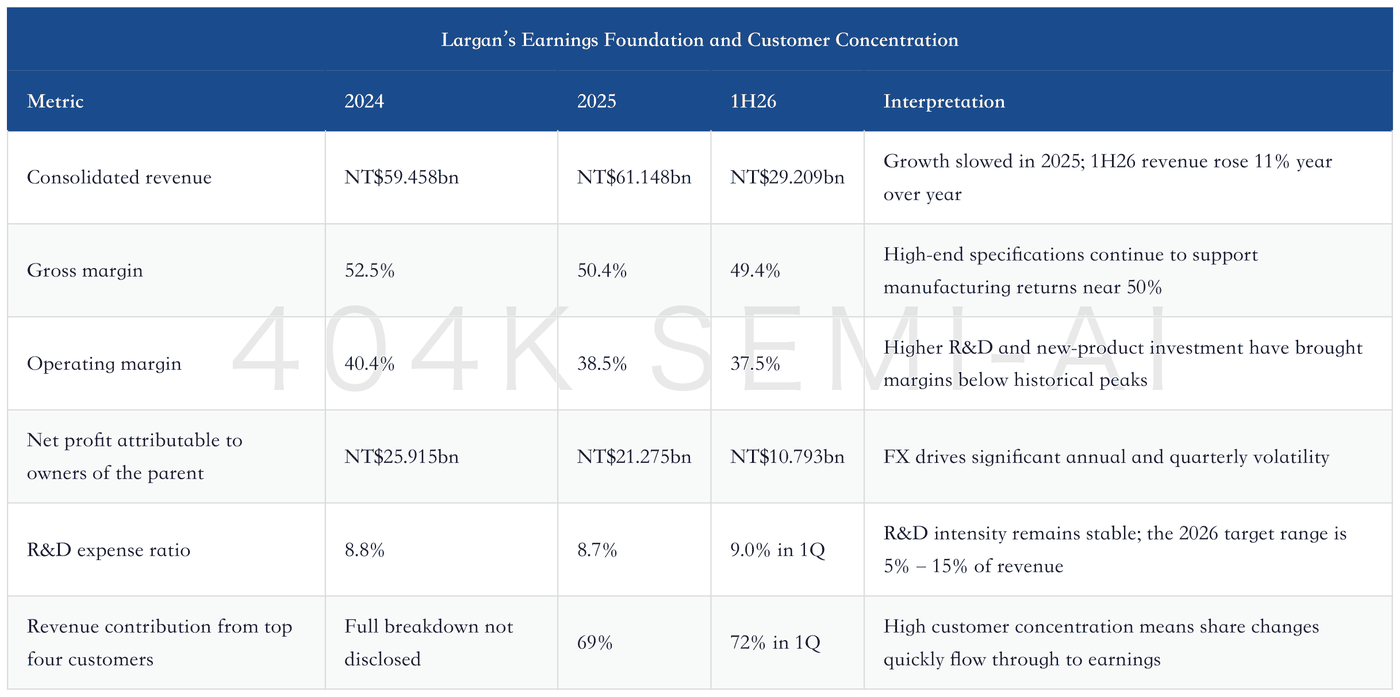
Customer concentration is both a moat and a source of volatility. The four largest customers contributed approximately 30%, 15%, 13%, and 11% of 2025 revenue, respectively, and their combined share increased to 72% in the first quarter. Official materials identify these customers by code rather than name, so each entry should not be mechanically mapped to a specific brand. What can be confirmed is that Largan depends on a small number of global premium-device customers, has deep design-in relationships, and can experience material monthly revenue changes when a single model is adjusted.
The geographic revenue mix also requires careful interpretation. Asia accounted for 99.78% of sales in 2025, reflecting supply and settlement locations rather than indicating that end demand comes exclusively from Asia. Largan’s lenses are used in flagship smartphones sold globally; end-brand mix and shipment geography cannot be inferred directly from this regional table.
II. What Does a 49.4% Gross Margin Indicate? High-End Lens Yields Have Stabilized Despite Lower Revenue
The most important second-quarter data point is that margins did not decline with scale. Revenue fell 12% sequentially in 2Q26, while gross and operating margins were 49.4% and 37.7%, respectively. First-quarter gross margin was also approximately 49.4%. Improved periscope-lens yields offset the pressure from lower capacity utilization, allowing the margin to remain stable in the second quarter.
Official financial materials disclose operating data across three levels—monthly revenue, quarterly financial statements, and annual reports—making it useful to assess monthly order momentum separately from quarterly margins.
Monthly Revenue. Quarterly Financial Statements. Company Annual Report.
Second-quarter EPS was NT$35.72, down from NT$46.63 in the first quarter. First-half EPS rose materially year over year to NT$82.35, partly because non-operating results swung from a loss in the prior-year period to a gain. First-half operating profit was NT$10.96 billion, nearly unchanged year over year. The 44% increase in net profit therefore cannot be attributed entirely to stronger competitiveness in smartphone lenses.
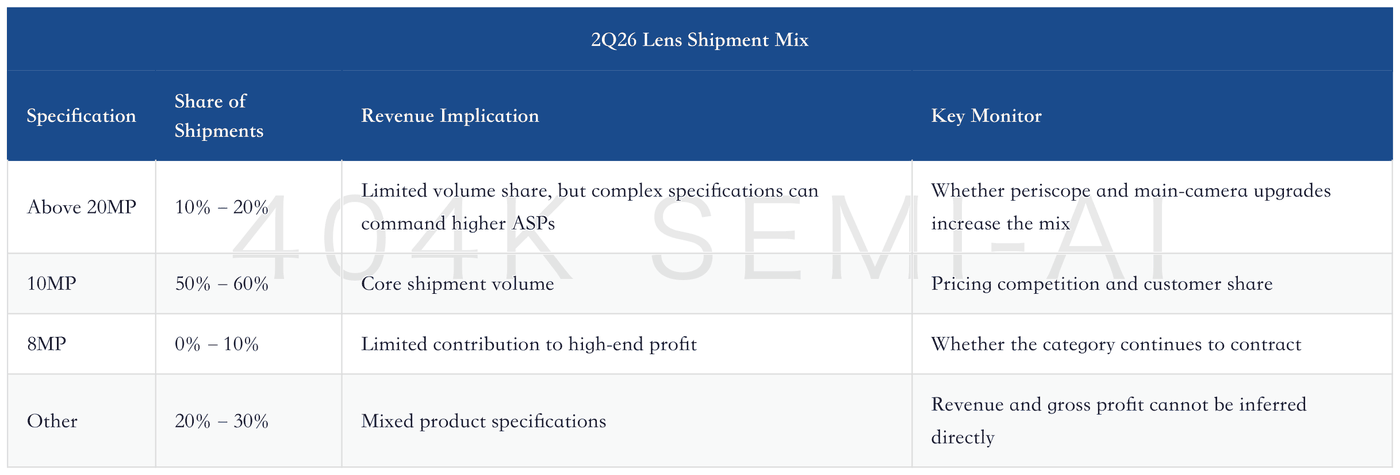
Shipment mix provides another useful indicator. The table below presents shipment-volume data compiled by UBS from the second-quarter earnings call; it should not be treated as revenue mix. Periscope, variable-aperture, and high-resolution lenses typically command higher prices and margins, meaning that even relatively small volumes of high-specification products can contribute disproportionately to profit.
The seasonal upswing in monthly revenue is arriving later than in previous years. Management expects July revenue to be only slightly above June, followed by a further increase in August, with peak inventory build for new devices potentially extending into the fourth quarter. If third-quarter revenue growth is less pronounced than in a typical peak season but the fourth quarter takes over, full-year revenue may not deteriorate. The 49.4% gross-margin floor would face a genuine test only if both July and August fall below guidance while capacity utilization declines.
III. Smartphone Lenses Can Still Grow: Optical Complexity per Handset Matters More Than Global Shipments
Total smartphone volumes have plateaued, but premium models continue to increase optical content per device. The 2025 annual report explicitly states that rising global smartphone penetration has pushed the industry into a plateau. Rather than waiting for aggregate volumes to return to rapid growth, Largan is increasing content per device through larger apertures, higher pixel counts, periscope designs, variable apertures, and more sophisticated zoom systems.
Largan’s technology history explains this strategy. The company introduced precision mold-core processing equipment for aspherical lenses in 1991, developed and launched mobile-phone lenses in 2002, developed an eight-element ultra-high-resolution lens in 2018, advanced 10x optical zoom in 2019, developed a 200MP lens in 2020, and added periscope zoom to its corporate milestones in 2022. Each upgrade increased the complexity of design, tooling, coating, assembly, and inspection.
Publicly listed on the Taiwan Stock Exchange (TWSE). Established operational headquarters. Developed projector zoom lenses.
This early corporate history has two implications. First, Largan accumulated expertise in both precision tooling and high-volume lens manufacturing at an early stage. Second, its transition from conventional camera zoom lenses to miniature smartphone lenses was not a one-off success in an adjacent field. It was a long process of compressing optical designs into smaller spaces and then using automation to scale yields. Success in CPO will likewise require three stages: design feasibility, customer validation, and stable mass production.
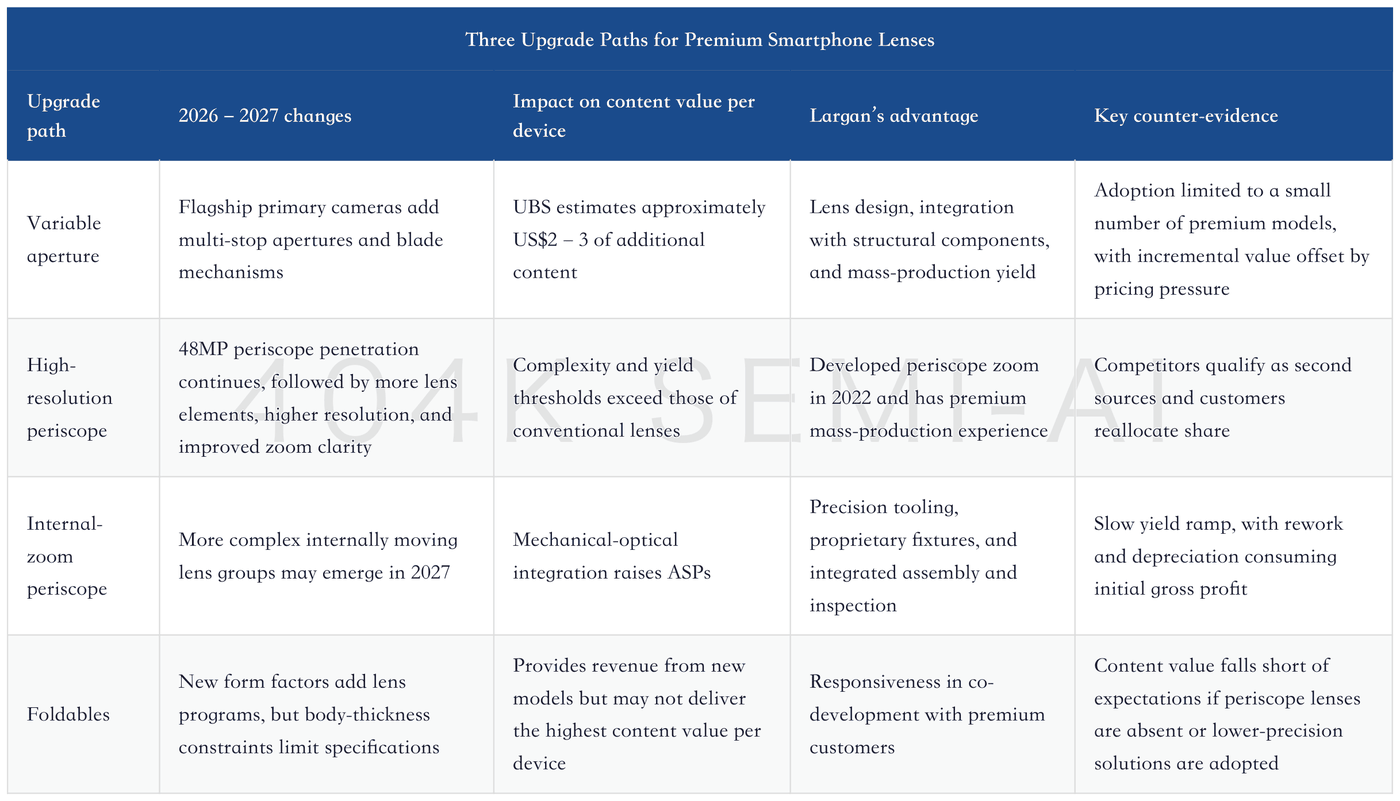
Variable aperture merits a plain-language explanation. A fixed-aperture lens operates at only one aperture setting. A variable aperture uses blades and mechanical components to alter the amount of incoming light, giving smartphones an additional hardware control across bright light, night scenes, and depth of field. This increases the number of lens and mechanism components, as well as assembly tolerances and inspection requirements. Customers will pay more only if the image-quality improvement is sufficiently clear and mass production does not impair overall device yields.
An internal-zoom periscope is more difficult than simply adding another lens element. The lens group must move within a confined space while maintaining optical-axis alignment, focal length, and image consistency. Largan’s profits come from converting this complexity into stable yields. If a new specification generates revenue but not gross profit, pricing or yields have failed to cover the additional process steps.
Luxshare Precision In-Depth: From Precision Manufacturing in Apple’s Supply Chain to AI Servers and Automotive Electronics—How High-Speed Connectivity Could Revalue Manufacturing Assets
This also explains the difference between Largan and conventional Apple supply-chain assemblers. Assemblers rely on scale, supply-chain management, and multi-category expansion; Largan relies on exceptionally high precision and yields within a single optical segment. Both types of companies are exposed to customer bargaining power, but Largan has higher margins and greater business concentration.
IV. Defining Largan’s CPO Position Precisely: Sell Fiber-Array Components First, Then Pursue Incremental Micro-Optics Content
Largan is currently entering the optical-coupling interface, not switch chips, lasers, or complete optical modules. CPO places the optical engine near the switch chip to shorten signal paths and reduce the power consumption of high-speed transmission. Optical signals must still be coupled from the photonic chip into optical fibers, creating value at the interface through fiber arrays, microlenses, prisms, alignment, and packaging.
Largan’s website now lists CPO solutions as a standalone category, but discloses only two products: PMLA and one- and two-dimensional fiber arrays. The page does not claim that the company has begun mass production of complete fiber-array units, nor does it disclose customers, orders, or revenue.
CPO Solutions. PMLA. Fiber Array (1D & 2D).
Following the July earnings call, JPMorgan revised its understanding of the product: Largan will initially manufacture fiber-array components and deliver them to existing fiber-array-unit vendors for assembly. The current specification is a single row with 10 channels, potentially upgrading to two or four rows in the future. This distinction is critical because component ASPs, customer responsibilities, and profit pools are all lower than for complete units. The market opportunity therefore cannot be calculated by simply multiplying complete-unit prices by Largan’s assumed market share.
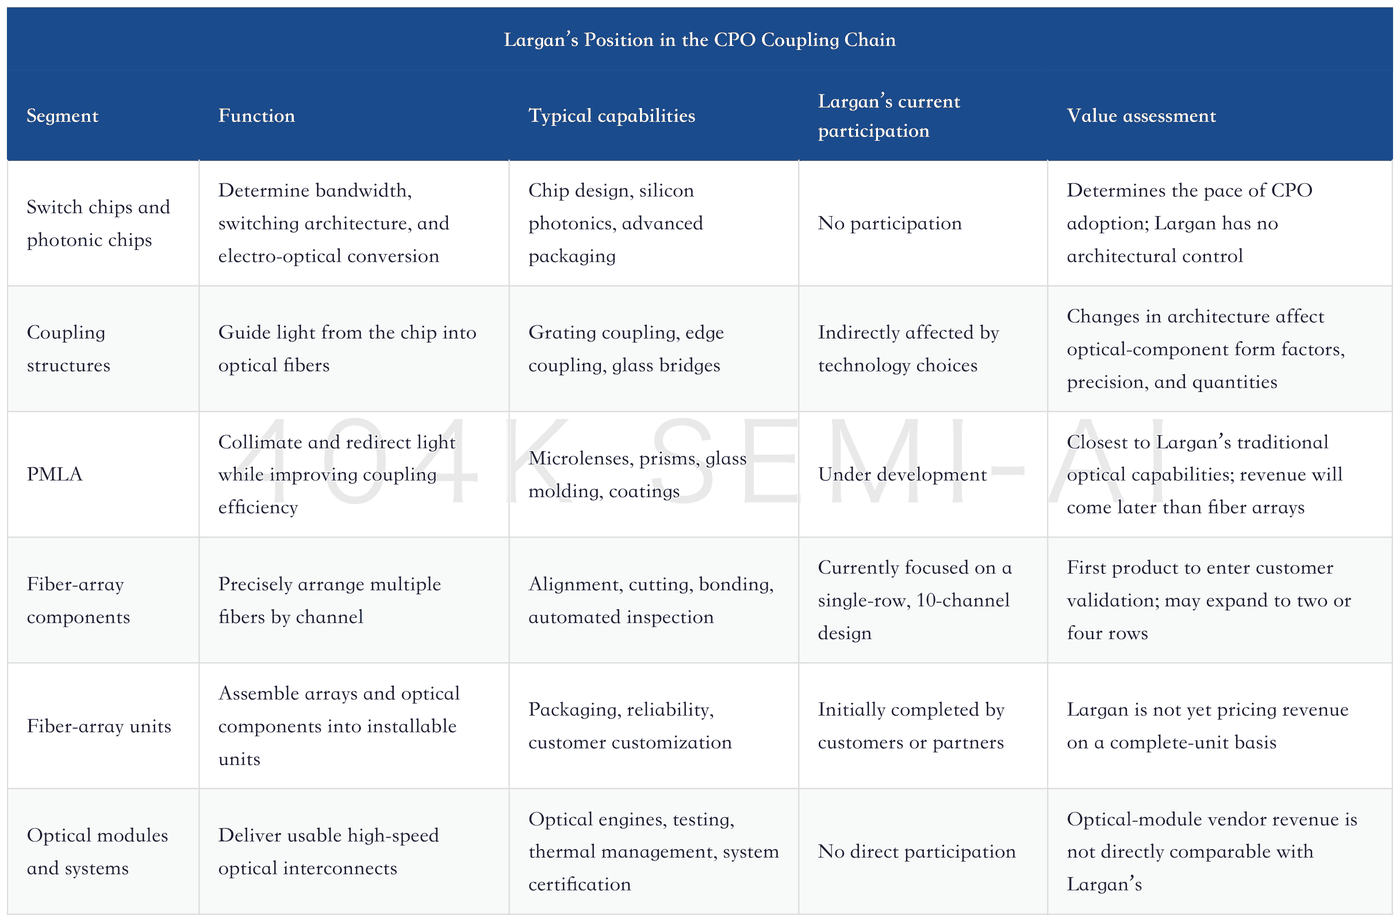
PMLA can be translated as a prism microlens array. It integrates multiple miniature optical surfaces into a single glass component to collimate, redirect, and focus light beams. Largan uses a glass-molding approach, while competing solutions include metalenses and semiconductor-process microlenses. The company aims to secure a position through lower loss and higher precision, but customer testing is still required to validate these claims.
The challenge in a fiber array is not simply “arranging 10 fibers in a row.” The center, angle, and end face of every fiber must remain within extremely tight tolerances. CPO switches require high channel density and long-term reliability. Achieving the required precision in a small number of samples is only the starting point; automated cycle times, process-capability distributions, adhesive life, thermal cycling, and batch-to-batch consistency ultimately determine profitability.
AI Networking Interconnect Hardware, Part I: Value Migration Behind 1.6T/3.2T—Who Benefits Most Across Switching, Copper Interconnects, Optical Interconnects, and the Physical Layer?
The transition from 1.6T to 3.2T and 6.4T increases the pressure on optical interconnect power consumption and density. The industry rationale for CPO is therefore sound, but the revenue captured by any individual supplier still depends on architecture, channel count, coupling approach, system content, ASPs, and customer share. Industry growth is not a substitute for company orders.
V. Grating Coupling vs. GlassBridge: Competing Architectures Will Not Automatically Eliminate the Value of Fiber Arrays
Mainstream designs are more likely to adopt grating coupling first over the next three years. Largan Precision’s management believes grating coupling is better suited to wafer-level testing, with more forgiving tolerances and a more mature supply ecosystem. GlassBridge primarily supports edge coupling, using a glass bridge to route light out from the edge of the chip. The two architectures differ in coupling efficiency, assembly methods, and component form factors, but both require stable fiber connections to optical interfaces.
Grating coupling offers easier integration of testing and assembly into wafer-level processes, but requires optimization of coupling loss and incidence-angle design. Edge coupling generally achieves lower loss, but chip-edge processing, alignment, and packaging are more complex. System customers will choose based on power consumption, reliability, mass-production cost, and supply-chain maturity rather than a single laboratory metric.
Market concerns over GlassBridge stem from an intuitive question: if the glass bridge integrates the optical path and fiber connection more completely, could conventional array components be eliminated? The common conclusion of the July reports is that edge-coupling solutions still require the arrangement and alignment of multi-channel fibers. The form of value may change, but the fibers will not simply disappear. The real risk is that, as component integration increases, Largan captures only a low-priced subcomponent, or competitors deliver the array, micro-optics, and packaging as an integrated solution.
Morgan Stanley CPO GlassBridge Deep-Dive Update: GlassBridge Displacement Concerns, TSMC’s 25kwpm PIC Capacity, and FAU Supply-Chain Repricing
CPO Bull-Case Expectations Cool: Architectural Competition Cannot Stop Optical Content Growth as AI Clusters Enter the Optical-Interconnect Era
Largan’s response sequence is now clear: first enter customer qualification with fiber arrays, then expand per-system content through PMLA, and only later consider taking on additional assembly work. This sequence reduces the risk of direct conflict with incumbent unit suppliers, but also means early revenue will be lower than under a “complete FAU supplier” model.
VI. Five Gates from Samples to Revenue: 2H27 Is Only the Earliest Window
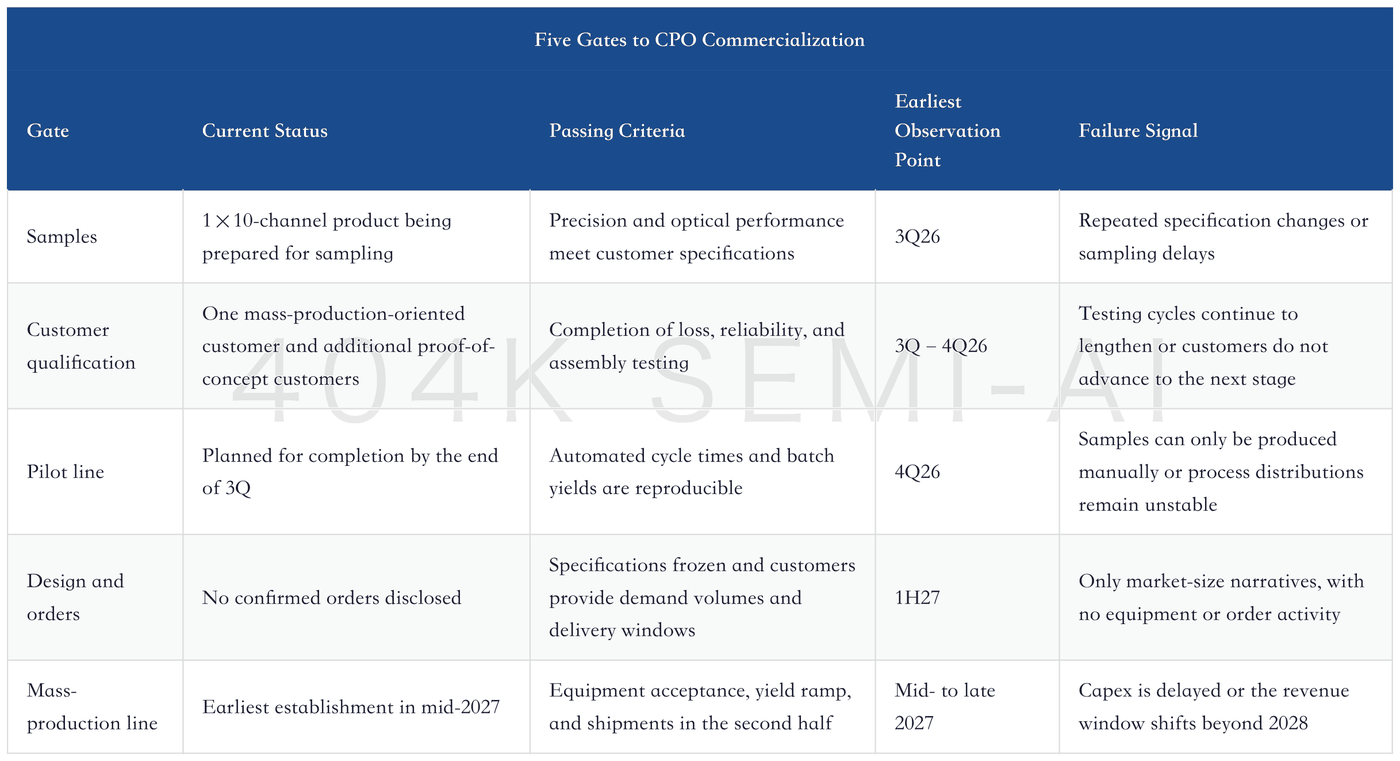
CPO has moved from concept demonstrations into engineering plans, but still faces five gates before stable mass production. The company plans to ship samples in July 2026, with customer qualification typically taking two to eight weeks. The pilot line is targeted for completion by the end of the third quarter. A mass-production line could be established by mid-2027 at the earliest, with revenue potentially beginning in the second half; meaningful contribution is unlikely before 2028.
The company is currently working with one mass-production-oriented customer and several proof-of-concept customers. “Mass-production-oriented” means the project is targeting commercialization; it does not mean the company has received long-term orders. Customers will continue to compare precision, loss, reliability, cost, supply assurance, and second-source availability. Revenue becomes credible only after qualification is completed, the design is frozen, equipment is installed, yields stabilize, and orders are released.
Largan has three major transferable advantages. First, its precision molds and micro-optical design capabilities can support PMLA. Second, its internally developed fixtures, automation equipment, and inspection expertise can support batch consistency in fiber arrays. Third, the co-development processes cultivated through high-end smartphone customers can help the company navigate stringent specifications and long qualification cycles.
There are also three challenges in transferring these capabilities. CPO customers differ from smartphone customers, and reliability testing is more oriented toward long-duration data-center operation. Fibers, adhesives, and photonic-chip interfaces introduce new processes. Incumbent fiber-array and unit suppliers also have established customer track records and system expertise. Largan’s position in smartphone lenses provides only an entry ticket; it does not automatically translate into CPO market share.
VII. Sell-Side Debate Has Shifted from “Can It Be Done?” to “When Will Mass Production Begin, and Will Largan Sell Components or Complete Units?”
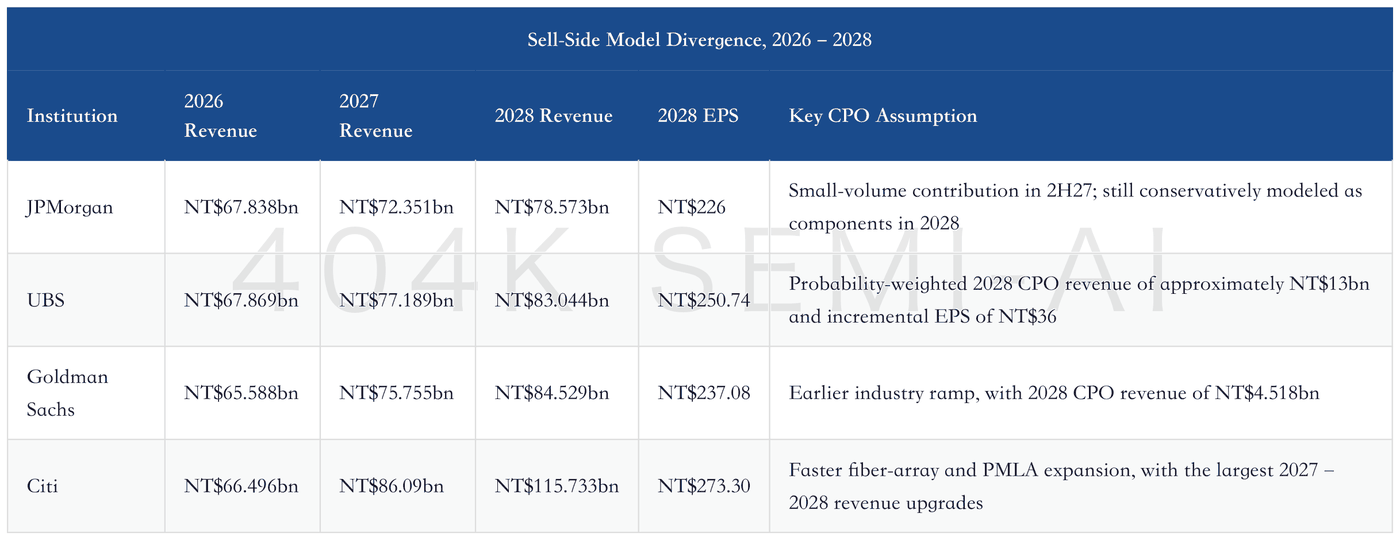
The July reports reflect a more conservative—and more verifiable—consensus than those published in June. JPMorgan explicitly positions Largan as a fiber-array component supplier. UBS places the earliest start of mass production in mid-2027, while Citi incorporates revenue from 2H27 into its model. Goldman Sachs’ late-June report assumes an earlier industry ramp and a higher valuation multiple, forming the optimistic upper bound.
The four institutions have similar 2026 revenue and EPS forecasts, indicating limited disagreement over the smartphone-lens base business. By 2028, revenue forecasts range from NT$78.573 billion to NT$115.733 billion. The gap primarily reflects assumptions regarding CPO adoption, product scope, and market share rather than total smartphone volumes.
UBS’s three scenarios are best used to understand the variables, not as direct order forecasts. Switch volumes, units per switch, average selling prices, and Largan’s market share compound one another, so changes in any single assumption can materially alter the outcome.
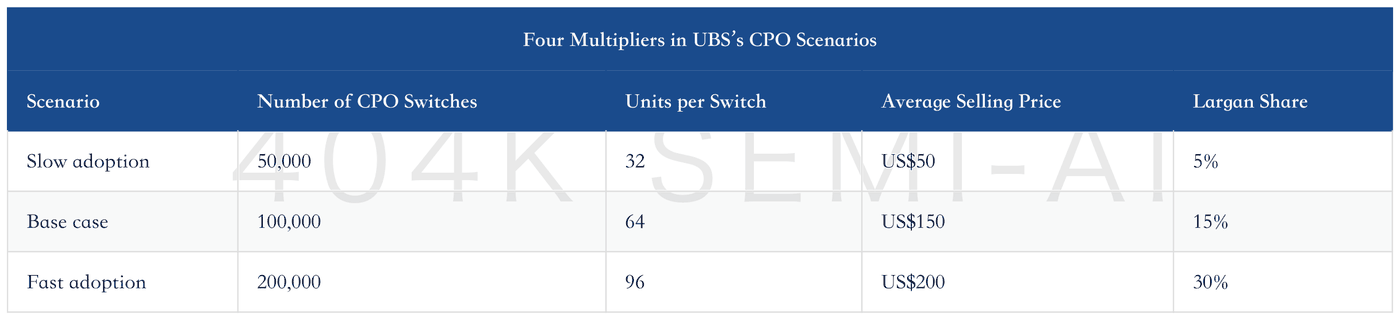
The weak point in these scenarios is the assumed ASP range. Largan currently plans to sell fiber-array components first, while the higher prices in UBS’s table are more consistent with complete units or highly integrated solutions. If the company remains a component-only supplier over the long term, actual ASPs could be significantly below US$150–200. The higher price range would be supported only if PMLA and additional assembly content are included.
