
Lam Research Earnings Deep Dive: $6.7 Billion in Revenue, 52% Gross Margin, and $8.1 Billion Guidance
目录
TL;DR
I. Behind $6.7 Billion in Revenue: Scale, Mix, and Efficiency Working Together
II. Multiple Business Drivers: Memory Returns, Foundry Holds Steady, and Services Accelerate
III. What Changed This Quarter—and What Did Not
IV. What Does the $8.1 Billion Guidance Imply?
V. Cash Flow Is Strong, but Working Capital Has Raised a Flag
VI. The Four Points the Market Is Most Likely to Misread
VII. Disconfirming Evidence and Future Validation Metrics
Conclusion
本内容基于公开资料和研报数据整理,不构成任何投资建议,不代表任何个人观点,仅供学习参考,请理性阅读
The results show simultaneous acceleration in new equipment, installed-base services, and margins; the next test is whether delivery, collections, and high margins can be sustained.
TL;DR
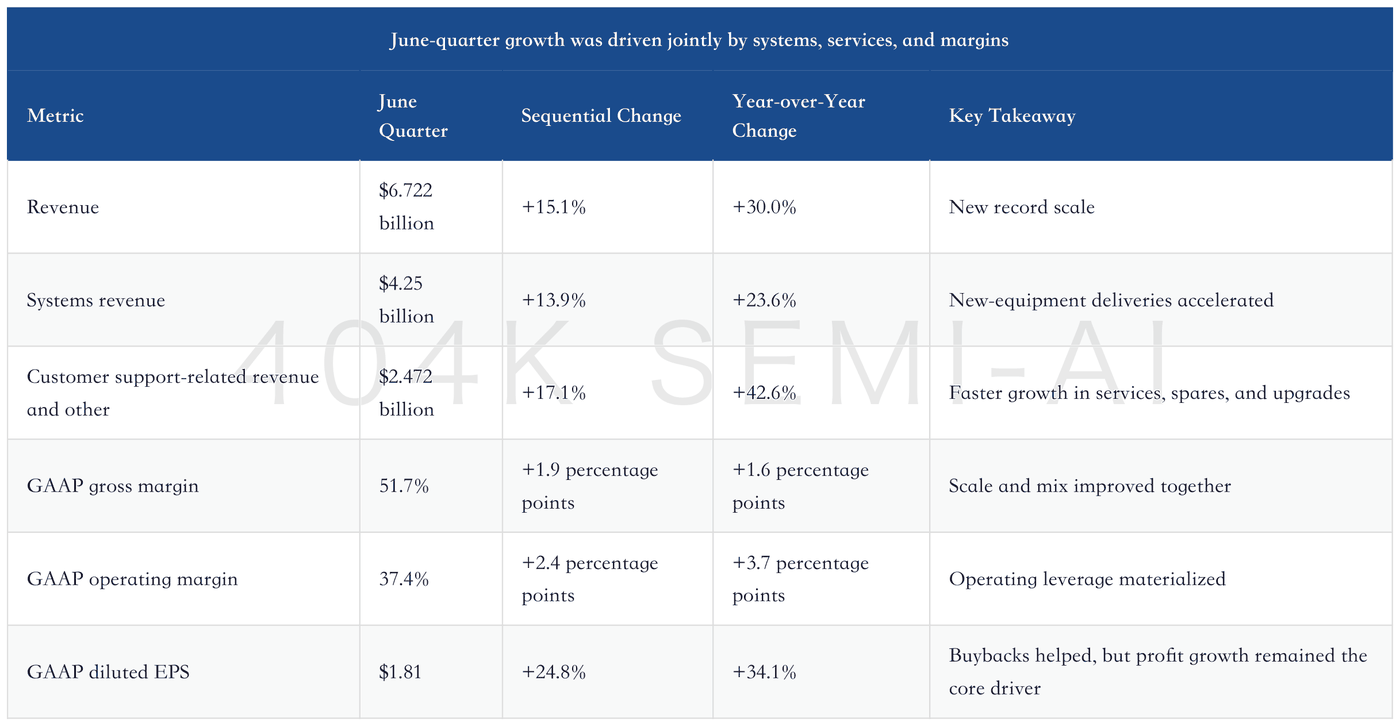
Lam Research generated $6.722 billion in revenue for the quarter ended June 28, 2026, up 15.1% sequentially and 30.0% year over year; GAAP gross margin rose to 51.7%, operating margin to 37.4%, and diluted EPS reached $1.81. Revenue growth, margins, and EPS all strengthened, indicating that the earnings beat was not merely an accounting outcome manufactured through expense reductions.
Growth was more diversified than simply “AI-driven demand for advanced-logic equipment.” Systems revenue increased 23.6% year over year, while customer support-related revenue and other increased 42.6%. Within systems revenue, memory, foundry, and logic and other accounted for 46%, 44%, and 10%, respectively. Management also disclosed that NAND revenue doubled sequentially and advanced-packaging revenue is expected to grow by more than 70% year over year, validating the previous thesis that four growth vectors—memory upgrades, advanced logic, packaging, and installed-base services—are progressing in parallel.
September-quarter revenue guidance is $8.1 billion±$400 million, implying another 20.5% increase from the June quarter at the midpoint; non-GAAP gross-margin and operating-margin guidance are 52% and 39.5%, respectively. The strong guidance also raises the validation threshold to delivery cadence, DSO, inventory, and operating cash flow, rather than merely orders or the AI narrative.
Cash generation remains strong, but the picture is less comfortable than the income statement suggests. June-quarter operating cash flow was $1.457 billion and free cash flow was $1.268 billion; however, FY2026 operating cash flow declined 5.1% year over year, accounts receivable increased 29.2% sequentially, and DSO rose from 64 days to 72 days. If revenue continues to surge without improvements in collections and working-capital turnover, earnings quality will be the first source of disconfirming evidence.
I. Behind $6.7 Billion in Revenue: Scale, Mix, and Efficiency Working Together
Lam Research generated June-quarter revenue of $6.722 billion, an increase of $881 million from the prior quarter. GAAP gross profit was $3.479 billion, with gross margin rising from 49.8% to 51.7%; operating income was $2.513 billion, with operating margin increasing from 35.0% to 37.4%. As operating expenses increased from $864 million to $965 million, expenses did not contract; operating-margin expansion primarily reflected greater revenue scale and a higher gross margin, rather than sacrificing R&D; to boost profits.
Year over year, revenue increased 30.0%, GAAP operating margin expanded by 3.7 percentage points, and net income grew 32.4% to $2.277 billion. GAAP diluted EPS was $1.81 versus non-GAAP diluted EPS of $1.82. The minimal difference between the two measures indicates that the quarter’s earnings surge did not depend on substantial adjustments. The full-year picture was equally clear: FY2026 revenue was $23.233 billion, up 26.0% year over year; net income was $7.265 billion, up 35.6%, while GAAP operating margin increased from 32.0% to 35.3%.
II. Multiple Business Drivers: Memory Returns, Foundry Holds Steady, and Services Accelerate
The most important mix shift this quarter was that memory re-emerged as an accelerator without pulling the company back into a single memory cycle. Within systems revenue, NVM and DRAM each accounted for 23%, foundry for 44%, and logic and other for 10%. In other words, memory represented 46% in aggregate, while foundry and logic and other represented 54%, leaving the revenue mix balanced. Management disclosed that NAND revenue doubled sequentially, consistent with memory capital expenditure moving from upgrades toward broader expansion. The company also expects CY2026 WFE to be in the low $150 billion range and believes Lam Research will outperform WFE for a third consecutive year.
