
目录
Executive Summary
1. First 20 Days of August: Semiconductors Lift South Korean Exports to a New Level
2. The 13-Month Trend: Semiconductor Share Rises from 24.6% to 47.2%
3. DRAM: Softer Pricing Does Not Prevent Exports from Reaching a Record High
4. NAND and SSD: Prices Drive Year-over-Year Growth; Volumes Begin to Drive Sequential Growth
5. MCP/HBM: Export Value, Pricing, and Volumes All Rise
6. Price–Volume Decomposition: YoY Growth Was Primarily Price-Driven
7. After Eliminating Overlap, Three Major Memory Categories Accounted for 80.0% of Semiconductor Exports
8. Destination Mix: Asian Manufacturing Supply Chains and U.S. Demand Both Provided Support
9. Implications for Samsung Electronics, SK Hynix, and the Supply Chain
10. Four-Stage Transmission from Export Value to Profit and Cash Flow
11. What to Watch: Full-Month Data Will Test the Durability of Price-Volume Momentum
12. Conclusion: South Korean Exports Are Entering a Memory-Led Phase
本内容基于公开资料和研报数据整理,不构成任何投资建议,不代表任何个人观点,仅供学习参考,请理性阅读
South Korea’s semiconductor exports reached US$26.032bn in the first 20 days of August, accounting for 47.2% of total exports. DRAM, NAND, SSD, and MCP all strengthened, with the balance between pricing and shipment volumes increasingly determining the durability of the current memory upcycle.
Executive Summary
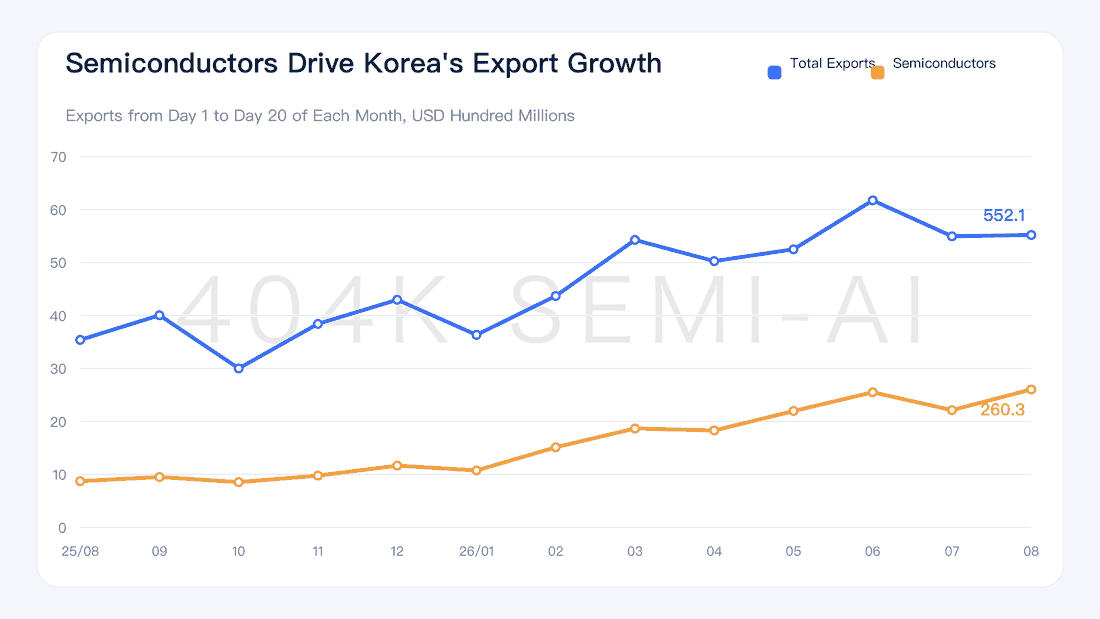
Semiconductors have become the decisive driver of South Korea’s export growth. Exports totaled US$55.207bn from August 1–20, up 56.0% YoY. Semiconductor exports rose 198.8% to US$26.032bn, representing 47.2% of the total. Despite 0.5 fewer working days than a year earlier, average daily exports still increased 61.5%, underscoring the underlying strength of aggregate growth.
Semiconductors drove most of the sequential acceleration from July. Total exports increased just 0.5% MoM, while semiconductor exports rose 17.7% and computer-peripheral exports gained 11.7%. Semiconductors’ share of exports climbed from 24.6% in August 2025 to 47.2% in August 2026, reflecting a marked 12-month shift in South Korea’s export mix toward memory and computing hardware.
DRAM shipment growth more than offset lower pricing. DRAM exports excluding modules totaled US$9.807bn, up 12% MoM, despite an 8% decline in unit prices. Based on export value and unit pricing, implied shipment volumes increased 21.7% MoM. DRAM exports including modules reached US$12.228bn, implying 9.6% volume growth, indicating that August’s gains were not driven solely by pricing.
NAND and SSD’s strong YoY growth was mainly price-driven, while volumes began to expand modestly MoM. NAND exports totaled US$1.751bn, with unit prices up 75% MoM and implied shipment volumes up 3.4%. SSD exports reached US$2.028bn, with unit prices up 7% and implied volumes up 7.5%. Enterprise-storage demand is now supporting export value through both pricing and volumes.
MCP was one of August’s highest-quality sources of incremental growth. MCP exports reached US$6.854bn, up 46% MoM, with unit prices rising 19% and implied shipment volumes increasing 22.7%. The simultaneous gains in value, pricing, and volume are consistent with the HBM supply chain’s combination of high value density and accelerating deliveries.
Avoiding double counting is critical when interpreting these figures. DRAM including modules already encompasses the ex-module category, so the two cannot be added together. The three non-overlapping categories—DRAM including modules, NAND, and MCP—totaled US$20.833bn, equivalent to 80.0% of semiconductor exports. SSDs are classified under computer peripherals; their US$2.028bn of exports represented 89.0% of that category.
1. First 20 Days of August: Semiconductors Lift South Korean Exports to a New Level
South Korea Customs Service data for August 1–20 provide a clear top-down picture. Exports totaled US$55.207bn, up 56.0% YoY, while imports rose 19.0% to US$41.231bn, generating a US$13.975bn trade surplus. The period contained 14.0 working days versus 14.5 days a year earlier, yet fewer working days did not constrain export growth. Average daily exports reached US$3.94bn, up 61.5% YoY.
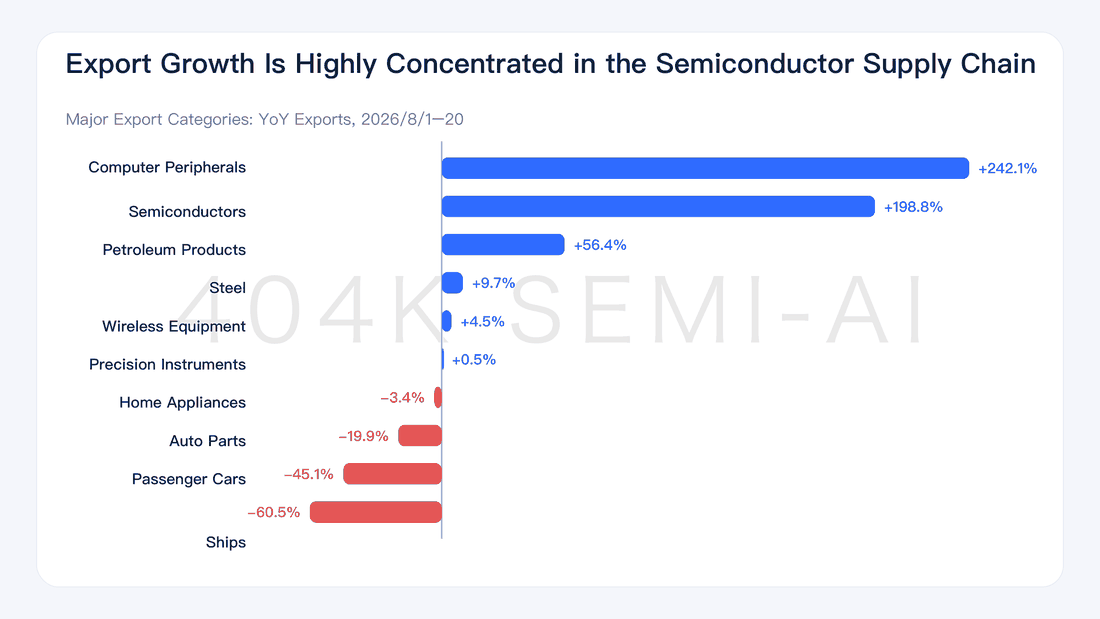
Semiconductors were the standout category. Semiconductor exports reached US$26.032bn in the first 20 days of August, up 198.8% YoY and accounting for 47.2% of South Korea’s total exports. Computer-peripheral exports rose 242.1% to US$2.278bn. Together, the two categories generated US$28.31bn, or 51.3% of total exports, meaning more than half of South Korea’s exports were directly tied to chips and computing hardware.
Performance across other major categories was sharply divergent. Petroleum-product exports rose 56.4% YoY to US$4.239bn; steel exports increased 9.7% to US$2.392bn; and wireless-device exports gained 4.5% to US$1.04bn. Passenger-car exports fell 45.1% to US$1.521bn, ship exports declined 60.5% to US$914mn, and auto-parts exports dropped 19.9% to US$797mn.
This mix shows that semiconductor growth has more than offset declines across several traditional export categories. From July to the first 20 days of August, total exports edged up from US$54.957bn to US$55.207bn, an increase of just US$249mn. Over the same period, semiconductor exports rose from US$22.12bn to US$26.032bn, an increase of US$3.912bn. Incremental semiconductor exports therefore far exceeded the net increase in total exports, with other categories offsetting most of the gain.
As exports become more concentrated, South Korea’s trade surplus and manufacturing income become increasingly sensitive to the memory cycle. Pricing, volumes, and product mix across DRAM, NAND, SSD, and the HBM supply chain are now jointly shaping total exports, average daily exports, and the trade surplus. The significance of the first 20 days of August is that all three metrics strengthened in tandem.
2. The 13-Month Trend: Semiconductor Share Rises from 24.6% to 47.2%
On a comparable first-20-days basis, semiconductor exports progressed through three distinct phases. From August 2025 to January 2026, exports fluctuated between US$8.533bn and US$11.645bn. From February to April 2026, they rose from US$15.111bn to approximately US$18.285bn. From May through August, exports remained above US$20bn, reaching US$25.504bn in June and US$26.032bn in August.
Over the same period, total exports increased from US$35.394bn in August 2025 to US$55.207bn in August 2026, up 56.0% YoY. Semiconductor exports climbed from US$8.712bn to US$26.032bn, nearly 3x the prior-year level. Semiconductors contributed US$17.32bn of the YoY increase, equivalent to 87.4% of the US$19.813bn growth in total exports.
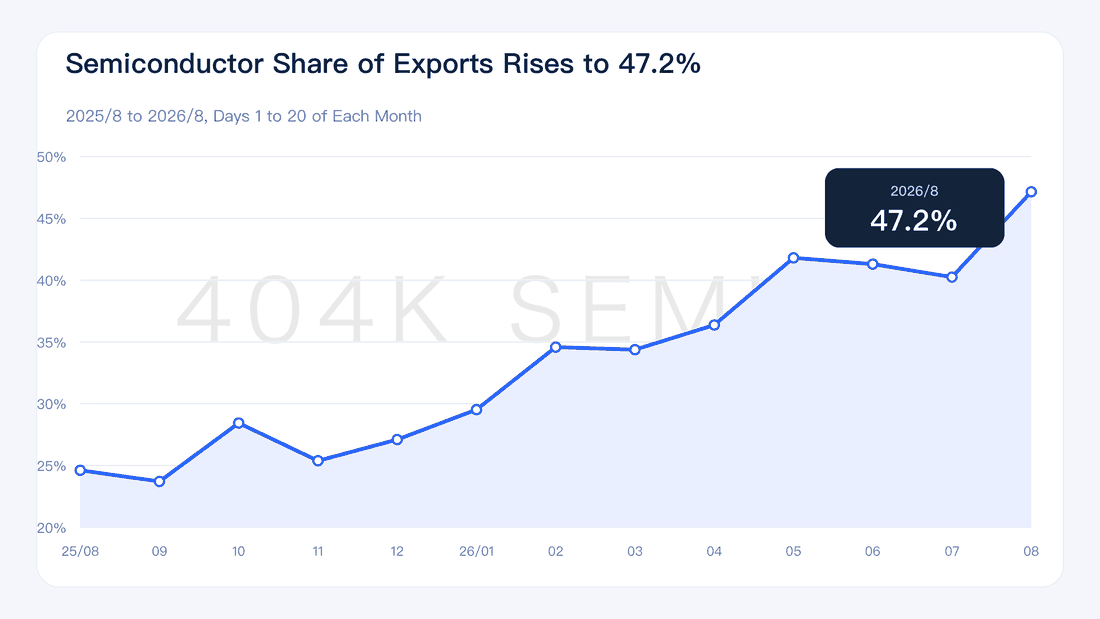
The rise in semiconductors’ share of total exports best illustrates the structural shift. Their contribution increased from 24.6% in August 2025 to 27.1% in December 2025, 34.6% in February 2026, 41.8% in May, 41.3% in June, 40.2% in July, and 47.2% in August. The 22.5-percentage-point increase over one year shows that semiconductors have moved from being one component of the export recovery to its principal driver.
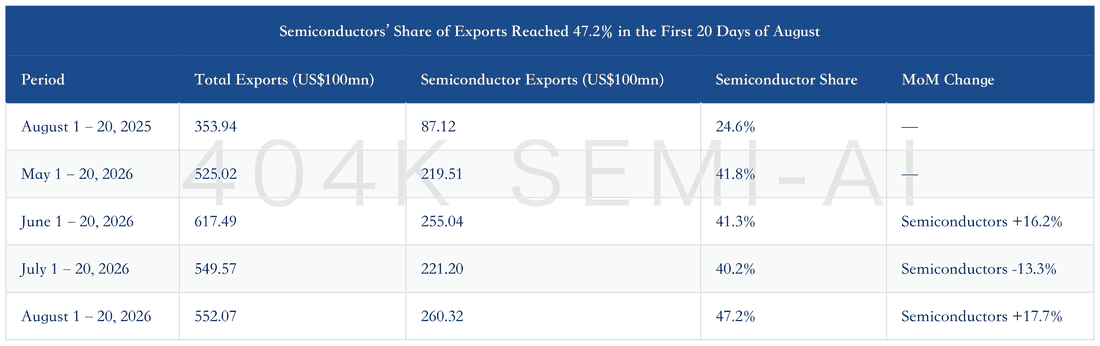
August’s sequential recovery has another important feature: semiconductor exports surpassed their June peak, while computer-peripheral exports remained below June’s US$3.066bn. This indicates that August’s hardware growth was more heavily concentrated in chips themselves. Device categories such as SSDs also improved, but did not account for the full increase.
Japan and South Korea’s AI Semiconductor Supply Chains: Japanese Equipment and Materials, Korean HBM, and Industrial Automation
3. DRAM: Softer Pricing Does Not Prevent Exports from Reaching a Record High
DRAM should be assessed on both an excluding-modules and including-modules basis. In the first 20 days of August, DRAM exports excluding modules reached US$9.807 billion, up 505% year over year and 12% month over month; unit prices were US$92,183/kg, up 401% year over year but down 8% month over month. Including modules, DRAM exports reached US$12.228 billion, up 415% year over year and 3% month over month; unit prices were US$66,567/kg, up 437% year over year but down 6% month over month.
Higher export value alongside lower month-over-month unit prices points to volume expansion. Using “(1 + export-value growth) ÷ (1 + unit-price growth) − 1,” implied shipment volume increased 21.7% month over month for DRAM excluding modules and 9.6% for DRAM including modules. August’s incremental growth came from higher volumes, while lower prices constrained export-value growth.
The year-over-year picture differs slightly. For DRAM excluding modules, export value rose 505% and unit prices increased 401%, implying shipment-volume growth of 20.8%. Including modules, export value rose 415% and unit prices increased 437%, implying a 4.1% decline in shipment volume. The divergence reflects differences in module mix, product weight, and pricing, so no single volume metric can explain the full change in DRAM exports.
