
Korean Equity Deleveraging Nears Its End: A 40% Drawdown, 5x Valuation, and Four Diversification Themes
目录
TL;DR
I. In Eight Days, the Market Shifted from “How Much Forced Selling Remains?” to “Can Earnings Take Over?”
II. A 40% Drawdown Means Neither That Fundamentals Are Fine nor That They Have Collapsed
III. Why Leveraged ETFs Were the Most Important Source of Forced Selling in This Cycle
IV. Hedge Funds Are Near Normalization, While Retail Margin Financing Was Never the Primary Source of Selling Pressure
V. $110 Billion of Outflows Looks Alarming, but the 90% Concentration Matters More
VI. The Real Bet Embedded in a 5x Valuation Is How Long Elevated Memory Profitability Can Last
VII. Four Diversification Themes, Not a Basket of Four Themes That Will All Rise Together
VIII. The Next Step Is Not to Call the Bottom, but to Validate Three Sets of Conditions
IX. Conclusion: The Liquidity Discount Is Beginning to Recede, and Earnings Durability Is Becoming the Central Test
本内容基于公开资料和研报数据整理,不构成任何投资建议,不代表任何个人观点,仅供学习参考,请理性阅读
The KOSPI has fallen nearly 40% from its June 22 peak, but the most mechanical selling by leveraged ETFs has largely run its course. The next phase is no longer just about asking “who still has to sell,” but about determining whether the memory earnings underpinning the 5x valuation can be sustained and whether capital is genuinely broadening out from the two index heavyweights into a wider range of Korean assets.
TL;DR
Deleveraging has moved from “halfway through” to “nearly normalized.” Assets under management in Korea-related leveraged ETFs have fallen from approximately US$50 billion in late June to US$17 billion, prompting JPMorgan to upgrade its assessment from “approximately 75% complete” on July 21 to “complete”; the equity long/short ratio in the JPM Prime sample has also declined from 5.7x to 3.2x.
Near-complete liquidation does not mean the index will bottom immediately. A weakening of the leveraged-ETF forced-liquidation chain only indicates that the marginal impact of mechanical selling has diminished; the FOMC, hyperscaler earnings, memory prices, and residual positioning may still generate volatility.
Retail margin financing is not the primary systemic risk. Korean retail investors’ margin-financing balance is approximately US$20 billion, or about 0.5% of total equity-market capitalization, and has not expanded aggressively this year. It has buffers in the form of margin top-ups and discretionary position management, unlike leveraged ETFs, which mechanically reduce exposure on down days.
The more than US$110 billion in foreign outflows has been highly concentrated. Approximately 90% of net selling came from two memory heavyweights. As their weights in the MSCI Emerging Markets Index have fallen to 6.5% and 4.5%, respectively, passive reductions driven by mandate limits are slowing; most sectors have not experienced withdrawals on a comparable scale.
A 5x valuation is cheap, but not unconditionally so. The KOSPI trades at approximately 5x both forward earnings and estimated free cash flow; at the same time, market prices already imply that memory prices will return to pre-AI-cycle levels in early 2027. The real valuation upside depends on the duration of earnings, not merely the current multiple.
Market leadership is broadening from the two memory heavyweights into a wider range of sectors. During the July correction, advance-decline breadth did not deteriorate in line with the index, while value and defensive sectors began to catch up. This suggests that losses in this round were concentrated primarily in a small number of heavyweights, rather than reflecting a simultaneous collapse in earnings expectations across all Korean companies.
The four diversification themes rest on independent rationales: wealth-effect beneficiaries depend on household assets and trading activity; biopharma depends on a recovery in global healthcare sentiment; preferred shares depend on discounts and dividend yields; and banks depend on asset quality, net interest margins, and brokerage income. This breaks down the risks of relying on a single memory theme and should not be treated as an “index-rebound basket” whose components will rise in tandem.
I. In Eight Days, the Market Shifted from “How Much Forced Selling Remains?” to “Can Earnings Take Over?”
JPMorgan’s first deleveraging report on July 21 addressed why the Korean market had fallen sharply even though fundamentals had not yet deteriorated across the board. At the time, the KOSPI had declined approximately 28%–29% from its June 22 peak, while assets under management in Korea-related leveraged ETFs had fallen from US$50 billion to US$26 billion. The authors estimated that approximately 75% of this deleveraging chain had been completed; equity long/short hedge funds were more than halfway through deleveraging, but positioning remained above the normal range. The most important question then was how much passive selling remained.
The second report, dated July 29, advanced the analysis by one step. The index drawdown widened to nearly 40%, but leveraged-ETF assets had already fallen to US$17 billion, below the approximately US$18 billion “acceptable range” cited in the previous report. The equity long/short ratio in the JPM Prime sample declined to 3.2x, and the price-momentum factor then fell sharply again over the following two days. The authors therefore concluded that the liquidation of leveraged ETFs was complete and that hedge funds had completed approximately 90% of their deleveraging.
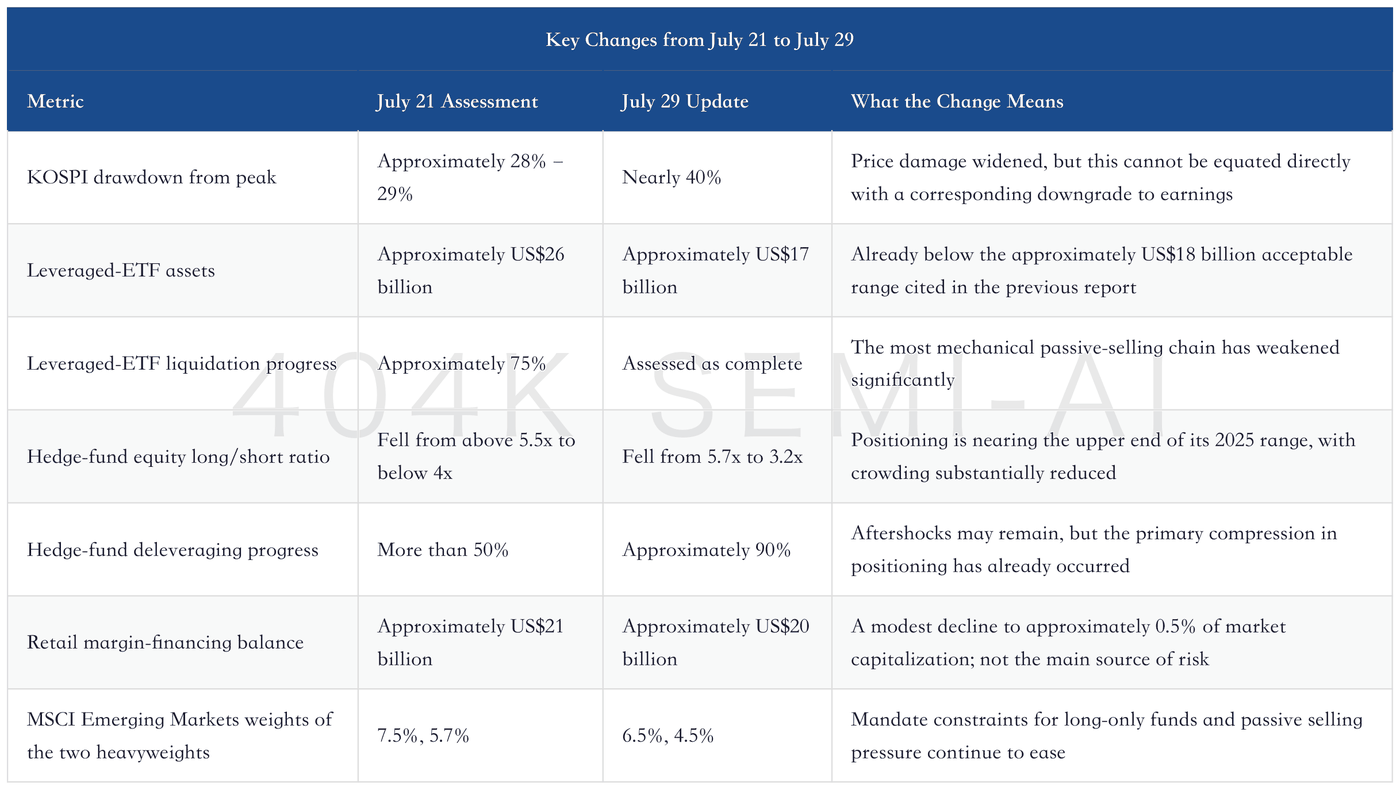
The table reveals a seemingly contradictory but important shift: the index is lower, yet the market structure is healthier. The July 21 low still contained substantial feedback loops in which falling prices forced further selling; by July 29, the low was closer to a valuation question following a reset in positioning. Prices may continue to fall, but the forces driving them have begun to shift from forced selling toward macro events, earnings delivery, and investor risk appetite.
II. A 40% Drawdown Means Neither That Fundamentals Are Fine nor That They Have Collapsed
Attributing the entire decline to fundamentals would overlook the amplification caused by leveraged products and crowded positioning; attributing it entirely to technical deleveraging would likewise understate uncertainty surrounding the memory earnings cycle. A more accurate decomposition is that conventional fundamental concerns and sector rotation triggered the correction; leveraged ETFs, swap capacity, and hedge-fund positioning amplified it; and concentrated selling in memory heavyweights subsequently dragged down the index.
This is also why a “nearly 40% drawdown” and “relatively stable market breadth” can coexist. The Korean market had previously been highly concentrated, with the proportion of stocks outperforming the KOSPI on a rolling six-month basis falling at one point to only approximately 10%–15%. When a small number of mega-cap heavyweights decline, the index appears extremely weak. During the July correction, however, advance-decline breadth did not collapse in tandem, while value and defensive sectors instead began to catch up. Most stocks still carry risk, but the index decline has exaggerated the breadth of the deterioration in market-wide fundamentals.
