
Korea Weekly Deep-Dive Update: KOSPI Pulls Back 1.9%; Can Returning Foreign Capital and Alphabet’s Capex Hike Support AI Hardware Earnings?
目录
TL;DR
From an 8.8% Decline to a 1.9% Decline: What Has the Market Repaired First?
Deleveraging Enters Its Second Half, Reducing the Rebound’s “Mechanical Resistance”
Foreign Investors Buy Technology Again: From Risk Avoidance to Position Rebuilding
What Alphabet’s Increased Spending Means for Korean AI Hardware
Earnings Have Not Collapsed, but the Market Has Shifted from “Broad-Based Upgrades” to “Structural Divergence”
How Cheap Is a 6x P/E? Look First at the Denominator, Then at P/B
A Stronger Won, Rising Government-Bond Yields, and Surging Oil Prices: Three Forces Pulling in Different Directions
What Sector Rotation Reveals: Defensiveness, Low Crowding, and Earnings Divergence Are Starting to Drive Pricing
Three Paths: Reversal, Range-Bound Recovery, or Another Leg Down
Next Week’s Watchlist: Turning the Narrative into Verifiable Data
Conclusion: Deleveraging Has Reversed, but Earnings Confirmation Is Still Pending
本内容基于公开资料和研报数据整理,不构成任何投资建议,不代表任何个人观点,仅供学习参考,请理性阅读
Deleveraging pressure in the Korean market is rapidly subsiding, while foreign investors have resumed buying technology stocks. The key determinant of whether this recovery can extend remains whether AI capex can translate into earnings upgrades for Korean companies.
TL;DR
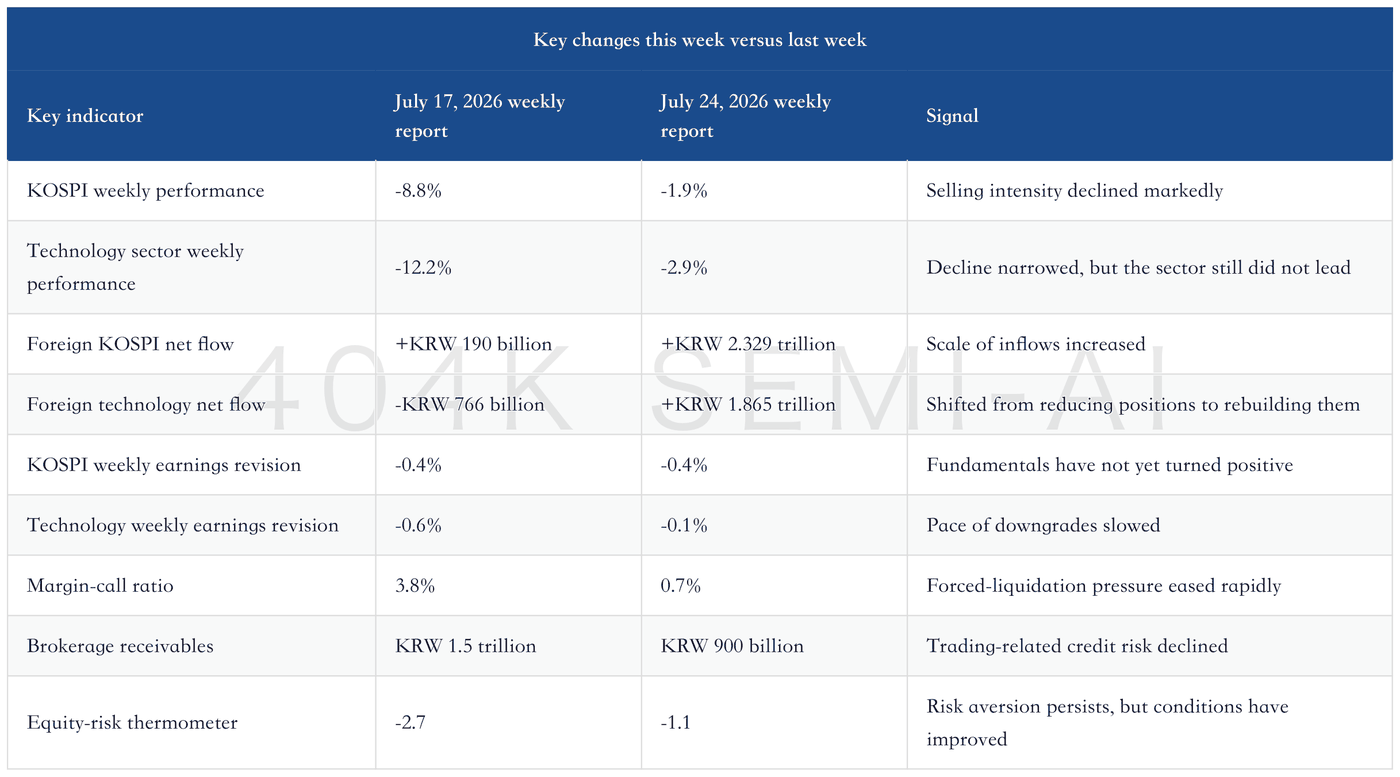
The clearest improvement this week was a marked easing in trading pressure. The KOSPI fell 1.9% for the week, far less than the previous week’s 8.8% decline; margin calls as a percentage of receivables fell from 3.8% to 0.7%, brokerage receivables declined from KRW 1.5 trillion to KRW 900 billion, and margin-loan balances dropped from a peak of US$25 billion to US$22 billion. The vicious cycle of forced liquidation and passive selling has been substantially interrupted.
The quality of foreign inflows improved from last week, but it is too early to call this a long-term reversal. Foreign investors recorded net purchases of KRW 2.329 trillion in the KOSPI this week, including KRW 1.865 trillion in technology. This is more constructive than last week’s “modest aggregate inflow but continued technology selling.” However, cumulative foreign net outflows since end-2024 still total KRW 159.033 trillion, while foreign ownership of semiconductors stands at approximately 50.1%, 1.8 standard deviations below the historical average. This week looks more like position rebuilding by underweight investors.
Alphabet’s capex guidance increase confirms that global AI infrastructure demand remains strong. The company’s second-quarter capex was US$44.924 billion. Of its technical infrastructure investment, approximately 60% went to servers and 40% to data centers and networking equipment. Its 2026 capex guidance was raised from US$180 billion–US$190 billion to US$195 billion–US$205 billion. Demand-side visibility has improved, but whether Korean suppliers benefit will depend on memory configurations, market share, contract pricing, and product mix.
The earnings inflection point has not yet arrived. The KOSPI’s 12-month forward EPS was still revised down 0.4% this week, while technology was revised down 0.1%, although this narrowed from last week’s 0.6% decline. Chemicals were revised up 2.3%, while autos were revised down 3.8%, indicating that the market has shifted from broad-based de-risking to sector-level earnings divergence. Fundamentals cannot be assessed solely from index moves.
A P/E of approximately 6x is very cheap, but that cheapness is conditional. The KOSPI’s 12-month forward P/E is approximately 6.1x, close to its historical low of 5.8x; Korea trades at forward-P/E discounts of 67% and 53% to global equities and Asia Pacific ex-Japan, respectively. However, Korea trades at a 14% P/B premium to Asia Pacific ex-Japan. The low P/E depends primarily on a denominator of sharply higher future earnings; not all assets are trading at liquidation value.
Three sets of synchronized signals should be monitored next. On trading conditions, watch margin calls, brokerage receivables, and volatility; on flows, watch foreign net flows into technology and semiconductor ownership; and on fundamentals, watch weekly technology earnings revisions, DRAM prices, and the realization of AI customer capex. Improvement across all three would signal a reversal; a liquidity recovery without earnings follow-through would still be only a high-volatility rebound.
From an 8.8% Decline to a 1.9% Decline: What Has the Market Repaired First?
Viewed only through the index, this week’s story could easily be summarized as “Korean equities are still falling.” But compared with one week ago, the signals are entirely different: last week, the KOSPI fell 8.8%, technology dropped 12.2%, the equity-risk thermometer declined to -2.7, and both margin calls and brokerage receivables were rising. This week, the KOSPI’s decline narrowed to 1.9%, technology’s decline shrank to 2.9%, the risk thermometer recovered to -1.1, and margin calls and receivables fell markedly. Prices remain weak, but the intensity of forced selling within the market has already eased substantially.
This distinction matters. Trend-driven declines are usually caused by downward revisions to earnings expectations, while trading-driven selloffs are amplified through the interaction of margin financing, leveraged products, volatility, and crowded positioning. The former requires a repricing of fundamentals; the latter can quickly create rebound potential once forced selling subsides. The Korean market completed the second type of repair first this week, but has not yet completed the first.
The price recovery did not replicate the previous technology-only rally. Construction, software, and telecommunications rose 8.4%, 7.1%, and 6.9%, respectively, ranking as the top three performers; securities, autos, and insurance fell 6.5%, 4.4%, and 3.8%, respectively, making them the weakest performers. Although technology attracted the largest foreign purchases, the sector still fell 2.9%. Capital has returned before price leadership, typically indicating that institutions are rebuilding core positions rather than chasing an already-confirmed acceleration in earnings.
Deleveraging Enters Its Second Half, Reducing the Rebound’s “Mechanical Resistance”
The strongest evidence this week comes from margin financing and leveraged products, not from any overarching narrative.
Margin-loan balances fell from a peak of US$25 billion to US$22 billion, while remaining at 0.5% of Korea’s total equity-market capitalization. The decline in absolute balances, without an abnormal increase relative to market capitalization, suggests that this round of deleveraging has been driven more by active position reductions and risk controls following the market decline and has not yet evolved into systemic credit contraction. On July 23, margin calls as a percentage of receivables fell to 0.7%; the 5-day moving average was 2.7% on July 22, while brokerage receivables declined to KRW 900 billion. The gap between the single-day figure and the moving average shows that the pressure did not disappear overnight, but the direction is already very clear.
The adjustment in Korean leveraged ETFs has been more severe. Assets under management fell from a peak of US$53 billion to US$26 billion, nearly halving; total leveraged exposure is equivalent to 2.1% of free-float market capitalization. These figures have two implications:
First, the highly elastic marginal buying of the past has shrunk significantly. Even if the market rises, the rebound may not immediately regain its previous rate of acceleration.
Second, the persistent selling pressure caused by passive position reductions and redemptions has also declined substantially. Provided volatility does not spike again, prices will be more responsive to incremental positive catalysts than they were last week.
Short-selling balances and short-selling activity are also declining. A reduction in short selling can typically reflect either profit-taking by short sellers or a contraction in risk budgets following excessive market volatility. Because it occurred this week alongside renewed foreign buying of technology and easing margin pressure, it is more consistent with “both longs and shorts reducing extreme positioning.” This environment supports stabilization, but it also means that for the market to continue rising, the driver must shift from passive positioning changes to active earnings pricing.
Deleveraging repair therefore answers “why the market is no longer falling as it did last week,” but not “why it should continue rising.” The latter question still depends on earnings.
Foreign Investors Buy Technology Again: From Risk Avoidance to Position Rebuilding
Foreign investors recorded net purchases of KRW 2.329 trillion in the KOSPI this week, while financial institutions recorded net sales of KRW 2.798 trillion, individuals recorded net purchases of KRW 461 billion, and pension funds recorded net purchases of KRW 170 billion. On the surface, foreign investors and domestic institutions were trading directly against each other; the more valuable information lies in the sector composition.
