
Korea Weekly Deep Dive: KOSPI Falls 8% as 6.2x Valuation Diverges from Samsung’s Record Profit
目录
TL;DR
I. From a 4% Pullback to an 8% Decline: Prices Keep Falling Even as Marginal Selling Eases
II. What Is a 6.17x P/E Pricing In? The Market Is Front-Loading a 33% Earnings Downgrade
III. Samsung’s Record-High Profit and 4.81x Valuation: The Core Disconnect in the Korean Index
IV. Earnings Are Still Being Upgraded, but More Slowly: From a Broad Rally to Divergence
V. Flow Structure: Foreign Investors Continue to Sell Technology, While Domestic Retail Continues to Buy
VI. Stronger Won, Rising Exports: Macro Data Do Not Validate the Equity Selloff
VII. 70% of Companies Trade Below 1x Book: An Inexpensive Market Still Contains Relative Winners and Losers
VIII. Three Scenarios: Oversold Recovery, Range-Bound Consolidation, and Cycle Peak
IX. Four-Week Validation Checklist: Six Metrics Will Determine Whether Low Valuations Translate into Returns
10. Conclusion: 6.17x Offers Attractive Odds; Earnings Durability Determines the Probability of Success
本内容基于公开资料和研报数据整理,不构成任何投资建议,不代表任何个人观点,仅供学习参考,请理性阅读
The divergence between valuation and earnings in the Korean equity market reached an extreme this week: the KOSPI fell 7.6%, its 12-month forward P/E declined to 6.17x, while Samsung’s core earnings and index EPS forecasts continued to be revised upward. The opportunity lies in easing foreign selling and a stronger won; the risks are a slowdown in earnings upgrades, elevated margin financing, and an incomplete unwinding of crowded technology positions.
TL;DR
Prices are falling faster than fundamentals. The KOSPI declined 7.6% for the week to 7,475.94, while its 12-month forward P/E fell to 6.17x, 3.1 standard deviations below its historical average. Meanwhile, 12-month forward EPS was still revised up by 1.4%. The market is front-running an earnings peak and unwinding crowded technology positions. The first issue to monitor is whether earnings revisions remain positive.
Marginal selling pressure has eased. Foreign investors sold a net KRW 4.12 trillion this week, sharply lower than KRW 19.84 trillion in the prior week, while the won appreciated 1.6% against the US dollar. Foreign investors still sold KRW 5.06 trillion of technology shares, indicating that systemic capital-outflow pressure has weakened but technology-position liquidation is not yet complete.
Samsung’s earnings and valuation are sharply misaligned. Driven by stronger DRAM, Samsung Electronics’ 2Q26 core operating profit prompted 2027 and 2028 EPS forecast upgrades of 3.7% and 4.4%, respectively. Yet its 12-month forward P/E fell to 4.81x, the lowest since 2000. Whether the multiple can recover depends on whether elevated memory profitability can be locked into 2027 cash flow.
The index’s 6.2x valuation embeds a deep-recession scenario. Even if consensus next-12-month EPS of 1,175 is cut by 33% to 787 and valued at the historical median trough P/E of 11.4x, the implied KOSPI level is approximately 8,936, still above the current level. This stress test offers attractive risk-reward, but not an immediate bottom-fishing signal.
Sector rotation has shifted from high-beta exposure toward cash flow. Banks and telecom rose against the market, while technology and shipbuilding fell nearly 10%. Securities led earnings upgrades. Portfolios should reduce concentrated technology risk, retain core memory exposure, and add securities, telecom, and selected chemicals, while waiting for earnings revisions in machinery to reaccelerate.
Monitor six signals over the next four weeks. KOSPI EPS, foreign flows into technology, Samsung’s July 30 earnings call, DRAM prices, the won, and the share of constituents trading above their 200-day moving averages will collectively determine the nature of the market. If earnings continue to be revised upward and foreign selling of technology eases, the 6.17x valuation will increasingly look like an overshoot. If earnings revisions turn negative alongside price declines, the low P/E will be interpreted as a cyclical-peak discount.
I. From a 4% Pullback to an 8% Decline: Prices Keep Falling Even as Marginal Selling Eases
The most significant new development this week was that the index decline deepened even as foreign selling fell sharply. The KOSPI pulled back 3.8% in the prior week and declined another 7.6% this week. The index fell from 8,088.34 to 7,475.94, bringing its cumulative two-week decline close to double digits. Over the same period, weekly net foreign selling declined from KRW 19.84 trillion to KRW 4.12 trillion, while USD/KRW fell from approximately 1,531 to 1,505. Risk-asset prices and marginal fund flows have begun to diverge.
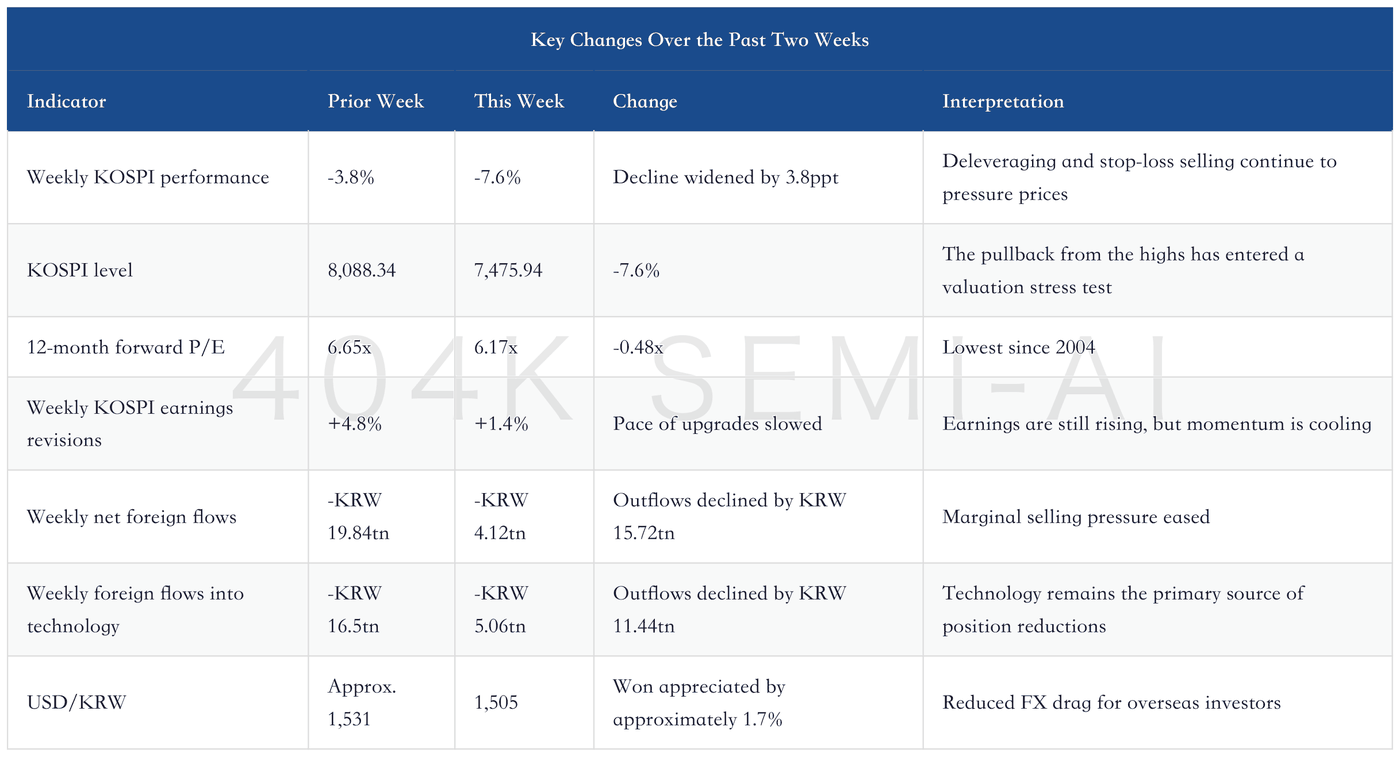
These changes provide a clear picture of current market conditions. Prices are still searching for a post-deleveraging clearing level, but marginal funding pressure is already lower than in the prior week. If selling continues to subside, the index should become less sensitive to incremental negative news. If foreign outflows reaccelerate, positioning pressure will continue to suppress the current low valuation.
“The Banking, Telecom and Chemicals sectors outperformed this week, while Machinery, Tech and Shipbuilding sectors underperformed the most. Foreign investors continued to sell the KOSPI market, driven by outflows for KOSPI Tech. KOSPI 12-month forward EPS was revised up by +1.4%.”
This passage brings together the week’s three core contradictions: the index and valuations fell first, foreign investors continued to sell technology, and earnings forecasts were still rising. Each layer must be validated separately in investment decisions. Neither a one-day rebound nor a low P/E alone is sufficient to identify a market bottom or establish a margin of safety.
Korea Market Deep Dive: Repricing AI Hardware After a 4% KOSPI Pullback, 6.65x Forward P/E, and Foreign Outflows
The prior week’s conclusion was that “earnings remain intact, while positioning has loosened first.” This week’s evidence reinforces that view but raises the bar for confirmation: the pace of earnings upgrades slowed from 4.8% to 1.4%, and bulls now need revisions to remain positive over the coming weeks. If prices continue to fall sharply, “earnings are still rising” will no longer be sufficient; fund flows and technical indicators must also improve.
II. What Is a 6.17x P/E Pricing In? The Market Is Front-Loading a 33% Earnings Downgrade
A 6.17x forward P/E reflects a crisis-level risk premium. According to Goldman Sachs, this is the lowest reading since 2004, below even the valuation trough during the 2008 global financial crisis and 3.1 standard deviations below the long-term average. At this valuation, the market is discounting more than an ordinary earnings slowdown. It is approaching a scenario in which the memory cycle peaks, earnings at technology heavyweights decline sharply, and overseas investors structurally reduce allocations at the same time.
“As of July 8, 2026, KOSPI forward P/E reached its lowest level since 2004 at 6.2x, below even the trough reached during the GFC in 2008. Korea’s largest semiconductor company also reached its lowest forward P/E since 2000 at 4.8x. Even excluding the top two names, Korea 12-month and 24-month forward P/Es fell to 10.1x and 8.6x respectively.”
There are two layers to this valuation. The first is the index P/E of 6.17x, which is depressed by the surge in earnings at Samsung Electronics and SK Hynix. The second is the broader market excluding the two largest constituents, which trades at 12-month and 24-month forward P/Es of 10.1x and 8.6x, respectively. Korea is inexpensive overall, but the index-level valuation extreme primarily reflects explosive profit growth and cyclical discounting among heavyweight semiconductor stocks.
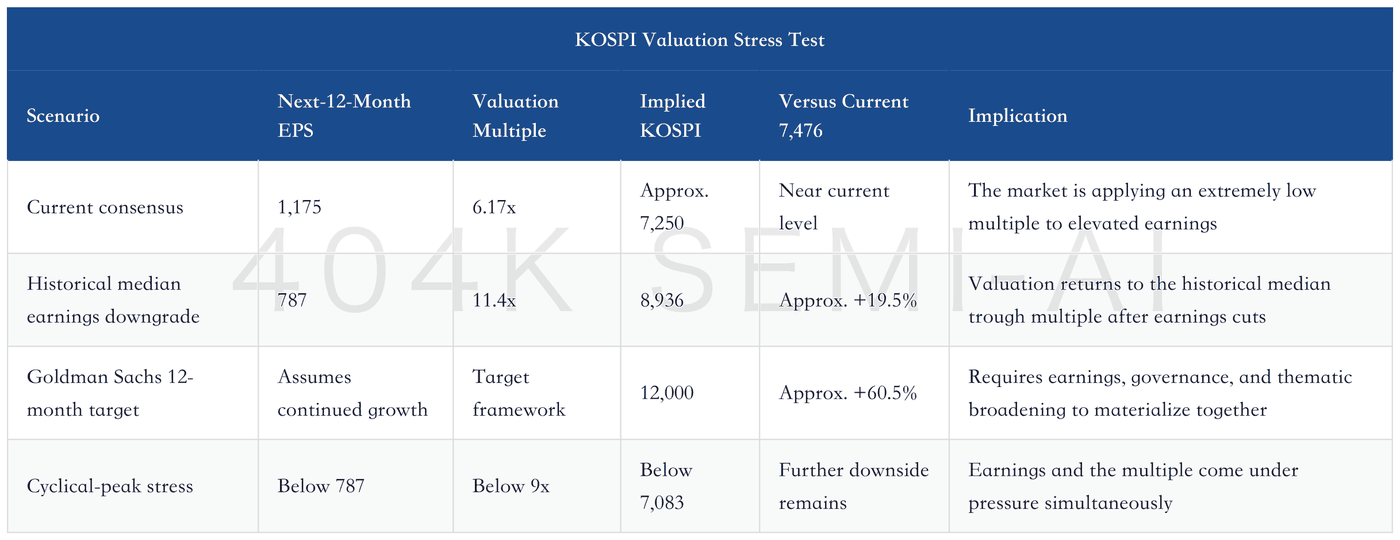
The key value of this stress test is that it separates “cheapness” into two axes: earnings and valuation multiples. Goldman Sachs reduces EPS by the historical median earnings downgrade of 33%, then applies the historical median trough P/E of 11.4x, producing an index level of 8,936. Historically, by the time earnings bottom, the market has often begun assigning a recovery multiple to the next cycle. The current market is still compressing peak earnings and the risk premium into the same low multiple.
The model also has clear failure conditions. If 2026 earnings merely reflect a short-lived peak in memory pricing and supply expands rapidly in 2027, the market will continue to apply a low multiple. If earnings decline by more than 33% while global risk appetite deteriorates, the 8,936 stress-test level will overstate the margin of safety. Low valuations provide favorable risk-reward; earnings durability determines the speed of realization.
III. Samsung’s Record-High Profit and 4.81x Valuation: The Core Disconnect in the Korean Index
Samsung Electronics encapsulates the contradiction of “strong earnings, weak share price.” The company’s reported 2Q26 profit was affected by provisions for special semiconductor bonuses, while Goldman Sachs estimates that core operating profit has already surpassed KRW100 trillion. Stronger DRAM earnings offset smartphone weakness, and Goldman Sachs also raised its medium- and long-term EPS forecasts, yet Samsung’s 12-month forward P/E fell to 4.81x.
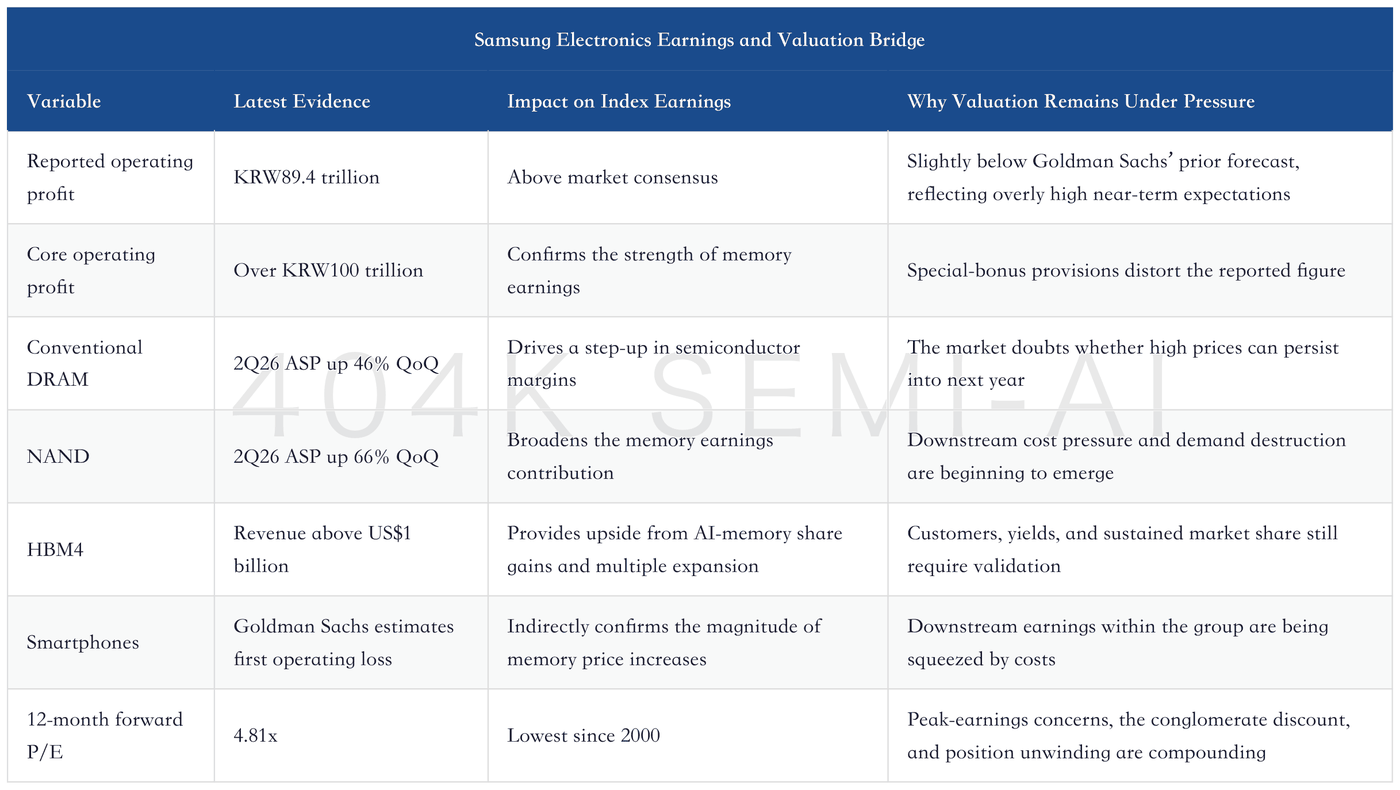
The Korean index’s low P/E cannot be understood without Samsung Electronics. Samsung’s conventional DRAM, NAND, and HBM4 businesses are jointly lifting earnings, driving a rapid increase in the index’s next-12-month EPS; at the same time, the market doubts the sustainability of these profits and is compressing the multiple. The stronger the earnings and the lower the multiple, the cheaper the stock appears; but once the pricing trajectory weakens, the elevated earnings base will also magnify the apparent scale of downgrades.
Samsung Electronics In-Depth Update: 2Q26 Core Profit Beat, HBM4 Revenue Above US$1 Billion, and Valuation Reset After the Smartphone Business’s First Loss
Samsung’s July 30 earnings call will determine how this disconnect closes. Investors need details on the number of customers, duration, pricing mechanisms, and prepayments for long-term agreements; HBM4 revenue, yields, and customer progress; and whether capex is concentrated in high-end products. If contracts lock high prices into 2027 cash flow, a 4.81x valuation will look too low; if capacity expands too quickly or downstream demand is impaired, the low multiple will persist.
IV. Earnings Are Still Being Upgraded, but More Slowly: From a Broad Rally to Divergence
Index earnings continued to be revised upward this week, but the sector distribution matters more than the aggregate. Securities led the upgrades, while chemicals, technology, and insurance maintained positive revisions; machinery and leisure turned negative. Index earnings have not weakened across the board. Growth is broadening from memory as the single engine to financials, materials, and parts of the industrial value chain; the precise figures are set out below.
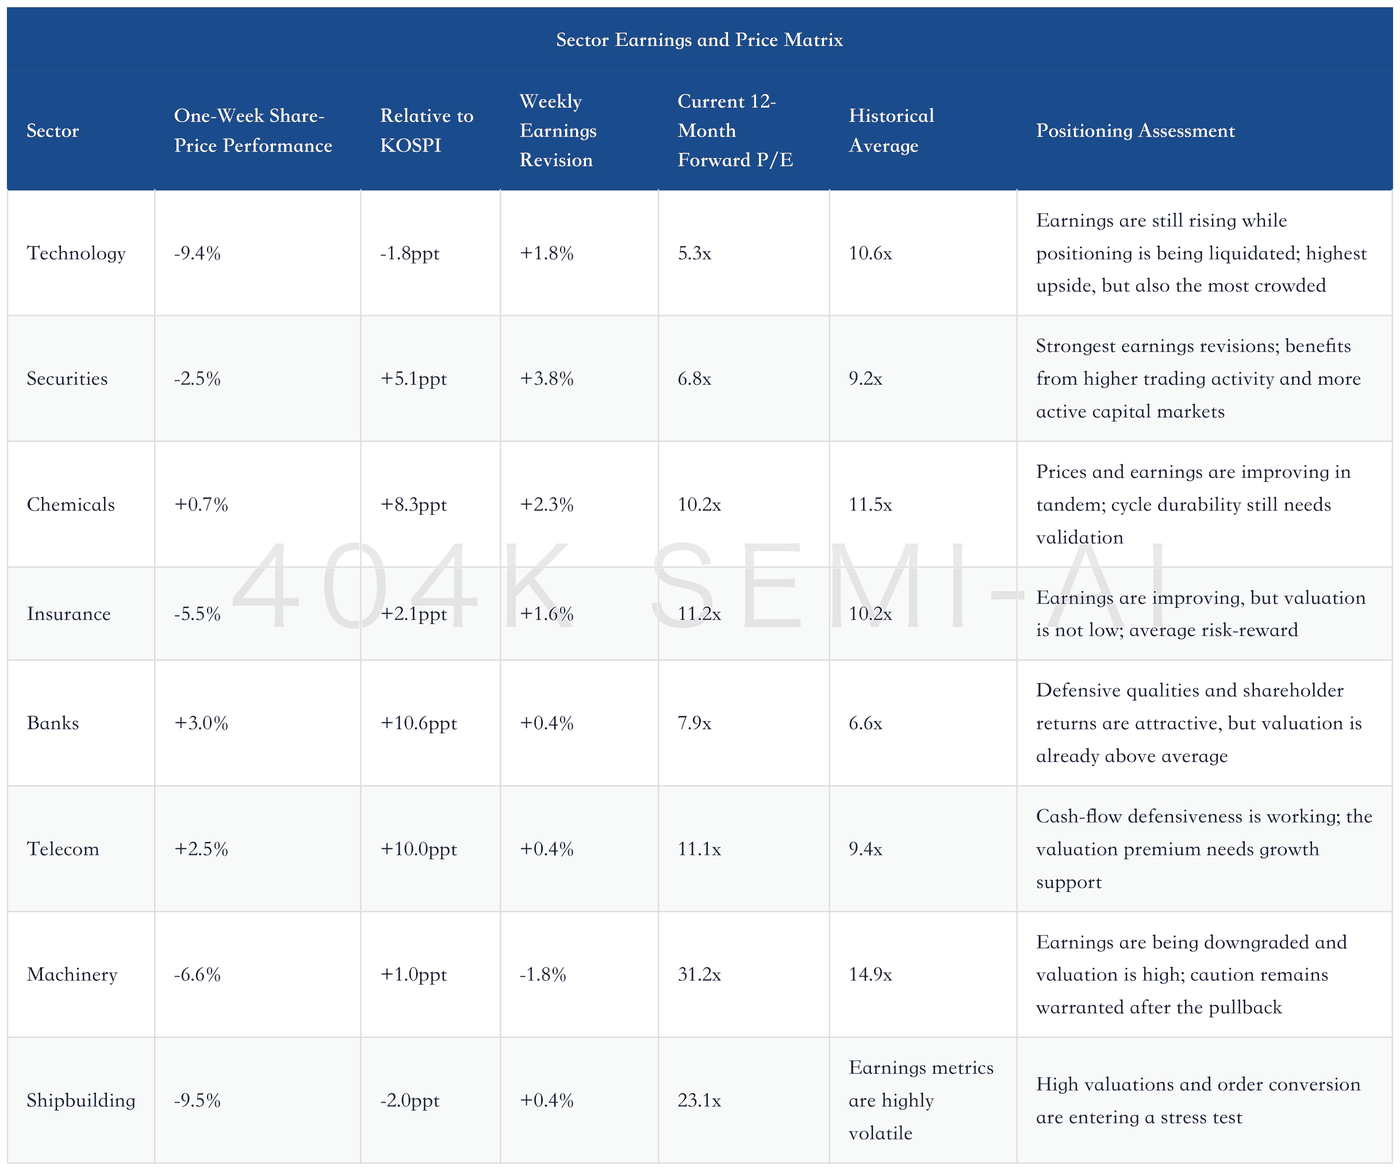
This matrix establishes a clear hierarchy. Technology remains the core first-tier position because earnings revisions are positive and valuations are at historical lows, while Samsung and SK Hynix determine index profits. Securities and selective chemicals form the second tier of incremental exposure, with a better alignment between earnings revisions and valuation. Banks and telecom provide defensive exposure, but current multiples are no longer cheap. Machinery and shipbuilding require earnings revisions to turn stronger again.
“Korean equities delivered the strongest performance in Asia during 1H26. This year’s 92% gains have been driven by earnings, with AI-related technology hardware and semiconductor stocks accounting for the majority of market returns. Although volatility has increased and may remain elevated, a broad thematic opportunity set, continuing rapid earnings growth, and attractive valuation should help propel KOSPI towards our 12-month 12,000 target.”
This assessment explains why sector broadening matters. Korea’s first-half returns were driven primarily by AI hardware and semiconductors, leaving both positioning and earnings excessively concentrated. If industrials, power infrastructure, corporate governance, reflation trades, and semiconductor capex take over as additional drivers in the second half, the index’s dependence on a single memory-pricing cycle will decline. If broadening fails, KOSPI volatility will continue to be amplified by its two heavyweight memory stocks.
V. Flow Structure: Foreign Investors Continue to Sell Technology, While Domestic Retail Continues to Buy
This week’s flow structure continued the pattern of “foreign selling, retail buying,” though at a lower intensity than the previous week. Foreign investors recorded net sales of KRW4.12 trillion in KOSPI, while retail investors bought a net KRW3.68 trillion and institutions bought a net KRW292 billion; pension-fund flows were broadly flat. Foreign investors sold a net KRW5.06 trillion in technology, exceeding their total net outflow from the index, indicating that foreign buying in banks, telecom, chemicals, software, and other sectors offset part of the technology selling.
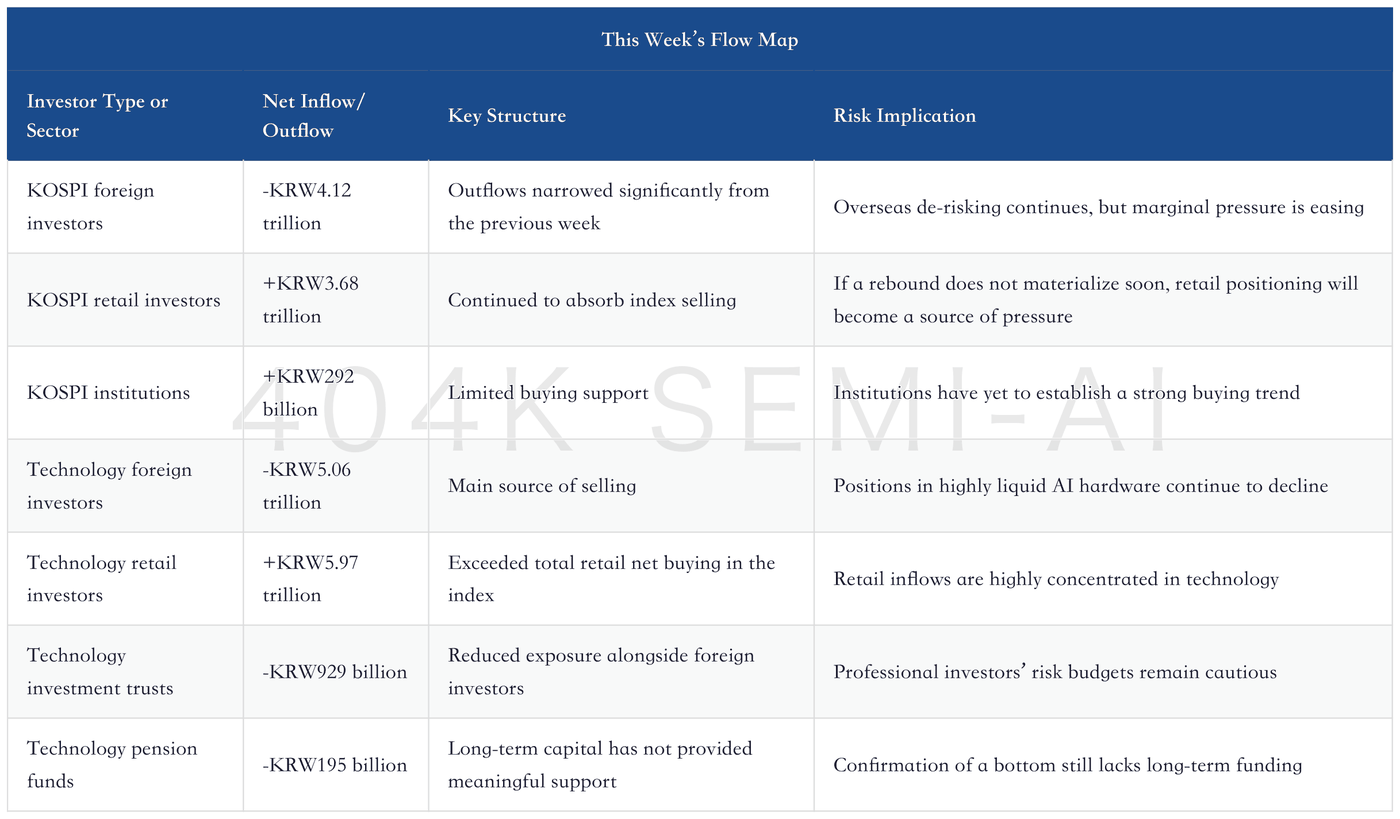
The year-to-date structure is even more extreme. Foreign investors have sold a cumulative net KRW161.58 trillion, retail investors have bought a cumulative net KRW109.45 trillion, financial institutions have bought a cumulative net KRW36.9 trillion, and pension funds have sold a cumulative net KRW9.01 trillion. The Korean index still shows substantial year-to-date gains, yet buying has come mainly from domestic retail investors and some financial institutions, making the market more sensitive to external shocks and changes in margin financing.
The ratio of margin loans to customer deposits remains elevated, VKOSPI has risen to around 90, and the share of KOSPI constituents trading above their 200-day moving averages has fallen to approximately 20%. Prices have entered oversold territory, but leverage and volatility have yet to return to healthy levels. During a rebound, the first priority is the composition of trading: if foreign investors and long-term capital begin to take over, the rebound will be higher quality; if retail investors continue to absorb selling alone, volatility will remain recurrent.
